
- Home
- »
- Clinical Diagnostics
- »
-
Infectious Respiratory Disease Diagnostics Market Report, 2033GVR Report cover

Infectious Respiratory Disease Diagnostics Market (2026 - 2033)
Size, Share & Trends Analysis By Product (Instruments, Services), By Application (COVID-19, Influenza, Tuberculosis), By Technology (Immunoassay, Microbiology, Molecular Diagnostics), By End-use, By Region, And Segment Forecasts
Market Size, 2025
$12.6BMarket Estimate, 2026
$12.9BMarket Forecast, 2033
$15.7BCAGR, 2026–2033
2.8%Infectious Respiratory Disease Diagnostics Market Summary
The global infectious respiratory disease diagnostics market size was valued at USD 12.6 billion in 2025 and is projected to grow from USD 12.9 billion in 2026 to USD 15.7 billion by 2033, at a CAGR of 2.8% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 44.6% in 2025. The market is being driven by several key factors, including the growing prevalence of diseases like tuberculosis and pneumonia, advancements in diagnostic technologies, and increased partnerships and collaborations between major players.
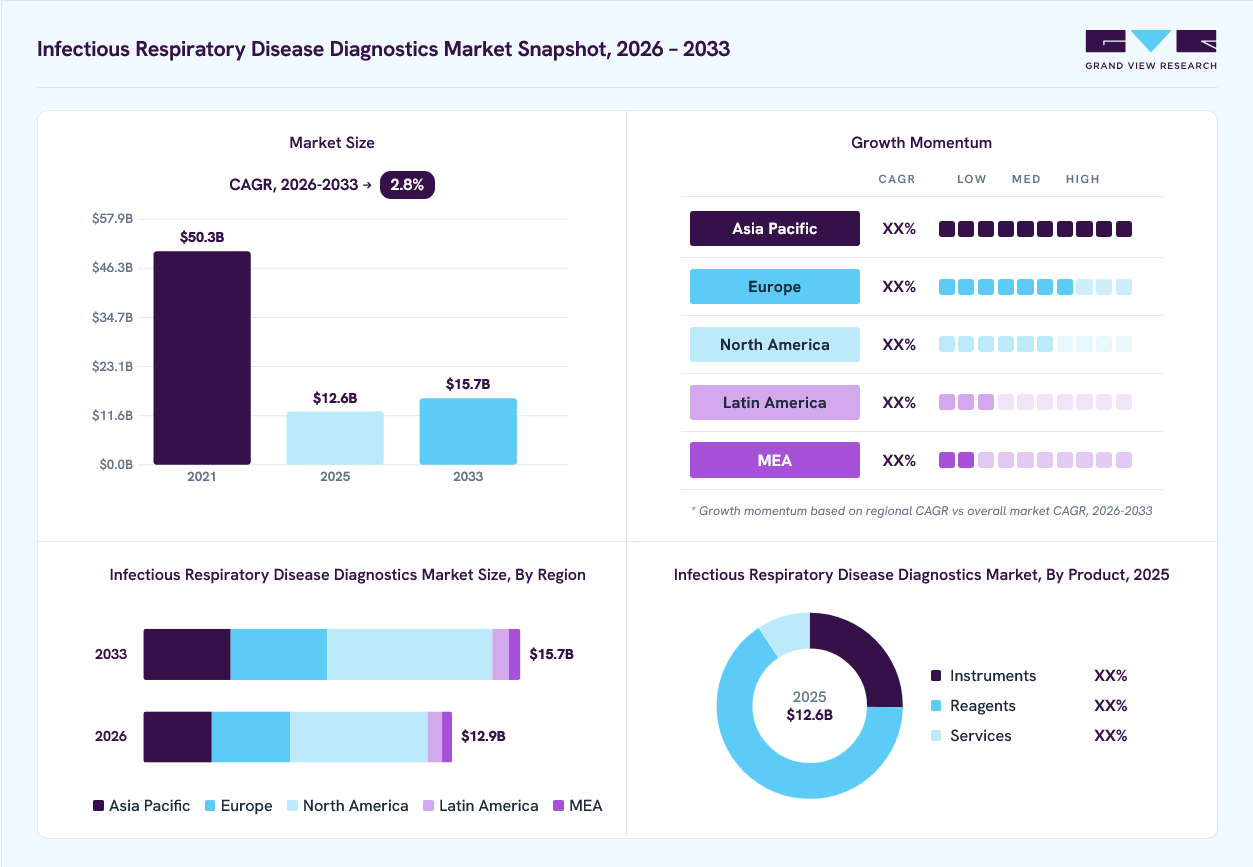 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By products: Reagents segment led the market with the largest revenue share of 65.4% in 2025.
- By technology: Molecular diagnostics segment led the market with the largest revenue share of 67.6% in 2025.
- By application: COVID-19 segment led the market with the largest revenue share of 89.2% in 2025.
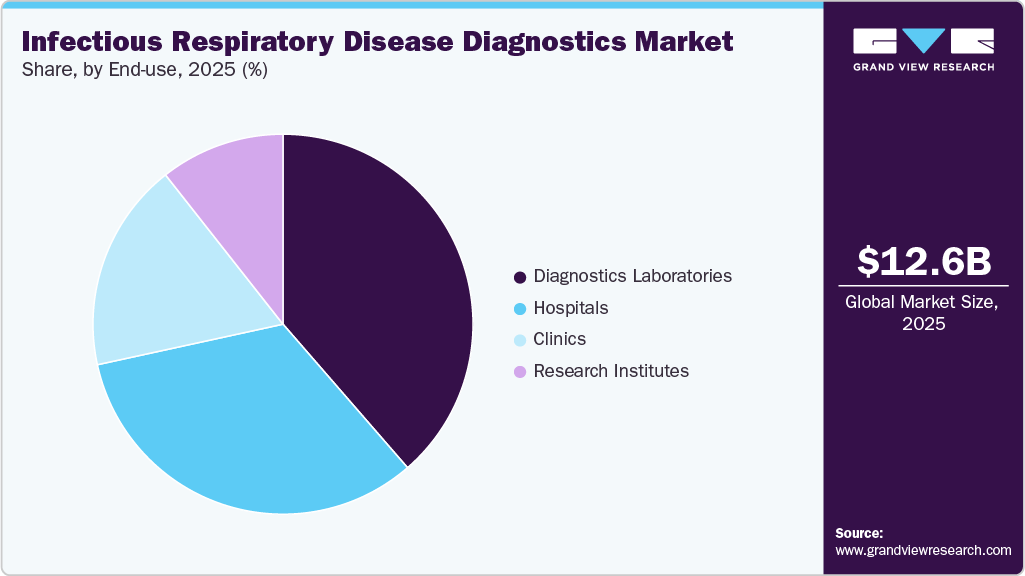
- By test end Use: Diagnostics laboratories segment led the market with the largest revenue share of 38.6% in 2025.
Regional Highlights
- Largest regional market: North America (44.6% revenue share, 2025)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 12.6 Billion
- Estimated market size in 2026: USD 12.9 Billion
- Projected market size by 2033: USD 15.7 Billion
- CAGR (2026-2033): 2.8%
GVR research-powered AIAsk Prism AI about the infectious respiratory disease diagnostics marketGet cited answers from GVR research on market growth, segments, regulations and forecasts.Start with✓ Source-linked answers ✓ Market-specific context ✓ Traceable figuresExplore Prism AI ↗
For instance, in February 2023, Thermo Fisher Scientific and Mylab Discovery Solutions announced a partnership to develop and distribute diagnostic test kits for infectious diseases such as multi-drug-resistant tuberculosis, hepatitis B virus, hepatitis C virus, HIV, and genetic analysis (HLA B27) in India. The collaboration aims to combine Thermo Fisher’s global expertise with Mylab’s local manufacturing capabilities to expand access to high-quality testing solutions.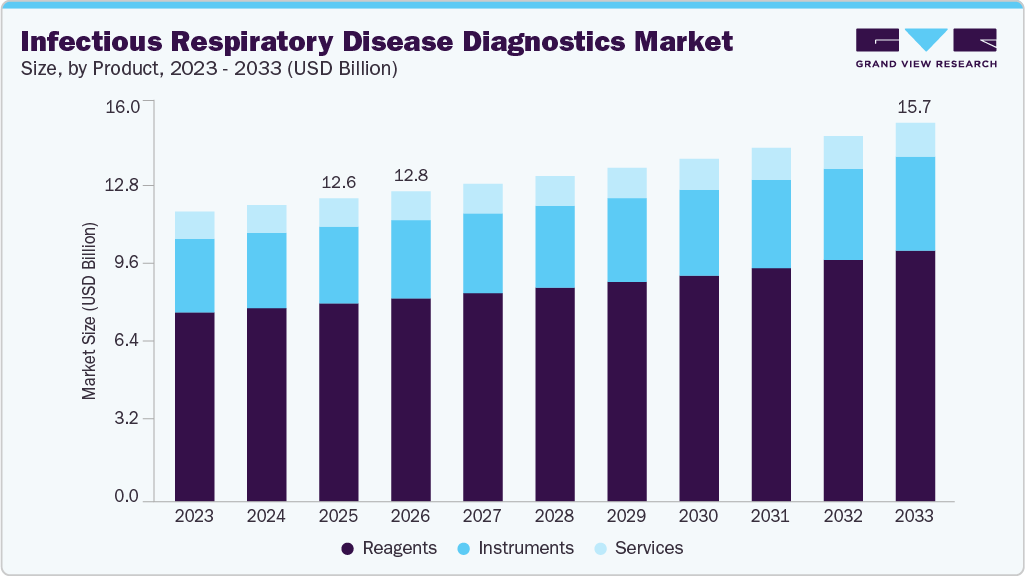 To learn more about this report, Download Free Sample Report
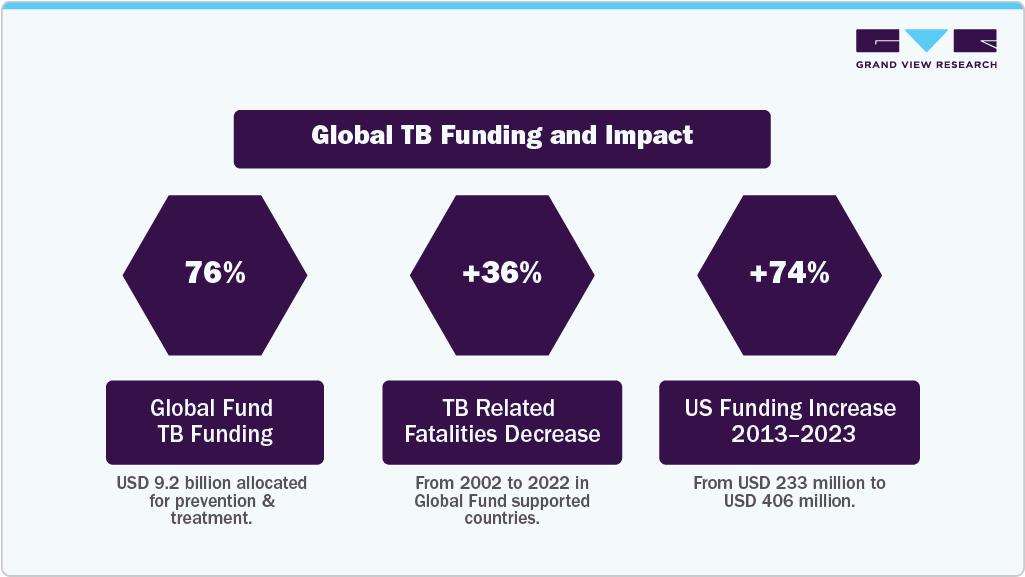
The increasing funding for TB diagnosis programs is crucial in the fight against this global disease. The current funding for prevention, diagnosis, and treatment is insufficient to meet the demand, hindering progress in reducing incidence & mortality rates. For instance, an annual investment of USD 22 billion by 2027 was set, with an additional USD 5 billion for research, and only USD 5.8 billion was allocated for TB services, falling short of the required amounts to achieve global targets. Moreover, WHO emphasizes the need for sustained & increased funding to combat TB effectively. Hence, the U.S. government has significantly increased its funding for TB initiatives, from USD 233 million in 2013 to USD 406 million in 2023. Investments in screening and preventive treatment have shown significant health & economic benefits, with a return on investment of up to USD 39 for every dollar spent.
Key global TB metrics
Metrics
Value
Estimated new TB cases (global, 2024)
10.7 million
TB incidence rate (global, 2023)
134 per 100,000 population
Actual notified (diagnosed & reported) TB cases (2024)
8.3 million
Estimated TB deaths (2024)
1.23 million
% of TB cases among people living with HIV (global, 2024)
~5.8%
Rifampicin-resistant (RR/MDR-TB) estimated new cases (2024)
~390,000
Proportion of RR/MDR-TB cases treated (2024)
~42%
Source: WHO, Grand View Research
 To learn more about this report, Download Free Sample Report
As of August 2022, the U.S. FDA had approved 439 diagnostic tests for COVID-19 under Emergency Use Authorization (EUAs). The market is becoming increasingly competitive with the introduction of new molecular diagnostic tests for detecting SARS-CoV-2. Rapid advancements in technology, which offer greater accuracy, portability, and cost-efficiency, are expected to drive market growth significantly. In April 2020, Canon Medical Systems introduced the Aquilion Prime SP CT system, designed for the quick diagnosis of viral infectious diseases. This system features an integrated decontamination tool that uses automated UV-C technology to sanitize the equipment after each use.
The growing adoption of self-testing and point-of-care products is expected to drive market expansion further. In May 2024, Wondfo Biotech was granted Emergency Use Authorization (EUA) for Wondfo Biotech’s point-of-care assay that simultaneously tests for WELLlife COVID-19 and influenza A and B. This dual testing capability allows for rapid diagnosis in a single test, which is particularly beneficial during flu season when symptoms can overlap with those of COVID-19. Furthermore, in May 2024, BioPerfectus received approval from Brazil’s ANVISA for its dengue and malaria diagnostic kits. In collaboration with the China CDC, the company developed the Malaria Pf/Pan (HRP2/pLDH) Antigen Rapid Test Kit, supplied to Papua New Guinea, to support local efforts in managing infectious diseases. Such product approvals are likely to fuel the overall market growth in the forecast period.
Advancements in diagnostic techniques, including molecular diagnostics and point-of-care testing, have further accelerated market expansion by improving accuracy and reducing turnaround times. Governments, healthcare organizations, and key players are increasing investments in research and development to enhance diagnostic capabilities, which is also contributing to market growth. The COVID-19 pandemic played a crucial role in increasing the demand for diagnostic tools, reagents, and assays, as well as spurring innovation and product launches. Moreover, growing awareness about the importance of early detection and diagnosis in managing infectious diseases is driving both consumer demand and healthcare providers’ adoption of advanced diagnostics, further fueling market expansion.
Market Dynamics
The Infectious Respiratory Disease Diagnostics Market is supported by the growing incidence of seasonal and emerging respiratory infections and the increasing need for rapid and accurate diagnostic solutions to enable timely clinical intervention. Healthcare providers are expanding the adoption of multiplex molecular assays and syndromic testing platforms that identify multiple respiratory pathogens through a single test, improving diagnostic efficiency and treatment decisions. Continued investments in laboratory automation and integrated diagnostic workflows are further strengthening testing capacity across hospitals and reference laboratories. This trend is reflected in ongoing product portfolio advancements by industry participants. For instance, in September 2025, QIAGEN expanded its QIAstat Dx respiratory syndromic testing portfolio, enhancing access to rapid multiplex diagnostics for respiratory pathogens across clinical settings. Such developments are supporting broader adoption of comprehensive respiratory testing, improving disease surveillance, enabling effective outbreak response, and facilitating evidence based therapeutic decisions across healthcare systems.
The growing adoption of molecular diagnostics and multiplex respiratory testing is a key driver of the Infectious Respiratory Disease Diagnostics Market. Healthcare providers are increasingly implementing PCR based and syndromic testing platforms that enable rapid and accurate detection of multiple respiratory pathogens from a single sample, supporting timely treatment decisions and infection control measures. The expansion of automated diagnostic workflows and increasing emphasis on respiratory disease surveillance are further accelerating demand for advanced testing solutions across hospitals and clinical laboratories. This trend is supported by continuous portfolio enhancements from leading manufacturers. For instance, in August 2025, F. Hoffmann-La Roche expanded the respiratory testing menu on its cobas molecular diagnostics platform, strengthening comprehensive respiratory pathogen detection and improving laboratory efficiency. Such advancements are supporting broader adoption of molecular diagnostics while enhancing clinical decision making and public health preparedness.
The high cost of advanced molecular diagnostic instruments and multiplex testing panels remains a significant restraint for the Infectious Respiratory Disease Diagnostics Market. Healthcare facilities in resource constrained settings often face challenges in adopting automated diagnostic platforms due to substantial capital investment, maintenance expenses, and the need for trained laboratory personnel. Reimbursement limitations and budget constraints further restrict the routine use of comprehensive respiratory diagnostic testing, particularly in smaller hospitals and decentralized healthcare facilities. As a result, conventional diagnostic methods continue to be used despite offering longer turnaround times and lower diagnostic accuracy for certain respiratory pathogens. These factors contribute to disparities in access to advanced respiratory diagnostics across developed and developing healthcare systems, limiting broader market penetration and slowing the adoption of next generation molecular testing technologies.
The expansion of high throughput syndromic diagnostic platforms presents a significant opportunity for the Infectious Respiratory Disease Diagnostics Market. Healthcare systems are increasingly investing in scalable molecular diagnostic solutions that can process larger testing volumes while delivering rapid and accurate identification of multiple respiratory pathogens. This demand is driven by the need to strengthen outbreak preparedness, improve laboratory efficiency, and support routine surveillance of seasonal and emerging respiratory infections. Manufacturers are responding by introducing advanced platforms with greater automation and expanded testing capabilities. For instance, in March 2026, QIAGEN received U.S. regulatory clearance for the QIAstat Dx Rise system, a higher throughput syndromic testing platform designed to enhance respiratory pathogen detection in clinical laboratories. Such innovations are expected to accelerate the adoption of advanced respiratory diagnostics while supporting efficient laboratory operations and timely patient management across healthcare settings.
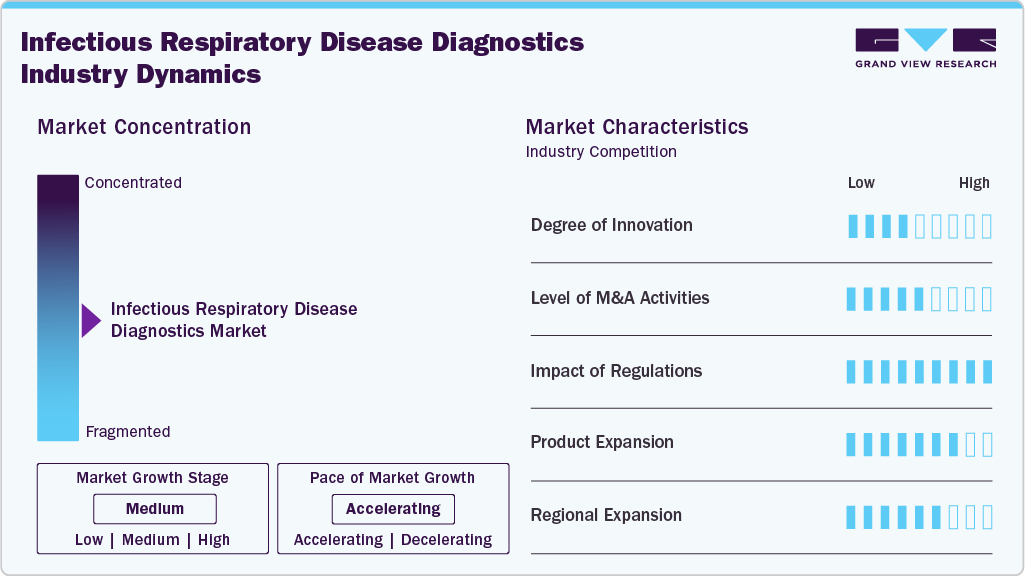
Market Concentration & Characteristics
Innovation in infectious respiratory disease diagnostics has accelerated since 2022, with manufacturers shifting toward multiplex, rapid molecular, and syndromic testing platforms. In January 2024, QIAGEN expanded its syndromic footprint by launching the QIAstat-Dx GI2 and Meningitis/Encephalitis panels in India, complementing its respiratory panel and signaling deeper global adoption of cartridge-based multiplex PCR. The post-pandemic period also drove refinements in respiratory panels, such as Seegene’s continuous optimization of Allplex SARS-CoV-2/Flu/RSV assays through 2022-23, reflecting the industry’s push for high-sensitivity multi-target testing. These advancements have strengthened market concentration around companies with the R&D capacity to develop rapid, automated, and clinically actionable molecular solutions.
The market has seen selective but strategically important M&A aimed at strengthening point-of-care and high-throughput molecular ecosystems. In July 2024, Roche acquired LumiraDx’s point-of-care technology assets, expanding its decentralized testing capabilities and positioning itself more competitively in respiratory molecular diagnostics. Such acquisitions highlight a broader trend: large diagnostics companies are consolidating emerging POC technologies to diversify testing settings beyond central laboratories. Earlier, during 2022-23, several regional partnerships and acquisitions across Asia and Europe concentrated on expanding syndromic testing portfolios, further intensifying competitive dynamics.
 To learn more about this report, Download Free Sample Report
Regulation has played a defining role in shaping market entry timelines and competitive intensity. The EU In Vitro Diagnostic Regulation (IVDR), enforced in 2022 with phased transitions to 2027, substantially increased evidence requirements for respiratory assays, raising development costs and extending approval timelines. This shift favored established players with strong compliance infrastructure while slowing market access for smaller innovators. In parallel, countries such as India and the U.S. strengthened post-market surveillance norms, pushing vendors to demonstrate consistent clinical accuracy, particularly for multiplex and rapid molecular respiratory tests.
The product expansion has centered on multiplex panels, rapid molecular assays, and broader pathogen coverage. QIAGEN’s January 2024 launch of new QIAstat-Dx panels in India exemplified manufacturers’ strategies to widen their syndromic disease portfolios beyond respiratory but interconnected with respiratory workflows. bioMérieux continued growing its BioFire FilmArray respiratory menu through 2022-23, reinforcing its leadership in syndromic testing. Seegene also expanded assays targeting combined viral respiratory pathogens, addressing hospital demand for single-run multi-pathogen identification as respiratory seasons became less predictable post-COVID.
Regional expansion efforts since 2022 have increasingly targeted high-burden, high-volume markets such as India, Southeast Asia, and Latin America. QIAGEN’s India launch in January 2024 underlined how global molecular diagnostics companies are prioritizing emerging regions where respiratory disease prevalence, infrastructure modernization, and government surveillance programs create strong demand for advanced diagnostics.
Analyst Perspective
The Infectious Respiratory Disease Diagnostics Market is expected to witness sustained growth, supported by the increasing burden of seasonal and emerging respiratory infections, expanding adoption of molecular diagnostics, and continued investments in laboratory automation. The market is transitioning toward multiplex and syndromic testing platforms that enable rapid identification of multiple respiratory pathogens while improving clinical efficiency. Regulatory approvals and ongoing product portfolio expansions by leading diagnostic companies are strengthening technology adoption across healthcare settings. Future opportunities are expected to arise from high throughput molecular platforms, decentralized testing, and respiratory disease surveillance programs, supported by advances in automation, digital connectivity, and integrated diagnostic workflows.
Product Insights
Based on products, the reagents segment led the market with the largest revenue share of 65.4% in 2025 and anticipated to grow at fastest CAGR over the forecast period. Technological advancements in diagnostic devices have resulted in more sophisticated testing methods, necessitating the use of specialized reagents. Innovations in point-of-care testing and home testing kits require reagents that are not only reliable but also easy to use, driving their demand among both healthcare professionals and patients. Moreover, the COVID-19 pandemic has accelerated the production and use of reagents, with a notable increase in the development of rapid tests and related materials. This trend has prompted manufacturers to invest in research and development, leading to the introduction of new and improved reagents.
In September 2021, the U.S. FDA granted authorization for approximately 261 molecular diagnostic products, 88 serological tests, and 34 antigen tests for COVID-19 diagnosis. The instrument segment emerged as the second-largest revenue contributor in 2025, driven by the launch of innovative products designed to assist healthcare professionals in diagnosing COVID-19. For example, in March 2021, Vyaire Medical, Inc. launched AioCare, a mobile spirometry system for diagnosing respiratory diseases in the European Union, Middle East, and Australia. This product delivers hospital-grade accuracy and allows physicians to monitor patients remotely through advanced digital connectivity, making it easier to manage care at home.
The instrument segment is anticipated to grow at a considerable rate of 2.67% CAGR over the forecast period. Rising demand for rapid, accurate, and broad coverage respiratory testing continues to push healthcare systems toward fully automated, syndromic diagnostic platforms. Clinicians increasingly require tools that can quickly identify the specific pathogen causing infection, especially in settings where timely treatment decisions are critical, such as emergency departments, pediatric care, and ICU units. Moreover, the increasing availability of advanced diagnostic instruments is further expanding the market growth. For instance, the FDA-cleared BIOFIRE System, which offers panels capable of detecting viruses, bacteria, parasites, yeast, and antimicrobial resistance genes, demonstrates the market shift toward rapid syndromic diagnostics by providing broad, reliable results from a single sample.
Technology Insights
Based on technology, the molecular diagnostics segment led the market with the largest revenue share of 67.6% in 2025. The significant market share for molecular tests is largely due to the growing demand for accurate diagnosis of COVID-19, RSV, influenza, and other respiratory infections. PCR remains the gold standard technology for amplifying DNA, making it a trusted choice for molecular diagnostics. In response to this demand, companies are developing multiplex tests that enable the simultaneous diagnosis of multiple infectious respiratory diseases using a single swab. For example, in December 2020, GENETWORx, LLC introduced an innovative test capable of detecting three respiratory viruses-SARS-CoV-2, RSV, and Influenza A & B-from a single sample.
The rapid/point-of-care diagnostics segment is anticipated to grow at the fastest rate of 3.54% CAGR over the forecast period, driven by advancements in Rapid point-of-care (POC) diagnostic innovation, which further propels the market growth. For instance, the transformative work led by Yuka Manabe and the Johns Hopkins University Center in February 2025, for innovative diagnostics for infectious diseases, is accelerating the development of fast, accurate, and user-friendly diagnostic tools that can be deployed globally. Their contributions to COVID-19 rapid tests created a technological and regulatory blueprint that is now being adapted for a wide range of infectious respiratory diseases, including influenza, RSV, and emerging pathogens.
Application Insights
Based on application, the COVID-19 segment led the market with the largest revenue share of 89.2% in 2025. This dominance was driven by the increasing number of COVID-19 variants, an increase in product approvals, and heightened research and development efforts. However, with rising vaccination rates expected to lessen the severity of the disease, testing rates are likely to decline in the coming years. In response to changing market dynamics, key players are launching direct-to-consumer testing kits that allow individuals to collect samples without the need for trained personnel, thereby reducing turnaround times.
Meanwhile, the tuberculosis segment is anticipated to grow at the fastest rate of 9.74% CAGR over the forecast period. The persistent global burden of tuberculosis (TB) demonstrates the urgent need for improved diagnostic tools, driving market growth. For instance, according to an article published by Tejaswini Dharmapuri Vachaspathi (Treatment Action Group), in November 2025, TB claimed approximately 1.25 million lives, and of the 10.84 million estimated cases, 2.7 million remained undiagnosed, unreported, or untreated in 2023. This significant diagnostic gap highlights the limitations of conventional TB tests and the growing need for innovative solutions.
End-use Insights
Based on test end Use, the diagnostics laboratories segment led the market with the largest revenue share of 38.6% in 2025. They are equipped with advanced technology and staffed by skilled professionals, enabling them to perform a wide array of diagnostic tests with high accuracy and reliability. This capability is essential for detecting infectious diseases and chronic conditions that require precise diagnosis. Furthermore, these laboratories offer comprehensive testing services, addressing both routine and specialized needs, and can handle large volumes of samples efficiently. The rising prevalence of diseases and an increasing focus on early diagnosis have led healthcare providers to increasingly depend on laboratory services for improved patient management. In addition, advancements in laboratory automation and artificial intelligence have enhanced the efficiency and speed of test results, further solidifying the reliance on diagnostic laboratories.
 To learn more about this report, Download Free Sample Report
The hospitals segment is projected to experience substantial growth during the forecast period. The hospital segment plays a pivotal role in driving market growth, as hospitals increasingly depend on advanced diagnostic technologies to ensure early and accurate detection of respiratory infections. With rising patient inflows, higher disease complexity, and the need for rapid clinical decision-making, hospitals are investing heavily in advanced molecular assays, imaging systems, and rapid point-of-care diagnostic tools.
Regional Insights
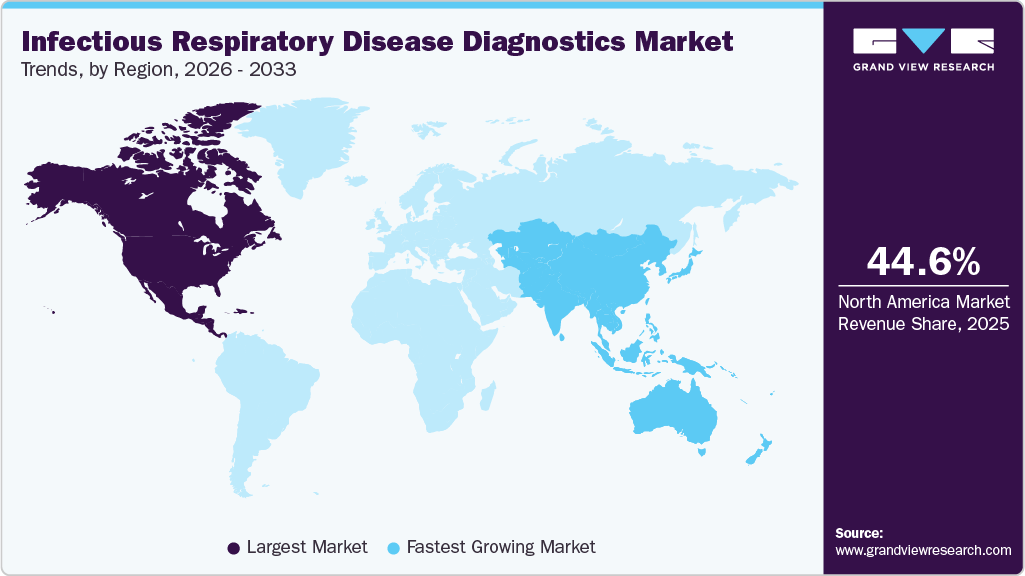
North America dominated the Infectious Respiratory Disease Diagnostics Market with the largest revenue share of 44.6% in 2025. The region benefits from advanced healthcare infrastructure and high healthcare expenditure, enabling the rapid adoption of innovative diagnostic technologies. The presence of leading biotechnology and pharmaceutical companies in the United States fosters continuous research and development, resulting in the introduction of cutting-edge diagnostic solutions.
 To learn more about this report, Download Free Sample Report
U.S. Infectious Respiratory Disease Diagnostics Market Trends
The Infectious Respiratory Disease Diagnostics Market in the U.S. held the largest share in the North America region in 2025, fueled by the presence of key players and a large end-user base. The increasing prevalence of chronic and infectious diseases, coupled with increasing public awareness about early diagnosis and preventive healthcare, drives demand for diagnostic tests.
Europe Infectious Respiratory Disease Diagnostics Market Trends
The infectious respiratory disease diagnostics market in Europe is experiencing significant growth. Europe holds a significant share of the overall market, driven by advanced healthcare systems, strong regulatory frameworks, and increasing demand for early disease detection. The region benefits from extensive research and development initiatives, leading to innovative diagnostic solutions. In addition, rising awareness of preventive healthcare further fuels market growth.
The UK infectious respiratory disease diagnostics market is likely to show significant growth owing to healthcare improvements and technological developments. The National Health Service (NHS) drives demand for accurate and efficient diagnostic solutions, particularly in response to rising chronic diseases. In addition, advancements in point-of-care testing and increased investment in medical technologies contribute to the market's growth, ensuring that the UK remains at the forefront of diagnostic advancements.
The infectious respiratory disease diagnostics market in Germany is experiencing significant growth. The country benefits from a well-established network of diagnostic laboratories and medical device manufacturers, driving the development of cutting-edge diagnostic technologies. Germany’s commitment to research and development, supported by significant government funding, fosters advancements in areas such as molecular diagnostics and point-of-care testing.
Asia Pacific Infectious Respiratory Disease Diagnostics Market Trends
The infectious respiratory disease diagnostics market in the Asia Pacific is experiencing the fastest growth, driven by significant advancements in terms of technology. Countries like China, India, and Japan are leading this expansion due to their large populations and growing demand for advanced diagnostic solutions. The region is witnessing significant advancements in technology, particularly in molecular diagnostics and point-of-care testing, which enhance the speed and accuracy of disease detection.
China infectious respiratory disease diagnostics market is growing, driven by the rapid expansion of its biotechnology and pharmaceutical industries. China is a prominent player in the market, characterized by rapid growth fueled by increasing healthcare investments and a vast population. The country has made significant strides in advancing its healthcare infrastructure, leading to a rising demand for innovative diagnostic solutions.
Latin America Infectious Respiratory Disease Diagnostics Market Trends
The infectious respiratory disease diagnostics market in Latin America is experiencing significant growth, driven by an increasing demand for healthcare services and improvements in medical infrastructure. The rising prevalence of chronic and infectious diseases, such as diabetes and COVID-19, is boosting the need for accurate and efficient diagnostic solutions.
Middle East and Africa Infectious Respiratory Disease Diagnostics Market Trends
The infectious respiratory disease diagnostics market in the MEA is expanding, driven by an increasing emphasis on healthcare improvement and disease prevention. Rapid urbanization, rising disposable incomes, and a growing burden of chronic and infectious diseases are key factors fueling demand for diagnostic solutions.
Saudi Arabia infectious respiratory disease diagnostics market growth is driven by substantial investments in healthcare infrastructure and a commitment to improving public health. The country's Vision 2033 initiative aims to enhance healthcare services, increase the availability of advanced diagnostic solutions, and promote preventive care.
Key Infectious Respiratory Disease Diagnostics Company Insights
The competitive scenario in the market is high, with key players such as Abbott, Thermo Fisher Scientific, Inc., Koninklijke Philips N.V., F. Hoffmann-La Roche Ltd., BD, bioMérieux SA, Bio-Rad Laboratories, Inc., Quidel Corporation, Siemens Healthcare GmbH, Danaher, and Qiagen holding significant positions. Prominent market participants are focusing on increasing the customer base by launching new products. For instance, in May 2024, F. Hoffman-La Roche Ltd. received FDA approval for its HPV self-testing kit, which can help identify women at risk of developing cervical cancer at an earlier stage. Furthermore, in March, SEKISUI Diagnostics obtained EUA clearance for the OSOM Flu SARS-CoV-2 Combo Test. It was approved for use in professional and home testing settings.
Key Infectious Respiratory Disease Diagnostics Companies
The following key companies have been profiled for this study on the infectious respiratory disease diagnostics market.
-
Abbott
-
Bio-Rad Laboratories, Inc
-
Siemens Healthineers AG
-
bioMérieux
-
BD
-
QIAGEN
-
QuidelOrtho Corporation
-
F. Hoffmann-La Roche
-
Koninklijke Philips N.V.
-
Cepheid (Danaher Corporation)
-
Seegene Inc.
-
EliTechGroup (Bruker Corporation)
-
CERTEST BIOTEC
-
Thermo Fisher Scientific, Inc.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Well Established Players (Abbott, F. Hoffmann-La Roche, Thermo Fisher Scientific, BD, Siemens Healthineers AG, bioMérieux, QIAGEN, Cepheid (Danaher Corporation))
- Expand infectious respiratory disease diagnostic portfolios through molecular diagnostics, immunoassays, multiplex respiratory panels, automated laboratory systems, and point of care testing solutions.
- Focus on continuous product innovation, regulatory approvals, strategic collaborations, manufacturing expansion, and integration of digital laboratory workflows to strengthen diagnostic capabilities across hospitals and reference laboratories.
- Broad diagnostic portfolios, strong global distribution networks, extensive research and development capabilities, established regulatory expertise, and integrated laboratory solutions.
- Ability to serve hospitals, diagnostic laboratories, public health agencies, and decentralized healthcare settings through comprehensive respiratory diagnostic platforms and scalable testing workflows.
- Premium pricing of advanced molecular diagnostic systems, lengthy regulatory approval processes, and dependence on centralized manufacturing can limit operational flexibility.
- High instrument acquisition costs and infrastructure requirements may restrict adoption among smaller laboratories and healthcare facilities with budget constraints.
Emerging and Specialized Players (QuidelOrtho Corporation, Seegene Inc., CERTEST BIOTEC, EliTechGroup (Bruker Corporation), Bio-Rad Laboratories, Inc.)
- Focus on specialized respiratory diagnostics through multiplex PCR assays, rapid antigen tests, syndromic respiratory panels, niche molecular testing solutions, and application specific diagnostic products.
- Emphasize rapid product development, technology innovation, strategic partnerships, geographic expansion, and strengthening presence in infectious disease surveillance and decentralized testing markets.
- Strong expertise in multiplex respiratory diagnostics, rapid innovation cycles, specialized assay development, and flexible product customization.
- Ability to respond quickly to emerging respiratory pathogens while addressing specific clinical and public health diagnostic requirements through differentiated testing solutions.
- Comparatively narrower product portfolios, limited commercial reach, and lower manufacturing capacity than multinational diagnostic companies.
- Greater reliance on regional distribution partnerships and respiratory disease focused product lines may limit competitiveness across the broader in vitro diagnostics market.
Recent Developments
-
In July 2025, BD announced the 510(k) clearance for the BD Veritor System for SARS-CoV-2 (the 510(k) will eventually replace the EUA version).
-
In April 2025, bioMérieux launched WATCHFIRE, a molecular testing solution (22-target respiratory panel) that runs on the BIOFIRE FILMARRAY TORCH and integrates with FIREWORKS software for real-time wastewater surveillance/outbreak detection.
-
In January 2025, Thermo Fisher’s TaqPath COVID-19, Flu A, Flu B, RSV Select Panel progressed from EUA/CE status to FDA 510(k) clearance, enabling broader clinical IVD adoption in the U.S.
-
In May 2024, Wondfo Biotech was granted Emergency Use Authorization (EUA) for Wondfo Biotech’s point-of-care assay that simultaneously tests for WELLlife COVID-19 and influenza A and B. This dual testing capability allows for rapid diagnosis in a single test, which is particularly beneficial during flu season when symptoms can overlap with those of COVID-19.
-
In May 2024, BioPerfectus received approval from Brazil’s ANVISA for its dengue and malaria diagnostic kits. In collaboration with the China CDC, the company developed the Malaria Pf/Pan (HRP2/pLDH) Antigen Rapid Test Kit, supplied to Papua New Guinea, to support local efforts in managing infectious diseases.
-
In May 2024, F. Hoffman-La Roche Ltd. received FDA approval for its HPV self-testing kit, which can help identify women at risk of developing cervical cancer at an earlier stage.
-
In April 2024, Cepheid announced that its Xpert HIV-1 Qual XC received prequalification from WHO, confirming its high standards of performance, quality, safety, and reliability. This in vitro nucleic acid amplification test detects HIV-1 total nucleic acids from dried blood spots and whole blood specimens, offering extended strain coverage and results up to seven to ten days before seroconversion. It was approved for early diagnosis in infants, adolescents, & adults in both POC and laboratory settings.
Infectious Respiratory Disease Diagnostics Market Report Scope
Report Attribute
Details
Market size in 2025
USD 12.6 billion
Estimated market size in 2026
USD 12.9 billion
Projected market size by 2033
USD 15.7 billion
Growth rate
CAGR of 2.8% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, Technology, Application, End Use, Regional
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Denmark; Sweden; Norway; Japan; China; India; South Korea; Australia; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; and Kuwait
Key companies profiled
Abbott, Bio-Rad Laboratories, Inc., Siemens Healthineers AG, bioMérieux, BD, QIAGEN, QuidelOrtho Corporation, F. Hoffmann-La Roche, Koninklijke Philips N.V., Cepheid (Danaher Corporation), Seegene Inc., EliTechGroup (Bruker Corporation), CERTEST BIOTEC, Thermo Fisher Scientific, Inc.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Infectious Respiratory Disease Diagnostics Market Report Segmentation
This report forecasts revenue growth at country levels and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global infectious respiratory disease diagnostics market report based on technology, pathogen, end-use, and region:
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Instruments
-
Reagents
-
Services
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
COVID-19
-
Influenza
-
Respiratory Syncytial Virus (RSV)
-
Tuberculosis
-
Non-tuberculosis Mycobacterium Testing
-
Bacterial Pneumonia Testing
-
Other Respiratory Disease Testing
-
-
Technology Outlook (Revenue, USD Million, 2021 - 2033)
-
Immunoassay
-
Molecular Diagnostics
-
Microbiology
-
Rapid/Point-of-Care Diagnostics
-
Other Technologies
-
-
End-use Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospitals
-
Diagnostic Laboratories
-
Clinics
-
Research Institutes
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Norway
-
Denmark
-
Sweden
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The infectious respiratory disease diagnostics market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each infectious respiratory disease diagnostics segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Instruments
Revenue is primarily captured through sales of molecular diagnostic analyzers, PCR systems, immunoassay analyzers, point of care diagnostic devices, automated sample preparation systems, and other instruments used for detecting infectious respiratory pathogens in clinical laboratories and healthcare settings.
Reagents
Revenue flows from the sale of assay kits, PCR reagents, multiplex respiratory panels, primers, probes, enzymes, extraction reagents, quality controls, calibrators, and other consumables required for infectious respiratory disease diagnostic testing.
Services
Revenue is derived from instrument installation, maintenance, calibration, technical support, laboratory testing services, software upgrades, validation services, training programs, and other service offerings that ensure efficient operation of respiratory diagnostic systems.
Segment - Application
Revenue capture definition
COVID-19
Revenue is primarily captured through sales of molecular assays, rapid antigen tests, immunoassays, multiplex respiratory panels, and related consumables used for the detection and monitoring of SARS CoV 2 infections across healthcare settings.
Influenza
Revenue flows from influenza diagnostic assay kits, molecular PCR tests, rapid antigen tests, multiplex respiratory panels, and associated reagents utilized for identifying influenza A and influenza B infections in clinical laboratories and hospitals.
Respiratory Syncytial Virus (RSV)
Revenue is derived from RSV molecular assays, antigen detection kits, multiplex respiratory panels, reagents, and diagnostic consumables used for detecting respiratory syncytial virus infections in pediatric and adult patient populations.
Tuberculosis
Revenue is captured through sales of molecular diagnostic assays, nucleic acid amplification tests, culture based diagnostic reagents, smear microscopy consumables, and automated testing systems used for tuberculosis detection and drug resistance testing.
Non tuberculosis Mycobacterium Testing
Revenue is generated through specialized molecular assays, culture media, identification kits, sequencing based tests, reagents, and laboratory consumables used for detecting and differentiating non tuberculosis mycobacterial infections.
Bacterial Pneumonia Testing
Revenue flows from molecular diagnostic panels, bacterial culture reagents, antigen detection assays, susceptibility testing products, and consumables used for identifying bacterial pathogens responsible for respiratory tract infections and pneumonia.
Other Respiratory Disease Testing
Revenue is primarily captured through diagnostic assays, multiplex respiratory panels, reagents, and laboratory consumables used for detecting respiratory pathogens including adenovirus, parainfluenza virus, human metapneumovirus, rhinovirus, and other respiratory infectious agents.
Segment - Technology
Revenue capture definition
Immunoassay
Revenue is primarily captured through sales of antigen detection assays, antibody tests, immunoassay analyzers, assay reagents, calibrators, controls, and related consumables used for infectious respiratory disease diagnosis.
Molecular Diagnostics
Revenue flows from molecular assay kits, PCR and RT PCR reagents, nucleic acid amplification tests, automated molecular analyzers, sample preparation systems, and associated consumables used for respiratory pathogen detection.
Microbiology
Revenue is derived from culture media, microbial identification systems, antimicrobial susceptibility testing products, staining reagents, laboratory consumables, and microbiology instruments used for respiratory pathogen isolation and characterization.
Rapid Point of Care Diagnostics
Revenue is captured through sales of rapid antigen tests, portable molecular diagnostic devices, lateral flow assays, point of care analyzers, disposable test cartridges, and related consumables for near patient respiratory testing.
Segment - End Use
Revenue capture definition
Hospitals
Revenue is primarily captured through procurement of respiratory diagnostic instruments, assay kits, reagents, point of care testing devices, laboratory consumables, and associated services used for inpatient and emergency diagnostic testing.
Diagnostic Laboratories
Revenue flows from high volume purchases of molecular diagnostic systems, multiplex respiratory panels, immunoassay kits, microbiology products, laboratory consumables, and testing services performed by independent and reference laboratories.
Clinics
Revenue is derived from the adoption of rapid diagnostic tests, point of care analyzers, respiratory assay kits, portable diagnostic devices, and consumables used for routine patient screening and outpatient respiratory disease diagnosis.
Research Institutes
Revenue is captured through sales of advanced diagnostic platforms, research assay kits, laboratory reagents, validation tools, and specialized consumables utilized for respiratory pathogen research, epidemiological studies, and diagnostic assay development.
Estimation Model
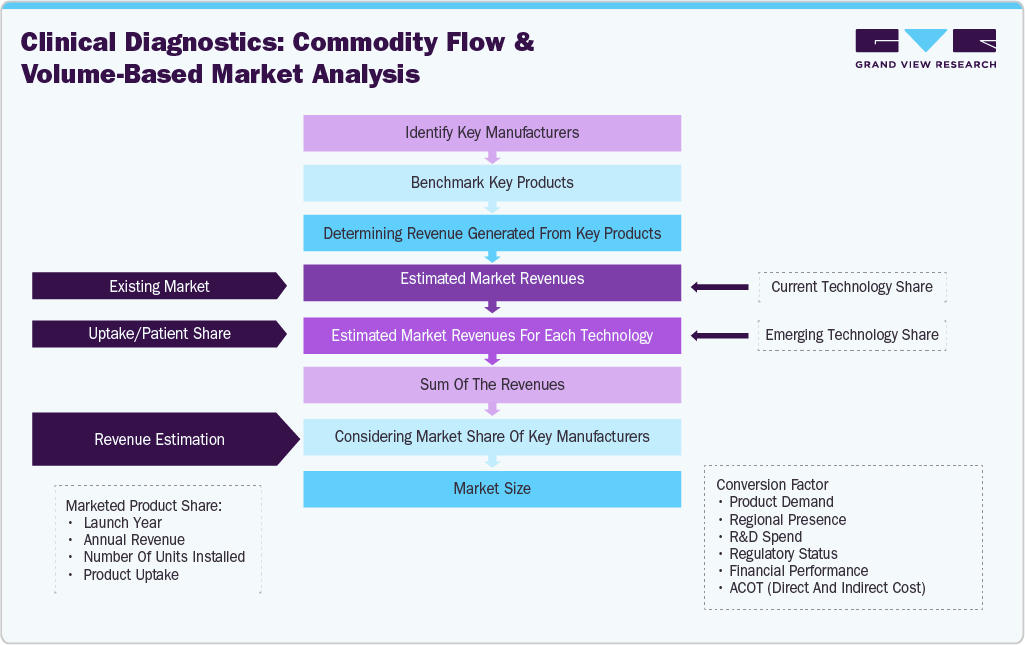
The Infectious Respiratory Disease Diagnostics Market was estimated using a bottom up approach by identifying key manufacturers, benchmarking their respiratory diagnostic product portfolios, and evaluating revenues generated from these products. Technology specific market revenues were estimated based on disease prevalence, testing uptake, and adoption across end users, followed by aggregation of segment revenues and validation using the market share of leading manufacturers to derive the overall market size.
 To learn more about this report, Download Free Sample Report
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Infectious Respiratory Disease Diagnostics Competitive Landscape & Technology Assessment
Assessed the global infectious respiratory disease diagnostics market across molecular diagnostics, immunoassays, microbiology, rapid point-of-care diagnostics, multiplex respiratory panels, and emerging diagnostic technologies. Evaluated competitive positioning, product portfolios, technology advancements, regulatory approvals, strategic collaborations, and adoption trends across hospitals, diagnostic laboratories, research institutes, and public health agencies.
Helped the client identify technology adoption trends, benchmark competitive capabilities, evaluate product differentiation, prioritize strategic investments, and assess expansion opportunities across respiratory diagnosis, syndromic testing, and infectious disease surveillance markets.
Infectious Respiratory Disease Diagnostics Technology Benchmarking Study
Delivered comprehensive benchmarking of molecular diagnostic platforms, multiplex PCR systems, rapid antigen tests, immunoassays, microbiology solutions, and point-of-care diagnostic devices. Assessed analytical performance, turnaround time, testing throughput, automation capabilities, workflow efficiency, application coverage, and product differentiation among leading market participants.
Enabled the client to evaluate technology competitiveness, identify innovation opportunities, benchmark product development strategies, prioritize investments in molecular diagnostics and point-of-care testing, and strengthen product positioning across respiratory infectious disease diagnostics.
Infectious Respiratory Disease Diagnostics Adoption & Commercialization Assessment
Assessed respiratory disease testing trends, healthcare infrastructure development, laboratory automation, regulatory landscape, reimbursement environment, procurement practices, and commercialization pathways influencing adoption of respiratory diagnostic technologies across major regional markets.
Supported commercialization planning by identifying market entry opportunities, evaluating customer adoption patterns, assessing operational and investment considerations, mitigating commercialization risks, and strengthening long-term strategies across diagnostic manufacturers, healthcare providers, and laboratory networks.
Frequently Asked Questions About This Report
Key players include Abbott; Thermo Fisher Scientific Inc.; Koninklijke Philips N.V.; F. Hoffmann-La Roche Ltd.; bioMérieux SA; BD; Quidel Corporation; QIAGEN; Danaher; Siemens Healthcare GmbH.
The major factors driving market growth are the rising incidence of infectious respiratory diseases, the rising number of product approvals, and increasing initiatives by government and non-profit organizations to improve diagnostic tests.
Asia Pacific is the fastest-growing region over the forecast period.
Reagent segment led with a 65.4% revenue share in 2025.
Diagnostics segment led with a 67.6% revenue share in 2025, while rapid/point-of-care diagnostics is the fastest-growing segment.
COVID-19 segment led with a 89.2% revenue share in 2025, while tuberculosis is the fastest-growing area.
The global infectious respiratory disease diagnostics market size was valued at USD 12.6 billion in 2025 and is estimated at USD 12.9 billion for 2026.
The global infectious respiratory disease diagnostics market is expected to grow at a CAGR of 2.9% from 2026 to 2033, reaching USD 15.7 billion by 2033.
North America dominated with a 44.6% revenue share in 2025.
About the Author(s)
Clinical Diagnostics Research Team
Healthcare · Clinical DiagnosticsThis report was authored by the clinical diagnostics research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the clinical diagnostics segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


