
- Home
- »
- Medical Devices
- »
-
U.S. Medical Examination Lights Market Size Report, 2033GVR Report cover

U.S. Medical Examination Lights Market (2025 - 2033) Size, Share & Trends Analysis Report By Product Type (LED Examination Lights, Halogen Examination Lights), By Mounting Type, By Application, By End-use, And Segment Forecasts
U.S. Medical Examination Lights Market Summary
The U.S. medical examination lights market size was estimated at USD 506.73 million in 2024 and is projected to reach USD 759.42 million by 2033, growing at a CAGR of 4.67% from 2025 to 2033. This growth is attributed to the increasing demand for high-quality visualization during medical examinations and minor procedures, driven by the rise in outpatient visits, chronic disease diagnoses, and preventive health screenings..
Key Market Trends & Insights
- Asia Pacific solar encapsulation market held the largest share of 62 % of the global market in 2024.
- By mounting type, the mobile/floor-standing segment accounted for the largest market revenue share in 2024.
- By application, the gynecological examination segment is anticipated to grow at the fastest CAGR from 2025 to 2033.
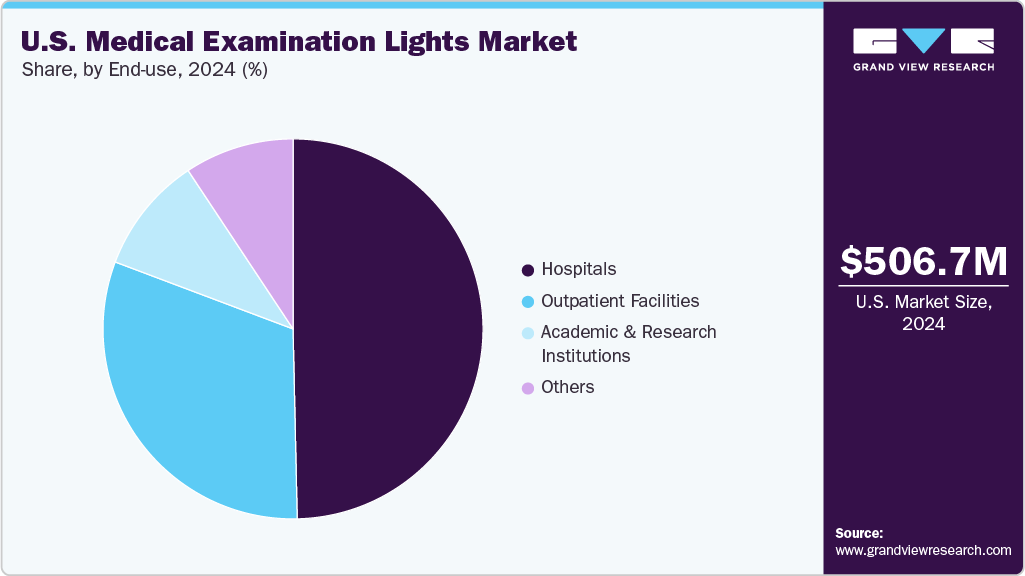
- By end use, the hospital segment led the market with the largest revenue share of 49.65% in 2024.
Market Size & Forecast
- 2024 Market Size: USD 17.03 Billion
- 2033 Projected Market Size: USD 759.42 Million
- CAGR (2025-2033): 4.67%
Prism AI by Grand View Research Free to tryAsk a question about the U.S. medical examination lights marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
In addition, advancements in LED technology, energy efficiency, and ergonomics have enhanced product performance and usability. According to the CDC, in 2024, approximately 85.2% of U.S. adults and 95.1% of children had at least one visit with a doctor or other healthcare professional.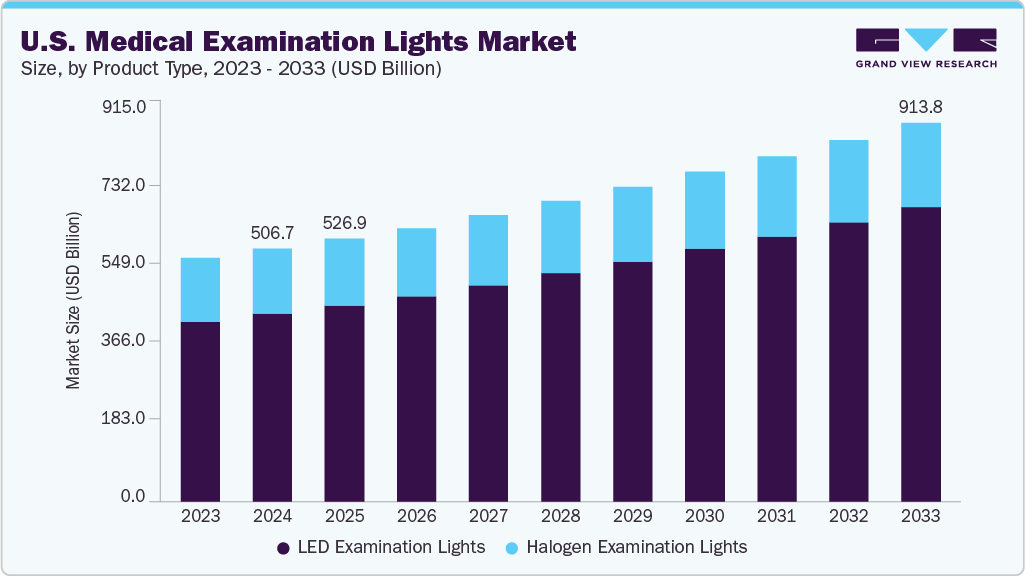 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Ambulatory Surgical Centers (ASCs) are significantly driving the U.S. medical examination lights industry, fueled by the ongoing shift from inpatient to outpatient care. ASCs offer same-day surgical procedures that do not require hospital admission, making them a cost-effective and efficient alternative for patients and payers. The demand for high-quality examination lights has surged as the number of ASCs continues to rise across the country, driven by technological advancements, favorable reimbursement policies, and patient preference for minimally invasive procedures. These facilities require reliable, energy-efficient, and ergonomic lighting systems supporting various diagnostic and minor surgical procedures. According to the MedPAC, in 2023, about 6,300 ASCs treated 3.4 million fee-for-service Medicare beneficiaries. FFS Medicare program and beneficiary spending on ASC services was about USD 6.8 billion. The volume of ASC surgical procedures per FFS beneficiary rose 5.7 percent in 2023.
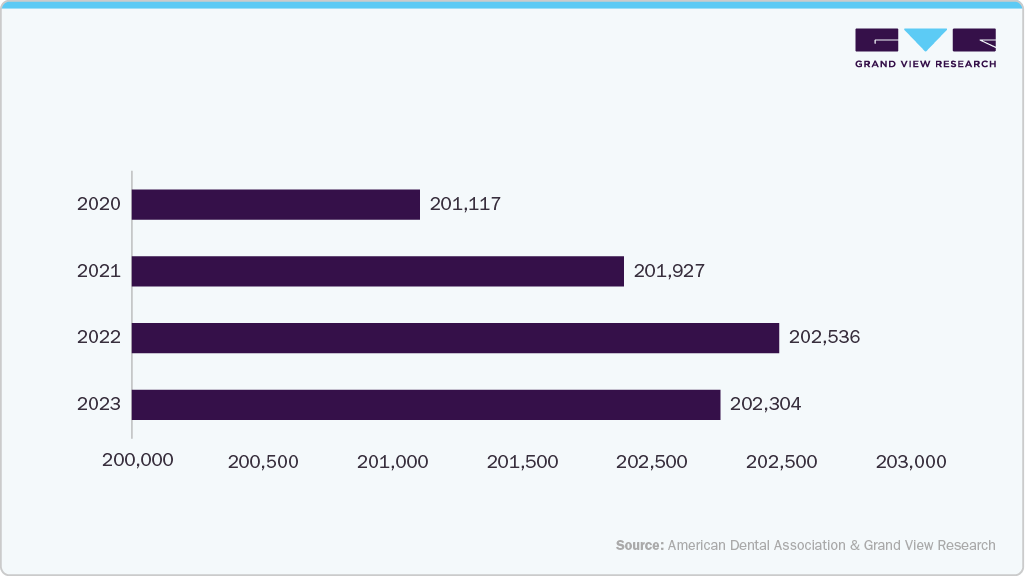
Dentists in the U.S. significantly contribute to the growth of the medical examination lights market due to the critical need for precision lighting during dental procedures such as examinations, surgeries, and cosmetic treatments. The increasing number of dental visits, rising awareness about oral health, and demand for advanced procedures have led clinics to invest in high-quality, shadow-free, and energy-efficient lighting systems. In addition, expanding dental chains, outpatient clinics, and mobile dental units have accelerated the adoption of compact and ergonomic examination lights. As per CDC, in 2022, 63.7% of U.S. adults age 65 and older had a dental visit in the past 12 months.
Number of Dentist in U.S.
Year
Total Number of Dentists
Dentists per 100,000 Population
2023
202,304
60.4
2022
202,536
60.8
2021
201,927
60.8
2020
201,117
60.7
 To learn more about this report, Download Free Sample Report
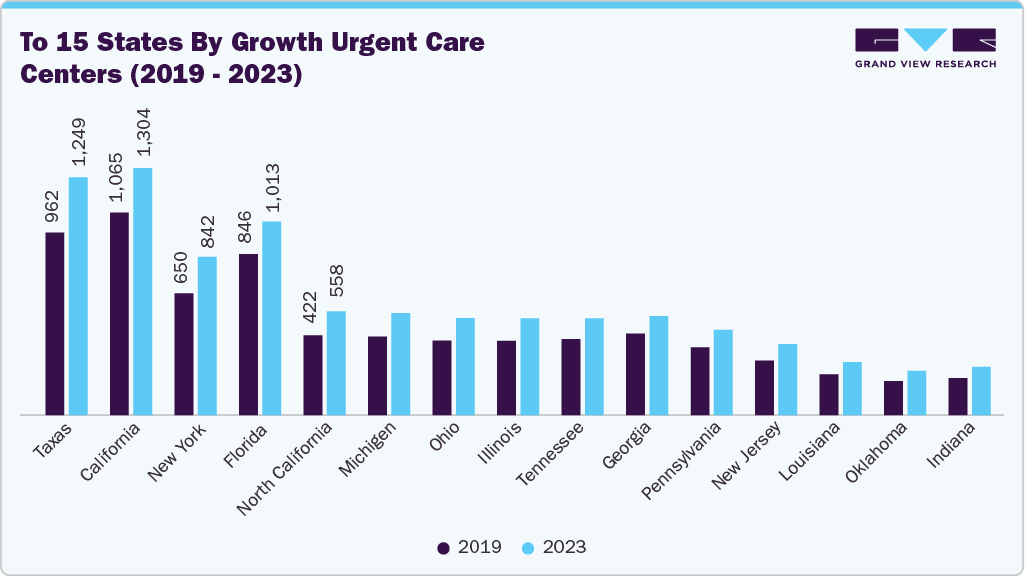
The rapid expansion of urgent care centers across the U.S. is a key driver of growth in the medical examination lights market. Urgent care facilities are increasingly becoming the preferred choice for patients seeking immediate, non-emergency medical attention due to their accessibility, extended hours, and shorter wait times compared to traditional hospitals. These centers require well-equipped examination rooms with high-performance lighting systems to ensure accurate clinical assessments and minor procedures. The need for energy-efficient, portable, and easily adjustable examination lights is particularly high in these settings to support a wide range of diagnostic and treatment services. In addition, the increasing scope of services offered by urgent care centers, including minor surgeries, wound care, and orthopedic procedures, further boosts the demand for advanced lighting solutions. This growth trend significantly contributes to the expansion of the examination lights market in the U.S.
 To learn more about this report, Download Free Sample Report
Market Concentration & Characteristics
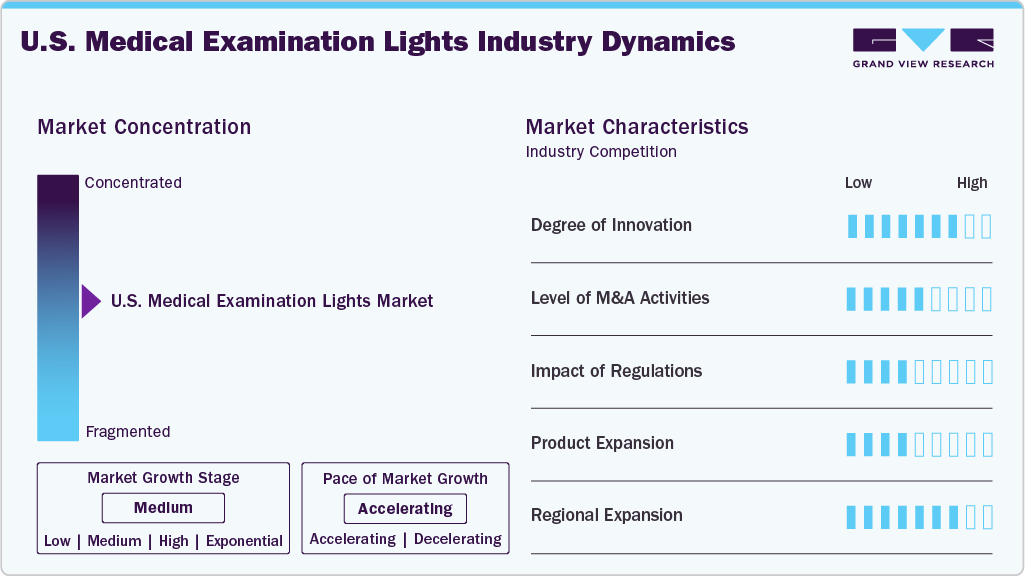
The U.S. medical examination lights industry is in a moderate-growth phase, driven by demand from hospitals, outpatient facilities, and specialty clinics. Factors such as the rising number of patient visits, an aging population, and the increasing focus on improving clinical infrastructure contribute to this growth.
The degree of innovation in the U.S. medical examination lights industry is high, as manufacturers continually invest in advanced technologies to meet evolving clinical needs. A key area of innovation is the widespread adoption of LED lighting, which offers superior brightness, lower heat emission, and longer operational life compared to traditional halogen lights. In addition, modern examination lights are equipped with smart features such as touchless controls, motion sensors, and variable intensity settings to enhance usability and hygiene. Innovations also focus on improved ergonomics and portability, with designs that allow flexible positioning and easy integration into various clinical setups. Moreover, infection control remains a priority, leading to the development of antimicrobial materials and sealed structures. These advancements collectively reflect a strong innovation-driven approach in the market,
 To learn more about this report, Download Free Sample Report
The level of mergers and acquisitions (M&A) activity in the medical examination lights market has been moderate, with select strategic deals occurring primarily as part of broader MedTech portfolio expansions. However, the medical device sector has seen a notable uptick in M&A activity, with global deal values rising significantly, driven by demand for integrated technologies and expansion into high-growth regions. This trend suggests future consolidation opportunities in the examination lights segment, especially for regional manufacturers or innovators offering LED, mobile, or hybrid-lighting technologies.
Regulations play a critical role in shaping medical examination lights' development, manufacturing, and commercialization. These devices are classified as medical equipment subject to stringent safety and performance standards. In major markets such as the U.S. and Europe, regulatory bodies such as the U.S. FDA and the European Medicines Agency (EMA) enforce classification under Class I or II medical devices, requiring compliance with electrical safety, photo biological safety, electromagnetic compatibility, and sterilization protocols.
Product expansion in the medical examination lights market is driven by continuous technological advancements, evolving clinical needs, and the growing demand for versatile, energy-efficient lighting solutions. Manufacturers focus on LED-based lights due to their longer lifespan, lower energy consumption, and reduced heat generation compared to traditional halogen lights. This has led to the introduction of portable, battery-operated examination lights, shadowless lighting systems, and multi-arm ceiling-mounted configurations that enhance visibility and ease of use in various medical settings. Moreover, companies integrate features like adjustable color temperature, touchless controls, and sterile handle designs to meet infection control standards and support workflow efficiency.
Regional expansion is a key growth strategy for manufacturers in the medical examination lights market, driven by rising healthcare infrastructure investments, demand for advanced medical technologies, and growing patient volumes across developing regions. Established players from North America and Europe are entering Asia-Pacific, Latin America, the Middle East, and Africa, where healthcare modernization and government-led initiatives fuel the need for high-quality examination and surgical lighting systems.
Product Type Insights
The LED examination lights segment accounted for the largest market revenue share in 2024 and is projected to grow at the fastest CAGR over the forecast period. This dominance is attributed to their superior performance, energy efficiency, and longer lifespan than traditional halogen or incandescent lights. LEDs offer consistent illumination, minimal heat emission, and better color rendering, which enhances visibility during clinical procedures and patient assessments. Healthcare providers prefer LED lights due to low maintenance requirements, reduced operational costs, and environmental sustainability factors aligning with the global shift toward green healthcare infrastructure. In addition, LED lights support adjustable brightness, color temperature, and shadow-free illumination, making them suitable for various medical settings, from general examinations to minor surgeries.
The halogen examination lights segment is expected to register at a significant CAGR during the forecast period. Halogen examination lights remain relevant due to their lower upfront cost, widespread availability, and familiarity among healthcare professionals, especially in low- and middle-income countries where budget constraints limit the adoption of more advanced LED systems. Halogen lights offer high-intensity illumination and warm color rendering, which are valued in specific clinical environments. In smaller clinics, rural healthcare settings, and temporary or mobile medical units, halogen lights are a suitable solution due to their ease of installation and lower initial investment. In addition, some end users still prefer halogen systems for their simple design, quick bulb replacement, and compatibility with existing infrastructure.
Mounting Type Insights
The mobile/floor-standing segment accounted for the largest market revenue share in 2024. This dominance is driven by these units' flexibility, portability, and ease of use across a wide range of clinical environments. Mobile examination lights can be easily relocated and repositioned, which is ideal for multi-use rooms, outpatient departments, emergency settings, and rural or temporary healthcare facilities. Their cost-effectiveness and minimal installation requirements also make them a preferred choice for small to mid-sized clinics and private practices where ceiling or wall-mounted solutions are not feasible. In addition, manufacturers are enhancing mobile models with adjustable arms, stable wheeled bases, and battery-powered options, which improve mobility and allow for uninterrupted use during power outages or in low-infrastructure settings. As the demand for home healthcare, telemedicine support, and point-of-care diagnostics increases, the need for versatile and easily transportable lighting solutions is also rising, further fueling the growth of mobile/floor-standing examination lights.
The combination mounting type segment is projected to register at the fastest CAGR during the forecast period. The increasing demand for customizable and versatile lighting configurations in modern healthcare facilities primarily fuels this growth. Combination-mounted systems offer dual mounting options such as ceiling-wall, ceiling-floor, or wall-mobile, which allow healthcare providers to maximize space efficiency while enhancing operational flexibility. These systems are particularly valuable in multi-functional rooms such as emergency departments, surgical prep areas, and specialized examination suites, where clinical needs vary rapidly. Hospitals and advanced outpatient centers are adopting combination mounts to optimize workflow, improve patient throughput, and reduce installation downtime.
Application Insights
The general examination segment accounted for the largest market revenue share in 2024. Examination lights' broad applicability and essential role in routine diagnostic and physical assessments across a wide range of healthcare settings, including primary care clinics, outpatient departments, emergency rooms, and community health centers, primarily drive this leadership. General examination lights are used for non-invasive procedures, physical evaluations, and minor treatments, making them a fundamental requirement in nearly all medical facilities. Their widespread use, rising outpatient visits, aging populations, and expanding primary healthcare infrastructure, especially in developing countries, have significantly boosted demand. Manufacturers continuously improve general examination lights by integrating LED technology, adjustable brightness, ergonomic designs, and battery backup options, ensuring performance and comfort during patient evaluation. Moreover, the segment benefits from frequent replacement cycles and volume-based procurement, particularly in government health systems and private clinic networks.
The gynecological examination segment is projected to register at the fastest CAGR over the forecast period. This rapid growth is driven by the rising focus on women’s health, increased awareness and screening for gynecological conditions, and the expansion of specialized women’s healthcare clinics and maternity centers, particularly in emerging markets. Gynecological procedures require precise and focused illumination to ensure accurate diagnosis and treatment, making high-quality examination lighting critical. As a result, there is increasing demand for lights with features like adjustable light intensity, shadow-free focus, flexible positioning, and sterile handle controls, especially in colposcopy, pelvic exams, and minor gynecological surgeries. Furthermore, the growth of minimally invasive procedures in gynecology and the integration of LED lighting technology in colposcopes and mobile exam units contribute to market expansion.
Governments and healthcare organizations are also investing in improving maternal and reproductive health services, which is further boosting installations in primary care units, rural health camps, and urban OB/GYN facilities. For instance, the National Institutes of Health has announced a significant USD 200 million investment in new funding for women’s health research across its institutes and centers for fiscal year 2025.
End-use Insights
The hospital segment led the market with the largest revenue share of 49.65% in 2024. This is primarily due to the high patient volume, diverse clinical departments, and greater purchasing capacity found in hospital settings. Hospitals rely heavily on examination lights across various departments such as emergency rooms, outpatient clinics, intensive care units, and specialized diagnostic areas, driving consistent and large-scale demand. Moreover, hospitals are investing in advanced LED-based examination lights with features such as adjustable intensity, shadow reduction, and integrated camera systems, which enhance diagnostic accuracy and workflow efficiency. The shift toward smart hospitals and digitally integrated healthcare environments is also fueling the adoption of advanced lighting systems that can be synced with other medical technologies.
 To learn more about this report, Download Free Sample Report
The outpatient facilities segment is anticipated to register at the fastest CAGR over the forecast period. This rapid expansion is driven by the growing preference for minimally invasive procedures, preventive healthcare services, and daycare surgeries outside traditional hospital settings. Outpatient facilities are expanding due to rising demand for convenient, cost-effective care and shorter recovery times, especially in urban areas and emerging economies. These settings require versatile, energy-efficient, and space-saving lighting solutions, making them ideal candidates for mobile and LED-based examination lights. In addition, the lower operational budgets of outpatient centers make low-maintenance, long-lasting lighting systems particularly attractive.
Number of ASCs 2022 - 2023
Year
Total Number of ASCs
New ASCs
2022
6,153
221
2023
6,308
250
Source: Ambulatory surgical center services: Status report
Key U.S. Medical Examination Lights Company Insights
STERIS, Baxter, Stryker, Skytron, LLC, Burton Medical, LLC., and Getinge are some of the major players in the U.S. medical examination lights industry. The industry players are undertaking several strategic initiatives such as acquisitions, partnerships and collaborations. Moreover, the launch of novel products is anticipated to boost the competitive rivalry in the U.S. medical examination lights industry.
Key U.S. Medical Examination Lights Companies:
- STERIS
- Baxter
- Stryker
- Skytron, LLC
- Burton Medical, LLC.
- Getinge
- S.I.M.E.O.N. Medical GmbH & Co. KG
- Medical Illumination
- Brandon Medical
- Derungs Light AG
Recent Developments
-
In September 2024, S.I.M.E.O.N. Medical GmbH & Co. KG launched its latest innovation in clinical illumination-the Sim.LED 3000 series examination lights. This new range includes two advanced models: The Sim.LED 3000 F, featuring field size adjustment, and the Sim.LED 3000 MC, offering adjustable color temperature.
-
In August 2024, Stryker’s partnership with the Dr. Lorna Breen Heroes’ Foundation to improve clinician well-being by addressing burnout, reducing stigma around mental health, and advocating for systemic change in healthcare settings. As a Signature Partner of the Foundation’s “ALL IN: Caring for Caregivers” program, Stryker supports initiatives that foster safer, more supportive work environments for healthcare professionals across the U.S.
U.S. Medical Examination Lights Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 526.99 million
Revenue forecast in 2033
USD 759.42 million
Growth rate
CAGR of 4.67% from 2025 to 2033
Base year for estimation
2024
Historical data
2021 - 2023
Forecast period
2025 - 2033
Quantitative units
Revenue in USD million/billion, and CAGR from 2025 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, trends, and volume analysis
Segments covered
Product type, mounting type, application, end-use
Country Scope
U.S.
Key companies profiled
STERIS; Baxter; Stryker; Skytron, LLC; Burton Medical, LLC.; Getinge; S.I.M.E.O.N. Medical GmbH & Co. KG; Medical Illumination; Brandon Medical; Derungs Light AG
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
U.S.Medical Examination Lights Market Report Segmentation
This report forecasts revenue growth at regional and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the U.S. medical examination lights market report based on product type, mounting type, application, end-use.
-
Product Type Outlook (Revenue, USD Million, 2021 - 2033)
-
LED Examination Lights
-
Halogen Examination Lights
-
-
Mounting Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Wall-mounted
-
Ceiling-mounted
-
Mobile/ Floor-standing
-
Head Lights / Lamps / Clamp-on
-
Combination
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
General Examination
-
Gynecological Examination
-
Dental Examination
-
ENT Examination
-
Dermatology
-
Others
-
-
End-use Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospitals
-
Outpatient Facilities
-
Academic & Research Institutions
-
Others
-
Frequently Asked Questions About This Report
The U.S. medical examination lights market size was estimated at USD 506.73 million in 2024.
The U.S. medical examination lights market is expected to grow at a compound annual growth rate of 4.67% from 2025 to 2033 to reach USD 759.42 billion by 2033.
By product type, the LED examination lights segment led the U.S. medical examination lights market with the largest revenue share in 2024. This dominance is primarily attributed to LED technology's numerous advantages over traditional lighting systems, including superior illumination quality, enhanced energy efficiency, longer operational lifespan, and reduced heat emission.
Some key players operating in the U.S. medical examination lights market include STERIS, Baxter, Stryker, Skytron, LLC, Burton Medical, LLC., Getinge, S.I.M.E.O.N. Medical GmbH & Co. KG, Medical Illumination, Brandon Medical, Derungs Light AG.
The U.S. medical examination lights market is driven by the rising demand for healthcare services, fueled by an aging population and the increasing prevalence of chronic diseases. As the number of elderly patients requiring regular medical examinations grows, so does the need for reliable, high-quality illumination in clinical settings. Technological advancements, particularly the widespread adoption of LED lighting, have further accelerated market growth.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


