
- Home
- »
- Pharmaceuticals
- »
-
Vaccine Adjuvants Market Size, Share Report, 2026-2033GVR Report cover

Vaccine Adjuvants Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Pathogen, Adjuvant Emulsion, Particulate), By Application (Infectious Disease, Cancer), By Administration (Oral, Intradermal, Intranasal), By Region, And Segment Forecasts
Market Size, 2025
$3.9BMarket Estimate, 2026
$4.1BMarket Forecast, 2033
$5.9BCAGR, 2026–2033
5.6%Vaccine Adjuvants Market Summary
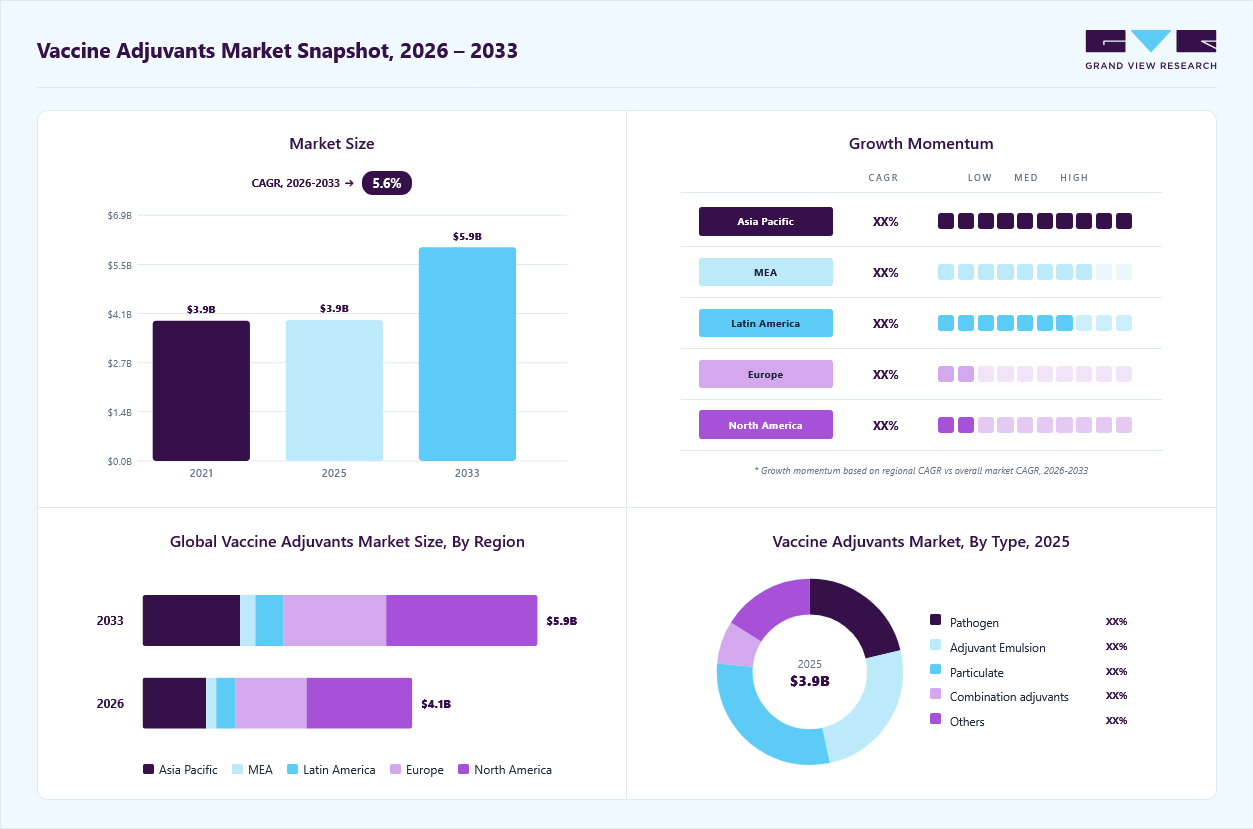
The global vaccine adjuvants market size was valued at USD 3.9 billion in 2025 and is projected to grow from USD 4.1 billion in 2026 to USD 5.9 billion by 2033, at a CAGR of 5.6% from 2026 to 2033. The market in North America dominated with a revenue share of 39.3% in 2025. The growth of the market is driven by the increasing demand for effective vaccines to combat emerging and re-emerging infectious diseases, as well as the rising prevalence of chronic conditions such as cancer.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Particulate segment held the largest market share of 29.8% in 2025.
- By application: Infectious disease segment held the largest market share of 61.8% in 2025.
- By administration: Intramuscular segment held the largest market share of 33.8% in 2025.
Regional Highlights
- Largest regional market: North America (39.3% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 3.9 Billion
- Estimated market size in 2026: USD 4.1 Billion
- Projected market size by 2033: USD 5.9 Billion
- CAGR (2026-2033): 5.6%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The growing recognition of adjuvants’ role in enhancing the efficacy, durability, and breadth of immune responses is propelling their adoption across both prophylactic and therapeutic vaccines. Advancements in immunology and molecular biology have enabled the development of next-generation adjuvants, including saponin-based adjuvants and toll-like receptor (TLR) agonists, which selectively target immune pathways and deliver improved safety and efficacy profiles. These innovations address the unmet need for vaccines capable of eliciting strong immune responses with reduced antigen doses, improving cost efficiency and scalability. For instance, in August 2025, Springer Nature published a review in Medicinal Chemistry Research (Volume 34, pages 1817-1832) highlighting that the widely studied saponin adjuvant QS-21 consists of approximately 65 percent QS-21-Api and 35 percent QS-21-Xyl isomers and has been incorporated into licensed vaccines such as Shingrix, Mosquirix, and Arexvy, with the authors reporting successful biosynthetic elucidation and comparing semi-synthetic yields, including engineered yeast production at roughly 0.0012 percent weight-by-weight versus about 0.0032 percent from natural sources, underscoring its role in enhancing antigen-specific antibody and cellular immune responses.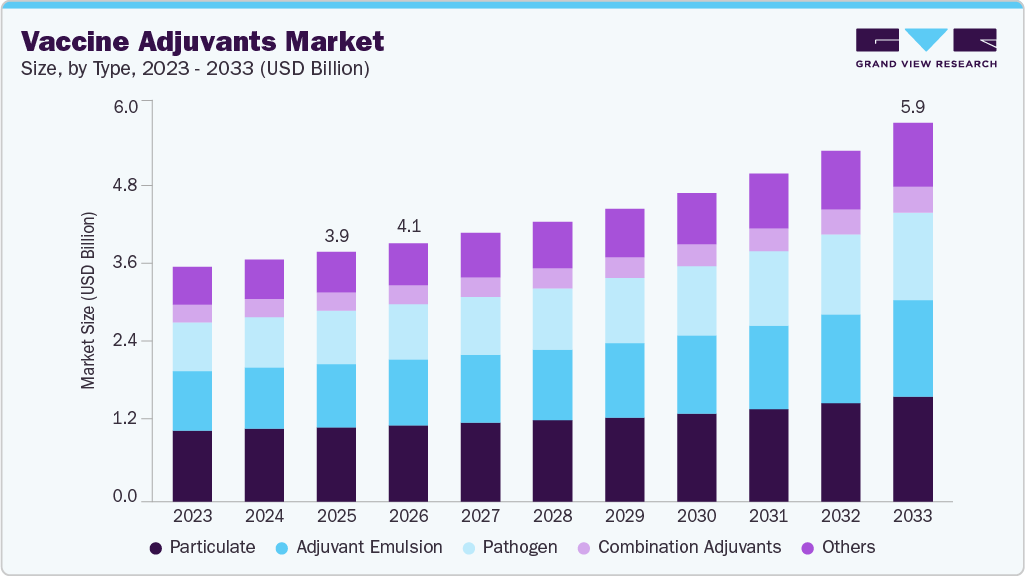 To learn more about this report, Download Free Sample Report
In addition, rising investments in vaccine research and development by governments, non-governmental organizations, and pharmaceutical companies are accelerating market growth. Global initiatives are playing a central role in expanding access to advanced adjuvanted vaccines, particularly in low- and middle-income countries. For instance, in June 2024, Gavi, the Vaccine Alliance approved its new five-year strategy, Gavi 6.0, committing to support countries in vaccinating more than 500 million additional children and adolescents, projecting the prevention of 8-9 million deaths, including 1.5 million through HPV vaccination, and expanding access to vaccines targeting 20+ diseases during the 2026-2030 period, with an added focus on climate-sensitive diseases such as dengue and the anticipated rollout of a new tuberculosis vaccine by the end of the strategy cycle. These initiatives, alongside heightened pandemic preparedness following COVID-19 and other outbreaks, have reinforced the need for adjuvant-enhanced vaccines that enable rapid development and deployment.
The market also benefits from favorable regulatory support, including expedited approval pathways and targeted funding for critical vaccine technologies. However, challenges such as high development costs, stringent regulatory requirements, and the need for extensive clinical validation remain key barriers. Despite these constraints, the expanding pipeline of adjuvant-based vaccines and growing global awareness of immunization’s role in public health continue to position the vaccine adjuvants industry for sustained growth over the forecast period.
Market Concentration & Characteristics
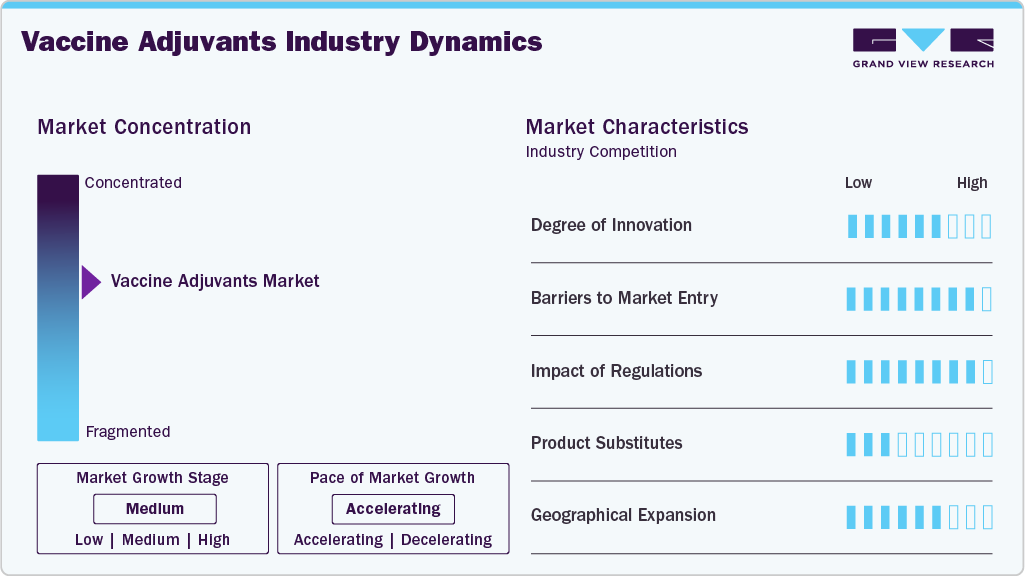
The vaccine adjuvants industry is characterized by a high degree of innovation, driven by continuous advances in immunology, molecular biology, and delivery systems. Companies are increasingly focusing on next-generation adjuvants such as saponin-based formulations, toll-like receptor (TLR) agonists, and emulsion systems designed to elicit targeted immune responses. Innovation is further supported by growing collaboration between pharmaceutical companies, biotechnology firms, and academic research institutes. The shift toward therapeutic and personalized vaccines has accelerated the development of adjuvants capable of stimulating both humoral and cellular immunity. Investment in platform technologies that can be applied across multiple vaccine candidates is also increasing. As a result, innovation remains a key competitive differentiator in the market.
Barriers to entry in the vaccine adjuvants industry are relatively high due to the complexity of development and stringent safety requirements. Adjuvants must demonstrate not only efficacy but also an excellent safety profile, which requires extensive preclinical and clinical testing. High research and development costs, long development timelines, and the need for specialized manufacturing capabilities further limit new entrants. Established players benefit from proprietary technologies, intellectual property protection, and long-standing relationships with vaccine manufacturers. In addition, scalability and consistency in large-scale production present significant challenges for smaller companies. These factors collectively favor well-capitalized and experienced market participants.
 To learn more about this report, Download Free Sample Report
Regulatory oversight plays a critical role in shaping the vaccine adjuvants industry, as adjuvants are evaluated as integral components of vaccine formulations. Regulatory agencies impose rigorous requirements related to safety, quality, and immunogenicity, often resulting in lengthy approval processes. However, favorable regulatory mechanisms such as accelerated pathways and emergency use provisions, particularly during public health crises, have supported market growth. Harmonization efforts across regions have improved transparency but have not fully eliminated regional differences in regulatory expectations. Post-marketing surveillance and pharmacovigilance obligations also add to compliance costs. Overall, regulation acts as both a safeguard and a structural constraint on market expansion.
The threat of direct product substitutes in market is moderate, as adjuvants perform a specialized function that cannot be easily replaced. Higher antigen doses, alternative delivery routes, or novel vaccine platforms may reduce reliance on traditional adjuvants in some cases. However, these alternatives often increase costs or introduce manufacturing and safety challenges. New technologies such as mRNA vaccines have reduced adjuvant use in specific applications, but many vaccines still depend on adjuvants to achieve robust and durable immune responses. Combination approaches that integrate adjuvants with advanced platforms are becoming more common. Consequently, substitutes complement rather than fully replace adjuvants.
Geographical expansion is a prominent characteristic of the market, supported by global immunization initiatives and rising vaccine demand in emerging economies. North America and Europe remain dominant due to strong research infrastructure and early adoption of advanced adjuvant technologies. Meanwhile, Asia Pacific, Latin America, and parts of Africa are experiencing faster growth driven by expanding healthcare access and government-backed vaccination programs. Partnerships with local manufacturers and technology transfer agreements are enabling wider regional penetration. International organizations and funding agencies are also facilitating deployment in low- and middle-income countries. This global expansion strategy is strengthening market reach and long-term growth potential.
Type Insights
The particulate segment held the largest market share of 29.8% in 2025, primarily due to its strong ability to enhance both humoral and cellular immune responses, making vaccines more effective. Its versatility allows formulation with various antigens and compatibility with multiple delivery systems, increasing adoption across diverse vaccine types. Growing demand for vaccines against complex and emerging pathogens has further driven this segment. For instance, in November 2023, MDPI published a review in vaccines detailing how particulate adjuvants, including virus‑like particles, liposomes, and polymeric micro‑ and nanoparticles, were developed as advanced vaccine adjuvants, highlighting the shift from traditional mineral salt adjuvants toward nano formulations that improve immune activation and safety. The article emphasized that these particulate systems can be tailored for enhanced antigen delivery and have demonstrated strong capacity to induce both humoral and cellular responses, reflecting their evolving role in modern vaccine design. Regulatory approvals and ongoing research in nanoparticle and liposome technologies further bolster market presence, while next-generation vaccines and combination therapies continue to support growth, making particulate adjuvants a preferred choice for pharmaceutical companies globally.
The pathogen-based adjuvants segment is projected to grow at the fastest CAGR of 6.74% over the forecast period, driven by its ability to mimic natural infections and elicit strong, targeted immune responses. Increasing focus on developing vaccines for challenging and emerging infectious diseases is fueling demand. Advances in recombinant and attenuated pathogen technologies have improved safety and efficacy, encouraging wider adoption. In addition, government initiatives and funding for infectious disease prevention are supporting market expansion. Growing awareness of the benefits of potent adjuvants in enhancing vaccine effectiveness, particularly in immunocompromised populations, is another key factor. Continuous research and development in pathogen-based formulations are expected to sustain rapid growth during the forecast period.
Application Insights
The infectious diseases segment accounted for the largest revenue share of 61.8% in 2025, driven by the increasing prevalence of viral and bacterial infections worldwide. Rising demand for vaccines against diseases such as influenza, hepatitis, and COVID-19 has significantly contributed to market growth. For instance, in July 2025, the World Health Organization published a fact sheet reporting that an estimated 254 million people were living with chronic hepatitis B infection in 2022, with 1.2 million new infections each year and about 1.1 million deaths mainly from cirrhosis and liver cancer, highlighting the global burden of the disease. The fact sheet also noted regional prevalence figures, including 97 million in the WHO Western Pacific Region, 65 million in the African Region, 61 million in South‑East Asia, 15 million in the Eastern Mediterranean, 11 million in Europe, and 5 million in the Americas, emphasizing the critical role of vaccination. Government vaccination programs and public health initiatives are further supporting adoption. Advances in adjuvant technologies that enhance immune response and vaccine efficacy are also fueling the segment. In addition, growing awareness among healthcare providers and patients about the benefits of vaccination is boosting uptake. Continuous research on novel adjuvants targeting infectious pathogens ensures that this segment remains the dominant application area in the vaccine adjuvants industry.
The cancer segment is expected to grow at the fastest CAGR of 6.03% during the forecast period, driven by the rising focus on therapeutic cancer vaccines and immunotherapies. Increasing incidence of various cancers globally is creating demand for adjuvants that enhance antigen-specific immune responses. Advances in oncology research, including the development of personalized vaccines and combination therapies, are supporting market expansion. Government funding and private investments in cancer vaccine development further accelerate growth. In addition, improvements in adjuvant formulations that boost safety and efficacy in oncology applications are encouraging adoption. Growing awareness among healthcare professionals about the potential of cancer vaccines is expected to sustain rapid growth in this segment.
Administration Insights
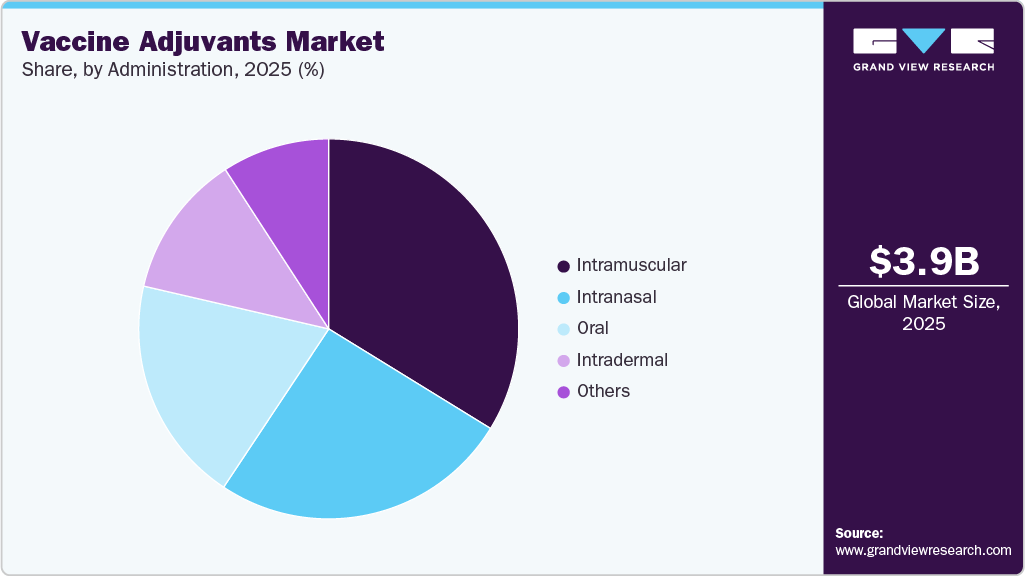
The intramuscular segment held the largest revenue share of 33.8% in 2025, driven by its established use in delivering vaccines effectively and safely across diverse patient populations. This route allows efficient absorption of adjuvanted vaccines, leading to strong immune responses. Widespread healthcare provider familiarity and existing infrastructure for intramuscular injections support its dominance. In addition, regulatory approvals and clinical guidelines favor intramuscular administration for most conventional and novel vaccines. The segment also benefits from ongoing development of vaccines requiring booster doses, which are conveniently administered intramuscularly. Rising demand for mass immunization programs and seasonal vaccination campaigns further reinforces the preference for this administration type in the vaccine adjuvants industry.
 To learn more about this report, Download Free Sample Report
The intradermal route is anticipated to be the fastest-growing segment, with a CAGR of 5.74% during the forecast period, owing to its ability to use lower vaccine doses while eliciting strong immune responses. This method targets abundant immune cells in the skin, enhancing efficacy and reducing side effects. Technological advancements in microneedle and jet injector devices are facilitating easier and less painful administration. Growing interest in dose-sparing strategies, especially during vaccine shortages or pandemics, is boosting adoption. In addition, intradermal vaccination supports rapid mass immunization campaigns and is increasingly preferred in research and clinical trials for novel vaccines. Rising awareness of its advantages among healthcare providers is expected to sustain strong growth.
Regional Insights
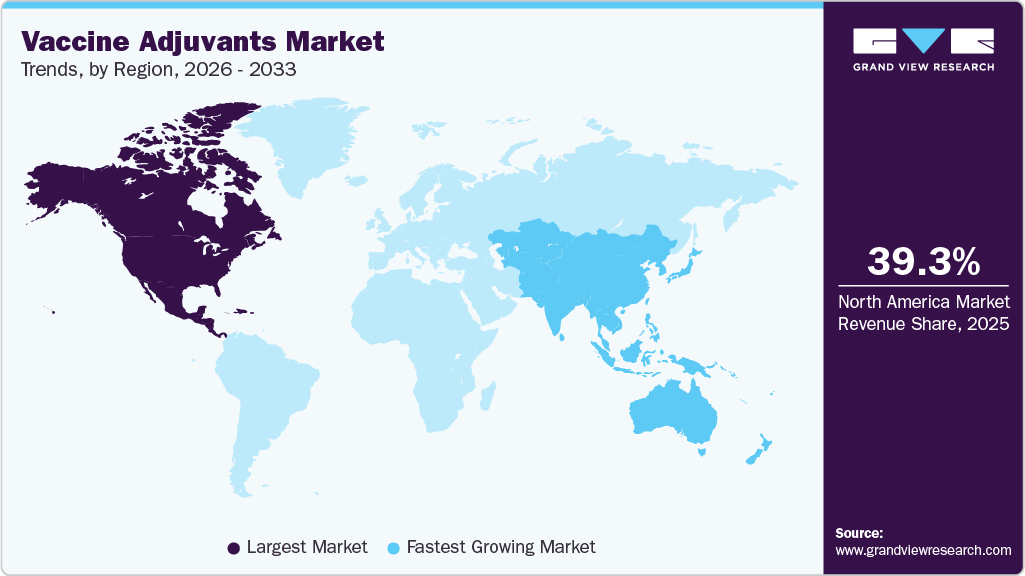
North America vaccine adjuvants industry dominated the global market in 2025 with the largest revenue share of 39.3%. This large share is attributed to its advanced vaccine development ecosystem and strong presence of leading pharmaceutical and biotechnology companies. The region benefits from high adoption of next-generation adjuvants in both prophylactic and therapeutic vaccines. Continuous innovation in immunology and formulation science has accelerated the use of complex adjuvant systems. A strong pipeline of vaccines targeting infectious diseases and cancer supports sustained demand. Well-established manufacturing infrastructure enables large-scale and consistent adjuvant production. High awareness of vaccine efficacy and safety further reinforces market leadership.
 To learn more about this report, Download Free Sample Report
U.S. Vaccine Adjuvants Market Trends
The U.S. vaccine adjuvants industry is experiencing steady growth due to the high adoption rate of adjuvant-containing vaccines for infectious diseases and cancer immunotherapies. Government-backed initiatives, such as the Biomedical Advanced Research and Development Authority (BARDA) programs, are accelerating the development of advanced adjuvant systems. For instance, in 2024, BARDA announced funding for multiple partnerships to explore innovative vaccine technologies, including adjuvants designed to combat emerging infectious diseases.
Europe Vaccine Adjuvants Market Trends
Europe vaccine adjuvants industry accounted for a significant revenue share in 2025, driven by high vaccination coverage and strong government support for vaccine R&D. Regulatory agencies such as the European Medicines Agency (EMA) are streamlining the approval process for novel adjuvants, focusing on safety and efficacy. The demand for advanced adjuvants is rising in response to the increasing burden of infectious and chronic diseases.
The vaccine adjuvants industry in the UK is witnessing growth driven by investments in innovative vaccine platforms and strategic collaborations. For instance, in 2024, the UK government announced funding for a multi-institutional project to develop new adjuvants targeting flu and respiratory syncytial virus (RSV) vaccines, addressing gaps in immunization for high-risk populations.
The vaccine adjuvants industry in Germany is expanding steadily due to government-backed R&D funding and the presence of leading pharmaceutical companies. Initiatives such as the German Center for Infection Research (DZIF) are fostering the development of cutting-edge adjuvant technologies. In 2024, additional funding was allocated to support vaccine innovation projects, particularly those incorporating novel adjuvant formulations.
The vaccine adjuvants industry in France is driven by public-private partnerships and increased focus on oncology vaccine development. In 2024, the French National Research Agency announced grants for projects exploring adjuvant systems in therapeutic cancer vaccines, signaling strong growth potential in this niche segment.
Asia-Pacific Vaccine Adjuvants Market Trends
Asia Pacific vaccine adjuvants industry is expected to register the fastest CAGR of 6.29% over the forecast period, driven by rising healthcare investments, growing immunization initiatives, and an increasing prevalence of vaccine-preventable diseases. The region is also witnessing significant R&D activities, with local players forming collaborations to enhance access to adjuvanted vaccines.
The vaccine adjuvants industry in Japan is growing rapidly, supported by government initiatives to address vaccine innovation. In 2024, Japan launched a national program to develop adjuvant-enhanced vaccines for emerging diseases, supported by collaborations with global organizations.
China vaccine adjuvants industry experienced rapid expansion driven by large-scale vaccine production and technological advancement. Domestic manufacturers increasingly invested in proprietary adjuvant platforms. Growing demand for improved vaccine efficacy supported adoption of complex adjuvants. Expanding research capabilities strengthened local innovation. Integration of adjuvants into both preventive and therapeutic vaccines increased market depth. Large population needs sustained long-term demand.
Latin America Vaccine Adjuvants Market Trends
The vaccine adjuvants industry in Latin America is gaining traction due to growing immunization campaigns, government investments, and partnerships with global vaccine manufacturers. Public health initiatives to combat diseases like dengue, Zika, and influenza are driving demand for adjuvanted vaccines in this region.
The vaccine adjuvants industry in Brazil is a key market in the region, benefiting from extensive vaccination programs and government support. In 2024, Brazil’s Ministry of Health partnered with leading vaccine developers to introduce adjuvanted vaccines for neglected tropical diseases, aiming to improve disease control outcomes.
Middle East and Africa Vaccine Adjuvants Market Trends
The vaccine adjuvants industry in the Middle East and Africa (MEA) is witnessing moderate growth, driven by the high disease burden and increased vaccination efforts. Partnerships with global organizations, such as Gavi and WHO, are improving access to advanced vaccines, including those containing novel adjuvants.
The vaccine adjuvants industry in Saudi Arabia is a growing market, bolstered by government-led immunization programs and investments in healthcare infrastructure. In 2024, the Ministry of Health announced new initiatives to improve vaccination coverage, focusing on introducing adjuvanted vaccines for influenza and pneumococcal diseases.
Key Vaccine Adjuvants Company Insights
GlaxoSmithKline plc and Novavax, Inc. lead the vaccine adjuvants industry with proprietary adjuvant platforms that enhance immune response and vaccine efficacy. Adjuvance Technologies, Inc. and Agenus, Inc. drive innovation through novel immunostimulatory compounds supporting dose-sparing and improved antigen presentation. SPI Pharma and Brenntag Biosector strengthen the market through formulation expertise, excipient supply, and scalable manufacturing support. CSL Limited integrates advanced adjuvants into biologics portfolios, while InvivoGen supports early-stage research and development.
Key Vaccine Adjuvants Companies:
The following are the leading companies in the vaccine adjuvants market. These companies collectively hold the largest market share and dictate industry trends.
- GlaxoSmithKline plc.
- Novavax, Inc.
- Adjuvance Technologies, Inc.
- SPI Pharma
- Agenus, Inc.
- CSL Limited
- InvivoGen
- Brenntag Biosector
Recent Developments
-
In September 2025, Novavax, Inc. announced that it had amended its collaboration and license agreement with Sanofi to broaden Sanofi’s license for use of Novavax’s Matrix-M adjuvant in Sanofi’s pandemic influenza vaccine candidate program, under terms that made Novavax eligible to receive up to USD 200 million for the first four products created by Sanofi using Matrix-M and up to USD 210 million in milestone payments for each subsequent product, plus ongoing royalties for all products utilizing the adjuvant.
-
In July 2025, GlaxoSmithKline plc announced that the US Food and Drug Administration had accepted an application to review an expanded indication for its adjuvanted respiratory syncytial virus vaccine, Arexvy, to include adults aged 18 to 49 at increased risk, noting that more than 125 million adults in the US were under 50 and an estimated 21 million of them had at least one risk factor for severe RSV, with an FDA decision anticipated in the first half of 2026.
-
In October 2023, SPI Pharma, Inc. reported that it had partnered with Q-Vant Biosciences, Inc. to expand Q-Vant’s proprietary 100 percent sustainable Q-SAP technology and sign an exclusive commercial agreement to accelerate global adoption of high-purity saponin adjuvants, noting that Quillaja saponin-based adjuvants were used in more than 17 human vaccine candidates and that the enhanced supply chain could support billions of doses of saponin-based vaccines per year.
Vaccine Adjuvants Market Report Scope
Report Attribute
Details
Market size in 2025
USD 3.9 billion
Estimated market size in 2026
USD 4.1 billion
Projected market size by 2033
USD 5.9 billion
Growth rate
CAGR of 5.6% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, application, administration, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Sweden; Norway; Japan; China; India; Australia; South Korea; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
GlaxoSmithKline plc.; Novavax, Inc.; Adjuvance Technologies, Inc.; SPI Pharma.; Agenus, Inc.; CSL Limited; InvivoGen; Brenntag Biosector
Customization scope
Free report customization (equivalent up to 8 analyst’s working days) with purchase. Addition or alteration to country, regional & segment scope
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Vaccine Adjuvants Market Report Segmentation
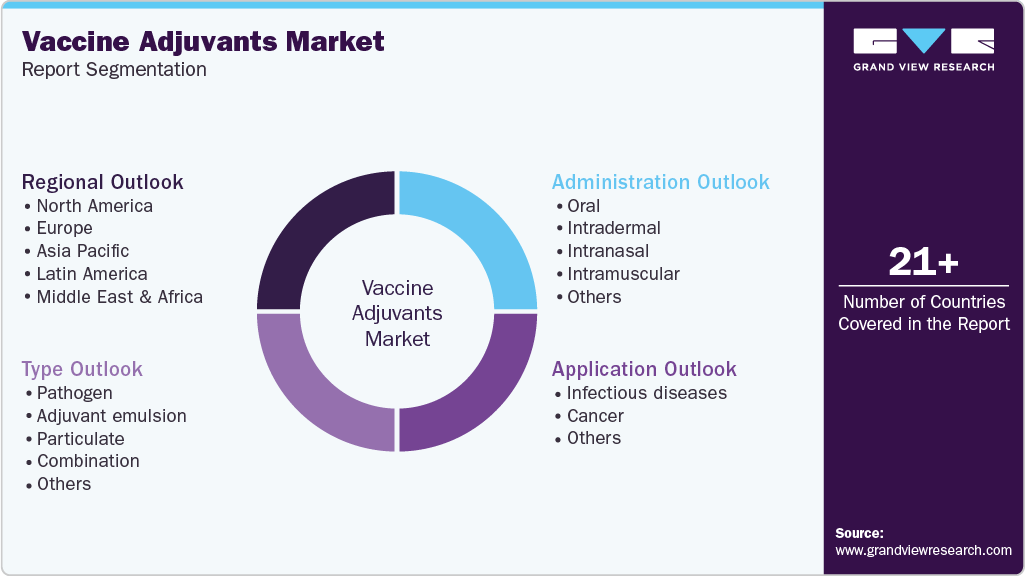
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global vaccine adjuvants market report based on type, application, administration, and region:
 To learn more about this report, Download Free Sample Report
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Pathogen
-
Adjuvant emulsion
-
Particulate
-
Combination
-
Others
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Infectious diseases
-
Cancer
-
Others
-
-
Administration Outlook (Revenue, USD Million, 2021 - 2033)
-
Oral
-
Intradermal
-
Intranasal
-
Intramuscular
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
Thailand
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Frequently Asked Questions About This Report
The growth of the Vaccine Adjuvants Market is driven by the increasing demand for effective vaccines to combat emerging and re-emerging infectious diseases, as well as the rising prevalence of chronic conditions such as cancer.
Asia Pacific is the fastest-growing region over the forecast period.
Particulate segment led with a 29.8% revenue share in 2025, while pathogen-based adjuvants is the fastest-growing segment.
Infectious disease segment led with a 61.8% revenue share in 2025, while cancer is the fastest-growing area.
Intramuscular segment led with a 33.8% revenue share in 2025 and intradermal route is the fastest-growing.
The global vaccine adjuvants market size was valued at USD 3.9 billion in 2025 and is estimated at USD 4.0 billion for 2026.
The global vaccine adjuvants market is expected to grow at a CAGR of 5.6% from 2026 to 2033, reaching USD 6.0 billion by 2033.
North America dominated with a 39.3% revenue share in 2025.
Key players include GlaxoSmithKline plc.; Novavax, Inc.; Adjuvance Technologies, Inc.; SPI Pharma.; Agenus, Inc.; CSL Limited; InvivoGen; and Brenntag Biosector.
About the Author(s)
Pharmaceuticals Research Team
Healthcare · PharmaceuticalsThis report was authored by the pharmaceuticals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the pharmaceuticals segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


