
- Home
- »
- Advanced Interior Materials
- »
-
Vapor Recovery Units Market Size, Share Report, 2026-2033GVR Report cover

Vapor Recovery Units Market (2026 - 2033)
Size, Share & Trends Analysis Report By Technology (Condensation, Adsorption, Membrane Separation, Absorption), By Application (Storage, Processing, Transportation/Loading), By End Use (Pharmaceutical, Oil & Gas), By Region, And Segment Forecasts
Market Size, 2025
$1.3BMarket Estimate, 2026
$1.4BMarket Forecast, 2033
$1.9BCAGR, 2026–2033
5.1%Vapor Recovery Units Market Summary
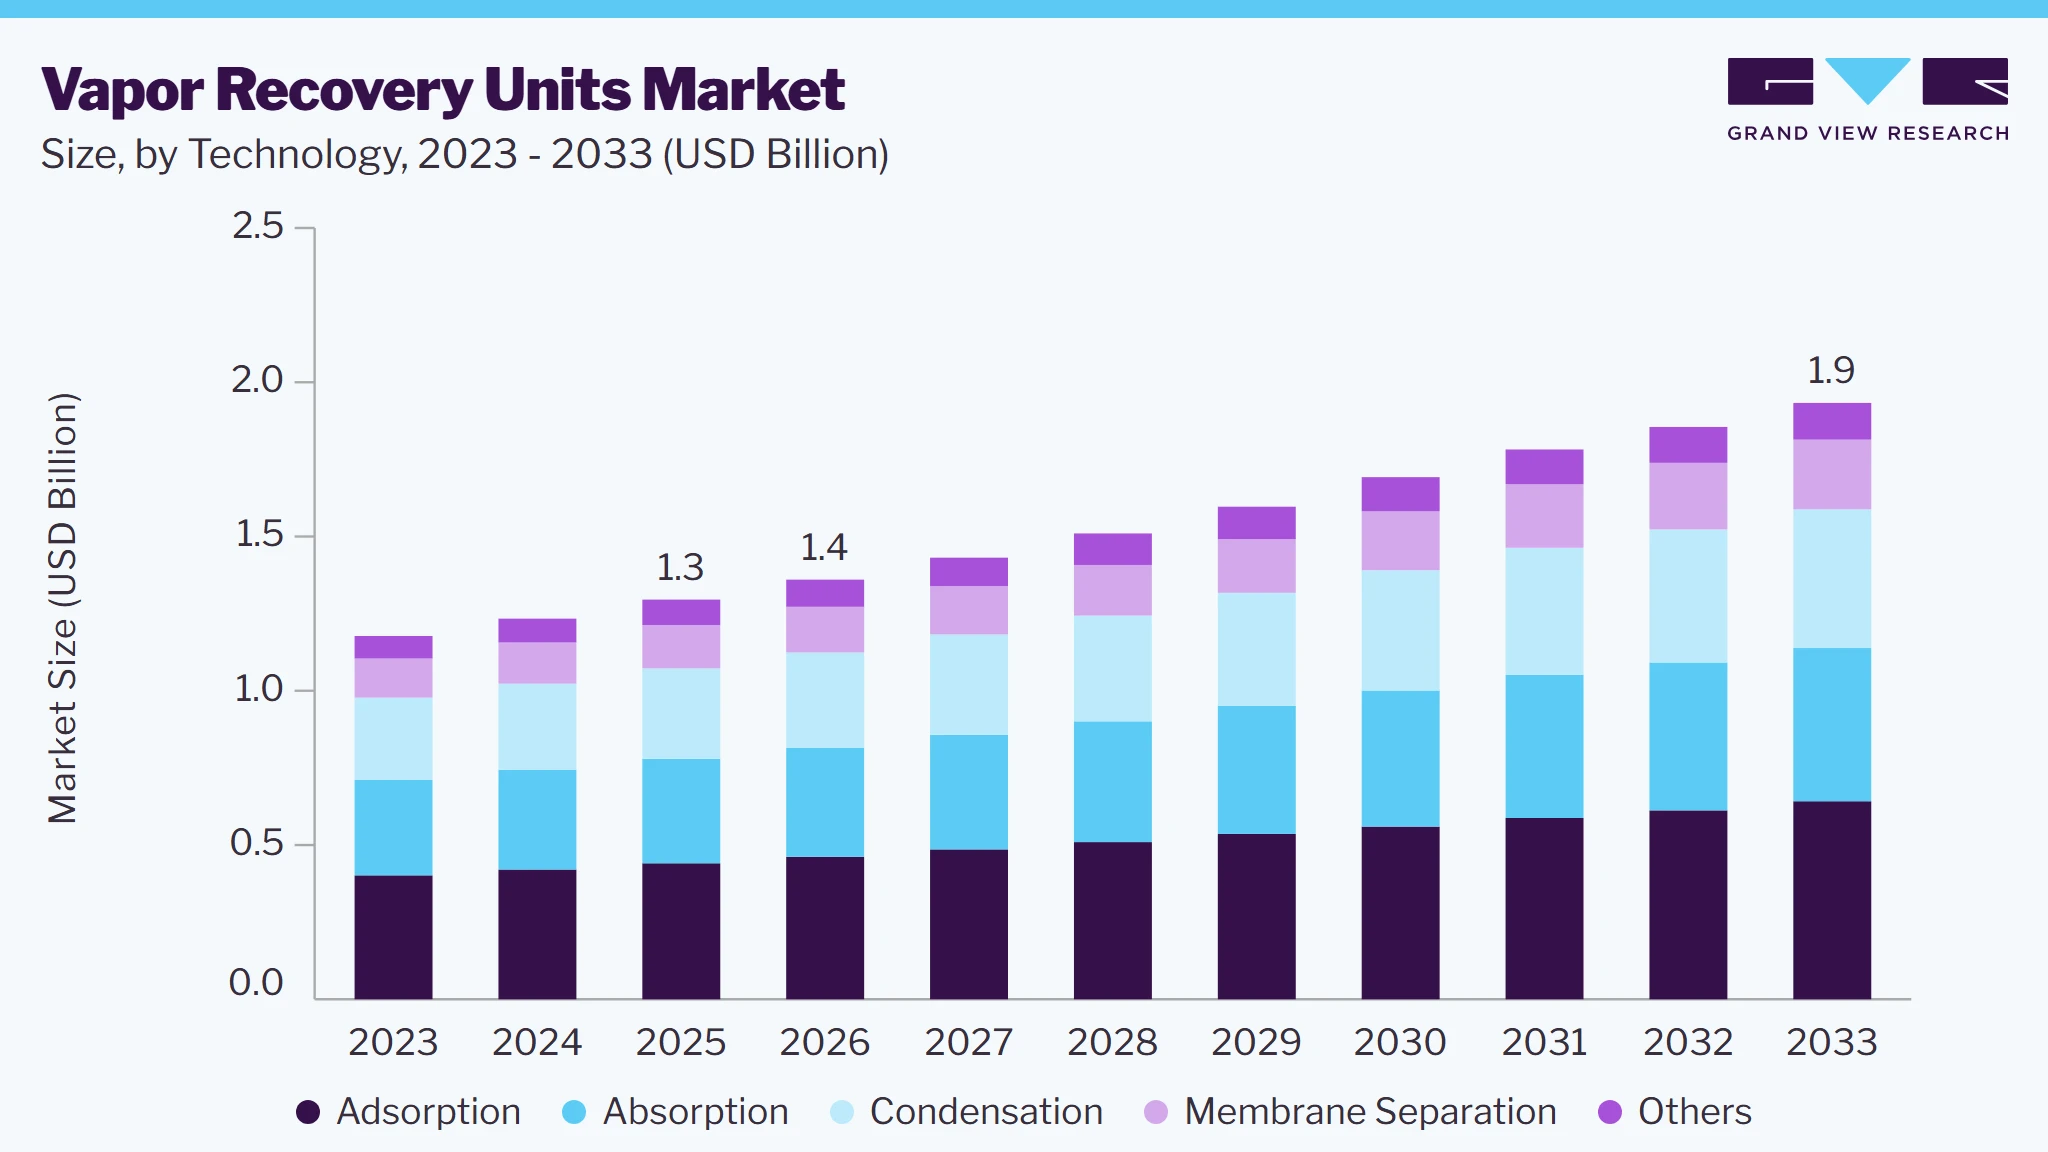
The global vapor recovery units market size was valued at USD 1.3 billion in 2025 and is projected to grow from USD 1.4 billion in 2026 to USD 1.9 billion by 2033, at a CAGR of 5.1% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 38.6% in 2025. The increasing focus on controlling VOC, methane, and hazardous air pollutant emissions is driving the adoption of vapor recovery units across oil & gas, chemical, and petroleum-handling facilities.
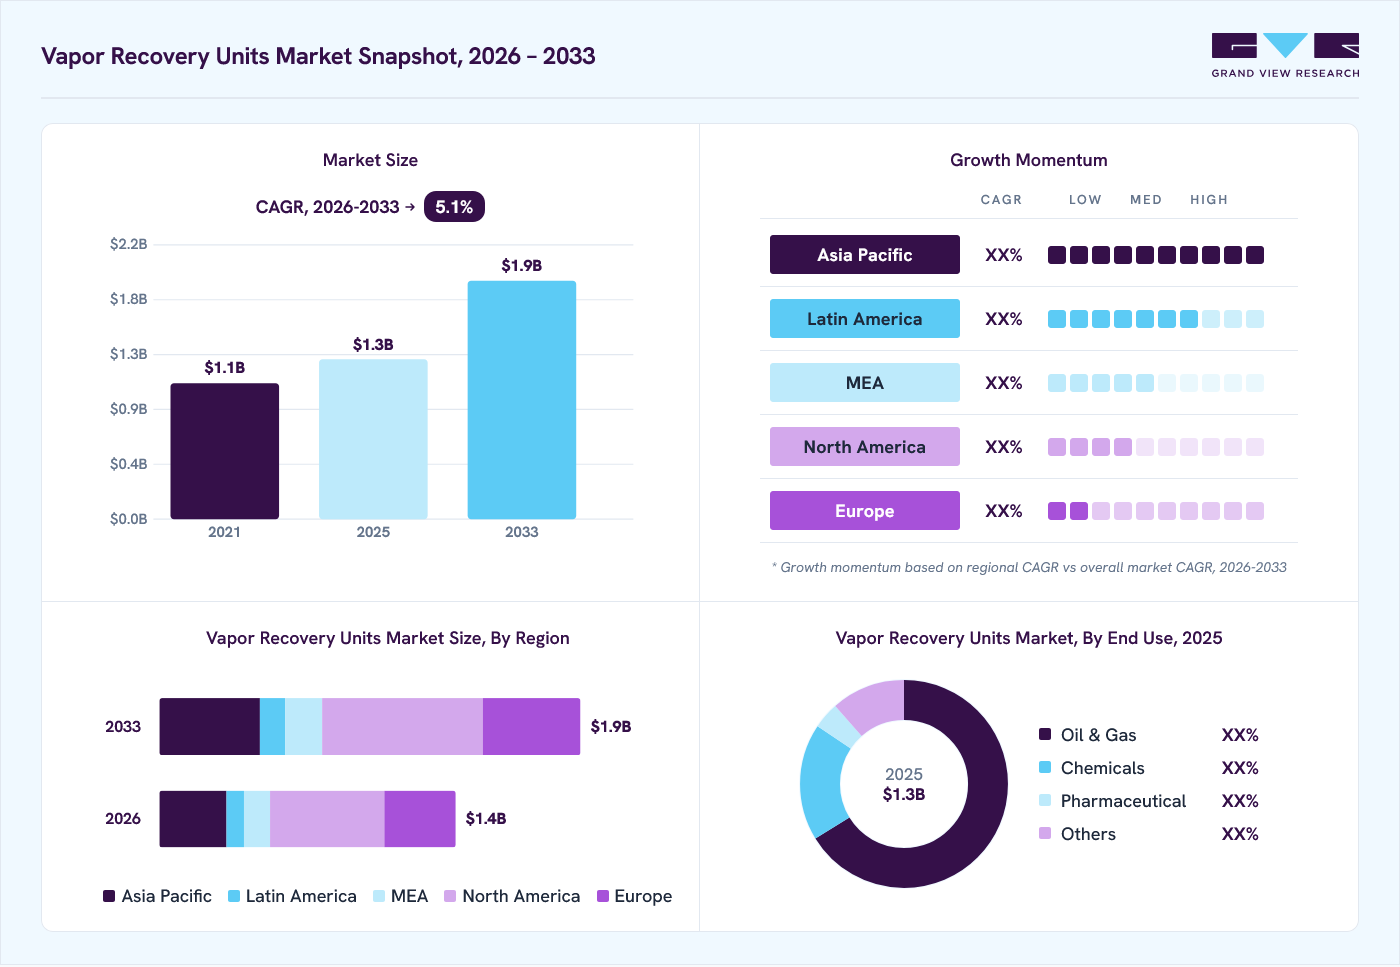 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By technology: Adsorption segment led the market with the largest revenue share of 34.0% in 2025.
- By application: Storage segment led the market with the largest revenue share of 39.0% in 2025.
- By end use: Oil & gas segment led the market with the largest revenue share of 66.2% in 2025.
Regional Highlights
- Largest regional market: North America (38.6% revenue share, 2025)
- Fastest growing market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 1.3 Billion
- Estimated market size in 2026: USD 1.4 Billion
- Projected market size by 2033: USD 1.9 Billion
- CAGR (2026-2033): 5.1%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Storage tanks, processing units, and loading terminals can release hydrocarbon vapors during storage and product transfer, encouraging operators to install recovery systems as environmental requirements become more stringent.
 To learn more about this report, Download Free Sample Report
The growing emphasis on recovering valuable hydrocarbons and improving operational efficiency is also supporting market expansion. Recovered vapors can contain methane, NGLs, and other hydrocarbons that can be reused as fuel, returned to the production process, or directed to sales and processing systems. At the same time, expansion of oil & gas production, storage infrastructure, fuel terminals, and chemical processing facilities is creating more locations where vapor losses occur, increasing the need for recovery systems.
Market Dynamics
The industry is influenced by a combination of emission-control requirements, expansion of oil & gas and chemical processing activities, the economic value of recovered hydrocarbons, technology improvements, and capital investment considerations. Demand is particularly shaped by the need to manage vapors generated during the storage, processing, and transportation of volatile liquids. At the same time, the economics of recovering vapors, availability of infrastructure for their reuse or sale, equipment complexity, and site-specific operating conditions affect adoption decisions.
Growing emphasis on reducing VOC, methane, and other hydrocarbon emissions is a major driver for VRU adoption. Storage tanks, processing facilities, and transfer operations can release vapors containing methane, VOCs, NGLs, and other pollutants. Increasing environmental requirements are encouraging operators to capture these emissions through recovery systems rather than venting them directly into the atmosphere. VRUs can also provide an economic benefit by recovering hydrocarbons that can subsequently be sold, processed, or used as onsite fuel. This is further strengthened by the broader push toward more efficient utilization of produced hydrocarbons. Recovered vapor can be routed to sales pipelines, production systems, or onsite fuel applications, creating value from material that would otherwise be lost. This combination of environmental compliance and product recovery improves the business case for VRU installation, particularly at facilities with steady vapor generation and an accessible outlet for recovered gas.
High upfront investment and the need for site-specific system design can limit VRU adoption, particularly among smaller facilities. Project economics depend on vapor volume, gas composition, compressor capacity, electrical availability, sales-line pressure, installation requirements, and the availability of an outlet for recovered vapors. Facilities with intermittent or low vapor generation may not generate sufficient recovered-product value to justify the investment, while remote sites may face additional infrastructure constraints.
The increasing adoption of modular, skid-mounted, automated, and digitally monitored VRU systems presents an important market opportunity. Manufacturers are developing systems that can operate more efficiently across changing vapor loads while enabling easier deployment at remote production, storage, and processing facilities. Variable-speed compression, improved monitoring, and integration with multiple low-pressure vapor sources can further improve recovery performance and operational flexibility.
Market Concentration & Characteristics
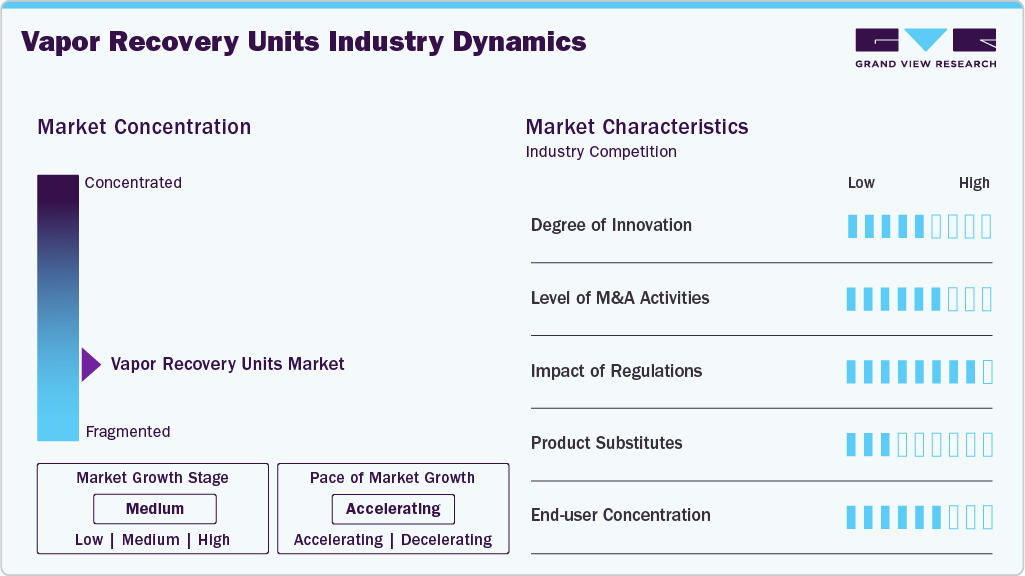
The industry is fragmented, with competition distributed among global equipment manufacturers, specialized technology providers, and regional system integrators. Market participants offer solutions tailored to different vapor compositions, operating conditions, recovery requirements, and end-use applications. Variations in environmental regulations, facility configurations, and customer requirements across regions also encourage the presence of specialized and regional suppliers, limiting market dominance by a small group of players.
The industry has a moderate-to-high degree of innovation, with technological development focused on improving vapor capture efficiency, handling low-pressure streams, reducing energy consumption, and enabling more flexible operation. Advances in compression systems, membrane separation, adsorption, condensation, and digital monitoring are helping VRUs accommodate different vapor compositions and operating conditions. Modular and skid-mounted designs are also improving deployment flexibility, particularly across remote oil & gas and processing facilities.
 To learn more about this report, Download Free Sample Report
Regulation has a high impact on the market because emission-control requirements are a major factor influencing VRU installation. Governments and environmental agencies are tightening controls on VOCs, methane, and other hydrocarbon emissions from storage, processing, and transportation activities. These requirements encourage operators to capture and recover vapors rather than vent them, making regulatory compliance an important consideration when selecting vapor recovery technologies.
The industry has a high degree of end-user concentration, with demand strongly centered on the oil & gas industry because hydrocarbon production, storage, processing, and transfer generate substantial volumes of recoverable vapors. Chemical and petrochemical facilities represent another important customer group, while pharmaceutical and other industrial users account for a smaller portion of demand. This concentration makes investment cycles, production activity, and environmental requirements within hydrocarbon-intensive industries particularly important to market development.
Analyst Perspective
The industry is positioned for steady expansion as industries increasingly combine emission control with recovery of valuable hydrocarbons and solvents. Demand remains closely linked to oil & gas storage, processing, and transportation activities, while chemical and other industrial applications provide additional growth opportunities. From a technology perspective, adsorption remains well established, while membrane separation and digitally monitored, modular systems are gaining attention for applications requiring greater flexibility and efficiency. North America benefits from mature infrastructure and established regulatory requirements, whereas Asia Pacific offers stronger expansion potential as refining, petrochemical, and storage infrastructure develop.
Technology Insights
The adsorption segment dominated the market with a revenue share of 34.0% in 2025, supported by its established use for capturing hydrocarbon vapors and VOCs across storage, processing, and loading applications. Adsorption-based systems typically use porous materials such as activated carbon to capture vapor molecules from gas streams, providing reliable recovery performance across varying operating conditions. Their proven technology, relatively straightforward integration with existing facilities, and suitability for emission-control applications continue to support widespread adoption.
The membrane separation segment is projected to grow at a CAGR of 6.2% over the forecast period, driven by increasing demand for compact, energy-efficient, and continuous vapor recovery solutions. Membrane systems selectively separate hydrocarbon components from gas streams and can be integrated with compression or other recovery technologies to improve overall performance. Their suitability for applications with limited space, changing vapor loads, and remote or modular facilities is encouraging greater adoption, while ongoing improvements in membrane materials are helping enhance recovery efficiency and reduce lifecycle costs.
Application Insights
The storage applications segment dominated the market with a revenue share of 39.0% in 2025, primarily because storage tanks are a major source of hydrocarbon and VOC vapors generated through tank breathing and working losses. VRUs installed on crude oil, condensate, and other liquid-hydrocarbon storage tanks capture low-pressure vapors and route the recovered gases for fuel use, processing, or sale. The expansion of storage terminals and continued emphasis on reducing emissions from tank operations are supporting sustained demand for VRUs in this application.
The processing segment is expected to witness strong growth at a 5.7% CAGR, as oil & gas, refining, and chemical facilities increasingly seek to recover vapors generated during separation, treatment, and other processing activities. The adoption of low-pressure and variable-speed recovery systems is improving the ability to capture valuable hydrocarbon gases under changing process conditions. Growing investments in processing capacity and the focus on recovering usable hydrocarbons while reducing emissions are further supporting the adoption of VRUs in processing facilities.
End Use Insights
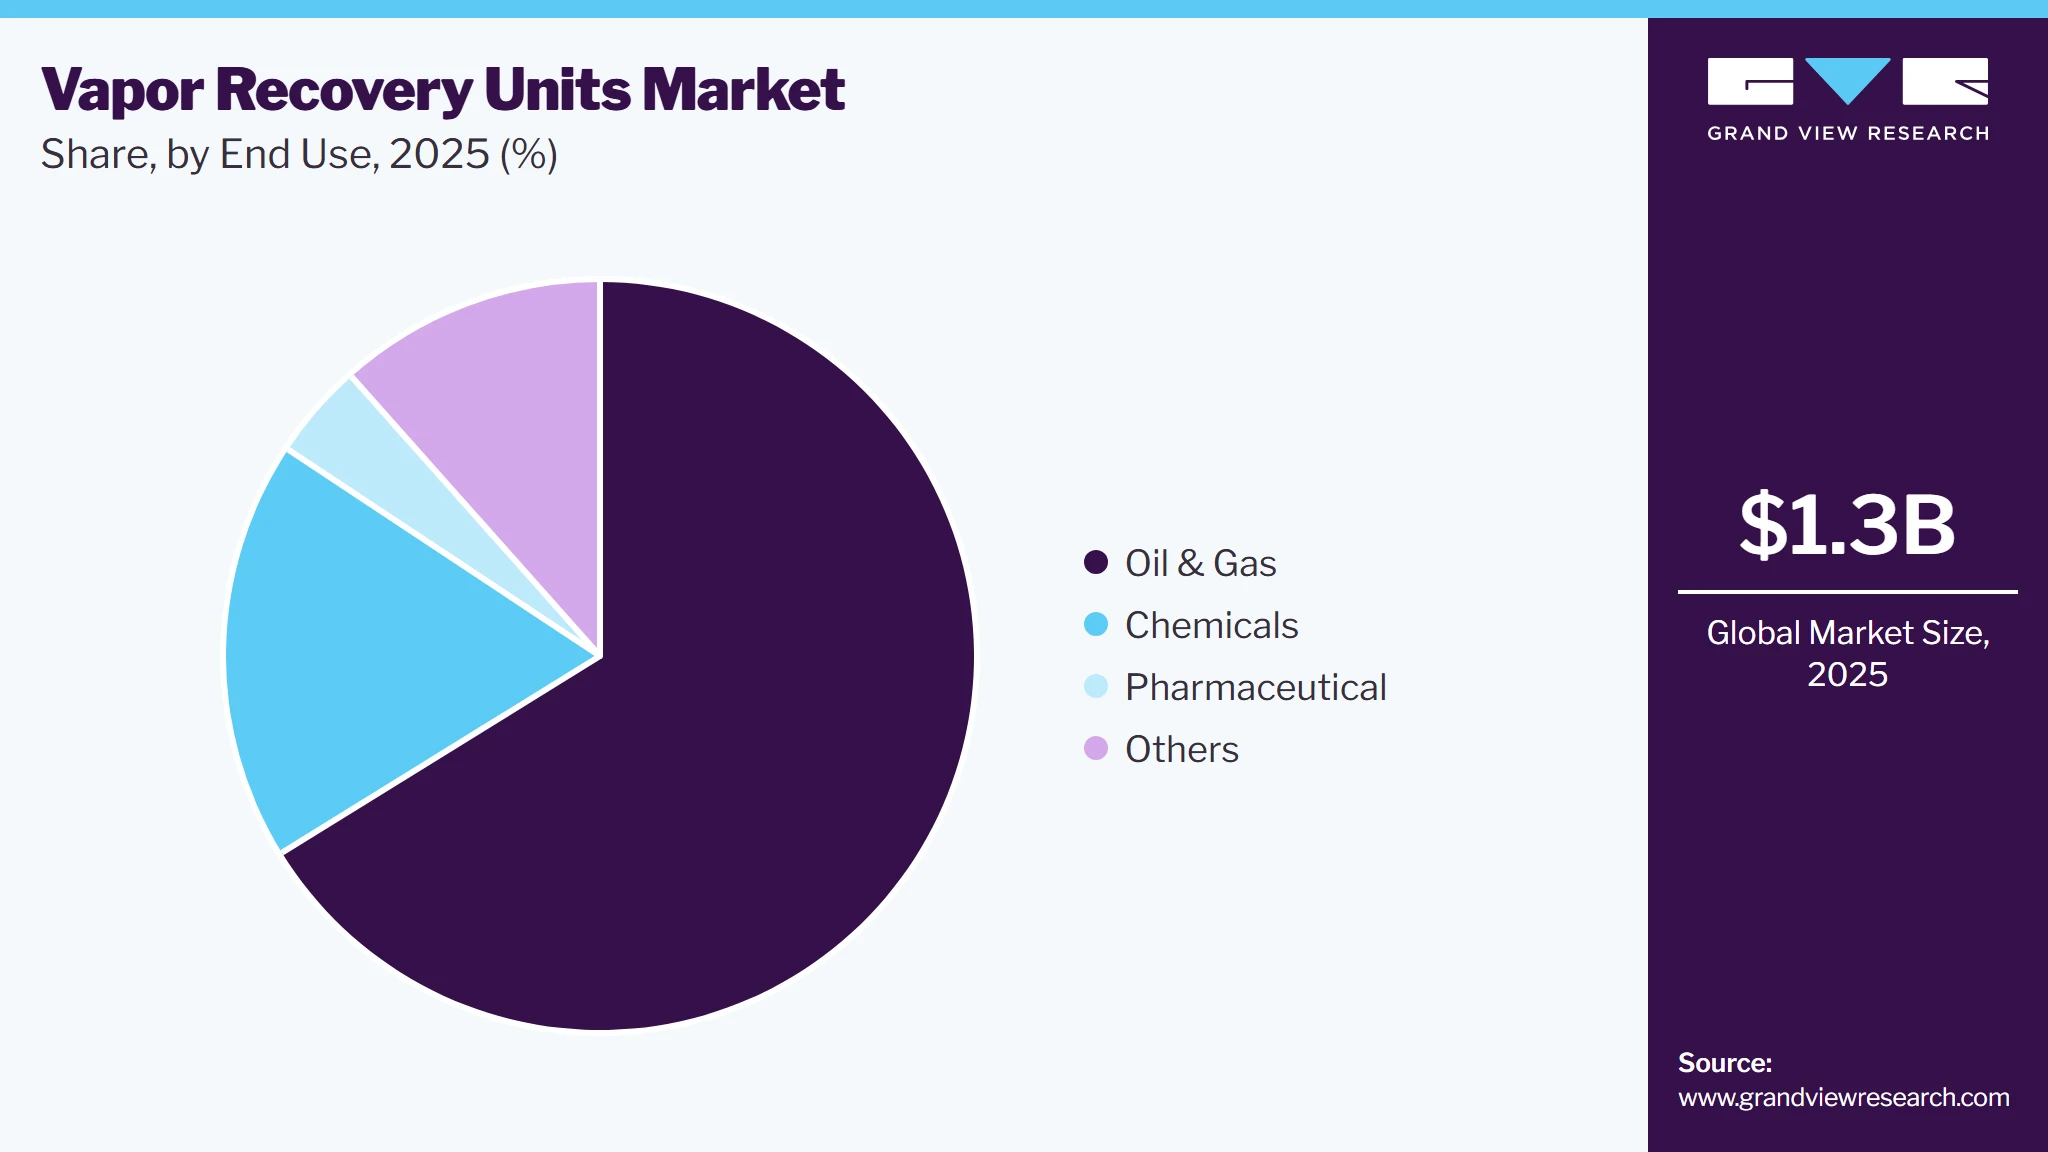
The oil & gas segment led the market with the largest revenue share of 66.2% in 2025, owing to the extensive generation of hydrocarbon vapors during crude oil and condensate production, storage, processing, and transportation. VRUs are widely deployed at storage tanks and other low-pressure emission sources to capture methane, VOCs, NGLs, and other recoverable hydrocarbons. The ability to reduce emissions while recovering valuable hydrocarbon streams continues to support strong adoption across the oil & gas industry.
 To learn more about this report, Download Free Sample Report
The pharmaceutical segment is expected to grow at the fastest CAGR of 5.7% from 2026 to 2033, supported by increasing solvent consumption and greater emphasis on controlling VOC emissions from pharmaceutical manufacturing processes. Production of APIs and other pharmaceutical products can generate solvent-laden vapors, creating demand for adsorption, condensation, and other recovery technologies. The opportunity to recover and reuse valuable solvents while improving environmental compliance is further encouraging pharmaceutical manufacturers to adopt vapor recovery solutions.
Regional Insights
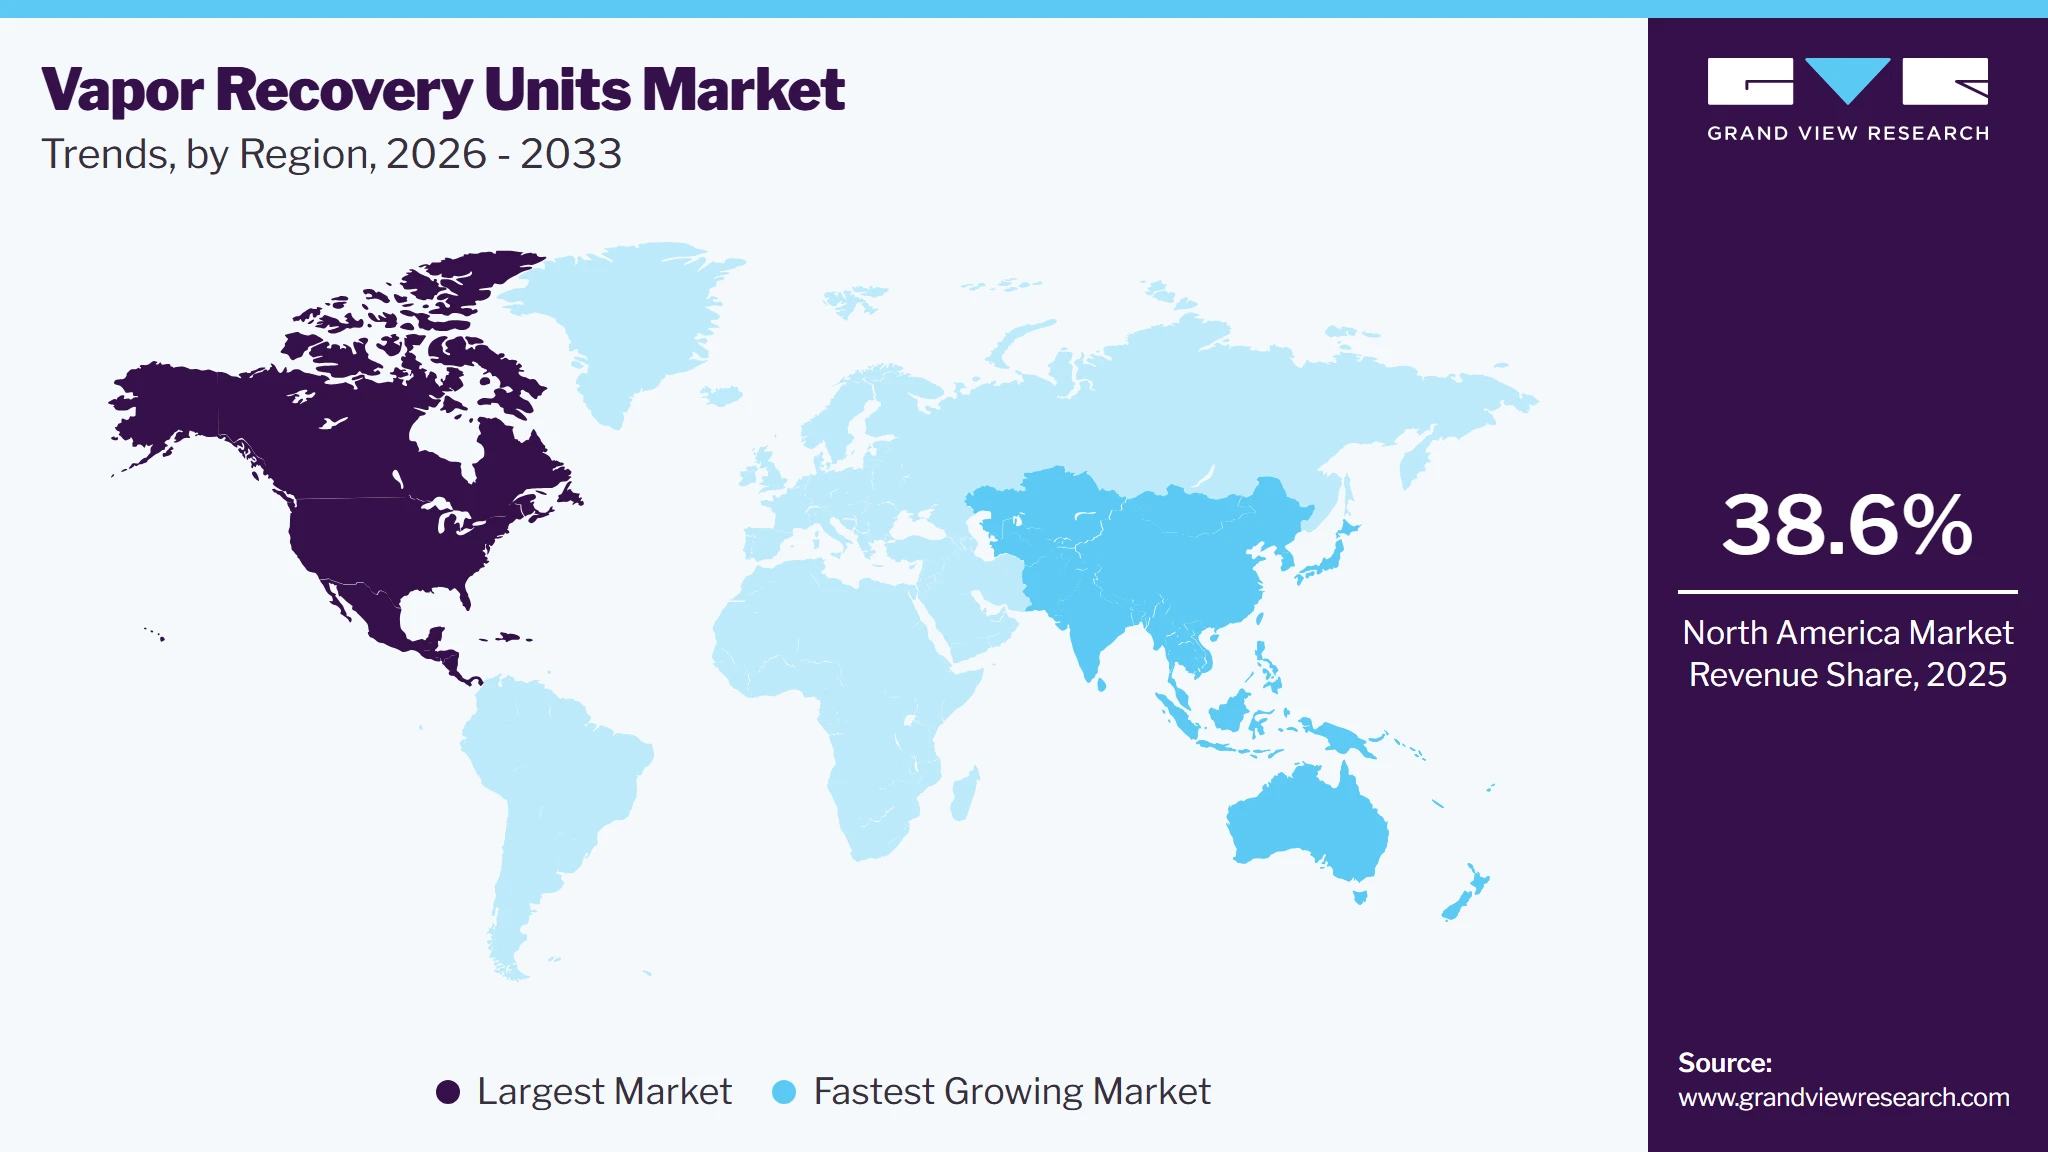
The North America vapor recovery units market dominated with the largest revenue share of 38.6% in 2025, supported by its well-established oil & gas value chain, extensive storage and transportation infrastructure, and strong emphasis on controlling hydrocarbon emissions. The region’s large installed base of production facilities, tank farms, refineries, and terminals creates continued demand for both new VRU installations and upgrades to existing systems. Established regulatory frameworks and the commercial value of recovered hydrocarbons further strengthen adoption.
 To learn more about this report, Download Free Sample Report
The vapor recovery units market in the U.S. is supported by its substantial oil and natural gas production and extensive network of hydrocarbon infrastructure. According to the U.S. Energy Information Administration (EIA), crude oil output averaged 13.6 million barrels per day in 2025, marking a 3% increase from the previous year. Natural gas production also reached a record 118.5 Bcf/d, strengthening the need for vapor recovery systems across production sites, storage facilities, processing plants, and transportation infrastructure.
The Canada vapor recovery units market is expected to see steady growth, supported by higher oil production and improving transportation infrastructure. According to the Canada Energy Regulator (CER), crude oil and equivalent production averaged 5.4 million barrels per day in 2025, up from 5.1 million barrels per day in 2024. Alberta contributed 83.8% of the country’s total production, making it a key market for oil and gas equipment. The expansion of pipeline capacity is also increasing hydrocarbon movement, supporting demand for VRUs in production, storage, processing, and transportation facilities.
Europe Vapor Recovery Units Market Trends
The Europe vapor recovery units market is expected to witness steady growth as environmental compliance and modernization of downstream infrastructure remain important investment priorities. Demand is supported by established refining, chemical, storage, and port facilities that require effective control of vapors during handling and transfer operations. The region’s focus on methane and VOC reduction is also encouraging upgrades and retrofits involving more efficient recovery technologies.
The Germany vapor recovery units market is supported by its strong industrial base, particularly in chemicals, oil & gas processing, and fuel handling. The country’s focus on reducing VOC emissions and improving industrial efficiency is encouraging the adoption of vapor recovery systems across storage, processing, and transportation facilities. Modernization of industrial infrastructure and the use of automated emission-control technologies are also supporting market development.
The vapor recovery units market in France is supported by its established chemical, pharmaceutical, refining, and fuel-storage industries. Growing efforts to control industrial emissions are encouraging companies to adopt technologies that can capture and recover vapors generated during production and material handling. Expansion of chemical and pharmaceutical activities is also creating additional applications for VRUs, particularly where volatile solvents and hydrocarbons are handled.
Asia Pacific Vapor Recovery Units Market Trends
The vapor recovery units market in Asia Pacific is the fastest-growing market, driven by rapid industrialization, expanding refining and petrochemical capacity, and increasing fuel consumption. Countries such as China, India, South Korea, and those in Southeast Asia are investing in energy infrastructure while progressively strengthening controls on VOC and hydrocarbon emissions. Expansion of terminals, fuel-storage facilities, and manufacturing activities is creating additional opportunities for VRU deployment.
The China vapor recovery units market is supported by its large refining, petrochemical, and industrial base. According to China’s National Bureau of Statistics, crude oil production reached 216.1 million tonnes in 2025, while crude oil imports totaled 577.7 million tonnes. The country’s extensive network of refineries, storage facilities, and chemical plants creates significant opportunities for vapor recovery systems, particularly as industries focus on improving hydrocarbon utilization and controlling emissions.
The vapor recovery units market in India is expected to witness strong growth, driven by expanding refining capacity, rising fuel demand, and continued development of petroleum infrastructure. According to India’s Ministry of Petroleum and Natural Gas, the country had 258.1 million tonnes per year of installed refining capacity across 22 operational refineries as of 2026. India’s growing refining and petroleum-product trade, along with increasing attention to emission control, is creating opportunities for VRUs across refineries, storage terminals, processing facilities, and loading operations.
Middle East & Africa Vapor Recovery Units Market Trends
The vapor recovery units market in the Middle East & Africa is supported by investments in oil & gas processing, export terminals, refineries, and large-scale storage infrastructure. In the Middle East, efforts to reduce routine flaring and improve hydrocarbon utilization are creating opportunities for vapor recovery systems, while African markets are gradually increasing their focus on emissions management across petroleum facilities. Adoption will vary across countries depending on regulatory enforcement, infrastructure development, and project economics.
The Saudi Arabia vapor recovery units market is supported by its large oil and gas production base and continued investment in processing infrastructure. According to Saudi Aramco, total hydrocarbon production reached 12.9 million barrels of oil equivalent per day in 2025, while gas production increased to 11.4 billion standard cubic feet per day. Ongoing development of gas processing facilities and efforts to reduce emissions and improve hydrocarbon utilization are creating opportunities for vapor recovery systems across production, processing, storage, and transportation operations.
Latin America Vapor Recovery Units Market Trends
The vapor recovery units market in Latin America is projected to experience gradual growth as oil-producing countries expand and modernize production, refining, storage, and fuel-distribution infrastructure. Increasing attention toward reducing product losses and controlling emissions is encouraging the adoption of vapor recovery solutions at terminals and hydrocarbon-handling facilities. Brazil and Argentina are expected to provide important opportunities as their energy infrastructure continues to develop.
The Brazil vapor recovery units market is supported by its expanding oil and natural gas industry and growing offshore production. According to Brazil’s National Agency of Petroleum, Natural Gas and Biofuels (ANP), the country’s oil production averaged 3.77 million barrels per day in 2025, an increase of 12.3% from 2024, while natural gas output reached a record 179 million cubic meters per day. The continued development of pre-salt fields, along with investments in production and processing infrastructure, is creating opportunities for vapor recovery systems across storage, processing, and transportation facilities.
Key Vapor Recovery Units Companies Insights
Some of the key players operating in the market include John Zink Company, LLC, Zeeco, Inc., and Cimarron Energy, Inc.
-
John Zink is a global provider of combustion and emissions-control solutions, offering technologies for industries such as refining, petrochemicals, gas processing, terminals, and marine operations. Its portfolio includes Vapor Recovery Units (VRUs), vapor combustion systems, crude oil vapor recovery systems, and marine vapor emission control systems, supporting the capture and management of hydrocarbon vapors. The company also provides equipment upgrades, replacement parts, and technical support to help improve system reliability and emissions performance.
-
Zeeco, Inc. is a global provider of advanced combustion and environmental solutions, serving industries such as refining, oil & gas, petrochemicals, LNG, power, pharmaceuticals, and biogas. Founded in 1979 and headquartered in Tulsa, Oklahoma, the company offers a broad portfolio that includes vapor control systems, flare systems, thermal oxidizers, industrial burners, and combustion electronics. Its solutions are designed to help customers reduce emissions, improve process efficiency, and meet environmental requirements.
Key Vapor Recovery Units Companies
The following key companies have been profiled for this study on the vapor recovery units market include:
-
John Zink Company, LLC
-
Zeeco, Inc.
-
Cimarron Energy, Inc.
-
Dover Corporation
-
Petrogas Systems
-
BORSIG GmbH
-
Diamond Key International
-
ALMA Group
-
Kappa GI S.r.l.
-
Kilburn Engineering Ltd.
-
Symex Technologies LLC
-
VOCZero Ltd.
-
SCS Technologies
-
S&S Technical, Inc.
-
Tecam Group
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (e.g., John Zink Company, LLC; Zeeco, Inc.; Cimarron Energy, Inc.; Dover Corporation; BORSIG GmbH)
- Expand integrated vapor recovery and emission-control portfolios for oil & gas, storage, processing, and loading applications.
- Invest in automation, monitoring, and advanced recovery technologies to improve system efficiency.
- Strengthen regional presence through large project execution capabilities and established distribution networks.
- Strong brand recognition and long-standing relationships with major industrial customers.
- Broad product portfolios that support different vapor loads, applications, and operating conditions.
- Greater ability to execute large-scale and complex VRU projects across multiple regions.
- Higher operating and project costs compared with smaller specialized suppliers.
- Large organizational structures can make customized solutions and decision-making less flexible.
- Strong exposure to capital-intensive oil & gas and downstream projects can make demand sensitive to industry investment cycles.
Emerging & Regional Players (e.g., Petrogas Systems; Diamond Key International; ALMA Group; Kappa GI S.r.l.; Kilburn Engineering Ltd.; Symex Technologies LLC; VOCZero Ltd.; SCS Technologies)
- Focus on customized VRU systems for specific storage, processing, and loading requirements.
- Target regional oil & gas and industrial customers through application-focused solutions.
- Develop modular and compact systems that can be deployed efficiently at smaller or remote facilities.
- Greater flexibility in customizing systems for specific customer requirements.
- Ability to compete through localized engineering, pricing, and faster project response.
- Specialized expertise in selected recovery technologies and applications provides differentiation.
- Smaller geographic coverage and less established international distribution networks.
- Lower brand visibility when competing for large multinational projects.
- More limited financial and R&D resources compared with established global suppliers.
Recent Developments
-
In March 2026, OPW Retail Fueling, a Dover company, received CARB EVR certification for its 71SO Segmented Overfill Prevention Valve. The valve features a modular design that facilitates handling, transportation, and installation. Its two-stage shut-off mechanism helps prevent fuel overfill while maintaining vapor-tight operation. The certification supports OPW’s presence in fuel-handling and vapor-control applications.
-
In December 2025, Cimarron Energy announced a strategic partnership with Bell Supply Company to expand the availability of advanced vapor recovery units (VRUs) for rental across key U.S. energy basins. The partnership combines Cimarron’s VRU technology with Bell Supply’s commercial reach and flexible rental model.
Global Vapor Recovery Units Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 1.3 billion
Estimated market size in 2026
USD 1.4 billion
Revenue forecast in 2033
USD 1.9 billion
Growth rate
CAGR of 5.1% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Technology, application, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa; Africa
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Spain; Italy; China; Japan; India; Australia; South Korea; Brazil; Argentina; Saudi Arabia; UAE; South Africa
Key companies profiled
John Zink Company, LLC; Zeeco, Inc.; Cimarron Energy, Inc.; Dover Corporation; Petrogas Systems; BORSIG GmbH; Diamond Key International; ALMA Group; Kappa GI S.r.l.; Kilburn Engineering Ltd.; Symex Technologies LLC; VOCZero Ltd.; SCS Technologies; S&S Technical, Inc.; Tecam Group.
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Vapor Recovery Units Market Report Segmentation
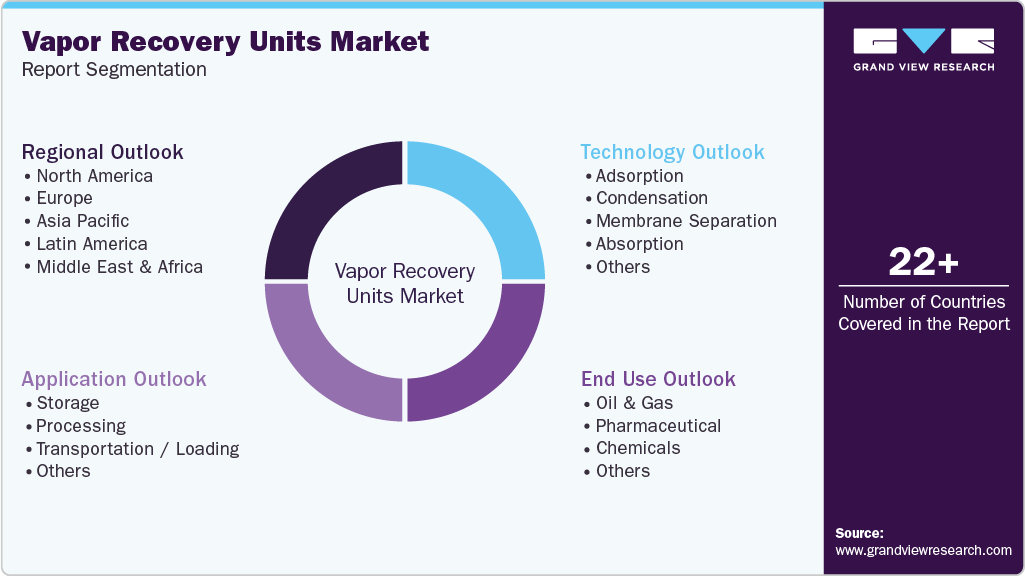
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global vapor recovery units market report based on technology, application, end-use, and region
 To learn more about this report, Download Free Sample Report
-
Technology Outlook (Revenue, USD Billion, 2021 - 2033)
-
Adsorption
-
Condensation
-
Membrane Separation
-
Absorption
-
Others
-
-
Application Outlook (Revenue, USD Billion, 2021 - 2033)
-
Storage
-
Processing
-
Transportation / Loading
-
Others
-
-
End Use Outlook (Revenue, USD Billion, 2021 - 2033)
-
Oil & Gas
-
Pharmaceutical
-
Chemicals
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
France
-
Italy
-
Spain
-
UK
-
-
Asia Pacific
-
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Arabia
-
UAE
-
South Africa
-
-
Research Methodology
The vapor recovery units market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each vapor recovery units segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Technology
Revenue Capture Definition
Adsorption
Revenue generated from the sale of vapor recovery units that use adsorbent materials to capture and recover hydrocarbons, VOCs, and other vapors from gas streams.
Condensation
Revenue generated from the sale of vapor recovery units that cool vapor streams to condense recoverable hydrocarbons or solvents into liquid form.
Membrane Separation
Revenue generated from the sale of membrane-based vapor recovery units that use selective membranes to separate hydrocarbons, VOCs, and other vapor components from gas streams.
Absorption
Revenue generated from the sale of vapor recovery units that use liquid absorbents to capture and recover hydrocarbons, VOCs, and other targeted vapor components.
Others
Revenue generated from the sale of vapor recovery units based on other recovery technologies or hybrid configurations not classified under adsorption, condensation, membrane separation, or absorption.
Application
Revenue Capture Definition
Storage
Revenue generated from the sale of vapor recovery units installed for capturing and recovering vapors released from storage tanks containing crude oil, fuels, chemicals, and other volatile liquids.
Processing
Revenue generated from the sale of vapor recovery units used to capture and recover vapors generated during oil & gas, chemical, petrochemical, and other industrial processing operations.
Transportation / Loading
Revenue generated from the sale of vapor recovery units used during the loading, unloading, and transfer of volatile liquids through trucks, railcars, ships, terminals, and other transportation systems.
Others
Revenue generated from the sale of vapor recovery units used in applications other than storage, processing, and transportation/loading.
End Use
Revenue Capture Definition
Oil & Gas
Revenue generated from the sale of vapor recovery units to oil & gas operators for capturing hydrocarbon vapors generated during production, storage, processing, transportation, and loading activities.
Pharmaceutical
Revenue generated from the sale of vapor recovery units to pharmaceutical manufacturers for recovering solvent vapors and controlling emissions generated during pharmaceutical production and processing.
Chemicals
Revenue generated from the sale of vapor recovery units to chemical manufacturers for capturing and recovering volatile chemical vapors generated during production, storage, processing, and material handling.
Others
Revenue generated from the sale of vapor recovery units to end-use industries other than oil & gas, pharmaceutical, and chemicals.
Estimation Model
Layer Name
Key Question
Description
Industry & Demand Assessment
Where is VRU demand generated?
Assess demand across oil & gas, chemicals, pharmaceuticals, and other industries by evaluating storage, processing, and transportation/loading activities where vapor recovery is required.
Technology & Application Assessment
What type of VRU is being adopted?
Estimate demand based on adsorption, condensation, membrane separation, absorption, and other technologies across different applications and operating requirements.
Supplier & Installation Assessment
What portion of demand converts into equipment sales?
Evaluate supplier presence, project installations, regional deployment, replacement demand, and new facility investments to determine the addressable market for VRU equipment.
Revenue
What is the final market value?
Calculate total revenue generated from the sale of vapor recovery units across technologies, applications, end-use industries, and geographic markets during the defined period.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Segmentation
The report provides a detailed regional assessment covering North America, Europe, Asia Pacific, Latin America, and Middle East & Africa, along with country-level analysis for key markets such as the U.S., Canada, Germany, France, China, India, Saudi Arabia, and Brazil. Regional demand is evaluated based on oil & gas activity, industrial infrastructure, environmental regulations, and vapor recovery adoption.
Provides a clear understanding of regional market attractiveness, growth potential, and demand drivers, helping identify high-opportunity countries and regions for VRU manufacturers and investors. Asia Pacific is highlighted as a key growth opportunity, while North America remains a major established market.
Competitive Benchmarking
The report benchmarks major market participants based on their VRU product portfolios, technology capabilities, application coverage, geographic presence, operating strategies, competitive advantages, and market positioning. Participants are further categorized into established and emerging/regional players to provide a structured view of the competitive environment.
Enables stakeholders to compare competitors based on technology expertise, application reach, customization capabilities, and regional strength. It also helps identify competitive gaps and areas where emerging suppliers can differentiate through modular, specialized, or application-specific VRU solutions.
Opportunity Assessment
The report evaluates opportunities across technology, application, end-use, and regional segments, with particular focus on membrane separation, processing applications, pharmaceutical and chemical industries, and high-growth markets in Asia Pacific and other emerging economies. Opportunities related to modular systems, automation, digital monitoring, emission reduction, and retrofit installations are also assessed.
Helps companies identify high-growth segments and emerging investment areas while supporting decisions related to product development, geographic expansion, partnerships, and market entry. The growing use of modular VRUs and increasing adoption in emerging industrial markets create additional opportunities for suppliers.
Frequently Asked Questions About This Report
Oil & gas segment led the market with the largest revenue share of 66.2% in 2025.The sector has extensive requirements for vapor recovery across production, storage, processing, and transportation facilities, particularly for controlling methane, VOCs, and hydrocarbon losses.
Some of the key players operating in the global vapor recovery units market include John Zink Company, LLC; Zeeco, Inc.; Cimarron Energy, Inc.; Dover Corporation; Petrogas Systems; BORSIG GmbH; Diamond Key International; ALMA Group; Kappa GI S.r.l.; Kilburn Engineering Ltd.; Symex Technologies LLC; VOCZero Ltd.; SCS Technologies; S&S Technical, Inc.; Tecam Group.
The market is primarily driven by the growing need to control VOC and methane emissions, stricter environmental regulations, and increasing oil & gas production, storage, processing, and transportation activities. VRUs also allow operators to recover valuable hydrocarbons that can be reused, sold, or used as fuel, improving the economic value of emission-control investments.
The global vapor recovery units market size was estimated at USD 1.3 billion in 2025 and is expected to be USD 1.4 billion in 2026.
The global vapor recovery units market, in terms of revenue, is expected to grow at a CAGR of 5.1% from 2026 to 2033 to reach USD 1.9 billion by 2033.
North America held the largest share, accounting for 38.6% of the global market in 2025.
Asia Pacific is expected to be the fastest-growing regional market.
Storage segment led the market with the largest revenue share of 39.0% in 2025 while processing segment is expected to be the fastest-growing market.
Adsorption accounted for the largest share, with 34.0% of global revenue in 2025. Its strong position is supported by its effectiveness in capturing hydrocarbons and VOCs from vapor streams and its suitability for storage, terminal, chemical, and oil & gas applications.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


