
- Home
- »
- Animal Health
- »
-
Veterinary Anti-Infectives Market Size Report, 2026-2033GVR Report cover

Veterinary Anti-infectives Market (2026 - 2033)
Size, Share & Trends Analysis Report By Animal Type, By Product (Antimicrobials, Antifungals, Antivirals), By Route Of Administration, By Type, By Distribution Channel, By Region, And Segment Forecasts
Market Size, 2025
$8.7BMarket Estimate, 2026
$9.2BMarket Forecast, 2033
$14.4BCAGR, 2026–2033
6.6%Veterinary Anti-infectives Market Summary
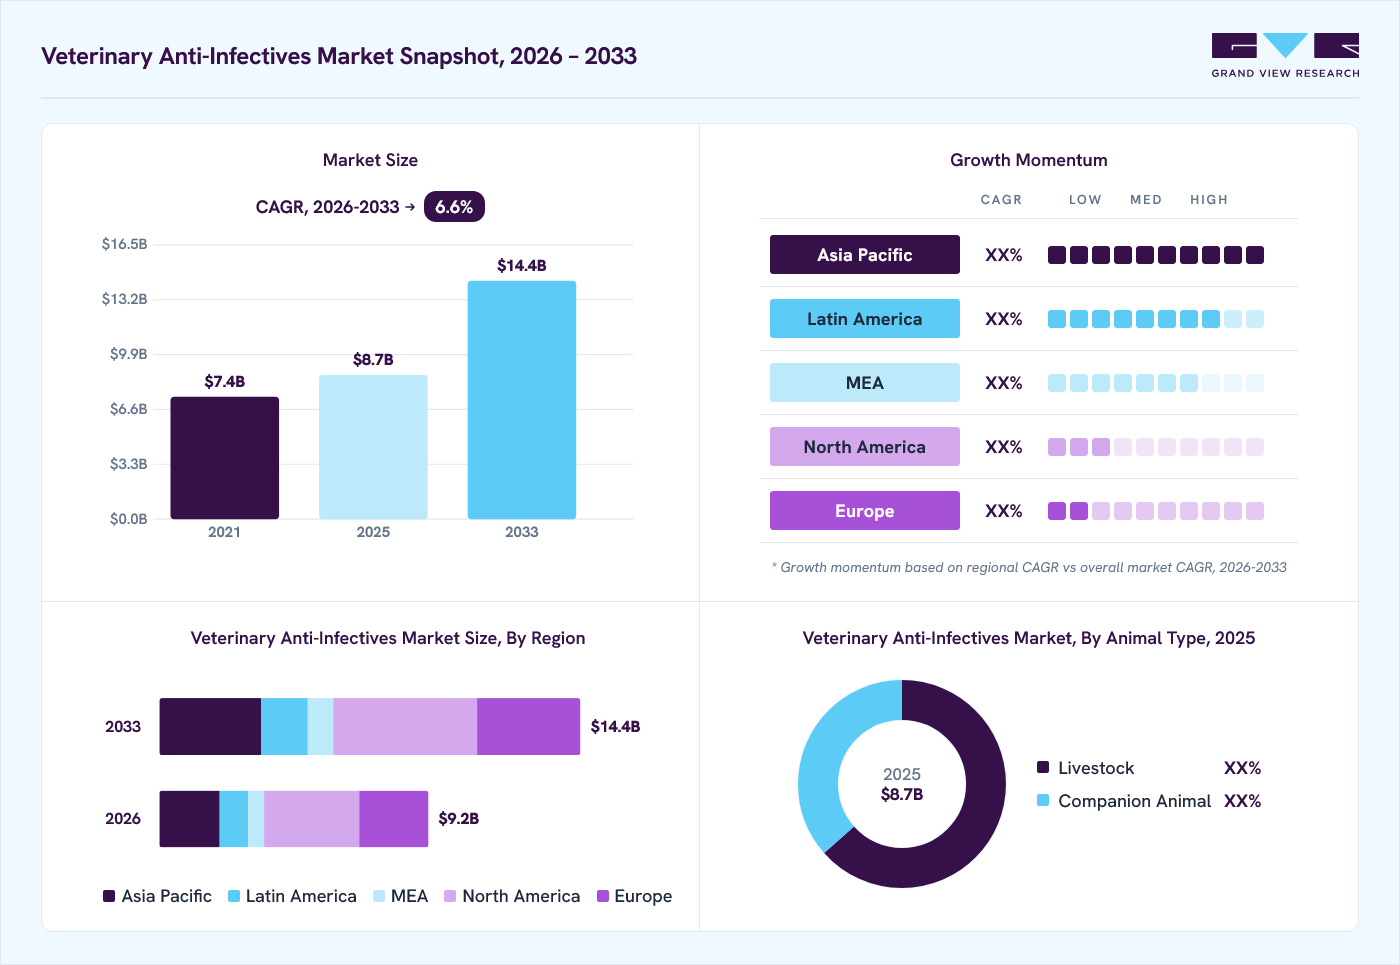
The global veterinary anti-infectives market size was valued at USD 8.7 billion in 2025 and is projected to grow from USD 9.2 billion in 2026 to USD 14.4 billion by 2033, at a CAGR of 6.6% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 35.5% in 2025. Key factors expected to drive the market include the rise in animal infectious diseases, emerging research initiatives, a push toward prudent antibiotic use, increasing regulatory approvals, and growing applications of Artificial Intelligence (AI).
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By animal type: Livestock segment led the market with the largest revenue share of 63.4% in 2025.
- By product: Antimicrobials segment led the market with the largest revenue share of 50.8% in 2025.
- By route of administration: Oral segment led the market with the largest revenue share of 71.1% in 2025.
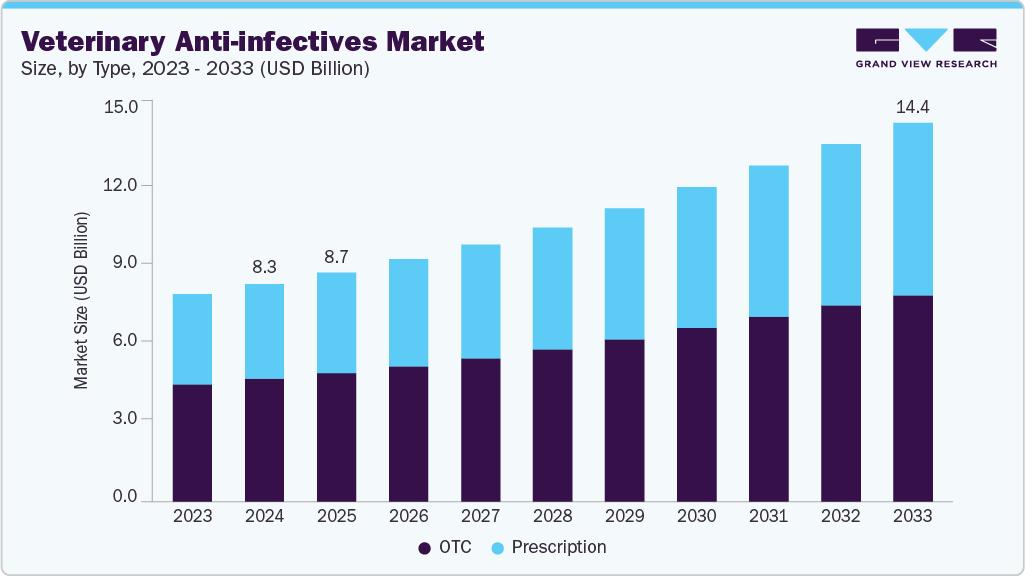
- By type: OTC segment led the market with the largest revenue share of 55.7% in 2025.
- By distribution channel: Retail pharmacies segment led the market with the largest revenue share of 55.2% in 2025.
Regional Highlights
- Largest regional market: North America (35.5% revenue share, 2025)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 8.7 Billion
- Estimated market size in 2026: USD 9.2 Billion
- Projected market size by 2033: USD 14.4 Billion
- CAGR (2026-2033): 6.6%
Prism AI by Grand View Research Free to tryAsk a question about the veterinary anti-infectives marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
One of the foremost drivers is the growing integration of artificial intelligence (AI) in veterinary practices. Educational institutions, animal welfare bodies, and commercial players are adopting AI to streamline clinical decision-making, assist in early disease detection, identify treatment gaps, and even accelerate veterinary drug discovery. AI also offers potential for predictive modeling in outbreak surveillance, helping to rationalize anti-infective use amid rising concerns of antimicrobial resistance (AMR).Another critical factor is the increasing global prevalence of infectious diseases in companion and livestock animals. For example, India-a leading dairy-producing country-witnessed a severe outbreak of Lumpy Skin Disease in 2023, which infected nearly 2.95 million cattle and resulted in over 155,000 deaths across 15 states. Similarly, in the U.S., one of the world's top beef producers, a recent outbreak of highly pathogenic avian influenza (HPAI) among cattle saw over 250 beef samples from 38 states testing positive as of May 2024. South Africa also faced a 30% drop in egg production and had to cull over a million poultry in 2023 due to HPAI. These disease outbreaks are directly escalating the demand for effective anti-infective therapies.
 To learn more about this report, Download Free Sample Report
Rising antimicrobial resistance (AMR) is also shaping the market, prompting stricter regulatory surveillance. In June 2025, India's Central Drugs Standard Control Organisation (CDSCO) launched a nationwide initiative to monitor antibiotic use in livestock. It established inter-agency collaborations and mandated AMU (antimicrobial use) data reporting to combat misuse and overuse of antibiotics, which can drive the development and adoption of newer, more targeted anti-infectives.
Intensive R&D and industry collaborations support these regulatory developments. In March 2024, Zoetis partnered with Blacksmith Medicines to develop novel antibiotics to circumvent bacterial resistance by selectively targeting drug-resistant strains. Likewise, discoveries such as bird flu's zoonotic shift to cattle-uncovered by a veterinarian in Texas-open new avenues for therapeutic innovation in livestock disease management.
Additionally, the growth of generic and value-added veterinary medicines is expanding market accessibility. The 2024 European Market Study by Access VetMed revealed that generics account for around 50% of all veterinary product authorizations, with significant traction in anti-infectives and antiparasitics. Despite regulatory burdens like EU Regulation 2019/6, especially for SMEs, the sector remains growing, particularly for companion animal products and alternative administration routes.
Overall, the rise in infectious disease outbreaks, regulatory tightening on antimicrobial use, technological innovations like AI, and increased investment in R&D and generics significantly propel the veterinary anti-infectives market. These forces are expected to meet current treatment demands and ensure veterinary antimicrobial therapy's long-term sustainability and efficacy.
 To learn more about this report, Download Free Sample Report
Market Dynamics
The veterinary anti-infective market is witnessing robust growth, driven by the increasing prevalence of bacterial, viral, fungal, and parasitic infections across companion and livestock animals, rising awareness of antimicrobial stewardship, and growing investments in advanced veterinary therapeutics. Expanding pet ownership, intensification of livestock production, and heightened focus on preventing zoonotic disease transmission are further accelerating the demand for effective anti-infective products. Regulatory agencies are also encouraging the development of innovative alternatives that improve treatment efficacy while addressing antimicrobial resistance. Intensive R&D and industry collaborations are strengthening these developments. For instance, in March 2024, Zoetis partnered with Blacksmith Medicines to develop novel antibiotics designed to overcome bacterial resistance by selectively targeting drug-resistant strains. Additionally, emerging disease discoveries, such as the identification of the zoonotic shift of avian influenza (bird flu) to cattle by a veterinarian in Texas, are creating new opportunities for therapeutic innovation and next-generation anti-infective solutions for livestock, further supporting long-term market growth.
The increasing occurrence of transboundary livestock diseases such as lumpy skin disease is driving demand for veterinary anti-infective products by supporting the need for comprehensive disease management and biosecurity measures. Fo instance, the April 2026 LSD outbreak in Sardinia, Italy, which led to mandatory culling, movement restrictions, enhanced surveillance, and expanded vaccination programs, highlights the significant economic and production losses associated with infectious disease outbreaks. Although LSD is a viral disease, infected animals are at increased risk of secondary bacterial infections that require anti-infective treatment to prevent complications and support recovery. These outbreaks also encourage governments and livestock producers to strengthen disease preparedness, invest in surveillance systems, and maintain adequate supplies of veterinary therapeutics, thereby contributing to the sustained growth of the veterinary anti-infective market.
Restraint - Rising Antimicrobial Resistance Limiting the Effectiveness of Veterinary Anti-infectives
The growing prevalence of antimicrobial resistance is a major challenge restraining the veterinary anti-infective market, as the effectiveness of commonly used antibiotics continues to decline against resistant bacterial pathogens. The widespread and, in some cases, inappropriate use of anti-infective drugs in companion animals and livestock has accelerated the emergence of multidrug-resistant organisms, resulting in treatment failures, prolonged disease outbreaks, and increased healthcare costs. In response, regulatory authorities are imposing stricter antimicrobial stewardship policies, limiting the use of critically important antibiotics and requiring veterinarians to adopt more targeted prescribing practices. While these measures are essential for preserving antibiotic efficacy, they reduce the routine use of existing anti-infective products, increase compliance costs for manufacturers, and necessitate significant investments in research and development to discover novel antimicrobial agents, thereby restraining the overall growth of the veterinary anti-infective market.
The emergence of RNA-based veterinary vaccines presents a significant growth opportunity for the veterinary anti-infective market by enabling the development of more effective and innovative solutions for infectious disease prevention. For instance, in May 2026, the European Medicines Agency's recommendation for market authorization of Merck Animal Health's Nobivac NXT HCPChFelV, the first veterinary vaccine containing self-amplifying RNA technology, marks a major advancement in veterinary immunization. Designed to protect cats against feline leukemia virus (FeLV) alongside other common feline pathogens, the vaccine demonstrates the expanding application of next-generation biotechnology in animal health. Such innovations are expected to improve disease prevention, reduce the incidence of infectious diseases, decrease reliance on antimicrobial treatments, and encourage further investment in advanced vaccine platforms, creating new commercial opportunities for companies operating in the veterinary anti-infective market.
Market Concentration & Characteristics
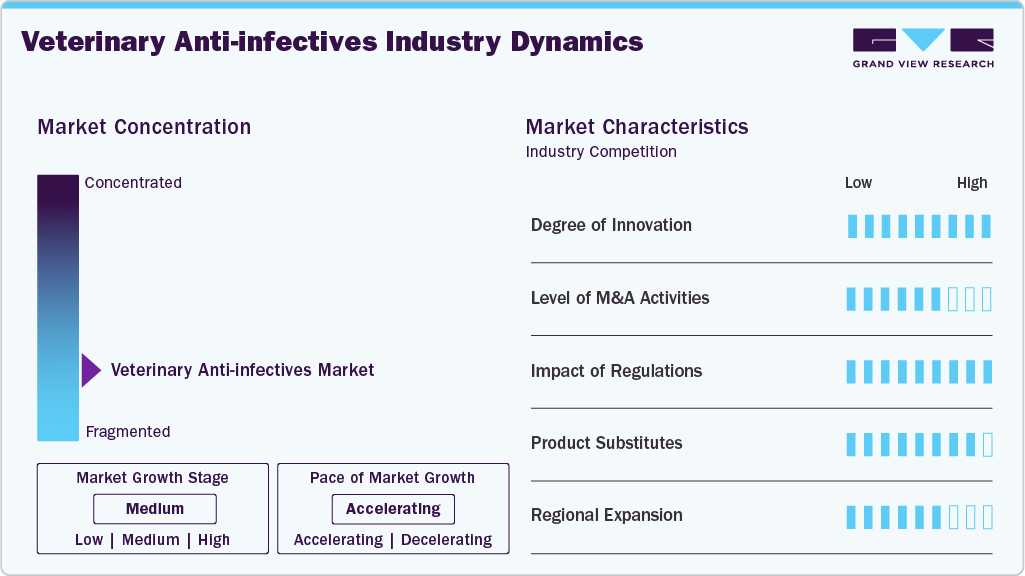
This industry is highly innovative, with researchers worldwide launching novel products and developing creative business activities to address growing infectious diseases in animals. For example, in March 2025, Agrovet Market launched a new line of intramammary suspension antibiotics tailored for lactating and dry cows to treat and prevent mastitis. The products include multi‑antibiotic + anti‑inflammatory combinations for lactation (e.g., Pen Tetra Strep LC, Kanacef LC, Cefquinox LC, Clox‑A‑Lac LC) and long‑acting dry‑cow formulations (Clox‑A‑Dry, Cefquinox DC) designed to improve udder health and boost dairy productivity.
The market has a moderate level of mergers and acquisitions. Industry participants are attempting to consolidate the distribution channels for veterinary medicines by acquiring other platforms. For instance, in May 2024, Pharmacy2U acquired PharmPet Co. to enhance its online pharmacy services.
 To learn more about this report, Download Free Sample Report
Regulations have a very high impact on this market. This can be attributed to regulatory restrictions on the use of antibiotics in animals amidst the rise in drug resistance. These restrictions have restricted the drugs from being used selectively and are subject to heavy regulatory scrutiny before approvals, as well as monitoring post-approval. These steps taken by organizations like the USFDA and EU aim to address concerns over antibiotic resistance and promote responsible antibiotic use.
A few players, such as Zoetis, Boehringer Ingelheim, Dechra Pharmaceuticals plc, and Merck & Co. Inc. lead the market. However, the adoption of regional products is very high due to factors like cost concerns and alternative therapies. Due to a shift in regulatory dynamics, many emerging startups aim to develop selective anti-infective drugs to bypass drug resistance.
The market is experiencing moderate regional expansion. Manufacturers are expanding their production capacity to boost revenues and introduce novel therapies in different countries to grow their regional presence. For instance, in February 2025, Zoetis expanded its cattle anti‑infective lineup by acquiring marketing rights to Loncor 300 (florfenicol) from Elanco. This adds a fourth class of antibiotics to their portfolio, providing a broad‑spectrum treatment for bovine respiratory disease (BRD) and foot rot.
Analyst Perspective
The veterinary anti-infectives market is evolving beyond conventional infection management toward integrated animal health solutions that combine advanced therapeutics, preventive healthcare, and precision disease control. Manufacturers are increasingly investing in long-acting formulations, species-specific anti-infective products, and combination therapies that improve treatment compliance while minimizing the frequency of drug administration. At the same time, advances in veterinary diagnostics, pathogen surveillance, and digital livestock monitoring enabling earlier disease detection and more targeted treatment decisions, improving therapeutic outcomes and supporting responsible antimicrobial use across both companion and food-producing animals.
Despite favorable growth prospects, the market faces challenges associated with increasingly stringent regulations governing antimicrobial use, lengthy product development and approval timelines, and the rising costs of clinical research required to bring novel anti-infective therapies to market. Manufacturers are also under pressure to develop effective alternatives that comply with antimicrobial stewardship initiatives while maintaining therapeutic efficacy and affordability. In addition, varying regulatory frameworks across regions and limited access to advanced veterinary healthcare in developing economies continue to create commercialization and market penetration challenges. Companies that can accelerate innovation, strengthen regulatory compliance, expand their geographic presence, and develop differentiated anti-infective solutions tailored to evolving disease patterns will be better positioned to gain a competitive advantage in the global veterinary anti-infectives market.
Animal Type Insights
Based on animal type, the livestock segment led the market with the largest revenue share of 63.4% in 2025. Fish, poultry, swine, cattle, sheep, and goats are among the subcategories of the livestock segment. These animals' high disease burden and routine anti-infective use drive this dominance. Rising global demand for animal protein, especially meat, further intensifies the need for preventive and therapeutic anti-infectives. For instance, according to an April 2025 article by FnBnews, India’s meat industry has witnessed steady expansion, with production reaching 10.25 million metric tons (MMT) in 2023-24, up 4.95% from the previous year. Poultry leads with over 5 MMT, followed by buffalo meat at 4.57 MMT. India now ranks as the fifth-largest global meat producer, contributing 7% of worldwide output. Additionally, increasing focus on food safety, productivity, and sustainable livestock farming bolsters the use.
The companion animal segment is projected to grow at the fastest CAGR in the veterinary anti-infectives market due to rising pet ownership and increased awareness of the health benefits of having pets, such as reduced stress, anxiety, and improved cardiovascular health. This trend is further supported by a shift toward preventive veterinary care and the availability of specialized anti-infective products tailored for pets. Additionally, higher spending on pet healthcare and emotional bonding with companion animals drive demand for advanced therapeutic solutions, contributing to the segment's rapid expansion.
Product Insights
Based on product, the antimicrobials segment led the market with the largest revenue share of 50.8% in 2025, driven by the high prevalence of bacterial infections in livestock and companion animals. Widely used classes such as cephalosporins, tetracyclines, penicillins, and macrolides are essential for treating respiratory, gastrointestinal, and systemic infections. Increasing global concerns over zoonotic diseases, food safety, and antimicrobial resistance have prompted greater regulation and responsible usage. Initiatives by organizations like the WHO to combat antibiotic resistance and improve animal health systems further support the segment's dominance by ensuring sustained demand and accountable innovation in antimicrobial therapies.
The antiviral segment in veterinary anti-infectives is poised for the fastest growth due to a surge in viral disease incidence across livestock and companion animals. Recent research underscores the significant economic threats posed by endemic and emerging viral infections in cattle, swine, and other species-such as bovine respiratory syncytial virus (BRSV), foot‑and‑mouth disease, and lumpy skin disease-which result in significant production losses and heightened demand for targeted antiviral therapies. Concurrently, advancements in antiviral drug development and vaccine technologies-highlighted in MDPI’s April 2025 article-fuel innovation in veterinary virology. Coupled with growing awareness of viral threats, One Health initiatives, and the imperative for food security, these factors drive rapid investment and expansion in the antiviral veterinary segment.
Route Of Administration Insights
Based on route of administration, the oral segment led the market with the largest revenue share of 71.1% in 2025, primarily due to the ease and convenience of administering livestock and companion animals. Oral dosage forms-such as tablets, chewables, and liquids-enable mass medication through feed or water, reducing the need for veterinary supervision and clinic visits. This cost-effective method improves treatment compliance and is suitable for large-scale preventive and therapeutic use. Additionally, commonly used antimicrobials like tetracyclines, macrolides, and sulphonamides are well-suited for oral delivery, further reinforcing their widespread adoption.
The "Others" segment, encompassing topical, rectal, and intrauterine routes, is projected to grow at the fastest CAGR from 2026 to 2033 in the veterinary anti-infectives market. This growth is driven by veterinarians' increasing adoption of alternative drug delivery methods, particularly for cases where oral or injectable routes show poor compliance or limited efficacy. These methods are often preferred for localized infections or disease-specific needs, such as intrauterine therapy for reproductive infections or topical treatment for skin conditions. Additionally, topical routes offer enhanced bioavailability for surface infections, further boosting the segment's demand.
Type Insights
Based on type, the OTC segment led the market with the largest revenue share of 55.7% in 2025. Animal owners prefer these products because they are affordable, suitable for mild diseases, convenient, and accessible without a prescription from a veterinarian. The popularity of over-the-counter (OTC) options indicates that animal owners prefer readily available, reasonably priced, and reliable solutions for their animals' everyday medical requirements, even while prescription treatments are necessary for severe health conditions.
The prescription segment is estimated to grow at the highest CAGR over the forecast period. This can be attributed to the recent regulatory changes that restrict veterinary drug use to prescriptive use, lowering the consumption of OTC anti-infectives and leading to increased adoption of prescription anti-infective drugs.
Distribution Channel
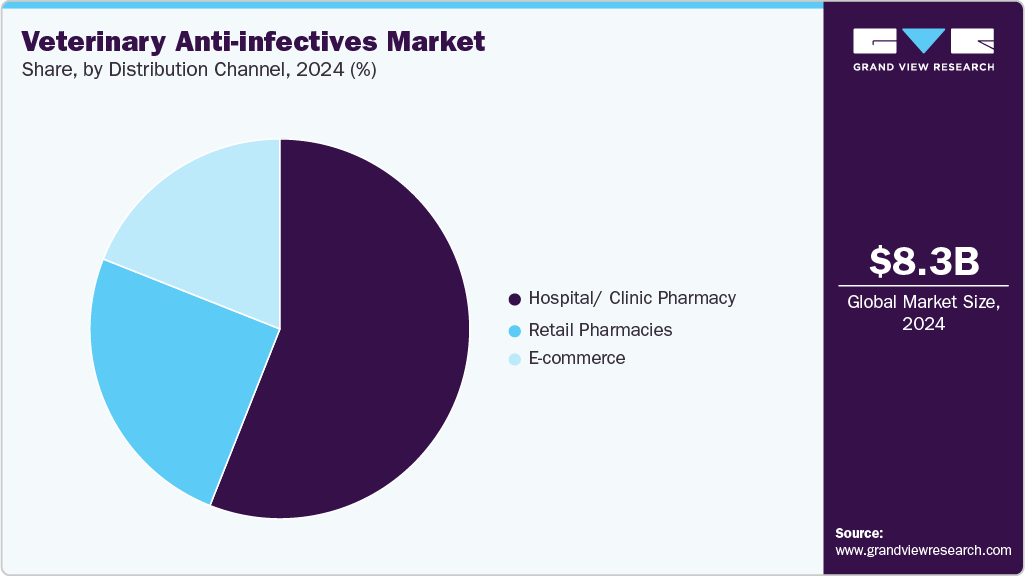
Based on distribution channel, the retail pharmacies segment led the market with the largest revenue share of 55.2% in 2025. This is explained by the accessibility and ease of obtaining immunizations and medications through retail pharmacies. Their extensive distribution networks ensure product availability, and their well-established standing and regulatory compliance cultivate consumer confidence. Furthermore, it is projected that the digitization of retail pharmacies will spur the expansion of this market in the coming years by reducing the risk of prescription errors.
 To learn more about this report, Download Free Sample Report
The e-commerce segment is estimated to grow at the highest rate over the forecast period. This segment will be driven by the ease of ordering from home and being accessible around the clock. Online retailers improve consumer satisfaction by offering a wide range of products at competitive prices and home delivery options. Further driving growth has been the shift to online purchasing, brought about by the pandemic, increased internet use, and rising digital literacy. These factors indicate a significant shift in consumer behavior toward online purchases.
Regional Insights
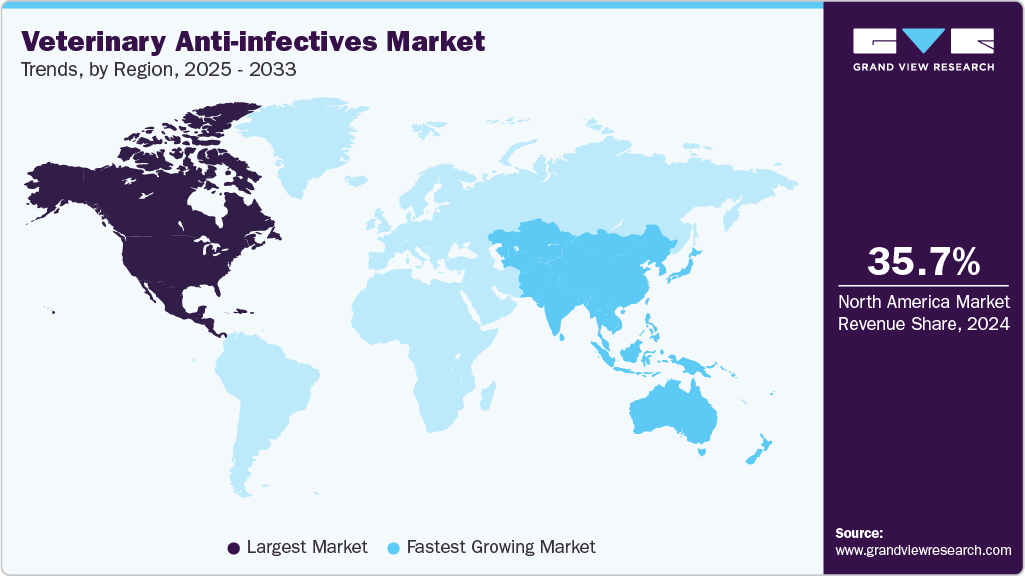
North America dominated the veterinary anti-infectives market with the largest revenue share of 35.5% in 2025. The existence of well-established competitors and rising treatment costs among veterinary clinics are the primary drivers of the industry. Zoonoses and Public Health (2016) states that zoonotic illnesses represent a significant burden on the North American continent. Given that animals frequently spread zoonotic illnesses, they pose an even greater risk to public health. The market is growing in part because zoonotic infections are so common. According to 2024 reports by the CDC, six out of ten infectious diseases known to spread to people can be spread by animals. Moreover, animals are the source of three of every four newly discovered or developing contagious human diseases.
 To learn more about this report, Download Free Sample Report
U.S. Veterinary Anti-infectives Market Trends
The veterinary anti-infectives market in the U.S. held the largest share in the North America region in 2025. The country market has benefited from the existence of significant industry players, including Kindred Biosciences, Elanco, Dechra, and Zoetis. These businesses make substantial R&D investments to meet consumer demand and develop innovative veterinary medications. For example, in March 2025, Dechra launched DuOtic, the first FDA-approved antibiotic-free otic gel for treating yeast-driven otitis externa (primarily Malassezia pachydermatis) in dogs. This innovation combines antifungal terbinafine with anti-inflammatory betamethasone, providing up to 45 days of relief with a pre-measured, clinic-administered dose. By eliminating unnecessary antibiotic use, such products support antimicrobial stewardship and address the growing concern over resistance in veterinary health.
Europe Veterinary Anti-infectives Market Trends
Advantageous government regulations, such as the EU Veterinary Medicines Regulation, which restricts antibiotics to specific situations and prohibits routine administration due to rising drug resistance in animals, are expected to significantly expand the European market. Furthermore, trade organizations such as EFTA, the growing pet population, rising pet insurance penetration, and improved animal husbandry practices bolster the region's market growth potential.
Germany veterinary anti-infectives market will likely expand due to the growing pet adoption rate and the growing importance of animal husbandry. German livestock data indicates that the nation has the second-biggest cow population in the EU and the largest dairy cattle herd. The International Committee for Animal Recording (ICAR) also reports that almost half of German farms are livestock-focused, which is expected to foster favorable conditions for the veterinary anti-infectives industry.
Asia Pacific Veterinary Anti-infectives Market Trends
The Asia Pacific market is growing fastest due to the rising incidence of animal diseases, the growing concern for animal health, the increasing number of livestock, and the growing adoption of pets. A significant number of cattle and growing healthcare spending on veterinary care and animal health are additional vital factors anticipated to drive market expansion. For instance, according to April 2025 data by USDA, more than 40% of all cattle worldwide are found in China and India. The expanding population of livestock has boosted the demand for the production of meat and dairy products, which is predicted to fuel the demand for veterinary antibiotics for livestock animals.
The India veterinary anti-infectives market is expected to grow at a CAGR of more than 8% over 2026-2033. This is owed to the developing dairy industry, growing veterinary healthcare institutions, and expanded livestock production. This large cattle population, i.e., about 30% of the global population, is set to boost the demand for anti-infective drugs to ensure that infectious outbreaks do not affect livestock production in the country. Furthermore, another crucial driving factor is the recent rise in the adoption of pets like dogs and cats among Indian households and spending on preventive and therapeutic care for various infectious diseases.
Latin America Veterinary Anti-infectives Market Trends
The growing incidence of pet injuries and increased product sales drive the Latin American industry. Additionally, throughout the forecast period, the market is anticipated to be driven by the growing number of livestock and the existence of animal pharmaceutical firms. The Food & Agriculture Organization of the United Nations estimates that, with a cattle herd nearing 360 million heads, Latin America accounts for roughly 24 percent of global cattle production. Furthermore, it exports over 22% of the world's beef, accounting for 23% of worldwide beef production.
The Brazil veterinary anti-infectives market is projected to grow due to growing vaccination laws aimed at preventing the spread of animal diseases and rising consumer demand for food items related to livestock. Brazil's increasing veterinary anti-infectives market results from the country's large cattle population. At around 186 million cattle, Brazil has the second-largest herd of cattle, according to USDA data from April 2025. Additionally, it is the biggest exporter of beef in the world. Because of this, there has recently been a higher awareness of the importance of animal health, which has increased the demand for veterinary medications like antibiotics, antifungals, and antivirals, among others.
Middle East & Africa Veterinary Anti-infectives Market Trends
The Middle East & Africa (MEA) market is formed by South Africa, Saudi Arabia, Kuwait, and the United Arab Emirates. The MEA's growing need for veterinary medicine is expected to fuel the market's growth throughout the forecast period. The region's increasing prevalence of infectious diseases in animals is also likely to boost demand for veterinary treatments and medications. A further factor driving demand for veterinary medicines, including veterinary antibiotics, is the spread of animal pathogens due to increased international trade. Finally, the MEA's rising livestock and poultry adoption is anticipated to spur regional market growth.
The South Africa veterinary anti-infectives market is driven by large farmer population in the country. Many farmers maintain their animals to supply milk and meat to consumers worldwide; livestock is an essential component of the country's economic system. However, since livestock are susceptible to a range of infectious diseases, there's a growing need for veterinary medicines to treat pets and livestock and prevent the spread of disease to other animals. Two major influenza outbreaks since 2003 were caused by avian influenza (H5N1) and swine flu (H1N1). Therefore, it is anticipated that the rising incidence of such infectious disorders would fuel the need for veterinary medications such as anti-infectives.
Key Veterinary Anti-infectives Company Insights
The veterinary anti-infectives market is highly regulated, with strict oversight by authorities like the USFDA, the EU, and the recent addition of CDSCO to curb antibiotic misuse and resistance. While major players such as Zoetis and Boehringer Ingelheim dominate, regional and cost-effective alternatives remain popular, and new startups are emerging with selective, resistance-bypassing therapies. The market is moderately expanding geographically, as seen with Zoetis’ acquisition of Anchor 300 to strengthen its cattle portfolio. Innovation remains a key driver, highlighted by Agrovet Market’s launch of specialized intramammary antibiotics. Mergers and acquisitions are also shaping the landscape, with efforts like Pharmacy2U’s acquisition of PharmPet Co. aimed at streamlining distribution and expanding digital access.
Key Veterinary Anti-infectives Companies:
The following key companies have been profiled for this study on the veterinary anti-infectives market.
-
Zoetis
-
Boehringer Ingelheim
-
Merck & Co. Inc.
-
Dechra Pharmaceuticals Plc.
-
Elanco Animal Health
-
Ceva Sante Animale
-
Virbac
-
Biogénesis Bagó
-
Vetoquinol
-
Calier
-
Norbrook Laboratories
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Zoetis; Boehringer Ingelheim; Merck & Co., Inc.; Elanco Animal Health; Ceva Santé Animale; Virbac; Dechra Pharmaceuticals Plc.)
- Established companies focus on expanding comprehensive veterinary anti-infective portfolios comprising antibiotics, antivirals, antifungals, antiparasitics, vaccines, and combination therapies for companion and livestock animals. They strengthen their market position through continuous investment in R&D, development of novel antimicrobial molecules, antimicrobial stewardship initiatives, strategic acquisitions, global distribution expansion, regulatory approvals, and collaborations with research institutes and veterinary organizations. These companies also emphasize lifecycle management, advanced drug formulations, manufacturing capacity expansion, and geographic penetration across developed and emerging markets.
- Established players benefit from strong global distribution networks, diversified animal health portfolios, extensive regulatory expertise, advanced manufacturing capabilities, well-established relationships with veterinarians and livestock producers, and significant investments in research and innovation. Their robust clinical development capabilities, broad product availability, strong brand reputation, and comprehensive sales infrastructure enable them to maintain leadership across both companion animal and livestock healthcare markets.
- Established vendors face challenges related to increasing antimicrobial resistance, stringent regulatory requirements governing antibiotic usage, lengthy product development timelines, high clinical trial and approval costs, and growing pressure to reduce antimicrobial use in food-producing animals. Patent expirations, generic competition, and rising compliance costs associated with antimicrobial stewardship programs may also impact long-term revenue growth.
Emerging Players (Biogénesis Bagó; Vetoquinol; Calier; Norbrook Laboratories)
- Emerging companies primarily focus on expanding specialized anti-infective products for regional livestock and companion animal markets through cost-effective manufacturing, niche therapeutic offerings, generic formulations, and targeted product innovation. Many emphasize regional expansion, strategic licensing agreements, contract manufacturing, distribution partnerships, and investments in improved formulations and disease-specific therapeutics to strengthen their competitive position. These companies also focus on expanding production capacity and increasing market access in high-growth emerging economies.
- Emerging players compete through competitive pricing, regional expertise, specialized product portfolios, flexible manufacturing capabilities, and faster commercialization of generic and niche anti-infective products. Their ability to respond quickly to regional disease outbreaks, establish local distribution partnerships, and provide cost-effective treatment options enables them to strengthen their presence in developing veterinary healthcare markets.
- Emerging vendors often have limited global market presence, smaller R&D budgets, lower brand recognition, and narrower product portfolios than multinational competitors. They may also face challenges in obtaining regulatory approvals across multiple regions, scaling international operations, expanding distribution networks, and competing with established companies that possess stronger innovation pipelines, larger commercial infrastructures, and greater financial resources.
Recent Developments
-
In January 2025, the Federation of Veterinarians of Europe launched Alternatives to Veterinary Antibiotics (AVANT). This ongoing project aims to reduce antimicrobial reliance in livestock by developing and promoting effective non-antibiotic solutions. It focuses on improving animal health and welfare while supporting sustainable farming practices.
-
In May 2024, Virbac acquired Sasaeah to strengthen its position in the veterinary antibiotics market, especially in the cattle segment. The company plans to offer manufacturing and R&D facilities in Japan and Vietnam through this acquisition.
-
In March 2024, Zoetis purchased a 21-acre manufacturing site in Melbourne to expand vaccine production for livestock and companion animals, increasing its footprint in Australia.
-
For instance, in April 2024, Norbrook Laboratories, a leading veterinary drugs manufacturer, doubled the production capacity at its existing facility in the U.S.
Veterinary Anti-infectives Market Report Scope
Report Attribute
Details
Market size in 2025
USD 8.7 billion
Estimated market size in 2026
USD 9.2 billion
Projected market size by 2033
USD 14.4 billion
Growth rate
CAGR of 6.6% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Animal type, product, route of administration, type, distribution channel, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; South Korea; Australia; Thailand; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait; Oman; Qatar.
Key companies profiled
Zoetis; Boehringer Ingelheim; Merck & Co. Inc.; Dechra Pharmaceuticals Plc.; Elanco Animal Health; Ceva Sante Animale; Virbac; Biogénesis Bagó; Vetoquinol; Calier; Norbrook Laboratories
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Veterinary Anti-infectives Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global veterinary anti-infectives market report based on animal type, product, route of administration, type, distribution channel & region.
-
Animal Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Livestock Animal
-
Poultry
-
Swine
-
Cattle
-
Sheep & Goats
-
Fish
-
Others
-
-
Companion Animal
-
Dogs
-
Cats
-
Others
-
-
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Antimicrobial
-
Tetracyclines
-
Penicillin
-
Cephalosporins
-
Macrolides
-
Quinolones
-
Others
-
-
Antifungals
-
Antivirals
-
Antiparasitic
-
Others
-
-
Route of Administration Outlook (Revenue, USD Million, 2021 - 2033)
-
Oral
-
Injectable
-
Topical
-
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
OTC
-
Prescription
-
-
Distribution Channel Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospital/ Clinic Pharmacy
-
Retail Pharmacies
-
E-commerce
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
India
-
China
-
South Korea
-
Australia
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa (MEA)
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The veterinary anti-infectives market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each veterinary anti-infectives segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Animal Type
Revenue Capture Definition
Livestock
Revenue generated from veterinary anti-infective products used for the prevention and treatment of infectious diseases in food-producing animals, including cattle, swine, poultry, sheep, goats, and aquaculture species.
Companion
Market revenue derived from anti-infective therapies administered to companion animals, such as dogs, cats, horses, and other pets, for the management of bacterial, viral, fungal, and parasitic infections.
Segment - Product
Revenue Capture Definition
Antimicrobials
Revenue generated from antibacterial agents used to prevent and treat bacterial infections in animals, including antibiotics and other antimicrobial formulations.
Antifungals
Income generated from veterinary medications formulated to treat fungal infections affecting the skin, ears, respiratory tract, and other organs in animals.
Antivirals
Revenue contributed by antiviral drugs developed to manage viral infections in companion and livestock animals by inhibiting viral replication or reducing disease severity.
Others
Market value generated from other anti-infective products, including antiparasitic agents, antiseptics, disinfectants, and combination therapies used in veterinary medicine.
Segment - Route of Administration
Revenue Capture Definition
Oral
Revenue generated from anti-infective products administered orally in the form of tablets, capsules, powders, liquids, boluses, or medicated feed additives.
Injectables
Sales generated from injectable veterinary anti-infective formulations administered via intravenous, intramuscular, or subcutaneous routes for rapid therapeutic action.
Others
Revenue derived from anti-infective products delivered through alternative routes, including topical, intramammary, ophthalmic, intranasal, and transdermal formulations.
Segment - Type
Revenue Capture Definition
OTC
Revenue earned from over-the-counter veterinary anti-infective products that can be purchased without a veterinary prescription, subject to regional regulatory requirements.
Prescription
Market revenue generated from prescription-only anti-infective medications dispensed under the supervision or authorization of a licensed veterinarian.
Segment - Distribution Channel
Revenue Capture Definition
Hospital/ Clinic Pharmacy
Revenue generated through the sale of veterinary anti-infective products dispensed by veterinary hospitals and clinics during the diagnosis and treatment of animal diseases.
Retail Pharmacies
Income derived from anti-infective products sold through retail pharmacies, agricultural supply stores, and veterinary drug retailers.
E-commerce
Revenue contributed by online sales of veterinary anti-infective products through manufacturer websites, digital pharmacies, and e-commerce platforms.
Estimation Model
Bottom-Up Revenue Model
Animal Healthcare Demand Model
Product Utilization & Distribution Model
Veterinary Infrastructure & Disease Management Model
• Market size is estimated by identifying leading veterinary pharmaceutical manufacturers and animal health companies across major regions.
• Revenue attributable to antimicrobials, antifungals, antivirals, antiparasitics, and other veterinary anti-infective products is derived from company annual reports, investor presentations, regulatory filings, financial disclosures, and paid industry databases.
• Individual company revenues are aggregated and validated using regional sales, product portfolios, pricing analysis, prescription trends, and estimated anti-infective product contribution to calculate the overall market size.
• Market value is estimated by assessing livestock and companion animal populations, disease prevalence, veterinary visits, hospitalization rates, and anti-infective treatment adoption across major countries.
• Adoption rates are evaluated using livestock production trends, companion animal ownership, zoonotic disease incidence, antimicrobial stewardship programs, and veterinary prescribing practices.
• Revenue is calculated by applying average treatment costs, prescription frequency, disease burden, and annual anti-infective expenditure across different animal categories.
• Market size is estimated by evaluating the utilization of oral, injectable, topical, and other anti-infective formulations distributed through veterinary hospitals, retail pharmacies, e-commerce platforms, and livestock supply channels.
• Parameters including prescription rates, OTC availability, hospital procurement, livestock healthcare expenditure, product replacement cycles, and distribution expansion are assessed across major regions.
• Revenue potential is estimated using product pricing, treatment duration, dosage frequency, channel-wise sales contribution, and manufacturer distribution networks.
• Market value is estimated by assessing veterinary infrastructure, animal disease surveillance systems, livestock production intensity, companion animal healthcare expenditure, and regulatory policies governing veterinary medicines.
• Anti-infective utilization is evaluated using infectious disease prevalence, vaccination coverage, antimicrobial resistance trends, veterinary workforce expansion, and government animal health initiatives.
• Revenue is calculated by applying treatment adoption rates, veterinary pharmaceutical spending, healthcare access, and disease management practices across veterinary hospitals, clinics, farms, and animal healthcare facilities.
Estimation Framework
This estimation framework enhances market visibility by integrating company revenues, infectious disease prevalence, veterinary treatment adoption, distribution channel performance, and animal healthcare infrastructure. The triangulated methodology provides a comprehensive assessment of veterinary anti-infective demand across livestock and companion animals while accurately identifying disease trends, prescribing patterns, regulatory developments, competitive positioning, and future growth opportunities.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Veterinary Anti-infectives Market Ecosystem & Market Assessment
Conducted a comprehensive assessment of the veterinary anti-infectives ecosystem, covering pharmaceutical manufacturers, contract manufacturing organizations (CMOs), active pharmaceutical ingredient (API) suppliers, veterinary hospitals and clinics, livestock producers, distributors, retail pharmacies, e-commerce platforms, regulatory authorities, and research institutions. Evaluated product portfolios, disease prevalence, antimicrobial stewardship initiatives, pricing strategies, distribution networks, regulatory landscape, and innovation trends across companion and livestock animal healthcare.
Provides a holistic understanding of the veterinary anti-infectives market landscape, disease management trends, regulatory developments, competitive dynamics, and revenue opportunities, enabling stakeholders to identify high-growth therapeutic areas, investment priorities, and strategic partnership opportunities.
Veterinary Anti-infectives Competitive Intelligence & Vendor Benchmarking
Performed detailed benchmarking of leading veterinary anti-infective manufacturers based on product portfolio breadth, antimicrobial and antiviral pipeline, geographic presence, manufacturing capabilities, R&D investments, regulatory approvals, pricing strategies, distribution network, strategic collaborations, acquisition activities, and innovation pipeline. Included comparative positioning of multinational companies and regional manufacturers across companion and livestock animal segments.
Enables identification of competitive gaps, product differentiation opportunities, licensing and partnership targets, portfolio optimization strategies, and innovation leadership while supporting long-term competitive positioning, investment planning, and strategic decision-making.
Market Penetration & Expansion Strategy
Evaluated regional growth opportunities for veterinary anti-infective products by assessing livestock and companion animal populations, infectious disease burden, antimicrobial usage patterns, veterinary healthcare infrastructure, regulatory frameworks, antimicrobial resistance (AMR) initiatives, animal healthcare expenditure, and competitive intensity. Identified priority countries and recommended market entry and expansion strategies based on disease prevalence, treatment adoption, distribution channel maturity, reimbursement landscape, and future market growth potential.
Enables companies to prioritize high-growth markets, optimize commercialization strategies, strengthen regional distribution networks, allocate investments efficiently, minimize regulatory and market-entry risks, and capitalize on emerging opportunities driven by increasing infectious disease incidence and advancements in veterinary therapeutics.
Frequently Asked Questions About This Report
The global veterinary anti-infectives market size was valued at USD 8.7 billion in 2025 and is estimated at USD 9.2 billion for 2026.
Some key players operating in the veterinary anti-infectives market include Zoetis, Boehringer Ingelheim, Merck & Co. Inc., Dechra Pharmaceuticals Plc., Elanco Animal Health, Ceva Sante Animale, Virbac, Biogénesis Bagó, Vetoquinol, Calier and Norbrook Laboratories
Key factors that are driving the market growth include rise in infectious diseases among animals, growing research initiatives, a boost to prudent antibiotic use, increasing regulatory approvals, and growing applications of Artificial Intelligence (AI).
Asia Pacific is the fastest-growing region over the forecast period.
The livestock segment led with a 63.4% revenue share in 2025, while the companion animals is the fastest-growing segment.
The antimicrobials segment led with a 50.8% revenue share in 2025, while the antiviral is the fastest-growing segment.
The oral segment led with a 71.1% revenue share in 2025, while the others is the fastest-growing segment.
The global veterinary anti-infectives market is expected to grow at a CAGR of 6.6% from 2026 to 2033, reaching USD 14.4 billion by 2033.
North America dominated with a 35.5% revenue share in 2025. This is attributable to the presence of advanced animal healthcare programs coupled with awareness regarding animal health.
About the Author(s)
Animal Health Research Team
Healthcare · Animal HealthThis report was authored by the animal health research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the animal health segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


