
- Home
- »
- Animal Health
- »
-
Veterinary Chemistry Analyzers Market Report, 2026-2033GVR Report cover

Veterinary Chemistry Analyzer Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Benchtop, Portable), By Product (Consumables, Instruments), By Species (Cattle, Canine), By Application, By End-use, By Region, And Segment Forecasts
Market Size, 2025
$3.0BMarket Estimate, 2026
$3.4BMarket Forecast, 2033
$8.6BCAGR, 2026–2033
14.3%Veterinary Chemistry Analyzer Market Summary
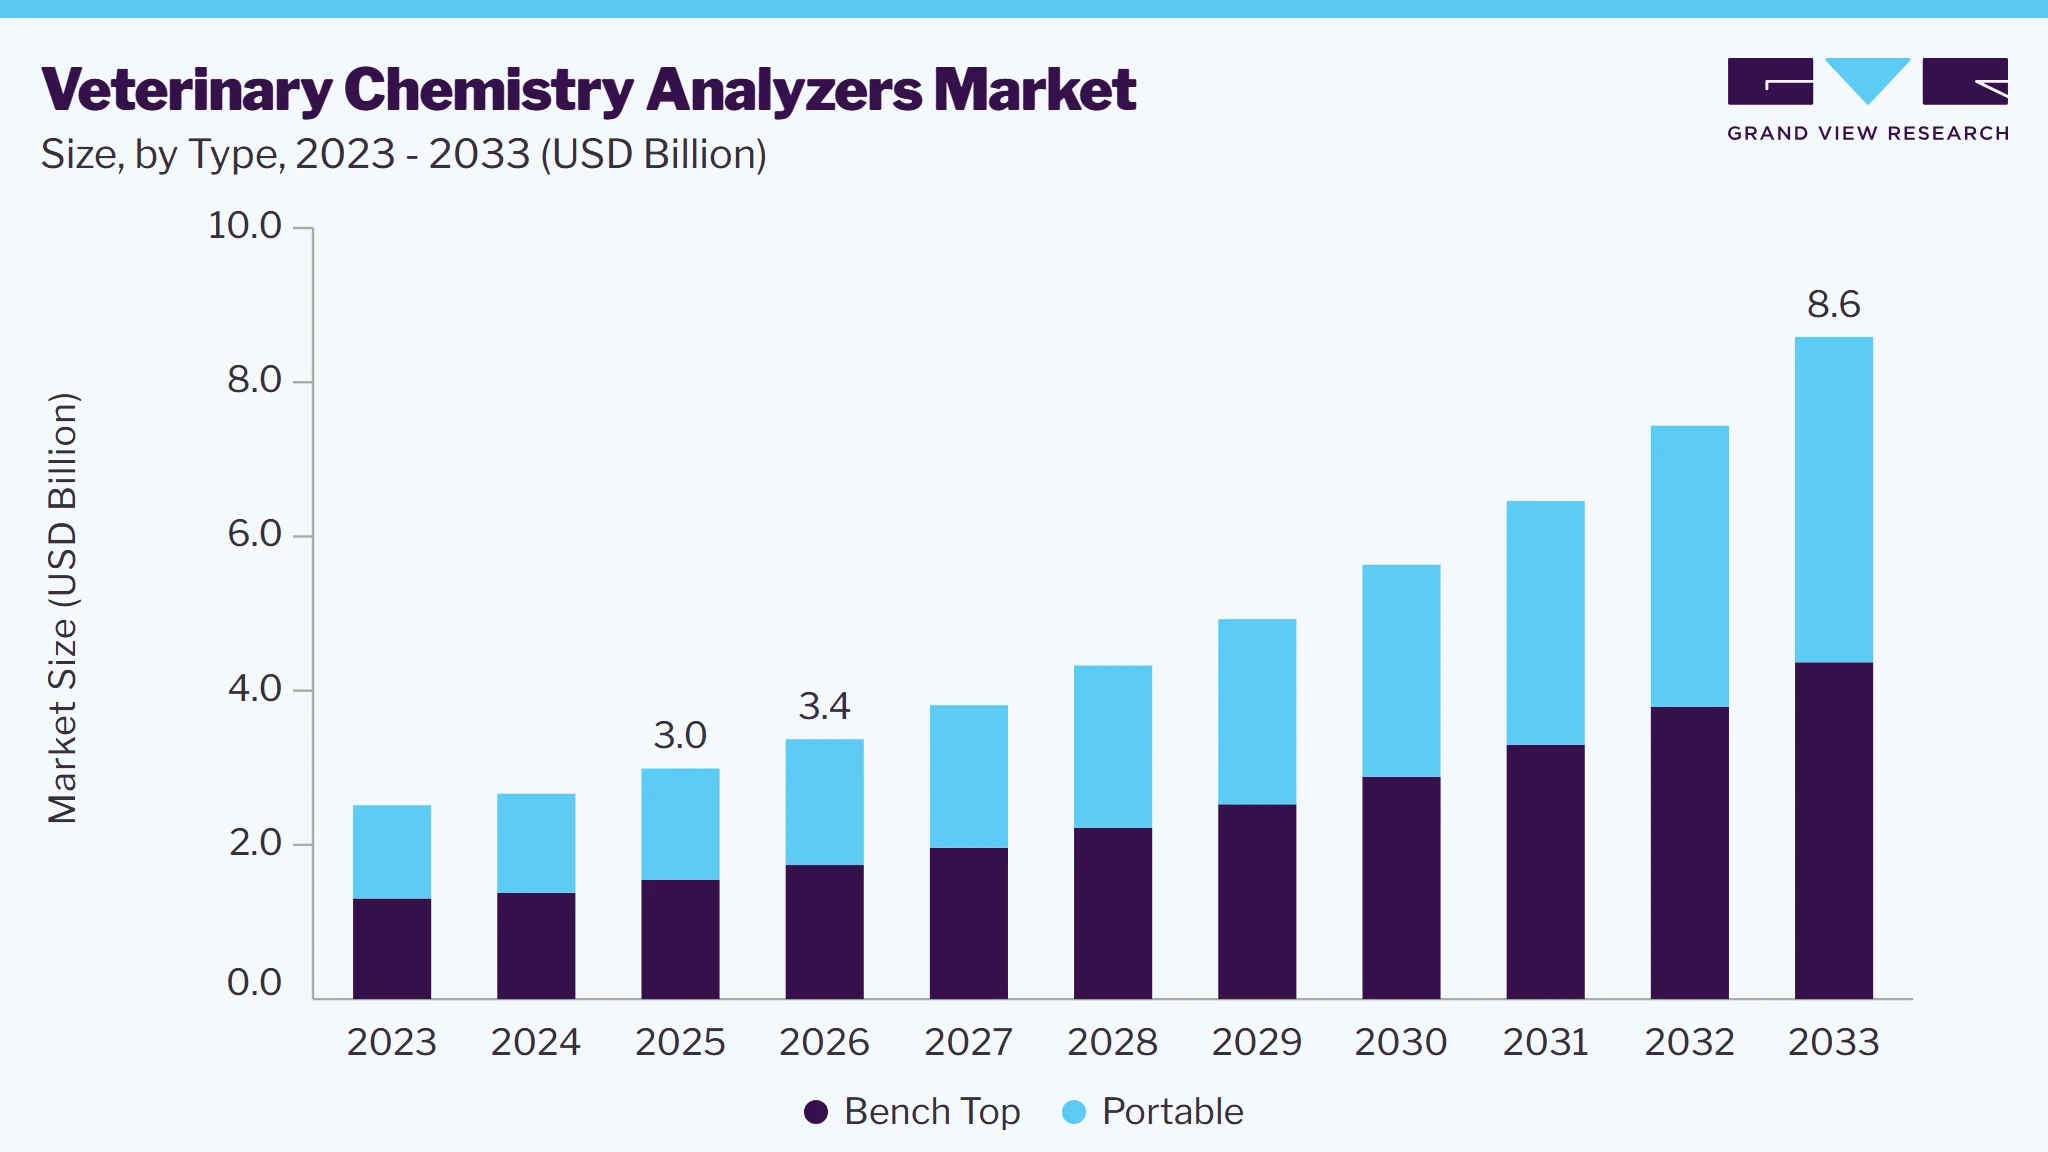
The global veterinary chemistry analyzer market size was valued at USD 3.0 billion in 2025 and is projected to grow from USD 3.4 billion in 2026 to USD 8.6 billion by 2033, at a CAGR of 14.3% from 2026 to 2033. North America dominated the veterinary chemistry analyzer market with the largest revenue share of 52.5% in 2025. The market is anticipated to develop due to the humanization of pets worldwide, increased investment in the animal health sector, novel technologies and developments in bringing testing to the point of care (POC), increased hospital pet visits, and increased POC diagnostics usage.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Bench top segment held the largest market share of 51.7% in 2025.
- By product: Consumables segment held the largest market share of 56.7% in 2025.
- By species: Canine segment held the largest market share of 36.1% in 2025.
- By application: Blood chemistry analysis segment held the largest market share of 40.0% in 2025.
Regional Highlights
- Largest regional market: North America (52.5% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 3.0 Billion
- Estimated market size in 2026: USD 3.4 Billion
- Projected market size by 2033: USD 8.6 Billion
- CAGR (2026-2033): 14.3%
Prism AI by Grand View Research Free to tryAsk a question about the veterinary chemistry analyzer marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
For instance, according to a study published by the American Veterinary Medical Association in October 2024, in the 2024 survey, 80% of pet owners indicated they had visited the veterinarian at least once in the past six months, with almost two-thirds making one to three visits, a rise of four percentage points compared to 2022. This surge in demand for veterinary services is driving greater use of diagnostic tools, including chemistry analyzers, to enable faster, more accurate health assessments in clinics. As a result, the market for these analyzers is experiencing robust growth to meet the rising need for efficient veterinary diagnostics.Additionally, the market for veterinary chemistry analyzers is predicted to grow due to the increased demand for pet insurance and increased pet adoption globally. The demand for pet insurance has grown due to rising veterinary expenses. Pet diagnostic tests can be expensive, and the high cost deters many pet owners from choosing treatment options. For eligible accidents and diseases, the majority of pet insurance policies will pay for diagnostics and treatments. For instance, if the "Preventative and Wellness" package is added to a Lemonade pet health insurance policy, annual wellness checkups, pet diagnostics such as x-rays, cytology, bloodwork, lab work, urinalysis, a heartworm test, and more will be covered.
 To learn more about this report, Download Free Sample Report
However, an unprecedented rise in the adoption of companion animals to alleviate psychological stress imposed by the coronavirus pandemic may promote industry recovery in the coming years. Dog-owning households surged from 31.3 million in 1996 to 59.8 million in 2024, while cat-owning households increased from 27 million to 42.1 million. As of 2024, dog-owning households represent nearly 45.5% of all U.S. households, up from 31.6% in 1996. Cat-owning households now account for 32.1%, compared to 27.3% in 1996. Furthermore, the growing prevalence of animal-to-human infections and the increasing demand for animal protein may drive growth in the veterinary chemistry analyzer market.
Clinical diagnostics are now accessible, affordable, quick, and simple to use since the development of point-of-care testing. The importance of this platform lies in its ability to enable patients to monitor their health more frequently from the comfort of their homes, allowing for the earliest possible diagnosis of diseases. For instance, veterinary glucometers are attributed to their ease of use in clinical settings, the workplace, and at home. An easy-to-use veterinary blood glucose monitoring system, AlphaTRAK from Zoetis, is available for cats and dogs. Additionally, a rise in the prevalence of diabetes in animals is another factor that increases the demand for analyzers.
In veterinary medicine, the overuse and misuse of antimicrobials are largely responsible for the development of antibiotic resistance. Antimicrobial resistance is currently regarded as one of the significant concerns to public health globally. Chemistry analyzer tests could enable veterinarians to identify if a patient's sickness is caused by bacteria earlier in the course of treatment, resulting in the prescription of fewer antibiotics when they are not necessary. As a result, this significantly contributes to reducing the overuse of antibiotics and promoting good antimicrobial stewardship, which in turn encourages overall market expansion.
Market Dynamics
The veterinary chemistry analyzer market is experiencing steady growth, driven by increasing pet ownership, rising livestock healthcare expenditure, and growing demand for rapid, accurate diagnostic testing. The market is witnessing rising prevalence of chronic diseases, metabolic disorders, kidney diseases, diabetes, and infectious conditions in companion and production animals that is encouraging routine biochemical testing across veterinary hospitals, clinics, and diagnostic laboratories.
In addition, technological advancements such as automated analyzers, point-of-care testing systems, cloud-enabled data management, AI-assisted diagnostics, and integrated laboratory information systems are improving diagnostic efficiency and clinical decision-making. Furthermore, growing awareness of preventive veterinary care and wellness screening is increasing demand for blood chemistry, urinalysis, electrolyte analysis, and glucose monitoring. However, high equipment costs, recurring consumable expenses, and limited access to advanced diagnostic infrastructure in developing regions continue to restrict adoption. Despite these challenges, expanding veterinary infrastructure, increasing investment in animal health, rising demand for portable analyzers, and continuous product innovation are expected to create significant growth opportunities for market participants over the forecast period.
Driver: Rising Prevalence of Chronic Diseases and Increasing Demand for Early Veterinary Diagnostics
The increasing prevalence of chronic and metabolic diseases among companion and livestock animals is a major driver of the market. Rising cases of diabetes, kidney disease, liver disorders, endocrine conditions, obesity, and infectious diseases have significantly increased the demand for routine biochemical testing. According to a publication of November 2025, studies indicated that over half of companion dogs and cats were overweight or obese, contributing to a growing incidence of diabetes, particularly in cats. In addition, in livestock production, approximately 20% of intensively raised pigs develop osteoarthritis, increasing the need for routine veterinary diagnostic testing and disease monitoring. In addition, aging pet populations and growing awareness of preventive healthcare are encouraging veterinarians to perform regular blood chemistry analysis, urinalysis, electrolyte testing, and glucose monitoring for early disease detection and continuous patient management. In livestock production, chemistry analyzers support herd health monitoring, disease surveillance, nutritional assessment, and productivity optimization, helping producers minimize economic losses.
Furthermore, increasing pet owner willingness to invest in advanced diagnostics and the growing adoption of wellness screening programs are expanding analyzer utilization across veterinary hospitals, clinics, and diagnostic laboratories. The availability of automated, high-throughput, and point-of-care chemistry analyzers enables faster clinical decision-making, improves treatment outcomes, and supports the transition toward preventive and precision veterinary medicine, further accelerating market growth.
The high acquisition cost of veterinary chemistry analyzers, coupled with ongoing expenses for reagents, cartridges, calibration materials, and maintenance, remains a significant restraint on market growth. The advanced automated analyzers require substantial upfront investment, making adoption difficult for small veterinary clinics, independent practices, rural hospitals, and animal shelters with limited budgets. In addition to equipment costs, recurring expenditures on proprietary consumables, software updates, service contracts, and quality control materials increase the overall cost of ownership. Budget-conscious veterinary practices often continue relying on external diagnostic laboratories instead of investing in in-house chemistry analyzers, particularly where testing volumes are low. Financial constraints are even more pronounced in developing regions, where limited veterinary infrastructure and lower healthcare spending reduce purchasing capacity. Although technological advancements are improving analyzer efficiency and reducing turnaround times, affordability remains a key challenge.
The growing adoption of point-of-care (POC) diagnostics presents a significant opportunity for the market. Veterinary hospitals, clinics, ambulatory practices, and livestock farms increasingly require rapid, on-site biochemical testing to support timely clinical decisions and improve patient outcomes. Some of the compact, portable chemistry analyzers capable of delivering accurate results within minutes gaining preference as they reduce dependence on centralized laboratories and shorten treatment initiation times. In addition, advances in AI-powered diagnostics, cloud connectivity, and integrated data management further enhance the value of POC systems by enabling real-time result interpretation and seamless patient record integration. For instance, in April 2026, Zoetis expanded its AI-powered Vetscan OptiCell hematology analyzer with cellular hemoglobin concentration mean (CHCM) and plateletcrit (PCT), delivering reference laboratory-quality complete blood count insights directly at the point of care to improve diagnostic accuracy and clinical decision-making. Moreover, expanding veterinary infrastructure, increasing demand for preventive healthcare, and rising investments in companion animal and livestock diagnostics are expected to accelerate adoption of portable chemistry analyzers, creating substantial growth opportunities for manufacturers globally.
Market Concentration & Characteristics
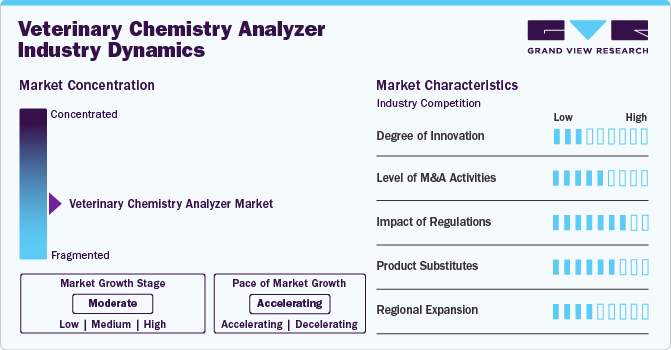
The market is characterized by moderate industry concentration, with a mix of established companies and emerging players. Key players include IDEXX Laboratories, Abaxis, and Zoetis, which dominate the market through innovative product offerings and extensive distribution networks. However, the presence of smaller companies and startups contributes to competitive dynamics, driving innovation and potentially enhancing service offerings.
The market demonstrates a high degree of innovation, driven by advancements in automation, AI integration, and point-of-care (POC) technology. Modern analyzers are now equipped with capabilities such as automated sample handling, cloud-based data storage, and streamlined interfaces for enhanced usability, enabling veterinarians to obtain accurate results quickly and efficiently. The market has seen significant growth in AI-powered diagnostic analyzers, which offer rapid, lab-quality accuracy at the POC, reducing turnaround time for critical decisions. For instance, in January 2024, IDEXX Laboratories introduced IDEXX inVue Dx Cellular Analyzer, a slide-free, AI-powered tool that delivers rapid, reference-quality cytology and blood morphology results in just 10 minutes. Offering 3D cellular imaging and real-time diagnostics enhances diagnostic accuracy and integrates seamlessly with IDEXX's ecosystem to support seamless veterinary workflows.
 To learn more about this report, Download Free Sample Report
The market has seen steady M&A activity as companies aim to strengthen diagnostic offerings, expand geographic reach, and integrate advanced technologies. Key players have been acquiring specialized diagnostics and analytics firms, targeting companies that provide innovative testing solutions, such as rapid biochemical analysis and point-of-care diagnostics. This M&A trend is driven by a growing need for enhanced diagnostic capabilities in response to increasing pet ownership, livestock health demands, and evolving veterinary care standards. For instance, in February 2024, Herdwatch acquired ComTag in Ireland and Lilac Technology in the UK, expanding its reach in the veterinary sector with software solutions for TB and blood testing. These acquisitions aim to integrate over 1,000 veterinary professionals onto the Herdwatch platform, enhancing veterinary practice management and strengthening Herdwatch’s position as a leading livestock management software provider in the UK and Ireland.
Regulations in the market significantly impact product development, compliance costs, and market entry timelines. Stricter standards, particularly in regions with advanced animal healthcare policies like the EU and the U.S., mandate rigorous testing, calibration, and quality control to ensure analyzer accuracy and safety. Compliance with these regulatory frameworks, such as the EU's In Vitro Diagnostic Regulation (IVDR) and the U.S. FDA's guidelines, raises operational costs but improves market credibility and product reliability. These regulations drive innovation as manufacturers develop analyzers that meet precise diagnostic needs while adhering to regulatory standards, ultimately enhancing diagnostic outcomes in veterinary practices.
The product substitutes include handheld diagnostic devices, rapid test kits, and point-of-care (POC) analyzers. Handheld devices and test kits offer quick, on-site testing that is convenient and cost-effective, and are often preferred for preliminary diagnostics in smaller practices. POC analyzers, while similar in function, are generally more compact and integrated with practice management systems, providing results rapidly with lower maintenance needs. These substitutes, though often less comprehensive than full-scale chemistry analyzers, appeal to veterinarians seeking efficiency and affordability in routine diagnostics, especially in rural or mobile veterinary settings.
The market is experiencing regional expansion driven by increasing pet ownership and the demand for advanced diagnostic tools, particularly in North America and Europe. Emerging markets in Asia-Pacific and Latin America are also seeing growth due to rising veterinary care standards and the integration of technology into animal healthcare, leading to greater adoption of automated, efficient diagnostic solutions. This trend reflects a global push to enhance veterinary practices and improve animal health outcomes.
Analyst Perspective
The veterinary chemistry analyzer market is experiencing steady growth, driven by rising pet ownership, increasing incidence of chronic and zoonotic diseases in companion and livestock animals, and growing awareness of preventive animal healthcare. In addition, demand for rapid, accurate point-of-care diagnostics is propelling veterinary clinics and hospitals toward compact, automated benchtop analyzers that reduce turnaround time and reliance on external labs. In addition, technological advancements such as AI-integrated diagnostics, cloud connectivity, and multi-parameter testing are enhancing accuracy and workflow efficiency, encouraging adoption even among small and mid-sized practices. Furthermore, emerging economies represent significant growth opportunities due to expanding veterinary infrastructure and rising animal healthcare expenditure. However, high equipment costs and limited skilled personnel in developing regions remain restraints. Thus, the market is expected to maintain a positive growth momentum, supported by innovation, rising companion animal insurance penetration, and increasing focus on livestock productivity and food safety monitoring worldwide.
Type Insights
Based on type, the bench top segment led the market with the largest revenue share of 51.7% in 2025. Advantages associated with benchtop analyzers, such as automation of tasks, reduced manual errors, high accuracy, and precision, drive global demand. These analyzers are efficient at diagnosing certain diseases in companion animals, which is one of the major factors contributing to the segment's largest share. The EasyRA benchtop analyzer is a fully automated chemistry analyzer that meets veterinary practices' low-cost, high-speed requirements. EasyRA is operational quickly, ready to run samples, and can analyze them in less than 8 minutes.
Portable analyzers are expected to experience robust growth over the forecast period. Portable analyzers enable bedside monitoring and are mobile. Ease of use, the ability to monitor pets at home, portability, on-the-spot results, and lower training requirements are some of the factors driving segment growth. Soaring demand for point-of-care analyzers is further spurring the growth of the segment. For instance, in January 2023, EKF Diagnostics launched the Lactate Scout Vet, a handheld lactate analyzer tailored for veterinary use. This device enables species selection for dogs, horses, pigs, and cattle, making it suitable for both small- and large-animal practices. The Lactate Scout Vet is designed to provide quick, cost-effective lactate testing, aiding in the diagnosis and prognosis of various clinical conditions while enhancing triage and risk stratification for veterinarians. Therefore, the global market expansion of products is anticipated to fuel market growth.
Product Insights
Based on product, the consumables segment led the market with the largest revenue share of 56.7% in 2025. Consumables can be further divided into reagents, panels, and strips. Reagents accounted for approximately half of the consumables segment in 2024. Continuous requirement of consumables is likely to augment the overall market. Also, recurring purchase requirements for consumables and easy-to-use reagents, and the availability of most reagents in liquid form, which require no preparation, are factors driving the segment's growth.
The instruments segment is projected to grow at a significant CAGR during the forecast period due to technological advancements in products. The segment has been further categorized into chemistry analyzers, blood gas & electrolyte analyzers, urine analyzers, and glucometers. The introduction of automated benchtop and portable analyzers, such as Element POC (Heska Corporation), Catalyst One (IDEXX), RX Series (Randox Laboratories Ltd.), and others, is poised to propel the growth of the market. For instance, in August 2023, Seamaty launched four innovative veterinary analyzers designed for pet hospitals, enhancing point-of-care diagnostics. These analyzers include the VG2 Blood Gas Electrolyte Immunoassay Analyzer, VG1 Blood Gas & Electrolyte Analyzer, Vi1 Fluorescence Immunoassay Analyzer, and VBC30 and VBC50 Hematology Analyzers.
Species Insights
Based on species, the canine segment led the market with the largest revenue share of 36.1% in 2025 due to the significant disease prevalence and rising adoption rates of dogs. The increasing incidence of obesity, diabetes, cancer, and other significant diseases is one of the major drivers for the market. According to the Morris Animal Foundation study published in August 2023, approximately 56% of dogs and 60% of cats in the U.S. are classified as overweight or obese. Additionally, around 30% of horses are also considered obese. As these health issues become more prevalent among companion animals, the demand for diagnostic tools that enable quick and accurate assessments of pet health is increasing. Veterinary chemistry analyzers play a crucial role in the early detection and management of these conditions, allowing veterinarians to provide timely interventions and improve patient outcomes.
The feline segment is anticipated to register the fastest CAGR during the forecast period, owing to the increasing cat adoption rates in households of both developing and developed economies. Prevalent conditions in cats, such as endocrine diseases, chronic kidney diseases, and diabetes, have further raised the demand for point-of-care diagnostics, presenting the segment with lucrative growth opportunities. Furthermore, the companies are constantly investing in R&D to develop innovative diagnostics tests for cats and dogs to gain market share. For example, in June 2023, IDEXX Laboratories launched the IDEXX Cystatin B Test, the first veterinary diagnostic test for detecting kidney injury in cats and dogs, enabling earlier intervention and improved patient outcomes. This test complements existing renal health assessments, such as IDEXX SDMA and creatinine tests, by identifying kidney injury even before changes in kidney function occur.
End-use Insights
Based on end use, the veterinary laboratories segment led the market with the largest revenue share of 36.8% in 2025. The rising incidence of diseases such as diabetes, renal disease, cancer, and abnormalities resulting from long-term medications in animals are some of the major factors estimated to contribute to the growth of the segment. The major role of veterinary laboratories is diagnostic services and pathology. The veterinary laboratories widely work on pathology, which covers investigating veterinary diseases. The growing number of advanced laboratories with better infrastructure is another factor propelling the segment's growth.
 To learn more about this report, Download Free Sample Report
Over the forecast period, the Point-Of-Care Testing segment is anticipated to grow faster than other market segments. The segment growth is estimated to be driven by the growing adoption of rapid diagnostic tools. Furthermore, increasing awareness regarding animal health is projected to fuel the segment's growth. Specific advantages of point-of-care instruments, such as cost-effectiveness and simplicity of use, are further expected to drive market growth.
Application Insights
Based on application, the blood chemistry analysis segment led the market with the largest revenue share of 40.0% in 2025, owing to the increasing incidence of zoonotic diseases and the rising number of veterinary practitioners. According to the WHO, it is estimated that zoonoses cause about a billion cases of disease and millions of fatalities each year globally. Zoonoses account for over 60% of newly reported infectious diseases globally.
On the other hand, the blood gas & electrolyte analysis segment is expected to register lucrative growth during the forecast period. The introduction of point-of-care analyzers is leading to an upswing in the demand for blood gas and electrolyte analysis. A growing need for analysis that facilitates testing of electrolytes and blood counts in samples of serum, plasma, or urine is anticipated to boost the segment's growth.
Idexx offers a Catalyst One Chemistry Analyzer that can run any of 34 parameters for electrolyte, chemistry, and immunoassay profiles in a single whole-blood run. This analyzer is the perfect fit for clinics of any size and provides testing flexibility.
Regional Insights
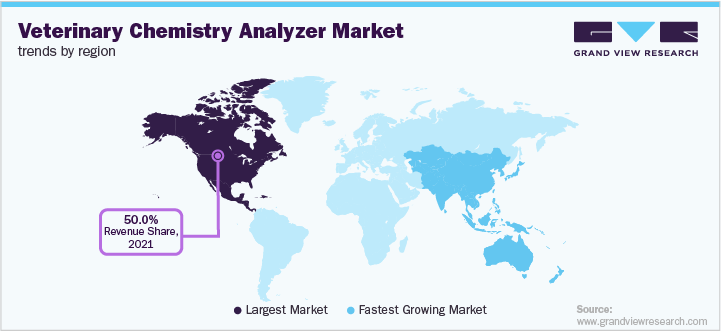
North America dominated the veterinary chemistry analyzer market with the largest revenue share of 52.5% in 2025. North America has numerous animal health and diagnostics companies. There has been a significant rise in veterinary healthcare expenditure in the region, which is expected to accelerate the growth of the market. Moreover, well-developed infrastructure and high R&D spending in the region are factors anticipated to boost the market in the North America region.
 To learn more about this report, Download Free Sample Report
U.S. Veterinary Chemistry Analyzer Market Trends
The veterinary chemistry analyzer market in the U.S. held the largest share in the North America region in 2025. This can be attributed to the presence of significant players in the country, such as Zoetis and IDEXX, who are involved in the development and introduction of analyzers required to diagnose various diseases in animals. Furthermore, technological advancements and a growing focus on improving pet healthcare drive regional markets. Manufacturers are continuously developing new devices with enhanced features such as improved accuracy, ease of use, and real-time data tracking capabilities. For example, in February 2023, Zoetis launched the AlphaTrak 3 blood glucose monitoring system for diabetic cats and dogs in the U.S., featuring a new mobile app for data collection and sharing between pet owners and veterinarians.
Europe Veterinary Chemistry Analyzer Market Trends
The veterinary chemistry analyzer market in Europe is driven by several key factors, including the rising prevalence of animal diseases, increasing pet ownership, and advancements in diagnostic technology. For example, the launch of IDEXX's Cystatin B Test allows for early detection of kidney injury in pets, addressing the growing need for precise veterinary diagnostics. Additionally, the integration of AI-powered analyzers, like Zoetis' Vetscan OptiCell, enhances diagnostic efficiency and accuracy, further propelling the market growth.
The UK veterinary chemistry analyzer market accounted for the largest share of the European market in 2024. The UK market is experiencing significant growth owing to an increase in product launches. Manufacturers are continuously innovating and expanding their product lines to meet the rising demand for advanced diagnostic solutions in veterinary practices. For example, according to data published by Zoetis in September 2024, Zoetis will introduce the Vetscan OptiCell, the first AI-powered cartridge-based hematology analyzer, at the London Vet Show on November 14-15, 2024. This innovative device offers Complete Blood Count analysis with laboratory-quality accuracy at the point of care, improving clinic efficiency while minimizing costs and maintenance.
Asia Pacific Veterinary Chemistry Analyzer Market Trends
The veterinary chemistry analyzer market in the Asia Pacific is projected to be the fastest-growing market with a CAGR of 16.3% over the forecast period due to the growing animal population, rising awareness about animal health, and increasing adoption of pets. Pet adoption in Asia has surged over the past decade, with 60% of residents now owning a pet. Notably, 32% of the population consider their cats and dogs their closest companions. Countries such as China and India are expected to witness rapid market growth owing to an increase in the number of manufacturing facilities in the region. Growing R&D investment by market players for the development of value-added devices is anticipated to drive market growth in the region.
India veterinary chemistry analyzer market is witnessing notable growth owing to rising pet ownership rates, increased awareness of animal health, and the growing demand for rapid and accurate diagnostic solutions in veterinary practices. For example, as more households adopt pets, there is a corresponding need for advanced veterinary diagnostics, leading to increased investment in veterinary chemistry analyzers to ensure timely and effective animal healthcare.
Latin America Veterinary Chemistry Analyzer Market Trends
The veterinary chemistry analyzer market in Latin America is primarily driven by increasing pet ownership, a growing emphasis on animal healthcare, and advancements in veterinary diagnostics technology. For instance, as more families adopt pets in countries like Brazil and Argentina, the demand for comprehensive veterinary services rises, leading to increased investment in veterinary chemistry analyzers for accurate and timely diagnosis. Additionally, the expansion of veterinary clinics and animal hospitals in urban areas further propels the market, facilitating access to advanced diagnostic tools for better animal health management.
Brazil veterinary chemistry analyzer market is driven by rising pet ownership, increasing awareness of animal health, and technological advancements in veterinary diagnostics. The growing trend of pet adoption, particularly among urban families, has increased the demand for regular veterinary checkups and diagnostics, including blood chemistry analysis. For example, cities like São Paulo are seeing a surge in veterinary clinics equipped with advanced chemistry analyzers to provide timely, accurate diagnostics, thereby enhancing overall animal healthcare.
Middle East & Africa Veterinary Chemistry Analyzer Market Trends
The veterinary chemistry analyzers market in the Middle East and Africa is driven by the increasing prevalence of diabetes in pets, advancements in pet healthcare technology, the growing pet population, rising awareness about pet health, and the availability of innovative glucose monitoring devices. These factors collectively contribute to the expansion of the market for veterinary chemistry analyzers in the Middle East and Africa region. Additionally, increased spending on animal health care and wellness, supported by a growing middle class and awareness of pet health, is propelling the market.The
Saudi Arabia veterinary chemistry analyzer market is driven by several factors, including increasing pet ownership, rising awareness of animal health, and government initiatives aimed at improving veterinary services. The growing trend of pet adoption, particularly among urban populations, has led to increased demand for routine veterinary care and diagnostics. For example, the establishment of specialized veterinary clinics in major cities like Riyadh and Jeddah reflects this trend, as these clinics are increasingly equipped with advanced veterinary chemistry analyzers to provide accurate and timely health assessments. Additionally, the Saudi government is promoting veterinary practices through regulations and initiatives to enhance animal welfare, further stimulating market growth.
Key Veterinary Chemistry Analyzer Company Insights
Competition in the overall markets is intense. The veterinary chemistry analyzers market is a well-established field with numerous competitors that have substantially greater financial resources and larger, more established marketing, sales, and service organizations. Market players are focusing on the development of new products and are entering into distribution and supply agreements with other players to achieve a higher market share.
Key Veterinary Chemistry Analyzer Companies:
The following are the leading companies in the veterinary chemistry analyzer market.
- IDEXX Laboratories, Inc.
- Zoetis
- Mars Inc. (Heska Corporation)
- HORIBA Medical
- URIT Medical Electronic Co., Ltd.
- Randox Laboratories Ltd.
- Shenzhen Mindray Animal Medical Technology Co., LTD.
- Chengdu Seamaty Technology Co., Ltd.
- SKYLA CORPORATION
- Bioevopeak Co., Ltd.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (IDEXX Laboratories, Inc.; Zoetis; Mars Inc. (Heska Corporation); HORIBA Medical; URIT Medical Electronic Co. Ltd.; Randox Laboratories Ltd)
- Focus on integrated diagnostic portfolios by combining chemistry analyzers with hematology, immunoassay, and digital data management platforms. Invest heavily in R&D, strengthen distribution partnerships, provide technical support and training, and introduce automated, high-throughput analyzers. Strategic acquisitions, software integration, and recurring consumables sales help reinforce customer retention and long-term revenue growth.
- Benefit from strong brand recognition, extensive installed analyzer bases, broad product portfolios, and validated diagnostic accuracy. Competitive advantage is reinforced through proprietary reagents, integrated laboratory information systems, global distribution networks, after-sales service, regulatory expertise, and continuous innovation. Long-standing relationships with veterinary hospitals, laboratories, and diagnostic chains strengthen leadership and customer loyalty.
- Face high equipment costs, dependence on consumable revenues, and slower adaptation to disruptive technologies introduced by emerging competitors.
Emerging Players (Shenzhen Mindray Animal Medical Technology Co., LTD.; Chengdu Seamaty Technology Co., Ltd.; SKYLA CORPORATION; Bioevopeak Co., Ltd.)
- Focus on developing cost-effective, portable, and user-friendly veterinary chemistry analyzers tailored for point-of-care testing. Emphasize product innovation, AI-enabled data management, cloud connectivity, strategic partnerships with veterinary clinics and distributors, and expansion into underserved markets. Competitive pricing, product launches, and regulatory approvals help strengthen market presence and customer confidence.
- Gain advantage through agile innovation, affordable diagnostic solutions, compact analyzer designs, and digital integration features. Their ability to rapidly incorporate cloud-based data management, wireless connectivity, and user-friendly interfaces addresses evolving veterinary practice needs. Flexible business models, customized customer support, and faster product development cycles enable effective competition against established market leaders.
- Face limited brand recognition, smaller distribution networks, constrained financial resources, and lower R&D budgets compared with established competitors.
Recent Developments
-
In September 2024, Zoetis Inc. introduced Vetscan OptiCell, a new cartridge-based hematology analyzer that employs AI-powered technology to deliver precise Complete Blood Count (CBC) analysis at the point of care, offering lab-quality results with time, cost, and space efficiencies for veterinary clinics.
-
In July 2024, EKF Diagnostics launched the Biosen C-Line, an advanced glucose and lactate analyzer designed for enhanced usability, featuring a touchscreen and advanced connectivity options that integrate seamlessly with hospital and lab IT systems via EKF Link. This benchtop analyzer provides highly precise glucose and lactate measurements, used in clinical settings for diabetes management and by elite sports teams to track lactate production during training.
Veterinary Chemistry Analyzer Market Report Scope
Report Attribute
Details
Market size in 2025
USD 3.0 billion
Estimated market size in 2026
USD 3.4 billion
Projected market size by 2033
USD 8.6 billion
Growth rate
CAGR of 14.3% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, product, species, application, end use and region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; South Korea; Australia; Thailand; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait; Oman; Qatar.
Key companies profiled
IDEXX Laboratories, Inc.; Zoetis; Mars Inc. (Heska Corporation); HORIBA Medical; URIT Medical Electronic Co. Ltd.; Randox Laboratories Ltd.; Shenzhen Mindray Animal Medical Technology Co., LTD.; Chengdu Seamaty Technology Co., Ltd.; SKYLA CORPORATION; Bioevopeak Co., Ltd.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Veterinary Chemistry Analyzer Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global veterinary chemistry analyzer market report based on type, product, species, application, end-use, and region:
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Bench Top
-
Portable
-
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Consumables
-
Reagents
-
Panels
-
Strips
-
-
Instruments
-
Blood Chemistry Analyzers
-
Urine analyzer
-
Blood Gas & Electrolyte Analyzer
-
Glucometers
-
-
-
Species Outlook (Revenue, USD Million, 2021 - 2033)
-
Cattle
-
Canine
-
Feline
-
Caprine
-
Equine
-
Ovine
-
Porcine
-
Avian
-
Others
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Blood Chemistry Analysis
-
Urinalysis
-
Blood Gas & Electrolyte Analysis
-
Glucose Monitoring
-
-
End-use Outlook (Revenue, USD Million, 2021 - 2033)
-
Veterinary Laboratories
-
Veterinary Hospitals and Clinics
-
Point-Of-Care Testing
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
Sweden
-
Denmark
-
Norway
-
Rest of Europe
-
-
Asia Pacific
-
Japan
-
China
-
India
-
South Korea
-
Australia
-
Rest of Asia Pacific
-
-
Latin America
-
Brazil
-
Argentina
-
Rest of Latin America
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
Rest of the Middle East & Africa
-
-
Research Methodology
The veterinary chemistry analyzer market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each veterinary chemistry analyzer segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Type
Revenue Capture Definition
Bench Top
Bench top analyzers are stationary diagnostic systems offering high-throughput testing, comprehensive chemistry panels, greater automation, and enhanced analytical accuracy for veterinary laboratories and large clinical facilities.
Portable
Portable analyzers are compact, lightweight diagnostic devices designed for rapid on-site biochemical testing, enabling immediate clinical decision-making in veterinary clinics, ambulatory practice, farms, and emergency settings.
Segment - Product
Revenue Capture Definition
Consumables
Consumables include disposable testing materials such as reagents, strips, panels, cartridges, calibrators, and quality-control products that are routinely replaced during veterinary diagnostic procedures.
Reagents
Reagents are specialized chemical formulations that react with biological samples to measure biochemical parameters accurately, supporting reliable veterinary chemistry analysis and consistent diagnostic performance.
Panels
Panels are preconfigured test combinations designed to simultaneously evaluate multiple biochemical markers, improving diagnostic efficiency for organ function assessment, metabolic disorders, and routine veterinary health screening.
Strips
Diagnostic strips are disposable testing materials primarily used for urine and point-of-care biochemical analysis, providing rapid qualitative or semi-quantitative results in veterinary clinical practice.
Instruments
Instruments comprise automated veterinary chemistry analyzers and related diagnostic systems that process biological samples, measure biochemical parameters, and generate accurate laboratory results for clinical decision-making.
Urine Analyzer
Urine analyzers evaluate physical, chemical, and microscopic urine characteristics to diagnose urinary tract diseases, kidney disorders, metabolic abnormalities, and systemic health conditions in animals.
Blood Gas & Electrolyte Analyzer
These analyzers measure blood pH, oxygen, carbon dioxide, and electrolyte concentrations, supporting assessment of respiratory function, acid-base balance, hydration status, and critical care management.
Glucometers
Glucometers are portable diagnostic devices used to rapidly measure blood glucose concentrations, supporting diabetes diagnosis, insulin therapy monitoring, and emergency management of glycemic disorders in animals.
Segment - Species
Revenue Capture Definition
Cattle
Includes dairy and beef cattle undergoing biochemical testing for metabolic disorders, infectious diseases, reproductive health, nutritional management, and routine herd health monitoring.
Canine
Covers dogs receiving chemistry testing for disease diagnosis, preventive wellness screening, chronic disease management, surgical evaluation, and monitoring of therapeutic interventions in companion animal practice.
Feline
Includes cats undergoing biochemical analysis for kidney disease, liver disorders, endocrine conditions, diabetes, urinary diseases, and routine preventive health assessments.
Caprine
Covers goats undergoing chemistry testing to evaluate metabolic health, infectious diseases, nutritional deficiencies, reproductive performance, and general herd health management.
Equine
Includes horses requiring biochemical analysis for performance monitoring, metabolic disorders, dehydration, organ function assessment, infectious diseases, and pre-surgical evaluation.
Ovine
Covers sheep receiving veterinary chemistry testing for nutritional disorders, metabolic diseases, reproductive health, infectious conditions, and flock health management programs.
Porcine
Includes pigs undergoing biochemical testing for disease surveillance, metabolic health, nutritional assessment, reproductive management, and commercial swine production monitoring.
Avian
Covers poultry and companion birds utilizing chemistry analyzers for disease diagnosis, nutritional evaluation, organ function assessment, and flock health monitoring.
Others
Includes camelids, rabbits, reptiles, exotic animals, wildlife, and other species requiring veterinary chemistry analysis for specialized diagnostic and health management applications.
Segment - Application
Revenue Capture Definition
Blood Chemistry Analysis
Involves measuring biochemical constituents in blood to evaluate organ function, metabolic disorders, nutritional status, disease progression, and therapeutic response in veterinary patients.
Urinalysis
Urinalysis evaluates urine composition and physical characteristics to detect urinary tract disorders, kidney disease, diabetes, dehydration, infections, and metabolic abnormalities.
Blood Gas & Electrolyte Analysis
Measures acid-base balance, blood gases, and electrolyte concentrations to assess respiratory, metabolic, cardiovascular, and critical care conditions in veterinary patients.
Glucose Monitoring
Glucose monitoring involves repeated measurement of blood glucose concentrations for diagnosis and management of diabetes mellitus, hypoglycemia, and metabolic disorders in animals.
Segment - End-Use
Revenue Capture Definition
Veterinary Laboratories
Veterinary laboratories perform high-volume biochemical testing using automated analyzers, supporting disease diagnosis, research, preventive screening, and specialized diagnostic services across multiple animal species.
Veterinary Hospitals and Clinics
Veterinary hospitals and clinics utilize chemistry analyzers for routine diagnostics, emergency evaluation, wellness screening, surgical assessment, and monitoring treatment outcomes during patient care.
Point-of-Care Testing
Point-of-care testing involves rapid biochemical analysis performed near the patient, enabling immediate diagnosis, treatment decisions, and improved workflow in veterinary clinical and field settings.
Others
Includes academic institutions, research centers, zoos, wildlife rehabilitation facilities, mobile veterinary services, and government organizations utilizing veterinary chemistry analyzers for specialized diagnostic applications.
Estimation Model
Estimation Model
Points
Bottom-Up Market Estimation
The bottom-up market estimation approach calculates revenue by assessing annual sales of veterinary chemistry analyzers, consumables, and reagents across manufacturers.• Company revenues are segmented by product type, end use, geography, and species.• Primary interviews with manufacturers, distributors, veterinary hospitals, and diagnostic laboratories validate shipment volumes, average selling prices (ASPs), and utilization rates.• Aggregating country-level revenues provides regional and global market estimates.
Top-Down Market Estimation Model
The top-down approach estimates the veterinary chemistry analyzer market by evaluating the overall veterinary diagnostics market and determining the proportion attributable to chemistry analyzers.• Market shares are allocated based on analyzer type, application, species, end use, and regional adoption trends.• Historical market performance, industry reports, company financial disclosures, and macroeconomic indicators are used to validate segment contributions and forecast future market growth.
Demand-Side Market Estimation Model
The demand-side model estimates market size by analyzing the number of veterinary hospitals, clinics, diagnostic laboratories, and point-of-care facilities using chemistry analyzers.• Average analyzer installation rates, annual test volumes, consumable usage, replacement cycles, and average selling prices are incorporated into the analysis.• Demand is further validated using companion animal populations, livestock healthcare expenditure, disease prevalence, and preventive diagnostic testing trends across major regions.
Installed Base & Consumables Revenue Estimation Model
This model estimates market size by evaluating the installed base of veterinary chemistry analyzers and the recurring revenue generated from consumables, including reagents, strips, panels, and calibration materials.• Revenue is calculated using analyzer utilization rates, average tests performed per instrument, consumables consumed per test, replacement frequency, and annual service contracts.• This approach captures both one-time instrument sales and recurring revenue streams, providing a comprehensive market assessment.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Detailed Market Segmentation & End-user Analysis
Conducted a comprehensive assessment of the veterinary chemistry analyzer ecosystem covering analyzer manufacturers, consumable suppliers, veterinary hospitals, diagnostic laboratories, point-of-care settings, research institutes, and distribution partners. Evaluated the market by product type, species, application, end use, pricing trends, adoption patterns, technology penetration, and regional demand across key countries.
Delivers comprehensive market intelligence, enabling stakeholders to identify high-growth segments, understand evolving diagnostic adoption trends, prioritize investment opportunities, and develop targeted commercialization strategies across companion and livestock animal healthcare markets.
Technology Adoption & Innovation Assessment
Assessed emerging technologies including AI-powered diagnostics, cloud-enabled laboratory management, automated chemistry analyzers, portable point-of-care systems, digital reporting platforms, connectivity solutions, and workflow automation. Evaluated their clinical adoption, commercialization potential, regulatory landscape, and impact on diagnostic efficiency and veterinary practice modernization.
Supports innovation planning, product development, technology investments, and digital transformation strategies while helping companies identify future growth areas, accelerate product launches, and strengthen long-term competitiveness in rapidly evolving veterinary diagnostic markets.
Regional Opportunity & Demand Assessment
Evaluated regional market opportunities by analyzing veterinary infrastructure, pet ownership trends, livestock population, disease prevalence, diagnostic testing frequency, healthcare expenditure, regulatory environment, and analyzer adoption across North America, Europe, Asia Pacific, Latin America, and Middle East & Africa.
Facilitates data-driven regional expansion, market prioritization, distribution planning, customer targeting, and investment decisions while identifying underserved markets, emerging demand centers, and sustainable long-term revenue opportunities for veterinary diagnostic companies.
Frequently Asked Questions About This Report
The global veterinary chemistry analyzer market size was valued at USD 3.0 billion in 2025 and is estimated at USD 3.4 billion in 2026.
The global veterinary chemistry analyzer market is expected to grow at a CAGR of 14.3% from 2026 to 2033, reaching USD 8.6 billion by 2033.
Some key players operating in the veterinary chemistry analyzer market include IDEXX Laboratories, Inc., Zoetis, Mars Inc. (Heska Corporation), HORIBA Medical, URIT Medical Electronic Co. Ltd., Randox Laboratories Ltd., Shenzhen Mindray Animal Medical Technology Co., LTD., Chengdu Seamaty Technology Co., Ltd., SKYLA CORPORATION, Bioevopeak Co., Ltd.
Key factors driving the veterinary chemistry analyzer market growth include the humanization of pets worldwide, increased investment in the animal health sector, novel technologies and developments in bringing testing to the point of care (POC), increased hospital pet visits, and increased POC diagnostics usage
Asia Pacific is the fastest-growing region over the forecast period.
The bench top segment led with a 51.7% revenue share in 2025, while the portable is the fastest-growing segment.
The consumables segment led with a 56.7% revenue share in 2025, and is the fastest-growing segment.
The canine segment led with a 36.1% revenue share in 2025, while the feline is the fastest-growing segment.
North America dominated the market in 2025 by contributing over 52.5 % to the overall revenue.
About the Author(s)
Animal Health Research Team
Healthcare · Animal HealthThis report was authored by the animal health research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the animal health segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


