
- Home
- »
- Animal Health
- »
-
Veterinary Dermatology Drugs Market Size Report, 2025-2030GVR Report cover

Veterinary Dermatology Drugs Market (2025 - 2030) Size, Share & Trends Analysis Report By Indication, By Type, By Animal Type, By Route of Administration, By Distribution Channel, By Region, And Segment Forecasts
Market Size, 2024
$17.4BMarket Estimate, 2026
$20.2BMarket Forecast, 2030
$29.5BCAGR, 2025–2030
9.6%Veterinary Dermatology Drugs Market Summary
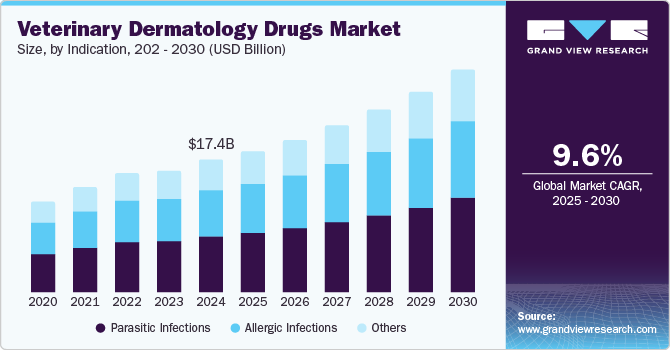
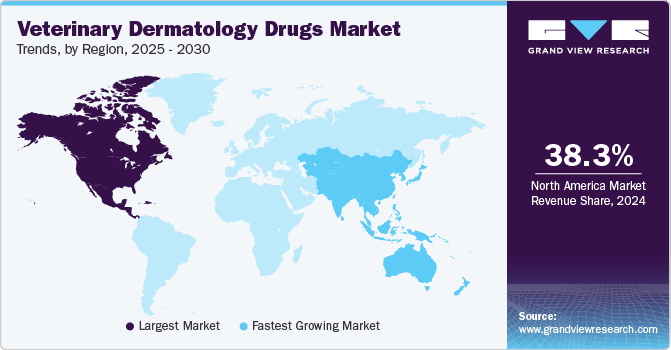
The global veterinary dermatology drugs market size was valued at USD 17.4 billion in 2024 and is projected to grow from USD 20.2 billion in 2026 to USD 29.5 billion by 2030, at a CAGR of 9.6% from 2025 to 2030. North America dominated the market, accounting for a revenue share of 38.3% in 2024. Increasing pet ownership, a growing number of clinical trials and approvals for dermatology drugs, a rising incidence of parasitic and other skin diseases in animals, and investments by market players are the key drivers of market growth.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- Asia Pacific is expected to witness the fastest CAGR over the forecast period.
- By indication, the parasitic infections segment dominated the market, holding the largest revenue share of 42.49% in 2024.
- By type, the OTC segment is anticipated to grow at the fastest CAGR of about 9.7% from 2025 to 2030.
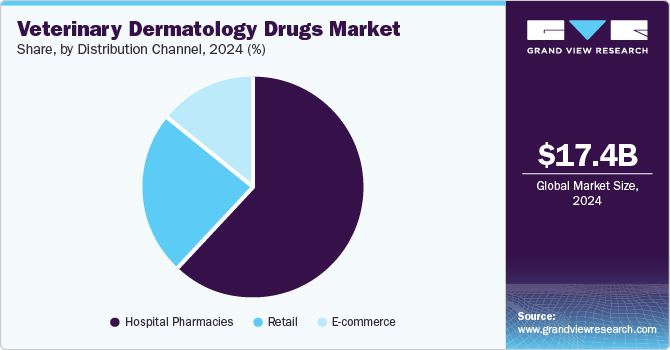
- By distribution channel, the hospital pharmacies segment dominated the market with a revenue share of 62.36% in 2024.
Market Size & Forecast
- 2024 Market Size: USD 17.4 Billion
- 2030 Projected Market Size: USD 29.5 Billion
- CAGR (2025-2030): 9.6%
- North America: Largest market in 2024
- Asia Pacific: Fastest growing market
Prism AI by Grand View Research Free to tryAsk a question about the veterinary dermatology drugs marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
For instance, in September 2024, the FDA approved Zenrelia (ilumunocitinib tablets), an oral immunosuppressant for managing itching and atopic dermatitis in dogs over 1 year old. Elanco sponsored it. Zenrelia is available by prescription and has multiple tablet strengths.Skin diseases are common in animals, affecting both domestic pets and livestock. Various factors can contribute to these conditions, including parasites, allergies, infections, environmental factors, and genetic predisposition. Some common skin diseases in animals include flea allergy dermatitis, atopic dermatitis, ringworm, and bacterial and fungal infections.
 To learn more about this report, Download Free Sample Report
According to the article published in the World Veterinary Journal in September 2024, Skin disorders are a significant issue in veterinary medicine globally, with studies showing prevalence rates of 21.4% in the UK, 17% in Iran, and 12%-27.6% in India among dogs. These conditions are a common concern in small animal practices. In addition, environmental changes, such as climate variations, pollution, and allergens, have increased skin-related problems in pets, further driving the demand for veterinary dermatology drugs.
Indication Insights
The parasitic infections segment dominated the market and held the largest revenue share of 42.49% in 2024. According to a February 2023 study published in Parasites & Vectors, the prevalence of tick infestation in Germany and Austria was estimated at about 79% in dogs and 69% in cats. This high prevalence is expected to drive the demand for medications to prevent and manage these parasites.
The allergic infections segment is expected to witness the fastest CAGR of over 9.9% during the forecast period. The rising incidence of ailments such as atopic dermatitis and other itch disorders, particularly in companion animals, is anticipated to support market growth. In addition, more pet owners are making pet care decisions, which is projected to drive market growth. Furthermore, allergic dermatitis is the most prevalent skin condition in dogs; according to 2023 Frontiers Media S.A., 20 to 30% of dogs have some form of allergic dermatitis. One of the most significant symptoms of allergic dermatitis is pruritus, which is also frequently the most difficult to treat.
Type Insights
The prescription segment dominated the veterinary dermatology drugs industry in 2024. Most dermatologist-prescribed skin drugs are taken orally, generally in the form of a delicious, chewable tablet. Veterinarians believe that some regions are experiencing increased resistance to fleas and ticks to ingredients in over-the-counter preventatives. Various compounds that may be more effective are used in prescription treatments for skin diseases. They are only available under the guidance of a veterinarian, as they have a reduced margin of error for safe, effective use.
The OTC segment is anticipated to grow at the fastest CAGR of about 9.7% from 2025 to 2030. Customers can purchase over-the-counter (OTC) dermatology products online, in shops, and in pharmacies. Over-the-counter medications are applied topically to a pet's skin to treat fleas and ticks, either as spot-on drops or as a collar that delivers the medication over time. A prescription is not necessary for the majority of topical flea and tick medications, including spot-on treatments, a Seresto collar, and flea and tick shampoo.
Animal Type Insights
The companion animals segment dominated the market in 2024 due to the rise in pet ownership, public awareness, and demand for high-quality animal care. The segment includes pet animals such as dogs, cats, horses, and rabbits. As pet ownership and adoption rates increase globally, people are more willing to make more significant financial and time commitments to the well-being of their cherished pets. In 2024, pet ownership in the U.S. has reached notable levels, with approximately 66% of households, or about 86.9 million homes, owning at least one pet. The pet population continues to grow, with the dog population peaking at 89.7 million.
The livestock animals segment is expected to witness a lucrative CAGR during the forecast period. The cost of animal healthcare is increasing, especially in industrialized economies, due to the greater adoption of farm animals, which promotes market growth. The National Agricultural Statistics Service reported in July 2024 that the total amount spent on American farms in 2023 was USD 481.9 billion, up from USD 481.9 billion in 2022. The livestock animals segment is further subdivided into cattle and others. The market for veterinary dermatology drugs is anticipated to be driven by the incidence of parasitic infections in livestock animals and the rising demand for animal protein.
Route of Administration Insights
The topical segment dominated the market in 2024 and is expected to witness a lucrative CAGR during the forecast period. Topical drugs allow direct application to the affected area, ensuring the medication is delivered precisely where needed. This targeted approach reduces the risk of systemic side effects with oral medications. When medications are applied topically, they are absorbed locally through the skin. This limited absorption into the bloodstream helps minimize the risk of systemic toxicity and interactions with other medications the animal may be taking.
Moreover, many animals may resist taking oral medications, making it challenging to ensure they receive the full course of treatment. Topical drugs can be easier to apply, leading to better compliance and treatment success. Also, topical medications often relieve localized skin problems more quickly than systemic medications, which take time to circulate throughout the body.
Distribution Channel Insights
The hospital pharmacies segment dominated the market with a revenue share of 62.36% in 2024, driven by more pet owners taking their animals to hospitals for treatment. Additionally, their desire to spend money on their pets and the rise in skin disorders in these animals are boosting the market growth. Patient footfall in veterinary hospitals is rising significantly as most medication brands require obligatory veterinary monitoring before use.
 To learn more about this report, Download Free Sample Report
The e-commerce segment is expected to witness a lucrative CAGR during the forecast period. Pet owners' quick transition to online shopping and the presence of major retailers like Amazon, Walmart, Chewy.com, and PetCo are the primary factors driving growth in the veterinary dermatology products market. These online merchants make it simple to choose and buy products with faster delivery options, which is fueling market growth. Moreover, online stores are accessible 24 hours a day, seven days a week, allowing customers to shop at their convenience, regardless of time zones or business hours.
Regional Insights
North America veterinary dermatology drugs market dominated and accounted for 38.29% in 2024. This can be attributed to the presence of key companies, high expenditure on pets, pet humanization, and rising awareness about animal diseases. For instance, key market players, such as Zoetis, Merck & Co., Inc., and Elanco Animal Health, are headquartered in the U.S. and are undertaking various strategic initiatives to increase their market share. Additionally, regulatory agencies, such as the FDA, continue to approve new treatments, allowing for more options for veterinarians and pet owners. Strategic partnerships between veterinary drug manufacturers and multinational companies are accelerating the development and distribution of dermatology products. For instance, in June 2023, Zoetis received FDA approval for Apoquel Chewable (oclacitinib chewable tablet), a new formulation for managing pruritus and atopic dermatitis in dogs 12 months and older. The chewable tablet offers efficacy comparable to the original Apoquel tablet and improves medication compliance, making it easier for pet owners to administer. This product is expected to improve outcomes for dogs with allergic skin conditions, with over 13 million dogs treated with Apoquel in the U.S. over the past decade.
 To learn more about this report, Download Free Sample Report
U.S. Veterinary Dermatology Drugs Market Trends
The U.S. veterinary dermatology drug industry’s growth is driven by the rising prevalence of skin disorders in pets, including allergies, infections, and inflammatory conditions. As pet ownership rises and demand for advanced treatment options grows, the market is evolving with new and more effective therapies. Furthermore, expanding the number of local players to provide adequate veterinary dermatology treatments in the U.S. supports regional market growth. For instance, in November 2023, Animal Dermatology Group (ADG) expanded its presence in Northern California and the Pacific Northwest by acquiring Animal Dermatology & Allergy in Rocklin, CA, and SkinVet Clinic in Lake Oswego, OR. These acquisitions enhance ADG's commitment to providing top-tier veterinary dermatology care across the U.S., with a network of nearly 70 doctors in 14 states.
Europe Veterinary Dermatology Drugs Market Trends
The Europe veterinary dermatology drugs industry is experiencing significant growth, driven by the rising prevalence of skin disorders in pets, particularly dogs. Canine skin diseases are a significant concern, with allergic skin disorders affecting around 25.47% of dogs in regions such as the UK. Skin disorders account for approximately 12.58% of all canine health issues diagnosed in primary veterinary care, highlighting their prevalence. Factors such as breed, age, and environmental influences, like exposure to allergens and pollutants, contribute to the frequency of these conditions. There is a growing emphasis on preventive care, including regular vet check-ups and proper grooming, to manage and reduce the incidence of skin diseases in dogs.
Germany veterinary dermatology drugs market growth is driven by several key factors, including the rising prevalence of skin disorders in pets, particularly dogs, and the growing awareness among pet owners about the importance of skin health. The increasing demand for innovative treatments, such as biologics and targeted therapies for conditions like atopic dermatitis and pruritus, also contributes to market growth. Additionally, advancements in diagnostic techniques and a rising focus on preventive care encourage early detection and treatment of skin conditions. Moreover, the strong veterinary healthcare infrastructure and increasing pet ownership further support the market expansion in Germany.
Asia Pacific Veterinary Dermatology Drugs Market Trends
Asia Pacific is expected to witness the fastest CAGR over the forecast period. As economies in the Asia Pacific region continue to grow, there is a noticeable increase in the size of the middle-class population, higher disposable incomes, and growing urbanization. Market players have begun to capture opportunities in these emerging markets. China, in particular, shows strong momentum due to advancements in veterinary pharmaceuticals and government support for pet healthcare. For instance, in October 2024, FelicaMed Biotechnology was approved by China's Ministry of Agriculture and Rural Affairs for Lirucitinib, a Class I veterinary drug to treat canine pruritus. Licensed to Elanco's Chinese subsidiary, Lirucitinib is a JAK inhibitor that disrupts the itch-scratch-inflammation cycle, offering rapid relief. This collaboration marks a milestone in China's veterinary innovation and strengthens FelicaMed's commitment to advancing pet health solutions. Additionally, Partnerships between local companies and global leaders (e.g., FelicaMed and Elanco in China) are driving the introduction of innovative drugs designed for regional market needs.
The veterinary dermatology drugs industry in India is witnessing steady growth due to rising pet ownership, growing awareness, and an expanding range of effective treatments for managing animal skin conditions. Canine and feline skin disorders, such as allergies, infections, and parasitic infestations, are common in India, with studies reporting a 12-27% prevalence in dogs. This contributes to a growing need for dermatology-specific treatments. Furthermore, Indian companies, along with multinational players like Elanco and Zoetis, are expanding their portfolios of veterinary dermatology drugs. For example, Lirucitinib, a JAK inhibitor for canine pruritus, has been licensed in India by Elanco. Other products, including antifungal and antibacterial agents, are marketed to treat skin infections.
Latin America Veterinary Dermatology Drugs Market Trends
The Latin America veterinary dermatology drugs industry is expanding due to increasing awareness of pet healthcare and rising skin conditions in animals. Key drivers include the growing pet population, increased adoption of veterinary dermatology treatments, and advances in drug formulations. The demand for effective treatments for conditions like atopic dermatitis, allergies, and parasitic infections particularly influences the market. Brazil, Mexico, and Argentina are significant contributors to the market's growth, focusing on innovative therapies and affordable solutions for pet owners.
The veterinary dermatology drugs market in Brazil is experiencing steady growth, driven by increasing awareness of animal health, expanding pet ownership, and a rise in skin-related issues among companion animals. Skin conditions such as allergies, infections, and parasitic diseases are common, driving increased demand for effective dermatological treatments. A study in Ilhéus, Bahia, found that 62.3% of dogs were infested with Tunga penetrans, a parasitic skin disease. Significant risk factors included semi-restricted living conditions and the presence of sand, with common clinical signs being edema and hyperkeratosis. The study highlights the high prevalence of tungiasis in the canine population and emphasizes the need for targeted interventions in areas with poor living conditions.
Middle East & Africa Veterinary Dermatology Drugs Market Trends
In the Middle East and Africa (MEA), veterinary dermatology therapies are seeing gradual growth driven by increased awareness of pet health and rising pet ownership in urban areas. Common treatments focus on conditions such as allergic dermatitis, parasitic infections, and fungal diseases. Antihistamines, corticosteroids, immunosuppressive drugs, and newer biologics like monoclonal antibodies are gaining popularity. Additionally, the market is evolving, with a rise in specialized veterinary dermatology clinics, particularly in countries such as the UAE, South Africa, and Saudi Arabia. However, challenges like limited access to advanced therapies in rural areas and economic constraints persist.
The South Africa veterinary dermatology drugs market is expected to grow during the forecast period. In South Africa, veterinary dermatology therapies are gaining traction due to rising awareness of pet health and an increasing number of animals suffering from skin disorders. The need for treatments for common conditions such as atopic dermatitis, allergic reactions, and parasitic infestations like ticks and fleas primarily drives the market growth. Popular therapies include corticosteroids, cyclosporine (e.g., Atopica), and newer treatments like Apoquel (oclacitinib) for pruritus control in allergic dermatitis. Additionally, South African veterinarians increasingly use immunotherapy and topical treatments, such as shampoos and sprays, to manage skin conditions. A growing market for biologic therapies, such as monoclonal antibodies, offers long-term management options for chronic conditions.
Key Veterinary Dermatology Drugs Company Insights
The market is fragmented owing to numerous companies offering veterinary dermatology drugs. These organizations employ a range of strategies to increase their market presence and market share. These initiatives include mergers and acquisitions, partnerships and collaborations, product launches, R&D, regional expansion, and more.
Key Veterinary Dermatology Drugs Companies:
The following are the leading companies in the veterinary dermatology drugs market. These companies collectively hold the largest market share and dictate industry trends.
- Elanco
- Ceva
- Vetoquinol
- Merck & Co., Inc.
- Zoetis
- Virbac
- Bimeda, Inc
- Vivaldis
- Bioiberica S.A.U.
- Boehringer Ingelheim International GmbH
Recent Developments
-
In September 2024, Elanco launched Zenrelia (ilunocitinib tablets), a once-daily oral JAK inhibitor for managing allergic and atopic dermatitis in dogs aged 12 months and older. Zenrelia offers significant itch relief at an affordable price, making it a safer, more effective alternative to competitors.
-
In August 2024, Boehringer Ingelheim India formed a strategic distribution partnership with Vvaan Lifesciences Pvt Ltd to enhance its pet parasiticide portfolio and expand its reach in India's pet health market, valued at around USD 124.51 million. This collaboration aims to improve access to quality pet healthcare in Tier 2 and underserved cities, leveraging Vvaan's expertise to better serve these regions and elevate veterinary care standards across the country.
Veterinary Dermatology Drugs Market Report Scope
Report Attribute
Details
Market size in 2024
USD 17.4 billion
Estimated market size in 2026
USD 20.2 billion
Projected market size by 2030
USD 29.5 billion
Growth rate
CAGR of 9.6% from 2025 to 2030
Base year for estimation
2024
Historical data
2018 - 2023
Forecast period
2025 - 2030
Quantitative units
Revenue in USD million/billion, and CAGR from 2025 to 2030
Report Coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments Covered
Indication, type, animal type, route of administration, distribution channel, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; UK; Germany; Italy; France; Spain; Denmark; Sweden; Norway; Japan; China; India; South Korea; Australia; Thailand; Brazil; Mexico; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
Elanco; Boehringer Ingelheim International GmbH; Ceva; Vetoquinol; Merck & Co., Inc.; Zoetis; Virbac; Bimeda, Inc.; Bioiberica S.A.U.; Vivaldis
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Veterinary Dermatology Drugs Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2018 to 2030. For the purpose of this report, Grand View Research has segmented the global veterinary dermatology drugs market report on the basis of indication, type, animal type, route of administration, distribution channel, and region:
-
Indication Outlook (Revenue, USD Million, 2018 - 2030)
-
Parasitic Infections
-
Allergic Infections
-
Others
-
-
Type Outlook (Revenue, USD Million, 2018 - 2030)
-
Prescription
-
OTC
-
-
Animal Type Outlook (Revenue, USD Million, 2018 - 2030)
-
Companion Animals
-
Dogs
-
Cats
-
Horses
-
Others
-
-
Livestock Animals
-
Cattle
-
Others
-
-
-
Route of Administration Outlook (Revenue, USD Million, 2018 - 2030)
-
Topical
-
Oral
-
Injectable
-
-
Distribution Channel Outlook (Revenue, USD Million, 2018 - 2030)
-
Hospital Pharmacies
-
Retail
-
E-commerce
-
-
Regional Outlook (Revenue, USD Million, 2018 - 2030)
-
North America
-
U.S.
-
Canada
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
Rest of Europe
-
-
Asia Pacific
-
Japan
-
China
-
India
-
South Korea
-
Australia
-
Thailand
-
Rest of Asia Pacific
-
-
Latin America
-
Brazil
-
Mexico
-
Argentina
-
Rest of Latin America
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
Rest of MEA
-
-
Frequently Asked Questions About This Report
The global veterinary dermatology drugs market size was valued at USD 17.4 billion in 2024 and is estimated at USD 20.2 billion for 2026.
Some key players operating in the veterinary dermatology drugs market include Elanco, Boehringer Ingelheim International GmbH, Ceva, Vetoquinol, Merck & Co., Inc., Zoetis, Virbac, Bimeda, Inc, Bioiberica S.A.U., Vivaldis.
Key factors that are driving the veterinary dermatology drugs market growth include a growing number of clinical trials related to veterinary dermatology drugs, the rising prevalence of skin diseases in animals as well as high investments by market players.
The global veterinary dermatology drugs market is expected to grow at a CAGR of 9.6% from 2025 to 2030, reaching USD 29.5 billion by 2030.
North America dominated with a 38.3% revenue share in 2024. The growing number of pet owners in North America has led to increased demand for veterinary services, including dermatological treatments for animal skin conditions.
About the Author(s)
Animal Health Research Team
Healthcare · Animal HealthThis report was authored by the animal health research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the animal health segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


