
- Home
- »
- Animal Health
- »
-
Veterinary Education Market Size & Share Report 2026-2033GVR Report cover

Veterinary Education Market (2026 - 2033)
Size, Share & Trends Analysis Report By Specialty (Veterinary Surgery, Veterinary Medicine), By Course, By Institution, By Delivery Mode, By Duration, By End Customer, Type, By Region, And Segment Forecasts
Market Size, 2025
$3.6BMarket Estimate, 2026
$3.8BMarket Forecast, 2033
$6.0BCAGR, 2026–2033
6.9%Veterinary Education Market Summary
The global veterinary education market size was valued at USD 3.6 billion in 2025 and is projected to grow from USD 3.8 billion in 2026 to USD 6.0 billion by 2033, at a CAGR of 6.9% from 2026 to 2033. North America dominated the veterinary education market with the largest revenue share of 32.2% in 2025. The market is driven by government and institutional funding for veterinary education and the growing demand for specialized services.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By course: Graduate courses segment held the largest market share of 40.3% in 2025.
- By specialty: Veterinary medicine segment held the largest market share of 33.4% in 2025.
- By institution: Public institutions segment held the largest market share 63.4% in 2025.
- By delivery mode: Classroom based courses segment held the largest market share 52.5% in 2025.
- By duration: More than 2years segment held the largest market share 46.5% in 2025.
Regional Highlights
- Largest regional market: North America (32.2% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 3.6 Billion
- Estimated market size in 2026: USD 3.8 Billion
- Projected market size by 2033: USD 6.0 Billion
- CAGR (2026-2033): 6.9%
Prism AI by Grand View Research Free to tryAsk a question about the veterinary education marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
Furthermore, integrating digital and simulation-based learning and bringing it into practice is estimated to drive the market growth in the forecast period. Increased investments in veterinary training by governments and international bodies such as the FAO, OIE (WOAH), and World Bank to strengthen animal health infrastructure and zoonotic disease surveillance have boosted market growth. For instance, in October 2025, Ireland Ministers approved the Veterinary Places Activation Programme (VPAP), establishing new veterinary schools at South East Technological University and Atlantic Technological University. In addition, in August 2025, Canada’s Lakehead University launched construction of a new facility under the Collaborative Doctor of Veterinary Medicine Program with the University of Guelph, supported by a USD 14.78 million government investment. This funding enables universities to modernize facilities, develop One Health-focused curricula, and support research in epidemiology, microbiology, and animal biotechnology. The resulting improvement in academic standards attracts more students globally, especially from developing nations.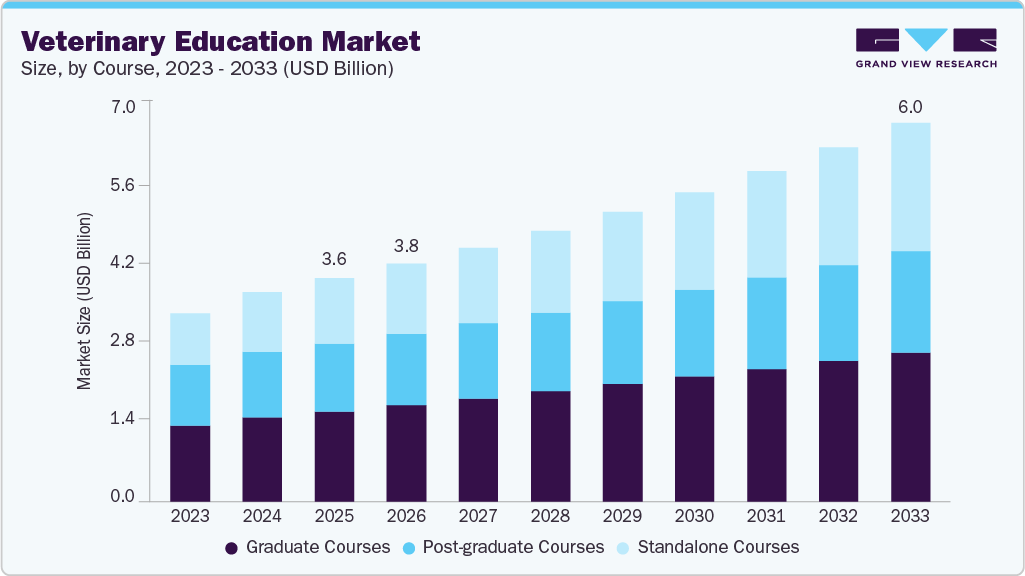 To learn more about this report, Download Free Sample Report
In addition, rising demand for specialized veterinary services has become a major market driver. According to the 2024 data of the American Veterinary Medical Association (AVMA), there are around 22 specialty organizations recognized by AVMA comprising 46 distinct specialties in the U.S., and over 16,500 veterinarians have been granted diplomas in these specialties after completion of postgraduate training, education, and examination requirements. Moreover, as pet owners become more aware and are willing to spend on advanced medical care, the demand for veterinary specialists in fields such as oncology, cardiology, and neurology is rapidly rising. Thus, veterinary schools are expanding curricula and introducing advanced specialization programs to prepare graduates capable of meeting the evolving demands of modern animal healthcare and precision veterinary medicine.
Furthermore, the shortage of live animal training opportunities and the rapid evolution of educational technology have encouraged veterinary institutions to adopt virtual dissection tools, 3D anatomy models, and AI-powered diagnostic simulators. According to the report of August 2024, a Texas A&M University professor developed VetClinPathGPT, an AI-powered study tool enabling veterinary students to interactively learn clinical pathobiology and diagnostics, reducing repetitive tasks for educators. In October 2025, Croatia introduced a pilot AI curriculum for secondary and vocational students, promoting responsible AI use, practical skill development, and ethical awareness through experiential, project-based learning. These initiatives improve student engagement, standardize learning outcomes, and allow global accessibility to practical veterinary training. Universities integrating such tools attract more international students and collaborations, especially through hybrid and online veterinary education platforms. This digital transformation enhances scalability, quality, and efficiency, becoming a major market growth.
Market Opportunity Insights for AI Integration in Veterinary Education
Opportunity Area
Description
Market Implication
AI-Based Learning Modules
AI tools to clarify concepts, generate exam prep questions, summarize lectures
High demand from students; universities can differentiate programs
Clinical Simulation & Diagnostics
AI-driven patient simulations, imaging (radiology, ultrasound, MRI), disease detection
Growing need for practical skills training; can reduce clinical training costs
Continuing Professional Education (CPE)
AI-based workshops and certifications for practicing veterinarians
Steady revenue stream; supports specialization areas like oncology, dentistry
E-Learning & Online Platforms
Remote, interactive AI learning for global student base
Expands reach; scalable solution for international markets
AI in Practice Management
AI tools to optimize clinic operations and patient management
High adoption by veterinarians running private practices; improves efficiency
Research & Development Collaborations
Joint R&D projects integrating AI in veterinary education
Opens new product/service lines; positions institutions as innovation leaders
Market Dynamics
The market is driven by increasing government and institutional funding for veterinary education, rising enrollment in veterinary programs, and growing demand for highly skilled veterinary professionals. In addition, expanding companion animal ownership, livestock healthcare needs, and the increasing prevalence of complex animal diseases have intensified the need for specialized veterinary services, encouraging universities and training institutes to modernize their educational infrastructure. In addition, the integration of digital technologies, simulation-based learning, virtual reality (VR), augmented reality (AR), artificial intelligence (AI), and 3D anatomy models is transforming veterinary training by providing immersive, standardized, and hands-on learning experiences without relying solely on live animals.
Furthermore, shortage of live animal training opportunities, ethical concerns surrounding animal use, and rapid technological advancements are accelerating the adoption of virtual dissection platforms and AI-powered diagnostic simulators. In addition, collaborations between academic institutions, veterinary hospitals, and technology providers are expanding practical learning opportunities, supporting continuous curriculum innovation and driving sustained market growth throughout the forecast period. For instance, in August 2025, Canada’s Lakehead University launched construction of a new facility under the Collaborative Doctor of Veterinary Medicine Program with the University of Guelph, supported by a USD 14.78 million government investment.
The growing demand for specialized veterinary services is a key driver of the veterinary education market. According to the 2024 data of the American Veterinary Medical Association (AVMA), there are around 22 specialty organizations recognized by AVMA comprising 46 distinct specialties in the U.S., and over 16,500 veterinarians have been granted diplomas in these specialties after completion of postgraduate training, education, and examination requirements. In addition, increasing pet ownership, higher spending on companion animal healthcare, and the rising prevalence of chronic diseases, cancer, orthopedic disorders, and infectious diseases have created a need for veterinarians with advanced clinical expertise.
Similarly, livestock producers are seeking professionals skilled in herd health management, disease surveillance, and food safety. These evolving healthcare requirements are encouraging veterinary schools to expand curricular in areas such as oncology, surgery, diagnostic imaging, emergency medicine, and exotic animal care. Furthermore, academic institutions are also investing in specialized training laboratories, simulation technologies, and clinical partnerships with veterinary hospitals to provide hands-on experience. Moreover, demand for continuing education and certification programs is increasing as practicing veterinarians seek to upgrade their skills and adopt emerging technologies. This emphasis on specialized competencies is driving investments in veterinary education infrastructure and supporting long-term market growth.
The rising cost of veterinary education and increasing student debt are significant restraints on the veterinary education market. In addition, tuition fees, laboratory expenses, clinical training costs, and educational materials have increased substantially, making veterinary programs financially challenging for many students. Some of the graduates often enter the workforce with considerable debt, which can discourage prospective students from pursuing veterinary careers or influence them to choose higher-paying specialties over underserved practice areas such as rural and livestock medicine. In addition, high educational debt also limits participation in advanced certifications and continuing education programs after graduation. Furthermore, financial pressure may contribute to workforce shortages, reduced enrollment in veterinary colleges, and lower diversity within the profession. Thus, addressing affordability through scholarships, government funding, loan forgiveness programs, and institutional financial support will be essential to sustain long-term growth in veterinary education.
The increasing adoption of digital learning technologies presents a significant opportunity for the veterinary education market. The veterinary schools and training institutions are integrating artificial intelligence (AI), virtual reality (VR), augmented reality (AR), mixed reality (MR), 3D anatomical models, haptic simulators, and cloud-based learning platforms to improve clinical competency while reducing reliance on live animal training. Such technologies enable students to repeatedly practice surgical procedures, diagnostic techniques, and emergency interventions in realistic virtual environments, enhancing confidence and skill development before treating live patients.
In addition, digital simulation also supports distance learning, standardized training, and continuing education for practicing veterinarians, addressing the growing need for lifelong professional development. Furthermore, AI-powered assessment tools provide personalized feedback and objective performance evaluation, improving educational outcomes. As veterinary curricula increasingly emphasize technology-enabled, competency-based learning, investments in advanced educational platforms and simulation laboratories are expected to create substantial growth opportunities for educational institutions, technology providers, and veterinary training organizations worldwide.
Market Concentration & Characteristics
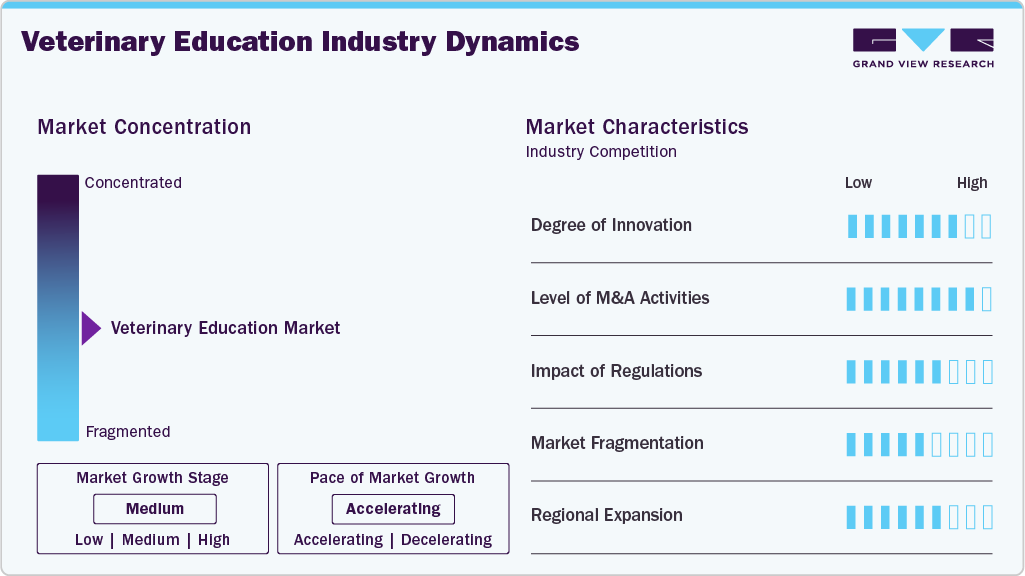
The veterinary education industry is moderately concentrated, dominated by leading universities, government-funded institutions, and prominent private providers. Numerous smaller schools and training platforms contribute to diversity, fostering competition, innovation, and expansion in specialized courses and continuing education programs.
The veterinary education industry is experiencing rising innovation through adopting digital platforms, AI-driven learning tools, and simulation-based training. Institutions are integrating virtual reality for clinical practice and diagnostics, improving experiential learning. For instance. In April 2025, the AVMA Council on Education approved new distance education policies ensuring online learning enhances in-person veterinary training, maintaining educational quality while integrating evolving digital tools to support professional readiness.
 To learn more about this report, Download Free Sample Report
Mergers and acquisitions in the veterinary education industry are increasing as edtech firms, veterinary universities, and corporate training providers collaborate to expand learning capabilities. For instance, in July 2025, Improve International and Central CPD merged to create a leading UK provider of veterinary postgraduate and CPD training, combining global expertise, digital learning, and hands-on education for professionals.
Regulatory frameworks are critical in shaping the quality of veterinary education and international accreditation. Agencies such as AVMA and EAEVE establish standards for curricula, clinical competence, and faculty qualifications.
The veterinary education industry remains fragmented due to numerous regional institutions, varying accreditation standards, and uneven access to advanced learning technologies. Differences in curriculum quality, infrastructure, and digital adoption across countries create disparities in training outcomes.
The veterinary education industry is witnessing strong regional expansion, particularly across Asia-Pacific, the Middle East, and Latin America, driven by rising demand for skilled veterinarians and government investment in new institutions. Education through E-learning is also gaining momentum in the market.
Analyst Perspective
The veterinary education market is undergoing significant transformation, propelled by rising companion animal ownership, growing livestock health concerns, and an expanding global demand for skilled veterinary professionals. A persistent shortage of qualified veterinarians in both developed and emerging economies is prompting governments and academic institutions to invest in expanding veterinary college capacity, upgrading curricula, and integrating advanced clinical training infrastructure. In addition, technological innovation is transforming the market, with simulation-based learning, virtual dissection tools, telemedicine training modules, and AI-assisted diagnostic education increasingly supplementing traditional hands-on instruction, improving accessibility while addressing ethical concerns around live-animal use.
Course Insights
Based on course, the graduate courses segment led the market with the largest revenue share of 40.3% in 2025, owing to the importance of graduate courses and the growing demand for advanced qualifications and specialization in fields such as surgery, pathology, and animal biotechnology. Universities worldwide are expanding postgraduate offerings with blended and online formats, meeting the need for career advancement and research expertise. For instance, in August 2025, Queen’s University Belfast launched Northern Ireland’s first undergraduate course in Veterinary Biosciences, blending theoretical and practical learning to meet rising demand for animal health professionals. Such initiatives are transforming graduate courses in the market.
The standalone courses represent the fastest-growing segment in the market, driven by the rising demand for short, flexible, and career-focused learning. This segment consists of courses in a variety of fields, such as pharmacology, animal nutrition, surgery, wildlife medicine, animal behavior, equine welfare and management, dairy production and management, and various other courses related to animal health and allied health verticals. Animal health associations and private providers have introduced more standalone continuing education courses and certifications in specialized areas like animal behavior, dentistry, and emergency care. This allows practicing vets to expand their skills. These courses are supported by online and hybrid learning formats, allowing flexibility for working professionals seeking continuous development and immediate application of new skills in clinical practice.
Specialty Insights
Based on specialty, the veterinary medicine segment led the market with the largest revenue share of 33.4% in 2025, contributing to the large share, including the increasing prevalence of diseases in companion and livestock animals. Modern methods for the diagnosis and treatment of chronic illnesses in animals are now available due to the remarkable advancements in veterinary medicine. As the core of this field, these programs ensure comprehensive training in animal health. For instance, in October 2025. IMU and the University of Surrey launched Asia’s first transnational veterinary medicine program, blending IMU’s medicine expertise with Surrey’s veterinary training to prepare globally skilled, future-ready veterinarians. This collaboration sets a new benchmark for international veterinary education. Furthermore, there is a growing emphasis on training students in telehealth, practice management, and client communication to prepare them for modern animal health practice.
The other specialty segment is the fastest-growing market, with the highest CAGR over the forecast period. This segment includes cardiology, dentistry, sports medicine, oncology, and behavioral specialties. The segment growth is fueled by rising expectations for advanced care by pet owners and the expanding companion animal population, which has prompted educational institutions to offer targeted training programs. These specialties equip veterinarians with in-depth expertise to manage complex cases, enhance clinical outcomes, and meet evolving industry needs, making them the fastest-growing segment in veterinary education.
Institution Insights
Based on institution, the public segment led the market with the largest revenue share of 63.4% in 2025 and is the fastest-growing segment over the forecast period. Government-funded veterinary schools and colleges remain key providers of animal health education, offering accessible and affordable programs. They drive research and innovation, transform curriculum standards, and promote global best practices through collaborations, thereby expanding facilities and enrollments to meet growing workforce demands.
The private segment is the second fastest growing over the forecast period, owing to their flexibility, innovative curricula, and industry-focused programs. They offer specialized courses, modern facilities, and global partnerships, attracting students seeking advanced skills and career-ready training. For instance, in June 2025, the five-year University of Wisconsin School of Veterinary Medicine (SVM)-Petco Love partnership has subsidized cancer treatments for dogs and cats, supporting over 95 families with USD 400,000 in funding, enhancing access to advanced veterinary oncology care and clinical research.
Delivery Mode Insights
Based on delivery mode, the classroom based courses segment led the market with the largest revenue share of 52.5% in 2025. The market growth is attributed to structured, in-person learning combining theoretical knowledge and practical experience. For instance, in June 2025, Bashkir State Agrarian University launched advanced training in "Veterinary Science," including modern diagnostic methods and veterinary-sanitary examinations, following WorldSkills Russia standards. These programs, conducted by university faculty and industry experts, equip students with essential skills and certifications.
The e-learning segment is projected to register the fastest CAGR over the forecast period, driven by demand for flexible, accessible, and scalable learning solutions. Online platforms provide on-demand courses, interactive webinars, and virtual simulations, enabling veterinarians and students to improve without geographical barriers. For instance, in October 2024, Brooke launched the Academy for Working Equids (AWE), a virtual learning platform providing open-access training for vets, enhancing skills to improve working equid welfare and community support worldwide. This mode of education supports continuing professional development, reduces training costs, and allows institutions to reach a broader audience.
Duration Insights
Based on duration, the more than 2 years segment led the market with the largest revenue share of 46.5% in 2025. These extended courses offer comprehensive training, including practical internships and research opportunities. These programs are essential for producing highly skilled professionals, particularly in specialized fields like surgery and pathology. In addition to traditional 4-year DVM programs, there is growth in accelerated 3-year degrees to fast-track students into the workforce. Shorter certificate and diploma programs of less than 1-year duration have also proliferated for roles like assistants and technicians.
Less than 1 year is anticipated to grow at the fastest CAGR over the forecast period. Short-term courses are designed for quick skill acquisition and specialization, catering to immediate market needs. They include certifications in areas such as animal first aid and pet nutrition, addressing urgent skill gaps in the industry.
Type Insights
Based on type, the tuition segment led the market with the largest revenue share of 68.2% in 2025 and is among the fastest-growing segments over the forecast period. The market is driven, significantly influencing program affordability and accessibility, from traditional 4-year DVMs to short-term certificate courses. Rising tuition costs have encouraged alternative learning models, including scholarships, financial aid, and e-learning platforms, making education more accessible. The growth of private veterinary schools offering competitive tuition has intensified market competition, further shaping the global tuition landscape.
The non-tuition segment is the second fastest growing market due to increasing demand for supplementary services such as accommodation, training materials, workshops, and practical internships. Investments in digital resources, e-learning platforms, and skill-development programs are also driving growth. These offerings enhance the overall learning experience, making non-tuition services a critical part of veterinary education.
End Customer Insights
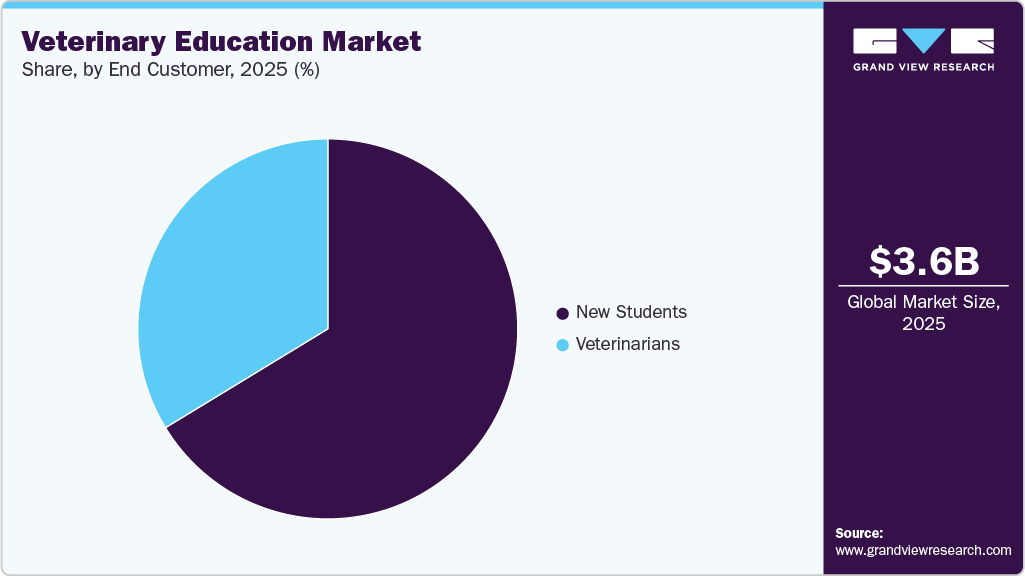
Based on end customer, the new students segment led the market with the largest revenue share of 66.3% in 2025 and is the fastest growing with the highest CAGR from 2026 to 2033. The market is expanding due to increasing demand for skilled veterinarians, rising pet ownership, and awareness of animal health careers. Institutions are developing programs, campuses, and course offerings to attract talent, including undergraduate, graduate, and specialized training tracks. The influx of new students and learners drives demand for innovative and engaging educational methods. According to the American Veterinary Medical Association (AVMA), a record number of first-year students, exceeding 4,000, enrolled in U.S. colleges for the 2022-23 academic year. The overall enrollment in U.S. colleges of animal medicine reached 15,157 in the 2022-23 school year, a notable increase from the 11,255 students enrolled a decade ago. This segment benefits from tuition fees, admission charges, and associated educational services, forming a stable and growing source of revenue for veterinary schools worldwide.
 To learn more about this report, Download Free Sample Report
The veterinarian segment is projected to be the second fastest-growing segment over the forecast period. Practicing veterinarians continually seek to enhance their knowledge and skills, driving strong demand for continuing education programs. This stimulates the creation of new courses, workshops, and digital learning platforms. As veterinarians increasingly focus on specialties like oncology, dentistry, or exotic animal care, schools expand curricula and offer more targeted training. In addition, veterinarians launching practices or innovative businesses influence educational programs, particularly in practice management and entrepreneurship. Furthermore, according to 2024 Iowa Dairy Ambassador Maggie Cronk, veterinarians also help dairy farms optimize operations, increase profitability, and implement sustainable, efficient practices, contributing to farm resilience and success.
Regional Insights
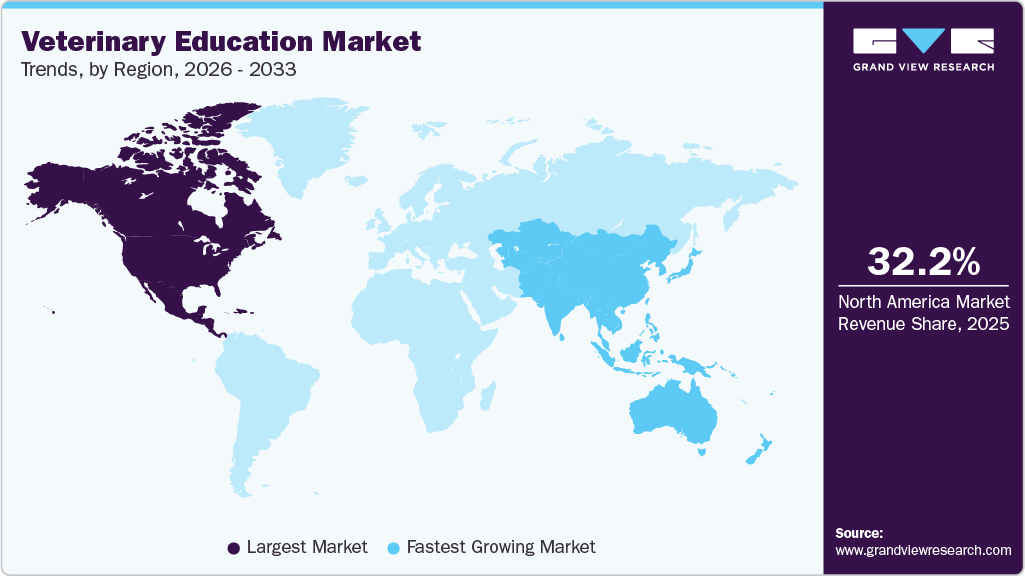
North America dominated the veterinary education market with the largest revenue share of 32.2% in 2025. The market is driven by increasing pet ownership and awareness of pet health in the region, as well as the demand for specialized veterinary services. This, in turn, creates a need for advanced veterinary education to meet rising expectations. Furthermore, the government and private organizations in countries like the U.S. offer various grants and funding opportunities to support veterinary education, enhancing the quality and reach of these programs.
 To learn more about this report, Download Free Sample Report
U.S. Veterinary Education Market Trends
The veterinary education market in the U.S. held the largest share in the North America region in 2025, owing to high demand, the integration of advanced technology (AI and telemedicine) into the curriculum, and addressing the ongoing shortage of qualified educators and rural veterinarians. For instance, in September 2025, UC Davis School of Veterinary Medicine announced a USD 110.5 million expansion to address workforce shortages, enhance research, and modernize facilities funded primarily through philanthropy, including hospitals, imaging, and education centers.
Europe Veterinary Education Market Trends
The veterinary education market in Europe is expected to grow significantly due to growing awareness of animal health and favorable government regulations. Pet owners and livestock farmers are increasingly aware of animal health and welfare, including the importance of pain management in enhancing the quality of life for animals.
Sweden veterinary education market is expected to grow significantly over the forecast period. The market is characterized by strong research integration, global collaboration, and government-backed sustainability initiatives. The Swedish University of Agricultural Sciences (SLU) leads One Health and animal welfare research, reinforcing Sweden’s global reputation for evidence-based veterinary training.
The veterinary education market in the UK held the largest revenue share in 2025. The country’s growth is influenced by innovation and research-led initiatives. According to the report of July 2025, the Veterinary Medicines Directorate launched the world’s first study on antibiotic resistance in healthy pets, highlighting the country’s leadership in One Health education and research. The initiative will drive the market by promoting One Health-focused curricula, expanding research and training in antimicrobial resistance, and enhancing interdisciplinary learning to prepare future-ready veterinary professionals.
Asia Pacific Veterinary Education Market Trends
The veterinary education market in the Asia Pacific is expected to grow at the fastest CAGR over the forecast period. The region's growth can be attributed to a number of factors, including an increasing number of pets, the rising prevalence of animal diseases, rising concerns about animal health, and the region's growing livestock population. In April 2024, a significant event in the Asia Pacific region was held to discuss the progress and future steps of the Veterinary Workforce Development Programme for Veterinarians & Veterinary Paraprofessionals (VPPs). The program aimed to strengthen the workforce through targeted training, capacity building, and strategic initiatives. It focused on addressing the current challenges in the field and planning for sustainable development.
China veterinary education market is witnessing new growth opportunities due to the growing economy, a notable increase in pet ownership, and growing awareness of animal welfare. This shift has led to a rising demand for qualified veterinary professionals, prompting the expansion and improvement of veterinary education programs nationwide. Chinese universities are increasingly partnering with international institutions to enhance curricula and align with global standards.
The market for veterinary education in Thailand is poised for lucrative growth, driven by international collaborations and research excellence. For instance, in June 2025, One Health partnered with Chulalongkorn University and UK institutions through the USD 118 million FarmAquaNet project, highlighting Thailand’s growing leadership in antimicrobial resistance research. This initiative will drive the market by fostering international research collaboration, advancing training in antimicrobial resistance, and strengthening academic programs.
Latin America Veterinary Education Market Trends
The veterinary education market in Latin America is driven by expanding veterinary services, rising animal healthcare awareness, increasing pet ownership, and the growing livestock industry. This growth is further supported by government initiatives and private-sector investments to improve education and training facilities. Advanced veterinary programs and specialized courses are becoming more prevalent, catering to the diverse needs of the region's animal health industry.
Brazil veterinary education marketis gaining momentum, supported by several key factors, such as rising veterinary healthcare expenditures and increasing awareness of animal welfare. Collaborations between schools and international institutions are enhancing the quality of education, providing students with access to the latest research, technologies, and best practices. The market also benefits from a growing emphasis on public health and zoonotic disease prevention, highlighting the critical role of well-trained professionals.
Middle East & Africa Veterinary Education Market Trends
The veterinary education market in MEA has grown over the forecasted years, attributable to the increasing requirement for veterinary medicine and grooming services. The growing demand for specialized services and increasing government initiatives to support veterinary education further drive the market in the region.
South Africa veterinary education market is expanding, fueled by the expansion of educational facilities. For instance, in June 2025, the University of the Free State (UFS) established the nation’s second veterinary training facility. The new BVSc program and teaching hospital in Bloemfontein will enhance access to professional training and address the country’s critical veterinarian shortage. The Paradys Experimental Farm for hands-on learning, UFS strengthens South Africa’s capacity in animal health, food security, and sustainable agriculture, bolstering its regional leadership in veterinary education.
The veterinary education market in UAE is experiencing growth due to strategic academic partnerships and advanced equine training initiatives. For instance, in July 2025, An-Najah National University collaborated with the University of Al Dhaid, the Sharjah Equestrian and Racing Club, and the Sharjah Equine Hospital reflects the country’s growing emphasis on specialized veterinary training.
Key Veterinary Education Company Insights
Key players such as the University of California-Davis, Royal Veterinary College, Utrecht University, and Improve International shape the market. These institutions dominate through advanced curricula, global research collaborations, and continuing professional development programs, fostering innovation, skill advancement, and leadership in veterinary science and postgraduate training worldwide. For instance, in June 2025, Immertec launched its Animal Health Division, expanding immersive real-time training to veterinary medicine. The platform enables global, collaborative surgical education, enhancing clinical consistency, onboarding, and continuing education across veterinary hospitals, manufacturers, and academic institutions.
Key Veterinary Education Companies
The following key companies have been profiled for this study on the veterinary education market.
-
University of California - Davis
-
Utrecht University
-
Cornell University
-
University of Guelph
-
University of Sao Paulo
-
Royal Veterinary College
-
King Saud University
-
Indian Veterinary Research Institute
-
University of Pretoria
-
China Agricultural University
-
University of Edinburgh
-
Swedish University of Agricultural Sciences
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Utrecht University, Cornell University and Others)
- Mature players strengthen their market position by expanding specialty programs, integrating AI-enabled simulation and virtual learning platforms, collaborating with veterinary hospitals for clinical training, increasing research funding, and establishing international academic partnerships.
- They emphasize curriculum modernization, accreditation compliance, faculty development, lifelong learning programs, and continuing veterinary education while investing in digital infrastructure and industry collaborations to enhance educational quality, graduate employability, and global institutional reputation.
- Established institutions benefit from strong academic reputations, accredited programs, experienced faculty, advanced teaching hospitals, extensive alumni networks, and robust research capabilities.
- Their access to government funding, industry partnerships, modern laboratories, simulation technologies, and international collaborations enables comprehensive clinical training and innovation.
- These advantages attract higher student enrollment, research grants, distinguished faculty, and employer recognition, strengthening their long-term leadership in veterinary education.
- Mature institutions often face challenges including high operational and infrastructure costs, lengthy curriculum approval processes, and slower adoption of emerging educational technologies. Legacy academic structures may limit curriculum flexibility and innovation.
Emerging Players (China Agricultural University and other regional pet hygiene brands)
- Emerging players focus on delivering flexible, technology-enabled veterinary education through online learning platforms, simulation-based training, AI-powered diagnostic modules, and industry-aligned curricula.
- They collaborate with veterinary hospitals, research institutes, and technology providers to expand clinical exposure and practical learning.
- Offering modular certification programs, continuing education courses, international partnerships, and affordable tuition structures enables them to attract students and practicing veterinarians while improving accessibility and workforce readiness.
- Emerging providers gain a competitive advantage through digital-first education models, virtual anatomy laboratories, AI-assisted learning tools, simulation technologies, and competency-based curricula. Faster curriculum updates, personalized learning pathways, smaller class sizes, and collaborations with veterinary clinics enhance practical skills development.
- Their ability to rapidly integrate emerging technologies, specialty certification programs, and flexible online education formats enables them to address evolving industry demands more effectively than many traditional institutions.
- Emerging players often face limited brand recognition, lower accreditation coverage, restricted research infrastructure, and fewer affiliated teaching hospitals compared to established veterinary universities. Limited faculty availability, smaller alumni networks, constrained financial resources, and reduced access to government funding can restrict program expansion.
Recent Developments
-
In November 2025, JIS College of Veterinary & Animal Sciences (JISCOVAS) begun operations as West Bengal’s first private veterinary college, offering a 5.5-year B.V.Sc. & A.H. course with 80 seats. The launch aims to narrow India’s large veterinarian shortage, helping meet growing livestock and animal-health demands.
-
In November 2025, Gulf Medical University (GMU) in the UAE secured initial accreditation from Commission for Academic Accreditation (CAA) for its new Doctor of Veterinary Medicine (DVM) course under Thumbay College of Veterinary Medicine. The program admits 60 students a year and links classroom learning with over 30 local and international veterinary partners to deliver global-standard clinical training and research exposure.
-
In September 2025, PetVivo launched new RACE-approved CE courses on osteoarthritis and regenerative therapies for small animal and equine practice, emphasizing clinical science and hands-on application. These programs advance veterinarians’ expertise in emerging therapeutic modalities.
-
In September 2025, Boehringer Ingelheim launched VetED Academy, a centralized, RACE-accredited education portal offering on-demand videos, webinars, and audio content for veterinary professionals. The platform simplifies continuing education and promotes lifelong learning. This initiative enhances global access to quality veterinary training.
-
In January 2025, Royal Canin unveiled a redesigned Royal Canin Academy at VMX 2025. The academy features flexible, mobile-friendly learning, progress tracking, and enhanced user experience. Each registration donates meals to pets in need. The update strengthens engagement and social responsibility in veterinary education.
Veterinary Education Market Report Scope
Report Attribute
Details
Market size in 2025
USD 3.6 billion
Estimated market size in 2026
USD 3.8 billion
Projected market size by 2033
USD 6.0 billion
Growth rate
CAGR of 6.9% from 2026 to 2033
Actual data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Course, specialty, institution, delivery mode, duration, type, end customer, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Sweden; Norway; Japan; China; India; Thailand; South Korea; Australia; Brazil; Argentina South Africa; UAE; Saudi Arabia; Kuwait; Qatar; Oman
Key companies profiled
University of California - Davis; Utrecht University; Cornell University; University of Guelph; University of Sao Paulo; Royal Veterinary College; King Saud University; Indian Veterinary Research Institute; University of Pretoria; China Agricultural University; University of Edinburgh; Swedish University of Agricultural Sciences
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Veterinary Education Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global veterinary education market report based on course, specialty, institution, delivery mode, duration, type, end customer, and region:
-
Course Outlook (Revenue, USD Million, 2021 - 2033)
-
Graduate Courses
-
Post-graduate Courses
-
Standalone Courses
-
-
Specialty Outlook (Revenue, USD Million, 2021 - 2033)
-
Veterinary Surgery
-
Veterinary Medicine
-
Veterinary Nursing
-
Animal Grooming
-
Other Specialties
-
-
Institution Outlook (Revenue, USD Million, 2021 - 2033)
-
Public
-
Private
-
-
Delivery Mode Outlook (Revenue, USD Million, 2021 - 2033)
-
Classroom based Courses
-
E-Learning
-
-
Duration Outlook (Revenue, USD Million, 2021 - 2033)
-
Less than 1 year
-
1 - 2 years
-
More than 2 years
-
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Tuition
-
Non-Tuition
-
-
End Customer Outlook (Revenue, USD Million, 2021 - 2033)
-
New Students
-
Veterinarians
-
-
Region Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
Thailand
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
UAE
-
Saudi Arabia
-
Kuwait
-
Qatar
-
Oman
-
-
Research Methodology
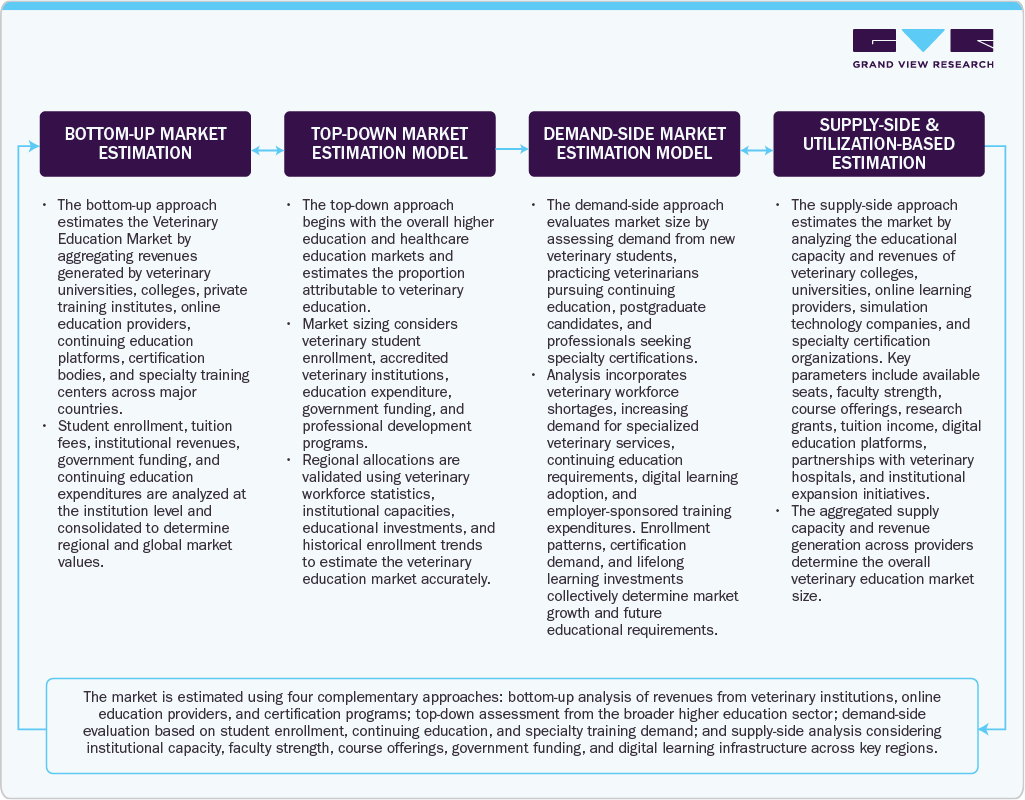
The veterinary education market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each veterinary education segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Course
Revenue Capture Definition
Graduate Courses
Graduate courses include undergraduate veterinary degree programs that provide foundational education in animal anatomy, physiology, pathology, diagnostics, surgery, and clinical practice, preparing students for veterinary licensure and professional careers.
Post-graduate Courses
Post-graduate courses include advanced degrees, residencies, internships, and specialty certifications enabling licensed veterinarians to develop expertise in disciplines such as surgery, oncology, radiology, cardiology, and internal medicine.
Standalone Courses
Standalone courses are short-term certification or continuing education programs focused on specific veterinary skills, technologies, or disciplines, helping students and professionals enhance competencies without enrolling in full-degree programs.
Segment - Specialty
Revenue Capture Definition
Veterinary Surgery
Veterinary surgery specialty covers education and training related to soft tissue, orthopedic, minimally invasive, and emergency surgical procedures, preparing professionals to perform complex operations across companion and livestock animals.
Veterinary Medicine
Veterinary medicine specialty includes diagnosis, treatment, disease prevention, pharmacology, and clinical management of animal health, providing comprehensive medical knowledge required for general and specialized veterinary practice.
Veterinary Nursing
Veterinary nursing focuses on training veterinary technicians and nurses in anesthesia assistance, patient monitoring, laboratory procedures, emergency care, rehabilitation, and clinical support for veterinary healthcare teams.
Animal Grooming
Animal grooming programs provide practical training in hygiene, coat maintenance, nail trimming, skin care, breed-specific grooming techniques, and animal handling, supporting preventive healthcare and pet wellness services.
Other Specialties
Other specialties include veterinary education in pathology, microbiology, epidemiology, animal nutrition, wildlife medicine, public health, behavior, laboratory animal science, and emerging interdisciplinary veterinary fields.
Segment - Institution
Revenue Capture Definition
Public
Public institutions are government-funded veterinary colleges and universities offering accredited veterinary education, research opportunities, and clinical training while maintaining comparatively affordable tuition and broad student accessibility.
Private
Private institutions are independently operated veterinary colleges and training centers offering academic programs, specialized curricula, industry collaborations, and modern learning infrastructure supported through tuition fees and private investments.
Segment - Delivery Mode
Revenue Capture Definition
Classroom-based Courses
Classroom-based courses deliver veterinary education through in-person lectures, laboratory practicals, clinical rotations, dissections, and supervised hands-on training within universities, teaching hospitals, and specialized veterinary institutions.
E-Learning
E-learning delivers veterinary education through online lectures, virtual simulations, digital laboratories, interactive assessments, and remote learning platforms, providing flexible education and continuous professional development opportunities globally.
Segment- Duration
Revenue Capture Definition
Less than 1 year
Less than one-year programs include certificate courses, workshops, and professional training modules designed to rapidly develop specialized veterinary knowledge and practical skills for students and practicing professionals.
1-2 years
One- to two-year programs include diploma courses, postgraduate certificates, internships, and advanced training that provide intermediate specialization while requiring shorter commitments than traditional veterinary degree programs.
More than 2 years
More than two-year programs include veterinary degree programs, master's degrees, doctoral studies, and specialty residencies requiring extensive academic coursework, research, and supervised clinical training before professional qualification.
Segment - Type
Revenue Capture Definition
Tuition
Tuition includes revenue generated from academic fees paid by students for enrollment, instruction, laboratory access, clinical training, examinations, and educational resources across veterinary education institutions.
Non-Tuition
Non-tuition includes institutional revenue from grants, research funding, donations, government support, consulting services, continuing education programs, accommodation, and other administrative or educational service fees.
Segment - End Customer
Revenue Capture Definition
New Students
New students include individuals enrolling in veterinary education programs for the first time to pursue academic qualifications and establish careers in veterinary medicine and animal healthcare professions.
Veterinarians
Veterinarians represent licensed professionals pursuing postgraduate education, specialty certifications, continuing education, or skill enhancement programs to maintain professional competence and expand expertise in advanced veterinary disciplines.
Estimation Model
 To learn more about this report, Download Free Sample Report
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Technology & Innovation Assessment
Detailed evaluation of emerging technologies in veterinary education, including AI-powered learning platforms, virtual simulation laboratories, 3D anatomy software, augmented and virtual reality training, digital learning management systems, competency-based education models, and adaptive assessment tools. The analysis also covers commercialization trends, institutional adoption rates, regulatory developments, and future technology roadmaps influencing veterinary education.
Helps stakeholders identify high-impact educational technologies, prioritize digital transformation investments, improve curriculum effectiveness, enhance student engagement, strengthen practical learning outcomes, and align institutional strategies with evolving veterinary education standards and workforce requirements.
Market Opportunity Analysis
Customized assessment of high-growth education segments, specialty training programs, continuing veterinary education, online certification courses, regional enrollment trends, funding opportunities, regulatory developments, workforce shortages, and future demand forecasts. The analysis incorporates scenario-based forecasting models and primary industry insights to identify emerging growth opportunities across the veterinary education ecosystem.
Supports informed investment decisions, strategic expansion planning, curriculum development, partnership identification, and resource allocation while enabling institutions and education providers to capitalize on evolving workforce needs, digital learning trends, and long-term revenue opportunities.
Competitive Benchmarking
Comprehensive benchmarking of veterinary universities, private institutions, e-learning providers, simulation technology companies, and professional training organizations based on course portfolio, accreditation status, tuition fees, faculty expertise, research capabilities, partnerships, digital infrastructure, student outcomes, and strategic initiatives. The analysis also includes competitive positioning, and recent collaborations.
Enables organizations to evaluate competitive positioning, identify curriculum and technology gaps, benchmark institutional performance, develop differentiation strategies, strengthen academic partnerships, improve student recruitment, and achieve sustainable competitive advantage in the evolving veterinary education market.
Frequently Asked Questions About This Report
Asia Pacific is the fastest-growing region over the forecast period.
The , graduate courses segment led with a 40.3% revenue share in 2025, while the standalone courses segment is the fastest-growing.
The veterinary medicine segment held the largest revenue share in 2025, while the other specialty segment is the fastest-growing.
The public institutions segment held the largest revenue share in 2025, while the public institutions segment is the fastest-growing.
Classroom based courses segment held the largest share in 2025, while the e-learning segment is the fastest-growing.
The global veterinary education market size was valued at USD 3.6 billion in 2025 and is estimated at USD 3.8 billion for 2026.
The global veterinary education market is expected to grow at a CAGR of 6.9% from 2026 to 2033, reaching USD 6.0 billion by 2033.
Some key players operating in the veterinary education market include University of California - Davis, Utrecht University, Cornell University, University of Guelph, University of Sao Paulo, Royal Veterinary College, King Saud University, Indian Veterinary Research Institute, University of Pretoria, China Agricultural University, University of Edinburgh, Swedish University of Agricultural Sciences.
Key factors that are driving the market growth include growing government and institutional funding for veterinary education and growing demand for specialized services, and integration of digital and simulation-based learning and bringing it into practice.
North America dominated with a 32.2% revenue share in 2025.
About the Author(s)
Animal Health Research Team
Healthcare · Animal HealthThis report was authored by the animal health research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the animal health segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


