
- Home
- »
- Animal Health
- »
-
Veterinary Intravenous Solutions Size & Share Report, 2033GVR Report cover

Veterinary Intravenous Solutions Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Isotonic crystalloids, Synthetic colloids, Blood products, Dextrose solutions, Parenteral nutrition, By Animal Type (Companion Animals, Production Animals), By Indication, By End-use, By Region, And Segment
Market Size, 2025
$1.5BMarket Estimate, 2026
$1.6BMarket Forecast, 2033
$2.5BCAGR, 2026–2033
6.6%Veterinary Intravenous Solutions Market Summary
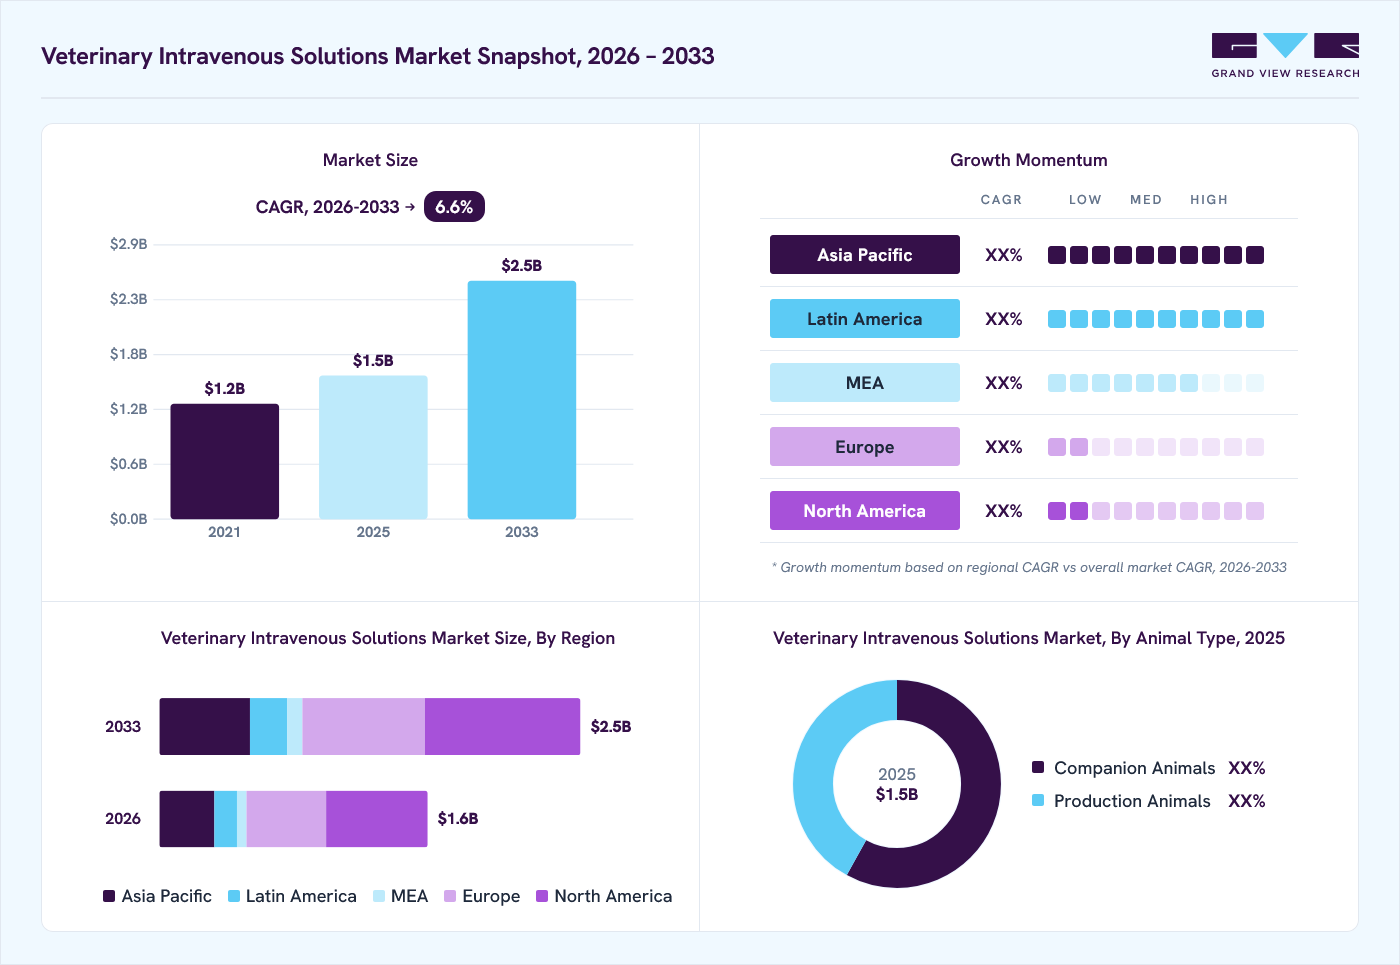
The global veterinary intravenous solutions market size was valued at USD 1.5 billion in 2025 and is projected to grow from USD 1.6 billion in 2026 to USD 2.5 billion by 2033, growing at a CAGR of 6.6% from 2026 to 2033. North America dominated the market, accounting for the largest global share of 38.0% in 2025. For instance, according to an article published by International Cat Care, in February 2025, chronic kidney disease (CKD) can affect cats at any age but is most frequently diagnosed in middle-aged to senior cats, particularly those over 7 years old.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Isotonic crystalloids segment led the market with the largest revenue share of 42.5% in 2025.
- By indication: Diabetic ketoacidosis segment led the market with the largest revenue share of 28.8% in 2025.
- By animal type: Companion animals segment led the market with the largest revenue share of 58.0% in 2025.
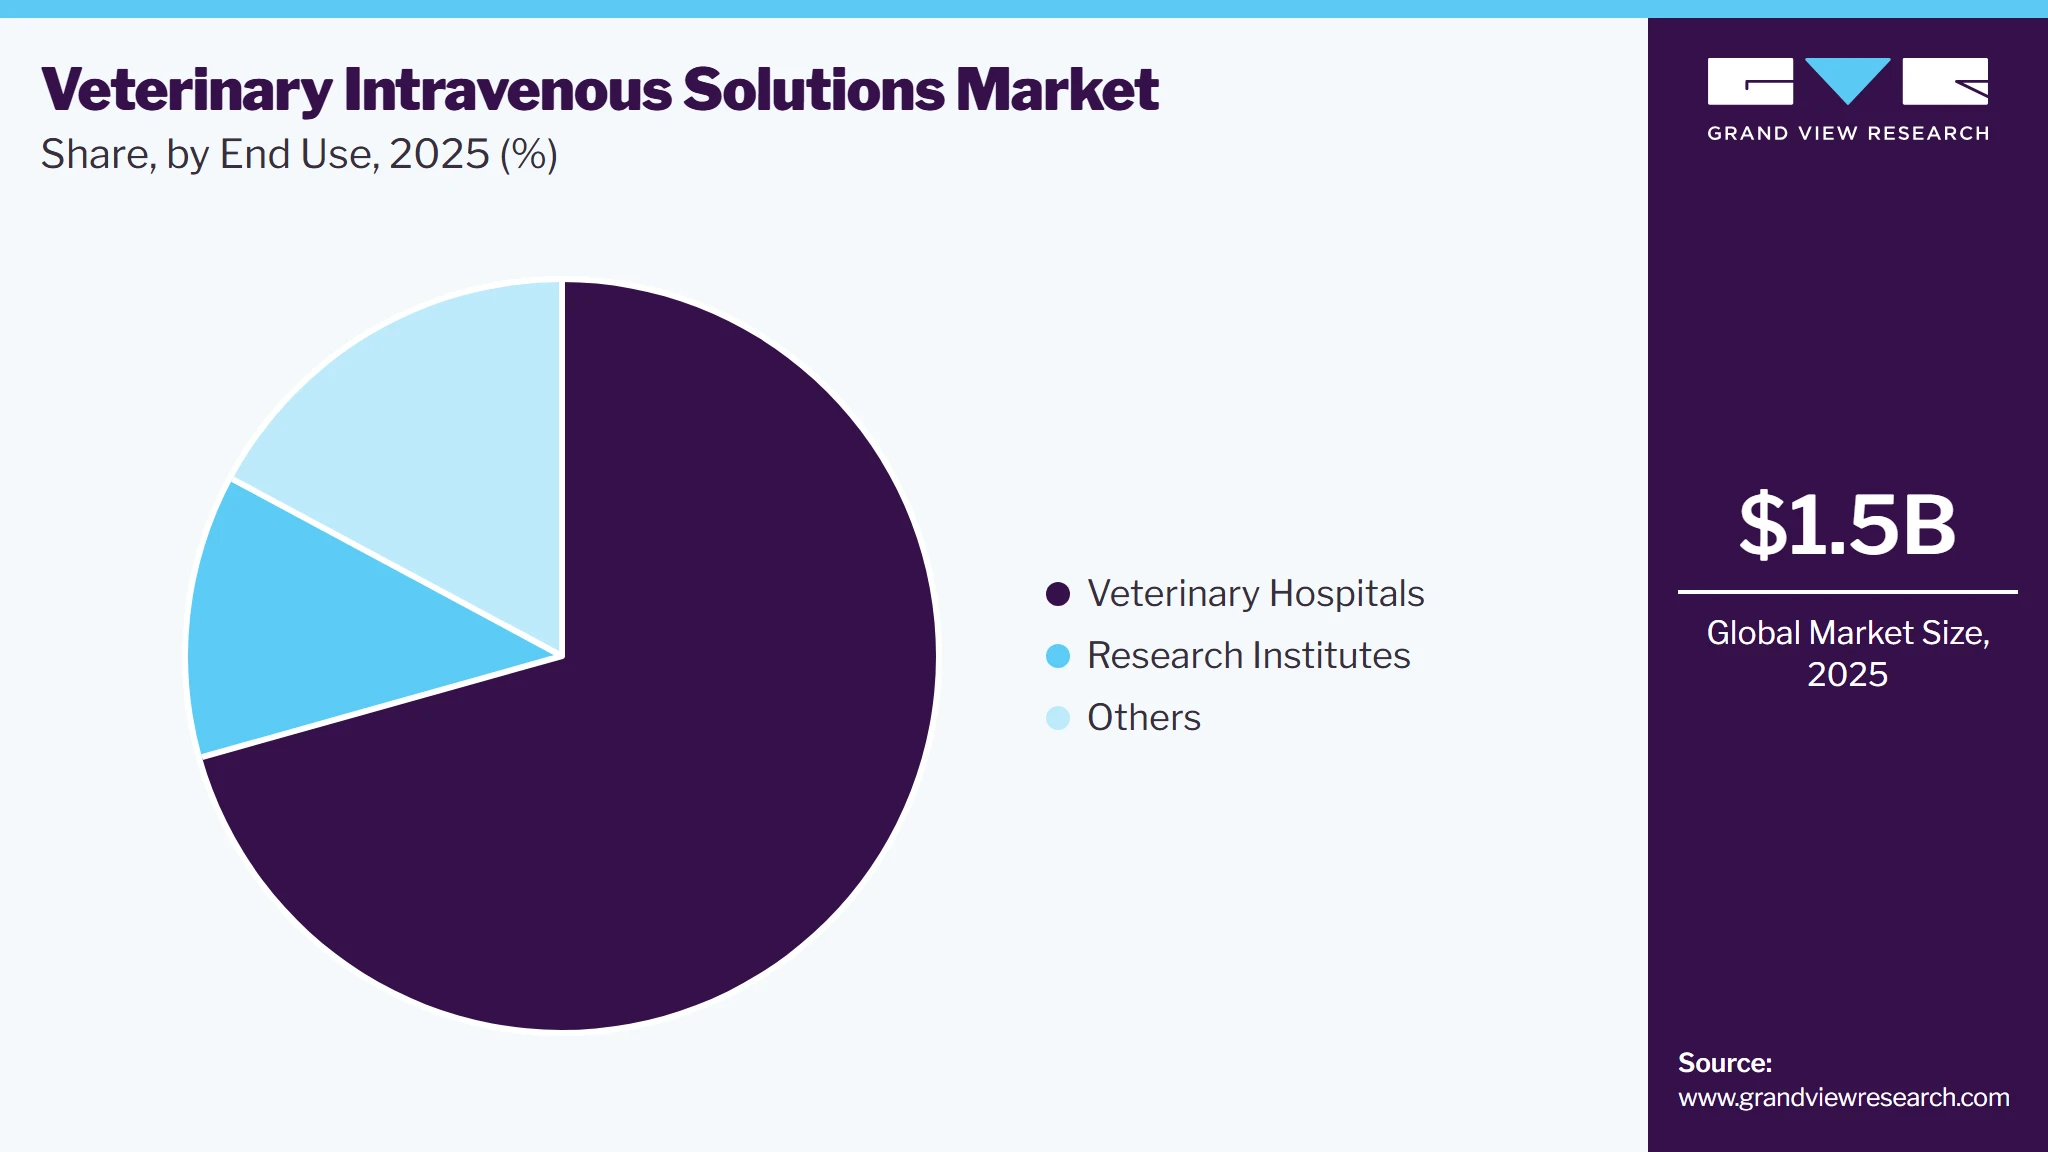
- By end-use: Veterinary hospitals segment led the market with the largest revenue share of 70.6% in 2025.
Regional Highlights
- Largest regional market: North America (38.0% revenue share, 2025)
- By country: The U.S. held the largest share of North America in 2025.
Market Size & Forecast
- Market size in 2025: USD 1.5 Billion
- Estimated market size in 2026: USD 1.6 Billion
- Projected market size by 2033: USD 2.5 Billion
- CAGR (2026-2033): 6.6%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
It is estimated that approximately 20% to 50% of cats aged 15 and older exhibit some level of CKD. The growing adoption of pet insurance worldwide is playing a pivotal role in driving demand for veterinary intravenous (IV) solutions. With rising veterinary costs, pet insurance helps owners manage expenses and opt for higher-quality treatments, especially in critical care situations where IV therapy is essential. IV therapy is a cornerstone in the treatment of a variety of pet health conditions such as dehydration, infections, post-surgical recovery, renal disorders, and toxin exposure, which are frequently covered under pet insurance policies. This access to reimbursement encourages pet owners to choose intensive care options that include IV administration, rather than delaying or avoiding treatment due to cost concerns.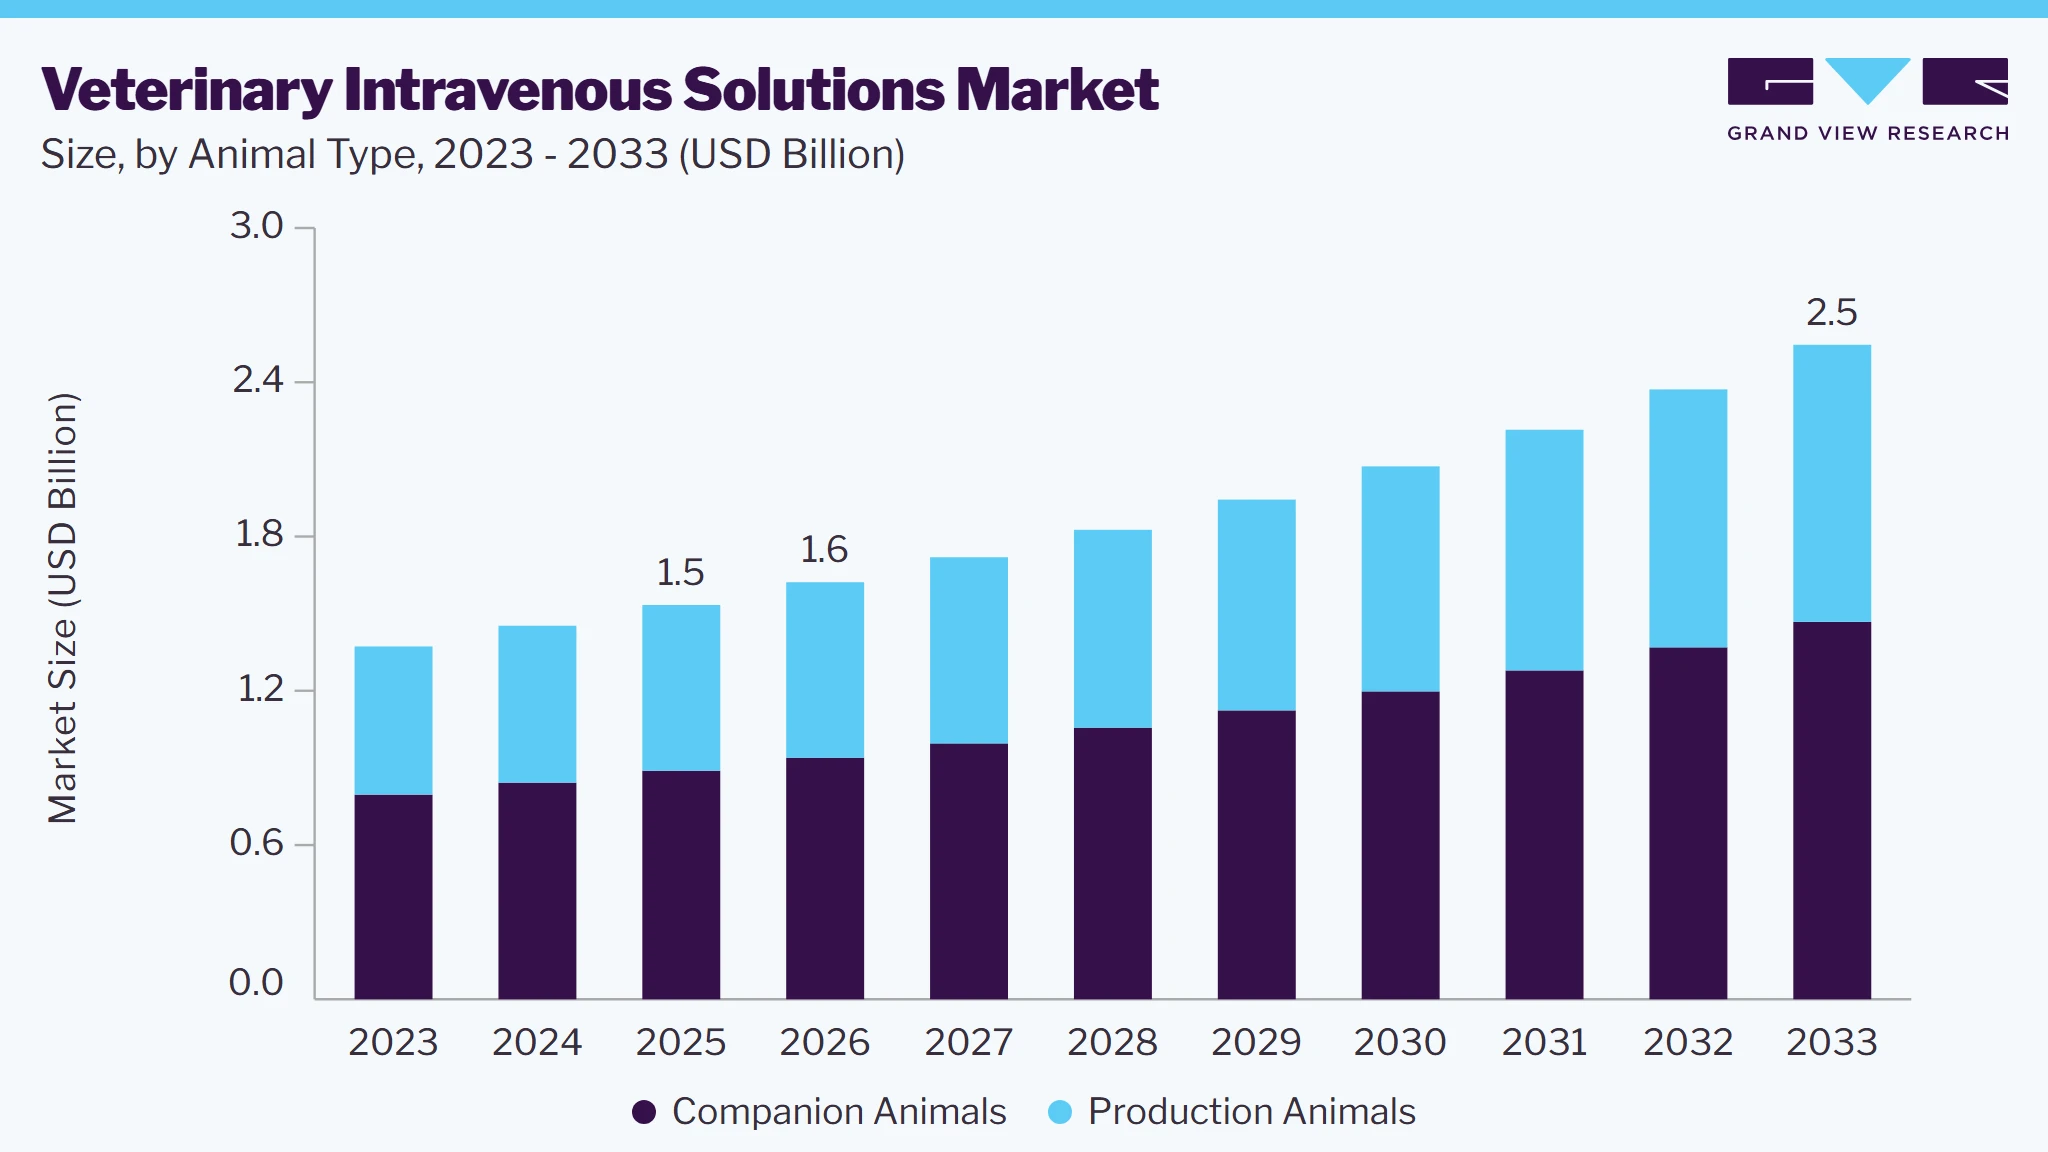 To learn more about this report, Download Free Sample Report
For example, according to an article published by the North American Pet Health Insurance Association, Inc. (NAPHIA) in April 2025, approximately 7.03 million pets were insured in North America by the end of 2024, marking a 12.2% increase from the 6.25 million insured pets in 2023. Additionally, a 2024 article by PetMD highlights that horse insurance can range from USD 300 to USD 3,000, with basic plans typically covering diagnostic tests, treatments, and surgeries, including those related to chronic diseases. With pet owners increasingly prioritizing the health of their horses and dogs, these trends are expected to significantly drive growth in the veterinary intravenous (IV) solutions industry.
Pricing Analysis
Type of Product
Price Range in USD
Size
Isotonic Crystalloids
Lactated Ringer’s Solution (LRS)
$8.00 - $15.00
1 x 1000 ml
0.9% Sodium Chloride (Normal Saline)
$7.00 - $11.00
1 x 1000 ml
Plasma-Lyte
$10.00 - $460.00
1 x 1000 ml
Normosol-R
$5.00 - $11.00
1 x 1000 ml
Synthetic Colloids
Hetastarch
$30 - $60
1 x 1000 ml
Tetrastarch
$40 - $70
1 x 1000 ml
Gelatins
$25 - $50
1 x 1000 ml
Dextrans
$30 - $60
1 x 1000 ml
Blood Products
Whole Blood
$100 - $200
1 x 500 ml
Packed Red Blood Cells (pRBCs)
$80 - $150
1 x 250 ml
Fresh Frozen Plasma (FFP)
$60 - $120
1 x 250 ml
Frozen Plasma (FP)
$50 - $100
1 x 250 ml
Cryoprecipitate
$100 - $200
1 x 50 ml
Platelet-rich plasma
$150 - $300
1 x 50 ml
Dextrose Solutions
5% Dextrose in Water (D5W)
$1 - $2
1 x 1000 ml
2.5% or 5% Dextrose in LRS or 0.45% NaCl
$2 - $3
1 x 1000 ml
50% Dextrose (concentrated)
$4 - $9
1 x 500 ml
Parenteral Nutrition
Amino acids
$25 - $50
1 x 1000 ml
Lipids
$30 - $60
1 x 1000 ml
Electrolytes
$10 - $20
1 x 1000 ml
Vitamins & trace elements
$20 - $40
1 x 1000 ml
Moreover, dehydration is a common and potentially life-threatening condition in both companion animals and livestock. For instance, according to an article published by Hindustan Times, in February 2025, in January 2025, a total of 177 dehydrated animals, including 158 birds and 19 mammals, were admitted to the Transit Treatment Centre (TTC) in Bavdhan, marking a notable increase in such cases. According to data from the RESQ Charitable Trust, a non-governmental organization working in partnership with the Maharashtra Forest Department, these admissions were primarily due to weather-related health issues, with dehydration being a leading concern. These conditions often necessitate immediate rehydration, electrolyte balance, and medication delivery, all of which are effectively managed through IV therapy.
Market Dynamics
The increasing adoption of advanced veterinary critical care and emergency medicine is a key factor driving the veterinary intravenous solutions market. Veterinary hospitals and specialty referral centers are witnessing a rising number of emergency admissions associated with trauma, poisoning, sepsis, heatstroke, acute gastrointestinal disorders, metabolic diseases, and surgical complications, all of which require immediate fluid resuscitation and electrolyte correction through intravenous therapy. In addition, the expansion of 24/7 emergency veterinary facilities, intensive care units, and specialty animal hospitals has significantly increased the routine use of IV fluids during hospitalization and perioperative care. The growing availability of advanced monitoring equipment, infusion pumps, and standardized fluid therapy protocols has further improved treatment outcomes, encouraging wider adoption of IV solutions across companion animal and livestock healthcare. As veterinary medicine continues to transition toward higher standards of critical care, demand for specialized IV formulations and supportive fluid therapy is expected to increase steadily.
However, manufacturers continue to face operational challenges related to sterile manufacturing requirements, stringent quality assurance standards, and uninterrupted supply of medical-grade raw materials. Regulatory agencies require compliance with Good Manufacturing Practices, sterility validation, and rigorous pharmacovigilance, increasing production complexity and operating costs.
The increasing prevalence of chronic kidney disease among companion cats is a major driver for the veterinary intravenous (IV) solutions market. CKD is one of the most common metabolic disorders and a leading cause of mortality in cats over five years of age. Fr instance, according to an article published by AVMA in May 2026, disease prevalence ranges from 1% to 50% and rises dramatically with age, affecting up to 81% of geriatric cats aged 15-20 years. As CKD progresses, affected cats frequently experience dehydration, electrolyte imbalances, reduced kidney function, and accumulation of metabolic toxins, making intravenous fluid therapy a critical component of clinical management. IV solutions are routinely administered to restore hydration, maintain electrolyte balance, improve renal perfusion, and support toxin elimination during hospitalization and emergency care.
Furthermore, international treatment guidelines such as those from the International Renal Interest Society (IRIS) recommend structured therapeutic management for CKD, increasing the number of veterinary interventions required throughout the disease course. As the global population of aging companion animals continues to grow and CKD diagnosis rates increase, the demand for veterinary IV solutions used in renal supportive care is expected to expand steadily, contributing significantly to market growth..
The high cost associated with veterinary hospitalization and intravenous fluid therapy remains a significant restraint for the veterinary intravenous solutions market. Administration of IV solutions often requires hospitalization, trained veterinary professionals, infusion equipment, and continuous patient monitoring, substantially increasing overall treatment expenses. For chronic conditions such as kidney disease, diabetic ketoacidosis, or severe dehydration, repeated or prolonged IV therapy may be necessary, further raising the financial burden on pet owners. In many developing regions, limited pet insurance coverage and out-of-pocket healthcare expenditures discourage owners from pursuing intensive IV treatment, leading to delayed or alternative treatment approaches. These affordability challenges can limit the adoption of veterinary intravenous solutions, particularly in cost-sensitive markets, thereby restraining overall market growth.
The growing adoption of pet insurance presents a significant opportunity for the veterinary intravenous solutions market. As veterinary treatment costs continue to rise, insurance coverage is enabling more pet owners to pursue advanced medical interventions, including hospitalization, emergency care, surgery, and intravenous fluid therapy, without significant financial constraints. According to Feather Insurance, in North America alone, the number of insured pets increased to 6.25 million, while several European countries, particularly Sweden, continue to demonstrate exceptionally high insurance penetration. Hence, higher pet insurance penetration reduces out-of-pocket treatment costs, encouraging greater adoption of advanced veterinary procedures and prolonged inpatient care. This, in turn, increases the demand for intravenous solutions used for fluid replacement, drug administration, anesthesia support, and critical care, thereby creating a sustained market growth opportunity.
Market Concentration & Characteristics
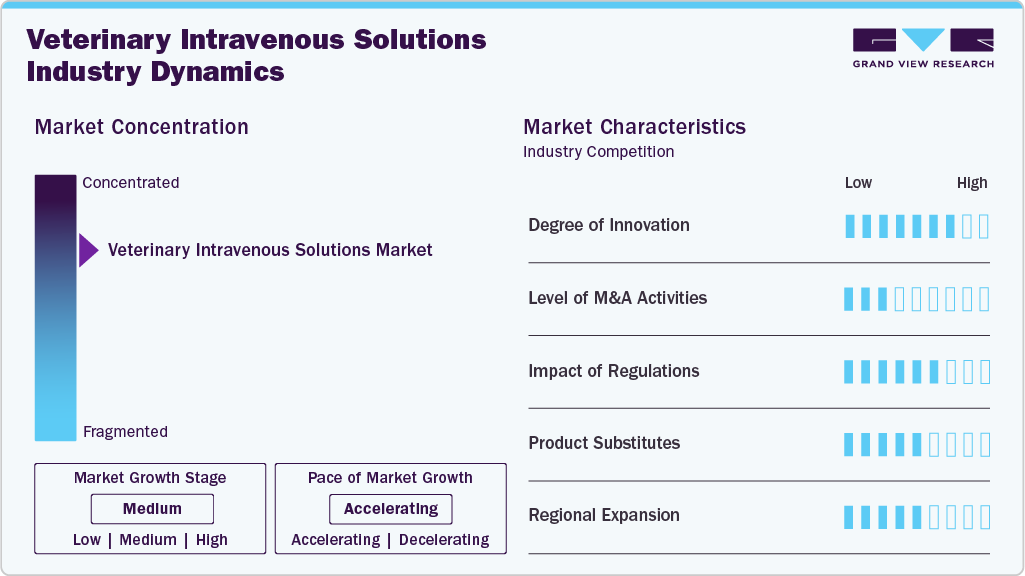
The IV solutions market exhibits a moderate market concentration, and the market growth is accelerating. One of the key factors fueling the market growth is the increasing number of surgical procedures in animals. With an increasing number of pets and livestock undergoing surgeries ranging from routine procedures like spaying to complex operations such as tumor removals and orthopedic interventions, the demand for supportive therapies like IV fluids has surged. For instance, according to an article published by Dr. Kelly's Surgical Unit, in February 2024, approximately 80% of dogs have been spayed or neutered. Intravenous solutions play a crucial role during and after surgery, helping maintain hydration, stabilize electrolyte balance, deliver medications, and support overall recovery.
The market demonstrates a moderate to high level of innovations, due to technological advancements and the launch of new products. For instance, in March 2025, Laboratories Alfa SRL introduced a solution combining 5.5% dextrose with 0.9% sodium chloride. This intravenous solution is designed for fluid and electrolyte replenishment, offering a balanced composition for veterinary use. These solutions are sterile, non-pyrogenic, and intended for single-dose use. They contain no antimicrobial agents and should be discarded if not used immediately after opening. The solutions are available in various concentrations and packaging sizes to meet clinical needs.
 To learn more about this report, Download Free Sample Report
Within the market, there exists a low level of mergers and acquisitions activity. As companies consolidate, they can pool resources for research and development, leading to the introduction of more advanced and cost-effective solutions. M&A also enhances market reach, enabling better distribution networks and access to a larger customer base, including veterinary clinics and hospitals.
Regulatory frameworks play a critical role in shaping the market by directly influencing product development, approval timelines, quality standards, and market accessibility. Agencies such as the FDA’s Center for Veterinary Medicine (CVM) in the U.S. and the European Medicines Agency (EMA) in the EU mandate strict compliance with Good Manufacturing Practices (GMP) and pharmacovigilance requirements to ensure the safety and efficacy of intravenous (IV) solutions administered to animals.
The product substitutes in the market exert a moderate to significant impact by influencing treatment choices, pricing, and innovation. Alternatives such as oral rehydration solutions, subcutaneous fluid therapy, and advanced drug delivery systems (e.g., transdermal patches or injectables) offer less invasive, more convenient, and sometimes cost-effective options, particularly in non-critical or outpatient settings. This can reduce demand for traditional IV solutions in routine veterinary care.
Expanding into new regions allows for better accessibility of IV solutions to a wider array of veterinary clinics, animal hospitals, and healthcare providers. This expansion fosters market penetration in emerging economies with growing pet populations and livestock industries, leading to increased demand for veterinary care.
Analyst Perspective
The veterinary intravenous solutions market is expected to witness stable long-term growth, supported by the continuous modernization of veterinary healthcare infrastructure and increasing clinical adoption of advanced supportive therapies. The expansion of specialty veterinary hospitals, emergency care networks, and referral centers is improving access to sophisticated treatment options that rely on intravenous fluid administration for stabilization, perioperative management, and intensive care. Simultaneously, technological advancements such as precision infusion systems, balanced crystalloid formulations, and improved sterile packaging are enhancing treatment efficiency and patient safety across veterinary settings. Furthermore, the market is benefiting from increasing investments in veterinary education, clinical training, and standardized treatment guidelines that promote appropriate fluid therapy across diverse animal species. Manufacturers are also focusing on expanding production capacity, strengthening regional distribution networks, and developing species-specific formulations to address evolving clinical requirements. As veterinary healthcare systems continue to advance globally and demand for high-quality critical care services rises, the veterinary intravenous solutions market is expected to maintain steady and sustainable growth over the forecast period.
Product Insights
Based on product, the isotonic crystalloids segment led the market with the largest revenue share of 42.5% in 2025. Isotonic crystalloids are commonly used in veterinary medicine to manage various diseases and conditions by restoring fluid and electrolyte balance. They have the same osmolality as blood plasma, ensuring they do not cause significant fluid shifts between compartments. These solutions have an osmolality similar to that of blood plasma, making them effective for treating dehydration, shock, and acid-base imbalances. Isotonic fluids contain the same osmolality as extracellular fluids. As a result, they are great solutions for rehydration and maintenance needs, particularly because they can be provided intravenously, intraosseously, subcutaneously, and intraperitoneally. Lactated Ringer's, 0.9 percent (physiologic or normal) saline, Ringer's, acetated Ringer's, and 2.5% dextrose in 0.45% saline and Plasma-Lyte A are examples of commonly used isotonic solutions.
The dextrose solutions segment is anticipated to grow at the fastest CAGR of about 7.26% from 2025 to 2030. Dextrose, also known as glucose, is a type of sugar that can be administered intravenously to supply a readily available source of energy to the animal's body. Veterinary dextrose solutions can also provide hydration support. By administering dextrose solutions intravenously, water is delivered along with the glucose, helping to maintain proper hydration levels in animals that may be dehydrated or unable to drink water adequately. The most commonly used concentration is 5% dextrose, which is considered isotonic and is often administered alone or in combination with other electrolytes like sodium chloride or lactate. For instance, combinations such as 5% dextrose with 0.33% sodium chloride or with lactated Ringer’s solution are formulated to address both fluid and electrolyte deficits. These combinations help in correcting dehydration while providing essential nutrients.
Animal Type Insights
Based on animal type, the companion animals segment led the market with the largest revenue share of 58.0% in 2025. Companion animals, particularly dogs and cats, are commonly kept as pets in many households. The high rate of pet ownership contributes to the significant demand for veterinary IV fluids, as these animals often require intravenous therapy for various health conditions, surgeries, or critical care situations. According to 2024 data from the American Pet Products Association (APPA), the U.S. is home to over 65.1 million dogs, making it the country with the highest number of owned pets. Apart from the U.S., over 32% of households in Asia own a dog, according to a 2021 survey by Rakuten Insights.
The production animal segment is expected to exhibit the fastest growth rate during the forecast period. Veterinary intravenous (IV) therapy is a critical component in managing the health of production animals such as cattle, sheep, goats, and pigs. These animals are susceptible to dehydration and metabolic imbalances due to factors like gastrointestinal diseases, heat stress, and nutritional deficiencies. Intravenous solutions enable rapid and controlled fluid and electrolyte replacement, which is essential for stabilizing these animals. As the prevalence of mouth disease in farm animals is increasing. For example, animals with cloven hooves, such as cattle, pigs, sheep, and goats, are most commonly affected by the extremely contagious viral disease known as foot-and-mouth disease. While it mainly causes lesions on the feet and mouth, the disease can spread rapidly and have a significant economic impact due to restrictions on animal movement and trade.
Indication Insights
Based on indication, the diabetic ketoacidosis segment led the market with the largest revenue share of 28.8% in 2025. The prevalence of DKA in animals is directly linked to the prevalence of diabetes mellitus in the animal population. Diabetes mellitus, which can be either type 1 or type 2, is relatively common in companion animals, particularly dogs and cats. The incidence of diabetes in animals has been increasing in recent years, potentially leading to a higher prevalence of DKA cases. Intravenous fluid treatment is an essential component of managing diabetic ketoacidosis (DKA) in animals. DKA is a dangerous and sometimes fatal side effect of diabetes mellitus that is typified by metabolic acidosis, hyperglycemia, and ketosis. The intravenous fluid treatment for DKA in animals aims to correct dehydration, restore electrolyte balance, and provide glucose and insulin therapy.
The others segment is expected to exhibit the fastest growth rate of over 6.9% over the forecast period. The others segment includes vomiting, diarrhea, and dehydration. Diarrhea is a frequent presenting condition in companion animal practice. Young dog puppies are considerably more likely to experience both diarrhea and vomiting, and the risk of developing diarrhea falls from 16% in 7- to 12-week-old puppies to 5.4% in 12- to 18-month-old dogs. Veterinary intravenous (IV) solutions are crucial in managing dehydration and electrolyte imbalances associated with diarrhea in animals. Isotonic crystalloids like Lactated Ringer’s and 0.9% Normal Saline are commonly used to restore fluid balance and address acidosis.
End Use Insight
Based on end-use, the veterinary hospitals segment led the market with the largest revenue share of 70.6% in 2025, the veterinary hospital segment accounted for the highest share in the market because more pet owners are taking their animals to hospitals for treatment. Veterinary hospitals often utilize IV fluid therapy as a fundamental component of patient care. Veterinary hospitals are equipped to handle emergencies and provide immediate and intensive care for animals in critical conditions. IV solutions are frequently used in emergencies to stabilize patients, address shock, and ensure prompt delivery of necessary medications and fluids. They play a pivotal role in administering intravenous (IV) solutions, which are essential for managing a wide array of medical conditions in animals. These solutions are utilized to address issues such as dehydration, shock, electrolyte imbalances, and to facilitate the delivery of medications and nutrients.
 To learn more about this report, Download Free Sample Report
The others segment is anticipated to grow at the fastest CAGR over the forecast period. Veterinary home care settings involve providing medical care and treatment for animals in the comfort of their own homes rather than in a traditional veterinary clinic or hospital setting. In such settings, veterinary professionals visit the pet owner's home to provide various healthcare services, including the administration of veterinary IV solutions. Veterinary home care offers convenience and comfort to both the animals and their owners. It eliminates the stress and anxiety associated with transporting animals to a clinic and allows them to receive care in a familiar environment.
Regional Insights
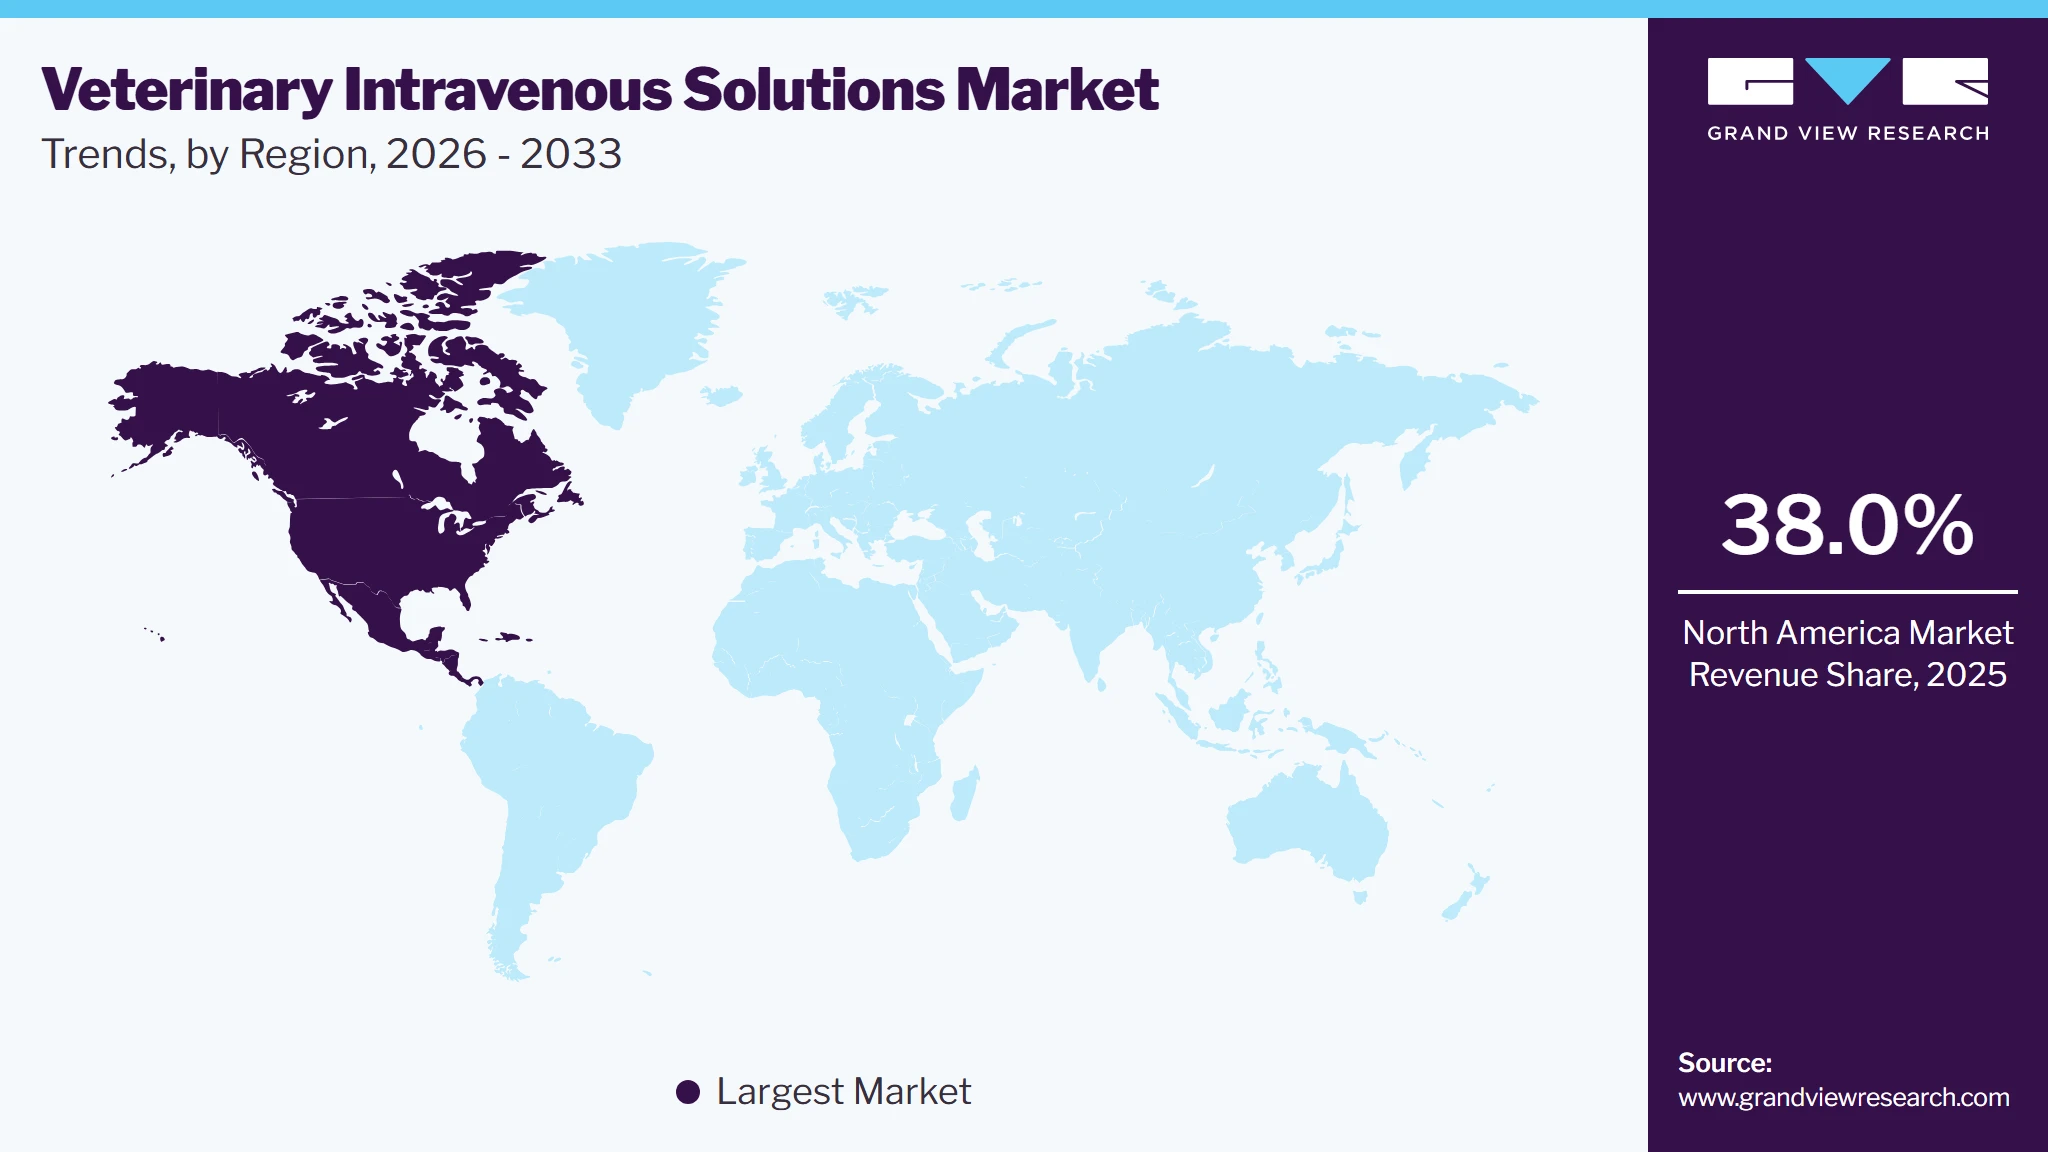
North America dominated the veterinary intravenous solutions market with the largest revenue share of 38.0% in 2025. The market is primarily driven by the rising prevalence of chronic and acute diseases in companion animals. Conditions such as chronic kidney disease (CKD), gastrointestinal illnesses, trauma, and infectious diseases necessitate supportive fluid therapy, making IV solutions an essential component of treatment. For example, CKD affects up to 80% of cats over 15 years old in the U.S., and IV fluids are critical in managing hydration and toxin clearance. Similarly, parvovirus in puppies often requires aggressive fluid therapy to address severe dehydration and electrolyte imbalance. These medical demands are contributing to steady market growth across veterinary practices and emergency clinics.
 To learn more about this report, Download Free Sample Report
U.S. Veterinary Intravenous Solutions Market Trends
The veterinary intravenous solutions market in the U.S. held the largest share in the North America region in 2025. The U.S. market is experiencing steady growth, driven by the rising incidence of chronic diseases in companion animals, such as chronic kidney disease (CKD), gastrointestinal disorders, and severe dehydration. With over 70 million pet dogs and 60 million pet cats in the U.S., and a growing number of aging pets, the demand for IV fluid therapy is escalating. Additionally, emergency and surgical care in veterinary practices routinely rely on IV solutions for anesthesia support, electrolyte balance, and shock management.
Europe Veterinary Intravenous Solutions Market Trends
The European IV solutions market is expected to grow rapidly due to growing emphasis on animal welfare, the expansion of advanced veterinary care, and the high prevalence of chronic and infectious diseases in livestock and companion animals. According to the European Pet Food Industry Federation (FEDIAF), there were approximately 352 million companion animals in Europe as of 2024, with a notable rise in veterinary visits per pet due to improved awareness and spending on animal health. Veterinary clinics across countries like Germany, France, and the UK are increasingly adopting IV fluid therapy in treatments for dehydration, renal disease, and post-surgical care, particularly in aging pet populations, boosting demand for diverse IV solution formulations such as electrolytes, saline, and glucose.
The UK IV solutions market is primarily driven by the increasing pet ownership rates and heightened awareness of veterinary healthcare. According to the Pet Food Manufacturers' Association (PFMA), approximately 59% of UK households owned pets, with dogs and cats being the most common. This growing pet population has directly increased demand for advanced veterinary treatments, including those requiring IV solutions for critical care, surgery, and management of chronic conditions. Veterinary practices are increasingly equipped with facilities for fluid therapy administration, particularly in response to the rising prevalence of kidney disease and diabetes in aging pet populations.
Asia Pacific Veterinary Intravenous Solutions Market Trends
The Asia Pacific veterinary intravenous (IV) solutions market is witnessing significant growth, primarily driven by the region’s expanding livestock population, increasing companion animal ownership, and rising incidence of infectious diseases in animals. Countries like India, China, Australia, and South Korea are seeing increased demand for veterinary healthcare services, particularly in treating dehydration, electrolyte imbalances, and infections in both livestock and pets. For instance, India and China, two of the world's leading producers of cattle and pigs, have seen frequent outbreaks of gastrointestinal infections such as calf diarrhea, swine dysentery, and avian enteritis, which have emphasized the necessity of IV fluid therapy to support animal recovery and reduce mortality rates.
The India veterinary intravenous solutions market is witnessing significant growth, driven by a sharp increase in chronic and acute illnesses among companion animals, particularly renal failure in dogs. According to an article published in February 2025 in the Times of India, Guru Angad Dev Veterinary and Animal Sciences University (GADVASU) in Ludhiana reports 6-7 new canine renal failure cases daily, with many requiring fluid therapy or dialysis. The root causes range from poor diet (junk food, grapes, chocolates), lack of exercise, and the overuse of human painkillers to infectious diseases like babesiosis and tick fever. In these cases, intravenous fluid therapy is essential to restore hydration, support kidney function, and flush out toxins from the body.
Latin America Veterinary Intravenous Solutions Market Trends
Latin America's livestock sector plays a pivotal role in the demand for veterinary IV solutions. Brazil, for instance, stands as a global leader in meat production, with cattle slaughter reaching 34.06 million head in 2023, marking a 13.7% increase from the previous year. Additionally, poultry and swine sectors set records with 6.28 billion chickens and 57.17 million pigs processed, respectively. Such large-scale operations necessitate advanced veterinary care, including IV therapies, to manage animal health effectively and ensure productivity.
The Brazil IV solutions market is experiencing sustained growth, driven by the widespread prevalence of infectious diseases such as neonatal calf diarrhea, alongside the country’s expansive cattle industry. Diarrheal diseases, particularly those caused by rotavirus A (RVA) and bovine viral diarrhea virus (BVDV), significantly threaten young calves and contribute to economic losses through reduced growth rates, increased mortality, and higher veterinary costs. A study covering Brazil’s Midwest, South, and Southeast regions found RVA in 27.4% of diarrheic fecal samples from calves, with beef calves showing a notably higher infection rate (31.9%) compared to dairy calves (17.4%), and the Midwest region alone showing 39.4% RVA-positive cases. These findings illustrate the urgent demand for supportive treatments such as IV fluid therapy to manage dehydration and stabilize infected animals.
Middle East & Africa Veterinary Intravenous Solutions Market Trends
The veterinary intravenous (IV) solutions market in the Middle East and Africa (MEA) region is growing steadily, driven by the expanding livestock sector, rising pet ownership, and increasing government investment in animal health infrastructure. Countries like Saudi Arabia, UAE, Kuwait, and South Africa have large livestock populations—Saudi Arabia alone has over 30 million livestock heads—necessitating IV treatments for dehydration, heat stress, and disease management, especially in arid climates.
The market in South Africa is experiencing notable growth. One of the primary drivers is the increasing prevalence of animal diseases such as infectious diseases, dehydration, and chronic conditions like kidney disease, which frequently require IV fluid therapy as part of treatment protocols. In both emergency and routine veterinary care, IV solutions are essential for managing dehydration, delivering medications, and supporting animals during surgical procedures or periods of critical illness. For example, outbreaks of diseases such as avian influenza in poultry and rising cases of chronic kidney disease in aging pets have increased the demand for supportive therapies like IV fluids to stabilize and treat affected animals.
Key Veterinary Intravenous Solutions Company Insights
The market is competitive and marked by the presence of key players. The key parameters affecting competition include a technological advancement. Additionally, to maintain market share and expand their product portfolios, leading companies are adopting strategies such as mergers and acquisitions, strategic partnerships, and the launch of innovative products.
Key Veterinary Intravenous Solutions Companies
The following are the leading companies in the veterinary intravenous solutions.
- Merck & Co., Inc (Animal Health
- Dechra
- Animalcare Limited
- B. Braun Vet Care (B Braun SE)
- Elanco Animal Health Incorporated (Animal Health
- Zoetis Inc.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Merck Animal Health; Dechra; Animalcare Limited; B. Braun Vet Care (B. Braun SE); Elanco Animal Health; Zoetis Inc.)
- Established companies focus on expanding comprehensive veterinary fluid therapy portfolios by offering isotonic crystalloids, synthetic colloids, dextrose solutions, parenteral nutrition, blood products, and specialty IV fluids for companion and production animals. They strengthen their position through continuous product innovation, GMP-certified manufacturing, strategic acquisitions, veterinary education programs, global distribution networks, and partnerships with veterinary hospitals and distributors. Investments in manufacturing expansion, supply chain optimization, and regulatory approvals enable broader market penetration.
- Leading companies benefit from strong brand recognition, diversified animal health portfolios, established relationships with veterinary hospitals and clinics, global manufacturing capabilities, and extensive regulatory expertise. Their ability to maintain high-quality manufacturing standards, ensure reliable product availability, invest in clinical research, and leverage worldwide distribution networks enables them to secure long-term contracts and maintain customer loyalty.
- Established vendors face challenges from increasing manufacturing and logistics costs, stringent regulatory requirements, raw material supply disruptions, pricing pressure from generic manufacturers, and growing competition from regional suppliers. Product recalls, supply shortages, and lengthy approval timelines for new formulations may also impact profitability and market expansion.
Emerging Players (Regional veterinary IV fluid manufacturers and specialty infusion solution providers)
- Emerging companies primarily focus on cost-effective IV solutions, niche fluid therapy products, customized formulations, and regional market expansion. They compete through flexible manufacturing, contract manufacturing partnerships, competitive pricing, localized distribution, and targeted product launches for veterinary hospitals and livestock sectors. Many also emphasize faster regulatory approvals in domestic markets and strategic collaborations with distributors.
- Emerging players compete through operational agility, quicker product commercialization, competitive pricing, regional manufacturing capabilities, and the ability to address underserved markets. Their focus on localized production, customized packaging, and responsive customer support enables them to establish a presence in developing veterinary healthcare markets.
- Emerging vendors often have limited manufacturing capacity, lower brand recognition, restricted global distribution, and fewer financial resources for R&D and regulatory compliance. They may face challenges in scaling production, meeting international quality standards, competing with multinational manufacturers, and maintaining consistent product availability.
Recent Developments
- In June 2018, Sypharma Pty Ltd, an Australian pharmaceutical manufacturer, achieved a significant milestone with FDA approval for the distribution of its Hartmann’s IV solution in the United States. Marketed under its veterinary brand Sykes IV Lyte Injection (Electrolytes), this approval marks a strategic expansion of Sypharma’s global footprint in the animal health sector.
Veterinary Intravenous Solutions Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 1.5 billion
Market size value in 2026
USD 1.6 billion
Revenue forecast in 2033
USD 2.5 billion
Growth rate
CAGR of 6.6% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, indication, animal type, end-use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; South Korea; Australia; Thailand; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait; Oman; Qatar.
Key companies profiled
Merck & Co., Inc (Animal Health; Dechra; Animalcare Limited; B. Braun Vet Care (B Braun SE); Elanco Animal Health Incorporated (Animal Health; Zoetis Inc.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Veterinary Intravenous Solutions Market Report
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the veterinary intravenous solutions market report based on animal type, product, indication, end use, and region.
-
Product Outlook (Revenue, USD Million; 2021 - 2033)
-
Isotonic crystalloids
-
Synthetic colloids
-
Blood products
-
Dextrose solutions
-
Parenteral nutrition
-
-
Indication Outlook (Revenue, USD Million; 2021 - 2033)
-
Diabetic Ketoacidosis
-
Pancreatitis
-
Anthrax
-
Chronic Kidney Disease
-
Others
-
-
Animal Type Outlook (Revenue, USD Million; 2021 - 2033)
-
Companion Animals
-
Production Animals
-
-
End Use Outlook (Revenue, USD Million; 2021 - 2033)
-
Veterinary Hospitals
-
Research Institutes
-
Others
-
-
Regional Outlook (Revenue, USD Million; 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
Rest of Europe
-
-
Asia Pacific
-
Japan
-
India
-
China
-
South Korea
-
Australia
-
Thailand
-
Rest of APAC
-
-
Latin America
-
Brazil
-
Argentina
-
Rest of LATAM
-
-
Middle East and Africa (MEA)
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
- Rest of MEA
-
-
Research Methodology
The veterinary intravenous solutions market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each veterinary intravenous solutions segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue Capture Definition
Isotonic crystalloids
Revenue generated from the sale of isotonic crystalloid intravenous solutions used to restore fluid volume, maintain electrolyte balance, and treat dehydration and shock in animals.
Synthetic colloids
Accounts for the market value associated with synthetic colloid intravenous solutions administered to expand plasma volume and stabilize circulation in critically ill veterinary patients.
Blood products
Comprises the income generated through the provision of veterinary blood products, including whole blood, plasma, and blood components used for transfusion and the treatment of anemia, hemorrhage, and coagulation disorders.
Dextrose solutions
Reflects the sales value of dextrose-based intravenous solutions utilized for energy supplementation, hypoglycemia management, and fluid therapy in animals.
Parenteral nutrition
Covers the market revenue attributable to parenteral nutrition formulations administered intravenously to animals requiring complete or supplemental nutritional support.
Segment - Indication
Revenue Capture Definition
Diabetic Ketoacidosis
Represents the market value of intravenous solutions used in the treatment of animals diagnosed with diabetic ketoacidosis, including fluid resuscitation and electrolyte correction.
Pancreatitis
Captures the demand-driven revenue from intravenous fluid therapy administered to animals with pancreatitis to maintain hydration and support recovery.
Anthrax
Encompasses the value of intravenous solutions utilized as supportive therapy for animals undergoing treatment for anthrax.
Chronic Kidney Disease
Reflects the expenditure on intravenous solutions used in managing chronic kidney disease, including therapies aimed at maintaining hydration and renal perfusion.
Others
Includes the market size contributed by intravenous solutions used across other disease conditions requiring fluid therapy and supportive veterinary care.
Segment - Animal Type
Revenue Capture Definition
Companion Animals
Represents the value of veterinary intravenous solutions administered to companion animals, including dogs, cats, horses, and other pets across various treatment settings.
Production Animals
Covers the market contribution from intravenous solutions used in livestock, including cattle, swine, poultry, sheep, goats, and other production animals for disease management and recovery.
Segment - End Use
Revenue Capture Definition
Veterinary Hospitals
Accounts for the procurement value of veterinary intravenous solutions by veterinary hospitals for emergency care, surgery, hospitalization, and intensive care applications.
Research Institutes
Represents the spending on veterinary intravenous solutions by research institutes for laboratory animal care, preclinical studies, and veterinary research activities.
Others
Includes the market value generated through the utilization of veterinary intravenous solutions by other healthcare settings, such as veterinary clinics, academic institutions, animal shelters, and rehabilitation centers.
Estimation Model
Estimation Model
Description
Animal Population & Clinical Utilization Model
Market size is estimated by identifying leading veterinary IV solution manufacturers, animal healthcare companies, infusion therapy suppliers, and contract manufacturers across major regions. Revenue attributable to isotonic crystalloids, synthetic colloids, blood products, dextrose solutions, parenteral nutrition, and specialty IV fluids is collected from annual reports, financial statements, company disclosures, and paid databases. Individual company revenues are aggregated and validated using product portfolio analysis, manufacturing capacity, regional sales, pricing trends, and estimated IV solution contribution to veterinary fluid therapy revenue.
Disease Burden & Veterinary Treatment Model
Market value is estimated by assessing companion and production animal populations, hospitalization rates, surgical procedures, emergency care, dehydration incidence, critical care admissions, and disease prevalence across major countries. Utilization rates are evaluated using veterinary treatment guidelines, procedure volumes, livestock health management practices, and companion animal healthcare expenditure. Revenue is calculated by applying average IV fluid consumption per procedure, treatment duration, hospitalization frequency, and product utilization across different animal types and clinical indications.
Healthcare Infrastructure & Distribution Model
Market value is estimated by assessing the prevalence of dehydration, diabetic ketoacidosis, pancreatitis, chronic kidney disease, trauma, surgical interventions, and other conditions requiring fluid therapy. Product utilization is evaluated using treatment protocols, critical care admissions, advances in veterinary intensive care, clinical practice guidelines, and availability of specialized IV formulations. Revenue is calculated by applying disease-specific treatment rates, average fluid consumption per patient, veterinary healthcare expenditure, and adoption of advanced fluid therapy products across major countries.
Veterinary Infrastructure & Procurement Model
Market size is estimated by evaluating IV solution utilization through veterinary hospitals, specialty clinics, emergency care centers, livestock farms, research institutes, and distribution partners. Parameters including veterinary infrastructure, healthcare accessibility, procurement practices, product availability, hospital purchasing patterns, and distribution network expansion are assessed across major regions. Revenue potential is estimated using average selling prices, institutional procurement volumes, channel-wise sales contribution, and utilization rates within veterinary healthcare facilities.
Summary & Triangulation Framework
This estimation framework enhances market visibility by integrating manufacturer revenues, animal population dynamics, disease burden, clinical treatment practices, healthcare infrastructure, and veterinary procurement trends. The triangulated methodology provides a comprehensive assessment of IV solution demand across companion and production animals while accurately identifying market opportunities, product innovation, and future investment priorities.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Veterinary Fluid Therapy Product Portfolio Assessment
Conducted a comprehensive assessment of the veterinary IV solutions landscape covering manufacturers of isotonic crystalloids, synthetic colloids, blood products, dextrose solutions, and parenteral nutrition. Evaluated product portfolios, indication-wise utilization, manufacturing capabilities, formulation advancements, pricing trends, regulatory approvals, and regional availability across companion and production animal healthcare.
Provides a detailed understanding of the competitive product landscape, identifies portfolio gaps, highlights innovation opportunities, and supports product development, licensing, and investment decisions within veterinary fluid therapy.
Veterinary IV Solutions Supplier Benchmarking
Performed a detailed benchmarking of leading veterinary IV solution manufacturers based on production capacity, manufacturing footprint, product breadth, quality certifications, distribution network, strategic collaborations, regional presence, and technology capabilities. Included comparative analysis of global and regional manufacturers to identify competitive positioning.
Enables identification of preferred manufacturing partners, sourcing opportunities, operational strengths, competitive differentiation, and partnership prospects while supporting procurement and strategic business expansion.
Veterinary Hospital Procurement & Demand Analysis
Assessed purchasing behavior across veterinary hospitals, specialty clinics, emergency care centers, livestock facilities, and research institutes by evaluating procedure volumes, disease prevalence, procurement models, treatment protocols, reimbursement trends, and future demand for IV solutions. Recommended priority end-use segments and regional growth opportunities.
Assists companies in prioritizing high-growth customer segments, optimizing sales strategies, strengthening distribution planning, and improving resource allocation based on evolving clinical demand patterns.
Frequently Asked Questions About This Report
Asia Pacific is the fastest-growing region over the forecast period.
The isotonic crystalloids segment led with a 42.5% revenue share in 2025, while the dextrose solutions is the fastest-growing segment.
The diabetic ketoacidosis segment led with a 28.8% revenue share in 2025, while the others is the fastest-growing segment.
The global veterinary intravenous (IV) solutions market size was estimated at USD 1.5 billion in 2025 and is expected to reach USD 1.6 billion in 2026.
The global veterinary intravenous (IV) solutions market is expected to grow at a compound annual growth rate of 6.6% from 2026 to 2033 to reach USD 2.5 billion by 2033.
North America dominated the veterinary intravenous solutions market with a share of 38.0% in 2025.
Some key players operating in the Veterinary Intravenous Solutions market include Merck & Co., Inc (Animal Health, Dechra, Animalcare Limited, B. Braun Vet Care (B Braun SE), Elanco Animal Health Incorporated (Animal Health, Zoetis Inc.
Key factors that are driving the veterinary intravenous solutions market growth include the increasing incidence of animal diseases & dehydration, the growing adoption of pet insurance, and the increase in pet ownership & pet expenditure.
The companion animals segment led with a 58.0% revenue share in 2025, while the production animals is the fastest-growing segment.
About the Author(s)
Animal Health Research Team
Healthcare · Animal HealthThis report was authored by the animal health research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the animal health segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


