
- Home
- »
- Next Generation Technologies
- »
-
Video Conferencing Market Size & Share Report, 2026-2033GVR Report cover

Video Conferencing Market (2026 - 2033)
Size, Share & Trends Analysis Report By Component (Hardware, Software, And Services), By Deployment, By Enterprise Size, By Application, By End Use, By Region, And Segment Forecasts
Market Size, 2025
$13.1BMarket Estimate, 2026
$14.4BMarket Forecast, 2033
$24.6BCAGR, 2026–2033
7.9%Video Conferencing Market Summary
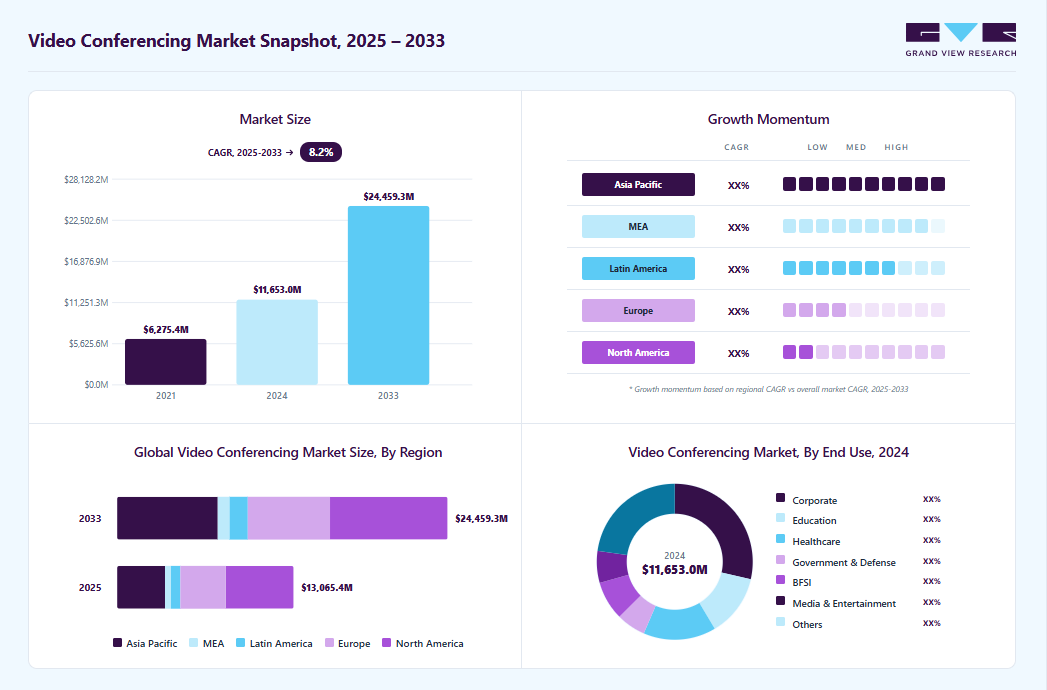
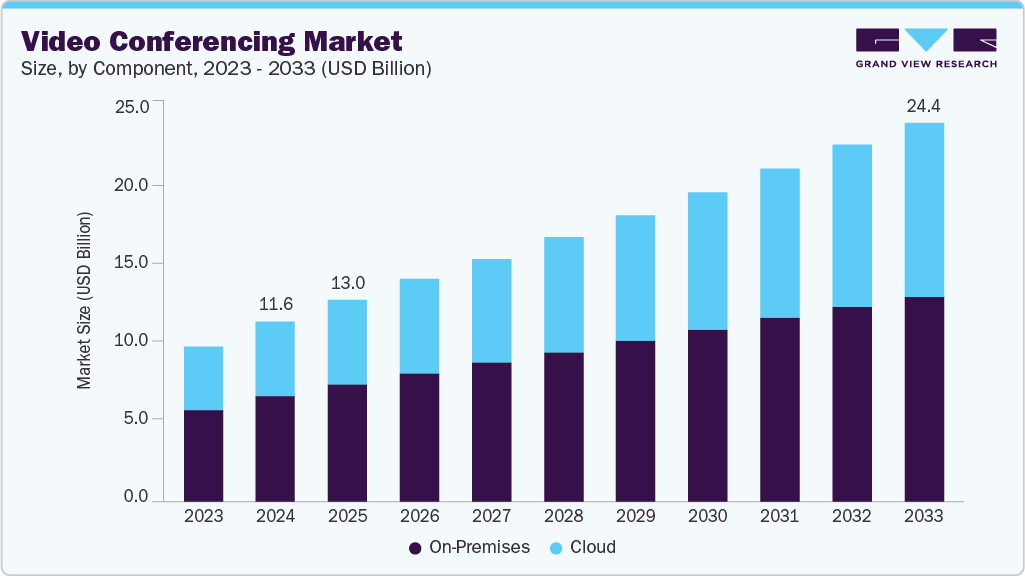
The global video conferencing market size was valued at USD 13.1 billion in 2025 and is projected to grow from USD 14.4 billion in 2026 to USD 24.6 billion by 2033, at a CAGR of 7.9% from 2026 to 2033. The market in North America dominated with a revenue share of 38.5% in 2025. The video conferencing market is primarily driven by the growing adoption of remote and hybrid work models, as well as the increasing need for real-time digital collaboration and communication across businesses, educational institutions, and healthcare organizations.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By application: Enterprise segment held the largest market share of 85.5% in 2025.
- By enterprise size: Large enterprises segment held the largest market share of 76.5% in 2025.
- By deployment: On-premise segment held the largest market share of 57.8% in 2025.
- By component: Hardware segment held the largest market share of 46.3% in 2025.
- By end use: Corporate segment held the largest market share of 28.8% in 2025.
Regional Highlights
- Largest regional market: North America (38.5% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 13.1 Billion
- Estimated market size in 2026: USD 14.4 Billion
- Projected market size by 2033: USD 24.6 Billion
- CAGR (2026-2033): 7.9%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Additionally, the growing advancements in internet connectivity, the widespread availability of high-speed broadband and 5G networks, and the growing demand for cost-effective virtual meetings and webinars are further fueling the market growth. This expansion is fueled by the widespread adoption of hybrid and remote work models, as organizations across sectors seek flexible, scalable communication tools to connect dispersed teams, boost productivity, and ensure business continuity in an increasingly digital work environment.The rapid shift toward cloud-based video conferencing solutions, which offer reduced operational and capital expenditures (OPEX and CAPEX), seamless scalability, and easy integration with other enterprise tools, is expanding the video conferencing industry. Additionally, the rise of cloud-native enterprises and the growing need for virtual meeting spaces have prompted significant investments in cloud infrastructure. This enables businesses to facilitate real-time collaboration while minimizing travel costs and supporting global connectivity, further accelerating the market growth.
 To learn more about this report, Download Free Sample Report
Additionally, technological advancements, particularly the integration of artificial intelligence (AI) and machine learning, are transforming the user experience in video conferencing. AI-powered features such as automatic noise cancellation, real-time language translation, intelligent background management, and in-meeting assistants make virtual meetings more efficient, accessible, and engaging. Such innovations help enhance audio and video quality and automate scheduling, note-taking, and participant management tasks, significantly improving meeting productivity and driving the video conferencing industry expansion.
Furthermore, security and privacy have become paramount as video conferencing platforms handle sensitive business and personal information. Implementing robust encryption protocols, complying with regulations such as GDPR and HIPAA, and continuously developing advanced security features are critical trends, especially as organizations become more vigilant about data protection in virtual environments. This focus on security also drives demand for on-premises solutions in industries with strict compliance requirements.
Moreover, companies are adopting various strategies to enhance their competitive edge. Key companies are integrating advanced technologies such as artificial intelligence (AI), cloud computing, and 5G connectivity to improve user experience, scalability, and security. Additionally, companies are investing heavily in robust security protocols, including end-to-end encryption and compliance with data privacy regulations, to protect sensitive communications. Key players' strategies will drive the video conferencing industry in the coming years.
Market Dynamics
The video conferencing industry is highly competitive and rapidly evolving, driven by continuous technological innovation, increasing demand for remote communication solutions, and the growing adoption of cloud-based collaboration platforms. The market comprises several global and regional players that compete on factors such as video and audio quality, security features, scalability, ease of use, integration capabilities, and pricing. Furthermore, growing advancements in artificial intelligence, virtual collaboration tools, and network infrastructure are reshaping the competitive landscape, encouraging companies to enhance their offerings and expand their market presence.
The widespread adoption of remote and hybrid work arrangements has become a major growth driver for the video conferencing market. Organizations across industries rely on virtual meeting platforms to maintain communication, coordinate projects, and support collaboration among geographically dispersed teams. Video conferencing has evolved from a supplementary communication tool into a core component of daily business operations.
Enterprises are investing in advanced conferencing solutions that offer features such as screen sharing, meeting recordings, virtual whiteboards, and real-time collaboration capabilities. These functionalities help improve productivity while reducing the need for frequent business travel. The growing acceptance of flexible work policies is driving demand for reliable, scalable video communication platforms.
Educational institutions and healthcare providers are also contributing to market growth. Schools and universities use video conferencing for remote learning and virtual classrooms, while healthcare organizations leverage teleconsultation services to connect patients with medical professionals. The broadening range of use cases strengthens the market's long-term growth prospects.
Security and privacy challenges remain significant restraints on the video conferencing market. Virtual meetings often involve the exchange of confidential business information, personal data, financial records, and sensitive healthcare details. Any security breach can result in reputational damage, regulatory penalties, and loss of customer trust.
Organizations operating in highly regulated sectors such as banking, healthcare, and government place strong emphasis on data protection requirements. Concerns related to unauthorized access, meeting disruptions, data leakage, and cyberattacks can discourage adoption or delay deployment decisions. Businesses frequently conduct extensive security assessments before selecting a video conferencing provider.
Meeting evolving compliance standards requires continuous investment in encryption technologies, identity management systems, and security monitoring capabilities. These additional requirements can increase operational costs for solution providers and create implementation challenges for end users, limiting market expansion in certain segments.
Artificial intelligence creates substantial opportunities for innovation and differentiation within the video conferencing market. AI-powered features such as automated meeting transcription, real-time language translation, intelligent noise suppression, speaker recognition, and meeting summaries improve user experience and enhance communication efficiency.
Global organizations with multilingual workforces increasingly value solutions that support seamless communication across languages and regions. AI-enabled translation and transcription tools help reduce communication barriers and improve accessibility for participants. These capabilities are becoming important decision-making factors in enterprise evaluations of conferencing platforms.
The continued development of generative AI technologies opens additional possibilities for workflow automation and productivity enhancement. Intelligent assistants can automatically generate action items, summarize discussions, identify key decisions, and organize meeting content. Vendors that successfully integrate advanced AI capabilities into their platforms are likely to gain a competitive advantage and new revenue opportunities.
Market Concentration & Characteristics
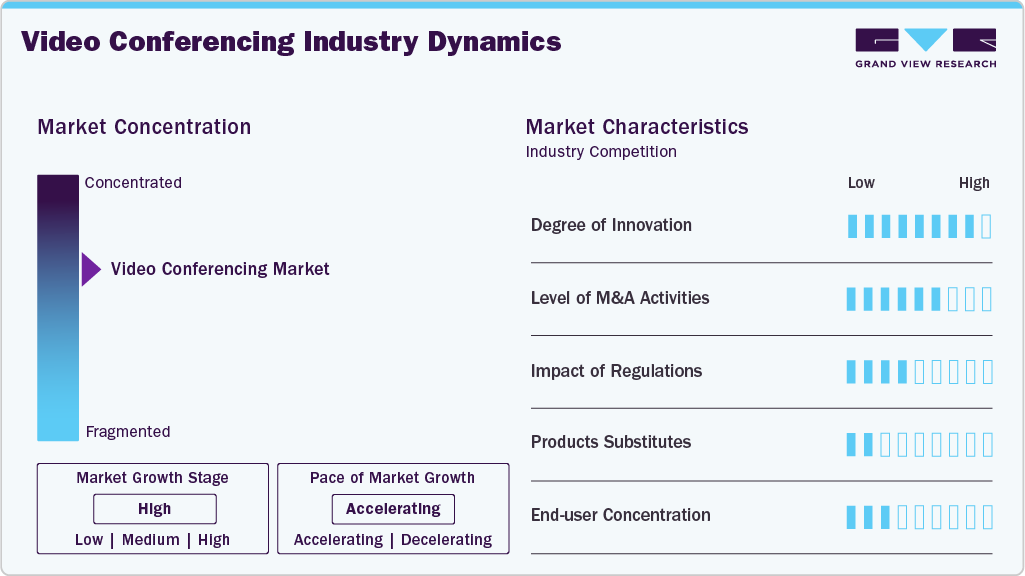
The video conferencing market is moderately concentrated, with a few dominant global players such as Microsoft, Zoom, Cisco, and Google holding significant market share, while several regional vendors and niche solution providers contribute to a competitive and diverse ecosystem. The market is highly innovation-driven, supported by rapid advancements in cloud computing, AI-powered collaboration tools, real-time transcription, and integrated unified communication platforms that continuously enhance user experience and enterprise productivity.
 To learn more about this report, Download Free Sample Report
The industry is witnessing steady consolidation through mergers, acquisitions, and strategic partnerships, as major technology firms expand ecosystems by integrating video conferencing with productivity suites and cloud platforms. Regulatory influence is moderately high, driven by data privacy, cybersecurity, and cross-border compliance requirements, which shape enterprise adoption without significantly limiting growth. The threat of substitutes is low, with tools like messaging, email, and asynchronous collaboration competing for attention but lacking the benefits of real-time interaction. End-user concentration remains low due to widespread adoption across enterprises, education, healthcare, government, and individual users globally.
Analyst Perspective
The video conferencing market is a rapidly expanding digital communication space driven by the widespread adoption of hybrid work models, cloud-based collaboration, and AI-enabled meeting solutions. It is evolving from a basic communication tool into an integrated enterprise collaboration ecosystem, driven by strong demand from the corporate, education, healthcare, and government sectors.
Component Insights
Based on component, the hardware segment led the market with the largest revenue share of 46.3% in 2025, driven by the increasing adoption of hybrid work models that require high-quality, reliable equipment such as cameras, microphones, collaboration bars, and codec systems to facilitate seamless communication across dispersed teams. Technological advancements such as AI-powered noise cancellation, intelligent framing, and 4K video resolution enhance the user experience. At the same time, the growing demand from educational institutions, corporate offices, and commercial spaces further fuels the segment's growth. Additionally, the rising popularity of all-in-one integrated devices simplifies setup and management, making hardware solutions more accessible to SMEs and large enterprises.
The software segment is expected to register the fastest CAGR of over 9.1% from 2026 to 2033, owing to the widespread shift to cloud-based platforms that offer scalable, flexible, and cost-effective video conferencing solutions. Increasing demand for features such as real-time collaboration, virtual backgrounds, AI-driven transcription, and meeting analytics drives software adoption. Integration capabilities with other enterprise applications, such as CRM and project management tools, enhance workflow efficiency. The growing preference for subscription-based models and the need for secure, encrypted communication further drive the segmental growth.
Deployment Insights
Based on deployment, the on-premise segment dominated the market with the largest revenue share of 57.8% in 2025. By deploying on-premises solutions, companies maintain full ownership and management of their data within their infrastructure, significantly reducing dependency on external service providers and limiting exposure to extraterritorial data laws. This control allows organizations to implement customized security policies, respond swiftly to security incidents, and ensure compliance with strict regulatory requirements, which is especially important for sectors handling sensitive information such as finance, government, and healthcare.
The cloud-based deployment segment is expected to register the fastest CAGR from 2026 to 2033, owing to its flexibility, scalability, and cost-effectiveness. The ability to quickly update features, support remote workforces, and integrate with multiple devices and platforms accelerates adoption. Cloud solutions also facilitate global collaboration by enabling seamless connectivity across geographies. The rise of AI-powered enhancements and analytics within cloud platforms further improves meeting productivity and user engagement, driving growth in both enterprise and consumer segments.
Enterprise Size Insights
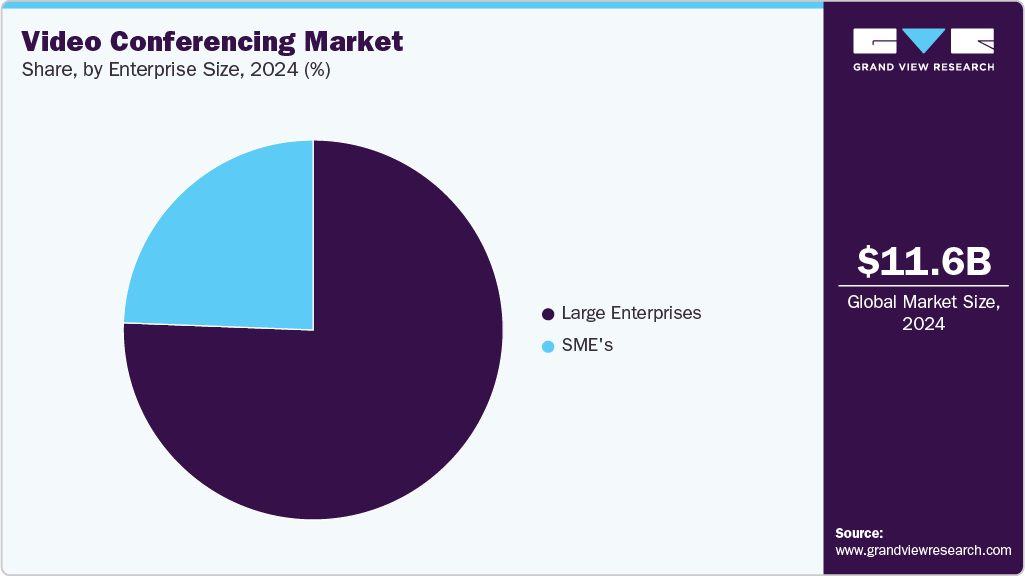
Based on enterprise size, the large enterprises segment led the market with the largest revenue share of 76.5% in 2025. They invest heavily in advanced conferencing solutions to support business continuity, employee training, and collaboration. The ability to reduce travel costs and improve decision-making speed are key drivers. Large enterprises also prioritize security and integration with existing IT infrastructure.
 To learn more about this report, Download Free Sample Report
The SMEs segment is expected to register the fastest CAGR from 2026 to 2033. SMEs are increasingly adopting video conferencing to enhance flexibility and reduce operational costs. Affordable, scalable, cloud-based solutions make video conferencing accessible to SMEs. The shift toward hybrid work models and the need to remotely maintain client and team engagement are key growth factors for this segment.
Application Insights
Based on application, the enterprise segment dominated the market with the largest revenue share of 85.5% in 2025, driven by the demand for room-based hardware solutions and software platforms that enable seamless virtual meetings. Enterprises seek solutions that improve productivity, support hybrid work, and offer integration with business applications. The growth of 5G networks and enhanced internet infrastructure further facilitates enterprise adoption.
The consumer application segment is expected to register the fastest CAGR from 2026 to 2033, owing to the increased social connectivity needs, remote learning, and virtual events. The pandemic accelerated usage, and ongoing demand for high-quality, easy-to-use platforms sustains growth. Consumer-focused solutions emphasize simplicity, mobile compatibility, and affordability.
End Use Insights
Based on end use, the corporate segment dominated the market with the largest revenue share of 28.8% in 2025, driven by the growing interest in cloud-based communication and collaboration tools. The shift toward hybrid work models and global business operations increases the need for reliable, high-quality video solutions. Corporations emphasize security, ease of use, and integration with existing IT infrastructure. The growing investments in upgrading conference rooms with advanced hardware and software solutions reflect the increasing importance of video conferencing in enhancing productivity and reducing travel expenses.
The healthcare segment is expected to grow at a significant CAGR from 2026 to 2033, owing to increased telemedicine demand, cost-effective remote patient care, and regulatory support for telehealth reimbursement. The need for HIPAA-compliant, secure platforms integrated with electronic health records drives the market. Innovations such as remote monitoring and virtual consultations are transforming healthcare delivery, especially in rural and underserved areas.
Regional Insights
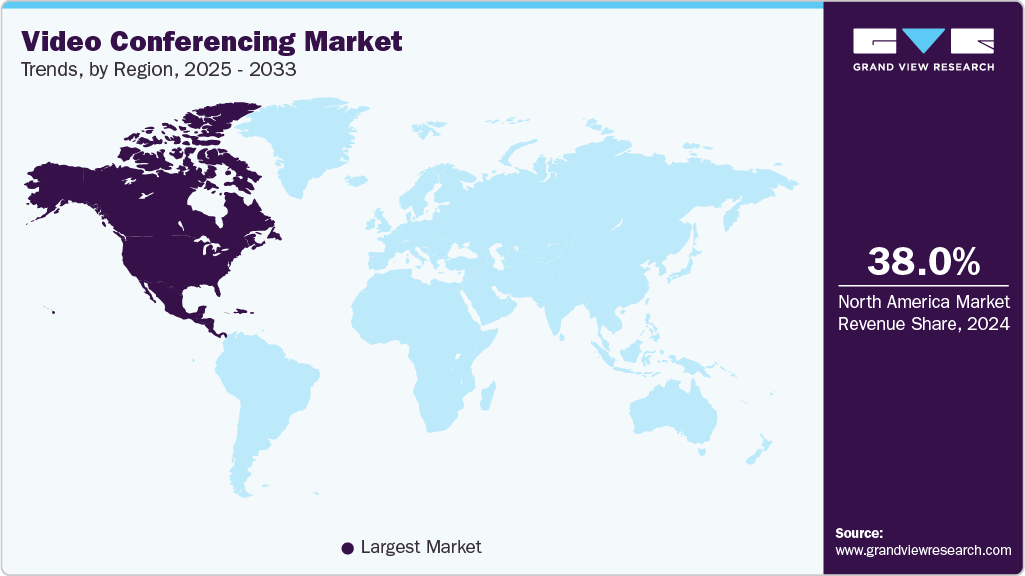
North America dominated the video conferencing market, accounting for the largest revenue share of 38.5% in 2025, driven by rapid technology adoption, widespread hybrid work models, and strong digital transformation across industries. The presence of major players is fueling innovation in cloud-based unified communication and AI-powered collaboration tools. Additionally, government initiatives promoting contactless meetings and digitalization, along with significant investments in advanced hardware and software solutions, are driving the market growth. The region also sees strong demand from educational institutions adopting video conferencing for remote learning and virtual classrooms.
 To learn more about this report, Download Free Sample Report
U.S. Video Conferencing Market Trends
The video conferencing market in the U.S. held the largest share in the North America region in 2025. The rapid rollout and adoption of 5G technology, which significantly enhances video call quality through faster network speeds, lower latency, and more reliable connectivity is driving the market growth in U.S. Such advancements support high-definition and even 3D video conferencing without lag or disruptions, enabling seamless remote collaboration and boosting demand for video conferencing solutions across enterprises and educational institutions.
Europe Video Conferencing Market Trends
The Europe video conferencing market accounted for a market share of over 25.7% in 2025, owing to the widespread adoption of hybrid work models, robust digital infrastructure, and increasing reliance on virtual collaboration tools. Key drivers include rising corporate R&D investments, government initiatives such as Europe’s Digital Strategy 2050 promoting digital transformation, and integrating advanced features such as AI-powered transcription, noise suppression, and virtual backgrounds.
The Germany video conferencing market is expected to grow significantly in the coming years, driven by the increasing importance of video conferencing tools for virtual meetings, collaboration, and productivity maintenance across organizations. Germany’s strong industrial base and digital transformation initiatives encourage adoption in both private and public sectors. The country’s emphasis on technological innovation and infrastructure upgrades, including 5G deployment, supports enhanced video conferencing experiences.
The UK video conferencing market is rapidly expanding, driven by improvements in internet speed, video quality, and user-friendly software platforms. The country’s strong corporate presence and digital infrastructure facilitate widespread adoption. Hybrid and remote work trends continue to boost demand, supported by government policies and investments in digital connectivity. The UK benefits from its role as a major business hub, encouraging enterprises to adopt video conferencing for efficient communication and collaboration.
Asia Pacific Video Conferencing Market Trends
The Asia Pacific video conferencing market is expected to grow at the fastest CAGR of 9.5% from 2026 to 2033, driven by a rising number of SMEs and startups, increasing penetration of high-speed internet, and growth across sectors such as IT, telecommunications, education, healthcare, and entertainment. The region’s rapid economic growth and technological adoption, including mobile broadband advancements, accelerate market expansion. The shift towards hybrid and remote work models, especially in urban centers, fuels demand for reliable and scalable video conferencing solutions.
The China video conferencing market is driven by rapid economic development, increasing digitalization, and domestic enterprises' adoption of advanced technologies. The government’s focus on digital infrastructure and smart city initiatives further propels market expansion.
The Japan video conferencing market is rapidly expanding, driven by the increasing trend toward remote and hybrid work models. As organizations prioritize flexible work arrangements, the need for dependable and high-quality video conferencing platforms is rising. Technological advancements in mobile broadband and network infrastructure also enhance the user experience. Japan’s corporate sector adoption and government support for digital transformation initiatives underpin this growth.
Key Video Conferencing Company Insights
Some of the key players operating in the market include Adobe, Inc., Cisco Systems, Inc., Huawei Technologies Co., Ltd., and Google LLC.
-
Adobe Inc. is a diversified multinational software solutions provider. The company’s solutions and services meet the needs of professionals, marketers, application developers, enterprises, and consumers by creating, managing, delivering, and optimizing content and experiences across multiple devices.
-
Avaya LLC. is a business communications company offering a wide range of services and software, including real-time video collaboration, unified communications, networking, contact centers, and related services, to companies of all sizes worldwide. The company operates through two business segments: products, solutions, and services.
Vidyo, Inc. (now Enghouse Video), West Corporation (Intrado Life & Safety, Inc.), and AURA Presence LLC are some of the emerging market participants in the video conferencing market.
-
Vidyo, Inc., is a global developer and provider of video conferencing solutions. It offers error-resilient, high-definition, and multi-point video conferencing to desktop and room system endpoints. The company’s video conferencing solutions include VidyoConnect, VidyoEngage, and VidyoCloud, which provide real-time, high-quality collaboration among geographically dispersed teams and offices.
-
Intrado Corporation, formerly known as West Corporation, is a network infrastructure and communication services provider. The company provides collaboration and conferencing services to various industries/sectors, such as consumer services, cable and satellite, education, financial services, healthcare, manufacturing, insurance, public safety, retail, technology, telecom, transportation and logistics, travel and hospitality, and utilities.
Key Video Conferencing Companies
The following key companies have been profiled for this study on the video conferencing market.
-
Adobe Inc.
-
AURA Presence, LLC
-
Avaya LLC
-
Cisco Systems, Inc.
-
Google LLC
-
Huawei Technologies Co., Ltd.
-
Logitech International S.A.
-
Microsoft Corporation
-
Plantronics, Inc. (acquired by HP Development Company, L.P.)
-
Enghouse Video (formerly Vidyo, Inc.)
-
West Corporation (Intrado Life & Safety, Inc.)
-
Zoom Video Communications, Inc.
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Established Players (Microsoft Corporation, Cisco Systems, Inc., Google LLC, Zoom Video Communications, Inc., Adobe Inc.)
- Expand unified communication ecosystems by integrating video conferencing with productivity suites, collaboration tools, and cloud platforms.
- Invest heavily in AI-driven features, enterprise-grade security, and hybrid work solutions.
- Strong global brand recognition, large enterprise customer base, and deeply integrated ecosystems.
- High scalability, advanced AI capabilities, and robust security frameworks support enterprise adoption.
- High dependency on enterprise customers and subscription models can create pricing pressure.
- Intense competition reduces differentiation, especially in core video meeting features.
Emerging & Specialized Players (Avaya LLC, Enghouse Video, AURA Presence, LLC, Logitech International S.A., Plantronics/HP, West Corporation (Intrado), Huawei Technologies Co., Ltd.)
- Focus on niche offerings such as hardware-enabled conferencing, industry-specific communication solutions, on-premises deployments, and hybrid infrastructure models.
- Emphasize cost-effective solutions, customization, and integration with legacy enterprise systems.
- Strong presence in specific segments such as hardware (cameras, audio devices), enterprise telephony, and on-premises communication systems.
- Flexibility in tailoring solutions for regulated industries like government, BFSI, and healthcare.
- Limited dominance in global cloud-based collaboration ecosystems compared to hyperscalers.
- Lower consumer visibility and weaker brand recognition in mainstream video conferencing markets.
Recent Developments
-
In April 2025, Avaya LLC launched the Avaya Infinity platform, a transformative solution designed to unify fragmented customer experiences and evolve traditional contact centers into connection centers. This platform integrates AI, intelligent orchestration, and seamless channel connectivity to enhance customer and employee relationships with flexibility across cloud, on-premises, and hybrid environments.
-
In April 2024, Adobe Inc. launched the latest all-new Frame.io V4, a flexible, fast, and intuitive creative collaboration platform that streamlines and simplifies workflows across content creation and production.
-
In April 2024, Zoom Video Communications, Inc. announced the general availability of Zoom Workplace, the company’s AI-powered collaboration platform that includes new features to help users reimagine teamwork, facilitate connections, and improve productivity.
Video Conferencing Market Report Scope
Report Attribute
Details
Market size in 2025
USD 13.1 billion
Estimated market size in 2026
USD 14.4 billion
Projected market size by 2033
USD 24.6 billion
Growth rate
CAGR of 7.9% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Component, deployment, enterprise size, application, end use, and region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; U.K.; Germany; France; Italy; China; Australia; Japan; India; South Korea; Brazil; Mexico; South Africa; Saudi Arabia, UAE
Key companies profiled
Adobe Inc.; AURA Presence, LLC; Avaya LLC; Cisco Systems, Inc.; Google LLC; Huawei Technologies Co., Ltd.; Logitech International S.A.; Microsoft Corporation; Plantronics, Inc. (acquired by HP Development Company, L.P.); Enghouse Video (formerly Vidyo, Inc.); West Corporation (Intrado Life & Safety, Inc.); Zoom Video Communications, Inc.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Video Conferencing Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global video conferencing market report based on component, deployment, enterprise size, application, end use, and region.
-
Component Outlook (Revenue, USD Million, 2021 - 2033)
-
Hardware
-
Camera
-
Microphone/Headphone
-
Others
-
-
Software
-
Service
-
Professional services
-
Managed services
-
-
-
Deployment Outlook (Revenue, USD Million, 2021 - 2033)
-
On-Premises
-
Cloud-based
-
-
Enterprise Size Outlook (Revenue, USD Million, 2021 - 2033)
-
SMEs
-
Large Enterprise
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Consumer
-
Enterprise
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Corporate
-
Education
-
Healthcare
-
Government & Defense
-
BFSI
-
Media & Entertainment
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
-
Latin America
-
Brazil
-
Mexico
-
-
Middle East and Africa (MEA)
-
Saudi Arabia
-
South Africa
-
-
Research Methodology
The video conferencing market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each video conferencing segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Component
Revenue capture definition
Hardware
Revenue is generated from the sale of video conferencing hardware, including cameras, microphones, headphones, speakers, conferencing endpoints, display systems, and related accessories used to facilitate virtual communication and collaboration.
Software
Revenue is generated through subscription fees, licensing agreements, and usage-based pricing for video conferencing platforms that offer features such as virtual meetings, webinars, screen sharing, recording, collaboration tools, and communication management.
Service
Revenue is generated through consulting, deployment, integration, maintenance, technical support, managed services, training, and system optimization services associated with video conferencing solutions.
Segment - Deployment
Revenue capture definition
On-Premises
Revenue is generated from the sale, installation, customization, and maintenance of video conferencing solutions hosted within an organization's own IT infrastructure, including software licenses, hardware, and support contracts.
Cloud-based
Revenue is generated through recurring subscription fees and service-based pricing models for video conferencing platforms hosted on cloud infrastructure, providing remote accessibility, scalability, and automatic software updates.
Segment – Enterprise Size
Revenue capture definition
SMEs
Revenue is generated from video conferencing solutions adopted by small and medium-sized enterprises for business communication, team collaboration, customer engagement, training, and remote work operations.
Large Enterprise
Revenue is generated from large-scale deployments of video conferencing platforms and services used by large organizations to support enterprise-wide communication, global collaboration, virtual events, and workforce management.
Segment – Application
Revenue capture definition
Consumer
Revenue is generated through subscriptions, premium features, virtual events, and other paid services utilized by individual users for personal communication, social interaction, online learning, and entertainment purposes.
Enterprise
Revenue is generated through software subscriptions, licensing agreements, hardware purchases, and service contracts used by organizations for business meetings, collaboration, training, client interactions, and corporate communications.
Segment – End Use
Revenue capture definition
Corporate
Revenue is generated from the adoption of video conferencing solutions by businesses for internal meetings, project collaboration, employee training, customer engagement, and communication across multiple locations.
Education
Revenue is generated through the deployment of video conferencing platforms and services by schools, colleges, universities, and training institutions for virtual classrooms, distance learning, academic collaboration, and administrative communication.
Healthcare
Revenue is generated by healthcare providers through the use of video conferencing technologies for telemedicine consultations, remote patient monitoring, medical training, and collaboration among healthcare professionals.
Government & Defense
Revenue is generated through the procurement and deployment of secure video conferencing solutions by government agencies and defense organizations for administration, strategic communication, public services, and mission-critical coordination.
BFSI
Revenue is generated from the implementation of video conferencing platforms by banking, financial services, and insurance organizations for customer consultations, internal communication, compliance activities, financial advisory services, and remote operations.
Media & Entertainment
Revenue is generated using video conferencing solutions for virtual productions, interviews, content creation, broadcasting coordination, remote collaboration, and online events within the media and entertainment industry.
Others
Revenue is generated from video conferencing adoption across industries such as retail, manufacturing, hospitality, transportation, legal services, and non-profit organizations for communication, collaboration, training, and operational management activities.
Estimation Model
Layer Name
Key Question
Description
Video Conferencing Population Layer
Who are the potential video conferencing users?
Represents the total global base of individuals and organizations that may require digital communication tools. This includes enterprises, small businesses, educational institutions, healthcare providers, government bodies, and individual users across urban and semi-urban regions with access to internet-enabled devices.
Platform & Technology Layer
What technologies power video conferencing solutions?
Includes core software platforms, communication protocols, and enabling technologies such as cloud-native architectures, WebRTC, artificial intelligence, machine learning, and encryption technologies. These technologies support features like real-time video streaming, virtual collaboration, transcription, and noise cancellation.
Use Case & Application Layer
How is video conferencing being used?
Covers the different functional applications across sectors such as corporate meetings, remote work collaboration, online education, telemedicine, virtual events, customer support, interviews, and training programs.
Revenue Generation Layer
How is revenue generated?
Revenue is generated through software subscriptions, cloud-based service plans, enterprise licensing, and premium feature offerings. Additional income comes from hardware sales, managed services, and value-added functionalities such as security enhancements, collaboration tools, and AI-enabled communication features.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Market Sizing, Competitive Landscape & Growth Opportunity Assessment
Conducted a detailed evaluation of the global video conferencing market size, growth drivers, competitive benchmarking of key players, regional penetration trends, and demand dynamics across the enterprise, education, healthcare, and government sectors. Analyzed revenue models, adoption rates, and future expansion opportunities across cloud and hybrid deployments.
Enables accurate market entry planning, identifies high-growth regions and segments, supports strategic investment decisions, enhances competitive positioning, and reduces uncertainty in expansion strategies within a rapidly evolving collaboration ecosystem.
Deployment Architecture, Infrastructure & Security Optimization
Assessed deployment models including cloud-native, on-premises, and hybrid architectures with a focus on scalability, latency performance, bandwidth optimization, and system interoperability. Evaluated cybersecurity frameworks, including encryption standards, identity management, compliance requirements, and data privacy regulations across industries.
Improves system reliability, enhances data security and regulatory compliance, optimizes infrastructure costs, ensures seamless performance across geographies, and supports enterprise-grade trust and adoption in sensitive sectors like BFSI, healthcare, and government.
Customer Segmentation, Adoption Strategy & Monetization Framework
Analyzed user segmentation across SMEs, large enterprises, and individual users, along with adoption patterns across corporate communication, education, telehealth, and virtual events. Evaluated pricing models including subscription tiers, freemium offerings, enterprise licensing, and value-added service monetization.
Maximizes revenue potential through tailored pricing strategies, improves customer acquisition and retention, enhances product-market fit across segments, and supports scalable monetization across both enterprise and consumer ecosystems.
Frequently Asked Questions About This Report
The global video conferencing market size was valued at USD 13.1 billion in 2025 and is estimated at USD 14.4 billion for 2026.
The global video conferencing market is expected to grow at a CAGR of 7.9% from 2026 to 2033, reaching USD 24.6 billion by 2033.
North America dominated with a 38.5% revenue share in 2025.
Key factors that are driving the video conferencing market growth include the rapidly growing demand for video communication on account of the globalization of businesses, geographically scattered business operations, and remote workforce management.
Some key players operating in the video conferencing market include Adobe Inc.; AURA Presence, LLC; Avaya LLC; Cisco Systems, Inc.; Google LLC; Huawei Technologies Co., Ltd.; Logitech International S.A.; Microsoft Corporation; Plantronics, Inc. (acquired by HP Development Company, L.P.); Enghouse Video (formerly Vidyo, Inc.); West Corporation (Intrado Life & Safety, Inc.); Zoom Video Communications, Inc.
Asia-Pacific is expected to register the fastest growth of over 9.0% from 2026 to 2033.
The hardware segment led with a 46.3% revenue share in 2025, while the software segment is the fastest-growing component.
Enterprise segment held the largest share (over 85.0%) in 2025, while the consumer segment is the fastest-growing application.
The corporate segment led with a 28.8% revenue share in 2025, and is the fastest-growing end use.
About the Author(s)
Next Generation Technologies Research Team
Technology · Next Generation TechnologiesThis report was authored by the next generation technologies research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the next generation technologies segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


