
- Home
- »
- Advanced Interior Materials
- »
-
Wet Pet Food Processing Equipment Market Report, 2033GVR Report cover

Wet Pet Food Processing Equipment Market (2026 - 2033)
Size, Share & Trends Analysis Report By Equipment (Processing, Packaging, Cleaning & Sanitization), By Food Type (Dog Food, Cat Food), By Form, By Package Type, By Region, And Segment Forecasts
Market Size, 2025
$1.7BMarket Estimate, 2026
$1.8BMarket Forecast, 2033
$2.7BCAGR, 2026–2033
5.7%Wet Pet Food Processing Equipment Market Summary
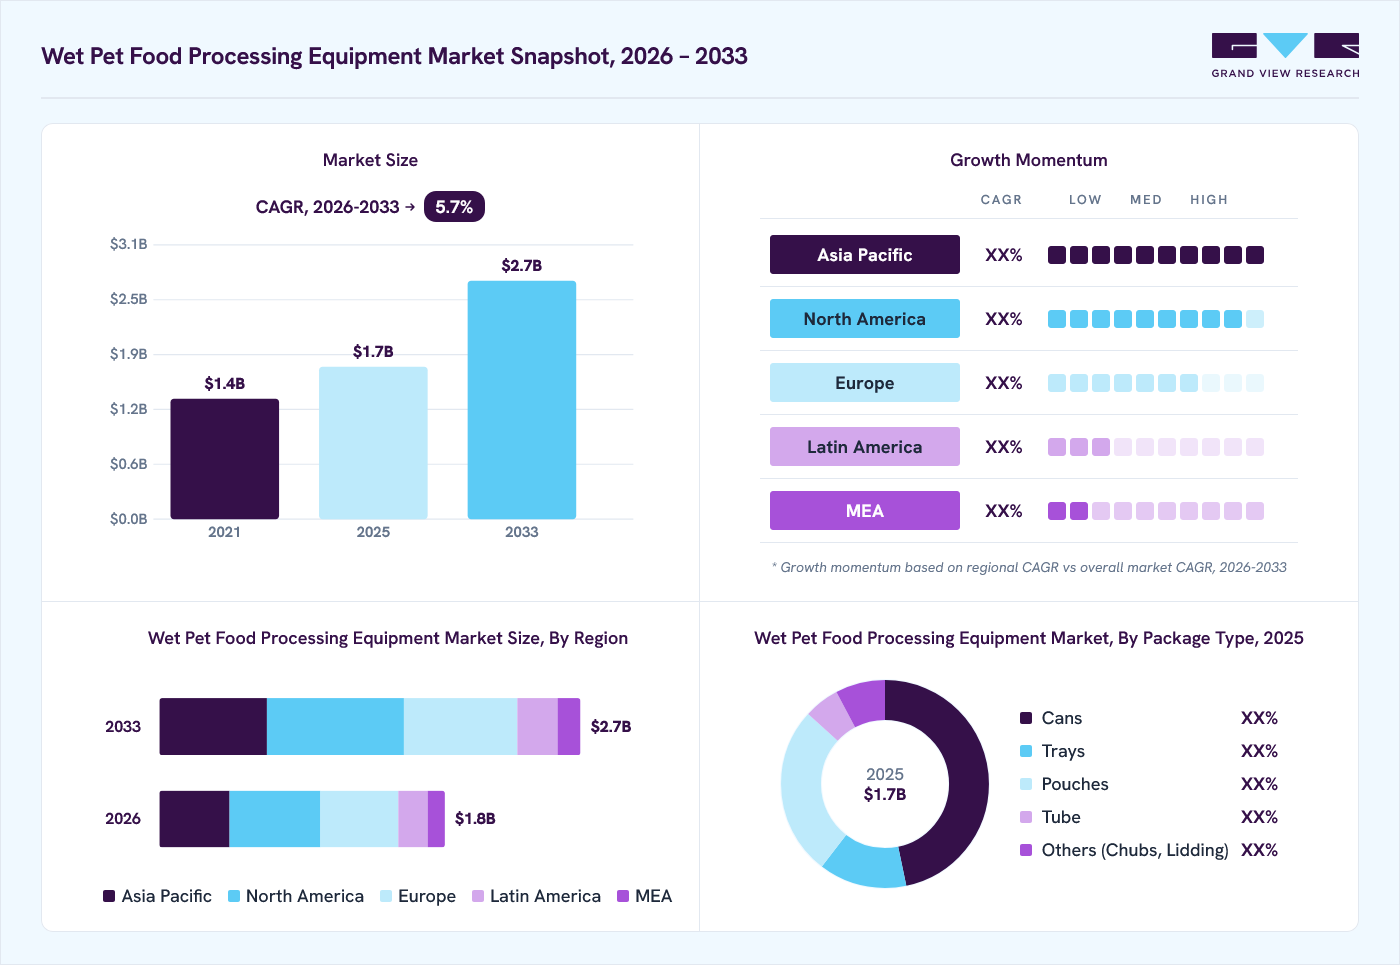
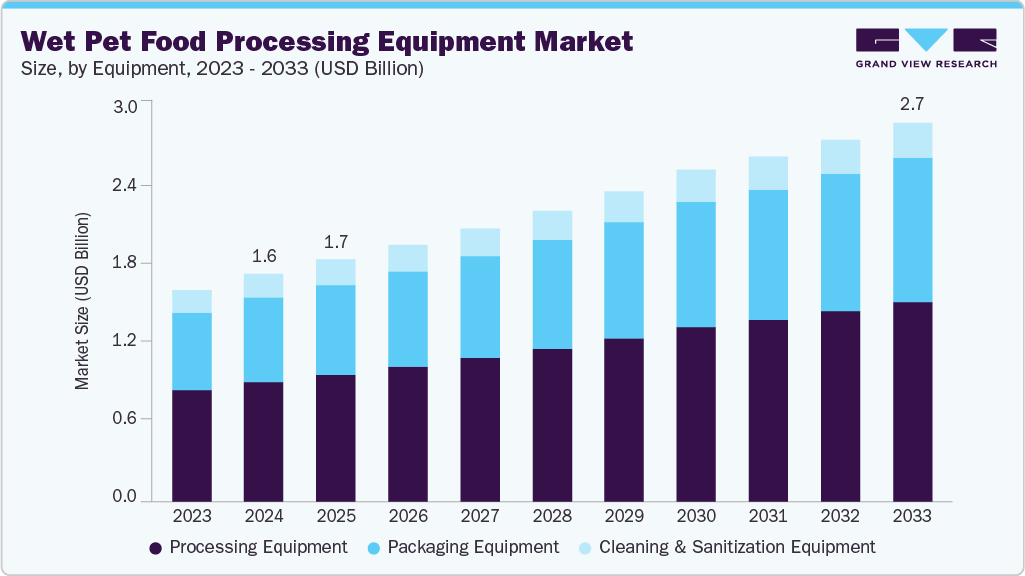
The global wet pet food processing equipment market size was valued at USD 1.7 billion in 2025 and is projected to grow from USD 1.8 billion in 2026 to USD 2.7 billion by 2033, at a CAGR of 5.7% from 2026 to 2033. North America market dominated, with a revenue share of 31.7% in 2025. The market’s expansion is primarily driven by rising pet ownership worldwide-especially across emerging regions such as Asia Pacific and Central & South America-combined with the growing trend of pet humanization.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By equipment: Processing equipment segment led the market with the largest revenue share of 52.5% in 2025.
- By food type: Cat food segment led the market with the largest revenue share of 62.5% in 2025.
- By form: Chunk in gravy segment led the market with the largest revenue share of 45.9% in 2025.
- By package type: Cans segment led the market with the largest revenue share of 46.7% in 2025.
Regional Highlights
- Largest regional market: North America (31.7% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 1.7 Billion
- Estimated market size in 2026: USD 1.8 Billion
- Projected market size by 2033: USD 2.7 Billion
- CAGR (2026-2033): 5.7%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
As pet owners increasingly seek high-quality, nutritious, and premium food options for their pets, manufacturers are investing in advanced processing technologies to meet evolving consumer preferences and regulatory standards. This shift is fueling demand for efficient, automated, and hygienic wet pet food processing equipment globally. Premiumization of pet food owing to the rising health-consciousness among the pet owners is expected to drive the market growth. Additionally, rising consumer preference for clean-label and organic pet food is pushing manufacturers to adopt advanced processing technologies, further fueling demand for specialized wet pet food processing equipment.
 To learn more about this report, Download Free Sample Report
Market Dynamics
The wet pet food processing equipment market is driven by the growing humanization of pets and increasing demand for premium, nutritious, and customized wet pet food products, encouraging manufacturers to invest in advanced processing technologies that ensure product quality, consistency, and food safety. Expanding production capacities and the need for higher operational efficiency are accelerating the adoption of automated, continuous processing systems integrated with sterilization, aseptic processing, and clean-in-place (CIP) technologies to comply with stringent food safety regulations. The market is also benefiting from the gradual integration of Industry 4.0 capabilities, including IoT-enabled monitoring and predictive maintenance, which improve production efficiency and minimize downtime.
The wet pet food processing equipment market is driven by the growing humanization of pets and increasing consumer preference for premium, high-protein, natural, and functional wet pet food products. Manufacturers are investing in advanced processing technologies, including high-shear mixers, cooking systems, emulsification equipment, and retort sterilization solutions, to preserve nutritional value, ensure product consistency, and meet stringent food safety standards.
Expanding pet food production capacities across emerging economies, coupled with modernization and automation initiatives in established markets, is further accelerating demand for energy-efficient, high-throughput processing equipment equipped with real-time monitoring, traceability, and process control capabilities.
The market faces challenges associated with the substantial capital investment required for advanced wet pet food processing lines, limiting adoption among small and medium-sized manufacturers. Processing highly viscous and particulate-rich formulations containing meat, vegetables, and grains also increases equipment wear, maintenance requirements, and operational complexity, necessitating frequent servicing and specialized engineering expertise.
In addition, fluctuations in the prices and availability of food-grade stainless steel, automation components, sensors, and electronic systems, along with extended procurement lead times, can increase equipment manufacturing costs and delay project execution.
The increasing adoption of smart manufacturing presents significant opportunities for equipment manufacturers to develop modular processing systems integrated with Industrial Internet of Things (IIoT), artificial intelligence, and predictive maintenance capabilities that improve production efficiency, minimize downtime, and optimize product quality. Growing demand for fresh, refrigerated, and minimally processed premium pet food is also creating opportunities for advanced technologies such as high-pressure processing (HPP) and flexible thermal processing solutions.
Furthermore, the expansion of regional pet food manufacturing facilities is encouraging demand for compact, scalable, and energy-efficient processing equipment that enables manufacturers to increase production capacity while maintaining high standards of food safety, operational efficiency, and product consistency.
Market Concentration & Characteristics
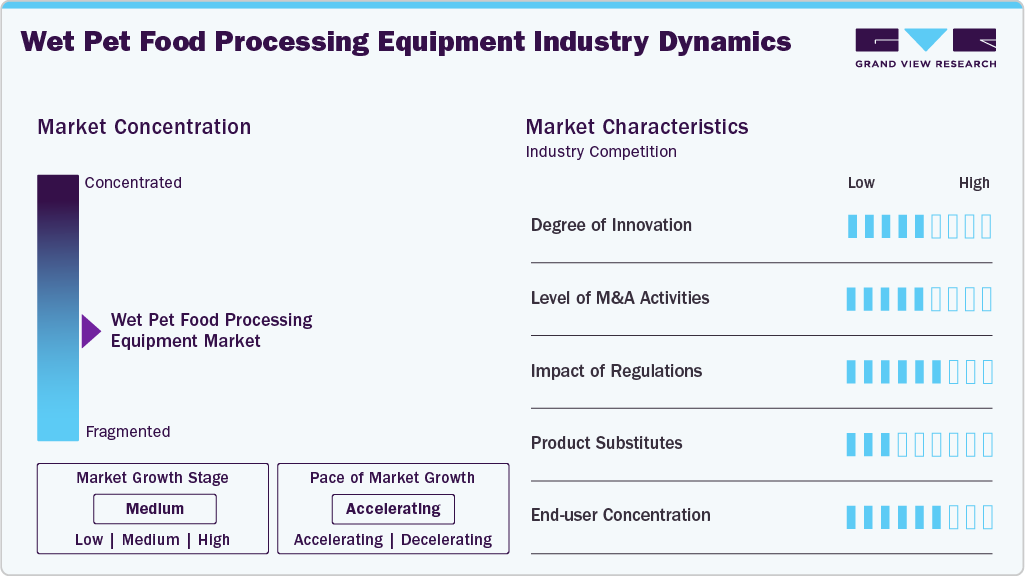
The global wet pet food processing equipment market is characterized by diverse players, including large multinational corporations and specialized regional manufacturers, all competing for market share. Key manufacturers focus on developing advanced processing equipment that ensures high-quality, nutritious, and safe pet food products. Innovation in this market is driven by the growing demand for high-quality pet food, stringent food safety regulations, and the need for efficient production processes. Manufacturers are investing in advanced technologies to improve the quality, consistency, and safety of wet pet food products.
Regulatory pressures from organizations such as the FDA and EFSA play a crucial role in shaping the market, with stringent standards focused on food safety, hygiene, and nutritional content. Compliance with these regulations is essential for manufacturers to remain competitive, as pet owners increasingly prioritize the health and well-being of their pets. As the demand for high-quality and nutritious pet food rises, the need for advanced processing equipment designed for efficiency and safety continues to grow.
 To learn more about this report, Download Free Sample Report
While opportunities are abundant, the wet pet food processing equipment market faces competition from alternative processing methods and technologies. To maintain market leadership, manufacturers must continue innovating, integrating smart technologies like IoT for real-time monitoring, and adapting to evolving regulatory landscapes. Emphasizing food safety, nutritional value, and efficient production processes is likely to lead to the expansion of wet pet food processing equipment market.
Analyst Perspective
The wet pet food processing equipment market is undergoing a transition toward advanced, automated, and integrated processing solutions as manufacturers prioritize operational efficiency, product consistency, and regulatory compliance. Demand for core equipment, including mixers, grinders, emulsifiers, cooking systems, filling equipment, retorts, and sterilization units, is increasing as producers expand capacity and modernize existing facilities. Equipment suppliers are differentiating through automation capabilities, digital process monitoring, energy-efficient designs, and flexible systems that support diverse wet pet food formulations. The market is gradually shifting from conventional processing machinery toward intelligent production platforms that enable improved throughput, reduced downtime, and enhanced quality control. Although high capital requirements, maintenance complexity, and customization needs present challenges, replacement cycles and capacity expansion among pet food manufacturers are creating sustainable growth opportunities.
Equipment Insights
Based on equipment, the processing equipment segment led the market with the largest revenue share of 52.5% in 2025. The adoption of advanced wet pet food processing equipment is rising as manufacturers respond to evolving consumer preferences for healthier, high-protein, and grain-free pet food products. Production facilities are investing in high-efficiency extruders, vacuum fillers, and aseptic packaging machines that allow for precise ingredient control and extended shelf life to meet these demands. For instance, companies such as Andritz and Clextral have developed sophisticated processing systems that offer high output while ensuring nutritional consistency.
Packaging equipment plays a critical role in the wet pet food processing equipment market, ensuring that the finished products are safely sealed, preserved, and ready for distribution. The packaging process for wet pet food is highly specialized due to the need to preserve the product’s moisture content and prevent contamination. The increasing demand for convenience and extended shelf life in the pet food industry is a significant driving factor of packaging equipment in the market.
Food Type Insights
Based on food type, the cat food segment led the market with the largest revenue share of 62.5% in 2025. In cat food production, wet pet food processing equipment is tailored to accommodate the specific needs of cats, particularly with regard to the texture, moisture content, and flavor profiles preferred by felines. The growing demand for premium and safe wet cat food has led to the adoption of more efficient and automated wet pet food processing systems that are capable of maintaining the delicate balance of quality and safety.
The growing demand for premium, nutritious, and safe dog food options is driving the adoption of advanced wet pet food processing equipment, ensuring high efficiency, product quality, and compliance with regulatory standards. In the production of dog food, wet pet food processing equipment is specifically designed to handle the unique requirements of meat-based, high-moisture products.
Form Insights
Based on form, the chunk in gravy segment led the market with the largest revenue share of 45.9% in 2025. Wet pet food processing technologies ensure a long shelf life while maintaining the sensory qualities that consumers associate with premium wet pet foods. The rising demand for human-grade aesthetics and variety in pet meals is driving manufacturers to invest in advanced equipment tailored specifically for chunk-in-gravy product lines.
In the wet pet food processing market, loaves are one of the popular formats for certain pet food products, particularly for dogs and cats that prefer a denser, meatier consistency. The demand for loaves in the wet pet food market has increased with the growing trend toward premium pet food offerings, where product texture and quality play a critical role in consumer choice.
Package Type Insights
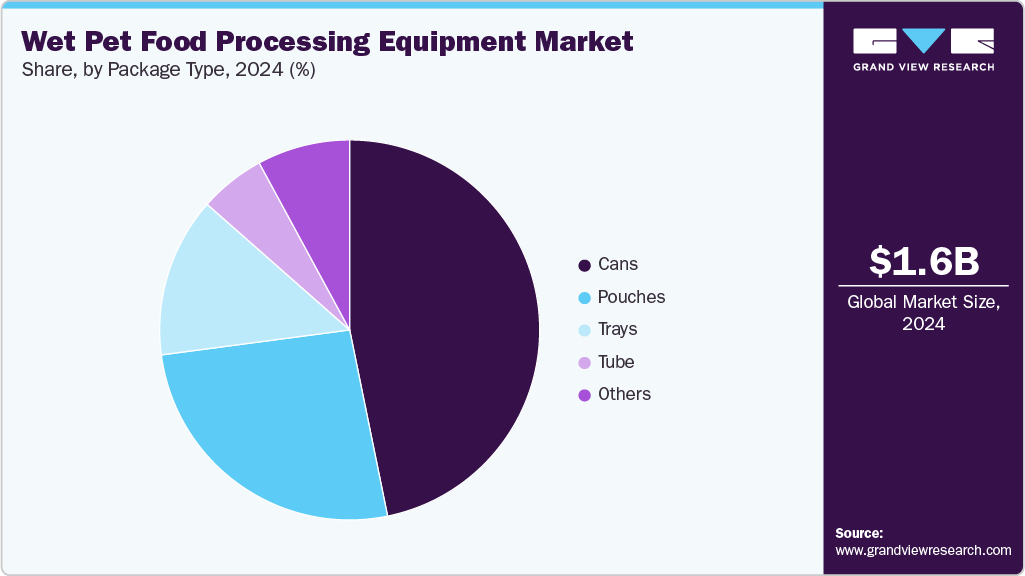
Based on package type, the cans segment led the market with the largest revenue share of 46.7% in 2025. Cans remain one of the most widely used packaging types in the wet pet food processing equipment market due to their durability, shelf stability, and compatibility with thermal sterilization processes. Their rigid structure allows them to withstand high-pressure retort sterilization, making them ideal for preserving the nutritional quality and flavor of dense, protein-rich wet pet foods such as loaves, pâtés, and chunks in gravy.
 To learn more about this report, Download Free Sample Report
Pouches have emerged as a highly versatile and efficient packaging type in the wet pet food processing equipment market, driven by their convenience, lightweight nature, and extended shelf stability. As brands increasingly focus on differentiated product lines such as single-serving gourmet meals or functional pet diets, the demand for equipment that can support high-volume, hygienic, and precise pouch packaging continues to grow, positioning pouches as a key driver in wet pet food production innovation.
Regional Insights
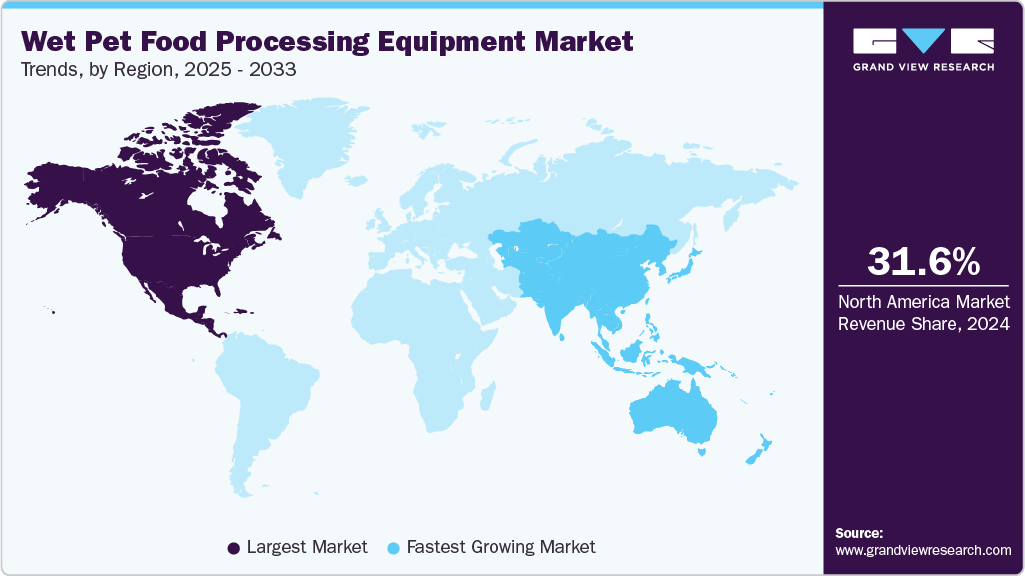
North America dominated the wet pet food processing equipment market with the largest revenue share of 31.7% in 2025 driven by a strong emphasis on pet health and nutrition. The trend of pet humanization is particularly pronounced, with pet owners increasingly seeking high-quality, protein-rich, and minimally processed pet food products. This has led to a surge in demand for advanced processing equipment that maintains ingredient integrity and ensure food safety. The region's well-established industrial base and advanced technological infrastructure support the integration of sophisticated processing technologies, driving innovation and market growth.
 To learn more about this report, Download Free Sample Report
U.S. Wet Pet Food Processing Equipment Market Trends
The wet pet food processing equipment market in U.S. held the largest share in the North America region in 2025 over the forecast perioddriven by a surge in pet ownership and evolving consumer preferences. 66% of households in the U.S. own a pet, marking a substantial increase from 56% in 1988 to 2025. This uptick in pet ownership has led to a heightened demand for pet food, particularly wet varieties, which are perceived as more palatable and nutritious.
Europe Wet Pet Food Processing Equipment Market Trends
The market in Europe is supported by a substantial and diverse pet population. This broad pet base supports a sophisticated market where consumer demand is shifting noticeably towards wet pet food products, valued for their higher moisture content and perceived health benefits. Countries such as Germany, France, and the UK lead in wet pet food consumption, driving the need for modernized processing equipment that can handle increasing volumes and diverse product formats.
The wet pet food processing equipment market in Germany is expected to grow at a CAGR of 7.6% over the forecast period due to the nation’s high pet density which creates a strong domestic demand for pet food, especially wet varieties favored for their palatability and nutritional benefits.
France wet pet food processing equipment market is expected to grow at a CAGR of 7.2% over the forecast period. The robust pet food production and export activity in France is a strong driver for the wet pet food processing equipment market, especially for dogs and cats.
Asia Pacific Wet Pet Food Processing Equipment Market Trends
The market in Asia Pacific is projected to be the fastest growing region with a CAGR of 6.3% over the forecast period. The Asia Pacific region is witnessing robust market growth across various sectors, driven by rapid urbanization, industrialization, and increasing consumer demand. The region's expanding middle class and rising disposable incomes are fueling the adoption of advanced technologies and premium products. In the wet pet food processing equipment market, the growing trend of pet humanization and increasing pet ownership are driving demand for high-quality pet food products.
The wet pet food processing equipment market in China is projected to expand at a CAGR of 7.9% over the forecast period. China's accelerating pet care industry is driving strong growth in the market, as consumer preferences shift toward higher-quality, ready-to-serve products-especially for cats.
India wet pet food processing equipment market is projected to expand at a CAGR of 8.4 % over the forecast period. India's pet food market is experiencing significant expansion, with retail sales projected to reach USD 1.3 billion by 2028, driven by a growing pet population and increasing consumer demand for high-quality pet food products.
Central & South America Wet Pet Food Processing Equipment Market Trends
The Central and South America region is seeing notable growth in the wet pet food processing equipment market, driven by increasing pet ownership and a growing middle class. The trend of pet humanization is gaining traction, with consumers demanding higher quality and more nutritious pet food products. The region's expanding pet food industry is investing in advanced processing, packaging, and sanitization technologies to meet these demands and comply with food safety standards.
The wet pet food processing equipment market in Argentina is projected to grow at a CAGR of 6.4% over the forecast period. The country has seen a marked rise in pet humanization, especially in urban centers like Buenos Aires and Córdoba, where consumers increasingly treat pets as family members. This trend has led to a notable shift toward premium wet pet food products, which in turn is driving demand for specialized processing equipment.
Middle East & Africa Wet Pet Food Processing Equipment Market Trends
The Middle East and Africa region is experiencing growth in the wet pet food processing equipment market, driven by rising pet ownership and changing consumer attitudes towards pet care. The trend of pet humanization is influencing consumer preferences, with pet owners increasingly seeking premium and nutritionally balanced pet food products. The region's growing pet food industry is investing in advanced processing technologies to meet these demands and comply with food safety standards. The presence of emerging markets and the increasing focus on export opportunities are further driving the adoption of sophisticated processing equipment.
The wet pet food processing equipment market in Saudi Arabia is projected to expand at a CAGR of 5.2% over the forecast period, largely driven by factors such as increasing disposable incomes, a growing expatriate population, western educational influences, and the widespread impact of social media. This shift in societal attitudes has led to the normalization of pets in both private and public spaces, with the popularity of pet-friendly venues such as cat and dog cafés and the proliferation of veterinary clinics and pet shops reflecting a more developed approach to pet care. As pet ownership becomes mainstream and responsible ownership practices take root, there is growing consumer demand for premium, health-focused pet food, particularly wet pet food, which is perceived as more nutritious and palatable.
Key Wet Pet Food Processing Equipment Company Insights
Some of the key players operating in the market include JBT Marel and DC Norris among others.
-
JBT Marel, also known as John Bean Technologies Corporation, is a global technology solutions provider primarily serving the food and beverage industry. The company was established as an independent publicly traded company in 2008 following FMC Technologies' divestiture of its non-energy businesses.
-
DC Norris designs, manufactures, installs, and services industrial and commercial food processing systems that cater to a broad range of food types, including ready meals, soups, sauces, beverages, pet food, and more. Their equipment portfolio includes advanced cooking kettles, cooling systems, sous vide technology, can opening and crushing machines, and vessels for safe food transfer and storage.
Key Wet Pet Food Processing Equipment Companies:
The following key companies have been profiled for this study on the wet pet food processing pquipment market.
-
JBT Marel
-
DC Norris
-
Kronitek – Food Processing Machines
-
Cabinplant A/S
-
Barry-Wehmiller Companies
-
Scansteel foodtech A/S.
-
Mepaco
-
ANDRITZ
-
The Middleby Corporation
-
GEA Group Aktiengesellschaft
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (e.g., JBT Marel, GEA Group Aktiengesellschaft, Provisur Technologies, Inc., Cabinplant A/S, scansteel foodtech A/S, Metalquimia S.A.U.)
- Focus on delivering integrated wet pet food processing solutions encompassing grinding, mixing, emulsification, cooking, filling, and thermal sterilization systems.
- Invest in automation, digital process control, and energy-efficient technologies to improve production efficiency and ensure compliance with global food safety standards.
- Strengthen market presence through continuous product innovation, strategic partnerships, global service networks, and long-term aftermarket support.
- Comprehensive product portfolios capable of supporting complete wet pet food production lines.
- Strong global presence, extensive installed equipment base, and established relationships with multinational pet food manufacturers.
- Advanced engineering capabilities, robust R&D investments, and extensive technical service and maintenance networks.
- Premium pricing and high capital investment requirements may limit adoption among small and medium-sized manufacturers.
- Longer delivery and implementation timelines for highly customized production lines.
- Complex equipment integration often requires specialized technical expertise for installation, operation, and maintenance.
Emerging & Regional Players (e.g., Tri-Mer Corporation, Bionomic Industries, regional players)
- Concentrate on specialized processing equipment and customized solutions for cooking, mixing, grinding, emulsification, and thermal processing applications.
- Compete through flexible equipment configurations, shorter project lead times, and responsive customer support tailored to regional market requirements.
- Expand market presence by strengthening distributor networks and targeting small and medium-sized pet food manufacturers with cost-effective processing solutions.
- Limited global footprint and brand recognition compared with established multinational competitors.
- Narrower product portfolios with fewer fully integrated processing line offerings.
- Smaller aftermarket service networks and comparatively lower investment in advanced automation, digital technologies, and international expansion.
Recent Developments
-
In January 2025 JBT finalized its voluntary takeover of Marel hf., merging the two companies to form JBT Marel Corporation. Shares of the new combined entity started trading under “JBT MarelM” on both the Nasdaq Iceland and the New York Stock Exchange as of January 3, 2025. The merger is designed to create a stronger, more diversified company in food processing solutions by combining the expertise, technologies, and market reach of both JBT Marel and Marel.
-
In May 2025, DC Norris acquired AE Mixers, strengthening its capabilities in industrial food processing equipment pertaining to pet food, food & beverage, and confectionery industries. This acquisition complements their existing portfolio and supports growth by enhancing their mixing technology offerings.
Wet Pet Food Processing Equipment Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 1.7 billion
Estimated market size in 2026
USD 1.8 billion
Projected market size by 2033
USD 2.7 billion
Growth rate
CAGR of 5.7% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Equipment, food type, form, package type, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Russia; China; India; Japan; Thailand; Malaysia; Indonesia; South Korea; Australia; Brazil; Argentina; South Africa; Saudi Arabia; UAE
Key companies profiled
JBT Marel, GEA Group Aktiengesellschaft, DC Norris & Company Ltd., Cabinplant A/S, scansteel foodtech A/S, Mepaco, Kronitek - Food Processing Machines, Provisur Technologies, Inc., Metalquimia S.A.U., FPEC Corporation.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Wet Pet Food Processing Equipment Market Report Segmentation
This report forecasts revenue growth at global, regional & country levels and provides an analysis on the industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research, Inc has segmented the global wet pet food processing equipment market based on product, food type, form, package type, and region:
-
Equipment Outlook (Revenue, USD Million, 2021 - 2033)
-
Processing Equipment
-
Mixing & Blending Equipment
-
Grinding Equipment
-
Pre-breakers
-
Pallet Inverters
-
Holding Bins
-
Others
-
-
Pre-Cooking Equipment
-
Cooling & Chilling Equipment
-
Others
-
-
Packaging Equipment
-
Cans
-
Filling Machines
-
Can Seaming Machines
-
Retort Systems
-
Saturated Steam
-
Water Spray
-
Water Immersion
-
Steam-air
-
Hydrostatic Retorts
-
-
Labeling Machines
-
Cartoning and Case Packing Machines
-
-
-
Trays
-
Filling Machines
-
Sealing Machines
-
Lidding Film Handling Systems
-
Retort Systems
-
Saturated Steam
-
Water Spray
-
Water Immersion
-
Steam-air4
-
Hydrostatic Retorts
-
-
Labeling Machines
-
Cartoning and Case Packing Machines
-
-
Pouches
-
Pouch Feeding/Loading Machines
-
Filling Machines
-
Sealing Machines
-
Retort Systems
-
Saturated Steam
-
Water Spray
-
Water Immersion
-
Steam-air4
-
Hydrostatic Retorts
-
-
Labeling Machines
-
Cartoning and Case Packing Machines
-
-
Tubes
-
Tube Feeding Machines
-
Filling Machines
-
Sealing Machines
-
Trimming Machines
-
Retort Systems
-
Saturated Steam
-
Water Spray
-
Water Immersion
-
Steam-air4
-
Hydrostatic Retorts
-
-
Labeling Machines
-
Cartoning and Case Packing Machines
-
-
Others
-
Filling Machines
-
Sealing Machines
-
Retort Systems
-
Saturated Steam
-
Water Spray
-
Water Immersion
-
Steam-air4
-
Hydrostatic Retorts
-
-
Labeling Machines
-
Cartoning and Case Packing Machines
-
-
Cleaning & Sanitization Equipment
-
-
Food Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Dog Food
-
Cat Food
-
- Form Outlook (Revenue, USD Million, 2021 - 2033)
-
Loaves
-
Stew
-
Chunk in Gravy
-
Others
-
-
Package Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Cans
-
Trays
-
Pouches
-
Tubes
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
France
-
Germany
-
Italy
-
Spain
-
Russia
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Thailand
-
Malaysia
-
Indonesia
-
South Korea
-
Australia
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
-
Research Methodology
The wet pet food processing equipment market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each wet pet food processing equipment segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Equipment
Revenue Capture Definition
Processing Equipment
Revenue generated from the sale of wet pet food processing equipment used for ingredient preparation, formulation, thermal processing, cooling, and handling operations before packaging. This segment includes mixing & blending equipment, grinding equipment, pre-cooking equipment, cooling & chilling equipment, and other supporting processing systems.
Packaging Equipment
Revenue generated from the sale of packaging equipment used in wet pet food manufacturing, including filling machines, can seaming machines, retort systems, labeling machines, and cartoning & case packing machines. The segment covers equipment supplied for packaging wet pet food in cans, trays, pouches, tubes, and other packaging formats.
Cleaning & Sanitization Equipment
Revenue generated from the sale of cleaning and sanitization equipment used in wet pet food manufacturing facilities to maintain hygiene, ensure regulatory compliance, and support efficient cleaning of processing and packaging systems. Revenue includes equipment supplied for new installations, facility expansions, and replacement or modernization projects.
Segment - Food Type
Revenue Capture Definition
Dog Food
Revenue generated from the sale of wet pet food processing equipment purchased by manufacturers producing wet dog food products, including processing lines and machinery supplied for dog food production facilities.
Cat Food
Revenue generated from the sale of wet pet food processing equipment purchased by manufacturers producing wet cat food products, including dedicated and integrated processing systems for cat food production.
Segment - Form
Revenue Capture Definition
Loaves
Revenue generated from the sale of wet pet food processing equipment to manufacturers producing loaf-form wet pet food products, including equipment systems designed for this product format.
Stew
Revenue generated from the sale of wet pet food processing equipment to manufacturers producing stew-form wet pet food products, including systems supporting liquid-rich product manufacturing.
Chunk in Gravy
Revenue generated from the sale of wet pet food processing equipment to manufacturers producing chunk-in-gravy products, including processing systems designed for mixed solid and liquid formulations.
Others
Revenue generated from the sale of wet pet food processing equipment for other wet food formats, including specialty product categories with customized processing requirements.
Segment - Package Type
Revenue Capture Definition
Cans
Revenue generated from the sale of wet pet food processing equipment used by manufacturers producing canned wet pet food products, including equipment lines configured for can-based production.
Trays
Revenue generated from the sale of wet pet food processing equipment purchased by manufacturers producing tray-packaged wet pet food products.
Pouches
Revenue generated from the sale of wet pet food processing equipment supplied to manufacturers producing pouch-based wet pet food products.
Tubes
Revenue generated from the sale of wet pet food processing equipment purchased for tube-format wet pet food production.
Others
Revenue generated from the sale of wet pet food processing equipment for alternative packaging formats, including specialty containers and customized product formats.
Estimation Model
Layer Name
Key Question
Description
Wet Pet Food Production Base Layer
Which manufacturing facilities represent the addressable market?
Quantify wet pet food manufacturing facilities across commercial pet food manufacturers, contract manufacturers, and private-label producers. Model production capacities, processing line installations, and manufacturing volumes for canned, pouch, tray, and fresh wet pet food products.
Processing Equipment Adoption Layer
Which facilities require wet pet food processing equipment?
Assess the adoption of core processing equipment, including grinders, mixers, emulsifiers, cookers, vacuum processing systems, filling equipment, retorts, sterilization systems, and integrated processing lines based on production capacity, product portfolio, and automation level.
Technology Penetration Layer
What share of facilities utilize advanced wet pet food processing technologies?
Estimate equipment penetration by processing technology, automation level, equipment type, production capacity, and region. Account for equipment modernization, replacement demand, smart manufacturing adoption, and Industry 4.0 integration across pet food manufacturing facilities.
Revenue Generation Layer
How much market revenue is generated?
Estimate annual shipments of wet pet food processing equipment by equipment type, process stage, application, and region. Quantify revenues generated exclusively from the sale of new wet pet food processing equipment supplied to pet food manufacturers, OEMs, and food processing companies.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Competitive Benchmarking
Benchmarked key wet pet food processing equipment manufacturers based on equipment portfolio, processing capabilities, automation integration, application coverage, geographic presence, and strategic positioning, while distinguishing established and emerging market participants.
Provided a clear view of the competitive landscape, enabling evaluation of supplier capabilities, technology differentiation, and market positioning.
Regional Segmentation
Analyzed the wet pet food processing equipment market across North America, Europe, Asia Pacific, Latin America, and Middle East & Africa by evaluating pet food production capacity, equipment adoption, manufacturing expansion, and facility modernization trends.
Delivered insights into regional demand patterns, growth opportunities, and market attractiveness to support expansion strategies and investment decisions.
Opportunity Assessment
Identified growth opportunities related to automation adoption, replacement of aging processing systems, demand for modular and energy-efficient equipment, and integration of smart monitoring technologies in wet pet food manufacturing facilities.
Enabled stakeholders to identify high-potential opportunities, prioritize technology investments, and align strategies with evolving market requirements.
Frequently Asked Questions About This Report
The global wet pet food processing equipment market size was valued at USD 1.7 billion in 2025 and is estimated at USD 1.8 billion in 2026.
The global wet pet food processing equipment marketexpected to grow at a CAGR of of 5.7% from 2026 to 2033 to reach USD 2.7 billion by 2033.
The cans segment led the market with the largest revenue share of 46.7% in 2025.
The chunk in gravy segment accounted for the largest revenue share of 45.9% in 2025.
Key factors include increasing pet ownership, rising demand for premium and wet pet food products, growing pet humanization trends, expanding investments in automated pet food manufacturing facilities, and increasing emphasis on food safety and production efficiency.
North America market dominated, with a revenue share of 31.7% in 2025.
Processing equipment segment led the market with the largest revenue share of 52.5% in 2025.
Cat food segment led the market with the largest revenue share of 62.5% in 2025.
Key players include GEA Group AG, Bühler AG, JBT Marel Corporation, Clextral SAS, FENCO Food Machinery S.r.l., The Middleby Corporation, Provisur Technologies, Inc., Krones AG, Selo B.V., and Della Toffola S.p.A.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


