
- Home
- »
- Next Generation Technologies
- »
-
Workforce Management Market Size & Share Report, 2033GVR Report cover

Workforce Management Market (2026 - 2033)
Size, Share & Trends Analysis Report By Deployment (On-premise, Cloud), By Company Size (Large Enterprises, SMEs), By Solution, By Application, By Region
Market Size, 2025
$20.6BMarket Estimate, 2026
$27.5BMarket Forecast, 2033
$205.5BCAGR, 2026–2033
33.3%Workforce Management Market Summary
The global workforce management market size was valued at USD 20.6 billion in 2025 and is projected to grow from USD 27.5 billion in 2026 to USD 205.5 billion in 2033, at a CAGR of 33.3% from 2026 to 2033. The European market dominated with a revenue share of approximately 33.5% in 2025. Factors such as workforce optimization, increasing cloud deployment, and the need to comply with regulatory requirements are driving the market growth.
Key Market Trends & Insights
- By solution: The time & attendance management segment held the largest market share of around 35.5% in 2025.
- By deployment: The on-premise held the largest market share of around 50.5% in 2025.
- By company size: The large enterprises segment held the largest market share of over 64.0% in 2025.
- By application: The BFSI segment held the largest market share of over 22.0% in 2025.
Regional Highlights
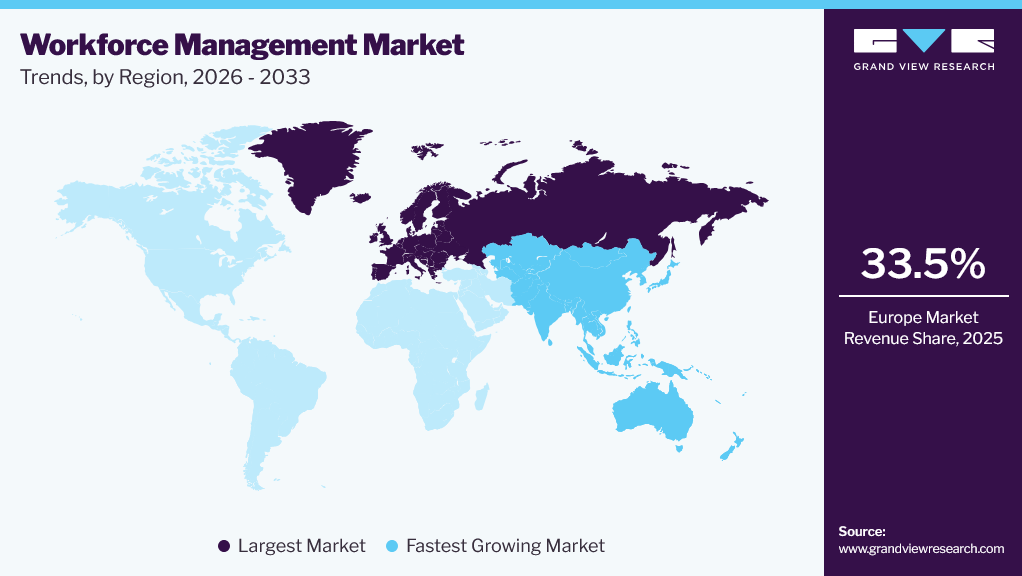
- Largest regional market: Europe (33.5% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 20.6 Billion
- Estimated market size in 2026: USD 27.5 Billion
- Projected market size by 2033: USD 205.5 Billion
- CAGR (2026-2033): 33.3%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The market is witnessing growing adoption of AI-enabled workforce management platforms as organizations increasingly focus on improving labor productivity, workforce planning, and operational efficiency. Modern workforce management solutions integrate scheduling, attendance, labor forecasting, and analytics capabilities within a unified platform, enabling businesses to make more informed workforce decisions.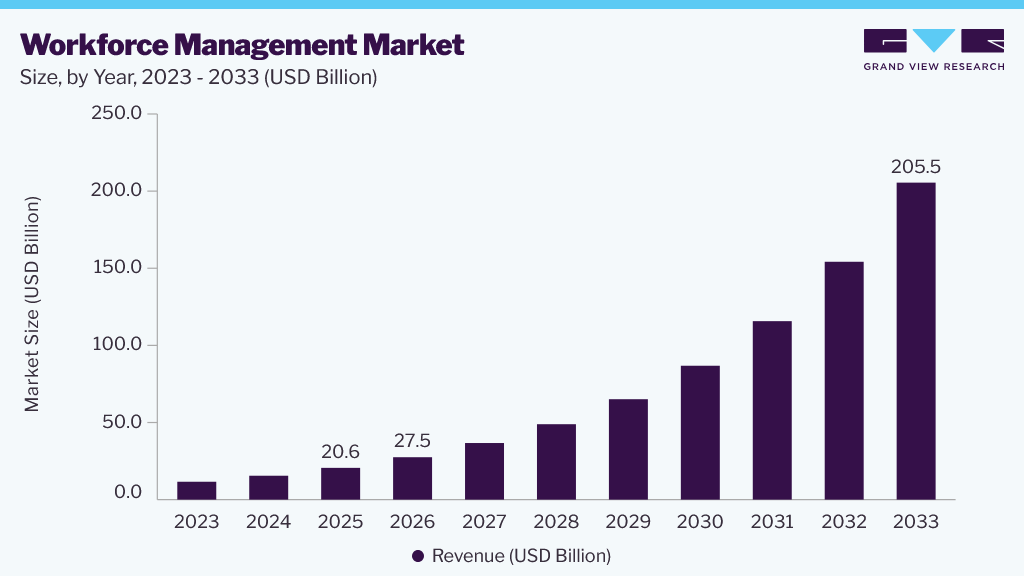 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
The rising need for centralized workforce visibility and data-driven resource allocation is further supporting adoption across industries. For instance, in November 2025, UKG launched the Workforce Intelligence Hub, an AI-powered solution designed to consolidate workforce-related information from multiple business functions. The platform provides organizations with advanced analytics and workforce insights to support staffing strategies, labor optimization, and operational decision-making across complex work environments.
Analyst Perspective
The market is evolving beyond traditional scheduling and time-tracking functions toward intelligence-driven workforce optimization. As labor costs rise and workforce models become increasingly complex, organizations are prioritizing platforms that combine workforce analytics, automation, and AI-enabled decision support within a unified environment. The competitive advantage is shifting from simple workforce administration to predictive workforce planning, productivity optimization, and real-time labor visibility. Vendors that successfully integrate operational, employee, and business performance data into a single platform will be better positioned to address workforce challenges and capture long-term demand across large enterprise and distributed workforce environments.
Solution Insights
The time & attendance management segment held the largest market share, at around 35.5%, in 2025, driven by its widespread adoption across industries with large and distributed workforces. Organizations increasingly rely on these solutions to automate attendance tracking, manage employee schedules, monitor labor costs, and maintain compliance with labor regulations. The growing need for real-time workforce visibility and accurate payroll processing continues to support adoption across manufacturing, healthcare, retail, logistics, and hospitality sectors. As businesses focus on improving operational efficiency and workforce productivity, demand for integrated time and attendance solutions remains strong.
The embedded analytics segment is expected to grow at the fastest CAGR during the forecast period, driven by increasing demand for real-time workforce insights and data-driven decision-making. Organizations are increasingly integrating analytics capabilities into workforce management platforms to improve labor forecasting, workforce planning, productivity measurement, and operational efficiency. The growing adoption of cloud-based workforce management systems is further accelerating demand for embedded analytics solutions. For instance, in May 2025, Deputy launched Deputy Analytics+, a business intelligence platform featuring advanced reporting capabilities and interactive dashboards that help organizations analyze workforce performance and operational trends. Such innovations are strengthening the role of analytics within workforce management ecosystems.
Deployment Insights
The on-premises segment accounted for around 50.5% of the market. The segment is anticipated to dominate in developing countries, where technology is adopted more slowly. As many labor management solution users are laggards in technological adoption, the cloud deployment segment is expected to grow in the latter part of the forecast period.
The cloud segment is expected to grow at the fastest CAGR during the forecast period. Cloud is the preferred deployment option for workforce solutions in the industry primarily because it offers flexibility, cost savings, and operational ease. Moreover, marketing efforts by leading solution vendors have been instrumental in establishing the cloud as a feasible and streamlined deployment option amongst industries with a traditional outlook.
Company Size Insights
The large enterprises segment held the largest market share of over 64.0% in 2025. Large organizations often operate across multiple locations, manage diverse workforce categories, and handle complex scheduling requirements, creating a strong need for scalable workforce management solutions. These organizations increasingly utilize workforce management platforms to automate scheduling, improve labor allocation, support compliance management, and enhance operational efficiency. The growing focus on workforce optimization and employee productivity continues to support adoption among large enterprises.
The small and medium enterprises segment is expected to grow at the fastest CAGR during the forecast period, driven by the growing digitalization of workforce operations among smaller businesses. SMEs are increasingly adopting workforce management platforms to improve employee coordination, automate routine administrative activities, and gain greater visibility into workforce performance. The availability of flexible cloud-based deployment models and subscription pricing structures has accelerated adoption by reducing barriers to technology investment. In addition, increasing emphasis on workforce transparency, documentation accuracy, and regulatory adherence is encouraging organizations to implement structured workforce management processes.
Application Insights
The BFSI segment held the largest market share of over 22.0% in 2025. Financial institutions increasingly rely on workforce management solutions to optimize employee scheduling, improve workforce productivity, manage labor costs, and maintain regulatory compliance. The expansion of branch networks, customer service operations, and digital banking support teams has increased the need for effective workforce planning and resource allocation. Organizations across the BFSI sector are also leveraging workforce analytics to improve staffing decisions and enhance employee performance management.
The healthcare channel segment is expected to grow at the fastest CAGR during the forecast period. Rising pressure to manage staffing shortages, optimize workforce utilization, and improve patient care delivery is increasing the adoption of workforce management solutions across healthcare organizations. Healthcare providers are increasingly implementing workforce scheduling, attendance management, and labor analytics tools to support operational efficiency and workforce planning. In addition, the growing adoption of cloud-based platforms, mobile workforce applications, and AI-enabled analytics is enhancing workforce visibility and supporting data-driven staffing decisions across healthcare facilities.
Regional Insights
Europe dominated the global workforce management market, accounting for the largest revenue share of approximately 33.5% in 2025. The region's growth is supported by stringent labor regulations, increasing workforce digitization, and growing emphasis on employee scheduling, attendance tracking, and compliance management. Organizations across Europe are increasingly adopting workforce management solutions to ensure adherence to regulations governing working hours, leave entitlements, and employee welfare. European labor laws require employers to comply with statutory provisions related to paid leave, parental leave, maternity leave, and working-time regulations. As a result, workforce management platforms are increasingly being used to automate compliance processes, maintain workforce records, and improve labor administration across organizations.
 To learn more about this report, Download Free Sample Report
Asia Pacific Workforce Management Market Trends
The workforce management market in the Asia Pacific is expected to grow at the fastest CAGR during the forecast period. Driven by increasing digital transformation initiatives, growing adoption of cloud-based business applications, and rising investments in workplace automation across emerging economies. Organizations across the region are increasingly implementing workforce management solutions to improve workforce visibility, optimize labor utilization, and enhance operational efficiency. The expansion of service industries, the growing mobile workforce, and the increasing focus on employee productivity are further supporting market growth. In addition, the rising adoption of artificial intelligence, analytics, and automation technologies is encouraging organizations to modernize workforce planning and labor management processes.
Key Workforce Management Company Insights
Vendors are increasingly enhancing their platforms with artificial intelligence, advanced reporting capabilities, and integrations with broader human capital management ecosystems. Companies are focusing on transforming workforce management from a traditional administrative function into a strategic decision-support tool that improves workforce productivity, labor optimization, and operational efficiency. Product innovation, acquisitions, strategic partnerships, and geographic expansion remain key approaches adopted by market participants to strengthen their competitive position.
Key Workforce Management Companies
The following key companies have been profiled for this study on the workforce management market:
-
UKG Inc.
-
SAP SE
-
Oracle Corporation
-
WorkForce Software, LLC
-
NICE Ltd.
-
ActiveOps PLC
-
Infor Inc.
-
Dayforce, Inc. (formerly Ceridian)
-
Blue Yonder Group, Inc.
-
Zebra Technologies Corporation
-
Replicon
-
SISQUAL Workforce Management, Lda.
-
ADP, Inc.
Recent Developments
-
In November 2025, ADP launched ADP WorkForce Suite across ADP Workforce Now, ADP Lyric HCM, and ADP Global Payroll. The platform brings together workforce management functions, including time and attendance tracking, employee scheduling, absence management, and workforce analytics, enabling organizations to manage workforce operations through a single global system.
-
In September 2025, RingCentral acquired CommunityWFM, an AI-driven workforce management platform. CommunityWFM offers capabilities such as workforce scheduling, performance monitoring, and compliance management. The acquisition strengthens RingCentral’s workforce engagement portfolio by expanding its workforce optimization and operational management capabilities.
Workforce Management Market Report Scope
Report Attribute
Details
Market size in 2025
USD 20.6 billion
Estimated market size in 2026
USD 27.5 billion
Projected market size by 2033
USD 205.5 billion
Growth rate
CAGR of 33.3% from 2026 to 2033
Actual data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Solution, deployment, company size, application, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; UK; Germany; France; China; India; Japan; South Korea; Australia; Brazil; Mexico; UAE; Saudi Arabia; South Africa
Key companies profiled
UKG Inc.; SAP SE; Oracle Corporation; WorkForce Software, LLC; NICE Ltd.; ActiveOps PLC; Infor Inc.; Dayforce, Inc. (formerly Ceridian); Blue Yonder Group, Inc.; Zebra Technologies Corporation
Replicon; SISQUAL Workforce Management, Lda.; ADP, Inc.
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Workforce Management Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global workforce management market report based on solution, application, deployment, company size, and region:
- Solution Outlook (Revenue, USD Billion, 2021 - 2033)
- Workforce Scheduling
- Time & Attendance Management
- Embedded Analytics
- Absence Management
- Others
- Application Outlook (Revenue, USD Billion, 2021 - 2033)
- Academia
- Automotive & Manufacturing
- BFSI
- Government
- Healthcare
- Retail
- Others
- Deployment Outlook (Revenue, USD Billion, 2021 - 2033)
- Cloud
- On-premise
- Company Size Outlook (Revenue, USD Billion, 2021 - 2033)
- Large Enterprises
- Small and Medium Enterprises (SMEs)
- Regional Outlook (Revenue, USD Billion, 2021 - 2033)
- North America
- U.S.
- Canada
- Europe
- UK
- Germany
- France
- Asia Pacific
- China
- Japan
- India
- Australia
- South Korea
- Latin America
- Brazil
- Mexico
- Middle East and Africa
- United Arab Emirates (UAE)
- Saudi Arabia
- South Africa
- North America
Frequently Asked Questions About This Report
The global workforce management market size was valued at USD 20.6 billion in 2025 and is estimated at USD 27.5 billion for 2026.
The global workforce management market is expected to grow at a CAGR of 33.3% from 2026 to 2033, reaching USD 205.5 billion.
Europe dominated with an approximately 33.5% revenue share in 2025.
Key players in the market include UKG Inc., SAP SE, Oracle Corporation, WorkForce Software, LLC, NICE Ltd., ActiveOps PLC, Infor Inc., Dayforce, Inc. (formerly Ceridian), Blue Yonder Group, Inc., Zebra Technologies Corporation, Replicon, SISQUAL Workforce Management, Lda, ADP, Inc, and others.
Which by solution segment accounted for the largest share of the global workforce management market?The time & attendance management segment workforce management segment accounted for the largest revenue share of around 35.5% in 2025.
About the Author(s)
Next Generation Technologies Research Team
Technology · Next Generation TechnologiesThis report was authored by the next generation technologies research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the next generation technologies segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


