
- Home
- »
- Medical Devices
- »
-
Wound Biologics Market Size, Share & Trends Report, 2033GVR Report cover

Wound Biologics Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Biological Skin Substitutes, Topical Agents, Collagen Dressing), By Application (Chronic Wounds, Acute Wounds), By End-use (Hospitals, Clinics), By Region, And Segment Forecasts
Market Size, 2025
$2.6BMarket Estimate, 2026
$2.8BMarket Forecast, 2033
$4.8BCAGR, 2026–2033
8.1%Wound Biologics Market Summary
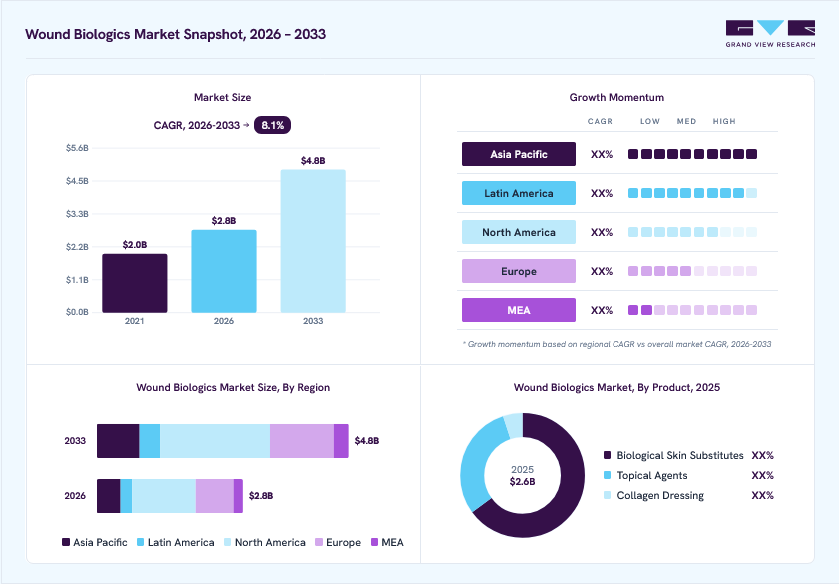
The global wound biologics market size was valued at USD 2.6 billion in 2025 and is projected to grow from USD 2.8 billion in 2026 to USD 4.8 billion in 2033, at a CAGR of 8.1% from 2026 to 2033. North America dominated the market, accounting for the largest revenue share of 43.5% in 2025. The wound biologics industry’s growth is primarily driven by the rising prevalence of chronic wounds, including diabetic foot ulcers, venous leg ulcers, and pressure ulcers, coupled with the growing global burden of diabetes and an aging population.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Biological skin substitutes held the largest revenue share of 64.9% in 2025.
- By application: Chronic wounds held the largest revenue share of 59.8% in 2025.
- By end-use: Hospitals held the largest revenue share of 45.4% in 2025.
Regional Highlights
- Largest regional market: North America (43.5% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 2.6 Billion
- Estimated market size in 2026:
- Projected market size by 2033: USD 4.8 Billion
- CAGR (2026-2033): 8.1%
Prism AI by Grand View Research Free to tryAsk a question about the wound biologics market✓Every figure cited from GVR research Prefer the report? Download free sample →
Increasing demand for advanced regenerative therapies, continuous innovations in bioengineered skin substitutes and growth factor-based products, and expanding clinical adoption of biologic wound care solutions to accelerate healing and reduce complications are further supporting market growth.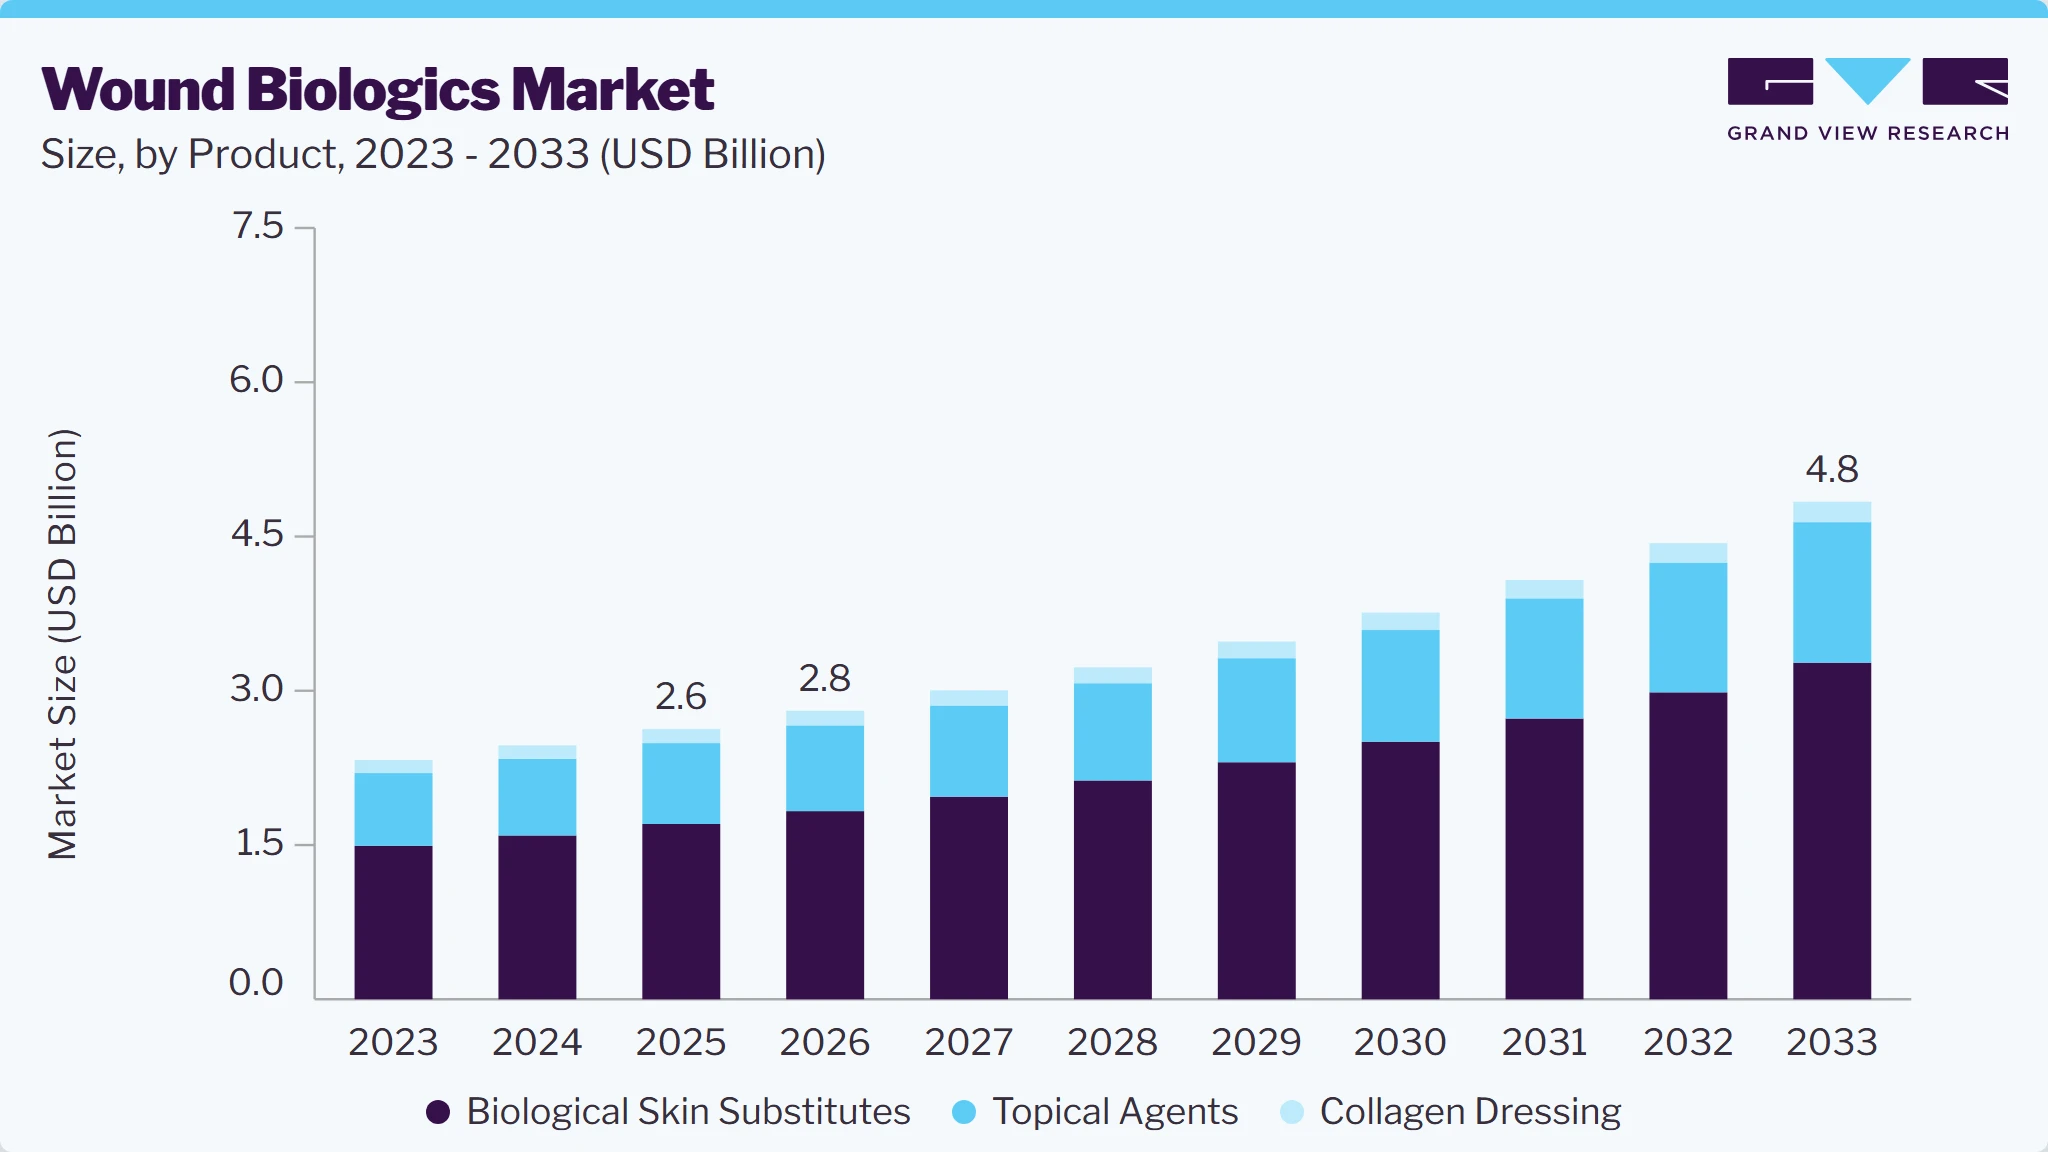 To learn more about this report, Download Free Sample Report
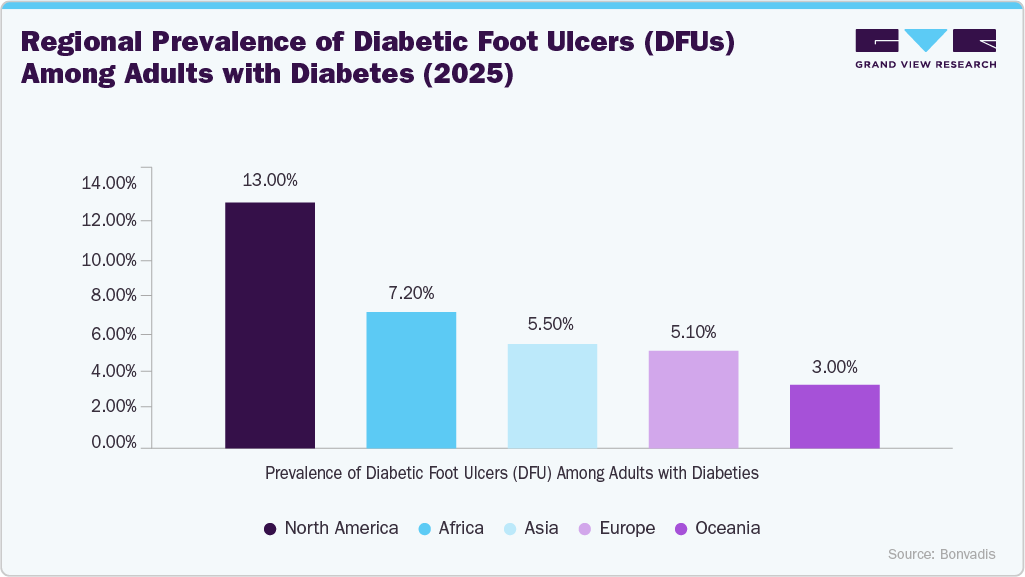
The increasing prevalence of chronic wounds and diabetes is a major growth driver for the wound biologics market, as diabetic foot ulcers, venous leg ulcers, pressure ulcers, and other non-healing wounds require advanced therapies that promote tissue regeneration and accelerate healing. According to the International Diabetes Federation, diabetes cases continue to rise globally, increasing the number of patients at risk of chronic wound complications. Biologic wound care products, including skin substitutes, placental tissue allografts, and extracellular matrix (ECM)-based therapies, are being adopted to improve healing outcomes, reduce infection risk, and lower amputation rates in patients with complex wounds.
 To learn more about this report, Download Free Sample Report
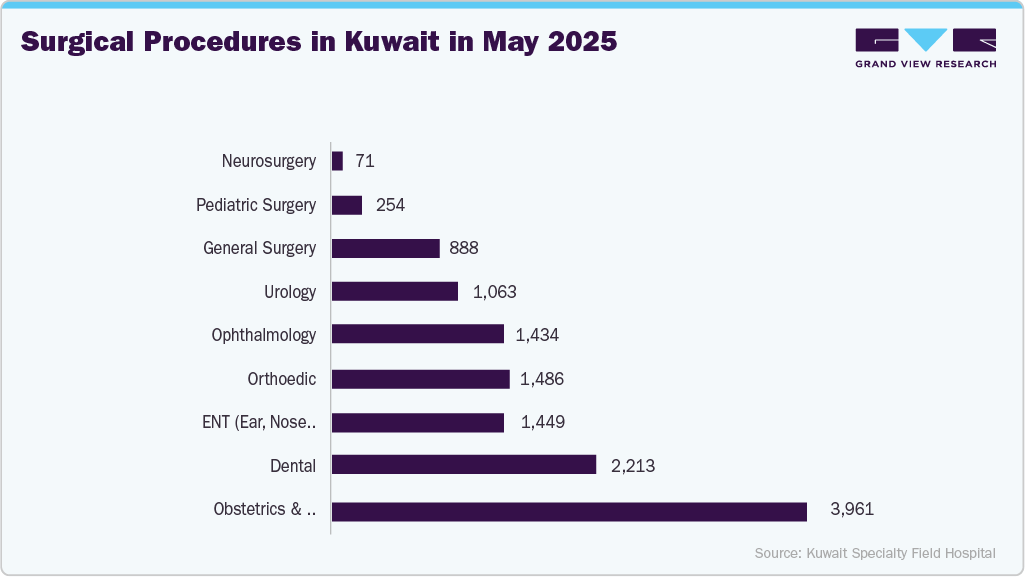
The growing number of surgical procedures and traumatic injuries is a key driver of the wound biologics market, as these conditions often require advanced wound management to accelerate tissue regeneration and reduce the risk of complications, such as infection and delayed healing. Biologic wound care products, including skin substitutes, amniotic membrane allografts, and extracellular matrix (ECM)-based therapies, are increasingly being used in complex surgical wounds, orthopedic procedures, burns, and trauma cases. The rising global surgical volume and increasing incidence of road traffic accidents, sports injuries, and burn injuries continue to expand the demand for regenerative wound biologics across hospitals and trauma centers.
Surgeries performed in Canada (April 1 - June 30, 2025)
Metric
Statistics
Surgeries Performed or Offered Within 3 Months
78%
Surgeries Performed or Offered Within 6 Months
88.50%
Surgeries Performed or Offered Within 12 Months
96.70%
Total Surgeries Performed
24,627
Source: Saskatchewan
 To learn more about this report, Download Free Sample Report
Moreover, the increasing adoption of regenerative medicine and advanced wound care therapies is a major driver of the wound biologics market, as healthcare providers seek treatments that enhance tissue regeneration, accelerate wound closure, and improve clinical outcomes. Biologic products, such as bioengineered skin substitutes, placental tissue allografts, extracellular matrix (ECM)-based therapies, and growth factor formulations, are incorporated into the management of chronic and complex wounds. Continuous advancements in tissue engineering, regenerative biomaterials, and cell-based technologies are further expanding the clinical applications and adoption of wound biologics across hospitals, specialized wound care centers, and outpatient settings.
-
In April 2026, Organogenesis Holdings announced the successful completion of a randomized controlled trial (RCT) for PuraPly AM in the treatment of diabetic foot ulcers. The study met its primary endpoint, reinforcing the growing clinical adoption of biologic extracellular matrix (ECM)-based therapies for chronic wound management.
-
In May 2026, ConvaTec Group showcased its Advanced Wound Care innovation pipeline at the European Wound Management Association (EWMA) 2026 Conference, highlighting next-generation regenerative wound care technologies designed to improve healing outcomes for chronic and hard-to-heal wounds.
Market Dynamics
The wound biologics market is driven by the rising prevalence of chronic wounds, the growing diabetic and aging populations, and the increasing demand for advanced regenerative therapies that accelerate healing and reduce complications. However, high treatment costs, stringent regulatory requirements, and limited reimbursement coverage in certain regions continue to restrain market growth.
The rising prevalence of chronic wounds is a major driver of the wound biologics market. Conditions such as diabetic foot ulcers, venous leg ulcers, pressure ulcers, and surgical wounds are becoming increasingly common due to the growing burden of diabetes, obesity, and an aging population. These wounds often require advanced treatment approaches because they are slow to heal and are prone to infection and recurrence. Wound biologics, including skin substitutes and tissue-based products, accelerate tissue regeneration and improve healing outcomes, driving their increased adoption in wound care management.
According to the European Wound Management Association (EWMA), 2025
• Chronic wounds affect approximately 2.2 individuals per 1,000 population, highlighting a significant healthcare burden across Europe.
• The point prevalence of venous leg ulcers is estimated at 0.33%-1.01% of the population, contributing substantially to the global burden of chronic wound management.
• An estimated 19-34% of people with diabetes are expected to develop diabetic foot disease during their lifetime, driving demand for advanced wound care and infection management solutions.
• Of the estimated 64.3 million people with diabetes in Europe, approximately 16.1 million are expected to develop a diabetic foot ulcer during their lifetime, highlighting the substantial burden of chronic wound care.
Stringent regulatory and approval processes act as a significant restraint on the wound biologics market. Manufacturers must comply with rigorous requirements related to product safety, efficacy, tissue sourcing, and manufacturing standards before obtaining market authorization. These complex regulations often lead to lengthy approval timelines and increased development costs, delaying product commercialization. As a result, smaller companies may face challenges in entering the market, limiting overall industry growth.
The increasing adoption of personalized regenerative therapies presents a significant opportunity for the wound biologics market. Advances in tissue engineering, stem cell-based treatments, and patient-specific biologic products are enabling more targeted and effective wound healing solutions. These therapies can address individual patient needs, improve clinical outcomes, and reduce healing times for complex and chronic wounds. As research and development efforts continue to expand, personalized regenerative approaches are expected to drive innovation and create new growth avenues within the market.
Market Concentration & Characteristics
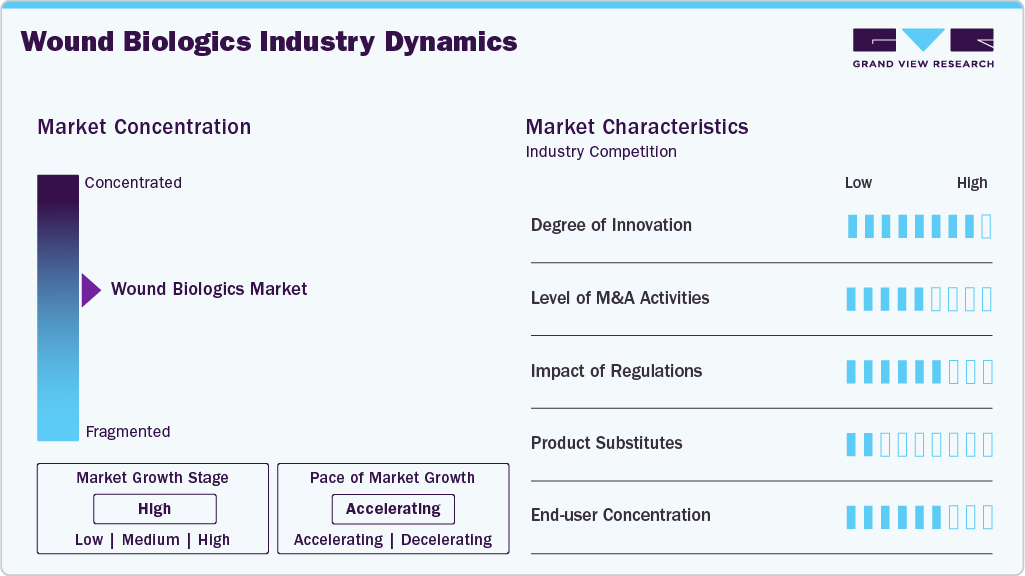
The wound biologics market is witnessing significant innovation driven by continuous advancements in regenerative medicine and tissue engineering. For instance, Smith+Nephew expanded its biologics portfolio with GRAFIX PLUS and STRAVIX PL, offering cryopreserved placental tissue matrices for complex wound management. MiMedx Group continues to advance amniotic tissue-based products such as EPIFIX, while Organogenesis Holdings has strengthened its portfolio with products including Apligraf and Dermagraft for diabetic foot ulcers and venous leg ulcers. In addition, emerging innovations in 3D bioprinted skin constructs, stem cell-based therapies, and AI-enabled wound assessment are further improving the precision and effectiveness of biologic wound care.
The wound biologics industry has seen moderate to high levels of mergers and acquisitions, as companies seek to strengthen their regenerative medicine portfolios, expand product pipelines, and enhance global market presence. Strategic acquisitions have focused on biologic wound care technologies, placental tissue products, and tissue engineering capabilities to address the growing demand for advanced wound management. These transactions enable manufacturers to accelerate innovation, broaden clinical indications, and gain access to established distribution networks, thereby intensifying competition within the market.
 To learn more about this report, Download Free Sample Report
Regulatory developments continue to play a pivotal role in shaping the market by strengthening product quality, clinical evidence requirements, and reimbursement oversight. For instance, in 2025, CMS finalized significant reimbursement reforms under the CY 2026 Medicare Physician Fee Schedule, reclassifying most skin substitutes as incident-to supplies while retaining ASP-based reimbursement only for licensed biologics under Section 351 of the Public Health Service Act. In addition, CMS withdrew the planned Local Coverage Determinations (LCDs) for skin substitute grafts to allow further stakeholder engagement, highlighting the dynamic regulatory environment governing advanced wound biologics.
The market is highly concentrated amonghospitals and specialized wound care centers, where advanced biologic therapies are primarily administered for complex chronic wounds and post-surgical wound management. These settings account for most of the product utilization due to the availability of multidisciplinary wound care teams, advanced diagnostic capabilities, and favorable reimbursement pathways. Adoption is gradually expanding into ambulatory surgical centers and home healthcare settings as biologic wound therapies become more accessible and outpatient wound management continues to grow.
Analyst Perspective
The wound biologics market is poised for significant growth, driven by the increasing burden of chronic wounds, rising diabetes prevalence, and a growing aging population that is more susceptible to slow-healing injuries. Healthcare providers are adopting biologic therapies, such as skin substitutes, amniotic tissue products, and extracellular matrix-based solutions, because they promote tissue regeneration and improve healing outcomes compared to conventional wound care methods. Although challenges such as high treatment costs and stringent regulatory requirements persist, ongoing advancements in regenerative medicine, expanding clinical evidence, and improving reimbursement support are expected to strengthen market adoption. As demand for advanced wound management continues to rise, companies that invest in innovation, clinical validation, and geographic expansion are likely to gain a competitive advantage in the evolving wound biologics landscape.
Product Insights
The biological skin substitutes segment led the wound biologics market with the largest revenue share of 64.9% in 2025, and is expected to grow at the fastest CAGR over the forecast period. The growth is driven by their proven effectiveness in promoting tissue regeneration and accelerating healing of chronic, non-healing wounds, including diabetic foot ulcers, venous leg ulcers, pressure injuries, and burns. Their widespread adoption has been supported by strong clinical evidence, increasing use in hospital-based wound care, and growing availability of bioengineered and human tissue-derived products. Continued product innovation, expanding clinical indications, and favorable reimbursement for selected products have further reinforced the segment's leading market position.
The topical agents segment is expected to grow significantly over the forecast period, driven by the increasing demand for minimally invasive therapies that can be easily applied in both clinical and home healthcare settings. Biologic topical formulations containing growth factors, antimicrobial peptides, collagen, and other regenerative biomolecules are gaining traction for their ability to accelerate wound healing, reduce the risk of infection, and improve patient outcomes. Ongoing research into advanced topical biologics, coupled with the rising prevalence of chronic wounds and the expanding outpatient wound management, is expected to further drive this segment's growth.
Application Insights
The chronic wounds segment led the market with the largest revenue share of 59.8% in 2025, driven by the increasing prevalence of diabetic foot ulcers, venous leg ulcers, and pressure ulcers, particularly among aging populations, those with diabetes, obesity, and vascular disorders. These wounds often require advanced biologic therapies to stimulate tissue regeneration, accelerate healing, and reduce the risk of infection and amputation. Growing clinical adoption of biologic skin substitutes, amniotic membrane products, and extracellular matrix-based therapies, supported by favorable clinical outcomes, further strengthened the segment’s leading market position.
The acute wounds segment is expected to grow at the fastest CAGR during the forecast period, driven by rising numbers of surgical procedures, traumatic injuries, and burn cases worldwide. The growing emphasis on reducing healing time, preventing surgical site infections, and improving postoperative recovery is accelerating the adoption of biologic wound care products in acute wound management. In addition, advances in bioengineered skin substitutes, growth factor therapies, and regenerative biologics, along with the shift toward minimally invasive, outpatient care, are expected to further propel this segment's growth.
End-use Insights
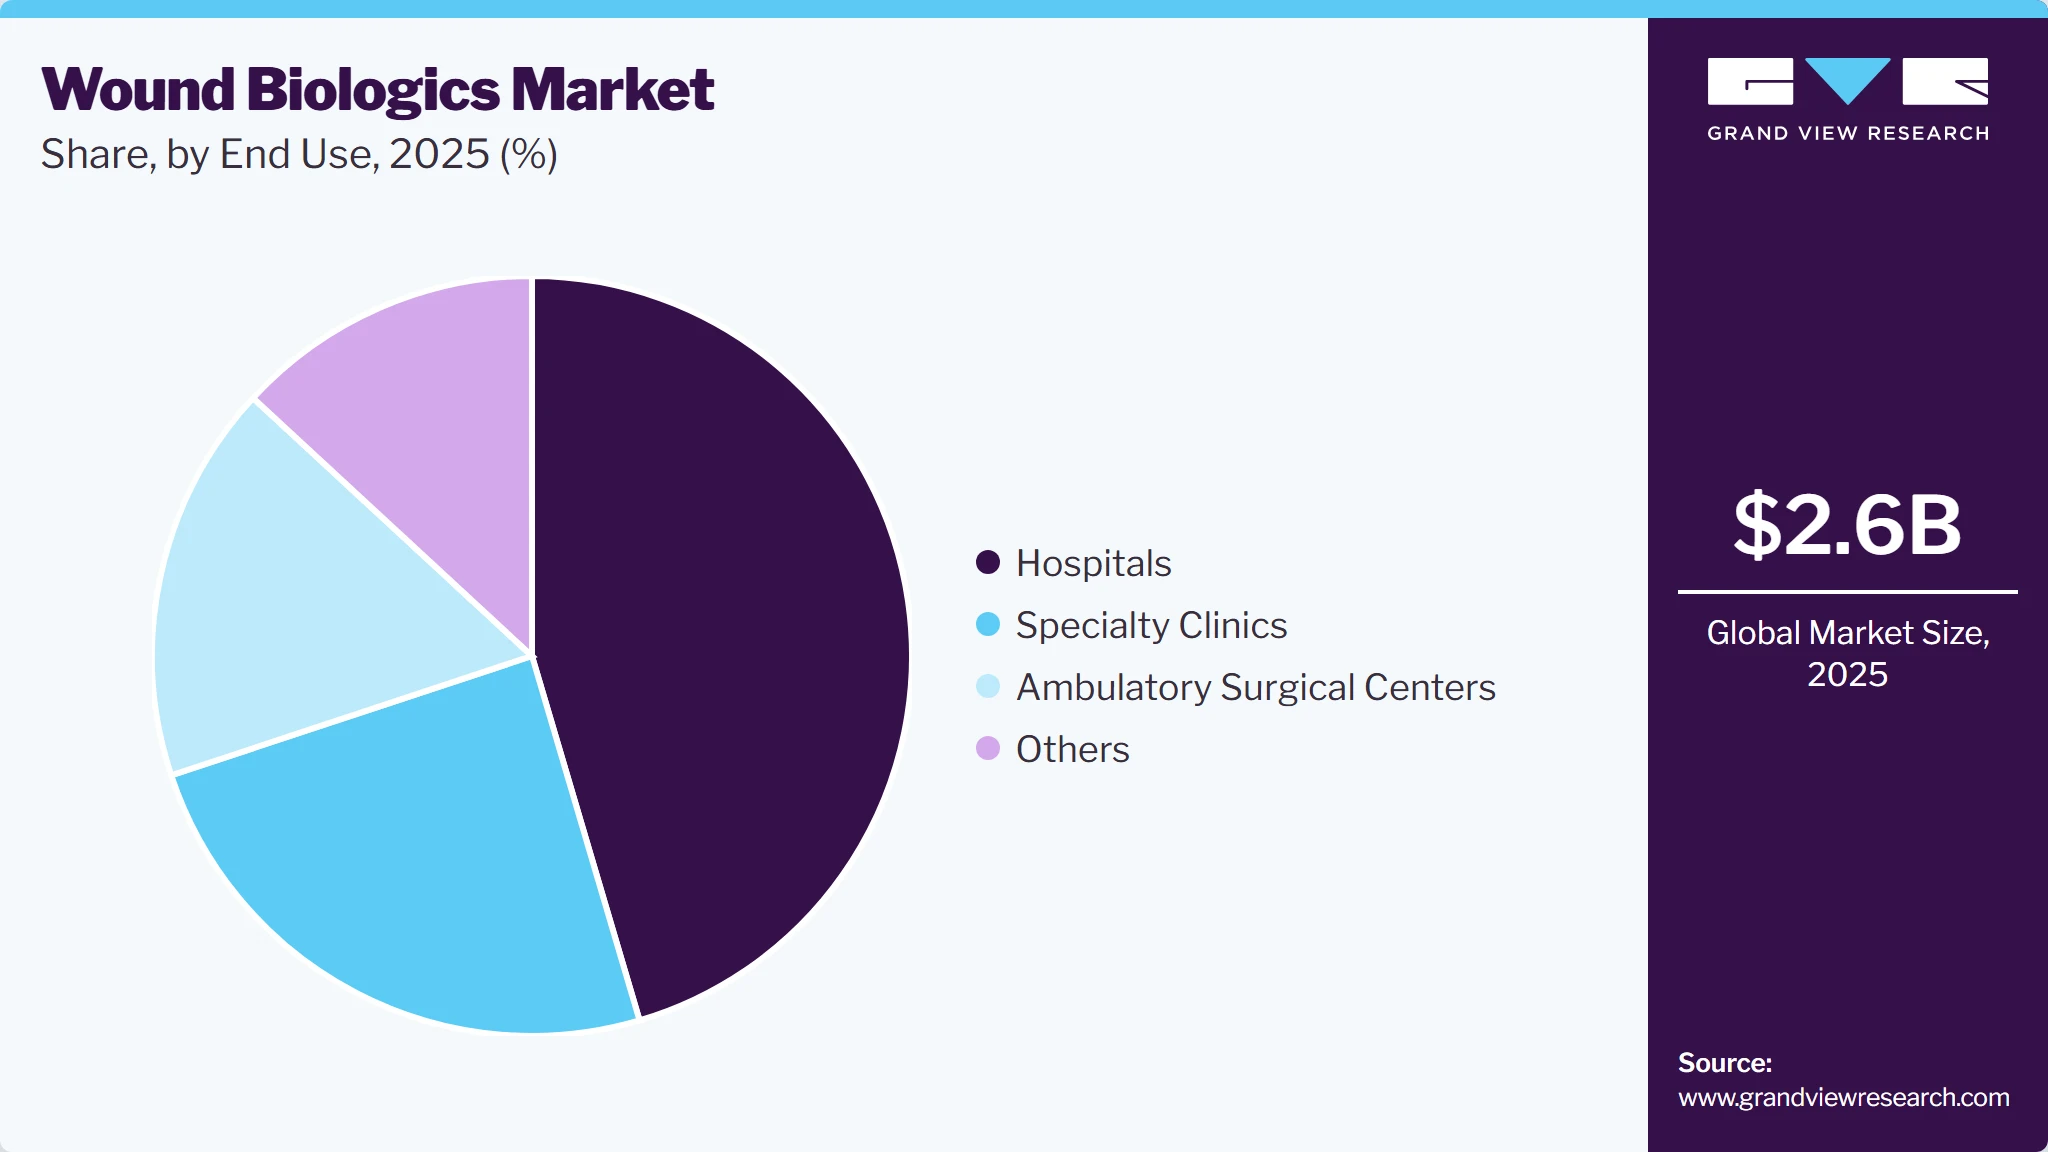
The hospitals segment dominated the wound biologics market with the largest revenue share of 45.4% in 2025, owing to the high volume of patients requiring treatment for chronic wounds, burns, traumatic injuries, and post-surgical wounds. Hospitals are the primary settings for the administration of advanced biologic therapies due to the availability of specialized wound care teams, multidisciplinary expertise, and access to advanced diagnostic and surgical infrastructure. Favorable reimbursement for selected biologic products and increasing adoption of regenerative wound care technologies have further reinforced hospitals as the leading end-user segment.
 To learn more about this report, Download Free Sample Report
The ambulatory surgical centers (ASCs) segment is expected to grow at the fastest CAGR during the forecast period, driven by the increasing shift toward outpatient surgical procedures and cost-effective wound management. ASCs are increasingly adopting biologic wound care products to accelerate healing, reduce post-operative complications, and shorten patient recovery times. Rising demand for minimally invasive surgeries, advancements in regenerative wound therapies, and expanding reimbursement for outpatient care are expected to further fuel this segment's growth.
Regional Insights
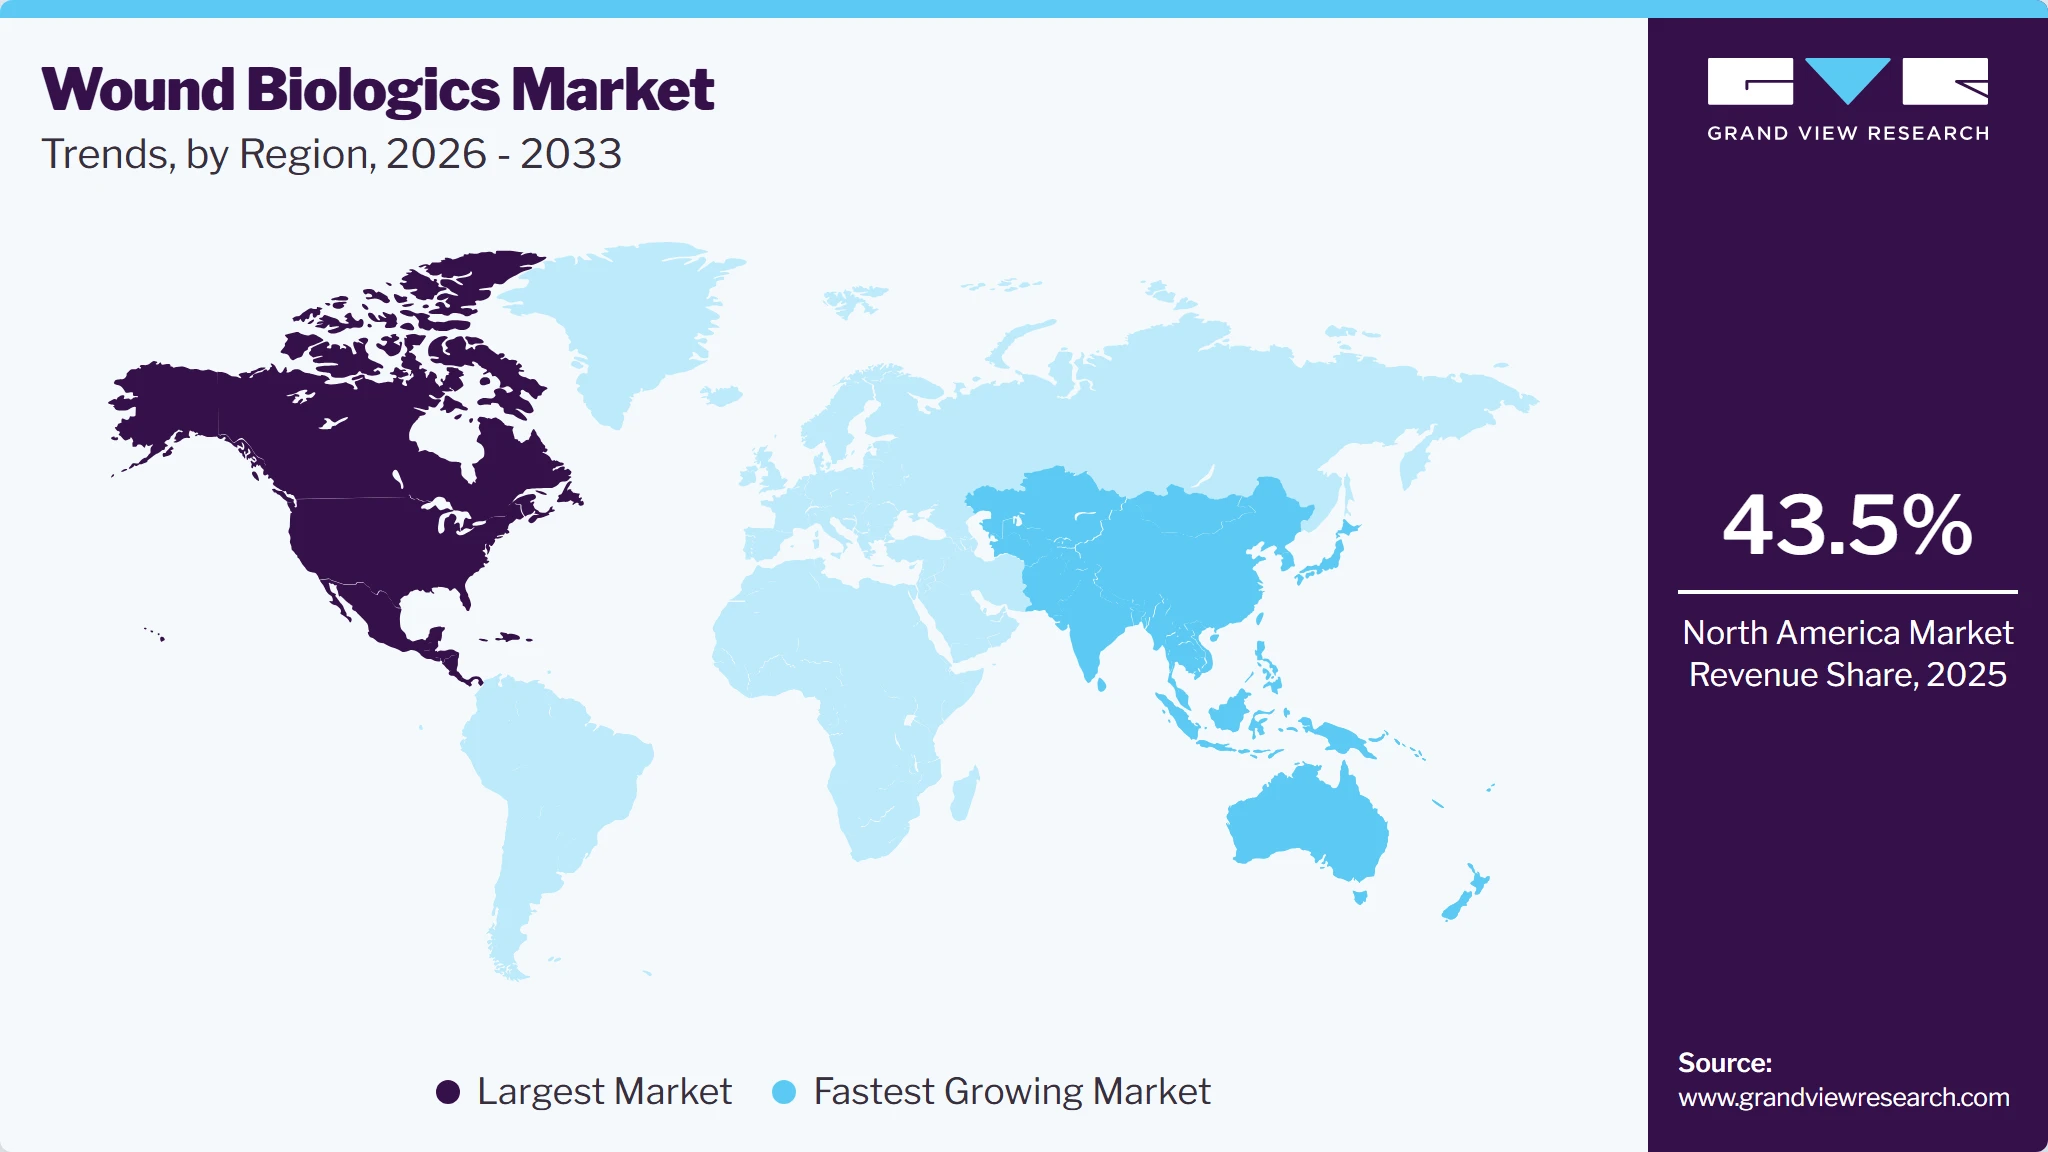
North America dominated the wound biologics market with the largest revenue share of 43.5% in 2025, driven by the high prevalence of chronic wounds, an aging population, and the growing incidence of diabetes and obesity. The region benefits from advanced healthcare infrastructure, widespread adoption of regenerative wound care technologies, and strong clinical utilization of biologic skin substitutes and tissue-based products. Continuous product innovation, favorable reimbursement for selected biologic therapies, and the presence of leading manufacturers further support market growth across the region.
 To learn more about this report, Download Free Sample Report
U.S. Wound Biologics Market Trends
The U.S. wound biologics industry held the largest share of North America in 2025, supported by the high burden of chronic wounds, rising diabetes prevalence, and a rapidly aging population. Market growth is being driven by strong adoption of biologic skin substitutes, placental tissue allografts, and other regenerative wound therapies across hospitals and specialized wound care centers. Ongoing product innovation, a favorable regulatory environment for advanced biologics, and expanding Medicare reimbursement for selected wound care products continue to strengthen the U.S. market.
Europe Wound Biologics Market Trends
The Europe wound biologics industry is experiencing significant growth, driven by the rising prevalence of chronic wounds, an aging population, and the increasing incidence of diabetes and vascular disorders. The region is witnessing greater adoption of biologic skin substitutes, amniotic membrane products, and tissue-engineered therapies supported by well-established healthcare systems and expanding wound care services. In addition, implementation of the Medical Device Regulation (MDR) and continued investment in regenerative medicine are encouraging innovation and improving the quality and safety of advanced wound biologic products.
The UK wound biologics market is growing due to the increasing prevalence of chronic wounds, an aging population, and the rising burden of diabetes-related foot ulcers. Adoption of biologic skin substitutes and regenerative wound care therapies is increasing across hospitals and community-based wound care services, supported by a strong focus on improving healing outcomes and reducing hospital admissions. Continued investment in advanced wound management, ongoing clinical research, and evolving reimbursement and procurement pathways is expected to further support market growth in the UK.
The wound biologics market in France is witnessing significant growth, driven by the increasing prevalence of chronic wounds, an aging population, and the rising incidence of diabetes and vascular diseases. The country is expanding the use of biologic skin substitutes and regenerative wound care therapies through hospitals and specialized wound care centers to improve healing outcomes and reduce long-term healthcare costs. In addition, continued investment in biomedical research, a strong public healthcare infrastructure, and the adoption of advanced tissue-engineered products are driving market growth.
Asia Pacific Wound Biologics Market Trends
The Asia Pacific wound biologics industry is expected to grow at the fastest CAGR during the forecast period, driven by the rising prevalence of diabetes, chronic wounds, burns, and traumatic injuries across the region. Improving healthcare infrastructure, increasing investments in regenerative medicine, and growing awareness of advanced wound care are accelerating the adoption of biologic skin substitutes and tissue-based therapies. In addition, expanding healthcare expenditure, a large patient population, and improving access to specialized wound care services are creating significant opportunities for market expansion across countries such as China, Japan, India, and South Korea.
The China wound biologics market is growing rapidly, driven by the rising prevalence of diabetes, an aging population, and the increasing incidence of chronic wounds and burn injuries. The country is witnessing greater adoption of regenerative wound care products, supported by expanding healthcare infrastructure, increasing investment in biotechnology, and the development of domestically manufactured biologic therapies. In addition, regulatory reforms and growing clinical research activities are accelerating the commercialization and adoption of advanced wound biologics across hospitals and specialized wound care centers.
Latin America Wound Biologics Market Trends
The Latin America wound biologics industry is experiencing significant growth, driven by the increasing prevalence of diabetes, chronic wounds, burns, and traumatic injuries across the region. Rising investments in healthcare infrastructure, improving access to advanced wound care therapies, and growing awareness of regenerative medicine are supporting the adoption of biologic skin substitutes and tissue-based products. In addition, expanding private healthcare services and government initiatives to enhance chronic wound management are expected to create new growth opportunities for the market.
MEA Wound Biologics Market Trends
The MEA wound biologics industry is witnessing gradual growth, driven by the increasing prevalence of diabetes, chronic wounds, burn injuries, and traumatic wounds across the region. Improving healthcare infrastructure, rising investment in advanced wound care, and expanding access to specialized treatment centers are supporting the adoption of biologic wound therapies. Furthermore, growing government initiatives to modernize healthcare systems and increasing awareness of regenerative medicine are expected to create new opportunities for wound biologics in the coming years.
Key Wound Biologics Company Insights
The wound biologics market is moderately consolidated, with leading players such as Smith+Nephew, Organogenesis Holdings, MiMedx Group, Integra LifeSciences, and Vericel Corporation accounting for a significant share of the global market through their broad portfolios of biologic skin substitutes, placental tissue products, and regenerative wound care solutions. Competition is driven by continuous product innovation, clinical evidence generation, regulatory approvals, strategic acquisitions, and expansion into emerging markets, while regional and emerging manufacturers continue to strengthen their presence with cost-effective biologic therapies.
Key Wound Biologics Companies:
The following key companies have been profiled for this study on the wound biologics market.
-
MIMEDX Group, Inc.
-
Integra LifeSciences Corporation
-
Organogenesis Inc.
-
BioTissue
-
Skye Biologics Holdings, LLC
-
Tissue Regenix Group
-
Vericel Corporation
-
Stimlabs LLC
-
Tides Medical
-
AlloSource
-
LifeNet Health
-
MTF Biologics
-
Stryker
-
Convatec
-
Smith+Nephew
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Integra LifeSciences Corporation, Stryker, Smith + Nephew, Organogenesis Inc. (Avista Healthcare Public Acquisition Corp.), MIMEDX Group, Inc)
- Invest heavily in R&D to develop next-generation biologic wound care products.
- Expand product portfolios through acquisitions, partnerships, and licensing agreements.
- Strong brand recognition and established market presence.
- Extensive clinical evidence supporting product efficacy and safety.
- Higher operational and manufacturing costs.
- Longer decision-making and product development cycles.
Emerging Players (BioTissue, Stimlabs LLC, Tides Medical, AlloSource)
- Focus on niche biologic technologies such as placental tissue, extracellular matrix products, and stem cell-based therapies.
- Collaborate with research institutions and healthcare organizations to develop products.
Greater flexibility and agility in responding to market trends.
Strong focus on innovation and emerging regenerative medicine technologies.
- Limited financial and commercial resources.
- Smaller sales and distribution networks.
Recent Developments
-
In May 2026, ConvaTec Group showcased the breadth and momentum of its Advanced Wound Care innovation pipeline at the European Wound Management Association (EWMA) 2026 Conference held in Bremen, Germany. The company highlighted its latest technologies and product developments to improve outcomes in chronic wound management and strengthen its leadership in advanced wound care.
-
In April 2026, Organogenesis Holdings announced the successful completion of a randomized controlled trial (RCT) evaluating PuraPly AM plus standard of care (SOC) versus SOC alone for the treatment of non-healing diabetic foot ulcers (DFUs). The study met its primary endpoint, demonstrating a statistically significant improvement in wound closure at 12 weeks, and highlighted the clinical impact of PuraPly AM in advanced wound care.
-
In January 2022, ConvaTec Group entered into a definitive agreement to acquire Triad Life Sciences, a U.S.-based medical device company specializing in biologically derived products for the treatment of surgical wounds, chronic wounds, and burns. The acquisition was aimed at strengthening ConvaTec's advanced wound care and biologics portfolio.
Wound Biologics Market Report Scope
Report Attribute
Details
Market size in 2025
USD 2.6 billion
Estimated market size in 2026
USD 2.8 billion
Projected market size by 2033
USD 4.8 billion
Growth rate
CAGR of 8.1% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD Million and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, application, end-use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; Russia; Iceland; Finland; China; Japan; India; South Korea; Australia; Thailand; Singapore; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait; Israel
Key companies profiled
MIMEDX Group, Inc.; Integra LifeSciences Corporation; Organogenesis Inc.; BioTissue; Skye Biologics Holdings, LLC; Tissue Regenix Group; Vericel Corporation; Stimlabs LLC; Tides Medical; AlloSource; LifeNet Health; MTF Biologics; Stryker; Convatec; Smith+Nephew
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Wound Biologics Market Report Segmentation
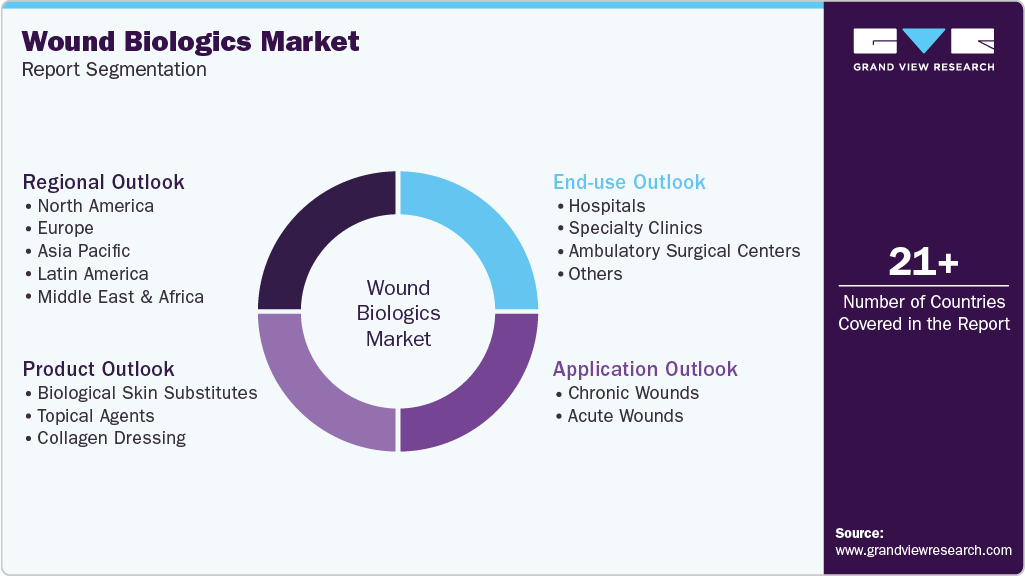
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global wound biologics market report based on product, application, end-use, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Biological Skin Substitutes
-
Allograft
-
Xenograft
-
Biosynthetic Products
-
-
Topical Agents
-
Collagen Dressing
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Chronic Wounds
-
Acute Wounds
-
-
End-use Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospitals
-
Specialty Clinics
-
Ambulatory Surgical Centers
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
Sweden
-
Denmark
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The wound biologics market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each wound biologics segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Biological Skin Substitutes
Revenue from biological skin substitutes includes sales of human-, animal-, and bioengineered skin replacement products used to promote tissue regeneration and wound healing in both acute and chronic wounds. This segment covers allografts, xenografts, amniotic membrane products, acellular dermal matrices, and living skin equivalents utilized in advanced wound care.
Topical Agents
Revenue for topical agents in the wound biologics market includes sales generated from biologically active topical formulations applied directly to wounds to promote healing, reduce infection risk, and support tissue regeneration. This segment covers growth factor-based gels, biologic ointments, antimicrobial biologic preparations, enzyme-based products, and other regenerative topical therapies used in advanced wound care.
Collagen Dressing
Revenue includes sales of collagen-based dressings used to promote wound healing and tissue regeneration. This segment covers collagen sheets, pads, powders, gels, and composite collagen dressings utilized in chronic and acute wound care.
Estimation Model
Approach
Description
Bottom-Up Epidemiological Modeling
Estimates the wound biologics market by modeling patient-level incidence and prevalence of target wounds (DFUs, VLUs, pressure injuries, burns, surgical & chronic wounds) across key geographies. Applies eligible patient pools, treatment penetration rates, biologics utilization rates, average units per patient, and ASPs to derive country-level and total market sizes.
Top-Down Revenue Triangulation
Aggregates supplier-side revenues for wound biologics from annual reports, investor presentations, regulatory filings, and commercial databases. Segments revenue by product type (e.g., amniotic membranes, collagen matrices, bioengineered skin, growth factors), application, and region, followed by triangulation with trade data, custom surveys, and expert inputs to validate total market size.
Demand-Side Care-Setting Modeling
Builds market estimates by capturing product consumption and spend across key care settings-hospitals, outpatient wound care centers, ASCs, long-term care, and home healthcare. Analyzes procedure volumes, biologics uptake per setting, reimbursement coverage, and ASPs to project demand and revenue across geographies.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Disease epidemiology and patient population analysis
Comprehensive epidemiological assessment covering diabetic foot ulcers (DFUs), venous leg ulcers (VLUs), pressure ulcers, burns, surgical wounds, and chronic non-healing wounds, with patient segmentation by severity, age group, comorbidities, and treatment eligibility for biologic products.
Enables accurate addressable market estimation, identifies high-value patient pools for advanced biologics, supports reimbursement discussions, and improves demand forecasting across wound care settings.
Product share analysis by manufacturer and product type
Revenue- and volume-based market share analysis across biological skin substitutes, amniotic membrane products, collagen dressings, growth factor therapies, bioengineered skin constructs, and cellular/tissue-based products, mapped to leading manufacturers and emerging innovators.
Reveals competitive positioning, identifies technology adoption trends, highlights white-space opportunities, and supports portfolio benchmarking and M&A evaluation.
Consumer behavior and treatment adoption analysis
In-depth assessment of physician prescribing patterns, patient preferences, biologic product awareness, treatment adherence, purchasing drivers, site-of-care utilization, and factors influencing adoption of wound biologics across hospitals, wound care centers, and home care settings.
Identifies key adoption barriers and decision-making factors, supports targeted commercialization strategies, improves customer segmentation, and enables optimization of product positioning and market penetration efforts.
Frequently Asked Questions About This Report
The global wound biologics market size was estimated at USD 2.6 billion in 2025 and is projected to grow from USD 2.8 billion in 2026.
The global wound biologics market is expected to witness a compound annual growth rate of 8.1% from 2026 to 2033 to reach USD 4.8 billion by 2033.
Key factors that are driving the market growth include technological advancement, increasing prevalence of chronic diseases, rising cases of accidents & trauma, and rising geriatric population.
The hospitals segment led the market with the largest revenue share of 45.4% in 2025, while ambulatory surgical centers segment is fastest growing end-use.
Some key players operating in the wound biologics market include MIMEDX Group, Inc, Integra LifeSciences Corporation, Organogenesis Inc., BioTissue, Skye Biologics Holdings, LLC, Tissue Regenix Group, Stimlabs LLC, Tides Medical , AlloSource, LifeNet Health, MTF Biologics, Stryker, Convatec, Smith+Nephew
North America dominated the wound biologics market with the largest revenue share of 43.5% in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
The chronic wounds segment led the market with the largest revenue share of 59.8% in 2025, while acute wounds segment is fastest growing application.
The biological skin substitutes segment led the market with the largest revenue share of 64.9% in 2025 and is expected to grow at the fastest CAGR over the forecast period.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


