
- Home
- »
- Automotive & Transportation
- »
-
Yacht Market Size, Share And Growth Report, 2026-2033GVR Report cover

Yacht Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Super Yacht, Sport Yacht, Flybridge Yacht, Long Range Yacht, Others), By Length (Up to 20 m, 20 to 50 m, Above 50 m), By Propulsion (Motor Yacht, Sailing Yacht), By Region, And Segment Forecasts
Market Size, 2025
$10.3BMarket Estimate, 2026
$10.9BMarket Forecast, 2033
$15.5BCAGR, 2026–2033
5.2%Yacht Market Summary
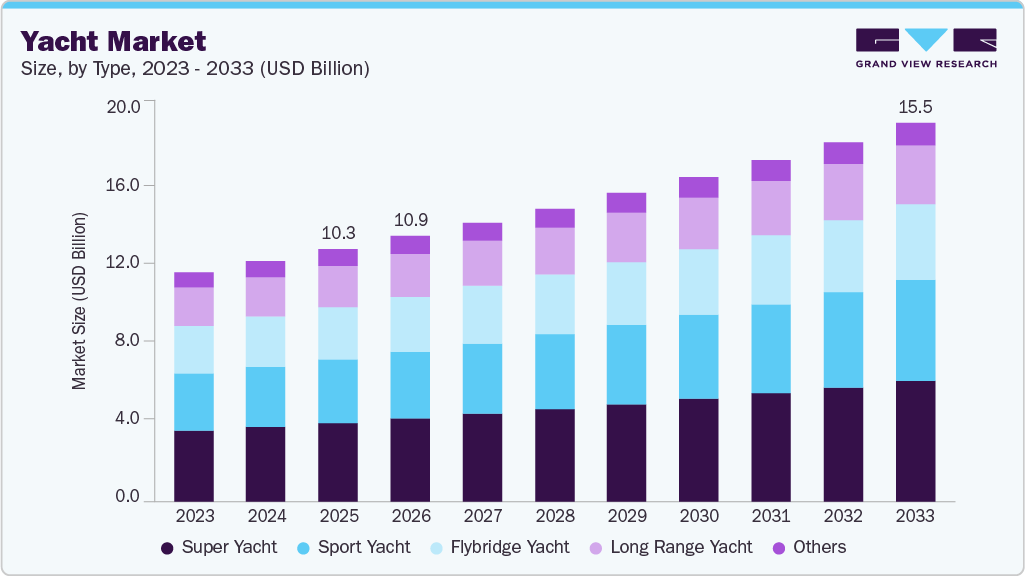
The global yacht market size was valued at USD 10.3 billion in 2025 and is projected to grow from USD 10.9 billion in 2026 to USD 15.5 billion by 2033, at a CAGR of 5.2% from 2026 to 2033. Europe dominated the global market, accounting for 39.2% of revenue in 2025. Demand for yachts is supported by high-net-worth consumers allocating more of their spending to leisure, private travel, and experiential recreation, as well as continued interest in yacht ownership and chartering.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Super yacht segment led with a 31.3% revenue share in 2025.
- By length: 20 to 50 m segment led with a 57.3% revenue share in 2025.
- By propulsion: Motor yacht segment held the largest revenue share in 2025.
Regional Highlights
- Largest regional market: Europe (39.2% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: France held the largest market share in Europe in 2025.
Market Size & Forecast
- Market size in 2025: USD 10.3 Billion
- Estimated market size in 2026: USD 10.9 Billion
- Projected market size by 2033: USD 15.5 Billion
- CAGR (2026-2033): 5.2%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Industry activity also reflects demand for larger, more customized vessels and technologically advanced propulsion systems. According to the National Marine Manufacturers Association, yacht retail sales increased 1.8% year over year during the first half of 2025 in the U.S. The yacht industry includes a wide variety of vessels, such as superyachts, sport yachts, flybridge yachts, long-range yachts, and other luxury recreational boats. Demand in this sector is closely linked to the growth of the luxury travel market, as high-net-worth individuals (HNWIs) increasingly seek personalized services, privacy, and exclusive leisure experiences. Yacht manufacturers are offering customized layouts, premium interiors, improved onboard amenities, and performance-oriented features that cater to specialized customer preferences.
 To learn more about this report, Download Free Sample Report
Yacht construction is evolving with the increased use of advanced materials and engineering techniques. While traditional methods have relied on wood, fiberglass, and fiber-reinforced polymers (FRPs), manufacturers are now incorporating carbon fiber and other lightweight composite materials. This shift enhances strength-to-weight ratios, fuel efficiency, durability, and overall vessel performance. These materials also allow for greater design flexibility, enabling shipbuilders to create larger and more complex vessels without a proportional increase in weight.
Technological advancements are significantly influencing yacht design, propulsion, navigation, and onboard systems. Hybrid propulsion, battery-electric systems, advanced energy management solutions, and lower-emission technologies are gaining traction as manufacturers adapt to environmental considerations and changing owner preferences. For instance, Sanlorenzo has announced plans for hybrid propulsion in its 2026 SHE model and has partnered with BYD Energy Storage to advance battery and energy storage applications for yachts. Similarly, Azimut Benetti is expanding the use of hybrid propulsion, lightweight carbon-fiber construction, and lower-emission designs in its portfolio. Digital technologies are also enhancing the capabilities of modern yachts. Integrated monitoring systems, connected onboard equipment, advanced navigation features, automation, remote diagnostics, and data-driven maintenance can improve operational visibility and vessel management. Sanlorenzo's 2026 business plan emphasizes digital and systems integration, AI, monitoring systems, automation, hybrid propulsion, fuel cells, and innovative materials as key areas for research and development. These innovations are gradually transforming yachts from primarily mechanical vessels into connected, digitally managed luxury platforms.
The growth of marine tourism and yacht chartering is driving demand in the yacht market. Affluent travelers seek coastal and island experiences with increased flexibility, privacy, and access to unique locations. Charter operations also create a need for purpose-built vessels and fleet expansions to cater to varying group sizes and cruising needs. This connects yacht ownership with charter activities, tourism spending, and the demand for new vessels.
Environmental regulations, such as the IMO’s Energy Efficiency Existing Ship Index (EEXI) and Carbon Intensity Indicator (CII), focus on energy efficiency and emissions but mainly target large ships. In April 2025, the IMO introduced draft measures for a broader Net-Zero Framework, which includes a marine fuel standard and emissions pricing.
Despite strong demand from affluent consumers, yacht ownership comes with high acquisition and operating costs, including crew salaries, marina fees, insurance, fuel, and maintenance. These expenses often lead potential buyers to consider chartering or shared-use models. Yacht manufacturers face challenges such as skilled labor shortages, component availability, and long construction times. Additionally, fluctuations in financial markets, interest rates, and consumer confidence can affect discretionary spending in the high-value yacht segment.
Market Dynamics
The yacht market is evolving due to changing consumer preferences, new trends in marine tourism, and ongoing investments in yachting infrastructure and technology. There is a rising demand for luxury and personalized leisure experiences, driving market growth. However, high ownership and operating costs remain significant challenges. Meanwhile, the development of specialized marinas, sustainable propulsion systems, and enhanced marine infrastructure is creating new opportunities for manufacturers, charter operators, and emerging yachting destinations.
Wealth growth among high-net-worth and ultra-high-net-worth individuals is driving the demand for premium leisure experiences, including private yacht ownership and chartering. Consumers are increasingly seeking personalized travel, privacy, and exclusive access to coastal destinations. This trend has led to a demand for yachts featuring customized interiors, entertainment systems, spacious accommodations, and advanced onboard amenities. The expansion of luxury tourism and yacht charter services is also allowing a broader audience to enjoy yachting experiences without the need for full ownership.
The shift toward experience-oriented luxury is prompting yacht manufacturers and charter operators to enhance their offerings with more personalization and destination-based experiences. Yacht owners are now viewing their vessels not just as recreational assets, but also as platforms for extended travel, social activities, and private entertainment. This change is supporting demand across various yacht sizes and configurations, while established cruising destinations and developing marine tourism infrastructure are creating further opportunities for market expansion.
The high costs associated with acquiring and maintaining a yacht, including insurance, crew salaries, marina fees, fuel, and periodic upgrades, pose a significant barrier to market expansion. Larger and more technologically advanced yachts require substantial ongoing expenses, which primarily limit ownership to affluent individuals and make buyers more sensitive to economic conditions. Fluctuations in fuel prices, maintenance costs, and interest rates can further increase the total cost of ownership. As a result, potential customers may choose to charter a yacht or consider fractional ownership instead of purchasing one outright.
The development of specialized yachting infrastructure is creating opportunities for market expansion, especially in emerging coastal destinations and established luxury tourism markets. Investments in modern marinas, yacht clubs, repair yards, fueling facilities, and dedicated berthing spaces can enhance the accessibility and convenience of operating yachts. This, in turn, encourages both ownership and charter activity. Expanding marina capacity is particularly important in destinations experiencing increased yacht arrivals, where limited berthing availability can hinder tourism growth and discourage longer stays.
Infrastructure development can also strengthen the broader yachting ecosystem by supporting maintenance, refitting, crew services, provisioning, and other ancillary activities. When governments and tourism authorities invest in coastal infrastructure, they can attract international yacht owners, charter operators, and marine service providers, fostering a more integrated yachting environment. Enhancements in marina facilities, digital booking systems, shore-side connectivity, and sustainable services—such as electric charging and waste management—can further increase the appeal of emerging destinations. As specialized infrastructure continues to grow, previously underserved cruising regions may become viable markets for yacht ownership, chartering, and marine tourism.
Market Concentration & Characteristics
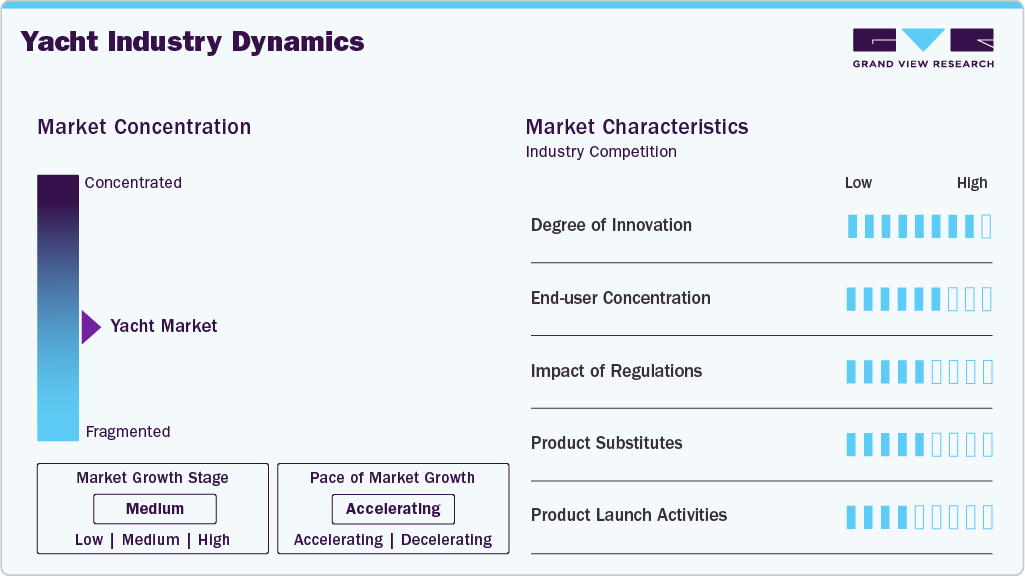
The yacht market features a diverse mix of established international shipbuilders, specialized superyacht yards, and regional manufacturers that cater to different vessel categories and customer segments. Competition in this sector is influenced by factors such as brand reputation, design capabilities, customization, craftsmanship, technology integration, and after-sales services. As buyers increasingly seek vessels tailored to their individual preferences, differentiation has become crucial. For instance, Ferretti Group reported that its Custom Line brand launched four made-to-measure yachts in the first quarter of 2026. This emphasizes the growing significance of bespoke design and owner-specific configurations.
Moreover, the yacht industry is witnessing ongoing product development in areas such as propulsion systems, materials, onboard technology, and vessel design. Manufacturers are investing in hybrid propulsion, energy storage systems, lightweight materials, and digital technologies while maintaining traditional performance and luxury features. Azimut|Benetti reports that over half of Azimut's fleet is equipped with low-emission yachts, and hybrid propulsion systems are available across multiple Benetti yacht families. Ferretti Group's product activities in 2026 also span various luxury yacht segments, with several new launches across its portfolio.
 To learn more about this report, Download Free Sample Report
End-user concentration remains relatively high because yacht purchases and charter activity are concentrated among affluent private owners, charter operators, and luxury hospitality businesses. This concentration increases the importance of personalization, onboard comfort, privacy, and ownership services. Product substitution is comparatively limited because yachts combine private accommodation, mobility, recreation, and luxury travel in a single platform; however, chartering, fractional ownership, and other access-based models can provide alternatives to outright ownership.
Regulatory requirements have a moderate influence on yacht design and operations, particularly regarding maritime safety, emissions, environmental protection, classification, and registration. Compliance requirements vary with vessel characteristics, operating region, and intended use, encouraging manufacturers to incorporate energy efficiency, safety, and environmental considerations into new designs. Product launch activity continues as shipbuilders introduce new models and custom vessels featuring updated layouts, propulsion systems, materials, and onboard technologies. For instance, CRN launched the 70-meter Project Thunderball in June 2026 as a fully bespoke yacht incorporating an energy-storage system for onboard energy management and silent operation at anchor.
Analyst Perspective
The yacht market is evolving as demand for personalized leisure, luxury tourism, and private marine recreation expands across established and emerging markets. Buyers increasingly seek customized vessel designs, amenities, technology, and performance, encouraging manufacturers to offer differentiated products. Advances in propulsion, navigation, connectivity, and energy-efficient technologies are improving operational efficiency and environmental performance. Charter tourism is broadening access to yacht experiences without direct ownership. However, high acquisition and maintenance costs, skilled-labor requirements, and evolving regulations remain key considerations. Long-term market development will depend on customization, design innovation, advanced technologies, and after-sales services while maintaining expected luxury and performance standards.
Type Insights
The super yacht segment accounted for the largest revenue share of 31.3% in 2025, supported by strong demand among high-net-worth individuals and corporate buyers. These vessels, typically ranging from 80 to more than 600 feet, represent the high end of the luxury boating market and are designed around comfort, exclusivity, and extensive customization. Large deck areas, spacious cabins, advanced entertainment systems, swimming pools, Jacuzzis, helipads, and private cinemas are among the features that can be tailored to owner preferences. Powerful propulsion systems further support the performance and cruising requirements associated with these vessels.
The sports segment is expected to grow at the fastest CAGR of 6.1% during the forecast period, supported by rising recreational boating and participation in water-based sports in markets such as China and France. Sport yachts serve multiple purposes, including cruising, fishing, marine tourism, sporting events, and water sports. Their appeal lies in combining yacht-style comfort with the handling and performance characteristics of sports boats. Sleek, aerodynamic hull designs are engineered to reduce drag and improve stability, while onboard spaces such as bedrooms, salons, and galleys provide a more comfortable cruising experience. The combination of performance, functionality, and luxury is supporting demand for sport yachts among recreational users.
Length Insights
The 20-50 m segment dominated the yacht industry, accounting for a revenue share of 57.3% in 2025, and is projected to grow at the fastest CAGR during the forecast period. Demand is increasing due to the growth of yacht charter services and fractional ownership models. Charter operators are increasingly favoring yachts of this size because they offer strong utilization potential and appeal to customers seeking premium experiences at relatively affordable prices. These yachts also have manageable operating requirements, require smaller crews, and offer flexible itineraries, which can lead to more efficient charter operations. Additionally, fractional ownership allows multiple users to share the acquisition and operating costs, reducing the financial and management burdens typically associated with yacht ownership.
The up to 20 m segment is expected to register a significant CAGR of 5.0% during the forecast period, supported by the versatility of smaller yachts for recreational cruising, leisure activities, and competitive use. Sustainability is becoming increasingly important as yacht manufacturers and owners look into renewable energy technologies, such as solar and wind power. The compact size and lower energy needs of these vessels make it easier to incorporate these technologies, which can help reduce fuel consumption and emissions. As interest in more energy-efficient marine transportation grows, we can expect additional opportunities for smaller yacht models.
Propulsion Insights
The motor yacht segment accounted for the largest revenue share of 81.8% in 2025 and is projected to register the fastest CAGR during the forecast period. Motor yachts offer high speed, power, and long-range cruising capabilities, making them ideal for users seeking efficient and versatile maritime experiences. The incorporation of advanced navigation, communication, safety, and onboard entertainment technologies further enhances their appeal. Manufacturers are continually improving propulsion systems and onboard equipment, which boosts performance, comfort, and overall functionality. Consequently, ongoing technological advancements are driving demand in both private ownership and yacht charter markets.
 To learn more about this report, Download Free Sample Report
The sailing yacht segment is projected to register a significant CAGR of 4.3% over the forecast period. Sailing yachts use wind power for propulsion, providing an alternative to engine-dependent cruising that has lower operating costs and a reduced environmental impact. The growing interest in sustainable recreational boating is leading consumers to view sailing yachts as a more environmentally friendly option. Advances in sail technology, rigging systems, and hull design are improving maneuverability and performance while preserving the traditional sailing experience. These developments are increasing the appeal of sailing yachts among both recreational users and environmentally conscious buyers.
Regional Insights
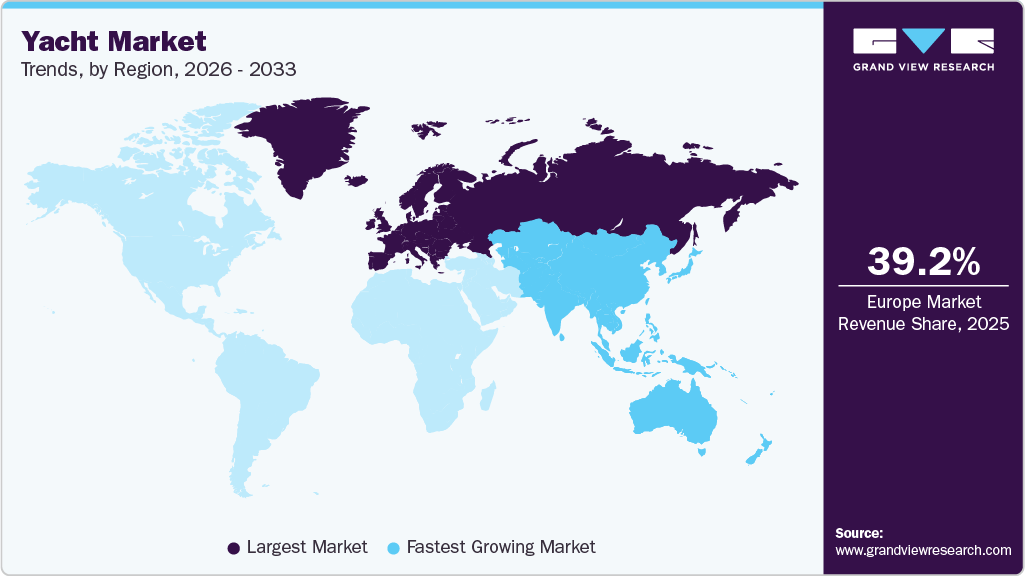
The Europe yacht market held the largest global revenue share of 39.2% in 2025, supported by a strong luxury tourism ecosystem, established maritime infrastructure, and a large base of affluent consumers. Demand is also benefiting from the region’s extensive coastline and the popularity of recreational boating, fishing, and water-based leisure activities. Europe has a well-developed network of marinas, yacht services, shipyards, and maintenance facilities, supporting both yacht ownership and charter activity. Increasing investment in coastal tourism infrastructure and growing interest in more sustainable marine technologies are further shaping the regional market.
 To learn more about this report, Download Free Sample Report
The France yacht market accounted for the largest revenue share in Europe in 2025, supported by its established yacht manufacturing base, maritime heritage, and strong luxury tourism industry. Shipbuilders such as Group Beneteau contribute to the country's manufacturing capabilities, while destinations along the French Riviera, including Cannes, Nice, and Saint-Tropez, attract international yacht owners and charter customers. The availability of premium marinas, maintenance facilities, and specialized marine services further supports market activity. France's established yachting ecosystem also provides a strong foundation for high-value vessels and charter operations.
The yacht market in Italy is expected to grow at the fastest CAGR of 7.0% from 2026 to 2033. The country benefits from a well-established yacht manufacturing industry, supported by shipyards such as Ferretti Group, Azimut|Benetti, and Sanlorenzo, and from strong expertise in luxury design and marine engineering. Italy's extensive coastline and destinations, including the Amalfi Coast, Sardinia, and the Italian Riviera, further support demand from international yacht owners and tourists. Product innovation is also contributing to market development. In February 2026, Benetti launched two 67-meter steel superyachts from its B. Now 67M series, Symmetry and Dagger, featuring hybrid propulsion systems designed to reduce environmental impact, noise, and energy consumption.
The Spain yacht market is expected to grow significantly from 2026 to 2033, supported by its extensive coastline, established marine infrastructure, and strong luxury tourism sector. The Balearic Islands remain an important yachting destination, while high-end marinas, maintenance facilities, and specialized service providers support yacht owners and charter operators. Regulatory developments and continued investment in coastal tourism are also influencing the country's attractiveness for larger vessels. Moreover, fluctuations in economic conditions and competition from other Mediterranean destinations may influence high-value yacht purchases and charter activity. Continued investment in marine infrastructure, service capabilities, and yacht-related tourism is expected to support the country's market development.
Asia Pacific Yacht Market Trends
The Asia Pacific yacht industry is anticipated to grow at the fastest CAGR of 6.3% during the forecast period, supported by rising disposable incomes, expanding luxury tourism, and increasing government investment in tourism infrastructure. Growing affluence is enabling more consumers to allocate spending toward premium leisure activities, including yacht ownership and chartering. In addition, tourism development initiatives are improving the attractiveness and accessibility of coastal destinations across the region. Programs such as India's Incredible India campaign and the Swadesh Darshan Scheme are contributing to broader tourism development and may create additional opportunities for marine leisure activities. Increasing international tourist arrivals and the development of supporting marina infrastructure are expected to further strengthen the regional yachting ecosystem.
The Indonesia yacht market is expected to expand rapidly during the forecast period, supported by the country's extensive archipelago and growing appeal as a luxury marine tourism destination. Indonesia, with over 17,000 islands, offers diverse cruising opportunities, including Raja Ampat and Sulawesi. Rising disposable income and growing interest from international yacht owners are driving demand. Improvements in marina infrastructure and yacht entry procedures enhance accessibility. However, challenges such as bureaucratic hurdles and a lack of specialized marine services persist. Ongoing infrastructure development and regulatory improvements could solidify Indonesia's status as a key destination for yachting and charters.
North America Yacht Market Trends
The North America yacht industry held a significant share in 2025, supported by a strong boating culture, extensive coastlines, and a large base of affluent consumers. The region has a high concentration of ultra-high-net-worth individuals (UHNWIs), supporting demand for customized yachts and premium vessels. Technological advances in navigation, propulsion, onboard systems, and design are also influencing product development, while growing interest in sustainable boating is encouraging the adoption of more efficient technologies. Canada further contributes to regional demand through its extensive cruising areas and expanding base of yacht owners.
The U.S. yacht market is growing at a notable pace, supported by strong domestic demand across luxury and recreational boating segments. The country's large UHNWI population provides a substantial customer base for high-end yachts, while established manufacturers such as Viking and Westport serve diverse ownership and charter requirements. Major yachting destinations, including Florida and California, benefit from extensive coastlines, established marine infrastructure, and favorable conditions for leisure boating. These factors continue to support yacht ownership, charter activity, and related marine services across the U.S.
Key Yacht Company Insights
The yacht market is characterized by competition across vessel size, design, customization, technology, and after-sales services, with established shipbuilders competing to differentiate their offerings for increasingly sophisticated customers. Companies such as Alexander Marine International (AMI) Co., Ltd., Azimut Benetti Group, Damen Shipyards Group, and Feadship are strengthening their positions through investments in vessel design, engineering capabilities, customization, and advanced onboard technologies.
Customization has become an important competitive factor, particularly in the premium and superyacht segments, where buyers increasingly seek distinctive layouts, amenities, and performance characteristics. In addition, manufacturers are incorporating hybrid propulsion, energy-efficient systems, advanced navigation, and digital connectivity to address evolving expectations around performance and sustainability. Strategic partnerships, acquisitions, and collaborations are also being used to expand technical capabilities, enter new customer segments, and strengthen geographic reach. As the market becomes more technology-driven and experience-focused, competitive differentiation is increasingly dependent on the ability to combine luxury design with engineering expertise, operational efficiency, and personalized customer solutions.
Key Yacht Companies
The following key companies have been profiled for this study on the yacht market.
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Mature Players: Azimut|Benetti Group; Ferretti S.p.A.; Sanlorenzo S.p.A.; Sunseeker International Limited
- Market leaders are investing strategically to expand their geographic presence by entering new regional markets and strengthening their foothold by serving regional customers effectively.
- Mature players are exploring opportunities for mergers & acquisitions to broaden their reach and gain a competitive edge in the market.
- Mature players operating in developing economies prioritize providing a diverse range of sustainable water vessels to ensure compliance with regulations aimed at reducing the carbon footprint.
- They are actively contributing to environmental sustainability efforts by offering a wide portfolio of eco-friendly yachts.
- For mature players, managing multiple production facilities can pose significant challenges.
- They can also find it demanding to maintain consistent quality standards across multiple production facilities.
- High capital investments in areas such as R&D, premium materials, skilled labor, compliance, and marketing can present challenges for the market leaders.
Emerging Players: Princess Yachts Limited; Heesen Yachts
- Emerging companies in the market are enhancing customer experience by prioritizing product improvement and after-sales services.
- Emerging players are exploring strategic alliances, collaborations, and partnerships that can deliver added value to their customers.
- Emerging companies are attracting cost-conscious customers by quoting prices lower than those quoted by the market leaders.
- They are utilizing the latest technologies, such as Artificial Intelligence (AI) and analytics, to offer custom vacation packages to enhance customer experience.
- Emerging companies may face challenges related to product quality and customer service due to their limited experience in the industry.
- Restricted marketing budgets can be detrimental to the efforts being pursued by emerging companies to effectively reach a broader audience and compete with established market players.
Recent Developments
-
In July 2026, Sanlorenzo launched SHE, a new yacht model that reinterprets the classic 1960s navetta concept through contemporary design, technology, and craftsmanship. Designed by Zuccon International Project and Piero Lissoni, the model introduces a new concept within Sanlorenzo’s range, with the first five units reportedly sold before its official debut.
-
In June 2026, CRN launched Project Thunderball, a 70-meter fully bespoke steel-and-aluminum displacement superyacht at Ferretti Group’s Superyacht Yard in Ancona. Developed in collaboration with Vripack Yacht Design and Nauta, the project highlights the continued demand for highly customized large yachts that combine bespoke design, advanced engineering, and owner-specific configurations.
-
In March 2026, Nautor Swan began construction of the Swan Alloy 44, its largest sailing yacht to date and the first aluminum yacht in the company's 60-year history. Designed by Malcolm McKeon, the yacht is being developed with a focus on long-range performance and energy autonomy, marking Nautor Swan’s entry into the large aluminum sailing yacht segment.
-
In March 2026, Van der Valk launched the 39.92-meter MY Shine, formerly Project EVO, at its Waalwijk facilities. The fully custom aluminum superyacht is the shipyard’s largest yacht to date and combines a fast-displacement hull with owner-specific design requirements, demonstrating continued demand for bespoke yachts in the 30-45-meter segment.
-
In February 2026, Silent Yachts and Luxe Elite Yachts partnered to introduce a professionally managed co-ownership model for solar-electric yachts, initially using the Silent 62 3-Deck Open. The four-share structure provides each owner with 10 weeks of annual usage while Luxe Elite manages operations, maintenance, and crew, creating a lower-commitment ownership model for electric yachts.
Yacht Market Report Scope
Report Attribute
Details
Market size in 2025
USD 10.3 billion
Estimated market size in 2026
USD 10.9 billion
Projected market size by 2033
USD 15.5 billion
Growth rate
CAGR of 5.2% from 2026 to 2033
Actual data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, length, propulsion, region
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; China; Japan; India; Indonesia; Australia; Brazil; KSA; UAE; South Africa
Key companies profiled
Alexander Marine International (AMI) Co., Ltd.; Azimut Benetti Group; Damen Shipyards Group; Feadship; Ferretti S.p.A.; Heesen Yachts; Princess Yachts Limited; Sanlorenzo S.p.A.; Sunseeker International Limited; Lürssen
Customization scope
Free report customization (equivalent to 8 analyst working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Yacht Market Report Segmentation
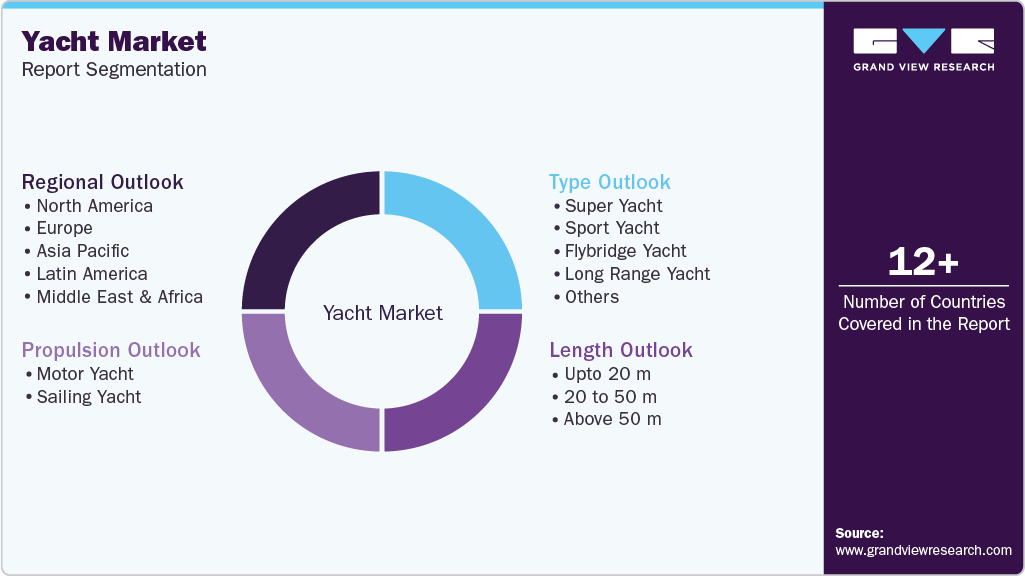
This report forecasts revenue growth and provides an analysis of the latest trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the yacht market report based on type, length, propulsion, and region:
 To learn more about this report, Download Free Sample Report
-
Type Outlook (Revenue, USD Million/Billion, 2021 - 2033)
-
Super Yacht
-
Sport Yacht
-
Flybridge Yacht
-
Long Range Yacht
-
Others
-
-
Length Outlook (Revenue, USD Million/Billion, 2021 - 2033)
-
Up to 20 m
-
20 to 50 m
-
Above 50 m
-
-
Propulsion Outlook (Revenue, USD Million/Billion, 2021 - 2033)
-
Motor Yacht
-
Sailing Yacht
-
-
Regional Outlook (Revenue, USD Million/Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
Japan
-
India
-
Indonesia
-
Australia
-
-
Latin America
-
Brazil
-
-
Middle East and Africa (MEA)
-
KSA
-
UAE
-
South Africa
-
-
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Yacht Market Opportunity Analysis
Country/region-wise analysis of yacht demand, marina infrastructure development, and luxury tourism trends
Assessment of high-net-worth individual (HNWI) population growth, yacht ownership patterns, and charter industry expansion
Identification of emerging luxury boating destinations and regional investment opportunities
Identified region-specific growth opportunities
Supported market entry and dealership expansion strategies
Enabled informed investment and production planning decisions
Yacht Market Volume Analysis
Analysis of yacht market volume by yacht type, size category, propulsion type, and region
Historical and forecast volume assessment of yacht production, deliveries, and charter fleet expansion
Evaluation of volume demand trends across private luxury ownership and commercial yacht tourism sectors
Enabled detailed demand and supply assessment across regional markets
Supported production capacity planning and inventory management strategies
Provided actionable insights for long-term market forecasting and operational decision-making
Competitive Benchmarking and Strategic Positioning in the Yacht Market
Benchmarking of major yacht manufacturers based on product portfolio, yacht size categories, customization capabilities, pricing, and sustainability initiatives
Comparative analysis of technological advancements, hybrid propulsion systems, partnerships, and global distribution networks
Evaluation of competitive strengths, market gaps, and differentiation opportunities
Identified competitive white spaces and premium segment opportunities
Supported strategic positioning and brand differentiation initiatives
Enabled data-driven competitive intelligence and long-term growth strategy development
Frequently Asked Questions About This Report
The global yacht market size was estimated at USD 10.3 billion in 2025 and is expected to reach USD 10.9 billion in 2026.
The global yacht market is expected to grow at a compound annual growth rate of 5.2% from 2026 to 2033, reaching USD 15.5 billion by 2033.
The super yacht segment dominated the global market with a revenue share of 31.3% in 2025. This is due to their high popularity among UHNWIs who desire luxury and exclusivity.
The 20-to-50-meter length segment dominated the yacht market in 2025, with a revenue share of 57.3%. Furthermore, it is expected to remain dominant over the forecast period due to lower maintenance costs, wind sailing capabilities, and shallower draft requirements.
The motor yacht segment accounted for the largest revenue share in the yacht market in 2025. The growth can be attributed to the benefits offered by these yachts, including the high speed and power, and large distance coverage, among others.
Europe dominated with a revenue share of 39.2% in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
The motor yacht segment led with the largest revenue share in 2025.
Some prominent players in the yacht market include Alexander Marine International (AMI) Co., Ltd., Azimut Benetti Group, Damen Shipyards Group, Feadship, Ferretti S.p.A., Heesen Yachts, Princess Yachts Limited, Sanlorenzo S.p.A., Sunseeker International Limited, and Lürssen.
About the Author(s)
Automotive & Transportation Research Team
Technology · Automotive & TransportationThis report was authored by the automotive & transportation research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the automotive & transportation segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


