
- Home
- »
- Paints, Coatings & Printing Inks
- »
-
Zinc Oxide Market Size, Share & Growth Report, 2026-2033GVR Report cover

Zinc Oxide Market (2026 - 2033)
Size, Share & Trends Analysis Report By Form (Powder, Pellets), By Process (Indirect, Direct, Wet Chemical, Others), By Application (Automotive, Cosmetics and Personal Care, Paints & Coatings), By Region, And Segment Forecasts
Market Size, 2025
$6.1BMarket Estimate, 2026
$6.4BMarket Forecast, 2033
$9.9BCAGR, 2026–2033
6.3%Zinc Oxide Market Size & Trends
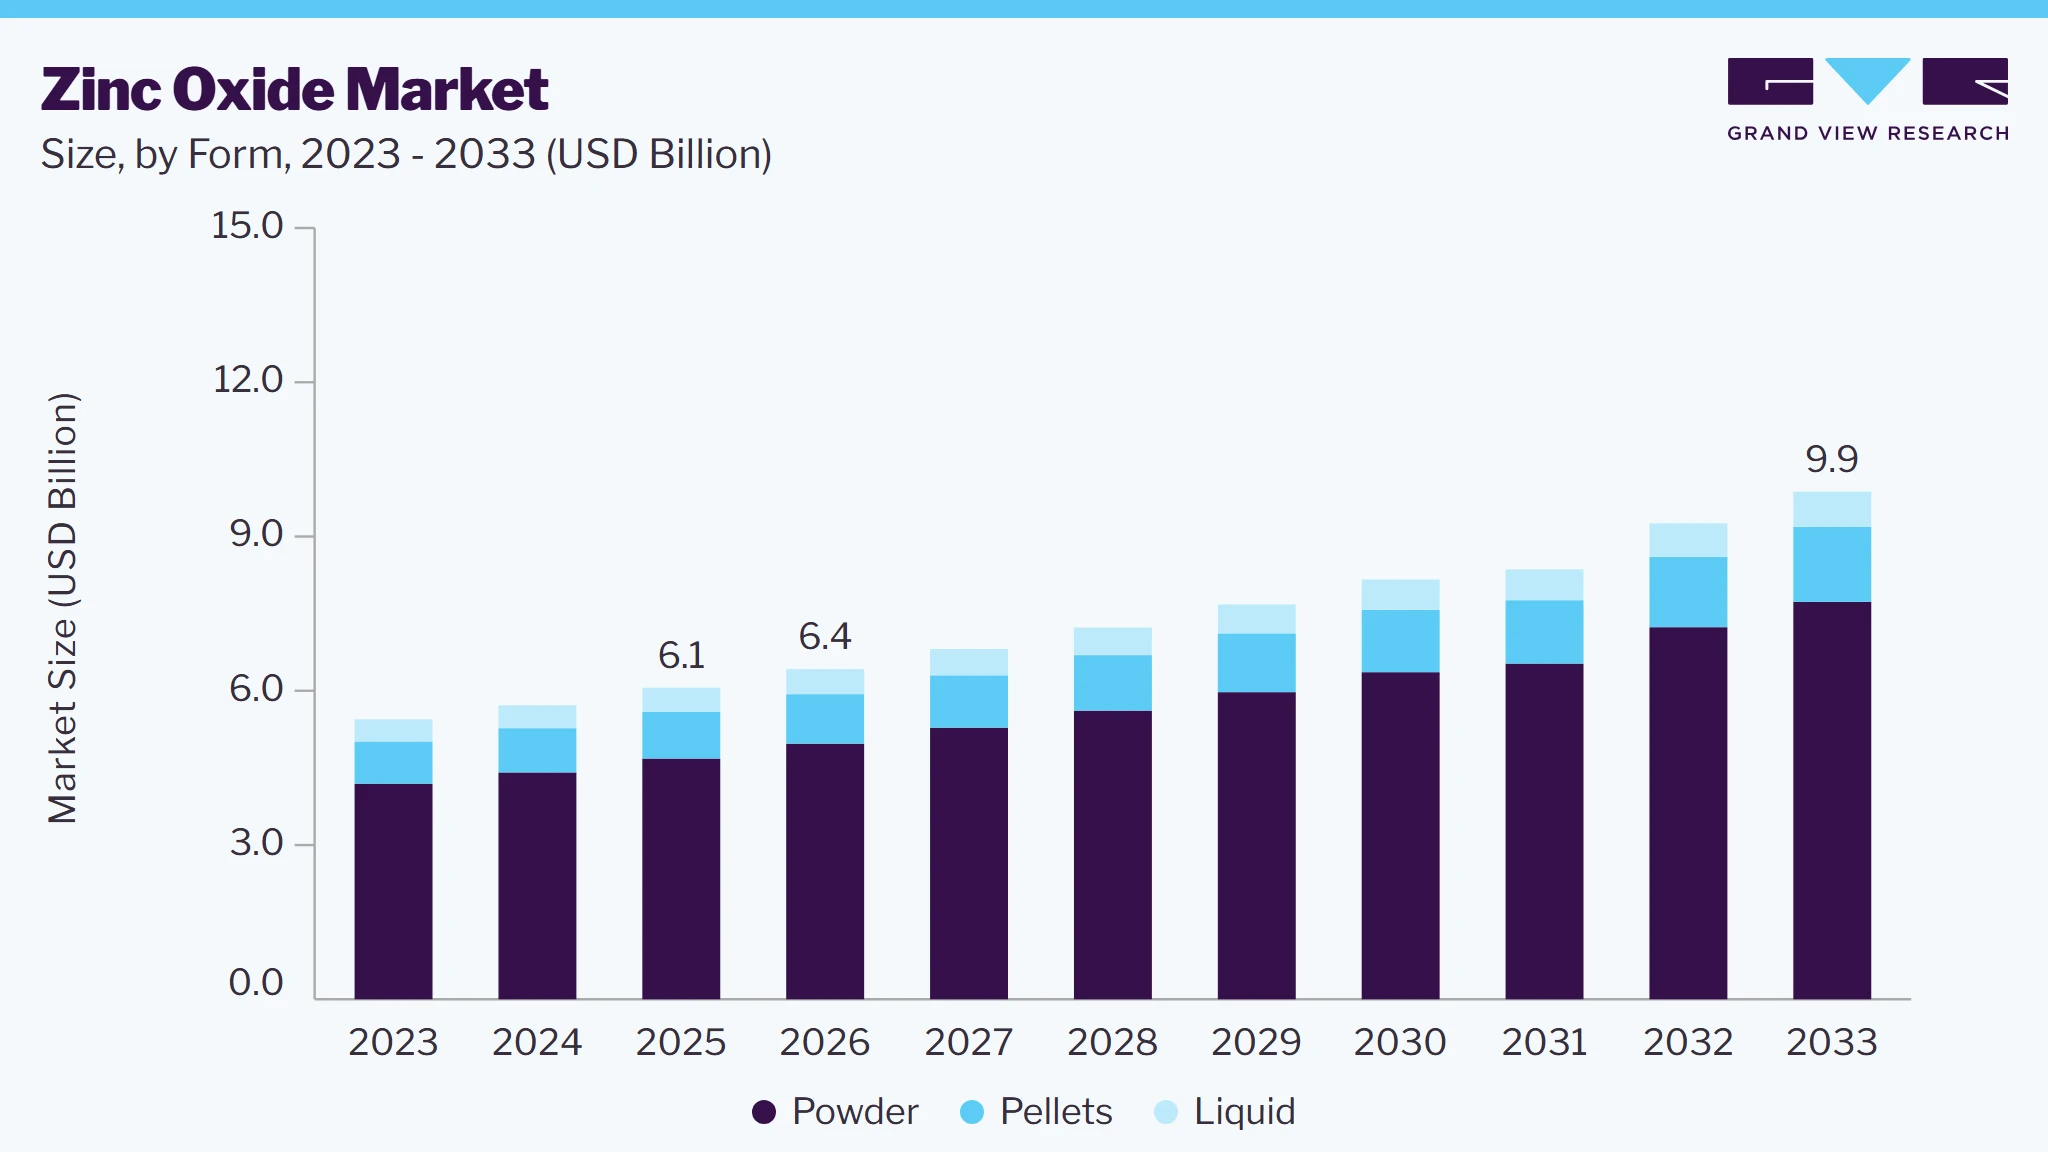
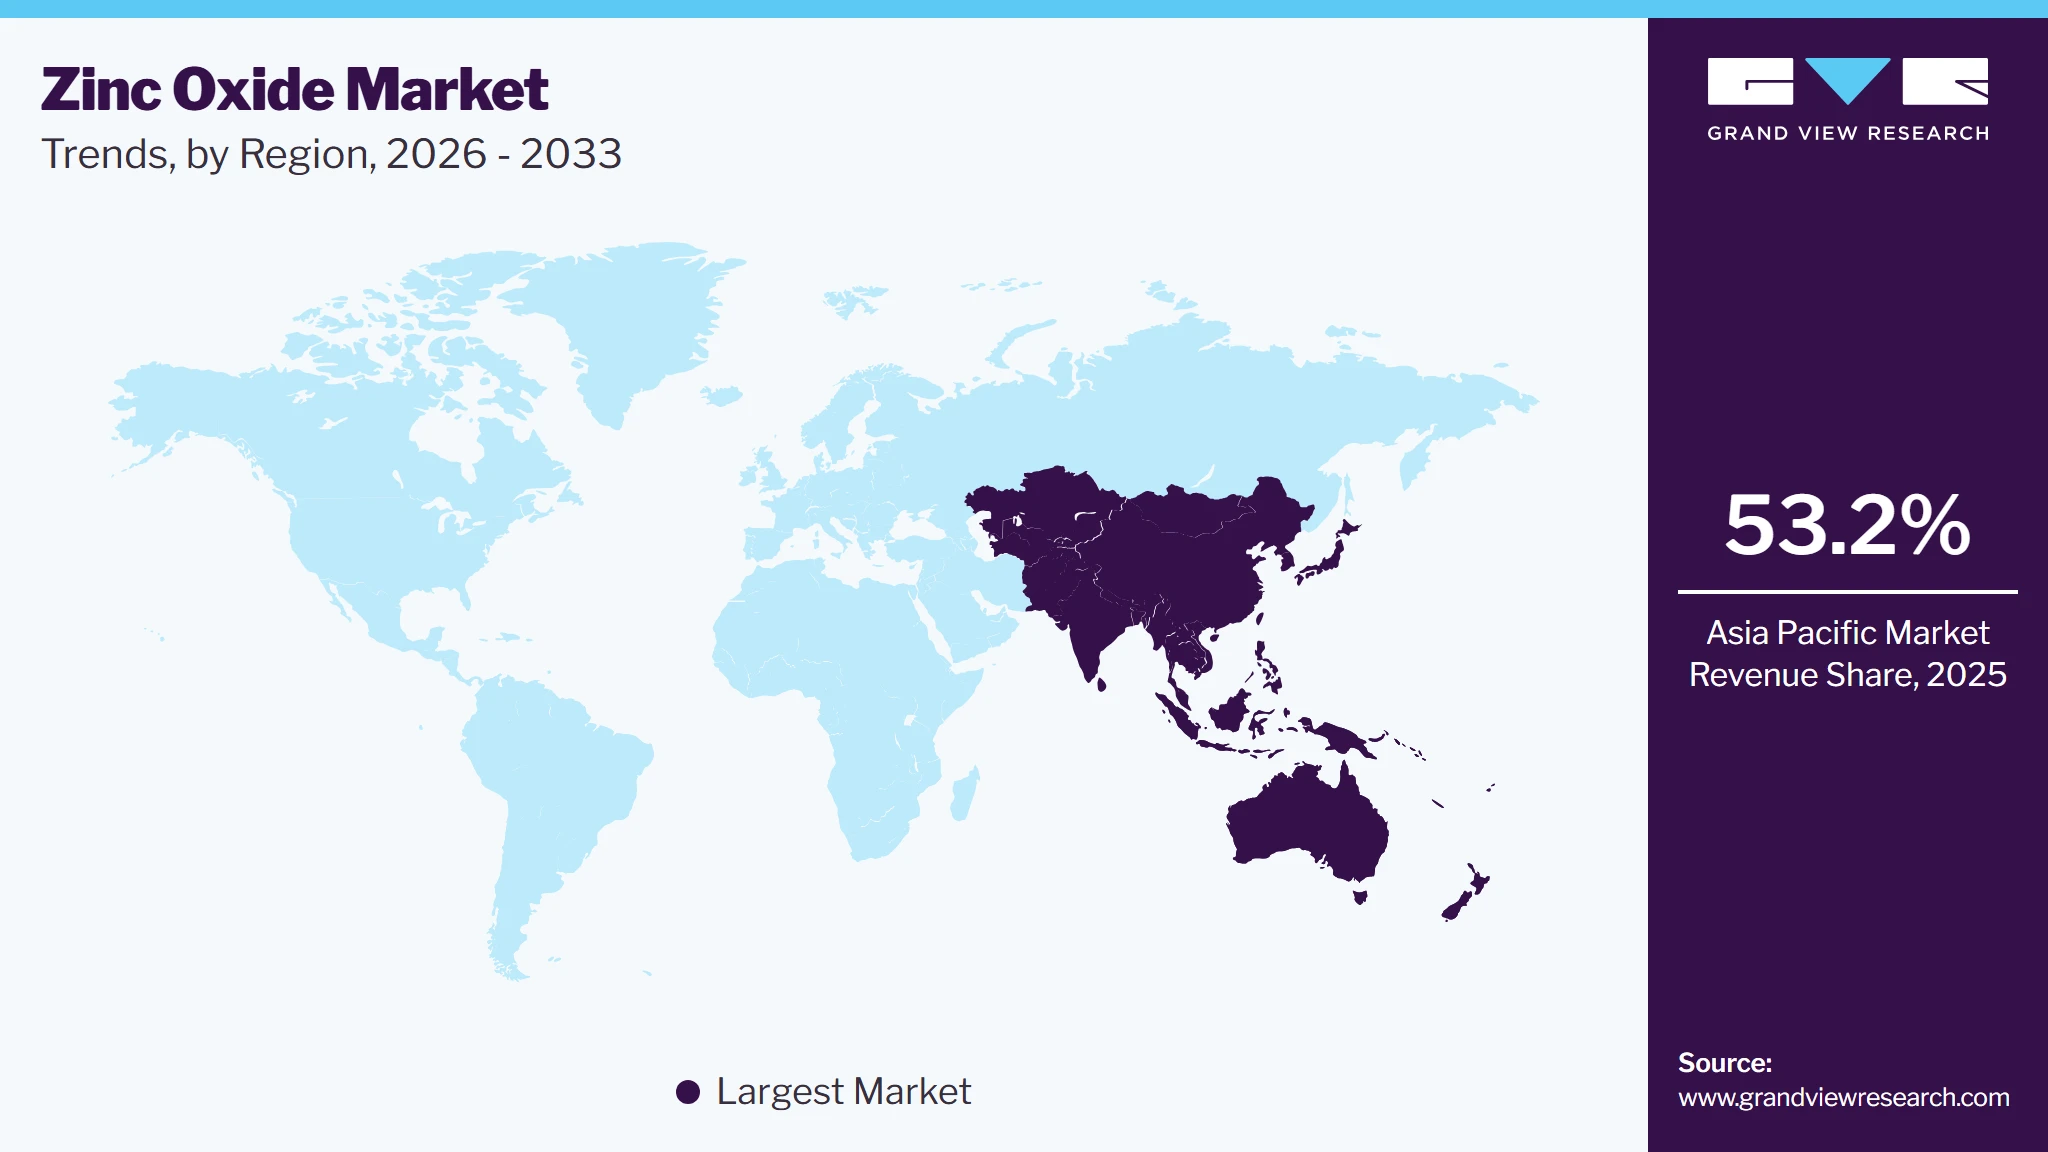
The global zinc oxide market size was valued at USD 6.1 billion in 2025 and is projected to grow from USD 6.4 billion in 2026 to USD 9.9 billion by 2033, at a CAGR of 6.3% from 2026 to 2033. Asia Pacific accounted for 53.2% of the zinc oxide market revenue in 2025, making it the largest regional market. This is attributable to its excessive use in rubber during the process of vulcanization, which is the prime component in tires for the automotive industry.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By form: Powder segment held the largest market share of 77.3% in 2025.
- By process: Indirect segment held the largest market share of 80.7% in 2025.
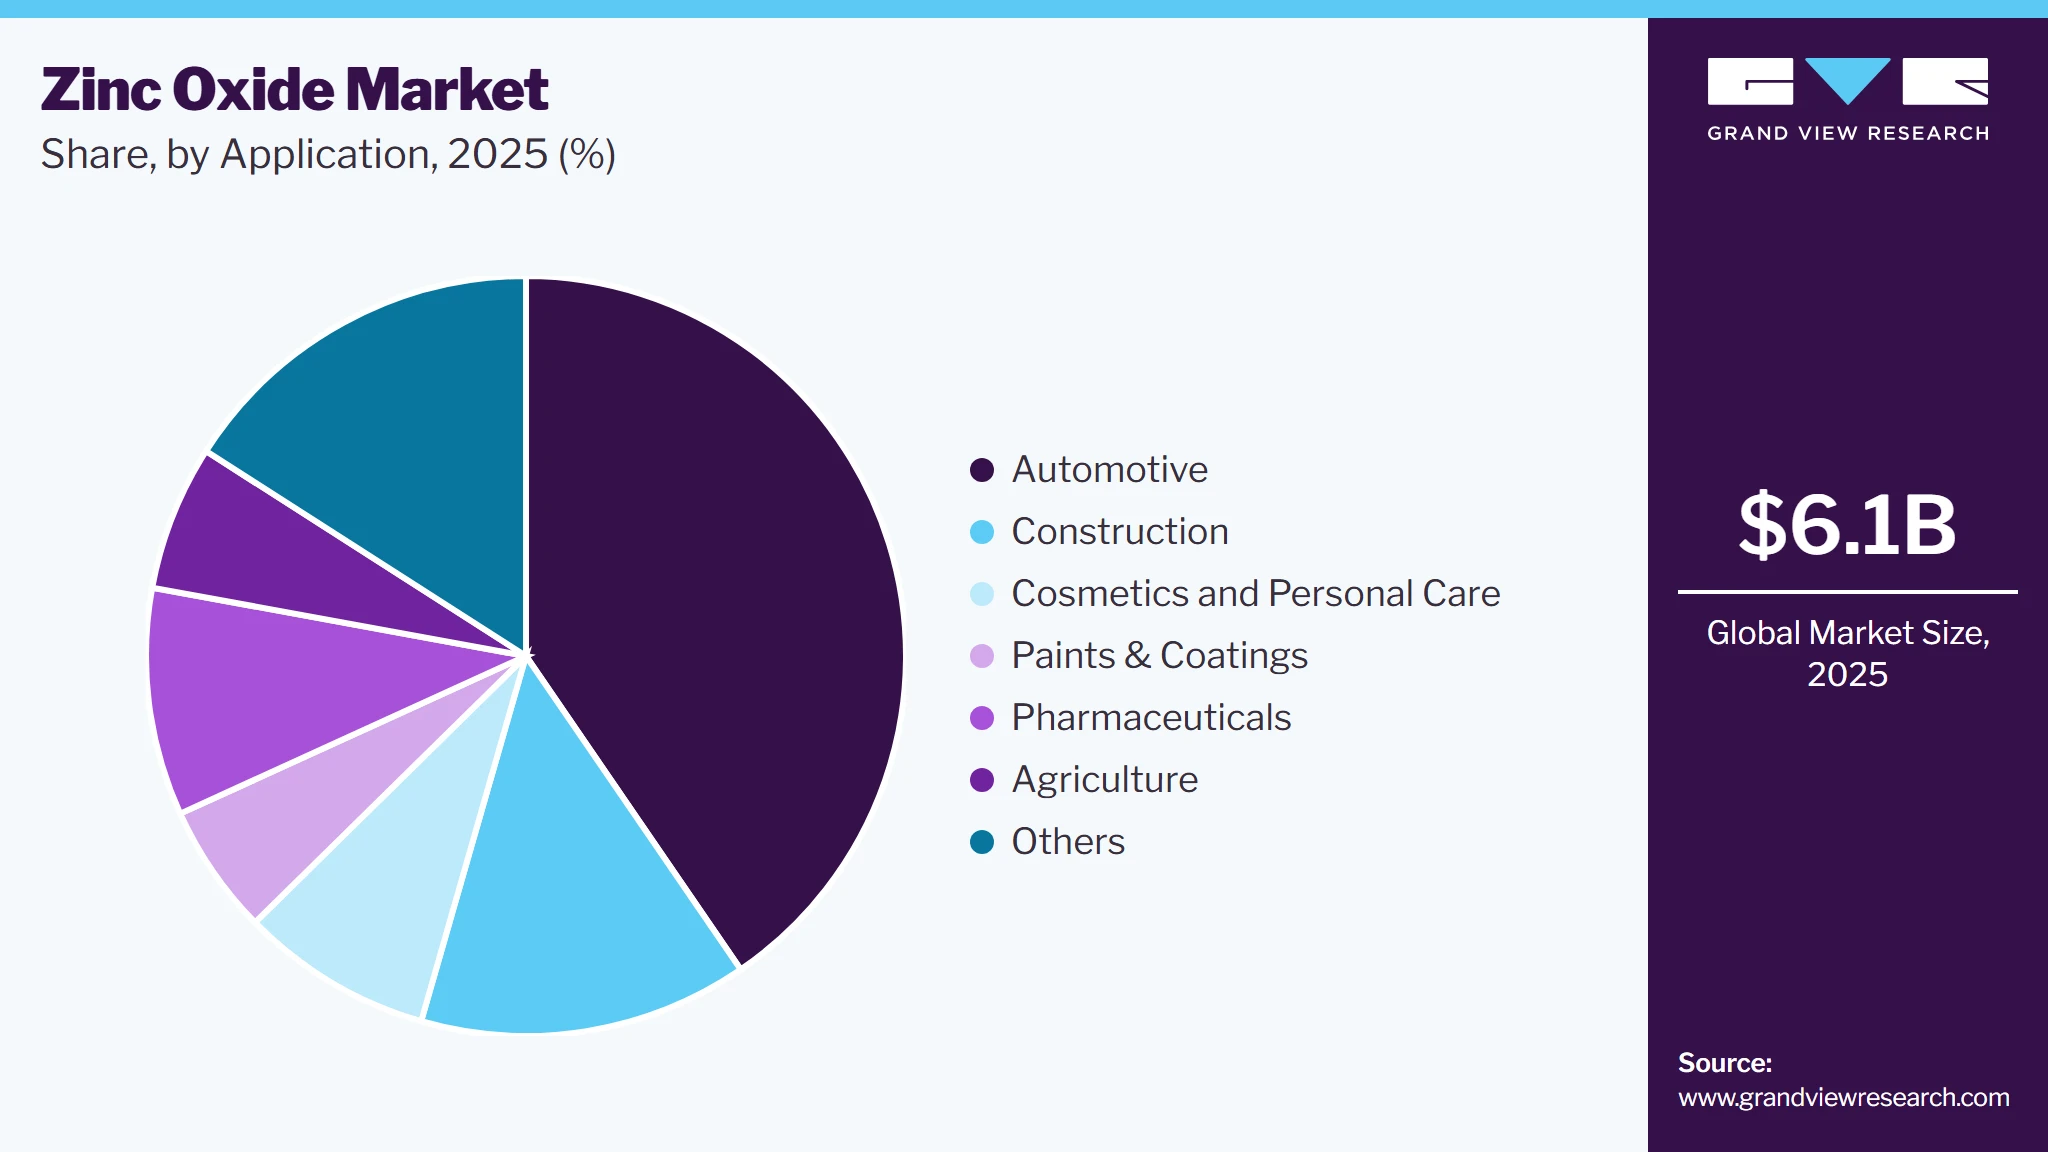
- By application: Automotive segment held the largest market share of 40.4% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (53.2% revenue share, 2025)
- By country: China held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 6.1 Billion
- Estimated market size in 2026: USD 6.4 Billion
- Projected market size by 2033: USD 9.9 Billion
- CAGR (2026-2033): 6.3%
Prism AI by Grand View Research Free to tryAsk a question about the zinc oxide marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →The growth of the automotive industry is directly proportional to the growth of the tire industry as around 75% of the rubber produced across the globe is used in tire production. The tires, wiper blades, and engine mounts are usually manufactured from rubber. Ceramics, particularly the tile industry, is the second largest application of zinc oxide. Both French (indirect) and American (direct) processes are suitable for these applications. The product finds its application in ceramics to reduce their melting temperature and energy and equipment requirements. Glass and ceramics have been used for manufacturing structural components for construction projects. Ceramic materials including porcelain, brick, and cement are commonly used to construct buildings. There has been an increasing trend to use nanomaterials in modern construction to improve the performance of construction materials.
 To learn more about this report, Download Free Sample Report
According to Oxford Economics, the global construction industry was valued at USD 10.7 trillion in 2020 and is predicted to reach USD 13.3 trillion by 2025. Additionally, the output of the construction industry in Asia Pacific is expected to reach USD 7.4 trillion while North America is predicted to reach USD 2.4 trillion by 2030. The growing number of mega infrastructure projects in the emerging economies of Asia Pacific, such as India and China, is likely to boost the growth of the construction industry thereby driving the demand for the product market in the coming years.
The growing research and development activities to develop production technologies with low carbon and high output muffle furnace is likely to offer growth opportunities from the sustainability perspective. For instance, Zochem is using its expertise to install a new state-of-the-art French process technology with high output and low carbon footprint design. Furthermore, key manufacturers are actively involved in increasing the production capacities in order to cater to the increasing demand from end-use industries.
Market Dynamics
The zinc oxide market is driven by expanding demand across the automotive, construction, cosmetics, pharmaceuticals, and agricultural industries. Increasing tire production and the growing adoption of high-performance rubber compounds continue to strengthen consumption, as zinc oxide serves as a critical activator in rubber vulcanization. Rising investments in infrastructure development and protective coatings further support market expansion through increased use in paints, ceramics, and construction materials. The market is also benefiting from heightened demand for mineral-based UV protection and skin care formulations, supported by evolving consumer preferences for safe and effective personal care ingredients. However, fluctuations in zinc raw material prices and stringent environmental regulations governing mining and manufacturing activities create cost pressures for producers. Despite these challenges, advancements in high-purity production technologies, sustainable manufacturing practices, and specialty-grade product development are opening new growth opportunities.
The increasing production of automobiles and replacement tires worldwide remains one of the primary growth drivers for the zinc oxide market. Zinc oxide plays a vital role as a vulcanization activator in rubber manufacturing, improving elasticity, tensile strength, heat resistance, and overall durability of rubber compounds. As automotive manufacturers continue to focus on producing high-performance, fuel-efficient, and longer-lasting tires, the demand for high-quality zinc oxide has grown substantially. In addition to passenger vehicles, expanding commercial transportation, industrial machinery, and off-road equipment manufacturing continue to generate sustained demand for rubber components incorporating zinc oxide.
The growing emphasis on electric vehicles (EVs) further strengthens market prospects, as EV tires require enhanced wear resistance, load-bearing capacity, and thermal stability to accommodate heavier battery systems and higher torque. Manufacturers are increasingly investing in advanced rubber formulations that improve rolling resistance and operational efficiency, supporting greater consumption of specialty-grade zinc oxide.
The zinc oxide market faces challenges due to fluctuations in zinc prices, which directly influence production costs and profit margins across the value chain. Since zinc metal is the primary raw material used in manufacturing zinc oxide, changes in mining output, energy costs, geopolitical uncertainties, trade policies, and supply-demand imbalances frequently result in unpredictable pricing. At the same time, manufacturers must comply with increasingly stringent environmental regulations related to mining activities, emissions control, waste management, and workplace safety. Meeting these regulatory requirements often necessitates investments in cleaner production technologies, pollution control systems, and operational upgrades, increasing capital and operating expenditures. These combined cost pressures are particularly challenging for small and medium-sized producers, limiting pricing flexibility and affecting competitiveness in price-sensitive end-use markets.
The growing demand for high-purity zinc oxide in pharmaceutical, cosmetic, and personal care applications presents a significant opportunity for market participants. Consumers are increasingly seeking mineral-based, skin-friendly ingredients in sunscreens, dermatological formulations, baby care products, and therapeutic creams, encouraging manufacturers to expand production of premium-grade zinc oxide. Regulatory acceptance of zinc oxide as a safe and effective UV-filter ingredient in numerous markets further supports its adoption across high-value personal care formulations.
Beyond traditional applications, technological advancements in purification processes are enabling manufacturers to develop zinc oxide grades with superior particle size control, purity, and performance characteristics for specialized healthcare and biomedical uses. Increasing research into antimicrobial coatings, wound-care materials, drug delivery systems, and functional medical products is creating additional avenues for product innovation. Companies investing in advanced manufacturing capabilities and value-added specialty formulations are well positioned to capitalize on these emerging opportunities while strengthening their competitive differentiation in the global zinc oxide market.
Analyst Perspective
The zinc oxide market is supported by sustained demand from the automotive, rubber, construction, and personal care industries. Increasing investments in high-performance materials and specialty-grade zinc oxide are enabling manufacturers to move toward higher-value applications. While volatility in zinc prices and tightening environmental regulations remain key challenges, advancements in production technologies and sustainable manufacturing practices are strengthening market resilience. Asia Pacific continues to dominate both production and consumption due to its strong industrial base and expanding manufacturing sector. Companies that focus on product innovation, operational efficiency, and strategic capacity expansion are expected to strengthen their competitive position over the forecast period.
Form Insights
Powder segment dominated the form segment with a market share of 77.3% in 2025. This is attributable to its increasing use in different applications such as batteries, lubricants, friction materials, gold extraction, silver extraction, spray galvanizing, and others.
Zinc oxide powder is primarily used to provide UV and corrosion protection in paints and as a catalyst in chemical processes. A very fine zinc oxide powder consists of irregular particles of around 4 to 10 microns. It is also used to manufacture zinc-rich paint formulations and chemicals such as sodium hydrosulfite, zinc phosphide, and others. Powdered ZnO is predominantly used across various industries.
ZnO pellets are made from high-purity (>99.995%) super high-grade zinc. They are an intermediate product between the dome and half ball in terms of size. These pellets can also be used in alkaline caustic potash or caustic soda baths without or with external dissolution tanks.
Liquid ZnO also finds applications in sun care and after-sun products, mineral makeup, and anti-aging skin care products. It has the ability to block wavelengths from 280 to 400 nm for UVB and UVA protection. Liquid product form helps formulators to create a high-performing anti-aging skin care and color cosmetic products.
Process Insights
Indirect segment dominated the process segment with a market share of 80.7% in 2025. This is attributable to its properties as it is considered the fastest and most productive method of production. The quality of ZnO manufactured depends upon the type of zinc used in the process. For example, special high-grade with 99.99% zinc concentration is used for the production of gold seals or pharmaceutical-grade, whereas ordinary with 99.95% concentration is adequate to produce zinc for the rubber industry. The maximum yield of ZnO from 1 ton of special high-grade zinc is 1.2 tons.
The direct or the American process is less preferred by industry players and involves the use of feedstock containing oxidized zinc-containing raw material. This process involves the initial production of zinc by reduction of zinc ore by heating with coal followed by oxidation of zinc in a similar way used in the indirect process. This process provides a less purified form of ZnO and the high-grade requirement of pharmaceutical applications is a major challenge for this process.
Some of the other processes used in the production of products involve spray pyrolysis, hydrometallurgical method, mechanochemical method, and chemical synthesis method. In the spray pyrolysis, a solution of thermally decomposable zinc bearing salt is used. The mechanochemical process is an inexpensive and straightforward way to produce nanoparticles on a large scale, but a key challenge with this method is uniformly grinding the powder and reducing the grains to the necessary size. This process involves high-energy dry milling at lower temperatures followed by the addition of thinner to form the nano particles.
Application Insights
Automotive segment projected the largest share of 40.4% in 2025. This is attributed to the growth of the tire industry as most of the rubber produced is used in automobiles of the manufacturing of the tire. ZnO is used in the vulcanization of rubber. It is also used as a cross-linking or curing agent for halogen-containing elastomers like polysulfides and neoprene.
 To learn more about this report, Download Free Sample Report
Ceramics, particularly the tile industry, is the second largest application of the product. Properties such as low coefficient of expansion, high heat capacity, high-temperature stability, and thermal conductivity of ZnO are suitable for producing ceramics.
ZnO in small amounts provides a glossy surface to the ceramic while the addition of moderate amounts of zinc oxide provides a matte finish. ZnO improves the elasticity of glazes by lowering the change in viscosity as a function of temperature thereby preventing shivering and crazing.
Zinc oxide is widely used in the personal care & cosmetics industry as a broad-spectrum UV absorber. It is used in several cosmetic products including foundations, moisturizers, lip products, face powders, lotions & hand creams, and ointments. ZnO attenuates UV radiation effectively in both UVA (320–400 nm) and UVB range (290–320 nm). It can be used as an ingredient in dry deodorants for reducing wetness under the arm between a concentration of 0.05 and 10% by weight with average particle size ranging from 0.02 to 200 microns. Other applications of ZnO nanoparticles in the personal care & cosmetics industry include nappy rash creams, anti-dandruff shampoos, and others.
Regional Insights
Asia Pacific accounted for 53.2% of the zinc oxide market revenue in 2025, making it the largest regional market. This is attributed to the advancing automobile, construction, and personal care & cosmetics industries in India, China, Japan, and South Korea. Moreover, the growing pharmaceutical industry is anticipated to drive the demand for ZnO owing to its anti-inflammatory, antiseptic, drying, and ultraviolet protection properties. China held the highest market revenue share of the Asia Pacific in 2025.
 To learn more about this report, Download Free Sample Report
According to the India Brand Equity Foundation, the pharmaceuticals industry in India meets over 50% of the global demand for different vaccines making it the third-largest pharmaceuticals industry worldwide. According to the Indian Economic Survey, the domestic pharmaceuticals market in India stood at USD 42 billion in 2021 which is further anticipated to reach USD 65 billion by the end of 2024.
Key Companies & Market Share Insights
The global zinc oxide market is fragmented with domestic and international players operating globally. A few of the prominent players in the product market are EverZinc, Rubamin Zinc Nacional, Ace Chemie Zynk Energy Limited, Lanxess, and Tata Chemicals Ltd. These players accounted for around 12% of the market share whereas the other small and domestic manufacturers capture the remaining market.
Domestic companies such are Zochem are involved in increasing their production capacities in order to expand their product offerings and eventually increase their market share. Whereas, players like EverZinc are involved in merger and acquisition activities to meet the high demand for zinc oxide from the end-use industries. Some prominent players in the global zinc oxide market include:
Key Zinc Oxide Companies
The following key companies have been profiled for this study on the zinc oxide market.
-
Ace Chemie Zynk Energy Limited
-
AG CHEMI GROUP s.r.o.
-
CCL
-
EverZinc
-
Zinc Nacional
-
HAKUSUI TECH
-
LANXESS
-
IEQSA
-
Neo Zinc Oxide
-
Pan-Continental Chemical Co., Ltd.
-
Rubamin
-
Tata Chemicals Ltd.
-
TOHO ZINC CO., LTD.
-
TP Polymer Private Limited
-
Upper India
-
Weifang Longda Zinc Industry Co., Ltd.
-
Yongchang zinc industry Co., Ltd.
-
Zinc Oxide Australia
-
Zochem, Inc
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (EverZinc, Zinc Nacional, LANXESS, Rubamin, Tata Chemicals Ltd., TOHO ZINC CO., LTD., Zochem, Inc., HAKUSUI TECH, Pan-Continental Chemical Co., Ltd., IEQSA)
- Invest in large-scale manufacturing facilities to achieve economies of scale and ensure reliable product availability.
- Develop high-purity and specialty zinc oxide grades for diverse end-use industries, including pharmaceuticals, cosmetics, and electronics.
- Strengthen global market presence through established distribution networks, subsidiaries, and long-term supply agreements.
- Continuously improve production efficiency through process optimization, automation, and sustainability initiatives.
- Strong brand reputation supported by decades of manufacturing expertise and customer trust.
- Extensive production capacities backed by advanced manufacturing technologies and integrated supply chains.
- Broad product portfolios addressing both commodity and specialty application requirements.
- Robust financial resources that support continuous R&D, capacity expansion, and international growth.
- High manufacturing and environmental compliance costs reduce operational flexibility.
- Significant exposure to fluctuations in zinc raw material prices and energy costs.
- Complex organizational structures can slow strategic decision-making and product commercialization.
- Premium pricing may limit competitiveness in highly cost-sensitive regional markets.
Emerging & Regional Players (Ace Chemie Zynk Energy Limited, AG CHEMI GROUP s.r.o., CCL, Neo Zinc Oxide, TP Polymer Private Limited, Upper India, Weifang Longda Zinc Industry Co., Ltd., Yongchang Zinc Industry Co., Ltd., Zinc Oxide Australia)
- Focus on regional markets and niche applications with customized zinc oxide solutions.
- Expand customer reach through distributor partnerships, contract manufacturing, and strategic collaborations.
- Maintain flexible production capabilities to address specialized customer requirements efficiently.
- Compete through cost-effective offerings, responsive technical support, and faster product development.
- Agile business models enable quick responses to changing customer needs and market trends.
- Lower organizational complexity supports faster operational and commercial decisions.
- Strong understanding of local market dynamics and customer requirements.
- Competitive pricing strategies improve penetration in developing and price-sensitive markets.
- Limited production capacities compared to established multinational manufacturers.
- Lower brand visibility reduces access to large global procurement opportunities.
- Restricted R&D investments may slow the development of advanced specialty products.
- Greater dependence on regional demand and third-party distribution channels increases business risk.
Zinc Oxide Market Report Scope
Report Attribute
Details
Market size in 2025
USD 6.1 billion
Estimated market size in 2026
USD 6.4 billion
Projected market size by 2033
USD 9.9 billion
Growth rate
CAGR of 6.3% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Form, process, application, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; U.K.; France; Italy; Spain; Netherlands; Belgium; China; India; Japan; South Korea; Vietnam; Brazil; Argentina; Peru; Saudi Arabia; South Africa
Key companies profiled
Ace Chemie Zynk Energy Limited; AG CHEMI GROUP s.r.o.; CCL; EverZinc; Zinc Nacional; HAKUSUI TECH; LANXESS; IEQSA; Neo Zinc Oxide; Pan-Continental Chemical Co., Ltd.; Rubamin; Tata Chemicals Ltd.; TOHO ZINC CO., LTD.; TP Polymer Private Limited; Upper India; Weifang Longda Zinc Industry Co., Ltd.; Yongchang zinc industry Co., Ltd.; Zinc Oxide Australia; Zochem, Inc
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Zinc Oxide Market Report Segmentation
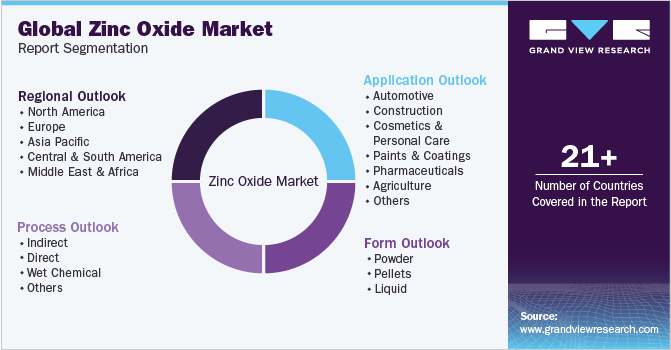
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global zinc oxide market report based on form, process, application, and region:
 To learn more about this report, Download Free Sample Report
-
Form Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Powder
-
Pellets
-
Liquid
-
-
Process Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Indirect
-
Direct
-
Wet Chemical
-
Others
-
-
Application Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Automotive
-
Construction
-
Cosmetics and Personal Care
-
Paints & Coatings
-
Pharmaceuticals
-
Agriculture
-
Others
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
U.K.
-
France
-
Italy
-
Spain
-
Netherlands
-
Belgium
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Vietnam
-
-
Central & South America
-
Brazil
-
Argentina
-
Peru
-
-
Middle East & Africa
-
Saudi Arabia
-
South Africa
-
-
Research Methodology
The zinc oxide market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each zinc oxide segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment – Form
Revenue capture definition
Powder
Includes revenue generated from powdered zinc oxide supplied for rubber compounding, ceramics, chemicals, pharmaceuticals, cosmetics, and coatings, where high dispersibility and consistent purity are essential.
Pellets
Represents income derived from pelletized zinc oxide manufactured for automated material handling and controlled industrial processing, minimizing dust generation while improving operational efficiency.
Liquid
Covers revenue from liquid zinc oxide dispersions and suspensions incorporated into coatings, personal care formulations, specialty chemicals, and agricultural products requiring uniform distribution and formulation stability.
Segment – Process
Revenue capture definition
Indirect
Captures revenue from zinc oxide produced through the indirect (French) process, delivering high-purity material for demanding applications including rubber, cosmetics, pharmaceuticals, and electronic components.
Direct
Represents sales generated from zinc oxide manufactured using the direct (American) process, primarily serving rubber goods, ceramics, glass, fertilizers, and general industrial applications requiring cost-effective production.
Wet Chemical
Includes revenue from chemically synthesized zinc oxide offering controlled particle size and enhanced purity for specialty formulations in healthcare, electronics, catalysts, and advanced functional materials.
Other Processes
Covers income from zinc oxide produced through alternative manufacturing technologies, including customized synthesis routes developed to meet application-specific performance and quality requirements.
Segment – Application
Revenue capture definition
Automotive
Includes revenue generated from zinc oxide used in tire manufacturing, rubber components, brake systems, lubricants, and automotive coatings to improve durability, processing performance, and product reliability.
Construction
Represents income derived from zinc oxide incorporated into cement additives, sealants, ceramics, protective coatings, adhesives, and construction chemicals to enhance durability and weather resistance.
Cosmetics and Personal Care
Covers revenue from zinc oxide supplied for sunscreens, skin protection creams, baby care products, cosmetics, and personal hygiene formulations requiring UV protection and skin-soothing properties.
Paints & Coatings
Captures revenue from zinc oxide utilized in industrial, architectural, marine, and protective coating formulations to improve corrosion resistance, opacity, mildew resistance, and long-term coating performance.
Pharmaceuticals
Includes revenue generated from pharmaceutical-grade zinc oxide used in topical ointments, medicated creams, wound-care products, dermatological preparations, and medicinal formulations.
Agriculture
Represents sales generated from zinc oxide incorporated into animal feed supplements, micronutrient fertilizers, crop nutrition products, and veterinary formulations to support healthy plant and livestock development.
Other Applications
Covers income from zinc oxide supplied to electronics, ceramics, glass manufacturing, chemical processing, batteries, catalysts, and other industrial sectors requiring specialized functional materials.
Estimation Model
Layer No.
Layer Name
Key Question
Description
01
Zinc Oxide Production Layer
What forms is the supply base?
Identify the global production capacity of zinc oxide by evaluating zinc smelting infrastructure, manufacturing processes (indirect, direct, wet chemical, and other technologies), raw material availability, refining capabilities, product grade development, packaging formats, and production capacities across major manufacturing hubs.
02
Application Adoption Layer
Where are zinc oxide utilized?
Estimate the distribution of zinc oxide demand across automotive, construction, cosmetics and personal care, paints & coatings, pharmaceuticals, agriculture, and other industrial applications by analyzing manufacturing activity, product penetration, regulatory requirements, technological developments, and end-use industry expansion across key regional markets.
03
Consumption Intensity Layer
How much zinc oxide is consumed?
Assess zinc oxide consumption across major end-use industries by evaluating tire and rubber production, coating and ceramic manufacturing, pharmaceutical output, cosmetic formulation volumes, agricultural input utilization, and industrial processing requirements to estimate annual demand across leading geographic markets.
04
Revenue Layer
How is market revenue generated?
Market revenue is generated through the sale of zinc oxide in powder, pellet, and liquid forms, manufactured using indirect, direct, wet chemical, and other production processes, and supplied to automotive, construction, cosmetics, paints & coatings, pharmaceutical, agricultural, and industrial customers through direct sales, OEM partnerships, distributors, and specialty chemical supply networks worldwide.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional segmentation
The study delivers detailed country-level analysis across key zinc oxide production and consumption markets. It evaluates manufacturing capacity, zinc smelting infrastructure, end-use industry demand, raw material availability, import-export trends, regulatory landscape, and regional growth outlook.
Enables effective market expansion by identifying high-growth countries, production hubs, demand patterns, supply chain dynamics, and investment opportunities across major regions.
Competitive Benchmarking
Comparative assessment of leading zinc oxide manufacturers based on product portfolio, production technologies, manufacturing capacity, geographic presence, distribution network, sustainability initiatives, R&D capabilities, strategic partnerships, and recent business developments.
Supports competitive decision-making by highlighting technological capabilities, product differentiation, operational excellence, market positioning, and long-term strategic advantages of leading industry participants.
Opportunity Assessment
Comprehensive evaluation of emerging growth opportunities driven by increasing tire production, expanding personal care and pharmaceutical applications, infrastructure development, advanced ceramics, electronics manufacturing, and demand for high-purity zinc oxide products.
Assists strategic planning by identifying fast-growing application segments, evolving industry requirements, innovation potential, emerging end-use sectors, and attractive investment avenues for sustainable business growth.
Frequently Asked Questions About This Report
Powder segment dominated the form segment with a market share of 77.3% in 2025. Its dominance is attributed to its excellent dispersibility, high purity, ease of processing, and widespread use across rubber manufacturing, paints & coatings, pharmaceuticals, cosmetics, and agricultural applications.
Indirect segment dominated the process segment with a market share of 80.7% in 2025. The segment's leadership is attributed to its ability to produce high-purity zinc oxide with superior consistency, making it the preferred manufacturing route for rubber, cosmetics, pharmaceutical, and other high-value industrial applications.
Automotive segment projected the largest share of 40.4% in 2025. Rising global tire production, increasing vehicle manufacturing, and growing demand for high-performance rubber compounds continue to drive zinc oxide consumption across the automotive industry.
Asia Pacific is the fastest growing region with a CAGR of 6.9% in the forecast period. Growth is driven by expanding tire manufacturing, rapid industrialization, increasing infrastructure investments, and rising demand for zinc oxide across rubber, construction, cosmetics, and electronics industries, particularly in China, India, Japan, and Southeast Asia.
Asia Pacific accounted for 53.2% of the zinc oxide market revenue in 2025, making it the largest regional market. The region's dominance is supported by robust tire and rubber manufacturing, expanding industrial production, increasing infrastructure development, and the strong presence of leading zinc oxide manufacturers, particularly in China and India.
Some key players operating in the zinc oxide market include Ace Chemie Zynk Energy Limited; AG CHEMI GROUP s.r.o.; CCL; EverZinc; Zinc Nacional; HAKUSUI TECH; LANXESS; IEQSA; Neo Zinc Oxide; Pan-Continental Chemical Co., Ltd.; Rubamin and others.
The zinc oxide market is primarily driven by increasing demand from the tire and rubber industry, where it is extensively used as a vulcanization activator to enhance product performance. Growth in construction, paints and coatings, cosmetics, pharmaceuticals, and agriculture, coupled with rising demand for high-purity zinc oxide in specialty applications, is further supporting market expansion.
The global zinc oxide market size was estimated at USD 6.1 billion in 2025 and is expected to reach USD 6.4 billion in 2026.
The global zinc oxide market is expected to grow at a compound annual growth rate of 6.3% from 2026 to 2033 to reach USD 9.9 billion by 2033.
About the Author(s)
Paints, Coatings & Printing Inks Research Team
Bulk Chemicals · Paints, Coatings & Printing InksThis report was authored by the paints, coatings & printing inks research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the paints, coatings & printing inks segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


