
- Home
- »
- Organic Chemicals
- »
-
1,4 Butanediol Derivatives Market Size Report, 2026-2033GVR Report cover

1,4 Butanediol Derivatives Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product By Application (THF, GBL, Spandex, PBT, PTMEG, NMP, NVP, PVP, PBS, PBAT), By Region (North America, Europe, Asia Pacific, Latin America, MEA), And Segment Forecasts
Market Size, 2025
$33.0BMarket Estimate, 2026
$35.1BMarket Forecast, 2033
$64.3BCAGR, 2026–2033
9.0%1,4 Butanediol Derivatives Market Summary
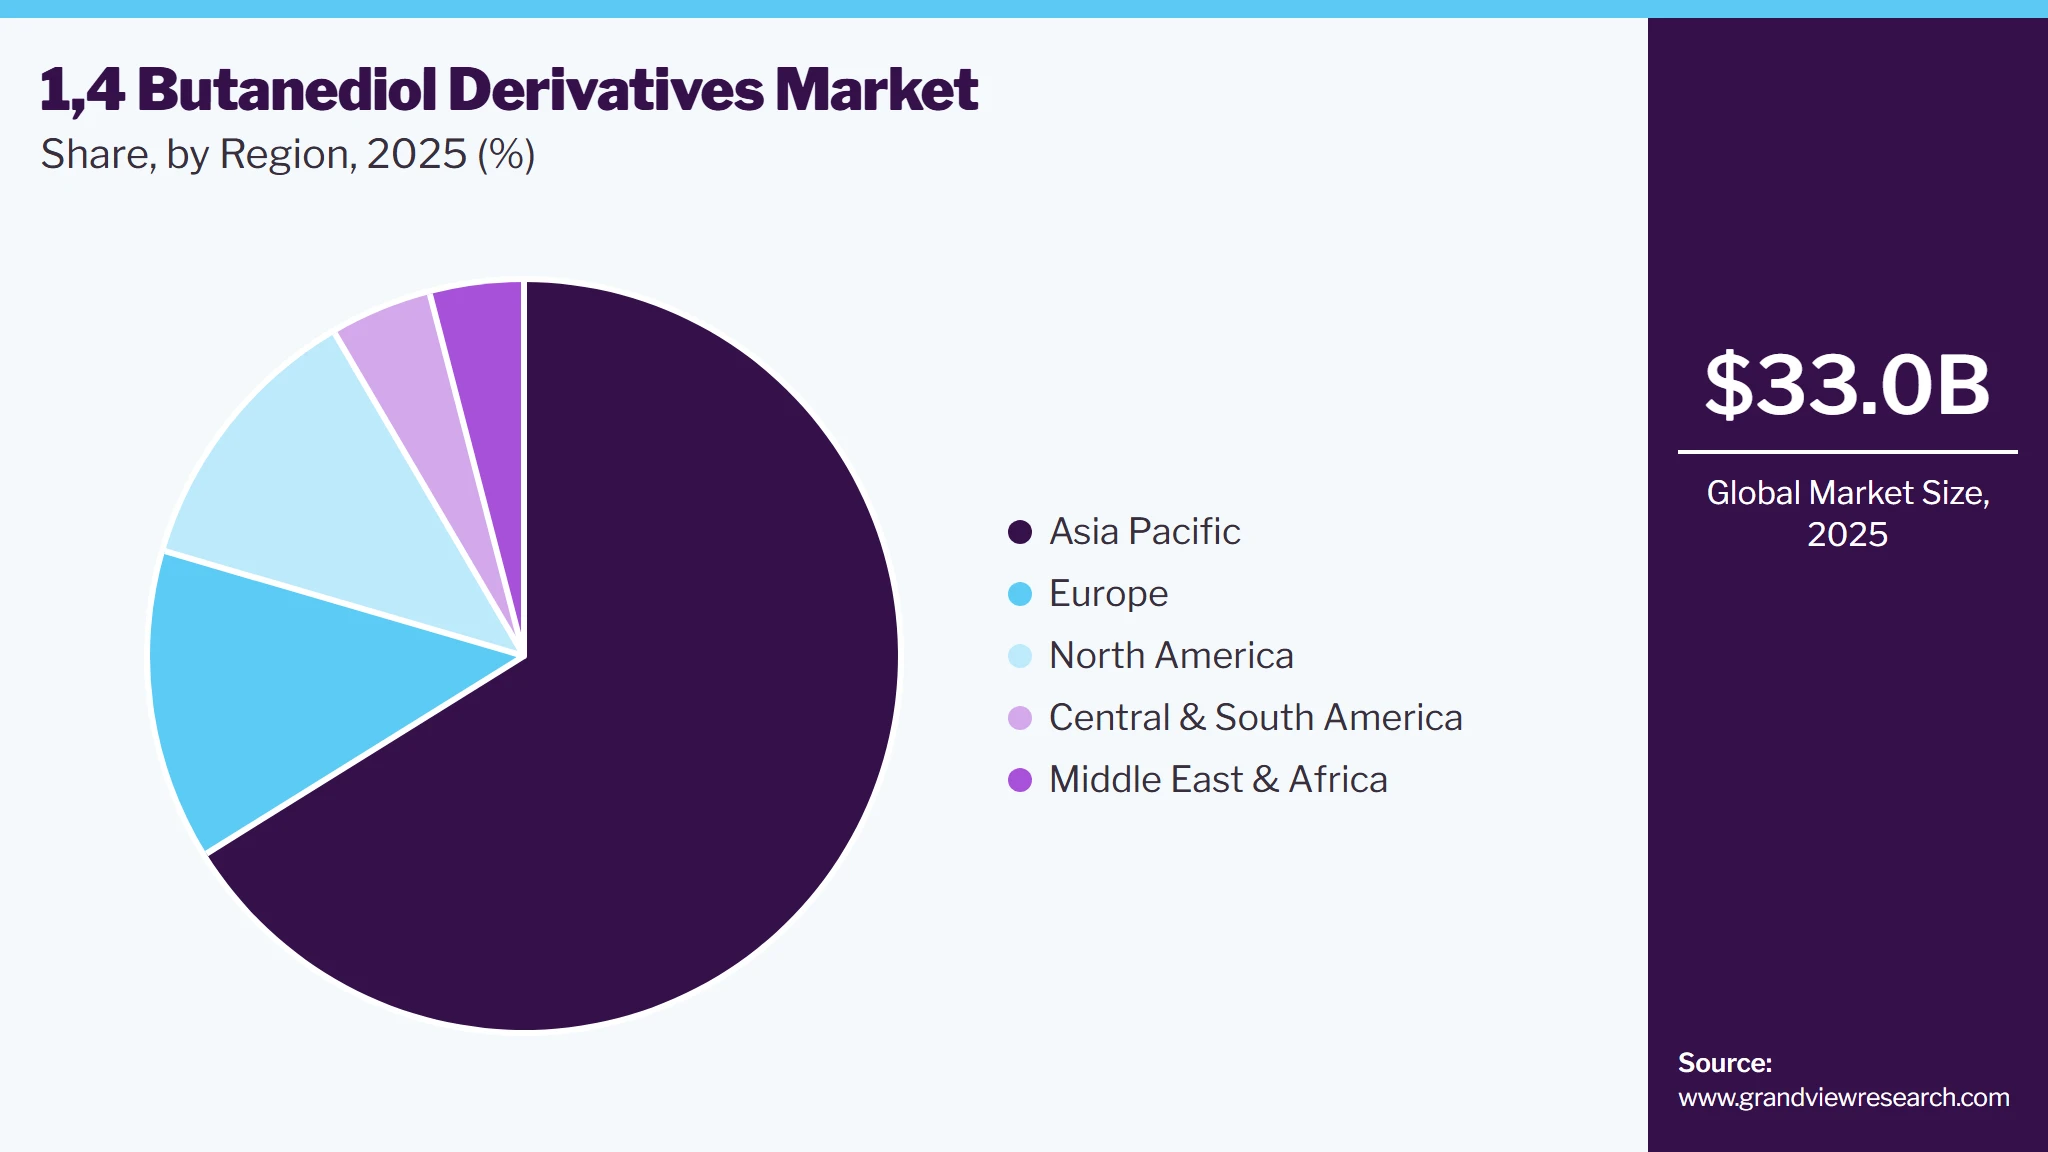
The global 1,4 butanediol derivatives market size was valued at USD 33.0 billion in 2025 and is projected to grow from USD 35.1 billion in 2026 to USD 64.3 billion by 2033, at a CAGR of 9.0% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 65.3% in 2025. The wide application scope of 1,4-butanediol derivatives in various industries, such as electronics, clothing, pharmaceuticals, and packaging, contributes to their popularity.
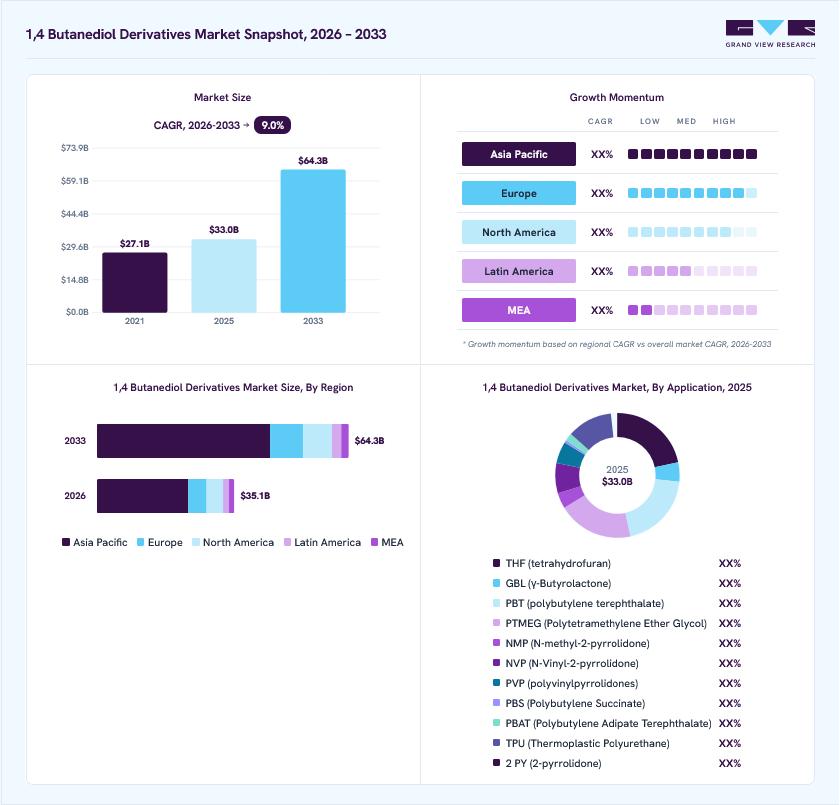 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product by application: Spandex segment dominated the market, with a revenue share of 24.6% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (66.1% revenue share, 2025)
- By country: China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 33.0 Billion
- Estimated market size in 2026: USD 35.1 Billion
- Projected market size by 2033: USD 64.3 Billion
- CAGR (2026-2033): 9.0%
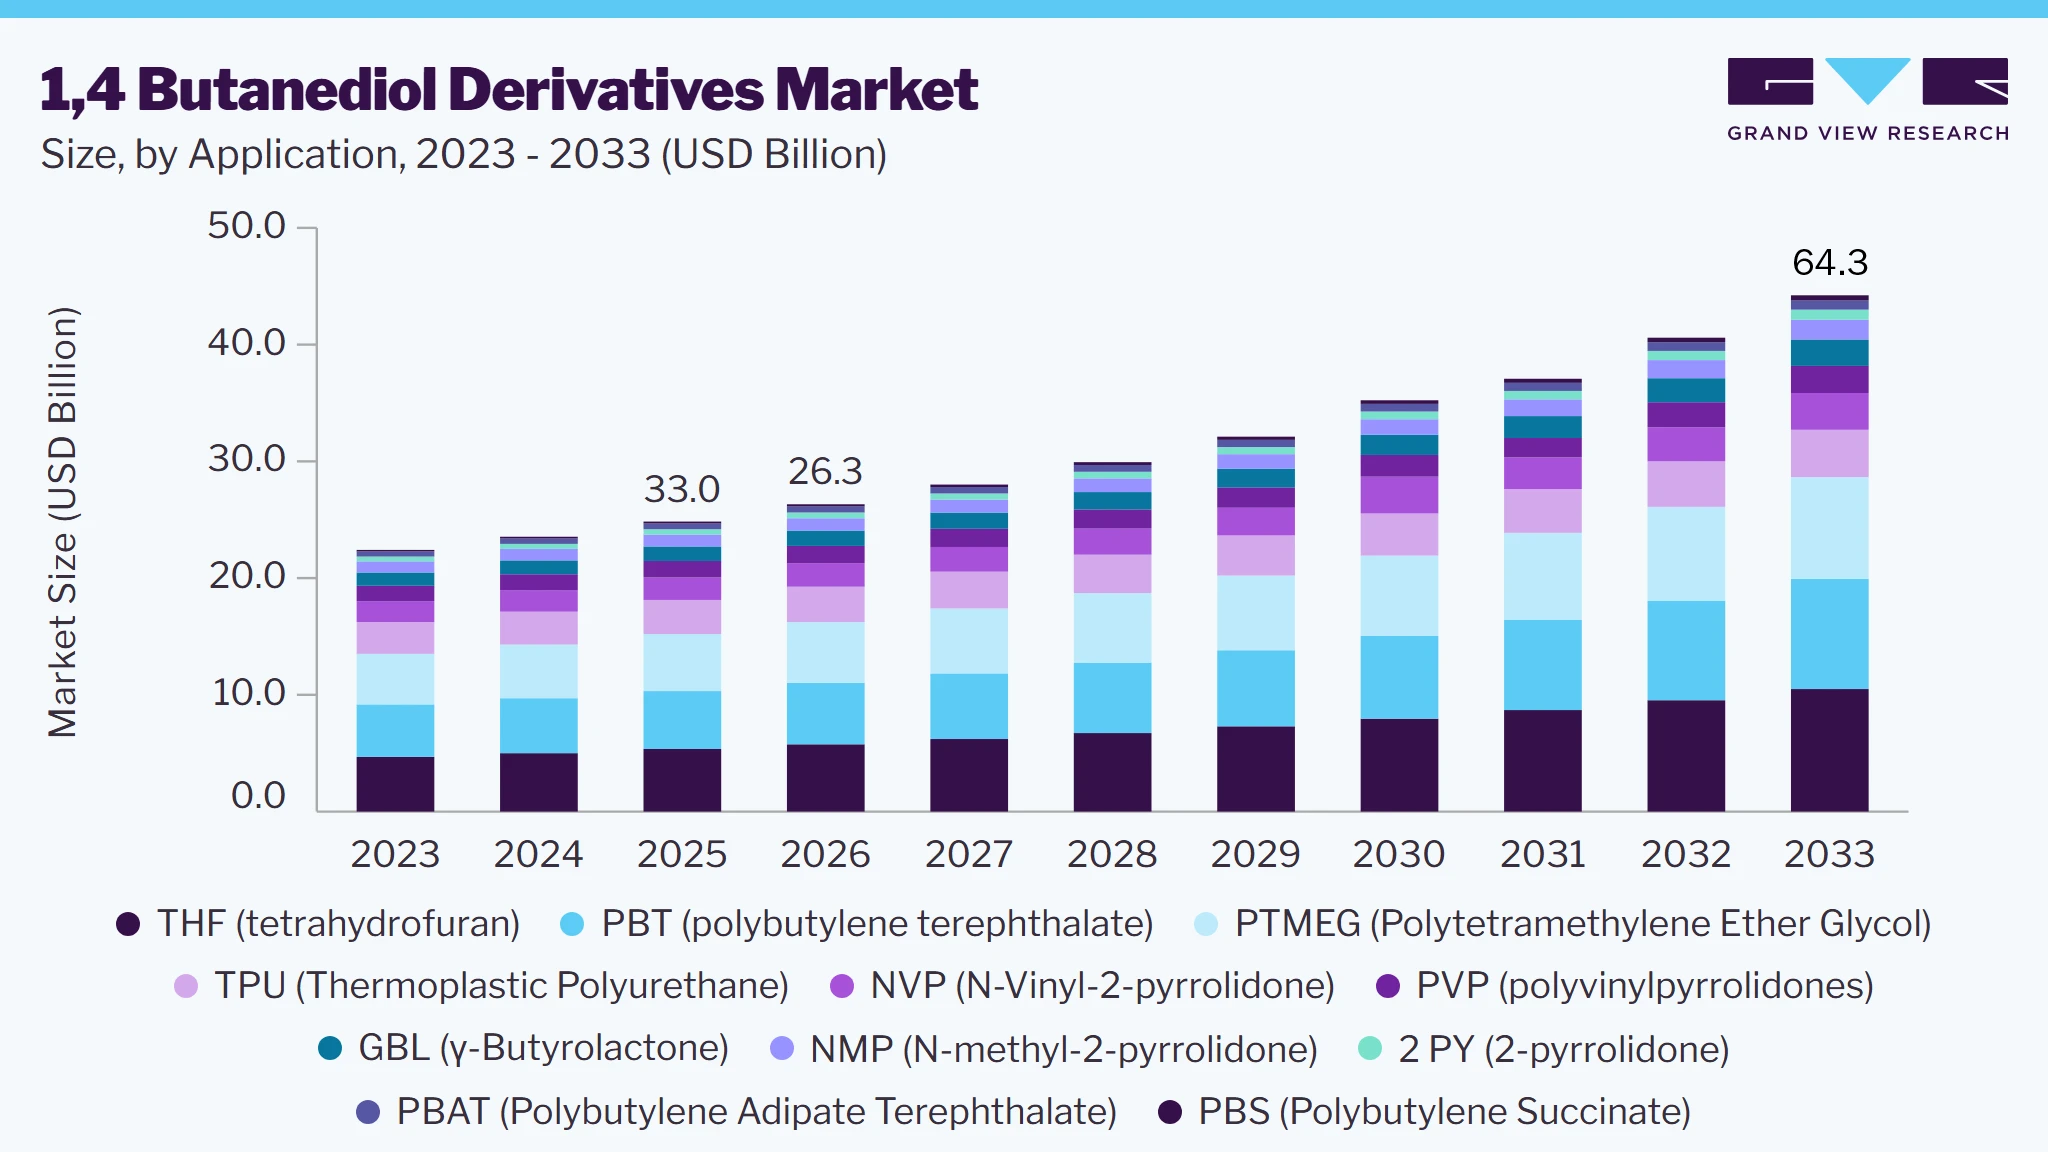
Prism AI by Grand View Research Free to tryAsk a question about the 1,4 butanediol derivatives marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →This rise in automobile production is driven by a growing population and increasing disposable income. As a result, consumers have greater purchasing power, leading to a surge in luxury buying behavior, particularly in rapidly developing countries such as China, India, several European nations, and Japan. Butylene glycol (BDO) is also used to produce solvents and PTMEG, which is essential for manufacturing spandex and polyurethanes. In emerging markets such as India, the electronics industry is rapidly developing due to the growing demand for electronic products and supportive government initiatives such as Make in India and Digital India. These initiatives are complemented by including a beneficial foreign direct investment policy and favorable policies, for electronics manufacturing. As a result, the expanding market for electronic goods is expected to increase the demand for PBT (Polybutylene Terephthalate), which will, in turn, elevate the demand for BDO derivatives in the coming years, driving overall market growth.
 To learn more about this report, Download Free Sample Report
The production of BDO involves the conversion of feedstock into 1, 4-butanediol through chemical processes. This includes reactions such as hydrogenation, catalytic reduction, or other suitable methods. Some of the key manufacturers of 1, 4-butanediol are BASF SE, Ashland, Mitsubishi Chemical Group, SINOPEC, and Evonik Industries AG. To produce 1, 4 Butanediol, numerous machines and equipment are used such as evaporators, gas-liquid stirred tank reactors, hydrolysis reactors, and melt crystallization apparatus. The production facilities can range from large-scale petrochemical plants to smaller specialty chemical plants, depending on the demand and application requirements.
The refined 1, 4 Butanediol product is then used in the manufacturing of its derivatives such as THF, GBL, Spandex, PTMEG, PBT, NMP, NVP, and PBAT among others. Johnson Matthey, a manufacturing company engaged in the production of 1, 4 Butanediol is also integrated at two levels as it undertakes the production of its derivatives as well by undertaking various processes such as esterification. Other companies which are forward integrated are BASF SE, and Ashland. The other prominent manufacturers of BDO derivatives are SABIC, Dow, SSB Polymers, Valco Group, Silver Fern Chemicals, and Capital Resin Corporation.
Market Dynamics
The 1,4-butanediol (BDO) derivatives market is primarily driven by rising demand for high-performance polymers, engineering plastics, elastomers, solvents, and specialty chemicals across automotive, textiles, electronics, packaging, and construction industries. Increasing consumption of downstream derivatives such as tetrahydrofuran (THF), polytetramethylene ether glycol (PTMEG), polybutylene terephthalate (PBT), gamma-butyrolactone (GBL), and polyurethane intermediates continues to support market expansion. Technological advancements in bio-based BDO production, growing investments in electric vehicles, and increasing adoption of sustainable materials are reshaping the competitive landscape. However, fluctuations in feedstock prices, stringent environmental regulations, and evolving sustainability requirements continue to influence production economics and investment decisions across the value chain.
Growing demand for spandex fibers in apparel, sportswear, medical textiles, and industrial fabrics is one of the primary drivers of the 1,4-butanediol derivatives market. THF produced from BDO serves as the key feedstock for PTMEG, which is the primary raw material used in manufacturing spandex fibers. Increasing consumer preference for comfortable, stretchable, and high-performance textiles, coupled with rising disposable incomes and expanding apparel production, continues to accelerate PTMEG consumption globally.
Beyond textiles, PTMEG is increasingly utilized in thermoplastic polyurethanes (TPU), elastomers, and specialty coatings due to its excellent flexibility, abrasion resistance, and durability. Rapid growth in automotive lightweighting, footwear manufacturing, industrial belts, hoses, and high-performance engineering applications is further strengthening demand for PTMEG and related BDO derivatives, particularly across Asia Pacific where textile manufacturing and polymer production capacities continue to expand.
The 1,4-butanediol derivatives market faces challenges due to volatile feedstock prices, particularly for natural gas, butane, acetylene, and maleic anhydride, which significantly influence production costs and profit margins. Stringent environmental regulations governing greenhouse gas emissions, hazardous chemical handling, and energy-intensive manufacturing processes are increasing compliance costs for producers. Additionally, fluctuations in demand from key downstream sectors such as textiles, automotive, and construction, along with growing competition from alternative materials and bio-based polymers, may restrain market growth in certain applications
Significant growth opportunities exist in the development of bio-based BDO and sustainable downstream derivatives, driven by increasing environmental regulations and corporate sustainability initiatives. Rising investments in biodegradable polymers such as polybutylene succinate (PBS), expanding electric vehicle production, and increasing demand for lightweight engineering plastics and high-performance elastomers are expected to create new avenues for market expansion. Furthermore, capacity additions across Asia Pacific, technological advancements in catalytic production processes, and growing adoption of specialty BDO derivatives in electronics, pharmaceuticals, and advanced industrial applications are anticipated to support long-term market growth
Analyst Perspective
The 1,4-butanediol (BDO) derivatives market is witnessing steady growth, supported by increasing demand for downstream products including tetrahydrofuran (THF), polytetramethylene ether glycol (PTMEG), polybutylene terephthalate (PBT), gamma-butyrolactone (GBL), and thermoplastic polyurethanes (TPU) across automotive, textiles, electronics, packaging, and industrial manufacturing industries. Growing adoption of lightweight engineering plastics, high-performance elastomers, and biodegradable polymers is expanding the application landscape for BDO derivatives. In parallel, manufacturers are increasingly investing in bio-based BDO technologies, process optimization, and integrated production facilities to improve sustainability, reduce carbon emissions, and enhance cost competitiveness. Companies with strong feedstock integration, diversified derivative portfolios, and advanced manufacturing capabilities are expected to maintain a competitive advantage as demand for specialty chemicals and performance materials continues to increase
Product by Application Insights
The spandex segment accounted for the largest share of the 1,4 butanediol derivatives market, representing 24.6% of total revenue in 2025. Spandex, also known as elastane, is a synthetic fiber celebrated for its exceptional stretchiness and elasticity. Its unique properties have led to its growing use in the textile and clothing industry. Spandex is particularly popular in producing sportswear and leggings, which require a high degree of stretch and recovery. It can stretch up to 600% of its original length while returning to its initial form. In addition, spandex blends well with other fibers, creating fabrics with unique characteristics.
Polybutylene terephthalate (PBT) is one of the most notable derivatives of 1,4-butanediol. This polyester is known for its rigidity, strength, and solvent resistance. Because of its non-conductive properties, PBT is an insulator commonly used in the electrical and electronics industries. In addition, thanks to its high strength and impact resistance, it is widely used in the automotive sector for producing parts such as connectors, sensors, and housings.
Polytetramethylene ether glycol (PTMEG) is a linear, long-chain polyether glycol developed through tetrahydrofuran (THF) polymerization. PTMEG is a raw material for various applications, including elastomers, coatings, and adhesives. It is particularly significant in the manufacture of high-performance elastomers, especially polyurethanes. These elastomers are known for their high tensile strength, durability, and resilience, making them suitable for various applications, from automotive suspension systems to sports equipment.
Regional Insights
The demand for North America 1,4-butanediol derivatives market is increasing due to the growth of various industries and the focus on sustainable production methods. Thus, the growing construction activities and the increasing demand for automotive, electronics, packaging, and paints & coatings in the region are anticipated to drive the demand for 1,4-butanediol over the forecast period.
 To learn more about this report, Download Free Sample Report
U.S. 1,4 Butanediol Derivatives Market Trends
The growth of the U.S.'s1,4-butanediol derivatives market is primarily driven by its increasing demand in key industrial applications, particularly in producing plastics, resins, and synthetic fibers. As the demand for products such as spandex, polyurethane, and plastics continues to rise across various industries such as automotive, construction, textiles, and electronics, the need for high-quality BDO as a versatile chemical building block also expands.
Europe 1,4 Butanediol Derivatives Market Trends
Europe 1,4 butanediol derivatives market has witnessed significant strides in terms of advancements of chemical recycling and green chemistry initiatives, which has helped improve the overall cost-effectiveness of BDO production processes. As Europe continues to focus on decarbonization and achieving its climate goals, BDO is increasingly being produced via bio-based and low-carbon processes, aligning with the region's commitment to a circular economy.
Asia Pacific 1,4 Butanediol Derivatives Market Trends
Asia Pacific for 66.1% of the 1,4 butanediol derivatives market revenue in 2025. The 1,4 butanediol derivatives market in Asia Pacific is witnessing growth backed by surging automotive, construction, and electronics industries in countries such as China, India, and Japan, which are major contributors to the demand for BDO. The rise in consumer demand for lightweight and durable materials in these sectors has spurred the need for advanced polymers and coatings, where BDO plays an essential role. Moreover, the shift toward bio-based BDO production methods is gaining traction, providing an added growth avenue for the market as manufacturers look to meet sustainability goals.
China 1,4 Butanediol Derivatives Market Trends
China maintained a leading position in the Asia Pacific 1,4 butanediol derivatives market. China’s 1,4-butanediol (BDO) derivatives market is shaped by strong demand from downstream industries, particularly spandex, engineering plastics, solvents, and biodegradable polymers. Tetrahydrofuran (THF), used in the production of polytetramethylene ether glycol (PTMEG) for spandex fibers, represents a key derivative segment, supported by demand from textiles and apparel.
Latin America 1,4 Butanediol Derivatives Market Trends
Latin America 1,4 butadeniol derivatives market is set to display decent growth as Latin countries in this region continue to industrialize and consumer purchasing power improves, the need for high-performance materials in manufacturing processes is rising, further boosting BDO demand. In addition, the electronics industry's rapid expansion, especially in Brazil and Mexico, contributes to the demand for BDO in producing electronic components and consumer goods, further driving market growth.
Middle East & Africa 1,4 Butanediol Derivatives Market Trends
The Middle East & Africa 1,4 butanediol derivatives market is developing owing to its expanding manufacturing sector, especially in countries such as Saudi Arabia and the UAE, fosters a higher consumption of BDO as it is integral to producing materials such as polyurethane and polybutylene terephthalate (PBT). In addition, the rise in automotive production and construction activities across these regions further propels the need for BDO-based products, which are essential for enhancing durability and performance.
Key 1,4 Butanediol Derivatives Company Insights
Some of the key players operating in the market include BASF SE, Ashland, and Evonik Industries AG.
-
BASF SE is a chemical production company. It has more than 340 production facilities worldwide and conducts business through subsidiaries and joint partnerships in over 80 countries. The company also offers a variety of system solutions and services. These include products for the automotive, chemical, construction, agriculture, oil, electrical, plastics, electronics, furniture, and paper sectors.
-
Ashland is engaged in manufacturing and distributing specialty chemicals to several end-use industries including architectural coating, adhesives, automotive, construction, food & beverage, pulp & paper, energy, pharmaceuticals, and personal care. It operates through three business segments, namely, specialty ingredients, composites, and intermediates & solvents. The specialty ingredients segment includes cellulose ethers, vinyl pyrrolidone, and biofunctionals.
Key 1,4 Butanediol Derivatives Companies:
The following key companies have been profiled for this study on the 1,4 butanediol derivatives market.
-
BASF SE
-
Ashland
-
DCC
-
Mitsubishi Chemical Group Corporation
-
Evonik Industries AG
-
LyondellBasell Industries Holdings B.V.
-
Sipchem Company
-
SINOPEC (China Petrochemical Corporation)
-
Genomatica, Inc.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (BASF SE, Mitsubishi Chemical Group Corporation, Evonik Industries AG, LyondellBasell Industries Holdings B.V., Sipchem Company, SINOPEC, DCC)
- Expand integrated BDO and downstream derivative production capacities (THF, PTMEG, PBT, GBL).
- Invest in process optimization, feedstock integration, and sustainable manufacturing technologies.
- Strengthen long-term partnerships with automotive, electronics, textile, and polymer manufacturers.
- Expand regional production and distribution networks through strategic investments and joint ventures.
- Integrated manufacturing operations with secure feedstock access.
- Strong global presence supported by diversified derivative portfolios.
- Extensive technical expertise and long-standing customer relationships.
- Strong financial capability to support innovation and capacity expansion..
- High dependence on volatile feedstock and energy prices.
- Capital-intensive manufacturing and downstream integration.
- Exposure to cyclical demand from automotive, textiles, and construction industries.
- Increasing environmental compliance and decarbonization costs.
Category
Operating Strategies
Competitive Edge
Weakness
Emerging / Regional Players (Ashland; Genomatica, Inc.)
- Focus on bio-based BDO technologies and sustainable derivative development.
- Establish technology licensing agreements and strategic collaborations.
- Target specialty chemicals, high-value polymers, and niche downstream applications.
- Expand commercialization of renewable and low-carbon production technologies.
- Strong innovation capabilities in sustainable chemical technologies.
- Greater flexibility in developing niche and specialty derivative solutions.
- Early positioning in bio-based and low-carbon value chains.
- Faster adoption of emerging production technologies.
- Limited production capacity compared with multinational manufacturers.
- Smaller global distribution network and customer base.
- Greater dependence on successful technology commercialization.
- • Limited financial resources for large-scale expansion projects
Recent Developments
-
In September 2023, BASF agreed with Qore LLC to secure long-term access to QIRA's bio-based 1,4-butanediol. This strategic move supports BASF's expansion of its bio-based derivatives portfolio, including tetrahydrofuran and polytetrahydrofuran, with commercial quantities anticipated by Q1 2025.
-
In October 2022, BASF SE announced the manufacturing of 1,4-butanediol through renewable feedstock, which includes Genomatica's patented GENO BDO technology. The moves toward bio-based technologies for producing 1,4-butanediol align with BASF SE and Genomatica, Inc. goal of promoting sustainable development in the industry.
1,4 Butanediol Derivatives Market Report Scope
Report Attribute
Details
Market size in 2025
USD 33.0 billion
Estimated market size in 2026
USD 35.1 billion
Projected market size by 2033
USD 64.3 billion
Growth rate
CAGR of 9.0% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Volume, Kilotons; Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue & Volume forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product by application, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Netherlands; Russia; China; India; Japan; South Korea; Australia; Vietnam; Brazil; Argentina; Saudi Arabia; South Africa
Key companies profiled
BASF SE; Ashland; DCC; Mitsubishi Chemical Group Corporation; Evonik Industries AG; LyondellBasell Industries Holdings B.V.; Sipchem Company; SINOPEC (China Petrochemical Corporation); Genomatica, Inc.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global 1,4 Butanediol Deravatives Market Report Segmentation
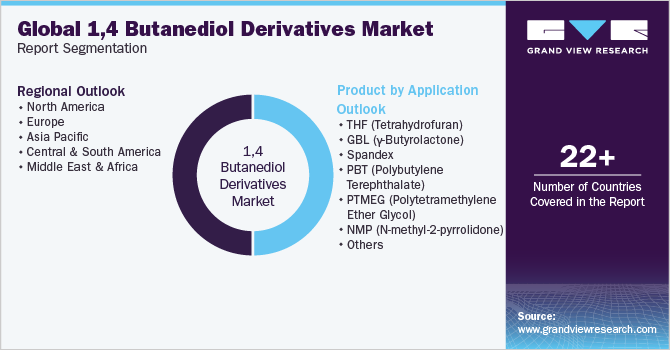
This report forecasts revenue and volume growth at global, regional, and country levels and analyzes the latest industry trends in each of the sub-segments from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the global 1, 4 butanediol derivatives market report by product by application, and region:
 To learn more about this report, Download Free Sample Report
-
Product by Application Outlook (Volume, Kil0tons; Revenue, USD Million, 2021 - 2033)
-
Tetrahydrofuran (THF)
-
PTMEG (Polytetramethylene Ether Glycol)
-
Solvents
-
-
γ-Butyrolactone (GBL)
-
NMP (N-methyl-2-pyrrolidone)
-
2 PY (2-pyrrolidone)
-
Others
-
-
Spandex
-
Clothing
-
Medical
-
Others
-
-
Polybutylene Terephthalate (PBT)
-
Electronics
-
Automotive
-
Consumer Goods
-
Others
-
-
PTMEG (Polytetramethylene Ether Glycol)
-
Spandex
-
Polyurethane
-
Others
-
-
NMP (N-methyl-2-pyrrolidone)
-
Petrochemicals
-
Electronics
-
Paints & Coatings
-
Others
-
-
NVP (N-vinyl-2-pyrrolidone)
-
PVP (polyvinylpyrrolidone)
-
Adhesives
-
Coatings
-
Others
-
-
PVP (Polyvinylpyrrolidones)
-
Pharmaceuticals
-
Personal Care/Cosmetics
-
Detergents
-
Others
-
-
PBS (Polybutylene Succinate)
-
Mulch Films
-
Packaging
-
Others
-
-
PBAT (Polybutylene Adipate Terephthalate)
-
Food Packaging
-
Agriculture Films
-
Others
-
-
TPU (Thermoplastic Polyurethane)
-
Footwear
-
Automotive
-
Electronics
-
Medical
-
Others
-
-
2 PY (2-pyrrolidone)
-
Coatings
-
Inks
-
Pharmaceuticals
-
Others
-
-
-
Regional Outlook (Volume, Kil0tons; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
Netherlands
-
Russia
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
Vietnam
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Arabia
-
South Africa
-
-
Research Methodology
The 1,4 butanediol derivatives Market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each 1,4 butanediol derivatives segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product by Application
Revenue capture definition
Tetrahydrofuran (THF)
Revenue is generated through the commercialization of tetrahydrofuran (THF) produced from 1,4-butanediol, which is primarily consumed in the manufacture of polytetramethylene ether glycol (PTMEG), solvents, elastomers, and specialty chemical intermediates. Strong demand from the spandex, polyurethane, and industrial solvent industries continues to support market growth.
γ-Butyrolactone (GBL)
Business income is derived from the production and supply of gamma-butyrolactone (GBL), a key intermediate used in pharmaceuticals, agrochemicals, electronics, specialty solvents, and chemical synthesis. Growing demand for high-purity solvents and specialty chemical intermediates continues to drive revenue generation.
Polybutylene Terephthalate (PBT)
Revenue is generated through the commercialization of polybutylene terephthalate (PBT), an engineering thermoplastic manufactured using BDO. Demand is supported by increasing consumption across automotive components, electrical & electronics, consumer appliances, connectors, and industrial equipment requiring high-performance engineering plastics
PTMEG (Polytetramethylene Ether Glycol)
Business income is generated through the production and commercialization of PTMEG, a major downstream derivative used in spandex fibers, thermoplastic polyurethanes (TPU), elastomers, coatings, adhesives, sealants, and industrial applications. Expanding textile production and increasing demand for high-performance elastomers continue to strengthen market growth
Spandex
Revenue is generated through the utilization of PTMEG-based spandex fibers across apparel, sportswear, medical textiles, industrial fabrics, and personal protective equipment. Rising consumer demand for stretchable, lightweight, and performance textiles continues to support revenue growth
NMP (N-methyl-2-pyrrolidone)
Revenue is generated through the commercialization of NMP manufactured via GBL, serving applications in lithium-ion battery production, electronics cleaning, petrochemical processing, coatings, and specialty solvents. Increasing electric vehicle production and battery manufacturing continue to drive market demand
NVP (N-Vinyl-2-pyrrolidone)
Business income is derived from the production of NVP utilized in adhesives, specialty coatings, printing inks, cosmetics, pharmaceuticals, and polymer manufacturing. Growing demand for high-performance specialty polymers supports steady market expansion
PVP (polyvinylpyrrolidones)
Revenue is generated through the commercialization of PVP used in pharmaceutical formulations, cosmetics, food processing, adhesives, coatings, and personal care products. Expanding pharmaceutical manufacturing and increasing demand for functional excipients continue to support growth
PBS (Polybutylene Succinate)
Revenue is generated from bio-based and biodegradable PBS resins utilized in sustainable packaging, agricultural films, disposable products, and compostable materials. Increasing environmental regulations and growing demand for biodegradable plastics are driving market expansion
PBAT (Polybutylene Adipate Terephthalate)
Business income is generated through the production of PBAT used in biodegradable packaging films, shopping bags, compostable products, agricultural mulch films, and flexible packaging. Rising sustainability initiatives and plastic waste reduction policies continue to accelerate product adoption
TPU (Thermoplastic Polyurethane)
Revenue is generated through the commercialization of TPU manufactured using PTMEG, serving footwear, automotive, industrial equipment, consumer electronics, cables, medical devices, and engineering applications requiring flexibility and abrasion resistance
2 PY (2-pyrrolidone)
Revenue is generated through the supply of 2-pyrrolidone utilized in pharmaceuticals, specialty solvents, agrochemicals, polymers, and fine chemical synthesis. Growing demand from pharmaceutical intermediates and specialty chemical manufacturing supports market growth
Other Applications
Revenue is generated through the commercialization of other BDO-based specialty derivatives utilized across solvents, resins, performance chemicals, specialty polymers, coatings, pharmaceuticals, and emerging sustainable material applications. Continuous product innovation and expanding downstream industrial applications create additional revenue opportunities
Estimation Model
Layer Name
Key Question
Description
Downstream Industry Demand Layer
Downstream Industry Demand Layer
Assess global demand across major downstream industries including textiles, automotive, electrical & electronics, construction, packaging, consumer goods, pharmaceuticals, industrial manufacturing, and specialty chemicals. This layer establishes the addressable demand base by evaluating consumption of spandex fibers, engineering plastics, biodegradable polymers, elastomers, solvents, battery materials, and specialty chemicals derived from BDO
BDO Derivatives Adoption Layer
BDO Derivatives Adoption Layer
Evaluate the adoption of major BDO derivatives including THF, PTMEG, GBL, PBT, TPU, PBS, PBAT, NMP, NVP, PVP, 2-pyrrolidone, and other specialty derivatives across global manufacturing industries. Adoption is influenced by technological advancements, sustainability initiatives, engineering material requirements, and downstream industrial expansion
Consumption Intensity Layer
Consumption Intensity Layer
Quantify derivative consumption by evaluating production volumes, conversion efficiencies, formulation ratios, manufacturing capacities, application-specific inclusion rates, and regional demand patterns. The assessment estimates annual consumption intensity across textiles, automotive, packaging, electronics, construction, pharmaceutical, and specialty chemical industries.
Revenue Layer
How is market revenue generated?
Market revenue is generated through the production, commercialization, and distribution of BDO derivatives supplied to manufacturers of spandex fibers, engineering plastics, biodegradable polymers, polyurethanes, specialty solvents, pharmaceuticals, electronics, battery materials, and industrial chemicals. Commercial performance is influenced by feedstock pricing, downstream demand, technological innovation, production efficiencies, sustainability regulations, long-term supply agreements, and expanding adoption across high-growth industrial applications.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Segmentation
Comprehensive regional assessment of the 1,4-butanediol derivatives market across North America, Europe, Asia Pacific, Latin America, and Middle East & Africa, including country-level analysis of downstream derivative demand, production capacity, trade dynamics, feedstock availability, manufacturing footprint, and regulatory developments. The study evaluates regional demand for THF, PTMEG, GBL, PBT, TPU, PBS, PBAT, and other BDO derivatives across major end-use industries. Enables identification of high-growth regional markets, downstream production hubs, and emerging demand centers. Supports capacity expansion planning, sourcing strategies, geographic prioritization, and investment decision-making through comprehensive regional market intelligence. Cross- Segmentation Benchmarking
Detailed cross-segmentation analysis evaluating demand across major BDO derivative products (THF, PTMEG, GBL, PBT, TPU, PBS, PBAT, NMP, PVP, and others) mapped against end-use industries including automotive, electronics, textiles, construction, packaging, pharmaceuticals, and industrial manufacturing.
Supports portfolio optimization by identifying high-growth product-end-use combinations, demand concentration trends, and evolving consumption patterns, enabling targeted market development and strategic resource allocation.
Pricing Analysis
Comprehensive assessment of historical and current pricing trends for BDO derivatives, including feedstock cost movements (natural gas, butane, acetylene, propylene, and maleic anhydride), production economics, energy costs, regional supply-demand balances, capacity utilization, and trade dynamics. The analysis also evaluates pricing variations across major derivative products and regions.
Supports procurement planning, supplier negotiations, pricing strategy development, and margin optimization through enhanced visibility into cost structures, pricing volatility, and future market outlook across the BDO derivatives value chain
Frequently Asked Questions About This Report
Spandex segment dominated the market with a revenue share of 24.6% in 2025.
Asia Pacific is expected to grow the fastest with a compound annual growth rate of 9.6% from 2026 to 2033
Polybutylene Succinate (PBS) product by application segment is expected to grow the fastest with a compound annual growth rate of 13.1% from 2026 to 2033.
Key factors that are driving the market growth include increasing application of derivatives of 1,4 butanediol in different end-use industries, including electronics, clothing, pharmaceutical, packaging, etc.
Some key players operating in the 1,4 butanediol derivatives market include BASF SE, Ashland, DCC, Mitsubishi Chemical Group Corporation, Evonik Industries AG, LyondellBasell Industries Holdings B.V., Sipchem Company, SINOPEC (China Petrochemical Corporation), Genomatica, Inc.
The global 1,4 butanediol derivatives market size was valued at USD 33.0 billion in 2025 and is estimated at USD 35.1 billion for 2026.
The global 1,4 butanediol derivatives market is expected to grow at a CAGR of 9.0% from 2026 to 2033, reaching USD 64.3 billion by 2033.
About the Author(s)
Organic Chemicals Research Team
Bulk Chemicals · Organic ChemicalsThis report was authored by the organic chemicals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the organic chemicals segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


