
- Home
- »
- Organic Chemicals
- »
-
1-Decene Market Size, Share And Trends Report, 2033GVR Report cover

1-Decene Market (2026 - 2033)
Size, Share & Trends Analysis Report By Application (PAO, Detergent Alcohol, Polyethylene), By Region (North America, Europe, Asia Pacific, Middle East & Africa), And Segment Forecasts
Market Size, 2025
$1.2BMarket Estimate, 2026
$1.3BMarket Forecast, 2033
$1.8BCAGR, 2026–2033
5.1%1-Decene Market Summary
The global 1-decene market size was valued at USD 1.2 billion in 2025 and is projected to grow from USD 1.3 billion in 2026 to USD 1.8 billion by 2033, at a CAGR of 5.1% from 2026 to 2033. Europe dominated the market, accounting for a revenue share of 45.5% in 2025. Increasing demand for synthetic lubricants, capacity expansions by key industry players, and focus on the development of alpha olefins from bio-based materials are likely to propel the industry demand.
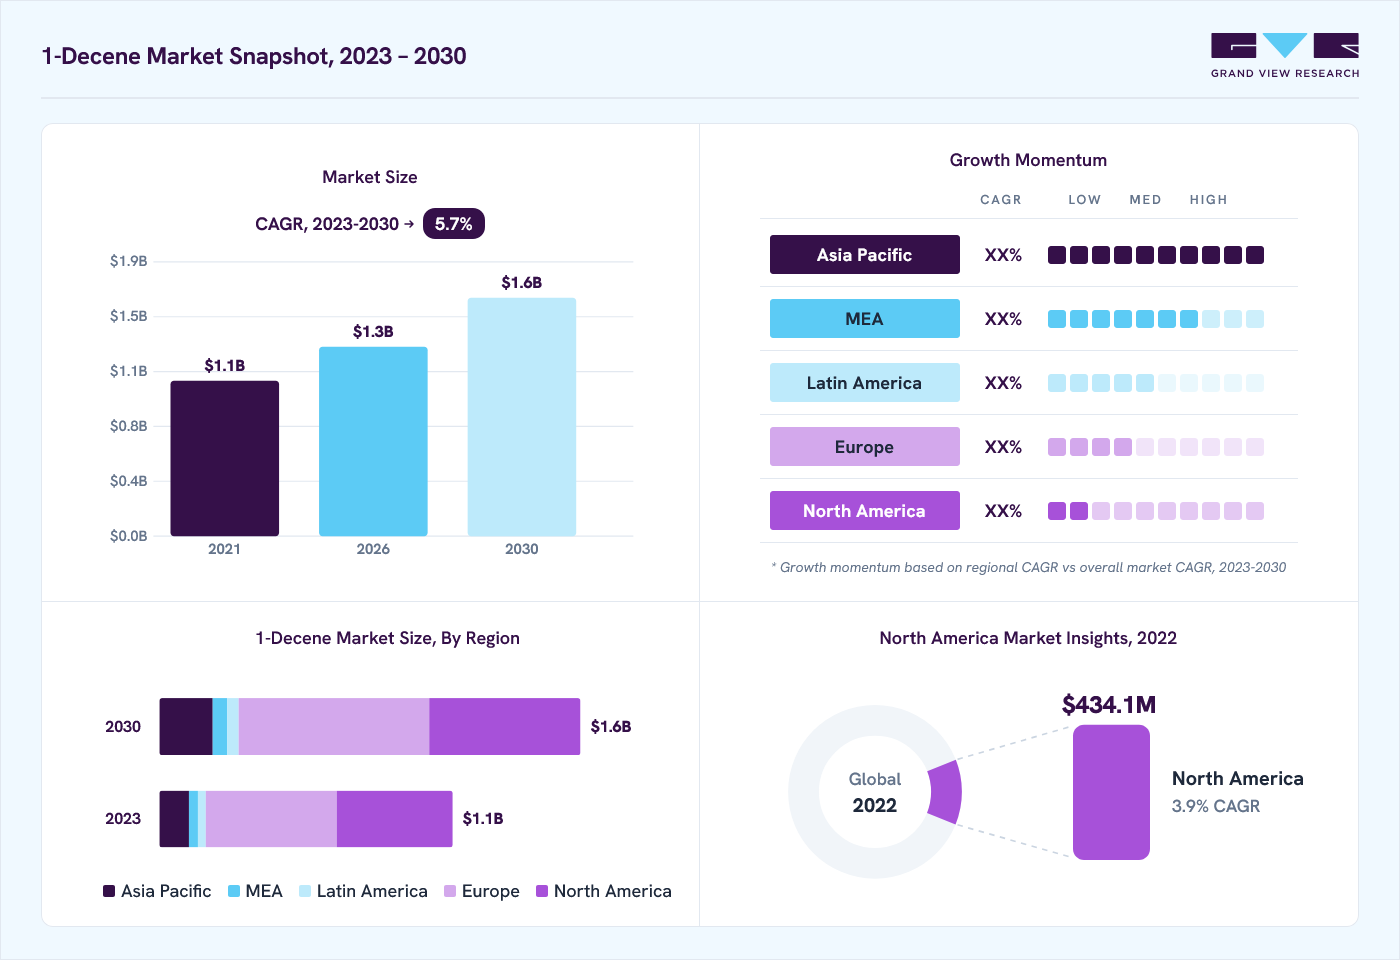 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By application: Poly alpha olefin held a dominant position, contributing 67.9% of total revenue in 2025.
Regional Highlights
- Largest regional market: Europe (45.5% revenue share, 2025)
- By country: Germany held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 1.2 Billion
- Estimated market size in 2026: USD 1.3 Billion
- Projected market size by 2033: USD 1.8 Billion
- CAGR (2026-2033): 5.1%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
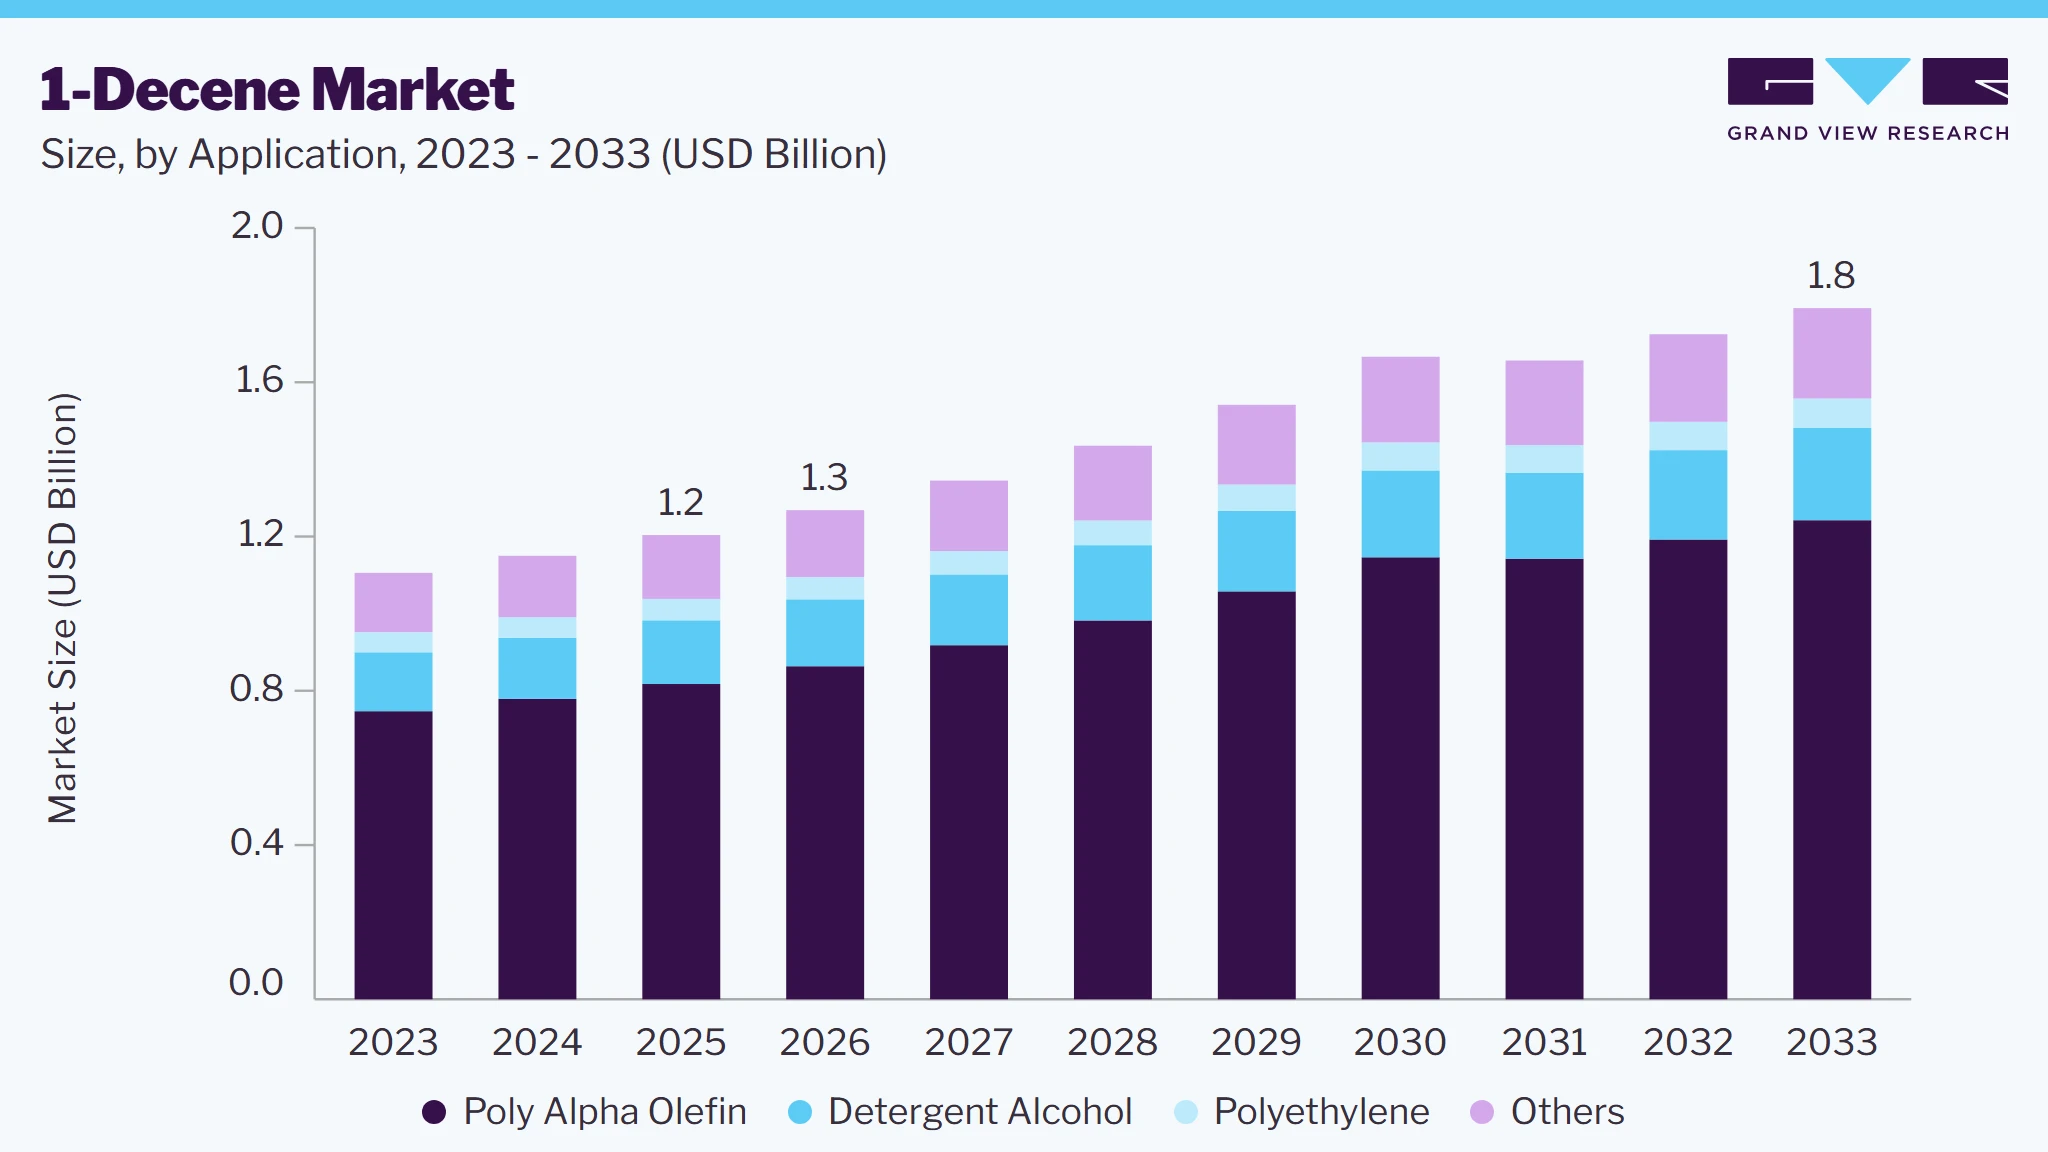
The increasing popularity of synthetic lubricants, as they offer better lubrication and cause less engine wear & tear has triggered Poly Alpha Olefin (PAO) demand over the recent past. It is prepared by oligomerization of linear alpha olefins and C-10 is the most preferred alpha-olefin for PAO production.
 To learn more about this report, Download Free Sample Report
Increasing Poly Alpha Olefin (PAO) demand for producing engine/gear oils, greases, and other lubricants is expected to be the key factor driving the industry's growth. The Shale gas boom, particularly in the U.S. and China, has provided new hope for petrochemical producers and has pushed ethylene production, which is an essential raw material for 1-decene production. The ample availability of critical raw materials in these regions is also expected to have a positive influence on product demand. 1-decene is obtained through the oligomerization of ethylene and can only be produced through full-range alpha olefin distribution, which cannot be obtained through on-purpose production processes like 1-hexene or 1-octene.
This has led to a limited C-10 supply for PAO production. The short supply of PAO in the market has left synthetic lubricant manufacturers with no choice other than to seek alternate raw materials for oil production. Ester-based synthetic oils are thus getting popular and are likely to affect the market growth over the forecast period. The global industry has always been highly sensitive to economic conditions along with the supply-demand scenario. The market price is normally based on the cost-plus pricing method, in which raw material prices play an important part. Ethylene prices have been fluctuating and the same trend can be observed in the case of alpha olefin prices.
Market Dynamics
The increasing use of synthetic lubricants across automotive, industrial, aerospace, and wind energy applications a key driver for the 1-decene market. As the primary feedstock for poly alpha olefins (PAOs), 1-decene benefits from growing demand for high-performance lubricants that offer superior thermal stability, oxidation resistance, and extended service life. Expanding industrial automation, stringent fuel efficiency regulations, and rising adoption of electric vehicles are further boosting PAO consumption, thereby supporting steady demand for 1-decene.
The production of 1-decene relies heavily on petrochemical feedstocks such as ethylene through alpha olefin manufacturing processes. Fluctuations in crude oil and natural gas prices directly impact production costs, affecting profit margins for manufacturers. Supply disruptions, refinery shutdowns, and geopolitical uncertainties can create raw material shortages and pricing instability, posing challenges for long-term market growth.
The increasing consumption of poly alpha olefins (PAOs) across automotive, industrial, aerospace, and energy sectors is a primary factor driving the growth of the 1-decene market. As one of the most widely used alpha olefins for PAO production, 1-decene serves as a critical feedstock for manufacturing synthetic lubricants that offer enhanced thermal stability, low-temperature fluidity, oxidation resistance, and extended equipment life. Rising industrialization, expanding vehicle production, and the growing need for energy-efficient machinery are accelerating demand for premium lubricants capable of performing under extreme operating conditions. The increasing deployment of wind turbines, industrial compressors, and heavy-duty machinery is supporting the adoption of high-performance lubricants, thereby strengthening consumption of 1-decene. Manufacturers are also investing in advanced alpha olefin production technologies to improve product quality and supply reliability, enabling the market to meet the evolving performance requirements of downstream lubricant and specialty chemical industries.
Fluctuations in petrochemical feedstock prices remain a significant challenge for the 1-decene market, as production is closely linked to ethylene-derived alpha olefin manufacturing processes. Variations in crude oil and natural gas prices directly influence raw material costs, creating uncertainty in production economics and reducing margin stability for manufacturers. In addition, supply chain disruptions caused by refinery maintenance, geopolitical tensions, transportation constraints, and fluctuations in global petrochemical operating rates can limit feedstock availability and affect production continuity. These cost pressures are particularly impactful for small and medium-sized producers with limited procurement flexibility. The market also faces challenges associated with balancing supply and demand during periods of changing industrial activity, leading to pricing volatility across the value chain. Such uncertainties may delay capacity expansion decisions and reduce investment confidence, ultimately restraining the pace of market growth despite sustained demand from key downstream applications.
The expansion of global polyethylene manufacturing capacity presents substantial growth opportunities for the 1-decene market, as the product is extensively used as a comonomer in the production of linear low-density polyethylene (LLDPE) and high-density polyethylene (HDPE). Increasing demand for lightweight, durable, and recyclable plastic materials in packaging, construction, consumer goods, and infrastructure projects is driving investments in advanced polyethylene production facilities. Alongside polymer applications, the growing utilization of 1-decene in detergent alcohols, surfactants, oilfield chemicals, lubricant additives, and other specialty chemical formulations is broadening its commercial potential. Rapid industrialization and rising manufacturing activity across emerging economies are creating additional demand for high-value chemical intermediates with superior performance characteristics. Technological advancements in alpha olefin production, coupled with investments in integrated petrochemical complexes, are improving production efficiency and product availability, allowing manufacturers to capitalize on expanding opportunities across diverse downstream industries.
Analyst Perspective
The 1-decene market is expected to witness steady growth, supported by rising demand from synthetic lubricants, polyethylene production, and specialty chemical applications. Increasing investments in high-performance materials and expanding petrochemical capacities are strengthening long-term consumption prospects. Market participants are focusing on production efficiency, catalyst innovations, and integrated manufacturing to enhance competitiveness. Demand is particularly robust in Asia Pacific and the Middle East, driven by industrial expansion and polymer manufacturing. While feedstock price volatility remains a key challenge, growing downstream applications and capacity additions are expected to sustain market growth over the forecast period.
Application Insights
On the basis of applications, the global industry has been further categorized into poly alpha olefin, polyethylene, detergent alcohol, and others. Poly alpha olefin held a dominant position, contributing 67.9% of total revenue in 2025 The segment is estimated to retain its dominance throughout the forecast period. This is attributed to the increasing demand for PAO for synthetic lubricant production.
Poly alpha olefin is anticipated to emerge as the largest as well as the fastest-growing application segment as PAO offers exceptional technical performance and also helps in the prevention of the environment. Detergent alcohols and their derivatives are key raw materials used for producing surfactants in laundry and dishwashing applications. This application segment is expected to witness an above-average growth rate over the forecast period.
Regional Insights
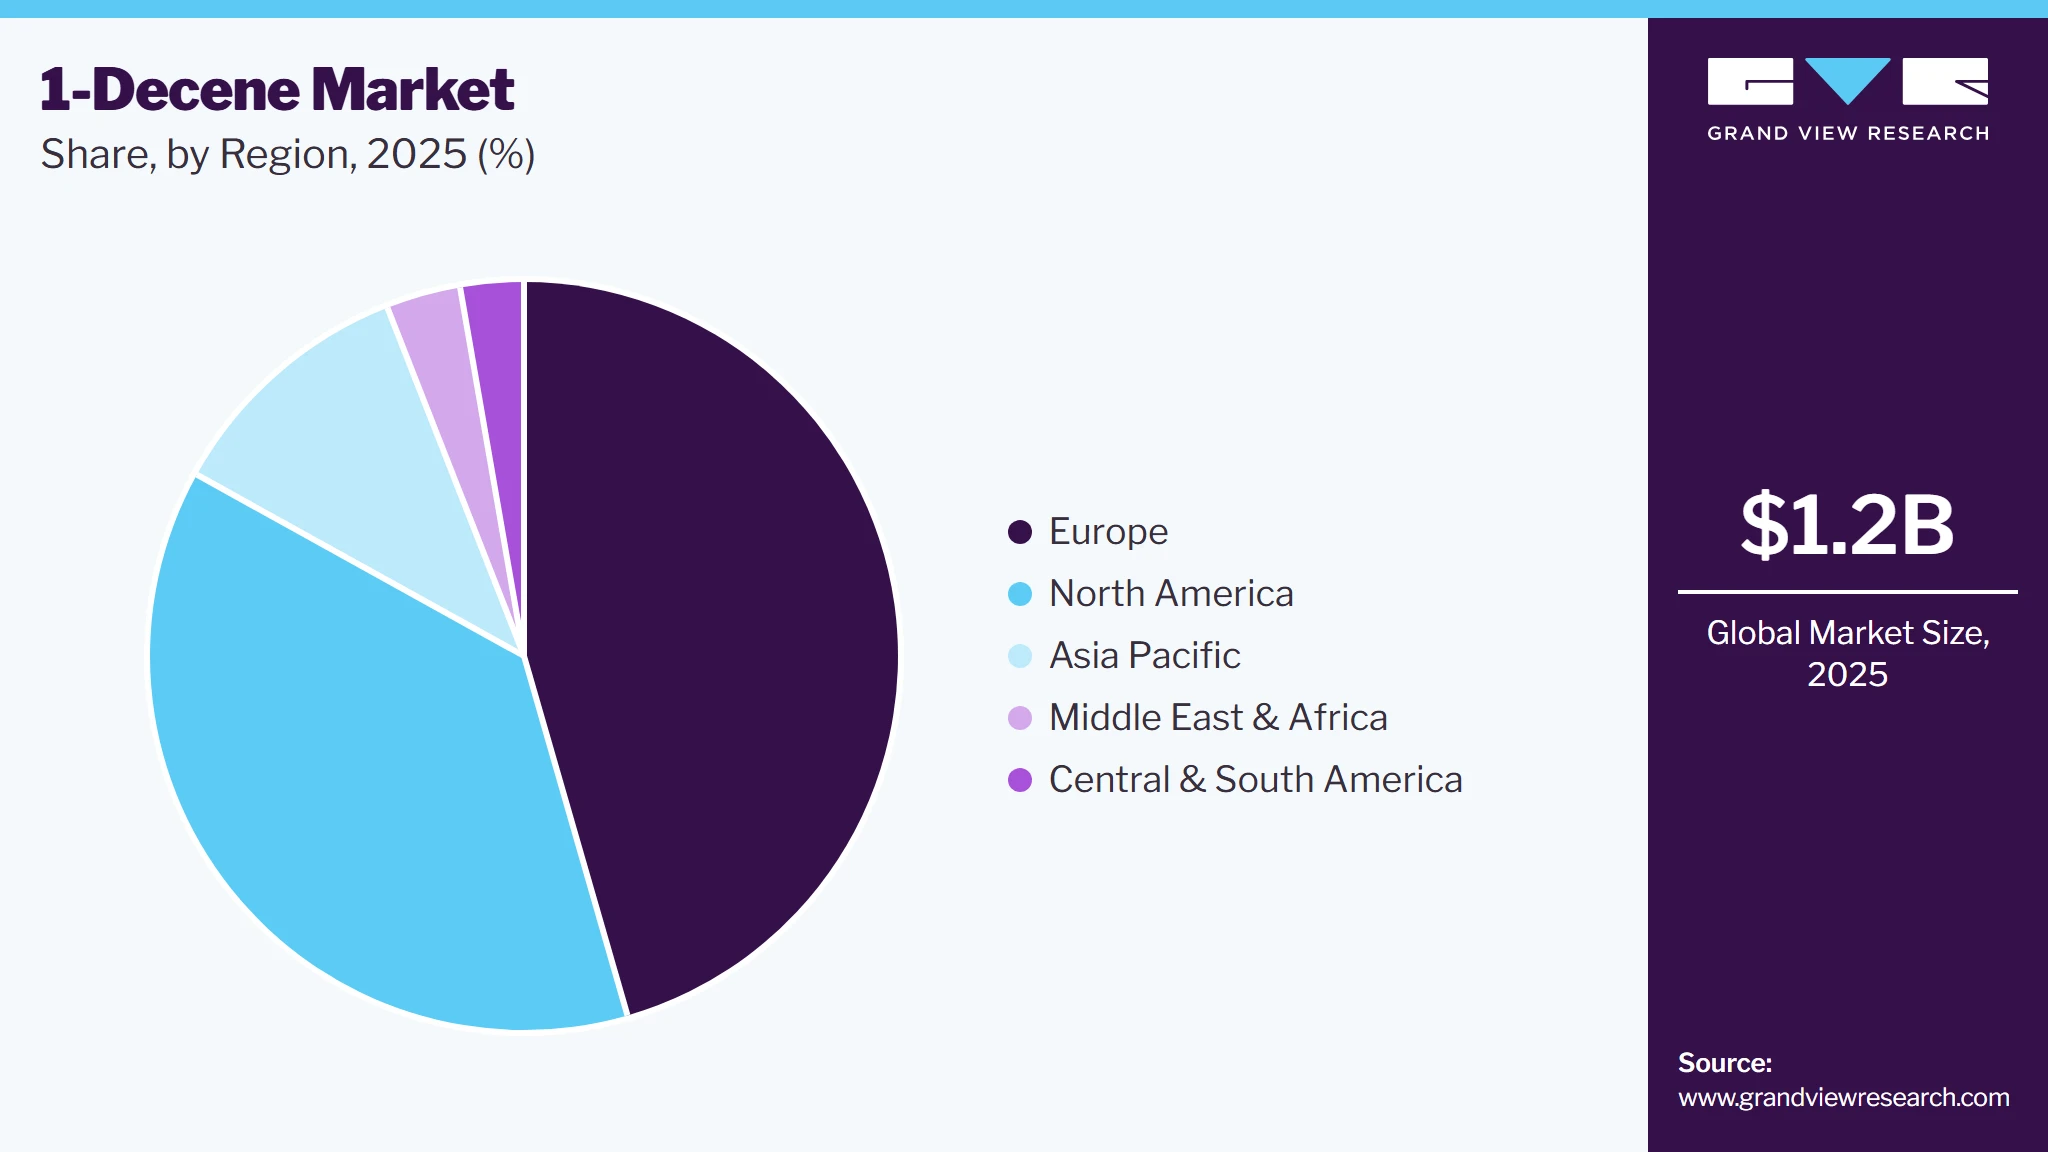
Europe dominated the 1-decene market with the highest revenue share of 45.5% in 2025. The region is projected to expand further at a steady growth rate retaining its leading position throughout the forecast period. This is attributed to the increasing PAO and synthetic lubricant production in the region by key product manufacturers. Regional growth can also be attributed to the easy availability of raw materials. Furthermore, as the U.S. is the largest oil manufacturing country, it has been responsible for the higher penetration in the North America regional market.
 To learn more about this report, Download Free Sample Report
Germany 1-Decene Market Trends
Germany accounted for 24.5% of the European 1-decene market in 2025. Moreover, the strong presence of the major industry participants, such as ExxonMobil Corp., Shell Chemicals, Chevron Phillips Chemical Company LP, and INEOS Oligomers, having patented technology for alpha olefin production has driven 1-decene demand in North America. The Asia Pacific region is estimated to register the fastest growth rate during the forecast period. This is mainly due to the rising demand for PAO for the production of lubricants.
Key Companies & Market Share Insights
The global industry is concentrated due to the presence of a few multinational players having their patented technology. The market has witnessed a high level of integration from major industry participants. Key members, such as Shell Chemicals, Chevron Phillips, and Q-Chem, have integrated their operations across the value chain including the production and supply of raw materials to end-use products.
Key 1-Decene Market Companies:
The following key companies have been profiled for this study on the 1-decene market.
-
Shell Chemicals
-
Chevron Phillips
-
INEOS
-
Qatar Chemicals
-
SASOL
-
ExxonMobil
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Shell Chemicals, Chevron Phillips Chemical, INEOS, Sasol, ExxonMobil)
- Operate fully integrated petrochemical complexes to ensure reliable ethylene and alpha olefin supply.
- Invest in process optimization, catalyst innovation, and capacity expansion to improve production efficiency.
- Establish long-term supply agreements with lubricant, polymer, and chemical manufacturers.
- Expand global distribution networks while strengthening sustainability and operational excellence initiatives.
- Strong global manufacturing footprint with integrated feedstock availability.
- Advanced proprietary production technologies deliver consistent product quality.
- Diversified customer base across multiple downstream industries and regions.
- Robust financial resources supporting continuous investment and innovation.
- Large-scale operations can limit flexibility in responding to short-term market changes.
- High capital expenditure requirements for plant expansion and modernization.
- Greater exposure to environmental compliance costs and regulatory obligations.
- Dependence on volatile petrochemical feedstock prices impacts profitability.
Emerging Players (Qatar Chemical Company (Q-Chem, NKNK)
- Focus on expanding production capabilities in high-growth regional markets.
- Develop strategic partnerships and joint ventures to enhance technology access and market reach.
- Prioritize niche applications and specialty chemical segments to strengthen market positioning.
- Optimize operational costs through localized manufacturing and flexible production planning.
- Greater flexibility to respond to changing customer requirements and regional demand.
- Competitive pricing supported by lower regional operating costs in selected markets.
- Ability to capitalize on expanding petrochemical investments in developing economies.
- Faster decision-making and targeted investments in growing application areas.
- Limited global brand recognition and customer diversification.
- Smaller production capacities restrict economies of scale.
- Greater reliance on external technology providers and strategic collaborations.
- Limited distribution infrastructure and international market penetration compared with established competitors.
1-Decene Market Report Scope
Report Attribute
Details
Market size in 2025
USD 1.2 billion
Estimated market size in 2026:
USD 1.3 billion
Projected market size by 2033
USD 1.8 billion
Growth rate
CAGR of 5.1% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion/million, Volume in Kilotons and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Application, region
Regional scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country scope
U.S.; U.K.; Germany; France; China; India; Japan; Thailand; Malaysia; Indonesia; Brazil; Saudi Arabia
Key companies profiled
Shell Chemicals; Chevron Phillips; INEOS; Qatar Chemicals; SASOL; ExxonMobil
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global 1-Decene Market Report Segmentation
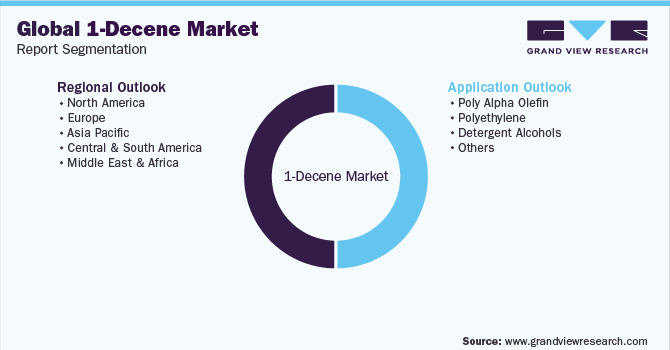
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the global 1-decene market report on the basis of application and region:
 To learn more about this report, Download Free Sample Report
-
Application Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Poly Alpha Olefin
-
Polyethylene
-
Detergent Alcohols
-
Others
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
-
Europe
-
Germany
-
U.K.
-
France
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Indonesia
-
Malaysia
-
Thailand
-
-
Central & South America
-
Brazil
-
-
Middle East & Africa
-
Saudi Arabia
-
-
Research Methodology
The 1-decene market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each 1-decene segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Application
Revenue capture definition
Poly Alpha Olefin
Strong commercial value stems from the use of 1-decene as a base material for poly alpha olefin (PAO) synthesis, supplying high-performance synthetic lubricants required in automotive, aviation, industrial equipment, and renewable energy systems. Growing preference for extended-drain and energy-efficient lubricants supports steady earnings.
Polyethylene
Financial growth is supported by the incorporation of 1-decene as a comonomer in polyethylene manufacturing, improving polymer strength, flexibility, and impact resistance. Expanding demand from flexible packaging, agricultural films, piping, and consumer products reinforces business potential.
Detergent Alcohols
Business expansion is fueled by the conversion of 1-decene into detergent alcohols used in surfactants for laundry detergents, dishwashing liquids, industrial cleaners, and personal hygiene products. Rising consumption of premium cleaning solutions continues to strengthen segment performance.
Other Applications
Economic contribution arises from the utilization of 1-decene in specialty chemicals, lubricant additives, oilfield chemicals, plastic modifiers, and wax formulations. Broadening industrial applications and increasing demand for performance chemicals enhance long-term market prospects.
Estimation Model
Layer Name
Key Question
Description
Raw Material & Production Layer
What forms the supply base?
Analyze the global production ecosystem for 1-decene, focusing on ethylene-derived alpha olefin manufacturing through oligomerization technologies. Assess ethylene feedstock availability, catalyst technologies, production processes, manufacturing capacities, integrated petrochemical complexes, regional production hubs, supplier landscape, and logistics infrastructure supporting the global supply chain.
Application Adoption Layer
Where is 1-decene consumed?
Evaluate the utilization of 1-decene across key applications including poly alpha olefins (PAOs), polyethylene comonomers, detergent alcohols, and other specialty chemical applications. Examine demand trends driven by synthetic lubricant production, advanced polymer manufacturing, surfactant formulations, oilfield chemicals, and industrial chemical intermediates across automotive, packaging, consumer goods, and industrial sectors.
Consumption Intensity Layer
How much 1-decene is utilized?
Quantify 1-decene consumption by analyzing application-wise demand, production volumes, conversion efficiencies, and usage intensity across downstream industries. The assessment covers PAO manufacturing, polyethylene production, detergent alcohol synthesis, lubricant additives, specialty chemicals, and other industrial applications to estimate regional and global consumption patterns.
Revenue Layer
How is market revenue generated?
Market revenue is generated through the supply of 1-decene to manufacturers of synthetic lubricants, polyethylene, detergent alcohols, and specialty chemicals. Revenue growth is influenced by alpha olefin production capacity, feedstock pricing, technological advancements, long-term supply contracts, product purity, expanding petrochemical investments, and increasing demand for high-performance materials across automotive, industrial, packaging, and consumer applications.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Segmentation
The study provides detailed country-level analysis across major 1-decene production and consumption markets. It evaluates ethylene feedstock availability, alpha olefin manufacturing infrastructure, production capacities, trade dynamics, regulatory environment, downstream demand, and growth opportunities across poly alpha olefins (PAOs), polyethylene, detergent alcohols, and other specialty chemical applications.
Supports strategic market expansion by identifying high-growth regions, assessing regional supply-demand trends, evaluating feedstock security, and highlighting investment opportunities across established and emerging petrochemical hubs.
Competitive Benchmarking
The study presents an in-depth competitive benchmarking assessment of leading 1-decene manufacturers based on production capacity, alpha olefin technology, feedstock integration, product portfolio, geographic presence, operational efficiency, strategic collaborations, innovation initiatives, and recent business developments.
Helps stakeholders evaluate competitive positioning, identify technology leadership, benchmark manufacturing strengths, uncover partnership opportunities, and develop effective long-term growth strategies.
Opportunity Assessment
The study analyzes emerging opportunities across synthetic lubricants, advanced polyethylene production, detergent alcohols, lubricant additives, specialty chemicals, and industrial intermediates. It further evaluates the impact of catalyst innovations, petrochemical capacity expansions, sustainability initiatives, and increasing demand for high-performance materials.
Assists organizations in identifying high-growth application areas, prioritizing capital investments, accelerating product development, expanding downstream market presence, and leveraging evolving opportunities across the global alpha olefin value chain.
Frequently Asked Questions About This Report
Europe dominated the 1-decene market with the highest revenue share of 45.5% in 2025, due to strong demand from synthetic lubricant manufacturers, well-established petrochemical infrastructure, and the presence of leading alpha olefin producers
The global 1-decene market size was valued at USD 1.2 billion in 2025 and is estimated at USD 1.3 billion in 2026.
The global 1-decene market is expected to grow at a CAGR of 5.1% from 2026 to 2033, reaching USD 1.8 billion by 2033.
By application, poly alpha olefin held a dominant position, contributing 67.9% of total revenue in 2025, driven by increasing demand for high-performance polymers in packaging, automotive, and industrial applications.
The 1-decene market is primarily driven by increasing demand for poly alpha olefins (PAOs) used in high-performance synthetic lubricants across the automotive and industrial sectors. Growth in polyethylene production, expanding specialty chemical applications, and ongoing investments in integrated petrochemical manufacturing are further supporting market expansion.
Some key players operating in the 1-decene market include Shell Chemicals; Chevron Phillips; INEOS; Qatar Chemicals; SASOL; ExxonMobil; NKNK.
About the Author(s)
Organic Chemicals Research Team
Bulk Chemicals · Organic ChemicalsThis report was authored by the organic chemicals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the organic chemicals segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


