
- Home
- »
- Next Generation Technologies
- »
-
3D Automotive Printing Market Size & Share Report, 2033GVR Report cover

3D Automotive Printing Market (2026 - 2033)
Size, Share & Trends Analysis Report By Offering (Hardware, Software), By Type (SLA, SLS, FDM), By Material, By Component, By Application, By Region, And Segment Forecasts
Market Size, 2025
$4.5BMarket Estimate, 2026
$5.5BMarket Forecast, 2033
$24.0BCAGR, 2026–2033
23.3%3D Automotive Printing Market Summary
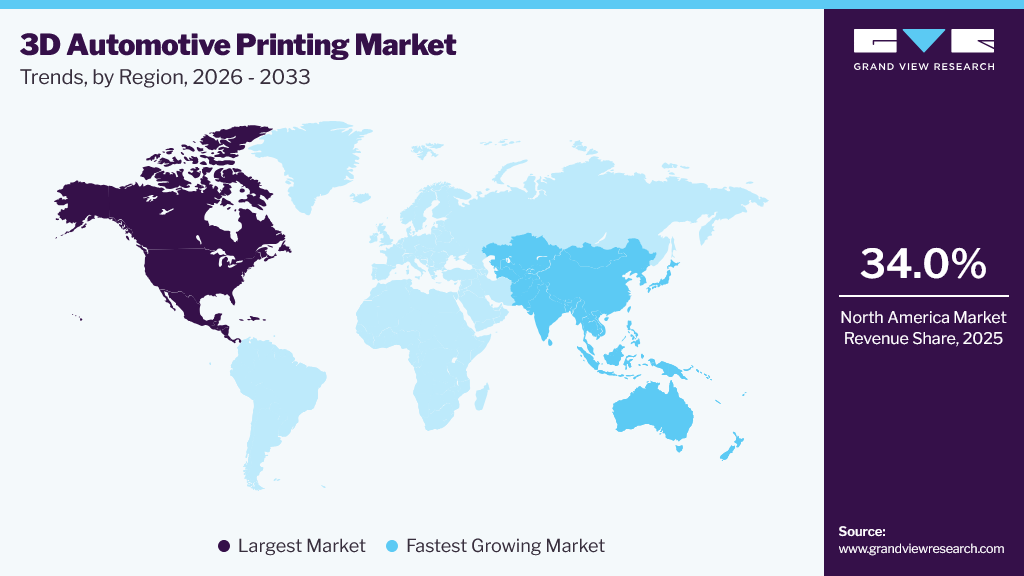
The global 3D automotive printing market size was valued at USD 4.5 billion in 2025 and is projected to grow from USD 5.5 billion in 2026 to USD 24.0 billion in 2033, at a CAGR of 23.3% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 34.0% in 2025. The rising demand for customized products in the automotive industry has become a significant driver of market advancement and growth.
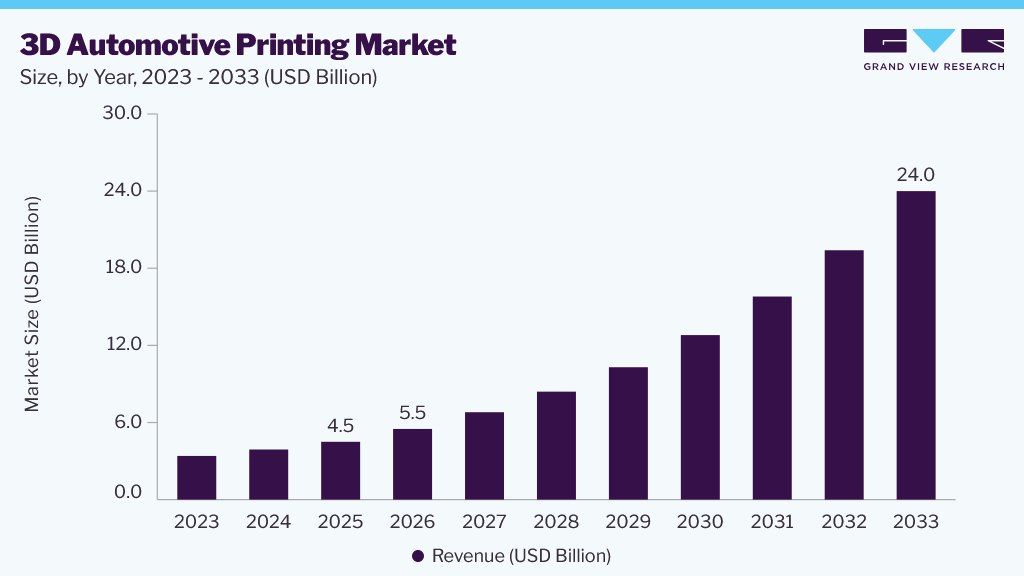 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By offering: The hardware segment dominated the market, accounting for the largest revenue share of over 67.0% in 2025.
- By application: The prototyping segment dominated the target market with the largest revenue share in 2025.
- By type: The fused deposition modeling (FDM) segment dominated the market with the largest revenue share in 2025.
- By material: The metal segment dominated the market with the largest revenue share in 2025.
- By component: The interior segment dominated the market with the largest revenue share in 2025.
Regional Highlights
- Largest regional market: North America (34.0% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 4.5 Billion
- Estimated market size in 2026: USD 5.5 Billion
- Projected market size by 2033: USD 24.0 Billion
- CAGR (2026-2033): 23.3%
Prism AI by Grand View Research Free to tryAsk a question about the 3D automotive printing marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
Additive manufacturing allows manufacturers to produce parts tailored to individual customer specifications. This capability is particularly beneficial for luxury and high-performance vehicles where buyers often seek unique features. In March 2026, BMW AG (the BMW Group) announced that it is further industrializing additive manufacturing by integrating highly automated production systems and open-material technologies at its Additive Manufacturing Campus. Additive Manufacturing Campus strengthens technological breadth and automation.Additive manufacturing significantly accelerates the product development cycle by enabling rapid prototyping, allowing automotive manufacturers to quickly produce and test multiple iterations of a component. This technology streamlines the design process, reducing the time required to move from concept to final product. As a result, companies can efficiently refine and validate designs, addressing potential issues early in development. This expedited timeline not only enhances productivity but also provides a competitive advantage by allowing faster adaptation to market demands and technological advancements. For instance, in January 2025, General Motors highlighted that additive manufacturing is being used across its design, engineering, vehicle manufacturing, and motorsports operations to accelerate prototype development, simplify tooling, and reduce product development time.
The use of lightweight materials in 3D printing is a significant trend in the automotive industry. This trend is driven by the need to reduce vehicle weight, improve fuel efficiency, and lower emissions. In traditional manufacturing processes, such as casting or machining, producing lightweight components can be challenging due to limitations in design and material properties. However, 3D printing enables the creation of complex geometries and the use of lightweight materials that meet the structural requirements of automotive parts while reducing overall weight. For instance, carbon fiber-reinforced polymers (CFRP) are lightweight materials employed in 3D printing. CFRP composites offer high strength-to-weight ratios, making them ideal for applications where weight reduction is crucial, such as in the aerospace and automotive industries. By incorporating carbon fiber into 3D printed parts, automotive manufacturers can achieve significant weight savings without compromising structural integrity.
The adoption of 3D printing for the development of electric and autonomous vehicles is a significant trend in the automotive industry. Major automotive companies, including BMW AG, Ford Motor Company, AB Volvo, General Motors, and Dr. Ing. h.c. F. Porsche AG utilizes 3D printing technology in this area. 3D printing offers advantages such as faster production times, cost savings, and the ability to create complex geometries that traditional manufacturing processes may struggle to achieve. As the electric and autonomous vehicle market continues to grow, 3D printing technology is expected to play a crucial role in driving innovation and advancement in the automotive industry.
Analyst Perspective
The role of automotive additive manufacturing is evolving from building prototyping to enabling the large-scale production of automotive components. This is attributed to the advancements in automation, materials, and digital manufacturing technologies. Automotive manufacturers are increasingly adopting additive manufacturing to accelerate product development, reduce tooling costs, and produce lightweight, high-performance components. 3D printing also offers greater design flexibility and enables part customization, making it a preferred choice for luxury, electric, and autonomous vehicles that require complex designs and design iterations. In addition, leading automotive companies are investing in dedicated additive manufacturing facilities and advanced production technologies, highlighting the industry's growing focus on scaling this technology for production. As the automotive sector shifts toward EVs, lower carbon emissions, and more resilient supply chains, additive manufacturing is expected to play a significant role in automotive manufacturing during the forecast period.
Offering Insights
By offering, the hardware segment dominated the market, accounting for over 67.0% of revenue in 2025. This is due to its essential role in additive manufacturing, continuous technological innovation, diverse product offerings, intense market competition, and adherence to industry standards and certifications. As additive manufacturing continues to revolutionize the automotive industry, hardware manufacturers will remain key players driving innovation and market growth. Manufacturers are constantly developing new printer models with enhanced features such as larger build volumes, faster printing speeds, and higher resolution. For instance, in April 2025, Stratasys introduced the Neo800+ stereolithography (SLA) 3D printer, designed to deliver faster print speeds, enhanced accuracy, and improved productivity for automotive manufacturers. These advancements enable automotive companies to produce complex components with greater precision and efficiency, driving demand for 3D printing hardware.
The services segment is expected to register the highest CAGR of approximately 26.0% over the forecast period. As the adoption of additive manufacturing technology grows within the automotive industry, many companies are seeking external expertise and services to supplement their in-house capabilities. Outsourcing 3D printing services allows automotive manufacturers to access specialized skills, equipment, and resources without making substantial investments in infrastructure or training.
Application Insights
Prototyping dominated the target market with the largest revenue share in 2025. Prototyping is a critical stage in the automotive manufacturing process. Before finalizing designs for mass production, automotive manufacturers need to create prototypes to test the functionality, aesthetics, and performance of various components. Additive manufacturing offers significant advantages in this regard, as it enables rapid, cost-effective production of prototypes with complex geometries and intricate details. In addition, printing enables iterative design processes, allowing engineers to quickly modify and refine designs based on test results and feedback. This iterative approach accelerates the development cycle, reducing time-to-market for new vehicle models.
The production segment is expected to grow at the fastest CAGR over the forecast period. This growth can be attributed to the industry’s transformative shift towards more customizable and on-demand manufacturing models. Consumers are increasingly demanding personalized vehicles with unique features and designs. 3D printing enables manufacturers to efficiently produce customized parts without the need for expensive tooling or lengthy retooling processes. For instance, in November 2025, HP introduced new industrial additive manufacturing solutions and expanded its Additive Manufacturing Network (AMN) program to simplify large-scale production and enable manufacturers to produce parts on demand at lower cost and with improved efficiency. This flexibility in manufacturing aligns well with the evolving demands of the market.
Type Insights
The fused deposition modeling (FDM) segment dominated the market with the largest revenue share in 2025. FDM technology is known for its relatively low cost compared to other additive manufacturing processes. The affordability of FDM printers and materials makes them accessible to a wide range of automotive manufacturers, including small and medium-sized enterprises (SMEs) with limited budgets. This cost-effectiveness has contributed to the widespread adoption of FDM technology within the automotive industry. In addition, FDM technology is scalable and can be used to produce both small and large-scale automotive components. Whether manufacturing a single prototype or producing batches of end-use parts, FDM printers can accommodate varying production volumes, making them suitable for automotive manufacturers of all sizes.
The stereolithography (SLA) segment is expected to grow at the fastest CAGR over the forecast period. SLA printers are known for their high printing speed and efficiency compared to other additive manufacturing technologies, such as selective laser sintering (SLS). The fast build times offered by SLA technology enable automotive manufacturers to accelerate their product development cycles and reduce time-to-market for new vehicle models and components. In addition, recent advancements in SLA technology have led to the development of printers with larger build volumes, capable of producing larger automotive components or multiple parts simultaneously.
Material Insights
The metal segment dominated the market with the largest revenue share in 2025. Metal 3D printing offers superior mechanical properties compared to other materials commonly used in automotive manufacturing, such as plastics or composites. Metals like titanium, aluminum, and stainless steel provide high strength, durability, and heat resistance, making them suitable for producing critical automotive components such as engine parts, brackets, and structural components. In addition, metal 3D printing technologies, such as fused deposition modeling (FDM) and electron beam melting (EBM), enable the production of high-performance, complex parts with tight tolerances and intricate geometries. For instance, in October 2025, EOS expanded its metal additive manufacturing portfolio by introducing four new metal materials optimized for Laser Powder Bed Fusion (LPBF) systems.
The polymer segment is expected to grow at the fastest CAGR over the forecast period. Polymer-based 3D printing offers a wide range of materials with diverse properties, including acrylonitrile butadiene styrene (ABS), polylactic acid, nylon, polyethylene terephthalate glycol (PETG), and thermoplastic polyurethane (TPU). These materials can be engineered to meet specific performance requirements, such as strength, flexibility, heat resistance, and chemical resistance. With ongoing material innovation and development, polymer 3D printing in the automotive industry continues to expand its use across prototyping, tooling, and end-use parts production.
Component Insights
The interior component segment dominated the market with the largest revenue share in 2025. Interior components often feature intricate designs and complex geometries that are challenging to manufacture using traditional methods. Additive manufacturing technologies, such as fused deposition modeling (FDM) and stereolithography (SLA), offer the flexibility to produce highly detailed and customized interior components, including dashboard panels, center consoles, door handles, and trim pieces. In addition, interior components play a significant role in reducing vehicle weight to improve fuel efficiency and overall performance. 3D printing allows us to manufacture lightweight yet durable interior parts using advanced polymers or composite materials. For instance, in April 2025, General Motors announced that the Cadillac CELESTIQ incorporates more than 130 additively manufactured components, including interior grab handles, console décor, window switches, and structural interior parts.
The exterior segment is expected to grow at the fastest CAGR over the forecast period. The segment's dominance can be attributed to the innovation in design and customization enabled by 3D printers. Exterior components, such as body panels, grilles, spoilers, and trim pieces, play a crucial role in defining a vehicle's aesthetics and brand identity. 3D printing technology enables automotive designers to explore innovative and customizable designs for exterior components, including complex geometries, intricate patterns, and textured surfaces. This design flexibility allows for greater differentiation and personalization of vehicles, driving demand for 3D-printed exterior components. For instance, in September 2025, Porsche unveiled the interior and exterior design philosophy of the upcoming Cayenne Electric, highlighting expanded personalization options through Porsche Exclusive Manufaktur and the Sonderwunsch program.
Regional Insights
North America asserted its dominance in 2025, capturing the largest revenue share at approximately 34.0%. This dominance can be attributed to a robust automotive industry with a high concentration of manufacturers, suppliers, and research institutions. This ecosystem fosters innovation and collaboration in adopting advanced manufacturing technologies like 3D printing. In addition, North America is home to leading additive manufacturing technology providers such as Stratasys Ltd., 3D Systems Corporation, Autodesk, Inc., and service bureaus specializing in automotive applications. These companies offer a wide range of 3D printing solutions tailored to automotive manufacturers' needs, including advanced materials, large-scale production capabilities, and expertise in design optimization.
 To learn more about this report, Download Free Sample Report
U.S. 3D Automotive Printing Market Trends
The 3D automotive printing market in the U.S. held the largest share of approximately 54.0% in North America in 2025 and is also anticipated to grow at a significant CAGR from 2025 to 2033. The U.S. government has been supportive of additive manufacturing technologies through initiatives such as funding for research and development, workforce training programs, and partnerships with industry stakeholders. These efforts have helped to accelerate the adoption of 3D printing in various sectors, including automotive manufacturing. For instance, in April 2025, America Makes and the National Center for Defense Manufacturing and Machining (NCDMM) announced a new open project call funded by the Office of the Under Secretary of Defense, Manufacturing Technology Office (OSD ManTech) worth a total of USD 4.5M. The project is called Improvements in Manufacturing Productivity.
Europe 3D Automotive Printing Market Trends
The 3D automotive printing market in Europe is on the rise, driven by several key factors. Europe is home to a highly advanced automotive industry with a strong focus on innovation and technology. Major automotive manufacturers and suppliers in countries like Germany, France, Italy, and the UK are increasingly integrating additive manufacturing technologies into their production processes to enhance efficiency, reduce costs, and accelerate product development cycles. In addition, Europe has a well-established network of research institutions, universities, and technology centers specializing in additive manufacturing and automotive engineering. Collaborative research projects and partnerships between academia and industry are driving innovation and advancements in 3D printing technologies tailored to automotive applications.
The UK 3D automotive printing market is driven by a combination of factors, including industry expertise, government support, sustainability goals, technological innovation, and market demand for customization. As the automotive industry continues to evolve, 3D printing is expected to play a significant role in driving innovation and competitiveness in the U.K. automotive sector.
Asia Pacific 3D Automotive Printing Market Trends
The 3D automotive printing market in the Asia Pacific recorded the fastest CAGR of over 25.0% over the forecast period. The presence of a large consumer market in the Asia Pacific drives demand for customized and personalized automotive products. 3D printing enables manufacturers to offer tailor-made solutions, such as custom-designed interior components and personalized vehicle accessories, catering to diverse consumer preferences and enhancing market competitiveness. In addition, the availability of skilled labor and relatively low labor costs in certain countries in the Asia-Pacific region contribute to the region's attractiveness for adopting 3D printing. This allows automotive manufacturers to leverage additive manufacturing technologies cost-effectively while maintaining high production standards.
China 3D automotive printing market is experiencing significant growth, driven by the rising adoption of electric vehicles and autonomous driving technologies across the country, supported by government incentives and environmental concerns. Collaborations and partnerships between automotive companies and 3D printing technology companies are also driving market growth in the region. For instance, in November 2025, Farsoon Technologies and automotive supplier Brose announced their collaboration to advance metal 3D printing for automotive manufacturing, supporting the production of complex, lightweight, and high-performance vehicle components for serial production.
Key 3D Automotive Printing Companies Insights
Some of the key companies operating in the market include Stratasys Ltd. and 3D Systems Corporation.
-
Stratasys Ltd. is one of the leading manufacturers of additive manufacturing printers and solutions. The company specializes in producing a wide range of 3D printing technologies, including fused deposition modeling (FDM) and stereolithography (SLA). Stratasys serves various industries, including aerospace, automotive, healthcare, and consumer goods, by providing solutions for rapid prototyping, tooling, and production of end-use parts. It operates globally and has a significant presence in the additive manufacturing market.
-
3D Systems Corporation is a comprehensive 3D printing and digital manufacturing solutions provider based in the U.S. The company offers a range of products and services, including 3D printers for both plastics and metals, software solutions for design and production optimization, on-demand manufacturing services, and digital design tools. With a global presence, 3D Systems operates through multiple offices and facilities across North America, Latin America, Europe, the Middle East & Africa, and Asia Pacific regions. The company's offerings cater to various industries, including automotive, aerospace, healthcare, consumer goods, and more.
Voxeljet AG and EOS GmbH are some of the emerging market companies in the target market.
-
Voxeljet AG is a supplier of 3D printing systems for industrial applications. The company specializes in powder-binder-jetting technology, which offers geometric freedom for complex designs and optimization of manufacturing processes. The company provides comprehensive 3D printing solutions, including printers for plastics, metals, and ceramics, as well as materials, software, on-demand manufacturing services, and digital design tools.
-
EOS GmbH is an emerging player in the additive manufacturing industry, specializing in industrial 3D printing solutions. It offers advanced technology and a wide range of solutions for industrial 3D printing of metals and plastics. The expertise lies in technologies such as selective laser sintering (SLS) and direct metal laser sintering (DMLS).
Key 3D Automotive Printing Companies
The following key companies have been profiled for this study on the 3D automotive printing market:
-
3D Systems Corporation
-
Stratasys Ltd.
-
Voxeljet AG
-
Materialize NV
-
Autodesk, Inc.
-
The ExOne Company
-
Envisiontec GmbH
-
Ultimaker BV
-
Nexa3D
-
SLM Solutions
-
EOS GmbH
-
Desktop Metal, Inc.
Recent Developments
-
In November 2025, ROCK HILL, South Carolina, announced the launch of a range of new products in its Stereolithography (SLA) portfolio at Formnext 2025, designed to help customers meet a variety of application needs and accelerate innovation. The new systems are designed to improve productivity, precision, and throughput for industrial manufacturing, including automotive prototyping and end-use component production.
-
In November 2025, EOS introduced the EOS M4 ONYX metal additive manufacturing platform, offering higher productivity, automated workflows, and improved process stability to support industrial-scale production of complex metal components for sectors including automotive.
-
In March 2024, Stratasys Ltd. announced that it had acquired the technology portfolio and intellectual property (IP) of Arevo, Inc., a technology company based in Silicon Valley, California, that specializes in direct digital additive manufacturing of parts using composite materials. This acquisition includes foundational patents in carbon fiber printing, Z-strength improvement, in situ and AI-based build monitoring, and hardware design. By integrating this technology into Stratasys' FDM print systems, the company aims to expand its manufacturing applications and offer higher-performing parts, more reliable builds, and improved system throughput.
-
In March 2024, EOS GmbH launched the EOS M 290 1kW, a new Laser Powder Bed Fusion (LPBF) metal additive manufacturing (AM) platform designed for serial production. The EOS M 290 1kW is suitable for various industries, including automotive, and offers an extensive range of validated materials and processes. This platform aims to provide enhanced design flexibility, reduced weight, and greater cost-effectiveness in metal additive manufacturing.
-
In April 2024, Materialize NV introduced three new materials to enhance accessibility in industrial 3D printing. These materials include Polyamide 11 (PA11), Bluesint PA12, and AlSiMg aluminum alloy. PA11 is a 100% bio-based polymer made from castor beans, Bluesint PA12 allows for 3D printing with up to 100% re-used powder, and AlSiMg is a strong and lightweight aluminum alloy suitable for industries like automotive and aerospace. These materials offer improved performance and reliability, addressing the specific needs of automotive manufacturers in prototyping, tooling, and end-use part production. The new materials aim to expand the capabilities of additive manufacturing in the automotive industry, enabling faster development cycles, cost savings, and greater design freedom.
3D Automotive Printing Market Report Scope
Report Attribute
Details
Market size in 2025
USD 4.5 billion
Estimated market size in 2026
USD 5.5 billion
Projected market size by 2033
USD 24.0 billion
Growth rate
CAGR of 23.3% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Offering, type, material, component, application, region
Regional scope
North America; Europe; Asia Pacific; CSA; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Spain; China; Japan; India; South Korea; Brazil; Saudi Arabia; UAE; South Africa
Key companies profiled
3D Systems Corporation; Stratasys Ltd.; Voxeljet AG; Materialise NV; Autodesk, Inc.; The ExOne Company; Envisiontec GmbH; Ultimaker BV; Nexa3D; SLM Solutions; EOS GmbH; Desktop Metal, Inc.
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global 3D Automotive Printing Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global 3D automotive printing market report based on offering, type, material, component, application, and region:
- Offering Outlook (Revenue, USD Billion, 2021 - 2033)
- Hardware
- Extrusion System
- Motion System
- Build Platform Environs
- Control And Monitoring System
- Software
- Design Software
- Inspection Software
- Printer Software
- Scanning Software
- Services
- Hardware
- Type Outlook (Revenue, USD Billion, 2021 - 2033)
- Stereolithography (SLA)
- Selective Laser Sintering (SLS)
- Fused Deposition Modeling (FDM)
- Electron Beam Melting (EBM)
- Digital Light Processing (DLP)
- Others
- Material Outlook (Revenue, USD Billion, 2021 - 2033)
- Metal
- Polymer
- Ceramic
- Component Outlook (Revenue, USD Billion, 2021 - 2033)
- Interior Component
- Exterior Component
- Application Outlook (Revenue, USD Billion, 2021 - 2033)
- Prototyping
- Tooling
- Production
- Others
- Regional Outlook (Revenue, USD Billion, 2021 - 2033)
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- Germany
- France
- Spain
- Asia Pacific
- China
- Japan
- India
- South Korea
- Latin America
- Brazil
- Middle East and Africa (MEA)
- Kingdom of Saudi Arabia (KSA)
- UAE
- South Africa
- North America
Frequently Asked Questions About This Report
The global 3D automotive printing market size was valued at USD 4.5 billion in 2025 and is estimated at USD 5.5 billion for 2026.
The global 3D automotive printing market is expected to grow at a CAGR of 23.3% from 2026 to 2033, reaching USD 24.0 billion.
North America dominated with an approximately 34.0% revenue share in 2025.
Key players in the market include 3D Systems Corporation, Stratasys Ltd., Voxeljet AG, Materialize NV, Autodesk, Inc., The ExOne Company, Envisiontec GmbH, Ultimaker BV, Nexa3D, SLM Solutions, EOS GmbH, Desktop Metal, Inc., and others.
The hardware 3D automotive printing segment accounted for the largest revenue share of approximately 67.0% in 2025.
About the Author(s)
Next Generation Technologies Research Team
Technology · Next Generation TechnologiesThis report was authored by the next generation technologies research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the next generation technologies segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


