
- Home
- »
- Next Generation Technologies
- »
-
3D Scanning Market Size, Share & Trends Report,2026-2033GVR Report cover

3D Scanning Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Laser Scanner, Structured Light Scanner, Optical Scanner), By Range (Short, Medium, Large), By Component, By Type, By Technology, By Application, By End Use, By Region, And Segment Forecasts
Market Size, 2025
$4.6BMarket Estimate, 2026
$5.1BMarket Forecast, 2033
$9.9BCAGR, 2026–2033
10.0%3D Scanning Market Summary
The global 3D scanning market size was valued at USD 4.6 billion in 2025 and is projected to grow from USD 5.1 billion in 2026 to USD 9.9 billion by 2033, at a CAGR of 10.0% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 40.0% in 2025. The market for 3D scanning is shifting toward integrated hardware-software ecosystems, with companies bundling scanners and advanced visualization platforms to deliver end-to-end solutions.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: The laser scanners segment held the largest market share of around 45.0% in 2025.
- By range: The short-range scanning segment held the largest market share of around 45.0% in 2025.
- By component: The hardware segment held the largest market share of around 70.0% in 2025.
Regional Highlights
- Largest regional market: North America (40.0% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 4.6 Billion
- Estimated market size in 2026: USD 5.1 Billion
- Projected market size by 2033: USD 9.9 Billion
- CAGR (2026-2033): 10.0%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The growing demand for seamless digital workflows across manufacturing, healthcare, construction, and other industries is accelerating the integration of 3D scanners with specialized software platforms. Improved interoperability enhances usability, processing speed, and data accuracy, making ecosystem compatibility an increasingly important competitive factor. For instance, in February 2025, Scantech (Hangzhou) Co., Ltd. partnered with InnovMetric Software Inc. to integrate PolyWorks software with its 3D scanners, providing more comprehensive solutions for industrial measurement and productivity. At the same time, manufacturers are developing high-precision scanners capable of capturing complex surfaces and detailed measurements across applications ranging from manufacturing and healthcare to cultural preservation.Reliability and measurement accuracy are also becoming critical requirements as 3D scanning expands from laboratory environments to field-based applications. Manufacturers are broadening their product portfolios to address diverse professional needs and support applications such as inspection, reverse engineering, and product development. For example, in April 2025, Artec 3D introduced its Artec Point 3D scanner to the Indian market through a partnership with Altem Technologies, targeting industries including aerospace, healthcare, and manufacturing. The collaboration supports wider adoption of 3D scanning for industrial digitization and product design.
Advancements in LiDAR technology are further improving the capabilities of 3D scanners. By using laser pulses to capture detailed spatial information, LiDAR enables faster and more accurate distance measurements, supporting demanding applications in automotive, aerospace, and industrial quality control. Improvements in sensor size, affordability, and integration are also making LiDAR-based solutions more accessible, creating new opportunities for 3D scanning across industries.
Analyst Perspective
The 3D scanning market supports digital inspection, product development, reverse engineering, and asset documentation. Its strategic relevance is increasing as manufacturers pursue faster design cycles and more reliable quality control. Demand is strengthened by the need to capture complex geometries without physical contact. Scanning data also improves dimensional accuracy across manufacturing, construction, healthcare, and cultural preservation. The strongest opportunity lies in portable systems connected to cloud-based analysis platforms. Artificial intelligence can automate feature recognition, defect detection, and comparison against digital models. Competition is shifting toward complete digital measurement ecosystems rather than standalone hardware performance. Integration with digital twins and automated production systems is expected to shape market leadership.
Product Insights
The laser scanners segment accounted for the largest share, around 45.0%, in 2025, because it provides highly accurate and detailed measurements. They are favored in industries such as manufacturing and construction for their precision and speed. Their ability to reliably capture complex surfaces makes them the preferred choice for many applications. Laser scanners excel in environments where exact data is critical. Their established technology and consistent performance help them maintain a strong market presence. This dominance is supported by ongoing advancements that enhance scanning capabilities. Companies investing in laser scanning technology continue to improve their offerings, reinforcing this lead.
The optical scanners segment is expected to grow at a significant CAGR over the forecast period, owing to their affordability and ease of use. They offer non-contact scanning with good resolution, which appeals to sectors such as healthcare and entertainment. Optical scanners benefit from continuous improvements in sensor technology and image processing. These enhancements enable them to deliver faster, more flexible scanning solutions. Their versatility makes them suitable for a wider range of applications. As a result, optical scanners are steadily increasing their market share and influence. Emerging startups and tech firms are actively developing innovative optical scanning products to expand this growth.
Range Insights
The short-range scanning segment accounted for the dominant share of around 45.0% in 2025, due to its high precision and suitability for detailed close-up work. It is widely used in industries such as electronics, medical imaging, and quality inspection, where accuracy is crucial. Short-range scanners can capture fine details with excellent resolution, making them ideal for small objects. Their compact size and ease of use also contribute to their popularity. Many manufacturers prefer short-range scanners for prototyping and design validation. Continuous improvements in sensor technology support this dominance. Overall, short-range scanners meet the demand for precision in many specialized applications.
The long-range scanning segment is expected to grow rapidly over the forecast period as it allows scanning of large objects and environments from a distance. It is increasingly used in construction, surveying, and outdoor mapping, where capturing wide areas quickly is essential. Advances in laser and LiDAR technology have enhanced the accuracy and speed of long-range scanners. Their ability to cover large distances without losing detail makes them valuable for infrastructure and landscape projects. Long-range scanners also benefit from improved portability and real-time data processing. Long-range scanning is gaining more applications and market share as these technologies develop. Many companies are investing in long-range solutions to address growing demand in large-scale industries.
Component Insights
The hardware segment has maintained dominance with around 70.0% market share in 2025, driven by strong demand for high-precision scanning devices. Technological advancements in laser and structured light scanners have improved speed and accuracy. Industries such as automotive, aerospace, and healthcare continue to rely on robust hardware for critical measurement applications. The availability of portable and handheld scanners has expanded use cases in field environments. Hardware providers have focused on durability and ease of integration with downstream applications. Investment in R&D has led to reduced costs and improved functionality of scanning equipment. Demand from quality control and inspection processes has further supported hardware growth. Strong distribution networks and global manufacturing partnerships have sustained the segment’s leading position.
The software segment is experiencing notable growth, driven by the need for improved data processing and analysis. Advancements in AI and machine learning have enhanced point cloud interpretation and modeling accuracy. Growing interest in virtual design, simulation, and reverse engineering has increased reliance on specialized 3D software. Cloud-based solutions have made collaboration and storage more efficient for remote teams. Software updates have enabled compatibility with a wider range of hardware devices. Industries are seeking automation in post-processing tasks to reduce manual intervention. The rise of metaverse applications and digital twins has expanded the scope for 3D scanning software. Partnerships between hardware firms and software developers have further accelerated innovation and adoption.
Type Insights
The tripod-mounted 3D scanners segment dominated the global market in 2025 due to their high precision and stability in fixed environments. These systems are widely used in industries requiring detailed and accurate measurements, such as aerospace and automotive. Their ability to capture large objects with minimal distortion makes them suitable for complex inspection tasks. Integration with advanced software enhances their scanning resolution and reliability. Manufacturers prefer tripod-mounted units for in-house quality control and reverse engineering. Their strong presence in established industrial workflows has helped maintain their dominant position. They are especially favored in applications where consistent environmental conditions can be controlled.
The portable CMM-based 3D scanners segment is anticipated to experience significant growth over the forecast period due to their flexibility and ease of use. They enable precise measurements in environments where fixed systems are impractical. The demand for on-site inspection and real-time data capture is driving their growing adoption. Industries value their ability to scan parts of various sizes and shapes directly on the shop floor. Advances in probe accuracy and wireless connectivity have improved efficiency and usability. Their role in speeding up inspection processes is driving wider market acceptance. Ongoing innovations are making these systems more compact and cost-effective for broader deployment.
Technology Insights
The laser triangulation segment dominated the market in 2025 due to its high accuracy and fast data acquisition. It is widely used in applications requiring detailed surface inspection, such as industrial manufacturing and quality control. The technique works well for short- to medium-range scanning, making it ideal for capturing intricate geometries. Continued enhancements in sensor resolution have improved its effectiveness in detecting small defects. Its compatibility with a variety of materials and finishes increases its versatility across industries. Manufacturers benefit from its reliability and relatively low operating cost. Its established performance and integration into automated systems have helped it maintain a leading position.
The laser pulse-based 3D scanning segment is gaining traction due to its suitability for long-range and outdoor applications. This method is commonly used in construction, mining, and large-scale surveying projects. It can measure distances by calculating the time it takes for laser pulses to return, allowing for accurate scans over hundreds of meters. Advancements in signal processing have increased the precision and speed of data collection. These scanners can operate in challenging lighting and weather conditions, expanding their practical use cases. Growing infrastructure projects and demand for geospatial data are supporting its adoption. Its expanding role in large-area mapping and digital twin creation is accelerating market growth.
Application Insights
The reverse engineering segment dominated the market in 2025, due to its extensive use in product redesign and quality analysis. Industries such as automotive, aerospace, and consumer electronics rely heavily on 3D scanning to replicate and modify existing parts. It enables accurate capture of legacy components that lack CAD documentation. The method supports efficient prototyping by converting physical models into digital designs. Consistent improvements in scanning resolution and software integration have streamlined the reverse engineering process. Manufacturers benefit from reduced production time and cost through accurate part replication. Its central role in innovation and product improvement continues to support its dominance.
The virtual simulation segment is expected to grow at the fastest CAGR over the forecast period as industries aim to enhance digital design workflows. It allows users to simulate product performance and interactions before physical production. Integration of 3D scanned data improves the realism and reliability of simulation models. The approach is widely used in industries that focus on predictive analytics, such as healthcare, defense, and industrial automation. Cloud-based simulation tools and real-time rendering have expanded accessibility. The rising demand for digital twins and immersive design validation supports this growth. Its contribution to reducing development errors and accelerating innovation is driving increased usage.
End Use Insights
The automotive segment dominated the market in 2025, due to its constant demand for precision in design and manufacturing. 3D scanning supports efficient inspection of complex components and surface geometries. It helps ensure tight tolerances in engine parts, body panels, and assemblies. Reverse engineering of legacy parts is widely practiced to maintain and replicate older vehicle components. Automotive OEMs use 3D scanning to streamline prototyping and speed up product development. Integration with CAD and simulation tools further enhances its utility in this sector. The industry's focus on quality, efficiency, and innovation has reinforced its dominant market role.
The healthcare segment is expected to witness the fastest CAGR over the forecast period, driven by demand for patient-specific solutions. The technology is increasingly used in prosthetics, orthotics, and dental applications. High-resolution scanning allows for accurate modeling of anatomical structures. Surgeons use 3D scans for preoperative planning and custom implant design. Advancements in portable and non-invasive scanners have improved adoption in clinical settings. The push toward personalized medicine is accelerating demand for precise medical modeling. Its ability to improve outcomes and streamline medical workflows is supporting ongoing market growth.
Regional Insights
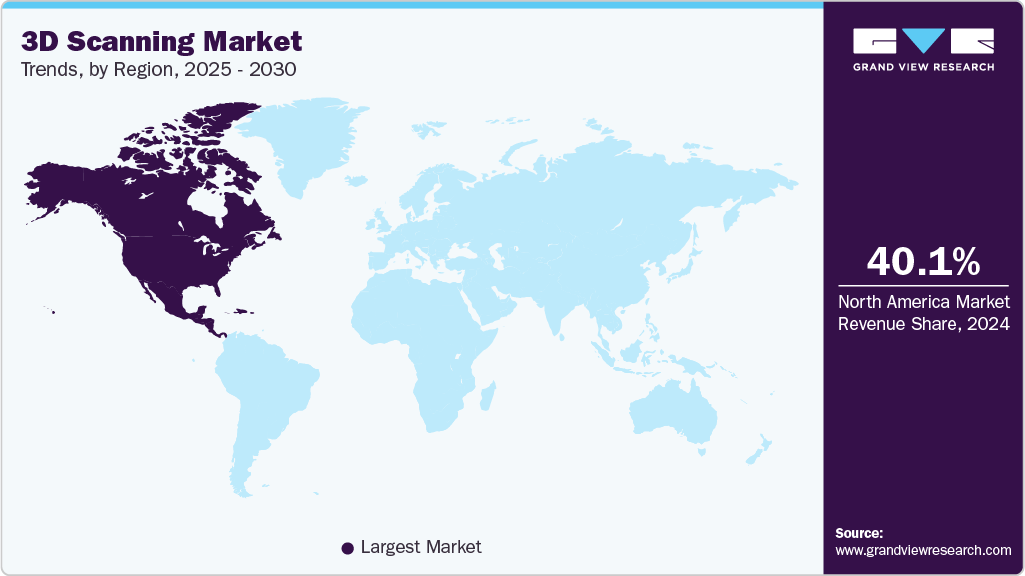
The 3D scanning industry in North America leads the global market, accounting for around 40.0% in 2025. North America holds a strong position in the market due to the presence of advanced manufacturing industries. Sectors such as aerospace, automotive, and healthcare heavily invest in precision measurement technologies. Government support and private sector initiatives encourage innovation through R&D and technology deployment. Increasing use of 3D scanning in quality control and prototyping has sustained demand. The region also benefits from the presence of leading 3D scanning solution providers across multiple industries.
 To learn more about this report, Download Free Sample Report
U.S. 3D Scanning Market Trends
The 3D scanning industry in the U.S. is the largest contributor in the North American market. High demand from the automotive, defense, and medical device industries drives market growth. Strong digital infrastructure supports simulation and digital twins with scanned data. The country is home to key software and hardware manufacturers who frequently launch updated solutions. Education and research institutions also contribute to adoption through training and pilot programs.
Europe 3D Scanning Market Trends
The 3D scanning industry in Europe is driven by strong engineering and industrial design traditions. Countries such as Germany, France, and the UK use 3D scanning in the automotive, aerospace, and cultural heritage preservation sectors. Emphasis on innovation and sustainability supports scanning in reverse engineering and product lifecycle management. Regulatory support for digitization and precision inspection encourages wider use. The presence of high-tech manufacturing hubs keeps demand steady across the region.
Asia Pacific 3D Scanning Market Trends
The 3D scanning industry in Asia Pacific is experiencing rapid growth due to expanding industrial bases. China, Japan, South Korea, and India are adopting scanning for automotive, electronics, and healthcare applications. Increased investment in infrastructure and smart manufacturing is driving regional demand. Local players are entering the market, offering cost-effective solutions tailored to domestic industries. Rising awareness and training initiatives are further accelerating adoption.
Key 3D Scanning Company Insights
Some of the key companies in the 3D scanning industry include 3D Systems, Inc., Artec 3D, Creaform, FARO, Hexagon AB, Konica Minolta, Inc., and others. Organizations are focusing on increasing their customer base to gain a competitive edge in the industry. Therefore, key players are taking several strategic initiatives, such as mergers and acquisitions, and partnerships with other major companies.
-
3D Systems, Inc. has contributed significantly to the development of 3D scanning through its integrated hardware and software solutions. The company offers a range of structured light and laser-based scanners designed for reverse engineering, inspection, and design. Its Geomagic software suite enhances the processing and modeling of scanned data. 3D Systems supports industries such as healthcare, aerospace, and manufacturing. Continuous innovation in scan accuracy and usability keeps the company relevant in advanced applications.
-
Artec 3D is known for high-performance handheld 3D scanners used in industrial design, forensics, and healthcare. Its scanners employ structured light technology, offering real-time processing and high-resolution capture. Artec Studio software improves workflow with advanced AI-driven features. The company focuses on portability, speed, and precision to meet a variety of professional needs. Artec's consistent product updates and global reach have strengthened its role in the 3D scanning industry.
Key 3D Scanning Companies
The following key companies have been profiled for this study on the 3D scanning market:
-
3D Systems, Inc.
-
Artec 3D
-
Creaform
-
FARO
-
Hexagon AB
-
Konica Minolta, Inc.
-
Nikon Metrology NV
-
Perceptron, Inc. (Atlas Copco AB)
-
Trimble Inc.
-
ZEISS
Recent Developments
-
In June 2025, Creaform announced a strategic licensing agreement with HP to introduce HP DesignScan. The professional-grade solution combines Creaform’s scanning technology with HP’s established product ecosystem. The partnership expands access to high-accuracy 3D scanning for professionals and small businesses. It also supports broader adoption across product design and engineering workflows.
-
In May 2024, Hexagon's manufacturing intelligence division introduced innovative handheld 3D scanning technology devices, ATLASCAN Max and MARVELSCAN, to enhance its diverse product line of manufacturing inspection devices. These devices are ideal for measuring parts in various inspection settings, including rail, automotive, industrial equipment, and general manufacturing.
3D Scanning Market Report Scope
Report Attribute
Details
Market size in 2025
USD 4.6 billion
Estimated market size in 2026
USD 5.1 billion
Projected market size by 2033
USD 9.9 billion
Growth rate
CAGR of 10.0% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, range, component, type, technology, application, end use, region
Regional Scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country Scope
U.S.; Canada; Mexico; Germany; UK; France; China; Japan; India; Australia; South Korea; Brazil; KSA; UAE; South Africa
Key companies profiled
3D Systems, Inc.; Artec 3D; Creaform; FARO; Hexagon AB; Konica Minolta, Inc.; Nikon Metrology NV; Perceptron, Inc. (Atlas Copco AB); Trimble Inc.; ZEISS
Customization scope
Free report customization (equivalent to 8 analyst working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global 3D Scanning Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends and opportunities across each sub-segment from 2021 to 2033. For this study, Grand View Research has segmented the global 3D scanning market report based on product, range, component, type, technology, application, end use, and region:
- Product Outlook (Revenue, USD Billion, 2021 - 2033)
- Laser Scanner
- Structured Light Scanner
- Optical Scanner
- Others
- Range Outlook (Revenue, USD Billion, 2021 - 2033)
- Short-Range
- Medium Range
- Long-Range
- Component Outlook (Revenue, USD Billion, 2021 - 2033)
- Hardware
- Software
- Services
- Type Outlook (Revenue, USD Billion, 2021 - 2033)
- Tripod Mounted
- Fixed CMM Based
- Portable CMM Based
- Desktop
- Technology Outlook (Revenue, USD Billion, 2021 - 2033)
- Laser Triangulation
- Pattern Fringe Triangulation
- Laser Pulse Based
- Laser Phase-shift Based
- Application Outlook (Revenue, USD Billion, 2021 - 2033)
- Reverse Engineering
- Quality Control & Inspection
- Virtual Simulation
- Others
- End Use Outlook (Revenue, USD Billion, 2021 - 2033)
- Automotive
- Aerospace & Defense
- Healthcare
- Architecture & Construction
- Education & Research
- Media & Entertainment
- Robotics & Automation
- Others
- Regional Outlook (Revenue, USD Billion, 2021 - 2033)
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- Germany
- France
- Asia Pacific
- China
- Japan
- India
- Australia
- South Korea
- Latin America
- Brazil
- Middle East & Africa (MEA)
- KSA
- UAE
- South Africa
- North America
Frequently Asked Questions About This Report
The global 3D scanning market size was valued at USD 4.6 billion in 2025 and is estimated at USD 5.1 billion in 2026.
The global 3D scanning market is expected to grow at a CAGR of 10.0% from 2026 to 2033, reaching USD 9.9 billion.
The North America region dominated the global 3D scanning market, accounting for approximately 40.0% of revenue in 2025.
Key players in the market include 3D Systems, Inc., Artec 3D, Creaform, FARO, Hexagon AB, Konica Minolta, Inc., Nikon Metrology NV, Perceptron, Inc. (Atlas Copco AB), Trimble Inc., and ZEISS, among others.
The laser scanners segment accounted for the largest revenue share of around 45.0% in 2025.
About the Author(s)
Next Generation Technologies Research Team
Technology · Next Generation TechnologiesThis report was authored by the next generation technologies research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the next generation technologies segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


