
- Home
- »
- Next Generation Technologies
- »
-
5G RAN Professional Services Market Size Report, 2033GVR Report cover

5G RAN Professional Services Market (2026 - 2033
Size, Share & Trends Analysis Report By Service Type (Consulting Services, Planning & Design Services), By Deployment Mode (On-premises, Cloud), By End Use, By Region, And Segment Forecasts
Market Size, 2025
$7.5BMarket Estimate, 2026
$9.2BMarket Forecast, 2033
$22.3BCAGR, 2026–2033
13.5%5G RAN Professional Services Market Summary
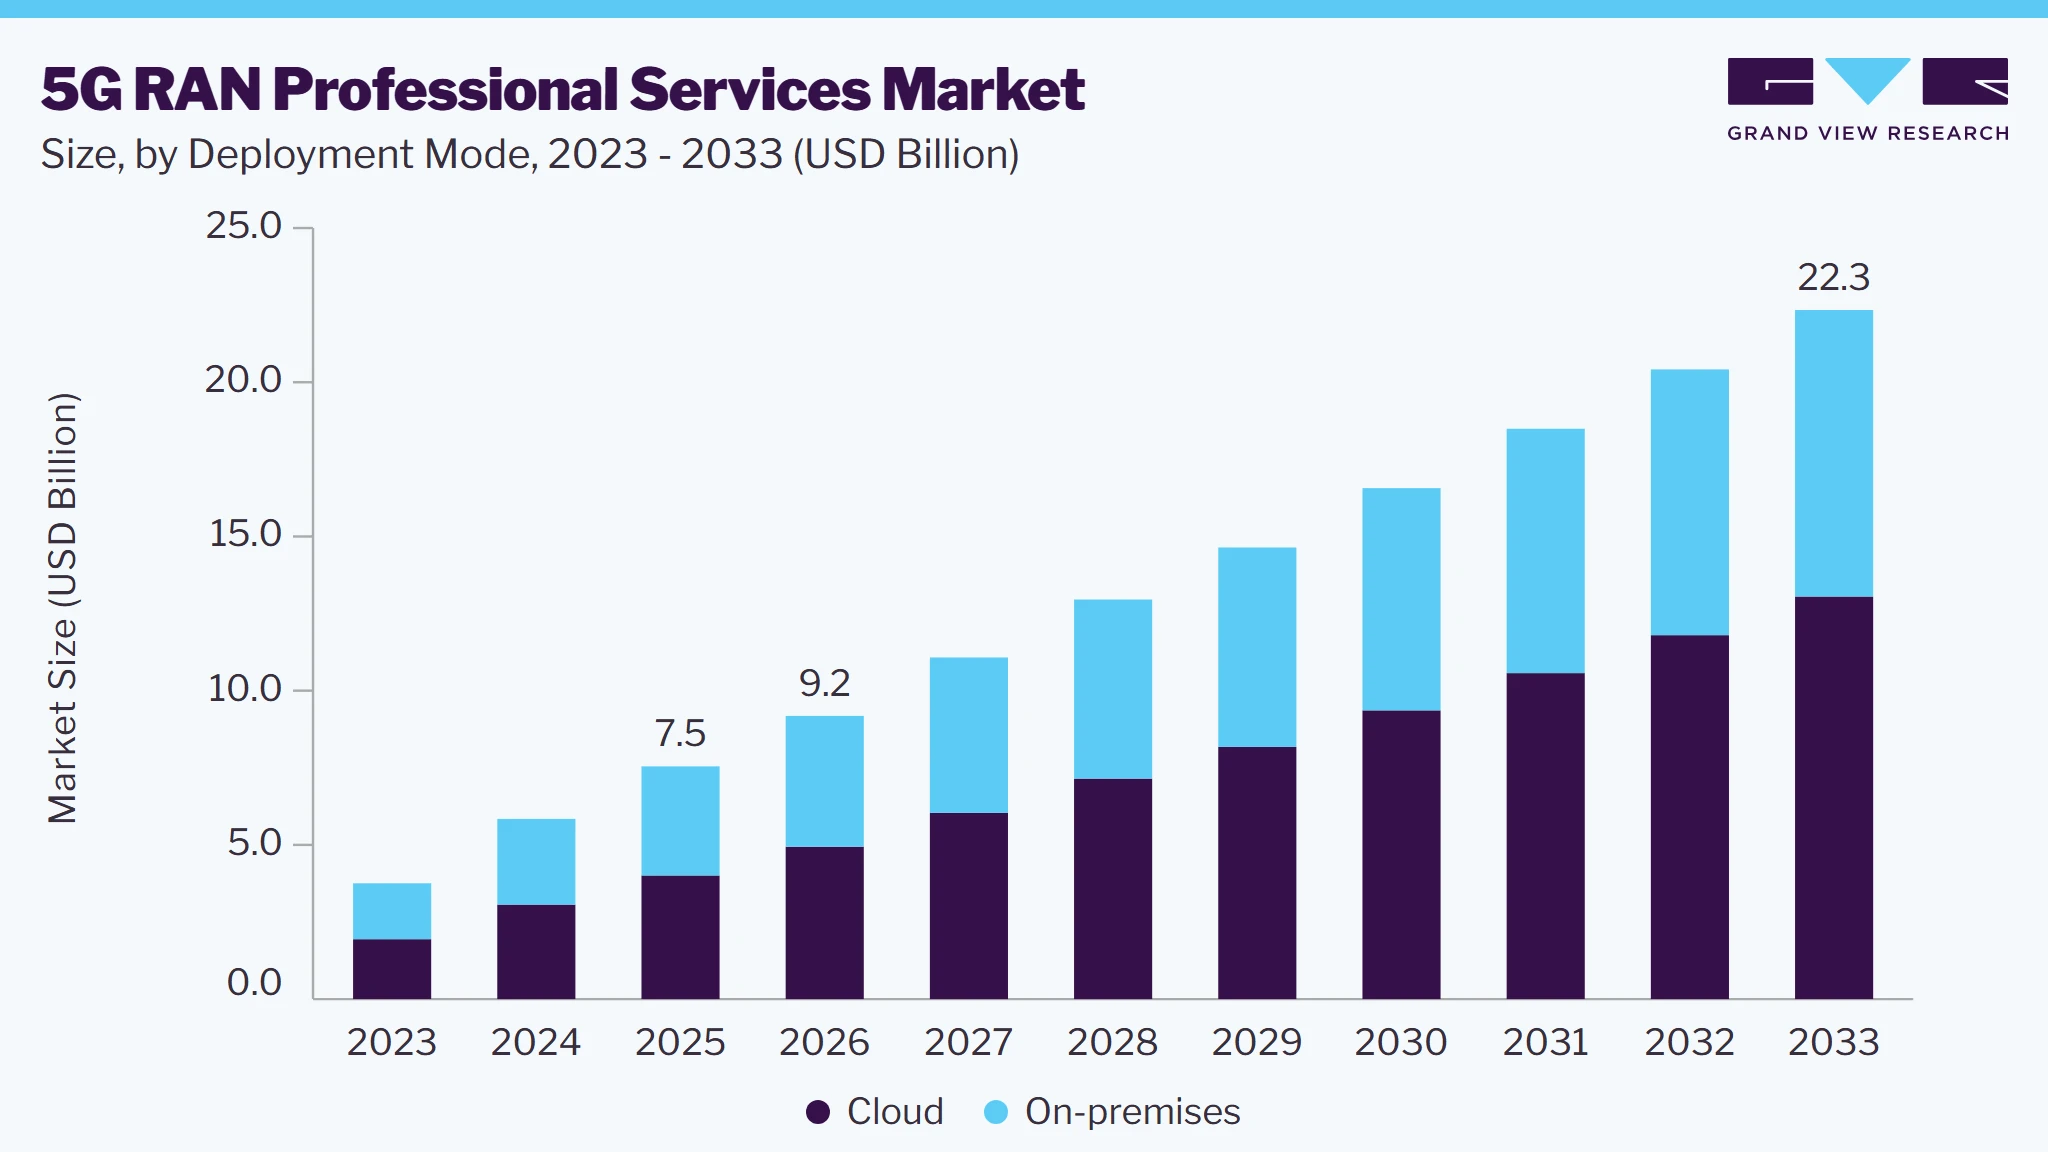
The global 5G RAN professional services market size was valued at USD 7.5 billion in 2025 and is projected to grow from USD 9.2 billion in 2026 to USD 22.3 billion by 2033, at a CAGR of 13.5% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 42.2% in 2025. The market is witnessing rapid growth, driven by the global rollout of 5G networks and the increasing complexity of deploying and managing next-generation radio access infrastructure.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By service type: Deployment services segment dominated the market, with a revenue share of 25.9% in 2025
- By deployment mode: Cloud segment held the largest market share of 53.1% in 2025
- By end use: Telecom Operators segment accounted for the largest revenue share in 2025
Regional Highlights
- Largest regional market: Asia Pacific (42.2% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 7.5 Billion
- Estimated market size in 2026: USD 9.2 Billion
- Projected market size by 2033: USD 22.3 Billion
- CAGR (2026-2033): 13.5%
Prism AI by Grand View Research Free to tryAsk a question about the 5G RAN professional services marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
Key drivers include the rising demand for high-speed, low-latency connectivity, growing mobile data consumption, and the proliferation of Internet of Things (IoT) devices. Telecom operators are increasingly relying on professional services for network planning, integration, optimization, and maintenance to accelerate 5G deployments and ensure quality of service. In addition, the shift toward cloud-native and virtualized network architectures is fueling demand for specialized expertise to manage complex 5G RAN environments.Technological advancements are significantly shaping the 5G RAN professional services landscape. The adoption of Open RAN, virtual RAN (vRAN), and massive MIMO technologies is transforming how networks are designed and deployed, necessitating tailored professional services to support multi-vendor ecosystems and ensure interoperability. Artificial intelligence (AI) and machine learning (ML) are also being integrated into network operations, enabling predictive maintenance, self-healing capabilities, and dynamic resource allocation. These trends are expanding the scope of professional services to include AI-driven automation, software integration, and continuous network performance tuning.
 To learn more about this report, Download Free Sample Report
Substantial investments from both the public and private sectors are also bolstering the market. Governments across the globe are launching national 5G strategies and providing funding to accelerate infrastructure development. At the same time, telecom operators and equipment vendors are investing heavily in R&D, pilot deployments, and the development of 5G-ready services. This influx of capital is not only accelerating network rollouts but also increasing the demand for skilled service providers capable of handling complex 5G RAN integration, testing, and lifecycle management tasks across diverse geographies.
Regulatory frameworks are playing a crucial role in shaping the 5G RAN professional services market. National telecom regulators actively allocate spectrum, define network security guidelines, and set standards for network interoperability and vendor diversity, particularly in support of Open RAN. In regions such as the U.S. and Europe, regulatory policies are encouraging the use of secure, energy-efficient, and multi-vendor solutions. These efforts are creating both opportunities and challenges for professional service providers, who must navigate evolving compliance requirements while helping clients build and maintain regulatory-compliant 5G networks.
Despite its growth potential, the 5G RAN professional services market faces several constraints. A major challenge is the shortage of skilled professionals with expertise in emerging technologies such as Open RAN, edge computing, and network automation. In addition, high deployment costs, especially in rural and underserved areas, can delay projects and reduce service provider margins. Security concerns and geopolitical tensions around network infrastructure vendors may also complicate procurement and deployment processes. Lastly, the need for continuous upgrades and evolving standards can add complexity and increase long-term operational costs for service providers and their clients.
Market Dynamics
The 5G RAN professional services market is evolving in response to accelerating 5G network rollouts, increasing architectural complexity, and the transition toward cloud-native and virtualized RAN environments. Telecom operators are moving beyond traditional turnkey deployments toward disaggregated, multi-vendor RAN models, driving demand for specialized consulting, integration, and optimization services. Technology forces such as Open RAN, network slicing, edge computing, and automation are reshaping service requirements. Moreover, the market is shifting toward high-value professional services that reduce deployment risk, improve network performance, and shorten time-to-revenue.
The deployment of 5G introduces significantly greater complexity than legacy networks, driven by densification, massive MIMO, spectrum diversity, and virtualization. Operators face challenges in integrating new radio units, centralized and distributed units, and software-defined components across heterogeneous vendor ecosystems. These challenges are compounded by aggressive rollout timelines and regulatory spectrum obligations, making in-house execution increasingly difficult.
5G RAN professional services address these challenges through expert-led planning, system integration, validation, and deployment support. Service providers enable operators to manage multi-vendor interoperability, optimize spectrum usage, and ensure compliance with performance benchmarks. As a result, professional services accelerate deployment cycles, reduce operational risk, and support faster commercialization of 5G services, directly contributing to market growth.
The cost of 5G RAN professional services remains a significant restraint, particularly for smaller operators and price-sensitive markets. Advanced consulting, system integration, and optimization services require highly specialized engineering talent with expertise in virtualization, cloud platforms, and radio optimization. Limited availability of such skills increases service pricing and extends project timelines.
This restraint has a pronounced impact on emerging markets and rural deployment scenarios, where return-on-investment considerations are more constrained. Smaller telecom operators and enterprise adopters of Private 5G often delay or scale back deployments due to budget constraints. Consequently, the high-cost structure slows adoption across certain regions and segments, tempering overall market expansion.
The growing adoption of private 5G networks and Open RAN architecture presents a significant opportunity for professional service providers. Enterprises across manufacturing, logistics, energy, and healthcare are investing in customized 5G networks to support automation, low-latency applications, and mission-critical connectivity. These deployments require tailored planning, integration, and ongoing optimization support.
This opportunity is expected to drive sustained demand for consulting, design, and performance optimization services. Vendors with strong system integration capabilities, cloud expertise, and Open RAN validation experience are best positioned to capture this growth. Service providers supporting enterprise-focused deployments and multi-vendor ecosystems are likely to see expanding revenue streams over the medium term.
Analyst Perspective
The 5G RAN professional services market is in a strong growth phase, supported by global 5G expansion and rising network complexity. Demand is shifting toward high-value services that support Open RAN, cloud-native architectures, and private 5G deployments. Automation, AI-driven optimization, and virtualization expertise are becoming critical differentiators among service providers. Investment is expected to increase in integration, validation, and optimization services as operators focus on performance and cost efficiency. Competitive dynamics are gradually shifting from hardware-centric models toward service-led engagement strategies.
Service Type Insights
Based on service type, the deployment services segment led the market with the largest revenue share of 25.9% in 2025. The growing adoption of Open RAN and disaggregated network models drives the growth of the segment as it requires deep technical and strategic consulting expertise. Since Open RAN promotes multi-vendor interoperability and a decoupled hardware-software stack, operators rely on consultants to evaluate vendor options, ensure standards compliance, and manage integration risks. Consulting firms guide telecom players through interoperability testing, systems validation, and open ecosystem alignment, helping reduce time-to-market and optimize performance across a diverse range of hardware and software components.
The deployment services segment is expected to grow at a significant CAGR during the forecast period. The accelerated rollout of 5G networks worldwide fuels the growth of the deployment services. As telecom operators race to expand their 5G coverage, they require highly specialized deployment services to install and configure new RAN equipment, including base stations, antennas, and small cells. The complexity and scale of 5G infrastructure, especially with dense urban deployments and multiple frequency bands (sub-6 GHz and mmWave), make it necessary for operators to engage professional service providers who have technical know-how and logistical capabilities to execute deployment quickly and efficiently.
Deployment Mode Insights
Based on deployment mode, the cloud segment led the market with the largest revenue share of 53.1% in 2025. The shift toward virtualization and disaggregation of network infrastructure is propelling the growth of cloud deployment in the 5G RAN professional services market. Traditional RAN systems, which are hardware-centric and vendor-locked, are being replaced by virtualized and software-defined RAN (vRAN) architectures that can be deployed on cloud platforms. This shift enables operators to decouple hardware from software, allowing for more agile, scalable, and cost-effective network deployments. Professional services are essential in this transition, as they support cloud-native design, orchestration, and management of distributed RAN components, often across multi-vendor environments.
The on-premise segment is expected to grow at a significant CAGR of 15.3% during the forecast period. The rise of private 5G networks for industrial and enterprise applications is accelerating the demand for on-premise deployments. Enterprises in sectors such as manufacturing, logistics, mining, and energy are adopting private 5G networks to support automation, real-time monitoring, and autonomous operations. These networks require localized, on-premise infrastructure to ensure ultra-low latency, minimal downtime, and seamless integration with internal systems. As a result, professional service providers are increasingly engaged to deploy and optimize customized 5G RAN solutions within enterprise premises.
End Use Insights
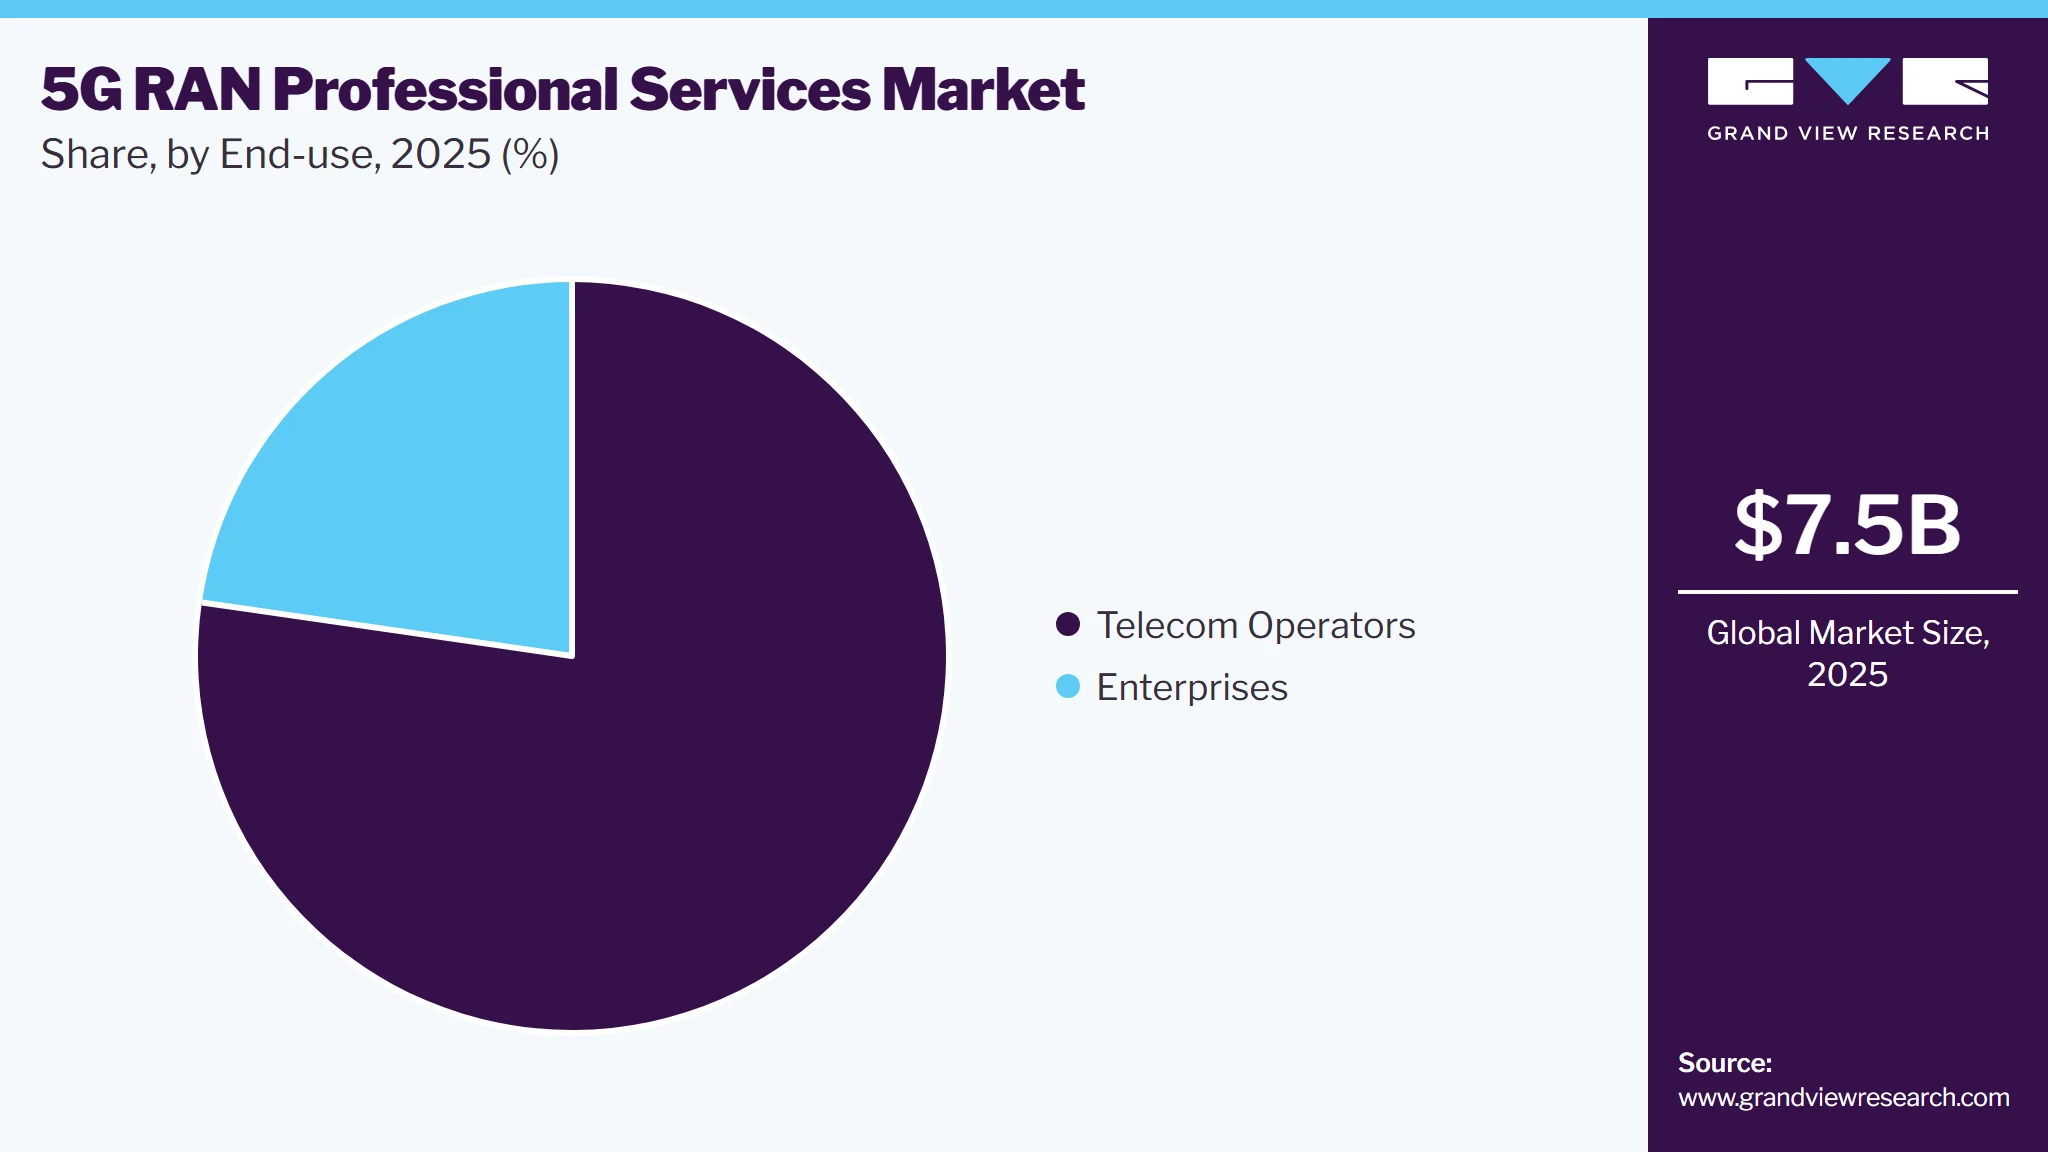
Based on end use, the telecom operators segment led the market with the largest revenue share of 77.3% in 2025. The adoption of Open RAN and multi-vendor ecosystems is pushing telecom operators to seek professional services. Open RAN introduces greater flexibility and cost-efficiency but requires interoperability across different vendors’ hardware and software components. Ensuring seamless integration in such multi-vendor environments demands specialized expertise that operators may lack in-house. Professional service providers help bridge this gap by managing vendor coordination, integration testing, and system validation, which are critical for the success of Open RAN deployments.
 To learn more about this report, Download Free Sample Report
The enterprises segment is projected to grow at the fastest CAGR of 24.0% over the forecast period. The digital transformation initiatives being pursued by enterprises globally contribute to the growth of 5G RAN professional services. Companies are modernizing their IT and operational technology infrastructures to gain competitive advantages, boost productivity, and support innovation. 5G is a key enabler of this transformation by providing the high-speed, low-latency connectivity needed to support automation, AI, and IoT platforms. Professional services help enterprises assess network requirements, develop deployment roadmaps, and implement scalable 5G RAN solutions that align with their digital goals.
Regional Insights
The North America 5G RAN professional services market held a significant share in 2025. The growth in the region is driven by early adoption of 5G technologies, strong investment from telecom operators, and widespread enterprise digitalization. The region benefits from a mature telecom infrastructure and a high concentration of technology companies that demand customized and advanced network solutions. There is increasing demand for services related to RAN virtualization, network optimization, and private 5G deployment across industrial sectors.
The U.S. 5G RAN professional services market held a dominant position in 2025 due to the aggressive 5G rollouts by major carriers such as Verizon, AT&T, and T-Mobile, all of whom rely on professional services for RAN deployment and management. The presence of leading technology firms and a strong push for private 5G networks in industries such as manufacturing, logistics, and healthcare is fueling demand for professional services.
U.S. 5G RAN Professional Services Market Trends
The U.S. 5G RAN professional services market held a dominant position in 2024 due to the aggressive 5G rollouts by major carriers such as Verizon, AT&T, and T-Mobile, all of whom rely on professional services for RAN deployment and management. The presence of leading technology firms and a strong push for private 5G networks in industries such as manufacturing, logistics, and healthcare is fueling demand for professional services.
Europe 5G RAN Professional Market Trends
The Europe 5G RAN professional services market was identified as a lucrative region in 2025. A coordinated regulatory approach and substantial investments from both public and private sectors characterize European market. Operators across the region are accelerating deployments to meet EU connectivity targets, driving demand for deployment, testing, and integration services. There is also growing interest in Open RAN frameworks and green network initiatives, encouraging operators to engage with professional services firms for sustainable and future-ready network design.
5G RAN professional services market in the UK is expected to grow rapidly in the coming years due to the competitive telecom landscape and government-backed initiatives to support nationwide 5G coverage. Enterprises in sectors such as transportation, public safety, and finance are actively exploring private 5G networks, increasing demand for customized RAN planning, deployment, and optimization services.
Germany 5G RAN professional services market held a substantial market share in 2025. The market is advancing rapidly, driven by strong industrial demand for private networks and Industry 4.0 applications. The country’s emphasis on manufacturing and logistics efficiency has accelerated the deployment of on-premise 5G RAN infrastructure, requiring expert professional services.
Asia Pacific 5G RAN Professional Services Market Trends
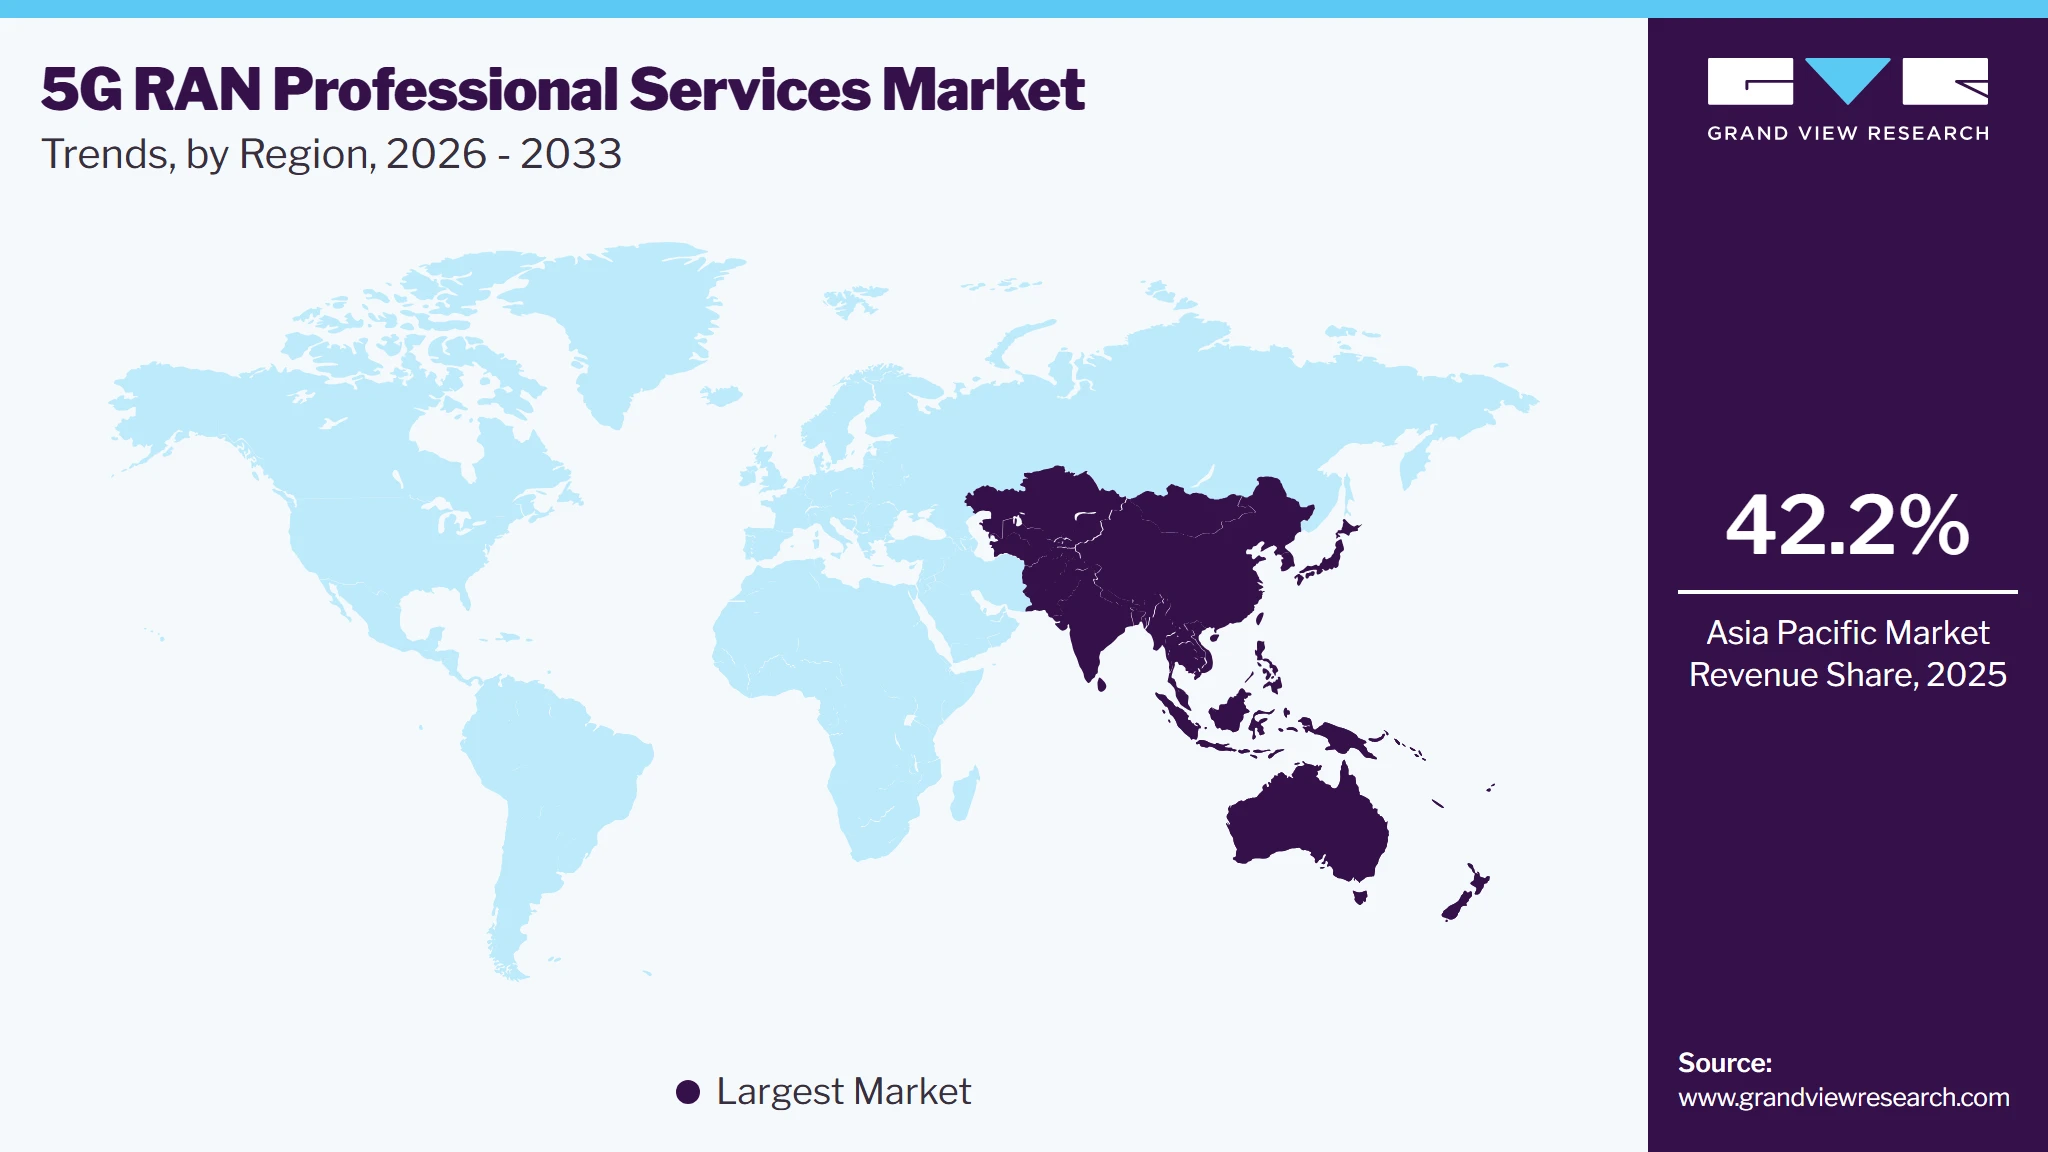
Asia Pacific dominated the global 5G RAN professional services market with the largest revenue share of 42.2% in 2025. The growth of the market in the region is driven by large-scale infrastructure development, rapid urbanization, and digital transformation across various industries. Governments across the region are investing in nationwide 5G coverage and smart city initiatives, creating strong demand for RAN deployment and system integration services. The region's diverse market conditions, from advanced economies to emerging markets, offer a wide range of service opportunities.
 To learn more about this report, Download Free Sample Report
China 5G RAN Professional Services Market Trends
The 5G RAN professional services market in the China held the largest share in the Asia Pacific region in 2025. The government's extensive support for 5G infrastructure development, including subsidies and policy incentives, has created strong momentum for service providers. Chinese operators are investing in next-generation RAN technologies and are increasingly engaging with professional services firms for network optimization, energy efficiency planning, and maintenance.
Japan 5G RAN professional services market is growing steadily, supported by early 5G adoption and a strong focus on technological innovation. Major telecom operators are deploying advanced RAN technologies to support applications in robotics, IoT, and smart manufacturing, driving demand for deployment and network engineering services. Japan's proactive stance on Open RAN adoption has also opened new avenues for professional services related to vendor-neutral network integration.
Key 5G RAN Professional Services Company Insights
Some of the key companies in the 5G RAN professional services market include Nokia Corporation, Infovista, Intel Corporation., Dell EMC, and others. Organizations are focusing on increasing their customer base to gain a competitive edge in the industry. Therefore, key players are taking several strategic initiatives, such as mergers and acquisitions, and partnerships with other major companies.
-
Nokia Corporation is a provider of telecommunications infrastructure and services, playing a pivotal role in the 5G RAN professional services market. Leveraging its extensive portfolio of radio access technologies and expertise in network planning and deployment, Nokia offers a comprehensive suite of services including 5G RAN design, site acquisition, network integration, optimization, and lifecycle management. The company also offers Open RAN and cloud-native architecture, enabling operators to build more flexible and vendor-neutral 5G networks. Through its "AnyRAN" approach and use of artificial intelligence for network automation and self-optimization, Nokia supports operators in accelerating 5G rollouts and enhancing network performance.
-
Intel Corporation plays a strategic and enabling role in the 5G RAN professional services market through its leadership in silicon innovation and network virtualization technologies. While not a traditional telecom equipment vendor, Intel provides the foundational hardware and software platforms, such as Intel Xeon processors, FlexRAN reference architecture, and advanced FPGAs, that power virtualized and Open RAN infrastructures. These technologies support telecom operators and network integrators in deploying flexible, software-defined 5G RAN solutions.
Key 5G RAN Professional Services Companies:
The following key companies have been profiled for this study on the 5G RAN professional services market.
- Telefonaktiebolaget LM Ericsson
- Nokia Corporation
- Infovista
- Tech Mahindra
- Tata Consultancy Services
- Nominos USA Inc
- Link Consulting Services
- GRANDMETRIC
- Dell EMC
- Intel Corporation
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Ericsson, Nokia, Tech Mahindra, Tata Consultancy Services)
- These players are focused on end-to-end service portfolios, global delivery models, and deep telecom domain specialization.
- These players have strong integration capabilities, global scale, and long-standing operator relationships.
- Higher cost structures and lower flexibility for smaller or niche deployments.
Emerging Players (Infovista, Nominos USA Inc, GRANDMETRIC)
- These players are focused focused service offerings, Open RAN specialization, and agile engagement models.
- These players have niche expertise in analytics, optimization, and multi-vendor environments.
- Limited global footprint and narrower service breadth compared to established players.
Recent Developments
-
In April 2025, Nokia extended its long-term strategic collaboration with T-Mobile US through a multi-year agreement aimed at enhancing and expanding the carrier’s nationwide 5G network coverage and capacity. As part of the deal, Nokia will supply its cutting-edge AirScale RAN solutions, including the latest Levante Ultra-Performance baseband units and Habrok Massive MIMO radios, both powered by energy-efficient ReefShark System-on-Chip (SoC) technology. This initiative is designed to improve the efficiency, performance, and reliability of T-Mobile’s 5G network, which already serves over 98% of the U.S. population.
-
In February 2025, Bell Canada expanded its 5G network partnership with Nokia to deploy Nokia’s Cloud RAN (Radio Access Network) solution and lay the foundation for future Open RAN integration. This multi-year agreement includes the rollout of Nokia’s Cloud RAN software and Open Fronthaul-compatible radios. It enables Bell to transition its network architecture while enhancing agility, scalability, and vendor diversity. The deployment leverages Nokia’s AirScale portfolio combined with Red Hat OpenShift’s cloud-native platform and Dell PowerEdge servers installed at cell sites and data centers to provide the processing power and reliability required for demanding 5G workloads.
5G RAN Professional Services Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 7.5 billion
Market size value in 2026
USD 9.2 billion
Revenue forecast in 2033
USD 22.3 billion
Growth rate
CAGR of 13.5% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company market share, competitive landscape, growth factors, and trends
Segments covered
Service type, deployment mode, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; U.K.; France; China; Japan; India; South Korea; Australia; Brazil; Saudi Arabia; UAE; and South Africa
Key companies profiled
Telefonaktiebolaget LM Ericsson; Nokia Corporation; Infovista; Tech Mahindra; Tata Consultancy Services; Nominos USA Inc; Link Consulting Services; GRANDMETRIC; Dell EMC; Intel Corporation
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global 5G RAN Professional Services Market Report Segmentation
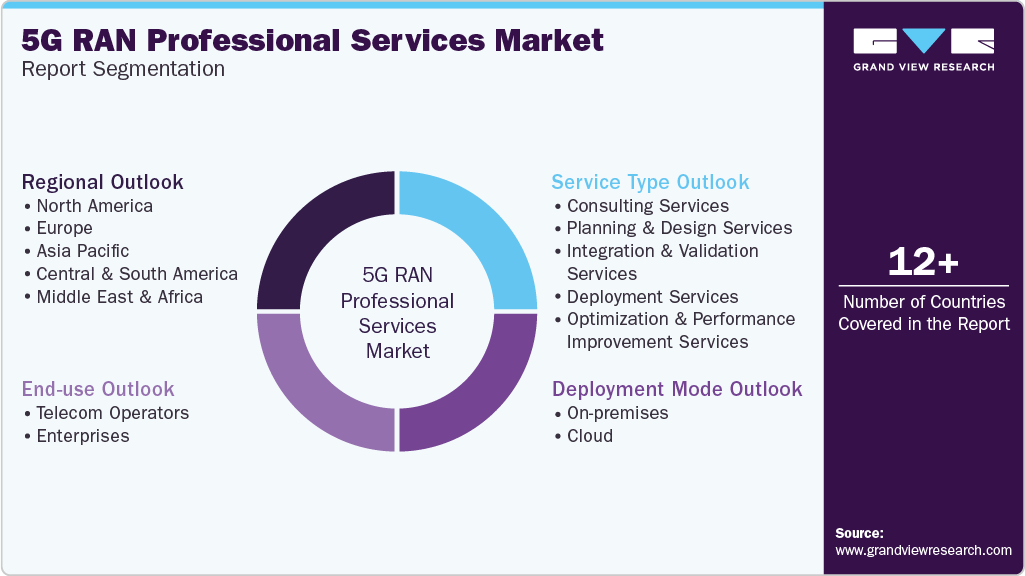
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global 5G RAN professional services market report based on service type, deployment mode, end use, and region.
 To learn more about this report, Download Free Sample Report
-
Service Type Outlook (Revenue, USD Billion, 2021 - 2033)
-
Consulting Services
-
Planning & Design Services
-
Integration & Validation Services
-
Deployment Services
-
Optimization & Performance Improvement Services
-
-
Deployment Mode Outlook (Revenue, USD Billion, 2021 - 2033)
-
On-premises
-
Cloud
-
-
End Use Outlook (Revenue, USD Billion, 2021 - 2033)
-
Telecom Operators
-
Enterprises
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
-
Middle East and Africa (MEA)
-
KSA
-
UAE
-
South Africa
-
-
Research Methodology
The 5G RAN professional services market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each 5G RAN professional services segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Service Type
Revenue capture definition
Consulting Services
Revenue generated from advisory engagements, including 5G RAN strategy formulation, Open RAN feasibility assessments, vendor evaluation, cost-benefit analysis, regulatory compliance consulting, and network modernization roadmaps, is billed through fixed-fee or time-based consulting contracts.
Planning & Design Services
Revenue captured from network planning and engineering activities, such as radio network planning, spectrum utilization analysis, site design, RAN architecture design, capacity planning, and network simulation services, is charged per project or per site.
Integration & Validation Services
Revenue generated from system integration activities, including multi-vendor RAN integration, Open RAN interoperability testing, hardware-software validation, acceptance testing, and lab-based certification services, is billed under integration or testing contracts.
Deployment Services
Revenue captured from on-site and remote network deployment activities, including RAN installation, configuration, commissioning, site acceptance testing, and initial network activation services charged per deployment phase or per site.
Optimization & Performance Improvement Services
Revenue generated from post-deployment services such as network optimization, performance tuning, traffic management, latency reduction, energy efficiency optimization, and SLA-based performance improvement services delivered under recurring or managed service contracts.
Segment - Deployment Mode
Revenue capture definition
On-premises
Revenue generated from professional services supporting RAN deployments hosted on operator- or enterprise-owned physical infrastructure, including installation, configuration, integration, optimization, and ongoing support for on-site network environments.
Cloud
Revenue captured from professional services related to cloud-native or virtualized RAN deployments, including cloud infrastructure integration, vRAN/Open RAN deployment on public or private cloud platforms, cloud orchestration setup, and cloud-based network optimization services.
Segment - End Use
Revenue capture definition
Telecom Operators
Revenue generated from professional services provided to mobile network operators for nationwide or regional 5G RAN rollout, modernization, Open RAN integration, network expansion, optimization, and managed professional services through planning, deployment, and lifecycle support.
Enterprises
Revenue captured from professional services delivered to enterprises for private 5G network deployment, in-building and campus RAN design, system integration, deployment, and performance optimization supporting use cases such as manufacturing, logistics, utilities, healthcare, and smart infrastructure.
Estimation Model
Layer Name
Key Question
Description
Network Rollout Activity
How extensive are global 5G RAN deployments?
This layer evaluates the scale of 5G RAN rollouts by region, including macro sites, small cells, and private networks. It considers spectrum availability, operator capex cycles, and regulatory timelines. The output establishes the addressable deployment base requiring professional services.
Service Intensity
What level of professional service is required per deployment?
This layer assesses the depth of consulting, integration, and optimization needed based on network complexity and architecture. It differentiates between traditional, Open RAN, and cloud-native deployments. Service intensity directly influences revenue per deployment.
Pricing & Engagement Models
What is the average service pricing structure?
This layer analyzes pricing benchmarks across service types, regions, and engagement models. It includes project-based, managed services, and outcome-based pricing structures. Pricing variability reflects skill requirements and deployment risk.
Adoption & Penetration
How widely are services adopted across end users?
This layer measures penetration of professional services among telecom operators and enterprises. It accounts for in-house capabilities versus outsourcing trends. The result determines realized market revenue.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional 5G RAN Professional Services Market Opportunity Assessment
Country/region-wise market sizing and forecasts
Analysis of demand, adoption trends, and regulatory landscape
Identification of high-growth regions and investment hotspots
Identified region-specific growth opportunities
Supported expansion and go-to-market strategy
Enabled informed regional investment decisions
Cross-Segmentation Analysis for the 5G RAN Professional Services Market
Criss-cross market analysis by Service type, deployment mode, end use
Demand and adoption assessment across key segments
Segment attractiveness and growth potential benchmarking
Identified high-potential market segments
Supported targeted Service Type positioning and marketing strategy
Improved customer and segment prioritization
Competitive Benchmarking and Strategic Positioning in the 5G RAN Professional Services Market
Benchmarking of key competitors across Service Types, pricing, partnerships, and innovation
Comparative assessment of market share, capabilities, and strategies
Analysis of competitive strengths, gaps, and differentiation areas
Identified competitive white spaces and growth gaps
Supported strategic positioning and differentiation
Enabled data-driven competitive strategy development
Frequently Asked Questions About This Report
Asia Pacific dominated the market with the largest revenue share of 42.2% in 2025. The growth of the market in the region is driven by large-scale infrastructure development, rapid urbanization, and digital transformation across various industries.
The China held the largest market share in 2025.
Cloud segment held the largest market share of 53.1% in 2025 and is the fastest-growing segment over the forecast period.
Telecom Operators segment accounted for the largest revenue share of 77.3% in 2025, while the enterprises is the fastest-growing segment over the forecast period.
The market is witnessing rapid growth, driven by the global rollout of 5G networks and the increasing complexity of deploying and managing next-generation radio access infrastructure.
Deployment Services segment dominated the market, with a revenue share of 25.9% in 2025. The accelerated rollout of 5G networks worldwide fuels the growth of the deployment services.
Some key players operating in the 5G RAN professional services market include Telefonaktiebolaget LM Ericsson; Nokia Corporation; Infovista; Tech Mahindra; Tata Consultancy Services; Nominos USA Inc; Link Consulting Services; GRANDMETRIC; Dell EMC; Intel Corporation.
The global 5G RAN professional services market size was valued at USD 7.5 billion in 2025 and is estimated at USD 9.2 billion for 2026.
The global 5G RAN professional services market is expected to grow at a CAGR of 13.5% from 2026 to 2033, reaching USD 22.3 billion by 2033.
About the Author(s)
Next Generation Technologies Research Team
Technology · Next Generation TechnologiesThis report was authored by the next generation technologies research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the next generation technologies segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


