
- Home
- »
- Medical Devices
- »
-
Acute Hospital Care Market Size & Growth Report 2026-2033GVR Report cover

Acute Hospital Care Market (2026 - 2033)
Size, Share & Trends Analysis Report By Medical Condition (Emergency Care, Trauma Care, Acute Care Surgery, Short-term Stabilization), By Service (ICU, NICU, CCU), By Facility Type, By Region, And Segment Forecasts
Market Size, 2025
$3,710.9BMarket Estimate, 2026
$3,915.1BMarket Forecast, 2033
$5,861.1BCAGR, 2026–2033
5.9%Acute Hospital Care Market Summary
The global acute hospital care market size was valued at USD 3,710.9 billion in 2025 and is projected to grow from USD 3,915.1 billion in 2026 to USD 5,861.1 billion by 2033, at a CAGR of 5.9% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 54.8% in 2025. The rapidly growing global geriatric population, rising prevalence of chronic diseases, and increasing disposable income are key factors propelling the industry's growth.
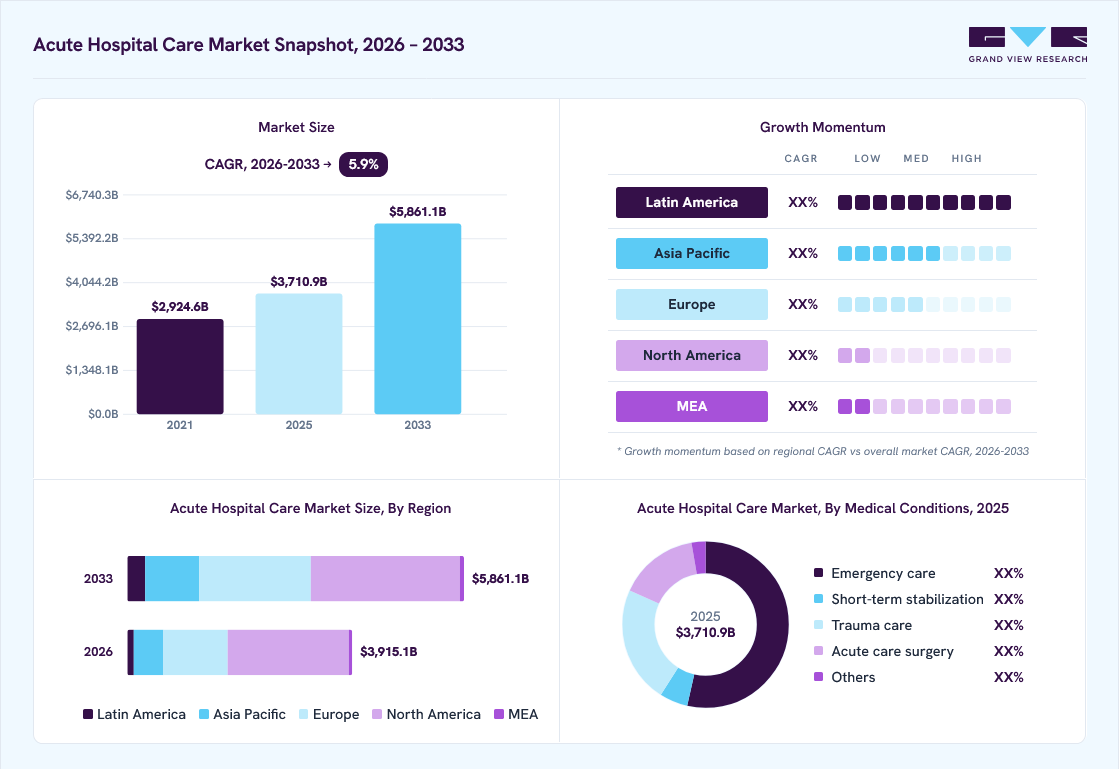 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By medical condition: Emergency care segment held the largest market share of 53.5% in 2025.
- By facility type: General acute care hospitals segment held the largest market share of 59.4% in 2025.
- By services: Intensive care unit (ICU) segment held the largest market share of 57.8% in 2025.
Regional Highlights
- Largest regional market: North America (54.8% revenue share, 2025)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 3,710.9 Billion
- Estimated market size in 2026: USD 3,915.1 Billion
- Projected market size by 2033: USD 5,861.1 Billion
- CAGR (2026-2033): 5.9%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
According to the United Nations estimates, in 2019, there were 703 million individuals above 65 years of age in the world. In addition, rising awareness about healthcare, advancing healthcare infrastructure & technologies, and favorable reimbursement policies are driving industry growth. It is estimated that by 2025, 49% of the population will be diagnosed with a chronic condition.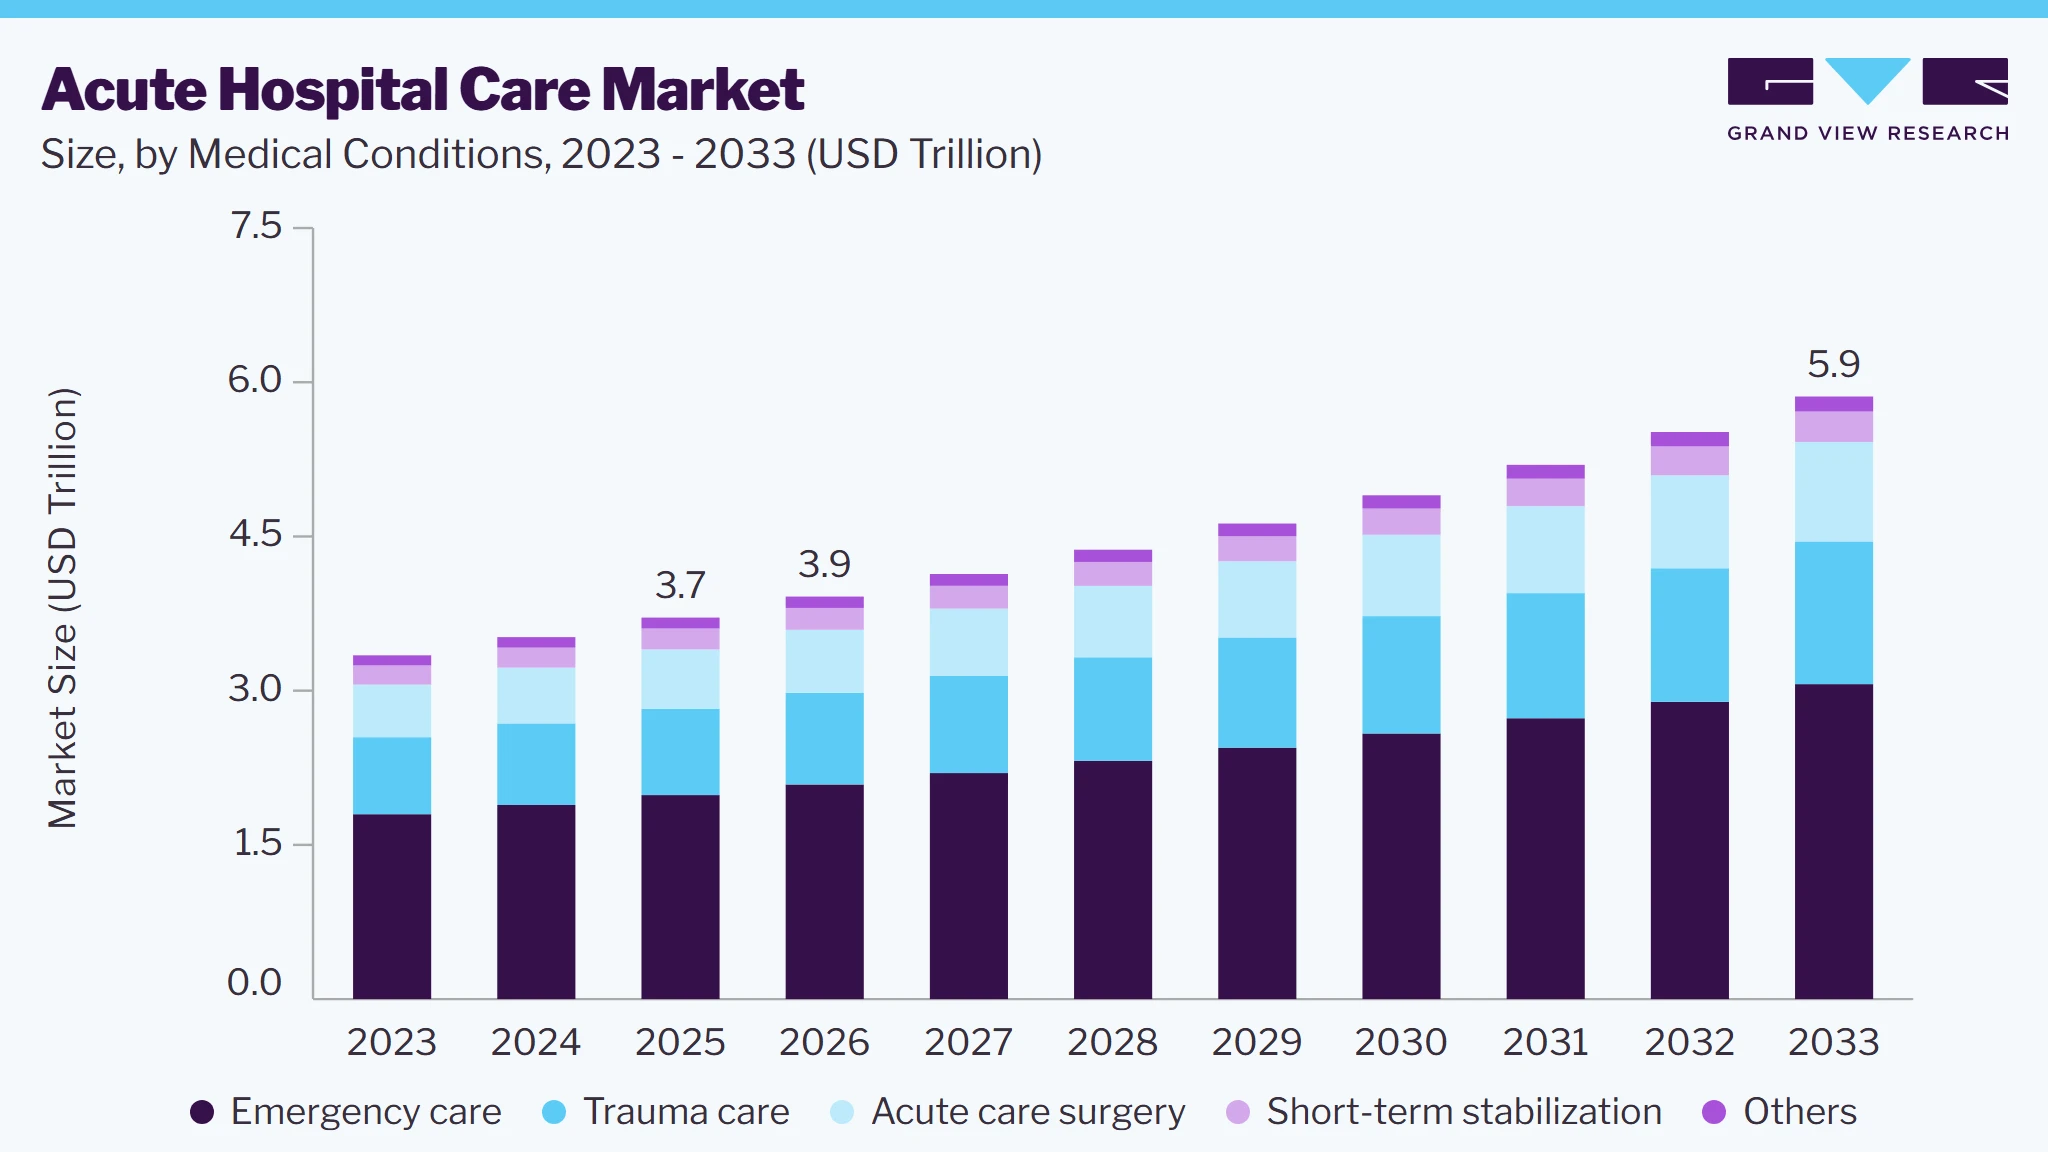 To learn more about this report, Download Free Sample Report
Rapid globalization, changing lifestyles, the adoption of unhealthy habits, increasing alcohol & tobacco consumption, and lack of physical activity are contributing to a rise in the prevalence of chronic diseases. These factors are expected to drive industry growth. Acute care hospitals need to maintain viability and assess new service lines to drive industry growth over the forecast period. These facilities can focus on expanding their service portfolio by providing post-acute care, which would ensure financial survival and offer multiple growth opportunities. It comprises inpatient rehabilitation facilities, LTAC facilities, home health agencies, and skilled nursing facilities.
Market Dynamics
The global acute hospital care market is witnessing significant growth, driven primarily by the rising prevalence of chronic diseases, the increase in emergency and trauma cases, and an aging population requiring intensive care. These trends are boosting demand for inpatient services, emergency care, ICUs, surgical procedures, and specialized acute treatments. Ongoing investments in hospital infrastructure, advanced medical technologies, digital health solutions, and integrated patient management systems are improving clinical efficiency, patient outcomes, and reducing hospital stays. In addition, increasing healthcare expenditure, expanding access to hospital services in emerging economies, and the growing emphasis on value-based and patient-centered care are further driving sustained growth in the acute hospital care market.
The rapid expansion of Hospital-at-Home (HaH) programs is emerging as a significant driver of the acute hospital care market by enabling healthcare providers to deliver inpatient-level acute care beyond traditional hospital settings. Rising emergency department visits, persistent hospital bed shortages, workforce constraints, and increasing healthcare costs have accelerated the adoption of this care model to improve patient capacity while maintaining clinical quality. Hospital-at-Home programs combine physician oversight, remote patient monitoring, nursing visits, diagnostic services, oxygen therapy, intravenous medications, and other acute interventions, allowing eligible patients to receive hospital-grade treatment in their homes. This approach alleviates pressure on hospital infrastructure while improving patient outcomes and operational efficiency. For instance, in March 2025, the U.S. government extended the Medicare Acute Hospital Care at Home (AHCAH) waiver through September 2025, reinforcing federal support for the model. As of early 2025, more than 350 U.S. hospitals had implemented Hospital-at-Home programs, while CMS reported that over 23,000 patients had received acute hospital-level care through the initiative, with studies demonstrating lower mortality, reduced post-discharge healthcare spending, and high patient satisfaction. These developments highlight the growing role of innovative acute care delivery models in driving market expansion.
U.S. Emergency + Inpatient Acute Care Load (2025)
The U.S. healthcare system continues to experience consistently high utilization of acute hospital services, driven by large volumes of outpatient visits and emergency-driven hospital admissions. Hospitals manage approximately 148.4 million outpatient visits annually, reflecting sustained dependence on hospital-based care services across the population. In addition, there are around 18.3 million total inpatient admissions, of which nearly 6.5 million are non-elective emergency admissions originating from emergency departments, highlighting the central role of EDs as the primary entry point for acute care.
Emergency departments contribute significantly to hospital inflow, with a large proportion of high-acuity patients requiring immediate stabilization followed by inpatient admission. This creates continuous pressure on hospital infrastructure, particularly inpatient beds, intensive care units, and emergency care capacity.
Key points:
- 148.4 million outpatient hospital visits annually in the U.S.
- 18.3 million total inpatient admissions per year
- 6.5 million admissions are emergency (non-elective) cases
- EDs act as a major gateway to acute hospital admissions
- High conversion of ED cases into inpatient care increases bed occupancy and ICU utilization
Interpretation:
These statistics indicate that acute hospital care demand in the U.S. is structurally high and sustained, with emergency-driven admissions accounting for a major share of inpatient admissions. This persistent patient load directly increases pressure on hospital capacity, thereby driving growth in acute hospital care services.Hospitals increasingly struggle to discharge medically stable patients due to shortages in skilled nursing facilities, rehabilitation centers, home healthcare, and long-term care. This persistent challenge, known as "bed blocking," prevents hospitals from freeing inpatient beds for new admissions. As a result, emergency departments become overcrowded, elective surgeries are postponed, patient waiting times increase, and operational efficiency declines. Hospitals cannot maximize bed utilization despite rising demand, which limits revenue and constrains investment in expanding capacity.
This issue has worsened as aging populations and higher rates of chronic disease have increased demand for post-acute services, which have not kept pace. Workforce shortages in nursing homes, rehabilitation facilities, and home health agencies further delay patient transfers, leading to longer hospital stays and higher operating costs.
For instance, Becker's Hospital Review in June 2025, citing Vizient's Sg2 Healthcare Market Outlook, which identified hospital capacity constraints and prolonged emergency department boarding as major operational challenges across U.S. hospitals. The report noted that admitted patients frequently remained in emergency departments for extended periods because inpatient beds could not be vacated due to discharge bottlenecks, significantly reducing hospitals' ability to admit new acute-care patients. Also, Connecticut hospitals reported in 2025 that 38.7% of admitted emergency department patients waited more than four hours for an inpatient bed, with several hospitals experiencing boarding rates exceeding 60%. Healthcare leaders attributed these delays largely to shortages in post-acute care facilities and insufficient long-term care, instead of to a lack of clinical demand. These systemic discharge bottlenecks continue to reduce patient throughput, increase treatment costs, delay time-sensitive care, and restrain market growth.
The increasing adoption of AI-enabled hospital command centers presents a significant growth opportunity for the acute hospital care market. Healthcare providers are investing in artificial intelligence, predictive analytics, and real-time data integration to improve patient flow, optimize bed utilization, enhance emergency department efficiency, and streamline clinical decision-making. These digital command centers enable hospitals to better manage rising patient volumes, reduce treatment delays, and improve operational efficiency while addressing workforce shortages. As hospitals continue their digital transformation initiatives, demand for AI-driven acute care management solutions is expected to increase, creating opportunities for technology providers, healthcare IT vendors, and acute care service providers.
For instance, in June 2025, Aster DM Healthcare announced a capital expenditure plan of approximately USD 220 millionto expand its hospital network by adding 3,300 new beds across India by FY2026–27. The expansion includes investments in advanced digital infrastructure, AI-enabled operational technologies, precision oncology, and robotic-assisted surgery to improve patient management and acute care delivery across its facilities. Such investments highlight the growing emphasis on intelligent hospital operations that enhance resource allocation, reduce patient wait times, and strengthen the capacity of acute care hospitals to deliver timely, high-quality care. This trend is expected to accelerate the adoption of AI-enabled command centers, creating substantial opportunities for market participants offering digital healthcare infrastructure and clinical workflow optimization solutions.
Key Opportunities in the Market:
Opportunity Area
Development / Example
Market Impact
Expansion of High-Acuity Hospital Infrastructure
In September 2025, Albany Medical Center announced a USD 25 million expansion of its adult emergency department, adding 20 new patient care spaces, a six-bed resuscitation unit, and redesigned triage and EMS facilities to accommodate rising emergency patient volumes.
Expands emergency care capacity, reduces patient wait times, improves clinical throughput, and creates demand for advanced acute care equipment and hospital infrastructure.
Source: Secondary Research, Grand View Research
Analyst Perspective
The global acute hospital care market is driven by the rising burden of acute diseases, increasing emergency visits, aging populations, and growing demand for specialized inpatient and critical care services. Hospitals are increasingly adopting advanced diagnostics, robotic surgery, AI-enabled clinical tools, telehealth, and EHRs to improve outcomes and operational efficiency. Government and private investments in hospital infrastructure, particularly in emerging economies, are further supporting market development. Meanwhile, hospital-at-home, remote monitoring, and value-based care models are reshaping acute care delivery. However, workforce shortages, rising operating costs, discharge delays, and limited bed capacity remain key challenges.
Medical Condition Insights
Based on medical condition, the emergency care segment led the market with the largest revenue share of 53.5% in 2025. This can be attributed to the high incidence of accidents, burns, heart attacks, trauma, stroke, acute infections, and other such conditions. Furthermore, favorable reimbursement and coverage policies laid down by several governments support segment growth. In addition, there are over 3.0 million non-fatal injuries each year, resulting in over 5 million deaths around the world. With such a high prevalence of disability and mortality due to trauma, the need for emergency services is expected to increase.
Short-term stabilization involves the provision of integrated medical and mental health interventions in a medical setting, tailored to the severity of the specific emergency (mild, moderate, or severe). If an individual has consumed a toxic amount of alcohol or medications, such as opiates, prompt medical attention is critical. Moreover, short-term stabilization may be beneficial in psychiatric emergencies. Furthermore, many psychiatry patients injure themselves as a result of stress, worry, and substance addiction, among others. These factors are expected to contribute to segment growth during the forecast period.
The acute care surgery segment is estimated to register at the fastest CAGR during the forecast period. It is a relatively new surgical specialty that combines training in surgical critical care, trauma surgery, and emergency general surgery to evaluate & treat patients with general surgical problems. The majority of emergency cases requiring acute care surgery involve abdominal disorders, such as acute appendicitis, diverticulitis, cholecystitis, intestinal blockage, pancreatitis, intra-abdominal infection, intestinal ischemia, incarcerated hernias, and ruptured internal organs.
Facility Type Insights
Based on facility type, the general acute care hospitals segment led the market with the largest revenue share of 59.4% in 2025, owing to the growing number of admissions at these facilities. Moreover, acute stabilization may be beneficial in psychiatric emergencies. Changing lifestyle & perusal of unhealthy habits contributing to stroke prevalence and rising awareness about mental disorders are driving the segment growth.
The psychiatric hospitals segment is anticipated to witness at the fastest CAGR during the forecast period. Psychiatric hospitals, alternatively referred to as behavioral health units or mental health units, are hospitals or wards dedicated to the treatment of mental illnesses, such as bipolar disorder, schizophrenia, and major depressive disorder. The prevalence of mental health problems is increasing at a significant rate among children and adults around the globe.
Inpatient rehabilitation hospitals/units are regulated and certified facilities that focus on rehabilitative health rather than on general medical and surgical care. Rehabilitation is described as the process of restoring a disabled individual to self-sufficiency or the highest level of functional independence attainable. The increasing prevalence of chronic diseases and the growing geriatric population are fueling the growth of the rehabilitation hospitals segment.
Services Insights
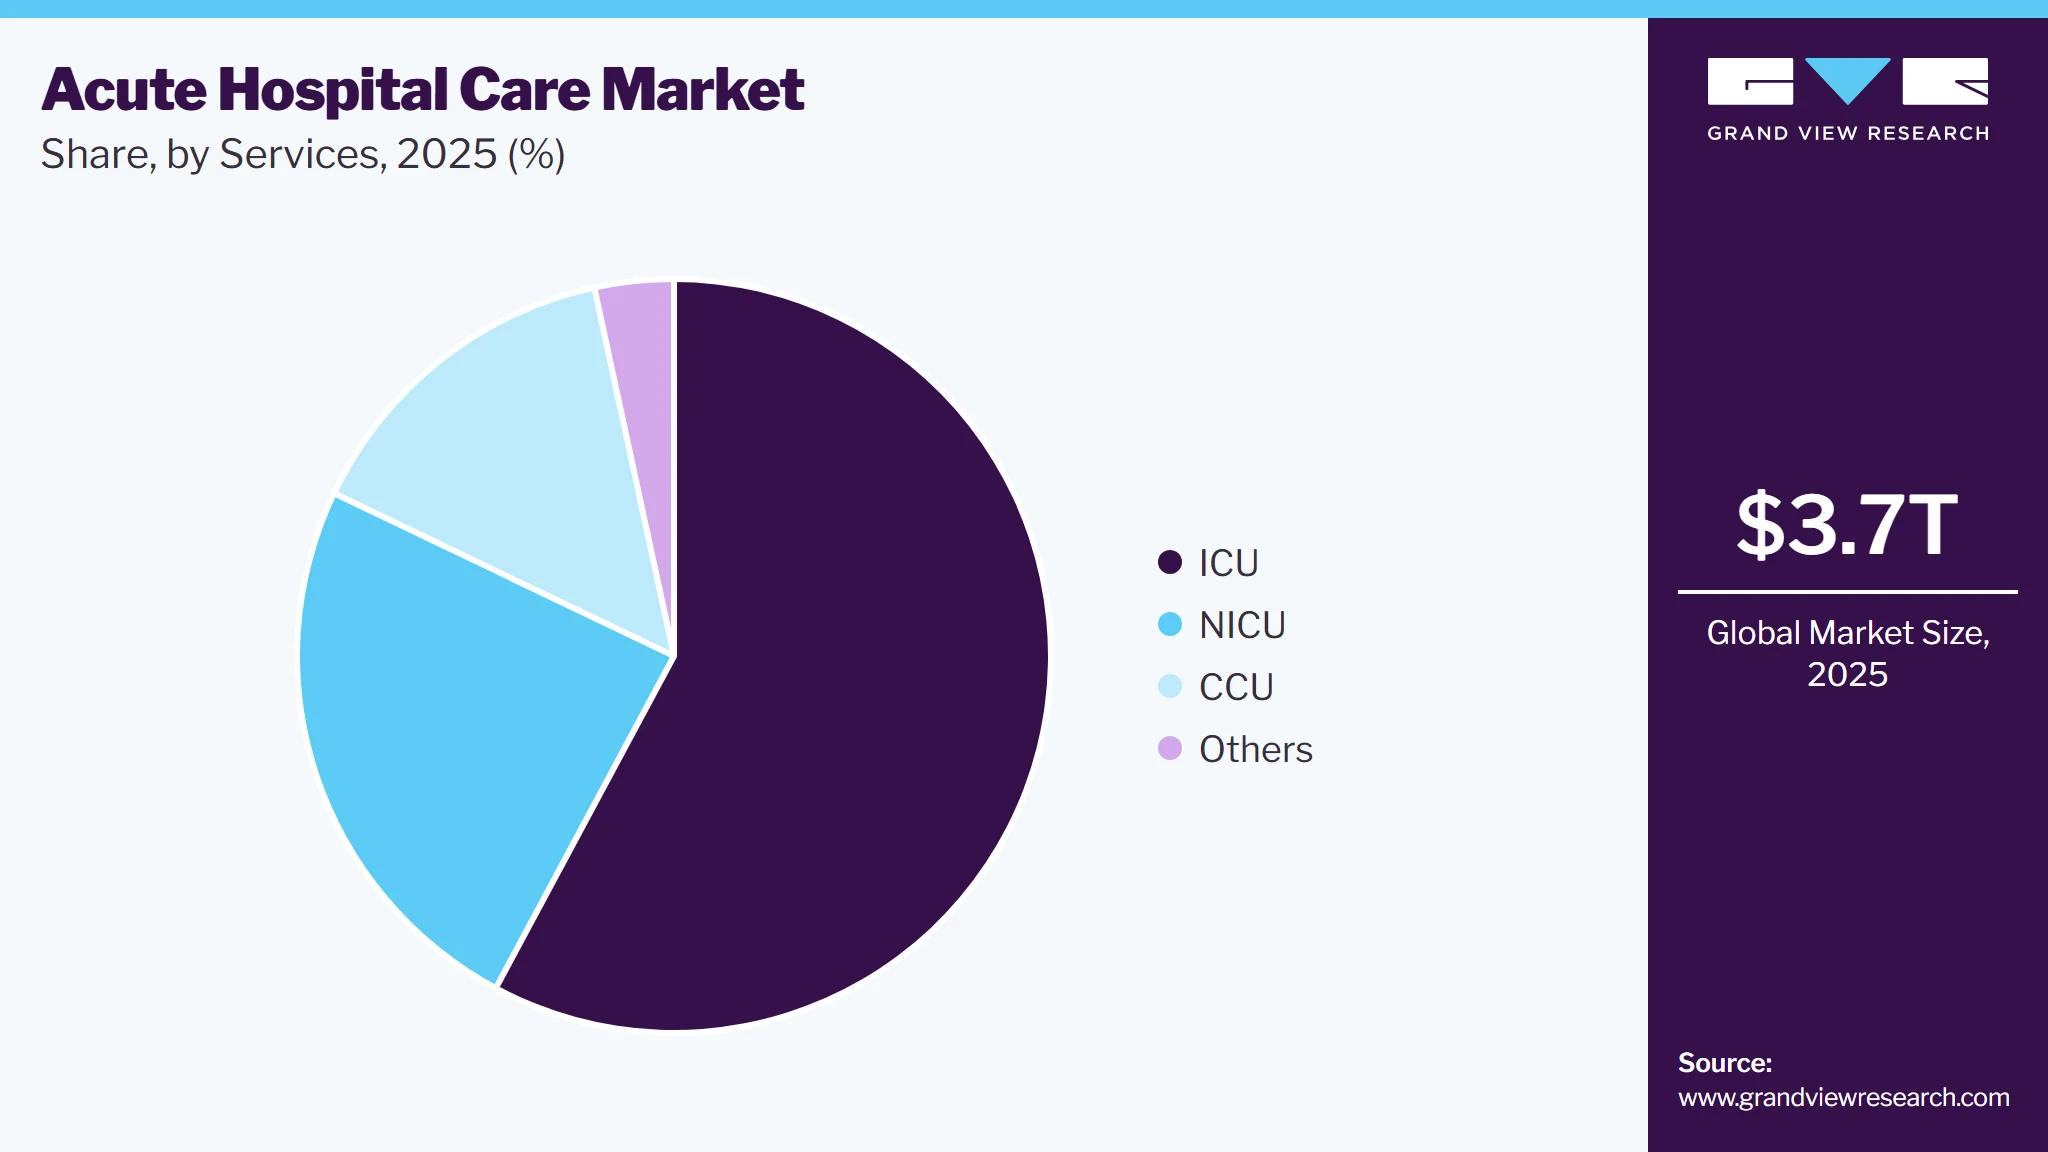
Based on the services, the ICU segment led the market with the largest revenue share of 57.8% in 2025, owing to the high patient population requiring intensive monitoring. According to studies, the majority of the admissions in acute care hospitals are to the ICU. Several hospitals have designated specialty ICUs for treating conditions such as surgical interventions, cardiac disorders, and medical emergencies.
The NICU segment is anticipated to register at the fastest CAGR during the forecast period. An increasing number of premature births with breathing difficulties requiring intensive monitoring is contributing to the segment growth. Rising global awareness regarding childcare, the entry of health insurance firms, and the advent of the private sector in NICUs are the other factors expected to contribute to the segment's growth.
 To learn more about this report, Download Free Sample Report
The increasing prevalence of cardiovascular conditions is a primary factor responsible for the Cardiac Care Units (CCUs) segment. Individuals with these disorders are at risk of experiencing sudden, unexpected changes in their state and often require continuous monitoring, such as targeted temperature regulation (inducing mild hypothermia).
Regional Insights
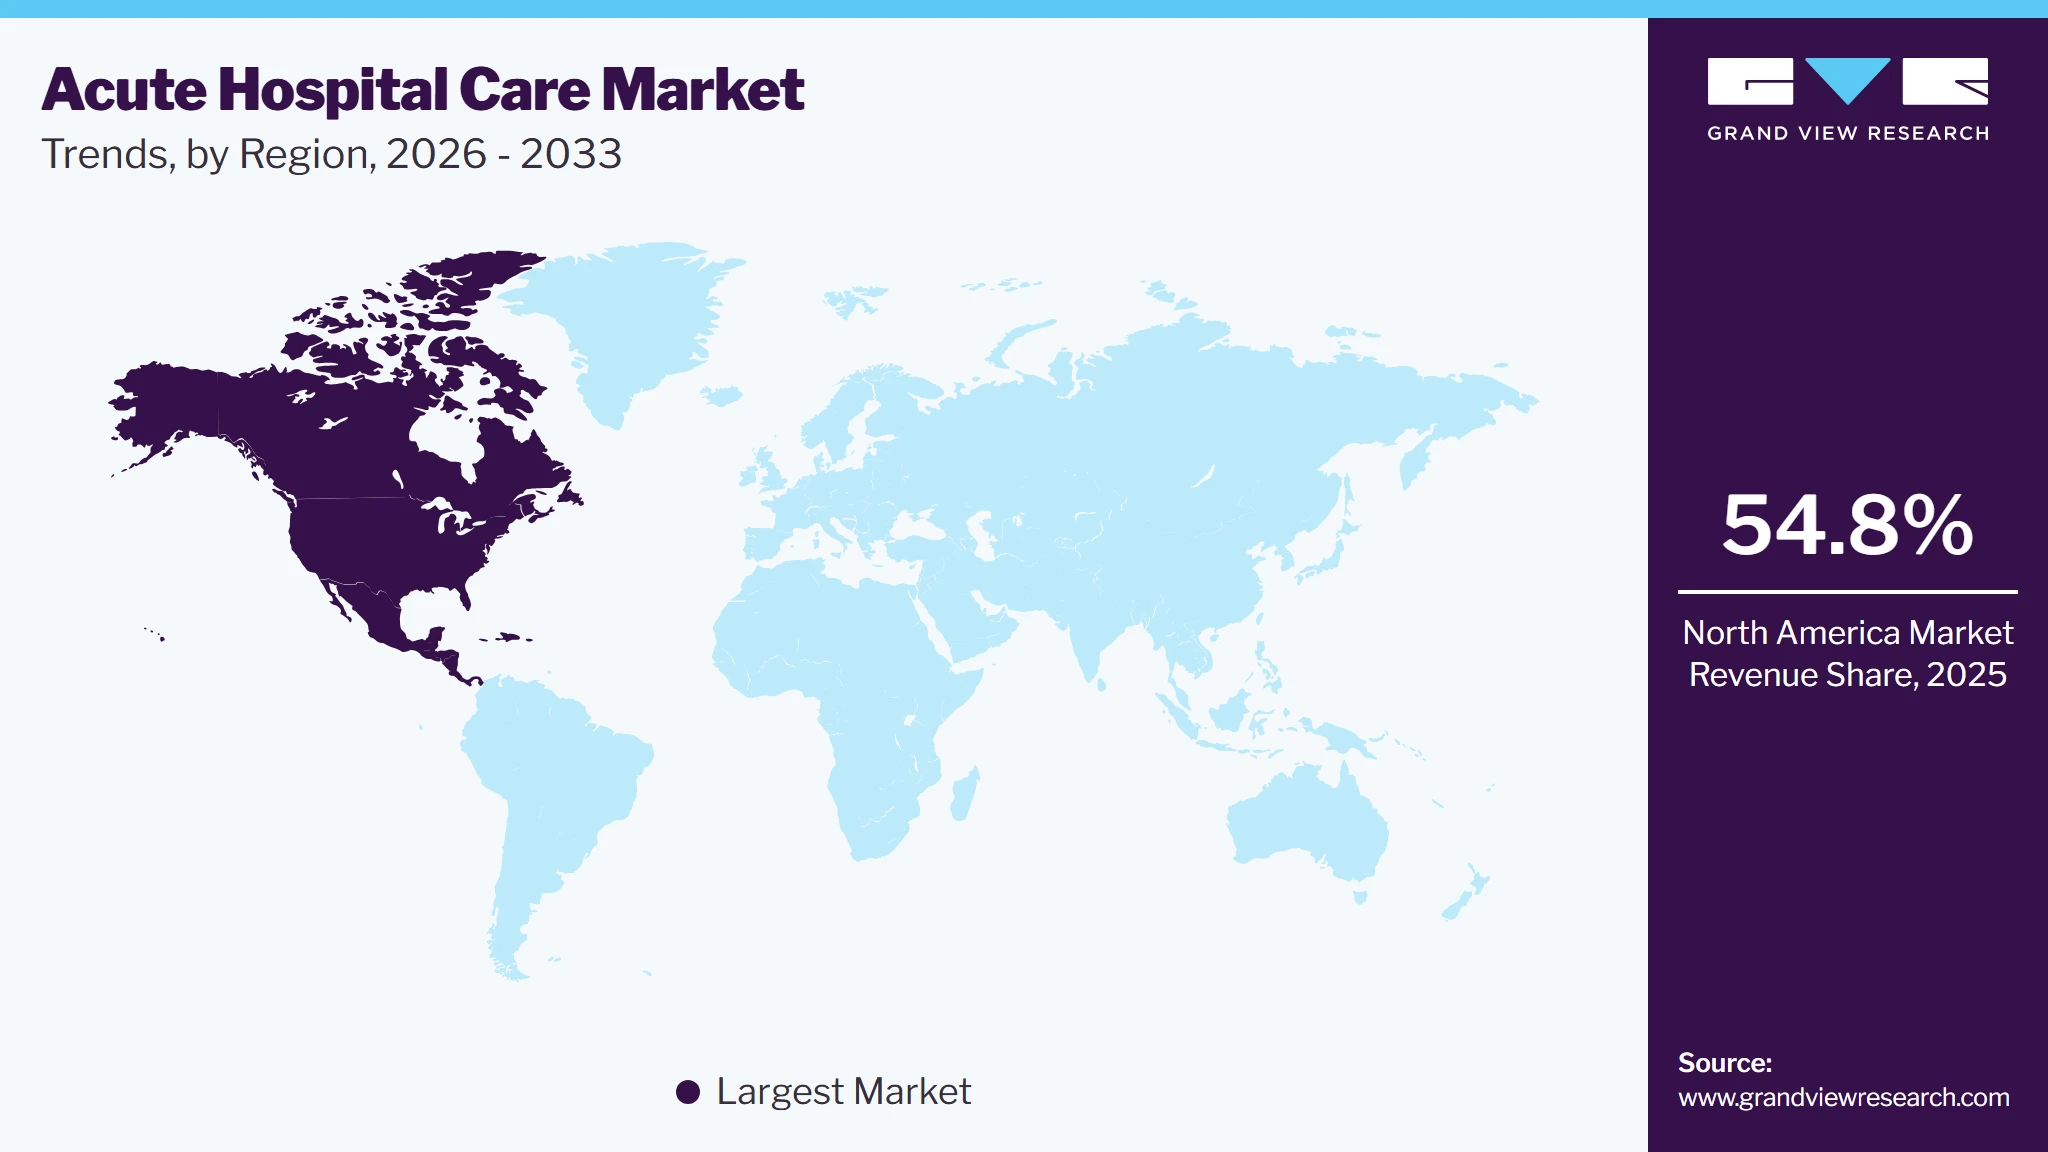
North America dominated the acute hospital care market the largest revenue shares of 54.8% in 2025, owing to the presence of adequate healthcare resources, well-established healthcare infrastructure, growing healthcare spending, and the rising prevalence of chronic disorders. Moreover, the government is introducing favorable initiatives to curb growing healthcare expenditure. According to the AHA's 2024 estimates, there are approximately 6,100 hospitals in the U.S.
 To learn more about this report, Download Free Sample Report
U.S. Acute Hospital Care Market Trends
The acute hospital care market in the U.S. held the largest share in the North America region in 2025. This is driven primarily by the growing burden of chronic and acute medical conditions, rising rates of trauma, cardiovascular emergencies, respiratory illnesses, infections, and an aging population that requires frequent hospitalization and intensive care. Increasing healthcare utilization due to lifestyle-related diseases, along with advancements in medical technology, surgical procedures, and critical care infrastructure, are further stimulating demand for acute care services. In addition, expanded insurance coverage under public and private health plans, coupled with government initiatives to strengthen hospital capacity and emergency preparedness are supporting market growth.
Europe Acute Hospital Care Market Trends
The acute hospital care market in Europe is anticipated to grow at a significant CAGR during the forecast period. The European healthcare system is challenged with short-term & long-term economic & financial restrictions, increasing the risk of chronic disorders, high demand for technological innovations, rising need for a skilled workforce, and the significant impact of the pandemic. Hospitals and healthcare facilities are transforming their business models from the hospital- & physician-centric to integrated models, wherein facilities would work in tandem with primary and community care.
Asia Pacific Acute Hospital Care Market Trends
The acute hospital care market in the Asia Pacific is expected to grow at a significant CAGR over the forecast period. The rapid growth of this region can be attributed to the factors such as advancements in healthcare technology, increasing healthcare expenditures, and the presence of a large patient population pool. Moreover, increased demand for acute care in countries such as India, China, and South Korea is expected to drive the expansion of the regional market in the years to come. The need for healthcare is being driven by an increase in the demand for high-quality equipment in the healthcare industry to diagnose and treat problems early.
Key Acute Hospital Care Company Insights
The global acute hospital care industry is highly fragmented, with the presence of various multinational and local healthcare facilities. Industry players are focusing on collaborations, mergers, and acquisitions to gain a competitive edge and expand their business footprint.
Key Acute Hospital Care Companies
The following key companies have been profiled for this study on the acute hospital care market.
-
TH Medical
-
Fresenius Medical Care AG
-
Ramsay Health Care
-
Asklepios Kliniken GmbH & Co. KGaA
-
UHS of Delaware, Inc.
-
CHSPSC, LLC
-
Ascension.
-
IHH Healthcare Berhad
-
Mediclinic Group
-
Lifepoint Health, Inc.
-
Ardent Health Management Services (AHS Management Company, Inc.).
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players
e.g., Tenet Healthcare, Universal Health Services, Community Health Systems, Ascension, Ramsay Health Care, IHH Healthcare
- Expand acute care networks through hospital acquisitions, capacity expansion, and strategic partnerships. Invest in advanced medical technologies, digital health platforms, emergency and critical care services, specialty care centers, and value-based care initiatives. Strengthen integrated care delivery, physician networks, and outpatient capabilities while enhancing operational efficiency and patient outcomes through AI, telehealth, and electronic health records.
- Extensive hospital networks, strong brand recognition, diversified specialty care portfolios, established physician relationships, advanced clinical infrastructure, and broad geographic presence. Significant financial resources enable investments in medical technology, quality improvement, workforce development, and regulatory compliance, supporting long-term market leadership.
- High capital expenditure and operating costs, persistent healthcare workforce shortages, reimbursement and pricing pressures, complex regulatory compliance, and challenges in integrating acquired facilities. Large health systems may also experience slower operational transformation and higher administrative complexity.
Emerging Players e.g., LifePoint Health, Ardent Health Services, Asklepios Kliniken, Mediclinic International, Fresenius Medical Care in specialized acute services
- Focus on expanding regional hospital networks, specialized acute care services, rehabilitation, critical care, and integrated care pathways. Invest in digital patient engagement, operational efficiency, clinical quality improvement, and partnerships with physicians and local healthcare providers. Differentiate through specialized service lines, patient-centered care models, and targeted expansion into underserved and high-growth healthcare markets.
- Greater operational flexibility, strong regional market presence, specialized clinical expertise, faster adoption of digital healthcare solutions, and the ability to tailor services to local patient populations. Efficient management structures enable quicker decision-making and responsiveness to evolving healthcare needs.
- More limited geographic reach and financial resources than global hospital systems, lower bargaining power with suppliers and payers, dependence on regional healthcare demand, and constrained capital for large-scale acquisitions, advanced technology investments, and international expansion.
Recent Developments
-
In March 2026, Lifepoint Health, Inc. announced signing an agreement to acquire eight ScionHealth acute care hospitals. This is projected to significantly strengthen its healthcare delivery network and expand its footprint.
-
In June 2025, Select Medical Corporation announced it had signed a membership interest purchase agreement with Ballad Health to operate the Kingsport, Tennessee -based critical illness recovery hospital, Select Specialty Hospital - Tri-Cities.
-
In January 2024, Universal Health Services, Inc. acquired four acute care hospitals from Vista Health System and its affiliate. This is expected to strengthen its network and acute care delivery capabilities.
Acute Hospital Care Market Report Scope
Report Attribute
Details
Market size in 2025
USD 3,710.9 billion
Estimated market size in 2026
USD 3,915.1 billion
Projected market size by 2033
USD 5,861.1 billion
Growth rate
CAGR of 5.9% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Medical condition, facility type, service, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; South Korea; Australia; Thailand; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait
Key companies profiled
TH Medical (Tenet Healthcare Corporation), Universal Health Services, Inc, Community Health Systems, Inc., Fresenius Medical Care AG & Co. KGaA, Lifepoint Health, Inc., Ardent Health Services, Ascension, Ramsay Health Care, Asklepios Kliniken GmbH & Co. KGaA, Mediclinic International, IHH Healthcare Berhad.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Acute Hospital Care Market Report Segmentation
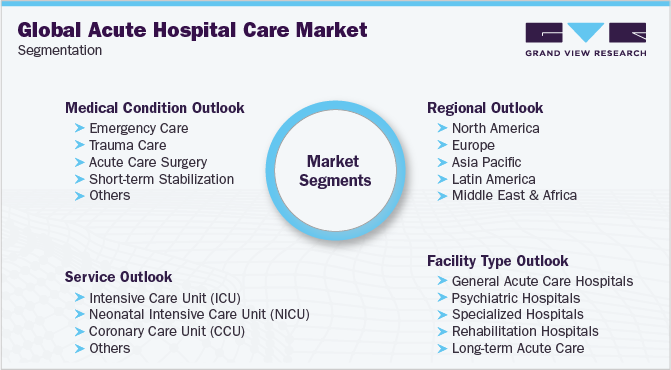
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the global acute hospital care market report on basis of medical condition, facility type, service, and region:
 To learn more about this report, Download Free Sample Report
-
Medical Condition Outlook (Revenue, USD Billion, 2021 - 2033)
-
Emergency Care
-
Trauma Care
-
Acute Care Surgery
-
Short-term Stabilization
-
Others
-
-
Facility Type Outlook (Revenue, USD Billion, 2021 - 2033)
-
General Acute Care Hospitals
-
Psychiatric Hospitals
-
Specialized Hospitals
-
Rehabilitation Hospitals
-
Long-term Acute Care
-
-
Service Outlook (Revenue, USD Billion, 2021 - 2033)
-
Intensive Care Unit (ICU)
-
Neonatal Intensive Care Unit (NICU)
-
Coronary Care Unit (CCU)
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
-
Latin America
-
Brazil
-
-
Middle East & Africa
-
Saudi Arabia
-
South Africa
-
-
Research Methodology
The acute hospital care market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each acute hospital care segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment
Revenue capture definition
By Medical Condition
Emergency Care
Medical services are provided for patients experiencing sudden, severe illnesses or injuries that require immediate diagnosis, stabilization, and treatment to prevent serious complications or death.
Short-term Stabilization
Acute medical interventions aimed at stabilizing patients with critical or rapidly worsening conditions before discharge, transfer, or further specialized treatment.
Trauma Care
Specialized hospital care for patients suffering from serious physical injuries caused by accidents, falls, violence, or other traumatic events, involving emergency surgery, critical care, and multidisciplinary treatment.
Acute Care Surgery
Surgical procedures performed urgently for life-threatening or rapidly progressing medical conditions such as appendicitis, bowel obstruction, internal bleeding, fractures, or severe infections requiring immediate intervention.
Others
Includes acute hospital care provided for other serious medical conditions such as severe infections, respiratory failure, stroke, cardiac emergencies, poisoning, burns, and other conditions requiring immediate inpatient treatment.
By Facility type
General Acute Care Hospitals
Hospitals that provide comprehensive short-term inpatient and outpatient medical, surgical, emergency, and critical care services across a broad range of specialties.
Psychiatric Hospitals
Specialized hospitals that provide intensive inpatient treatment and emergency care for patients with acute mental health disorders, psychiatric crises, and behavioral health conditions.
Specialized Hospitals
Healthcare facilities dedicated to treating specific diseases or medical specialties such as cardiac care, oncology, orthopedics, neurology, or children’s health through advanced acute care services.
Rehabilitation Hospitals
Hospitals focused on intensive rehabilitation and recovery for patients following acute illnesses, major surgeries, strokes, spinal cord injuries, traumatic brain injuries, or other disabling conditions requiring multidisciplinary care.
Long Term Acute Care (LTAC)
Specialized hospitals providing extended inpatient care for medically complex patients who require prolonged hospitalization, advanced respiratory support, wound care, or ongoing intensive medical treatment after stabilization.
By Services
Intensive Care Unit (ICU)
Highly specialized hospital units that provide continuous monitoring and advanced life-support treatment for critically ill or unstable patients requiring intensive medical attention.
Neonatal Intensive Care Unit (NICU)
Dedicated hospital units providing specialized acute care for premature newborns, critically ill infants, and babies with congenital or life-threatening medical conditions.
Coronary Care Unit (CCU)
Specialized intensive care units focused on monitoring and treating patients with acute cardiovascular conditions such as heart attacks, severe arrhythmias, heart failure, and other cardiac emergencies.
Others
Includes other specialized acute hospital care services such as burn units, stroke units, high dependency units (HDUs), respiratory care units, infectious disease units, and post-anesthesia care units that support the management of critically ill patients.
Estimation Model
Model Details
This research methodology outlines the process for estimating the size of the global acute hospital care market for the period from 2021 to 2033. The study covers key service segments, including emergency care, intensive care, trauma care, acute medical care, acute surgical care, critical care, cardiac care, neurological care, infectious disease management, maternity and neonatal acute care, and other inpatient acute care servicesacross major geographic regions including North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa.
The objective is to develop a robust and defensible market estimate through a combination of bottom-up and top-down approachessupported by primary industry validation.
A triangulated market sizing approach was used, combining:
-
Bottom-Up Analysis from acute hospital admissions, inpatient volumes, emergency department visits, hospital revenues, average length of stay, and bed occupancy rates.
-
Top-Down Checks using healthcare expenditure, hospitalization rates, disease burden, aging population trends, trauma incidence, emergency care utilization, hospital infrastructure, and government healthcare spending.
-
Primary Research with hospitals, healthcare providers, hospital administrators, physicians, healthcare consultants, insurers, health system executives, policymakers, and industry experts.
Step-By-Step Market Estimation Process
- Acute Hospital Patient Utilization Model
This model calculates market size by estimating the number of patients receiving acute hospital care and the associated annual healthcare spending.
- Step 1:
Country-level data for acute hospital admissions, emergency department visits, inpatient admissions, ICU admissions, disease prevalence, trauma incidence, hospital bed capacity, and healthcare infrastructure for 2021–2025 was collected from government health agencies, ministries of health, hospital associations, healthcare databases, WHO publications, and public health statistics.
- Step 2:
Acute hospital utilization rates were applied to estimate the percentage of eligible patients receiving inpatient acute care annually. Utilization rates were derived from hospital discharge databases, national health surveys, insurance claims databases, hospital registries, published literature, and primary interviews.
- Step 3:
Average annual spending per acute care patient was estimated using hospitalization costs, inpatient treatment expenses, ICU charges, physician fees, diagnostic and surgical procedure costs, reimbursement schedules, provider billing data, and hospital financial reports.
- Step 4:
Market size was calculated by multiplying:
- Number of Acute Hospital Patients × Average Annual Spending per Patient
- Step 5:
Calculations were performed at the country level and subsequently aggregated to regional and global levels.
- Step 6:
Historical and forecast growth rates were incorporated based on increasing emergency admissions, aging populations, rising chronic disease burden, trauma cases, infectious disease outbreaks, surgical volumes, healthcare expenditure growth, and expansion of hospital infrastructure.
- Hospital Revenue Extrapolation Model
This model estimates market size using revenues generated by acute care hospitals.
- Step 1:
The number of active general hospitals, specialty hospitals, trauma centers, academic medical centers, tertiary care hospitals, and long-term acute care hospitals by country was identified through healthcare registries, hospital associations, government databases, company disclosures, and proprietary databases.
- Step 2:
Average annual revenue per acute care hospital was estimated using hospital financial statements, annual reports, reimbursement databases, healthcare benchmarks, industry publications, and primary interviews.
- Step 3:
Hospital revenues were adjusted for regional differences in treatment costs, payer mix, reimbursement systems, hospital size, case complexity, patient volumes, occupancy rates, and healthcare spending.
- Step 4:
Country-level market size was calculated by multiplying:
- Number of Acute Care Hospitals × Adjusted Average Annual Revenue per Hospital
- Step 5:
Regional and global market values were generated through aggregation of country-level estimates.
- Step 6:
Annual adjustments were applied to account for hospital capacity expansion, new facility development, digital health adoption, hospital-at-home integration, reimbursement reforms, technological advancements, and government healthcare investments.
- Hospital Admission Volume and Treatment Cost Model
This model estimates market size based on hospital admission volumes and average treatment costs across major acute care services.
- Step 1:
Hospital admission volume data was collected from hospitals, healthcare systems, government agencies, insurance databases, healthcare associations, hospital discharge registries, and industry publications.
- Step 2:
Services were categorized into:
-
Emergency Care
-
Intensive Care Unit (ICU) Services
-
Trauma Care
-
Acute Medical Care
-
Acute Surgical Care
-
Cardiac Care
-
Neurological Care
-
Infectious Disease Management
-
Maternity & Neonatal Acute Care
-
Other Acute Hospital Services
- Step 3:
Average treatment costs and average length of stay were established using hospital pricing data, reimbursement schedules, healthcare claims databases, diagnosis-related group (DRG) payment systems, hospital financial data, and expert interviews.
- Step 4:
Revenue generated by each service category was calculated by multiplying:
- Number of Hospital Admissions/Treatment Episodes × Average Cost per Admission/Treatment Episode
- Step 5:
Category-level revenues were aggregated to determine country, regional, and global market sizes.
- Step 6:
Forecast assumptions incorporated increasing hospitalization rates, growth in emergency care utilization, rising surgical procedures, expanding ICU capacity, technological advancements in hospital care, digital health integration, improved reimbursement coverage, and increasing investments in healthcare infrastructure.
- Market Validation and Forecasting
The estimates derived from the acute hospital patient utilization model, hospital revenue extrapolation model, and hospital admission volume and treatment cost model were cross-validated through data triangulation. Findings were further verified through primary interviews with hospital executives, physicians, healthcare administrators, health system managers, insurers, policymakers, healthcare consultants, and industry experts.
Final market forecasts were developed by evaluating demographic trends, healthcare expenditure growth, hospitalization rates, disease burden, emergency care demand, hospital capacity expansion, reimbursement policies, workforce availability, technological innovations, digital transformation, and government investments shaping the global acute hospital care market.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Company Positioning & Competitive Landscape Assessment
Developed a comprehensive Company Positioning & Competitive Landscape (CPCL) assessment covering leading acute hospital care providers. Evaluated market positioning, service portfolio, geographic footprint, capacity (beds and specialty units), strategic initiatives, mergers & acquisitions, technology adoption, partnerships, and competitive differentiation across major regional and global healthcare providers.
Provides a clear understanding of competitive positioning, identifies market leaders and emerging challengers, supports benchmarking against peers, and enables informed strategic planning, partnership evaluation, and market entry decisions.
Patient Volume & Service Utilization Analysis
Detailed assessment of acute hospital utilization across emergency care, trauma care, intensive care, acute surgery, cardiac care, neurological care, and short-term inpatient services. Analysis included hospital admissions, emergency department visits, average length of stay, bed occupancy trends, and service demand across major healthcare markets.
Supports demand estimation, capacity planning, resource allocation, service expansion strategies, and long-term market opportunity assessment across key acute care specialties.
Healthcare Infrastructure & Technology Analysis
Assessment of emerging trends in acute hospital care, including Hospital-at-Home programs, digital health integration, AI-enabled clinical decision support, tele-ICU platforms, electronic health records (EHR), robotic-assisted surgery, remote patient monitoring, and smart hospital technologies. Innovation analysis focused on technology adoption, operational efficiency, and patient outcome improvements across acute care settings.
Helps identify future growth drivers, technology adoption trends, operational efficiency opportunities, and competitive differentiation strategies for healthcare providers and investors.
Frequently Asked Questions About This Report
The global acute hospital care market size was valued at USD 3,710.9 billion in 2025 and is estimated at USD 3,915.1 billion for 2026.
Key players include TH Medical (Tenet Healthcare Corporation), Universal Health Services, Inc, Community Health Systems, Inc., Fresenius Medical Care AG & Co. KGaA, Lifepoint Health, Inc., Ardent Health Services, Ascension, Ramsay Health Care, Asklepios Kliniken GmbH & Co. KGaA, Mediclinic International, IHH Healthcare Berhad.
North America dominated with a 54.8% revenue share in 2025 owing to the presence of adequate healthcare resources, well-established healthcare infrastructure, growing healthcare spending, and the rising prevalence of chronic disorders.
The acute care surgery segment is the fastest-growing over the forecast period.
The psychiatric hospitals segment is the fastest-growing over the forecast period.
The emergency care segment led with a 53.5% revenue share in 2025. This can be attributed to the high incidence of accidents, burns, heart attacks, trauma, stroke, acute infections, and other such conditions.
The general acute care hospitals segment led the market with the largest revenue share of 59.4% in 2025, owing to the growing number of admissions at these facilities.
The global acute hospital care market is expected to grow at a CAGR of 5.9% from 2026 to 2033, reaching USD 5,861.1 billion by 2033.
Intensive care unit (ICU) dominated the acute hospital care market with a share of 57.8% in 2025 owing to the high patient population requiring intensive monitoring.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


