
- Home
- »
- Medical Devices
- »
-
Acute Wound Care Market Size & Share Report, 2026-2033GVR Report cover

Acute Wound Care Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Advanced Wound Dressing, Surgical Wound Care), By Application (Surgical & Traumatic Wounds, Burns), By End-use, By Region, And Segment Forecasts
Market Size, 2025
$10.1BMarket Estimate, 2026
$10.5BMarket Forecast, 2033
$14.3BCAGR, 2026–2033
4.4%Acute Wound Care Market Size & Trends
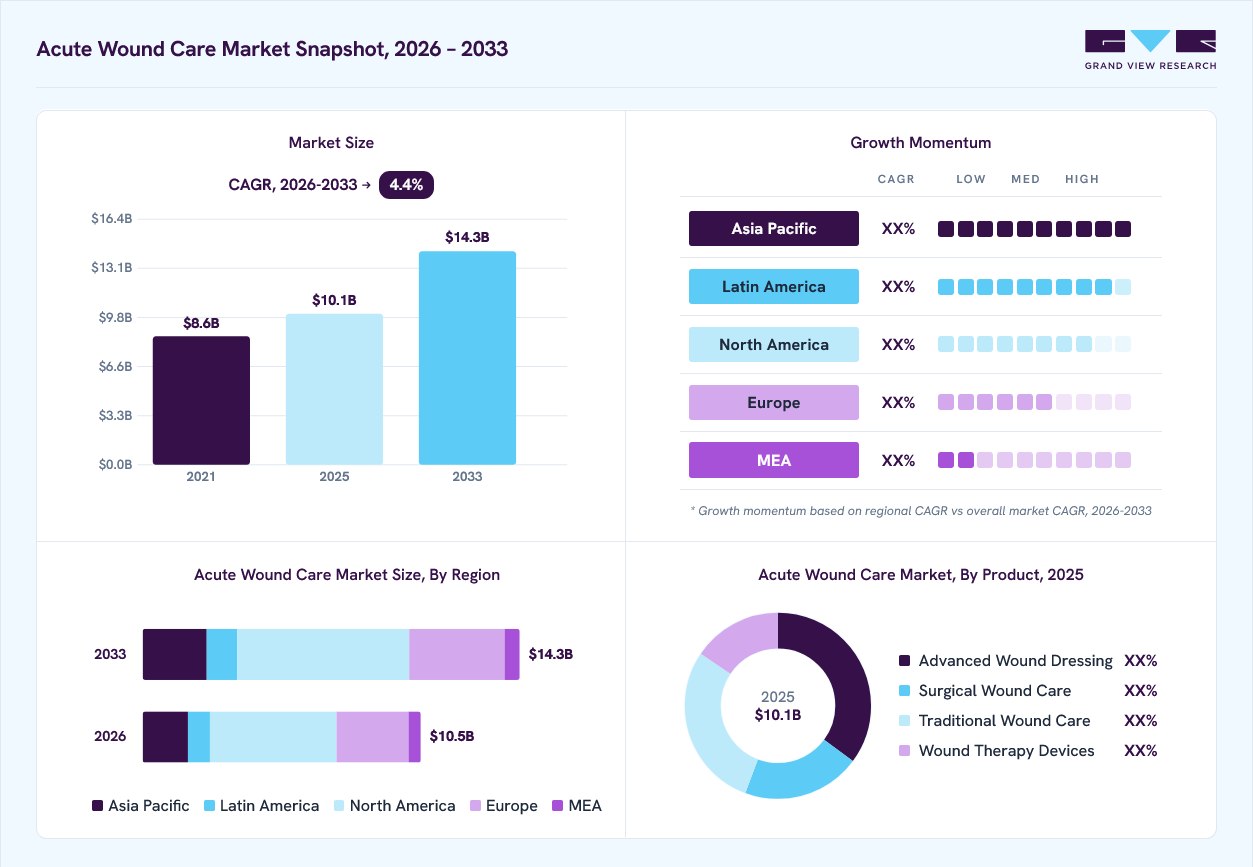
The global Acute Wound Care market size was valued at USD 10.1 billion in 2025 and is projected to grow from USD 10.5 billion in 2026 to USD 14.3 billion by 2033, at a CAGR of 4.4% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 45.5% in 2025. The increase in demand for acute wound care products can be attributed to a rise in surgical cases globally.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By application: The surgical & traumatic wound segment led the market with the largest revenue share of 80.2% in 2025.
- By product: The advanced wound dressing segment led the market with the largest revenue share of 35.1% in 2025.
- By end-use: The hospitals segment led the market with the largest revenue share of 45.5% in 2025.
Regional Highlights
- Largest regional market: North America (45.5% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 10.1 Billion
- Estimated market size in 2026: USD 10.5 Billion
- Projected market size by 2033: USD 14.3 Billion
- CAGR (2026-2033): 4.4%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
An increase in the number of accidents, traumatic injuries, and surgeries performed has resulted in the demand for wound care solutions. A growing number of patients suffering from illnesses such as diabetes and obesity has resulted in the increased occurrence of surgical wounds as these disorders increase the chances of wounds and infections. Hence, increased demand for wound management due to these disorders has contributed to the market growth. In addition, a rise in traumatic accidents such as crush injuries, road accidents, and assaults is expected to drive the market. According to the World Health Organization (WHO), road traffic injuries are the leading cause of death for the population aged between 5 and 29. Therefore, there is an increased demand for wound management and treatments. Major companies are investing in research and development to improve the healing qualities of wound treatment products and therapy devices.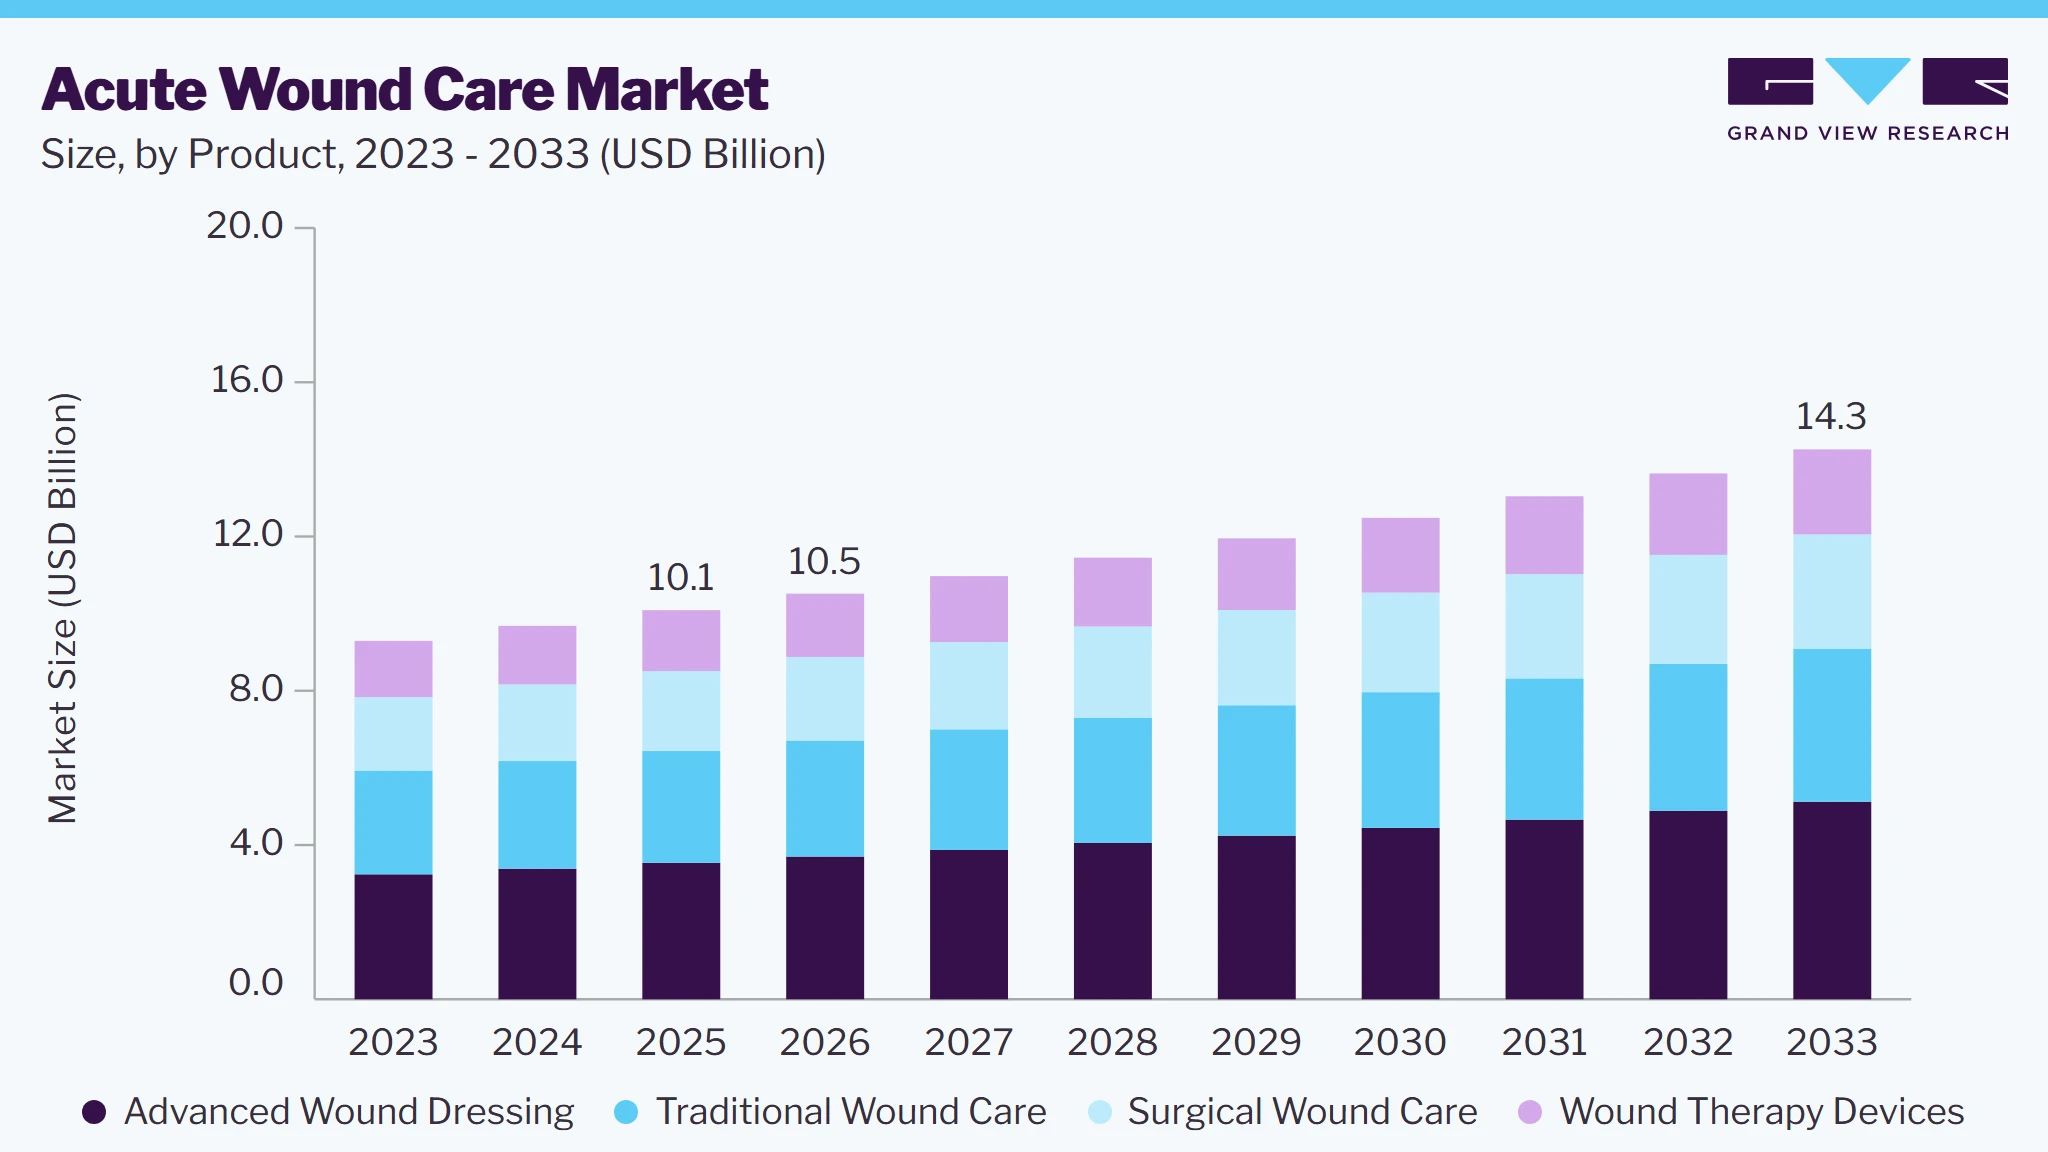 To learn more about this report, Download Free Sample Report
The rising incidence of various burn injuries may also help the market grow. According to WHO, 180,000 deaths are caused by burn injuries. The increasing prevalence of diseases such as diabetes and obesity has led to a rise in patients suffering from chronic wounds. There is an increase in the number of patients with diabetic leg ulcers and foot ulcers. To cope with the rising demand for acute wound care products, the market players are undergoing strategic initiatives such as product launches, conducting awareness programs, geographic expansion, and mergers & acquisitions. Furthermore, development in the healthcare sector and the easy availability of medical treatments have contributed to the market growth.
Market Dynamics
The acute wound care market is experiencing sustained growth driven by the increasing volume of surgical procedures, traumatic injuries, burns, and lacerations that require prompt wound management. Rising awareness of infection prevention and faster healing has accelerated the adoption of advanced wound care products, including antimicrobial dressings, hydrocolloids, foams, and tissue adhesives across hospitals and outpatient settings. Technological advancements in wound care materials, coupled with the expansion of ambulatory surgical centers and emergency care services, continue to support market growth. However, the high cost of advanced wound care products and inconsistent reimbursement policies in certain healthcare systems may limit broader adoption, particularly in cost-sensitive markets.
The increasing volume of surgical procedures, trauma cases, burns, and accidental injuries is a major driver of the acute wound care market. Surgical incisions and traumatic wounds require timely intervention with advanced dressings and wound management products to minimize infection, promote faster healing, and reduce complications. The growing adoption of minimally invasive and outpatient surgeries, coupled with expanding emergency and trauma care services, is further increasing the demand for effective acute wound care solutions across hospitals, ambulatory surgical centers, and clinics.
Global Injury Burden: Causes, Mortality, and Healthcare Impact
Category
Key Statistics
Global Injury Burden
Injuries result from road traffic crashes, falls, drowning, burns, poisoning, and interpersonal or self-directed violence, among other causes.
Annual Injury-Related Deaths
Approximately 4.4 million people die from injuries globally each year.
Unintentional Injury Deaths
Around 3.16 million deaths annually are caused by unintentional injuries.
Violence-Related Injury Deaths
Approximately 1.25 million deaths each year result from violence-related injuries.
Distribution of Injury Deaths
About 1 in 3 injury deaths are due to road traffic crashes, 1 in 6 from suicide, 1 in 10 from homicide, and 1 in 61 from war and conflict.
Leading Causes of Death (Age 5–29 Years)
Road traffic injuries, homicide, and suicide are three of the top five leading causes of death among individuals aged 5–29 years.
Child Mortality (Age 5–14 Years)
Drowning is the 6th leading cause of death among children aged 5–14 years.
Falls
Falls account for more than 684,000 deaths annually worldwide and remain a growing public health concern.
Source: WHO
Limited reimbursement for advanced wound care products remains a key restraint in the acute wound care market. In many healthcare systems, reimbursement policies primarily cover conventional dressings, while advanced products such as antimicrobial, bioactive, and negative-pressure wound therapy may receive partial or no coverage. This increases patients' out-of-pocket costs and discourages adoption by hospitals and outpatient facilities, particularly in cost-sensitive regions.
The development of advanced bioactive and antimicrobial wound dressings presents a significant growth opportunity for the acute wound care market. Innovations incorporating antimicrobial agents, growth factors, hydrogels, collagen, and other bioactive materials are improving infection control, accelerating tissue regeneration, and enhancing healing outcomes. As healthcare providers seek products that reduce healing time and minimize complications, manufacturers are investing in next-generation wound dressings with enhanced therapeutic performance, expanding the market’s growth potential.
Analyst Perspective
The acute wound care market is poised for significant growth, supported by the rising incidence of surgical procedures, traumatic injuries, burns, and sports-related wounds, alongside increasing demand for faster healing and infection prevention. The market is shifting toward advanced wound dressings, antimicrobial technologies, and portable wound therapy devices that improve clinical outcomes and patient convenience. Manufacturers focusing on product innovation, clinical evidence, and expansion into outpatient and home healthcare settings are expected to gain a competitive advantage, while addressing cost, reimbursement, and regulatory challenges will remain essential for sustained market growth.
Regulatory and Reimbursement Trends
The acute wound care market, including burn management, is undergoing significant regulatory and reimbursement transformation as CMS intensifies oversight of advanced wound therapies, particularly skin substitutes frequently used in complex burns and difficult-to-heal acute wounds. In 2026, CMS reclassified many skin substitutes and cellular/tissue-based products from separate Average Sales Price (ASP)-based reimbursement to an "incident-to" supply payment methodology under the Medicare Physician Fee Schedule, a move aimed at improving payment accuracy and reducing inappropriate utilization after Medicare spending on these products escalated sharply in recent years. In addition, CMS withdrew the proposed Final Local Coverage Determinations (LCDs) that sought to impose stricter evidence and documentation requirements, signaling that although access to these products remains intact, future coverage decisions will favor therapies supported by strong clinical evidence, clear medical necessity, and demonstrated value. For burn care providers and manufacturers, these developments indicate a shift toward value-based reimbursement, where products that can prove superior healing outcomes, reduced complications, and cost-effectiveness in acute wound and burn treatment are likely to gain a competitive advantage while low-evidence, high-cost offerings face mounting pressure.
Product Insights
Based on product, the advanced wound dressing segment led the market with the largest revenue share of 35.1% in 2025 and is expected to grow at the fastest CAGR over the forecast period, the advantages of advanced wound dressing, and increased investments by government and private medical institutes in research and development to improve wound dressing products. There is an increased demand for wound dressing products that aid in fast healing and infection prevention. Furthermore, the rising number of road accidents and crash injuries has increased the demand for wound dressing treatments.
The surgical wound care segment is expected to grow at a CAGR of 4.4% during the forecast period. The global rise in surgical cases is expected to propel market growth. Growth in the healthcare sector has resulted in the availability of technologically advanced surgical procedures and equipment. Therefore, this has increased awareness among the population regarding the availability of surgical procedures. The increasing geriatric population and growing instances of road accidents and crash injuries have further propelled the market growth of this segment. Hence, these factors have resulted in the market growth of this segment.
Application Insights
Based on application, the surgical & traumatic wound segment led the market with the largest revenue share of 80.2% in 2025 and is expected to grow at the fastest CAGR over the forecast period. The market growth is attributed to the rising number of surgical site infections (SSIs). Surgical wounds majorly occur due to SSIs, and the rising incidence rate of SSIs is predicted to boost segment growth. Furthermore, the rising number of non-fatal injuries requiring medical attention and the easy availability of wound treatment products for wound management have contributed to the market growth. Hence, these factors are responsible for the market growth of this segment.
The burns segment is expected to grow at a CAGR of 4.1% during the forecast period, owing to the increasing cases of burn injuries worldwide. According to the American Burn Association, 398,000 burn injuries received medical treatment in the U.S. Moreover, technological advancements have been made to cure burn marks. Major companies are launching wound care products that have improved healing properties. Therefore, these factors aid in the market growth of this segment.
End Use Insights
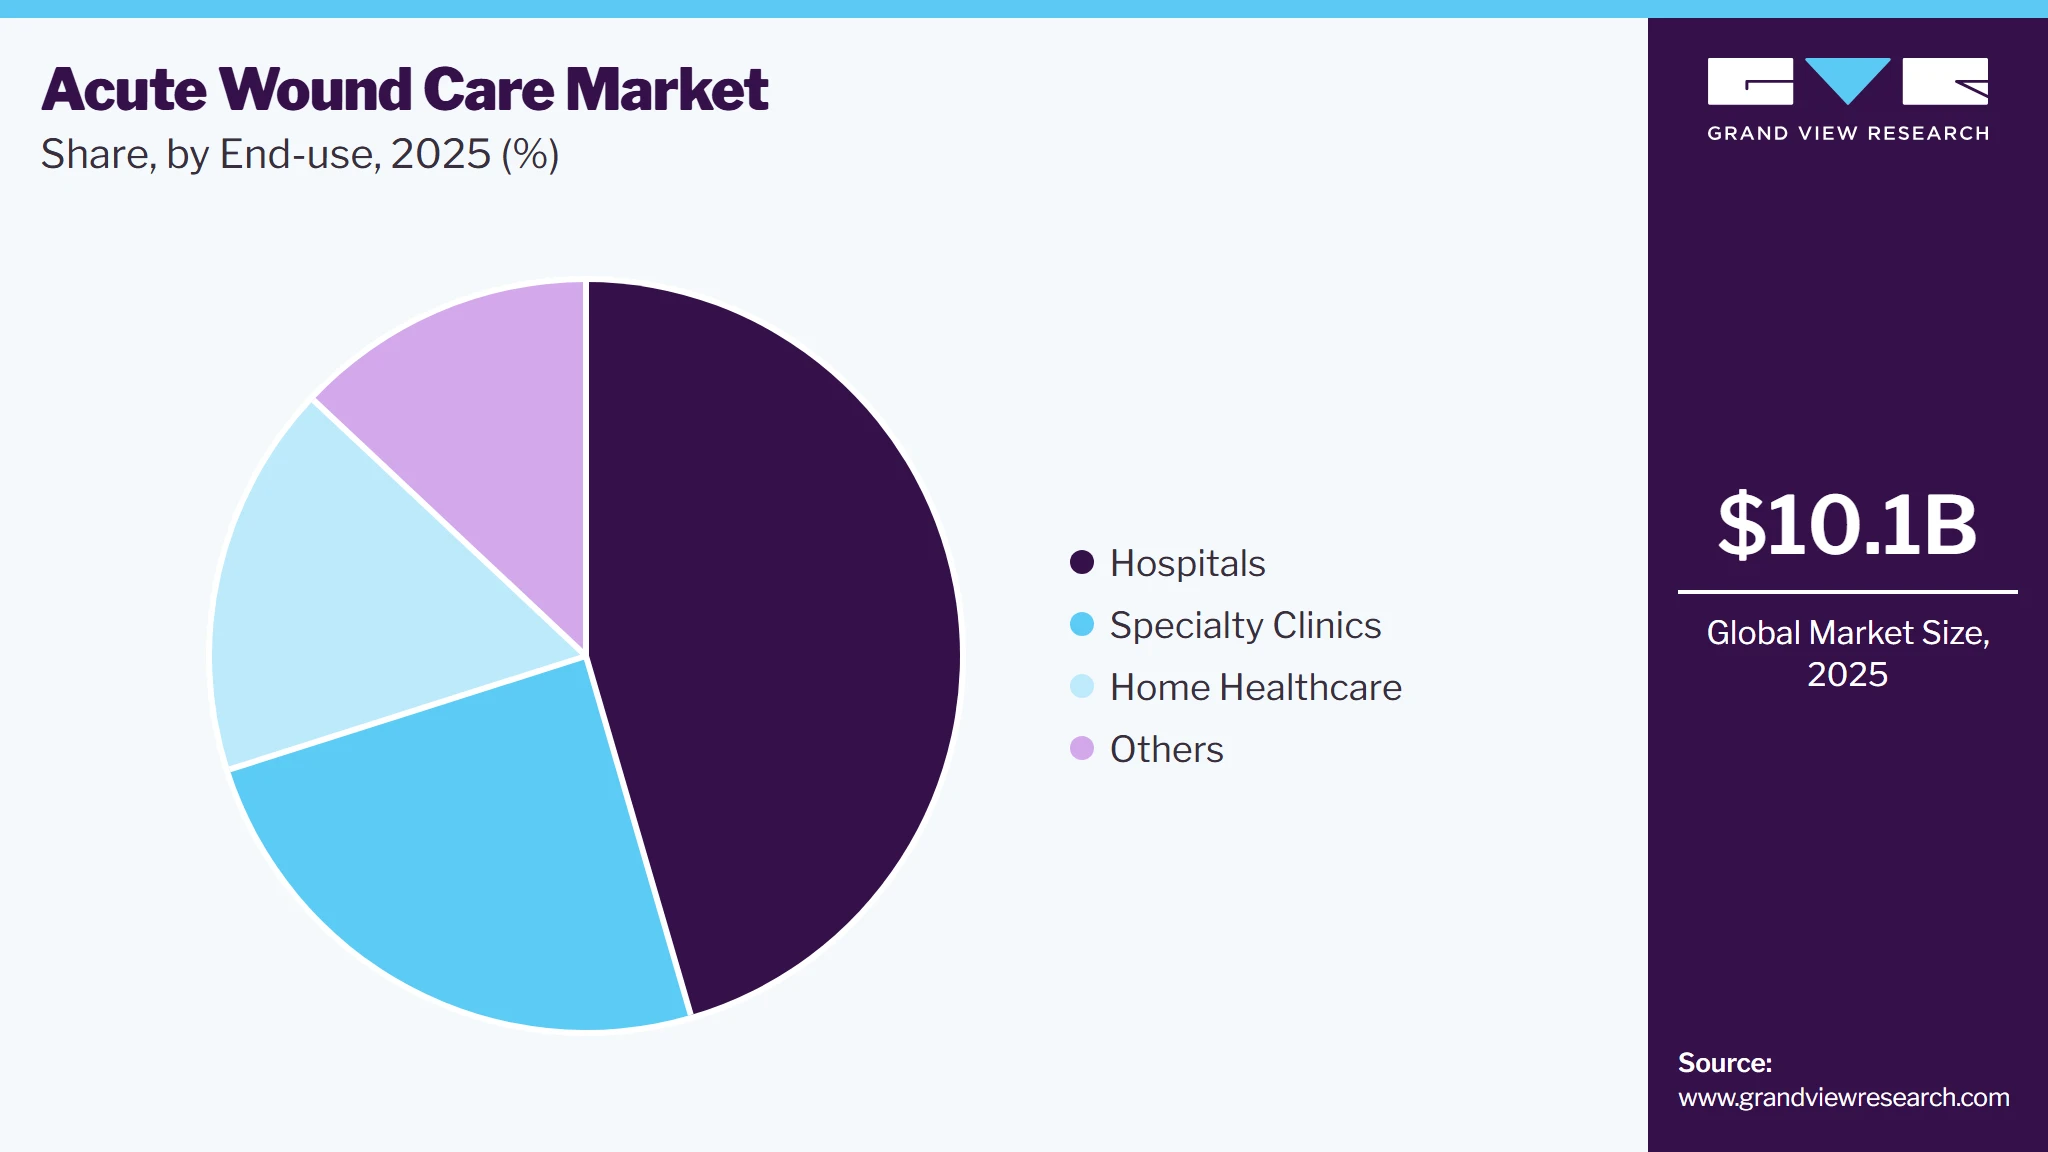
Based on end-use, the hospitals segment led the market with the largest revenue share of 45.5% in 2025 of the rising hospitalization and increasing incidence of surgical site infections in hospitals. Development in the healthcare sector has resulted in hospitals adopting the use of technologically advanced surgical equipment and treatments. Initiatives taken by government and private medical institutes to improve the availability of various surgeries to the population have further enhanced the growth of this segment. Furthermore, the increase in disposable income has led to patients seeking costly surgeries available in hospitals. Therefore, there is an increase in the demand for wound management in hospitals. These factors have resulted in the segment’s growth.
 To learn more about this report, Download Free Sample Report
Home healthcare is expected to grow at the fastest CAGR over the forecast period. This market growth is attributed to the rising geriatric population and increased treatment costs in hospitals and ambulatory surgical centres, which is expected to fuel the demand for home healthcare practice. Increased awareness regarding at-home treatments due to their affordability and customisation to the patient has resulted in major companies investing in producing wound care products compatible with at-home usage. Hence, these factors have contributed to the market growth of this segment.
Regional Insights
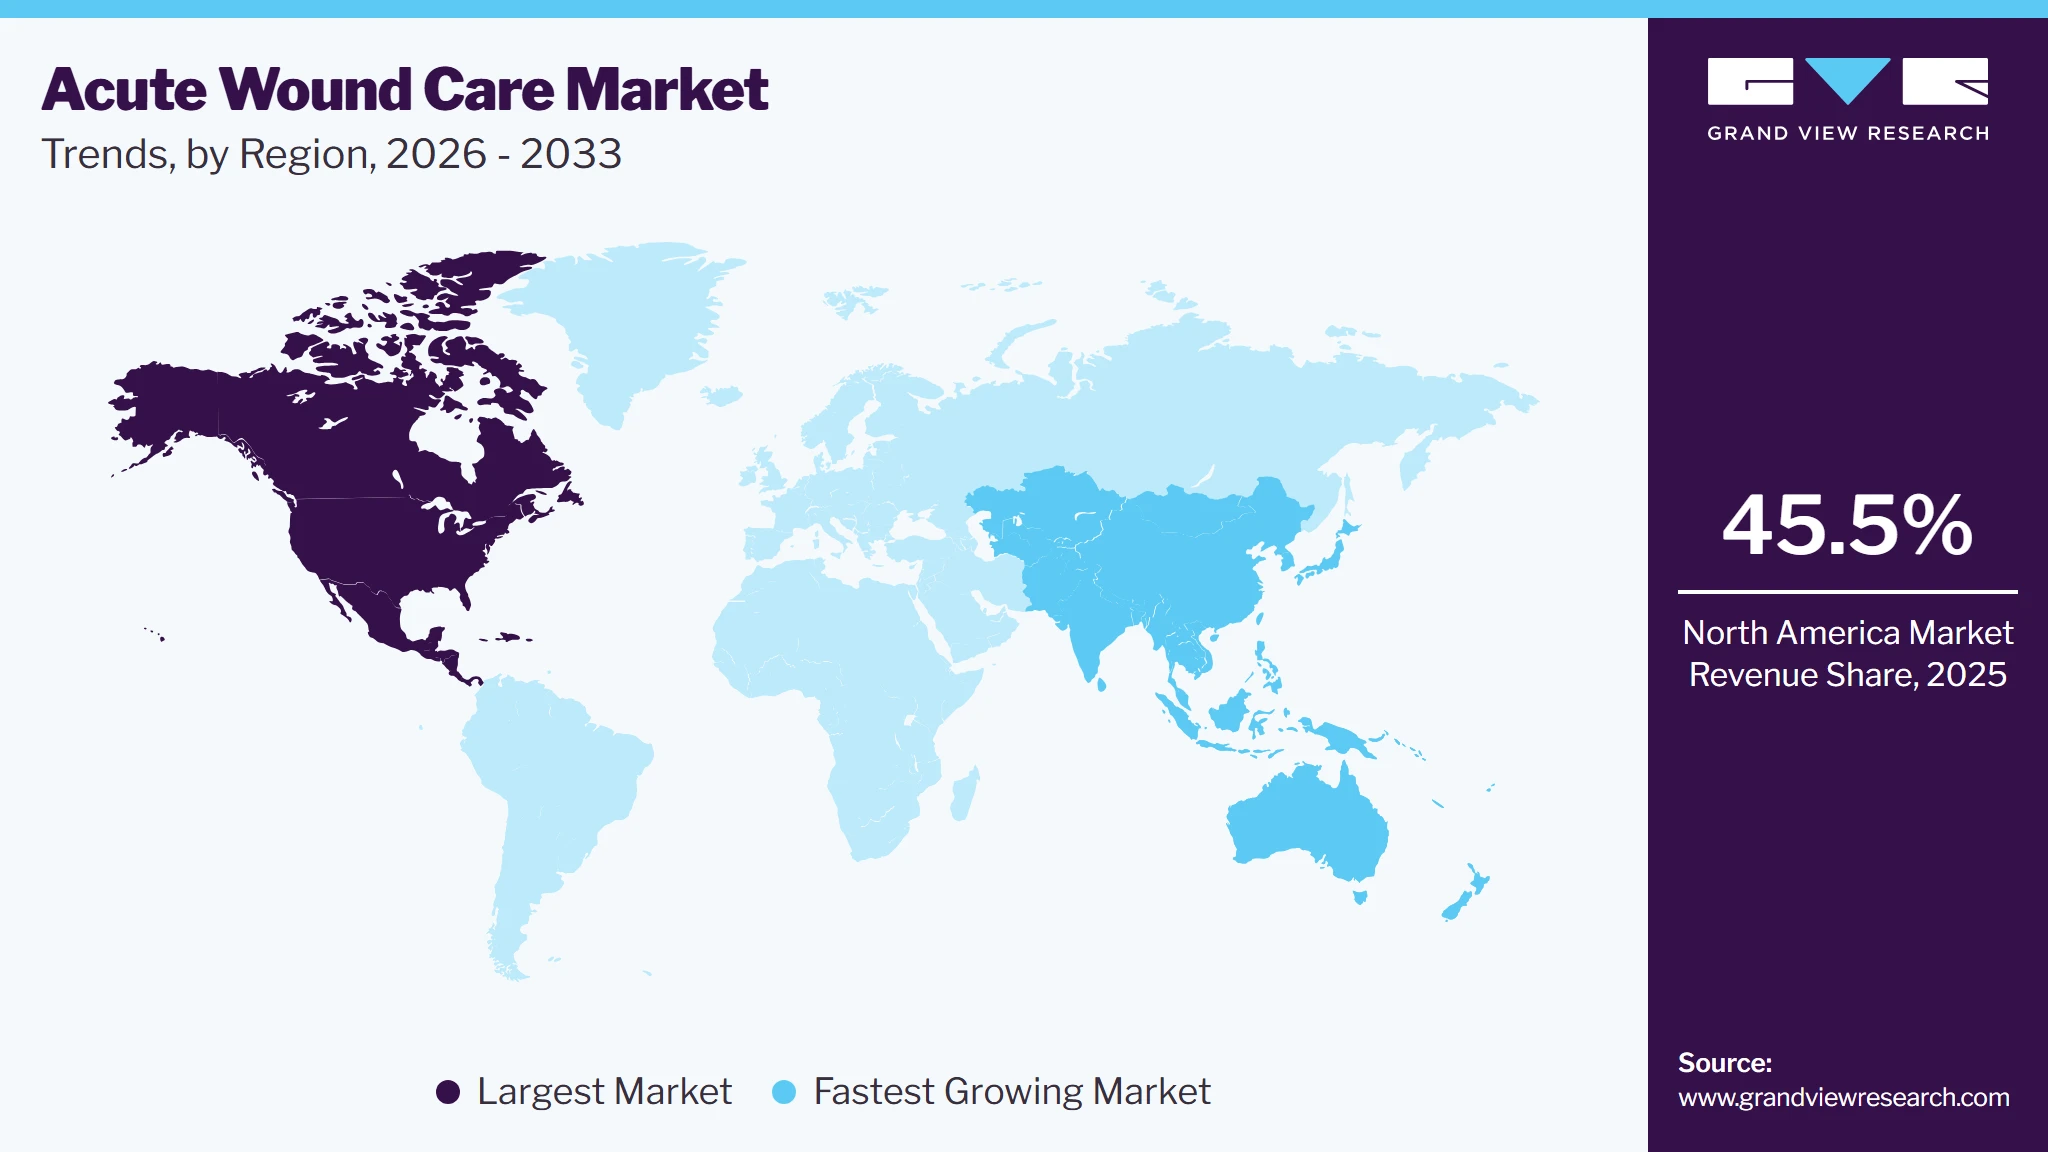
North America dominated the acute wound care market with the largest revenue share of 45.5% in 2025. The growth can be attributed to factors such as several key market players in this region, growing demand for high-quality healthcare services, well-established healthcare infrastructure, and favourable reimbursement policies and regulatory reforms in the healthcare sector. In addition, the rising geriatric population in this region is expected to raise the demand for acute wound care products. According to the Population Reference Bureau, the population above 65 in the U.S. is projected to grow from 58 million in 2022 to 82 million by 2050, an increase of 47.0%. Therefore, there is an increase in surgical procedures and wound management as the senior population is more susceptible to wounds. Thus, these factors have resulted in the market growth of this region.
 To learn more about this report, Download Free Sample Report
U.S. Acute Wound Care Market Trends
The acute wound care market in the U.S. held the largest share in the North America region in 2025. The U.S. acute wound care market held a substantial revenue share in North America owing to the presence of a developed healthcare sector and major companies in the country. The rising number of road accidents and crash injuries has increased the demand for wound care procedures in the country. According to the National Highway Traffic Safety Administration, 40,990 people died due to vehicle crashes in 2024. Furthermore, the rising geriatric population requiring surgical treatments has contributed to the market growth because geriatric patients are more susceptible to wounds. Hence, these factors contribute to the country's market growth.
Europe Acute Wound Care Market Trends
The Europe acute wound care market was identified as a lucrative region in this industry, with a market share of 26.1% in 2025. This growth was attributed to the growing number of surgical procedures requiring wound management and the presence of major medical facilities in the region. Growth in the healthcare sector and an increase in the disposable income of the population have resulted in increased demand for surgical operations. Hence, this has led to a rise in the demand for wound management. Therefore, these factors have resulted in market growth in this region.
The UK acute wound care market is expected to grow rapidly due to the rising number of surgical procedures and the increasing prevalence of road accidents and other crash injuries among the population. Major companies are investing in the launch of improved wound management products to mitigate the demand from hospitals and in-house treatments. Furthermore, the rising number of patients suffering from wounds caused by diseases such as diabetes and obesity has contributed to the market growth in this country.
Asia Pacific Acute Wound Care Market Trends
The acute wound care market in Asia Pacific held a share of 16.1% in 2024. The growth can be accredited to the rising population, road accidents, and increasing surgical procedures in this region. The rising number of surgical procedures has increased the risk of surgical site infections, increasing demand for high-quality wound management dressings and treatments. Furthermore, the rising population in countries such as China, India, and Japan has increased the number of surgical procedures performed, resulting in the increased usage of wound management products. Therefore, these factors aid in the market growth in this region.
China acute wound care market dominated the Asia Pacific in 2024. The factors responsible for the market growth in the country are the rising geriatric population requiring surgical procedures and the increase in the number of crash injuries among the population. The rise in the number of patients suffering from wounds caused by diseases such as diabetes has further increased the demand for wound management. Furthermore, increased awareness regarding surgical procedures and favourable reimbursement policies given by the government has increased the number of surgeries performed in the country. Hence, this has led to an increase in the demand for wound care treatments and products.
Key Acute Wound Care Company Insights
Some major companies in the market are 3M, Coloplast Corp, Medline Industries, Inc., Smith + Nephew, Medtronic, and others. To strengthen their foothold in the market, companies are adopting strategies such as mergers and acquisitions, partnerships, and new product launches.
-
ConvaTec Group PLC is a company that produces medical products and technologies. The company focuses on solutions for managing chronic conditions, advanced wound care, ostomy care, continence care, and infusion care.
-
Coloplast Corp is a medical company that develops products and services for medical conditions. The company specializes in ostomy, urology, continence, and wound care services.
Key Acute Wound Care Companies:
The following key companies have been profiled for this study on the acute wound care market.
-
3M
-
Coloplast Corp
-
Medline Industries, Inc.
-
Smith + Nephew
-
Medtronic
-
ConvaTec Group PLC
-
Integra LifeSciences
-
Ethicon (Johnson & Johnson)
-
Baxter
-
Molnlycke Health Care AB
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (3M, Coloplast, Smith + Nephew, Molnlycke Health Care AB, Medline Industries)
- Focus on expanding comprehensive wound care portfolios covering traditional dressings, advanced dressings, wound therapy devices, and surgical wound care.
- Invest heavily in R&D to develop antimicrobial, bioactive, and infection-prevention technologies.
- Strong global brand recognition and established relationships with hospitals and healthcare systems.
- Broad product portfolios enabling bundled sales across multiple wound care categories.
- Premium-priced products may limit adoption in price-sensitive healthcare systems.
- Large organizational structures can slow product development and commercialization.
Emerging Players (Tasami, Changzhou Major Medical Products Co., Ltd., Mediq, Datt Mediproducts Private Limited, Bravida Medical)
- Focus on niche product categories such as bioactive dressings, antimicrobial technologies, and portable wound therapy devices.
- Expand through regional distributors, OEM manufacturing, and cost-competitive offerings with affordable and easy-to-use products.
- Greater flexibility in product development and faster commercialization of new technologies.
- Competitive pricing strategies suited to cost-sensitive markets.
- Limited brand recognition and smaller sales and distribution networks.
- Lower R&D budgets and manufacturing scale compared with established competitors.
Recent Developments
-
In May 2024, ConvaTec Group PLC. announced the clinical results from a multinational, randomized controlled trial (RCT) showcasing the advancements in healing venous leg ulcers with AQUACEL Ag+ Extra compared to standard care dressing. The study found that AQUACEL Ag+ Extra aided in the healing of the venous leg ulcer, with a 31% chance of completely healing the wound in 12 weeks.
-
In January 2023, Coloplast Corp. announced the launch of Biatain Silicone Fit for pressure injury prevention and wound management in the U.S. The launch was aimed at expanding the company's position in advanced wound care by launching a new silicone foam that will benefit healthcare professionals and patients.
Acute Wound Care Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 10.1 billion
Estimated market size in 2026
USD 10.5 billion
Projected market size by 2033
USD 14.3 billion
Growth rate
CAGR of 4.4% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, application, end-use,region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; Russia; Iceland; Finland; China; Japan; India; South Korea; Australia; Thailand; Singapore; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait; Israel
Key companies profiled
Solventum (3M), Coloplast Corp, Medline Industries, L.P., Smith+Nephew, Cardinal Health, Convatec Inc., Mölnlycke Health Care AB, Integra LifeSciences, Ethicon (Johnson & Johnson), Baxter, Essity, Medtronic, DermaRite Industries, LLC, B. Braun SE, Tasami, Mediq, Datt Mediproducts Private Limited, Changzhou Major Medical Products Co., Ltd., Ningbo Medelast Co., Ltd., Aero Healthcare AU Pty Ltd, Zhejiang Kawamoto Health Care Products Co., Ltd. (Kawamoto Corporation)
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
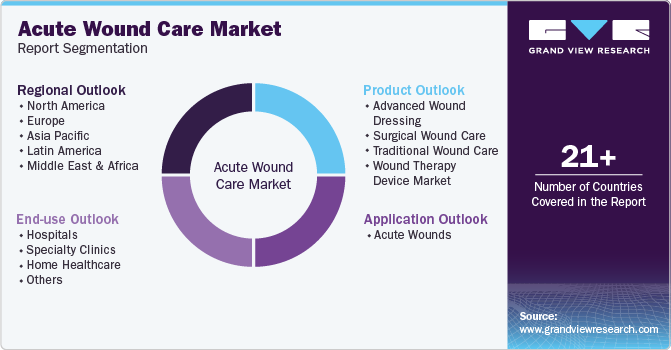
Global Acute Wound Care Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global acute wound care market report based on product, application, end use, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Advanced Wound Dressing
-
Foam Dressing
-
Hydrocolloid Dressing
-
Film Dressing
-
Alginate Dressing
-
Hydrogel Dressing
-
Collagen Dressing
-
Other Advanced Dressing
-
-
Surgical Wound Care
-
Sutures & Staples
-
Tissue Adhesive & Sealants
-
Anti-infective Dressing
-
-
Traditional Wound Care
-
Medical Tapes
-
Cleansing Agents
-
Others
-
-
Wound Therapy Device Market
-
Negative Pressure Wound Therapy
-
Oxygen & Hyperbaric Oxygen Equipment
-
Electric Stimulation Devices
-
Pressure Relief Devices
-
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Acute Wounds
-
Surgical & Traumatic Wounds
-
Burns
-
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospitals
-
Specialty Clinics
-
Home Healthcare
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
Thailand
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
Kuwait
-
UAE
-
-
Research Methodology
The acute wound care market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each acute wound care segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Advanced Wound Dressing
This segment captures revenue from advanced wound dressings used to promote healing, manage exudate, maintain a moist wound environment, and reduce infection risk in acute wounds. It includes foam, hydrocolloid, hydrogel, alginate, film, antimicrobial, silicone, superabsorbent, and bioactive/collagen dressings used across hospitals, ambulatory surgical centers, clinics, and home healthcare settings.
Surgical Wound Care
This segment captures revenue from products used to manage and protect surgical incisions during the postoperative healing process. It includes surgical dressings, incision management products, tissue adhesives, and surgical sealants used across hospitals, ambulatory surgical centers, and clinics.
Traditional Wound Care
This segment captures revenue from conventional wound care products used for basic management and protection of acute wounds. It includes gauze, cotton dressings, adhesive bandages, absorbent pads, and wound tapes used across hospitals, clinics, ambulatory surgical centers, and home healthcare settings.
Wound Therapy Devices
This segment captures revenue from devices used to support the healing and management of acute wounds. It includes negative-pressure wound therapy (NPWT) systems, wound irrigation devices, oxygen therapy devices, and related accessories used in hospitals, ambulatory surgical centers, clinics, and home healthcare settings.
Estimation Model
Approach
Methodology
Description
Bottom-Up
Procedure Volume Modeling
Models the total volume of acute wounds, including surgical incisions, traumatic injuries, burns, lacerations, abrasions, and emergency wounds requiring treatment. Estimates product demand based on procedure volumes, wound incidence, dressing change frequency, average products used per patient, and treatment protocols across hospitals, ambulatory surgical centers, trauma centers, emergency departments, and home healthcare settings.
Top-Down
Revenue Triangulation
Estimates the market by aggregating revenue generated from acute wound care product portfolios of leading manufacturers, including advanced wound dressings, traditional wound care products, wound therapy devices, and surgical wound care products. Revenue estimates are validated using product segmentation, regional sales distribution, company financial reports, public disclosures, and channel analysis to eliminate double-counting and ensure accurate market sizing.
Demand-Side
Care-Setting Modeling
Evaluates demand for acute wound care products across hospitals, trauma centers, emergency departments, ambulatory surgical centers, specialty clinics, and home healthcare settings. The model incorporates surgical procedure volumes, trauma and burn incidence, procurement trends, wound management protocols, reimbursement policies, treatment guidelines, healthcare expenditure, and regional clinical practices to estimate product consumption across major markets.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Disease Epidemiology Analysis
Country-wise epidemiology of acute wounds and burn injuries.
Incidence and prevalence of burn cases categorized into First-degree, Second-degree, and Third-degree burns across major countries.
Analysis of trauma, surgical wounds, and burn burden.
Identifies high-growth geographies and patient pools.
Supports demand forecasting and market sizing.
Enables targeted regional expansion and product positioning.
Product Share Analysis
Market share analysis by product category, including traditional wound care, advanced wound dressings, surgical wound care, wound therapy devices, and tissue adhesives/surgical sealants.
Product adoption trends by healthcare setting and region.
Identifies high-revenue product segments.
Supports portfolio optimization and investment decisions.
Highlights emerging product opportunities and competitive positioning.
Regulatory & Reimbursement Trends
Country-wise review of regulatory pathways, product approval requirements, and reimbursement policies for acute wound care products.
Assessment of changes in healthcare coverage, coding, and reimbursement affecting product adoption.
Facilitates market entry and regulatory planning.
Identifies reimbursement-driven growth opportunities and barriers.
Supports pricing, commercialization, and long-term market strategy.
Frequently Asked Questions About This Report
The global acute wound care market size was valued at USD 10.1 billion in 2025 and is eestimated at USD 10.5 billion in 2026.
Key factors that are driving the acute wound care market growth include the increasing prevalence of traumatic accidents , the increase in a number of surgical procedures, and changing lifestyles are anticipated to drive the growth of the wound care market.
The global acute wound care market is expected to grow at a CAGR of 4.4% from 2026 to 2033 to reach USD 14.3 billion by 2033.
Advanced wound dressing segment led the market with the largest revenue share of 35.1% in 2025 and is the fastest growing product.
North America dominated the acute wound care market with the largest revenue share of 45.5% in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
The hospitals segment led the market with the largest revenue share of 45.5% in 2025, while home healthcare is the fastest growing end-use.
Some key players operating in the wound care market include Solventum (3M), Coloplast Corp, Medline Industries, L.P., Smith+Nephew, Cardinal Health, Convatec Inc., Mölnlycke Health Care AB, Integra LifeSciences, Ethicon (Johnson & Johnson), Baxter, Essity, Medtronic, DermaRite Industries, LLC, B. Braun SE, Tasami, Mediq, Datt Mediproducts Private Limited, Changzhou Major Medical Products Co., Ltd., Ningbo Medelast Co., Ltd., Aero Healthcare AU Pty Ltd and Zhejiang Kawamoto Health Care Products Co., Ltd. (Kawamoto Corporation).
The surgical & traumatic wound segment led the market with the largest revenue share of 80.2% in 2025 and is the fastest growing application.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


