
- Home
- »
- Medical Devices
- »
-
Advanced Ophthalmology Technology Market Report, 2033GVR Report cover

Advanced Ophthalmology Technology Market (2026 - 2033 )
Size, Share & Trends Analysis Report By Type (Diagnostic, Therapeutic), By End Use (Hospitals, Ambulatory Surgical Centers, Ophthalmic Clinics), By Region, And Segment Forecasts
Market Size, 2025
$9.1BMarket Estimate, 2026
$9.7BMarket Forecast, 2033
$16.4BCAGR, 2026–2033
7.8%Advanced Ophthalmology Technology Market Summary
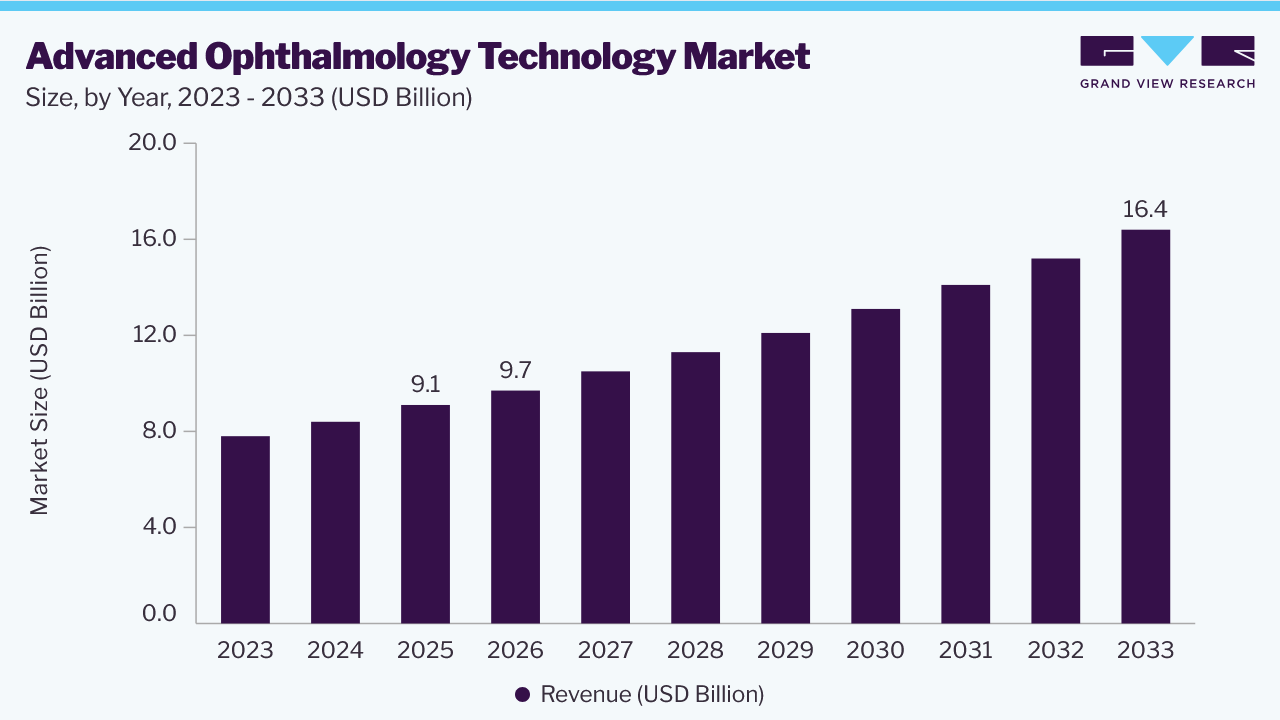
The global advanced ophthalmology technology market size was valued at USD 9.1 billion in 2025 and is projected to grow from USD 9.7 billion in 2026 to USD 16.4 billion in 2033, at a CAGR of 7.8% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 35.0% in 2025. Advanced ophthalmology technologies include imaging, surgical instruments, laser systems, and biotechnology advances that improve the accuracy and effectiveness of ophthalmic care. Factors such as the growing geriatric population, rising rates of eye-related disorders, technological advancements, and the need for minimally invasive procedures are significantly driving market growth.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type, the diagnostics segment dominated the market and accounted for a share of around 55.0% in 2025.
- By end use, the hospitals segment dominated the market and accounted for a share of around 40.0% in 2025.
Regional Highlights
- Largest regional market: North America (35.0% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 9.1 Billion
- Estimated market size in 2026: USD 9.7 Billion
- Projected market size by 2033: USD 16.4 Billion
- CAGR (2026-2033): 7.8%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
A direct answer, usually in 1 working day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The market for advanced ophthalmology devices is booming in 2025 due to the increasing prevalence of eye-related conditions such as cataracts, glaucoma, diabetic retinopathy, and myopia. A growing awareness of preventive diagnostics and innovative surgical techniques further fuels this surge. Key factors driving this growth include precise eye care, a shift towards less invasive laser surgeries, and AI-supported diagnosis, all of which have significantly improved treatment outcomes and raised global awareness.
Cataracts are currently the most common age-related eye condition, with over 20 million surgeries performed each year globally, and this number is expected to rise as the population ages. Additionally, estimates from ophthalmic organizations indicate that more than a billion people worldwide suffer from curable or preventable vision impairment, highlighting the substantial unmet clinical demand in the field of ophthalmology.
Considering the rising prevalence of myopia, it's projected that nearly 50 percent of the global population could be myopic by 2050. This growing demand for corrective technologies and diagnostic methods is likely to drive market growth in the coming years.
Analyst Perspective
The advanced ophthalmology technology market is evolving as eye care providers increasingly adopt precision-based diagnostic and treatment solutions to improve patient outcomes. Technologies such as advanced imaging systems, AI-assisted diagnostics, and minimally invasive surgical tools are becoming more important in managing complex eye conditions and supporting early disease detection. Companies with strong clinical expertise, innovative product portfolios, and established relationships with hospitals and ophthalmology centers are likely to strengthen their market position. As demand for specialized eye care continues to rise, healthcare providers are expected to prioritize technologies that improve workflow efficiency, diagnostic accuracy, and treatment effectiveness. Over time, market success will depend on clinical reliability, ease of integration, and the ability to support more personalized and efficient ophthalmic care.
Type insights
The diagnostics segment dominated the market, accounting for around 55.0% in 2025. The growing prevalence of ophthalmic disorders such as eyestrain, glaucoma, cataracts, diabetic retinopathy, and color blindness is driving the demand for early-stage diagnosis and advanced ophthalmic screening solutions. In addition, the rapidly increasing geriatric population has contributed to a higher burden of avoidable blindness and age-related vision disorders, further supporting the need for regular eye examinations and preventive healthcare services.
Rising healthcare awareness among individuals is also encouraging routine eye check-ups, thereby contributing to market growth. According to the 2025 update of the International Diabetes Federation (IDF) Diabetes Atlas, diabetic retinopathy remains one of the leading causes of vision impairment globally. The report further indicates that the global diabetic population is expected to surpass 500 million, increasing the risk of diabetes-related eye complications and driving the demand for advanced retinal imaging and ophthalmic screening equipment.
The therapeutic segment is anticipated to witness the fastest CAGR over the forecast period. This segment comprises therapies and pharmaceutical products used to treat ophthalmic disorders, including retinal diseases, glaucoma, allergies, infections, and other vision-related conditions. Market growth is primarily driven by the rising prevalence of ophthalmic diseases, increasing commercialization and approval of innovative treatment products, and the growing adoption of advanced technologies in ophthalmic care. In addition, ongoing research and development activities, along with the increasing demand for effective and minimally invasive treatment solutions, are further contributing to the growth of the segment.
End Use Insights
The hospitals segment dominated the market, accounting for approximately 40.0% of revenue in 2025, driven by the rapid adoption of advanced ophthalmology technologies, rising patient volumes, and the increasing availability of skilled healthcare professionals in hospital settings. In addition, hospitals generally have larger equipment budgets than other end-use settings, enabling greater investment in technologically advanced ophthalmic devices and diagnostic systems. Growing awareness of the benefits of advanced ophthalmology equipment in improving treatment outcomes, enhancing surgical precision, and reducing patient recovery time has further supported the segment's growth.
The ASCs (Ambulatory Surgery Centers) segment is expected to grow at the fastest CAGR over the forecast period. The growth of this segment is primarily driven by increasing awareness regarding the benefits of advanced ophthalmic technologies used in treatment procedures, along with the rising number of ASCs globally. In addition, the growing availability of skilled healthcare professionals and the increasing preference for cost-effective, minimally invasive outpatient procedures have significantly contributed to market growth. The adoption of technologically advanced ophthalmic equipment in ASCs is further improving surgical efficiency, reducing hospital stays, and enhancing patient outcomes.
Regional Insights
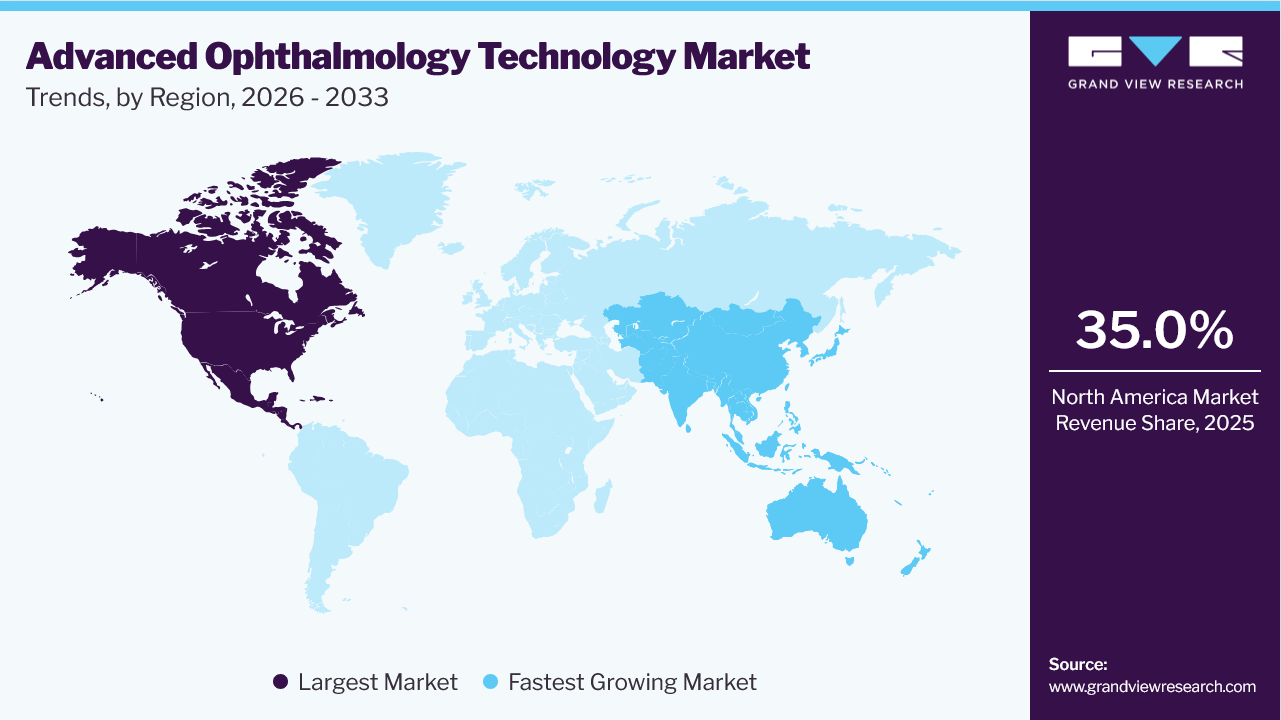
The North America advanced ophthalmology technology market dominated the market with a share of around 35.0% in 2025. The presence of a large patient pool, the growing patient population, various market players in the region, and initiatives to improve healthcare infrastructure have significantly influenced the market's growth. In addition, high-sugar diets in the region have contributed to the rise in diabetes, further increasing the number of patients and boosting the advanced ophthalmology technology market. According to the American Academy of Ophthalmology, dry eye affects nearly 16 million Americans, and its prevalence increases with age. Approximately 3.2 million women and 1.68 million men aged 50 and over are affected by this condition. In addition, around 7 million intravitreal injections are administered annually in the U.S. to prevent vision loss from macular degeneration and diabetic retinopathy.
 To learn more about this report, Download Free Sample Report
U.S. Advanced Ophthalmology Technology Market Trends
The U.S. advanced ophthalmology technology market dominated North America in 2025, with the largest share, due to the increasing number of diabetic patients, increased research and development by major players, and rising patient numbers. In addition, the presence of major players has driven advancements in technology and minimally invasive treatments, further fueling market growth.
Europe Advanced Ophthalmology Technology Market Trends
The advanced ophthalmology technology market in Europe was identified as a lucrative region in 2025. The increasing number of patients and the growing use of mobile phones, TVs, and laptops have led to various eye disorders. Initiatives by the region’s governments to improve their healthcare infrastructure have largely influenced the market growth. In addition, the rise in medical tourism, driven by the availability of more highly skilled professionals and improved infrastructure, has further fueled market growth. According to the European Blind Union (EBU), over 30 million people are estimated to be blind or partially sighted, with sight loss affecting an average of 1 in 30 Europeans. The number of partially sighted individuals is four times higher than that of blind people.
The UK advanced ophthalmology technology market is expected to grow rapidly in the coming years due to an aging population, rising prevalence of eye diseases such as glaucoma and cataracts, and increasing demand for minimally invasive procedures. In addition, advancements in diagnostic tools, treatment technologies, and supportive healthcare policies fuel market growth. In 2025, NHS-linked eye hospitals in the UK expanded the use of minimally invasive cataract surgery systems and femtosecond laser-assisted procedures to address the increasing burden of age-related eye disorders, supported by rising demand for faster recovery and outpatient-based ophthalmic treatments.
The advanced ophthalmology technology market in Germany held a substantial share in 2025, driven by the strong presence of advanced medical equipment manufacturers and increasing research and development activities across the country. The market growth is further supported by the adoption of technologically advanced ophthalmic diagnostic and surgical systems to improve treatment precision and patient outcomes. In addition, the growing prevalence of age-related vision disorders and rising demand for minimally invasive ophthalmic procedures have accelerated the adoption of innovative treatment technologies across Europe.
Asia Pacific Advanced Ophthalmology Technology Market Trends
The advanced ophthalmology technology market in Asia Pacific is projected to experience the fastest CAGR during the forecast period. This growth is driven by the expansion of healthcare infrastructure and significant investments to enhance medical facilities and access. As a result, cutting-edge ophthalmic technologies will become more widely available and adopted. Improved infrastructure supports the region's increasing demand for advanced eye care solutions. According to the World Bank Health Expenditure Data, countries in the Asia-Pacific region have been witnessing sustained growth in healthcare spending, driven by the expansion of insurance coverage and healthcare modernization initiatives, particularly in China, India, and Southeast Asia.
The Japan advanced ophthalmology technology market is expected to grow rapidly in the coming years. Innovations in surgical equipment, imaging systems, and diagnostic tools are significantly improving precision and patient outcomes. Additionally, the shift toward minimally invasive procedures is increasing demand for advanced ophthalmic technologies that enhance treatment effectiveness and overall patient experience.
The advanced ophthalmology technology market in China held a significant market share in 2025, largely due to the aging population. This demographic shift has resulted in a higher incidence of age-related eye conditions such as cataracts, macular degeneration, and glaucoma. Consequently, there is an increasing demand for advanced ophthalmology technologies to address these prevalent issues effectively. As the need for improved diagnostic and treatment solutions grows, the market for advanced ophthalmology technology continues to expand. According to the WHO Vision Health Updates, cases of vision impairment in Asia are rising, driven by the increasing prevalence of diabetes and an aging population. This trend further strengthens the demand for advanced diagnostic and treatment technologies in ophthalmology.
Key Advanced Ophthalmology Technology Market Company Insights
Some of the key players in the advanced ophthalmology technology market are Carl Zeiss Meditec AG, Bausch + Lomb, Teva Pharmaceutical Industries Ltd., CooperVision, Alcon, NIDEK CO., LTD., TOPCON CORPORATION, Ziemer Ophthalmic Systems AG, and Essilor International S.A.
Key Advanced Ophthalmology Technology Market Companies
Some key players in the global advanced ophthalmology technology market include:
-
Carl Zeiss Meditec AG
-
Bausch + Lomb.
-
Teva Pharmaceutical Industries Ltd.
-
CooperVision
-
Alcon
-
NIDEK CO., LTD.
-
TOPCON CORPORATION
-
Ziemer Ophthalmic Systems AG
-
Essilor International S.A.
Recent Developments
- In January 2026, CooperVision announced the launch of MyDay MiSight 1-day contact lenses in select global markets, combining silicone hydrogel material with myopia management technology to address rising demand for advanced vision correction and digital eye strain solutions associated with increasing screen usage.
- In September 2025, NIDEK showcased advancements in its ophthalmic and refractive surgery technologies, including upgraded excimer laser and diagnostic systems, at the European Society of Cataract and Refractive Surgeons (ESCRS) 2025 conference. The developments reflected ongoing innovation aimed at improving precision and efficiency in LASIK and cataract-related procedures.
Advanced Ophthalmology Technology Market Report Scope
Report Attribute
Details
Market size in 2025
USD 9.1 billion
Estimated market size in 2026
USD 9.7 billion
Projected market size by 2033
USD 16.4 billion
Growth rate
CAGR of 7.8% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Sweden; Norway; Japan; China; India; Australia; South Korea; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
Carl Zeiss Meditec AG; Bausch + Lomb.; Teva Pharmaceutical Industries Ltd.; CooperVision; Alcon; NIDEK CO., LTD.; TOPCON CORPORATION; Ziemer Ophthalmic Systems AG; Essilor International S.A.
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Advanced Ophthalmology Technology Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global advanced ophthalmology technology market report based on type, end use, and region.
-
Type Outlook (Revenue, USD Billion, 2021 - 2033)
-
Diagnostic
-
Therapeutic
-
-
End Use Outlook (Revenue, USD Billion, 2021 - 2033)
-
Hospitals
-
Ambulatory Surgical Centers (ASCs)
-
Ophthalmic Clinics
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa (MEA)
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Frequently Asked Questions About This Report
The global advanced ophthalmology technology market is expected to grow at a CAGR of 7.8% from 2026 to 2033, reaching USD 16.4 billion.
The diagnostics segment accounted for the largest revenue share of approximately 55.0% in 2025.
North America dominated with an approximately 35.0% revenue share in 2025.
The global advanced ophthalmology technology market size was valued at USD 9.1 billion in 2025 and is estimated at USD 9.7 billion for 2026.
Key players in the market include Carl Zeiss Meditec AG; Bausch + Lomb.; Teva Pharmaceutical Industries Ltd.; CooperVision; Alcon; NIDEK CO., LTD.; TOPCON CORPORATION; Ziemer Ophthalmic Systems AG; Essilor International S.A., and others.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


