
- Home
- »
- Digital Media
- »
-
Advertising-based Video On Demand Market Report, 2033GVR Report cover

Advertising-based Video On Demand Market (2026 - 2033)
Size, Share & Trends Analysis Report By Advertisement Position, By Device, By Enterprise Size, By Industry Vertical (Media & Entertainment, Retail & Consumer Goods), By Region, And Segment Forecasts
Market Size, 2025
$62.5BMarket Estimate, 2026
$78.7BMarket Forecast, 2033
$239.3BCAGR, 2026–2033
17.2%Advertising-based Video On Demand Market Summary
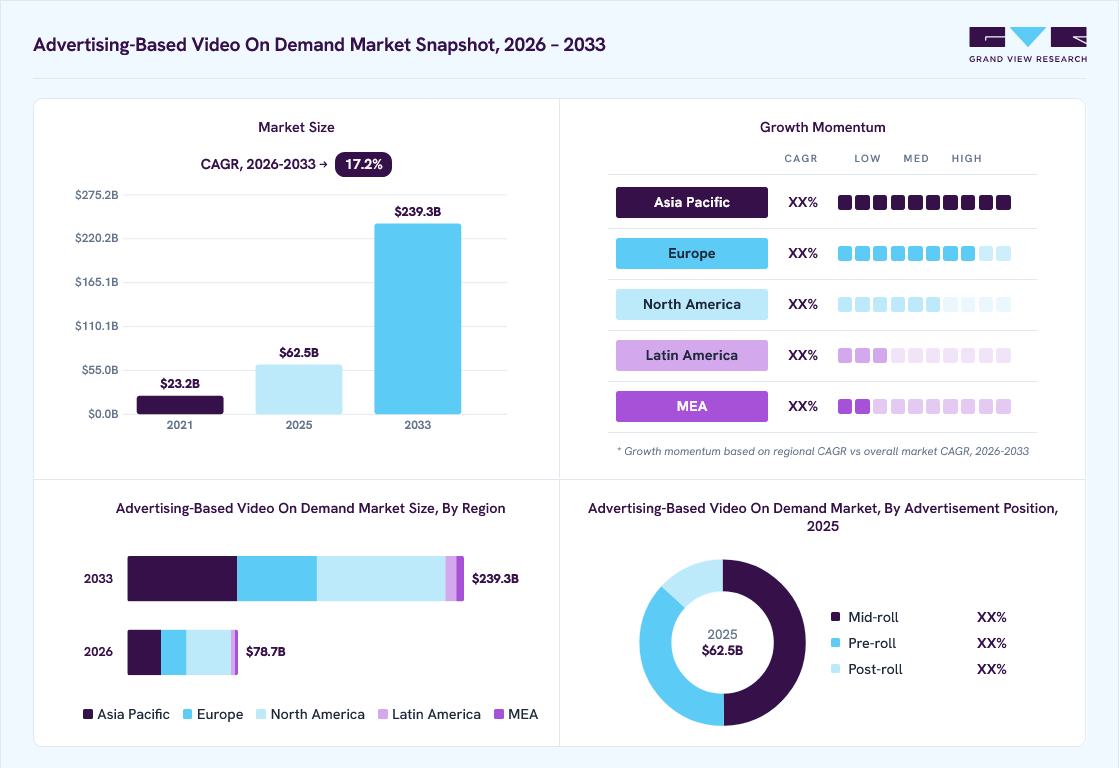
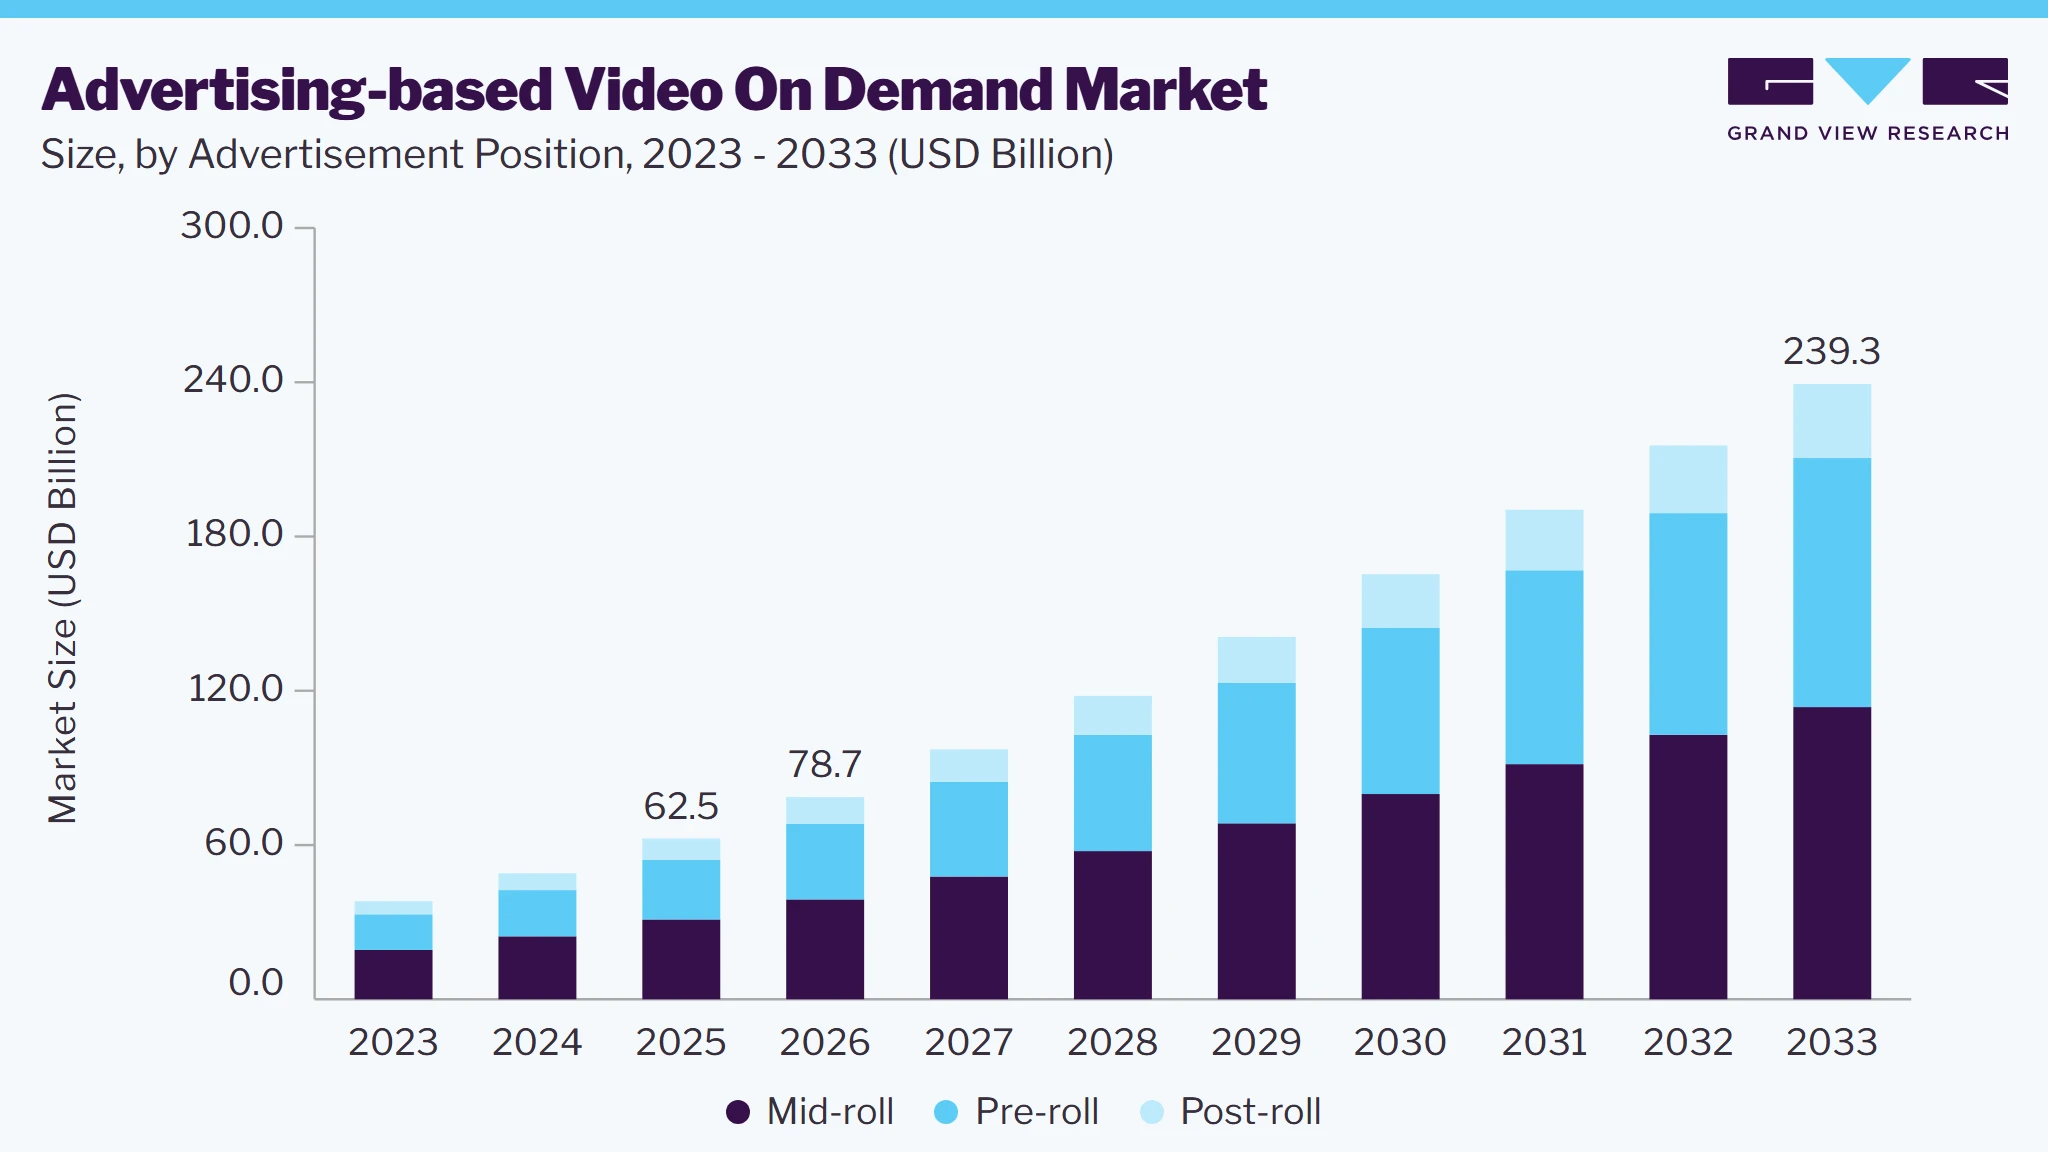
The global advertising-based video on demand market size was valued at USD 62.5 billion in 2025 and is projected to grow from USD 78.7 billion in 2026 to USD 239.3 billion by 2033, at a CAGR of 17.2% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 40.4% in 2025. The advertising-based video on demand market is driven by the increasing adoption of connected TVs and smart devices, the growing shift of advertising budgets toward digital video platforms, and the rising consumer preference for free, ad-supported streaming services.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By advertisement position: Mid-roll segment dominated the market, with a share of 49.7% in 2025.
- By device: Mobile segment accounted for the largest market share of 46.6% in 2025.
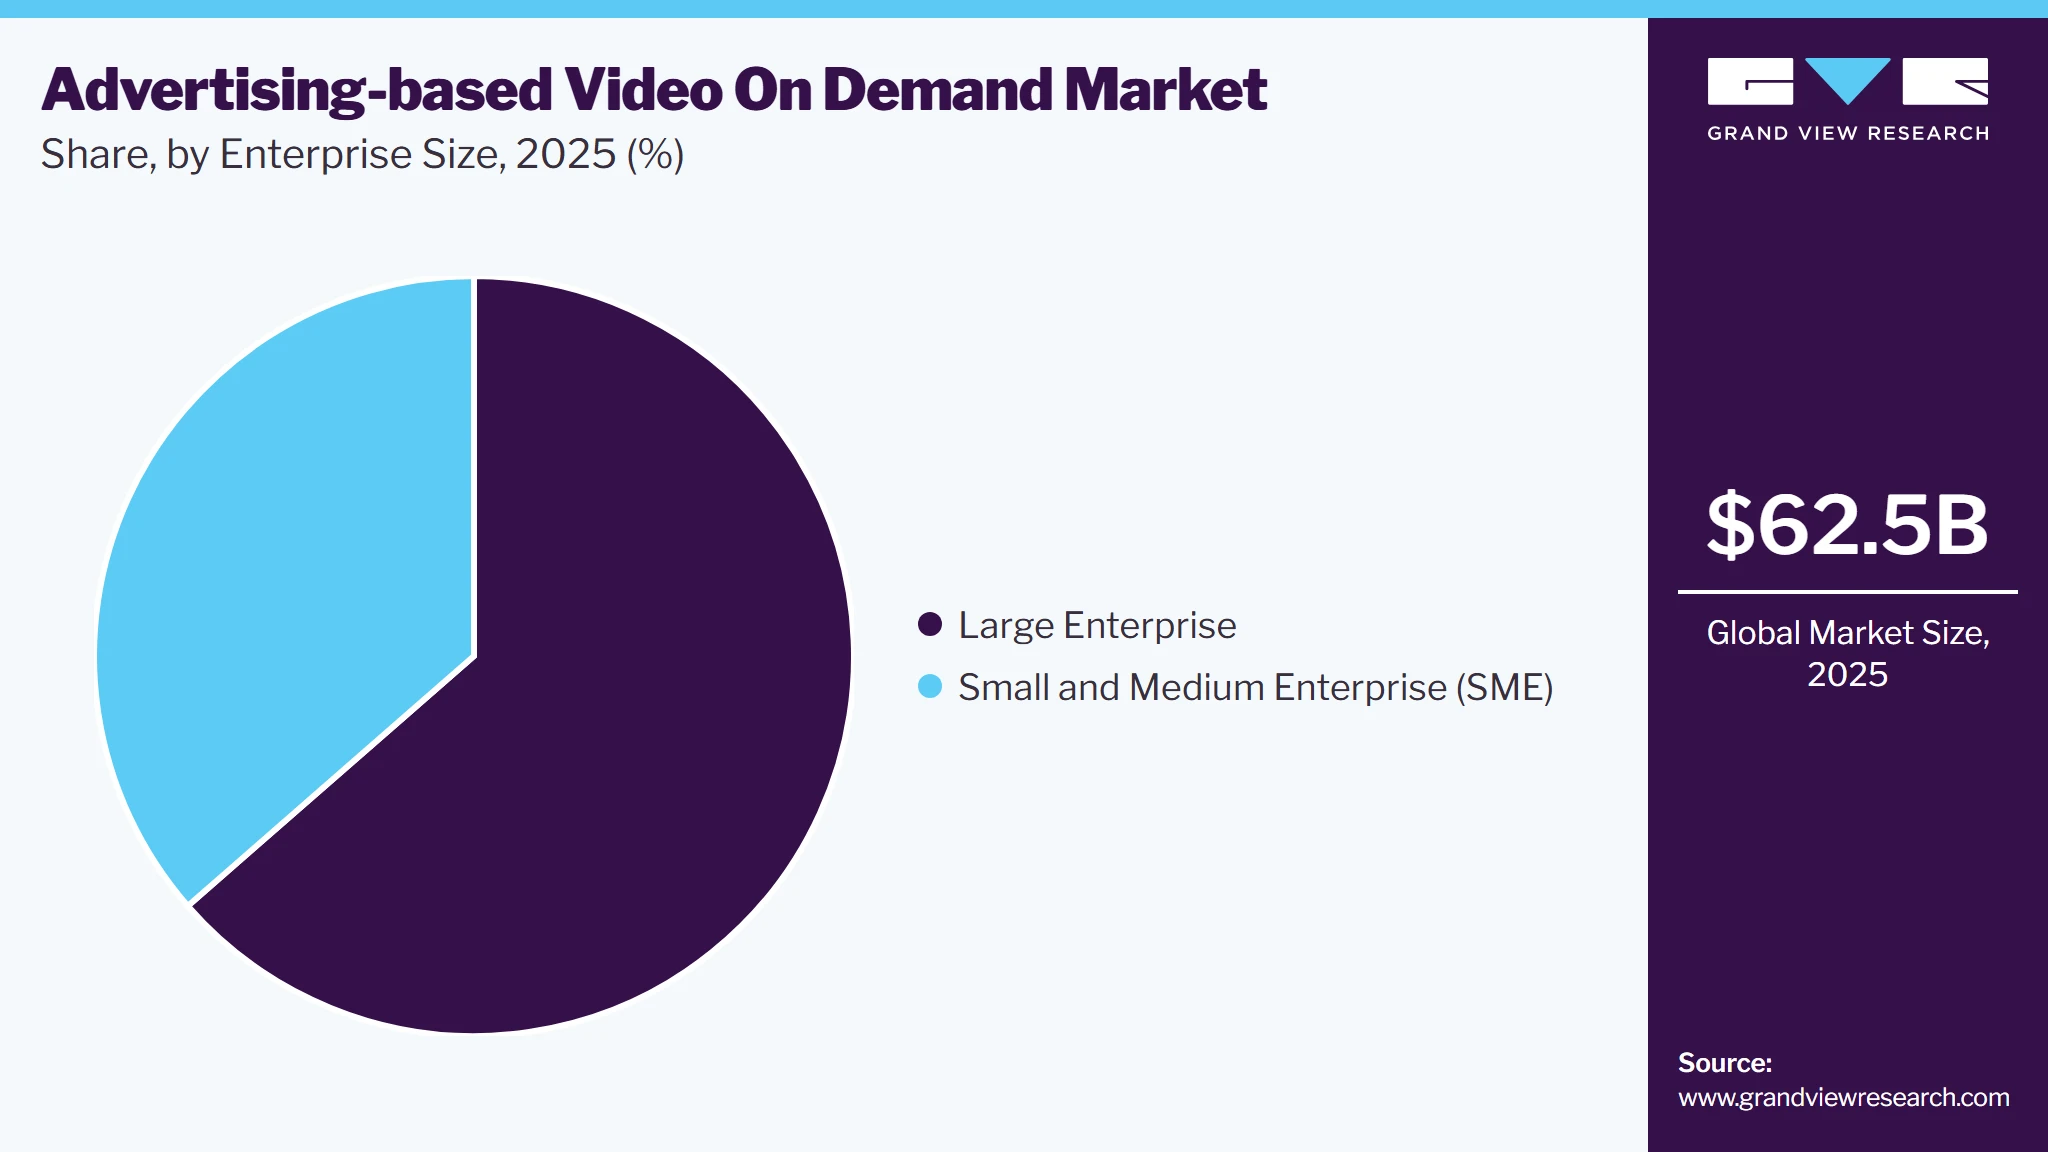
- By enterprise size: Large enterprise segment held the largest market share of 63.3% in 2025.
- By industry vertical: Retail and consumer goods segment dominated the market with a revenue share of 28.8% in 2025.
Regional Highlights
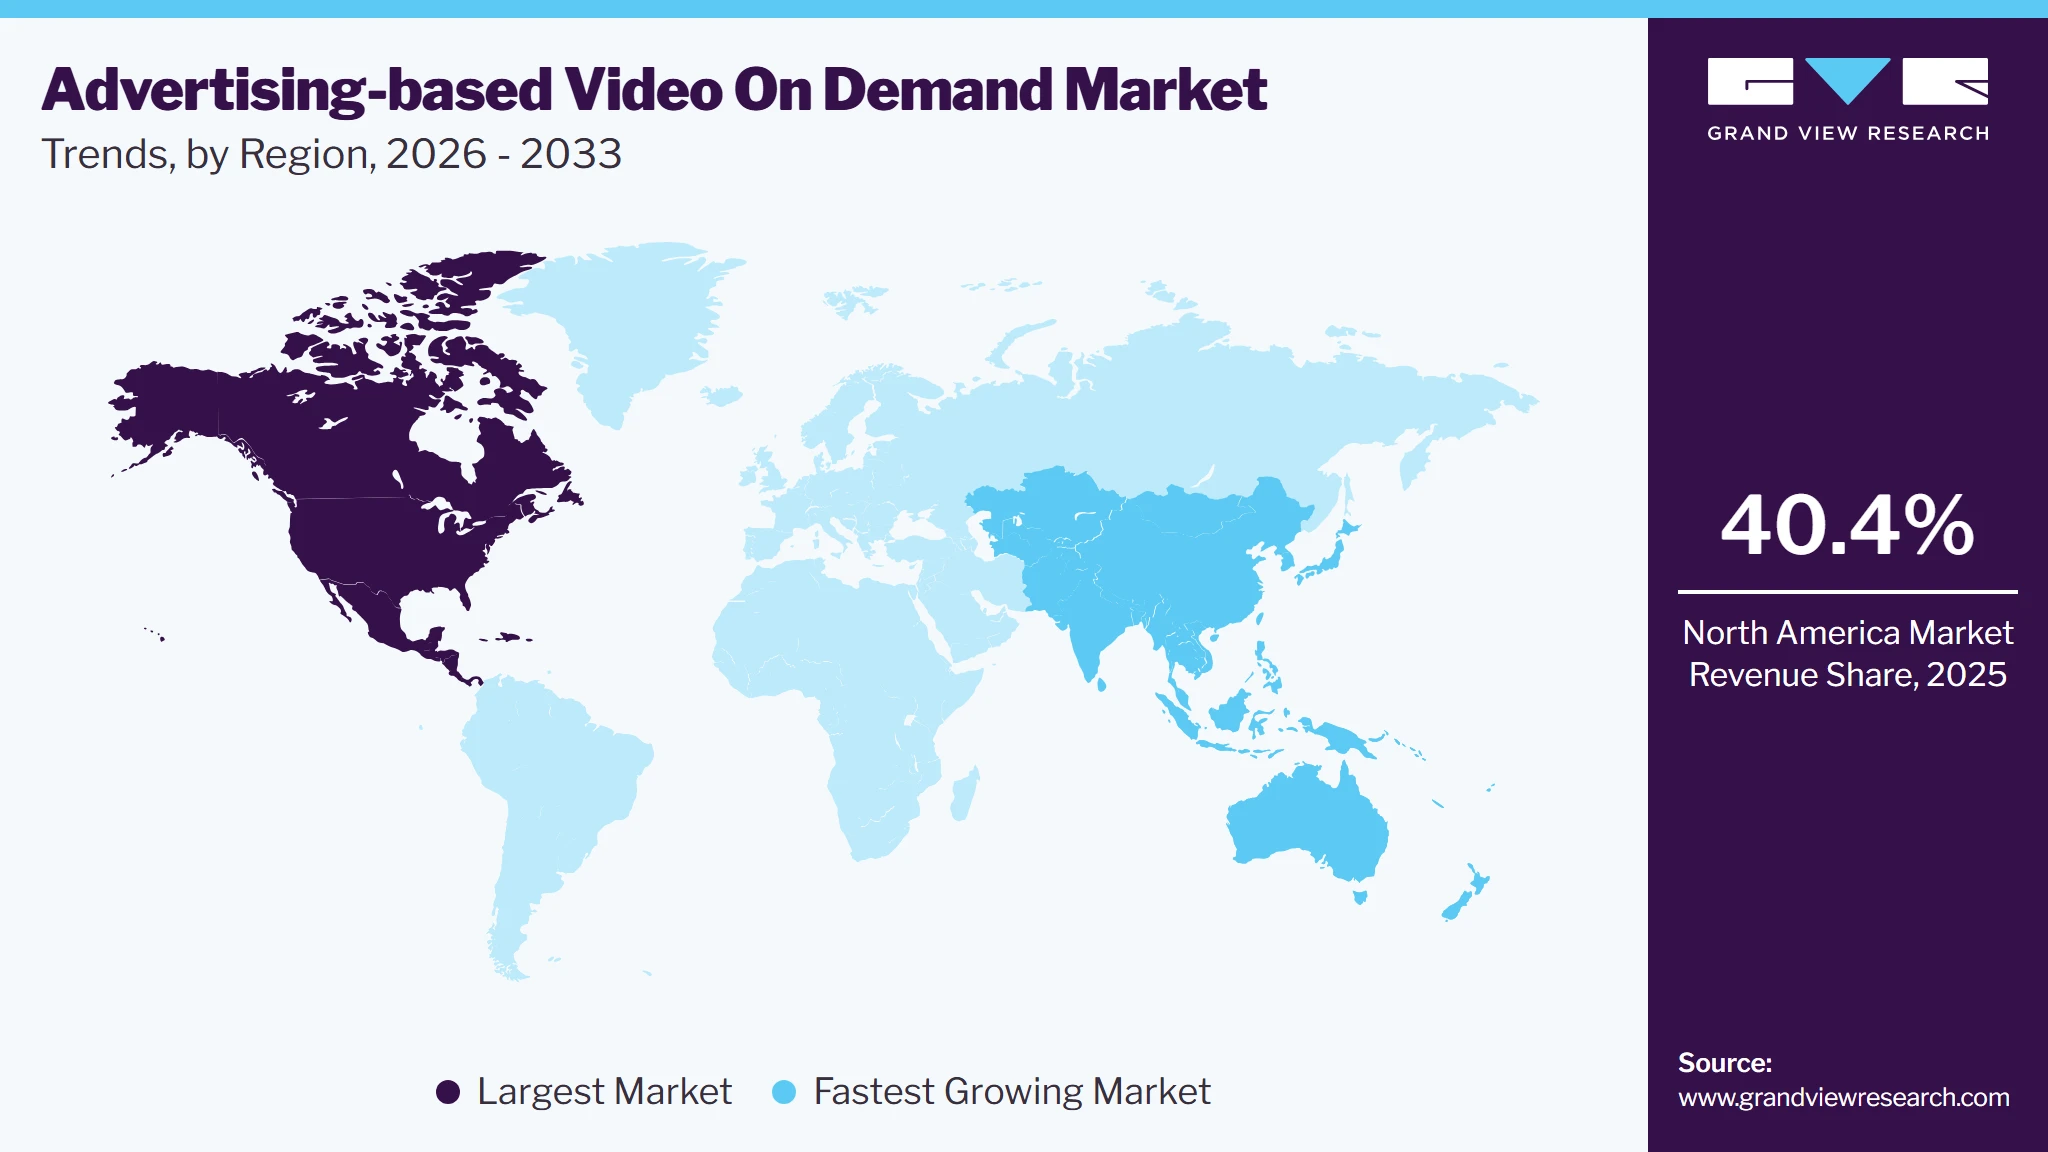
- Largest regional market: North America (40.4% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR of 18.4%, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 62.5 Billion
- Estimated market size in 2026: USD 78.7 Billion
- Projected market size by 2033: USD 239.3 Billion
- CAGR (2026-2033): 17.2%
Prism AI by Grand View Research Free to tryAsk a question about the advertising-based video on demand marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →The increasing utilization of AI-powered ad targeting, programmatic advertising, personalized content recommendations, and advanced audience analytics is enhancing advertiser engagement, maximizing monetization opportunities, improving viewer experiences, and creating new growth opportunities in the advertising-based video on demand market. AVOD services are gaining popularity, particularly as more subscription-based on-demand services proliferate and take up a substantial share of consumers' budgets. Advertising-based video on demand (AVOD) platforms leverage analytics of user activity as well as device specifications and capabilities to target advertisements to viewers. Because publishers may utilize user activity data to customize ad targeting, marketers are becoming more interested in AVOD services. AVOD platforms can use user activity analytics to provide tailored advertising that boosts conversion rates and ROI for advertisers.
 To learn more about this report, Download Free Sample Report
Customers who are willing to watch advertising in exchange for free material are the target audience for Advertising-based video on demand (AVOD) providers. The absence of advertisements in the model is understandably appealing to consumers who have become accustomed to fast service and are willing to pay for convenience. YouTube is a prime example of an AVOD media service where content producers can upload original content to YouTube's servers and monetize their work with adverts. One significant challenge AVOD services face is balancing the number of adverts and the user experience. Too many advertisements or advertisements that are not relevant to the user may turn them off. Some advertising-based video on demand systems allow consumers to comment on the advertisements they watch, click a button to skip an intrusive ad, or respond to a survey question in its place.
Advertising-based video on demand (AVOD) platforms analyze user engagement and behavior analytics, revenue, and conversion rates to determine the efficacy of tailored advertising. In addition to audience reach, preferences, demographics, user activity and engagement metrics, and income, AVOD service providers can collect data from everything on their platforms. Service providers can enhance user suggestions and ad targeting, promote engagement, and optimize revenue production by analyzing AVOD data with the appropriate software solutions. In order to gauge the success of tailored commercials, AVOD systems can also track ad impressions, clicks, and conversions. These analytics allow AVOD platforms to identify the most successful advertising and modify their targeting tactics accordingly.
Market Dynamics
The advertising-based video on demand market is witnessing substantial growth driven by the increasing adoption of connected TVs (CTV), high-speed internet connectivity, digital advertising technologies, and AI-powered content recommendation engines. The growing consumer preference for free, ad-supported streaming services, coupled with the rising demand for personalized advertising and data-driven audience targeting, is accelerating the expansion of AVOD platforms across diverse content categories. The increasing investments in original ad-supported content, programmatic advertising ecosystems, advanced audience measurement solutions, and strategic partnerships between streaming providers and advertisers are creating significant growth opportunities across the global market.
The increasing preference for free digital entertainment is a primary factor accelerating the adoption of advertising-based video on demand services. Consumers are increasingly seeking cost-effective alternatives to subscription-based streaming platforms, particularly amid rising subscription fatigue and inflationary pressures. AVOD platforms enable viewers to access diverse libraries of movies, television shows, live channels, and exclusive content without recurring fees, making them an attractive option across multiple demographic groups.
Advertisers are simultaneously shifting larger portions of their marketing budgets toward digital video channels that offer measurable audience engagement and targeted campaign delivery. AI-powered recommendation engines, programmatic advertising, audience segmentation, and real-time analytics improve advertising efficiency while maintaining viewer engagement. This combination of free content accessibility and highly targeted advertising continues to strengthen platform monetization strategies while expanding viewer adoption across connected televisions, smartphones, and other streaming devices.
Excessive advertising frequency remains a significant challenge for platform operators seeking to balance revenue generation with user satisfaction. Frequent commercial interruptions, repetitive advertisements, and poorly optimized ad placements can negatively impact the viewing experience, prompting users to abandon content or migrate to subscription-based services that offer uninterrupted playback. Maintaining the right balance between monetization and viewer engagement remains a critical operational challenge.
The increasing consumer expectations for personalized and seamless streaming experiences require AVOD providers to continuously optimize advertisement delivery. Privacy regulations limiting user data collection further complicate targeted advertising strategies, reducing campaign effectiveness in certain regions. Platforms must therefore invest in advanced advertising technologies, contextual targeting, and improved user experience management to minimize viewer dissatisfaction while sustaining advertising revenue.
The rapid expansion of connected television ecosystems presents a significant opportunity for AVOD platform providers to reach highly engaged audiences through premium digital video experiences. Smart TV adoption, improved broadband infrastructure, and increasing availability of streaming devices are encouraging viewers to consume long-form content on larger screens, creating a highly valuable environment for advertisers seeking greater brand visibility and measurable campaign performance.
Programmatic television advertising, dynamic ad insertion, AI-driven audience targeting, and cross-device campaign measurement are transforming connected TV- into a preferred advertising channel for brands. As streaming platforms continue to invest in exclusive content, live sports, regional programming, and interactive advertising formats, connected television environments are expected to attract greater advertising investment while strengthening long-term monetization capabilities for AVOD service providers.
Market Concentration & Characteristics
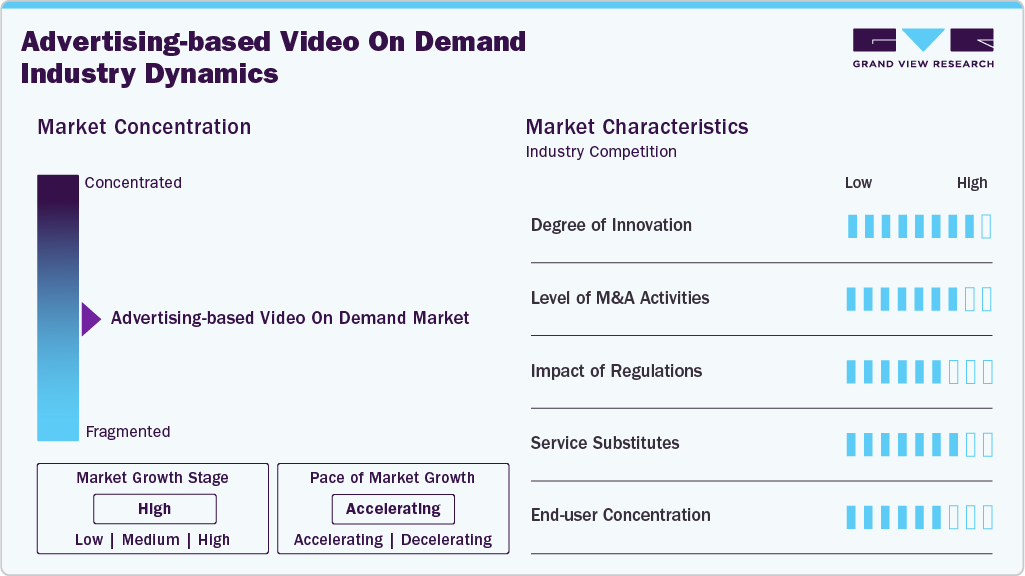
The advertising-based video on demand market is moderately concentrated, with several established streaming platforms, digital media companies, broadcasters, and advertising technology providers competing across entertainment, sports, news, children's programming, and regional content segments. Market expansion is driven by increasing consumer preference for free streaming services, rising digital advertising expenditure, and growing adoption of connected TV (CTV) platforms. Companies are focusing on exclusive content development, strategic partnerships, platform expansion, and advanced advertising capabilities to strengthen their competitive position. Vendors are increasingly investing in AI-powered content recommendation engines, programmatic advertising, dynamic ad insertion, audience analytics, and personalized advertising technologies to improve viewer engagement, advertising effectiveness, and monetization performance.
 To learn more about this report, Download Free Sample Report
The market is characterized by a high degree of innovation, supported by advancements in artificial intelligence, machine learning, programmatic advertising, real-time audience measurement, and cross-device targeting technologies. Merger and acquisition activity remains moderately high, with leading streaming platforms, media companies, and advertising technology firms acquiring content providers, analytics companies, and digital advertising solutions to expand their service portfolios and technological capabilities. The threat from substitutes remains high due to the availability of subscription video-on-demand (SVOD), transactional video-on-demand (TVOD), free ad-supported streaming television (FAST), social media video platforms, and traditional television services. Regulatory influence remains moderate, driven by evolving data privacy regulations, digital advertising standards, consumer protection requirements, and content licensing policies that continue to shape platform operations and advertising practices.
Analyst Perspective
The advertising-based video on demand market is experiencing significant expansion, driven by rising consumer preference for free streaming services, ongoing advancements in digital advertising technologies, and the growing adoption of connected TV (CTV) platforms. The rising deployment of advanced AVOD capabilities, including AI-powered content recommendations, programmatic advertising, dynamic ad insertion, and real-time audience analytics, is further enhancing monetization efficiency across entertainment, sports, news, education, and regional content platforms. As advertisers increasingly prioritize personalized campaigns, audience targeting, cross-device measurement, and data-driven marketing strategies, AVOD platform providers are well-positioned to capitalize on emerging opportunities, reinforcing long-term market expansion and sustained advertising revenue generation across the global digital streaming ecosystem.
COVID-19 Impact
The COVID-19 epidemic has significantly affected AVOD platforms and the advertising sector. Due to lockdowns and social dissociation brought on by the pandemic, many customers are now spending more time online, which has caused a change in digital channels. The pandemic also substantially increased the e-commerce and internet services industries. Businesses in these areas have raised advertising spending to attract potential clients as more individuals have shifted to online shopping and other digital services. Digital advertising has become more popular as a result, especially on social media sites and search engines.
Digital advertising was at a disadvantage in the early stages of the pandemic, but as marketing spending began to pick up again, it became obvious that money was pouring in digitally. Budgets from advertisers have been redirected to digital advertising, especially AVOD platforms. The pandemic has increased media usage, particularly video streaming on televisions with internet connections. As a result, ad-supported streaming video has become more widely used, giving Advertising-based video on demand (AVOD) services a chance to develop. By giving them clear data to work with and allowing them to be extremely selective with their ad budgets, AVOD platforms are creating new opportunities for advertisers. Advertisers can increase their return on investment (ROI) by using AVOD platforms, which can assist with proper reporting and performance attribution.
The pandemic has accelerated the move toward AVOD platforms, with a notable increase in ad revenue beginning in Q2 2020. AVOD platforms are enabling advertisers to reach consumers who spend more time at home and consume more media than before, although this pandemic has had a severe impact on the advertising sector.
Advertisement Position Insights
Based on advertisement position, the mid-roll segment led the market with the largest revenue share of 49.7% in 2025 and is expected to grow at a significant CAGR over the forecast period. Mid-roll advertising is placed in the middle of a video or audio clip, frequently interrupting the viewer's or listener's experience. Additionally, a mid-roll advertisement's position might vary based on the platform and content format. Moreover, mid-roll adverts on online video platforms such as YouTube are often put at regular intervals, such as every five minutes or at specified timestamps defined by the content provider. This maintains a balance between keeping viewer interest and allowing advertising to reach their intended group.
The pre-roll advertisement position segment is anticipated to grow with the fastest CAGR of 30.6% throughout the forecast period. Pre-roll advertising appears before the main video or audio content begins. Additionally, this advertising is widespread in online video platforms, streaming services, and podcasts. Pre-roll advertising appears at the start of the content and is usually played automatically before the viewer or listener can access the desired content. Furthermore, pre-roll commercials can run for various lengths, but they are often kept brief to minimize disturbance to the user experience. Pre-roll ad lengths can range from a few seconds to a minute, with 15 to 30 seconds being the most popular. The main aim of this sort of advertisement position is to create a favorable balance between generating ad revenue and maintaining a positive user experience.
Device Insights
Based on device, the mobile segment dominated the market with the largest revenue share of 46.6% in 2025. The mobile segment dominated the overall market, gaining a market share of 45.8% in 2024. The segment's growth is attributed to the increasing mobile device adoption due to its unparalleled convenience and accessibility. These devices are also portable and lightweight, allowing users to stay connected and access information on the go. The widespread availability of affordable smartphones has made them accessible to many people, including in developing countries such as India, China, and Japan. According to a report by GSMA, a global non-profit industry organization that advocates for the interests of mobile network operators worldwide, in 2023, there will be a global population of approximately 5.48 billion individuals who are currently using mobile phones.
The laptops and tablet PCs segment is anticipated to grow with the fastest CAGR of 30.6% throughout the forecast period. Laptops and tablets are popular video consumption devices owing to their bigger screens and a more immersive viewing experience than smartphones or mobile phones. Many people choose these devices for long-term viewing, such as watching films, TV series, or web videos. Moreover, laptop and tablet devices capitalize on technological advancements and enhanced connectivity. With improved screen resolutions, more robust processing capabilities, and faster internet speeds, users can enjoy a smooth and immersive experience on these devices. These technological enhancements contribute to a seamless and pleasurable viewing experience for AVOD content on laptops and tablets.
Enterprise Size Insights
Based on enterprise size, the large enterprise segment dominated the market with a revenue share of 63.6% in 2025. Large enterprises usually have significant resources to develop high-quality video material. They create professional videos such as advertisements, product demonstrations, brand promotions, and corporate documentaries for distribution on advertisement channels. Furthermore, large enterprises use sophisticated advertising strategies in the industry. Additionally, they employ AVOD platforms' user data and analytics to target certain demographics, interests, and watching behaviors. This allows companies to provide personalized adverts to their target demographic, increasing the efficacy of their marketing initiatives.
 To learn more about this report, Download Free Sample Report
The small and medium enterprises (SMEs) segment is expected to grow with the fastest CAGR of 30.1% throughout the projected period. AVOD platforms provide SMEs with a low-cost advertising channel to market their products and services. Additionally, SMEs may only reach a large audience by incurring the significant expenses associated with traditional advertising channels by leveraging the AVOD industry. They may boost brand recognition by creating tailored commercials that resonate with their unique target market. Furthermore, SMEs cater to specific regional or specialty markets. They may target local or niche audiences via AVOD platforms. SMEs may maximize the relevance and efficacy of their advertising campaigns by placing their commercials on AVOD channels that are relevant to their target audience.
Industry Vertical Insights
Based on industry vertical, the retail and consumer goods segment accounted for the largest market share of 28.8% in 2025. Retailers and consumer goods corporations use advertising-based video on demand platforms to market their brands and products through tailored adverts. Additionally, retail & segment often focus on advertisements that showcase their products, highlight promotional offers, or tell brand stories to capture viewers' attention and drive consumer engagement. Furthermore, AVOD platforms often offer opportunities for retailers to integrate e-commerce capabilities directly into their video content. This allows viewers to buy or learn more about the items featured in the videos without leaving the AVOD site, streamlining the purchasing process.
The media & entertainment segment is expected to grow with the fastest CAGR of 31.1% throughout the forecast period. Advertising-based video on demand platforms offer media and entertainment enterprises a large distribution network via which they may reach a large audience. They may use AVOD channels to disseminate their movies, TV shows, web series, documentaries, and other video material to audiences worldwide. Furthermore, AVOD systems allow media and entertainment firms to monetize their content by generating advertising income. They can display adverts to viewers during their content consumption by collaborating with advertisers or through programmatic advertising, collecting money depending on ad impressions or interactions.
Regional Insights
North America dominated the advertising-based video on demand Market with the largest revenue share of 40.4% in 2025. The regional growth can be attributed to several major AVOD platforms that have a strong presence in the North American region. Platforms like YouTube, Hulu, Tubi, Facebook, and Roku Channel have established themselves as leading players, offering viewers a wide range of free, ad-supported content. For instance, in February 2023, according to a report by Digital TV Research, the U.S. is expected to contribute USD 30 billion, with the remaining amount coming from Canada. Such trends are anticipated to propel regional growth over the forecast period.
 To learn more about this report, Download Free Sample Report
U.S. Advertising-based Video On Demand Market Trends
The advertising-based video on demand market in the U.S. held the largest share in the North America region in 2025. The AVOD market in the U.S. is one of the largest in the world, dominated by global players like Hulu, Peacock, and Paramount+. While subscription-based services have gained popularity, AVOD remains a significant part of the market, offering a free and accessible way to consume content. However, the market is facing increasing competition from ad-free streaming services and challenges in monetizing ad inventory.
The advertising-based video on demand market in Asia Pacific is expected to witness the fastest CAGR over the projected period. The AVOD market in Canada is similar to the U.S., with a strong presence of global players. However, the market is smaller in size and faces challenges due to language barriers and competition from local broadcasters. To attract and retain viewers, AVOD platforms in Canada are focusing on offering a diverse range of content, including French-language programming.
Asia Pacific Advertising-based Video On Demand Market Trends
The advertising-based video on demand market in Asia Pacific is expected to witness the fastest CAGR of 30.5% over the projected period. The AVOD industry in Asia Pacific is one of the largest and fastest-growing markets in the world. It has experienced significant growth in recent years, driven by increased internet penetration, rising demand for online video content, and the shift toward digital advertising. Additionally, the affordability of smartphones has significantly increased their accessibility, particularly in developing countries like India, China, and Japan. Notably, iQiyi, MXPlayer, JioCinema, Viu, and Line TV have established themselves as key players in the Asia Pacific region. Their diverse range of AVOD content offerings has played a significant role in driving the growth of the AVOD market in the region.
Japan advertising-based video on demand market is expected to grow at a significant CAGR from 2026 to 2033. The AVOD market in Japan is dominated by established broadcasters like NHK and private networks. While subscription-based services are gaining traction, AVOD remains popular due to its free accessibility. However, the market is facing challenges due to competition from global streaming giants and a declining population.
The advertising-based video on demand market in India is expected to grow at a significant CAGR from 2026 to 2033. The AVOD market in India is rapidly growing, driven by increasing internet penetration and a large population of young consumers. Local platforms like Hotstar and Zee5 have gained significant market share, offering a wide range of content, including movies, TV shows, and sports. The market is also witnessing increased competition from international players like Netflix and Amazon Prime Video.
South Korea advertising-based video on demand market is expected to grow at a significant CAGR from 2026 to 2033. The AVOD market in South Korea is relatively mature, with a strong presence of local and international players. However, the market is facing challenges due to rising production costs and competition from subscription-based services. To maintain their position, AVOD platforms are focusing on producing original content and exploring new revenue streams, such as advertising partnerships and merchandise sales.
Key Advertising-based Video On Demand Company Insights
The market is fragmented and is anticipated to witness competition due to several players' presence. The players in the market compete based on the type of advertisements and the quality and creativity of these advertising services. Furthermore, the AVOD model is growing quickly due to its dynamic ad delivery and higher personalization and customization of the ad-delivery experience. The surge in demand for advertising videos for product and service promotions is also driving the growth of AVOD services.
Some of the key companies operating in the market include IBM, Facebook, and YouTube, among others.
-
IBM's advantage in the AVOD market stems from its cutting-edge technology infrastructure and proficiency in AI, cloud computing, and data analytics. Through IBM Watson’s AI capabilities, the company offers sophisticated ad-targeting solutions, including predictive audience insights and dynamic ad personalization, which enhance viewer engagement. IBM’s cloud services enable scalable video delivery and seamless content management for AVOD providers, ensuring high-quality streaming experiences across devices. Furthermore, IBM’s focus on secure data handling and compliance with privacy regulations makes it an attractive partner for media companies seeking robust and reliable advertising solutions. By integrating cutting-edge technologies with video platforms, IBM allows businesses to optimize their ad strategies in real time, helping them compete in a data-driven AVOD landscape where precise targeting and user experience are paramount.
-
Facebook’s competitive edge in the AVOD market is rooted in its vast user base, detailed audience data, and integrated advertising ecosystem. With billions of active users across Facebook Watch, Instagram, and Messenger, the company offers unparalleled reach for advertisers targeting specific demographics. Meta’s advanced data analytics and machine learning models provide precise audience segmentation, helping advertisers serve personalized ads that resonate with users. The platform supports a variety of ad formats, such as in-stream video ads, carousel ads, and interactive formats, enhancing engagement. Additionally, Facebook’s seamless integration across its social platforms boosts content discovery and ad delivery, driving higher viewability and conversions. Its emphasis on short-form video and user-generated content aligns with current viewing trends, ensuring Facebook remains competitive as AVOD continues to evolve.
-
YouTube’s advantage in the AVOD market comes from its unmatched scale, vast content variety, and advanced advertising ecosystem. As the largest video platform globally, it hosts an immense variety of content, from professional productions to user-generated videos, attracting billions of users monthly. Its advanced advertising system, powered by Google Ads, offers precise targeting, real-time analytics, and ad formats like skippable, non-skippable, and bumper ads, giving advertisers diverse engagement options. YouTube’s integration with Google’s ecosystem ensures seamless cross-platform campaigns, enhancing reach and effectiveness. Additionally, YouTube’s recommendation algorithm increases user engagement, leading to higher ad impressions. With strong content creator support through monetization programs, it maintains a steady stream of fresh content, further reinforcing its dominance in the AVOD space.
Brightcove and Dailymotion are some of the emerging companies in the target market.
-
Brightcove's strength as an emerging player in the AVOD market is its emphasis on enterprise-level solutions, setting it apart from mainstream platforms. By empowering media companies, broadcasters, and publishers with customizable streaming tools, Brightcove taps into a niche segment seeking more control over monetization and user experiences. Its emphasis on dynamic ad insertion (DAI) and data-driven ad targeting offers businesses a tailored approach to audience engagement, which is increasingly valued in a crowded digital landscape. Furthermore, Brightcove’s commitment to secure video delivery, reliable global content delivery networks (CDN), and API-driven integrations positions it to grow alongside the increasing demand for professional-grade AVOD platforms. This business-to-business focus helps Brightcove carve a unique path as more enterprises pivot toward video-based advertising models.
-
Dailymotion’s strength as an emerging player in the AVOD market lies in its focus on premium, curated content and its emphasis on international markets. While larger platforms like YouTube dominate with user-generated content, Dailymotion focuses on fostering partnerships with professional media houses and broadcasters, creating an attractive environment for advertisers seeking brand-safe content. Its strength in localized content and regional ad-targeting helps it tap into non-English-speaking and underserved markets, where larger competitors may have less traction. Additionally, Dailymotion’s cleaner, less cluttered platform appeals to audiences and advertisers looking for more focused engagement. As more consumers seek alternatives to large platforms, Dailymotion is well-positioned to capture a loyal user base and secure a foothold in the evolving AVOD space.
Key Advertising-based Video On Demand Companies:
The following key companies have been profiled for this study on the advertising-based video on demand market.
-
YouTube
-
Facebook
-
IBM
-
Vimeo
-
Brightcove
-
Vidyard
-
Kaltura
-
Dailymotion
-
Vdocipher
-
SymphonyAI Media
-
Muvi
-
Dacast
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (IBM, Facebook, YouTube)
- Focus on expanding premium ad-supported streaming ecosystems through exclusive content, AI-driven personalization, and strategic partnerships.
- Invest heavily in advertising technologies, connected TV capabilities, programmatic platforms, and global content distribution networks.
- Strong global audience reach, extensive relationships with advertisers, and advanced audience-targeting capabilities strengthen market leadership.
- Diverse content portfolios, robust monetization models, and scalable streaming infrastructure support sustained competitive advantage.
- Reliance on advertising revenue exposes profitability to fluctuations in digital advertising spending and economic conditions.
- Large platform ecosystems may reduce agility when responding to emerging competitors and evolving viewer preferences.
Emerging Players (Brightcove and Muvi, VdoCipher)
- Emerging players focus on delivering flexible AVOD platforms through cloud-native architecture, customizable streaming, and monetization solutions.
- Invest in AI-driven video management, scalable OTT infrastructure, and regional content distribution capabilities.
- Agile business models enable rapid feature deployment, customized streaming services, and faster customer onboarding.
- Cost-effective platform offerings attract independent creators, enterprises, educational institutions, and regional media providers.
- Limited global brand recognition restricts advertiser acquisition, audience reach, and premium content partnerships.
- Limited financial resources constrain large-scale content investments and the development of advanced advertising technology.
Recent Developments
-
In October 2024, Amazon announced that Prime Video will incorporate advertisements in its content starting in 2025 for Indian viewers. This decision is due to increased competition in the streaming market and the need for more content investment. This move marks a shift away from the ad-free model that Prime Video has previously offered.
-
In May 2023, wedotv launched its core AVoD (Advertising Video on Demand) service on the LG app store. Additionally, wedotv's FAST (Free Ad-Supported TV) channels, namely wedo big stories & movies, are expanding their reach across Europe on the LG Channels smart TV platform.
-
In March 2023, Brightcove introduced Brightcove Ad Monetization, a dedicated service designed to help media companies monetize their content by leveraging advertising opportunities. The solution offers support for monetizing both live and video-on-demand content, incorporating yield optimization to fill any unsold ad inventory. It provides client-side and server-side advertising insertion capabilities across various platforms, including web players, android, iOS, and connected TV platforms.
-
In December 2021, Kaltura, the video experience cloud provider, revealed its collaboration with Astro, Malaysia's leading entertainment and content firm. Astro has selected the Kaltura TV Platform to power its new streaming service, sooka, specifically targeting millennials. By harnessing the advantages offered by Kaltura Cloud TV, sooka was successfully launched nationwide in June, with hosting support provided by Amazon Web Services (AWS).
Advertising-based Video On Demand Market Report Scope
Report Attribute
Details
Market size in 2025
USD 62.5 billion
Estimated market size in 2026
USD 78.7 billion
Projected market size by 2033
USD 239.3 billion
Growth rate
CAGR of 17.2% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Advertisement position, device, enterprise size, industry vertical, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; U.K.; Germany; France; China; Japan; India; South Korea; Australia; Brazil; Saudi Arabia; UAE; South Africa
Key companies profiled
YouTube; Facebook; IBM; Vimeo; Brightcove; Vidyard; Kaltura; Dailymotion; Vdocipher; SymphonyAI Media; Muvi; Dacast
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Advertising-based Video on Demand Market Report Segmentation
This report forecasts revenue growths at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global advertising-based video on demand market report based on advertisement position, device, enterprise size, industry vertical, and region.
-
Advertisement Position Outlook (Revenue, USD Million, 2021 - 2033)
-
Pre-roll
-
Mid-roll
-
Post-roll
-
-
Device Outlook (Revenue, USD Million, 2021 - 2033)
-
Laptops and Tablet PCs
-
Mobile
-
Console
-
TV
-
-
Enterprise Size Outlook (Revenue, USD Million, 2021 - 2033)
-
Small and Medium Enterprise (SME)
-
Large Enterprise
-
-
Industry Vertical Outlook (Revenue, USD Million, 2021 - 2033)
-
Media & Entertainment
-
BFSI
-
Education
-
Retail & Consumer Goods
-
IT & Telecom
-
Healthcare
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
U.K.
-
Germany
-
France
-
-
Asia-Pacific
-
China
-
Japan
-
India
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
-
Middle East & Africa
-
UAE
-
KSA
-
South Africa
-
-
Research Methodology
The advertising-based video on demand market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each advertising-based video on demand segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Advertisement Position
Revenue capture definition
Pre-roll
Revenue is generated from advertisements displayed before video content begins on AVOD platforms. This segment is driven by high viewer visibility, strong ad completion rates, premium-brand campaigns, and increasing adoption of AI-powered audience targeting and programmatic advertising technologies.
Mid-roll
Revenue is generated from advertisements inserted during video playback, typically within long-form content such as movies, television shows, and live streaming events. This segment is driven by higher viewer engagement, improved ad recall, dynamic ad-insertion technologies, and increasing advertiser demand for premium video inventory.
Post-roll
Revenue is generated from advertisements that appear after video content ends. This segment is supported by campaigns focused on brand awareness, call-to-action promotions, and viewer retention strategies, although lower audience completion rates than pre-roll and mid-roll advertisements limit its overall revenue contribution.
Segment - Device
Revenue capture definition
Laptops and Tablet PCs
Revenue is generated from advertisements delivered through AVOD platforms accessed on laptops and tablet PCs. This segment is driven by increasing consumption of long-form video content, browser-based streaming, educational viewing, and high-quality digital advertising experiences across portable computing devices.
Mobile
Revenue is generated from advertisements served through smartphones and mobile applications. This segment is driven by widespread smartphone adoption, affordable mobile internet, increasing video consumption on social and streaming platforms, location-based advertising, and personalized mobile advertising campaigns.
Console
Revenue is generated from advertisements displayed on AVOD applications accessed through gaming consoles. This segment is supported by growing entertainment consumption among gaming audiences, increasing integration of streaming applications into gaming ecosystems, and premium video advertising opportunities targeting highly engaged users.
TV
Revenue is captured from advertisements delivered through smart TVs, connected TVs (CTV), streaming devices, and Free Ad-Supported Streaming TV (FAST) platforms. This segment is driven by rising connected TV adoption, increasing household streaming hours, premium advertising inventory, and growing migration of television advertising budgets toward digital platforms.
Segment - Enterprise Size
Revenue capture definition
Small and Medium Enterprise (SME)
Revenue is generated from advertising campaigns launched by small and medium enterprises through AVOD platforms. This segment is driven by affordable digital advertising solutions, self-service campaign management tools, precise audience targeting, flexible budgeting options, and measurable advertising performance.
Large Enterprise
Revenue is generated from advertising investments made by large enterprises across AVOD platforms. This segment is driven by large-scale brand awareness campaigns, omnichannel marketing strategies, advanced audience analytics, premium content sponsorships, and programmatic advertising technologies supporting broad consumer reach.
Segment - Industry Vertical
Revenue capture definition
Media & Entertainment
Revenue is captured from advertising campaigns promoted by media companies, streaming providers, film studios, broadcasters, and entertainment brands. This segment is driven by content promotion, audience acquisition initiatives, new release marketing, and increasing investments in digital video advertising.
BFSI
Revenue is generated from advertising campaigns by banks, financial institutions, insurance companies, and fintech organizations using AVOD platforms. This segment is driven by digital customer acquisition, financial product promotion, personalized advertising strategies, and increasing investment in online marketing channels.
Education
Revenue is captured from advertisements placed by educational institutions, e-learning platforms, certification providers, and online tutoring services. This segment is driven by rising demand for online education, student recruitment campaigns, professional training promotion, and digital learning adoption.
Retail & Consumer Goods
Revenue is generated from advertising campaigns by retailers, e-commerce companies, consumer brands, and direct-to-consumer businesses. This segment is driven by increasing digital shopping, personalized product recommendations, seasonal promotional campaigns, and performance-based video advertising strategies.
IT & Telecom
Revenue is generated from advertising campaigns by software providers, cloud service companies, telecommunications operators, and technology vendors. This segment is driven by digital service promotion, customer acquisition initiatives, product launches, and increasing investments in targeted online video advertising.
Healthcare
Revenue is captured from advertising campaigns by hospitals, pharmaceutical companies, healthcare providers, wellness brands, and telehealth platforms. This segment is driven by rising healthcare awareness, patient engagement initiatives, the promotion of preventive care, and the increasing adoption of compliant digital advertising strategies.
Others
Revenue is generated from advertising campaigns across government organizations, automotive companies, travel and hospitality providers, real estate firms, food and beverage brands, and other commercial sectors utilizing AVOD platforms. This segment is driven by expanding digital marketing investments, broad consumer reach, and increasing adoption of data-driven video advertising solutions.
Estimation Model
Layer Name
Key Question
Description
Viewer Demand Layer
Who are the potential users?
Identifies the total addressable viewer base consuming free ad-supported streaming content, including households, individual consumers, mobile users, connected TV viewers, sports audiences, entertainment enthusiasts, and regional language content viewers across various age groups and demographics.
Digital Streaming Enablement Layer
Who can deliver AVOD services?
Adoption is influenced by the availability of high-speed broadband, mobile internet connectivity, connected TV ecosystems, smart devices, cloud-based content delivery networks (CDNs), digital advertising platforms, AI-powered recommendation engines, programmatic advertising infrastructure, and advanced audience analytics capabilities.
Content Distribution Layer
Where are AVOD services actively utilized?
Applies adoption levels across streaming environments where ad-supported video content is delivered, including connected TVs (CTV), smart TVs, smartphones, tablets, laptops, desktop browsers, gaming consoles, OTT applications, and web-based streaming platforms serving entertainment, news, sports, educational, and regional content.
Revenue Generation Layer
How is revenue generated?
Revenue is generated through digital video advertising (pre-roll, mid-roll, post-roll), programmatic advertising, display advertising, sponsored content, branded partnerships, audience targeting services, advertising technology solutions, premium advertising inventory, content licensing, and recurring advertising revenue from viewer engagement across AVOD platforms.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
AVOD Platform Monetization Optimization & Advertising Performance Assessment
Conducted detailed evaluation of advertising-based video on demand platforms across entertainment, sports, news, education, and regional content providers, integrating programmatic advertising, AI-powered audience targeting, and audience analytics solutions to optimize advertising monetization and viewer engagement.
Improves advertising effectiveness, enhances viewer engagement, optimizes monetization strategies, increases campaign performance, and supports long-term platform profitability.
Connected TV Advertising Deployment & Cross-Platform Integration Strategy
Assessed deployment of connected TV advertising solutions across smart TVs, mobile devices, web platforms, and streaming applications, integrating dynamic ad insertion, cross-device measurement, content delivery networks, and real-time analytics to improve advertising reach and campaign effectiveness.
Enhances audience reach, improves campaign measurement, enables personalized advertising, supports digital transformation, and strengthens advertising performance.
AI-Powered Audience Analytics & Personalized Advertising Strategy
Evaluated implementation of artificial intelligence-powered recommendation engines, predictive audience analytics, programmatic advertising platforms, and real-time viewer behavior analysis frameworks to improve advertising efficiency, content personalization, and platform monetization capabilities.
Enables data-driven advertising, improves audience targeting, increases monetization efficiency, enhances viewer retention, and supports scalable streaming operations.
Frequently Asked Questions About This Report
The mobile segment led with a 46.6% revenue share in 2025 while laptops and tablet PCs segment is expected to be the fastest-growing market.
The large enterprise segment dominated with a 63.6% revenue share in 2025 while small and medium enterprises (SMEs) segment is second fastest growing market.
The global advertising-based video on demand market size was estimated at USD 62.5 billion in 2025 and is expected to reach USD 78.7 billion in 2026.
The global advertising-based video on demand market is expected to grow at a compound annual growth rate of 17.2% from 2026 to 2033 to reach USD 239.3 billion by 2033.
North America dominated the market with a share of 40.4% in 2025.
Key players of advertising-based video on demand market are YouTube, Facebook, IBM, Vimeo, Brightcove, Vidyard, Kaltura, Dailymotion, Vdocipher, SymphonyAI Media, Muvi, and Dacast.
The factors driving the advertising-based video on demand market include advertiser demand, user engagement, cost-effectiveness, data-driven advertising, and monetization opportunities.
The Asia Pacific is the fastest-growing region with a CAGR of 18.4% from 2026 to 2033.
The mid-roll segment dominated with a 49.7% revenue share in 2025.
About the Author(s)
Digital Media Research Team
Technology · Digital MediaThis report was authored by the digital media research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the digital media segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


