
- Home
- »
- Advanced Interior Materials
- »
-
Air Cooled Heat Exchanger Market Size Report, 2026-2033GVR Report cover

Air Cooled Heat Exchanger Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Forced Draft, Induced Draft), By Fin Type (L Fin, Extruded Fins), By Material (Stainless Steel), By Construction (Vertical), By End-use, By Region, And Segment Forecasts
Market Size, 2025
$4.7BMarket Estimate, 2026
$4.9BMarket Forecast, 2033
$7.9BCAGR, 2026–2033
7.0%Air Cooled Heat Exchanger Market Summary
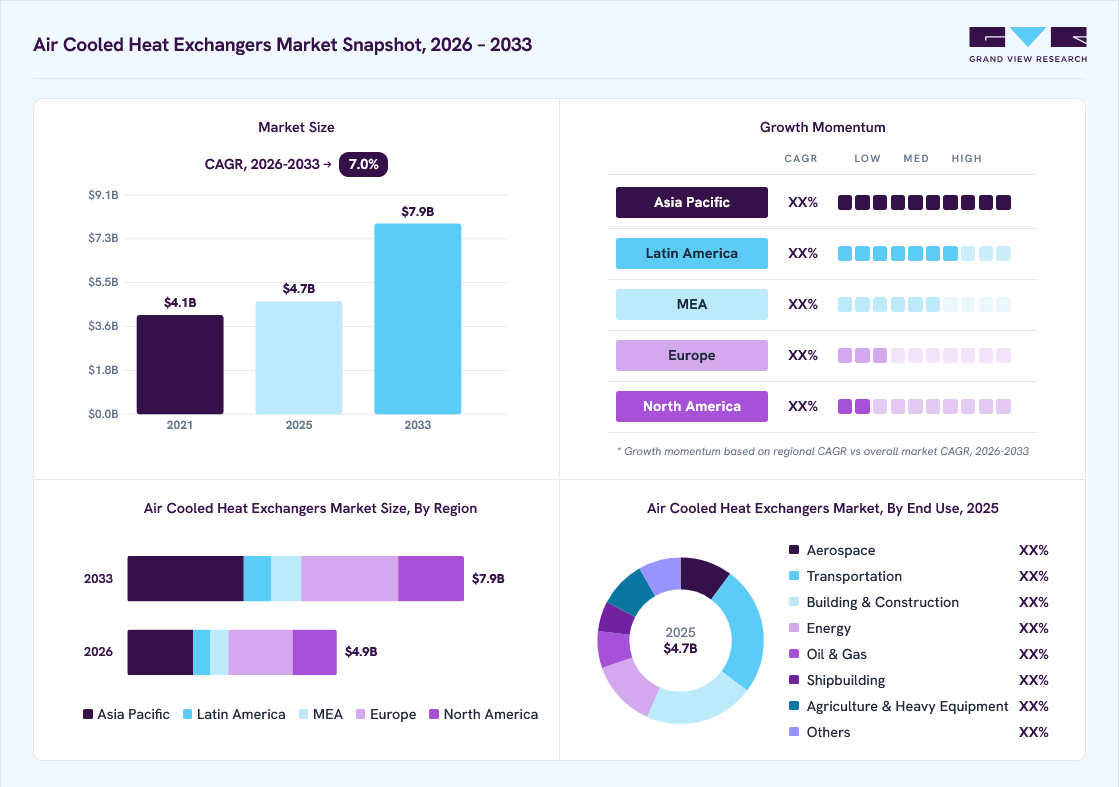
The global air cooled heat exchangers market size was valued at USD 4.7 billion in 2025 and is projected to grow from USD 4.9 billion in 2026 to USD 7.9 billion by 2033, at a CAGR of 7.0% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 31.2% in 2025. The growth of the global air-cooled heat exchanger (ACHE) market is driven by several key factors that address both the increasing demand for energy efficiency and the evolution of industrial processes.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Forced draft segment dominated the market, with a revenue share of 57.0% in 2025.
- By fin type: L-Fin segment held the largest market share of 46.5% in 2025.
- By material: Stainless steel segment held the largest revenue share of 37.4% in 2025.
- By construction: Vertical segment accounted for the largest revenue share of 55.7% in 2025.
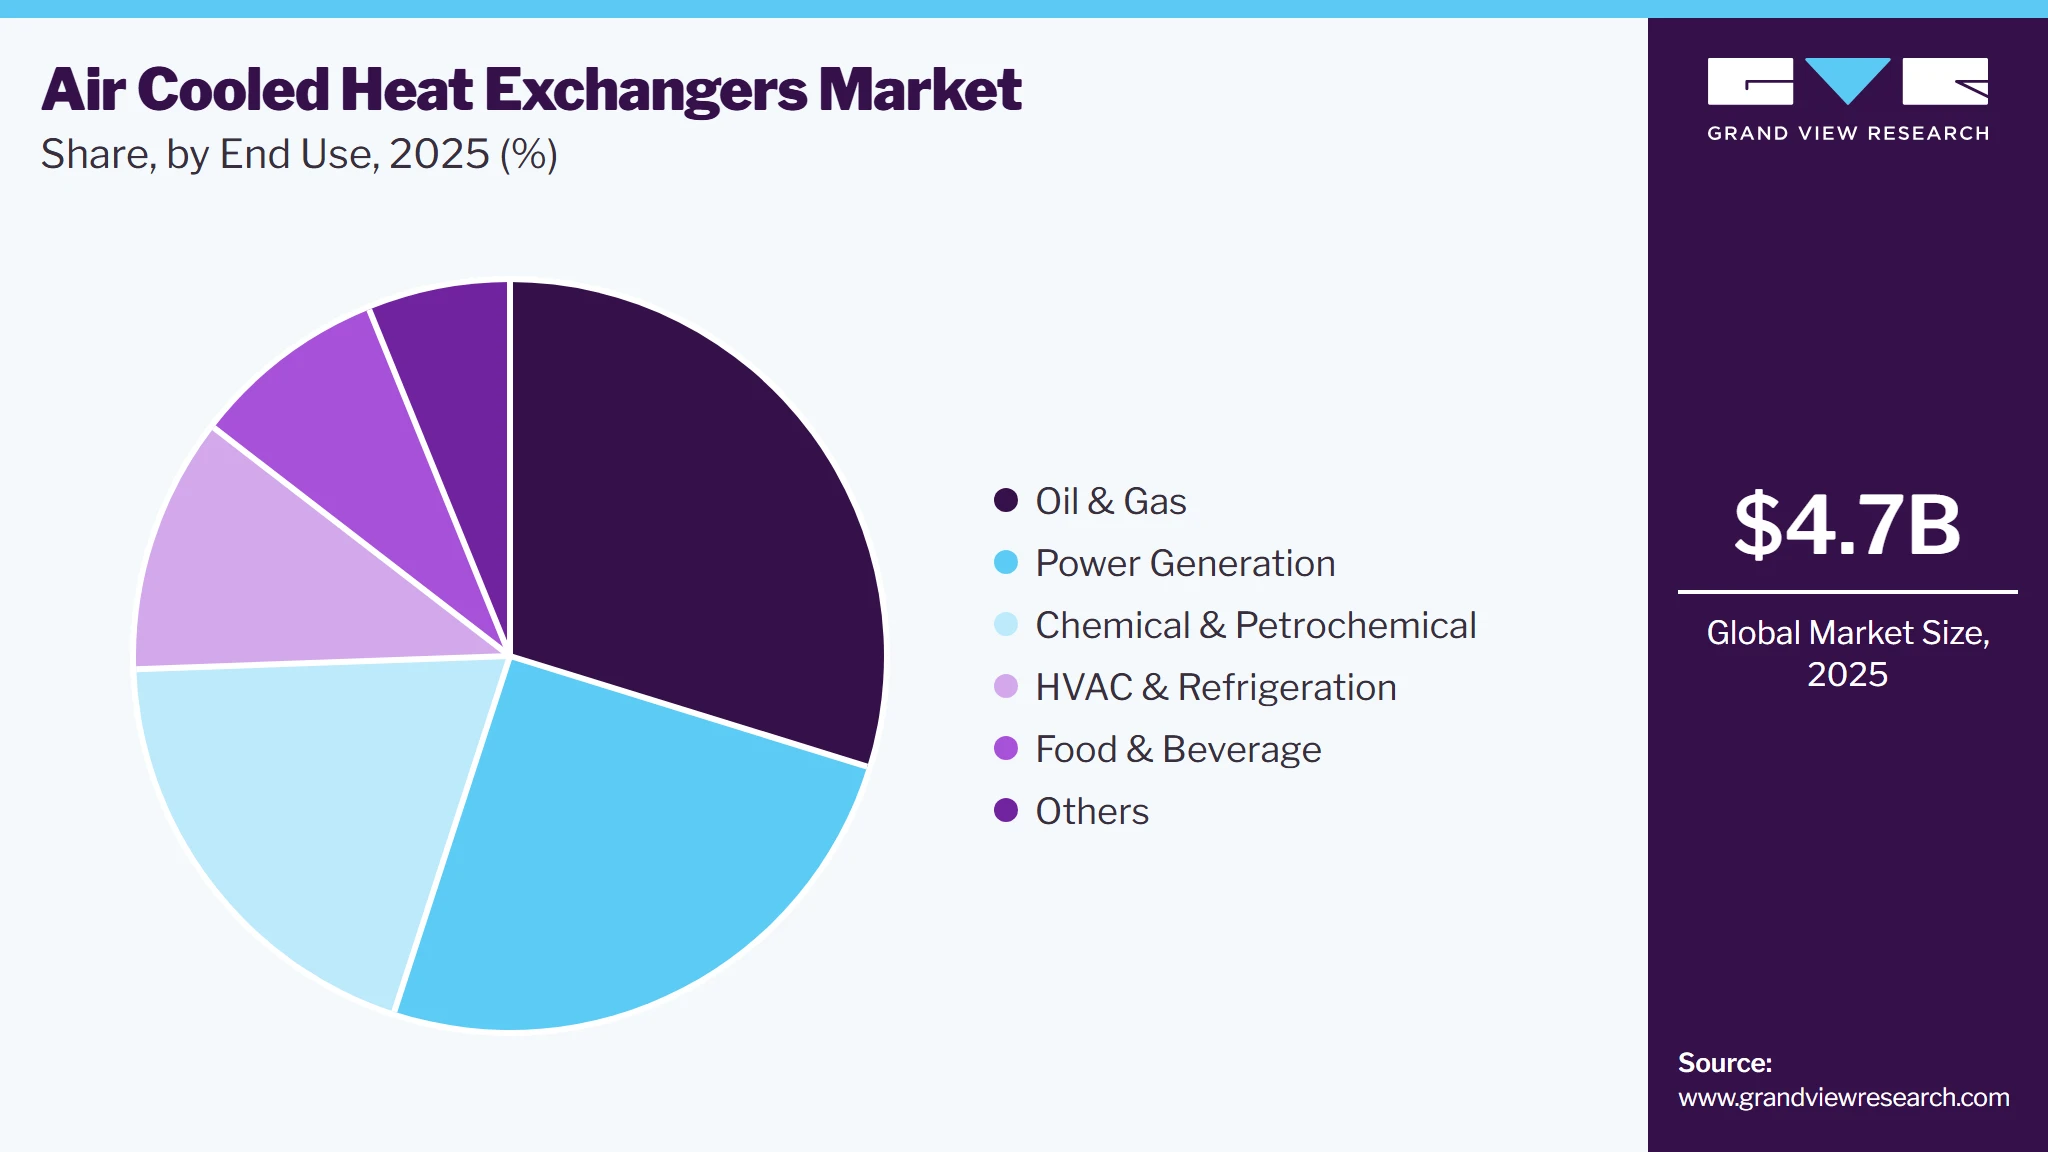
- By end use: Oil & gas segment dominated the market, with a revenue share of 29.8% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (31.2% revenue share, 2025)
- By country: China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 4.7 Billion
- Estimated market size in 2026: USD 4.9 Billion
- Projected market size by 2033: USD 7.9 Billion
- CAGR (2026-2033): 7.0%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
A significant factor is the growing emphasis on energy conservation and sustainability across various sectors. Air-cooled heat exchangers are typically preferred over water-cooled alternatives for their energy efficiency, especially in regions with water scarcity or where water usage regulations are stringent.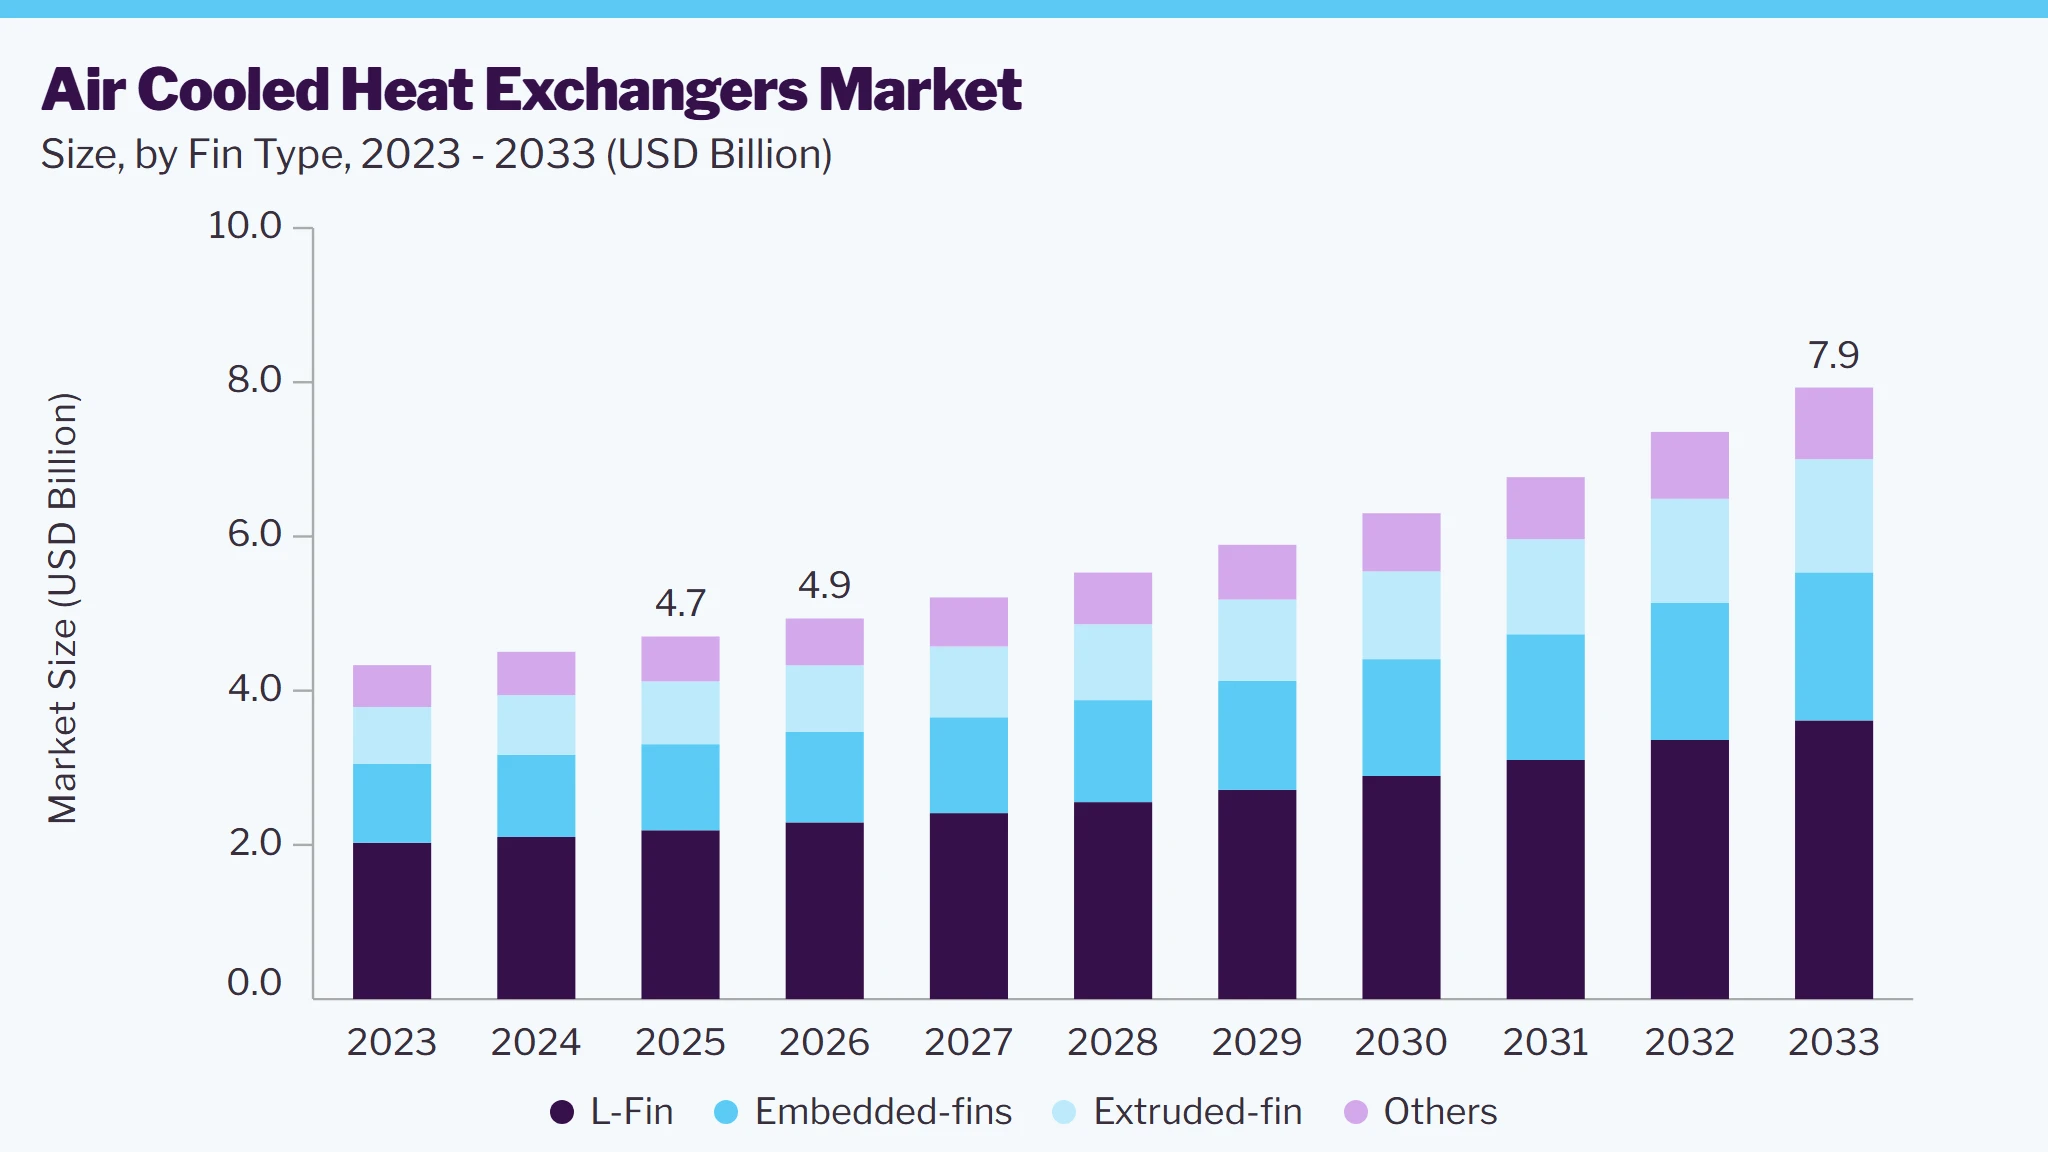 To learn more about this report, Download Free Sample Report
The reduced need for water makes ACHEs an environmentally friendly option, contributing to their increasing adoption.
Market Dynamics
The air cooled heat exchangers market is witnessing steady growth, supported by rising demand for water-efficient thermal management solutions across process industries. As industrial facilities face increasing pressure to reduce water consumption and comply with stricter environmental regulations, air cooled heat exchangers have become a preferred alternative to water-cooled systems. Their ability to operate without continuous water supply makes them particularly suitable for regions experiencing water scarcity and for industries seeking to improve sustainability. Technological advancements in fin designs, fan efficiency, corrosion-resistant materials, and digital monitoring systems are further enhancing equipment performance, reliability, and lifecycle value, encouraging wider adoption across oil & gas, power generation, chemical processing, HVAC, and other industrial applications.
Air cooled heat exchangers are gaining significant traction as industries increasingly prioritize water conservation and sustainable operations. Unlike conventional water-cooled systems, these units rely on ambient air to dissipate heat, eliminating the need for large volumes of cooling water. This advantage is becoming increasingly important in regions facing water shortages, stricter water-use regulations, and rising costs associated with water treatment and disposal. Industries are investing in dry cooling technologies to reduce operational risks linked to water availability while improving environmental performance.
The transition toward sustainable industrial infrastructure is also driving investments in advanced air cooled heat exchanger technologies. Modern systems incorporate optimized fin geometries, variable-speed fans, corrosion-resistant materials, and digital performance monitoring to maximize heat transfer efficiency while minimizing energy consumption. Expanding investments in oil & gas facilities, petrochemical complexes, LNG terminals, power plants, and large-scale industrial manufacturing projects are further strengthening demand for reliable air cooled heat exchangers capable of operating efficiently under diverse environmental conditions.
The performance of air cooled heat exchangers is directly influenced by ambient air temperature, making them less efficient in extremely hot climates where the temperature difference required for effective heat transfer is reduced. During periods of high environmental temperatures, cooling capacity may decline, potentially affecting process efficiency and requiring larger heat transfer surfaces or additional equipment. These performance challenges, combined with higher installation space requirements and elevated capital costs compared to certain water-cooled alternatives, can limit adoption in applications demanding consistent high-capacity cooling.
Rapid industrialization across emerging economies and increasing investment in manufacturing, refining, petrochemical, and energy infrastructure are creating substantial opportunities for the air cooled heat exchangers market. Many of these projects are being developed in regions where freshwater resources are limited, making dry cooling technologies an attractive long-term solution. Additionally, the growing adoption of renewable energy facilities, hydrogen production plants, carbon capture projects, and industrial decarbonization initiatives is generating new demand for efficient heat rejection systems. As manufacturers continue to develop compact, high-performance, and digitally connected air cooled heat exchangers, the market is expected to benefit from broader deployment across both new installations and retrofit projects.
Market Concentration & Characteristics
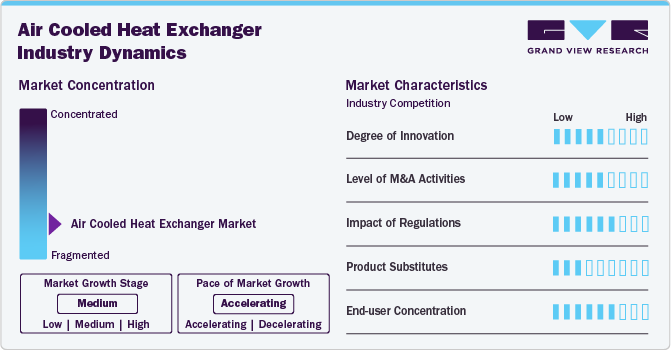
The global air-cooled heat exchanger market is characterized by a moderately fragmented competitive landscape, with a mix of established multinational companies and regional players vying for market share. The leading manufacturers focus on offering customized and highly efficient air-cooled heat exchangers to meet the diverse needs of industries such as oil and gas, power generation, chemicals, and HVAC. Innovations in this market are primarily centered on enhancing heat transfer efficiency, improving energy performance, and optimizing designs for a wider range of operating conditions. Manufacturers are also exploring advancements in materials, such as corrosion-resistant alloys, to improve the durability and performance of heat exchangers in harsh environments.
Regulatory bodies play a significant role in shaping the industry dynamics. Compliance with stringent regulations on energy efficiency, environmental impact, and safety standards is essential for manufacturers to remain competitive. As global awareness of sustainability and environmental concerns rises, regulatory frameworks continue to tighten, urging manufacturers to develop products that reduce water consumption and minimize carbon emissions. In addition, manufacturers are responding to the growing demand for energy-efficient technologies by focusing on design innovations that reduce the overall carbon footprint of air-cooled heat exchangers, further promoting their adoption in industries aiming to meet sustainability targets.
 To learn more about this report, Download Free Sample Report
A growing opportunity in the air cooled heat exchanger industry lies in the increasing demand for energy-efficient systems, particularly in water-scarce regions where water-cooled systems may be less viable. Manufacturers are also capitalizing on advancements in digital technologies, such as predictive maintenance and smart monitoring systems, which enhance the reliability and operational efficiency of air-cooled heat exchangers. As industries, including renewables and manufacturing, continue to expand, demand for reliable and environmentally sustainable cooling solutions is expected to grow, driving further industry expansion.
However, competition from alternative cooling systems, such as water-cooled heat exchangers and evaporative cooling solutions, presents challenges for companies in this industry. These alternatives often offer higher heat transfer efficiency, especially in regions with ample water resources. As a result, key manufacturers in the air-cooled heat exchanger market are expected to continuously innovate, improve their systems' efficiency, and align with evolving regulatory standards to stay competitive. The increasing focus on renewable energy integration, particularly in power generation, also creates collaboration opportunities for manufacturers to provide integrated cooling solutions that complement sustainable energy production. Ultimately, companies will need to maintain a balance between advancing technology and meeting the growing demand for energy-efficient, environmentally friendly solutions.
Analyst Perspective
The air cooled heat exchangers market is expected to witness steady growth over the forecast period, driven by rising demand for energy-efficient cooling solutions, stricter environmental regulations, and increasing industrial investments. Technological advancements, improved heat transfer efficiency, and growing adoption in water-scarce regions are further supporting market growth. Manufacturers that focus on innovation, customization, and reliable after-sales support will be well positioned to capitalize on the increasing demand for sustainable and efficient cooling solutions.
Type Insights
Based on type, forced draft segment led the market with the largest revenue share of 57.0% in 2025. Forced Draft (FD) air-cooled heat exchangers are valued for their ability to maintain consistent airflow by pushing air through the system. They are commonly used in compact spaces and applications requiring high airflow, such as HVAC and power generation. Their efficiency in managing higher ambient temperatures drives their adoption in energy-conscious and space-constrained environments.
Induced Draft (ID) air-cooled heat exchangers draw air through the system, making them more energy-efficient than FD systems in some cases. Their ability to handle large volumes of air with lower fan pressure makes them ideal for large-scale applications such as oil & gas and chemical processing, where high cooling capacity and energy efficiency are critical.
Fin Type Insights
Based on fin type, L-Fin segment led the market with the largest revenue share of 46.5% in 2025. L-Fin air-cooled heat exchangers are designed to provide enhanced surface area for better heat transfer, improving cooling efficiency. Their compact design and effectiveness at capturing heat in tight spaces make them ideal for applications in HVAC systems and smaller industrial units, driving demand in sectors looking for space-saving, efficient solutions.
Extruded-fin air-cooled heat exchangers offer superior heat transfer due to their robust and continuous fin structure. These are especially effective in environments with high heat loads and are widely used in industries like power generation, where high-performance cooling is critical. Their durability and efficiency in demanding conditions fuel their market growth.
Material Insights
Based on material, stainless steel segment led the market with the largest revenue share of 37.4% in 2025. Stainless steel air-cooled heat exchangers are favored for their corrosion resistance and durability in harsh environments. They are ideal for industries like oil & gas and chemical processing, where exposure to aggressive substances is common. Their longevity and ability to withstand extreme conditions drive demand, particularly in corrosive and high-pressure applications.
Nickel and nickel alloy air-cooled heat exchangers are highly valued for their exceptional resistance to corrosion, especially in aggressive and extreme environments. These materials are ideal for industries such as oil & gas, chemical processing, and marine applications, where exposure to harsh chemicals, high pressures, and elevated temperatures is common.
Construction Insights
Based on construction, vertical segment led the market with the largest revenue share of 55.7% in 2025. Vertical air-cooled heat exchangers are favored for applications where space is at a premium, as they optimize the vertical dimension for cooling. These systems are widely used in the oil & gas and chemical industries, where vertical installation maximizes space usage while ensuring effective heat exchange in tight or constrained spaces.
The horizontal construction segment in the air-cooled heat exchangers market is widely preferred across industries due to its efficient heat dissipation, ease of maintenance, and suitability for large-scale applications. These exchangers are typically installed in power plants, petrochemical facilities, and refineries, where they provide effective cooling solutions for high-temperature processes. Their horizontal orientation allows for a larger heat exchange surface, improving thermal efficiency while minimizing pressure drop.
End-use Insights
Based on end use, oil & gas segment led the market with the largest revenue share of 29.8% in 2025. The industry relies heavily on air-cooled heat exchangers for cooling processes in extreme conditions, especially in offshore platforms and refineries. The demand for high-efficiency and robust cooling solutions that can withstand harsh environments is driving significant growth in this segment, particularly with the rise in energy-efficient technologies.
 To learn more about this report, Download Free Sample Report
In the HVAC and refrigeration industry, air-cooled heat exchangers are essential for managing heat dissipation in air conditioning and refrigeration units. The increasing demand for energy-efficient and environmentally friendly systems is driving the growth of these exchangers in residential, commercial, and industrial HVAC applications.
Regional Insights
The air cooled heat exchanger market in North America is driven by increasing industrialization, energy efficiency regulations, and a growing demand for sustainable solutions in industries like oil & gas, power generation, and HVAC. Strong investments in renewable energy and infrastructure modernization further contribute to market expansion.
U.S. Air Cooled Heat Exchanger Market Trends
The U.S. air cooled heat exchanger market is projected to expand at a CAGR of 5.2% over the forecast period. The U.S. market is driven by growing demand for energy-efficient solutions across various industries, including oil & gas, power generation, and HVAC. Stringent environmental regulations and a shift toward sustainable technologies further fuel market growth. Investments in infrastructure modernization and renewable energy also contribute significantly.
Europe Air Cooled Heat Exchanger Market Trends
Europe air cooled heat exchanger market led the global market and accounted for 31.2% overall revenue share in 2024. The market growth in Europe is supported by stringent environmental regulations, a strong focus on sustainability, and investments in energy-efficient technologies. The region's transition to green energy, coupled with governmental support for decarbonization and energy efficiency, boosts demand for air-cooled heat exchangers in industries such as chemicals and power generation.
The air cooled heat exchanger market in Germany is expected to grow at a rapid CAGR of 5.8% over the forecast period Germany's market growth is driven by strong industrial sectors, including chemical processing and power generation, which require advanced heat exchange solutions. The country’s commitment to sustainability, energy efficiency, and decarbonization, along with stringent environmental regulations, boosts demand for air-cooled heat exchangers.
France air cooled heat exchanger market is expected to grow at a rapid CAGR of 5.5% over the forecast period, driven by investments in renewable energy and energy-efficient infrastructure. The oil & gas, chemical, and power generation sectors are expanding, driving the need for advanced heat exchange systems.
Asia Pacific Air Cooled Heat Exchanger Market Trends
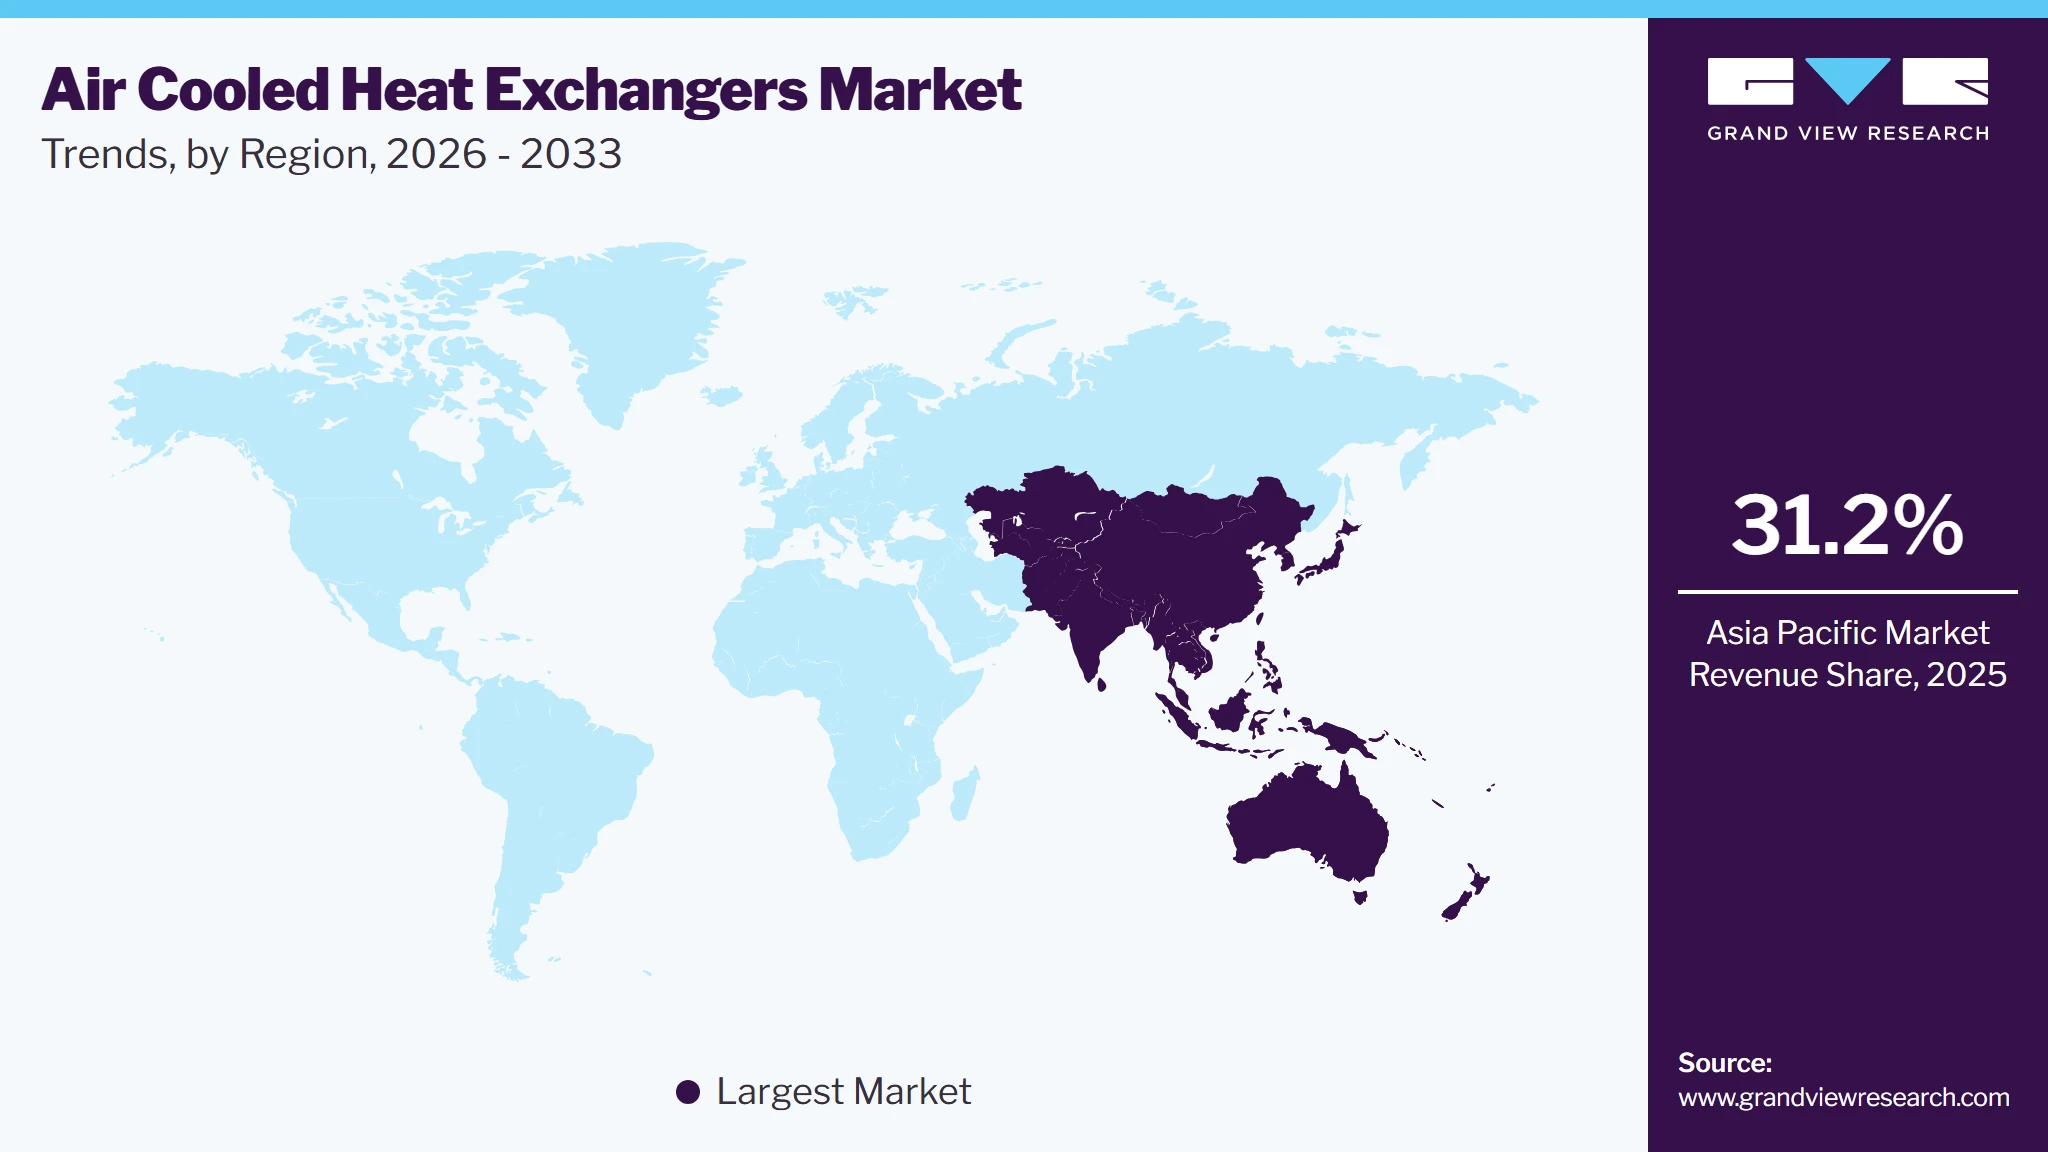
Asia Pacific dominated the air cooled heat exchangers market with the largest revenue share of 31.2% in 2025. The region’s growth is also influenced by expanding manufacturing and oil & gas sectors, along with increasing demand for energy-efficient solutions driven by environmental concerns.
 To learn more about this report, Download Free Sample Report
The air cooled heat exchangers market in the China held the largest share in the Asia Pacific region in 2025. China’s rapid industrialization, urbanization, and growing manufacturing sector are major drivers of the air-cooled heat exchanger market. The demand for energy-efficient technologies, particularly in the oil & gas, power generation, and HVAC industries, is increasing due to government policies aimed at reducing carbon emissions.
The air cooled heat exchanger market in India is projected to grow at a CAGR of 8.3% over the forecast period. India’s market growth is fueled by significant investments in infrastructure, industrial growth, and the expansion of the oil & gas and power generation sectors. Rising environmental awareness and government regulations focused on energy efficiency and sustainability are driving the demand for air-cooled heat exchangers.
Middle East & Africa Air Cooled Heat Exchanger Market Trends
The Middle East and Africa air cooled heat exchanger market are seeing growth due to the dominant presence of the oil & gas industry, which drives the need for efficient heat exchange systems. Additionally, increasing focus on energy efficiency and sustainable solutions in industries like power generation and petrochemicals is spurring market growth.
The air cooled heat exchanger market in Saudi Arabia is projected to grow at a CAGR of 6.7% over the forecast period. Saudi Arabia’s market growth is driven by the oil & gas industry, which remains a significant demand driver for air-cooled heat exchangers. With increasing investments in petrochemical and power generation sectors, along with a focus on improving energy efficiency and adopting sustainable technologies, the market is poised for growth.
Latin America Air Cooled Heat Exchanger Market Trends
Latin America's air cooled heat exchanger market growth is fueled by the ongoing expansion of oil & gas, power generation, and chemical industries, coupled with increasing investments in infrastructure. The region’s adoption of sustainable technologies to meet environmental standards is also contributing to the demand for air-cooled heat exchangers.
The air cooled heat exchanger market in Brazil is projected to grow at a CAGR of 6.9% over the forecast period. In Brazil, the oil & gas and power generation industries are major contributors to market growth. The country’s push for sustainable energy solutions, combined with industrial expansion and government investments in infrastructure, are key factors driving demand for efficient heat exchange systems
Key Air Cooled Heat Exchanger Company Insights
Some key players operating in the market include Xylem, Inc. and Alfa Laval among others.
-
Xylem, Inc is a global water technology company engaged in the manufacturing, designing, and servicing of products that primarily cater to the water sector as well as the electric and gas sectors. The company has a presence in North America, Latin America, Europe, the Middle East & Africa, and Asia Pacific with North America and Europe being its major geographical markets
-
Alfa Laval is a global company involved in industrial technology focused on heat transfer, separation, and fluid handling. The company now serves diverse industries including energy, marine, food processing, water treatment, and pharmaceuticals, with operations spanning over 100 countries. The company operates through three primary divisions: Energy, Food & Water, and Marine. These divisions provide specialized equipment such as heat exchangers, separators, pumps, and valves, which are critical for large-scale industrial processes.
Key Air Cooled Heat Exchanger Companies:
The following key companies have been profiled for this study on the air cooled heat exchanger market.
-
ALFA LAVAL
-
Kawasaki Heavy Industries, Ltd.
-
Xylem
-
Exchanger Industries Limited
-
SPX Cooling Tech, LLC
-
Baker Hughes Company
-
Chart Industries
-
Armstrong International Inc.
-
Hayden Industrial
-
SNT Energy Co., Ltd.
-
Boldrocchi
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (e.g., ALFA LAVAL; Xylem; Baker Hughes Company; SPX COOLING Tech, LLC; Kawasaki Heavy Industries Ltd.)
- Focus on expanding global presence through acquisitions, strategic partnerships, and strengthening industrial service networks.
- Development of advanced air cooled heat exchangers for oil & gas, LNG, petrochemical, power generation, and industrial process applications.
- Emphasis on digital monitoring, automation integration, and lifecycle service offerings.
- Strong global brand recognition and extensive installed customer base.
- Broad product portfolio with advanced engineering and thermal management capabilities.
- Strong R&D investments supporting innovation and energy-efficient solutions.
- Higher equipment and installation costs compared to regional manufacturers.
- Exposure to fluctuations in industrial capex and energy sector investments.
- Complex global supply chain and operational structure.
Emerging & Regional Players (e.g., Exchanger Industries Limited; Armstrong International Inc.; Hayden Industrial; SNT Energy Co., Ltd.; Boldrocchi)
- Focus on customized and application-specific air cooled heat exchanger solutions.
- Expansion through regional partnerships and project-based industrial contracts.
- Competitive pricing strategies targeting regional industrial customers.
- Strong expertise in niche industrial applications and customized thermal solutions.
- Faster response time and flexible customer support for regional projects.
- Limited global brand visibility and distribution reach.
- Narrower product portfolio compared to multinational competitors.
- Lower investment capacity in advanced automation and digital technologies.
Recent Developments
-
In February 2023, ALFA LAVAL announced it is enhancing its heat exchanger production capacity in Sweden, Italy, China, and the U.S. as part of a broader investment initiative. The company has committed USD 358.3 million to this capacity expansion program, which will focus on boosting production, distribution, and service capabilities at four of its existing facilities in these countries. This decision to invest in increased capacity is driven by rising demand to support customers during the ongoing global energy transition.
-
In October 2023, SPX Cooling Tech, LLC, a manufacturer of evaporative cooling systems, announced its plans for a new 100,000-square-foot manufacturing facility in Springfield, Missouri. Operational within six months, the facility will employ approximately 60 workers and expand production capacity for Marley brand cooling towers and fluid coolers, which serve industries like data centers, semiconductor fabrication, and electric vehicle infrastructure.
Air Cooled Heat Exchanger Market Report Scope
Report Attribute
Details
Market size in 2025
USD 4.7 billion
Estimated market size in 2026
USD 4.9 billion
Projected market size by 2033
USD 7.9 billion
Growth rate
CAGR of 7.0% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, fin type, material, construction, end-use, region.
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Spain; Italy; China; India; Japan; Australia; South Korea; Brazil; Argentina; Saudi Arabia; South Africa; UAE
Key companies profiled
Alfa Laval; Kawasaki Heavy Industries, Ltd.; Xylem; Exchanger Industries Limited; SPX Cooling Tech, LLC; Baker Hughes Company; Kelvion Holding GmbH; Armstrong International Inc.; Hayden Industrial; SNT Energy Co., Ltd.; Boldrocchi; Thermofin; Marmon Industrial Water; Rex Heat Exchanger India Pvt. Ltd.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Air Cooled Heat Exchangers Market Report Segmentation
This report forecasts revenue growth at global, regional & country levels and provides an analysis of the industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global air cooled heat exchanger market report based on type, fin type, materials, construction, end-use, and region:
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Forced Draft
-
Induced Draft
-
-
Fin Type Outlook (Revenue, USD Million, 2021 - 2033)
-
L-Fin
-
Embedded-fins
-
Extruded-fin
-
Others
-
-
Materials Outlook (Revenue, USD Million, 2021 - 2033)
-
Carbon steel
-
Stainless steel
-
Duplex stainless steel
-
Nickel & Nickel Alloys
-
Titanium
-
Others
-
-
Construction Outlook (Revenue, USD Million, 2021 - 2033)
-
Vertical
-
Horizontal
-
Inclined
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Oil & Gas
-
Power Generation
-
Chemical & Petrochemical
-
HVAC & Refrigeration
-
Food & Beverage
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Spain
-
Italy
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Arabia
-
South Africa
-
UAE
-
-
Research Methodology
The air cooled heat exchanger market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each v segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Fin Type
Revenue Capture Definition
L-Fin
Revenue generated from the sale of air cooled heat exchangers incorporating L-shaped wrapped fin tubes designed for cost-effective heat transfer in moderate operating environments.
Embedded-fins
Revenue generated from the sale of air cooled heat exchangers utilizing embedded fin tubes that provide improved mechanical strength and thermal efficiency for demanding industrial applications.
Extruded-fin
Revenuegenerated from the sale of air cooled heat exchangers featuring extruded fin tubes that offer superior corrosion resistance and long service life in harsh operating conditions.
Others
Revenue generated from the sale of air cooled heat exchangers using alternative fin configurations, including Wire Finned Tube, ‘KL’ Finned Tube, Helical Fins, and Elfin.
Material
Revenue Capture Definition
Carbon steel
Revenue generated from the sale of air cooled heat exchangers manufactured using carbon steel for general industrial and moderate corrosion environments.
Stainless steel
Revenue generated from the sale of air cooled heat exchangers fabricated from stainless steel to provide enhanced corrosion resistance and durability.
Duplex stainless steel
Revenue generated from the sale of air cooled heat exchangers constructed using duplex stainless steel for high-strength and corrosion-resistant applications.
Nickel & Nickel Alloys
Revenue generated from the sale of air cooled heat exchangers manufactured with nickel-based alloys for high-temperature and highly corrosive process environments.
Titanium
Revenue generated from the sale of air cooled heat exchangers fabricated using titanium for applications requiring exceptional corrosion resistance and long operational life.
Others
Revenue generated from the sale of air cooled heat exchangers manufactured using specialty materials such as copper alloys, aluminum alloys, and other engineered metals.
Type
Revenue Capture Definition
Forced Draft
Revenue generated from the sale of air cooled heat exchangers equipped with fans positioned to force ambient air through finned tube bundles for industrial cooling applications.
Induced Draft
Revenue generated from the sale of air cooled heat exchangers that use fans located above the heat exchange surface to draw air through the tube bundles, enhancing thermal performance.
Construction
Revenue Capture Definition
Vertical
Revenue generated from the sale of vertically configured air cooled heat exchangers designed for installations with limited ground space or specific process requirements.
Horizontal
Revenue generated from the sale of horizontally configured air cooled heat exchangers widely used across industrial facilities for efficient heat dissipation and ease of maintenance.
Inclined
Revenue generated from the sale of inclined air cooled heat exchangers designed to optimize airflow distribution and improve operational efficiency under specific installation conditions.
End Use
Revenue Capture Definition
Oil & Gas
Revenue generated from the sale of air cooled heat exchangers for upstream, midstream, downstream, LNG, and refinery applications.
Power Generation
Revenue generated from the sale of air cooled heat exchangers used for steam condensation, turbine cooling, and auxiliary thermal management in power plants.
Chemical & Petrochemical
Revenue generated from the sale of air cooled heat exchangers for process cooling, condensation, and heat recovery across chemical and petrochemical facilities.
HVAC & Refrigeration
Revenue generated from the sale of air cooled heat exchangers for commercial and industrial HVAC systems, refrigeration equipment, and district cooling applications.
Food & Beverage
Revenue generated from the sale of air cooled heat exchangers used in food processing, beverage production, cold storage, and hygienic thermal management systems.
Others
Revenue generated from the sale of air cooled heat exchangers for applications across mining, pharmaceuticals, pulp & paper, marine, metallurgy, and other industrial sectors.
Estimation Model
Layer Name
Key Question
Description
End-use Industry Assessment
Which industries generate demand for air cooled heat exchangers?
Estimate the installed base and annual demand across key end-use industries such as oil & gas, power generation, chemical & petrochemical, HVAC & refrigeration, food & beverage, and other industrial sectors where process cooling is required.
Product & Configuration Assessment
Which product configurations are being adopted?
Analyze demand based on type (forced draft, induced draft), fin type, construction (vertical, horizontal, inclined), and material selection according to operating conditions, corrosion resistance, and thermal efficiency requirements.
Manufacturer Supply Assessment
Who supplies the market and what is the shipment volume?
Assess production capacity, annual shipments, regional manufacturing footprint, project deliveries, and sales of leading air cooled heat exchanger manufacturers across global markets.
Revenue Estimation
What is the total market revenue generated?
Estimate market revenue by consolidating sales of air cooled heat exchangers across all product types, materials, configurations, and end-use industries at regional and global levels after validating demand and supply-side data.
Delivered Customizations
This report has been delivered with the following In-depth customizations
CLIENT REQUEST
CUSTOMIZATION DELIVERED
VALUE ADDS
Regional Segmentation
Detailed assessment of the air-cooled heat exchanger market across North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa, including country-level analysis for the U.S., China, India, Saudi Arabia, UAE, Germany, and other major industrial economies. Evaluation includes refinery capacity additions, LNG infrastructure development, petrochemical investments, power generation projects, and industrial cooling demand trends.
Identify high-growth regional markets and industrial investment hotspots. Support regional expansion, localization, and distributor alignment strategies. Enable prioritization of markets based on industrial infrastructure growth and process cooling demand.
Competitive Benchmarking
Detailed benchmarking of key market participants based on product offerings, specifications, regional dominance, application specialization, distribution strength, and engineering expertise.
Understand market concentration and competitive positioning across industrial cooling applications. Support competitive differentiation and long-term strategic planning. Identify underserved customer segments and expansion opportunities across regional markets.
Opportunity Assessment
Identification of high-growth opportunities driven by LNG infrastructure expansion, refinery modernization, hydrogen economy investments, water conservation initiatives, petrochemical capacity additions, and industrial energy efficiency projects.
Prioritize the most attractive investment and expansion opportunities. Support long-term strategic planning and product roadmap development. Enable early identification of emerging industrial demand centers and future revenue streams.
Frequently Asked Questions About This Report
The global air cooled heat exchangers market size was valued at USD 4.7 billion in 2025 and and is estimated at USD 4.9 billion for 2026.
Key factors driving the air cooled heat exchanger market include increasing demand for energy-efficient and environmentally friendly cooling solutions, along with rapid industrial growth in sectors like HVAC, power generation, and chemicals. Technological advancements and stricter environmental regulations also contribute to market expansion.
The L-Fin segment accounted for the largest market share of 46.5% in 2025, owing to its cost-effectiveness, reliable thermal performance, and widespread use across industrial cooling applications.
The forced draft segment dominated the market with a revenue share of 57.0% in 2025, driven by its high cooling efficiency, ease of maintenance, and extensive adoption in process industries.
Based on material, stainless steel segment led the market with the largest revenue share of 37.4% in 2025.
The global air cooled heat exchanger market, in terms of revenue, is expected to grow at a compound annual growth rate of 7.0% from 2026 to 2033, reaching USD 7.9 billion by 2033.
Asia Pacific dominated the global air cooled heat exchangers market with the largest revenue share of 31.2% in 2025
Some of the key players operating in the market are Alfa Laval; Kawasaki Heavy Industries, Ltd.; Xylem; Exchanger Industries Limited; SPX Cooling Tech, LLC; Baker Hughes Company; Kelvion Holding GmbH; Armstrong International Inc.; Hayden Industrial; SNT Energy Co., Ltd.; Boldrocchi; Thermofin; Marmon Industrial Water; Rex Heat Exchanger India Pvt. Ltd.
Oil & gas segment led the market with the largest revenue share of 29.8% in 2025.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


