
- Home
- »
- Automotive & Transportation
- »
-
Amphibious Vehicle Market Size & Share Report, 2026-2033GVR Report cover

Amphibious Vehicle Market (2026 - 2033)
Size, Share & Trends Analysis Report By Propulsion (Track-Based, Water Jet), By End Use (Defense Forces, Disaster Management Agencies), By Vehicle, By Application, By Region, And Segment Forecasts
Market Size, 2025
$4.3BMarket Estimate, 2026
$4.6BMarket Forecast, 2033
$8.3BCAGR, 2026–2033
8.8%Amphibious Vehicle Market Summary
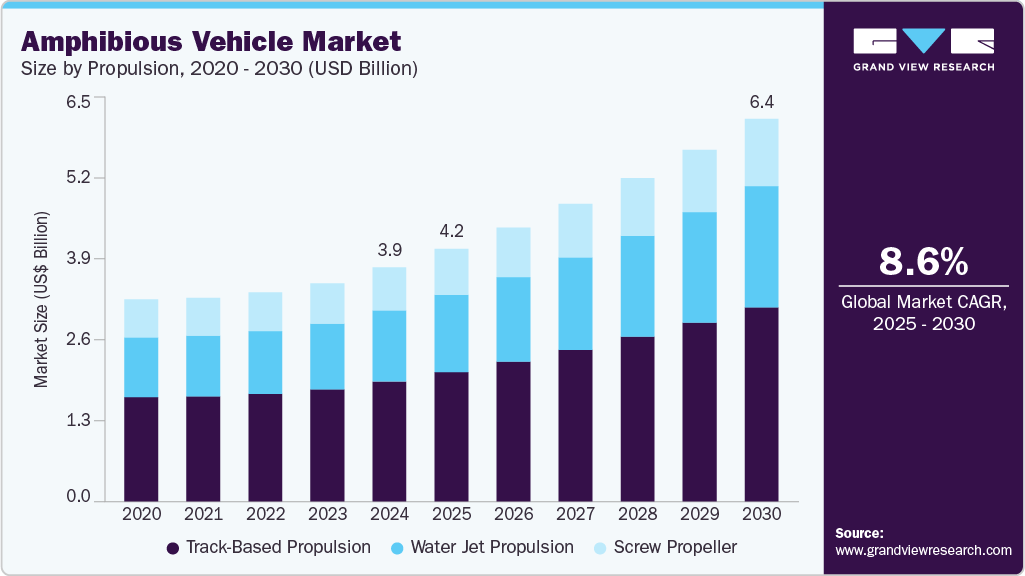
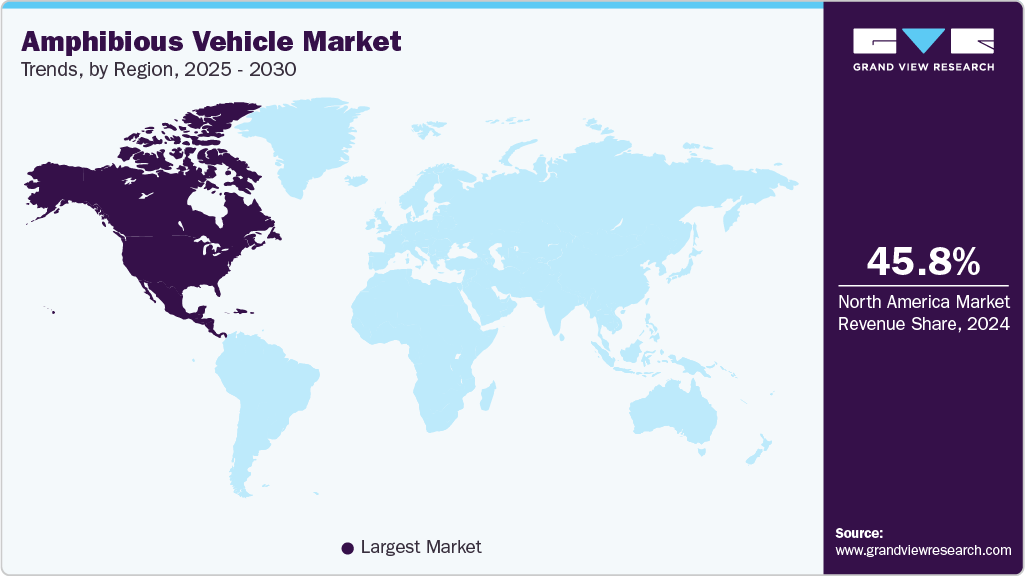
The global amphibious vehicle market size was valued at USD 4.3 billion in 2025 and is projected to grow from USD 4.6 billion in 2026 to USD 8.3 billion by 2033, at a CAGR of 8.8% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 45.0% in 2025. The market is gaining momentum, driven by expanding defense investments to enhance tactical mobility and command capabilities, and by increased deployment by disaster management agencies in response to more frequent climate-induced emergencies.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By propulsion: Track-based propulsion held the largest share of around 51.0% in 2025.
- By vehicle: Armored amphibious vehicles held the largest share of around 35.0% in 2025.
- By application: Military combat & troop transport segment held the largest market share of around 48.0% in 2025.
- By end use: Defense forces segment led the market, with a share of around 30.0% in 2025.
Regional Highlights
- Largest regional market: North America (45.0% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 4.3 Billion
- Estimated market size in 2026: USD 4.6 Billion
- Projected market size by 2033: USD 8.3 Billion
- CAGR (2026-2033): 8.8%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
In addition, rising infrastructure development in flood-prone and waterlogged regions is creating strong demand for amphibious excavators and utility vehicles among construction and dredging contractors. However, the market face challenges such as high production and operational costs to develop and maintain versatile amphibious vehicles. The increasing interest in amphibious transport solutions for tourism and intermodal passenger mobility presents a promising growth opportunity, especially in regions investing in water-based transportation infrastructure.The ongoing wave of defense modernization is steadily reinforcing demand for advanced armored amphibious vehicles tailored to multi-domain operations. For instance, in January 2025, the U.S. Marine Corps accepted delivery of the ACV Command and Control (ACV C) variant at Camp Lejeune, designed to function as a mobile battlefield command center. The vehicle enhances tactical communication and situational coordination, aligning with the Corps’ Force Design 2030 initiative to enhance expeditionary warfare capabilities. Globally, similar modernization programs emphasize mobility, survivability, and digitized command infrastructure in amphibious platforms. As legacy fleets are phased out, defense procurement strategies are increasingly centered on modular, network-enabled vehicles capable of both sea and land operations. This has positioned next-generation amphibious armored units as critical assets within modern force structures, driving consistent demand across allied military agencies.
The growing frequency and severity of climate-related disasters are accelerating the deployment of amphibious vehicles for emergency response, particularly in flood-prone regions. According to the ESCAP Disaster Risk Reduction in Asia and the Pacific Report 2025, floods remain among the region's most damaging natural hazards, causing significant human and economic losses and underscoring the need for resilient emergency response capabilities. These conditions prompted governments and disaster management agencies to adopt amphibious rescue units capable of navigating submerged or damaged infrastructure during high-impact flood events. Their dual terrain capability makes them indispensable for delivering relief supplies, evacuating stranded populations, and accessing remote or inundated areas when conventional vehicles fail.
Amphibious tour operations are gaining popularity for offering seamless land-to-water sightseeing experiences. For instance, Amsterdam and Singapore have introduced amphibious buses and boat tours to attract tourists seeking unique, multi-terrain travel. In addition, governments are exploring amphibious shuttles for last-mile connectivity across rivers and coastal zones, where fixed infrastructure is limited or impractical. As urban planners and transport operators seek innovative mobility solutions, amphibious vehicles offer both functional versatility and passenger appeal, supporting growth in commercial and recreational applications.
Amphibious vehicles must meet separate and often conflicting safety, environmental, and technical standards established by both road and maritime authorities. For instance, in the U.S., amphibious vehicles must comply with Department of Transportation (DOT) standards for on-road use and U.S. Coast Guard (USCG) regulations for watercraft. This includes compliance with vehicle crashworthiness, lighting, and emissions standards on land, as well as flotation stability, navigation lighting, and safety equipment mandates on water. Similarly, in Europe, manufacturers face separate homologation requirements under EU vehicle approval frameworks and inland waterway regulations. These overlapping compliance demands significantly increase development time, testing complexity, and certification costs, especially for commercial and civil operators.
Analyst Perspective
The global amphibious vehicle market is experiencing steady growth, driven by increasing defense modernization programs, rising demand for multi-domain mobility, and expanding deployment in disaster response and flood-resilient infrastructure. Investing next-generation amphibious combat vehicles, advanced propulsion systems, and digital platform integration technologies are improving operational efficiency in both military and civilian domains. The use of amphibious vehicles for rescue missions, dredging operations, construction, and tourism is also contributing to the growth of the market. High initial and lifecycle costs, and regulatory compliance with land and water vehicle standards, are among the major challenges the industry faces. However, future market growth is expected to be supported by innovation, indigenous military procurement, and resilient transport systems.
Propulsion Insights
The track-based propulsion segment held the largest market share in 2025, at around 51.0%, driven primarily by its superior mobility and traction on challenging terrain, including mud, swamps, and uneven floodplains. This propulsion enhances off-road performance, essential for military amphibious vehicles engaged in rugged combat and tactical operations. In addition, its robust design supports heavy payloads, making it ideal for construction and dredging applications in challenging environments where stability and durability are critical.
The water jet propulsion segment is expected to grow at the fastest CAGR from 2026 to 2033. This propulsion enables rapid response in disaster relief and amphibious troop deployments where quick, precise navigation is critical. Its superior speed and agility in shallow and coastal waters, enhanced safety due to reduced underwater hazards from minimal draft, and increasing demand for rapid, precise maneuvering in disaster relief and amphibious missions support the segment growth.
Vehicle Insights
The armored amphibious vehicles segment held the largest market share, at around 35.0%, in 2025. Growth in this segment is driven by increasing demand for versatile, technologically advanced combat vehicles capable of operating across diverse terrains, an enhanced focus on amphibious mobility and survivability, and strategic collaborations for localized production to meet regional defense needs. For instance, in December 2024, ST Engineering and Kazakhstan Paramount Engineering signed an agreement to co-develop an 8×8 amphibious armored vehicle based on the Terrex platform. This partnership includes design and production support, with manufacturing planned in Kazakhstan to fulfill future military deployment requirements, highlighting the segment’s expansion through international collaboration and regional manufacturing capabilities.
The commercial amphibious transport segment is expected to grow at a significant CAGR during the forecast period. The growth of this segment is mainly attributed to rising consumer demand for versatile vehicles that enable seamless travel on land and water, increasing interest in unique leisure and tourism experiences, and advancements in amphibious vehicle technology that enhance safety and performance. For instance, in February 2024, H2O Amphibious Inc. launched its next-generation amphibious cars designed for effortless land-to-water transitions. These vehicles mark a significant advancement in consumer mobility, combining automotive and marine capabilities, and underscore the evolving landscape of commercial amphibious transport driven by innovation and growing market appeal.
Application Insights
The military combat & troop transport segment held the largest market share of around 48.0% in 2025, driven by accelerating military modernization programs focused on replacing legacy vehicles, rising geopolitical tensions that require rapid force deployment across diverse terrains, and advancements in vehicle survivability and unmanned systems integration. Strategic investments by defense agencies to enhance amphibious assault and littoral combat capabilities are fueling growth in the segment. Also, growing emphasis on expeditionary warfare and rapid amphibious mobility continues to reinforce the importance of this segment in defense planning worldwide.
The commercial & recreational transport segment is expected to register a notable CAGR from 2026 to 2033, driven by rising consumer interest in versatile vehicles capable of navigating both land and water, expanding tourism activities focused on unique amphibious experiences, and innovations in vehicle design enhancing safety and user convenience. In addition, growing investments in waterfront infrastructure and eco-friendly transport solutions are supporting market growth.
End Use Insights
The defense forces segment held the largest market share of around 30.0% in 2025, driven by increased procurement of advanced amphibious vehicles to enhance operational mobility and adaptability across diverse terrains. Growth has been supported by ongoing military modernization initiatives, strategic investments in versatile armored platforms, and heightened geopolitical tensions necessitating enhanced defense readiness. For instance, in January 2024, JSW Group secured a USD 26 million contract from India’s Ministry of Defense to produce 96 Ator N1200 amphibious vehicles based on the Sherp N1200 platform, aimed at strengthening the Indian Army’s amphibious capabilities with deliveries scheduled by June 2024.
The tourism & transport operators segment is expected to register a notable CAGR from 2026 to 2033, driven by the growing adoption of amphibious vehicles for unique travel experiences and urban mobility. Innovations, including the HafenCity RiverBus in Hamburg, Germany, which operates both on land and water, highlight the rising demand for such versatile transport options. Built on a MAN truck chassis and designed to carry 36 passengers plus crew, this amphibious bus offers combined sightseeing tours and river cruises, enhancing tourist engagement while addressing urban transport challenges. Growing interest in eco-friendly, multimodal travel options is also driving investment and expansion within this segment.
Regional Insights
The North America amphibious vehicle industry accounted for 45.0% of the global revenue share in 2025. The market in North America is being driven by increasing defense modernization efforts focused on enhanced amphibious combat capabilities, rising demand for multi mission vehicles capable of rapid deployment on land and at sea, and growing investments in advanced autonomous amphibious platforms. For instance, in January 2024, BAE Systems secured a USD 169 million contract from the U.S. Marine Corps for 33 additional Amphibious Combat Vehicles under full-rate production Lot 2. This contract includes personnel, command, 30mm cannon, and recovery variants developed in partnership with IVECO Defense Vehicles, highlighting ongoing modernization initiatives.
 To learn more about this report, Download Free Sample Report
Asia Pacific Amphibious Vehicle Market Trends
The U.S. amphibious vehicle industry held a dominant position in 2025. The market is being driven by the U.S. Marine Corps' ongoing transition to next-generation amphibious platforms to enhance expeditionary mobility, survivability, and operational readiness in the Indo-Pacific. For instance, in December 2024, the U.S. Marine Corps' 4th Marine Regiment conducted its first open-water movement with the Amphibious Combat Vehicle (ACV) in Okinawa. This milestone marked a significant advancement in the Corps' modernization efforts, replacing the legacy Assault Amphibious Vehicle with a platform offering improved mobility, survivability, and firepower. The deployment reflects the Marine Corps' continued focus on strengthening amphibious operations across contested littoral environments. These developments demonstrate how defense modernization and the deployment of next-generation amphibious platforms are reshaping the U.S. amphibious vehicle industry.
The amphibious vehicle industry in Canada is driven by the increasing investments in disaster response and emergency preparedness, particularly for flood and wildfire management. In addition, the development of amphibious vehicles suited to remote and Arctic terrain supports growth in this region.
Mexico amphibious vehicle market growth is supported by expanding border and coastal security measures and infrastructure development in flood-prone regions. Enhanced government focus on disaster management and rescue operations also bolsters demand for amphibious vehicles in the country.
Asia Pacific Amphibious Vehicle Market Trends
The Asia Pacific amphibious vehicle industry was identified as a lucrative market in 2025. Factors including the rising military expenditures, increasing territorial tensions, and the growing adoption of naval modernization programs are driving the market growth. The strategic focus of several regional powers is on enhancing expeditionary and amphibious assault capabilities amid geopolitical tensions in the South China Sea, East China Sea, and the Indian Ocean. The market is also being propelled by increasing investment in joint land-sea operations and rapid-response logistics platforms tailored for archipelagic and flood-prone geographies. For instance, in December 2024, China launched its first Type 076 amphibious assault ship, Sichuan, a 40,000-tonne vessel equipped with an electromagnetic catapult and arrestor gear for fixed-wing aircraft operations. The platform significantly expands China's long-range amphibious deployment and force projection capabilities, directly influencing demand for advanced amphibious combat vehicles and air-cushioned landing craft to complement these naval assets. In addition, countries including India, Japan, and South Korea are accelerating upgrades to their amphibious forces for island defense, humanitarian missions, and regional deterrence, reinforcing demand for both armored and utility-class amphibious vehicles across the defense sector.
The China amphibious vehicle industry held a substantial market share in 2025. The market is being driven by China's continued investment in advanced amphibious combat platforms to strengthen its littoral warfare capabilities, improve operational mobility, and enhance firepower during amphibious operations. As part of its broader military modernization efforts, the country continues to prioritize developing next-generation amphibious systems to support complex coastal and island-based missions. This strategic focus is accelerating the testing and deployment of specialized amphibious platforms equipped with advanced combat capabilities. For instance, in April 2025, China tested a new amphibious anti-tank missile platform integrating 12 HJ-10 top-attack missiles onto the ZTD-05 amphibious assault vehicle chassis. The platform is designed to improve mobility and firepower during littoral operations while enhancing the military's ability to engage armored targets in amphibious combat scenarios. This development highlights China's continued focus on advancing specialized amphibious combat vehicles and supports growing domestic demand for technologically advanced platforms aligned with its long-term defense modernization objectives.
Amphibious vehicle market in Japan held a significant regional share in 2025. In Japan, the market is influenced by sustained investment in force modernization, a strategic pivot toward rapid response capabilities, and rising regional security concerns in the East China Sea. At the International Armored Vehicles (IAV) 2024 event, Japan’s Ministry of Defense emphasized its focus on advanced amphibious vehicle development and hybrid propulsion technologies. Central to this is the Future Amphibious Technology Replacement (FATR) program, which aims to phase out legacy AAV7 platforms in favor of next-generation systems offering improved speed, seaworthiness, and stealth. Backed by the Acquisition, Technology & Logistics Agency (ATLA), this initiative is expected to directly stimulate domestic demand for high-performance amphibious solutions aligned with Japan’s evolving defense posture.
Europe Amphibious Vehicle Market Trends
The Europe amphibious vehicle industry was identified as a lucrative region in 2025. The European market is witnessing a significant transformation, driven by escalating defense modernization efforts, growing investments in amphibious mobility platforms, and a focus on enhancing interoperability among NATO member states. In December 2024, MilDef Group AB secured an approximately USD 7.3 million contract with BAE Systems Hägglunds to supply rugged IT equipment for the amphibious-capable BvS10 tracked vehicles. Scheduled for delivery between 2025 and 2029, this collaboration is set to bolster regional defense capabilities and strengthen critical supply chains across Europe, further propelling market growth.
Germany's amphibious vehicle industry growth is shaped by the increasing number of defense modernization programs, with a focus on enhancing rapid deployment and multi-domain operational capabilities. Germany’s strategic emphasis on strengthening its Bundeswehr’s amphibious forces aligns with broader NATO commitments to improve readiness in response to evolving security challenges in the Baltic and North Sea regions. Investment in upgraded amphibious platforms, including tracked and wheeled vehicles equipped with advanced communication and navigation systems, is underway. Collaborative projects with European partners are further driving technological innovation and regional defense integration.
Amphibious vehicle market in the UK is heavily influenced by the ongoing modernization of the Royal Marines’ amphibious capabilities to support expeditionary and littoral operations. The Ministry of Defense’s investment in interoperability with NATO allies and the expansion of rapid response forces drive demand for versatile amphibious platforms suitable for both high-intensity conflict and humanitarian missions. The UK also prioritizes integrating autonomous systems and network-centric warfare capabilities into its amphibious fleet, positioning its forces for future multi-domain operations. Also, the UK’s commitment to sustainable military technologies fosters the development of energy-efficient propulsion solutions within this sector.
Key Amphibious Vehicle Market Company Insights
Some of the key players operating in the market include BAE Systems plc, General Dynamics Corporation, Rheinmetall AG, and Hanwha Aerospace.
- Founded in 1999 and headquartered in London, UK, BAE Systems plc is a global defense, security, and aerospace company. The company specializes in the design, manufacture, and support of advanced amphibious vehicles, combat systems, and military platforms. It offers a broad portfolio including armored vehicles, naval ships, and cybersecurity solutions. BAE Systems plc operates worldwide, delivering integrated defense solutions and leveraging cutting-edge technologies, including autonomous systems, electronic warfare, and advanced weaponry, to support military and government clients.
- Founded in 1952 and headquartered in Virginia, U.S., General Dynamics Corporation is a global aerospace and defense company. The company specializes in amphibious combat vehicles, armored systems, and mission-critical technologies. Its product portfolio includes the Amphibious Combat Vehicle (ACV), ground combat vehicles, marine systems, and IT services. General Dynamics serves defense, government, and commercial customers worldwide, employing advanced engineering, innovation, and integration capabilities to enhance operational effectiveness and force readiness.
Key Amphibious Vehicle Companies
The following key companies have been profiled for this study on the amphibious vehicle market:
-
BAE Systems plc
-
EIK Engineering Sdn. Bhd.
-
General Dynamics Corporation
-
Hanwha Aerospace
-
Hitachi Construction Machinery Co., Ltd.
-
Hydratrek, Inc.
-
Marsh Buggies Incorporated
-
Rheinmetall AG
-
Wetland Equipment Company
-
Wilco Manufacturing L.L.C.
Recent Developments
-
In April 2025, BAE Systems received a USD 188.5 million contract from the U.S. Marine Corps for 30 ACV-30mm vehicles, including spares and fielding support. The ACV-30 features a 30mm remote turret and supports ship-to-shore and advanced land operations.
-
In February 2025, BAE Systems debuted its Amphibious Combat Vehicle (ACV) at the IDEX defense exhibition in the UAE. The ACV, designed for rugged terrain and open-ocean amphibious operations, highlights the program’s goal for international expansion and enhanced operational flexibility for allied militaries worldwide.
-
In April 2024, Louisiana-based Metal Shark Boats announced the launch of a new 30-foot autonomous surface vehicle that combines semi-submersible and amphibious navigation. Designed for US Navy and Marine Corps requirements, the autonomous amphibious surface vehicle (ASV) offers high speed, long range, and simplified launch/recovery, with remote operation capability on land via an electric-drive system.
Amphibious Vehicle Market Report Scope
Report Attribute
Details
Market size in 2025
USD 4.3 billion
Estimated market size in 2026
USD 4.6 billion
Projected market size by 2033
USD 8.3 billion
Growth rate
CAGR of 8.8% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Propulsion, vehicle, application, end use, and region
Regional Scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country Scope
U.S.; Canada; Mexico; UK; Germany; France; China; India; Japan; Australia; South Korea; Brazil; UAE; Kingdom of Saudi Arabia (KSA); South Africa
Key companies profiled
BAE Systems plc; General Dynamics Corporation; Rheinmetall AG; Hanwha Aerospace; Hitachi Construction Machinery Co., Ltd.; EIK Engineering Sdn. Bhd.; Wetland Equipment Company; Wilco Manufacturing L.L.C.; Hydratrek, Inc.; Marsh Buggies Incorporated
Customization scope
Free report customization (equivalent to 8 analyst working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Amphibious Vehicle Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends and opportunities across each sub-segment from 2021 to 2033. For this study, Grand View Research has segmented the global amphibious vehicle market report based on propulsion, vehicle, application, end use, and region:
-
Propulsion Outlook (Revenue, USD Billion, 2021 - 2033)
-
Track-Based Propulsion
-
Water Jet Propulsion
-
Screw Propeller
-
-
Vehicle Outlook (Revenue, USD Billion, 2021 - 2033)
-
Armored Amphibious Vehicles
-
Amphibious Excavators
-
Light Amphibious Utility Vehicles
-
Commercial Amphibious Transport
-
-
Application Outlook (Revenue, USD Billion, 2021 - 2033)
-
Military Combat & Troop Transport
-
Disaster Response & Humanitarian Aid
-
Construction & Dredging
-
Commercial & Recreational Transport
-
-
End Use Outlook (Revenue, USD Billion, 2021 - 2033)
-
Defense Forces
-
Disaster Management Agencies
-
Construction & Dredging Contractors
-
Tourism & Transport Operators
-
Government Municipalities
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Australia
-
South Korea
-
-
Latin America
-
Brazil
-
-
Middle East and Africa (MEA)
-
UAE
-
Kingdom of Saudi Arabia (KSA)
-
South Africa
-
-
Frequently Asked Questions About This Report
The global amphibious vehicle market size was valued at USD 4.3 billion in 2025 and is estimated at USD 4.6 billion in 2026.
The global amphibious vehicle market is expected to grow at a CAGR of 8.8% from 2026 to 2033, reaching USD 8.3 billion.
North America dominated with an approximately 45.0% revenue share in 2025.
Key players in the market include BAE Systems plc, General Dynamics Corporation, Rheinmetall AG, Hanwha Aerospace, Hitachi Construction Machinery Co., Ltd., EIK Engineering Sdn. Bhd., Wetland Equipment Company, Wilco Manufacturing L.L.C., Hydratrek, Inc., and Marsh Buggies Incorporated, among others.
The track-based propulsion segment accounted for the largest revenue share, at around 51.0%, in 2025.
About the Author(s)
Automotive & Transportation Research Team
Technology · Automotive & TransportationThis report was authored by the automotive & transportation research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the automotive & transportation segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


