
- Home
- »
- Plastics, Polymers & Resins
- »
-
Ampoules Packaging Market Size & Share Report 2026-2033GVR Report cover

Ampoules Packaging Market (2026 - 2033)
Size, Share & Trends Analysis Report By Material (Glass, Plastic), By Ampoule Type (Straight-Stem, Easy-Open, Closed/Form D, Easy-Open), By Capacity(?2 mL, o 3-5 mL), By Application, By Region, And Segment Forecasts
Market Size, 2025
$4.9BMarket Estimate, 2026
$5.2BMarket Forecast, 2033
$8.7BCAGR, 2026–2033
7.7%Ampoules Packaging Market Summary
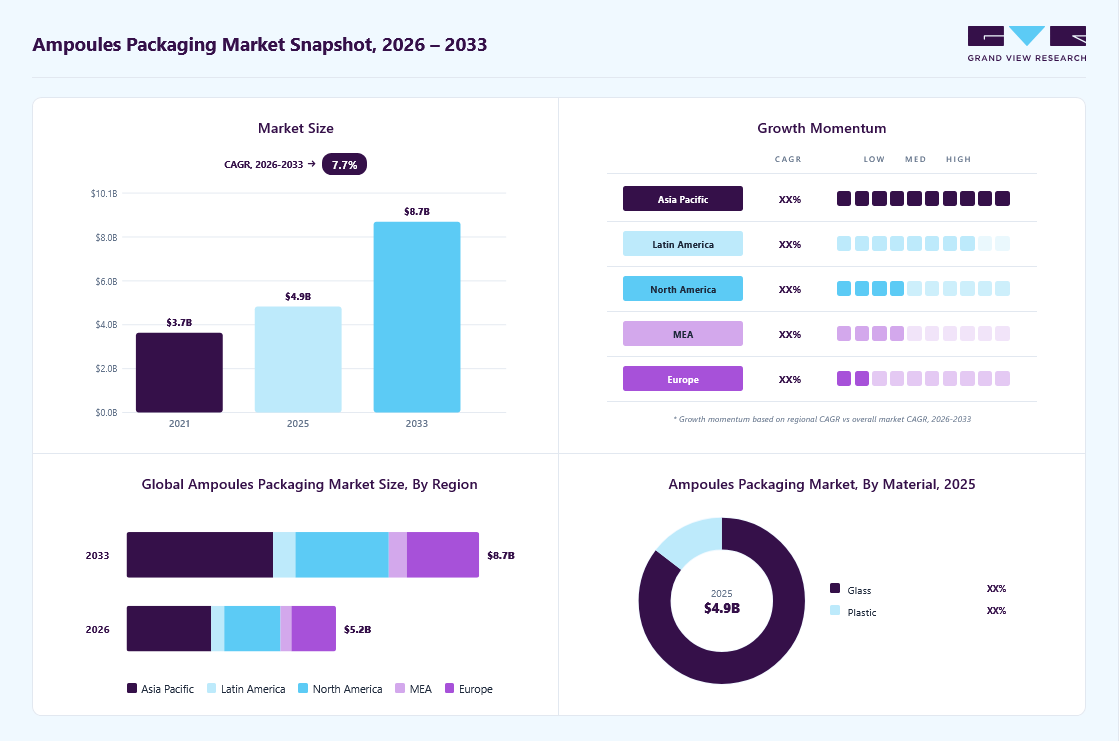
The global ampoules packaging market size was valued at USD 4.9 billion in 2025 and is projected to grow from USD 5.2 billion in 2026 to USD 8.7 billion by 2033, at a CAGR of 7.7% from 2026 to 2033. The market in Asia Pacific dominated with a revenue share of 40.2% in 2025. The market is primarily driven by the growing demand for injectable drugs, vaccines, and biologics, along with increasing pharmaceutical production, stringent requirements for sterile and contamination-resistant primary packaging, and expanding healthcare infrastructure across emerging economies.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By material: Glass segment held the largest market share of 85.3% in 2025.
- By ampoule type: Straight-stem segment held the largest market share of 61.5% in 2025.
- By capacity: ≤2 mL segment held the largest market share of 42.4% in 2025.
- By application: Injectable drugs segment held the largest market share of 56.8% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (40.2% revenue share, 2025)
- By country: China held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 4.9 Billion
- Estimated market size in 2026: USD 5.2 Billion
- Projected market size by 2033: USD 8.7 Billion
- CAGR (2026-2033): 7.7%
GVR research-powered AIAsk Prism AI about the ampoules packaging marketGet cited answers from GVR research on market growth, segments, regulations and forecasts.Start with✓ Source-linked answers ✓ Market-specific context ✓ Traceable figuresExplore Prism AI ↗
The market is driven by the growing demand for safe, sterile, and contamination-resistant primary packaging for injectable pharmaceutical products. As pharmaceutical manufacturers expand production of injectable drugs, vaccines, biologics, and diagnostic formulations, there is increasing demand for ampoules that provide high chemical stability, product protection, and reliable barrier performance. Glass remains the dominant material, generating approximately USD 4.14 billion in revenue in 2025 and accounting for the market majority, supported by the established use of pharmaceutical-grade glass for sensitive drug formulations. The continued expansion of injectable therapies and stringent requirements for pharmaceutical container quality are expected to sustain demand for glass ampoules across global healthcare supply chains.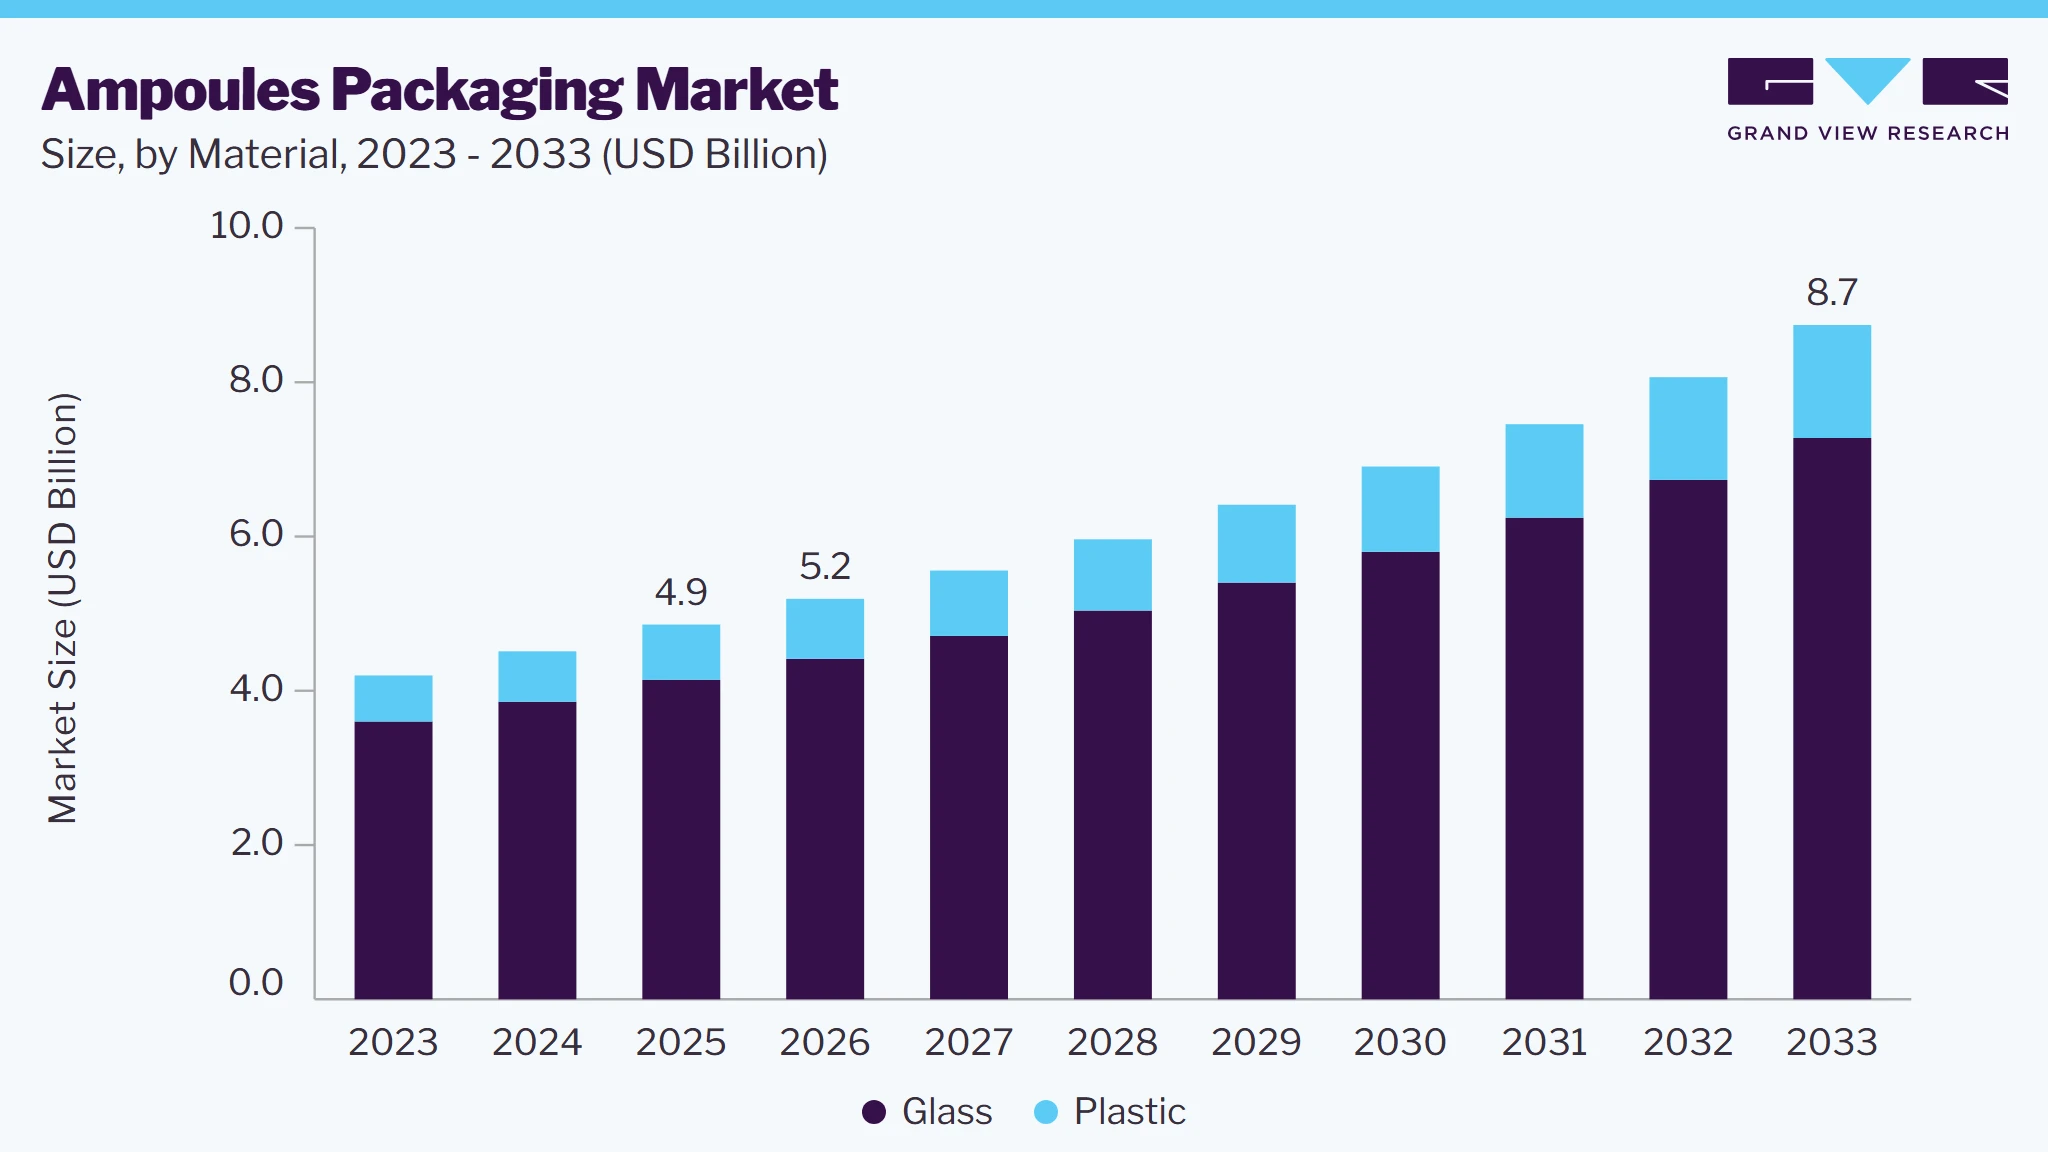 To learn more about this report, Download Free Sample Report
An increasing focus on pharmaceutical safety, sterility, and regulatory compliance is expected to boost market growth. Glass ampoules offer excellent chemical resistance, transparency, impermeability, and compatibility with a wide range of pharmaceutical formulations, making them particularly suitable for injectable drugs and vaccines. At the same time, manufacturers are increasingly adopting plastic ampoules for applications where lightweight construction, breakage resistance, and ease of handling provide advantages. The plastic segment is projected to expand at the fastest CAGR of 9.5% from 2026 to 2033, compared with 7.4% for glass, indicating increasing adoption of alternative materials in selected pharmaceutical and healthcare applications.
Sustainability initiatives and the transition toward more resource-efficient pharmaceutical packaging systems are also influencing the industry. A defining trend is the development of lightweight packaging formats and improved material-efficiency processes aimed at reducing raw material consumption, transportation weight, and packaging waste while maintaining the stringent performance requirements of pharmaceutical containers. Glass manufacturers are increasingly focusing on lightweight pharmaceutical containers and efficient production processes, while plastic ampoule manufacturers are exploring recyclable and lower-material-content formats. These developments are expected to support material diversification and improve the environmental performance of ampoule packaging while maintaining product protection and regulatory compliance.
Market Dynamics
The market is witnessing steady growth, driven by increasing demand for injectable drugs, vaccines, and biologics, along with the expansion of pharmaceutical manufacturing and healthcare infrastructure worldwide. Manufacturers are focusing on high-quality, sterile, chemically resistant, and reliable packaging formats to meet stringent pharmaceutical requirements. Glass remains the dominant material due to its established compatibility with injectable formulations, while advancements in lightweight glass manufacturing, easy-open designs, and plastic ampoules are supporting product innovation. Increasing regulatory emphasis on container integrity and drug safety is further shaping the development of ampoule packaging solutions.
The growing production and consumption of injectable drugs, vaccines, and biologics is a key market driver. Injectable formulations require primary packaging that provides strong protection against contamination, moisture, oxygen, and chemical interaction while maintaining product stability throughout storage and transportation. In the provided market data, injectable drugs accounted for USD 2,758.4 million in revenue in 2025, representing the largest application segment with a 56.8% market share.
As pharmaceutical companies expand their injectable product portfolios, demand for reliable ampoule packaging is increasing. The rising adoption of biologic therapies and vaccines is also creating additional demand for high-performance primary containers. Pharmaceutical manufacturers are increasingly seeking ampoules with consistent dimensions, high-quality glass, reliable sealing, and improved opening characteristics to support safe filling, storage, transportation, and administration of injectable formulations.
A significant market restraint is the stringent regulatory and quality requirements associated with pharmaceutical primary packaging. Ampoules for injectable formulations must comply with strict standards related to chemical resistance, hydrolytic resistance, dimensional consistency, container integrity, sterility, and drug compatibility. These requirements increase testing, validation, quality-control, and manufacturing costs, while the need for highly controlled production environments can raise operational complexity and capital expenditure. Such regulatory requirements may particularly challenge smaller manufacturers and extend product-development timelines.
A major market opportunity lies in the development of lightweight, easy-open, and resource-efficient packaging solutions. Pharmaceutical manufacturers are increasingly seeking packaging formats that reduce material consumption, transportation weight, and handling risks while maintaining product protection, sterility, and safety. Growing emphasis on user convenience and workplace safety is encouraging manufacturers to develop improved opening mechanisms and ergonomic designs. In addition, sustainability initiatives are creating opportunities for lightweight glass technologies, recyclable materials, and energy-efficient manufacturing processes, enabling ampoule producers to reduce environmental impact while meeting stringent pharmaceutical packaging requirements.
Industry Concentration & Characteristics
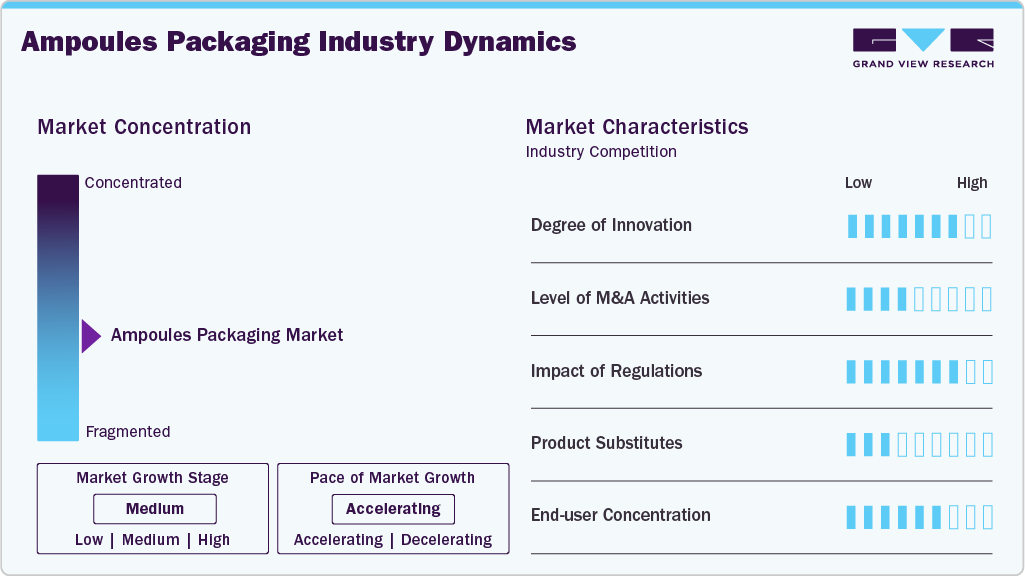
The market is characterized by its strong focus on product safety, sterility, chemical compatibility, and stringent quality requirements, driven primarily by the pharmaceutical industry's dependence on reliable primary packaging for injectable drugs, vaccines, biologics, and diagnostic formulations.
The industry relies heavily on pharmaceutical-grade glass, particularly borosilicate glass, due to its high chemical resistance, impermeability, transparency, and ability to protect sensitive formulations from contamination and environmental exposure. Manufacturers prioritize dimensional consistency, container integrity, controlled manufacturing conditions, and reliable sealing technologies to meet pharmaceutical quality standards. Leading players such as SCHOTT Pharma, Gerresheimer, Stevanato Group, SGD Pharma, and Nipro have developed specialized manufacturing capabilities focused on high-quality pharmaceutical ampoules and customized container solutions.
 To learn more about this report, Download Free Sample Report
The industry is also evolving toward lightweight ampoule designs, easy-open formats, improved manufacturing efficiency, and greater material utilization to address safety, operational, and sustainability requirements. Regulatory frameworks and pharmacopeial standards governing pharmaceutical glass containers are influencing material selection, production processes, testing, and quality control. In parallel, increasing pharmaceutical production, rising demand for injectable therapies, and growing adoption of biologics and vaccines are encouraging manufacturers to invest in advanced glass-forming, sealing, inspection, and automated production technologies.
Analyst Perspective
The market has evolved from traditional glass ampoules used mainly for injectable drugs into a specialized primary pharmaceutical packaging segment serving injectables, vaccines, biologics, and diagnostic reagents. While glass continues to dominate due to its chemical resistance, sterility, barrier properties, and compatibility with sensitive formulations, plastic ampoules are gaining adoption in selected applications. Looking ahead, the market is expected to witness steady growth through 2033, supported by rising injectable drug production, biologics and vaccine demand, pharmaceutical manufacturing, sterile packaging requirements, and advancements in easy-open and high-performance ampoule designs.
Material Insights
The glass segment led the market with the largest revenue share of 85.3% in 2025, generating approximately USD 4,142.9 million. Glass is the dominant material used in ampoule packaging due to its excellent chemical resistance, impermeability, transparency, and compatibility with sensitive pharmaceutical formulations. Pharmaceutical-grade glass, particularly borosilicate glass, provides strong protection against contamination and interaction with drug products, making it widely preferred for injectable drugs, vaccines, biologics, and diagnostic applications. The established pharmaceutical infrastructure, stringent packaging standards, and proven performance of glass continue to support its dominant position in the market.
The plastic segment is expected to grow at the fastest CAGR of 9.5% during the forecast period. Plastic ampoules are gaining traction due to their lightweight, shatter-resistant, and convenient handling characteristics compared with conventional glass formats. They can offer advantages in applications requiring reduced breakage risk, easier transportation, and improved handling efficiency. The increasing focus on lightweight pharmaceutical packaging, material efficiency, and alternative packaging formats is supporting the adoption of plastic ampoules, particularly in applications where their functional and handling benefits complement the requirements of pharmaceutical manufacturers.
Ampoule Type Insights
The straight-stem segment dominated with the largest revenue share of 61.5% in 2025, generating approximately USD 2,986.0 million. Straight-stem ampoules are widely used in pharmaceutical packaging due to their established design, reliable sealing characteristics, and suitability for storing injectable formulations. Their compatibility with conventional filling, sealing, and handling processes makes them a preferred format across pharmaceutical manufacturing operations, particularly for injectable drugs and other sterile products.
The easy-open segment is expected to grow at the fastest CAGR of 9.2% during the forecast period. Easy-open ampoules are gaining adoption because they provide greater convenience during product administration while reducing the effort required to access the contents. Their user-friendly design is particularly relevant for healthcare professionals handling injectable medications, where efficient opening and controlled access are important. Growing emphasis on safer and more convenient pharmaceutical packaging formats is expected to support the increasing adoption of easy-open ampoules.
Capacity Insights
The ≤2 mL segment dominated with the largest revenue market share of 42.4% in 2025, generating approximately USD 2,061.5 million. Small-capacity ampoules are widely used for pharmaceutical and injectable formulations where precise dosing, product stability, and efficient material utilization are important. Their suitability for vaccines, injectable drugs, and other concentrated formulations, along with their compatibility with established filling and sterilization processes, supports their leading position in the market.
The 6-10 mL segment is expected to grow at the fastest CAGR of 8.4% during the forecast period. The segment is benefiting from increasing demand for ampoules capable of accommodating higher-volume injectable formulations and multi-dose or larger-volume pharmaceutical applications. Growing use of injectable therapies and biologic formulations requiring greater fill volumes is supporting demand for mid-capacity ampoules, while advancements in filling and sealing technologies are improving their suitability across pharmaceutical manufacturing operations.
Application Insights
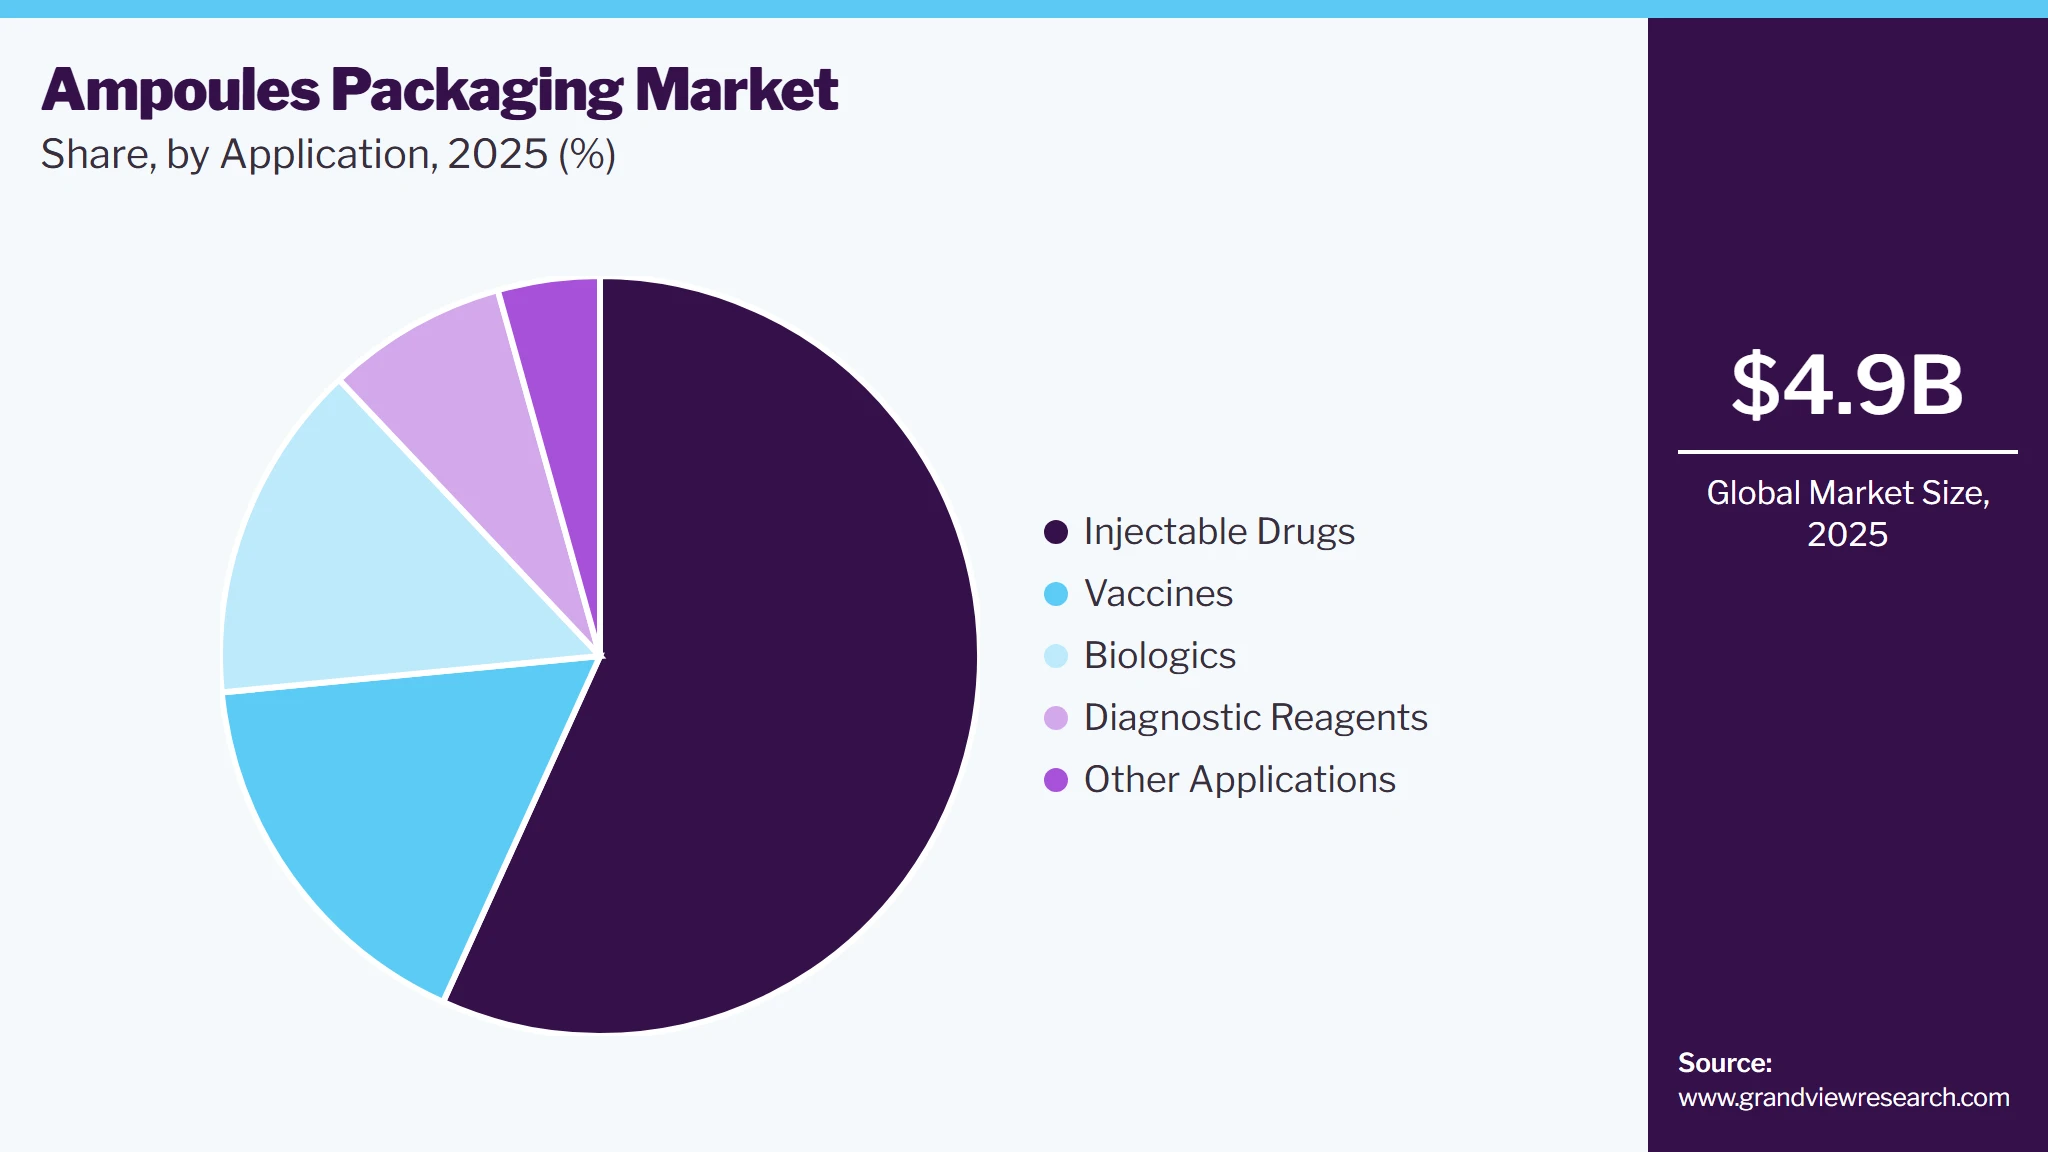
The injectable drugs segment dominated with the largest revenue share of 56.8% in 2025, generating approximately USD 2,758.4 million. Ampoules are widely used for injectable drug formulations because they provide a sterile, hermetically sealed container that helps protect sensitive pharmaceutical products from contamination and external exposure. The established use of ampoules for parenteral medications, combined with the continued demand for injectable therapies across hospitals, clinics, and pharmaceutical manufacturing facilities, supports the segment’s leading position.
 To learn more about this report, Download Free Sample Report
Biologics is expected to grow at the fastest CAGR of 8.3% during the forecast period. Increasing use of biologic therapies, including vaccines, therapeutic proteins, and other complex injectable formulations, is driving demand for high-quality primary packaging capable of maintaining product integrity and sterility. Ampoules provide strong protection against environmental exposure and are compatible with stringent pharmaceutical handling and sterilization requirements, supporting their adoption for sensitive biologic formulations.
Regional Insights
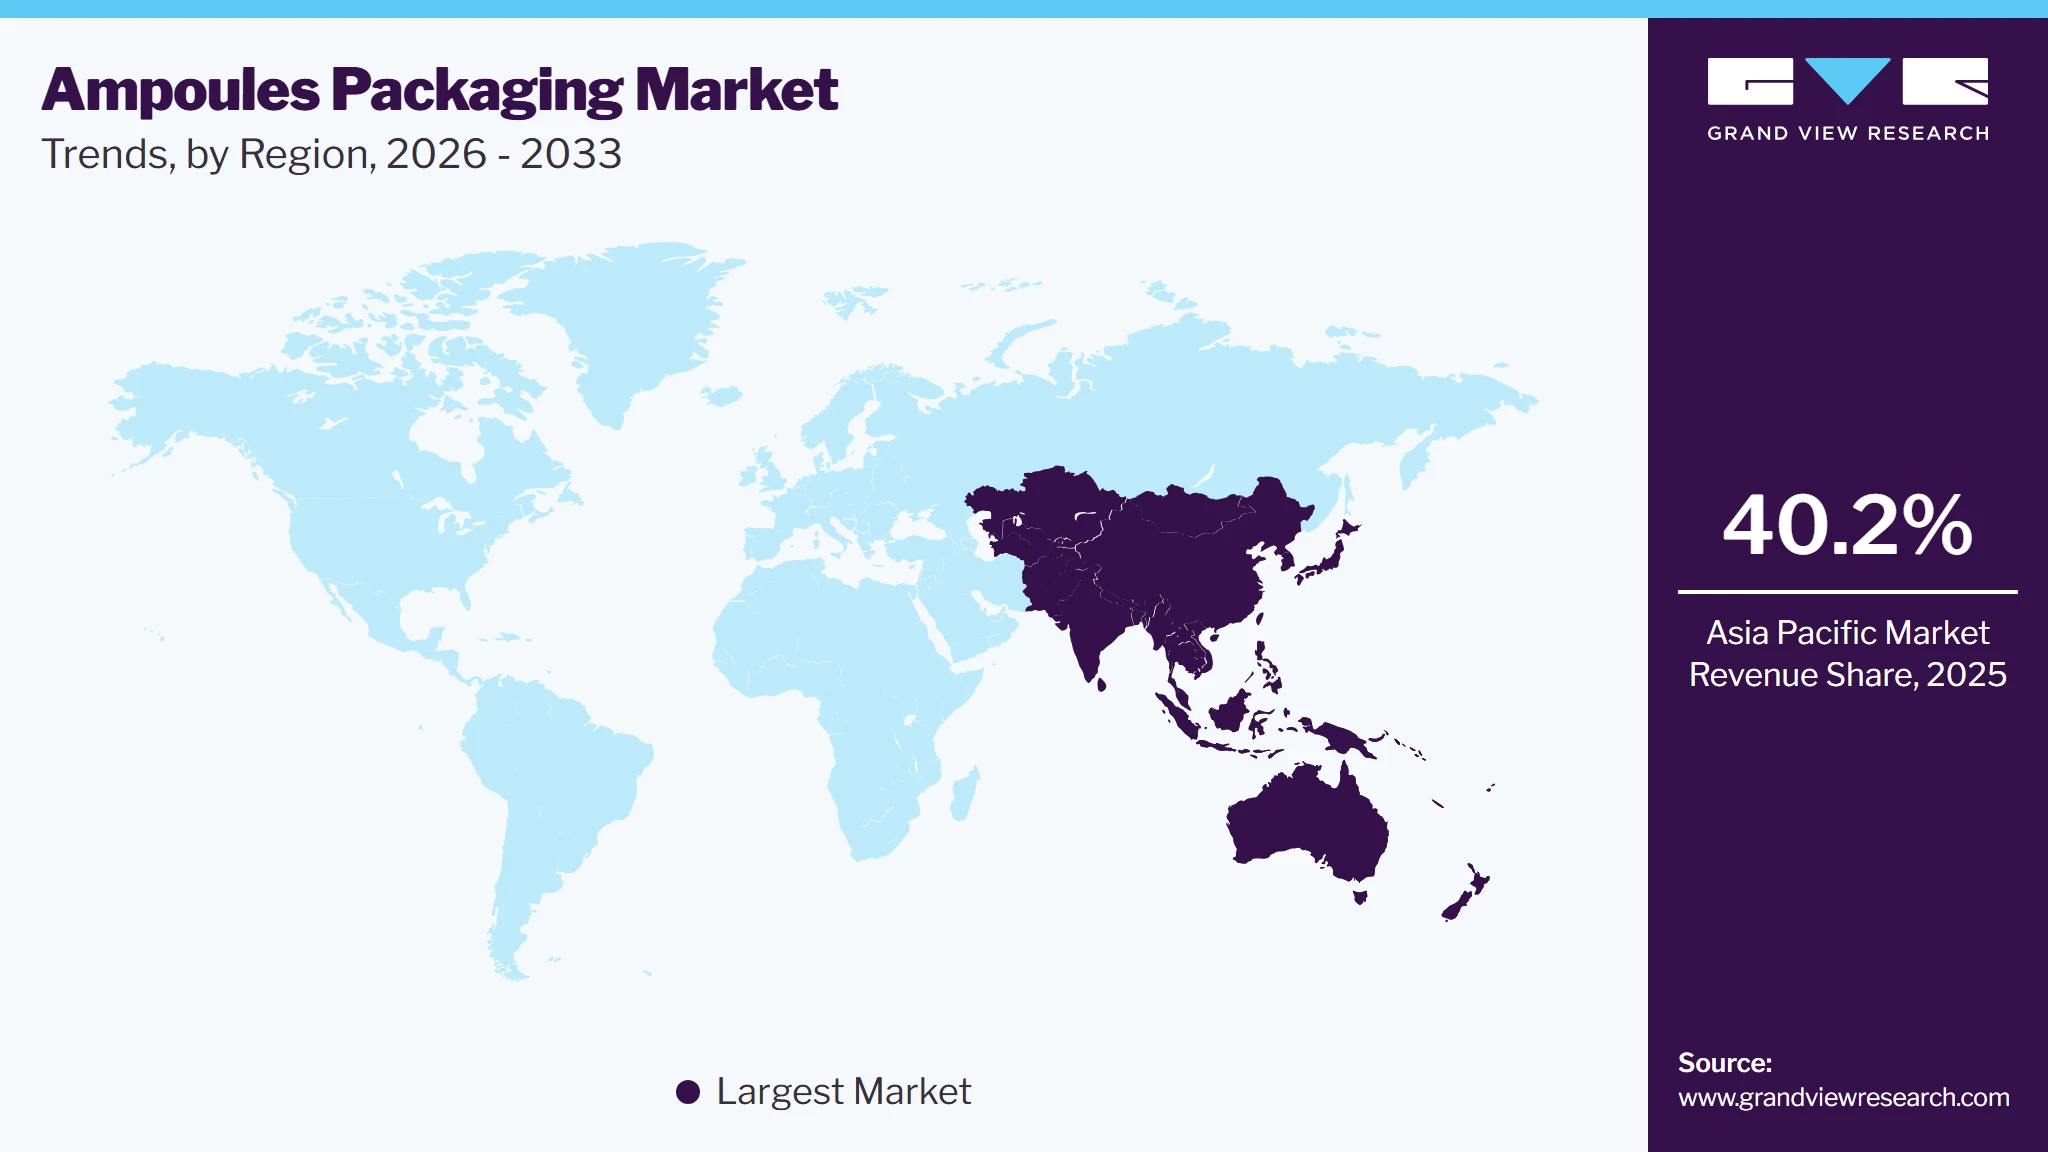
Asia Pacific dominated the global ampoules packaging market with a revenue share of 40.2% in 2025, and is projected to register the fastest CAGR of 8.2% during the forecast period. Regional leadership is supported by rapid pharmaceutical manufacturing expansion, growing healthcare expenditure, increasing production of injectable drugs and vaccines, and the presence of large-scale pharmaceutical manufacturing centers. Expansion of healthcare infrastructure and rising demand for sterile primary packaging across emerging economies are further strengthening the region's market position.
 To learn more about this report, Download Free Sample Report
China Ampoules Packaging Market Trends
The ampoules packaging market in China represents a major market in the Asia Pacific, supported by its extensive pharmaceutical manufacturing industry and expanding production of injectable medicines, vaccines, and biologics. Increasing healthcare investment and the development of domestic pharmaceutical manufacturing capabilities are strengthening demand for sterile primary packaging. The growing adoption of automated filling and sealing processes is also supporting the use of standardized ampoule formats.
India ampoules packaging market is expected to be one of the key growth markets for ampoules packaging in Asia Pacific, driven by expanding pharmaceutical production, increasing demand for injectable formulations, and the country's growing role in global drug manufacturing. Rising healthcare expenditure and increasing production of vaccines and generic injectable medicines are creating opportunities for ampoule manufacturers. Investments in pharmaceutical manufacturing capacity and sterile packaging infrastructure are expected to further support market expansion.
Europe Ampoules Packaging Market Trends
The ampoules packaging market in Europe is projected to witness steady growth throughout the forecast period, supported by the region's established pharmaceutical industry and strong demand for sterile packaging formats. The market reached approximately USD 1,038.2 million in 2025, accounting for a 21.4% revenue share. Growing production of injectable medicines, vaccines, and biologics, combined with stringent pharmaceutical packaging standards, is encouraging manufacturers to adopt reliable and high-quality ampoule solutions.
Germany ampoules packaging marketrepresents a significant market in Europe, owing to its strong pharmaceutical manufacturing base, advanced healthcare infrastructure, and established production of injectable medicines. Demand is supported by the country's focus on pharmaceutical quality and precision manufacturing, while continued development of biologics and specialized injectable therapies is expected to create additional demand for sterile primary packaging solutions.
The ampoules packaging market in the UKis expected to grow at a steady pace, supported by pharmaceutical manufacturing, vaccine production, and increasing demand for injectable and biologic therapies. The country's emphasis on pharmaceutical quality and sterile drug delivery systems is encouraging the use of secure primary packaging formats. Manufacturers are also focusing on improving ampoule design, handling characteristics, and compatibility with modern filling and sealing operations.
North America Ampoules Packaging Market Trends
The ampoules packaging market in North America is expected to expand steadily during the forecast period, supported by strong pharmaceutical manufacturing capabilities, increasing demand for injectable medicines, and the well-established use of sterile primary packaging. The region generated approximately USD 1,306.2 million in revenue in 2025, representing a 26.9% share of the global market. Demand is further supported by stringent quality requirements for pharmaceutical packaging and continued investment in injectable drug manufacturing and healthcare infrastructure.
The U.S. ampoules packaging marketis anticipated to maintain consistent growth, driven by its large pharmaceutical and biotechnology industry and substantial demand for injectable drugs, vaccines, and biologic therapies. The country's advanced sterile manufacturing infrastructure and emphasis on pharmaceutical quality, container integrity, and contamination prevention continue to support the adoption of ampoules across healthcare and pharmaceutical applications.
Latin America Ampoules Packaging Market Trends
The ampoules packaging market in Latin America is projected to grow steadily during the forecast period, reaching approximately USD 303.7 million in 2025 and representing a 6.2% revenue share. Market expansion is supported by increasing pharmaceutical production, improving healthcare infrastructure, and rising demand for injectable medicines and vaccines. Growth in domestic healthcare manufacturing and greater access to pharmaceutical treatments are expected to sustain demand for sterile ampoule packaging solutions.
Brazil ampoules packaging marketrepresents a significant market share in Latin America due to its relatively large pharmaceutical sector and expanding healthcare infrastructure. Demand is supported by the production and consumption of injectable medicines, vaccines, and other sterile pharmaceutical formulations. Continued development of local pharmaceutical manufacturing and increasing healthcare accessibility are expected to contribute to market growth.
Middle East & Africa Ampoules Packaging Market Trends
The ampoules packaging market in MEA is expected to register steady growth during the forecast period, supported by improving healthcare infrastructure, increasing pharmaceutical consumption, and expanding access to injectable medicines. The market generated approximately USD 255.6 million in 2025, representing a 5.3% revenue share. Investments in healthcare facilities, pharmaceutical manufacturing, and vaccine supply infrastructure are expected to support the adoption of sterile ampoule packaging across the region.
Key Ampoules Packaging Company Insights
Some key companies in the market include SCHOTT, Gerresheimer, Stevanato Group, SGD Pharma, Nipro, Corning Incorporated, Borosil, DWK Life Sciences, Accu-Glass, Essco Glass, Kapoor Glass India Pvt. Ltd., and Shandong Province Medicinal Glass Co., Ltd. The market is characterized by strong emphasis on pharmaceutical-grade glass manufacturing, dimensional precision, chemical resistance, sterility, and compatibility with automated filling and sealing processes. Key participants are focusing on expanding production capabilities, improving glass quality, developing specialized ampoule formats, and strengthening manufacturing technologies to meet the stringent requirements of pharmaceutical and injectable drug applications.
-
SCHOTT is a major pharmaceutical glass packaging manufacturer offering specialty glass solutions for injectable medicines and other sensitive pharmaceutical products. Its portfolio includes SCHOTT FIOLAX® glass tubing, which is used in the manufacture of pharmaceutical containers such as ampoules. The company focuses on high-quality glass materials, dimensional consistency, and advanced manufacturing technologies to support the safe storage and delivery of pharmaceutical formulations.
-
Gerresheimer is a global manufacturer of pharmaceutical primary packaging with a broad portfolio of glass containers, including ampoules for injectable applications. The company emphasizes high-quality pharmaceutical glass, precision manufacturing, and customized packaging solutions designed to meet stringent requirements for drug protection, sterility, and product integrity.
Key Ampoules Packaging Companies
The following key companies have been profiled for this study on the ampoules packaging market
-
SCHOTT
-
Gerresheimer
-
Stevanato Group
-
esscoglass
-
SGD Pharma
-
Nipro
-
Borosil
-
Kapoor Glass India Pvt. Ltd.
-
Accu-Glass
-
Corning Incorporated
-
Shandong Province Medicinal Glass Co., Ltd.
-
DWK Life Sciences
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (SCHOTT; Gerresheimer; Stevanato Group; SGD Pharma; Nipro; Corning Incorporated)
- Expand pharmaceutical ampoule portfolios through advanced glass manufacturing, automation, quality control, and capacity expansion. Focus on sterile packaging, dimensional consistency, and pharmaceutical compliance.
- Strong manufacturing scale, global presence, advanced glass-forming technology, established pharma customers, and broad packaging portfolios.
- High production costs, energy-intensive glass manufacturing, and stringent quality and regulatory requirements.
Emerging Players (Essco Glass; Borosil; Kapoor Glass India Pvt. Ltd.; Accu-Glass; Shandong Province Medicinal Glass Co., Ltd.; DWK Life Sciences)
- Focus on specialized ampoules, customized glass packaging, regional expansion, and improved manufacturing quality for pharmaceutical and laboratory applications.
- Flexible production, regional customer relationships, customized ampoule solutions, and specialized glass packaging expertise.
- Smaller production scale, limited global distribution, and lower brand visibility compared with established multinational players.
Recent Development
-
In July 2026, Gerresheimer started operations at its new pharmaceutical packaging plant in Zhenjiang-Dagang, China. The facility doubles the company’s production capacity for primary packaging for injectable pharmaceuticals and strengthens its regional manufacturing capabilities for pharmaceutical glass packaging.
-
In June 2026, SCHOTT Pharma inaugurated its expanded pharmaceutical glass production facility in Lebanon, Pennsylvania, U.S. The expansion strengthens local supply capabilities for pharmaceutical containers and supports growing demand for high-quality primary packaging for injectable medicines.
Ampoules Packaging Market Report Scope
Report Attribute
Details
Market size in 2025
USD 4.9 billion
Estimated market size in 2026
USD 5.2 billion
Projected market size by 2033
USD 8.7 billion
Growth rate
CAGR of 7.7% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Material, ampoule type, capacity, application, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; France; UK; Italy; Spain; China; India; Japan; South Korea; Australia; Brazil; Argentina; Saudi Arabia; UAE; South Africa
Key companies profiled
SCHOTT; Gerresheimer; Stevanato Group; esscoglass; SGD Pharma; Nipro; Borosil; Kapoor Glass India Pvt. Ltd.; Accu-Glass; Corning Incorporated; Shandong Province Medicinal Glass Co., Ltd.; DWK Life Sciences
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Ampoules Packaging Market Report Segmentation
This report forecasts revenue growth at the regional and country levels and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global ampoules packaging market report based on material, ampoule type, capacity, application, and region:
-
Material Outlook (Revenue, USD Billion, 2021 - 2033)
-
Glass
-
Plastic
-
-
Ampoule Type Outlook (Revenue, USD Billion, 2021 - 2033)
-
Straight-Stem
-
Funnel-Type
-
Closed/Form D
-
Easy-Open
-
-
Capacity Outlook (Revenue, USD Billion, 2021 - 2033)
-
≤2 mL
-
3-5 mL
-
6-10 mL
-
>10 mL
-
-
Application Outlook (Revenue, USD Billion, 2021 - 2033)
-
Injectable Drugs
-
Vaccines
-
Biologics
-
Diagnostic Reagents
-
Other Applications
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
France
-
UK
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Arabia
-
UAE
-
South Africa
-
-
Research Methodology
The ampoules packaging market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each ampoules packaging segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Material
Revenue capture definition
Glass
Revenue generated from the sale of glass ampoules, primarily manufactured from pharmaceutical-grade Type I borosilicate glass, used for packaging injectable drugs, vaccines, biologics, and diagnostic solutions. Includes straight-stem, funnel-type, closed-form, and other glass ampoules supplied to pharmaceutical and healthcare manufacturers.
Plastic
Revenue generated from the sale of plastic ampoules used for packaging pharmaceutical, healthcare, diagnostic, and specialty liquid formulations. Includes plastic ampoules designed for lightweight, break-resistant, single-dose, and easy-handling applications, where alternatives to conventional glass packaging are preferred.
Ampoule Type
Revenue capture definition
Straight-Stem
Revenue generated from the sale of straight-stem ampoules designed for pharmaceutical and healthcare applications, particularly for packaging injectable drugs, vaccines, and other sterile liquid formulations.
Funnel-Type
Revenue generated from the sale of funnel-type ampoules featuring an expanded upper section that facilitates filling and handling of pharmaceutical formulations, including injectable drugs and specialty solutions.
Closed/Form D
Revenue generated from the sale of closed or Form D ampoules designed with specialized neck and opening configurations to provide secure containment and controlled access for pharmaceutical and healthcare formulations.
Easy-Open
Revenue generated from the sale of easy-open ampoules incorporating opening systems such as break rings or scored necks that enable safe and convenient access to single-dose pharmaceutical formulations.
Capacity
Revenue capture definition
≤2 mL
Revenue generated from the sale of small-capacity ampoules with a volume of up to 2 mL, primarily used for single-dose injectable drugs, vaccines, and highly concentrated pharmaceutical formulations.
3-5 mL
Revenue generated from the sale of ampoules with capacities ranging from 3 to 5 mL, used for injectable drugs, biologics, vaccines, and other pharmaceutical liquid formulations requiring moderate fill volumes.
6-10 mL
Revenue generated from the sale of ampoules with capacities ranging from 6 to 10 mL, designed for larger-dose injectable medicines, diagnostic solutions, and other pharmaceutical liquid applications.
>10 mL
Revenue generated from the sale of ampoules with capacities above 10 mL, used for higher-volume pharmaceutical formulations, specialty injectable products, and selected healthcare and laboratory applications.
Application
Revenue capture definition
Injectable Drugs
Revenue generated from the sale of ampoules used for packaging injectable pharmaceutical drugs, including sterile liquid formulations intended for parenteral administration.
Vaccines
Revenue generated from the sale of ampoules used for packaging and protecting vaccine formulations, supporting sterile containment, storage, and administration requirements.
Biologics
Revenue generated from the sale of ampoules used for packaging biologic formulations, including sensitive injectable products requiring high-quality, chemically resistant primary packaging.
Diagnostic Reagents
Revenue generated from the sale of ampoules used to contain diagnostic reagents and laboratory solutions requiring controlled, secure, and contamination-resistant packaging.
Other Applications
Revenue generated from the sale of ampoules used in other applications, including veterinary medicines, specialty pharmaceuticals, laboratory chemicals, and healthcare formulations.
Estimation Model
Layer Name
Key Question
Description
Pharmaceutical Industry Layer
What drives demand?
Estimate demand from pharmaceutical and healthcare industries, including injectable drugs, vaccines, biologics, diagnostic reagents, and specialty formulations that require secure primary packaging.
Application Adoption Layer
Where are ampoules used?
Assess adoption of ampoules across injectable drugs, vaccines, biologics, diagnostic reagents, and other healthcare applications based on sterility, chemical resistance, protection, and single-dose packaging requirements.
Ampoule Consumption Layer
Which ampoule segments generate demand?
Evaluate consumption based on material, ampoule type, and capacity, including glass and plastic ampoules, straight-stem, funnel-type, closed/Form D, easy-open formats, and different fill-volume ranges.
Revenue Layer
How is revenue generated?
Revenue is generated through the sale of ampoules supplied to pharmaceutical and healthcare manufacturers for packaging injectable drugs, vaccines, biologics, diagnostic reagents, and other sterile liquid formulations.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Competitive Benchmarking
Comparative benchmarking of leading ampoules packaging companies based on material portfolio, ampoule types, manufacturing capabilities, product quality, sterile packaging expertise, geographic presence, R&D capabilities, and strategic developments.
Enables clients to assess competitor positioning, identify product and technology gaps, benchmark capabilities, and develop effective competitive strategies.
Pricing Analysis
Detailed assessment of ampoule packaging pricing across glass and plastic materials, considering manufacturing processes, raw material costs, ampoule capacity, ampoule type, quality requirements, sterilization needs, and regional supply-demand conditions.
Supports pricing strategy, procurement planning, supplier negotiations, cost optimization, and margin management across key markets.
Opportunity Assessment
Evaluation of growth opportunities across materials, ampoule types, capacities, applications, and regional markets, with particular focus on injectable drugs, vaccines, biologics, diagnostic reagents, and emerging pharmaceutical packaging requirements.
Helps clients identify high-potential segments, prioritize investments, target emerging applications, and develop market expansion strategies.
Frequently Asked Questions About This Report
The ampoules packaging market is primarily driven by increasing demand for injectable drugs, vaccines, and biologics, expansion of pharmaceutical manufacturing, rising healthcare expenditure, growing diagnostic applications, and stringent requirements for sterile and chemically resistant primary pharmaceutical packaging.
Asia Pacific dominated the ampoules packaging market with a 40.2% revenue share in 2025.
Asia Pacific is the fastest-growing region in the ampoules packaging market, with a CAGR of 8.2% over the forecast period.
The Plastic segment is the fastest-growing material segment in the ampoules packaging market, with a CAGR of 9.5% over the forecast period.
The Glass segment led the ampoules packaging market with an 85.3% revenue share in 2025.
The Straight-Stem segment led the ampoules packaging market with a 61.5% revenue share in 2025.
The Biologics segment is the fastest-growing application segment in the ampoules packaging market, with a CAGR of 8.3% over the forecast period.
The global ampoules packaging market size was valued at USD 4.9 billion in 2025 and is estimated at USD 5.2 billion for 2026.
The global ampoules packaging market is expected to grow at a CAGR of 7.7% from 2026 to 2033, reaching USD 8.7 billion by 2033.
About the Author(s)
Plastics, Polymers & Resins Research Team
Bulk Chemicals · Plastics, Polymers & ResinsThis report was authored by the plastics, polymers & resins research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the plastics, polymers & resins segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


