
- Home
- »
- Pharmaceuticals
- »
-
Angina Pectoris Drugs Market Size & Share Report, 2033GVR Report cover
![Angina Pectoris Drugs Market (2026 - 2033)Report]()
Angina Pectoris Drugs Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Stable Angina, Unstable Angina, Microvascular Angina, Prinzmetal Angina), By Drug Class, By Distribution Channel, By Region, And Segment Forecasts
Market Size, 2025
$12.9BMarket Estimate, 2026
$13.4BMarket Forecast, 2033
$17.6BCAGR, 2026–2033
4.0%Angina Pectoris Drugs Market Summary
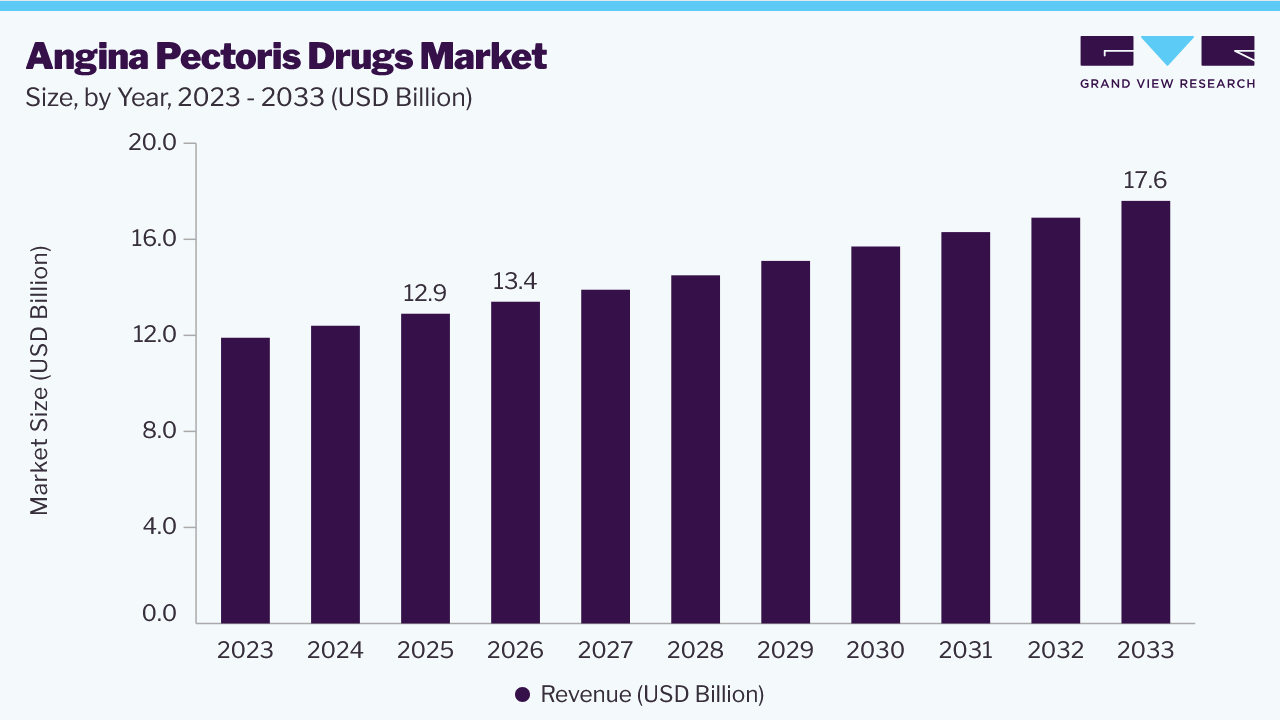
The global angina pectoris drugs market size was valued at USD 12.9 billion in 2025 and is projected to grow from USD 13.4 billion in 2026 to USD 17.6 billion by 2033, at a CAGR of 4.0% from 2026 to 2033. The North America dominated the global market, accounting for the largest revenue share of 40.0% in 2025. Advancements in personalized cardiovascular medicine and novel drug delivery systems are driving market expansion.
Key Market Trends & Insights
- By type: The stable angina segment held the largest market share of over 52.0% in 2025.
- By drug class: The beta blockers segment held the largest market share of over 38.5% in 2025.
- By distribution channel: The hospital pharmacies segment held the largest market share of over 48.5% in 2025.
Regional Highlights
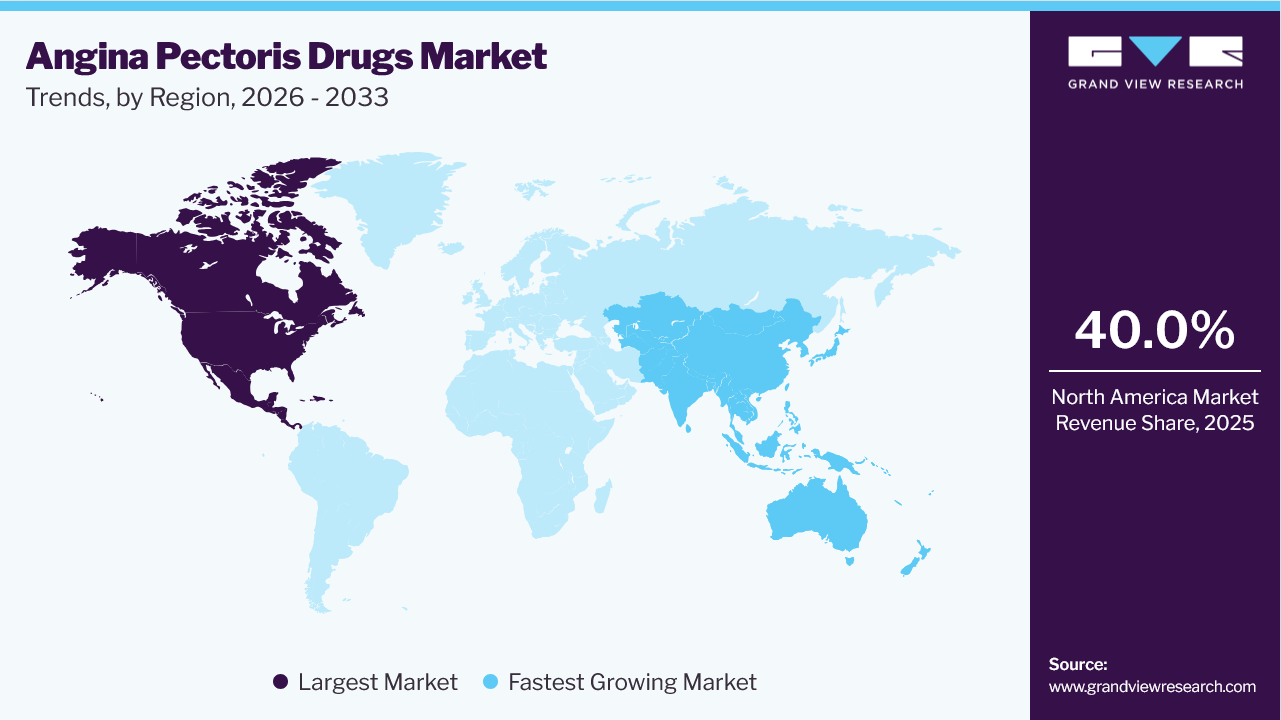
- Largest regional market: North America (40.0% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 12.9 Billion
- Estimated market size in 2026: USD 13.4 Billion
- Projected market size by 2033: USD 17.6 Billion
- CAGR (2026-2033): 4.0%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
A direct answer, usually in 1 working day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Moreover, worldwide market growth is fueled by the escalating prevalence of cardiac disorders, including coronary heart disease. Pharmaceutical companies are investing heavily in clinical trials to develop innovative treatments with improved efficacy, further propelling market growth. These developments are expected to significantly contribute to the market’s continued expansion.
The global angina pectoris drugs market is driven by a combination of factors, including the increasing occurrence of cardiovascular diseases worldwide. The growing demand for effective treatments is driven by the fact that cardiovascular diseases are a leading contributor to global mortality rates. Advances in drug delivery systems, such as transdermal patches and sustained-release formulations, are also boosting the efficiency and patient compliance of angina pectoris medications.
The growing geriatric population is another key driver of the market, as the elderly are more susceptible to cardiovascular diseases. This demographic shift presents an opportunity for pharmaceutical companies to develop targeted therapies that address the unique needs of older adults and improve their quality of life. Strategic partnerships and collaborations between pharmaceutical companies and research institutions are also driving market growth by advancing the development of innovative drug formulations and accelerating drug discovery.
Advancements in cardiology treatment, ongoing research and development efforts, and a growing number of drug approvals from regulatory bodies such as the FDA are also driving market growth. The rise in retail pharmacies and patient preference for purchasing angina drugs through these channels is creating market opportunities. As the global population continues to age, there will be increasing demand for effective treatments for angina pectoris, presenting an opportunity for pharmaceutical companies to develop and market new products to meet this growing need.
Analyst Perspective
The angina pectoris drugs market is experiencing steady growth, driven by the increasing prevalence of cardiovascular diseases, rising incidence of angina, and growing demand for effective cardiac therapies. Pharmacological management of angina cases, improvements in the quality of life of patients, and reduction in cardiovascular risks are majorly driving the adoption of these drugs by medical practitioners. Aging population trends, increased awareness about heart health, and developments in the cardiovascular medication sector are contributing to the growth in this market. Ongoing research into new treatment approaches and drug formulations is enhancing the efficacy of the therapy. As the demand for safe, efficient, and accessible cardiovascular treatment options continues to rise, companies that focus on innovation, clinical advancements, and patient-centric drug development will be well-positioned to capture long-term growth opportunities.
Type Insights
The stable angina segment held the largest market share of over 52.0% in 2025. The number of patients suffering from chronic stable angina is rising, and almost half of these patients have it as the initial sign of ischemic heart disease. Factors such as cold weather or physical exertion can trigger stable angina, contributing to the expansion of this particular group. The dominance of the stable angina segment can be attributed to several factors, including research and development, public awareness, and effective treatment options. In addition, the widespread availability of established pharmacological therapies, including beta blockers, calcium channel blockers, nitrates, and antiplatelet agents, has significantly improved symptom management and disease control in patients with stable angina. Growing emphasis on early diagnosis, risk factor management, and preventive cardiovascular care is also supporting treatment adoption and contributing to the continued growth of the segment.
The unstable angina segment is expected to grow at the fastest CAGR over the forecast period. The growing geriatric population, along with lifestyle choices such as smoking, poor eating habits, and lack of physical activity, are key factors contributing to the increasing prevalence of cardiovascular diseases (CVDs). This rise in CVD cases has led to a higher demand for angina pectoris medications, especially for unstable angina, a more severe form of the condition. With improved healthcare infrastructure, advancements in diagnostic tools, and increased awareness about CVDs, unstable angina is now being diagnosed at an earlier stage. This early detection enables timely treatment, which supports market growth.
Drug Class Insights
The beta blockers segment held the largest market share of over 38.5% in 2025. Segment growth is primarily driven by increasing adoption of the segment as a first-line therapy for angina pectoris. The aging population and strategic market developments among players to enhance the commercial availability of beta blockers also contribute to this growth. These medications reduce heart rate and weaken heart muscle contractions, making them a crucial treatment option for an increasingly aging population. For instance, in September 2025, results from the BETAMI and DANBLOCK clinical trials presented at the European Society of Cardiology (ESC) Congress showed that beta-blocker therapy reduced cardiovascular events in selected patients after myocardial infarction (MI) with preserved or mildly reduced left ventricular function. The trials evaluated beta-blocker use and demonstrated a reduction in the composite risk of all-cause mortality and major adverse cardiovascular events compared with no beta-blocker therapy.
The anticoagulants segment is expected to grow at a significant CAGR over the forecast period. The surge in cases of angina pectoris is propelling the expansion of the anticoagulant drug market, as these medications are frequently prescribed to prevent blood clots and subsequent cardiovascular complications in patients with this condition. The introduction of novel oral anticoagulants (NOACs) has revolutionized the market by offering safer and more effective alternatives to traditional warfarin, thereby driving market growth. In addition, increasing awareness regarding thrombotic risk management in patients with coronary artery disease supports the adoption of anticoagulant therapies as part of comprehensive cardiovascular care. Ongoing advancements in anticoagulant formulations, coupled with favorable clinical outcomes and reduced monitoring requirements associated with newer agents, are expected to further drive segment growth during the forecast period.
Distribution Channel Insights
The hospital pharmacies segment held the largest market share of over 48.5% in 2025. This can be attributed to the fact that hospitals equipped with advanced infrastructure and suitable facilities are witnessing a rise in the number of patients seeking treatment for angina pectoris disorders. In addition, the expansion of hospitals, tied with effective policies, is also playing a significant role in driving the growth of this particular segment. Hospital pharmacies ensure timely access to prescription medications and specialized cardiovascular therapies under the supervision of healthcare professionals, improving treatment adherence and patient outcomes. The increasing number of hospital admissions related to cardiovascular diseases and the availability of comprehensive diagnostic and treatment services are also expected to support the continued growth of the segment.
The online pharmacy segment is expected to grow at the fastest CAGR over the forecast period. Online pharmacies have emerged as a convenient way to obtain angina pectoris medications. These platforms enable patients to order medicines from the comfort of their homes, offering a diverse range of options, including customized treatments for angina pectoris. Competitive pricing and home delivery services further facilitate access to medication, particularly for patients with mobility limitations. In addition, the growing adoption of digital healthcare platforms, increasing internet penetration, and rising consumer preference for contactless purchasing are contributing to the rapid expansion of online pharmacies. The availability of prescription refill services, medication reminders, and teleconsultation support is further enhancing patient convenience and supporting segment growth.
Regional Insights
The North America angina pectoris drugs industry dominated the global market, accounting for over 40.0% of revenue in 2025. The increasing demand for minimally invasive procedures is expected to drive the market’s growth in the forecast period. In addition, the market is also being driven by factors such as unhealthy lifestyles, favorable regulatory actions, and a rise in cardiac diseases. The presence of a well-established healthcare infrastructure, high awareness regarding cardiovascular health, and strong adoption of advanced therapeutic options further support market growth in the region. Moreover, increasing investments in cardiovascular research and the availability of reimbursement coverage for prescription medications are contributing to improved patient access to angina treatments.
U.S. Angina Pectoris Drugs Market Trends
The angina pectoris drugs industry in the U.S. is poised to experience substantial growth during the forecast period, driven by increasing awareness about the condition, improved accessibility of treatments, and favorable insurance coverage. As a result, patients in the U.S. are opting for prescribed therapies, thereby driving the market’s expansion.
Europe Angina Pectoris Drugs Market Trends
The angina pectoris drugs industry in Europe expects lucrative opportunities over the forecast period. Market growth is aided by the increasing number of patients with cardiovascular diseases, technological advancements, awareness, government initiatives, and hospital research on the angina pectoris drug. In addition, the rising geriatric population is one factor driving market growth.
The Germany angina pectoris drugs industry is anticipated to experience rapid growth during the forecast period, driven by the increasing prevalence of cardiovascular diseases among the elderly. Factors such as a sedentary lifestyle, smoking, and other unhealthy habits are contributing to the rise in cardiovascular diseases, leading to a greater demand for angina pectoris treatments in Germany.
The angina pectoris drugs industry in the UK is showing significant growth in the forecast period. Rising awareness about angina pectoris and its risk factors, combined with public health programs designed to educate about cardiovascular health, is expected to fuel the need for angina pectoris medications in the UK.
Asia Pacific Angina Pectoris Drugs Market Trends
The angina pectoris drugs industry in the Asia Pacific is expected to register the fastest CAGR over the forecast period. The rise in urbanization, changing lifestyles, and the increasing occurrence of risk factors such as cardiovascular diseases have driven the need for angina pectoris drugs in countries such as China, India, and Japan. As healthcare expenditures continue to rise and the emphasis on preventive care grows, the demand for these medications is on the rise. Furthermore, the growing geriatric population and increasing prevalence of hypertension, diabetes, and obesity are contributing to the rising burden of coronary artery disease across the region. Expanding healthcare infrastructure, improved access to healthcare services, and increasing awareness regarding early diagnosis and treatment of cardiovascular conditions are expected to further support market growth during the forecast period.
The China angina pectoris drugs industry is projected to experience significant growth during the forecast period, primarily driven by the country’s rapidly aging population and rising prevalence of unhealthy dietary habits. The growing incidence of cardiovascular diseases among the elderly population, coupled with a lack of awareness about healthy lifestyles, is expected to fuel the demand for angina pectoris treatments in China.
The angina pectoris drugs industry in India is anticipated to witness significant growth in the forecast period as increased awareness of cardiovascular diseases and the importance of early checkups and treatment lead more individuals to get medical consultations. In addition, government initiatives and awareness programs drive the market growth.
Key Angina Pectoris Drugs Company Insights
The global angina pectoris drugs market is characterized by a competitive landscape featuring established pharmaceutical giants and emerging biotechnology firms, such as Amgen Inc., Bayer AG, Eli Lilly and Company, Gilead Sciences, Inc., and Merck & Co., Inc. Strategic collaborations, partnerships, and licensing agreements drive innovation, while mergers and acquisitions consolidate resources to accelerate drug development and commercialization efforts.
- Amgen Inc. utilizes living cells to create biologic medicines. These medicines play a crucial role in treating serious illnesses and address diseases with a limited number of treatment options. By concentrating on areas with substantial unmet medical needs.
- Gilead Sciences manufactures medications for serious illnesses. The company places a significant emphasis on scientific research.
Key Angina Pectoris Drugs Companies
The following key companies have been profiled for this study on the angina pectoris drugs market:
-
Pfizer Inc.
-
Bayer AG
-
AstraZeneca
-
Gilead Sciences, Inc.
-
Novartis AG
-
GSK plc.
-
Merck & Co., Inc.
-
Amgen Inc.
-
Lilly USA, LLC
-
Otsuka Pharmaceutical Co., Ltd.
-
Sanofi S.A.
-
Boehringer Ingelheim International GmbH
Recent Developments
- In November 2025, Novartis and AC Health entered a partnership for integrated cardiovascular and cancer care, with the objective of expanding access to innovative medicines in the areas of cancer, cholesterol, and heart failure, as well as empowering patients through this collaborative effort.
- In February 2025, Novartis announced the acquisition of Anthos Therapeutics for USD 925 million to strengthen its cardiovascular pipeline. The acquisition included abelacimab, a Phase III monoclonal antibody targeting Factor XI inhibition, a pathway being investigated for reducing thrombotic cardiovascular events.
- In July 2023, Riparian Pharmaceuticals partnered with Pfizer to advance novel cardiovascular programs, granting Pfizer exclusive rights to a preclinical program to support Riparian’s efforts to discover further drug targets for vasoprotection.
Angina Pectoris Drugs Market Report Scope
Report Attribute
Details
Market size in 2025
USD 12.9 billion
Estimated market size in 2026
USD 13.4 billion
Projected market size by 2033
USD 17.6 billion
Growth rate
CAGR of 4.0% from 2026 to 2033
Base year for estimation
2025
Actual data
2021 – 2024
Forecast period
2026 – 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, drug class, distribution channel, region
Regional Scope
North America; Europe; Asia Pacific; Latin America; MEA
Country Scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Sweden; Norway; Japan; China; India; Australia; South Korea; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
Pfizer Inc.; Bayer AG; AstraZeneca; Gilead Sciences, Inc.; Novartis AG; GSK plc.; Merck & Co., Inc.; Amgen Inc.; Lilly USA, LLC; Otsuka Pharmaceutical Co., Ltd.; Sanofi S.A.; Boehringer Ingelheim International GmbH
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Angina Pectoris Drugs Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global angina pectoris drugs market report by type, drug class, distribution channel, and region:
-
Type Outlook (Revenue, USD Billion, 2021 - 2033)
-
Stable Angina
-
Unstable Angina
-
Microvascular Angina
-
Prinzmetal Angina
-
-
Drug Class Outlook (Revenue, USD Billion, 2021 - 2033)
-
Beta Blockers
-
Calcium Antagonists
-
Nitrates
-
Anticoagulants
-
Anti-Platelets
-
Other Drug Classes
-
-
Distribution Channel Outlook (Revenue, USD Billion, 2021 - 2033)
-
Hospital Pharmacy
-
Retail Pharmacy
-
Online Pharmacy
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Frequently Asked Questions About This Report
The global angina pectoris drugs market size was valued at USD 12.9 billion in 2025 and is estimated at USD 13.4 billion for 2026.
The global angina pectoris drugs market is expected to grow at a CAGR of 4.0% from 2026 to 2033, reaching USD 17.6 billion by 2033.
Some key players operating in the angina pectoris drugs market include Amgen, Inc., Sanofi S.A., Gilead Sciences, Inc., AstraZeneca Plc, GlaxoSmithKline Plc., Eli Lilly and Company, Pfizer, Inc., Novartis AG, XyloCor Therapeutics, Inc., and Tasly Pharmaceuticals, Inc.
North America dominated with an over 40.0% revenue share in 2025.
The stable angina segment accounted for the largest revenue share of over 52.0% in 2025.
About the Author(s)
Pharmaceuticals Research Team
Healthcare · PharmaceuticalsThis report was authored by the pharmaceuticals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the pharmaceuticals segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst


Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


