
- Home
- »
- Pharmaceuticals
- »
-
Anti-obesity Medication Market Size & Share Report, 2033GVR Report cover

Anti-obesity Medication Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Approved, Off-label), By Mechanism Of Action (Peripherally Acting Drugs, Centrally Acting Drugs), By Distribution Channel (Retail Pharmacies, Hospital Pharmacies), By Region, And Segment Forecasts
Market Size, 2025
$19.5BMarket Estimate, 2026
$25.7BMarket Forecast, 2033
$176.4BCAGR, 2026–2033
31.7%Anti-obesity Medication Market Summary
The global anti-obesity medication market size was valued at USD 19.5 billion in 2025 and is projected to grow from USD 25.7 billion in 2026 to USD 176.4 billion by 2033, growing at a CAGR of 31.7% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 37.0% in 2025. Increasing awareness of the health consequences of being overweight fuels market growth. In addition, the rising adoption of highly effective GLP-1 receptor agonists and next-generation weight loss therapies is significantly accelerating market expansion.
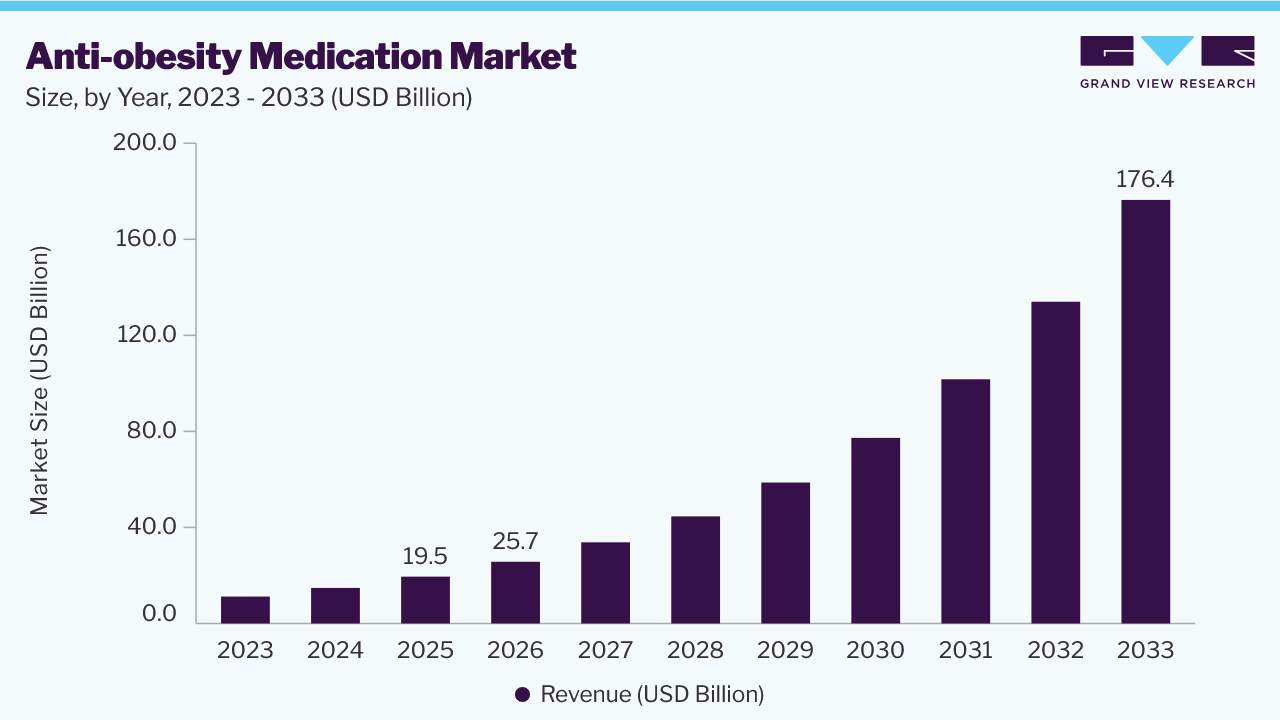 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: The approved product segment dominated the market with a revenue share of about 37.0% in 2025.
- By mechanism of action: The peripherally acting anti-obesity drugs segment held the largest revenue share of over 59.0% in 2025.
- By distribution channel: The retail pharmacies segment held the largest revenue share of over 55.0% in 2025.
Regional Insights
- Largest regional market: North America (37.0% revenue share, 2025)
Market Size & Forecast
- Market size in 2025: USD 19.5 Billion
- Estimated market size in 2026: USD 25.7 Billion
- Projected market size by 2033: USD 176.4 Billion
- CAGR (2026-2033): 31.7%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Accelerated development of anti-obesity drugs, supported by significant R&D investments, is expected to drive market growth. With advancements in drug development technologies, the market is poised for further growth, addressing the pressing need to combat overweight-related health challenges. In March 2025, the World Obesity Federation published the World Obesity Atlas, which projects that the number of obese adults will grow by more than 115% from 2010 to 2030, rising from 524 million to around 1.13 billion. The report states that two-thirds of countries lack most key national obesity policies, and only 7% have health systems adequately prepared to address obesity.
Furthermore, overweight and obesity are associated with approximately 1.6 million premature deaths annually from conditions including diabetes, cancer, heart disease, and stroke. The growing burden of obesity and inadequate healthcare preparedness is expected to accelerate demand for pharmacological interventions, thereby supporting market expansion. Moreover, the projected increase in obesity prevalence directly correlates with market growth, creating opportunities for pharmaceutical companies, healthcare providers, and other stakeholders. As healthcare costs associated with obesity continue to escalate, there is a growing imperative for innovative solutions and interventions to curb this epidemic and ensure sustainable healthcare cost containment.
Market players are actively investing in R&D to develop innovative medicines for weight management. For instance, in October 2025, Eli Lilly reported successful topline results from the Phase III trial, in which oral GLP-1 receptor agonist orforglipron achieved significant weight reduction and improvements in cardiometabolic risk factors in adults with obesity or overweight. These advancements are expected to intensify competition, broaden therapeutic options, and accelerate market growth.
The introduction of new medications such as CagriSema, Oral Sema Obesity, GELA, INV-202, and orforglipron is propelling the market growth. Investing in this sector enables companies to seize opportunities arising from evolving demands and gain a competitive edge. Leading the development and commercialization of innovative medications positions companies as frontrunners, consolidating their market presence.
Analyst Perspective
The global obesity treatment market is expected to grow strongly, driven by rising obesity prevalence and increasing adoption of conventional and advanced incretin-based therapies, including GLP-1, dual, and triple agonists. Strong clinical outcomes from semaglutide and tirzepatide are expanding treatment adoption among adults and adolescents. Advances in oral formulations, combination therapies, R&D, and regulatory approvals are further supporting growth. Despite affordability, reimbursement, and supply challenges, expanding distribution through hospitals, retail pharmacies, and online channels is expected to sustain long-term market expansion.
Product Insights
The approved product segment held a dominant revenue share in 2025 and is expected to grow at a significant CAGR from 2026 to 2033. This dominance is due to the accessibility of therapeutically effective weight management drugs, the rising prevalence of overweight, and the high consumption of approved anti-obesity medications. Approved medications such as Zepbound, Wegovy, Saxenda, Orlistat, and Qsymia have undergone rigorous clinical trials and received FDA approval. These drugs are specifically formulated and indicated for the treatment of weight-related medical conditions, with well-established safety and efficacy profiles. The dominance of the approved segment is also attributed to the effectiveness and safety of these medications, as well as to pharmaceutical companies' strategic initiatives and the launch of advanced new products, thereby increasing the adoption of these drugs.
The off-label segment comprises medications that are not specifically approved for obesity treatment but are increasingly prescribed for weight management based on physician discretion. Common off-label medications include Ozempic, Victoza, Trulicity, and Topiramate. Segment growth is driven by increasing physician adoption, strong clinical evidence supporting weight-loss outcomes, and rising demand for accessible alternatives to approved anti-obesity therapies. The growing adoption of these off-label therapies for weight management is further supporting segment growth, as they offer effective pharmacological alternatives for treating obesity.
Mechanism Of Action Insights
The peripherally acting anti-obesity drugs segment accounted for the largest revenue share of approximately 59.0% in 2025. The substantial share can be attributed to this mechanism's ability to enhance nutrient absorption and reduce hunger. These drugs work by blocking fat absorption in the intestines, thereby reducing calorie intake and promoting weight loss. The dominance of this segment is also attributed to the effectiveness of these drugs in promoting a sense of fullness without causing side effects commonly associated with appetite suppressants. Moreover, their mechanism of action allows for less reliance on calorie restriction and physical activity, making them appealing to patients seeking convenient and sustainable weight-management solutions.
The market for centrally acting drugs is expected to grow at a lucrative CAGR over the forecast period. Centrally acting drugs in the anti-obesity market target the central nervous system to regulate appetite, reduce food cravings, and promote weight loss. These drugs, such as CONTRAVE (naltrexone/bupropion), phentermine, and diethylpropion, work by modulating neurotransmitter activity associated with hunger, satiety, and reward pathways. The growth of this segment can be attributed to its ability to provide a sense of fullness and reduce calorie intake, supporting long-term weight management. For instance, in April 2026, Currax Pharmaceuticals expanded patient access to CONTRAVE through its partnership with PeekDirect, improving affordability and access to the centrally acting obesity therapy for self-funded employers and patients. Furthermore, their mechanism of action aligns with lifestyle changes integral to weight management programs, making them a preferred choice for many individuals.
Distribution Channel Insights
Retail pharmacies dominated the distribution channel segment in 2025 with a revenue share of approximately 55.0%. These outlets offer convenient access to anti-obesity medications through their extensive presence across urban and rural communities. For instance, in 2025, CVS Pharmacy expanded access to Wegovy through its pharmacy-benefit and retail channels, improving patient access to prescription weight-loss treatment. The widespread availability of blockbuster GLP-1 therapies through retail pharmacy networks continues to support the dominance of this segment. Retail pharmacies provide a trusted environment for patients seeking obesity and weight management treatment, enabling timely prescription fulfillment, improved product accessibility, and pharmacist guidance on medication adherence and lifestyle modification.
Hospital pharmacies also play a significant role, particularly in managing severe obesity or patients with comorbidities that require specialized care. These pharmacies are integral in dispensing medications prescribed by healthcare professionals within hospital settings, ensuring continuity of care and adherence to treatment protocols. The growth of this segment is further supported by the increasing number of patients requiring multidisciplinary obesity management, including endocrinology, cardiology, and bariatric care services within hospital settings. In addition, rising hospital admissions associated with obesity-related conditions such as type 2 diabetes, cardiovascular diseases, and hypertension are contributing to greater demand for anti-obesity medications through hospital pharmacies.
Regional Insights
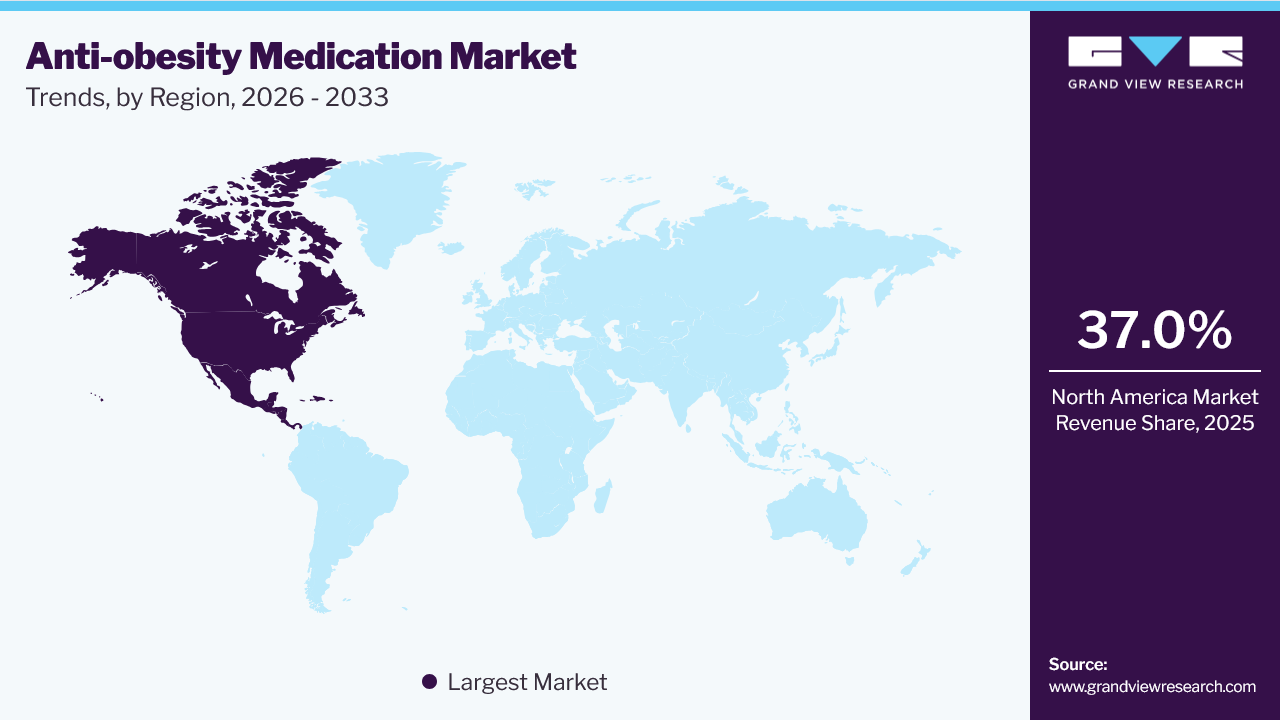
North America dominated the market, accounting for approximately 37.0% of revenue in 2025. The region’s dominance can be attributed to the high prevalence of obesity, strong healthcare infrastructure, and increasing adoption of advanced anti-obesity therapies. Supportive reimbursement frameworks, rising awareness regarding obesity management, and favorable regulatory approvals are further accelerating regional market growth. Key market players such as Novo Nordisk, Eli Lilly and Company, Roche, and Currax Pharmaceuticals further strengthen the competitive landscape. Strategic initiatives such as mergers, acquisitions, and partnerships among pharmaceutical companies are actively shaping market expansion. For instance, in December 2023, Roche acquired Carmot Therapeutics for USD 2.7 billion to gain access to promising clinical-stage obesity drugs, including CT-388, CT-996, and CT-868. In addition, the strong uptake of GLP-1 therapies across the U.S. and Canada continues to support North America’s market leadership.
U.S. Anti-Obesity Medication Market Trends
The anti-obesity medication market in the U.S. is expected to grow steadily over the forecast period, driven by a strong pharmaceutical industry, with leading players such as Eli Lilly and Company and Novo Nordisk driving innovation in GLP-1 and next-generation obesity therapies. Rising obesity prevalence, increasing awareness regarding obesity as a chronic disease, and growing physician adoption of prescription weight-loss medications are further supporting market growth. In addition, expanding insurance coverage, favorable reimbursement policies, and ongoing advancements in obesity drug development are expected to improve treatment accessibility and accelerate market expansion in the country.
 To learn more about this report, Download Free Sample Report
Europe Anti-Obesity Medication Market Trends
The anti-obesity medication market in Europe presents significant growth opportunities, driven by rising obesity prevalence, increasing awareness of obesity as a chronic disease, and growing adoption of advanced pharmacological treatments. The region is witnessing increasing demand for GLP-1 receptor agonists and other next-generation anti-obesity therapies due to their strong clinical efficacy in weight management. Favorable regulatory support and growing physician awareness are further contributing to market expansion across major European countries. However, limited reimbursement coverage and restricted access to obesity treatments under public healthcare systems remain key challenges, affecting affordability and patient access in several markets. Despite these constraints, continued innovation in obesity drug development and increasing focus on long-term weight management are expected to support steady market growth in Europe.
The UK anti-obesity medication market is at a turning point with the limited launch of Wegovy, targeting individuals with obesity or at risk of type 2 diabetes through specialist NHS services. A pilot program explores broader access to prescriptions amid supply issues affecting GLP-1 RAs such as Ozempic and Wegovy, at least through 2025. Rising obesity prevalence and increasing burden of obesity-related conditions, including type 2 diabetes, are driving demand for pharmacological weight management solutions in the UK. Expanding NHS-backed access programs and the introduction of innovative GLP-1 therapies such as Wegovy are further supporting market growth.
The anti-obesity medication market in France is poised for growth despite challenges. The heightened surveillance by the French National Agency for the Safety of Medicines (ANSM) and Assurance Maladie of Ozempic, due to its misuse for weight loss, highlights the need for effective regulation. Social media influence and forged prescriptions indicate non-diabetic usage for weight loss, prompting ANSM to emphasize Ozempic's intended use solely for diabetes treatment. Increasing awareness of obesity-related health risks and rising adoption of GLP-1 receptor agonists are driving market growth in France. Strengthened regulatory monitoring and efforts to curb misuse are supporting the safe and sustainable expansion of anti-obesity therapies.
Germany anti-obesity medication market is experiencing significant growth, driven by rising obesity prevalence, robust pharmaceutical R&D, and increasing adoption of next-generation weight-loss therapies. For instance, in 2024, Boehringer Ingelheim and Zealand Pharma continued advancing survodutide in late-stage clinical development, strengthening Germany’s position in obesity drug innovation. Clinical studies demonstrated significant weight reduction, highlighting the strong potential of next-generation obesity therapies.
Asia Pacific Anti-Obesity Medication Market Trends
The anti-obesity medication market in the Asia-Pacific is set for significant growth, propelled by rising obesity rates and government initiatives in countries such as China, Japan, and India. Pharmaceutical firms are investing in research. For instance, in February 2024, Innovent Biologics announced the NMPA's acceptance of the mazdutide NDA for the treatment of overweight in China, showcasing Phase 3 trial success with weight reduction and cardiometabolic benefits, potentially revolutionizing anti-obesity pharmacotherapy. In addition, advancements in drug development technology enhance treatment options. Co-occurring health issues linked to obesity underscore the urgent need for sophisticated medications. This collective effort signifies a burgeoning market, driven by the regional commitment to combat overweight and pharmaceutical innovation, poised to meet the escalating demand for effective anti-obesity treatments.
China anti-obesity medication market is expected to grow over the forecast period. The rising prevalence of obesity, driven by changing lifestyles and a large population, underscores the urgent need for effective treatments. Government initiatives prioritize addressing this health crisis, supporting research and treatment development. A large patient population and lifestyle changes associated with urbanization are creating strong demand for anti-obesity medications in China. Favorable government initiatives and expanding focus on metabolic health are supporting the development and adoption of novel therapies.
The anti-obesity medication market in India is expected to grow significantly over the forecast period, driven by rising obesity prevalence, increasing awareness regarding weight management, and growing adoption of pharmacological treatments. The market is expanding rapidly, supported by increasing urbanization, sedentary lifestyles, and changing dietary habits, which are contributing to a higher burden of obesity across the country. Anti-obesity medications available in India include orlistat, liraglutide, semaglutide, and tirzepatide, offering a broad range of treatment options for weight management. Growing participation from domestic pharmaceutical companies, increasing availability of GLP-1 therapies, and improving access to advanced anti-obesity drugs are further supporting market expansion. In addition, rising healthcare expenditure and growing physician acceptance of obesity as a chronic disease are expected to accelerate market growth in India.
Japan's anti-obesity medication market is expected to grow over the forecast period, driven by increasing awareness of obesity-related health risks and rising demand for effective weight-management therapies. Although Japan has a relatively lower obesity prevalence compared to other developed countries, growing concerns regarding visceral obesity and metabolic syndrome are contributing to increasing demand for anti-obesity medications. The market is further supported by strong preventive healthcare initiatives, rising physician awareness, and increasing adoption of advanced pharmacological treatments for weight management. Favorable regulatory developments and growing demand for convenient treatment options are also expected to support market expansion in Japan.
Latin America Anti-Obesity Medication Market Trends
The anti-obesity medication market in Latin America is expected to grow over the forecast period due to the high prevalence of obesity. An increase in healthcare spending and a robust pharmaceutical industry are other significant factors driving growth in the regional market. The increasing incidence of obesity and metabolic disorders is creating a strong demand for effective weight management therapies across Latin America. Growing healthcare investments and enhanced availability of pharmaceutical products are supporting market expansion.
Brazil anti-obesity medication market is expected to grow significantly over the forecast period, driven by rising obesity prevalence, increasing awareness of weight management, and growing demand for pharmacological treatments for obesity. Brazil has one of the largest obese populations in Latin America, creating strong demand for effective weight-loss therapies. The market is witnessing increasing adoption of GLP-1-based therapies such as Saxenda and newer anti-obesity medications, particularly through private healthcare channels. Rising healthcare expenditure, improving access to advanced obesity treatments, and increasing physician awareness of obesity as a chronic disease are further supporting market expansion. Despite limited reimbursement coverage, continued efforts by pharmaceutical companies to expand product availability and improve treatment accessibility are expected to drive market growth in Brazil.
Middle East & Africa Anti-Obesity Medication Market Trends
The anti-obesity medication market in MEA is expected to grow over the forecast period due to the high prevalence of obesity and increasing healthcare spending. With the growing middle class and changing dietary habits, demand for effective therapeutic measures is increasing. The fast-track designation of tirzepatide for obesity treatment and the positive opinion on Wegovy for chronic weight management highlight the evolving market landscape. The current pipeline of market players indicates a surge in R&D activities to meet demand for novel anti-obesity drugs. Rising obesity rates, changing lifestyles, and increasing healthcare investments are creating strong demand for effective weight management therapies across the Middle East and Africa. Growing R&D activity and the introduction of innovative GLP-1-based treatments are further supporting regional market growth.
South Africa anti-obesity medication market is expected to grow steadily over the forecast period, driven by the high prevalence of obesity and its increasing burden on public health and the economy. Rising urbanization, sedentary lifestyles, and changing dietary patterns are contributing to increasing obesity rates, creating a strong demand for effective weight management solutions. The growing burden of obesity-related comorbidities, including type 2 diabetes and cardiovascular diseases, is further accelerating demand for anti-obesity medications in the country. In addition, expanding access to innovative weight-loss therapies and increasing focus on reducing obesity-related healthcare costs are expected to support market growth in South Africa.
Key Anti-Obesity Medication Company Insights
Some of the leading market players include Novo Nordisk, Eli Lilly and Company, Roche, VIVUS LLC, Currax Pharmaceuticals, and Boehringer Ingelheim. Market participants are adopting various strategies to strengthen their market position, including product launches, regulatory approvals, strategic collaborations, and expansion of manufacturing capabilities. Companies are also focused on expanding their geographic presence and improving patient access to anti-obesity therapies, particularly in emerging markets.
Emerging players such as Rhythm Pharmaceuticals, Viking Therapeutics, and Structure Therapeutics are actively pursuing strategic initiatives, including partnerships, pipeline expansion, and the clinical development of next-generation obesity therapies. These companies are focusing on innovative treatment approaches, including oral therapies, GLP-1 receptor agonists, and dual- and triple-agonists, to strengthen their competitive position in the market.
Key Anti-Obesity Medication Companies
The following key companies have been profiled for this study on the anti-obesity medication market:
-
Novo Nordisk A/S
-
Lilly USA, LLC
-
Amgen Inc.
-
Pfizer Inc.
-
Boehringer Ingelheim International GmbH
-
Rhythm Pharmaceuticals, Inc.
-
Currax.
-
VIVUS LLC.
-
Viking Therapeutics
-
Structure Therapeutics Inc.
Recent Developments
- In April 2026, Boehringer Ingelheim announced positive Phase III topline results for survodutide, showing up to 16.6% weight loss over 76 weeks in patients with obesity or overweight. The results strengthened its position in the late-stage obesity drug pipeline.
- In December 2024, the U.S. FDA approved Zepbound (tirzepatide) as the first and only prescription medicine for moderate-to-severe obstructive sleep apnea (OSA) in adults with obesity. The approval was based on results from the Phase III SURMOUNT-OSA trials, in which adults receiving Zepbound experienced up to 20% weight loss and at least 25 fewer breathing interruptions per hour during sleep. This marked the first drug approval for OSA and expanded the clinical utility of Zepbound beyond chronic weight management
Anti-Obesity Medication Market Report Scope
Report Attribute
Details
Market size in 2025
USD 19.5 billion
Estimated market size in 2026
USD 25.7 billion
Projected market size by 2033
USD 176.4 billion
Growth rate
CAGR of 31.7% from 2026 to 2033
Actual data
2021 – 2025
Forecast period
2026 – 2033
Quantitative units
Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, mechanism of action, distribution channel, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; UK; Germany; Spain; Denmark; Sweden; Norway; France; Italy; China; India; Japan; Thailand; South Korea; Australia; Brazil; Mexico; Argentina; South Africa; Saudi Arabia; UAE; Kuwait.
Key companies profiled
Novo Nordisk; Lilly USA, LLC; Amgen; Pfizer; Boehringer Ingelheim; Rhythm Pharmaceuticals; Currax Pharmaceuticals; VIVUS LLC; Viking Therapeutics; Structure Therapeutics
Customization scope
Free report customization (equivalent to up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Anti-Obesity Medication Market Segmentation
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global anti-obesity medication market report based on product, mechanism of action, distribution channel, and region:
-
Product Outlook (Revenue, USD Billion, 2021 - 2033)
-
Approved
-
Bupropion-naltrexone (Contrave)
-
Liraglutide (Orlistat)
-
Orlistat
-
Xenical
-
Alli
-
-
Phentermine-topiramate (Qsymia)
-
Semaglutide (Wegovy)
-
Setmelanotide (Imcivree)
-
Tirzepatide (Zepbound)
-
-
Off Label
-
Semaglutide (Xenical Alli)
-
Liraglutide (Semaglutide (Wegovy))
-
Dulaglutide (Trulicity)
-
Topiramate (Dulaglutide (Trulicity))
-
Others
-
-
-
Mechanism of Action Outlook (Revenue, USD Billion, 2021 - 2033)
-
-
Peripherally Acting Drugs
-
Centrally Acting Drugs
-
-
Distribution Channel Outlook (Revenue, USD Billion, 2021 - 2033)
-
Retail Pharmacies
-
Hospital Pharmacies
-
Others
-
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
-
Europe
-
Germany
-
UK
-
Spain
-
France
-
Italy
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
South Korea
-
Australia
-
Thailand
-
-
Latin America
-
Brazil
-
Mexico
-
Argentina
-
-
MEA
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Frequently Asked Questions About This Report
Key players in the market include Novo Nordisk, Lilly USA, LLC, Amgen, Pfizer, Boehringer Ingelheim, Rhythm Pharmaceuticals, Currax Pharmaceuticals, VIVUS LLC, Viking Therapeutics, Structure Therapeutics, and others.
The retail pharmacies segment accounted for the largest revenue share of approximately 55.0% in 2025.
The global anti-obesity medication market size was valued at USD 19.5 billion in 2025 and is estimated at USD 25.7 billion for 2026.
The global anti-obesity medication market is expected to grow at a CAGR of 31.7% from 2026 to 2033, reaching USD 176.4 billion.
North America dominated with an approximately 37.0% revenue share in 2025.
About the Author(s)
Pharmaceuticals Research Team
Healthcare · PharmaceuticalsThis report was authored by the pharmaceuticals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the pharmaceuticals segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


