
- Home
- »
- Clinical Diagnostics
- »
-
Antimicrobial Resistance Diagnostics Market Report, 2033GVR Report cover

Antimicrobial Resistance Diagnostics Market (2026 - 2033)
Size, Share & Trends Analysis Report By Technology (Microbiology Culture, Immunoassay, PCR, NGS, Mass Spectrometry), By Pathogen, By End Use (Hospitals, Diagnostic Laboratories), By Region, And Segment Forecasts
Market Size, 2025
$3.4BMarket Estimate, 2026
$3.5BMarket Forecast, 2033
$4.7BCAGR, 2026–2033
4.1%Antimicrobial Resistance Diagnostics Market Summary
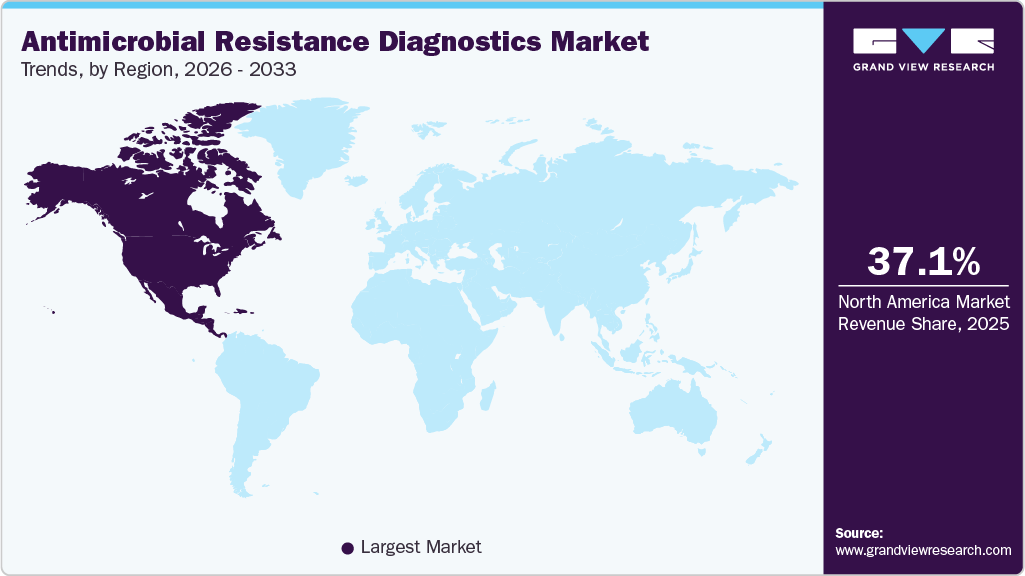
The global antimicrobial resistance diagnostics market size was valued at USD 3.4 billion in 2025 and is projected to grow from USD 3.5 billion in 2026 to USD 4.7 billion by 2033, at a CAGR of 4.1% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 37.1% in 2025. The high prevalence of pathogens such as Streptococcus pneumoniae, MRSA, and C. difficile, along with the increasing number of antimicrobial-resistant (AMR) infections, is significantly driving market expansion.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By technology: Microbiology culture segment led the market with the largest revenue share of 51.7% in 2025
- By pathogen: Methicillin resistant staphylococcus aureus (MRSA) segment led the market with the largest revenue share of 20.9% in 2025.
- By end use: Hospitals segment led the market with the largest revenue share of 58.2% in 2025.
Regional Highlights
- Largest regional market: North America (37.1% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 3.4 Billion
- Estimated market size in 2026: USD 3.5 Billion
- Projected market size by 2033: USD 4.7 Billion
- CAGR (2026-2033): 4.1%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
According to the CDC, approximately 2.8 million AMR cases occur annually in the U.S., and the U.S. Pharmacopeial Convention reports that AMR leads to around 700,000 deaths globally each year. This number could potentially rise to 10 million by 2050 if proper diagnosis and treatment of microbial infections are not implemented.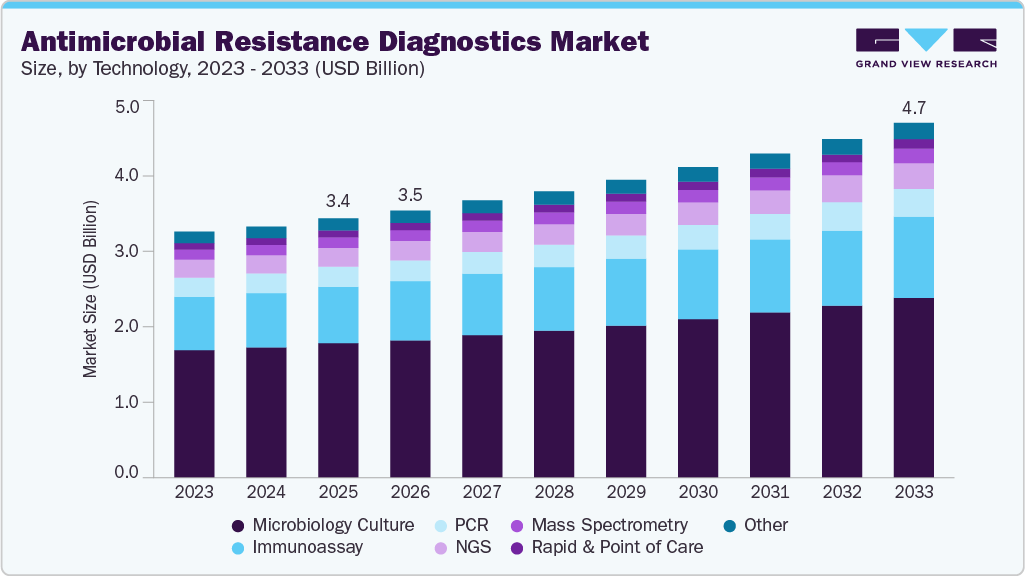 To learn more about this report, Download Free Sample Report
The rise in regulatory approvals for advanced and accurate diagnostic solutions is expected to meet the growing demand in the market. For example, in October 2021, Hologic, Inc. launched the fully automated Novodiag molecular diagnostic system from Mobidiag Oy in Europe. This system, which integrates microarray and real-time PCR technology, enables on-demand testing for antimicrobial resistance and infectious diseases, identifying multiple pathogens from a single sample. Additionally, in the same month, OpGen, Inc. received 510(k) clearance from the U.S. FDA to market its Acuitas AMR Gene Panel. This panel tests for 28 genetic antimicrobial resistance markers across various pathogens, aiding healthcare providers in managing resistant bacterial infections.
Recent surveillance-based prevalence of key drug-resistant pathogens
Pathogen
Metric (value)
Drug Resistant Streptococcus pneumoniae (DRSP)
Penicillin non-susceptibility 49.9% (non-susceptible = intermediate + resistant)
Drug Resistant Campylobacter (DRC)
Ciprofloxacin resistance among poultry isolates 68.8%
Clostridioides difficile (CD)
Hospital-based CDI incidence 6.2 cases per 10,000 patient-days
CPE (Carbapenemase-producing Enterobacterales)
Population-weighted mean carbapenem resistance in invasive K. pneumoniae 0.4% (EU/EEA mean)
VRE (vancomycin-resistant Enterococci)
Estimated prevalence 14.1% (period estimate from meta-analysis)
MRSA (Methicillin-resistant Staphylococcus aureus)
MRSA proportion among S. aureus isolates 26.39%
Drug-Resistant Neisseria gonorrhoeae (DRNG)
Ceftriaxone resistance 27% among 352 isolates
Drug-Resistant Salmonella (DRNTS)
Outbreak cases: 47 ceftriaxone-resistant S. Typhi cases
Others (aggregate signal)
One in six laboratory-confirmed bacterial infections resistant to at least one antibiotic
Moreover, leading players in the antimicrobial resistance diagnostics industry are collaborating to develop innovative solutions that address drug-resistant infections. For instance, in July 2022, Boehringer Ingelheim, bioMérieux, and Evotec SE formed a joint venture to develop actionable diagnostics and next-generation antibiotics to combat antimicrobial resistance. As part of this initiative, bioMérieux will focus on developing testing solutions for antibiotic resistance, with 80% of the investment dedicated to fighting AMR. Additionally, in June 2024, Sysmex Astrego was announced as a winner of the Longitude Prize for its PA-100 AST System, which is a point-of-care test for urinary tract infections.
Governments worldwide are working to enhance diagnostic quality for accurate and point-of-care diagnoses. For example, the UK government has launched initiatives to incentivize R&D for new AMR diagnostics. By 2024, the UK aims to bridge R&D gaps, collaborate with global stakeholders to develop next-generation diagnostic tests, and promote AMR diagnostics research. In February 2020, the UK invested approximately USD 12 million in partnership with Nigeria to combat drug-resistant infections by upgrading laboratory equipment, improving public health surveillance, and training scientists and technicians.
Furthermore, vendors have moved from promising proofs of concept to regulated, cleared products for rapid phenotypic AST and integrated ID plus AST workflows. A clear example is the June 21, 2024, US FDA 510(k) clearance of bioMérieux’s VITEK REVEAL system that reports actionable phenotypic susceptibility directly from positive blood cultures within a single work shift, facilitating same-day therapeutic adjustments. At the same time, Sysmex publicly documented compact AST systems in 2023 and 2024 that yield presence calls and antimicrobial efficacy results from urine samples in under 30 minutes, demonstrating how microfluidics can be applied to bedside decision-making. These concrete launches alter the procurement calculus by reducing validation risk for hospital labs.
Market Dynamics
The antimicrobial resistance diagnostics market is expanding as healthcare systems place greater emphasis on the rapid identification of drug-resistant pathogens to improve patient outcomes and support antimicrobial stewardship programs. Growing prevalence of antimicrobial resistance, increasing adoption of molecular diagnostics, and rising demand for rapid susceptibility testing are driving the integration of advanced diagnostic technologies into routine clinical practice. Healthcare providers are investing in diagnostic solutions that enable timely and targeted antimicrobial therapy while reducing inappropriate antibiotic use. For instance, in May 2026, Biotia launched clinically approved drug resistance reporting for complicated urinary tract infections, integrating genomic analysis to identify antimicrobial resistance markers and support precision guided antimicrobial therapy. The launch expanded the availability of genomic resistance testing and strengthened the role of molecular diagnostics in clinical decision making. Continued advancements in rapid diagnostic technologies and broader implementation of antimicrobial stewardship programs are expected to sustain market growth over the forecast period.
The growing emphasis on antimicrobial stewardship and the need for rapid detection of drug-resistant pathogens are key drivers of the Antimicrobial Resistance Diagnostics market. Healthcare providers are increasingly adopting molecular diagnostics and rapid antimicrobial susceptibility testing to identify resistance mechanisms at an early stage, enabling timely and targeted treatment decisions. These diagnostic approaches help reduce inappropriate antibiotic prescribing, improve clinical outcomes, and support infection control programs across hospitals and reference laboratories. Rising investments in surveillance initiatives and diagnostic infrastructure are further strengthening the adoption of antimicrobial resistance testing worldwide. For instance, in June 2025, the Global Antibiotic Research and Development Partnership launched a global collaboration to improve access to innovative antimicrobial resistance diagnostic solutions and strengthen surveillance networks for drug resistant pathogens. The collaboration is expected to accelerate the adoption of advanced diagnostic technologies and reinforce antimicrobial stewardship efforts across global healthcare systems.
The high cost of advanced molecular diagnostics and limited laboratory infrastructure remain significant restraints for the antimicrobial resistance diagnostics market. Many antimicrobial resistance diagnostic technologies require specialized instruments, skilled laboratory personnel, and sophisticated data analysis capabilities, increasing the overall cost of implementation. Healthcare facilities in low- and middle-income countries often face budget constraints that limit investment in advanced diagnostic platforms and routine antimicrobial susceptibility testing. In addition, inconsistent reimbursement policies and limited access to laboratory infrastructure can delay the adoption of innovative diagnostic solutions across decentralized healthcare settings. These challenges are particularly evident in resource constrained regions where conventional microbiology methods continue to be widely used because of lower costs. Expanding access to affordable diagnostic technologies, strengthening laboratory capacity, and improving reimbursement frameworks will be essential to support broader adoption of antimicrobial resistance diagnostics and address the growing burden of drug-resistant infections.
Increasing investment in innovative diagnostic technologies is creating significant opportunities for the antimicrobial resistance diagnostics market. Public and private organizations are expanding funding to accelerate the development of rapid, accurate, and cost effective diagnostic solutions that can identify antimicrobial resistance at an early stage. These investments are supporting the advancement of molecular diagnostics, point of care testing, and next generation sequencing technologies while encouraging collaboration between diagnostic developers, research institutions, and healthcare providers. Improved access to funding is also helping emerging companies translate novel diagnostic platforms into commercial products and expand their presence in global markets. For instance, in February 2025, CARB X launched its 2025 funding round to support the development of innovative diagnostic technologies for drug resistant bacterial infections, with dedicated funding for rapid antimicrobial resistance diagnostics. The initiative is expected to accelerate product innovation, strengthen commercialization opportunities, and support long term market expansion.
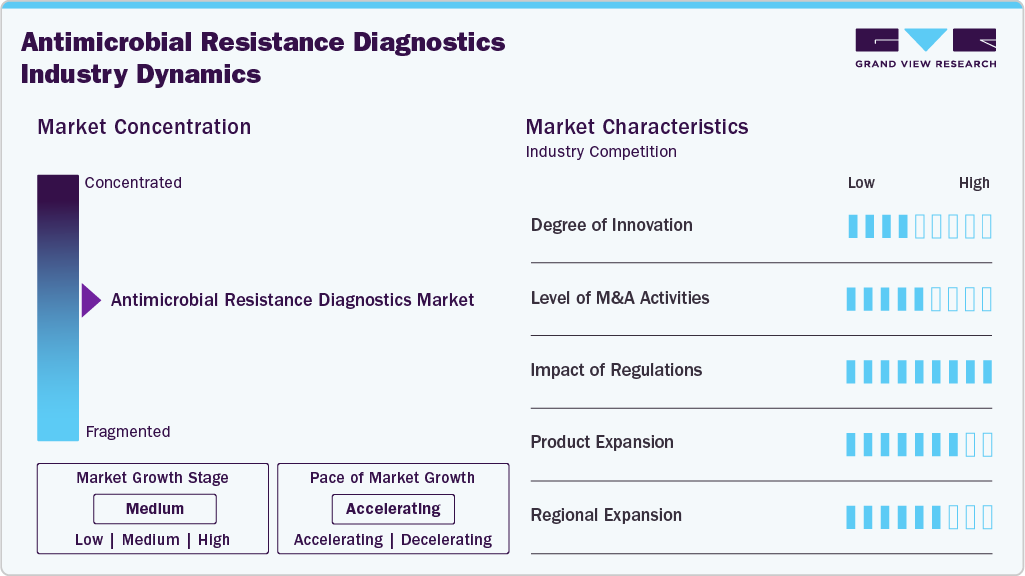
Market Concentration & Characteristics
Innovation in AMR and DRNG diagnostics has accelerated in recent years, driven by the urgent need for rapid resistance detection and targeted therapy. On 18 March 2024, Visby Medical announced the launch of its single-use, patient-side PCR test for gonorrhoea with resistance-marker detection, advancing same-visit decision-making at the point of care. Earlier, SpeeDx expanded the market availability of its ResistancePlus GC assay in the EU, Australia, and New Zealand, enabling the molecular prediction of ciprofloxacin susceptibility by detecting gyrA S91F mutations, thereby supporting the reuse of oral ciprofloxacin in select patients.
Mergers and acquisitions in AMR and broader infectious disease diagnostics have primarily focused on companies seeking molecular capabilities, automation, and expansion of rapid test portfolios. In February 2024, bioMérieux completed the acquisition of LuminUltra Technologies to strengthen its position in rapid microbial detection and environmental surveillance, reinforcing its AMR-related capabilities. In January 2023, Thermo Fisher Scientific finalised its acquisition of The Binding Site, expanding its specialty diagnostics footprint, including immunodiagnostic tools relevant to infection management and antimicrobial stewardship.
 To learn more about this report, Download Free Sample Report
Regulation has played a defining role in shaping market entry and adoption of DRNG and AMR diagnostics. Under the European IVDR transition, assays predicting antimicrobial resistance, including those for DRNG, now require more extensive analytical and clinical validation, which slows the time to market but improves reliability. In the United States, the FDA’s shift away from pandemic-era Emergency Use Authorizations has tightened requirements for molecular assays, and point-of-care AMR diagnostics must meet full regulatory standards.
Diagnostic companies have expanded their AMR-related test menus, particularly in molecular assays capable of predicting resistance profiles. SpeeDx continues to expand the availability of its ResistancePlus GC test across multiple geographies, supporting clinical programs that allow selective use of ciprofloxacin. In June 2024, Seegene expanded its Allplex AMR assay portfolio, including enhanced panels for detecting fluoroquinolone resistance. In March 2024, Visby Medical introduced a palm-sized PCR test for gonorrhoea with resistance markers, representing a major shift toward ultra-portable, disposable molecular diagnostics.
Global demand for AMR diagnostics is driving geographic expansion by major players. SpeeDx achieved broader regulatory recognition for its ResistancePlus GC test across the EU, Australia, and New Zealand, allowing clinicians in these regions to access resistance-guided therapy. In 2023 and 2024, WHO and FIND-led initiatives encouraged the expansion of DRNG testing capacity in Africa and Southeast Asia, regions where ceftriaxone-resistant gonorrhoea outbreaks have been on the rise. Visby Medical’s recognition in the 2024 federal AMR diagnostic competition has accelerated interest from US healthcare systems preparing for point-of-care deployment once regulatory approval is achieved. These expansions signal a gradual global shift toward strengthening DRNG detection infrastructure, particularly in regions with high disease burden.
Analyst Perspective
The antimicrobial resistance diagnostics market is expected to witness sustained growth as healthcare systems prioritize rapid identification of drug-resistant pathogens and strengthen antimicrobial stewardship initiatives. Rising adoption of molecular diagnostics, next generation sequencing, and rapid antimicrobial susceptibility testing is improving clinical decision making and supporting targeted antimicrobial therapy. Market participants are investing in product innovation, strategic collaborations, and laboratory automation to enhance diagnostic accuracy and workflow efficiency. Increasing surveillance programs and global efforts to address antimicrobial resistance are further supporting market expansion. As diagnostic technologies become more accessible and integrated into routine clinical practice, antimicrobial resistance diagnostics are expected to play an increasingly important role in infection management and public health surveillance.
Technology Insights
Based on technology, the microbiology culture segment led the market with the largest revenue share of 51.7% in 2025 and anticipated to grow at fastest CAGR over the forecast period. The microbiology culture segment continues to drive the market growth as it remains the only universally accepted starting point for confirmed pathogen isolation and phenotypic antimicrobial susceptibility testing. Even with the rapid expansion of molecular and sequencing options, hospitals and reference laboratories still depend on culture to generate viable organisms for drug-susceptibility reporting, epidemiological assessment, and public health notification. This dependency means culture-based consumables, automation systems, and AST cards maintain consistent purchasing cycles across high- and middle-income markets.
However, the rapid and point-of-care (PoC) diagnostic segment is projected to experience the fastest compound annual growth rate (CAGR) of 5.47% during the forecast period. The increasing demand for PoC and rapid diagnostics is driven by their benefits, including quick turnaround times, fast results, and cost-effectiveness. The increasing demand for PoC and rapid diagnostics is driven by their benefits, including quick turnaround times, fast results, and cost-effectiveness. Recent product launches and innovations reinforce the shift toward immediate, bedside, or near-patient diagnostics for antimicrobial resistance and acute infections. In June 2023, Sysmex announced the launch of a point-of-care system in Europe capable of delivering antimicrobial susceptibility test (AST) results from urine samples in as little as 30 minutes, a significant reduction compared with conventional AST times that often take days.
Pathogen Insights
Based on pathogen, the methicillin resistant staphylococcus aureus (MRSA) segment led the market with the largest revenue share of 20.9% in 2025. The rising incidence of MRSA in hospital settings is a key driver for the expansion of this segment. Hospitalized MRSA cases are projected to increase from 714,000 to 791,000 by 2033 across seven major markets, including the U.S., Japan, and European countries, driven by factors such as poor infection control, antibiotic resistance, and demographic changes. According to the CDC, approximately 33% of people carry Staphylococcus aureus in their noses without showing symptoms; however, about two out of every 100 of these individuals become infected with MRSA. Additionally, an increase in regulatory approvals for diagnostic tests targeting MRSA detection is further contributing to this growth.
 To learn more about this report, Download Free Sample Report
The Drug-Resistant Neisseria Gonorrhoeae (DRNG) segment is likely to grow with a lucrative CAGR of 6.06% over the forecast period. Gonorrhoea remains one of the world’s most common bacterial sexually transmitted infections, so the diagnostics market must service large testing volumes as well as targeted AMR surveillance. The WHO’s global STI data estimate about 82.4 million new Neisseria gonorrhoeae infections among adults aged 15-49 in 2020. WHO’s surveillance programmes (GASP/EGASP) continue to document the emergence and spread of strains with decreased susceptibility to ceftriaxone and with high-level azithromycin resistance in sentinel sites; WHO published the Enhanced Gonococcal Antimicrobial Surveillance Programme (EGASP) guidance on 24 January 2024 to strengthen sentinel AMR surveillance.
End Use Insights
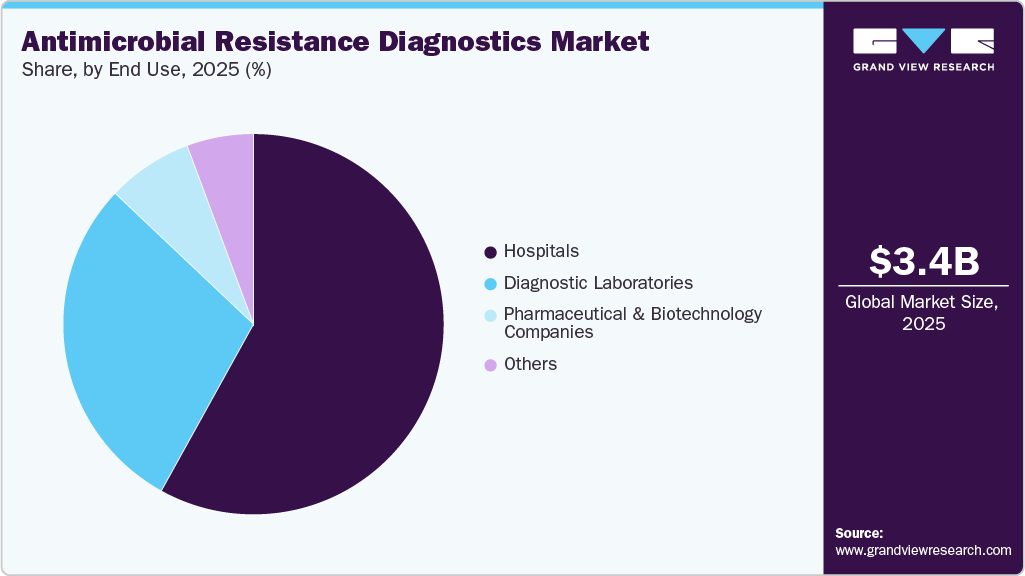
Based on end-use, the hospitals segment led the market with the largest revenue share of 58.2% in 2025. Hospitals remain the primary demand engine for antimicrobial resistance diagnostics because they manage the highest-acuity infections where rapid identification and susceptibility data directly influence patient outcomes. Rising rates of bloodstream infections, surgical-site infections, ventilator-associated pneumonia, and other hospital-onset infections push hospitals to expand adoption of rapid molecular tests, automated culture systems, and stewardship-aligned diagnostic workflows.
Additionally, greater access to advanced diagnostic technologies, affordability, and improved healthcare coverage are contributing to the segment's expansion. Pathogens like MRSA, CDI, and DRSP can cause serious conditions such as bloodstream infections, sepsis, pneumonia, and surgical site infections, making the high occurrence of these infections in hospitals a key factor supporting market growth. Furthermore, a study conducted in April 2022 by BD, Pfizer, and Merck revealed that over 270 hospitals in the U.S. saw a rise in antimicrobial resistance during the COVID-19 pandemic, highlighting the ongoing challenge posed by AMR infections in healthcare settings.
The diagnostic laboratories segment is expected to grow at the fastest CAGR of 4.93% over the forecast period. The growing prevalence of infectious diseases, combined with advancements in laboratory technology, is projected to propel segment growth. Additionally, the availability of affordable diagnostic services and the widespread presence of laboratories capable of conducting various diagnostic procedures are expected to contribute to market expansion. Laboratory testing plays a crucial role in patient management by identifying emerging threats and delivering accurate results essential for effective treatment. The CDC has also established its Antimicrobial Resistance (AMR) laboratory network to facilitate rapid resistance diagnosis and inform local authorities, helping to combat the spread of resistant infections.
Regional Insights
North America dominated the antimicrobial resistance diagnostics market with the largest revenue share of 37.1% in 2025. Growth in the region is supported by rising rates of drug-resistant infections, strong government initiatives, and well-established healthcare infrastructure. The presence of major diagnostic companies, along with ongoing product development and collaborations, further strengthens regional expansion. For example, in December 2024, the US Centers for Disease Control and Prevention expanded its AMR surveillance networks to include more laboratories and resistance pattern reporting, reinforcing the need for advanced diagnostics across hospitals and reference labs.
 To learn more about this report, Download Free Sample Report
U.S. Antimicrobial Resistance Diagnostics Market Trends
The antimicrobial resistance diagnostics market in the U.S. held the largest share in the North America region in 2025, fueled by the presence of key players and a large end user base. Furthermore, the U.S. invests heavily in research and development in the healthcare sector. In March 2025, the US National Institutes of Health announced additional funding for diagnostic innovation targeting priority AMR pathogens, supporting the development of new molecular and rapid testing solutions. These efforts are expected to strengthen market growth over the next several years. This investment fuels advancements in diagnostic technologies and the development of new solutions for combating antimicrobial resistance.
Europe Antimicrobial Resistance Diagnostics Market Trends
The Europe antimicrobial resistance diagnostics industry is experiencing significant growth. Many European countries face significant challenges related to antimicrobial resistance, with rising rates of drug-resistant infections. According to the UK Health Security Agency, nearly 400 new cases of antibiotic-resistant infections were reported per week in 2024, as published in November 2025 by the European Medical Journal. Government funding for innovation and AMR programs continues to rise, supporting the adoption of molecular and rapid testing platforms across the healthcare system. This situation drives the urgent need for effective diagnostic solutions to identify resistant pathogens and manage infections.
The UK antimicrobial resistance diagnostics market is experiencing significant growth due to advancements in healthcare and technological improvements. The rising incidence of drug-resistant infections has increased awareness among healthcare providers and policymakers about the urgent need for effective diagnostic solutions. The growing threat of drug-resistant infections in the UK is creating urgent demand for advanced diagnostic solutions to manage and contain antimicrobial resistance. For instance, according to an article published in the European Medical Journal in November 2025, new surveillance data from the UK Health Security Agency (UKHSA) indicate a significant increase in antibiotic-resistant infections, with nearly 400 new cases reported weekly in 2024.Furthermore, increasing government funding for healthcare innovation and antimicrobial resistance initiatives is driving the demand for antimicrobial resistance diagnostic solutions in the UK.
The Germany antimicrobial resistance diagnostics market is experiencing significant growth. Germany boasts a highly developed healthcare infrastructure, characterized by advanced laboratories and medical facilities, which facilitates the integration and adoption of innovative diagnostic technologies.
Asia Pacific Antimicrobial Resistance Diagnostics Market Trends
The Asia Pacific antimicrobial resistance diagnostics industry is experiencing the fastest growth, driven by significant advancements in healthcare infrastructure and technology. The increasing prevalence of infectious diseases and the rising incidence of drug-resistant infections in the region are the key factors for the market growth. Countries in Asia Pacific are grappling with significant public health challenges related to antimicrobial resistance, prompting a heightened need for effective diagnostic tools to identify resistant pathogens and manage infections effectively.
The China antimicrobial resistance diagnostics market is growing, driven by the rapid expansion of its biotechnology and pharmaceutical industries. China is making great strides in advancing its healthcare infrastructure, with significant investments in medical technology and diagnostic facilities. The rapid adoption of cutting-edge diagnostic tools, such as molecular testing and rapid point-of-care diagnostics, is helping healthcare professionals in China respond quickly and accurately to AMR challenges.
Latin America Antimicrobial Resistance Diagnostics Market Trends
The Latin America antimicrobial resistance diagnostics industry is experiencing significant growth, driven by increasing investments in the pharmaceutical and biotechnology sectors, particularly in countries such as Brazil and Argentina. Government initiatives aimed at combating antimicrobial resistance are also gaining momentum in the region. Several Latin American countries have developed national action plans that prioritize the surveillance of antimicrobial resistance, promote research and development in diagnostics, and encourage the appropriate use of antibiotics.
Middle East and Africa Antimicrobial Resistance Diagnostics Market Trends
The MEA antimicrobial resistance diagnostics industry is expected to grow over the forecast period. The regional growth is attributed to rising investments in the overall healthcare and life sciences sector, especially in countries such as South Africa, Saudi Arabia, and the UAE.
The Saudi Arabia antimicrobial resistance diagnostics market is expanding due to increased healthcare investment and improved infrastructure. Saudi Arabia's government has prioritized public health and is actively implementing strategies to combat AMR as part of its Vision 2030 initiative. This includes the establishment of national action plans to enhance surveillance, promote research, and improve the overall management of antimicrobial use.
Key Antimicrobial Resistance Diagnostics Company Insights
The competitive scenario in the antimicrobial resistance diagnostics market is high, with key players such as bioMerieux; F. Hoffmann-La Roche Ltd.; Abbott; Hologic, Inc.; BD; and Danaher holding significant positions. Prominent market participants are focusing on increasing the customer base using acquisition strategies. For instance, in April 2022, bioMérieux announced the acquisition of Specific Diagnostics. This acquisition has strengthened its position in the global market.
Key Antimicrobial Resistance Diagnostics Companies:
The following key companies have been profiled for this study on the antimicrobial resistance diagnostics market.
-
BD
-
BIOMÉRIEUX
-
Abbott
-
Accelerate Diagnostics, Inc.
-
Danaher
-
Hologic Inc. (Gen Probe)
-
Molsid
-
F. Hoffmann-La Roche, Ltd.
-
Vela Diagnostics
-
Visby Medical, Inc.
-
OpGen
-
Seegene Inc
-
EliTechGroup
-
CERTEST BIOTEC
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Well Established Players (BD, BIOMÉRIEUX, Abbott, Danaher, F. Hoffmann La Roche Ltd., Hologic Inc. (Gen Probe))
- Expand antimicrobial resistance diagnostics portfolios through molecular diagnostics, antimicrobial susceptibility testing, microbiology culture systems, rapid diagnostic platforms, and laboratory automation. Focus on product innovation, regulatory approvals, acquisitions, strategic collaborations, and expansion of integrated diagnostic workflows to strengthen global market presence and support antimicrobial stewardship programs.
- Comprehensive antimicrobial resistance diagnostic portfolios, established global distribution networks, extensive regulatory expertise, broad installed instrument base, advanced research and development capabilities, and integrated laboratory solutions. Ability to support hospitals, diagnostic laboratories, public health institutions, and reference laboratories through comprehensive diagnostic platforms, consumables, software, and technical services.
- Large organizational structures may increase product development and commercialization timelines. Premium pricing, complex regulatory requirements, and dependence on healthcare reimbursement and laboratory procurement cycles may limit adoption in cost sensitive and resource constrained healthcare markets.
Emerging Players (Accelerate Diagnostics, Inc., Molsid, Vela Diagnostics, Visby Medical, Inc., OpGen, Seegene Inc., EliTechGroup, CERTEST BIOTEC)
- Focus on developing rapid antimicrobial resistance diagnostics, molecular assays, point of care testing platforms, antimicrobial susceptibility testing solutions, and strategic collaborations to expand product portfolios. Emphasize workflow simplification, faster turnaround time, decentralized testing, multiplex assay development, and expansion into underserved infectious disease applications.
- Specialized expertise in rapid antimicrobial resistance diagnostics, flexible product development, faster commercialization, and strong focus on molecular testing and decentralized diagnostic solutions. Ability to address evolving clinical needs through targeted resistance detection assays, portable testing platforms, and innovative microbiology technologies.
- Comparatively narrower product portfolios, smaller global commercial footprint, and limited manufacturing scale relative to multinational diagnostics companies. Dependence on selected product categories, clinical validation, regulatory approvals, and regional commercialization strategies may limit competitiveness across the broader antimicrobial resistance diagnostics market.
Recent Developments
-
In September 2025, Molecular Designs, a leading developer of molecular infectious disease assays, introduced the Urogenital Microbiota with ABX 53 Simplicity Panel, an advanced, multiplex PCR-based panel intended for research use that enables broad detection of urinary pathogens and antibiotic resistance (ABX) genes.
-
IN February 2025, CARB-X, the Combating Antibiotic-Resistant Bacteria Biopharmaceutical Accelerator, announced a new, strategically focused funding call aimed at accelerating solutions for two critical unmet needs in global health. It focuses on advancing next-generation diagnostics for Salmonella Typhi, with the goal of enabling faster, more accurate detection to improve patient management and support public health efforts.
-
In November 2024, The Combating Antibiotic-Resistant Bacteria Biopharmaceutical Accelerator (CARB-X) and the Clinton Health Access Initiative (CHAI) partnered to assess clinical requirements and overcome market challenges for diagnostic, preventive, and therapeutic solutions aimed at combating gonorrhea infections in low- and middle-income countries.
-
In October 2024, Seegene partnered with Werfen to establish a European hub, localizing syndromic real-time PCR product development and expanding molecular diagnostics in European markets.
Antimicrobial Resistance Diagnostics Market Report Scope
Report Attribute
Details
Market size in 2025
USD 3.4 billion
Estimated market size in 2026
USD 3.5 billion
Projected market size by 2033
USD 4.7 billion
Growth rate
CAGR of 4.1% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Technology, pathogen, end use , regional
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Denmark; Sweden; Norway; Japan; China; India; South Korea; Australia; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
BD, BIOMÉRIEUX, Abbott, Accelerate Diagnostics, Inc., Danaher, Hologic Inc. (Gen Probe), Molsid, F. Hoffmann La Roche Ltd., Vela Diagnostics, Visby Medical, Inc., OpGen, Seegene Inc., EliTechGroup, CERTEST BIOTEC.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Antimicrobial Resistance Diagnostics Market Report Segmentation
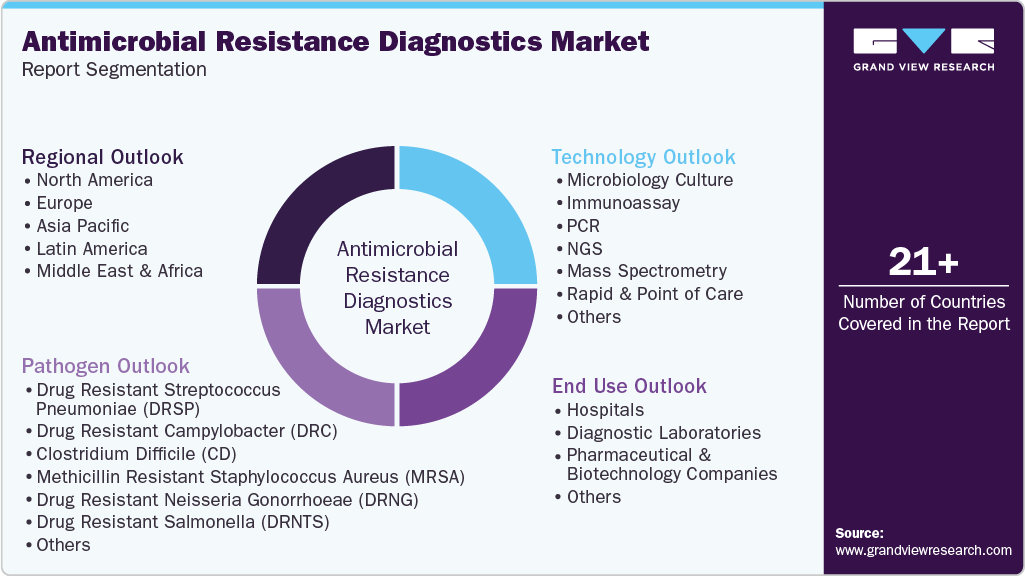
This report forecasts revenue growth at the global, regional & country levels and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the antimicrobial resistance diagnostics market report based on technology, pathogen, end use, and region:
 To learn more about this report, Download Free Sample Report
-
Technology Outlook (Revenue, USD Million; 2021 - 2033)
-
Microbiology Culture
-
Immunoassay
-
PCR
-
NGS
-
Mass Spectrometry
-
Rapid & Point of Care
-
Others
-
-
Pathogen Outlook (Revenue, USD Million; 2021 - 2033)
-
Drug Resistant Streptococcus Pneumoniae (DRSP)
-
Drug Resistant Campylobacter (DRC)
-
Clostridium Difficile (CD)
-
Methicillin Resistant Staphylococcus Aureus (MRSA)
-
Drug Resistant Neisseria Gonorrhoeae (DRNG)
-
Drug Resistant Salmonella (DRNTS)
-
Others
-
-
End Use Outlook (Revenue, USD Million; 2021 - 2033)
-
Hospitals
-
Diagnostic Laboratories
-
Pharmaceutical & Biotechnology Companies
-
Others
-
-
Regional Outlook (Revenue, USD Million; 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Norway
-
Denmark
-
Sweden
-
Norway
-
Portugal
-
Turkey
-
Switzerland
-
Belgium
-
Netherlands
-
Rest of Europe
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
Malaysia
-
Indonesia
-
Vietnam
-
Rest of Asia Pacific
-
-
Latin America
-
Brazil
-
Argentina
-
Colombia
-
Peru
-
Ecuador
-
Rest of Latin America
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The antimicrobial resistance diagnostics market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each antimicrobial resistance diagnostics segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Technology
Revenue capture definition
Microbiology Culture
Revenue is primarily captured through culture media, automated blood culture systems, microbial identification instruments, antimicrobial susceptibility testing platforms, incubators, and laboratory consumables used for phenotypic detection of antimicrobial resistance.
Immunoassay
Market value is derived from immunoassay analyzers, antigen and antibody detection kits, reagents, controls, calibrators, and consumables used to identify antimicrobial resistance associated pathogens and resistance markers.
PCR
Revenue flows from PCR instruments, nucleic acid extraction systems, master mixes, primers, probes, amplification reagents, and assay kits used for rapid detection of antimicrobial resistance genes.
NGS
Revenue is captured through next generation sequencing instruments, library preparation kits, sequencing reagents, bioinformatics software, data analysis platforms, and consumables used for comprehensive antimicrobial resistance gene profiling.
Mass Spectrometry
Revenue is supported by mass spectrometry systems, sample preparation kits, identification databases, software platforms, and associated consumables used for microbial identification and antimicrobial resistance characterization.
Rapid & Point of Care
Revenue is driven by rapid molecular testing platforms, portable diagnostic instruments, cartridge based assays, lateral flow tests, consumables, and integrated software enabling near patient antimicrobial resistance detection.
Others
Revenue originates from emerging antimicrobial resistance diagnostic technologies including microarrays, biosensors, CRISPR based assays, microfluidic platforms, artificial intelligence enabled analytical software, and associated reagents and consumables.
Segment - Pathogen
Revenue capture definition
Drug Resistant Streptococcus pneumoniae (DRSP)
Revenue is primarily captured through culture based assays, molecular diagnostic kits, antimicrobial susceptibility testing systems, reagents, and consumables used to detect drug resistant Streptococcus pneumoniae infections.
Drug Resistant Campylobacter (DRC)
Market value is derived from microbiology culture media, PCR assays, antimicrobial susceptibility testing platforms, identification systems, reagents, and consumables used for detecting drug resistant Campylobacter species.
Clostridioides difficile (CD)
Revenue flows from molecular assays, immunoassay kits, culture media, toxin detection tests, laboratory analyzers, and associated consumables used for identifying Clostridioides difficile infections and antimicrobial resistance.
Methicillin Resistant Staphylococcus aureus (MRSA)
Revenue is captured through MRSA screening assays, PCR based diagnostic tests, culture media, antimicrobial susceptibility testing instruments, rapid diagnostic platforms, and supporting laboratory consumables.
Drug Resistant Neisseria gonorrhoeae (DRNG)
Revenue is supported by nucleic acid amplification tests, culture systems, antimicrobial susceptibility testing platforms, sequencing assays, reagents, and consumables used for detecting resistant Neisseria gonorrhoeae strains.
Drug Resistant Salmonella (DRNTS)
Revenue originates from culture based diagnostics, molecular assays, antimicrobial susceptibility testing systems, identification platforms, reagents, and consumables used for detecting drug resistant Salmonella infections.
Others
Revenue is driven by diagnostic assays, microbiology systems, molecular platforms, sequencing technologies, reagents, and consumables used for detecting other clinically significant antimicrobial resistant bacterial pathogens not classified elsewhere.
Segment - Application
Revenue capture definition
Hospitals
Revenue is primarily captured through antimicrobial resistance diagnostic instruments, molecular and microbiology assays, antimicrobial susceptibility testing systems, consumables, software, and laboratory services used within hospital diagnostic laboratories.
Diagnostic Laboratories
Market value is derived from high throughput antimicrobial resistance testing platforms, laboratory analyzers, reagents, consumables, sequencing workflows, bioinformatics software, and reference testing services performed for healthcare providers.
Pharmaceutical & Biotechnology Companies
Revenue flows from antimicrobial resistance diagnostic platforms, companion diagnostic development, biomarker analysis, antimicrobial susceptibility testing services, sequencing solutions, and research reagents supporting antimicrobial drug discovery and clinical development.
Others
Revenue originates from antimicrobial resistance diagnostic products and services supplied to academic research institutes, public health laboratories, government agencies, contract research organizations, and veterinary diagnostic laboratories conducting surveillance and research activities.
Estimation Model
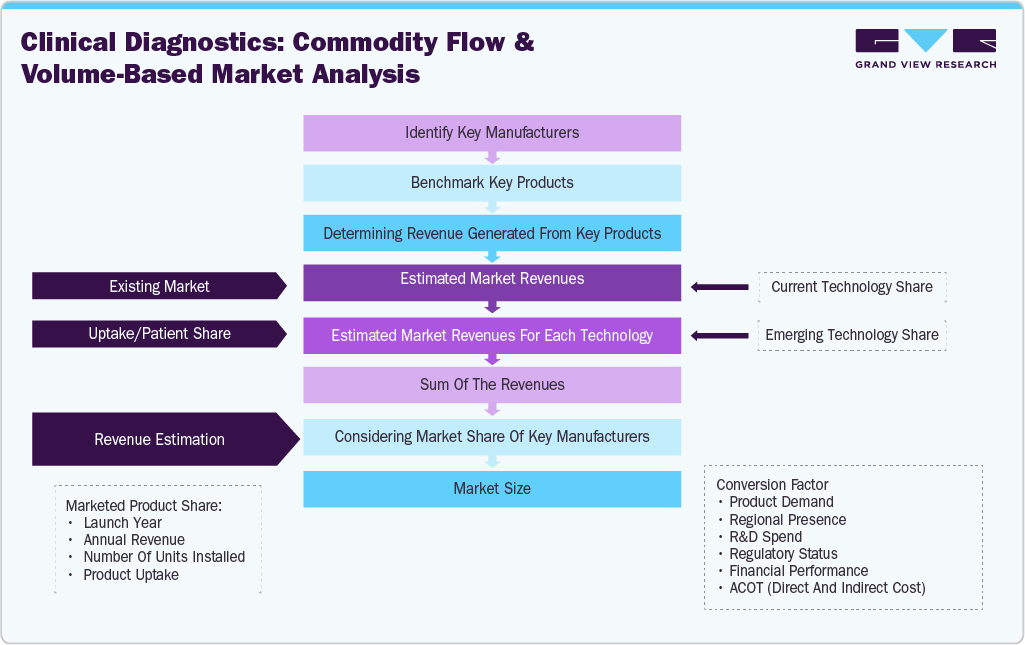
The Antimicrobial Resistance Diagnostics market size was estimated using a bottom up approach by identifying leading manufacturers and benchmarking their antimicrobial resistance diagnostic product portfolios across microbiology culture, molecular diagnostics, immunoassays, antimicrobial susceptibility testing, and rapid diagnostic technologies. Revenue contributions from key products were assessed and mapped across individual technology segments based on adoption rates and patient testing volumes. The aggregated segment revenues were validated by considering the market share of major manufacturers, existing market penetration, and utilization across hospitals, diagnostic laboratories, pharmaceutical and biotechnology companies, and other end users to derive the overall market size.
 To learn more about this report, Download Free Sample Report
Delivered Customizations
This report has been delivered with the following In-depth customizations
CLIENT REQUEST
CUSTOMIZATION DELIVERED
VALUE ADDS
Antimicrobial Resistance Diagnostics Competitive Landscape & Technology Assessment
Assessed the global antimicrobial resistance diagnostics market across microbiology culture, immunoassays, PCR, next generation sequencing, mass spectrometry, rapid and point of care diagnostics, and emerging technologies. Evaluated competitive positioning, product portfolios, technology advancements, strategic developments, laboratory adoption trends, and antimicrobial stewardship initiatives across hospitals, diagnostic laboratories, public health institutions, and pharmaceutical companies.
Helped the client identify technology adoption opportunities, benchmark competitive capabilities, evaluate product differentiation, prioritize strategic investments, and assess market expansion opportunities across antimicrobial resistance diagnostics and infectious disease testing.
Antimicrobial Resistance Diagnostics Product & Technology Benchmarking Study
Delivered comprehensive benchmarking of antimicrobial resistance diagnostic platforms across microbiology culture, molecular diagnostics, antimicrobial susceptibility testing, sequencing technologies, rapid diagnostics, laboratory automation, and bioinformatics solutions. Assessed diagnostic accuracy, turnaround time, workflow efficiency, automation capabilities, ease of laboratory integration, and product differentiation among leading market participants.
Enabled the client to evaluate technology competitiveness, identify innovation opportunities, benchmark product development strategies, prioritize investments in molecular diagnostics, rapid susceptibility testing, laboratory automation, and antimicrobial resistance surveillance technologies.
Antimicrobial Resistance Diagnostics Laboratory Adoption & Commercialization Assessment
Assessed laboratory infrastructure, antimicrobial resistance surveillance programs, diagnostic testing trends, reimbursement landscape, regulatory environment, procurement practices, and commercialization pathways influencing adoption across major regional markets. Evaluated utilization across hospitals, diagnostic laboratories, public health agencies, academic research institutes, and pharmaceutical and biotechnology companies.
Supported commercialization planning by identifying market entry opportunities, evaluating customer adoption patterns, assessing operational and investment considerations, and strengthening long term growth strategies across healthcare providers, diagnostic laboratories, public health organizations, and antimicrobial resistance surveillance networks.
Frequently Asked Questions About This Report
The global antimicrobial resistance diagnostics market size was valued at USD 3.4 billion in 2025 and is estimated at USD 3.5 billion for 2026.
The increasing risk of developing drug-resistant infections, the increasing introduction of technologically advanced tests, and government initiatives to reduce AMR disease burden are the major factors driving the antimicrobial resistance diagnostics market growth over the forecast period.
The global antimicrobial resistance diagnostics market is expected to grow at a CAGR of 4.1% from 2026 to 2033, reaching USD 4.7 billion in 2033
Asia Pacific is the fastest-growing region over the forecast period.
Methicillin-resistant staphylococcus aureus segment led with a 20.9% revenue share in 2025.
Antimicrobial resistance diagnostics segment led with a 58.2% revenue share in 2025, while diagnostic laboratories is the fastest-growing area.
Microbial culture segment led with a 51.7% revenue share in 2025, while rapid and point-of-care (PoC) diagnostic is the fastest-growing segment.
Key players include BIOMERIEUX, F. Hoffmann-La Roche Ltd, Abbott, BD, and Danaher among others.
North America dominated with a 37.1% revenue share in 2025.
About the Author(s)
Clinical Diagnostics Research Team
Healthcare · Clinical DiagnosticsThis report was authored by the clinical diagnostics research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the clinical diagnostics segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


