
- Home
- »
- Medical Devices
- »
-
Arterial Filter Market Size, Share, Trends Report, 2026-2033GVR Report cover

Arterial Filter Market (2026 - 2033)
Size, Share & Trends Analysis Report By Age Category (Adult, Neonatal/Pediatric), By End-use (Hospitals, Ambulatory Surgical Centers), By Region (North America, Europe, Asia Pacific, Latin America, MEA), And Segment Forecasts
Market Size, 2025
$651.3MMarket Estimate, 2026
$688.8MMarket Forecast, 2033
$1,022.7MCAGR, 2026–2033
5.8%Arterial Filter Market Summary
The global arterial filter market size was valued at USD 651.3 million in 2025 and is projected to grow from USD 688.8 million in 2026 to USD 1,022.7 million in 2033, at a CAGR of 5.8% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 40.0% in 2025. This market growth can be attributed to the rising incidence of Cardiovascular Diseases (CVDs) worldwide, increasing demand for cardiac surgeries, and advancements in cardiopulmonary bypass technologies.
Key Market Trends & Insights
- By end use: The hospitals segment held the largest market share of 40.0% in 2025.
- By age category: The adult segment held the largest market share of 75.0% in 2025.
Regional Highlights
- Largest regional market: North America (40.0% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 651.3 Million
- Estimated market size in 2026: USD 688.8 Million
- Projected market size by 2033: USD 1,022.7 Million
- CAGR (2026-2033): 5.8%
Prism AI by Grand View Research Free to tryAsk a question about the arterial filter marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
The rising global burden of cardiovascular diseases (CVDs), coupled with a growing geriatric population and improving healthcare access in emerging economies, is driving demand for safer and more efficient cardiac surgical procedures. CVDs remain a major cause of morbidity and mortality worldwide, with risk factors including unhealthy diets, physical inactivity, smoking, and aging contributing to the growing disease burden. The increasing prevalence of heart disease is consequently expanding the volume of cardiac surgeries and supporting demand for arterial filters.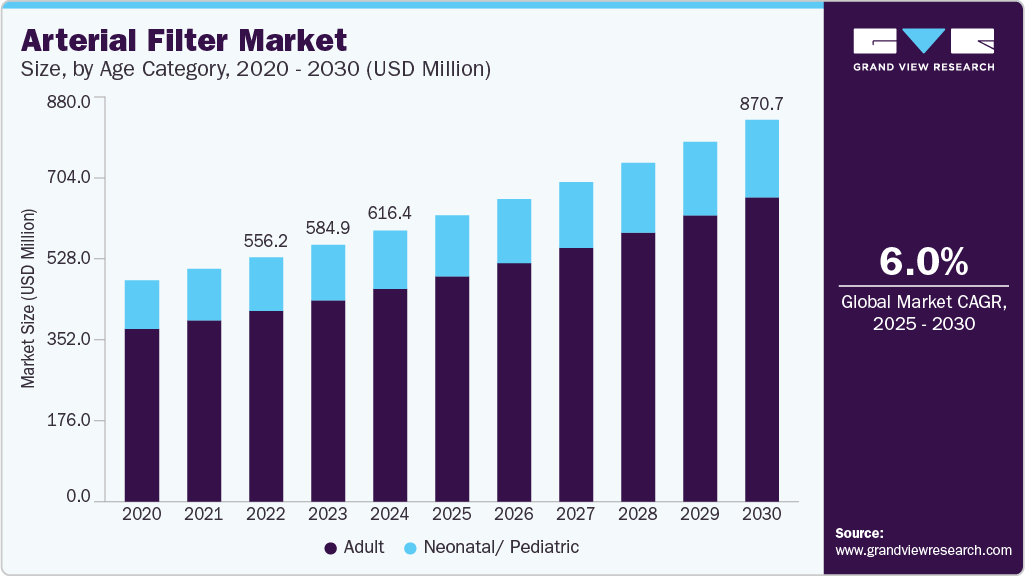 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Arterial filters play an important role during cardiopulmonary bypass by removing embolic materials, including air bubbles, blood clots, and tissue debris, from the blood before it is returned to the patient. Their use helps reduce the risk of embolic complications and supports safer surgical outcomes. As the number of procedures such as coronary artery bypass grafting (CABG) and valve replacement increases, demand for arterial filtration systems is expected to rise accordingly.
The expanding geriatric population is another important market driver, as older adults are more susceptible to conditions such as coronary artery disease, valvular heart disease, and arrhythmias that may require surgical intervention. According to Our World in Data, approximately 830 million people worldwide were aged 65 or older in 2024, and this population is expected to grow substantially in the coming decades. Asia is also experiencing rapid population aging, further increasing the potential patient pool for cardiac procedures. This demographic shift is expected to support sustained demand for arterial filters used in cardiopulmonary bypass procedures.
Market Concentration & Characteristics
The arterial filter industry exhibits a moderate level of innovation, driven by ongoing advances in materials, filtration efficiency, and biocompatibility. Manufacturers are integrating cutting-edge membrane technologies and ergonomic designs to enhance blood flow management during cardiovascular surgeries. Emphasis on minimizing embolic events and improving patient outcomes encourages the development of smarter, more precise filters. In addition, innovation is supported by rising R&D investments and regulatory support for medical device advancements.
Mergers and acquisitions (M&A) in the arterial filter industry remain moderate, largely driven by strategic consolidation among key players in the broader cardiopulmonary and cardiovascular device sectors. While the arterial filter segment is highly specialized, companies increasingly seek to integrate it within comprehensive product portfolios through targeted acquisitions. Notable trends include large medical device firms acquiring niche filter manufacturers to gain a technological edge, expanding surgical product lines, and enhancing global distribution capabilities.
The impact of regulations is considerably high in the arterial filter industry. Strict regulatory approvals from authorities such as the FDA and the European Medicines Agency (EMA) ensure high standards of safety, efficacy, and biocompatibility. Rigorous clinical evaluation and post-market surveillance obligations have increased compliance costs and extended product approval timelines, especially for new filter technologies involving novel materials or smart integration features. However, these regulations have also improved patient safety and clinical outcomes, reinforcing market trust.
Product expansion in the arterial filter industry has been steadily advancing, driven by technological innovation and the growing demand for safer, more efficient cardiopulmonary bypass procedures. Manufacturers are increasingly developing next-generation arterial filters with enhanced microembolus removal, integrated air-elimination chambers, and improved hemocompatibility. Recent expansions have included pediatric arterial filters, addressing a previously underserved segment.
The arterial filter industry is witnessing notable regional expansion, particularly in emerging economies across the Asia Pacific, Latin America, and the Middle East, owing to improvements in cardiac care infrastructure and an increase in advanced surgical procedures, which are driving demand beyond traditionally dominant markets such as North America and Europe.
Analyst Perspective
The arterial filter market is growing as cardiovascular surgeries increasingly require effective blood filtration to reduce the risk of embolic complications. These devices are widely used during cardiopulmonary bypass procedures to remove blood clots, tissue debris, and other particulate matter before blood is returned to the patient. The rising prevalence of cardiovascular diseases, increasing volumes of cardiac surgery, and improvements in extracorporeal circulation technologies are driving market demand. Companies with strong cardiovascular product portfolios, advanced device technologies, and established healthcare distribution networks are likely to strengthen their market position. In the coming years, growth will depend on surgical volumes, technological advancements, clinical adoption, and the continued focus on reducing procedure-related complications.
Age Category Insights
The adult segment led the market with over 75.0% share in 2025, driven by factors such as the high prevalence of CVDs among adults, an increasing rate of lifestyle-related disorders such as hypertension, obesity, and diabetes, and the growing volume of adult open-heart surgeries globally. Adults are more susceptible to CAD, aortic valve disorders, and myocardial infarction, which often require cardiopulmonary bypass procedures where arterial filters are critical for removing microemboli and ensuring safe perfusion. As per the U.S. Centers for Disease Control and Prevention, in October 2024, around 1 in 20 adults aged 20 and older had CAD in 2022. This demographic shift and expansion in surgical infrastructure in emerging economies drive the dominance of the adult segment in the market.
The neonatal/pediatric segment is projected to expand at a notable CAGR over the forecast period, driven by the rising incidence of Congenital Heart Defects (CHDs), advancements in pediatric cardiac care, and increasing availability of specialized equipment for infant and child surgeries. For instance, in March 2025, the U.S. CDC stated that nearly 1% of births in the U.S., or about 40,000 babies, have heart defects each year. Almost 1 in 4 babies with a heart condition has a critical heart defect.
End-use Insights
The hospitals segment dominated the market with around 40.0% share, owing to factors such as the high number of Cardiopulmonary Bypass (CPB) procedures performed in hospital settings, the availability of advanced surgical infrastructure, and a growing focus on patient safety during open-heart surgeries. In addition, hospitals offer comprehensive post-surgery care and use advanced medical devices, which help enhance recovery and improve surgical outcomes. Hospitals buy medical devices in bulk, see a high volume of patients, and often receive better financial support through insurance and reimbursement. For instance, in May 2024, Terumo Cardiovascular announced that the U.S. FDA granted 510(k) clearance for its CDI OneView Monitoring System, an advanced perfusion monitoring platform designed for use during cardiopulmonary bypass procedures. The system provides real-time monitoring of multiple patient parameters to improve perfusion safety during complex cardiac surgeries, reinforcing the continued adoption of advanced extracorporeal circulation technologies in hospitals, where arterial filters are routinely used in CPB circuits.
The Ambulatory Surgical Centers (ASCs) segment is anticipated to expand at a significant CAGR over the forecast period, driven by the increasing shift toward minimally invasive cardiac procedures, growing cost-efficiency of outpatient surgical care, and rising demand for faster patient turnaround times. ASCs are gaining popularity due to their lower operational costs, shorter hospital stays, and improved scheduling flexibility compared to traditional hospitals. These centers are increasingly equipped to perform certain cardiac interventions that may involve short-term extracorporeal support, in which compact arterial filters are used to ensure safety during perfusion. For instance, in November 2024, the U.S. Centers for Medicare & Medicaid Services (CMS) finalized the CY 2025 Hospital Outpatient Prospective Payment System and Ambulatory Surgical Center (ASC) Payment System, continuing policies that support the expansion of services performed in ASCs. The reimbursement framework encourages the migration of eligible cardiovascular procedures to outpatient settings, creating favorable conditions for the adoption of compact perfusion technologies, including arterial filters, during selected cardiac interventions.
Regional Insights
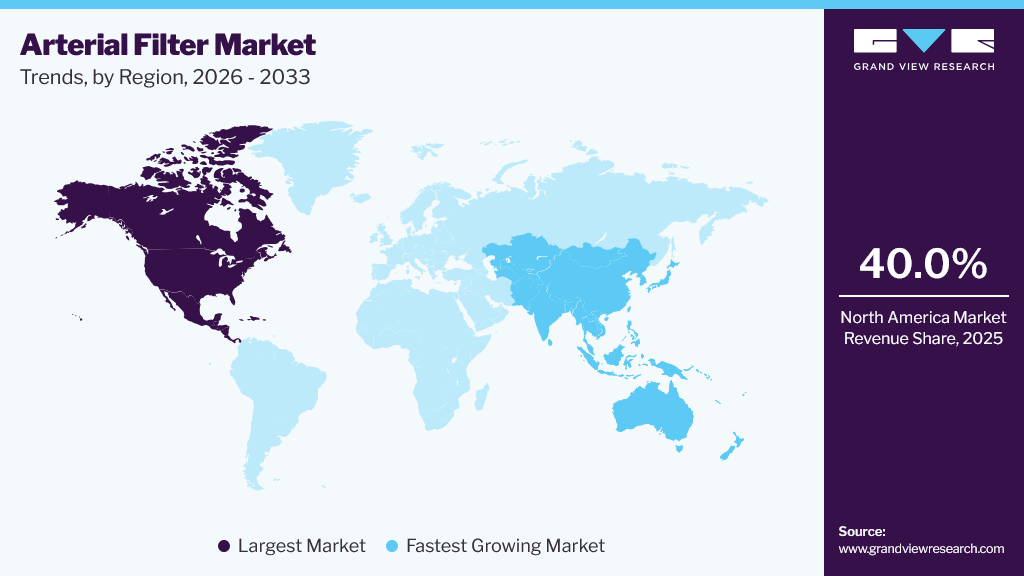
The North America arterial filter market held the largest global share, at around 40.0% in 2025. It is driven by expanding cardiac care infrastructure, rising healthcare investment, public sector initiatives to improve surgical outcomes, and ongoing technology reinvestment. Widespread adoption of best-practice guidelines for extracorporeal circulation and strong ties between clinical centers and device innovators foster rapid adoption of next-generation filters. In addition, regional emphasis on procedural efficiency and patient safety encourages hospitals to standardize the use of advanced arterial filtration in adult and pediatric bypass programs.
 To learn more about this report, Download Free Sample Report
U.S. Arterial Filter Market Trends
The arterial filter industry in the U.S. held the highest share of the North American market in 2025. The country has the highest global volume of cardiac bypass surgeries, supportive Centers for Medicare & Medicaid Services (CMS) reimbursement policies, and a dynamic ecosystem of medical device R&D. Stringent FDA requirements for device safety and efficacy drive manufacturers to improve filter materials and designs continuously. In addition, the expansion of ambulatory surgical centers that perform select cardiac procedures is driving demand for compact, high-performance arterial filters tailored for outpatient settings.
Europe Arterial Filter Market Trends
The arterial filter industry in Europe is expected to grow significantly, fueled by rising investments by public healthcare systems in modernizing cardiac surgery suites and a large geriatric population requiring surgical treatments. The region’s focus on cost-effectiveness and centralized tendering processes also compels suppliers to offer filters combining high performance with competitive pricing.
The UK arterial filter industry is driven by a large geriatric population with a high burden of CVDs, extensive public healthcare funding for cardiac surgery, and harmonized regulatory standards under the EU Medical Device Regulation. In addition, Europe's emphasis on value-based healthcare encourages hospitals to standardize high-efficiency arterial filters with low priming volumes and proven biocompatibility, driving the market.
The arterial filter industry in Germany is expected to grow at the fastest CAGR over the forecast period, driven by an aging population, a high prevalence of CVDs, and the highest per-capita rate of cardiac surgeries. The country’s decentralized hospital financing model and Diagnosis-Related Group reimbursement framework allow hospitals to invest in advanced perfusion technologies. At the same time, early health technology assessment pathways facilitate the rapid adoption of innovative devices.
Asia Pacific Arterial Filter Market Trends
The arterial filter industry in Asia Pacific is expected to grow at the fastest CAGR over the forecast period, driven by rising CVD prevalence, expanding tertiary care infrastructure, and increasing healthcare spending across emerging economies. Governments prioritize cardiac surgery capacity through public-private partnerships and insurance reforms. The growing middle-class patient population and improving access to advanced surgical tools support strong adoption of arterial filters designed for varied clinical settings.
China arterial filter industry is driven by the large-scale expansion of healthcare infrastructure and strong government initiatives to improve cardiac care across urban and rural regions. Growing cardiovascular health awareness, with strategic public funding for hospitals and specialty cardiac centers, is creating sustained demand for reliable perfusion consumables, further driving the arterial market in the country.
The arterial filter industry in Japan is expected to grow significantly over the forecast period. Japan’s large elderly population, rising demand for cardiac interventions, and the country’s comprehensive public health insurance system support growth. A well-developed medical device sector and supportive regulatory framework enable rapid adoption of new filtration technologies. Emphasis on patient safety and procedural efficiency drives manufacturers to develop compact filters that are easy to integrate into existing perfusion setups and feature design elements aligned with the country’s focus on innovation and quality of care.
Latin America Arterial Filter Market Trends
The arterial filter industry in Latin America is driven by rapidly growing surgical capacity as countries expand tertiary hospitals and specialized heart centers to address rising CVD burdens. Public–private partnerships further boost growth, with joint ventures equipping new facilities with modern Cardiopulmonary Bypass (CPB) suites incorporating up-to-date arterial filtration technology.
Middle East and Africa Arterial Filter Market Trends
The arterial filter industry in the Middle East & Africa is growing due to the rising prevalence of CVDs, increasing numbers of cardiac surgeries, and expanding healthcare infrastructure. In addition, improved access to healthcare, government health initiatives, medical tourism, a high incidence of CHDs, the region's reliance on imports, and emerging local manufacturing efforts further drive the market growth.
Key Arterial Filter Company Insights
Some of the leading companies in the arterial filter industry are Medtronic, Pall Corporation (a Danaher Company), Fresenius Medical Care AG, and Terumo Corporation. These companies prioritize new product development, Research & Development (R&D) investments, and strategic M&As to strengthen their market positions.
Key Arterial Filter Companies
The following key companies have been profiled for this study on the arterial filter market:
-
Medtronic plc
-
Pall Corporation (a Danaher Company)
-
Fresenius Medical Care AG
-
Terumo Corporation
-
Nipro Corporation
-
Haemonetics Corporation
-
ICU Medical, Inc.
-
Braile Biomédica S.A.
-
LivaNova PLC
-
EUROSETS S.r.l.
Recent Developments
-
In April 2024, Terumo Corporation expanded the availability of its CAPIOX FX Advance Oxygenator with Integrated Arterial Filter into additional global markets. The system features improved flow dynamics, enhanced removal of gaseous microemboli, and lower priming volumes, supporting safer and more efficient cardiopulmonary bypass procedures.
Arterial Filter Market Report Scope
Report Attribute
Details
Market size in 2025
USD 651.3 million
Estimated market size in 2026
USD 688.8 million
Projected market size by 2033
USD 1,022.7 million
Growth rate
CAGR of 5.8% from 2026 to 2033
Base year for estimation
2025
Actual data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, trends, and product outlook
Segments covered
Age category, end-use, region
Regional Scope
North America; Europe; Asia Pacific; Latin America; MEA
Country Scope
U.S.; Canada; UK; Germany; Italy; France; Spain; Denmark; Sweden; Norway; Japan; China; India; South Korea; Australia; Thailand; Brazil; Mexico; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
Medtronic plc; Pall Corporation (a Danaher Company); Fresenius Medical Care AG; Terumo Corporation; Nipro Corporation; Haemonetics Corporation; ICU Medical, Inc.; Braile Biomédica S.A.; LivaNova PLC; EUROSETS S.r.l.
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Arterial Filter Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global arterial filter market report based on age category, end-use, and region:
- Age Category Outlook (Revenue, USD Million, 2021 - 2033)
- Adult
- Neonatal/ Pediatric
- End-use Outlook (Revenue, USD Million, 2021 - 2033)
- Hospitals
- Ambulatory Surgical Centers
- Others
- Regional Outlook (Revenue, USD Million, 2021 - 2033)
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- Germany
- France
- Italy
- Spain
- Denmark
- Sweden
- Norway
- Asia Pacific
- China
- Japan
- India
- Australia
- South Korea
- Thailand
- Latin America
- Brazil
- Argentina
- Middle East and Africa (MEA)
- South Africa
- Saudi Arabia
- UAE
- Kuwait
- North America
Frequently Asked Questions About This Report
The global arterial filter market size was valued at USD 651.3 million in 2025 and is estimated at USD 688.8 million for 2026.
The global arterial filter market is expected to grow at a CAGR of 5.8% from 2026 to 2033, reaching USD 1,022.7 million.
The North America region dominated the global arterial filter market, accounting for approximately 40.0% of revenue in 2025. It is driven by expanding cardiac care infrastructure, rising healthcare investment, public sector initiatives to improve surgical outcomes, and ongoing technology reinvestment.
Key players in the market include Medtronic plc, Pall Corporation (a Danaher Company), Fresenius Medical Care AG, Terumo Corporation, Nipro Corporation, Haemonetics Corporation, ICU Medical, Inc., Braile Biomédica S.A., LivaNova PLC, and EUROSETS S.r.l., among others.
The adult segment accounted for the largest revenue share of over 75.0% in 2025.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


