
- Home
- »
- Pharmaceuticals
- »
-
: Asia Pacific Medical Foods Market Size & Share Report 2033GVR Report cover

Asia Pacific Medical Foods Market (2026 - 2033)
Size, Share & Trends Analysis Report By Route Of Administration (Oral, Enteral), By Product (Powder, Pills, Liquid), By Application (Diabetic Neuropathy, ADHD), By Modules, By Sales Channel, By Country, And Segment Forecasts
Market Size, 2025
$7.3BMarket Estimate, 2026
$7.8BMarket Forecast, 2033
$11.9BCAGR, 2026–2033
6.2%Asia Pacific Medical Foods Market Summary
The Asia Pacific medical foods market size was valued at USD 7.3 billion in 2025 and is projected to grow from USD 7.8 billion in 2026 to USD 11.9 billion by 2033, at a CAGR of 6.2% from 2026 to 2033. China dominated the market, accounting for the largest revenue share of 33.0% in 2025. The region has a large patient pool and geriatric population, and lifestyle changes are leading to an increase in the prevalence of various diseases, such as cancer, diabetes, gastrointestinal disorders, & autoimmune diseases.
Key Market Trends & Insights
- By product: The powder segment accounted for the largest market revenue share of 36.0% in 2025.
- By route of administration: The oral segment led the market and accounted for 73.4% of the total revenue in 2025.
- By application: The cancer segment dominated the market with the largest revenue share of 12.3% in 2025.
- By module: The protein module segment dominated the market with the largest revenue share of 12.9% in 2025.
- By sales channel: The Direct-to-consumer (DTC) sales channel segment held the largest share of 60.9% in 2025.
Market Size & Forecast
- Market size in 2025: USD 7.3 Billion
- Estimated market size in 2026: USD 7.8 Billion
- Projected market size by 2035: USD 11.9 Billion
- CAGR (2026-2033): 6.2%
Prism AI by Grand View Research Free to tryAsk a question about the asia pacific medical foods market✓Every figure cited from GVR research Prefer the report? Download free sample →According to data published by the WHO in February 2023, Thailand had 12 million elderly people out of a population of 67 million, with the elderly population expected to reach 28% within the next decade, increasing the demand for medical foods to address age-related nutritional needs.
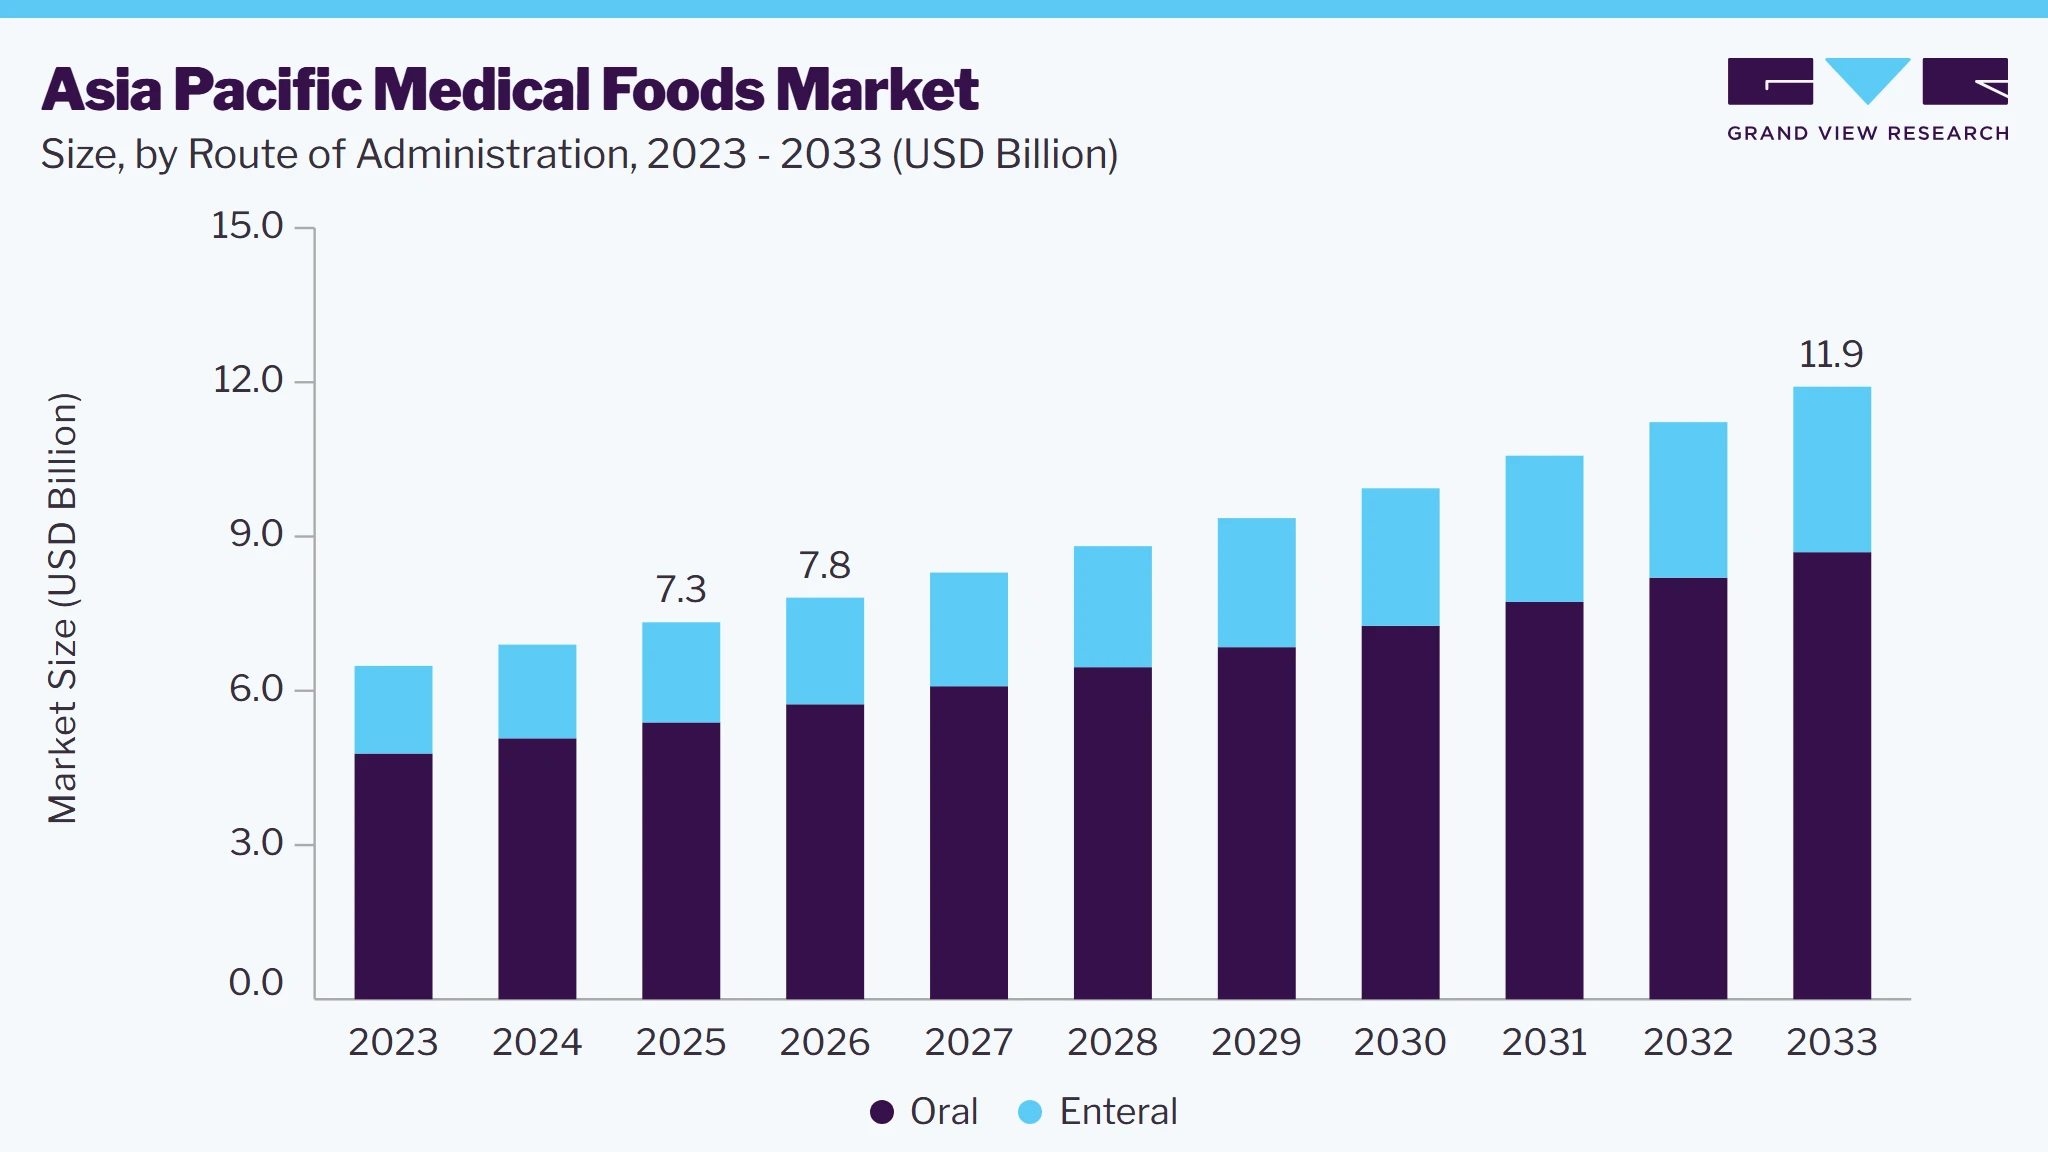 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Market Dynamics
The industry is witnessing significant growth, driven by the rising prevalence of chronic diseases, increasing nutritional deficiencies, and growing demand for specialized nutrition among preterm infants and aging populations. Expanding healthcare infrastructure, greater awareness of disease-specific nutrition, and increasing adoption of specialized dietary products are supporting market expansion. In addition, rising healthcare expenditure and advancements in medical nutrition formulations are expected to sustain market growth over the forecast period.
Government initiatives and evolving regulatory frameworks across Asia Pacific are expected to support the growth of the medical foods industry. For instance, in May 2023, Japan's Consumer Affairs Agency revised the labeling guidelines for Food for Special Dietary Uses (FOSDU), allowing companies to seek certification for Oral Rehydration Solution (ORS) products. The amendment created a new category for ORS products, potentially encouraging product development for specific medical conditions, including dehydration caused by illness or post-surgical recovery.
Similarly, China has progressively strengthened its regulatory framework for Foods for Special Medical Purposes (FSMPs), with regulatory oversight managed by the National Medical Products Administration (NMPA). The evolving regulatory environment, product registration processes, and potential expansion of reimbursement coverage are expected to support market growth. As of September 2024, China had 206 registered FSMPs, reflecting the expanding availability of specialized nutritional products in the country, with key examples highlighted in the table below.
Source: CIRS GroupSr. No.
Applicant
Product Name
Dosage Form
Certificate Number
Expiry Date
1
MEAD JOHNSON B.V.
Enfagrow infant lactose free formula (powder) for special medical purpose
Powder
国食注字TY20185005
2028.7.17
2
NESTLE NEDERLAND B.V.
早瑞能恩 preterm/low birth weight infant formula for special medical purpose
Powder
国食注字TY20185006
2028.7.17
3
HANGZHOU BEINGMATE MATERNAL AND CHILD NUTRITION CO., LTD.
Beingmate infant lactose free formula for special medical purpose
Powder
国食注字TY20180001
2028.1.17
4
SUZHOU HENGRUI JIANKANG TECHNOLOGY CO., LTD
乐赋 electrolyte formula for special medical purpose
Liquid
国食注字TY20180002
2028.6.12
5
SUZHOU HENGRUI JIANKANG TECHNOLOGY CO., LTD
乐棠 electrolyte formula for special medical purpose
Liquid
国食注字TY20180003
2028.5.30
Reimbursement and insurance limitations may restrain the growth of the Asia Pacific medical foods market, particularly in emerging economies where specialized nutritional products are often not fully covered under public or private health insurance schemes. High out-of-pocket expenses may limit product adoption among patients requiring long-term nutritional management, especially those with chronic diseases and complex medical conditions.
In addition, variations in reimbursement policies and healthcare coverage across countries may create disparities in access to medical foods. Limited reimbursement support can reduce affordability and discourage healthcare providers and patients from choosing specialized products, thereby restricting market penetration and overall growth in price-sensitive markets.
Market Concentration & Characteristics
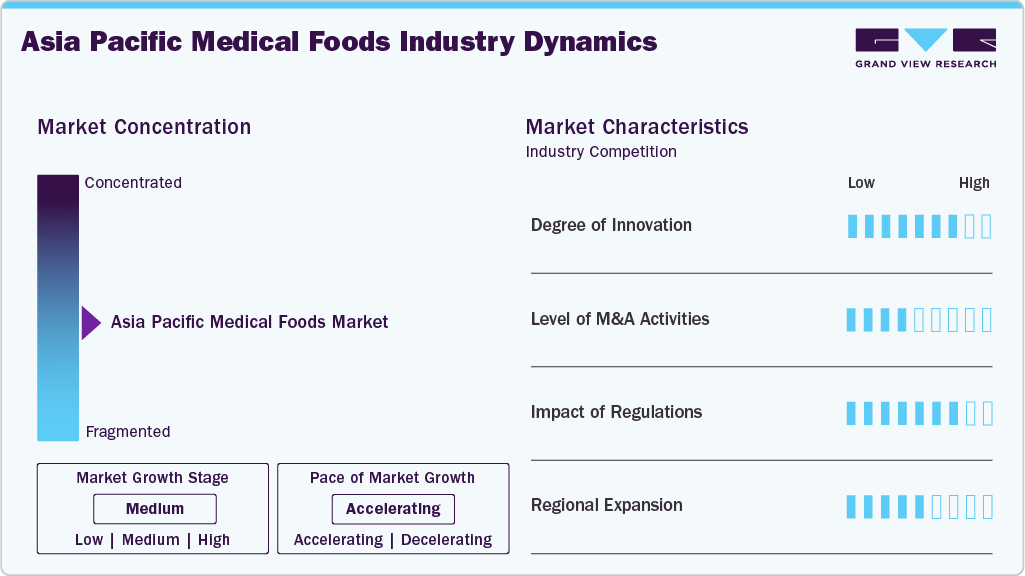
The degree of innovation in the industry is high. Leading manufacturers are focusing on increasing partnerships with hospitals and are targeting different population cohorts to gain large market shares. For instance, in August 2024, Danone India (NIPL) and Apollo 24|7 partnered to launch the Super 6 Diabetes Program, targeting India’s growing diabetes epidemic. As the exclusive nutrition partner, Danone would provide Protinex Diabetes Care (PDC), formulated as a Food for Special Dietary Use (FSDU) to support diabetes management. PDC features high dietary fiber for gradual sugar absorption, reduced carbohydrates, and a low Glycemic Index (GI) to help regulate blood sugar levels.
Mergers, acquisitions, and strategic partnerships enable companies to expand their geographic presence, strengthen manufacturing and supply chain capabilities, and enhance their specialized nutrition portfolios. For instance, in August 2025, The a2 Milk Company acquired Yashili New Zealand Dairy Co. Limited from China Mengniu Group for approximately NZD 282 million. The acquisition strengthened the company's manufacturing and supply chain capabilities and supported its expansion in China's infant nutrition market, thereby contributing to the growth of the regional medical foods market.
 To learn more about this report, Download Free Sample Report
The industry is subject to moderate regulatory impact, as regulatory requirements govern product composition, labeling, safety, and market authorization. For instance, in Australia and New Zealand, Standard 2.9.5 of the Food Standards Code regulates the composition, labeling, and sale of foods for special medical purposes (FSMPs), with requirements broadly aligned with international regulatory frameworks. These regulations ensure product safety and quality while influencing market entry and product commercialization.
Geographic expansion drives the industry by enabling access to diverse resources, increasing market penetration and revenue, and fostering regulatory compliance and standardization. For instance, in November 2023, Danone launched its first medical nutrition product, Fortimel, for adults in China, categorized under foods for special medical purposes. This launch is a crucial component of Danone’s strategy in China, aimed at utilizing its scientific expertise across all life stages and promoting the growth of the adult medical nutrition segment.
“The launch of Fortimel Balanced is another milestone on Danone’s ‘Innovated in China, Made in China’ journey. The product leverages Danone’s cutting-edge science and research capability to cater to the nutritional needs of Chinese patients. It marks a solid step into the aFSMP market in China, and helps Danone to further grow its portfolio covering the full life spectrum.”
- Bruno Chevot, Danone’s President China, North Asia and Oceania
Analyst Perspective
The industry is driven by the rising prevalence of chronic and metabolic disorders, the increasing geriatric population, and growing awareness of specialized nutritional products. Expanding healthcare expenditure, improving access to clinical nutrition, and rising demand for disease-specific dietary solutions are supporting market development. In addition, increasing investments by manufacturers in product innovation and distribution expansion are expected to create new growth opportunities, while growing adoption of medical foods in hospitals and home-care settings is likely to sustain long-term market expansion.
Route of Administration Insights
The oral segment led the market and accounted for 73.4% of the total revenue in 2025. Increased preference for orally administered products, commercial viability, and supportive initiatives drive the demand for medical foods. Generally, most people requiring Oral Nutritional Supplements (ONS) are treated using standard ONS products with a calorific value of 1.5 to 2.4 Kcal/ml. These products are available in different flavors to suit patient requirements. Moreover, increased preference for orally administered products, commercial viability, and supportive initiatives are key factors driving the demand for orally administered medical foods.
The enteral segment is expected to witness the fastest growth over the forecast period. The demand for enteral feeding formulas is increasing due to the rising prevalence of chronic diseases, such as cancer and cardiovascular diseases, which may lead to metabolic complications and difficulty in consuming food during treatment. In critically ill patients, enteral nutrition plays an important role in preventing undernutrition and loss of lean body mass, particularly during catabolic states associated with systemic inflammation. The growing adoption of enteral nutrition in critical care settings and increasing awareness of its clinical benefits are expected to support segment growth in the market.
Product Insights
The powder segment accounted for the largest revenue share of 36.0% in 2025. Medical foods are mostly available in powder form, which can be administered through the oral route or enteral route by mixing with milk or water, as advised by the physician. Medical foods in the powdered formula are suitable for patients of all age groups, especially in the oral route. Owing to a high preference for powdered formulations due to ease of consumption, manufacturers are developing product categories in line with consumer preferences.
The liquid segment is anticipated to grow at the fastest CAGR during the forecast period, owing to the rising adoption of liquid formulations in the pediatric and geriatric population, where the intake of solid formulations is limited or impossible, and in cases of clinically diagnosed dysphagia or when oral physiology is limited. Moreover, liquid-formulated food helps to maintain the sufficient hydration and electrolyte balance, thereby supporting segment growth.
Application Insights
The cancer segment dominated the market with the largest revenue share of 12.3% in 2025. The segment is driven by the rising prevalence of cancer and the growing incidence of malnutrition among patients undergoing cancer treatment. Increasing adoption of specialized medical foods to support nutritional requirements, maintain body weight, and manage treatment-related nutritional deficiencies is expected to further drive segment growth. For instance, in August 2024, the release of the Clinical Oncology Society of Australia (COSA) Cancer-related Malnutrition and Sarcopenia Implementation Toolkit provided multidisciplinary healthcare professionals in Australia with a practical resource to improve the management of malnutrition and sarcopenia in cancer patients. This toolkit follows COSA's national Position Statement on Cancer-Related Sarcopenia and Malnutrition, emphasizing the need for standardized practices to address these conditions. Cancer-related malnutrition and sarcopenia, affecting one in three cancer patients, are expected to contribute to market growth.
The Parkinson's Disease (PD) segment is expected to grow at the fastest CAGR during the forecast period, driven by the rising prevalence of neurodegenerative disorders and increasing demand for specialized nutritional support. Medical foods containing omega-3 fatty acids, coenzyme Q, and vitamins D and B, along with ketogenic diets and probiotics, are increasingly being explored to support nutritional management and complement pharmacological treatment, thereby driving segment growth.
Modules Insights
The protein module segment dominated the market with the largest revenue share of 12.9% in 2025. Protein modules are used in severe infections, trauma, burns, malnutrition, post-surgery recovery, and critically ill patients. The increasing prevalence of chronic diseases, such as cancer, chronic kidney disease, and malnutrition, which require specialized nutritional interventions likely drive the segment growth. Patients undergoing treatments like chemotherapy or dialysis often suffer from muscle wasting and protein deficiencies, boosting demand for protein-enriched medical foods. In addition, the aging population, particularly in developed countries, further contributes to the need for protein modules to combat age-related muscle loss (sarcopenia).
The hypoallergic module segment is anticipated to grow at the fastest CAGR during the forecast period. The growth is driven by the increasing prevalence of food allergies and intolerances, especially among infants and individuals with chronic health conditions. Hypoallergenic medical foods cater to patients with specific dietary needs, such as those unable to tolerate proteins found in common foods like cow's milk or soy. These products are formulated to minimize allergenic responses and are crucial for managing conditions like severe food allergies, eosinophilic esophagitis, and gastrointestinal disorders. The rising awareness of food-related health issues and advancements in hypoallergenic formulations, such as amino acid-based or extensively hydrolyzed proteins, are expected to further support segment expansion over the forecast period.
Sales Channel Insights
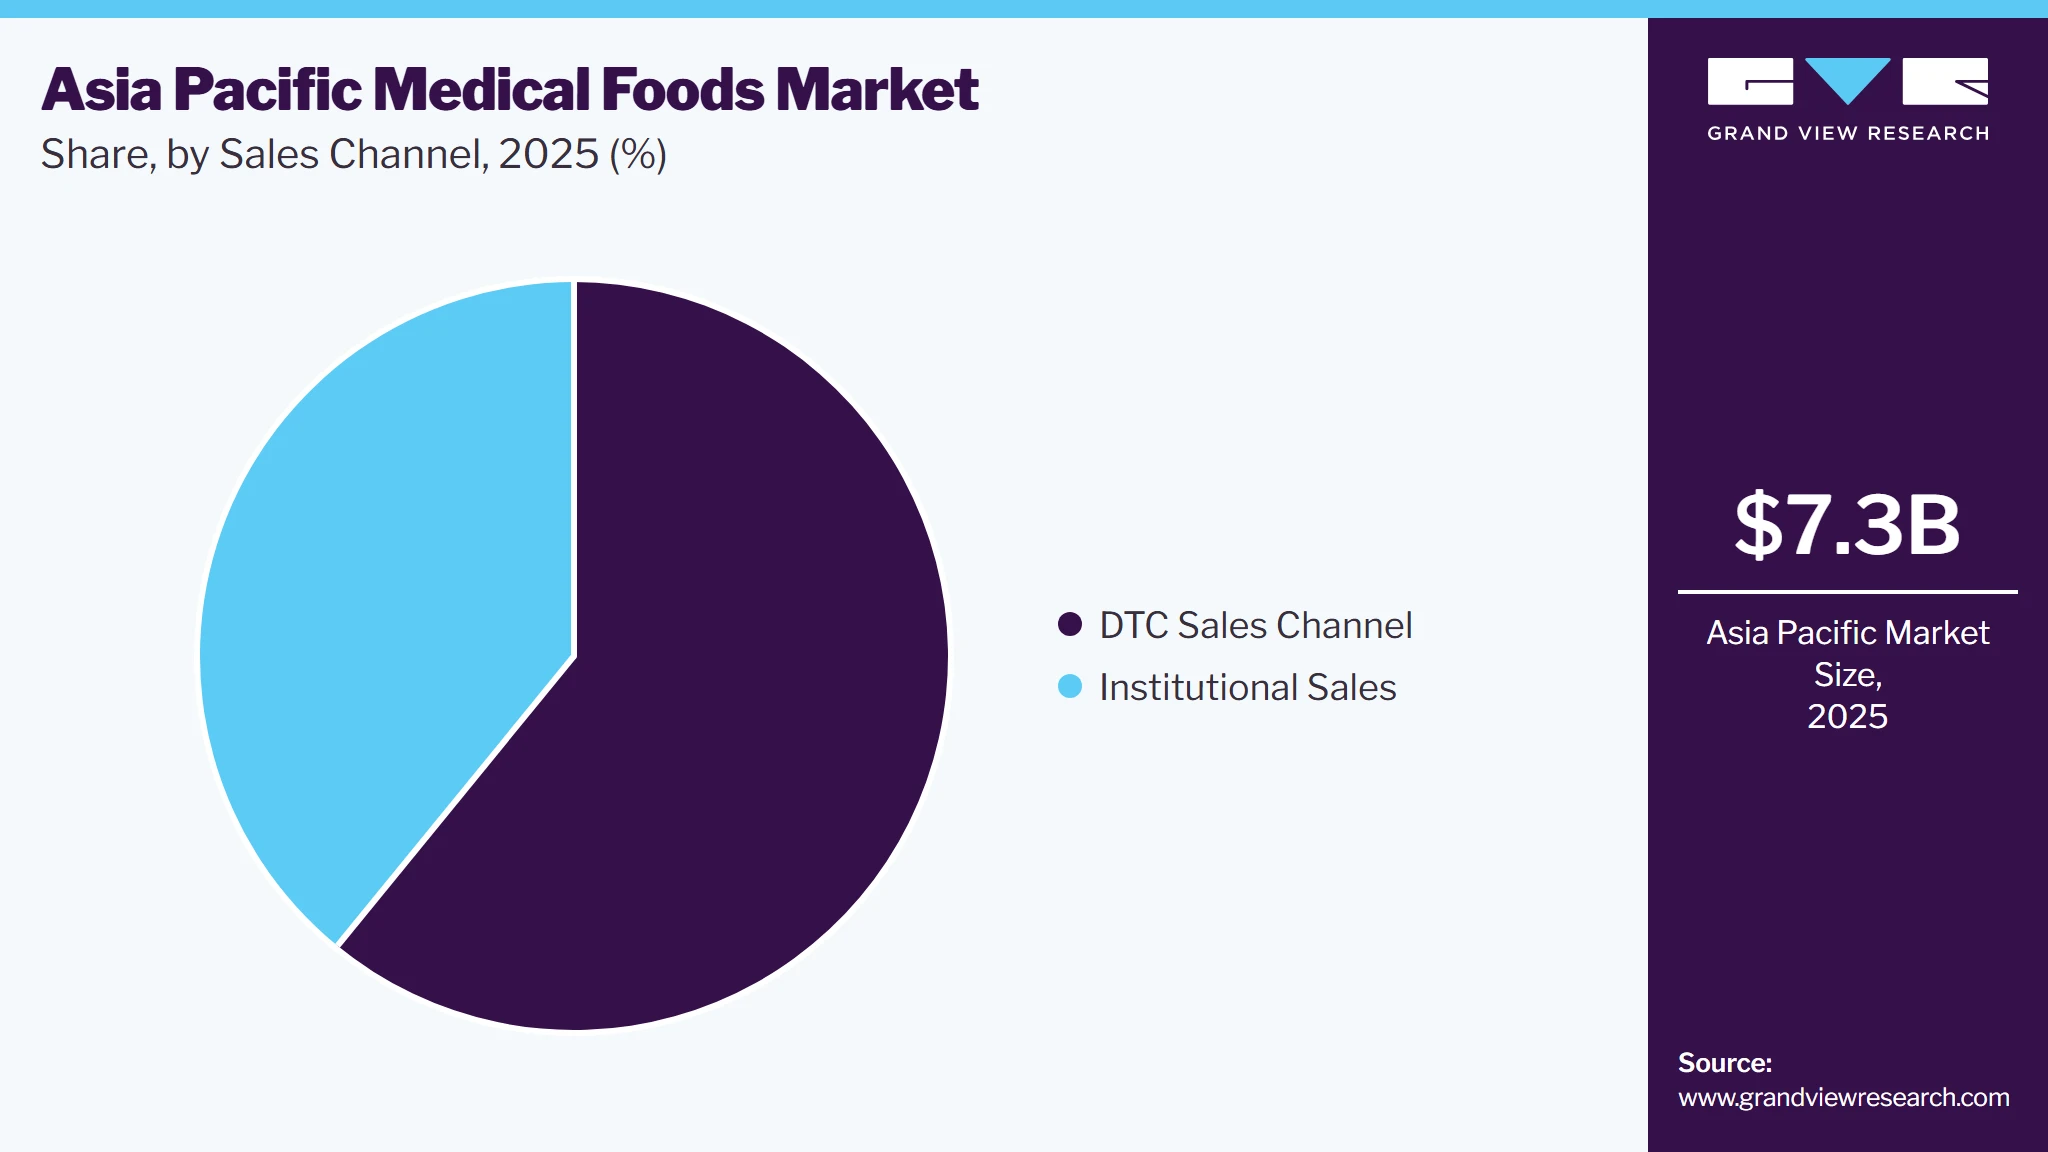
The Direct-to-consumer (DTC) sales channel segment held the largest share of 60.9% in 2025 and is expected to grow at the fastest CAGR during the forecast period. DTC sales have emerged as a significant channel within the medical foods market, providing opportunities for manufacturers to engage directly with consumers and tailor their offerings to meet specific health needs. DTC sales in the medical foods sector allow companies to bypass traditional retail channels and establish a direct relationship with end users. This model has gained traction due to its ability to provide personalized customer experiences and strengthen brand loyalty. By leveraging online platforms, companies can offer detailed product information, educational resources, and tailored recommendations based on individual health conditions.
 To learn more about this report, Download Free Sample Report
The institutional sales segment is anticipated to grow significantly over the forecast period. The segment's growth is driven by increasing recommendations from doctors to use medical foods. Institutions that purchase medical foods include hospitals, long-term care centers, hospices, clinics, and disability facilities. Since the consumption of medical foods is recommended under medical supervision, the revenue generated through institutional sales is the highest. In addition, training programs for healthcare professionals on the benefits of medical foods further enhance their adoption within institutions. As awareness grows among clinicians about the efficacy of these products in improving patient outcomes, institutional sales are expected to witness significant growth.
Country Insights
China Medical Foods Market Trends
The China medical foods market dominated with a share of 33.0% in 2025, due to an increasing geriatric population and growing FSMP approvals. A UN report indicates that the elderly population in China is projected to double from 10% in 2017 to 20% by 2037. This growing geriatric demographic, along with higher per capita healthcare spending and the growing prevalence of esophageal cancer, is anticipated to be a key market driver.
Japan Medical Foods Market Trends
The medical foods market in Japan is driven by the growing geriatric population. Regulatory support and streamlined approval processes for medical foods in Japan, along with advancements in product formulation and innovation, are contributing to market expansion. For instance, in August 2024, Wada Calcium Pharmaceutical, a company with over 110 years of expertise in calcium-based products, launched a new Food with Function Claims (FFC) designed to enhance bone and immune health in older adults. Their latest offering, the "Bone Density & Immune Care Tablet," is the company’s first FFC formulated with calcium maltobionate and postbiotics. This product incorporates Kirin’s Lactococcus lactis strain Plasma (LC-plasma) postbiotics, along with its signature calcium maltobionate, to support overall health in aging individuals.
India Medical Foods Market Trends
The medical foods market in India is expected to grow at the fastest CAGR of 6.7% over the forecast period, driven by the rising prevalence of malnutrition and diabetes. The increasing burden of diabetes is expected to fuel demand for specialized nutritional products designed to support disease management and address associated nutritional requirements. According to the India Diabetes (INDIAB) study published by the Indian Council of Medical Research (ICMR) in 2023, around 1.2 million people have diabetes, highlighting the substantial disease burden and potential demand for medical foods.
Key Medical Foods Company Insights
Some of the key players operating in the market include Danone, Nestlé, Fresenius Kabi AG and Abbott. Key innovators in the market are utilizing strategies like new product launches to enhance their market presence. For instance, Nestlé, a global player in specialized nutrition, has been actively expanding its range of medical nutrition products in Vietnam. Its offerings include products like Peptamen, a specialized formula for patients with compromised gastrointestinal function, and Resource, aimed at addressing malnutrition in the elderly and individuals recovering from illness.
Key Medical Foods Companies
-
Mead Johnson & Company, LLC
-
SHS International Ltd
-
Synutra International Ltd
-
Milupa Gmbh
-
Danone
-
Nestlé
-
Abbott
-
Fresenius Kabi AG
-
GSK plc
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Danone, Nestlé, Abbott, Fresenius Kabi AG, etc.)
Strengthen market presence through product innovation, strategic partnerships, localized manufacturing, and expansion across emerging Asia Pacific markets.
Strong brand recognition, extensive distribution networks, and established relationships with hospitals, healthcare professionals, and retail channels.
Complex regulatory requirements and varying medical food standards across Asia Pacific countries can increase product development and market entry costs.
Emerging Players (SHS International Ltd, Synutra International Ltd, Milupa GmbH)
Expand regional presence through targeted distribution partnerships, specialized product development, and focus on underserved medical nutrition segments.
Strong expertise in niche medical nutrition categories and specialized formulations tailored to specific patient needs.
Greater dependence on specific product categories and exposure to pricing pressure from larger global and regional competitors.
Recent Developments
-
In February 2026, Life Health Foods India Pvt. Ltd. launched a high-protein, plant-based beverage range designed to support active and balanced lifestyles. The product portfolio expanded nutritional offerings by providing consumers with convenient protein-rich alternatives aligned with the growing demand for health-focused dietary products.
-
In September 2024, Dutch Medical Food B.V. and Pristine Pearl Pharma Pvt. Ltd. collaborated to introduce specialized medical nutrition solutions in India. The initiative aimed to enhance patient care by expanding access to targeted nutritional products and addressing the evolving dietary requirements of patients.
-
In August 2024, Avesthagen and Apollo AyurVAID launched medical foods and nutritional supplements in India, combining nutrigenomics-based research with Ayurveda-inspired formulations. The initiative expanded specialized nutritional offerings and targeted personalized dietary management, reflecting growing demand for evidence-based products addressing diverse health and nutritional requirements.
-
In September 2023, Danone announced a EUR 50 million (USD 53.78 million) line expansion of its production facility at Opole, Poland, to meet the increasing demand for medical nutrition worldwide. This move aims to enhance its position in the adult medical nutrition market, with the growing rate of chronic diseases and an aging population. The expansion is anticipated to enable Danone to serve patients across the globe, as many people are expected to require medical nutrition at some point in their lives due to diseases such as cancer and stroke, which can result in malnutrition.
-
In April 2023, Danone acquired ProMedica, a Poland-based company that specializes in providing care services for patients in their homes. This acquisition is part of Danone's lucrative specialized nutrition market expansion strategy to strengthen its presence in Poland.
-
In February 2023, Neslte and EraCal Therapeutics entered into a research collaboration to identify novel nutraceuticals relevant to controlling food intake.
Asia Pacific Medical Food Market Report Scope
Report Attribute
Details
Market size in 2025
USD 7.3 billion
Estimated market size in 2026
USD 7.8 billion
Revenue forecast in 2033
USD 11.9 billion
Growth rate
CAGR of 6.2% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Route of administration, product, application, modules, sales channel, country
Regional scope
Asia Pacific
Country scope
Japan; China; Australia; India; South Korea; Thailand; Vietnam; Malaysia; Indonesia; Singapore
Key companies profiled
Mead Johnson & Company, LLC; SHS International Ltd; Synutra International Ltd; Milupa Gmbh; Danone; Nestlé; Abbott; Fresenius Kabi AG; GSK plc
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Asia Pacific Medical Food Market Report Segmentation
This report forecasts revenue growth at the regional and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the Asia Pacific medical foods market report based on route of administration, product, application, modules, sales channel, and country:
-
Route of Administration Outlook (Revenue, USD Billion, 2021 - 2033)
-
Oral
-
Enteral
-
-
Product Outlook (Revenue, USD Billion, 2021 - 2033)
-
Pills
-
Powder
-
Liquid
-
Others (semisolid, semiliquid)
-
-
Application Outlook (Revenue, USD Billion, 2021 - 2033)
-
Chronic Kidney Disease
-
Minimal Hepatic Encephalopathy
-
Chemotherapy Induced Diarrhoea
-
Pathogen Related Infections
-
Diabetic Neuropathy
-
ADHD
-
Depression
-
Alzheimer's Disease
-
Nutritional Deficiency
-
Orphan Diseases
-
Tyrosinemia
-
Eosinophilic Esophagitis
-
Food Protein Module-induced enterocolitis syndrome (Food Protein Module-induced enterocolitis syndrome (FPIES))
-
Phenylketonuria (PKU)
-
Maple syrup urine disease (Maple syrup urine disease (MSUD))
-
Homocystinuria
-
Others (Urea Cycle Disorder (UCD), Glycogen Storage Disease (GSD), etc.)
-
-
Wound Healing
-
Chronic Diarrhea
-
Constipation Relief
-
Protein Booster
-
Dysphagia
-
Pain Management
-
Parkinson's Disease
-
Epilepsy
-
Other Cancer related treatments
-
Severe Protein Allergy
-
Cancer
-
Cachexia
-
Other (debilitating conditions, COPD, etc.)
-
-
Modules Outlook (Revenue, USD Billion, 2021 - 2033)
-
Amino Acid Module
-
Protein Module
-
Vitamin & Mineral Modules
-
Fatty Acid based Modules
-
Carbohydrate Modules
-
Fiber Modules
-
Ketogenic Modules
-
Peptide based Modules
-
Hypoallergic Modules
-
Others (Electrolyte Module, etc.)
-
-
Sales Channel Outlook (Revenue, USD Billion, 2021 - 2033)
-
DTC Sales Channel
-
Online Sales
-
Retail Sales
-
-
Institutional Sales
-
Hospitals
-
Others (Long-term Care Facilities, etc.)
-
-
-
Country Outlook (Revenue, USD Billion, 2021 - 2033)
-
Japan
-
China
-
Australia
-
India
-
South Korea
-
Thailand
-
Vietnam
-
Malaysia
-
Indonesia
-
Singapore
-
Research Methodology
The Asia Pacific medical foods market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each Asia Pacific medical foods segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment-Route of Administration
Revenue Capture Definition
Oral
Revenue generated from medical food products administered orally and consumed directly by patients to provide specialized nutritional support for managing disease-specific dietary requirements. This route includes formulations delivered in various product forms, such as pills, powders, liquids, and other oral formats, for individuals capable of consuming medical nutrition by mouth.
Enteral
This segment captures income from medical foods delivered through enteral feeding methods to patients who are unable to meet their nutritional requirements through regular oral intake. Products are administered through feeding tubes and support individuals with severe dysphagia, neurological disorders, chronic diseases, and other conditions requiring specialized nutritional intervention.
Segment- Product Type
Revenue Capture Definition
Pills
Revenue derived from medical food products formulated in pill-based formats to provide concentrated nutrients and disease-specific nutritional components. These products offer convenient administration and are utilized for managing specialized nutritional requirements associated with various medical conditions.
Powder
This segment represents income from powdered medical food formulations that are typically mixed with water, beverages, or other suitable foods before consumption or administration. These products enable flexible dosing and customized nutritional supplementation across clinical and home-care settings.
Liquid
Market value in this category stems from ready-to-use or concentrated liquid medical foods designed to provide complete or supplemental nutrition. These formulations are particularly suitable for patients experiencing swallowing difficulties or requiring easily consumable nutritional support.
Others (semisolid, semiliquid)
Includes revenue from alternative medical food formats, including semisolid and semiliquid formulations, developed to facilitate nutritional intake among patients with specific dietary, swallowing, or disease-related requirements.
Segment- Application
Revenue Capture Definition
Chronic Kidney Disease
Revenue generated from medical foods formulated to address the specialized nutritional requirements of individuals with chronic kidney disease. These products help manage nutrient intake and support dietary interventions involving proteins, electrolytes, minerals, and other nutrients under medical supervision.
Minimal Hepatic Encephalopathy
This segment captures income from disease-specific medical foods designed to provide nutritional support for patients with minimal hepatic encephalopathy by addressing altered nutritional requirements associated with impaired liver function.
Chemotherapy Induced Diarrhoea
Market value arises from medical food products intended to provide nutritional support and help manage dietary requirements among cancer patients experiencing diarrhea associated with chemotherapy treatment.
Pathogen Related Infections
Revenue originates from specialized medical foods used to support nutritional requirements during pathogen-related infections, helping maintain nutritional status and support recovery in affected patients.
Diabetic Neuropathy
This segment reflects earnings from medical foods designed to provide specialized nutritional support for individuals experiencing diabetic neuropathy, with formulations intended to complement dietary management and address specific nutritional needs.
ADHD
Revenue generated from medical food products formulated to support the nutritional requirements of individuals with attention-deficit/hyperactivity disorder (ADHD), particularly where specific dietary interventions are recommended as part of clinical management.
Depression
This category captures income from specialized medical foods intended to address nutritional requirements associated with depression and support dietary management under healthcare professional supervision.
Alzheimer's Disease
Market value in this segment stems from medical foods formulated to provide nutritional support for individuals with Alzheimer's disease, including products designed to address disease-associated nutritional challenges and maintain adequate nutrient intake.
Nutritional Deficiency
Revenue derived from medical foods developed to address specific nutrient deficiencies arising from inadequate intake, impaired absorption, metabolic disorders, or increased nutritional requirements.
Orphan Diseases
Revenue generated from specialized medical foods developed to address the unique nutritional requirements associated with rare and orphan diseases. These products provide disease-specific nutritional support for patients with inherited metabolic disorders and other rare conditions requiring specialized dietary management, including disorders involving amino acid, protein, and metabolic pathways.
Wound Healing
This segment encompasses income from specialized medical foods containing nutrients that support tissue repair, collagen formation, immune function, and recovery in patients with wounds or compromised healing capacity.
Chronic Diarrhea
Revenue generated from medical food products designed to provide nutritional support for individuals experiencing persistent diarrhea, helping address nutrient losses and support dietary management.
Constipation Relief
This category reflects earnings from medical foods formulated to support bowel regularity and dietary management in individuals experiencing constipation through specialized nutritional components.
Protein Booster
Market value stems from protein-enriched medical foods intended to supplement dietary protein intake among individuals with increased protein requirements or inadequate protein consumption due to disease or nutritional challenges.
Dysphagia
Revenue originates from medical foods developed for individuals with swallowing difficulties, providing appropriately formulated nutritional support through products that facilitate safer and more manageable intake.
Pain Management
This segment captures income from specialized medical foods used as part of nutritional management strategies for individuals experiencing chronic or disease-associated pain.
Parkinson's Disease
Revenue generated from medical foods formulated to support nutritional management among individuals with Parkinson's disease, addressing specific dietary requirements that may arise from disease progression and treatment.
Epilepsy
This category includes income from medical foods designed to support specialized dietary interventions for epilepsy, including nutritional formulations associated with ketogenic and other medically supervised dietary approaches.
Other Cancer Related Treatments
This segment reflects revenue from medical foods used alongside cancer-related treatments to address nutritional challenges, support dietary requirements, and help maintain nutritional status during treatment and recovery.
Severe Protein Allergy
Market value arises from specialized medical foods formulated for individuals with severe protein allergies, providing nutritionally adequate alternatives while limiting exposure to specific allergenic proteins.
Cancer
Revenue derived from medical foods developed to address the nutritional needs of cancer patients, including products intended to support nutritional status, manage disease-related malnutrition, and complement clinical care.
Cachexia
This segment captures income from medical foods designed to provide nutritional intervention for patients experiencing cachexia, supporting energy and nutrient intake in conditions associated with severe weight and muscle loss.
Other (debilitating conditions, COPD, etc.)
Includes revenue from medical foods used for additional debilitating conditions and chronic disorders, including chronic obstructive pulmonary disease (COPD) and other medical conditions requiring specialized nutritional management.
Segment- Modules
Revenue Capture Definition
Amino Acid Module
Revenue generated from medical food formulations containing specific amino acids or amino acid combinations designed to meet disease-specific nutritional requirements and support metabolic management in patients with specialized dietary needs.
Protein Module
This segment captures income from protein-based medical food formulations developed to provide supplemental or complete protein nutrition for individuals with disease-related malnutrition, increased nutritional requirements, or impaired dietary intake.
Vitamin & Mineral Modules
Market value in this category stems from medical foods containing essential vitamins and minerals formulated to address nutritional deficiencies and support physiological functions in patients requiring specialized dietary intervention.
Fatty Acid Based Modules
Revenue originates from medical food formulations enriched with specific fatty acids, including essential and specialized lipid components, to support energy provision and disease-specific nutritional requirements.
Carbohydrate Modules
This segment reflects earnings from medical foods containing tailored carbohydrate sources designed to provide energy while addressing specific metabolic or dietary requirements associated with medical conditions.
Fiber Modules
Revenue derived from fiber-based medical food formulations intended to support digestive health, bowel regularity, and nutritional management in patients with specific gastrointestinal and metabolic requirements.
Ketogenic Modules
This category captures income from medical foods formulated around high-fat, low-carbohydrate nutritional profiles used primarily in medically supervised dietary interventions, particularly for epilepsy and selected metabolic conditions.
Peptide Based Modules
Market value stems from medical food products incorporating specialized peptides designed to provide easily utilized nutritional components and support targeted nutritional requirements in patients with specific medical conditions.
Hypoallergic Modules
Revenue generated from medical food formulations designed to minimize allergic reactions by utilizing extensively hydrolyzed, amino acid-based, or otherwise modified nutritional components for individuals with food allergies or intolerances.
Others (Electrolyte Module, etc.)
Includes revenue from medical food modules incorporating other specialized nutritional components, such as electrolytes and other disease-specific nutrients, developed to address specialized dietary requirements.
Segment- Sales Channel
Revenue Capture Definition
DTC Sales Channel
Revenue generated through direct-to-consumer channels that enable patients and caregivers to purchase medical food products without relying exclusively on institutional procurement pathways. This segment includes online sales platforms and retail sales outlets that provide access to specialized nutritional products for home-based use and ongoing dietary management.
Institutional Sales
This segment captures income from medical foods supplied through institutional healthcare channels, primarily hospitals and other care facilities such as long-term care institutions. Products distributed through these channels are used to support patients requiring medically supervised nutritional intervention and specialized dietary management.
Estimation Model
Methodology Stage
Analysis / Component
Details
Top-Down
Commodity Flow Analysis
Market size was estimated by analyzing revenues generated by key medical food manufacturers and suppliers operating across Asia Pacific, supported by company annual reports, investor presentations, product portfolios, distributor insights, and premium industry databases. Revenue contributions from private and regional companies were assessed through secondary research and validated through interviews to derive the overall market value.
Bottom-Up
Demand-Side Analysis
The market was estimated by quantifying the addressable patient population across key medical food applications, diagnosis and treatment rates, eligible patients requiring specialized nutritional intervention, average consumption per patient, and product-specific annual usage. Country-level patient demand was further adjusted for physician prescribing, healthcare access, adoption rates, and average selling prices to derive medical food consumption and market value across Asia Pacific.
Segmentation
Country-Level Segment Share Modeling
Market shares for product type, route of administration, application, modules, and sales channel segments were derived using country-specific disease prevalence, healthcare infrastructure, clinical nutrition practices, reimbursement scenarios, physician awareness, and medical food adoption rates. Weighted-average calculations were applied to determine country, regional, and segment-level market distributions across Asia Pacific.
Validation
Data Triangulation & Validation Model
Market estimates were validated through triangulation of secondary research, primary interviews, company-level revenue assessments, patient population analysis, healthcare utilization data, product adoption trends, and country-level demand assessments to ensure consistency and accuracy across all market segments and Asia Pacific geographies.
Forecasting
Forecasting & CAGR Modeling
Market forecasts were developed using historical demand trends, rising prevalence of chronic and metabolic disorders, aging populations, increasing awareness of specialized nutrition, growth in clinical nutrition practices, healthcare expenditure, and expansion of healthcare infrastructure across Asia Pacific. Regression-based analysis and trend modeling were applied to project future market growth and CAGR.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Cross-Segmentation Analysis of Medical Foods Across Applications and Product Formats
Delivered a detailed cross-segmentation assessment linking medical food applications such as chronic kidney disease, nutritional deficiencies, cancer, diabetes, and orphan diseases with product type formats including pills, powders, liquids, and other formulations. Analysis also covered module types and route of administration to identify demand patterns across key therapeutic and nutritional needs.
Enables clients to identify high-growth application-product combinations, assess unmet nutritional needs, prioritize high-potential product categories, and identify opportunities for targeted portfolio expansion and product development.
Country-Level Market Opportunity & Demand Assessment
Developed a customized country-level assessment across key Asia Pacific markets, including Japan, China, India, Australia, South Korea, Thailand, and Vietnam. Analysis incorporated market size, growth outlook, disease burden, healthcare infrastructure, regulatory environment, adoption patterns, and sales channel dynamics across DTC and institutional channels.
Helps clients identify high-growth countries, evaluate market attractiveness, prioritize geographic expansion, and develop country-specific commercialization and distribution strategies based on local demand and market conditions.
Competitive Benchmarking & Sales Channel Analysis
Conducted detailed benchmarking of key medical food companies based on product portfolios, application coverage, module offerings, geographic presence, pricing and positioning, distribution networks, and strategic initiatives. The analysis also assessed online, retail, hospital, and long-term care sales channels.
Supports clients in evaluating competitive positioning, identifying portfolio and channel gaps, assessing best practices, and developing differentiated market entry, partnership, distribution, and expansion strategies.
Frequently Asked Questions About This Report
The cancer segment dominated the market with the largest revenue share of 12.3% in 2025, while parkinson's Disease (PD) segment is the fastest growing application.
The protein module segment dominated the market with the largest revenue share of 12.9% in 2025, while hypoallergic module segment is the fastest growing modules.
The Direct-to-consumer (DTC) sales channel segment held the largest share of 60.9% in 2025 and is the fastest growing sales channel.
The Asia Pacific medical foods market size was valued at USD 7.3 billion in 2025 and is expected to reach USD7.8 billion in 2026.
The powder segment accounted for the largest revenue share of 36.0% in 2025, while liquid segment is the fastest growing product.
The Asia Pacific medical foods market is expected to grow at a CAGR of 6.2% from 2026 to 2033 to reach USD 11.9 billion by 2033.
Some key players operating in the Asia Pacific medical foods market include Mead Johnson & Company, LLC, SHS International ltd, Synutra International ltd, Milupa Gmbh, Danone, Nestlé, Abbott, Fresenius Kabi AG, GSK plc.
Key factors that are driving the market growth includes the increase in preterm birth rates, rising government initiatives, growing geriatric population and favorable regulatory and reimbursement coverage policies.
About the Author(s)
Pharmaceuticals Research Team
Healthcare · PharmaceuticalsThis report was authored by the pharmaceuticals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the pharmaceuticals segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


