
- Home
- »
- Biotechnology
- »
-
Automated Microbiology Market Size, Share Report, 2033GVR Report cover

Automated Microbiology Market (2026 - 2033)
Size, Share & Trends Analysis Report By Application (Clinical Diagnostics, Biopharmaceutical Production), By Product (Instruments, Reagents & Kits, Software), By Automation Type, By End Use, By Region, And Segment Forecasts
Market Size, 2025
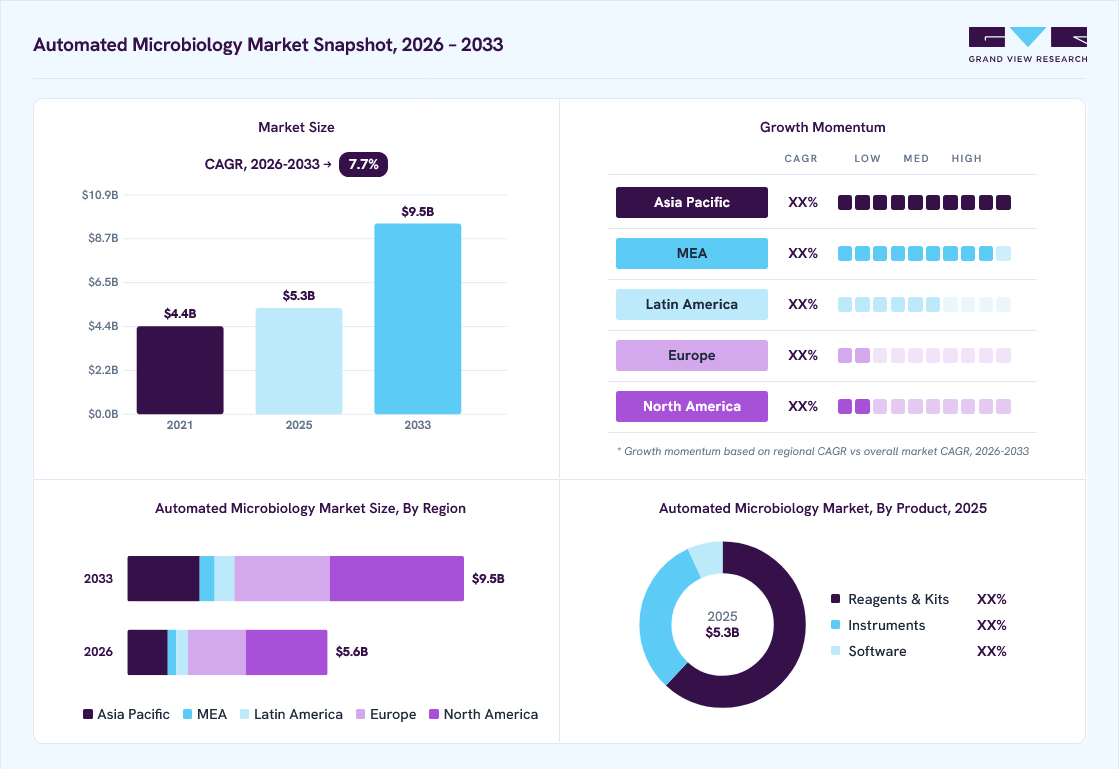
$5.3BMarket Estimate, 2026
$5.6BMarket Forecast, 2033
$9.5BCAGR, 2026–2033
7.7%Automated Microbiology Market Summary
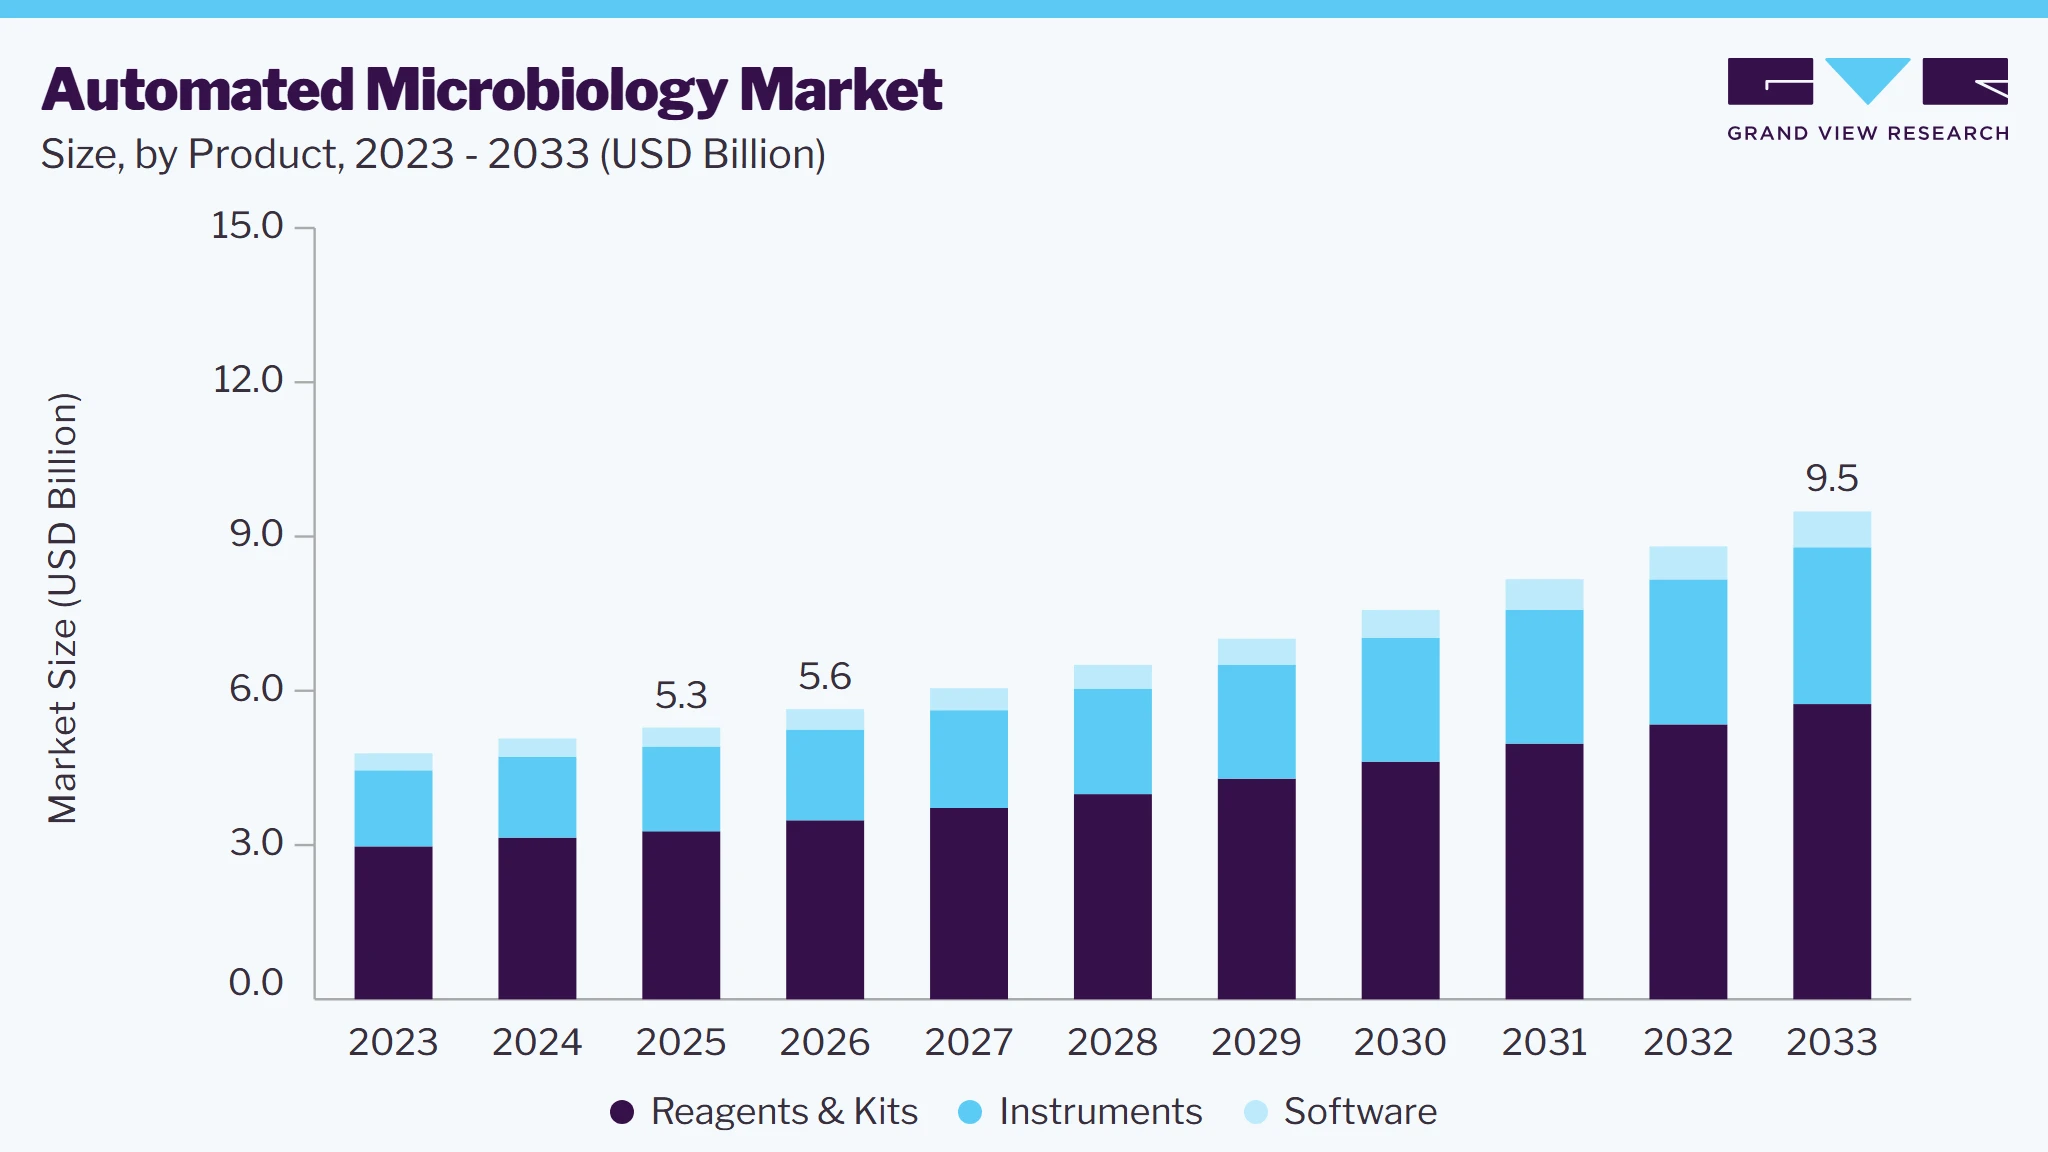
The global automated microbiology market size was valued at USD 5.3 billion in 2025 and is projected to grow from USD 5.6 billion in 2026 to USD 9.5 billion by 2033, at a CAGR of 7.7% from 2026 to 2033. North America dominated the market, accounting for the largest revenue share of 41.0% in 2025. The market growth is driven by the rising burden of antimicrobial resistance and sepsis, which requires faster identification and susceptibility testing, shortages of trained laboratory staff that push laboratories toward automation, and growing quality control testing in biopharmaceutical and food production.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: The reagents & kits segment held the highest market share of 61.8% in 2025.
- By automation type: The fully automated segment held the highest market share of 64.4% in 2025.
- By application: The clinical diagnostics segment held the highest market share of 54.0% in 2025.
- By end use: The hospitals & diagnostic laboratories segment held the highest market revenue share of 49.0% in 2025.
Regional Highlights
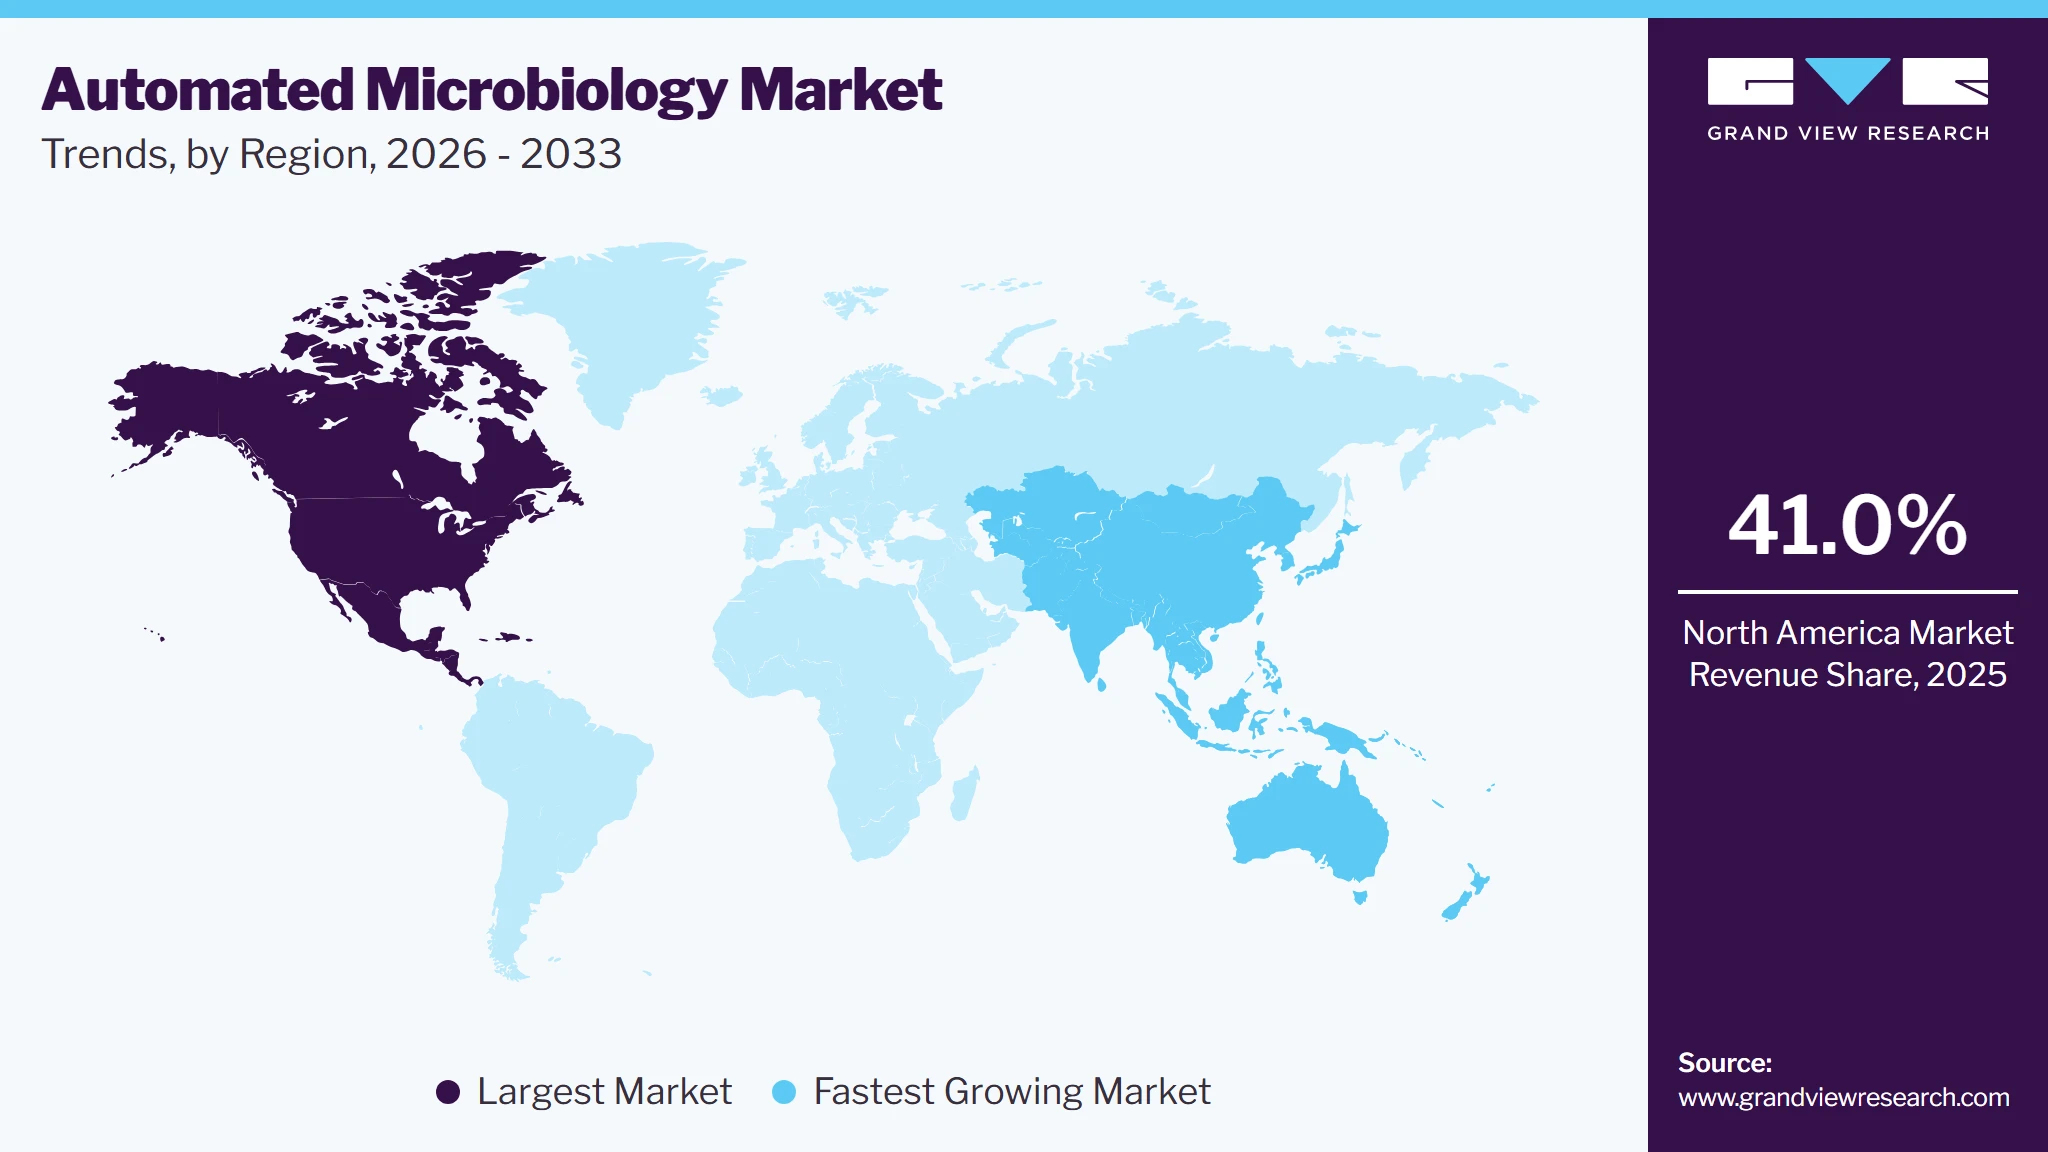
- Largest regional market: North America (41.0% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 5.3 Billion
- Estimated market size in 2026: USD 5.6 Billion
- Projected market size by 2033: USD 9.5 Billion
- CAGR (2026-2033): 7.7%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
 To learn more about this report, Download Free Sample Report
Market Dynamics
The market is growing steadily as clinical and industrial laboratories replace manual culture, identification, and susceptibility testing with automated systems that deliver faster and more consistent results. The burden of infections that require culture-based diagnosis remains high. According to the Global Research on Antimicrobial Resistance (GRAM) study published in The Lancet in September 2024, antimicrobial resistance directly caused 1.14 million deaths in 2021 and was associated with 4.71 million deaths, while the WHO estimates 48.9 million sepsis cases and 11 million sepsis-related deaths each year. Automated blood culture, MALDI-TOF identification, and rapid AST systems shorten the time to targeted therapy, which supports their adoption in hospital laboratories.
Rising antimicrobial resistance is a key market driver, as clinicians need rapid and accurate identification and susceptibility results to choose effective antibiotics. According to the WHO Global Antimicrobial Resistance and Use Surveillance System (GLASS) report released in October 2025, one in six laboratory-confirmed bacterial infections worldwide in 2023 were resistant to antibiotics, and resistance increased in more than 40% of the monitored pathogen-antibiotic combinations between 2018 and 2023. In September 2024, world leaders at the UN General Assembly approved a political declaration on AMR that targets a 10% reduction in the 4.95 million deaths associated with bacterial AMR by 2030. Such commitments are expected to increase investment in microbiology laboratory capacity and automated testing.
In addition, shortages of trained laboratory staff are encouraging laboratories to automate labor-intensive microbiology workflows. According to the ASCP 2024 Vacancy Survey published in October 2025, vacancy rates in U.S. clinical laboratories remain above pre-pandemic levels, and retirement rates increased in 10 of 17 laboratory departments. A comparison of manual, semi-automated, and fully automated microbiology workflows highlights differences in turnaround time, staffing needs, and standardization.
Comparison of manual, semi-automated, and fully automated microbiology workflows
Feature
Manual Microbiology
Semi-Automated Systems
Fully Automated Systems / Total Lab Automation
Specimen processing
Manual plating and streaking by technologists
Automated plating for selected specimen types
Automated plating, smart incubation, and digital plate imaging
Identification & AST
Biochemical tests and disk diffusion; 24-72 hours
Automated ID/AST panels with manual set-up
MALDI-TOF ID and automated or rapid AST linked to middleware
Staffing
High; depends on skilled microbiologists
Moderate
Lower hands-on time; staff focus on result review
Turnaround & standardization
Variable; limited by working hours
Improved for automated steps
Faster, continuous processing; standardized and traceable
Cost
Low equipment cost; high labor cost
Moderate capital cost
High capital cost (USD 2-3 million for total lab automation)
Source: Company Press Releases, Journal Articles, Secondary Research, Grand View Research Analysis
High capital costs and the time needed to validate and integrate new systems may restrain the market, particularly for small and mid-sized laboratories. A total laboratory automation line for microbiology typically costs USD 2-3 million, and rapid technologies can take longer than expected to gain adoption. For instance, in May 2025, Accelerate Diagnostics, the developer of the Pheno and Arc rapid AST systems, filed for Chapter 11 bankruptcy protection, and its assets were later acquired by Indaba Capital and subsequently sold to Bruker in November 2025. Budget constraints in public hospital laboratories in emerging economies further limit the adoption of fully automated systems.
The integration of artificial intelligence and digital imaging into microbiology automation is creating significant market opportunities. AI-based image analysis can automatically screen culture plates and flag negative specimens, reducing manual reading and allowing laboratories to handle higher volumes with the same staff. For instance, in February 2026, Copan Diagnostics received FDA 510(k) clearance for PhenoMATRIX, an AI colony image assessment module for its WASPLab system that sorts digital images of culture plates and estimates colony counts for review by trained staff. Such tools are expected to increase the value of automated microbiology systems and support software revenue.
Industry Concentration & Characteristics
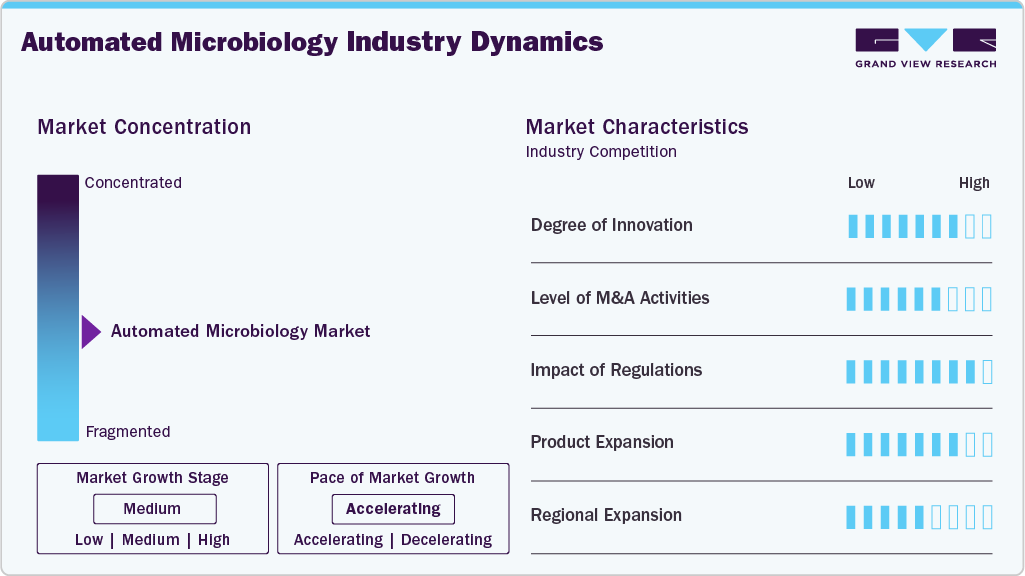
The degree of innovation in the automated microbiology industry is high, driven by MALDI-TOF identification, rapid AST, total laboratory automation, and AI-based image analysis. For instance, in April 2024, Q-linea received U.S. FDA 510(k) clearance for its ASTar System, which provides rapid antimicrobial susceptibility results directly from positive blood cultures in about six hours.
The automated microbiology industry is witnessing a moderate to high level of M&A activity, as large companies reshape their diagnostics portfolios. For instance, in February 2026, BD completed the combination of its Biosciences & Diagnostic Solutions business, which includes BD BACTEC, Phoenix, and Kiestra, with Waters Corporation, valuing the business at USD 18.8 billion. In August 2026, Thermo Fisher Scientific completed the sale of its microbiology business, including Oxoid and Remel, which generated USD 645 million in revenue in 2025, to private equity firm Astorg for about USD 1.1 billion.
 To learn more about this report, Download Free Sample Report
“The successful combination of our Biosciences & Diagnostic Solutions business with Waters marks the final milestone of our BD 2025 strategy, positioning BD for its next chapter as a focused, pure-play MedTech company built for the next era of healthcare.”
- Tom Polen, Chairman, Chief Executive Officer and President, BD
Regulations have a high impact on the automated microbiology industry, as automated systems and their reagents are regulated as in vitro diagnostic devices and must meet performance and quality requirements. In May 2024, the WHO updated its Bacterial Priority Pathogens List, covering 15 families of antibiotic-resistant bacteria, which guides surveillance and testing priorities. In the U.S., a federal court vacated the FDA's Laboratory Developed Tests rule in March 2025, keeping laboratory-developed microbiology assays under CLIA oversight.
The automated microbiology industry is witnessing product expansion as leading companies renew their automated ID/AST platforms. For instance, in March 2025, bioMérieux received U.S. FDA 510(k) clearance for VITEK COMPACT PRO, a next-generation automated identification and antibiotic susceptibility testing system designed for both clinical and industrial laboratories.
“VITEK® COMPACT PRO delivers fast, accurate and reproducible results comparable to VITEK® 2 and VITEK® 2 COMPACT systems.”
- Céline Roger-Dalbert, Executive Vice President, Research and Development, bioMérieux
The automated microbiology industry is witnessing regional expansion as companies add local manufacturing and service capacity. For instance, in September 2025, Copan announced more than USD 7 million in new U.S. manufacturing investment in California and Puerto Rico to expand production capacity and domestic sourcing.
“With more than three decades of United States presence, we remain committed to fostering economic growth by strengthening local manufacturing, increasing access to advanced technologies, and creating new employment opportunities in our communities.”
- Fabrizio Mazzocchi, CEO, COPAN Diagnostics Inc.
Analyst Perspective
The automated microbiology market is expected to witness steady growth, supported by rising antimicrobial resistance and sepsis burden, shortages of laboratory staff, and growing quality control testing in biopharmaceutical and food production. Reagents and kits remain the largest revenue source because of recurring consumption on installed systems, while lab automation instruments and software are expected to grow faster. Fully automated systems continue to gain share as laboratories invest in total laboratory automation, MALDI-TOF identification, and rapid AST. Market participants are focusing on new rapid testing systems, AI-based image analysis, acquisitions, and expansion of manufacturing and service networks.
Product Insights
The reagents & kits segment accounted for the largest revenue share of 61.8% in 2025, as each installed system generates recurring demand for ID and AST panels, blood culture bottles, culture media, and other consumables. Within this segment, assay kits & panels held the largest share of 51.7% in 2025. For instance, in July 2026, bioMérieux reported 4.3% organic growth in clinical microbiology in the first half of 2026, led by BACT/ALERT blood culture bottles.
The instruments segment is expected to grow at a CAGR of 8.1% over the forecast period, supported by investments in lab automation. Within instruments, automated sample preparation systems are projected to grow the fastest at a CAGR of 8.7%. For instance, in November 2025, the Los Angeles County Board of Supervisors approved the purchase of a Copan WASPLab total lab automation system with PhenoMATRIX for Harbor-UCLA Medical Center for about USD 2.6 million, allowing the laboratory to process up to 416 additional specimens per day without extra staff. The software segment is expected to grow at the fastest CAGR of 8.3%; in January 2024, bioMérieux acquired LUMED, a developer of software that supports antimicrobial stewardship in hospitals.
Application Insights
The clinical diagnostics segment accounted for the largest revenue share of 54.0% in 2025, driven by high volumes of blood, urine, and respiratory cultures in hospital laboratories. Updated guidance is reinforcing the role of culture-based testing; in March 2026, the Surviving Sepsis Campaign international guidelines recommended obtaining blood cultures as soon as possible and ideally before antimicrobial therapy is started.
The biopharmaceutical production segment is projected to grow at the fastest CAGR of 8.3% during 2026-2033, supported by growing quality control testing for sterility, bioburden, and environmental monitoring. For instance, bioMérieux reported 8.8% organic growth in its industrial applications business in 2025, with pharmaceutical quality control growing about 14%. The food & beverage testing segment is expected to grow at a CAGR of 7.9%; in January 2025, bioMérieux completed the acquisition of Brazil-based Neoprospecta, which provides microbiome analytics for food and pharmaceutical quality control.
End Use Insights
The hospitals & diagnostic laboratories segment accounted for the largest revenue share of 49.0% in 2025, as these laboratories perform most clinical culture, identification, and susceptibility testing and are the main buyers of blood culture, ID/AST, and lab automation systems.
The pharmaceutical & biotechnology companies segment is expected to grow at the fastest CAGR of 8.2% over the forecast period, driven by expanding biologics manufacturing and stricter microbial quality control requirements. The academic & research institutes segment is expected to grow at a CAGR of 7.6%.
Automation Type Insights
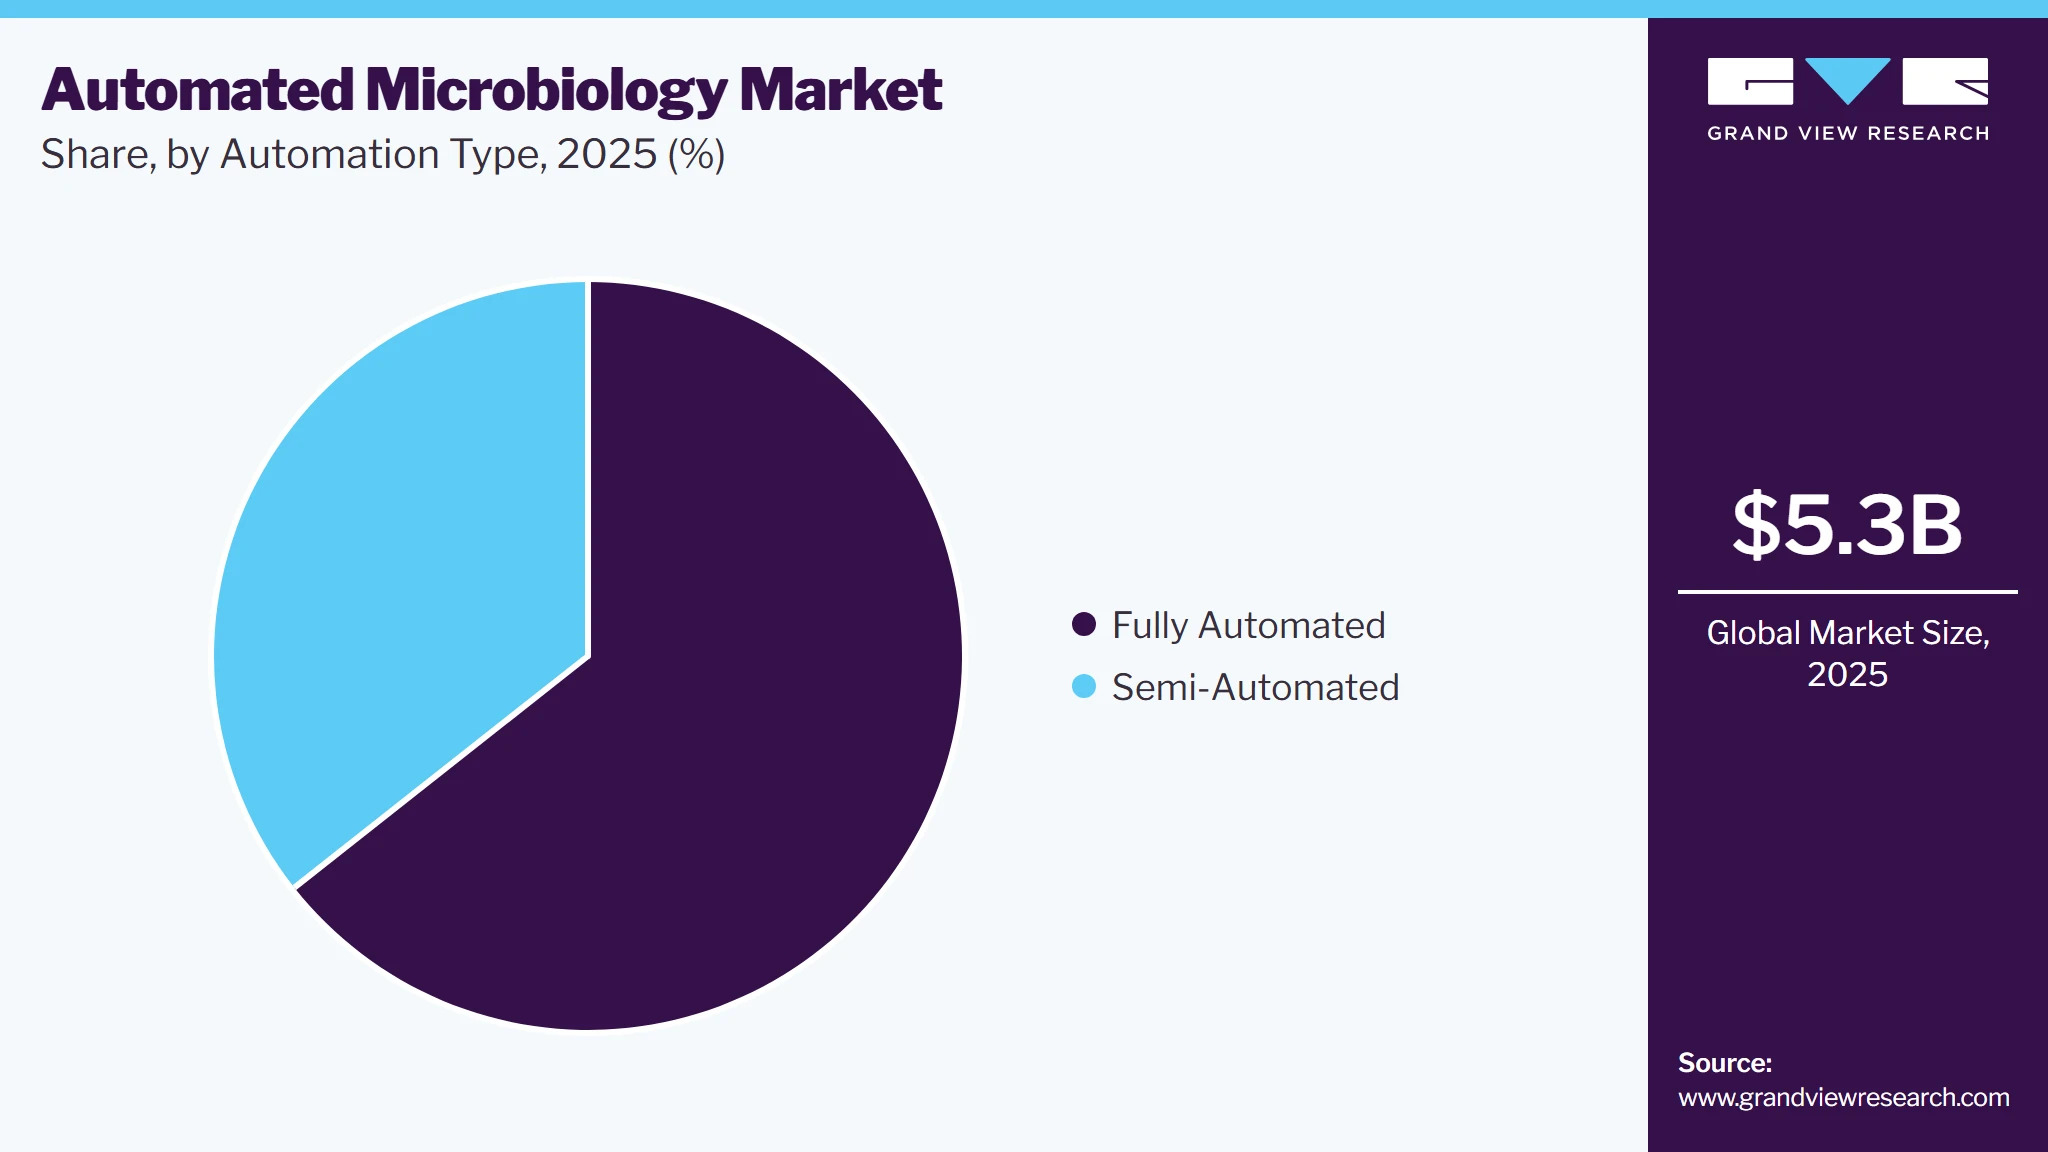
The fully automated segment accounted for the largest revenue share of 64.4% in 2025 and is expected to grow at the fastest CAGR of 8.0% over the forecast period, as laboratories adopt continuous-monitoring blood culture systems, fully automated ID/AST systems, and total laboratory automation to manage rising specimen volumes with fewer staff.
 To learn more about this report, Download Free Sample Report
The semi-automated segment is expected to grow at a CAGR of 7.1% during 2026-2033, as small and mid-sized laboratories, particularly in emerging markets, adopt semi-automated ID/AST systems and plate readers that require lower capital investment.
Regional Insights
North America dominated the automated microbiology market, accounting for the largest revenue share of 41.0% in 2025, supported by a large installed base of automated microbiology systems, high testing volumes, and the presence of leading companies such as bioMérieux, Waters (BD), Danaher, and Bruker.
 To learn more about this report, Download Free Sample Report
U.S. Automated Microbiology Market Trends
The automated microbiology market in the U.S. is expected to grow over the forecast period, supported by FDA clearances of new rapid testing systems. For instance, in April 2026, Q-linea received FDA clearance for its expanded ASTar Gram-negative blood culture panel, covering 215 bug-drug combinations with results in about six hours from a positive blood culture.
“Our FDA-cleared panel now closely matches what ASTar already provides to patients in Europe and other markets under CE-IVDR clearance. We look forward to providing patients in the US with the full power of the ASTar platform to improve outcomes and reduce costs for healthcare systems.”
- Stuart Gander, CEO, Q-linea
Europe Automated Microbiology Market Trends
The automated microbiology market in Europe is anticipated to grow significantly over the forecast period, supported by a strong base of microbiology laboratories and suppliers. The EU In Vitro Diagnostic Regulation (IVDR) is shaping product renewals; in July 2024, the EU extended the IVDR transition periods for legacy devices to 2027-2029, depending on device class, giving manufacturers more time to certify AST panels, culture media, and identification systems.
The UK automated microbiology market is expected to grow over the forecast period, supported by national efforts to tackle antimicrobial resistance. In May 2024, the UK government published its five-year national action plan, "Confronting antimicrobial resistance 2024 to 2029", noting that nearly 8,000 people in the UK die each year from drug-resistant infections, which is anticipated to propel demand for faster microbiology testing.
The automated microbiology market in Germany is anticipated to grow significantly over the forecast period, supported by investments in hospital laboratory automation. For instance, in May 2024, Universitätsmedizin Rostock opened an automated laboratory line in its new emergency center, shared by clinical chemistry, transfusion medicine, and the Institute for Medical Microbiology, Virology and Hygiene, with equipment worth EUR 4.4 million.
Asia Pacific Automated Microbiology Market Trends
The automated microbiology market in Asia Pacific is expected to grow at the fastest CAGR of 8.7% during the forecast period, supported by investments in hospital laboratories and rising AMR surveillance. For instance, in September 2024, NSW Health Pathology opened a new microbiology laboratory with a robotic track automation system at Liverpool Hospital in Sydney, where microbiology sample volumes rose from about 203,000 in 2018/19 to 283,000 in 2023/24. In India, in August 2025, KIMS in Bhubaneswar installed the first MALDI-TOF microbial identification system in Odisha.
China automated microbiology market is expected to grow over the forecast period, supported by large testing volumes and a high burden of resistant infections. According to the China Antimicrobial Surveillance Network (CHINET), its 2025 surveillance covered more than 516,000 clinical isolates from 80 hospitals, with carbapenem resistance of about 72% in A. baumannii, which is anticipated to propel demand for automated identification and susceptibility testing. Volume-based procurement of diagnostics may slow price growth in the near term.
The automated microbiology market in Japan is expected to grow steadily, supported by the economic value of faster diagnosis. A health-economic analysis published by bioMérieux and the Office of Health Economics in April 2026 found that fast identification and susceptibility testing for bloodstream infections could reduce sepsis cases by more than 20% across G7 countries, with the highest per-patient savings, about EUR 3,800, in Japan.
Latin America Automated Microbiology Market Trends
The automated microbiology market in Latin America is expected to grow steadily over the forecast period, supported by the first investments in full microbiology automation in the region. For instance, in February 2025, Hospital Angeles Pedregal in Mexico City installed the first Copan WASPLab microbiology automation line in Latin America, covering specimen processing, smart incubation, and digital imaging.
MEA Automated Microbiology Market Trends
The automated microbiology market in MEA is growing steadily, supported by private hospital investment in advanced laboratory technologies. For instance, in February 2025, Saudi German Health and BD signed a memorandum of understanding in Jeddah to bring BD BACTEC blood culture, Phoenix ID/AST, EpiCenter data management, and MALDI-TOF systems to the group's laboratories, expected to benefit about 2 million patients each year.
“Technologies like MALDI-TOF have demonstrated their effectiveness in enhancing diagnostic outcomes in other regions, and we believe this collaboration will yield similar results in the Kingdom of Saudi Arabia.”
- Philippe Villard, Senior Director of Commercial Operations, EMEA, BD
Key Automated Microbiology Company Insights
The market is moderately consolidated, with a few global leaders and a number of specialized and regional suppliers. Leading players include bioMerieux SA, Waters Corporation (BD Diagnostic Solutions), Danaher Corporation (Beckman Coulter), Bruker Corporation, Merck KGaA, Copan Group, Autobio Diagnostics Co., Ltd., Charles River Laboratories, Rapid Micro Biosystems, Inc., and Q-linea AB. These companies focus on new automated ID/AST and rapid testing systems, total laboratory automation, AI-based software, acquisitions, and expansion of manufacturing and service networks.
Key Automated Microbiology Companies
The following key companies have been profiled for this study on the automated microbiology market.
-
bioMerieux SA
-
Waters Corporation (BD Diagnostic Solutions)
-
Danaher Corporation (Beckman Coulter)
-
Bruker Corporation
-
Merck KGaA
-
Copan Group
-
Autobio Diagnostics Co., Ltd.
-
Charles River Laboratories
-
Rapid Micro Biosystems, Inc.
-
Q-linea AB
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (bioMérieux SA, Waters Corporation (BD Diagnostic Solutions), Danaher Corporation (Beckman Coulter), Bruker Corporation, Merck KGaA)
- Renewing ID/AST and blood culture platforms, expanding MALDI-TOF libraries, adding software and AI, and acquiring complementary technologies.
- Large installed bases with recurring reagent revenue, broad menus, global sales and service networks, and regulatory experience.
- High system prices; exposure to price pressure in China and to hospital budget constraints.
Emerging Players (Copan Group, Autobio Diagnostics Co., Ltd., Charles River Laboratories, Rapid Micro Biosystems, Inc., Q-linea AB)
- Focusing on lab automation, rapid AST, industrial QC microbiology, and cost-competitive systems for regional markets.
- Specialized technologies, faster time to result, and strong positions in specific workflows or regions.
- Smaller scale and installed bases; dependence on distribution partners and limited menus.
Recent Developments
-
In September 2026, Pattern Bioscience received FDA Breakthrough Device Designation for its Urine ID/AST Panel, its second breakthrough designation after the Pneumonia ID/AST Panel. The single-cell platform is designed to deliver identification and susceptibility results directly from patient specimens within hours instead of two to three days.
“Pneumonia and urinary tract infections (UTIs) are the two most common infection types that progress to sepsis, and with this designation, Pattern now has breakthrough-designated programs for both.”
- Carey-Ann Burnham, Ph.D., CEO, Pattern Bioscience
-
In June 2026, Bruker showcased its expanding microbiology and infection diagnostics portfolio at ASM Microbe 2026, including FDA-cleared expansions of the MALDI Biotyper CA library to 549 species and the Bruker Arc automated positive blood culture preparation system. The company placed 140 new MALDI Biotyper and IR Biotyper systems in the U.S. in 2025.
“We believe the future of microbiology lies in integrated innovations that can deliver faster, clinically actionable answers for some of the most critical patient conditions, including sepsis.”
- Carla Schneider, Director, Commercial Operations, Microbiology & Infection Diagnostics, Americas, Bruker
-
In June 2024, bioMérieux received U.S. FDA 510(k) clearance for the VITEK REVEAL AST System, which delivers antimicrobial susceptibility results for Gram-negative bacteria from positive blood cultures in about 5.5 to 6 hours.
“VITEK® REVEAL™ is fully aligned with bioMérieux's priority to provide innovative diagnostics to support antimicrobial stewardship.”
- Dr. Charles K. Cooper, Executive Vice President, Chief Medical Officer, bioMérieux
Automated Microbiology Market Report Scope Table
Report Attribute
Details
Market size in 2025
USD 5.3 billion
Estimated market size in 2026
USD 5.6 billion
Projected market size by 2033
USD 9.5 billion
Growth rate
CAGR of 7.7% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, automation type, application, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Denmark; Sweden; Norway; Japan; China; India; South Korea; Australia; Thailand; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait
Key companies profiled
bioMerieux SA; Waters Corporation (BD Diagnostic Solutions); Danaher Corporation (Beckman Coulter); Bruker Corporation; Merck KGaA; Copan Group; Autobio Diagnostics Co., Ltd.; Charles River Laboratories; Rapid Micro Biosystems, Inc.; Q-linea AB
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Automated Microbiology Market Report Segmentation
This report forecasts revenue growth and provides an analysis of the latest trends in each of the sub-segments from 2021 to 2033. For this report, Grand View Research has segmented the global automated microbiology market report based on product, automation type, application, end use, and region:
-
Product Outlook (Revenue, USD Billion, 2021 - 2033)
-
Reagents & Kits
-
Assay Kits & Panels
-
Culture Media
-
Stains & Dyes
-
Others
-
-
Instruments
-
Automated Microbial Identification Systems
-
Automated Blood Culture Systems
-
Automated Antibiotic Susceptibility Testing (AST) Systems
-
Automated Sample Preparation Systems
-
Automated Colony Counters
-
Other Instruments
-
-
Software
-
-
Automation Type Outlook (Revenue, USD Billion, 2021 - 2033)
-
Fully Automated
-
Semi-Automated
-
-
Application Outlook (Revenue, USD Billion, 2021 - 2033)
-
Clinical Diagnostics
-
Biopharmaceutical Production
-
Food & Beverage Testing
-
Environmental & Water Testing
-
Other Applications
-
-
End Use Outlook (Revenue, USD Billion, 2021 - 2033)
-
Hospitals & Diagnostic Laboratories
-
Pharmaceutical & Biotechnology Companies
-
Other End Use (Environmental & Water Testing Laboratories and Food & Beverage Manufacturers)
-
Academic & Research Institutes
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
South Korea
-
Australia
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa (MEA)
-
Saudi Arabia
-
South Africa
-
UAE
-
Kuwait
-
-
Research Methodology
The automated microbiology market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each automated microbiology segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment- Product
Revenue Capture Definition
Reagents & Kits
This segment includes revenues generated by the sale of reagents and kits used on automated and semi-automated microbiology systems, such as ID and AST panels and cards, blood culture bottles, culture media, stains and other consumables.
Instruments
This segment includes revenues generated by the sale of automated and semi-automated microbiology instruments, including identification, blood culture, AST, sample preparation, colony counting and lab automation systems, together with their service contracts.
Software
This segment includes revenues generated by the sale of microbiology software, such as middleware and data management, digital plate reading and AI image analysis, expert AST rules and AMR surveillance tools, as licenses or subscriptions.
Segment- Reagents & Kits
Revenue Capture Definition
Assay Kits & Panels
This segment includes revenues generated by the sale of assay kits and panels, such as ID and AST cards and panels, MALDI-TOF reagents and target plates, and blood culture bottles.
Culture Media
This segment includes revenues generated by the sale of culture media (plates, broths and chromogenic media) used with automated plating, incubation and reading systems.
Stains & Dyes
This segment includes revenues generated by the sale of stains and dyes used on automated slide stainers and in automated workflows, such as Gram stains.
Others
This segment includes revenues generated by the sale of other reagents, such as enzymes, substrates, quality control strains and calibrators.
Segment- Instruments
Revenue Capture Definition
Automated Microbial Identification Systems
This segment includes revenues generated by the sale of automated microbial identification systems, including MALDI-TOF mass spectrometry and automated biochemical identification systems.
Automated Blood Culture Systems
This segment includes revenues generated by the sale of automated blood culture systems that incubate and continuously monitor blood culture bottles for microbial growth.
Automated Antibiotic Susceptibility Testing (AST) Systems
This segment includes revenues generated by the sale of automated antibiotic susceptibility testing (AST) systems, including combined ID/AST systems and rapid AST systems.
Automated Sample Preparation Systems
This segment includes revenues generated by the sale of automated sample preparation and specimen processing systems, including total lab automation lines with automated plating, smart incubation and digital imaging.
Automated Colony Counters
This segment includes revenues generated by the sale of automated colony counters used to count and assess colonies on culture plates.
Other Instruments
This segment includes revenues generated by the sale of other automated microbiology instruments, such as automated slide stainers, air samplers with automated reading and rapid microbial detection systems.
Segment- Automation Type
Revenue Capture Definition
Fully Automated
This segment includes revenues generated by the sale of fully automated systems, which run the whole step without manual handling, and their reagents and software.
Semi-Automated
This segment includes revenues generated by the sale of semi-automated systems, which need manual loading, inoculation or reading steps, and their reagents and software.
Segment- Application
Revenue Capture Definition
Clinical Diagnostics
This segment includes revenues generated by the sale of automated microbiology instruments, reagents and software used to diagnose infections in patients, such as bloodstream, urinary tract and respiratory infections.
Biopharmaceutical Production
This segment includes revenues generated by the sale of automated microbiology instruments, reagents and software used for quality control of biopharmaceutical and pharmaceutical manufacturing, such as sterility, bioburden and environmental monitoring.
Food & Beverage Testing
This segment includes revenues generated by the sale of automated microbiology instruments, reagents and software used to test food and beverages for pathogens and spoilage organisms.
Environmental & Water Testing
This segment includes revenues generated by the sale of automated microbiology instruments, reagents and software used to test drinking water, wastewater and environmental samples.
Other Applications
This segment includes revenues generated by the sale of automated microbiology instruments, reagents and software used in other applications, such as cosmetics testing, veterinary testing and research.
Segment- End Use
Revenue Capture Definition
Hospitals & Diagnostic Laboratories
This segment includes revenues generated by the sale of automated microbiology instruments, reagents and software to hospital laboratories and independent diagnostic laboratories.
Pharmaceutical & Biotechnology Companies
This segment includes revenues generated by the sale of automated microbiology instruments, reagents and software to pharmaceutical and biotechnology companies and their contract manufacturers.
Other End Use (Environmental & Water Testing Laboratories and Food & Beverage Manufacturers)
This segment includes revenues generated by the sale of automated microbiology instruments, reagents and software to environmental and water testing laboratories and food and beverage manufacturers.
Academic & Research Institutes
This segment includes revenues generated by the sale of automated microbiology instruments, reagents and software to universities, research institutes and public health laboratories.
Estimation Model
Section
Methodology
Description
Top-Down
Commodity Flow Analysis
Market value was estimated by assessing revenues of key suppliers from automated microbial identification, blood culture, antimicrobial susceptibility testing, sample preparation and lab automation systems. Key reports and SEC documents, and microbiology software, company financials, segment disclosures, installed base, and pricing were analyzed to quantify revenue across product, automation type, application, and end use.
Benchmark
Parent Market, Company Share & Application Benchmarking
The market was benchmarked against the IVD market. Company share analysis of leading suppliers, and application-level profiling and industrial microbiology. Published estimates were reviewed and normalized to a common base year and scope.
Segmentation
Country-Level Segment Share Modeling
Country-level shares were estimated using company regional sales mixes, hospital and laboratory infrastructure, healthcare spending, and IVD and product benchmarks. Country-level automation adoption and procurement trends were incorporated to determine country and regional distributions across all segments.
Validation
Data Triangulation & Validation Model
Market estimates were reconciled using company revenues, the SKU parent market, application-level use, and published secondary research. Cross-validations by type, application, end use, country, and region ensure consistency between supply-side and demand-side calculations.
Forecasting
Forecasting & CAGR Modeling
Future demand was projected using company organic growth, and system rates, laboratory automation adoption, R&D spend, and pharmaceutical and food quality control testing. Price pressure from volume-based procurement was incorporated into segment-level growth assumptions.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Installed Base & Replacement Analysis
Estimation of the installed base of blood culture, ID/AST, MALDI-TOF, and lab automation systems by country and replacement cycles.
Helps clients size instrument opportunities and plan sales coverage.
Competitive Benchmarking
Comparison of leading systems by throughput, time to result, menu, connectivity, and price across clinical and industrial laboratories.
Helps clients position products and identify gaps in their portfolios.
Reagent Pull-Through Modeling
Modeling of reagent and panel consumption per installed system and test volume by application.
Helps clients forecast recurring revenue and evaluate placement strategies.
Frequently Asked Questions About This Report
The global automated microbiology market size was estimated at USD 5.3 billion in 2025 and is expected to reach USD 5.6 billion in 2026.
The global automated microbiology market is expected to grow at a compound annual growth rate of 7.7% from 2026 to 2033 to reach USD 9.5 billion by 2033.
North America dominated the market with the largest revenue share of 41.0% in 2025. The market is driven by advanced healthcare infrastructure, increasing prevalence of infectious diseases, and growing concerns over antimicrobial resistance.
Some key players operating in the automated microbiology market include BD, QIAGEN, Thermo Fisher Scientific Inc., Agilent Technologies, Inc., Danaher, Merck KGaA, bioMérieux, Abbott, DiaSorin S.p.A., BioRad Laboratories, Inc.
The increasing prevalence of infectious diseases globally is a significant driver for the automated microbiology market. With the rise of hospital-acquired infections (HAIs), antimicrobial resistance (AMR), and foodborne illnesses, there is a growing demand for rapid and accurate microbial identification and susceptibility testing.
Asia Pacific is the fastest-growing region over the forecast period.
The reagents & kits segment held the largest revenue share of over 61.8% in 2025.
The fully automated segment held the largest revenue share of over 64.4% in 2025, and it is expected to grow with the fastest CAGR over the forecast period.
The clinical diagnostics segment held the largest revenue share of over 54.0% in 2025.
About the Author(s)
Biotechnology Research Team
Healthcare · BiotechnologyThis report was authored by the biotechnology research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the biotechnology segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


