
- Home
- »
- Automotive & Transportation
- »
-
Automotive Driveline Aftermarket Industry Report, 2026-2033GVR Report cover

Automotive Driveline Aftermarket Industry (2026 - 2033)
Size, Share & Trends Analysis Report By Product (AWD Systems, Automatic Transmissions, Transfer Case), By Service (Replacement, Repair), By Vehicle, By Distribution Channel, And Segment Forecasts
Market Size, 2025
$22.8BMarket Estimate, 2026
$24.9BMarket Forecast, 2033
$44.8BCAGR, 2026–2033
8.8%Automotive Driveline Aftermarket Industry Summary
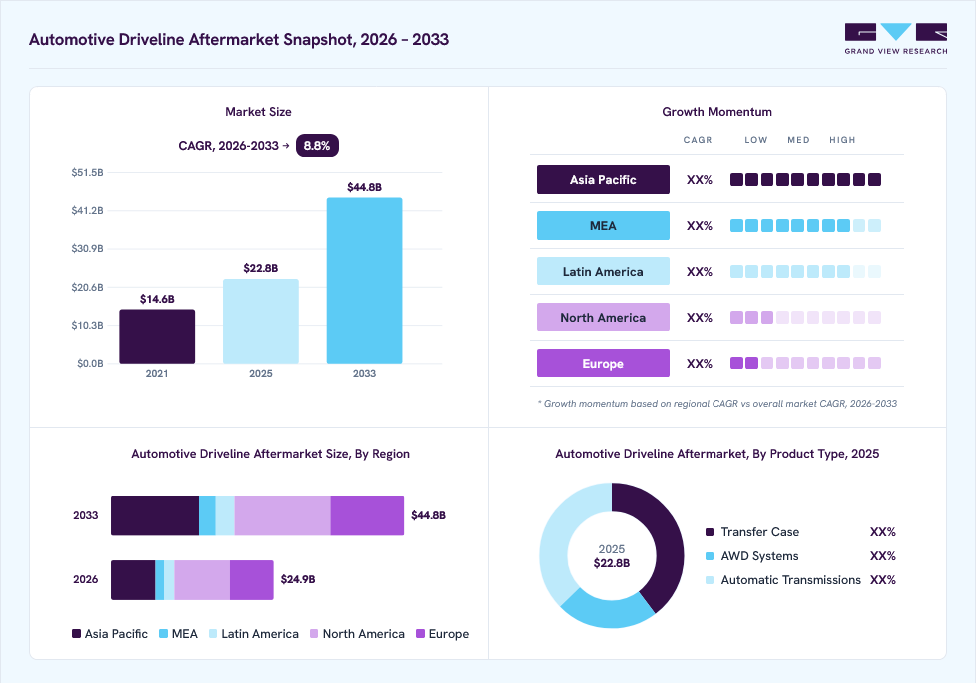
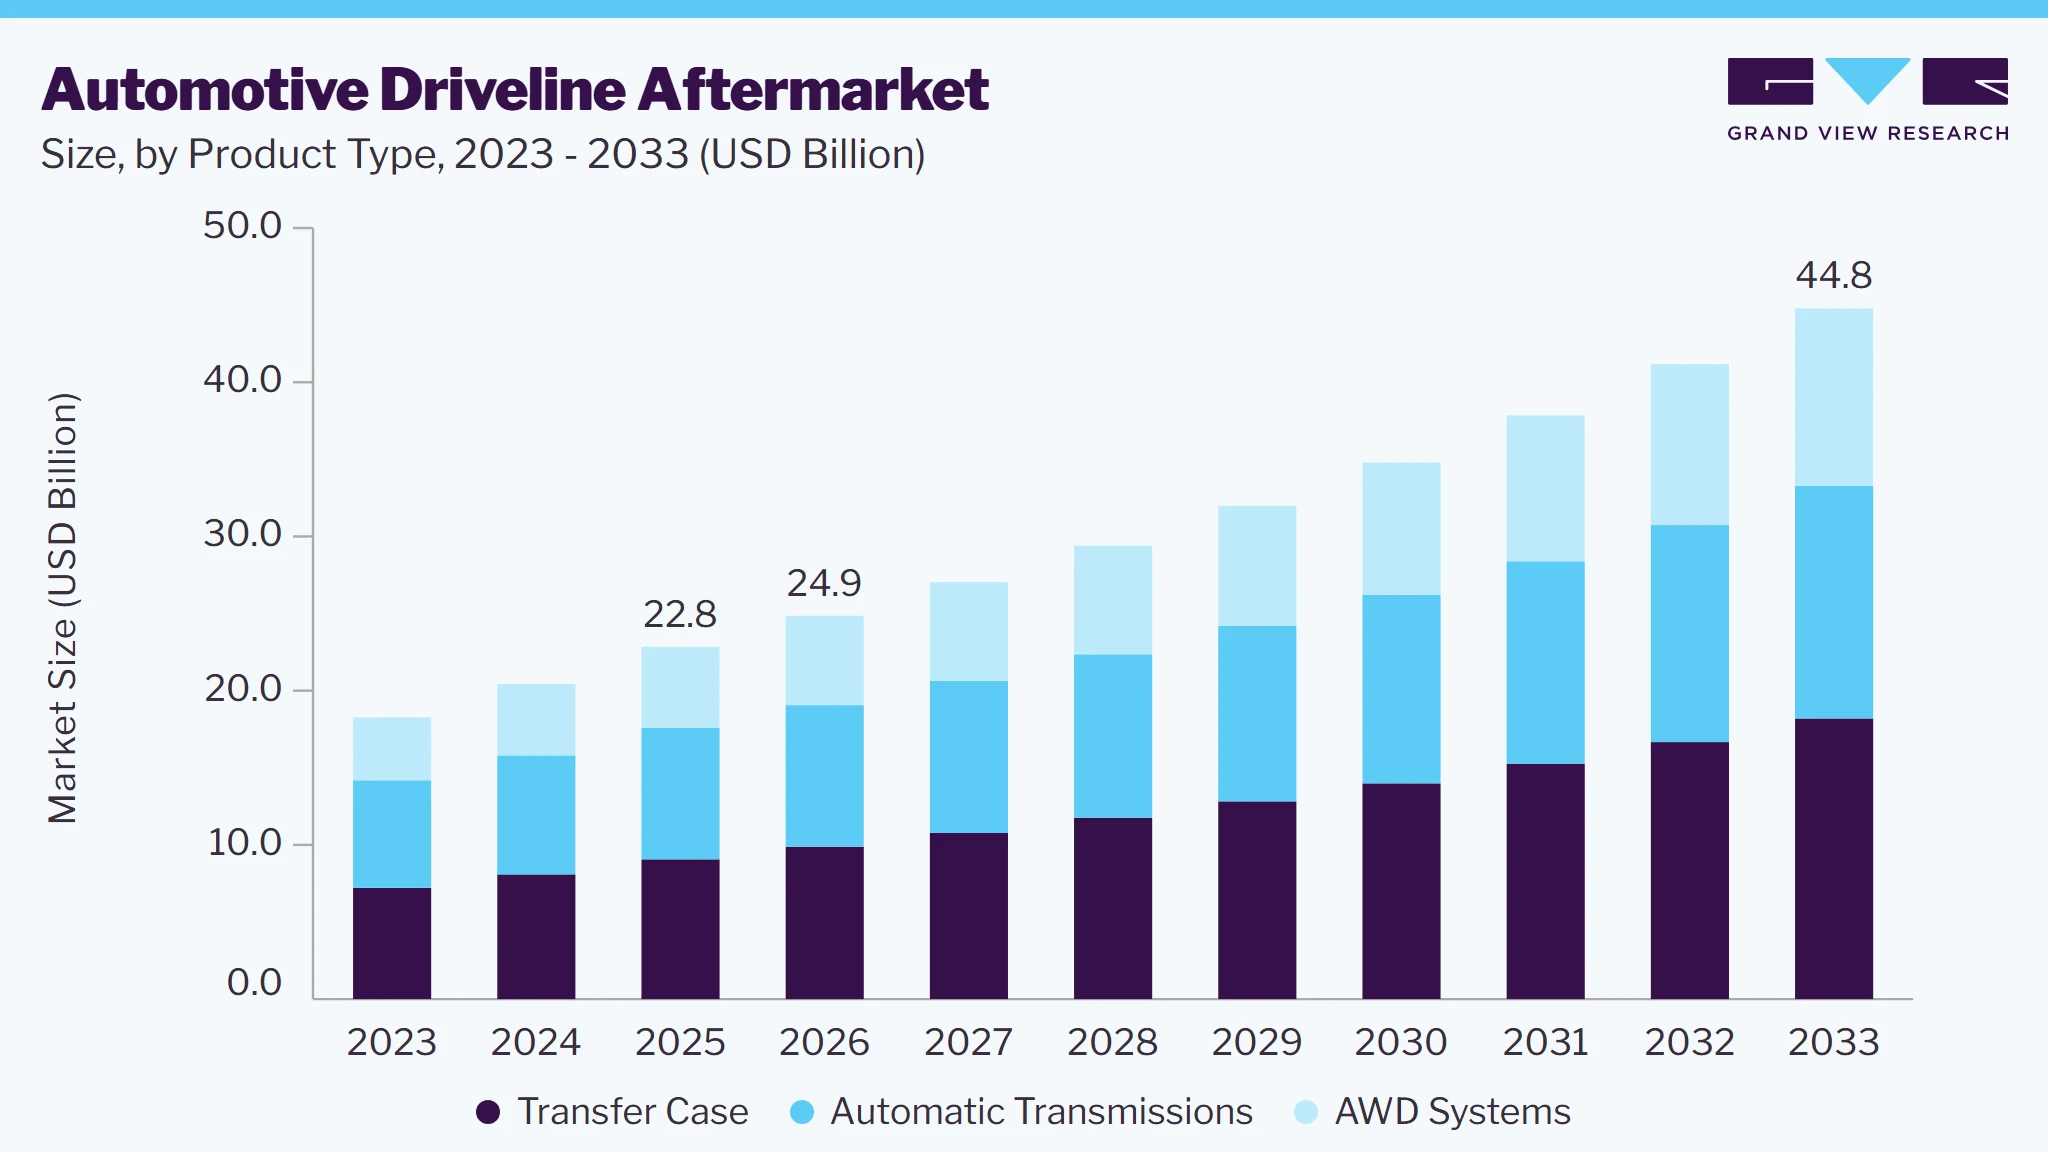
The global automotive driveline aftermarket industry size was valued at USD 22.8 billion in 2025 and is projected to grow from USD 24.9 billion in 2026 to USD 44.8 billion by 2033, at a CAGR of 8.8% from 2026 to 2033. North America dominated the market, accounting for the largest revenue share of 34.3% in 2025. Digitalization and predictive maintenance are transforming the global market by enabling connected diagnostics, proactive servicing, and faster replacement of driveline components through data-driven maintenance solutions.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Transfer case segment dominated the market, with a revenue share of 39.7% in 2025.
- By service: Repair segment held the largest market share of 36.7% in 2025.
- By vehicle: SUVs segment held the largest market share of 34.0% in 2025.
- By distribution channel: Independent aftermarket segment held the largest market share of 42.1% in 2025.
Regional Highlights
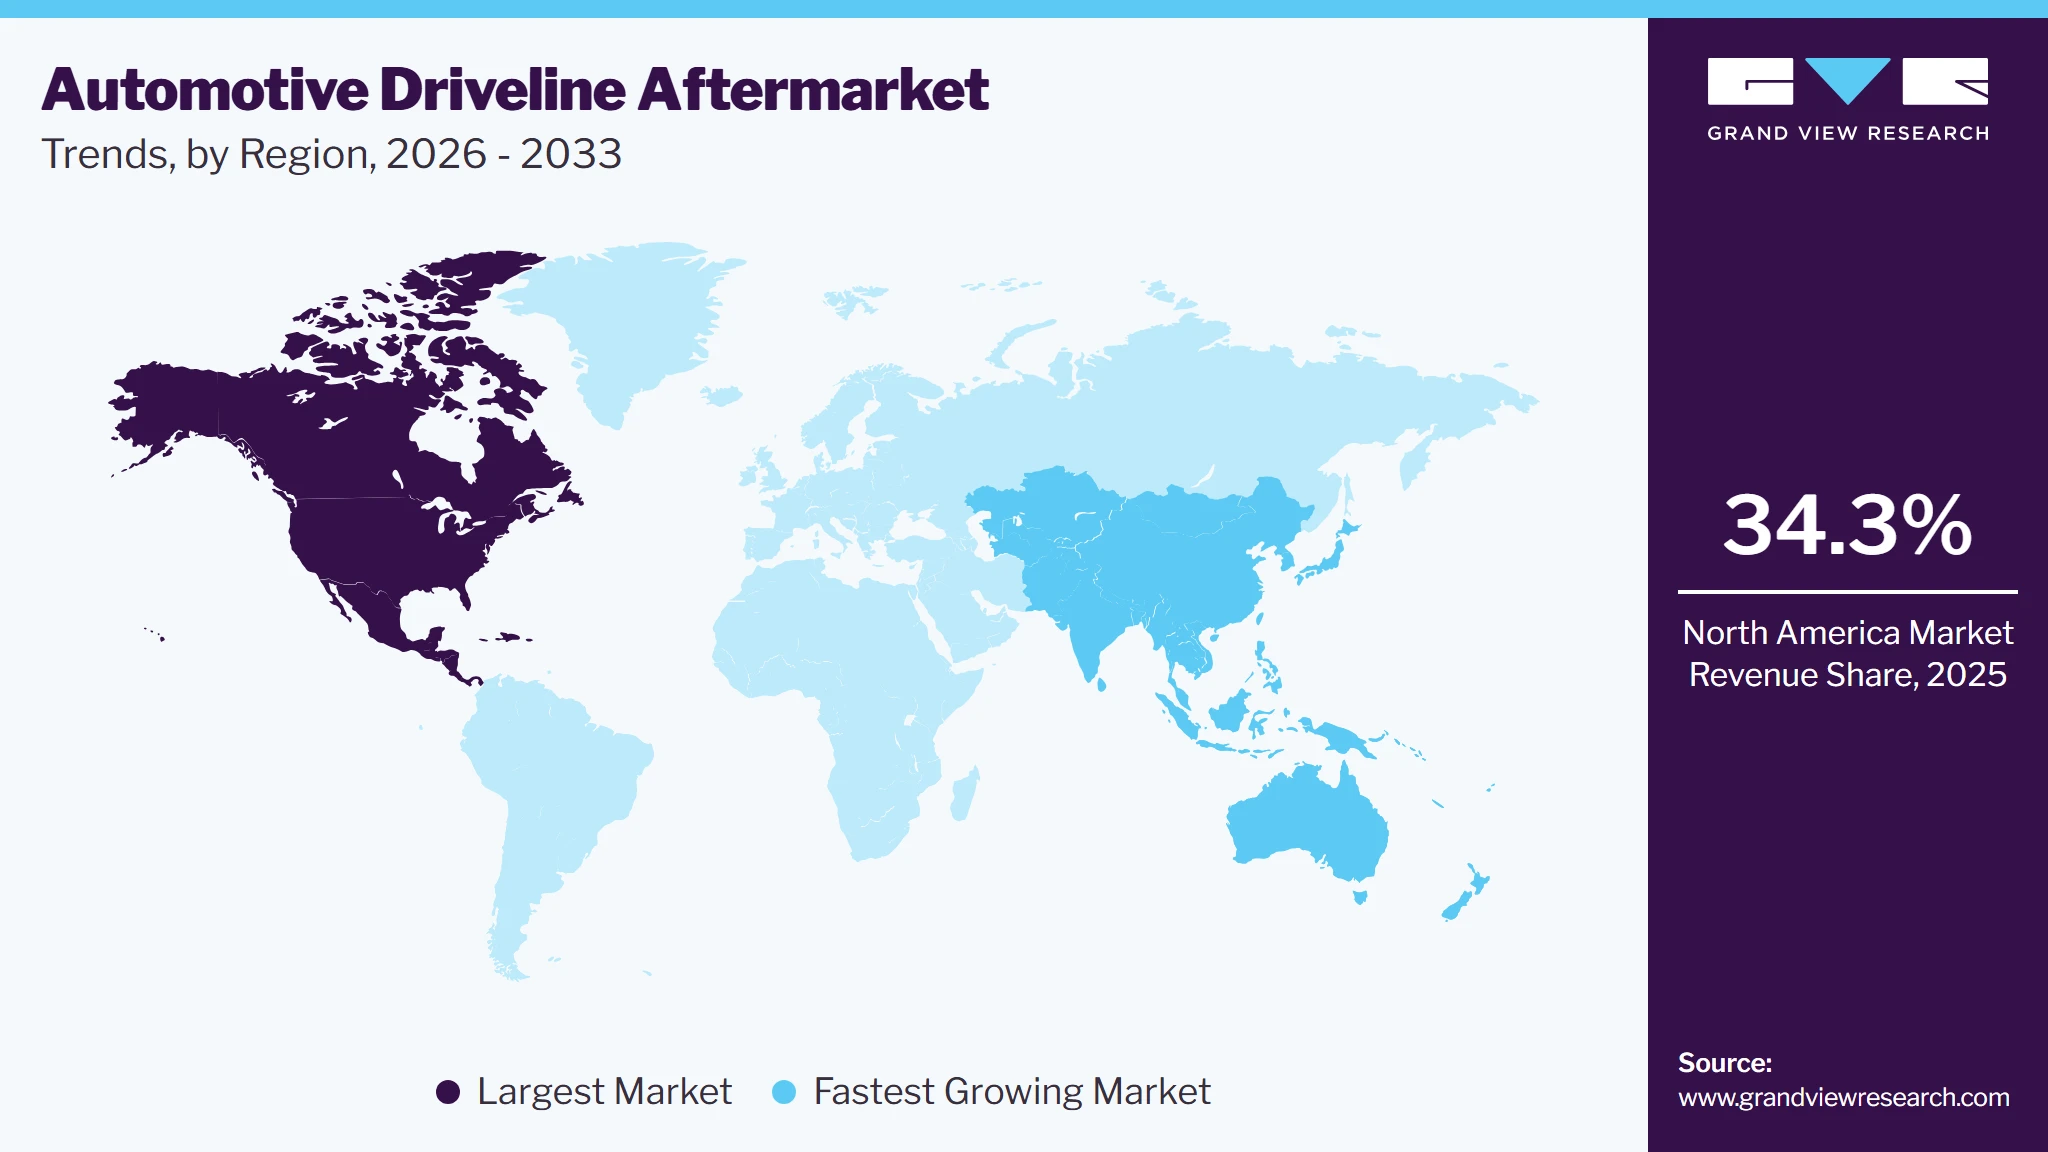
- Largest regional market: North America (34.3% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 22.8 Billion
- Estimated market size in 2026: USD 24.9 Billion
- Projected market size by 2033: USD 44.8 Billion
- CAGR (2026-2033): 8.8%
Prism AI by Grand View Research Free to tryAsk a question about this marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →The growing number of vehicles on the road and the increasing average age of vehicles are creating steady demand for automotive driveline aftermarket products. As vehicles are used for longer periods, key driveline components such as driveshafts, CV joints, clutches, and differentials experience gradual wear due to continuous operation. Vehicle owners often replace these parts to maintain performance and avoid costly breakdowns instead of purchasing new vehicles. This trend is especially visible in developing markets where vehicle ownership continues to rise and replacement cycles are longer. As a result, the expanding vehicle parc and aging fleet continue to support consistent growth in the global automotive driveline aftermarket.
 To learn more about this report, Download Free Sample Report
Vehicle owners and fleet operators are increasingly choosing aftermarket driveline components because they provide a more affordable alternative to original equipment parts while maintaining reliable performance. The availability of high-quality replacement parts from established aftermarket manufacturers has improved customer confidence in non-OEM products. At the same time, the expansion of independent repair workshops and service networks has made aftermarket components more accessible across regions. Regular maintenance and timely replacement of driveline parts also help reduce long-term repair expenses and improve vehicle reliability. This growing focus on cost-effective maintenance is driving demand across the market.
Modern vehicles are being equipped with advanced driveline technologies, including all-wheel drive (AWD), hybrid powertrains, and electric driveline systems, which require specialized replacement parts and technical servicing. These systems contain more sophisticated components that must be maintained or replaced to ensure efficient vehicle operation. As the global fleet of hybrid and electric vehicles continues to expand, the need for compatible aftermarket driveline components and diagnostic services is also increasing. Independent service providers are expanding their technical capabilities to meet these changing maintenance requirements. This shift toward more advanced vehicle technologies is creating new growth opportunities for the global market.
Market Dynamics
The expansion of independent repair networks and multi-brand service centers is supporting the growth of the automotive driveline aftermarket by improving access to maintenance and replacement services. These workshops offer a wide range of driveline components for different vehicle brands, giving customers more options at competitive prices. Their presence is increasing in both developed and emerging markets as vehicle owners look for convenient and cost-effective repair solutions.
Independent service providers are also investing in advanced diagnostic equipment and technician training to handle modern driveline systems, including those used in hybrid and electric vehicles. This enables them to perform high-quality repairs while reducing service time and maintenance costs. As a result, more vehicle owners are choosing independent workshops for driveline replacement and repair, driving demand for aftermarket driveline components globally.
The increasing complexity of modern driveline systems is creating challenges for the automotive driveline aftermarket as vehicles incorporate electronically controlled transmissions, integrated sensors, and advanced control units. These technologies require specialized diagnostic tools, updated software, and skilled technicians to accurately identify and repair driveline issues. Many independent repair workshops need to invest in new equipment and technical training, which increases service costs and limits their ability to support advanced driveline systems.
The integration of mechanical, electronic, and software-based components also makes component-level repairs more difficult, as faults often require detailed diagnostics before replacement. In many cases, larger driveline assemblies must be replaced instead of individual parts, increasing repair costs for both service providers and vehicle owners. As driveline technologies continue to advance, these technical and investment requirements can limit the participation of independent workshops and restrain the growth of the automotive driveline aftermarket.
The increasing complexity of modern driveline systems is creating opportunities for advanced diagnostic technologies in the automotive driveline aftermarket. Modern transmissions, differentials, and AWD/4WD systems are equipped with sensors, electronic control units, and software that require digital diagnostic tools for accurate fault detection. These technologies help technicians identify driveline issues more quickly, improve repair accuracy, and reduce unnecessary component replacements, making maintenance more efficient.
The growing use of connected diagnostic platforms, cloud-based repair systems, and advanced scan tools is further expanding opportunities for aftermarket service providers and component manufacturers. These solutions provide access to real-time vehicle data, repair procedures, and technical information, enabling independent workshops to service a wider range of modern vehicles with greater confidence. As vehicles continue to adopt more software-controlled driveline technologies, demand for diagnostic equipment, specialized software, and integrated repair solutions is expected to increase, creating new growth opportunities across the automotive driveline aftermarket.
Market Concentration & Characteristics
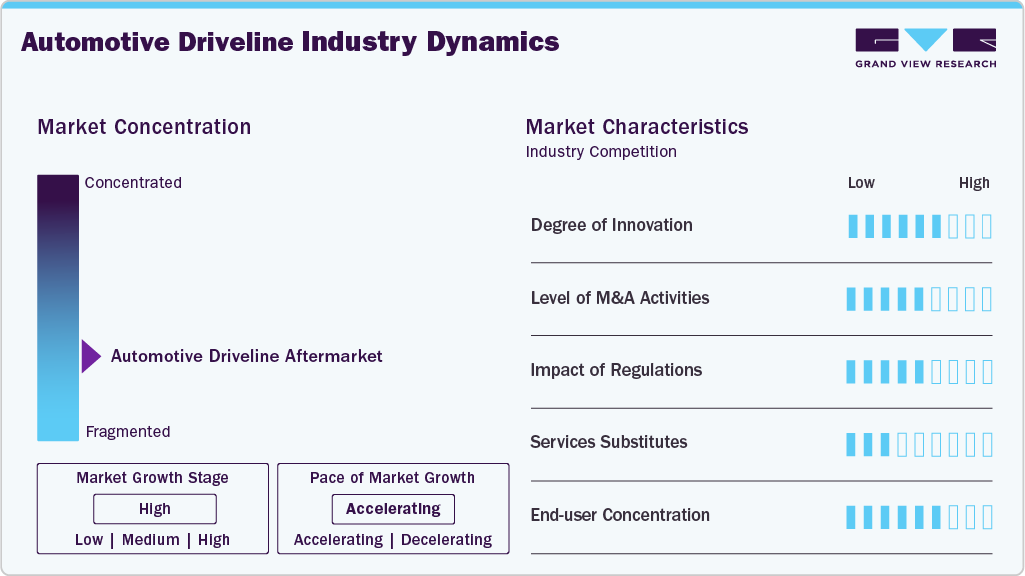
The market is experiencing a moderately high level of innovation as manufacturers develop driveline components that support hybrid, electric, and advanced all-wheel-drive vehicles. Companies are introducing lightweight materials, improved sealing technologies, enhanced durability, and digitally compatible components to meet changing vehicle requirements. The growing adoption of diagnostic tools and remanufacturing technologies is also improving repair efficiency. Innovation is primarily focused on extending component life, improving performance, and supporting the evolving vehicle fleet.
 To learn more about this report, Download Free Sample Report
Government regulations related to vehicle safety, emissions, product quality, and environmental sustainability have a moderate-to-high influence on the automotive driveline aftermarket. Manufacturers must ensure replacement components comply with regional performance and safety standards while meeting evolving regulatory requirements. Environmental regulations are also encouraging remanufacturing and recycling of driveline components to reduce waste and support circular economy initiatives. Compliance with these standards increases product reliability while influencing manufacturing and service practices.
Analyst Perspective
The aftermarket for automotive driveline is entering a phase where growth is increasingly supported by an expanding global vehicle parc, longer vehicle ownership cycles, and the growing complexity of modern powertrain systems. While electrification is reshaping drivetrain architectures, demand for replacement components remains resilient across internal combustion, hybrid, and electric vehicles as maintenance requirements evolve. The companies best positioned for long-term growth are those that combine broad aftermarket coverage with advanced diagnostics, digital service capabilities, and strong distribution networks, enabling them to support both conventional and next-generation driveline systems while maintaining close relationships with repair channels and fleet operators.
Product Insights
The transfer case segment led the market in 2025, accounting for 39.7% of global revenue. The transfer case segment is witnessing steady growth in the automotive driveline aftermarket due to the expanding global parc of four-wheel-drive (4WD) and all-wheel-drive (AWD) SUVs and pickup trucks requiring periodic drivetrain servicing and replacement. The independent workshops are increasingly adopting remanufactured drivetrain components to provide cost-effective repair solutions. For instance, in April 2025, ZF Aftermarket showcased its REMAN portfolio at Rematec Amsterdam 2025, featuring more than 2,000 remanufactured transmission variants and expanding its circular aftermarket strategy through its "Maintain-Repair-Replace" approach.
The AWD systems segment is anticipated to be the fastest-growing segment during the forecast period, as all-wheel-drive technology becomes increasingly common across passenger vehicles, crossovers, SUVs, and light commercial vehicles. The growing installed base of AWD-equipped vehicles is increasing demand for replacement components, including AWD couplings, differentials, propeller shafts, transfer cases, and electronic control modules, as these vehicles age beyond the OEM warranty period. The continuous operation under varying road conditions, combined with higher drivetrain complexity, is driving recurring maintenance and repair requirements.
Service Insights
The repair segment led the market with the largest revenue share of 36.7% in 2025, due to the increasing preference for restoring worn driveline components instead of replacing complete assemblies. Rising vehicle age and extended ownership periods are increasing demand for repairs involving driveshafts, differentials, transfer cases, CV joints, universal joints, and transmission systems. The availability of OE-equivalent repair kits and specialized service tools is further improving repair efficiency while reducing vehicle downtime. For instance, in October 2025, ZF Aftermarket introduced ZF MultiScan and ZF [pro]Tech plus at AAPEX and SEMA to strengthen its aftermarket diagnostic and technical support portfolio in North America.
The remanufacturing segment is expected to grow at the fastest CAGR during the forecast period, as vehicle owners and fleet operators seek cost-effective alternatives to new driveline assemblies. Increasing vehicle age and higher replacement costs are encouraging the adoption of remanufactured transmissions, differentials, transfer cases, driveshafts, axle assemblies, and related components. These products restore OE-level performance through comprehensive inspection, cleaning, machining, component replacement, assembly, and quality testing, ensuring reliable operation and extended service life. Fleet operators are increasingly choosing remanufactured assemblies to reduce maintenance costs, minimize vehicle downtime, and improve asset utilization.
Vehicle Insights
The SUVs segment led the market with the largest revenue share of 34.0% in 2025, due to the increasing global parc of mid-size, full-size, and premium SUVs equipped with AWD and 4WD systems. Rising vehicle ownership periods are increasing maintenance requirements beyond the OEM warranty period, while the growing complexity of electronically controlled driveline systems is driving demand for specialized aftermarket parts and technical expertise. Independent workshops are expanding their capabilities to service modern SUV drivetrains, supported by broader availability of OE-quality and remanufactured components. For instance, in April 2025, ZF Aftermarket expanded its remanufactured transmission portfolio by introducing additional automatic transmission and torque converter solutions for passenger vehicles.
The crossovers segment is expected to grow significantly in the coming years, due to the increasing global adoption of compact and mid-size crossover utility vehicles equipped with front-wheel-drive (FWD) and all-wheel-drive (AWD) systems. Frequent urban driving, stop-and-go traffic, and long-distance commuting accelerate wear of driveline components, supporting recurring maintenance and repair activities. Independent workshops are expanding their expertise in servicing advanced crossover drivetrains, while aftermarket suppliers continue to broaden the availability of OE-quality replacement parts. For instance, in April 2025, Nexteer Automotive introduced new driveline technologies, including the 8-Ball Joint, Face Spline Axle, and Premium Double Offset Joint, and expanded its Cross-Glide Joint portfolio for electric and hybrid vehicles.
Distribution Channel Insights
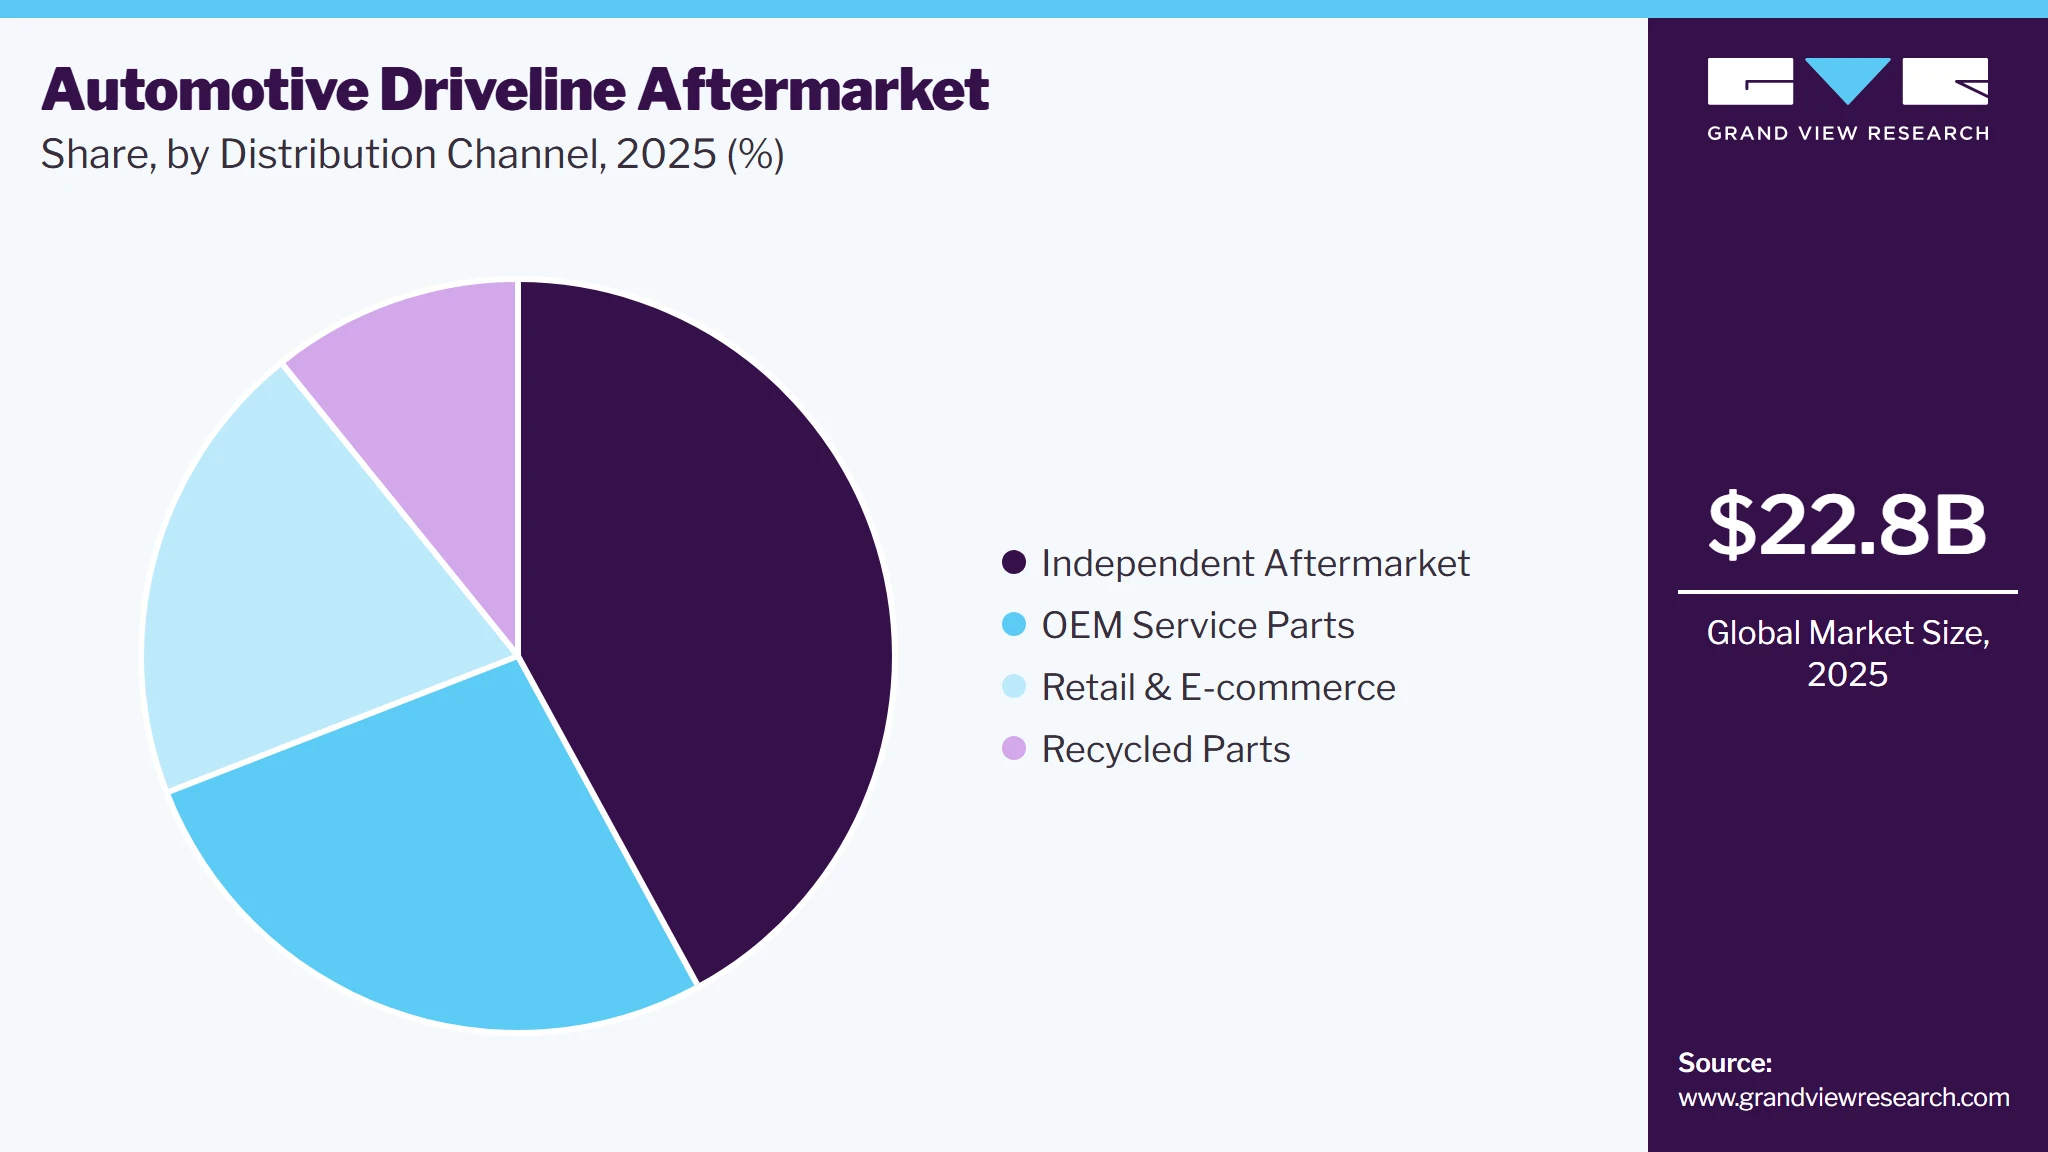
The independent aftermarket segment led the market with the largest revenue share of 42.1% in 2025, driven by a broad network of distributors, wholesalers, retailers, and independent repair workshops that serve vehicles beyond the OEM warranty period. The rising average age of passenger and commercial vehicles is increasing demand for cost-effective replacement driveline components across multiple vehicle brands. Independent suppliers are continuously expanding their portfolios with OE-equivalent parts, remanufactured assemblies, repair kits, and performance components to meet diverse customer requirements.
 To learn more about this report, Download Free Sample Report
The OEM service parts segment is anticipated to exhibit the fastest CAGR over the forecast period. This segment is anticipated as digital purchasing becomes an integral part of automotive parts purchasing. Vehicle owners, independent repair workshops, and fleet operators are increasingly purchasing driveline components through online platforms due to broader product availability, competitive pricing, and simplified ordering processes. Advanced digital catalogs with VIN- and vehicle-specific compatibility tools are improving part-selection accuracy and reducing ordering errors.
Regional Insights
North America automotive driveline aftermarket industry dominated the global market with the largest revenue share of 34.3% in 2025. The market is being driven by the growing expansion of transmission remanufacturing capabilities, as aftermarket companies focus on strengthening cost-effective replacement solutions and improving drivetrain component availability. Rising demand for remanufactured transmissions is encouraging industry participants to expand their aftermarket portfolios and strengthen distribution and service capabilities.
 To learn more about this report, Download Free Sample Report
U.S. Automotive Driveline Aftermarket Industry Trends
The automotive driveline aftermarket industry in the U.S. held the largest share in the North American region in 2025. The market is being driven by the growing introduction of advanced driveline components that improve durability, torque-handling capability, weight efficiency, and overall vehicle performance. Increasing vehicle powertrain complexity across internal combustion, hybrid, and electric platforms is encouraging suppliers to expand driveline component portfolios and develop solutions compatible with front-, rear-, and all-wheel-drive configurations.
Europe Automotive Driveline Aftermarket Industry Trends
Europe's automotive driveline aftermarket industry is driven by increasing adoption of digital reverse-logistics solutions is accelerating remanufacturing efficiency by improving the collection, tracking, and reuse of automotive components in the aftermarket. The shift toward more structured core-return processes is enabling suppliers and distributors to improve component availability while supporting circular aftermarket operations.
Asia Pacific Automotive Driveline Aftermarket Industry Trends
The automotive driveline aftermarket industry in the Asia Pacific is anticipated to register the fastest CAGR over the forecast period. Rapid vehicle parc expansion and rising adoption of automatic, hybrid, and electrified powertrains are driving demand for specialized driveline maintenance, repair, and replacement solutions across the region. The transition from manual to automatic transmissions, particularly in high-growth markets such as India, is encouraging aftermarket suppliers to strengthen transmission servicing and replacement capabilities. Growing localization of transmission and eAxle production is strengthening regional supply ecosystems, improving component availability while expanding the installed base that will generate future aftermarket requirements.
Key Automotive Driveline Aftermarket Company Insights
Some key players in the automotive driveline aftermarket include Sonnax Industries, BorgWarner Inc., Dauch Corporation, Motive Gear Performance Drivetrain and among others.
-
The Sonnax Industries company is an automotive drivetrain and transmission manufacturing company that operates as part of Marmon Holdings, Inc. (a Berkshire Hathaway company) and provides specialized transmission rebuilding products, torque converter components, remanufactured valve bodies, and upgraded aluminum driveshafts. The company offers products under its market brands, including Sonnax, Sonnax Transmission Products, and Sonnax Sleeve Repair.
-
The Dauch Corporation (formerly American Axle & Manufacturing / AAM) operates as a global driveline and metal-forming supplier providing driveline systems, electric drive units, rear axle modules, power transfer units, and powder metallurgy solutions. The company acquired Dowlais Group plc and its subsidiaries - GKN Automotive and GKN Powder Metallurgy in February 2026. The company offers products and services under its core brand portfolio, including AAM (American Axle & Manufacturing), GKN Automotive, and GKN Powder Metallurgy.
Key Automotive Driveline Aftermarket Companies:
The following key companies have been profiled for this study on the automotive driveline aftermarket.
-
ZF AFTERMARKET
-
Dana Incorporated
-
Dauch Corporation
-
BorgWarner Inc.
-
Sonnax Industries
-
Transtar Industries, Inc.
-
Jasper Engines & Transmissions
-
Motive Gear Performance Drivetrain
-
Dorman Products
-
Raybestos Powertrain
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (ZF Aftermarket; Dana Incorporated; Dauch Corporation; BorgWarner Inc.; Dorman Products; Raybestos Powertrain)
- Focus on expanding global aftermarket distribution networks and maintaining strong OEM-to-aftermarket integration.
- Invest in advanced driveline technologies, digital service platforms, and broad product portfolios covering conventional and electrified vehicles.
- Extensive global presence, established brands, and comprehensive driveline product offerings provide a broad customer reach.
- Strong engineering capabilities and OE expertise enable consistent product quality and compatibility across multiple vehicle platforms.
- Large manufacturing and distribution operations result in higher operating costs and longer product development cycles.
- Dependence on mature automotive markets can limit growth compared with niche or rapidly expanding aftermarket segments.
Emerging Players (Sonnax Industries; Transtar Industries, Inc.; Jasper Engines & Transmissions; Motive Gear Performance Drivetrain)
- Focus on specialized driveline components, transmission solutions, remanufactured products, and performance applications.
- Expand through independent distributors, repair networks, and targeted regional market penetration.
- Greater flexibility enables faster response to changing customer requirements and specialized after-market demand.
- Competitive pricing and niche product expertise help build a strong presence in selected vehicle categories.
- Limited global distribution and lower brand recognition reduce market reach compared with established suppliers.
- Smaller R&D budgets and manufacturing scale can slow expansion into advanced driveline technologies and new vehicle platforms.
Recent Developments
-
In July 2026, ZF announced new digital, training, and braking solutions for Automechanika Frankfurt 2026, including an AI Voice Agent integrated with ZF Manager to improve workshop customer communication and appointment management. The company also introduced the High Voltage Battery Insights Training Program to enhance workshop expertise in diagnosing and servicing high-voltage battery systems.
-
In June 2026, BorgWarner announced an investment of USD 49 million to expand its operations in San Luis Potosí, Mexico, with a focus on increasing the production capacity of electronic components and solutions for electric vehicles. The expansion supports the company's electromobility manufacturing capabilities. The project also enhances the region's role in North America's automotive supply chain and advanced vehicle component manufacturing.
-
In June 2026, Dana Incorporated entered into a definitive agreement to combine with Eaton's Mobility business through a Reverse Morris Trust transaction. The combination brings together complementary powertrain technologies across the commercial and light-vehicle segments, including driveline, transmission, thermal, sealing, and electrification solutions. The combined company expands its aftermarket portfolio and broadens its global customer base while enhancing its product offerings across traditional and electrified mobility applications.
Automotive Driveline Aftermarket Industry Report Scope
Report Attribute
Details
Market size in 2025
USD 22.8 billion
Estimated market size in 2026
USD 24.9 billion
Projected market size by 2033
USD 44.8 billion
Growth rate
CAGR of 8.8% from 2026 to 2033
Base Year
2025
Actual data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, service, vehicle, distribution channel, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; China; India; Japan; South Korea; Australia; Brazil; KSA; South Africa; UAE
Key companies profiled
ZF Aftermarket; Dana Incorporated; Dauch Corporation; BorgWarner Inc.; Sonnax Industries; Transtar Industries, Inc.; Jasper Engines & Transmissions; Motive Gear Performance Drivetrain; Dorman Products; Raybestos Powertrain
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Automotive Driveline Aftermarket Industry Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global automotive driveline aftermarket industry report based on product, vehicle, service, distribution channel, and region.
-
Product Outlook (Revenue, USD Billion, 2021 - 2033)
-
AWD Systems
-
Transfer Case
-
Automatic Transmissions
-
-
Service Outlook (Revenue, USD Billion, 2021 - 2033)
-
Replacement
-
Repair
-
Remanufacturing
-
-
Vehicle Outlook (Revenue, USD Billion, 2021 - 2033)
-
SUVs
-
Light-Duty Pickup Trucks
-
Crossovers
-
Commercial Vehicles
-
-
Distribution Channel Outlook (Revenue, USD Billion, 2021 - 2033)
-
OEM Service Parts
-
Retail & E-commerce
-
Independent Aftermarket
-
Recycled Parts
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Australia
-
South Korea
-
-
Latin America
-
Brazil
-
MEA
-
UAE
-
South Africa
-
KSA
-
-
Research Methodology
The Automotive Driveline Aftermarket Industry figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each Automotive Driveline After segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Transfer Case
Transfer cases generate aftermarket revenue through replacement of worn gears, chains, bearings, seals, and actuators used in four-wheel-drive and all-wheel-drive vehicles. Demand is supported by component wear in SUVs, pickup trucks, and off-road vehicles operating under high-load conditions.
AWD Systems
Revenue from AWD systems is driven by the replacement of differentials, couplings, electronic control modules, and related driveline components to maintain traction and vehicle stability. Growing adoption of AWD-equipped passenger vehicles and crossovers supports consistent aftermarket demand.
Automatic Transmissions
Automatic transmission aftermarket revenue is generated from replacement parts such as torque converters, valve bodies, clutch packs, filters, and transmission control components. Increasing vehicle ownership and regular transmission maintenance contribute to sustained demand across passenger and commercial vehicles.
Segment - Service
Revenue capture definition
Repair
Repair services include inspection, diagnosis, and restoration of worn or damaged driveline components to restore normal vehicle operation. These services extend component life while reducing replacement frequency and maintenance costs.
Replacement
Replacement services involve installing new aftermarket driveline components when existing parts reach the end of their service life or cannot be repaired economically. Demand is supported by routine maintenance, component wear, and vehicle aging.
Remanufacturing
Remanufacturing involves restoring used driveline components to performance standards through disassembly, refurbishment, testing, and reassembly. This service offers a cost-effective alternative to new parts while supporting resource efficiency and extending product life.
Segment - Vehicle
Revenue capture definition
SUVs
This segment covers aftermarket sales of driveline parts for sport utility vehicles, including AWD and 4WD systems. Revenue is driven by increasing SUV ownership and the replacement of high-wear driveline components during the vehicle lifecycle.
Light-Duty Pickup Trucks
Revenue from this segment includes aftermarket driveline components used in light-duty pickup trucks for routine maintenance, wear-related replacement, and performance restoration. Demand is supported by frequent towing, payload carrying, and extended vehicle ownership.
Crossovers
Revenue in this segment comprises replacement driveline components designed for crossover utility vehicles used in daily commuting and family transportation. Growth is supported by the expanding crossover vehicle parc and regular maintenance requirements.
Commercial Vehicles
This segment includes aftermarket revenue generated from driveline components used in trucks, buses, and other commercial vehicles. High vehicle utilization, long operating hours, and scheduled fleet maintenance contribute to consistent demand for replacements.
Segment - Distribution Channel
Revenue capture definition
OEM Service Parts
Revenue is generated through replacement driveline components supplied by original equipment manufacturers and their authorized dealer networks. This channel serves customers seeking parts that match original vehicle specifications and manufacturer quality standards.
Retail & E-commerce
Revenue is captured through automotive retailers and online platforms offering driveline parts directly to consumers and repair workshops. Digital sales channels improve product accessibility and simplify purchasing through a wide range of vehicle applications.
Recycled Parts
Revenue is generated from refurbished, remanufactured, and salvaged driveline components supplied through specialized recycling and remanufacturing companies. This channel addresses demand for cost-efficient replacement parts while extending the usable life of automotive components.
Independent Aftermarket
Revenue comes from independent manufacturers, distributors, and repair networks supplying replacement driveline components across multiple vehicle brands. Competitive pricing and broad product availability support high sales volumes in this channel.
Estimation Model
Layer Name
Key Questions
Description
Ownership Layer
Which vehicles require driveline replacement?
Identify the global vehicle parc by vehicle and age to estimate the addressable base of vehicles requiring driveline maintenance and replacement. This establishes the potential population for aftermarket driveline components.
Replacement Layer
How many vehicles require component replacement?
Apply replacement cycles, vehicle utilization, mileage, and failure rates for components such as CV joints, driveshafts, clutches, differentials, and axle shafts. This converts the total vehicle parc into annual aftermarket replacement demand.
Distribution Channel Layer
Where are replacement components purchased?
Measure the distribution of aftermarket sales across OEM service parts, independent aftermarket suppliers, retail & e-commerce platforms, and recycled/remanufactured parts channels. This reflects the penetration of each sales channel within the aftermarket ecosystem.
Monetization Layer
How much aftermarket revenue is generated?
Apply the average selling price of driveline components along with replacement volumes across each product category and distribution channel. Aggregate revenues from component sales and related installation services to estimate the total automotive driveline aftermarket revenue.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Market Entry & Expansion Assessment
Regional demand sizing and forecasting
Customer segmentation and buying behavior analysis
Competitive landscape benchmarking
Regulatory and distribution channel assessment
Identified high-growth market opportunities
Supported go-to-market strategy development
Highlighted investment priorities and risks
Enabled data-driven expansion planning
Channel Partner & Distribution Study
Dealer/distributor network analysis
Channel performance benchmarking
Margin and profitability assessment
Route-to-market evaluation
Optimized channel strategy
Identified distribution gaps
Improved partner engagement approach
Enhanced market penetration planning
Customer & End-User Insights Study
Consumer awareness and adoption analysis
Purchase decision journey mapping
Satisfaction and loyalty assessment
Usage pattern and pain-point evaluation
Revealed key adoption drivers and barriers
Supported customer-centric product development
Improved targeting and engagement strategy
Identified opportunities for retention and upselling
Frequently Asked Questions About This Report
Asia Pacific is the fastest-growing region over the forecast period.
The global automotive driveline aftermarket industry size was estimated at USD 22.8 billion in 2025 and is projected to grow from USD 24.9 billion in 2026.
The global automotive driveline aftermarket industry is expected to grow at a compound annual growth rate of 8.8% from 2026 to 2033 to reach USD 44.8 billion by 2033.
Independent aftermarket held the largest revenue share in 2025, while retail & e-commerce is the fastest growing segment.
North America dominated the automotive driveline aftermarket industry with a share of 34.3% in 2025.The market is being driven by the growing expansion of transmission remanufacturing capabilities, as aftermarket companies focus on strengthening cost-effective replacement solutions and improving drivetrain component availability.
Digitalization and predictive maintenance are transforming the automotive driveline aftermarket by enabling connected diagnostics, proactive servicing, and faster replacement of driveline components through data-driven maintenance solutions.
Some key players operating in the automotive driveline aftermarket industry include ZF Aftermarket; Dana Incorporated; Dauch Corporation; BorgWarner Inc.; Sonnax Industries; Transtar Industries, Inc.; Jasper Engines & Transmissions; Motive Gear Performance Drivetrain; Dorman Products; Raybestos Powertrain
Transfer case held the largest revenue share in 2025, while AWD Systems is the fastest growing segment.
Repair held the largest revenue share in 2025, while remanufacturing is the fastest growing segment.
About the Author(s)
Automotive & Transportation Research Team
Technology · Automotive & TransportationThis report was authored by the automotive & transportation research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the automotive & transportation segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


