
- Home
- »
- Automotive & Transportation
- »
-
Automotive Semiconductor Market Size Report, 2026-2033GVR Report cover

Automotive Semiconductor Market (2026 - 2033)
Size, Share & Trends Analysis Report By Component (Processor, Sensor, Memory), By Vehicle Type (Passenger Vehicle, LCV, HCV), By Application (Chassis, Powertrain, Safety, Body Electronics, Telematics & Infotainment), By Region, And Segment Forecasts
Market Size, 2025
$59.6BMarket Estimate, 2026
$67.2BMarket Forecast, 2033
$146.4BCAGR, 2026–2033
11.8%Automotive Semiconductor Market Summary
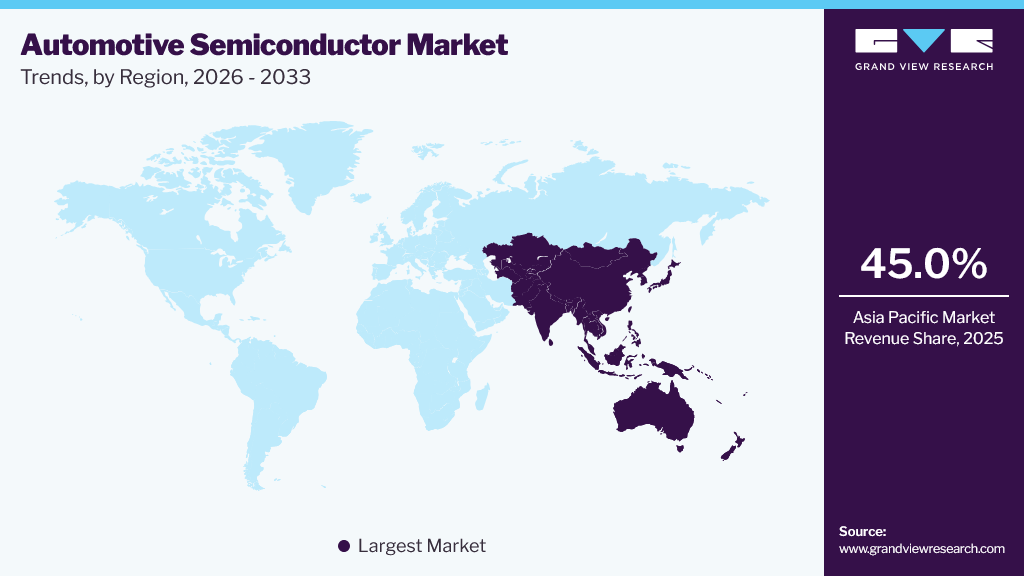
The global automotive semiconductor market size was valued at USD 59.6 billionin 2025 and is projected to grow from USD 67.2 billion in 2026 to USD 146.4 billion by 2033, at a CAGR of 11.8% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 45.0% in 2025. The increasing penetration of electronic components in luxury to mass-produced cars, the adoption of electronic control units (ECUs) in modern vehicles, and the growing focus on vehicle safety are expected to drive steady market growth over the next few years.
Key Market Trends & Insights
- By component: The discrete power segment held the largest market share of above 28% in 2025.
- By vehicle type: The passenger vehicles segment held the largest market share of more than 66% in 2025.
- By application: The body electronics segment held the largest market share of more than 23% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (45.0% revenue share, 2025)
- By country: The China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 59.6 Billion
- Estimated market size in 2026: USD 67.2 Billion
- Projected market size by 2033: USD 146.4 Billion
- CAGR (2026-2033): 11.8%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The other factors contributing to the market growth include the proliferation of connected cars, infotainment systems, automotive safety systems, and fuel efficiency standards. The growing demand for electric and hybrid vehicles presents a significant opportunity for the automotive semiconductor industry. These vehicles require semiconductors for devices such as ADAS and ECUs to manage the battery, motor, and other components, thereby driving demand for sophisticated, specialized semiconductors in the automotive semiconductor market. These developments in the market are likely to affect the supply chain, the aftermarket, and semiconductor component manufacturers. As a result, conventional diagnostic systems may be replaced by onboard diagnostic systems to enable the continuous monitoring of the condition of a vehicle's mechanical and electrical components.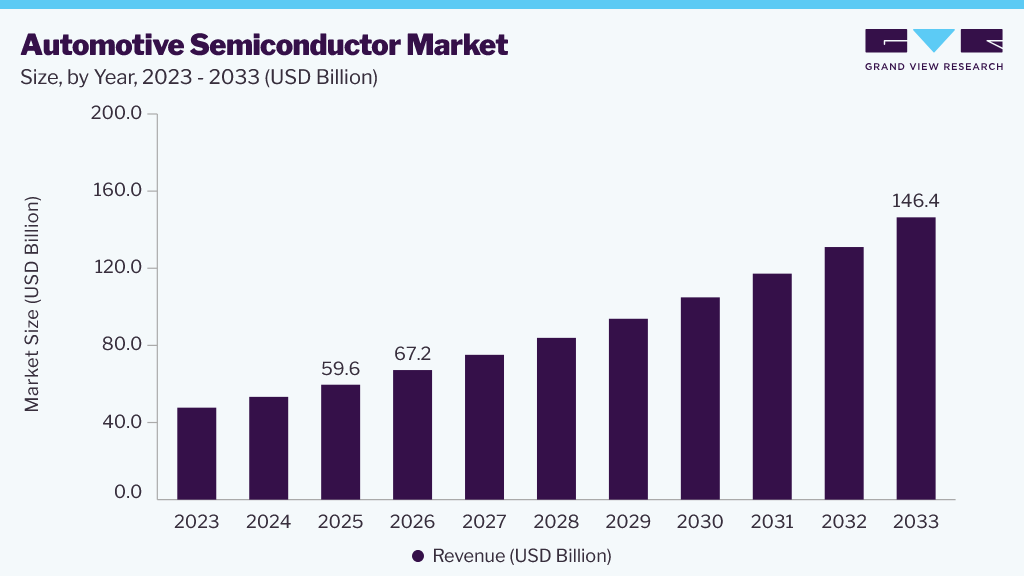 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Three key trends, namely autonomy, electrification, and connected mobility, are expected to emerge as major revenue drivers for the global market. These trends play a pivotal role in driving the demand for electronic components in a car, subsequently driving the demand for semiconductors in the automotive space.
According to the World Health Organization, approximately 1.24 billion individuals are killed or injured as a result of road traffic crashes each year. This has triggered an increased focus on the prevention of accidents through the implementation of active safety measures. As a result, active safety features are increasingly being integrated into vehicles to help avoid collisions and accidents. Amongst the vehicle safety provisions, crash avoidance technology, including automatic emergency braking systems, automatic driver assistance systems (ADAS), for passenger vehicles, is set to remain a standard feature for the majority of the new vehicles produced. These technologies, such as ADAS and emergency braking systems, use sensors to monitor changes in vehicle behavior, and semiconductors the part of the sensors. Thus, with the rise in the adoption of vehicle safety systems, the market for automotive semiconductors is expected to grow significantly over the forecast period.
The automotive semiconductor industry faced severe shortages of semiconductors globally due to several factors, including the pandemic and disruptions in the semiconductor supply chain owing to wars. The Russia-Ukraine conflict has added to these disruptions in the global supply chain, which has affected the automotive semiconductor production. The Minister of State for Electronics and Information Technology in the Government of India stated that Ukraine and Russia are major sources of Neon and Hexafluorobutadiene gases; moreover, the impact of the war is expected to affect the supply chains of semiconductors. These gases are essential for semiconductor chip production, as they are used in the lithography process.
Market Dynamics
The demand for electric and hybrid vehicles is witnessing a rapid surge in recent years majorly attributed to growing environmental concerns and rising fuel prices. This has encouraged the demand for automotive semiconductors. According to the data published by the International Energy Agency, one in four cars sold in 2025 was electric. This percentage rises to 97% in Norway and 53% in China. These technologically advanced vehicles employ several electronic systems, including power electronics and battery management systems. With stringent government emission and safety standards, EV and hybrid car manufacturers are continuously upgrading their offerings to meet the mandates. This has further boosted the demand for automotive semiconductors.
The growing popularity of ADAS and investments in self-driving or autonomous cars are another key driver for market growth. Modern automobiles equipped with ADAS offer features such as cruise control, radar monitoring, automatic energy braking, and an anti-collision system. In addition, in-car infotainment, automatics climate control, advanced interior and exterior lighting, and advanced safety features require discrete and complex electronics components. Owing to these, automotive manufactures are partnering with major semiconductor manufacturers, namely NVIDIA and Qualcomm, to design, develop, and manufacture automotive semiconductors. Heavy investments and collaborations are further helping the overall automotive semiconductors market to grow.
The automotive semiconductor market faces a consistent challenge of maintaining a seamless supply of semiconductor raw material and disruption of the supply chain. Frequent undesirable global events, such as the Ukraine-Russia war, U.S. sanctions on China and other major manufacturing countries, and the U.S.-Iran war, disrupted the global supply chain and affected several commodities, including agricultural products, fuel, and semiconductor raw materials. Automotive semiconductors are carefully designed, complex discrete electronics. These electronics cannot be easily swapped for alternatives.
Automotive semiconductors require specific materials and specialized manufacturing environments. Global phenomena such as regional trade disputes, embargoes, or localized logistics breakdowns immediately create bottlenecks for semiconductor manufacturing and thus stall the production of advanced electronic control units.
The emergence of software-defined vehicles is transforming automotive architectures from distributed electronic control units to centralized computing platforms. Such transformations are incurring heavy investments for developing high-performance computing chips, automotive-grade memory, and domain controllers. Growing demand for advanced driver assistance systems (ADAS) and autonomous vehicles requiring high-performance processors, sensors, microcontrollers, and AI accelerators capable of handling vast amounts of real-time data is expected to further boost the demand for advanced automotive semiconductors.
In addition to the growing demand for EVs, government mandates for IC vehicles are also compelling automotive manufactures to improve the efficiency of vehicles in terms of emissions, fuel consumption, and vehicle safety and longevity. Furthermore, the promotion of philosophies such as ‘repair, not replace’ and the recycling of automotive components is encouraging semiconductor developers to develop rugged, reliable semiconductors that can withstand harsh, adverse conditions. Innovations, investments in R&D, and continuous advancements in the automotive industry are expected to create multiple growth opportunities for the overall market in the coming years.
Analyst Perspective
The growing complexity of electric and software-defined vehicles is demanding better coordination and collaboration between automotive manufacturers and semiconductor companies. Recent partnerships involving Infineon, NVIDIA, Continental, and automotive OEMs are evidently showcasing that chip suppliers are evolving from component vendors into strategic technology partners. As EV adoption accelerates and vehicles become increasingly software-centric, demand for power semiconductors, AI processors, sensors, and battery-management chips is expected to strengthen, creating significant growth opportunities across the automotive semiconductor value chain.
Component Insights
The discrete power segment led the market with the largest revenue share of more than 28% in 2025 and is expected to grow at the fastest CAGR of 10.9% over the forecast period. The component segment is divided into processors, discrete power, sensors, memory, and others. These components help enhance vehicle electrification, connectivity, and shared mobility services. Several key players are taking strategic initiatives to launch new products in the market to expand their market share in discrete power. For instance, in December 2025, Littelfuse, Inc. launched six new automotive current sensors for electric and hybrid vehicle performance, efficiency, and functional safety.
The memory devices segment is projected to emerge as the second-fastest-growing component segment over the forecast period. This growth can be mainly attributed to the ongoing electrification of the major applications of automobiles, such as powertrain, which is creating more demand for power components such as IGBT and MOSFET. The need for greater safety and advanced features in vehicles is driving the need for more memory devices per vehicle to program various control systems for an autonomous system.
Vehicle Type Insights
The passenger vehicles segment led the market with the largest revenue share of more than 66% in 2025. This growth can be attributed to the high demand for passenger cars across the globe. Moreover, increasing installation of automotive infotainment systems in passenger cars for hands-free phone connectivity and providing navigational services, climate control, voice control, parking assistance, two-way communication tools, and access to the internet is further stimulating the segment growth.
The light commercial vehicle segment is expected to expand at a significant CAGR of above 6.0% over the forecast period, offering significant scope for global market growth. Several governments are implementing various incentive schemes and programs to encourage semiconductor manufacturing, which is expected to boost the growth of the automotive semiconductor industry. India's National Critical Mineral Mission (NCMM), launched to reduce import dependence, this comprehensive mission funds domestic exploration, abolishes customs duties on 25 critical minerals, and includes an approximately USD 160 billion incentive scheme to build processing capacity.
Application Insights
The body electronics accounted for the largest market revenue share in 2025 and is projected to grow at the fastest CAGR of more than 9.0% from 2026 to 2033. With the growing demand for comfort and convenience features, such as power windows, electric seats, and climate control systems, automakers are incorporating more body electronics in their vehicles. Numerous key players in the market are taking initiatives to strengthen their operations in this segment. For instance, NOVOSENSE and Continental AG expanded their partnership in April 2025 to develop system-on-chip (SoC) and low-side switch solutions for automotive platforms. In another instance, NVIDIA and Toyota entered into a partnership at CES 2025 to develop and integrate AI computing for autonomous and intelligent vehicles.
The telematics & infotainment segment is expected to witness at a significant CAGR over the forecast period. The growth can be attributed to the adoption of connected cars, autonomous, and semi-autonomous vehicles. Telematics and infotainment systems play a crucial role in enhancing the driving experience by providing real-time information, entertainment options, and connectivity with external networks. Furthermore, the adoption of electric vehicles and the development of autonomous driving technologies, such as advanced driver assistance systems (ADAS), which require semiconductors for power management, battery monitoring, and control, are expected to propel the growth of the telematics & infotainment segments in the automotive semiconductor industry.
Regional Insights
Asia Pacific dominated the global automotive semiconductor market with the largest revenue share of more than 45.0% in 2025 and is expected to grow at the fastest CAGR of 9.6% from 2026 to 2033. This is attributed to the growth of the automotive industry, especially in emerging economies such as India, China, and Japan. In the Asia Pacific, China accounted for the largest market revenue share in the Asia Pacific in 2025. Moreover, the growing e-commerce industry in the region is anticipated to surge the demand for commercial vehicles in the coming years, in the market as the manufacturing of commercial vehicles would require the usage of automotive semiconductors.
 To learn more about this report, Download Free Sample Report
Europe Automotive Semiconductor Market Trends
The automotive semiconductor market in Europe is projected to grow at a significant CAGR of 7.0% over the forecast period. The introduction of numerous automotive semiconductor production facilities in Germany is contributing to the country’s high production capacity, driving the development of new technologies, attracting further investment, and creating new job opportunities in the automotive semiconductor industry. This is expected to bode well for the growth of the automotive semiconductors market in the country. In addition, government and regulatory body support is further driving the local market. For instance, the European Chips Act II is a key initiative to support Europe’s semiconductor ecosystem. One of the core objectives of this act is to strengthen the semiconductor supply chain in the region and maintain a constant availability for the automotive sector.
Key Automotive Semiconductor Company Insights:
The automotive semiconductor industry is moderately consolidated, with the presence of several global as well as regional players. The players in the market are focusing on product launches to expand product offerings and meet consumer demands. The key players in the market also focus on acquisitions to expand product offerings and presence across the global market.
Key Automotive Semiconductor Companies
The following key companies have been profiled for this study on the automotive semiconductor market.
-
Analog Devices, Inc.
-
Infineon Technologies AG
-
NXP Semiconductors
-
Renesas Electronics Corporation
-
Robert Bosch GmbH
-
ROHM CO., LTD.
-
Semiconductor Components Industries, LLC
-
STMicroelectronics
-
Texas Instruments Incorporated
-
TOSHIBA CORPORATION
Recent Development
-
In December 2025, Renesas Electronics Corporation announced the expansion of its software-defined vehicle (SDV) solution for the fifth-generation (Gen 5) R-Car family. The Gen 5 R-car family of devices is the industry’s first multi-domain automotive system-on-chip (SoC) manufactured with advanced 3nm process technology.
-
In September 2025, Qualcomm and BMW Group jointly launched an automated driving software stack and AI-enabled Snapdragon Ride Pilot Automated Driving System powered by Snapdragon Ride system-on-chips.
Automotive Semiconductor Market Report Scope
Report Attribute
Details
Market size in 2025
USD 59.6 billion
Estimated market size in 2026
USD 67.2 billion
Projected market size by 2033
USD 146.4 billion
Growth rate
CAGR of 11.8% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Component, vehicle type, application, region
Regional Scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country Scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; China; India; Japan; Brazil; United Arab Emirates (UAE); Saudi Arabia; South Africa
Key companies profiled
Analog Devices, Inc.; Infineon Technologies AG; NXP Semiconductors; Renesas Electronics Corporation; Robert Bosch GmbH, ROHM CO., LTD.; Semiconductor Components Industries, LLC; STMicroelectronics; Texas Instruments Incorporated; TOSHIBA CORPORATION
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Automotive Semiconductor Market Report Segmentation
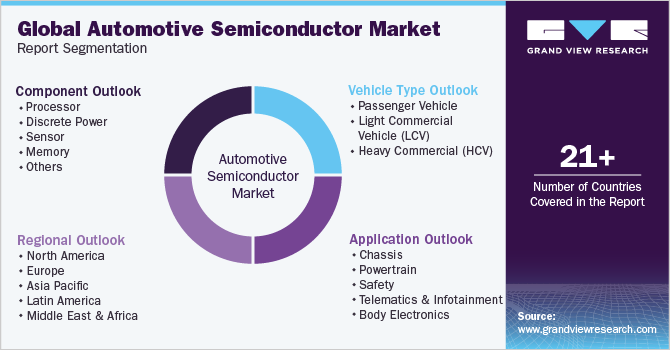
The report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global automotive semiconductor market report based on component, vehicle type, application, and region:
 To learn more about this report, Download Free Sample Report
-
Component Outlook (Revenue, USD Billion, 2021 - 2033)
-
Processor
-
Discrete Power
-
Sensor
-
Memory
-
Others
-
-
Vehicle Type Outlook (Revenue, USD Billion, 2021 - 2033)
-
Passenger Vehicle
-
Light Commercial Vehicle (LCV)
-
Heavy Commercial (HCV)
-
-
Application Outlook (Revenue, USD Billion, 2021 - 2033)
-
Chassis
-
Powertrain
-
Safety
-
Telematics & Infotainment
-
Body Electronics
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
U.K.
-
Germany
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
-
Latin America
-
Brazil
-
-
Middle East & Africa (MEA)
-
United Arab Emirates (UAE)
-
Saudi Arabia
-
South Africa
-
-
Frequently Asked Questions About This Report
The global automotive semiconductor market size was valued at USD 59.6 billion in 2025 and is estimated at USD 67.2 billion for 2026.
The global automotive semiconductor market is expected to grow at a CAGR of 11.8% from 2026 to 2033, reaching USD 146.4 billion.
Key players include Analog Devices, Inc.; Infineon Technologies AG; NXP Semiconductors; Renesas Electronics Corporation; Robert Bosch GmbH, ROHM CO., LTD.; Semiconductor Components Industries, LLC; STMicroelectronics; Texas Instruments Incorporated; TOSHIBA CORPORATION
Asia Pacific dominated with a 45.0% revenue share in 2025.
Passenger vehicles dominated the automotive semiconductor market with a share of 66.0% in 2025.
About the Author(s)
Automotive & Transportation Research Team
Technology · Automotive & TransportationThis report was authored by the automotive & transportation research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the automotive & transportation segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


