
- Home
- »
- Automotive & Transportation
- »
-
Automotive Smart Display Market Size Report 2026-2033GVR Report cover

Automotive Smart Display Market (2026 - 2033)
Size, Share & Trends Analysis Report By Display Size (Less than 5'', 5''-10'', Greater than 10''), By Display Technology (LCD, TFT-LCD, OLED), By Application, By Region, And Segment Forecasts
Market Size, 2025
$13.6BMarket Estimate, 2026
$15.0BMarket Forecast, 2033
$35.4BCAGR, 2026–2033
13.1%Automotive Smart Display Market Summary
The global automotive smart display market size was valued at USD 13.6 billion in 2025 and is projected to grow from USD 15.0 billion in 2026 to USD 35.4 billion by 2033, at a CAGR of 13.1% from 2026 to 2033. Asia Pacific dominated the market with the largest revenue share of over 52.0% in the global market in 2025. The increasing demand for advanced functions, including navigation, multimedia systems, driver assistance, and connected car features that help improve the driver-to-vehicle communication, is anticipated to boost the use of smart displays in the automotive sector.
Key Market Trends & Insights
- By display size: The less than 5” display size segment held the largest market share of around 40.5% in 2025.
- By display technology: The TFT-LCD display segment held the largest market share of around 49% in 2025.
- By application: The center stack display segment held the largest market share of approximately 37% in 2025.
Regional Highlights
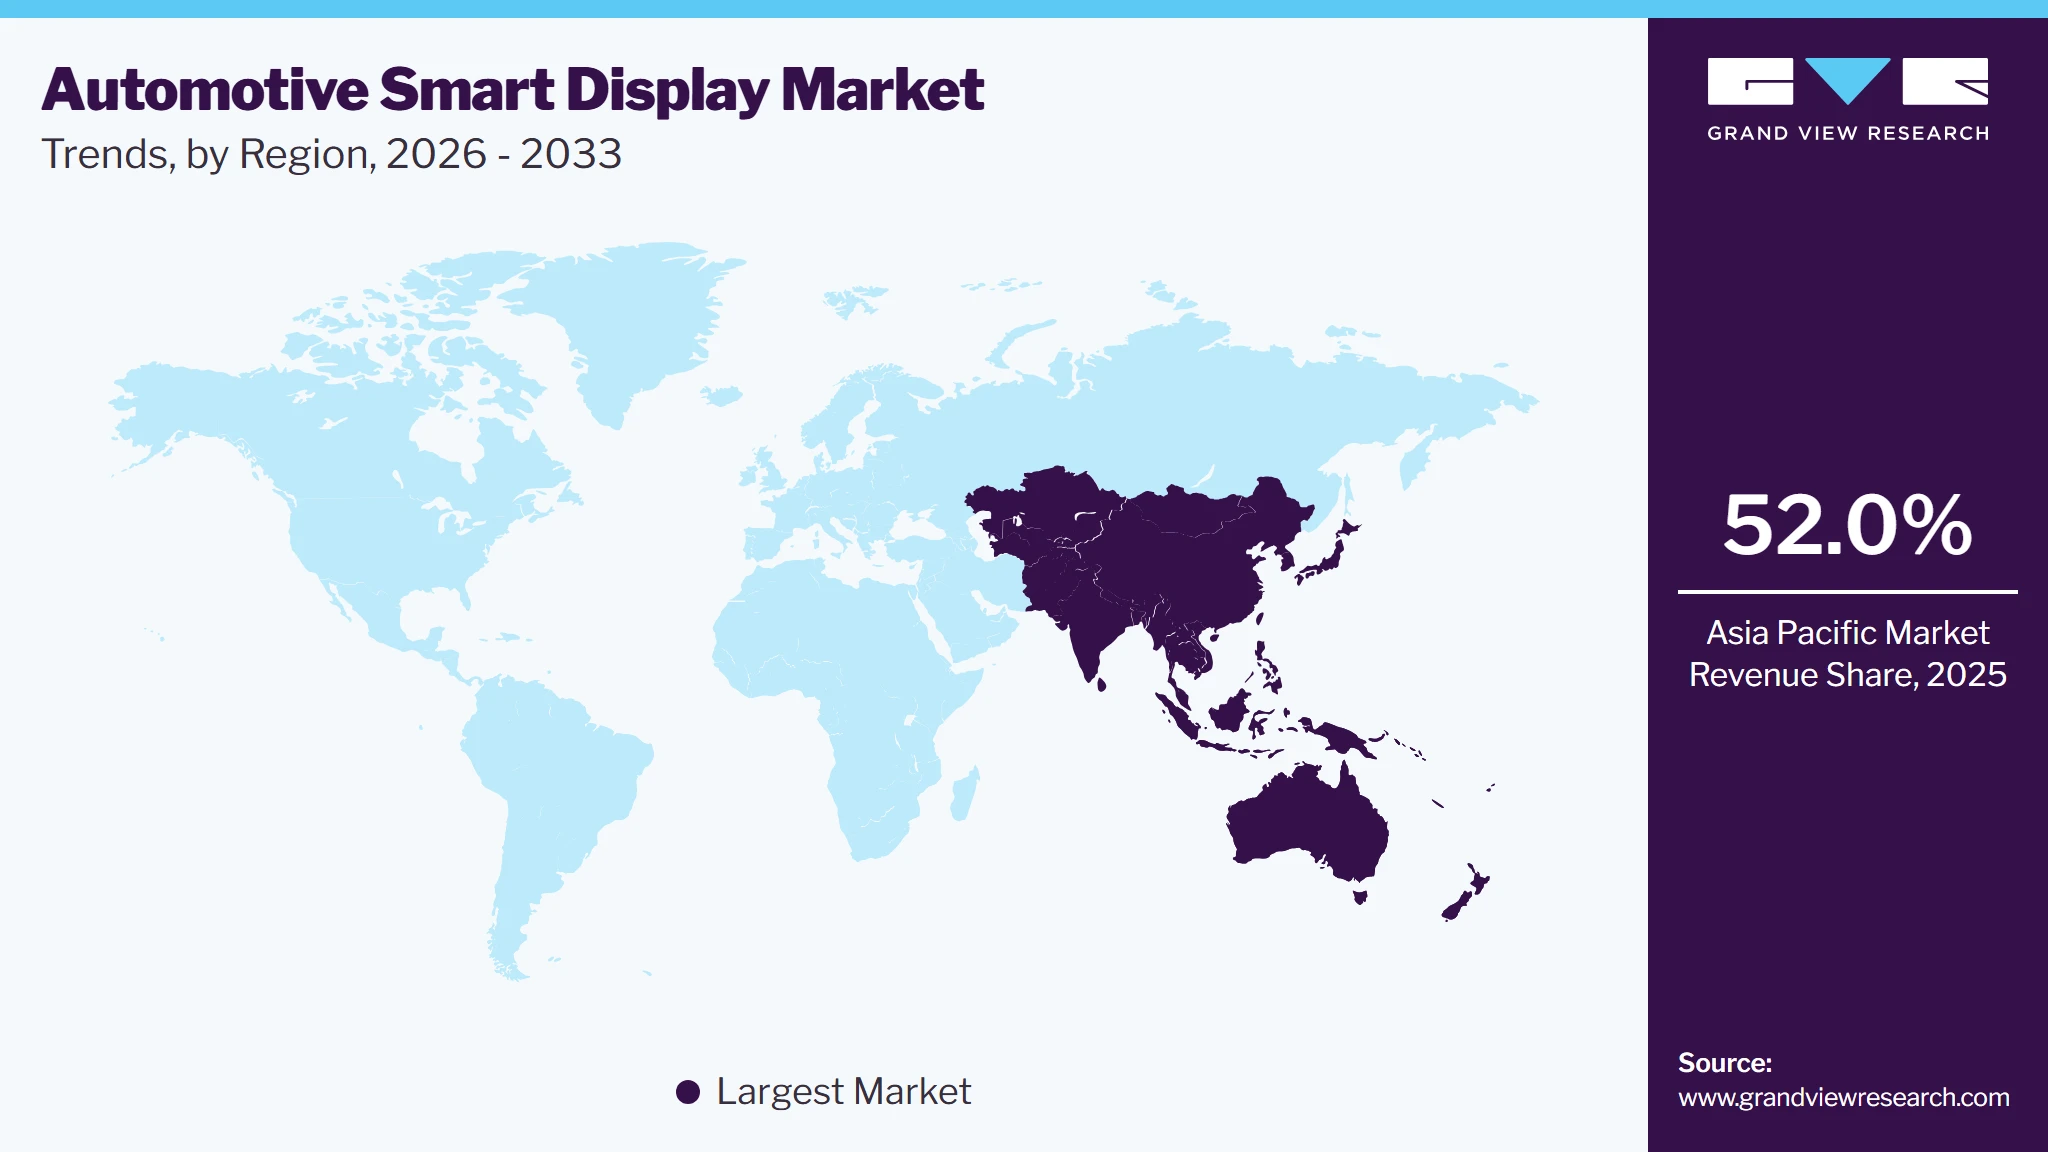
- Largest regional market: Asia Pacific (52.0% revenue share, 2025)
Market Size & Forecast
- Market size in 2025: USD 13.6 Billion
- Estimated market size in 2026: USD 15.0 Billion
- Projected market size by 2033: USD 35.4 Billion
- CAGR (2026-2033): 13.1%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Furthermore, growing demand for enhanced safety, comfort, and convenience in automobiles, especially in developing and mature economies, is also anticipated to propel the automotive smart display industry growth over the forecast period.The rise in the demand for autonomous and semi-autonomous vehicle technology and the growth of the high-end and luxury car segments, especially in emerging markets, are also expected to offer growth avenues for the global market over the forecast period.
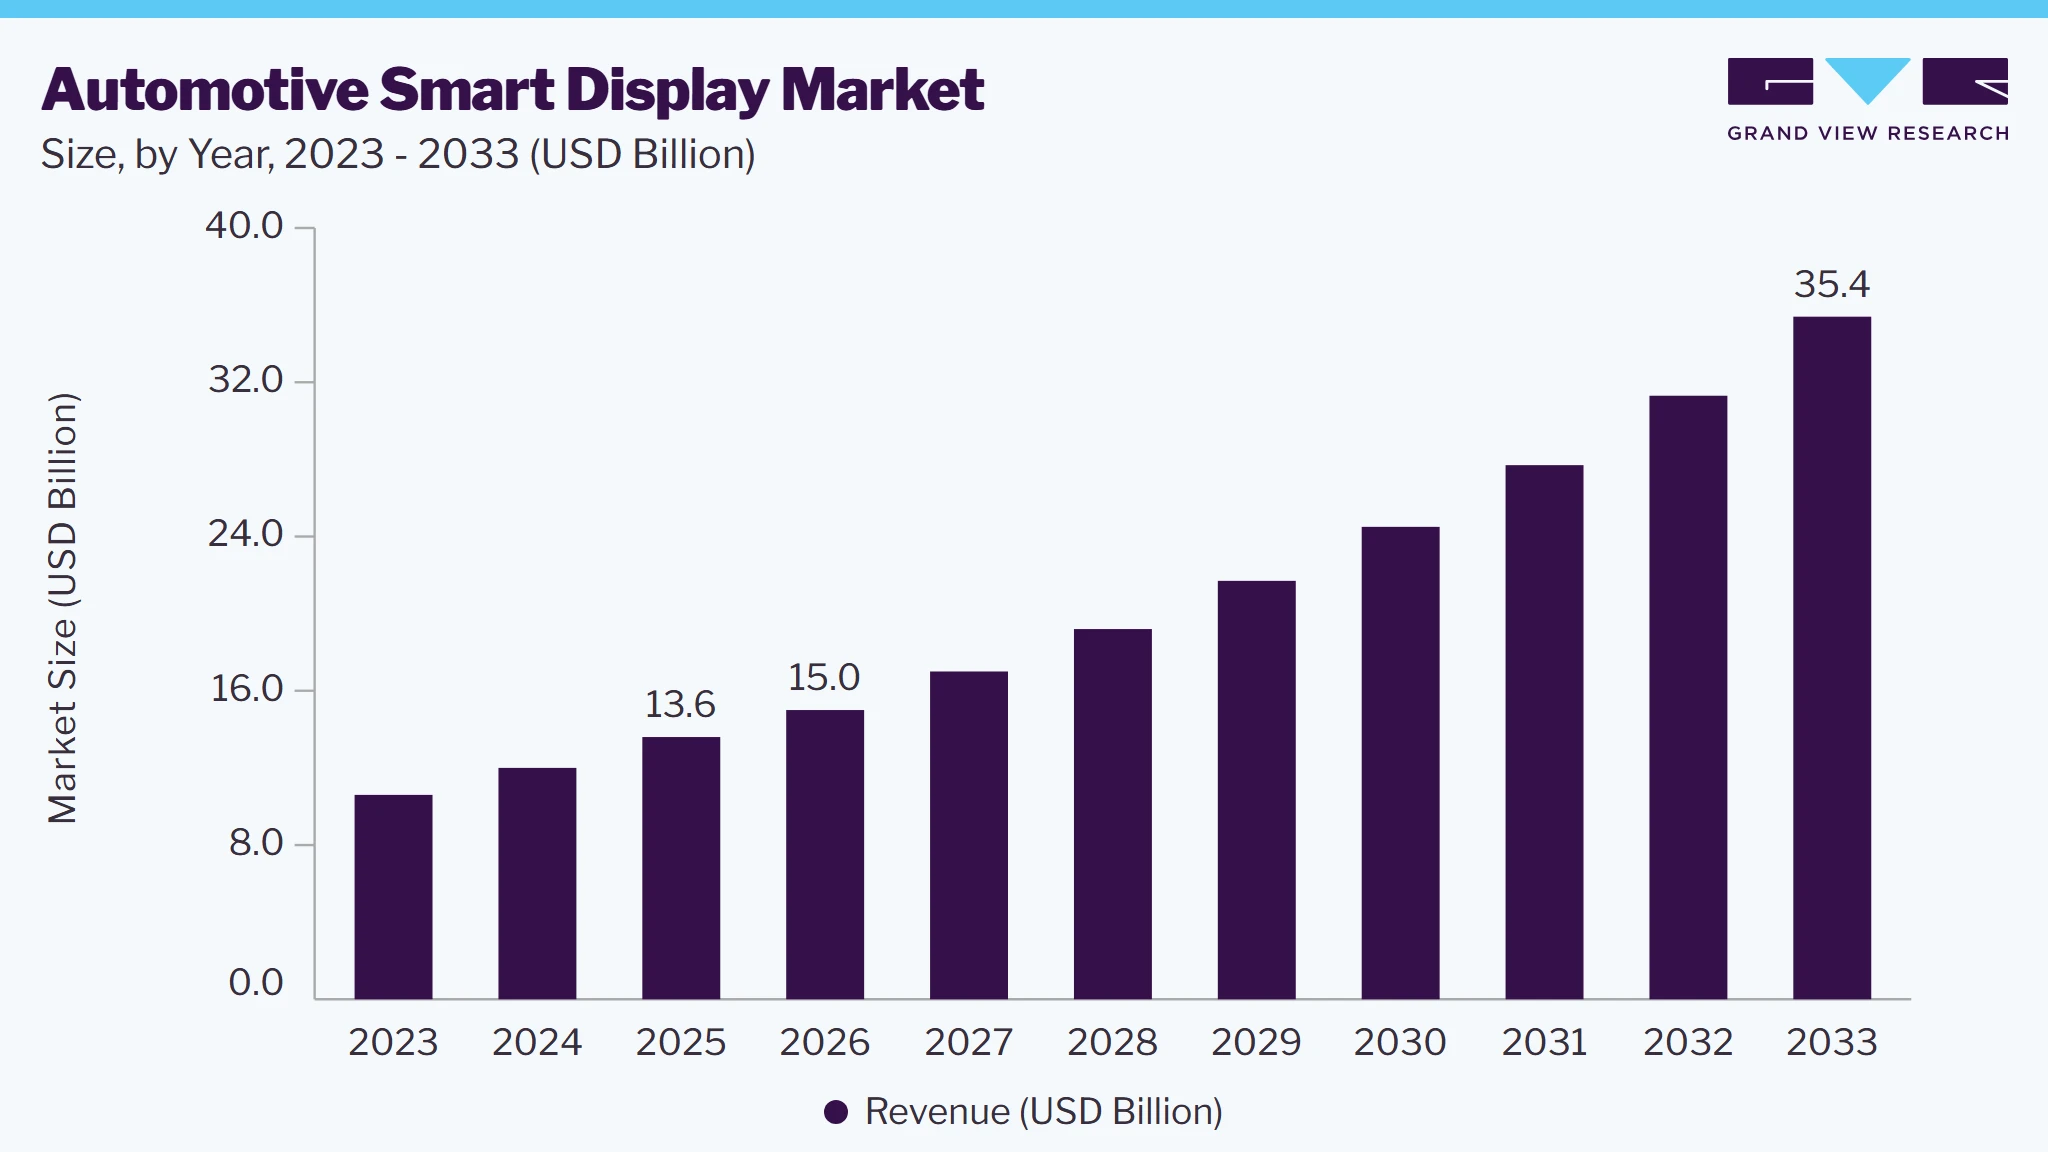 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
The use of smart displays in automotive applications is growing rapidly. The automotive smart display industry relies on demand trends in the automotive industry, progress toward the development of autonomous vehicles, technological advancements in cockpit electronics, and buyer preferences. Moreover, smart displays play an essential role in making critical driver-assistance functions available on a single touchscreen platform.
Technologies such as gesture control systems, advanced infotainment systems, head-up displays, telematics, central controllers, and steering-mounted controls are increasingly used in passenger vehicles for safety, comfort, luxury, and security. The governments of several countries across the globe are implementing regulations pertaining to vehicle safety and security. For instance, the document by the National Highway Traffic Safety Administration (NHTSA) states that vehicle and equipment manufacturers should review and enhance the vehicle cybersecurity system as a primary priority. This has prompted the demand for electronic devices, including smart displays, across the globe.
Market Dynamics
The growing demand for advanced in-car infotainment systems, connected vehicles, and enhanced user experiences is one of the prime factors stimulating growth in the automotive smart display industry. The manufacturers are adopting advanced technologies, such as large touch screens, digital instrument clusters, HUDs, and AI-driven cockpits, for drivers’ comfort and safety, and also for enhancing the connectivity of vehicles. Advancing technologies, such as ADAS, Autonomous driving, and connected car platforms, are boosting the adoption of smart displays for vehicle navigation, diagnostics, infotainment, and vehicle safety. As consumers prefer connected and technologically advanced cars, automakers are focusing on the development of a new generation of cockpit electronics and display technologies.
The high cost of advanced display technologies and increasing concerns about driver distraction are key factors restraining market growth. The use of advanced hardware (high-resolution displays, processors, sensors) and software integration into vehicle smart displays increases the overall production costs. Expensive hardware such as OLED displays, augmented reality head-up displays (HUDs), 3D visualization systems, and multi-display cockpit solutions is difficult to implement in mass-market cars and also contributes to this factor. With a rise in the number and size of display elements, vehicle cabin distraction and road safety have become a concern, potentially limiting the widespread adoption of advanced smart display solutions across all vehicle segments.
The growing adoption of AI-enabled cockpit systems, autonomous driving technologies, and next-generation display solutions presents significant opportunities for the automotive smart display industry. The integration of AI assistants, voice-controlled interfaces, and personalized digital experiences is transforming the role of displays from information screens to intelligent vehicle control centers. In addition, the increasing penetration of electric and software-defined vehicles is driving demand for larger, high-resolution, multifunctional displays. The growing popularity of advanced display architectures, including pillar-to-pillar screens and immersive digital cockpits, is expected to create new growth opportunities for manufacturers and technology providers during the forecast period.
Analyst’s Perspective
Hardware is no longer the only factor driving automotive smart display innovation, as the market shifts toward integrated cockpit platforms. Future value will increasingly come from software upgrades, AI-powered features, and personalized in-cabin experiences. Seamless integration with digital ecosystems will become a key competitive differentiator. As electric and autonomous vehicles evolve, smart displays will play a central role in safety, navigation, entertainment, and vehicle control. Suppliers offering integrated hardware and software solutions will be better positioned for long-term growth. Strong automaker partnerships, scalable technologies, and compliance with safety and cybersecurity regulations will provide a competitive advantage.
Display Size Insights
The less than 5-inch display size segment led the market with the largest revenue share of around 40.5% in 2025. The use of less than 5" smart displays is expected to gain traction in line with the growing preference for features, such as navigation, multimedia support, driving assistance, and driver-to-vehicle communication. Furthermore, as vehicles become more compact and advanced, there is a growing need for displays that take up less space and provide more information. Smaller smart displays are an efficient solution to this problem as they can fit in tight spaces while still providing a range of features and information.
The greater than 10” smart display segment is projected to register at the fastest CAGR from 2026 to 2033. The greater than 10" displays in automobiles allow integration of all functions, including the instrument cluster and the central stack system, and make accessing them easy via a single screen. OEMs, such as LG Display, are developing pillar-to-pillar displays that span the entire dashboard, combining the instrument cluster display, co-driver display, and central information display into a single screen to improve visibility.
Display Technology Insights
The TFT-LCD display segment led the market with the largest revenue share of around 49% in 2025. LCDs and TFT LCDs are commonly used in display applications as they meet durability and temperature standards. Depending on the range of temperature required for the function of the display, manufacturers use a combination of TFT and LCD in a vehicle. The basic instrument cluster, center stack touchscreen displays, and rear-seat entertainment touchscreen display are equipped with LCD panels. Advanced applications are equipped with TFT-LCD displays for their enhanced visual quality.
The OLED display segment is expected to register at a significant CAGR from 2026 to 2033. Passenger cars with OLED displays are being showcased at various automotive exhibitions; however, the penetration rate is low compared to LCDs in consumer models. Moreover, OLED automotive smart display systems are expected to experience faster adoption than other display technologies over the forecast period. Most of the upcoming vehicles are equipped with OLED displays.
Application Insights
The center stack display segment led the market with the largest revenue share of 37% in 2025. Center stack displays are infotainment systems that offer a range of interactive features, including navigation, music, cabin temperature controls, and other information. Advancements in the field of self-driven and connected cars are expected to propel the demand for center stack displays in vehicles. In addition, several vehicle OEMs are aiming to offer advanced center-stack display solutions across mid-segment and economical vehicle variants, thereby driving segment growth.
The Head-Up Display (HUD) segment is projected to register at a significant CAGR over the forecast period. Advances in display technologies and the growing prices of head-up displays are expected to play a vital role in shaping the growth of the segment. The head-up display projects information about road signs, speed, speed limit, and turn-by-turn navigation, along with other driver alerts, directly within the driver’s line of sight, thereby reducing the chances of driver distraction. Head-up displays are often TFT-LCD displays backlit by a white LED.
Regional Insights
Asia Pacific dominated the global automotive smart display market with the largest revenue share of over 52.0% in 2025. The rising growth of the automotive industry and increasing demand for vehicles with smart displays enabled with the latest technologies are driving the market growth in the region. Strategies pursued by key global automakers toward the electrification of mobility are opening new opportunities for the growth of the market in China. For instance, in February 2025, ECARX stated that its first intelligent cockpit, developed under its joint strategic cooperation with FAW Group, will debut in the Hongqi Tiangong 05 EV. This intelligent cockpit relies on ECARX’s computing platform Antora 1000 Pro and integrates the company’s AutoGPT in-car AI model for intelligent display and human-computer interaction experiences.
 To learn more about this report, Download Free Sample Report
Europe Automotive Smart Display Market Trends
The automotive smart display market in Europe is anticipated to grow at a significant CAGR over the forecast period. The region is a manufacturing hub for prominent automotive OEMs and premium vehicle manufacturers. Production activity in the region has been propelled by investments made by OEMs such as Daimler, Jaguar Land Rover, Volkswagen, BMW, Nissan, and Honda. A majority of premium vehicle manufacturers in the region have installed advanced automotive electronics systems, which is projected to drive the European market.
Key Automotive Smart Display Company Insights
Key players in the global automotive smart display industry offer a wide range of components, including digital instrument clusters, digital cockpit systems, center stack displays, rear-seat entertainment systems, and Head-Up Display (HUD) units for passenger cars and commercial vehicles. The companies are focusing on providing technologically driven and advanced products to enhance their product offerings in the market.
Companies are undertaking strategic initiatives such as regional expansions, acquisitions, mergers, partnerships, and collaborations to grow in the market. Moreover, these players are consolidating their market share through M&A activity.
Key Automotive Smart Display Companies:
The following key companies have been profiled for this study on the automotive smart display market.
-
Alps Alpine Co., Ltd.
-
Continental AG
-
Denso Corporation
-
Hyundai Mobis
-
Nippon Seiki Co., Ltd.
-
Panasonic Corporation
-
Pioneer Corporation
-
Robert Bosch GmbH
-
SAMSUNG (HARMAN International)
-
Visteon Corporation
Recent Developments
-
In April 2025, Visteon launched an AI smart cockpit solution based on large language models, multi-modal interaction, and displays together with ByteDance’s Volcano Engine at Auto Shanghai.
-
In January 2025, Qualcomm Technologies, Inc. and Alps Alpine Co., Ltd. announced the expansion of their technology collaboration to integrate the latest generation Snapdragon Cockpit platform of the former into Alps Alpine’s automotive products. This partnership aims to revolutionize automotive mobility with advanced GenAI for personalized in-cabin experiences.
-
In January 2025, Continental unveiled its "Emotional Cockpit" at CES 2025, which offers a 1.3-meter-wide E Ink Prism display spanning the vehicle dashboard. Developed in partnership with E Ink, the technology enables personalized and customizable vehicle display experiences
Automotive Smart Display Market Report Scope
Report Attribute
Details
Market size in 2025
USD 13.6 billion
Estimated market size in 2026
USD 15.0 billion
Projected market size by 2033
USD 35.4 billion
Growth rate
CAGR of 13.1% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Display size, display technology, application,
region
Regional Scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country Scope
U.S.; Canada; Mexico; UK.; Germany; Spain; China; Japan; India; Brazil
Key Companies Profiled
Alps Alpine Co., Ltd.; Continental AG; Denso Corporation; Hyundai Mobis; Nippon Seiki Co., Ltd.; Panasonic Corporation; Pioneer Corporation; Robert Bosch GmbH; SAMSUNG (HARMAN International); Visteon Corporation.
Customization scope
Free report customization (equivalent to up to 8 analysts’ working days) with purchase. Addition or alteration to country, regional & segment scope
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Automotive Smart Display Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global automotive smart display market report based on the display size, display technology, application, and region:
-
Display Size Outlook (Revenue, USD Billion, 2021 - 2033)
-
Less than 5''
-
5''-10''
-
Greater than 10''
-
-
Display Technology Outlook (Revenue, USD Billion, 2021 - 2033)
-
LCD
-
TFT-LCD
-
OLED
-
Others
-
-
Application Type Outlook (Revenue, USD Billion, 2021 - 2033)
-
Digital Instrument Cluster
-
Center Stack
-
Head-Up Display (HUD)
-
Rear Seat Entertainment
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
Spain
-
-
Asia Pacific
-
China
-
Japan
-
India
-
-
Latin America
-
Brazil
-
-
Middle East and Africa
-
Frequently Asked Questions About This Report
The global automotive smart display market size was valued at USD 13.6 billion in 2025 and is estimated at USD 15.0 billion for 2026.
The global automotive smart display market is expected to grow at a CAGR of 13.1% from 2026 to 2033, reaching USD 35.4 billion by 2033.
Some key players operating in the automotive smart display market include Continental AG, Denso Corporation, Hyundai Mobis, Robert Bosch GmbH, and Visteon Corporation.
Key factors that are driving the automotive smart display market growth include increasing demand for advanced functions, including navigation, multimedia system, driver assistance, and connected car features, growing demand for smarter and more complex vehicle displays, and growing demand for enhanced safety, comfort, and convenience, in automobiles.
Asia Pacific dominated the automotive smart display market with a share of more than 52.0% in 2025. This is attributable to increased production and sales of passenger vehicles in the region.
About the Author(s)
Automotive & Transportation Research Team
Technology · Automotive & TransportationThis report was authored by the automotive & transportation research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the automotive & transportation segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


