
- Home
- »
- Automotive & Transportation
- »
-
Automotive Test Equipment Market Size, Share Report, 2033GVR Report cover

Automotive Test Equipment Market (2026 - 2033) Size, Share & Trends Analysis Report By Product, By Vehicle (Passenger Vehicle, Light Commercial Vehicle), By Application Tools (Handheld Scan Tool, PC/Laptop-based Scan Tool), By Region, And Segment Forecasts
Market Size, 2025
$2.9BMarket Estimate, 2026
$3.0BMarket Forecast, 2033
$4.5BCAGR, 2026–2033
5.5%Automotive Test Equipment Market Summary
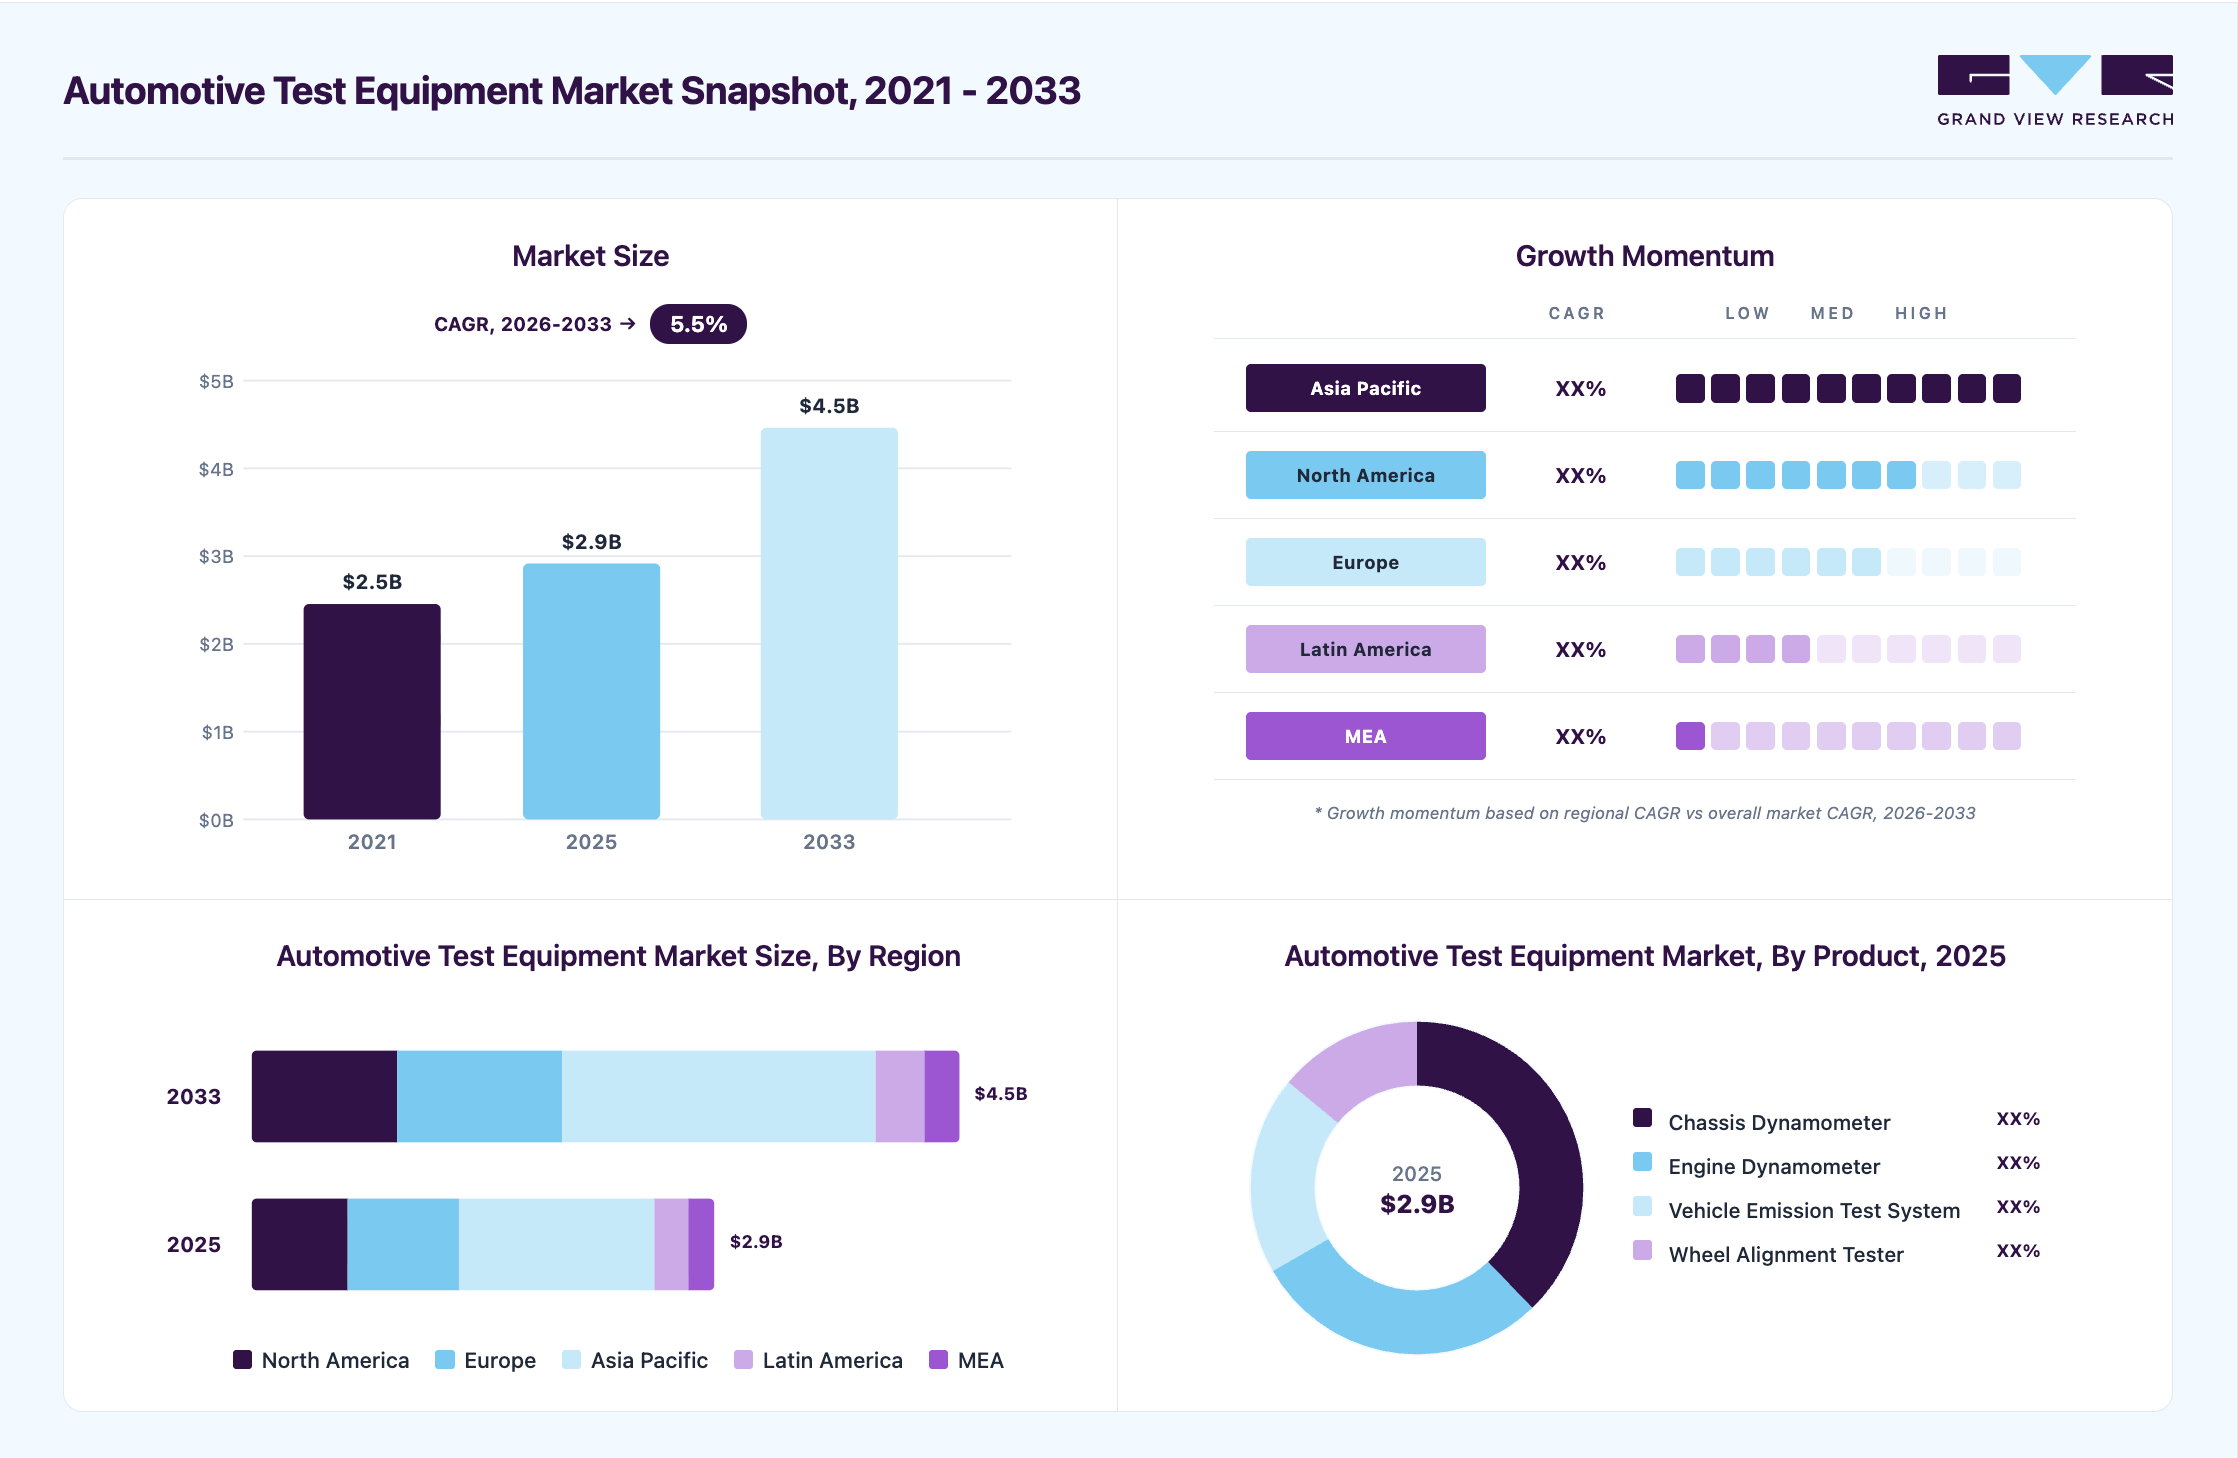
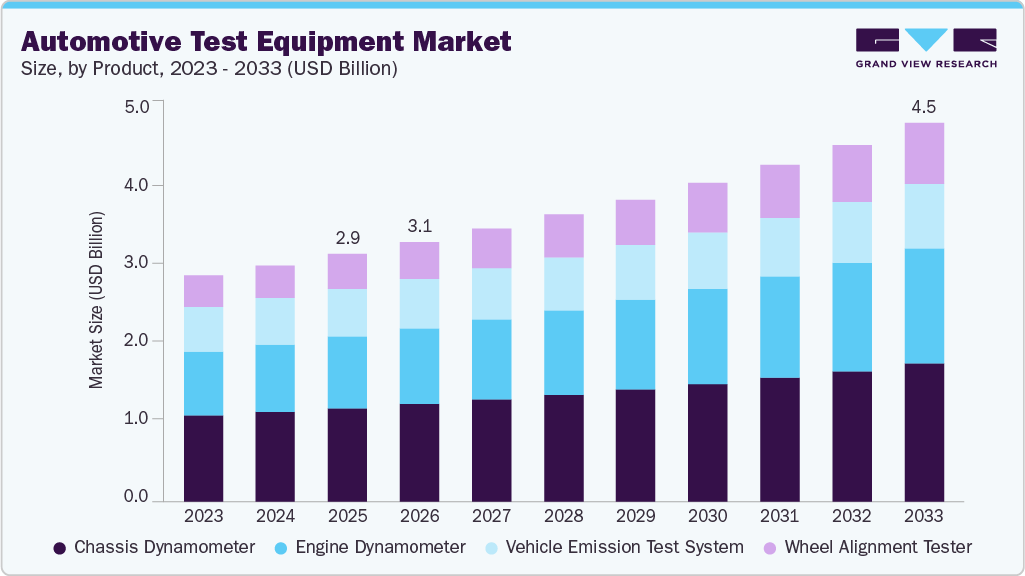
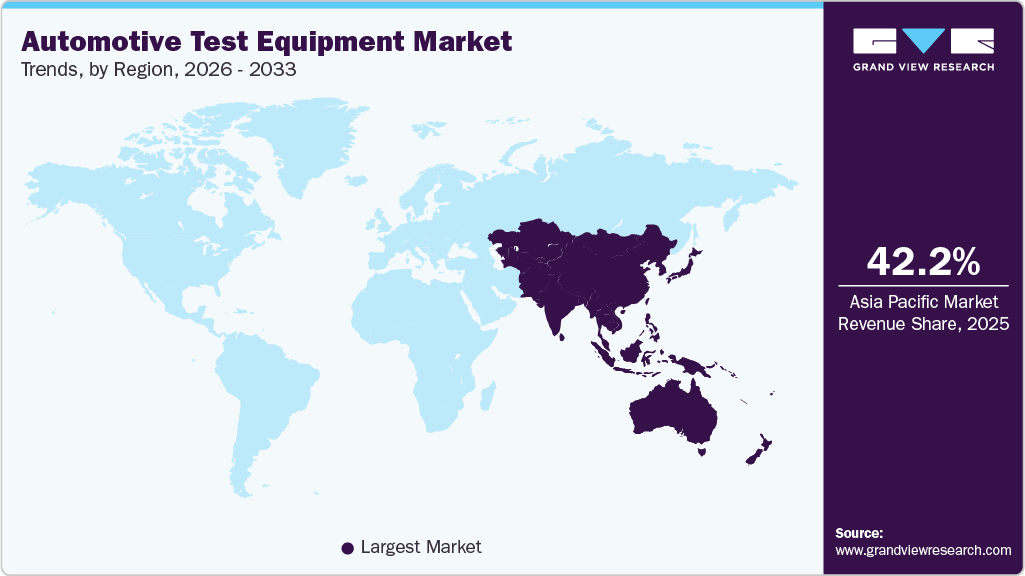
The global automotive test equipment market size was valued at USD 2.9 billion in 2025 and is projected to grow from USD 3.0 billion in 2026 to USD 4.5 billion by 2033, at a CAGR of 5.5% from 2026 to 2033. Asia Pacific automotive test equipment industry accounted for a 42.2% share of the overall market in 2025. Rising vehicle electrification, increasing software content, and tighter quality expectations across OEMs and suppliers are driving market growth.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Chassis dynamometer segment accounted for the largest share of 37.8% in 2025.
- By vehicle: Passenger vehicle segment held the largest market share of 61.0% in 2025.
- By application tools: Handheld scan tool segment dominated the market in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (42.2% revenue share, 2025)
- The automotive test equipment industry in the China held a dominant position in 2025.
Market Size & Forecast
- Market size in 2025: USD 2.9 Billion
- Estimated market size in 2026: USD 3.0 Billion
- Projected market size by 2033: USD 4.5 Billion
- CAGR (2026-2033): 5.5%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Higher model proliferation and shorter development cycles have necessitated broader validation coverage, resulting in increased volumes of functional, durability, and end-of-line testing across the powertrain, chassis, body electronics, and ADAS domains.The global automotive industry is witnessing a historic transformation as electric and hybrid vehicles rapidly gain traction across major markets. Governments worldwide are setting ambitious carbon neutrality targets and phasing out internal combustion engine (ICE) vehicles, prompting automakers to accelerate electrification strategies. For instance, the European Union plans to ban new petrol and diesel car sales by 2035, while countries like China and the U.S. are offering subsidies and tax credits for EV purchases.
 To learn more about this report, Download Free Sample Report
This large-scale transition is not only reshaping vehicle architectures but also revolutionizing the entire supply chain from powertrain components to testing and validation systems. Unlike traditional vehicles, electric and hybrid vehicles require precise testing of high-voltage systems, energy efficiency, and battery management. As a result, automakers and suppliers are investing heavily in new categories of automotive test equipment designed to ensure safety, performance, and regulatory compliance. The shift toward electrification thus serves as a fundamental growth catalyst for the automotive test equipment ecosystem.
The regulatory environment is intensifying the need for advanced test equipment. Global safety and environmental standards for EVs and hybrids are evolving rapidly to address new risks such as battery fire hazards, high-voltage shock protection, and electromagnetic interference. Agencies like the United Nations Economic Commission for Europe (UNECE) and National Highway Traffic Safety Administration (NHTSA) have introduced specific testing protocols for EV safety, battery integrity, and emissions compliance from hybrid drivetrains (UNECE Regulation No. 100). Compliance with such stringent regulations compels OEMs and component suppliers to establish dedicated testing facilities equipped with specialized instruments for durability, vibration, crash, and electrical safety validation. As these standards become globally harmonized, even suppliers operating in smaller markets must upgrade their testing infrastructure. This ongoing regulatory alignment continues to drive growth in demand for automotive test equipment designed for electrified vehicle platforms.
The automotive industry is undergoing a major transformation with the rapid rise of autonomous driving technologies. Automakers and technology companies are investing heavily in developing vehicles capable of operating with minimal or no human input. Levels of autonomy have progressed from basic driver-assist features such as adaptive cruise control and lane-keeping (Level 1-2) to more advanced Level 3 and Level 4 systems capable of handling complex urban environments. For instance, Mercedes-Benz received approval in Germany and the U.S. for its Level 3 “Drive Pilot” system, marking a significant regulatory milestone. Similarly, Waymo and Cruise are advancing pilot operations for driverless robotaxis in cities like San Francisco and Phoenix. These technological advancements are fueling demand for sophisticated testing tools capable of validating AI algorithms, radar and LiDAR sensor accuracy, and vehicle-to-everything (V2X) communication systems creating a surge in demand for automotive test equipment.
The increasing technological sophistication of modern vehicles, particularly with the rise of electric, hybrid, and autonomous platforms, has significantly escalated the cost of testing and validation infrastructure. Automotive testing now requires advanced equipment such as dynamometers, HIL (Hardware-in-the-Loop) simulators, ADAS validation rigs, and environmental chambers capable of replicating diverse real-world conditions. These systems often integrate sensors, artificial intelligence, and cloud analytics, driving up both capital and operational expenses. For instance, validating autonomous driving functions demands high-resolution LiDAR calibration systems and complex simulation setups that can cost millions of dollars to deploy and maintain. Smaller automakers and Tier-2 suppliers often struggle to justify these investments, limiting the widespread adoption of high-end test platforms and creating disparities in technological readiness across the supply chain.
Market Dynamics
The increasing integration of connected vehicles and advanced in-vehicle electronics, driven by the emergence of software-defined vehicles (SDVs), is significantly propelling the growth of the automotive test equipment market. Modern vehicles are rapidly evolving into highly connected digital platforms, incorporating technologies such as infotainment systems, telematics, vehicle-to-everything (V2X) communication, and over-the-air (OTA) software updates. This growing electronic and software content has substantially increased system complexity, requiring extensive validation of electronic control units (ECUs), embedded software, and communication networks to ensure seamless performance and interoperability.
In addition, the shift toward SDVs is transforming vehicles into continuously upgradable platforms where software plays a central role in defining vehicle functionality and user experience. This necessitates continuous testing and validation across the vehicle lifecycle, including performance testing, functional safety validation, and cybersecurity assessment. Automotive OEMs and suppliers are increasingly investing in advanced test equipment such as simulation tools, Hardware-in-the-Loop (HIL) systems, and automated validation platforms to replicate real-world driving conditions and ensure system reliability.
The high cost and complexity of advanced automotive testing infrastructure are restraining the growth of the automotive test equipment market. Modern testing systems such as Hardware-in-the-Loop (HIL) platforms, ADAS validation rigs, environmental simulation chambers, and autonomous driving test systems require significant capital investment and ongoing operational expenses. These systems also demand skilled personnel, advanced calibration capabilities, and continuous upgrades, increasing the total cost of ownership for manufacturers and suppliers.
The increasing adoption of autonomous driving and connected vehicle technologies presents a significant growth opportunity for the automotive test equipment market. The development of advanced driver assistance systems (ADAS), vehicle-to-everything (V2X) communication, and autonomous driving capabilities requires rigorous testing of sensors, software algorithms, and real-time data processing systems. Technologies such as LiDAR, radar, and camera-based perception systems must be extensively validated under diverse real-world conditions, driving demand for advanced simulation and testing platforms.
Furthermore, the rise of connected vehicles and intelligent mobility ecosystems is accelerating the need for cybersecurity testing, software validation, and communication protocol testing. Features such as infotainment systems, telematics, and over-the-air updates require continuous testing throughout the vehicle lifecycle.
Market Concentration & Characteristics
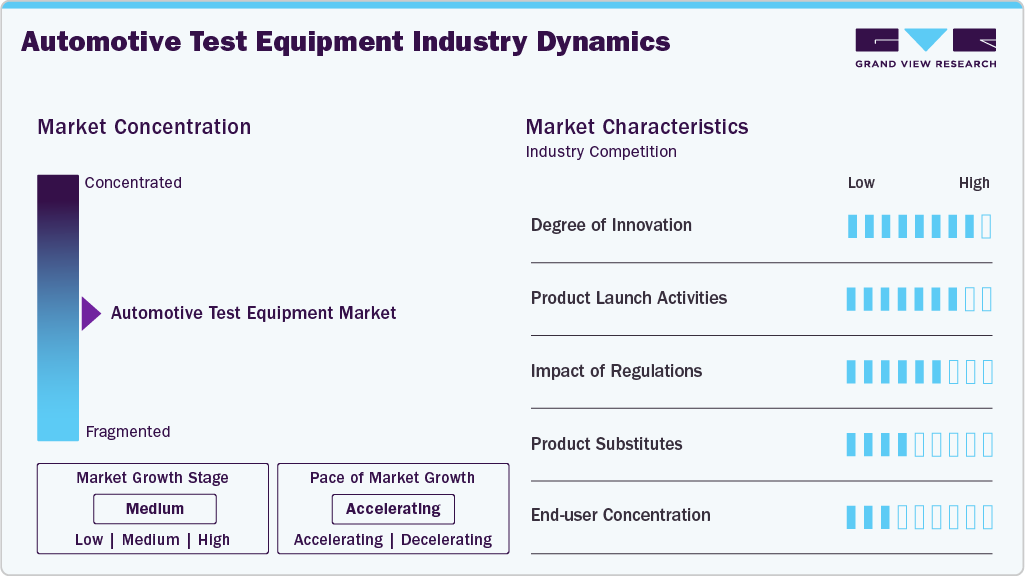
The automotive test equipment market is moderately consolidated, with a strong presence of a few global leaders alongside a broad base of specialized and regional players. Market leadership is dominated by established companies such as Robert Bosch GmbH, Horiba, Siemens, and others, which collectively hold a significant share of the market. These players maintain strong positions through advanced R&D capabilities, comprehensive product portfolios spanning powertrain, electronics, ADAS, and emissions testing, and long-standing relationships with global OEMs and Tier-1 suppliers.
 To learn more about this report, Download Free Sample Report
Consolidation is gradually increasing as large players expand their capabilities through mergers, acquisitions, and strategic partnerships, particularly in areas such as electric vehicle (EV) testing, autonomous driving validation, and software-defined vehicle (SDV) testing. The growing complexity of vehicle architectures, coupled with rising demand for integrated testing ecosystems, is pushing the market toward greater integration of hardware, software, and simulation-based testing solutions.
Product Insights
The chassis dynamometer segment accounted for the largest share of 37.8% in 2025. The growing emphasis on real-world vehicle performance, durability, and NVH (noise, vibration, harshness) is driving the adoption of chassis dynamometers. Rather than simply certifying vehicles under standard conditions, automakers and suppliers now demand test rigs that can replicate varied, repeatable on-road loads (such as towing, hills, extended high-speed runs) in a controlled lab environment. This capability reduces development time, enables precise tuning of powertrain, suspension, and NVH characteristics, and helps ensure that the finished vehicle behaves as expected in real-life conditions.
The wheel alignment tester segment is expected to grow at the fastest CAGR during the forecast period. The steady rise in global vehicle production and the rapid expansion of the automotive aftermarket service industry is fueling growth of the growth of wheel alignment testers in the automotive test equipment industry. With the increasing number of vehicles on the road, the need for regular maintenance, tire replacement, and wheel alignment services has grown substantially. Proper alignment is crucial for ensuring vehicle safety, driving stability, maximizing tire lifespan, and enhancing fuel efficiency.
Vehicle Insights
The passenger vehicle segment held the largest market share of 61.0% in 2025. The growing focus on vehicle safety, performance, and environmental compliance, coupled with evolving regulatory standards and rising consumer expectations, is driving the demand for automotive test equipment in passenger vehicles. Global vehicle production continues to expand, particularly in emerging markets, placing automakers under increasing pressure to design safer, more efficient, and lower-emission cars. Stringent norms such as Euro 7, CAFÉ standards, and BS VI have intensified the need for advanced testing technologies to ensure compliance and optimize vehicle performance. Automotive test systems play a crucial role in evaluating powertrain efficiency, emissions, and component durability under various operating conditions, enabling manufacturers to meet international quality standards.
The light commercial vehicle segment is expected to grow at a significant CAGR during the forecast period. The increasing demand for vehicle reliability, durability, and efficiency in logistics, delivery, and small-scale transport applications is driving the growth of automotive test equipment for light commercial vehicles (LCVs). The surge in e-commerce and last-mile delivery services has led to a significant rise in the production and utilization of LCVs worldwide. Fleet operators and manufacturers are focusing on minimizing downtime, improving operational efficiency, and ensuring compliance with emission and safety standards. This has accelerated the adoption of advanced testing systems to evaluate critical performance parameters such as engine health, braking efficiency, load endurance, and emission control.
Application Tools Insights
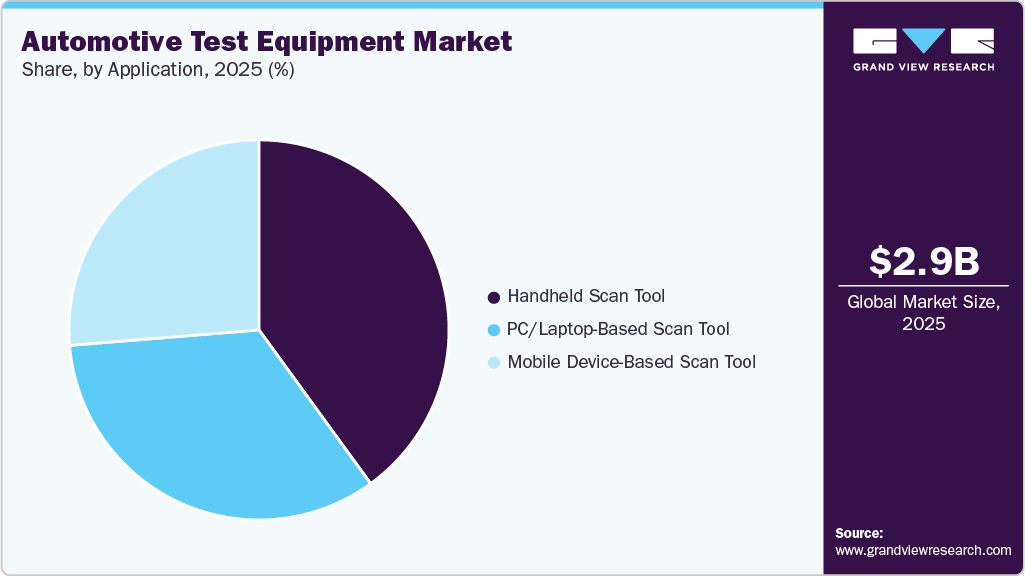
The handheld scan tool segment dominated the market in 2025. The rising demand for efficient and cost-effective maintenance solutions is driving the growth of the segment. Automotive workshops and fleet operators are under pressure to reduce vehicle downtime and service costs while maintaining high diagnostic accuracy. Handheld scan tools provide quick, on-site diagnostics without the need for large, stationary systems, allowing faster turnaround and improved service productivity. Their ease of use and affordability make them especially popular among small and mid-sized repair facilities.
 To learn more about this report, Download Free Sample Report
The mobile device-based scan tool segment is projected to grow at the fastest CAGR of 6.8% over the forecast period. The expansion of the global automotive aftermarket and the increasing number of vehicles in operation are major factors driving the demand for portable and scalable diagnostic solutions. As vehicles age and require more frequent maintenance, the need for quick, reliable, and flexible diagnostic tools has become essential for both service providers and vehicle owners. Mobile device-based scan tools address this need by enabling real-time data access, cloud-based service history tracking, and compatibility across a wide range of vehicle models and systems.
Regional Insights
The North America automotive test equipment industry held a significant share in 2025. The demand in the region is driven by rapid electrification, as OEMs and suppliers accelerated investments in high-voltage battery, e-motor, and charging system validation. A major growth in drivers was the rising demand for ADAS and autonomous vehicle testing, prompting the expansion of sensor calibration, software-in-the-loop, and scenario simulation systems.
U.S. Automotive Test Equipment Market Trends
The U.S. automotive test equipment industry held a dominant position in 2025 due to the surge in electric vehicle production, leading to heightened demand for advanced battery cyclers, power analyzers, and high-voltage safety testing systems. The country witnessed significant modernization of proving grounds, where 5G connectivity and edge computing were introduced to enhance real-time testing and data transfer.
Europe Automotive Test Equipment Industry Trends
The Europe automotive test equipment industry was identified as a lucrative region in 2025. The European market is experiencing a strong transition toward AI-driven and digitalized testing solutions as manufacturers seek to reduce costs and shorten development cycles under strict EU regulations. Increasing focus on electrification, sustainability, and autonomous vehicle technologies is driving the need for intelligent test systems capable of managing complex validation tasks.
The UK automotive test equipment industry is expected to grow rapidly in the coming years due to growing focus on advanced vehicle diagnostics. Workshops and service centers are increasingly adopting multi-system diagnostic tools capable of handling diverse vehicle make and models to meet complex servicing needs.
The German automotive test equipment industry held a substantial market share in 2025. The growth in the country is attributed to the rising complexity of electric and hybrid powertrains, which require more integrated and precise validation systems. The country continues to strengthen its position as a global hub for advanced testing and certification, with a strong focus on multi-domain testing that combines mechanical, electrical, and environmental parameters.
Asia Pacific Automotive Test Equipment Industry Trends
The Asia Pacific automotive test equipment industry is anticipated to grow at a CAGR of 6.2% during the forecast period. The rapid advancement driven by the growing adoption of high-speed in-vehicle communication systems and digital testing technologies is fueling growth of the market in the region. The region’s automakers and component suppliers are increasingly investing in optical and Ethernet-based automotive testing solutions to support next-generation connected and software-defined vehicles.
 To learn more about this report, Download Free Sample Report
The India automotive test equipment industry is expected to grow rapidly in the coming years, fueled by increasing investments in advanced testing infrastructure and vehicle validation facilities. The focus on enhancing safety, performance, and reliability standards is encouraging the development of modern test tracks and laboratories across the country.
The China automotive test equipment industry held a substantial market share in 2025. The market growth is primarily driven by the growing localization of R&D and testing capabilities. The increasing collaboration between international technology suppliers and domestic testing institutions is accelerating the development of advanced validation facilities.
Key Automotive Test Equipment Company Insights
Some of the key companies in the automotive test equipment industry include Robert Bosch GmbH, Siemens, Delphi Technologies (PHINIA Inc.), Continental AG, and others. Organizations are focusing on increasing customer base to gain a competitive edge in the industry. Therefore, key players are taking several strategic initiatives, such as mergers and acquisitions, and partnerships with other major companies.
-
Robert Bosch GmbH (Bosch) is a technology and services provider, offering innovative solutions that enhance automation, electrification, digitalization, and sustainability across industries. The company operates through key business sectors, including Mobility, Industrial Technology, Consumer Goods, and Energy and Building Technology. Its product portfolio encompasses sensor technology, software, and cross-domain connectivity solutions that integrate artificial intelligence for smarter, more efficient applications. The company specializes in advanced diagnostic tools, sensors, and software that enable precise testing and maintenance of vehicle systems.
-
Siemens AG is a technology company that delivers solutions across electrification, automation, and digitalization to drive industrial and societal advancement. The company operates through five primary segments: Digital Industries, Smart Infrastructure, Mobility, Siemens Healthineers, and Siemens Financial Services. Its diverse portfolio includes intelligent infrastructure systems, digital manufacturing technologies, smart mobility solutions, and medical and energy systems tailored to meet the complex needs of customers. The company focuses on providing digital simulation, automation, and testing solutions that enable efficient design validation and production optimization for vehicle systems.
Key Automotive Test Equipment Companies:
The following are the leading companies in the automotive test equipment market. These companies collectively hold the largest market share and dictate industry trends.
- Robert Bosch GmbH
- Siemens
- Delphi Technologies (PHINIA Inc.)
- Continental AG
- Honeywell International Inc
- ABB
- Softing AG
- HORIBA
- SGS Société Générale de Surveillance SA
- Anthony Best Dynamics Limited.
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Mature Players: Robert Bosch GmbH; Siemens; Continental AG; Honeywell International Inc.; ABB
- Mature players focus on delivering integrated automotive test and validation ecosystems covering powertrain testing, emissions validation, electronics testing, and ADAS validation.
- Strategies emphasize end-to-end solutions combining hardware test systems, simulation platforms, automation, and industrial digitalization capabilities.
- Strong global presence with diversified industrial and automotive client base.
- Advanced capabilities in automation, electrification testing, simulation, and digital twin technologies.
- High cost of advanced testing systems may limit adoption among smaller OEMs and suppliers.
- Complex product portfolios and industrial-scale operations can slow customization cycles.
Emerging Players: HORIBA; Anthony Best Dynamics Limited; SGS Société Générale de Surveillance SA; Softing AG; Delphi Technologies
- Emerging players focus on niche automotive testing domains such as emissions testing, vehicle dynamics, durability testing, diagnostics, and certification services.
- Strategies emphasize high-precision instrumentation, compliance-driven testing services, and software-based diagnostics solutions.
- Deep technical expertise in specialized testing domains such as emissions, vehicle dynamics, and diagnostics.
- Strong reputation in regulatory compliance testing and certification services.
- Limited ability to offer fully integrated end-to-end testing ecosystems compared to large industrial conglomerates.
- Narrower product portfolios focused on specific testing domains.
Recent Developments
-
In September 2025, Siemens Digital Industries Software launched Tessent AnalogTest, a solution designed to automate analog circuit test generation and dramatically reduce development time. The software enables testing of analog components up to 100 times faster than conventional methods while maintaining high defect detection accuracy. By integrating automated design-for-test features and digital test patterns, it allows engineers to achieve over 90% defect coverage and significantly accelerate chip validation processes.
-
In December 2024, HORIBA partnered with Monolith AI to advance battery and powertrain testing using artificial intelligence. The collaboration allows Monolith AI to utilize HORIBA MIRA’s research data to improve its Anomaly Detector and Next Test Recommender tools, while integrating these capabilities into MIRA’s cloud-based development platform. This partnership aims to accelerate testing processes, reduce physical prototypes, and optimize system-level development for automotive manufacturers and suppliers.
Automotive Test Equipment Market Report Scope
Report Attribute
Details
Market size in 2025
USD 2.9 billion
Estimated market size in 2026
USD 3.0 billion
Projected market size by 2033
USD 4.5 billion
Growth rate
CAGR of 5.5% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report vehicle
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, vehicle, application tools, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; China; Japan; India; South Korea; Australia; Brazil; KSA; UAE; South Africa
Key companies profiled
Robert Bosch GmbH; Siemens; Delphi Technologies (PHINIA Inc.); Continental AG; Honeywell International Inc; ABB; Softing AG; HORIBA; SGS Société Générale de Surveillance SA; Anthony Best Dynamics Limited
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Automotive Test Equipment Market Report Segmentation
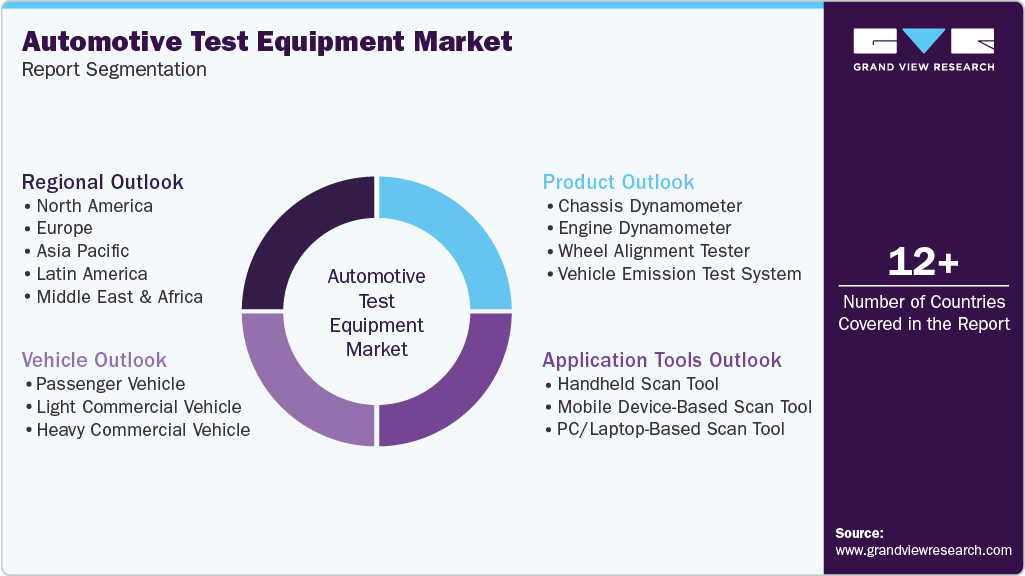
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global automotive test equipment market report based on product, vehicle, application tools, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Chassis Dynamometer
-
Engine Dynamometer
-
Wheel Alignment Tester
-
Vehicle Emission Test System
-
-
Vehicle Outlook (Revenue, USD Million, 2021 - 2033)
-
Passenger Vehicle
-
Light Commercial Vehicle
-
Heavy Commercial Vehicle
-
-
Application Tools Outlook (Revenue, USD Million, 2021 - 2033)
-
Handheld Scan Tool
-
Mobile Device-Based Scan Tool
-
PC/Laptop-Based Scan Tool
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
-
Middle East and Africa (MEA)
-
KSA
-
UAE
-
South Africa
-
-
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Automotive Test Equipment Market Opportunity Assessment
- Product-wise market sizing and forecast analysis across chassis dynamometer, engine dynamometer, wheel alignment testers, and vehicle emission test systems
- • Vehicle-type-wise assessment covering passenger vehicles, light commercial vehicles (LCVs), and heavy commercial vehicles (HCVs)
- • Regional demand analysis aligned with EV adoption, emission norms, and testing infrastructure maturity
- Identified product-level growth hotspots within automotive test equipment
- Supported investment prioritization across EV and emissions testing segments
Automotive Diagnostics & Application Tools Usage Study
- Evaluation of workshop-level vs OEM-level diagnostic usage patterns
- Assessment of digitization trends in automotive diagnostics and remote vehicle monitoring
- Analysis of software integration and cloud-based diagnostic evolution
- Supported product innovation and digital diagnostics strategy
- Enabled targeting of workshop digitization opportunities
Automotive Test Equipment Regulatory & Compliance Impact Study
- Analysis of global emission standards, safety regulations, and EV testing mandates
- Evaluation of compliance-driven demand for vehicle emission test systems and dynamometers
- Supported compliance-driven product development strategies
- Identified regulation-led demand growth opportunities
Frequently Asked Questions About This Report
The global automotive test equipment market size was estimated at USD 2.9 billion in 2025 and is expected to reach USD 3.0 billion in 2026.
Asia Pacific dominated the automotive test equipment market with a share of 42.2% in 2025. The rapid advancement driven by the growing adoption of high-speed in-vehicle communication systems and digital testing technologies is fueling growth of the market in the region.
Some key players operating in the automotive test equipment market include Robert Bosch GmbH; Siemens; Delphi Technologies (PHINIA Inc.); Continental AG; Honeywell International Inc; ABB; Softing AG; HORIBA; SGS Société Générale de Surveillance SA; Anthony Best Dynamics Limited.
Rising vehicle electrification, increasing software content, and tighter quality expectations across OEMs and suppliers are driving the growth of the market.
Chassis dynamometer segment accounted for the largest share of 37.8% in 2025, while wheel alignment tester is the fastest-growing segment.
Passenger vehicle segment held the largest market share of 61.0% in 2025, while light commercial vehicle is the fastest-growing segment.
Handheld scan tool segment dominated the market in 2025, while mobile device-based scan tool segment is the fastest-growing segment
The global automotive test equipment market is expected to grow at a compound annual growth rate of 5.5% from 2026 to 2033 to reach USD 4.5 billion by 2033.
About the Author(s)
Automotive & Transportation Research Team
Technology · Automotive & TransportationThis report was authored by the automotive & transportation research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the automotive & transportation segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


