
- Home
- »
- Plastics, Polymers & Resins
- »
-
Automotive Tinting Film Market Size Report, 2026-2033GVR Report cover

Automotive Tinting Film Market (2026 - 2033)
Size, Share & Trends Analysis Report By Application (Windows, Windshields), By Vehicle Type (Passenger Cars, LCVs, HCVs), By Region (North America, Europe, Asia Pacific, Latin America, MEA), And Segment Forecasts
Market Size, 2025
$8.1BMarket Estimate, 2026
$8.7BMarket Forecast, 2033
$14.7BCAGR, 2026–2033
7.8%Automotive Tinting Film Market Summary
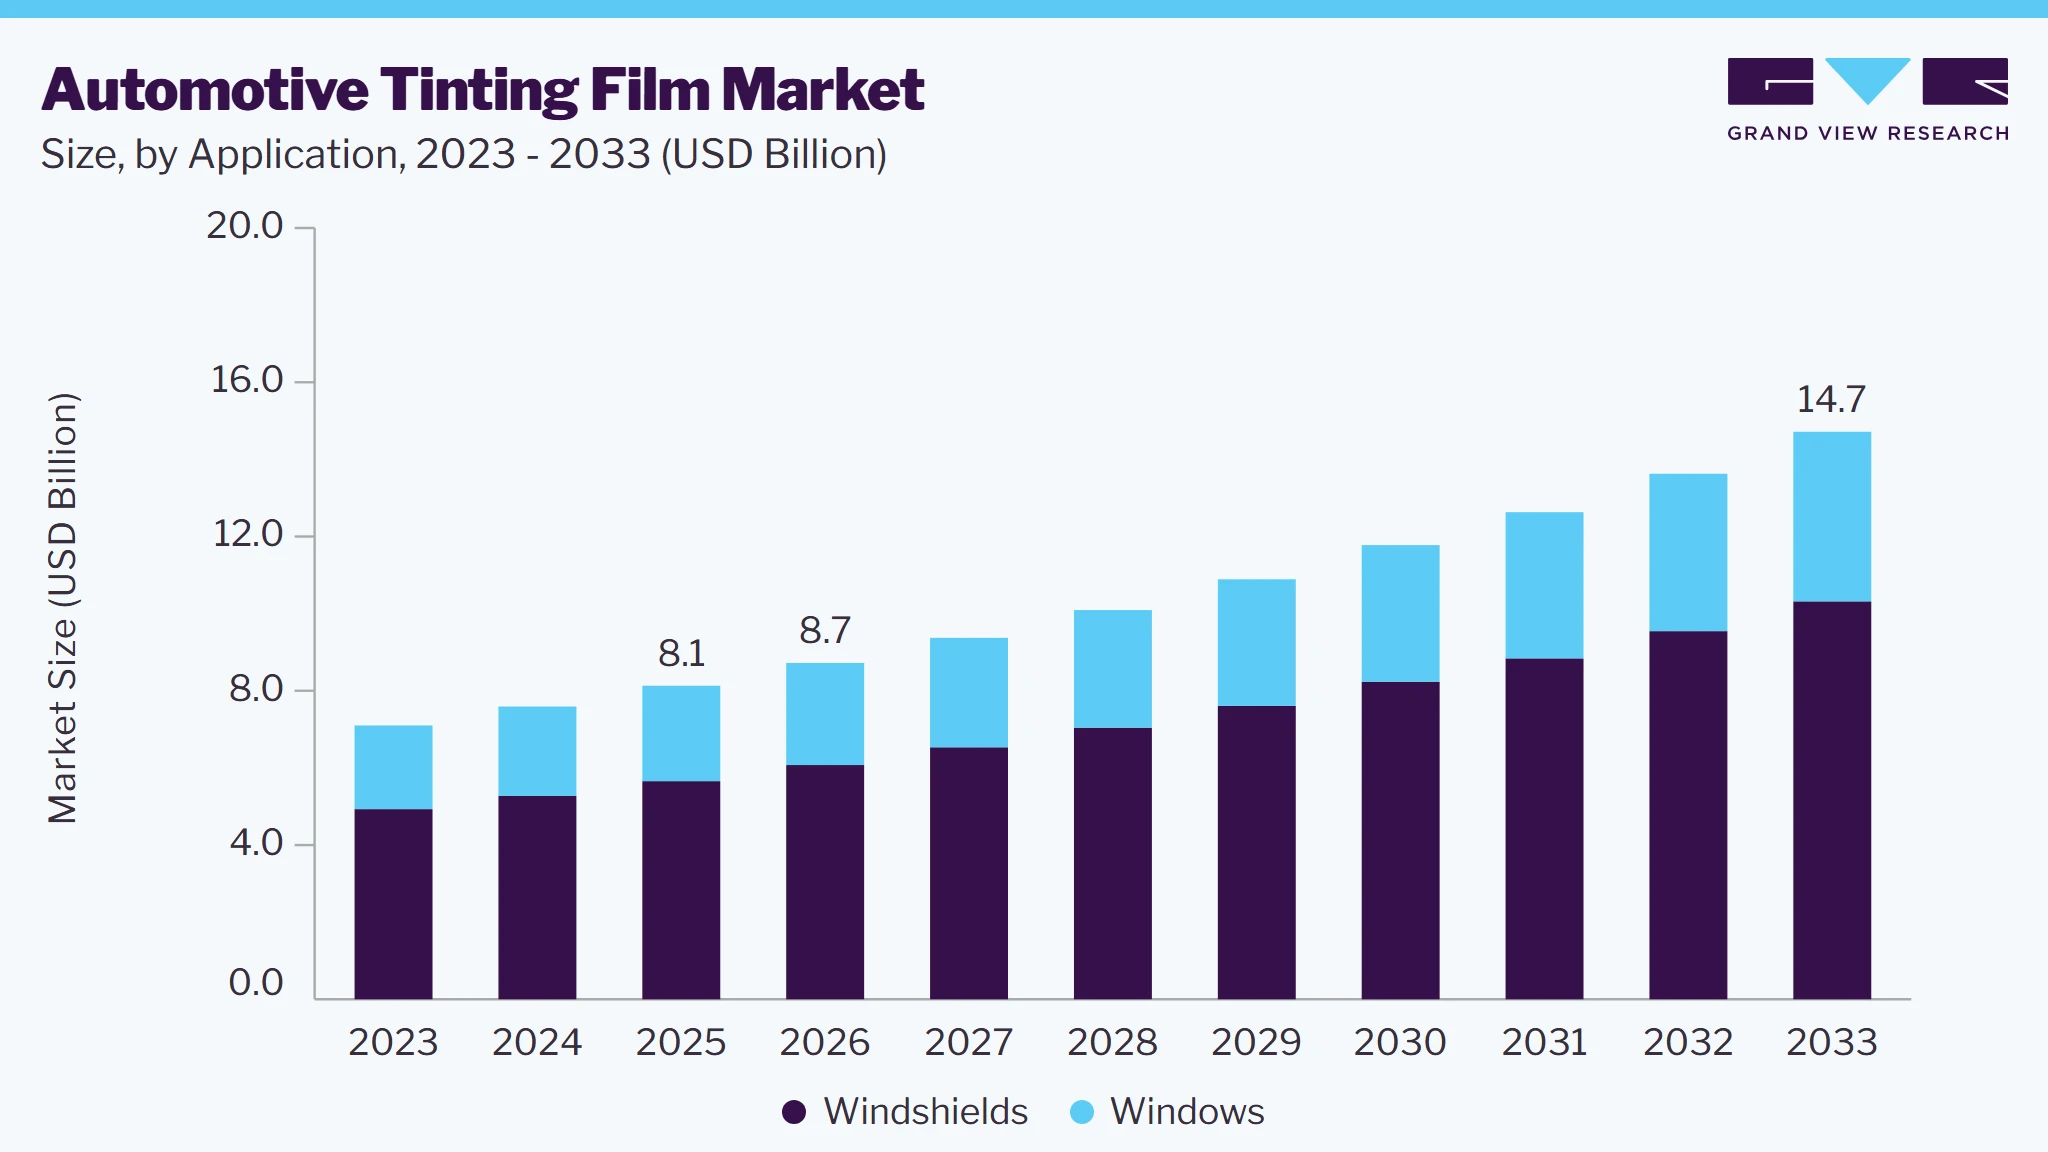
The global automotive tinting film market size was valued at USD 8.1 billion in 2025 and is projected to grow from USD 8.7 billion in 2026 to USD 14.7 billion by 2033, at a CAGR of 7.8% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 33.4% in 2025. Automotive tinting films are commonly used across applications, including passenger vehicles, luxury automobiles, electric vehicles, commercial fleets & car rental services such as taxi companies, rideshare drivers, and rental agencies, as well as logistics and public transit vehicles.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By application: Windshields segment led the market with the largest revenue share of 69.6% in 2025.
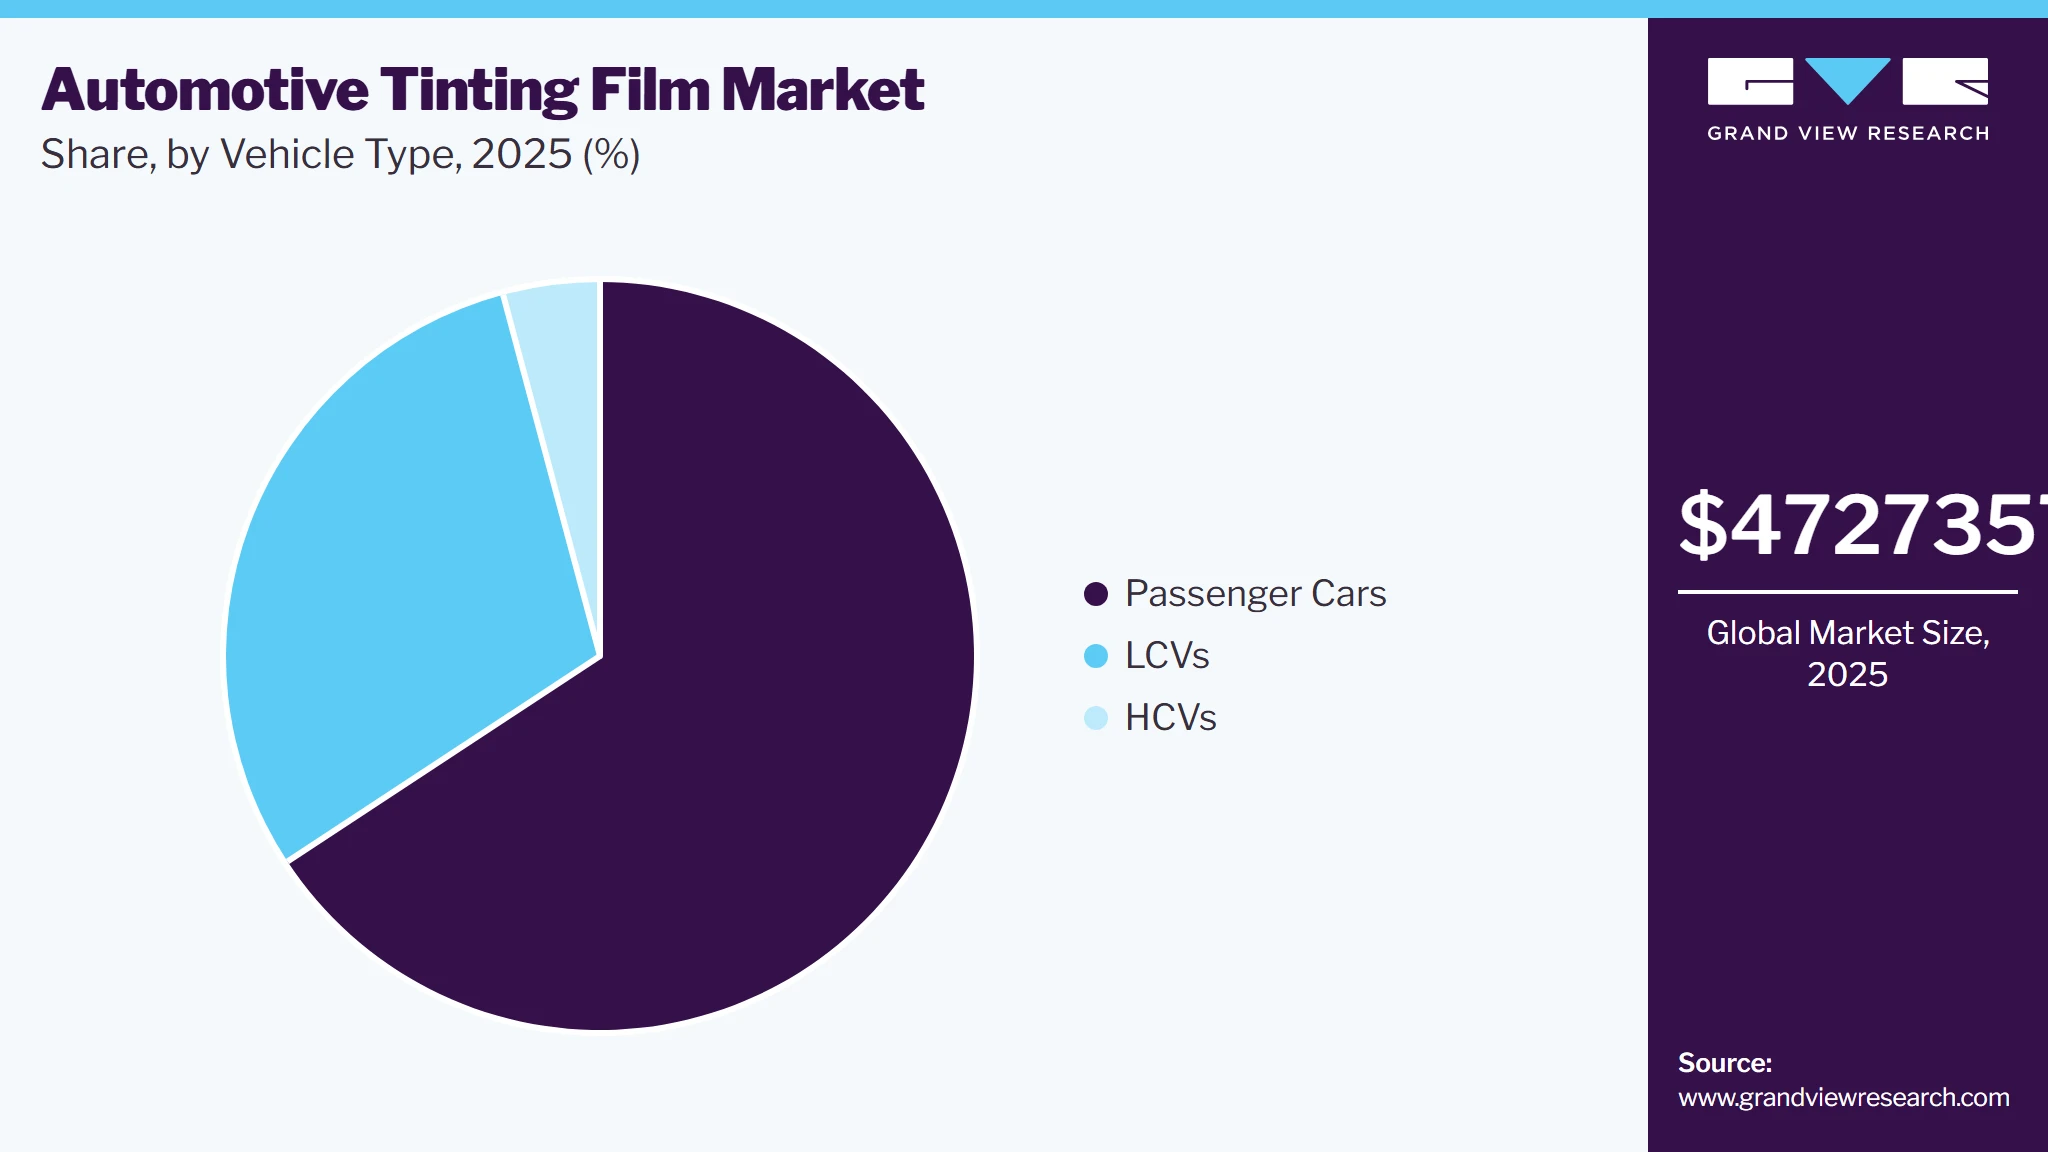
- By vehicle type: Passenger cars segment led the market with the largest revenue share of 65.7% in 2025.
Regional Highlights
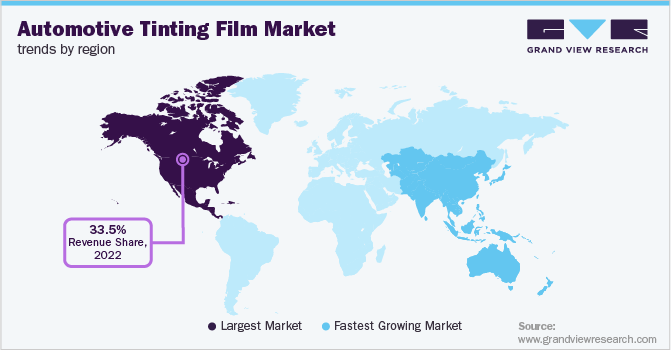
- Largest regional market: North America (33.4% revenue share, 2025)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 8.1 Billion
- Estimated market size in 2026: USD 8.7 Billion
- Projected market size by 2033: USD 14.7 Billion
- CAGR (2026-2033): 7.8%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
These films are installed to improve solar heat rejection, UV protection, glare reduction, privacy, passenger comfort, and energy efficiency while supporting vehicle aesthetics and regulatory compliance across diverse transportation segments. Consumers' desire to protect expensive luxury car interiors and personal safety from harmful sun rays is expected to drive the market over the forecast period. The demand for passenger cars in developing countries has increased due to rising disposable income, a growing working population, and rapid urbanization.Automotive tinting film is a thin layer applied to vehicle windows to enhance comfort, privacy, and safety by reducing glare, blocking harmful UV rays, and controlling heat inside the car. The market for these films is growing rapidly due to rising consumer interest in improving vehicle appearance and protecting interiors from sun damage. In hotter climates, the demand is especially strong as tinting films help maintain cooler cabin temperatures and reduce glare.
 To learn more about this report, Download Free Sample Report
The growing automotive industry, due to the growing demand globally as well as the increasing rate of adoption of automotive vehicles, is driving the demand for automotive tinting films. As per an article published by ACEA, in 2023, global car production accounted for nearly 76 million units, reflecting a 10.2% increase from the previous year. This increase can be attributed to rising disposable incomes, a growing working population, and rapid urbanization. As more people move to urban areas and earn higher wages, they are more likely to purchase vehicles, further boosting the market for automotive tinting films.
One key factor fueling this demand is consumers' desire to protect the interiors of their expensive luxury cars. Tinting films offer protection against harmful sun rays, which can damage upholstery and other interior components over time. Additionally, these films enhance personal safety by reducing glare and blocking UV rays, making driving more comfortable and safer.
In addition, advances in materials like ceramic and nano-ceramic films offer better heat rejection and UV protection without compromising visibility or interfering with electronic signals, making them highly popular. Safety concerns drive growth, as these films can hold shattered glass together during accidents, enhancing passenger protection. Additionally, evolving regulations encourage film innovation that balances light transmission with effective sun blocking.
Market Dynamics
Automotive tinting films are gaining strong momentum as consumers increasingly prioritize vehicle comfort, interior preservation, privacy, and protection from harmful UV radiation. Rising disposable incomes, expanding urban populations, and growing passenger vehicle ownership in developing economies are supporting market growth. Demand is particularly strong for premium and luxury vehicles, where owners seek to safeguard interior materials from sun-induced fading and heat damage. In regions with high temperatures and intense sunlight exposure, tinting films are widely adopted to reduce cabin heat buildup, minimize glare, improve driving comfort, and enhance overall vehicle aesthetics, reinforcing their importance across the automotive sector.
The automotive tinting film market is experiencing sustained growth as vehicle owners increasingly prioritize heat reduction, UV protection, privacy, and enhanced driving comfort. Rising global temperatures and greater awareness of the harmful effects of ultraviolet radiation are accelerating the adoption of advanced tinting solutions capable of blocking infrared and UV rays. Increasing urbanization and consumer preference for improved privacy and security are also supporting demand across passenger vehicle segments. At the same time, growth in global vehicle production continues to expand the addressable customer base for both original equipment manufacturers (OEMs) and aftermarket tinting installations, strengthening long-term market potential.
Automotive remains the primary end-use sector for tinting films, supported by growing demand for vehicle customization, aesthetics, and interior protection. Tinting films offer a cost-effective way to enhance the appearance of both economy and premium vehicles while helping preserve interior materials from sun-related damage. The rapid expansion of electric vehicle production is creating additional growth opportunities, as EVs increasingly incorporate large glass surfaces and panoramic roofs that elevate cabin heat exposure. As manufacturers focus on energy efficiency and passenger comfort, specialized tinting films are being adopted to reduce cooling loads, extend driving range, and improve overall vehicle performance.
Strict Government Regulations remain a significant restraint for the automotive tinting film market. Regulatory authorities across different countries and regions enforce strict Visible Light Transmission (VLT) requirements that determine the amount of light permitted through vehicle windows. Compliance with these regulations requires manufacturers, installers, and vehicle owners to carefully select tinting films that meet legal transparency standards. The use of excessively dark or non-compliant aftermarket films can result in fines, vehicle inspection failures, and mandatory film removal. These regulatory complexities can limit product adoption and customization options, particularly in markets with stringent enforcement, creating challenges for market expansion despite the benefits of heat rejection, UV protection, privacy enhancement, and driving comfort offered by automotive tinting films.
The increasing emphasis on vehicle thermal comfort and energy efficiency presents an opportunity for automotive tinting film manufacturers. Advanced films incorporating infrared (IR) and ultraviolet (UV) blocking technologies can reduce solar heat entering vehicle cabins, helping lower the cooling load on air-conditioning systems and improve passenger comfort. Demand for premium vehicles equipped with advanced glazing and cabin comfort features is also encouraging the adoption of high-performance tinting solutions. In addition, the development of ceramic and multilayer films with improved heat rejection, optical clarity, and durability is creating opportunities for product differentiation. Manufacturers can further capitalize on this trend by developing films that provide enhanced solar control while complying with varying regional regulations on visible light transmission, thereby expanding adoption across passenger and commercial vehicles.
Market Concentration & Characteristics
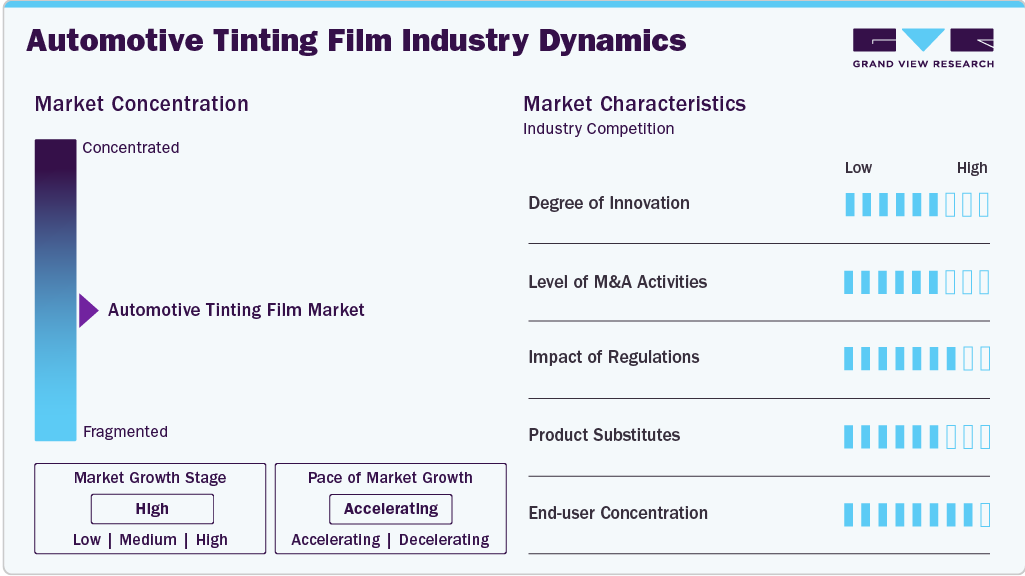
The market is characterized by a slightly high degree of innovation. Technological advancements such as the introduction of bio-based polyester films, combined with rising consumer purchasing power, are expected to drive vehicle type growth. Companies are driving innovation in automotive tinting films to compete with other market players and strengthen their positions.
For instance, in April 2024, Hyundai Motor Company launched an innovative vehicle window tint film named Nano Cooling Film that improves interior cooling performance significantly compared to conventional tint films. The Nano Cooling Film uses a nanostructure design to maximize heat dissipation, making it more effective in hot and dry climates. Tests show it can reduce interior temperatures by up to 12.33°C compared to an untinted vehicle. Hyundai launched a "Made Cooler By Hyundai" campaign in Lahore, Pakistan, and applied the film to 70 customer vehicles to demonstrate its effectiveness. Unlike dark tints that compromise visibility, Nano Cooling Film maintains high transparency while reflecting incoming heat and radiating internal heat outwards. It can also be used in combination with conventional tints for improved cooling effects.
 To learn more about this report, Download Free Sample Report
The regulations governing tinted windows in various countries are anticipated to have a detrimental effect on market growth within those nations. Certain countries, such as the U.S., provide exemptions in cases where passengers or drivers suffer from specific medical conditions such as sunlight allergies, lupus, photosensitivity, or melanoma. In India, the utilization of tinted glass on vehicles is strictly controlled.
Analyst Perspective
The Automotive Tinting Film Market is expected to evolve from a predominantly volume-driven aftermarket industry toward a value-led market centered on advanced performance, energy efficiency, and premium vehicle enhancement solutions over the next decade. Demand will continue to be supported by rising vehicle ownership, increasing adoption of electric and luxury vehicles, expanding commercial fleets, and growing consumer awareness of UV protection, heat reduction, privacy, and cabin comfort. Technological innovation is expected to accelerate the adoption of ceramic, nano-ceramic, spectrally selective, and smart tinting films that offer superior solar control without compromising visibility or connectivity. Regulatory compliance related to vehicle safety, visible light transmission standards, and sustainability objectives will increasingly influence product development and regional market dynamics. Competitive advantage will shift toward companies with strong R&D capabilities, proprietary film technologies, integrated manufacturing operations, extensive installer networks, and broad geographic reach. Strategic partnerships with automotive OEMs, dealerships, and aftermarket service providers will further strengthen market positioning. However, competitive pricing pressure, regulatory variations across countries, raw material cost fluctuations, counterfeit products, and supply chain disruptions will remain key challenges. Long-term growth opportunities will increasingly emerge from premium film technologies, electric vehicle applications, multifunctional protective films, and integrated vehicle appearance and protection solutions, reinforcing innovation as the primary driver of value creation across the market.
Vehicle Type Insights
Based on vehicle type, the passenger cars segment led the market with the largest revenue share of 65.7% in 2025, driven by rising consumer demand for comfort, privacy, and vehicle personalization. In addition, the increase in passenger car production directly boosts the automotive tinting films market, as more vehicles on the road drive higher demand for UV protection, heat reduction, and enhanced privacy features. According to European Automobile Manufacturers’ Association, in 2023, global passenger car production reached 75.9 million units, reflecting a robust recovery in the automotive industry and signaling an increased demand for related markets. Consumers seek tinting films for protection against UV radiation, heat, and glare, as well as to enhance vehicle aesthetics and interior preservation.
 To learn more about this report, Download Free Sample Report
The LCV segment is expected to grow at a CAGR of 7.9% over the forecast period, owing to the need for heat reduction, privacy, and protection of goods during transit. LCVs are widely used in commercial operations and fleet management, where maintaining optimal interior temperatures and safeguarding cargo are crucial. The rise in commercial activities, especially in urban and developing markets, increases demand for tinting solutions. Furthermore, regulatory trends, increased awareness of energy savings, and the push for fleet efficiency drive the adoption of high-performance tinting films in LCVs.
Application Insights
Based on application, the windshields segment led the market with the largest revenue share of 69.6% in 2025. Tinting films protect passengers from the heat of the sun and UV rays. These films also reduce glare and ensure clear vision and the safety of the vehicle driver. Most automobile manufacturers use tinting films to provide the best driving experience, protection, and to avoid glare. In addition, regulatory mandates on visible light transmission encourage the adoption of high-performance, transparent films, which contribute to the market’s growth. Furthermore, growing awareness of skin protection and energy efficiency in vehicles, along with the rise of electric and autonomous cars, further propels the use of tinting films on windshields.
The windows application segment is expected to grow at a CAGR of 7.5% over the forecast period. These tinting films are used to protect against harmful UV rays. Growing demand for a vehicle type to reduce interior temperatures, protect interiors from UV rays, and provide a comfortable driving experience for passengers is expected to drive demand over the forecast period. Furthermore, increasing demand for luxury and customized vehicles drives the use of advanced films that block UV rays and reduce cabin temperature. Moreover, urbanization, rising disposable incomes, and innovations in smart and adaptive tinting technologies also contribute significantly to the growing adoption of tinting films on automotive windows.
Regional Insights
North America dominated the automotive tinting film market with the largest revenue share of 33.4% in 2025. This growth is attributed to the growing demand for light commercial and passenger vehicles in the US. The market is also expected to grow due to minimum regulations regarding visible light transmission (VLT) percentage of tint films. Furthermore, technological advancements in premium, durable films and a preference for luxury and SUV models further fuel demand.
 To learn more about this report, Download Free Sample Report
U.S. Automotive Tinting Film Market Trends
The automotive tinting film market in the U.S. accounted for the largest market revenue share in North America in 2025, driven by the well-established road infrastructure and higher income per capita leading to an increased demand for automobile in the country. Moreover, a growing emphasis on vehicle customization and personalization among American consumers, with tinting films offering a practical and stylish way to enhance the appearance of vehicles while providing functional benefits such as UV protection and heat reduction.
Asia Pacific Automotive Tinting Films Market Trends
The Asia Pacific automotive tinting film market is expected to grow at the fastest CAGR of 8.4% over the forecast period. Tinting films are becoming increasingly popular in emerging markets for privacy and security reasons. Another factor expected to impact the Asia Pacific market positively is the increasing demand for the films from OEMs. Furthermore, the region’s climate, characterized by high temperatures and intense sunlight, increases demand for heat-reducing and UV-protective tinting films. Moreover, emerging economies are witnessing a surge in passenger car ownership, while consumers increasingly prioritize comfort and interior protection.
China's automotive tinting film market led the Asia Pacific market and held the largest revenue share in 2025. The country’s market is rapidly growing due to its booming automotive industry, which sees a high demand for vehicles. According to CEIC, in China, passenger car sales increased from 20.54 million units in 2022 to 21.92 million units in 2023, demonstrating strong growth and rising consumer demand in the automotive market. This surge in vehicle production and ownership increases the need for tinting films that offer UV protection, heat reduction, and enhanced privacy. Furthermore, government initiatives aimed at reducing vehicle emissions and improving energy efficiency are promoting the use of tinting films.
Automotive tinting film market in Japan is poised to grow notably from 2026 to 2033, driven primarily by its status as a major vehicle manufacturer with significant domestic and international demand. The country's renowned automotive industry not only fuels the need for tinting films domestically but also supports export requirements, where high-quality products are essential to meet global standards. This demand is further amplified by consumer preferences for top-notch automotive solutions prioritizing durability, UV protection, and aesthetic enhancement.
Europe Automotive Tinting Films Market Trends
The Europe automotive tinting film market is anticipated to grow moderately during the forecast period. The European Union's strict regulations on vehicle safety and energy efficiency push manufacturers to use tinting films that meet these high standards, ensuring compliance and enhancing vehicle performance. In addition, there is a growing focus on environmental sustainability, leading to increased adoption of tinting films that improve energy efficiency by reducing the need for air conditioning, lowering carbon emissions. These combined efforts to adhere to regulations and promote eco-friendly practices significantly boost the demand for automotive tinting films in Europe.
Central & South America Automotive Tinting Film Trends
In Central and South America, the automotive tinting film market is experiencing significant growth driven by several key factors. The region's hot and sunny climates demand tinting films that provide adequate UV protection and heat reduction, enhancing driving comfort and protecting vehicle interiors from sun damage. As the middle-class population expands across countries like Brazil and Argentina, there is a notable rise in disposable incomes and a corresponding increase in vehicle ownership. This demographic shift fuels the adoption of automotive tinting films as consumers seek to enhance both the aesthetic appeal and practical functionality of their vehicles.
Middle East & Africa Automotive Tinting Film Trends
In the Middle East and Africa, the automotive tinting film market is thriving due to the region's extreme climate, characterized by scorching heat and intense sunlight that underscores the necessity for tinting films that effectively reduce heat inside vehicles. The region boasts a strong market for luxury and premium vehicles, where consumers prioritize both style and functionality. This preference drives the demand for high-quality tinting films that offer superior UV protection, privacy, and aesthetic appeal.
Key Automotive Tinting Film Company Insights
Key companies are adopting several organic and inorganic expansion strategies, such as mergers & acquisitions, new product launches, capacity expansion, mergers & acquisitions, and joint ventures, to maintain and expand their market share.
-
TintFit Window Films Ltd. manufactures and deals in car window films, heat reduction films, privacy films, UV protection films, safety films, and decorative films. TintFit operates across multiple segments, including automotive tinting, architectural glazing solutions, and energy-saving window treatments, providing both trade and public customers with innovative solutions for comfort, security, and aesthetic enhancement.
-
Johnson Window Films, Inc. produces a wide variety of automotive window films, including nano-ceramic, metallized, and hybrid films designed for UV protection, heat rejection, glare reduction, and enhanced vehicle aesthetics. In addition to automotive applications, Johnson Window Films also operates in the architectural and safety film segments, catering to diverse needs for residential, commercial, and paint protection solutions.
Key Automotive Tinting Film Companies:
The following key companies have been profiled for this study on the automotive tinting film market.
- 3M
- Eastman Chemical Company
- TintFit Window Films Ltd.
- Avery Dennison Israel Ltd. (Hanita Coatings RCA Ltd.)
- Johnson Window Films, Inc.
- GLOBAL WINDOW FILMS
- Madico, Inc.
- Saint-Gobain Performance Plastics Corporation
- TWF
- Armolan
- NEXFIL
- Solar Screen International SA
- Huper Optik USA
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Companies (3M, Eastman Chemical Company, Avery Dennison Israel Ltd., Johnson Window Films, Inc., Madico, Inc., Saint-Gobain Performance Plastics Corporation, Huper Optik USA)
- Diversified product portfolios encompassing dyed, metallized, carbon, ceramic, nano-ceramic, safety & security, and spectrally selective automotive tinting films serving passenger vehicles, luxury automobiles, electric vehicles, commercial fleets, and specialty transportation applications.
- Continuous investment in film technologies focused on superior heat rejection, UV protection, optical clarity, infrared blocking, signal-friendly performance, and long-term durability. Strategic expansion through global manufacturing facilities, certified installer networks, dealership partnerships, aftermarket distribution channels, and collaborations with automotive OEMs.
- Increasing emphasis on premium ceramic and nano-ceramic solutions that support energy efficiency, passenger comfort, vehicle aesthetics, and regulatory compliance across global markets.
- Strong global brand recognition, extensive distribution networks, and decades of expertise in specialty films and advanced material technologies. Broad product portfolios serving multiple vehicle categories and geographic markets reduce dependence on individual customer segments.
- Extensive intellectual property, proprietary coating technologies, and established installer ecosystems create significant barriers to entry and high customer loyalty. Strong technical support capabilities, quality certifications, and relationships with dealerships, fleet operators, and automotive service providers enable reliable market penetration.
- Ability to leverage economies of scale, advanced R&D resources, and premium branding to maintain leadership in high-performance automotive tinting film applications.
- Exposure to fluctuations in polyester film, specialty coatings, adhesives, metals, and energy costs can impact manufacturing expenses and profit margins. Diverse regional regulations governing visible light transmission (VLT) limits and vehicle tinting standards require ongoing product adaptation and compliance investments.
- Demand can be influenced by automotive production cycles, consumer discretionary spending, and aftermarket installation activity. Competition from lower-cost regional manufacturers and private-label brands may create pricing pressure, particularly in value-oriented market segments.
- Mature penetration levels in developed automotive markets can limit volume growth and increased reliance on premium product innovation and replacement demand.
Emerging Companies (TintFit Window Films Ltd., GLOBAL WINDOW FILMS, TWF, Armolan, NEXFIL, and Solar Screen International SA)
- Focus on selective participation in the automotive tinting film value chain through specialized window film solutions, regional distribution networks, installer partnerships, and aftermarket vehicle enhancement services rather than competing directly with large multinational film manufacturers.
- Emphasis on offering cost-competitive products across dyed, carbon, ceramic, and hybrid tinting film categories tailored to local regulatory requirements and consumer preferences. Continuous investment in film performance improvements, UV rejection capabilities, heat reduction technologies, and installer training programs.
- Strategic expansion through dealer networks, automotive customization centers, and regional distributors to strengthen market penetration and increase brand visibility in high-growth automotive aftermarket segments.
- Strong ability to address regional market requirements and respond quickly to changing customer preferences.
- Established relationships with independent installers, automotive detailing centers, and vehicle customization businesses provide access to growing aftermarket demand.
- Greater operational flexibility enables faster introduction of niche products, customized film solutions, and competitive pricing strategies. Ability to focus on specific geographic markets and customer segments allows efficient targeting of opportunities in developing automotive markets and emerging vehicle enhancement trends.
- Limited global brand recognition and distribution reach compared with established industry leaders.
- Smaller manufacturing scale and narrower product portfolios reduce economies of scale and limit influence over pricing dynamics within the automotive tinting film industry.
- Dependence on aftermarket sales channels and regional market performance can constrain long-term growth potential. Relatively lower investment capacity in advanced film technologies, large-scale R&D programs, and global marketing initiatives increases competitive pressure from multinational manufacturers with stronger technological capabilities, broader product offerings, and extensive installer and dealership networks.
Recent Developments
-
In February 2025, Avery Dennison announced the launch of its Encore Series automotive film portfolio for windows. It features three-tier lineup, including Encore Supreme, Encore Supreme IR and Encore. These automotive films deliver superior heat rejection, glare reduction, and over 99% UV protection, while offering enhanced privacy and a sleek, color-stable finish.
-
In February 2025, Luminous launched a novel window tint, the Carbon Window Film, expanding its product line to offer enhanced durability, heat rejection, UV protection, and aesthetic appeal. The product was available through Al-Rabiya Auto Accessories in the MENA region.
Automotive Tinting Film Market Report Scope
Report Attribute
Details
Market size in 2025
USD 8.1 billion
Estimated market size in 2026
USD 8.7 billion
Projected market size by 2033
USD 14.7 billion
Growth rate
CAGR of 7.8% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion, volume in square foot, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Vehicle Type, application, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Russia; China; India; Japan; Thailand; Indonesia; Brazil; Argentina; UAE; South Africa
Key companies profiled
3M; Eastman Chemical Company; TintFit Window Films Ltd.; Avery Dennison Israel Ltd. (Hanita Coatings RCA Ltd.); Johnson Window Films, Inc.; GLOBAL WINDOW FILMS; Madico, Inc.; Saint-Gobain Performance Plastics Corporation; TWF; Armolan; NEXFIL; Solar Screen International SA; Huper Optik USA.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Automotive Tinting Film Market Report Segmentation
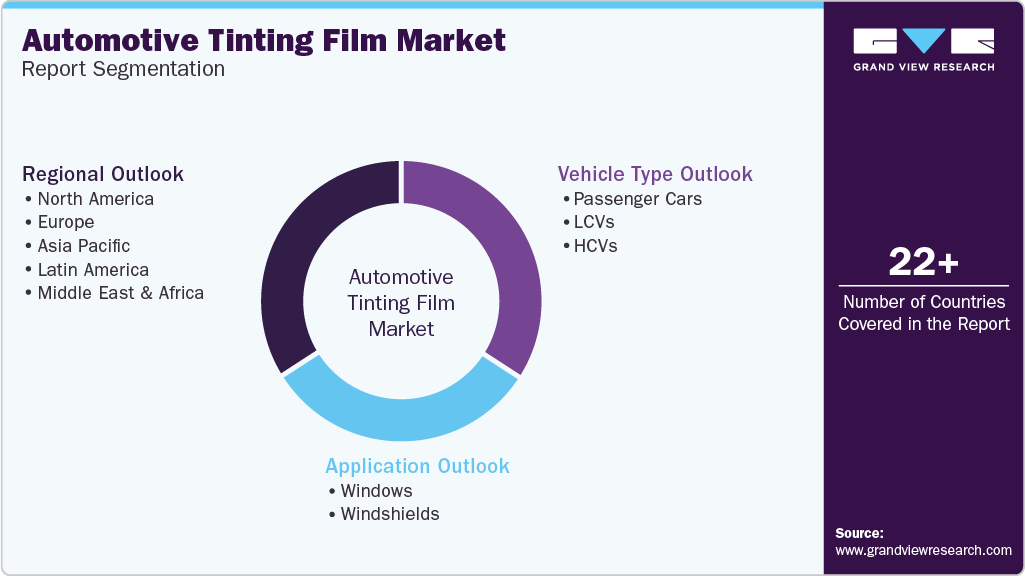
This report forecasts revenue growth and volume growth at global, regional, and country levels and analyzes the latest industry trends in each sub-segment from 2021 to 2033. For this study, Grand View Research has segmented the global automotive tinting film market report based on, vehicle type, application, and region:
 To learn more about this report, Download Free Sample Report
-
Vehicle Type Outlook (Volume, Square Foot; Revenue, USD Million, 2021 - 2033)
-
Passenger Cars
-
LCVs
-
HCVs
-
-
Application Outlook (Volume, Square Foot; Revenue, USD Million, 2021 - 2033)
-
Windows
-
Windshields
-
-
Regional Outlook (Volume, Square Foot; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Russia
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Thailand
-
Indonesia
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa
-
UAE
-
South Africa
-
-
Research Methodology
The automotive tinting film market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each automotive tinting film segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Application
Revenue capture definition
Windows
Revenue is captured through the sale of automotive tinting films applied to side and rear windows in passenger cars, SUVs, luxury vehicles, and commercial fleets. Demand is driven by the film’s ability to reduce glare, block harmful UV rays, improve cabin comfort, enhance privacy, and protect interior surfaces from fading and heat damage. Growth is further supported by rising consumer preference for vehicle aesthetics, increased adoption in hot climates, and the need for energy-efficient solutions that reduce reliance on air conditioning.
Windshields
Revenue is captured through the supply of specialty tinting films designed for automotive windshields, where legal compliance, optical clarity, and heat rejection are critical. These films are valued for their ability to minimize sun glare, improve driving comfort, reduce UV exposure, and enhance safety without compromising visibility. Sales are supported by increasing demand for premium vehicle protection, growing awareness of interior preservation, and the need for advanced solutions that balance solar control, durability, and regulatory requirements in high-exposure driving environments.
Segment - Vehicle Type
Revenue capture definition
Passenger Cars
Revenue is captured through automotive tinting films installed in sedans, hatchbacks, SUVs, crossover vehicles, and luxury passenger automobiles. Value is driven by UV protection, solar heat rejection, glare reduction, privacy enhancement, interior preservation, and improved passenger comfort. Demand is supported by rising passenger vehicle ownership, increasing consumer awareness of vehicle protection solutions, growing disposable incomes, and strong adoption of premium aftermarket customization products.
LCVs (Light Commercial Vehicles)
Revenue is generated through automotive tinting films used in vans, pickup trucks, delivery vehicles, service fleets, and small commercial transportation vehicles. Pricing is influenced by cabin temperature control, driver comfort, fuel efficiency benefits, UV protection, and compliance with local tinting regulations. Growth is supported by expanding e-commerce logistics networks, increasing urban delivery operations, fleet modernization initiatives, and rising demand for cost-effective vehicle enhancement solutions that improve operational efficiency.
HCVs (Heavy Commercial Vehicles)
Revenue is captured through automotive tinting films installed in trucks, trailers, buses, coaches, and other heavy-duty transportation vehicles. Value is driven by heat reduction, glare control, driver safety, passenger comfort, privacy, and long-term interior protection under intensive operating conditions. Demand is supported by growth in freight transportation, public transit expansion, commercial fleet investments, and increasing focus on driver welfare, energy efficiency, and vehicle maintenance cost reduction across the transportation sector.
Estimation Model
Layer Name
Key Question
Description
Top-Down Automotive Tinting Film Demand Assessment Layer
What defines market boundaries?
This layer establishes global automotive tinting film demand across passenger vehicles, luxury automobiles, electric vehicles, commercial fleets, rental vehicles, logistics vehicles, and public transportation systems. Demand is filtered through macro drivers such as vehicle production growth, rising disposable incomes, urbanization, increasing vehicle ownership, climate conditions, and growing consumer awareness of UV protection, privacy, and energy efficiency. This defines the total addressable market based on tinting film adoption across key vehicle categories and aftermarket installations.
End-Use Demand Validation Layer
Where is demand generated?
This layer maps demand across passenger cars, premium and luxury vehicles, electric vehicles, commercial fleets, rideshare vehicles, rental car fleets, logistics vehicles, and public transit applications. Market sizing is aligned with performance requirements such as solar heat rejection, UV protection, glare reduction, privacy enhancement, safety improvement, aesthetic appeal, and compliance with regional tinting regulations.
Consumption-to-Revenue Conversion Layer
Who captures market revenue?
This layer translates vehicle production volumes and aftermarket installation activity into revenue potential using tinting film coverage area, film type, performance specifications, installation complexity, and product grade. Pricing differentials across dyed, metallized, carbon, ceramic, and premium nano-ceramic films are incorporated to estimate value realization across film manufacturers, distributors, installers, dealerships, and automotive service providers.
Regional Demand Verification Layer
How are assumptions validated?
This layer validates demand distribution across Asia Pacific, North America, Europe, Latin America, and the Middle East & Africa by assessing vehicle ownership trends, automotive production levels, climatic conditions, consumer spending patterns, and regulatory frameworks governing window tinting. Regional aftermarket activity, premium vehicle penetration, solar exposure intensity, and transportation sector expansion are used to verify market penetration assumptions and strengthen forecast reliability.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Segmentation
Detailed market breakdown across North America, Europe, Asia Pacific, Latin America, and Middle East & Africa, with country-level analysis for key automotive tinting film markets including the U.S., Canada, Germany, UK, France, China, India, Japan, South Korea, UAE, and Brazil.
Enables identification of high-growth regions, regulatory differences, climate-driven demand patterns, and region-specific investment opportunities for market entry and expansion strategies.
Competitive Benchmarking
Comparative assessment of leading and emerging players based on product portfolio, technology capabilities, geographic presence, distribution network, installer partnerships, pricing strategy, innovation pipeline, and strategic initiatives.
Provides actionable insights into competitor positioning, market share opportunities, differentiation strategies, and potential partnership or acquisition targets.
Opportunity Assessment
Identification of emerging growth opportunities across electric vehicles, luxury vehicles, smart tinting technologies, advanced ceramic films, commercial fleet applications, vehicle protection solutions, and developing automotive markets. Includes attractiveness ranking and investment prioritization analysis.
Enables informed strategic decision-making by highlighting high-potential revenue pools, future demand drivers, innovation opportunities, and long-term market expansion areas.
Frequently Asked Questions About This Report
The global automotive tinting film market was valued at around USD 8.1 billion in the year 2025 and is expected to reach around USD 8.7 billion in 2026.
The global automotive tinting film market is expected to grow at a compound annual growth rate of 7.8% from 2026 to 2033 to reach around USD 14.7 billion by 2033.
The windshields led the automotive tinting film market in 2025 with a 69.6% share. The market is supported by increasing demand from passenger vehicles, luxury automobiles, electric vehicles, commercial fleets, and public transportation applications, where windshield tinting films are utilized to enhance UV protection, reduce solar heat gain, improve driving comfort, and support overall vehicle safety and energy efficiency.
The North America automotive tinting film market accounted for the largest share of 33.4% market size in 2025.
U.S. was the leading Automotive Tinting Film market and is expected to grow at a compound annual growth rate of 7.7%.
Based on application, the windshields segment is expected to grow at a compound annual growth rate of 7.9%. The market is supported by increasing demand from passenger vehicles, luxury automobiles, electric vehicles, commercial fleets, and public transportation applications, where windshield tinting films are utilized to enhance UV protection, reduce solar heat gain, improve driving comfort, and support overall vehicle safety and energy efficiency.
The LCVs segment is expected to grow at a CAGR of 7.9% for the forecast period.
The key players in the automotive tinting film market are 3M, Eastman Chemical Company, TintFit Window Films Ltd., Avery Dennison Israel Ltd. (Hanita Coatings RCA Ltd.), Johnson Window Films, Inc., GLOBAL WINDOW FILMS, Madico, Inc., Saint-Gobain Performance Plastics Corporation, TWF, Armolan, NEXFIL, Solar Screen International SA, and Huper Optik USA.
The market growth is being fueled by the increasing use of automotive tinting films across passenger vehicles, luxury automobiles, electric vehicles, commercial fleets & car rental services, including taxi operators, rideshare drivers, and rental agencies, as well as logistics and public transit vehicles.
About the Author(s)
Plastics, Polymers & Resins Research Team
Bulk Chemicals · Plastics, Polymers & ResinsThis report was authored by the plastics, polymers & resins research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the plastics, polymers & resins segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


