
- Home
- »
- Next Generation Technologies
- »
-
Banking Encryption Software Market Size, Share Report 2033GVR Report cover

Banking Encryption Software Market (2026 - 2033)
Size, Share & Trends Analysis Report By Component (Software, Service), By Deployment (On-Premise, Cloud), By Enterprise Size (Large Enterprises, Small & Medium Enterprises), By Function, By Region, And Segment Forecasts
Market Size, 2025
$2.6BMarket Estimate, 2026
$3.0BMarket Forecast, 2033
$7.6BCAGR, 2026–2033
14.4%Banking Encryption Software Market Trends
The global banking encryption software market size was valued at USD 2.6 billion in 2025 and is projected to grow from USD 3.0 billion in 2026 to USD 7.6 billion by 2033, at a CAGR of 14.4% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 28.5% in 2025. Banking encryption software provides numerous advantages, including seamless data transaction services and enhanced security.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By component: Software segment dominated the market, with a revenue share of 64.4% in 2025.
- By deployment: On-Premise segment held the largest market share of 60.2% in 2025.
- By enterprise size: Large Enterprises segment accounted for the largest revenue share in 2025.
- By function: Disk Encryption segment accounted for the largest revenue share in 2025.
Regional Highlights
- Largest regional market: North America (28.5% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 2.6 Billion
- Estimated market size in 2026: USD 3.0 Billion
- Projected market size by 2033: USD 7.6 Billion
- CAGR (2026-2033): 14.4%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The increasing demand for secure payment solutions in the banking sector, aimed at delivering safer services to customers, is driving the market’s growth. In addition, the emergence of digital payment platforms and increased utilization of digital payment methods create a positive outlook for the industry. The prevalence of online payment platforms is intertwined with the threat of cyberattacks, which will provide additional opportunities for the market. Integrating artificial intelligence (AI) in banking encryption software is transforming the financial sector by enhancing security measures and improving operational efficiency. This development is critical as the banking industry faces increasing cyberattack threats, necessitating robust protective measures for sensitive data. AI enhances the effectiveness of encryption software by enabling real-time adjustments to security protocols based on evolving threats. It employs machine learning algorithms to analyze vast datasets, identify patterns, and predict potential vulnerabilities, thus adapting encryption methods dynamically. This proactive approach allows banks to stay ahead of cybercriminals, significantly improving data protection. Thus, the rapid adoption of AI-enabled encryption software in the banking and finance sector, owing to its abovementioned benefits, is expected to boost market growth during the forecast period.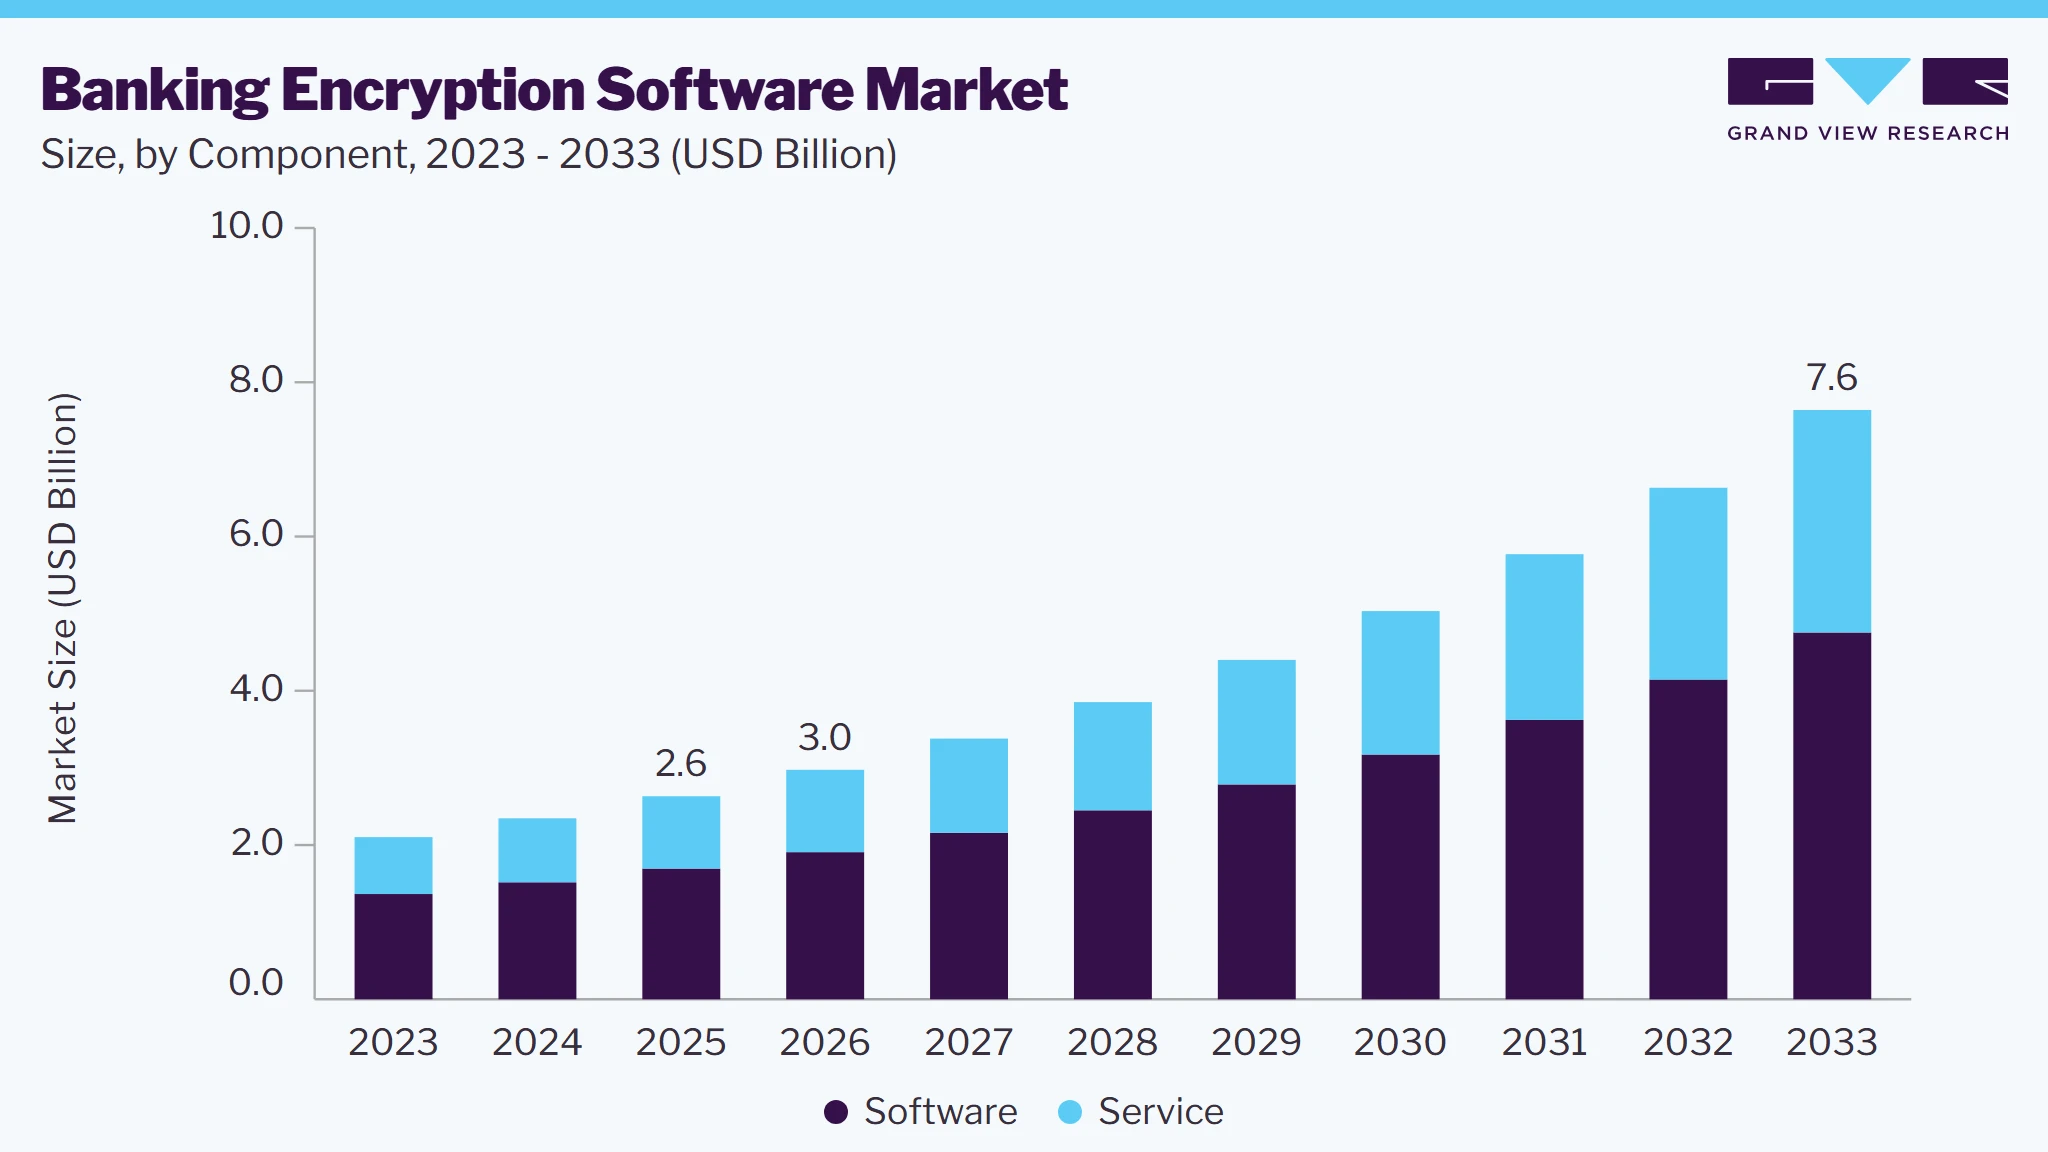 To learn more about this report, Download Free Sample Report
A surge in the implementation of data privacy laws, such as the Payment Card Industry Data Security Standards (PCI DSS) for the banking sector to protect sensitive data from fraud and theft, creates the demand for banking encryption software. Although authorities highly regulate the banking sector, it is the prime target of cybercriminals. The sector houses a large volume of data such as personal information, social security numbers, and payment card details. This creates a need for the banking industry to implement security measures to safeguard such data, leading to promising growth opportunities.
The banks are required to uphold the integrity of data throughout their life cycle. Consequently, it is also crucial for banks to implement the proper threat detection and response procedures as per their requirements. Data integrity can thereby be maintained by enforcing a variety of security policies, including data masking and encryption software by banks. As a result, this is anticipated to drive the demand for banking encryption software within the banking, finance, and insurance (BFSI) sector.
However, high implementation and maintenance costs associated with advanced encryption technologies can deter smaller financial institutions from adopting these solutions. In addition, the complexity of integrating encryption software with existing systems poses technical hurdles, leading to potential disruptions in operations. Regulatory compliance and evolving data protection laws can also create uncertainty, making it difficult for banks to navigate the landscape and adopt new technologies. Moreover, a lack of awareness and understanding of encryption benefits among customers may hinder broader adoption, which in turn is expected to hamper the market’s growth.
Market Dynamics
The banking encryption software market is shaped by the rising digitization of financial services, the increasing frequency of cyberattacks, and stringent global data protection regulations. Banks are expanding digital channels, adopting cloud, and building API-driven ecosystems, which have significantly increased the volume of sensitive financial and identity data in motion and at rest. Technology forces such as zero-trust security models, post-quantum cryptography research, and encryption-as-a-service platforms are redefining how banks secure data across hybrid IT environments. As a result, the market is transitioning from siloed encryption tools toward integrated, policy-driven encryption frameworks embedded within core banking and security architectures.
Banks face persistent threats from ransomware, data breaches, and insider attacks, driven by the expansion of digital banking, open banking APIs, and real-time payment systems. Financial institutions remain prime targets due to the high monetary value of transactional and customer data. Simultaneously, regulations such as data localization mandates, payment security standards, and privacy laws have increased the complexity of compliance. These combined pressures have made encryption a non-negotiable security control rather than an optional enhancement.
Banking encryption software directly addresses this driver by securing data across endpoints, databases, networks, and cloud workloads using strong cryptographic algorithms and centralized key management. Modern solutions enable banks to meet compliance requirements while reducing the impact of breaches through data unreadability. Integrated encryption across disks, files, communications, and cloud environments lowers operational risk and strengthens audit readiness. This functional expansion is accelerating enterprise-wide adoption and sustaining market growth.
Deployment of enterprise-grade encryption software often requires significant upfront investment, skilled security teams, and integration with legacy core banking systems. Key management, performance overhead, and interoperability challenges increase the total cost of ownership, particularly for institutions operating in heterogeneous IT environments. These factors create barriers to adoption, especially for mid-tier banks with limited cybersecurity budgets.
This restraint disproportionately affects on-premise deployments and small & medium-sized banking institutions in emerging markets, where legacy infrastructure remains prevalent. Complex implementation cycles slow decision-making and extend procurement timelines, limiting short-term market expansion. As a result, adoption growth remains uneven across regions, with slower uptake outside North America and Western Europe.
The accelerating migration of banking workloads to public and private cloud platforms is driving strong demand for scalable, cloud-native encryption solutions. Advances in hardware security modules (HSMs), bring-your-own-key (BYOK) models, and encryption-as-a-service are lowering deployment complexity. Regulatory acceptance of cloud security controls further enables this shift.
Cloud encryption and managed services offer recurring revenue potential and faster deployment cycles, positioning vendors with strong cloud security portfolios to capture incremental demand. Segments such as communication encryption and cloud encryption are expected to benefit most. Vendors offering integrated encryption with identity, access management, and threat detection are best positioned to monetize this opportunity.
Analyst Perspective
The banking encryption software market is in a structurally strong position, supported by sustained cybersecurity investment and regulatory enforcement. Encryption is increasingly embedded in broader security platforms rather than deployed as a standalone tool. Cloud native encryption centralized key management, and zero-trust architectures are reshaping product strategies. Investment momentum is expected to favor subscription-based and managed encryption services. Competitive differentiation is shifting toward integration depth, compliance automation, and performance optimization in hybrid environments.
Component Insights
Based on component, the software segment led the market with the largest revenue share of 64.4% in 2025. The software provides the infrastructure for deploying, creating, and managing financial products. In addition, account holders' personal information, including names, addresses, and dates of birth, is stored and secured using the software. The segment is expected to grow as banks increasingly use encryption software to provide secure money transfer services to their customers.
The service segment is expected to witness significant growth during the forecast period. It includes professional services, managed services, and training and development, among others. Professional services help banks smoothly integrate encryption software with their existing systems. Managed services offer deep infrastructure support and maintenance to the banks.
Deployment Insights
Based on deployment, the on-premise segment led the market with the largest revenue share of 60.2% in 2025. Institutions worldwide are making efforts to gain authority over their software and control over their data. As a result, they are demanding on-premise deployment, as it enables them to control their data and its security. At the same time, even if the connection to the internet is interrupted, employees can gain access to the data with on-premise solutions.
Cloud deployment is expected to grow at the highest CAGR during the forecast period. Since there are many management and security options available with cloud deployment, it can be deployed by practically any type of business. Banking companies can benefit from improved levels of fault tolerance, data protection, and disaster recovery with cloud deployment, where the service provider manages the technology. In addition, cloud deployment provides high levels of redundancy and backup at a lesser cost.
Function Insights
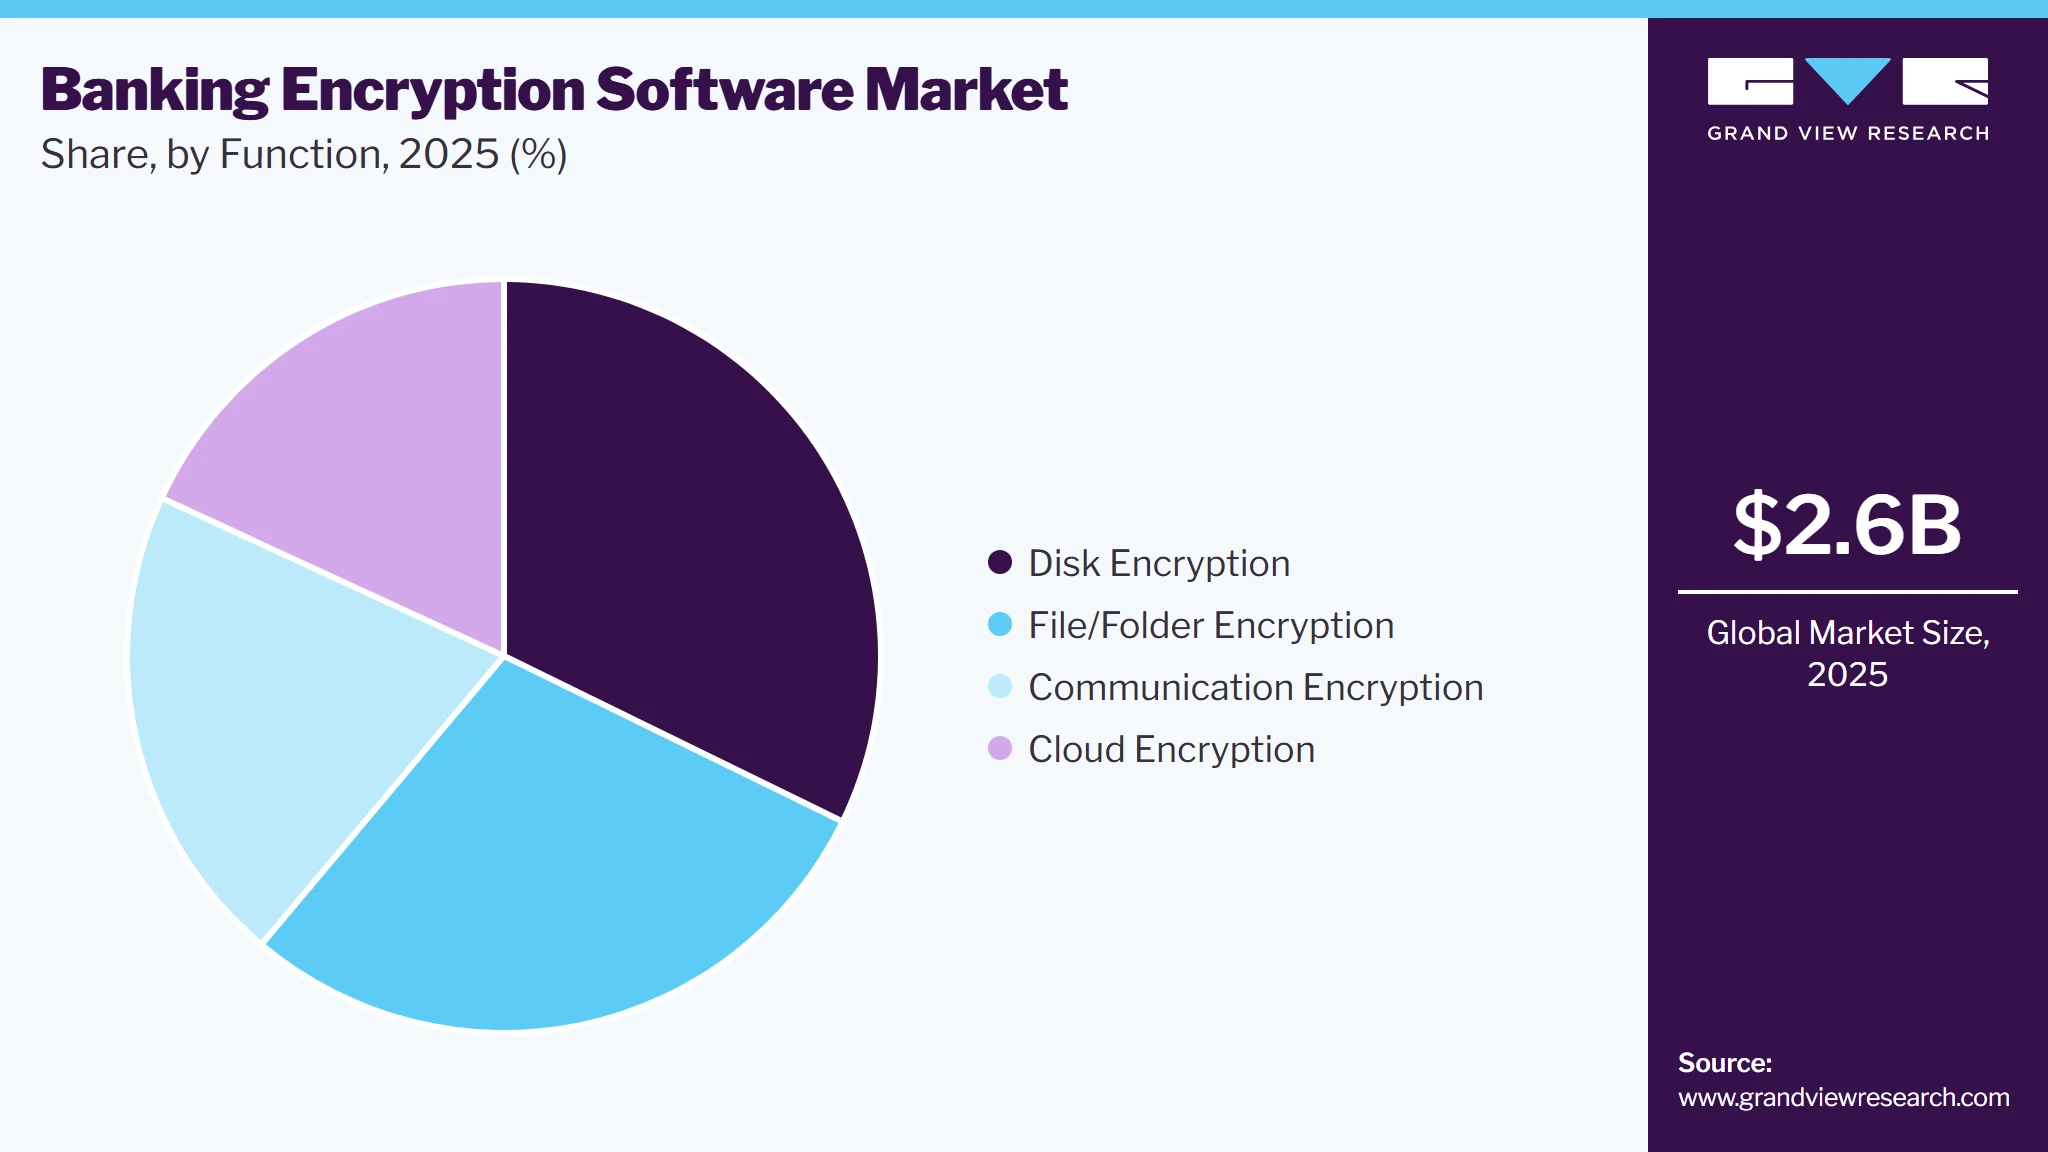
Based on function, the disk encryption segment led the market with the largest revenue share of 32.2% in 2025. Disk encryption's capability to encrypt the tiniest bit of data stored in the disk volume creates demand across the banking sector. In addition, the market for this category is expanding because encrypted disks are secure. Even if they are lost or stolen, only authorized users can access their information. Moreover, it is comparably easier to implement across the institute, hence it is preferred over other functions.
 To learn more about this report, Download Free Sample Report
The cloud encryption segment is anticipated to grow rapidly during the forecast period. Cloud encryption enables secure remote work and real-time data security. An encryption algorithm converts data into ciphertext. In addition, cloud encryption serves as proactive protection against data breaches and cyberattacks. It enables businesses and their clients to benefit from the advantages of cloud collaboration services without unduly risking their customers' data.
Enterprise Size Insights
Based on enterprise size, the large enterprises segment led the market with the largest revenue share of 60.8% in 2025. Large enterprises comparably have to handle a lot of data owing to their large customer base, which is the key attribute responsible for the segment’s dominance. Unlike SMEs, they have huge funds to implement software to enhance security and protect customers’ interests. As a result, they can easily adopt modern security solutions to enhance their standards.
The small & medium enterprises segment is expected to grow at the highest CAGR during the forecast period. The rising incidents of cyber-attacks and frauds on SMEs are expected to increase the demand for comprehensive security solutions. These security solutions help banks prevent revenue loss due to the theft of sensitive information. Thus, the growing number of small and medium banks is expected to drive the segment’s growth.
Regional Insights
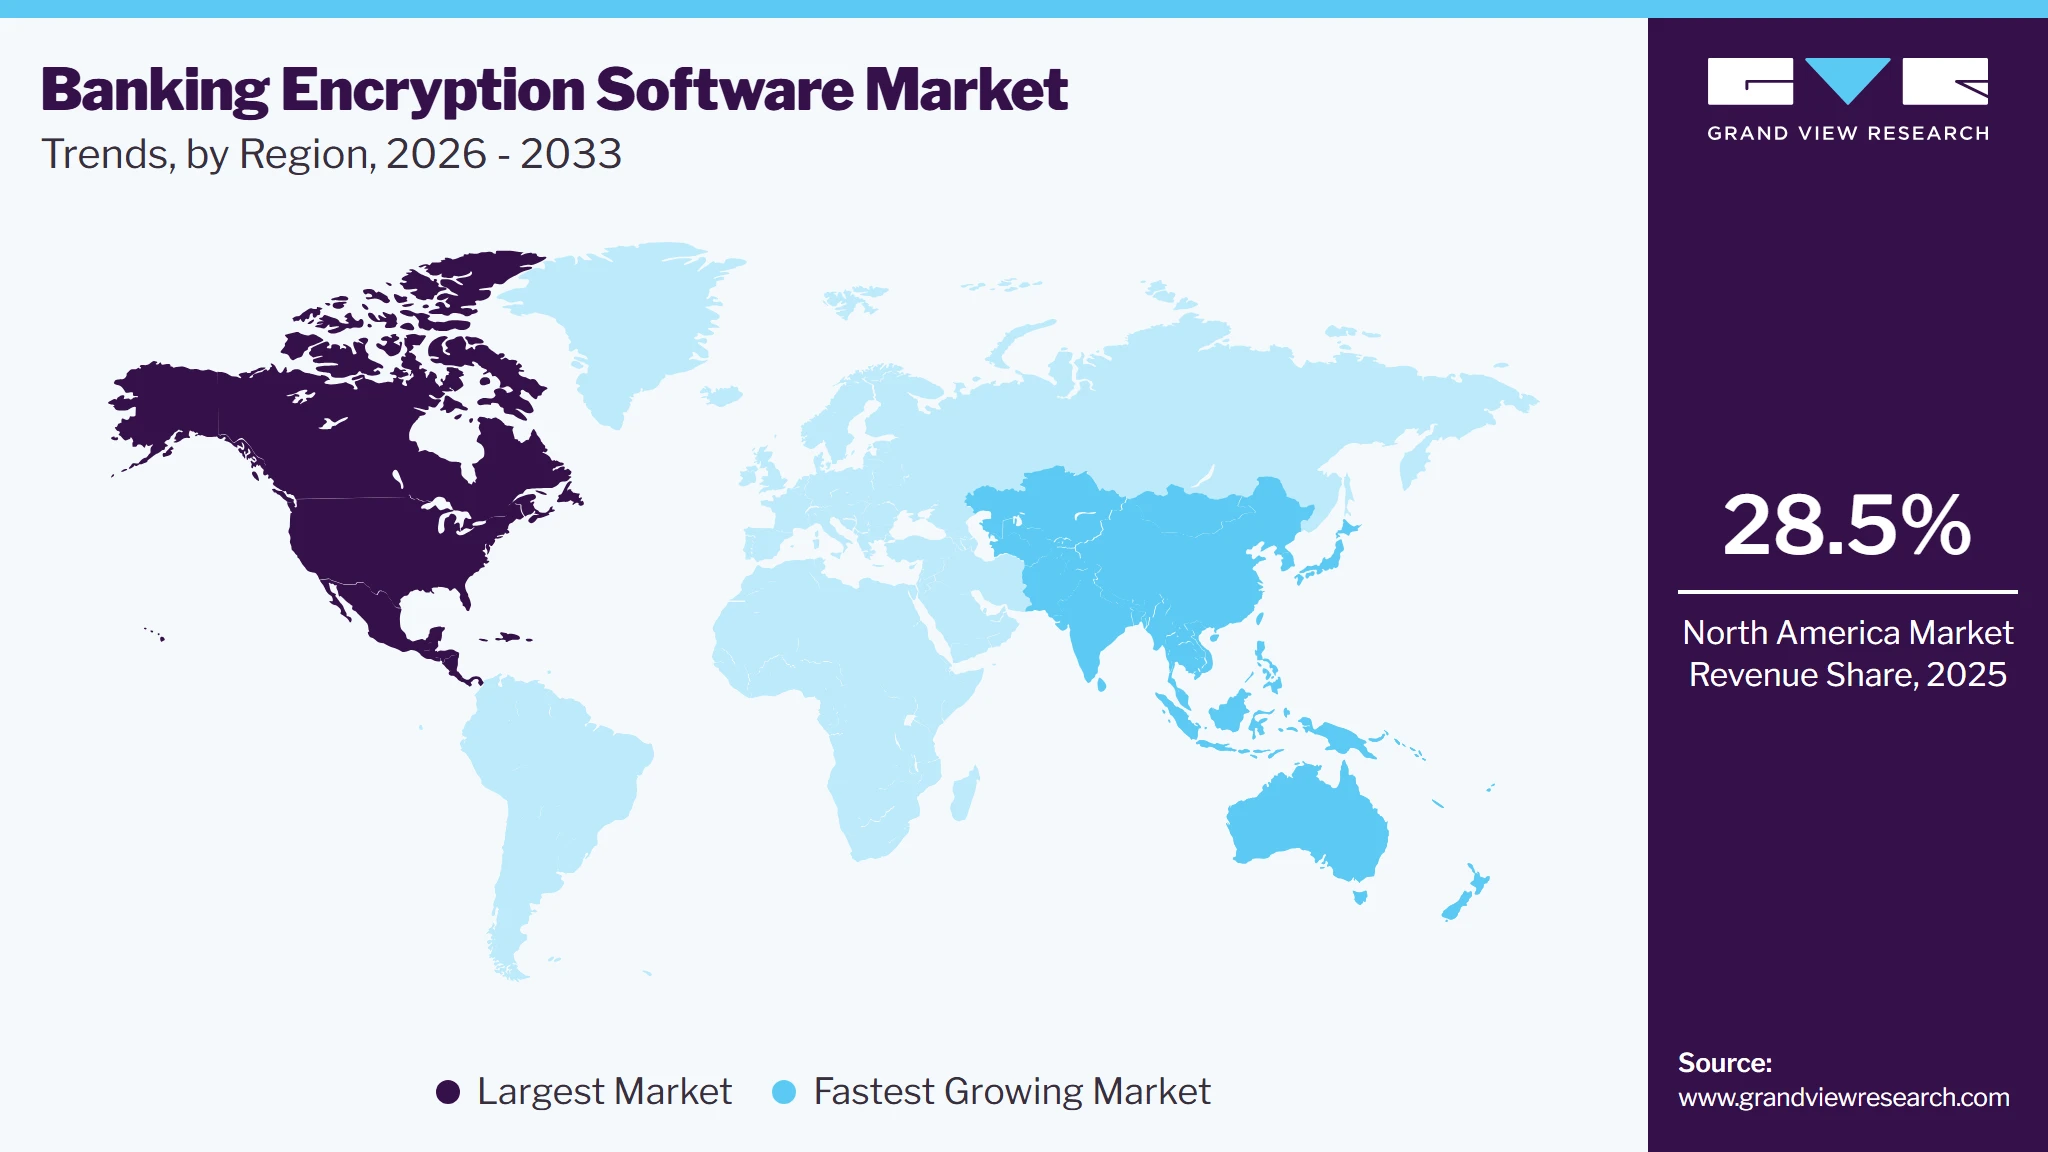
North America dominated the global banking encryption software market with the largest revenue share of 28.5% in 2025. The dominance is attributable to the improved regulatory norms in countries such as Canada and the U.S. that require banks to improve data privacy. Public and private banks have also expanded their demand for cryptographic software to safeguard privacy. In addition, the rise in cyberattacks & the threat to the information that affects business is expected to drive the regional market growth.
 To learn more about this report, Download Free Sample Report
U.S. Banking Encryption Software Market Trends
The banking encryption software market in the U.S. held the largest share in the North America region in 2025. With the rise in cyber threats and data breaches, U.S. financial institutions are prioritizing the protection of sensitive customer information. Regulatory requirements, such as the Payment Card Industry Data Security Standard (PCI DSS), push banks to invest in robust encryption solutions. The increasing prevalence of cyber threats drives demand for advanced encryption solutions as banks seek to secure sensitive customer information and maintain trust.
Europe Banking Encryption Software Market Trends
The banking encryption software market in Europe was identified as a lucrative region in 2024 owing to factors such as rising demand for digital payment solutions and enhanced data security measures. The region's focus on digital transformation in banking drives financial institutions to adopt comprehensive encryption strategies to protect customer data across various platforms. Regulatory frameworks such as the General Data Protection Regulation (GDPR) compel banks to prioritize data privacy, further propelling market growth.
The UK banking encryption software market is expected to grow rapidly in the coming years. With a strong emphasis on compliance with regulations such as GDPR, banks are investing in advanced encryption solutions to mitigate risks associated with data breaches and cyberattacks. The growing trend of mobile banking and digital payment platforms necessitates secure transaction processes, driving demand for effective encryption technologies.
The banking encryption software market in Germany held a substantial market share in 2024. The market's growth can be attributed to a strong emphasis on data protection and compliance with stringent regulatory standards. The rise of digital banking services has increased the need for secure data transmission methods, encouraging banks to invest in advanced encryption technologies and thereby driving market growth.
Asia Pacific Banking Encryption Software Market Trends
The banking encryption software market in Asia Pacific is anticipated to grow at a CAGR of 14.9% during the forecast period. The market’s regional growth can be attributed to the growing awareness in countries such as China, Japan, and India about the benefits offered by banking encryption software. The demand for secure, all-encompassing, and dependable security systems among banking service providers is fueling the industry’s expansion. In addition, rising government privacy regulations and the use of mobile payment technology are two other key growth drivers.
China banking encryption software market held a substantial market share in 2024, driven by increasing awareness of cybersecurity among financial institutions. The country’s growing adoption of digital payment technologies necessitates robust encryption solutions to protect sensitive customer information from rising cyber threats. Government initiatives aimed at enhancing data privacy regulations also contribute to market growth.
The banking encryption software market in Japan is expected to register a moderate growth rate during the forecast period. The country's advanced technological infrastructure supports the adoption of sophisticated encryption solutions that protect sensitive financial data during transactions. In addition, the rise of mobile banking and e-commerce further highlights the necessity for secure data transmission methods, propelling market growth in this country.
Key Banking Encryption Software Company Insights
Some of the key companies in the banking encryption software market include IBM Corporation, Microsoft Corporation, and Broadcom Inc. Organizations are focusing on integrating advanced technologies into their offerings to maintain competitive advantages. Therefore, key players are taking several strategic initiatives, such as new product launches, mergers and acquisitions, and partnerships.
-
IBM Corporation provides IBM Guardium Data Encryption, a key management and data encryption software. It features a unified suite of products built on a shared infrastructure and offers capabilities such as data masking, tokenization, data encryption, and key management.
-
Broadcom Inc.'s Symantec Encryption portfolio provides versatile data protection through a variety of solutions, including folder and file encryption, endpoint drive encryption, email encryption, and encryption for data exchange and transfer.
Key Banking Encryption Software Companies
The following key companies have been profiled for this study on the banking encryption software market.
-
Broadcom Inc.
-
ESET North America
-
IBM Corporation
-
Intel Corporation
-
McAfee, LLC
-
Microsoft Corporation
-
Sophos Ltd.
-
Thales Group
-
Trend Micro Incorporated
-
WinMagic
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (IBM Corporation, Microsoft Corporation, Thales Group, Broadcom Inc.)
- These players are focused on broad portfolios, deep banking relationships, hybrid cloud security integration, and global delivery models.
- These players have strong compliance capabilities, scalability, and integration with core banking and cloud platforms.
- High pricing and complex implementation cycles for mid-tier banks.
Emerging Players (Sophos Ltd., Trend Micro Incorporated, WinMagic)
- These players are focused on encryption offerings, endpoint-centric security, and simplified deployment models.
- These players have cost efficiency, faster deployment, and specialization in specific encryption functions.
- Limited breadth across large-scale banking environments and fewer legacy system integrations.
Recent Developments
-
In January 2024, Kurdistan International Islamic Bank for Investment and Development (KIB), a prominent Islamic financial institution in Iraq, initiated a digital transformation by adopting iMAL, the Islamic core banking platform from Azentio Software, a Singapore-based technology firm. The iMAL incorporates advanced encryption and security measures to protect against the most sophisticated electronic cyber threats.
Banking Encryption Software Market Report Scope
Report Attribute
Details
Market size in 2025
USD 2.6 billion
Estimated market size in 2026
USD 3.0 billion
Projected market size by 2033
USD 7.6 billion
Growth rate
CAGR of 14.4% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company market share, competitive landscape, growth factors, and trends
Segments covered
Component, deployment, enterprise size, function, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; U.K.; France; China; Japan; India; South Korea; Australia; Brazil; Saudi Arabia; UAE; South Africa
Key companies profiled
Broadcom Inc., ESET North America, IBM Corporation, Intel Corporation, McAfee, LLC, Microsoft Corporation, Sophos Ltd., Thales Group, Trend Micro Incorporated, WinMagic
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Banking Encryption Software Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global banking encryption software market report based on component, deployment, enterprise size, function, and region:
-
Component Outlook (Revenue, USD Million, 2021 - 2033)
-
Software
-
Service
-
-
Deployment Outlook (Revenue, USD Million, 2021 - 2033)
-
On-Premise
-
Cloud
-
-
Enterprise Size Outlook (Revenue, USD Million, 2021 - 2033)
-
Large Enterprises
-
Small & Medium Enterprises
-
-
Function Outlook (Revenue, USD Million, 2021 - 2033)
-
Disk Encryption
-
Communication Encryption
-
File/Folder Encryption
-
Cloud Encryption
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
-
Middle East & Africa
-
KSA
-
UAE
-
South Africa
-
-
Research Methodology
The banking encryption software market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each banking encryption software segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Component
Revenue capture definition
Software
Revenue generated from perpetual licenses and subscription-based licenses for banking encryption software, including disk, file/folder, communication, and cloud encryption modules; fees from centralized key management platforms, compliance reporting tools, encryption policy engines, and encryption APIs integrated into core banking and security systems.
Service
Revenue derived from professional services such as encryption architecture consulting, deployment and system integration, customization for regulatory compliance, managed encryption services, software upgrades, annual maintenance contracts, and ongoing technical support provided to banking institutions.
Segment - Deployment
Revenue capture definition
On-Premise
Encryption solutions are deployed within bank-owned data centers and private IT infrastructure to secure data stored on internal servers, databases, endpoints, and private networks, with full control over encryption keys and security policies.
Cloud
Encryption solutions delivered through public, private, or hybrid cloud environments, protecting banking data stored or processed in cloud platforms, SaaS applications, and virtualized workloads using cloud-based key management and encryption controls.
Segment - Enterprise Size
Revenue capture definition
Large Enterprises
Tier-1 and multinational banks with complex IT infrastructure and stringent compliance requirements are deploying encryption across their global operations.
Small & Medium Enterprises
Regional banks, cooperative banks, and fintech-aligned institutions with focused encryption needs and cost-sensitive security budgets.
Segment - End-use
Revenue capture definition
Disk Encryption
Revenue generated from encryption solutions that secure entire storage devices, including licensing fees for endpoint and server disk encryption and associated management tools.
Communication Encryption
Revenue earned from software and services that encrypt data in transit, including secure email, online banking sessions, payment transactions, and encrypted network communications.
File/Folder Encryption
Revenue captured from solutions that encrypt specific files or folders, including per-user or per-file licensing fees and access-control management features.
Cloud Encryption
Revenue generated from encryption tools designed to secure data stored and processed in cloud environments, including cloud key management, data-at-rest protection, and subscription-based cloud security services.
Estimation Model
Layer Name
Key Question
Description
Banking IT Security Spend
How much do banks spend on security?
This layer estimates total banking IT security expenditure across regions, covering infrastructure, software, and services. It forms the addressable security budget base from which encryption spending is derived.
Encryption Allocation
What share is allocated to encryption?
This layer isolates the portion of security budgets dedicated to encryption tools, including data-at-rest and data-in-motion protection. Regulatory requirements and breach history influence allocation ratios.
Banking Use-Case Penetration
Where is encryption deployed?
This layer evaluates encryption adoption across disks, communications, files, and cloud workloads within banking environments. Deployment maturity varies by bank size and region.
Vendor Revenue Realization
How is revenue captured?
This layer translates deployment intensity into vendor revenue through licenses, subscriptions, and services, reflecting pricing models and contract structures.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Banking Encryption Software Market Opportunity Assessment
Country/region-wise market sizing and forecasts
Analysis of demand, adoption trends, and regulatory landscape
Identification of high-growth regions and investment hotspots
Identified region-specific growth opportunities
Supported expansion and go-to-market strategy
Enabled informed regional investment decisions
Cross-Segmentation Analysis for the Banking Encryption Software Market
Criss-cross market analysis by component, deployment, enterprise size, function
Demand and adoption assessment across key segments
Segment attractiveness and growth potential benchmarking
Identified high-potential market segments
Supported targeted product positioning and marketing strategy
Improved customer and segment prioritization
Competitive Benchmarking and Strategic Positioning in the Banking Encryption Software Market
Benchmarking of key competitors across products, pricing, partnerships, and innovation
Comparative assessment of market share, capabilities, and strategies
Analysis of competitive strengths, gaps, and differentiation areas
Identified competitive white spaces and growth gaps
Supported strategic positioning and differentiation
Enabled data-driven competitive strategy development
Frequently Asked Questions About This Report
North America dominated the global market with the largest revenue share of 28.5% in 2025. The dominance is attributable to the improved regulatory norms in countries such as Canada and the U.S. that require banks to improve data privacy.
Asia Pacific is the fastest-growing region during the forecast period.
On-Premise segment held the largest market share of 60.2% in 2025, while cloud segment is the fastest growing during the forecast period.
Some key players operating in the banking encryption software market include Broadcom Inc., ESET North America, IBM Corporation, Intel Corporation, McAfee, LLC, Microsoft Corporation, Sophos Ltd., Thales Group, Trend Micro Incorporated, and WinMagic
The increasing demand for secure payment solutions in the banking sector, aimed at delivering safer services to customers, is driving the market’s growth.
The global banking encryption software market size was estimated at USD 2.6 billion in 2025 and is expected to reach USD 3.0 billion in 2026.
The global banking encryption software market is expected to grow at a compound annual growth rate of 14.4% from 2026 to 2033, reaching USD 7.6 billion by 2033
Large Enterprises segment accounted for the largest revenue share in 2025, while small & medium enterprises are the fastest growing during the forecast period.
Software segment dominated the market, with a revenue share of 64.4% in 2025. The software provides the infrastructure for deploying, creating, and managing financial products.
About the Author(s)
Next Generation Technologies Research Team
Technology · Next Generation TechnologiesThis report was authored by the next generation technologies research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the next generation technologies segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


