
- Home
- »
- Renewable Chemicals
- »
-
Biopolymers Market Size, Share & Trends Report, 2026-2033GVR Report cover

Biopolymers Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Bio-PE, Bio-PET), By End-use (Packaging, Consumer Goods), By Application (Films, Bottle, Vehicle Components), By Region, And Segment Forecasts
Market Size, 2025
$24.3BMarket Estimate, 2026
$27.9BMarket Forecast, 2033
$61.0BCAGR, 2026–2033
11.8%Biopolymers Market Summary
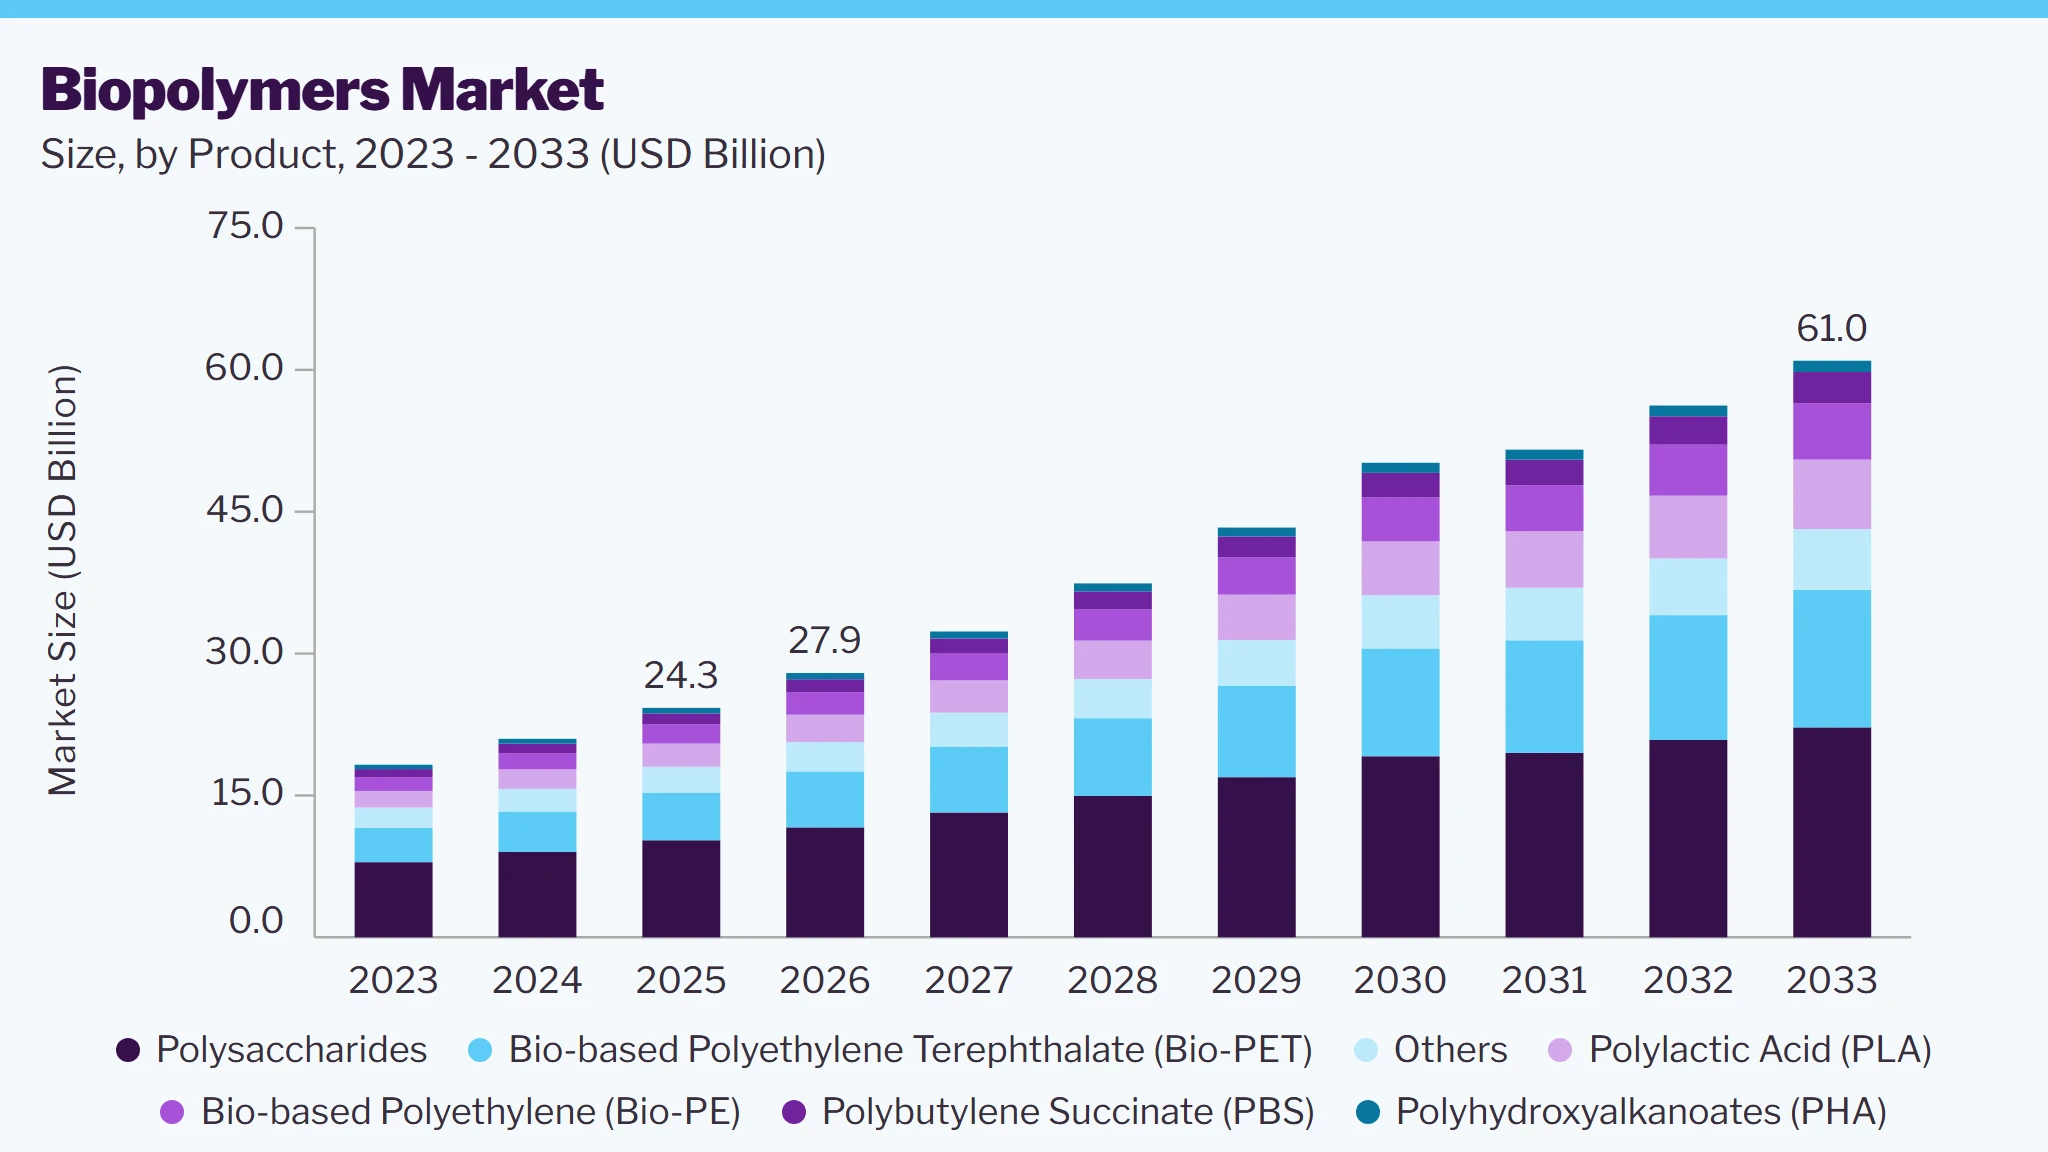
The global biopolymers market size was valued at USD 24.3 billion in 2025 and is projected to grow from USD 27.9 billion in 2026 to USD 61.0 billion by 2033, at a CAGR of 11.8% from 2026 to 2033. Europe dominated the market, accounting for a revenue share of 43.8% in 2025. Growing demand for sustainable packaging and increasing adoption of biodegradable materials across the packaging, food, pharmaceutical, and biomedical industries are driving the biopolymers market growth.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Polysaccharides segment dominated the market, with a revenue share of 42.3% in 2025.
- By end use: Films segment held the largest market share of 29.2% in 2025.
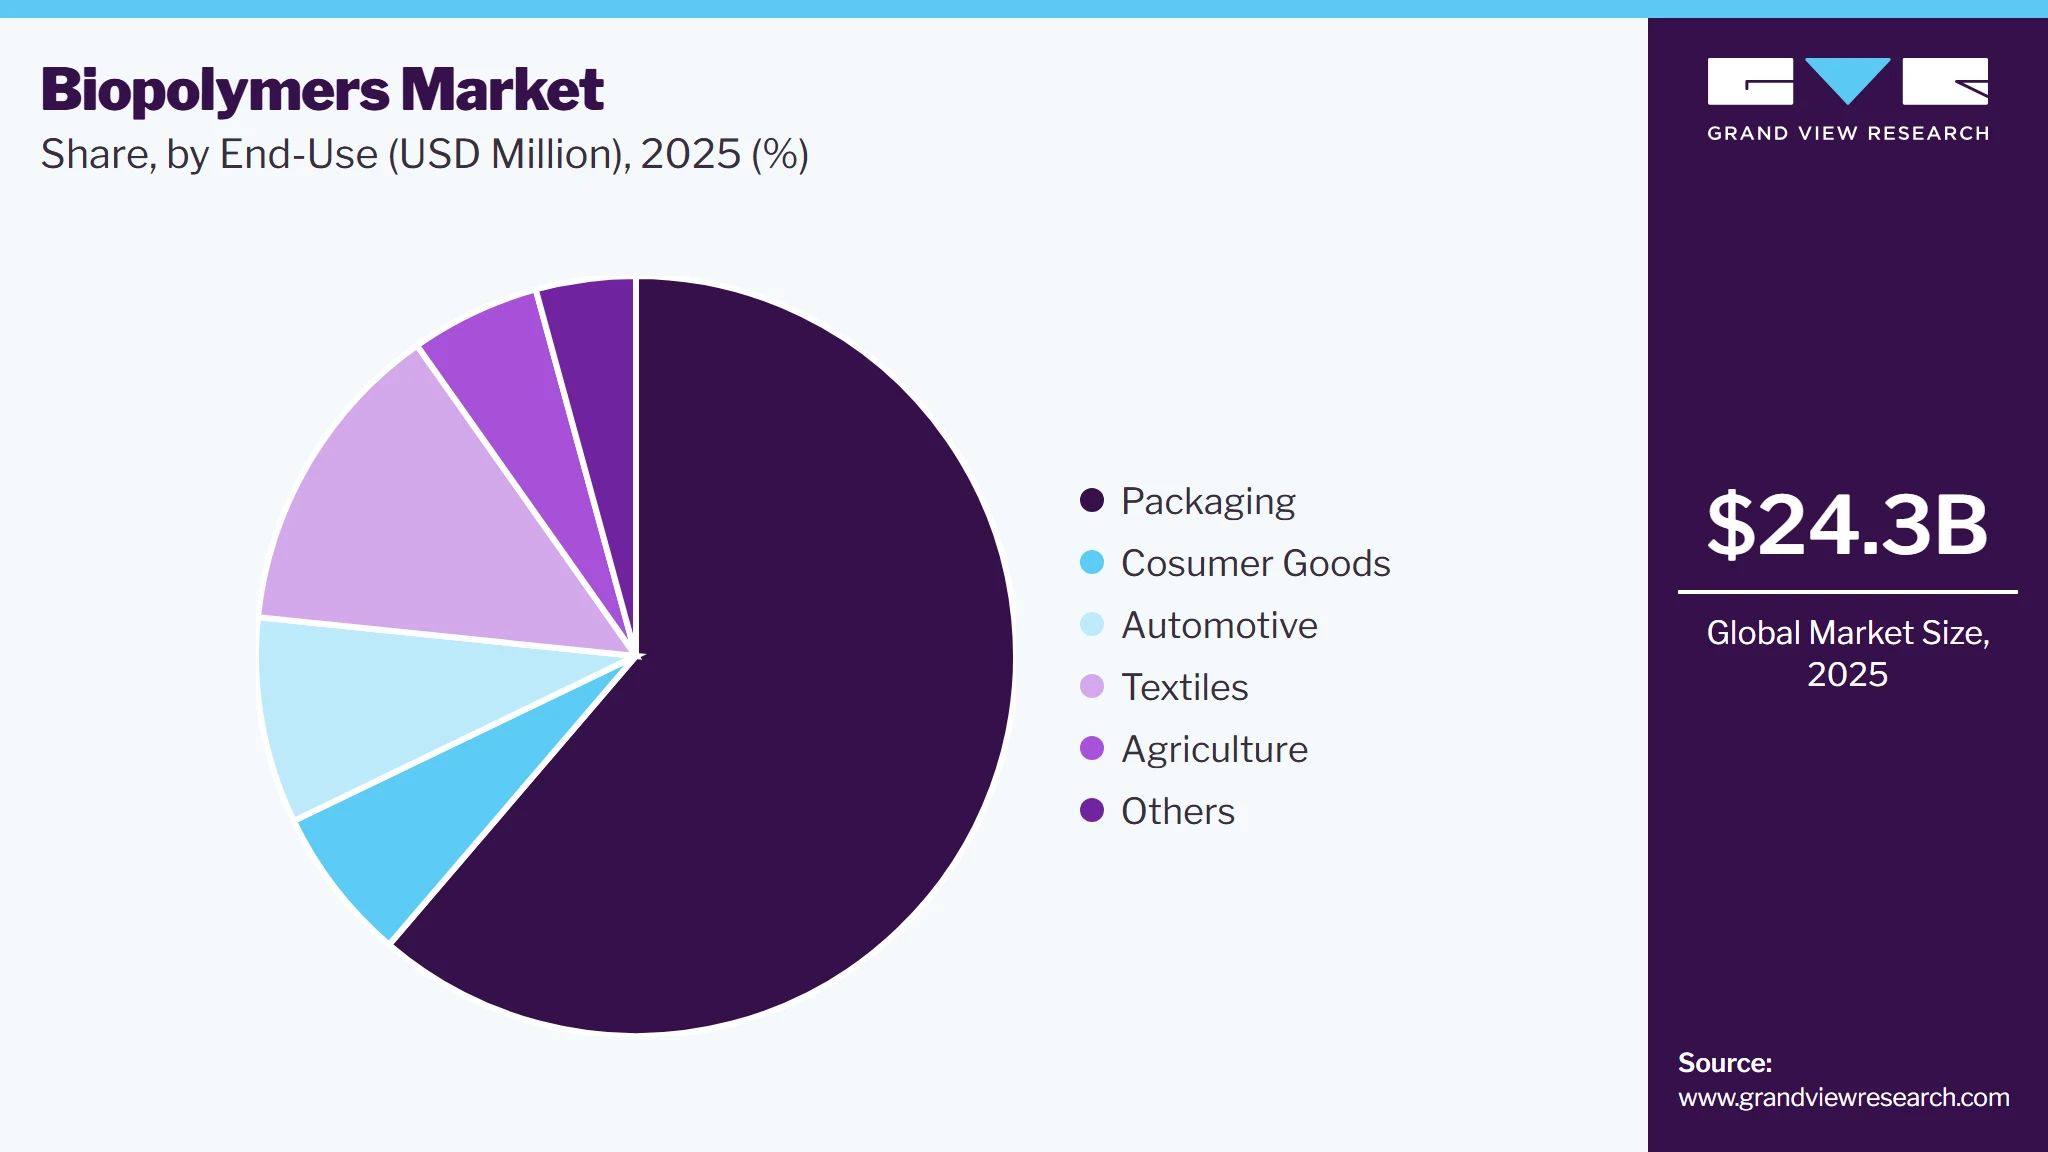
- By application: Packaging segment held the largest revenue share of 61.3% in 2025.
Regional Highlights
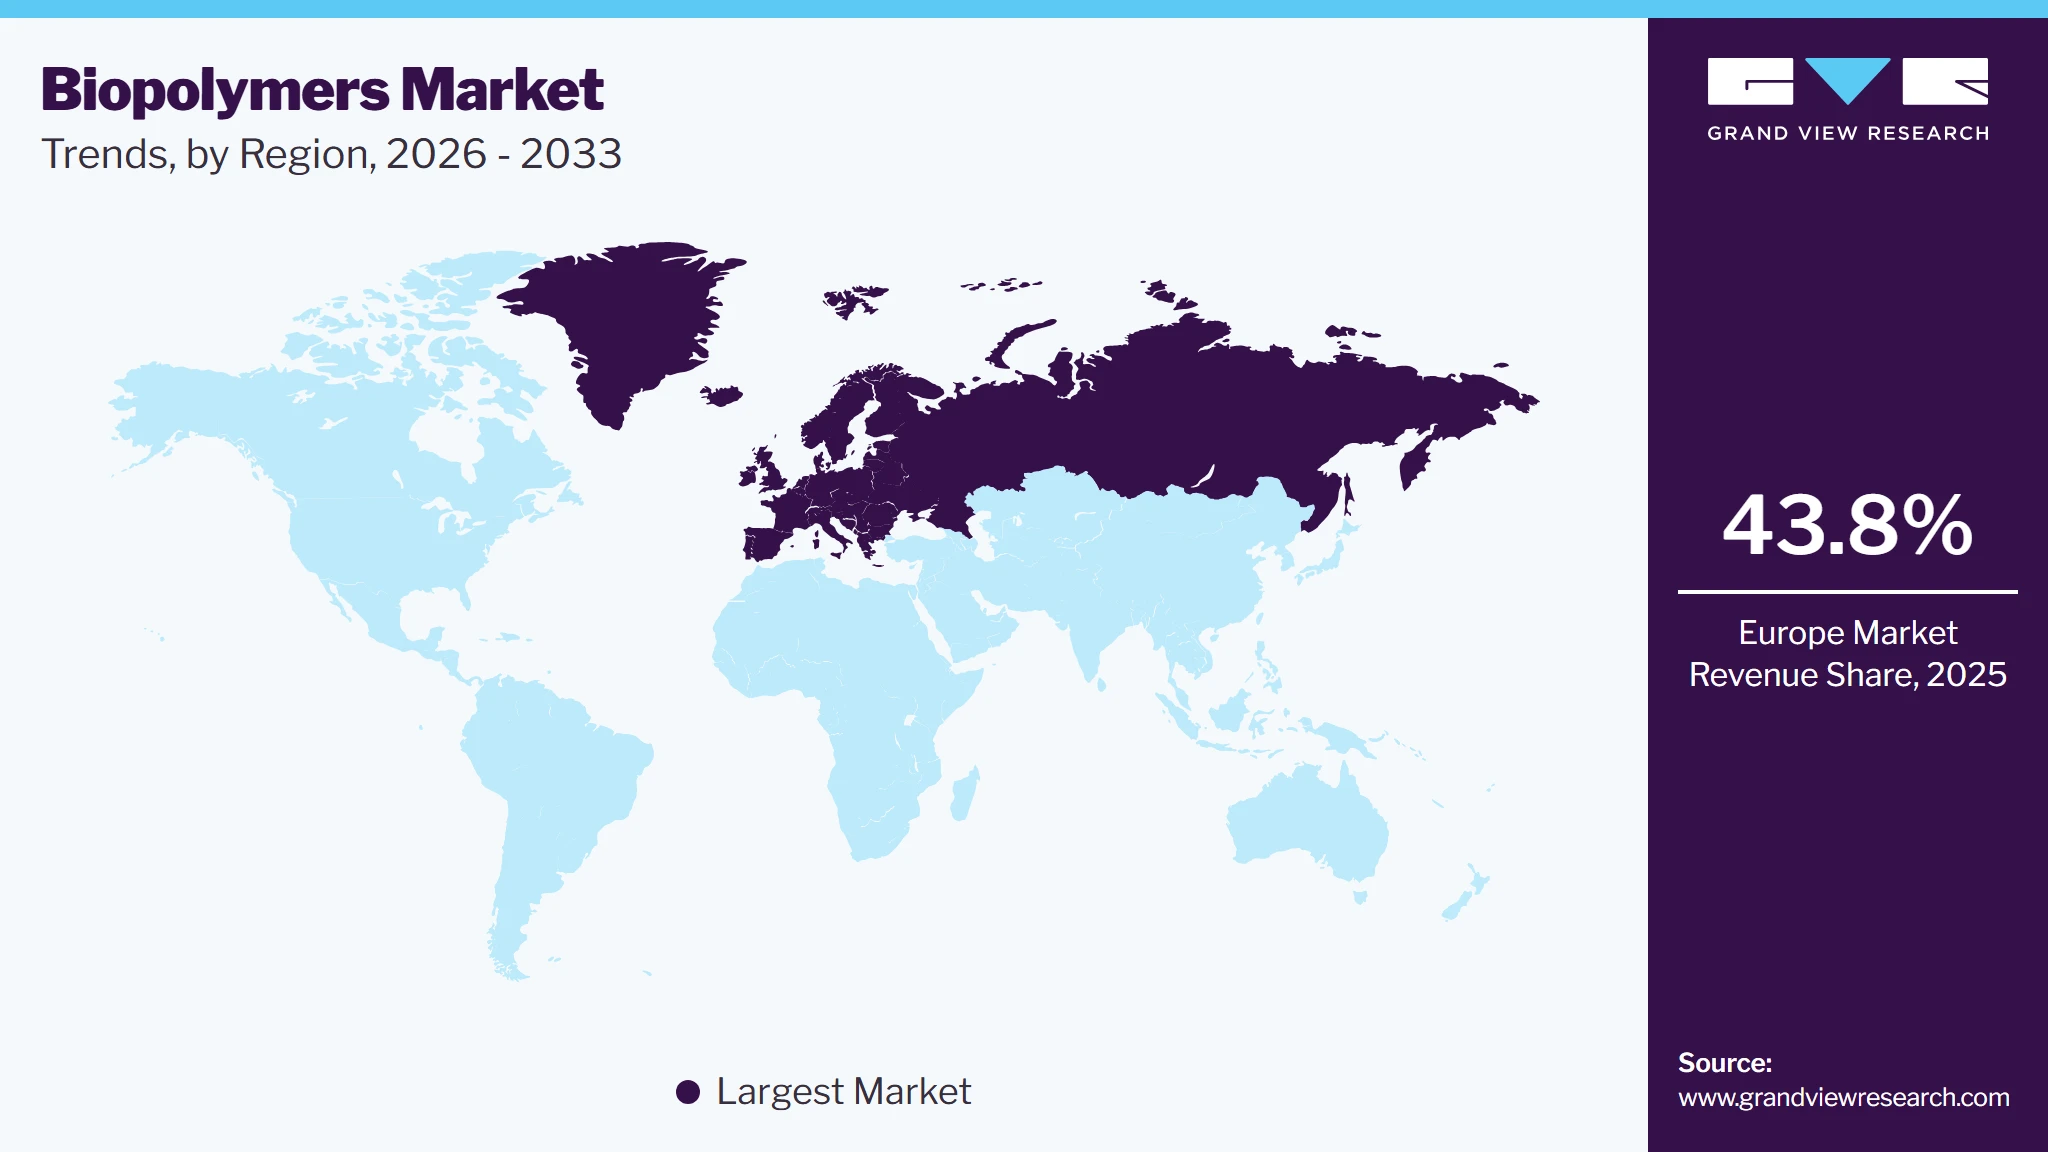
- Largest regional market: Europe (43.8% revenue share, 2025)
- By country: Germany held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 24.3 Billion
- Estimated market size in 2026: USD 27.9 Billion
- Projected market size by 2033: USD 61.0 Billion
- CAGR (2026-2033): 11.8%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Rising use of polyhydroxyalkanoates (PHA) in environmentally friendly plastics further supports demand. In addition, biopolymers are gaining wider acceptance in biomedical applications due to their excellent biocompatibility, biodegradability, and wound healing capabilities, strengthening long-term market expansion. Corresponding to the heightened demand for eco-friendly packaging from an extensive variety of end-use areas, major packaging and plastics manufacturing companies are shifting to biodegradable products. Biopolymers are engaged in an array of end-use applications, including biomedical, pharmaceuticals, and food. Because of their excellent recovery characteristics, they are in tremendous demand in biomedical applications, as they assist in the treatment of wounds of all shapes and sizes.
 To learn more about this report, Download Free Sample Report
According to the Ellen MacArthur Foundation (EMF), 78 million tons of single-use plastic packaging is manufactured yearly- of which under 2% is successfully recycled. Staggeringly, 32% of this product is poured out into the natural environment, as a result of insufficient processing and waste collection infrastructure. Given this realism, policymakers, manufacturing companies, and brands globally are examining techniques to remove the destructive pollution triggered by leakage and to improve recycling rates. Thus, there has been an enormous endeavor to foster packaging that can be recycled in numerous end-of-life environments. As a result, the demand for the product is subjected to strengthen rapidly.
Biopolymers are polymeric products derived from raw materials like sugarcane, and corn, as well as residual wood and standing timber. Biopolymers are biodegradable, in contrast to the conventional polymers or plastics, which results in global warming and pollution. The surge in perception of the usage of bio-based polymers is predicted. As a result, biopolymers are regarded as a more sustainable replacement to traditionally used petroleum-based plastics, because they can be broken down by natural methods and do not pose a risk to the ecosystem.
Customers are becoming extra sensible about their carbon footprint and are asking for more eco-friendly products. Administrations around the globe are also taking measures to decrease plastic waste by enforcing sanctions on single-use plastics and advocating the use of natural packaging solutions. This inclination is expected to continue over the forecasted period, as businesses and consumers become more responsive to the impact that conventional petrochemical-based plastics have on the ecosystem.
On the other hand, the elevated cost of manufacturing biopolymers is predicted to restrict market growth. Biopolymers are more expensive than conventional petroleum-based plastics. Bio-based ethylene, for instance, is more costly than petroleum-based ethylene. Regardless of strengthening customer pressure for renewable products as well as government regulation/ guidelines on the utilization of virgin plastics, the expansion of the biopolymer sector is being ‘held back’ by differences in product quality and costs.
Market Dynamics
The biopolymers market is shaped by rising replacement demand for conventional polyolefin and polyester packaging, especially in film and bottle formats where brand owners seek renewable, compostable, and lower-carbon material options. Demand is concentrated in packaging, with bottles and biodegradable polyester grades carrying strong commercial pull, while Asia Pacific remains the core demand base because of feedstock availability and manufacturing depth. The market is commercially structured around a limited set of major manufacturers pursuing cost-effective grades, new product launches, capacity expansion, M&A, and certifications, which keeps competition focused on scale, performance, and application specificity.
The strongest driver is the ongoing shift away from virgin plastics in packaging, supported by regulatory action, brand sustainability commitments, and recycling limitations that continue to expose the leakage problem in single-use formats. The report notes that packaging holds the largest end-use share and that biopolymers are increasingly adopted as renewable alternatives in response to consumer and policy pressure. This supports demand for bio-based films, bottles, and other packaging formats where recyclability, compostability, and lower environmental impact can be monetized through premium procurement channels.
A second layer of demand comes from the growing acceptance of biopolymers as functional materials rather than only sustainability substitutes. Bio-PE is gaining traction because it can be processed on existing polyethylene lines, while PLA and biodegradable polyesters are increasingly used in bottles, disposable tableware, biomedical devices, and textiles. This wider use case improves commercial pull because buyers can link environmental positioning with usable performance, and manufacturers can defend pricing through application-specific grades rather than commodity resin sales alone.
The main restraint is the persistent cost premium versus petroleum-based plastics, combined with uneven product quality across biopolymer families. The report explicitly notes that biopolymers remain more expensive than conventional plastics and that differences in quality and cost continue to hold back sector expansion. This creates a difficult commercial environment for converters and brand owners, especially in price-sensitive packaging where margins are narrow and substitution must be justified by regulation, procurement policy, or consumer-facing sustainability goals.
A clear opportunity lies in higher-value functional niches such as medical implants, controlled-release formats, and specialty packaging grades. The report highlights biopolymer uses in medical applications because some materials can biodegrade over time, remove the need for second surgery, and support temporary structural or drug-release functions. This opens a premium pathway beyond commodity substitution, particularly for suppliers that can combine biocompatibility, processing consistency, and regulatory validation.
Analyst Perspective
The biopolymers market is moving from early substitution toward a more disciplined value-led phase in which material performance, certification, and application fit will matter as much as sustainability positioning. Packaging and bottles will remain the primary demand center, but the next layer of growth is likely to come from premium films, fibers, medical applications, and other functional uses where buyers can justify a higher material cost through compliance or brand differentiation. The competitive field will favor producers with feedstock access, scalable manufacturing, application-specific grades, and credible sustainability credentials. Technology progress in PLA, Bio-PE, and PHA will help broaden the use base, while partnerships with converters and brand owners will become more important than simple resin capacity. The main headwinds will remain cost pressure, inconsistent performance across product families, and supply chain sensitivity tied to agricultural and renewable feedstock inputs.
End-use Insights
Based on end-use, the packaging segment led the market with the largest revenue share of 61.3% in 2025. The demand for biopolymers in packaging is increasing for several reasons, driven by environmental, regulatory, and consumer-driven factors. Biopolymers are often derived from renewable resources such as plants or bacteria, making them a more sustainable alternative to traditional petroleum-based plastics. The environmental impact of traditional plastics, particularly in terms of pollution and long degradation times, has led to increased interest in eco-friendly alternatives.
 To learn more about this report, Download Free Sample Report
Biopolymers are gaining traction in consumer goods for diverse reasons, mirroring a broader shift towards sustainability and environmental accountability in the consumer product sector. Governments and regulatory bodies across different regions are instituting measures to diminish plastic waste and endorse the utilization of more sustainable materials. This has established a regulatory landscape fostering the integration of the product into consumer goods.
In the automotive sector, biopolymers can be engineered to have favorable strength-to-weight ratios. By replacing traditional materials with lightweight biopolymers, vehicles can achieve weight reduction, contributing to improved fuel efficiency and reduced carbon emissions. In addition, advances in material science have led to the development of biopolymers with enhanced mechanical properties, durability, and heat resistance. These innovations make them more suitable for a wider range of automotive applications.
Application Insights
Based on application, the films segment led the market with the largest revenue share of 29.2% in 2025. This is attributable to the shift in the consumption trends regarding renewable/bio-based plastics. Biopolymers like PLA are being used increasingly in the manufacturing of bottles due to their eco-friendly nature.
In the medical sector, due to their biocompatibility, biopolymers are being extensively used. In addition, some biopolymers can be designed to biodegrade over time, eliminating the need for a second surgery to remove the implants. This property is beneficial where controlled drug release or temporary support is required. To sum up, the use of biopolymers is in alignment with the growing emphasis on materials that are eco-friendly, effective, and safe.
Biopolymers are often biocompatible, meaning they are well-tolerated by plant tissues. This compatibility can enhance the interaction between the coating and the seed, promoting successful germination and seeding development. Moreover, some biopolymers can be engineered to carry and release bioactive molecules and nutrients. These controlled release methods can provide essential elements to germinating seeds, thus supporting their initial growth rate.
Product Insights
Based on product, the polysaccharides segment led the market with the largest revenue share of 42.3% in 2025. This is attributed to environmental concerns and a growing emphasis on sustainable and eco-friendly practices in numerous end-use industries. In addition, biodegradable polyesters provide a solution to the end-of-life challenges associated with traditional plastics. Products made from biodegradable polyesters can be designed to break down naturally, reducing the need for long-term disposal and contributing to a circular economy.
Bio-polyethylene (Bio-PE) production typically results in lower greenhouse gas emissions when compared to traditional polyethylene. The cultivation of plants for feedstock absorbs CO2 from the atmosphere, contributing to a more favorable carbon footprint. Further, ongoing technological advancements have improved the production processes and properties of bio-PE, making it more viable for a boarder range of application areas.
Polylactic Acid (PLA) is a bio-based polymer, meaning it is not derived from fossil fuels. This reduces the dependency on non-renewable resources and aligns with the global shift towards sustainable and eco-friendly products. PLA has versatile properties due to which it is suitable for various applications like packaging, disposable tableware, biomedical devices, and textiles. Its adaptability contributes to its increasing demand across various end-use industries.
Regional Insights
Asia Pacific region accounted for the largest revenue share of around 37.25% in 2023. The region has abundant agricultural resources that can be used as feedstocks for the production of biopolymers. For example, sugarcane and corn, common raw materials for bio-based polymers/ plastics, are grown in significant quantities in this region, providing a sustainable source for the production of biopolymers.
Europe dominated the biopolymers market with the largest revenue share of 43.8% in 2025. Europe has been at the forefront of promoting a circular economy aiming to reduce waste and encourage recycling. Biopolymers, especially those that are biodegradable or compostable, align with these initiatives by offering sustainable alternatives to traditional plastics. In addition, the packaging industry in Europe has been actively adopting biopolymers to meet sustainability goals and address concerns related to single-use plastics. Biodegradable and bio-based packaging materials, including biopolymer alternatives, are gaining traction.
 To learn more about this report, Download Free Sample Report
There have been significant investments in North America in the production and development of biopolymers. This includes investment in research and development, new manufacturing facilities, and partnerships between companies to advance biopolymer technologies. In addition, while not as stringent as European regulations, North America has seen developments in regulations and guidelines promoting sustainable practices. These include measures at the state and federal levels aimed at reducing plastic waste and encouraging the use of biodegradable and bio-based materials. The biopolymers market in Germany accounted for the largest market revenue share in the Europe in 2025.
Key Companies & Market Share Insights
The development of cost-effective biopolymers is one of the major strategies undertaken by numerous manufacturing companies around the globe. In addition, major manufacturers dominate the market with various strategy initiatives such as product launches, expansion, mergers & acquisitions, and certifications for their products. For instance, in April 2023, NatureWorks introduced the latest ‘Ingeo’ biopolymer solution for increased strength and softness in biobased nonwovens for hygiene applications.
Key Biopolymers Companies
The following key companies have been profiled for this study on the biopolymers market.
-
Biopolymer Industries
-
BASF SE
-
Solanyl Biopolymers
-
BioPolymer GmbH & Co. KG
-
Ecovia Renewables Inc.
-
BiologiQ, Inc.
-
ADM
-
DuPont
-
Novamont
-
BIOTEC
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (BASF SE, ADM, DuPont, Novamont, BIOTEC)
- Build scale-led portfolios around cost-effective biopolymers and broader conversion compatibility.
- Use product launches, certifications, expansions, and partnerships to defend share in packaging-led demand.
- Reinforce downstream access through integrated supply chains and multinational distribution.
- Stronger capital base and manufacturing scale.
- Established market presence with better buyer trust and regulatory familiarity.
- Broader portfolio depth across industrial and packaging channels.
- Higher cost structure and slower pivoting into niche applications.
- Greater exposure to margin pressure in standardized resin grades.
- Less agility in serving small, customized demand windows.
Emerging Players (Biopolymer Industries, Solanyl Biopolymers, BioPolymer GmbH & Co. KG, Ecovia Renewables Inc., BiologiQ, Inc.)
- Target focused applications such as specialty packaging, niche blends, and local supply opportunities.
- Rely on partnerships, pilot programs, and application-led commercialization.
- Use lean structures to move faster on custom grades and customer trials.
- Faster product adaptation and shorter innovation cycles.
- Better fit for underserved or technical subsegments.
- More flexible positioning on sustainability-led customer requirements.
- Limited scale and weaker global distribution reach.
- Lower pricing power versus large integrated producers.
- Higher dependence on external feedstock, tolling, or selective customer contracts.
Biopolymers Market Report Scope
Report Attribute
Details
Market size in 2025
USD 24.3 billion
Estimated market size in 2026
USD 27.9 billion
Projected market size by 2033
USD 61.0 billion
Growth rate
CAGR of 11.8% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, volume in kilotons, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, application, end-use, region
Regional scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Netherlands; China; India; Japan; South Korea; Australia; Brazil; Argentina; Saudi Arabia; South Africa
Key companies profiled
Biopolymer Industries; BASF SE; Solanyl Biopolymers; BioPolymer GmbH & Co. KG; Ecovia Renewables Inc.; BiologiQ, Inc.; ADM; DuPont; Novamont; BIOTEC
Customization scope
Free report customization (equivalent to up to 8 analysts' working days) with purchase—addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Biopolymers Market Report Segmentation
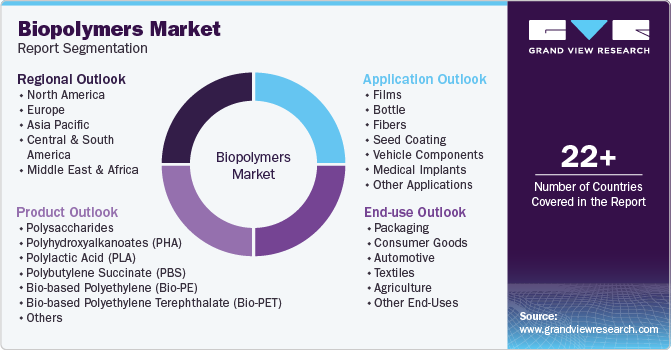
This report forecasts revenue & volume growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global biopolymers market report based on product, application, end-use, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Polysaccharides
-
Cellulose Acetate
-
Others
-
-
Polyhydroxyalkanoates (PHA)
-
Polylactic Acid (PLA)
-
Polybutylene Succinate (PBS)
-
Bio-based Polyethylene (Bio-PE)
-
Bio-based Polyethylene Terephthalate (Bio-PET)
-
Others
-
-
Applications Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Films
-
Bottle
-
Fibers
-
Seed Coating
-
Vehicle Components
-
Medical Implants
-
Other Applications
-
-
End-use Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Packaging
-
Consumer Goods
-
Automotive
-
Textiles
-
Agriculture
-
Other End-Uses
-
-
Region Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Arabia
-
South Africa
-
-
Research Methodology
The biopolymers market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each biopolymers segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Product
Revenue capture definition
Polysaccharides
Revenue is captured through sales of cellulose acetate-led and related polysaccharide grades into films, coatings, molded parts, and specialty biodegradable applications where renewable content and processability are critical.
Polyhydroxyalkanoates (PHA)
Revenue is generated through premium biodegradable resin sales into packaging, agriculture, and medical uses where compostability, performance, and regulatory positioning justify a higher price point.
Polylactic Acid (PLA)
Revenue is captured through resin sales to bottle, film, fiber, disposable tableware, biomedical, and textile converters that need renewable input and broad commercial processing compatibility.
Polybutylene Succinate (PBS)
Revenue is earned through compostable resin sales into flexible packaging, films, and molded articles where flexibility, biodegradability, and end-of-life compliance are commercial buying factors.
Bio-based Polyethylene (Bio-PE)
Revenue is captured through drop-in polyethylene replacement sales to packaging and consumer goods converters using conventional PE infrastructure but seeking lower-carbon material sourcing.
Bio-based Polyethylene Terephthalate (Bio-PET)
Revenue is generated through bottle-grade and fiber-grade bio-PET sales to beverage, textile, and packaging converters that want renewable PET parity without changing existing downstream conversion systems.
Others
Revenue includes specialty blends, niche bio-based copolymers, pilot-scale grades, and application-specific resins sold into residual commercial channels that do not fit the core product families.
Application
Revenue capture definition
Films
Revenue is generated through sale of resin and conversion-grade materials for flexible and industrial film applications, especially where compostability, sealability, and renewable content drive buyer selection.
Bottle
Revenue is captured through bottle-grade resin supply for beverage, personal care, and food-contact packaging, where clarity, stiffness, and sustainability claims support premium positioning.
Fibers
Revenue is earned through fiber-grade polymer sales into textile, nonwoven, hygiene, and specialty fabric applications where renewable content and processing stability support conversion economics.
Vehicle Components
Revenue is captured through material sales for lightweight interior and non-structural automotive parts where reduced mass, design flexibility, and sustainability credentials are commercially relevant.
Medical Implants
Revenue is generated through biocompatible, biodegradable grades used in temporary implants, controlled support devices, and related medical applications that require validated performance and regulatory compliance.
Others
Revenue includes seed coating, tableware, specialty agricultural, and other niche application sales that support smaller but commercially distinct demand pools.
End-Use
Revenue capture definition
Packaging
Revenue is captured through supply to rigid and flexible packaging converters, with the largest value pool tied to food, beverage, and consumer packaging that can absorb sustainable material premiums.
Consumer Goods
Revenue is generated through sales to household and personal product manufacturers that use biopolymers for sustainable casing, disposables, and branded consumer-facing materials.
Automotive
Revenue is captured through sales into vehicle lightweighting programs, where material substitution is justified by durability, weight reduction, and emissions-related design objectives.
Textiles
Revenue is earned through fibers, nonwovens, and specialty textile inputs that support renewable-content positioning and performance-led material replacement.
Agriculture
Revenue is generated through mulch films, seed-related coatings, and controlled-release solutions that benefit from biodegradability and soil compatibility.
Others
Revenue includes biomedical, pharmaceutical, and other specialty end-uses where application value is driven by functional performance rather than volume scale.
Estimation Model
Layer No.
Layer Name
Key Question
Description
1
Regional Demand Layer
Why prioritize regional demand?
This layer anchors the forecast by region because the report shows Asia Pacific as the leading demand base and North America and Europe as important commercial centers.
2
Product Mix Layer
Why assess product mix?
This layer separates value by resin family because biodegradable polyesters, PLA, and Bio-PE monetize differently depending on price, performance, and application fit.
3
Application Conversion Layer
Why analyze application demand?
This layer captures revenue by use case because bottles, films, fibers, and medical uses have different conversion intensity and realization levels.
4
End-Use Validation Layer
Why validate end-use demand?
This layer reconciles buyer behavior across packaging, consumer goods, automotive, textiles, and agriculture to avoid overlap and preserve commercial accuracy.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Country level demand view
The report can be expanded to include country-wise biopolymers demand across the United States, China, Germany, India, and Brazil, with separate commentary on packaging-led consumption and feedstock-linked supply concentration.
Improves regional commercialization planning and highlights the most attractive demand pockets.
Application profitability lens
The report can include a margin-oriented view across films, bottles, fibers, vehicle components, and medical implants, showing where premium pricing and technical barriers improve revenue capture.
Helps identify the most commercially resilient end-use channels.
Company benchmarking
The report can be extended with a company comparison matrix covering product focus, market presence, strategic initiatives, and application exposure for the profiled biopolymer manufacturers.
Strengthens competitive positioning analysis and helps identify share-building opportunities.
Frequently Asked Questions About This Report
Some of the key players in the global biopolymers market include Biopolymer Industries; BASF SE; Solanyl Biopolymers; BioPolymer GmbH & Co. KG; Ecovia Renewables Inc.; BiologiQ, Inc.; ADM; DuPont; Novamont; BIOTEC
Biopolymers are polymeric products derived from raw materials like sugarcane, and corn, as well as residual wood and standing timber. The surge in perception of the usage of bio-based polymers is predicted. As a result, biopolymers are regarded as a more sustainable replacement to traditionally used petroleum-based plastics, because they can be broken down by natural methods and do not pose a risk to the ecosystem.
The biopolymers market size was valued at USD 24.3 billion in 2025 and is estimated at USD 27.9 billion in 2026.
Based on product, the polysaccharides segment led the market with the largest revenue share of 42.3% in 2025. This is attributed to environmental concerns and a growing emphasis on sustainable and eco-friendly practices in numerous end-use industries.
Based on application, the films segment led the market with the largest revenue share of 29.2% in 2025. This is attributable to the shift in the consumption trends regarding renewable/bio-based plastics.
Based on end-use, the packaging segment led the market with the largest revenue share of 61.3% in 2025.
The global biopolymers market is expected to grow at a CAGR of 11.8% from 2026 to 2033, reaching USD 61.0 billion by 2033.
Europe dominated the biopolymers market with the largest revenue share of 43.8% in 2025.
About the Author(s)
Renewable Chemicals Research Team
Specialty & Chemicals · Renewable ChemicalsThis report was authored by the renewable chemicals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the renewable chemicals segment of the specialty & chemicals industry. All findings are based on proprietary specialty & chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


