
- Home
- »
- Nutraceuticals & Functional Foods
- »
-
Canada Liquid Dietary Supplements Market Report, 2033GVR Report cover

Canada Liquid Dietary Supplements Market (2026 - 2033)
Size, Share & Trends Analysis Report By Ingredients (Vitamins, Botanicals, Minerals, Proteins & Amino Acids, Fibers & Specialty Carbohydrates), By Type, By Application, By End-use, By Distribution Channel, And Segment Forecasts
Market Size, 2025
$232.2MMarket Estimate, 2026
$254.4MMarket Forecast, 2033
$462.1MCAGR, 2026–2033
8.9%Canada Liquid Dietary Supplements Market Summary
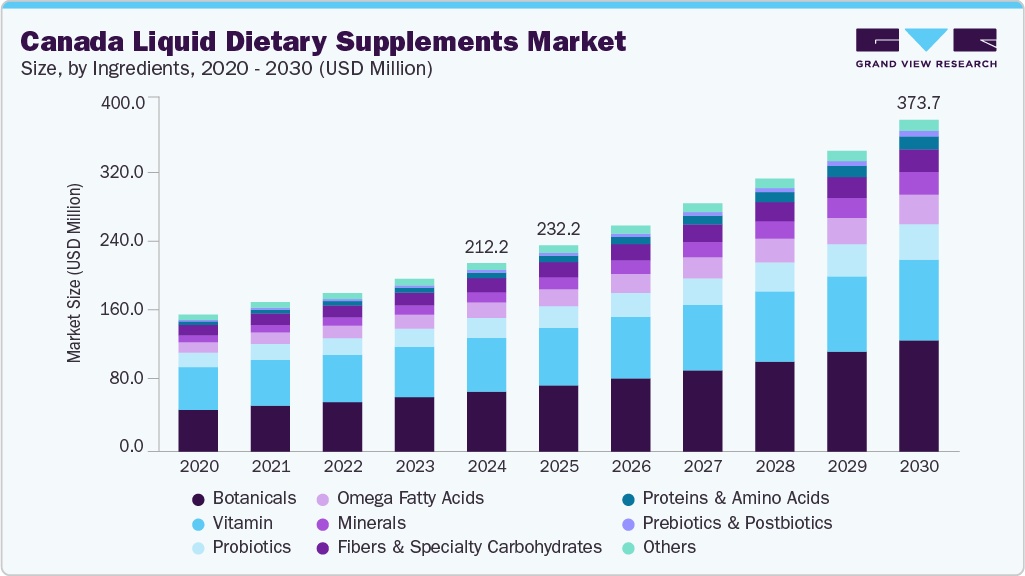
The Canada liquid dietary supplements market size was valued at USD 232.2 million in 2025 and is projected to grow from USD 254.4 million in 2026 to USD 462.1 million by 2033, at a CAGR of 8.9% from 2026 to 2033. The market's growth is driven by rising health consciousness among the population, many older adults seeking solutions for healthy aging, and changing consumer preferences toward convenient, easily digestible liquid formats of dietary supplements. In addition, the strong trend towards preventive healthcare and increased accessibility through various distribution channels, especially online platforms, drives the market’s continued expansion.
Key Market Trends & Insights
- By ingredient: Botanicals led the market and accounted for a share of 30.8% in 2025.
- By type: OTC led the market and accounted for a share of 76.2% in 2025.
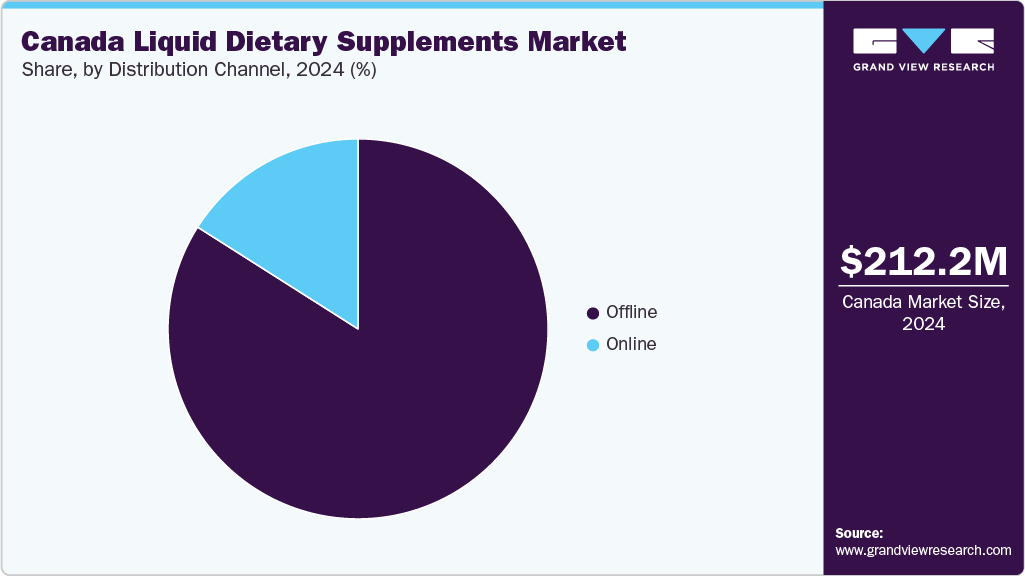
- By distribution channel: Offline segment led the market and accounted for a share of 83.5% in 2025.
Market Size & Forecast
- Market Size in 2025: USD 232.2 Million
- Estimated market size in 2026: USD 254.4 Million
- Projected Market Size by 2033: USD 462.1 Million
- CAGR (2026-2033): 8.9%
Prism AI by Grand View Research Free to tryAsk a question about the canada liquid dietary supplements marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →Canadian consumers are actively seeking proactive health management solutions, driving greater demand for dietary supplements that support overall well-being and preventive care. This raised awareness is evident in the growing consumers’ interest in products that can boost immunity, enhance energy levels, and address specific nutritional gaps. Furthermore, the increasing accessibility of these products through online retail and the rising demand for plant-based and clean-label alternatives are significantly contributing to the expansion of the Canada liquid dietary supplements industry.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Furthermore, the rising consumer preference for convenient and easily digestible liquid formats is a vital factor driving the market's growth. Liquid supplements offer various advantages, such as quicker absorption and ease of consumption, particularly appealing to a wider demographic, including those who face difficulties with pills or prefer ready-to-drink options. For instance, in February 2025, New Chapter vitamin and supplement company introduced its liquid-based multivitamin. This new product, "Liquid Multivitamin," contains 22 essential vitamins and minerals, providing comprehensive wellness support. Liquid Multivitamin is formulated to cater to the entire family, offering age-appropriate dosages for both adults and children aged two and above from a single bottle. The company’s products are available in Canada through various retailers and dealer partnerships.
Market Dynamics
Liquid supplements are increasingly moving beyond conventional vitamins and minerals toward multifunctional wellness products that combine hydration, electrolytes, vitamins, minerals, and amino acids. This broadens the role of liquid supplementation from basic nutrient replacement to products tailored to specific everyday needs, such as exercise, travel, heat exposure, recovery, and general wellness. The ability to combine several functional ingredients in a single serving also gives manufacturers greater scope to differentiate liquid products through targeted formulations.
In August 2025, Liquid I.V. introduced its Sugar-Free Hydration Multiplier in Canada, marking the company's first sugar-free offering for Canadian consumers. The launch demonstrates how supplement manufacturers are extending beyond traditional vitamin-focused formulations by combining multiple functional ingredients within a convenient, single-serving format.
Liquid supplements require manufacturers to maintain tighter controls over sanitation, equipment, storage, stability, batch consistency, and quality assurance. Health Canada's GMP framework specifically covers premises, equipment, sanitation, operations, quality assurance, stability, batch samples, records, and recall procedures for NHP manufacturers.
The additional controls can make liquid production more operationally demanding than simpler solid formats. Manufacturers must maintain consistent ingredient concentration throughout the liquid, manage appropriate storage conditions, and ensure that the finished product continues to meet specifications during its stated shelf life. This can increase production and quality-assurance costs and impose greater operational requirements on companies seeking to scale their liquid supplement portfolios.
Liquid multivitamins can go beyond basic nutrient replacement by combining a broader range of vitamins, minerals, and functional ingredients into a single formulation. This gives manufacturers an opportunity to position liquid products as comprehensive daily wellness solutions while differentiating them through nutrient density, ingredient quality, and multiple benefit claims.
Analyst Perspective
The Canada liquid dietary supplements market is moving beyond traditional vitamin supplementation toward convenience-led, function-specific formats, where liquids can command greater consumer relevance through faster integration into daily routines, targeted wellness benefits, and easier consumption. The key competitive advantage will not simply be product breadth, but the ability to combine clinically credible formulations, clean-label positioning, precise dosing, and differentiated delivery formats while building strong omnichannel access. As Canadian consumers increasingly evaluate supplements based on efficacy, ingredient transparency, and convenience, brands that convert liquid delivery from a dosage format into a premium wellness experience are best positioned to capture value and defend pricing.
Consumer Insights
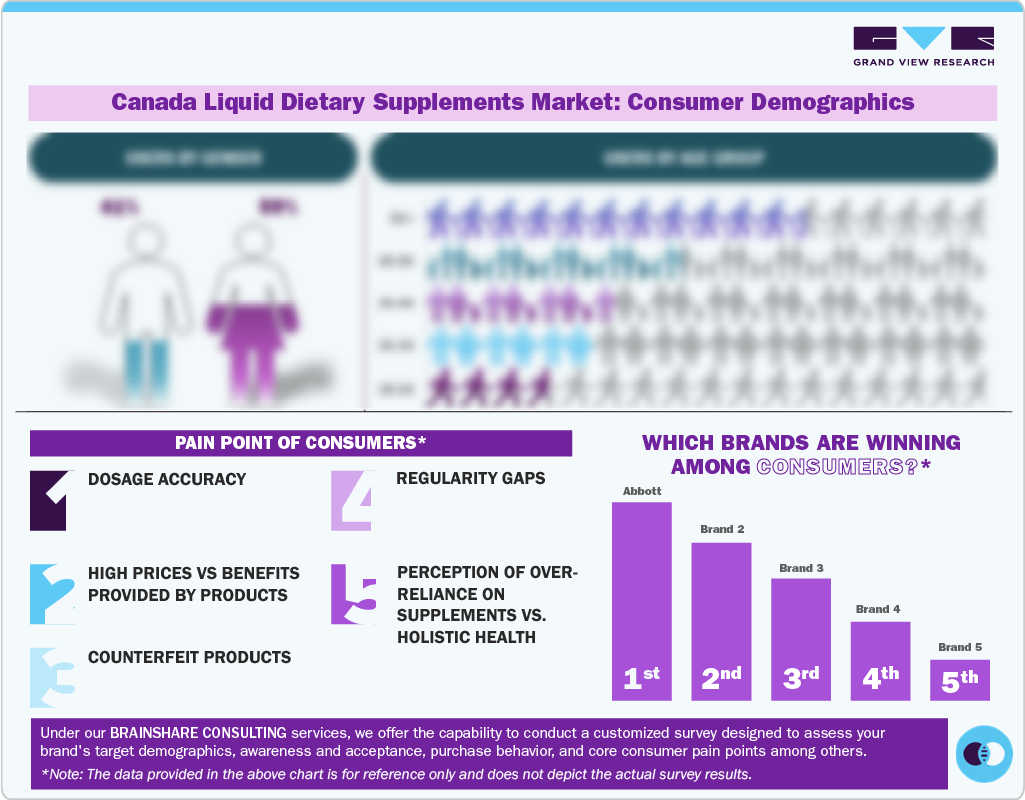
Consumers in Canada show broad acceptance of natural health products, creating a strong underlying consumer base for liquid dietary supplements. Health Canada reports that 71% of Canadians have used natural health products, including vitamins and minerals, herbal products, probiotics, amino acids, and other products that can be offered in liquid forms such as drops, solutions, and tinctures. Consumer adoption also varies across demographic groups. NielsenIQ indicates that 85% of Canadian consumers regularly think about their health and wellness, while 52% are actively taking steps to improve it, highlighting continued engagement with preventive health and everyday wellness. This creates a favorable environment for supplements positioned around specific nutritional needs, including immunity, digestive health, energy, hydration, and healthy aging. These patterns indicate opportunities for liquid supplements targeting specific life stages and wellness requirements, particularly among consumers already familiar with supplementation. Product information and transparency are also becoming important considerations in purchasing.
 To learn more about this report, Download Free Sample Report
Furthermore, consumer insights reveal a growing preference for liquid supplements due to their inherent convenience, portability, and pleasant consumption experience. Busy lifestyles and the need for efficient, on-the-go nutritional solutions drive this shift away from traditional pills and powders. In June 2025, BioSteel, a Canadian sports nutrition brand, launched its first Ready-to-Drink protein beverage, providing 30 grams of clean protein per 330 mL bottle, free from sugar, lactose, and preservatives. This launch is expected to enhance consumer demand for clean-label options in Canada liquid dietary supplements industry.
Ingredients Insights
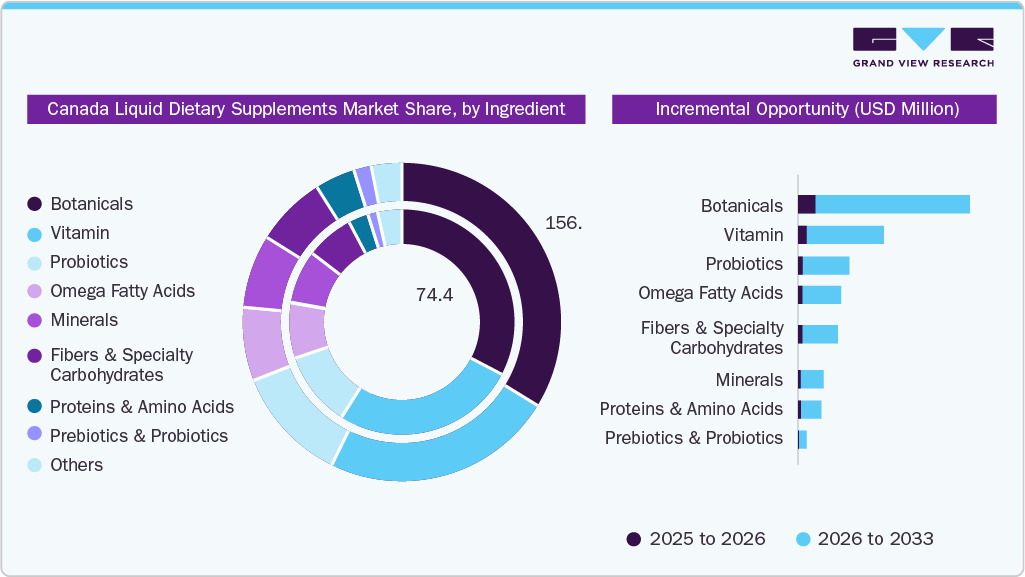
The botanicals segment dominated the Canada liquid dietary supplements market and accounted for a revenue share of 30.8% in 2025. This prominence is driven by increasing consumer preference for natural and plant-derived health solutions. Botanicals offer a range of perceived health benefits, from immune support and stress management to improved digestion and overall wellness. In January 2024, dsm-firmenich collaborated with Italy-based Indena to launch science-backed botanical ingredient solutions addressing consumer demand for natural, effective health products. This strategic alliance combined expertise to deliver innovative formulations targeting immunity, brain health, and more, marking a new era in nutraceutical innovation. It enables dsm-firmenich to enhance liquid supplement offerings with high-potency, great-tasting botanical solutions tailored to modern consumer preferences. dsm-firmenich has a strong presence in Canada, offering a variety of its products in the country.
 To learn more about this report, Download Free Sample Report
The proteins & amino acids segment is expected to witness the fastest growth of 12.6% in Canada's liquid dietary supplements industry during the forecast period. This growth is fueled by increasing consumer interest in muscle health, active lifestyles, and healthy aging. The demand among fitness enthusiasts is rising for convenient, ready-to-drink products that provide high-quality protein sources and functional amino acids to support muscle recovery, endurance, and overall performance. In May 2024, Lactalis Canada launched Enjoy!, a high-protein plant-based beverage line. Featuring oat, almond, and hazelnut variants with 8g of pea protein per serving, the line addressed the rising demand for nutritious, unsweetened, dairy-free options with clean labels and sustainable packaging.
Type Insights
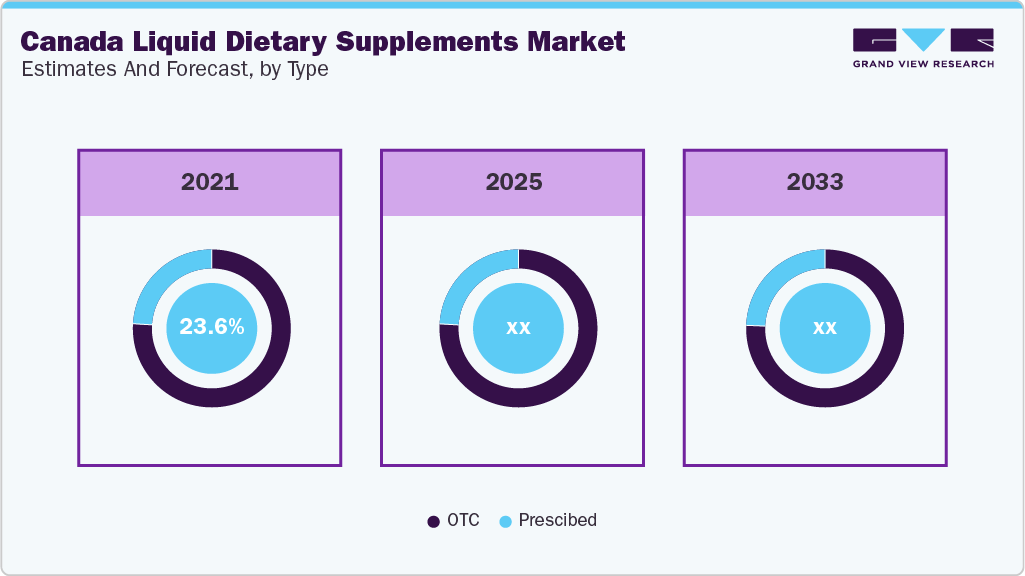
The OTC segment accounted for the largest revenue share of 76.2% in 2025. This segment's prevalence is attributed to the widespread consumer preference for easily accessible, non-prescription products that support general health and wellness. OTC liquid supplements, such as multivitamin blends, botanical extracts, and protein-based drinks, are commonly available in pharmacies, health food stores, and online platforms. These make them convenient for consumers seeking to address health concerns such as immunity, digestive health, and energy levels. In January 2024, Nature’s Way Brands, LLC launched its PROTALITY high-protein nutrition shake in North America, targeting adults pursuing weight loss and muscle preservation. This strategic introduction expands Nature’s Way Brands, LLC's presence in the over-the-counter liquid dietary supplement market, potentially impacting the competitive landscape in Canada through increased consumer awareness and demand for similar products in retail and online channels.
 To learn more about this report, Download Free Sample Report
The prescribed liquid dietary supplements segment is expected to grow at the fastest CAGR of 9.1% from 2026 to 2033. This growth is driven by an increasing recognition of the need for specialized nutritional support in managing chronic conditions and age-related health issues. Healthcare professionals typically recommend these supplements to address specific deficiencies or health concerns, offering higher concentrations of active ingredients tailored to individual needs.
Application Insights
The immunity segment held a significant share of 10.9% in 2025, supported by continued consumer interest in nutrients and botanical ingredients associated with immune function. Canada's seasonal conditions and limited sunlight exposure during parts of the year also support demand for supplementation, particularly vitamin D; Health Canada recommends daily vitamin D supplementation for Canadians when dietary intake is insufficient. Liquid formulations provide an additional advantage for consumers seeking easy-to-administer products, particularly in vitamin and mineral combinations.
The prenatal health segment is expected to grow at the fastest CAGR of 12.6% from 2026 to 2033, driven by a high degree of awareness for maternal nutrition and the importance of supplementation during pregnancy. Products such as DHA and folic acid-enriched liquid supplements are gaining popularity among expectant mothers seeking convenient and effective ways to support fetal development and maternal health.
End-use Insights
The adults segment accounted for the largest market share of 63.3% in 2025. This demand reflects the widespread engagement of adult consumers in managing their general health, supporting active lifestyles, and addressing age-related nutritional needs. This segment benefits from various product offerings, including liquid multivitamins for comprehensive wellness, protein-based drinks for muscle support, and specialized formulations targeting cognitive function and immunity.
The infants segment is anticipated to grow at the fastest CAGR of 9.7% during the forecast period. According to Statistics Canada, approximately 3.5 lakh children are born every year in Canada. This consistent demographic inflow heightened parental awareness of crucial early-life nutrients, and strong healthcare recommendations for infant supplementation create sustained market demand. This convergence of factors underpins the segment's impressive expansion.
Distribution Channel Insights
The offline segment held the largest revenue share of 83.5% in 2025. The offline distribution channel remains dominant due to the well-established presence of pharmacies, health stores, and supermarkets nationwide. For instance, Shoppers Drug Mart Inc. is one of the leading pharmacy retailers, with over 1300 stores in Canada and approximately 18 million registered customers across Canada. The extensive network and high foot traffic of such major retailers provide unparalleled convenience and immediate product availability, fostering a strong consumer preference for in-person purchases and contributing significantly to the continued strength of the offline segment.
 To learn more about this report, Download Free Sample Report
The online distribution segment is expected to experience the fastest CAGR of 10.6% from 2026 to 2033. The increasing consumer inclination towards e-commerce for convenience, wider product variety, and home delivery options has accelerated growth in this channel. New product developments and digital-first launches are increasingly targeted at online platforms to capture tech-savvy and health-conscious consumers. Additionally, digital marketing initiatives and subscription-based models are helping brands build strong consumer engagement and loyalty through online channels, driving significant growth in this segment.
Key Canada Liquid Dietary Supplements Company Insights
The Canada liquid dietary supplements market remains fragmented, with competition shaped by portfolio breadth, liquid-format manufacturing capabilities, ingredient expertise, regulatory compliance, distribution reach, and brand trust rather than dependence on a single product category. Leading players are expanding their offerings across vitamins, minerals, botanicals, proteins, amino acids, probiotics, and specialized nutritional formulations, while increasingly developing products focused on immunity, healthy aging, sports nutrition, digestive health, and preventive wellness.
 To learn more about this report, Download Free Sample Report
Key Canada Liquid Dietary Supplements Companies
-
CanPrev Premium Health Products Ltd.
-
Bioforce Canada Inc.
-
Seroyal International Inc.
-
Nature’s Way Brands, LLC
-
SALUS HAUS GMBH & CO. KG
-
Organika Health Products Inc.
-
APHINA INC.
-
St. Francis Herb Farm Inc.
-
Nutralab Canada Corp.
-
Land Art Inc.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (CanPrev Premium Health Products Ltd.; Bioforce Canada Inc.; Seroyal International Inc.; Nature’s Way Brands, LLC; Organika Health Products Inc.; APHINA INC.; St. Francis Herb Farm Inc.)
• Mature players leverage broad nutrition portfolios, established R&D capabilities, regulatory expertise, and extensive distribution networks to expand caffeine-based formulations across energy, sports nutrition, and wellness applications.
• Strong brand recognition, established customer relationships, product-development capabilities, and broad channel access support faster commercialization and portfolio expansion.
• Large portfolio structures can limit agility in responding to niche caffeine trends, while premium positioning and complex regulatory requirements can increase product-development costs.
Emerging Players (SALUS HAUS GMBH & CO. KG; NutraLab Canada Corp.; Land Art Inc.)
• Emerging players focus on specialized formulations, natural ingredients, convenient delivery formats, and flexible product development to target specific energy, wellness, and active-lifestyle needs.
• Greater formulation flexibility, niche positioning, and faster response to changing consumer preferences enable differentiation against larger supplement companies.
• Smaller distribution footprints, lower brand recognition, and comparatively limited resources for large-scale R&D, marketing, and market expansion constrain their competitive reach.
Recent Developments
- In March 2025, New Chapter launched its first Liquid Multivitamin, a family-oriented liquid supplement containing 22 essential vitamins and minerals, including fermented B vitamins, vitamins C and K, and organic superfoods. The formulation is designed for adults and children aged 2 years and above and supports multiple wellness areas, including immune function, cellular energy, heart, bone, brain, hair, skin, nail, and digestive health.
Canada Liquid Dietary Supplements Market Report Scope
Report Attribute
Details
Market size in 2025
USD 232.2 million
Estimated market size in 2026
USD 254.4 million
Projected market size by 2033
USD 462.1 million
Growth rate
CAGR of 8.9% from 2026 to 2033
Actual data
2021 - 2025
Forecast data
2026 - 2033
Quantitative units
Revenue in USD million, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, trends
Segments covered
Ingredients, type, application, end-use, distribution channel
Key companies profiled
CanPrev Premium Health Products Ltd.; Bioforce Canada Inc.; Seroyal International Inc.; Nature’s Way Brands, LLC; SALUS HAUS GMBH & CO. KG; Organika Health Products Inc.; APHINA INC.; St. Francis Herb Farm Inc.; Nutralab Canada Corp.; Land Art Inc.
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Canada Liquid Dietary Supplements Market Report Segmentation
This report forecasts revenue growth at the country level and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the Canada liquid dietary supplements market report based on ingredients, type, application, end-use, and distribution channel:
-
Ingredients Outlook (Revenue, USD Million, 2021 - 2033)
-
Vitamin
-
Multivitamin
-
Vitamin A
-
Vitamin B
-
Vitamin C
-
Vitamin D
-
Vitamin K
-
Vitamin E
-
-
Botanicals
-
Minerals
-
Calcium
-
Potassium
-
Magnesium
-
Iron
-
Zinc
-
Others (Selenium, Chromium, Copper)
-
-
Proteins & Amino Acids
-
Collagen
-
Others
-
-
Fibers & Specialty Carbohydrates
-
Omega Fatty Acids
-
Probiotics
-
Prebiotics & Postbiotics
-
Others
-
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
OTC
-
Prescribed
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Bone & Joint Health
-
Gastrointestinal Health
-
Immunity
-
Cardiac Health
-
Diabetes
-
Anti-cancer
-
Lungs Detox/Cleanse
-
Skin/ Hair/ Nails
-
Sexual Health
-
Brain/Mental Health
-
Insomnia
-
Menopause
-
Anti-aging
-
Prenatal Health
-
Others
-
-
End-use Outlook (Revenue, USD Million, 2021 - 2033)
-
Adults
-
Millennials
-
Male
-
Female
-
Pregnant Women
-
Non-pregnant Women
-
-
-
Gen X
-
Male
-
Female
-
Pregnant Women
-
Non-pregnant Women
-
-
-
Gen Z
-
Male
-
Female
-
Pregnant Women
-
Non-pregnant Women
-
-
-
Boomers
-
Male
-
Female
-
-
-
Geriatric
-
Children
-
Infants
-
-
Distribution Channel Outlook (Revenue, USD Million, 2021 - 2033)
-
Offline
-
Hypermarkets/Supermarkets
-
Pharmacies
-
Specialty Stores
-
Practitioner
-
Others (Direct to Consumer, MLM)
-
-
Online
-
Amazon
-
Other Online Retail Stores
-
-
Research Methodology
The Canada liquid dietary supplements marketfigures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with eachCanada liquid dietary supplementssegment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Distribution Channel
Revenue capture definition
Online
This segment includes sales of liquid dietary supplements through digital channels such as brand websites, online marketplaces, and e-commerce platforms. Revenue is generated through direct-to-consumer websites, online retail stores, and marketplace purchases.
Offline
This segment includes sales of liquid dietary supplements through physical retail and healthcare channels such as hypermarkets/supermarkets, pharmacies, specialty stores, practitioner channels, and other retail outlets. Revenue is generated through in-store purchases, with consumers benefiting from physical product access.
Segment - Type
Revenue capture definition
OTC
This segment includes the sales of liquid dietary supplements available directly through pharmacies, retail stores, and online channels. Revenue is generated through products targeting general nutritional support, immunity, energy, and wellness needs.
Prescribed
This segment includes the sales of liquid dietary supplements recommended or prescribed by healthcare professionals for specific nutritional requirements. Revenue is generated through clinically guided supplementation for targeted deficiencies and health-related needs.
Estimation Model
Epidemiology Layer
Market Access Layer
Adoption Layer
Revenue Generation Layer
Who uses liquid dietary supplements?
Who can access liquid supplements?
Who actively purchases liquid supplements?
How is market revenue generated?
Identify the addressable Canadian population consuming vitamins, minerals, herbal supplements, amino acids, probiotics, and other liquid NHPs for health maintenance and wellness.
Apply Canada-specific retail, pharmacy, specialty-store, and e-commerce penetration rates to the eligible consumer pool, accounting for Health Canada’s NHP licensing framework.
Apply liquid-supplement usage and purchase rates across adults, children, geriatric consumers, and health-focused groups to convert reachable consumers into active users.
Multiply active users by average annual spending on liquid dietary supplements across OTC and prescribed products, incorporating retail, pharmacy, specialty-store, and online sales.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Canada Liquid Dietary Supplements Consumer & Benefit Landscape
Assessed consumer preferences across immunity, digestive health, energy, healthy aging, sports nutrition, and general wellness, including preferred ingredients, dosage formats, flavor profiles, and clean-label attributes.
Helps identify high-demand benefit areas and refine product positioning for priority Canadian consumer groups.
Canada Liquid Dietary Supplements Product & Innovation Assessment
Analyzed liquid formats such as ready-to-drink supplements, liquid drops, shots, concentrates, syrups, and single-dose formats, along with emerging formulations including botanical, vitamin, mineral, protein, and functional blends.
Supports portfolio expansion, format prioritization, and identification of whitespace opportunities for product innovation.
Canada Liquid Dietary Supplements Pricing & Premiumization Landscape
Benchmarked pricing across mainstream and premium liquid supplements based on ingredient complexity, dosage concentration, functional claims, format, pack size, and brand positioning.
Enables pricing strategy development, premiumization assessment, and identification of attractive price-value gaps.
Frequently Asked Questions About This Report
Online distribution channel is the fastest growing segment with a CAGR of 10.6% from 2026 to 2033.
By end-user, adults accounts for the largest market share of 63.3% in 2025.
Key market players include Amway, Nestle, Herbalife Ltd., Abbott, DUOLIFE S.A., Pfizer Canada, BASF, Bayer AG, Nutralab Canada Corp., Land Art
The market's growth is driven by growing health consciousness among the population, many older adults seeking solutions for healthy aging and changing consumer preference toward convenient and easily digestible liquid formats of dietary supplements.
The OTC type segment leads the market accounting a share of 76.2% in 2025.
By application, prenatal health segment is the fastest growing segment with a CAGR of 12.6% from 2026 to 2033.
Botanicals segment leads the Canada dietary supplements market accounting a share of 30.8% in 2025.
The Canada liquid dietary supplements market was valued at USD 232.2 million in 2025 and is estimated at USD 254.4 million in 2026.
The Canada liquid dietary supplements market is expected to grow at a CAGR of 8.9% from 2026 to 2033, reaching USD 462.1 million in 2033.
About the Author(s)
Nutraceuticals & Functional Foods Research Team
Consumer Goods · Nutraceuticals & Functional FoodsThis report was authored by the nutraceuticals & functional foods research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the nutraceuticals & functional foods segment of the consumer goods industry. All findings are based on proprietary consumer goods databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


