
- Home
- »
- Consumer F&B
- »
-
Canada Premium Bottled Water Market Size Report, 2033GVR Report cover
![Canada Premium Bottled Water Market (2026 - 2033)Report]()
Canada Premium Bottled Water Market (2026 - 2033)
Size, Share & Trend Analysis Report By Product (Still Water, Sparkling Water), By Price Point (Premium, Super- Premium), By Packaging Type (Glass, Cans), By Distribution Channel, By Pack Size, By Pack Type, And Segment Forecasts
Market Size, 2025
$3.9BMarket Estimate, 2026
$4.2BMarket Forecast, 2033
$6.2BCAGR, 2026–2033
5.6%Canada Premium Bottled Water Market Summary
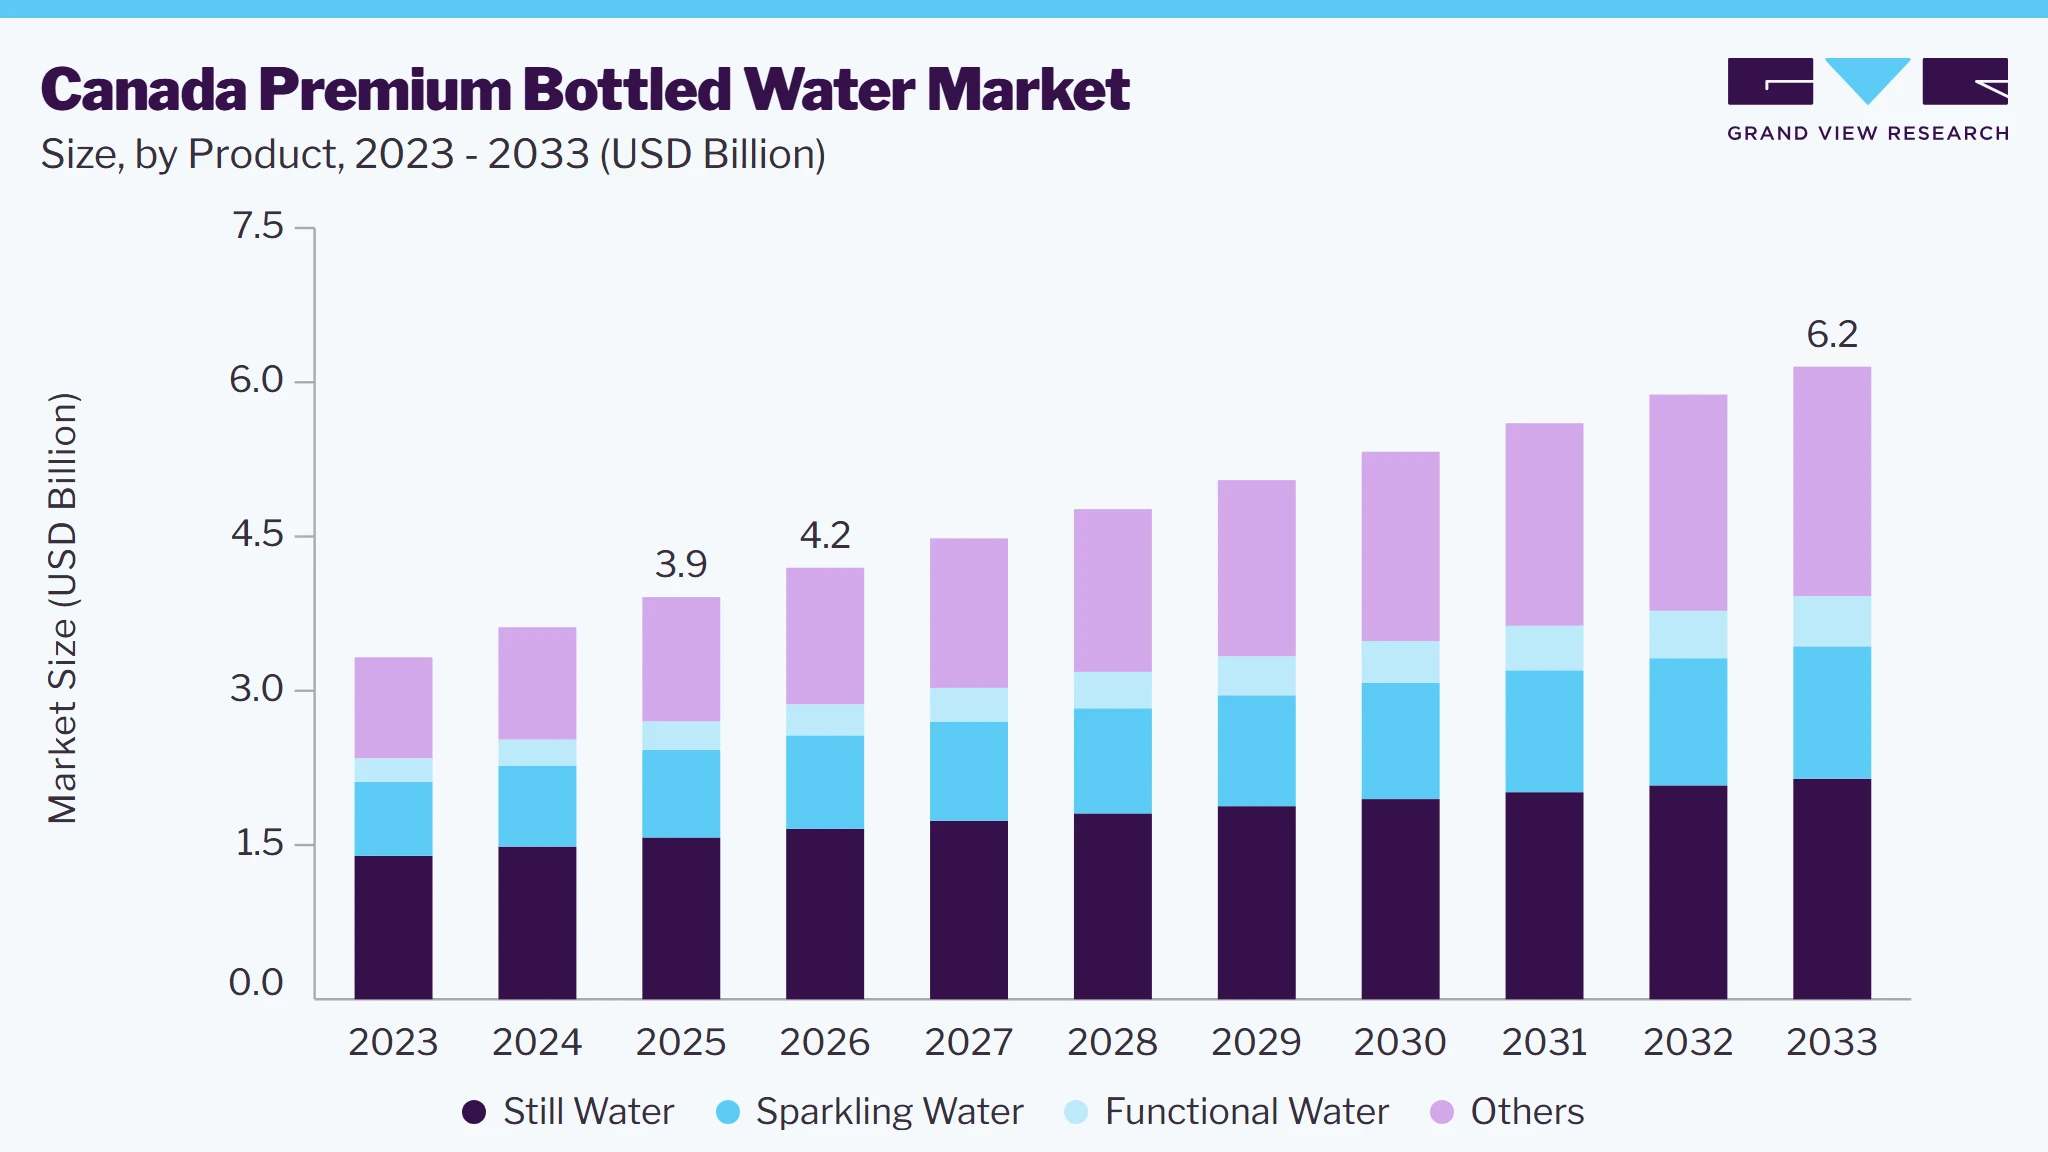
The Canada premium bottled water market size was valued at USD 3.9 billion in 2025 and is expected to grow from USD 4.2 billion in 2026 to USD 6.2 billion by 2033, at a CAGR of 5.6% from 2026 to 2033. The market is witnessing increasing demand as consumers place greater emphasis on wellness, distinctive water sources, and premium product experiences. Brands are strengthening their market positioning through differentiated mineral profiles, sparkling and functional offerings, sophisticated packaging, and sustainability-focused formats.
Key Market Trends & Insights
- By product: Still water led the Canada premium bottled water market and accounted for a share of 40.2% in 2025.
- By price point: Premium bottled water market accounted for a share of 60.5% in 2025.
- By packaging type: PET bottles led the market and accounted for a share of 56.0% in 2025.
- By distribution channel: Off-premise dominated the Canada premium bottled water market, accounting for a 59.8% share in 2025.
- By pack size: Upto 500ml of premium bottled water is projected to register highest CAGR of 6.1% in the forecast period.
- By pack type: Multi pack premium bottled water is projected to register the fastest CAGR of 6.0% from 2026 to 2033.
Key Market Trends & Insights
- Market Size in 2025: USD 3.9 Billion
- Estimated Market Size in 2026: USD 4.2 Billion
- Projected Market Size by 2033: USD 6.2 Billion
- CAGR (2026-2033): 5.6%
Three ways to get this report
Buy it, customize it, or ask a question.Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Ask an Analyst
A direct answer, usually in 1 working day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Canada consumers are increasingly shifting toward premium bottled water as health, wellness, convenience, and product quality become stronger purchasing considerations. Demand is supported by interest in products perceived to offer greater purity, distinctive mineral profiles, natural or protected sources, and added functional benefits compared with conventional bottled water. Functional waters containing electrolytes, minerals, vitamins, and other wellness-oriented ingredients are gaining traction among health- and fitness-conscious consumers seeking more than basic hydration. For instance, in August 2026, Canadian wellness brand Organika launched Sparkling Electrolytes, its first ready-to-drink beverage, combining electrolytes, magnesium glycinate, and prebiotic fibre in a zero-sugar, grab-and-go format, highlighting the industry's shift toward convenient and functional hydration. Portability also keeps bottled water relevant across commuting, travel, exercise, dining, and other on-the-go occasions.
The growing emphasis on sustainability and product transparency is also influencing purchasing behavior. Consumers are paying greater attention to packaging materials, recyclability, water sourcing, and environmental credentials, encouraging premium brands to explore recycled PET, glass, aluminum, and other alternative formats. Premium water is also becoming increasingly associated with lifestyle and social experiences, particularly across restaurants, hotels, resorts, fitness facilities, and luxury events.
Market Dynamics
The Canada premium bottled water industry is benefiting from growing demand for health-focused and higher-value hydration products, as consumers increasingly prioritize purity, natural mineral content, taste, and wellness attributes when making purchase decisions. This shift is expanding the category beyond conventional hydration toward premium, functional, and lifestyle-oriented products, particularly sparkling and flavored waters that serve as alternatives to sugar-containing beverages. For instance, in April 2026, Flow expanded its Canadian offering with Flow Sparkling, a range of Canadian mineral spring waters featuring naturally occurring minerals and electrolytes, with zero sugar, zero calories, and no sweeteners across Original, Lemon + Ginger, Wild Berry, and Cucumber + Mint variants. The launch reflects how manufacturers are leveraging clean-label formulations, functional attributes, flavor innovation, and premium positioning to align with evolving consumer expectations.
Canada's Food and Drug Regulations, Division 12 - Prepackaged Water and Ice, establish specific requirements for packaged water, including source, treatment, microbiological safety, product classification, and labeling. In particular, mineral and spring water must originate from qualifying underground sources and meet prescribed compositional standards, while labels must disclose source location, dissolved mineral content, and fluoride levels. These requirements can increase testing, documentation, labeling, and compliance costs for premium bottled-water manufacturers, particularly brands differentiated by mineral composition and natural source claims.
The Canada premium bottled water industry presents attractive opportunities through functional product development and packaging innovation. Manufacturers can differentiate their portfolios with electrolyte- and mineral-enhanced waters, premium sparkling and flavored variants, and clean-label formulations aligned with evolving wellness preferences. At the same time, adopting recyclable, recycled, aluminum, and lower-plastic packaging solutions can strengthen brand differentiation and address growing environmental expectations. The market also offers scope for occasion-based positioning across fitness, travel, dining, and workplace consumption. By integrating functional benefits, distinctive taste profiles, convenience, and sustainability into a single value proposition, brands can support premium pricing, increase consumer trade-up, and unlock incremental growth in the Canadian premium hydration segment.
Analyst Perspective
The Canada premium bottled water market is shifting beyond basic hydration toward health, wellness, quality, convenience, and premium lifestyle consumption. Purchasing decisions are increasingly influenced by factors such as purity, mineral composition, source provenance, taste, functional benefits, and distinctive packaging. Sustainability is also gaining importance, with greater attention to recyclable materials, recycled-content packaging, and circular water systems. At the same time, premium brands must demonstrate clear value as higher price points can limit adoption relative to conventional bottled or filtered water. Market participants are therefore emphasizing product innovation, sustainable packaging, Canadian and natural sourcing, functional offerings, strategic partnerships, and premium brand experiences to strengthen differentiation and capture evolving demand.
Consumer Insights
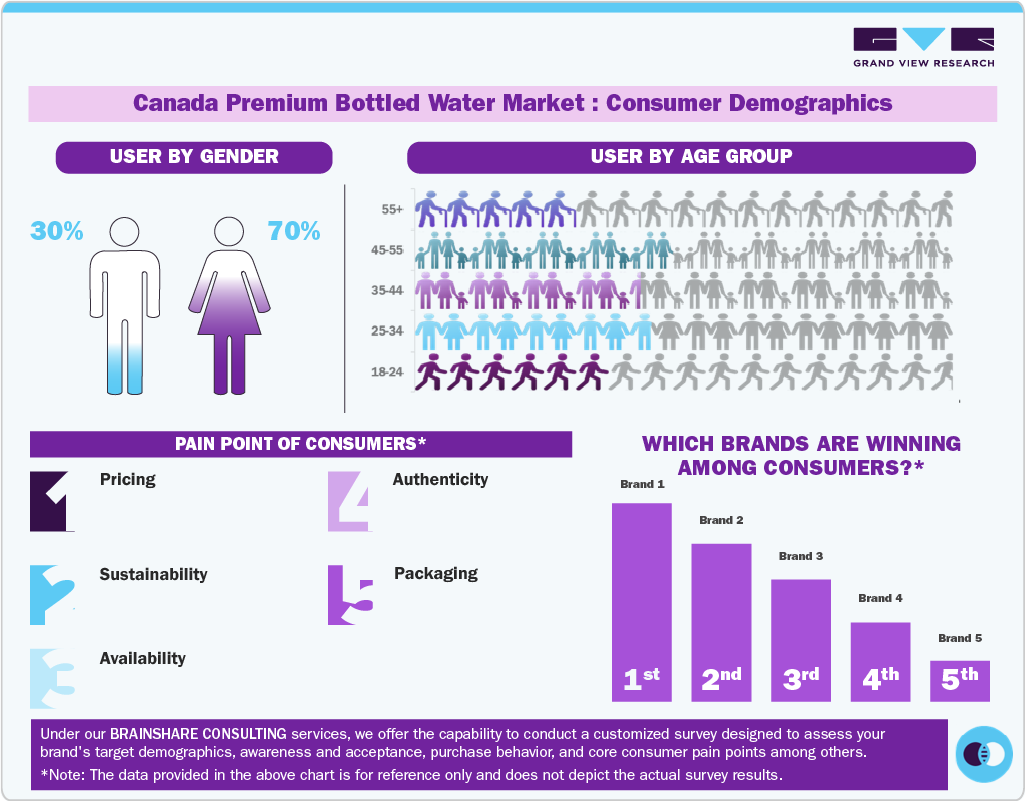
Canadian consumers are increasingly trading up to premium bottled water as hydration becomes linked with health, lifestyle, and product quality. Natural sourcing, purity, taste, mineral profile, and brand credibility are key purchase triggers, with consumers seeking water that offers a differentiated experience beyond basic hydration. Demand is also supported by the shift toward healthier beverage choices, as consumers favor mineral, spring, sparkling, and functional waters over sugary drinks. Convenience remains a core driver, particularly for single-serve formats suited to commuting, travel, fitness, workplaces, and dining. Sustainability is becoming a stronger purchase consideration, encouraging preference for recyclable, recycled, and lower-plastic packaging. At the premium end, consumers also respond to transparent sourcing, attractive packaging, brand story, and perceived authenticity, which help justify higher price points. Overall, the category is being shaped by consumers who seek a combination of quality, wellness, convenience, and sustainability, with premium water increasingly positioned as a lifestyle product rather than a basic hydration necessity.
Product Insights
Still water accounted for the largest share of the Canada premium bottled water market, representing 40.2% of revenue in 2025. The market is driven by its broad acceptance as a convenient and versatile hydration option. Consumer demand remains strong across daily consumption, travel, workplaces, fitness, dining, and hospitality, where still water fits seamlessly into multiple consumption occasions. Within the premium segment, purchasing is further supported by consumer interest in natural sources, purity, mineral composition, taste, and brand authenticity. The segment’s established consumer familiarity and suitability for both routine and premium consumption occasions continue to reinforce its leading position in the Canadian premium bottled water market.
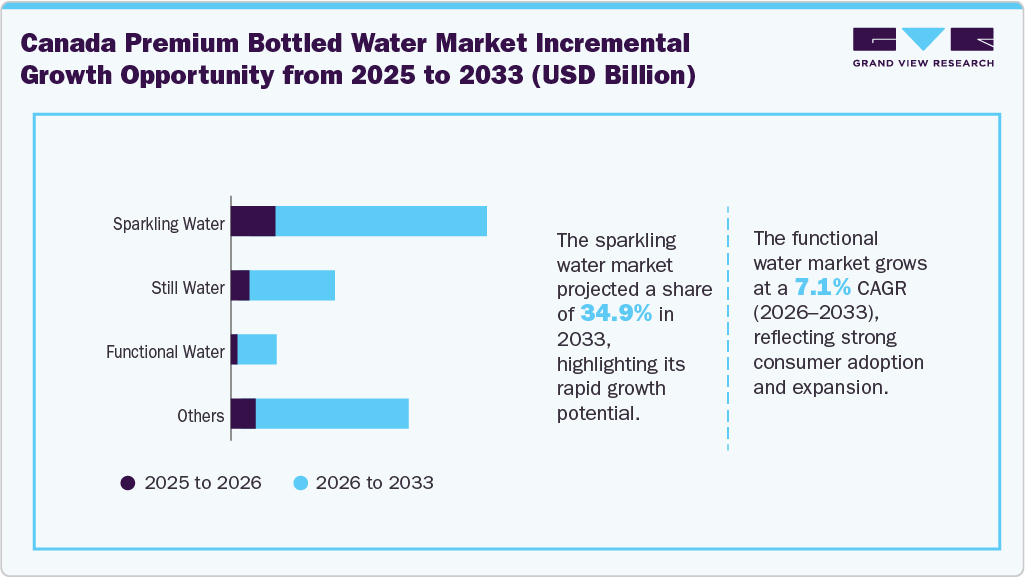
Functional premium bottled water is projected to record the fastest CAGR of 7.1% from 2026 to 2033, supported by rising demand for hydration products that deliver added wellness value beyond conventional thirst relief. Increasing consumer focus on active lifestyles, daily wellness, and preventive health is driving interest in formulations enriched with electrolytes, minerals, vitamins, and other functional ingredients. The segment is further benefiting from the growing preference for low- and zero-sugar beverage options, positioning functional water as a healthier substitute for traditional soft drinks. These trends are encouraging brands to expand functional offerings and strengthen premium positioning through health benefits, clean-label formulations, and convenient consumption formats.
Price Point Insights
By price point, the premium bottled water accounted for the largest share representing 60.5% of total revenue in 2025. The market is supported by consumers’ willingness to pay more for superior taste, natural sourcing, purity, mineral composition, and distinctive brand positioning. Demand is increasingly influenced by premiumization trends, as bottled water is being positioned as a lifestyle and wellness product rather than a basic hydration commodity. Consumers also place greater value on attractive packaging, source transparency, brand heritage, and sustainability credentials, particularly across dining, hospitality, travel, and on-the-go consumption occasions. The segment continues to benefit from product differentiation through premium spring and mineral waters, sparkling variants, sophisticated packaging, and wellness-oriented propositions, enabling brands to command higher price points and strengthen consumer perceived value.
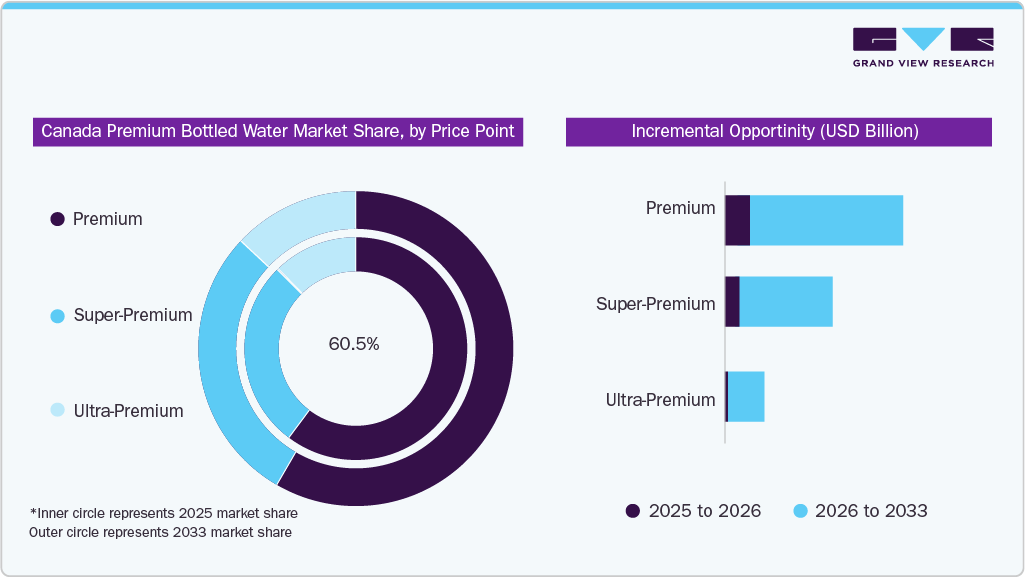
The ultra-premium bottled water market is projected to record the fastest CAGR of 6.4% from 2026 to 2033. The market is driven by increasing consumer interest in exclusive, differentiated, and experience-led hydration products. Demand is being supported by consumers who place greater value on distinctive water sources, natural mineral profiles, provenance, sophisticated packaging, and strong brand narratives. The segment is also benefiting from premium consumption occasions across fine dining, luxury hospitality, travel, and upscale retail, where product presentation and brand prestige influence purchasing decisions. Growing willingness among affluent consumers to trade up for products perceived as authentic, high-quality, and environmentally responsible is creating additional momentum. Manufacturers are responding through limited-edition offerings, distinctive bottle designs, premium sourcing, and sustainability-focused packaging, strengthening the segment’s ability to command higher price points and capture incremental consumer spending.
Packaging Type Insights
By packaging type, PET bottle held the largest share of the Canada premium bottled water industry, accounting for 56.0% of total revenue in 2025. Leading position is supported by the transport efficiency, durability, portability, cost-effectiveness, and reliability of PET packaging, making it suitable for repeated consumption across travel, work, fitness, and everyday hydration occasions. PET also benefits from established distribution across grocery, convenience, foodservice, and other high-volume retail channels. Canada’s evolving recycled-content requirements are further supporting the transition toward more sustainable PET solutions, with applicable beverage bottles required to contain at least 20% recycled content from 2026-27, increasing to 40% in 2028-29 and 60% by 2030. These requirements encourage greater adoption of recycled PET while allowing brands to retain the convenience and functional advantages of PET packaging.
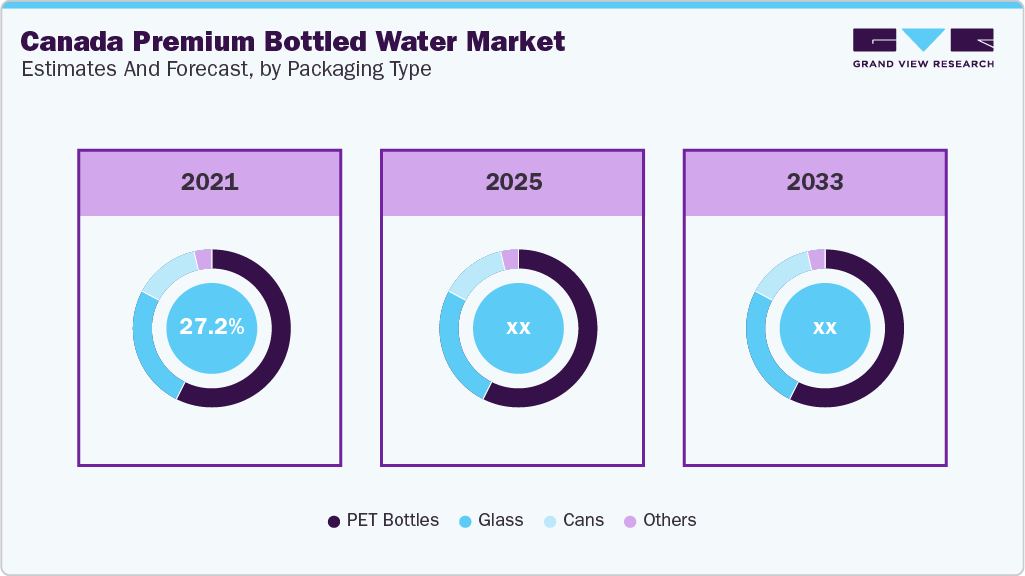
By packaging type, cans are projected to record the fastest CAGR of 6.8% from 2026 to 2033, driven by growing preference for recyclable, lightweight, and convenient packaging. Aluminum cans offer portability and strong shelf appeal while addressing concerns surrounding conventional plastic. BE WTR highlighted the scale of Canada’s waste challenge in February 2026, noting that the country generates more than 35 million tons of waste annually, with only around 27% recycled and nearly half of plastic waste originating from single-use packaging. This is increasing the focus on circular packaging and lower-waste solutions. Against this backdrop, aluminum cans offer premium water brands an opportunity to combine convenience, durability, and sustainability while responding to evolving environmental expectations.
Distribution Channel Insights
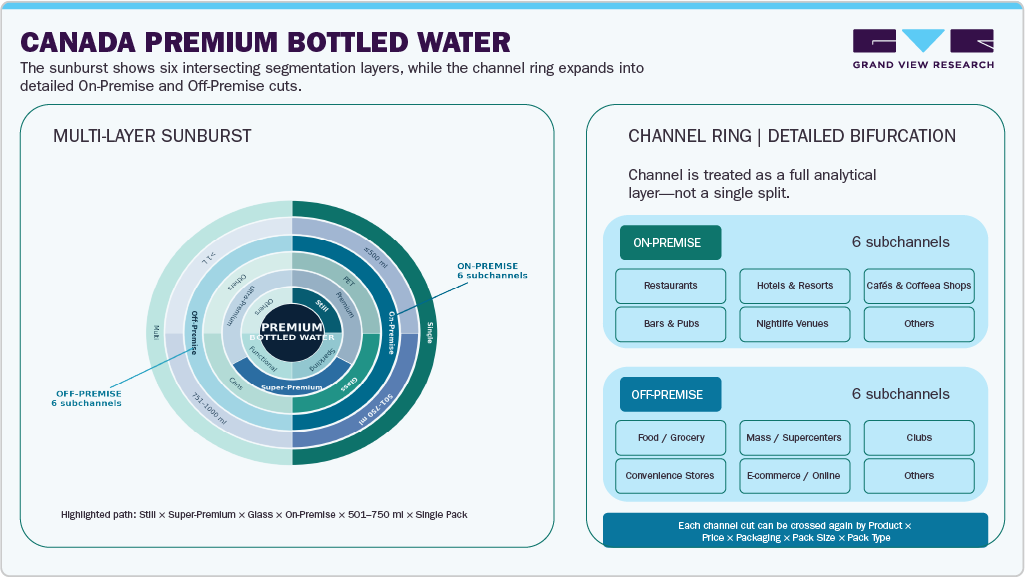
The off-premise channels in the Canada premium bottled water market accounted for the largest share of 59.8% of the revenue in 2025. The market is supported by the extensive availability of premium bottled water across supermarkets, grocery stores, convenience outlets, specialty retailers, club stores, and e-commerce platforms. These channels provide consumers with convenient access to premium products for routine and on-the-go consumption while enabling brands to achieve broader market coverage, stronger shelf visibility, and greater product discoverability. The expansion of premium bottled water into mainstream retail is also supported by consumer demand for convenient, high-quality, and differentiated hydration options. E-commerce is further complementing physical retail by offering wider product selections and convenient replenishment. Overall, the strong retail footprint of premium water brands and the convenience of purchasing through multiple off-premise formats continue to reinforce the channel’s leading position in Canada.
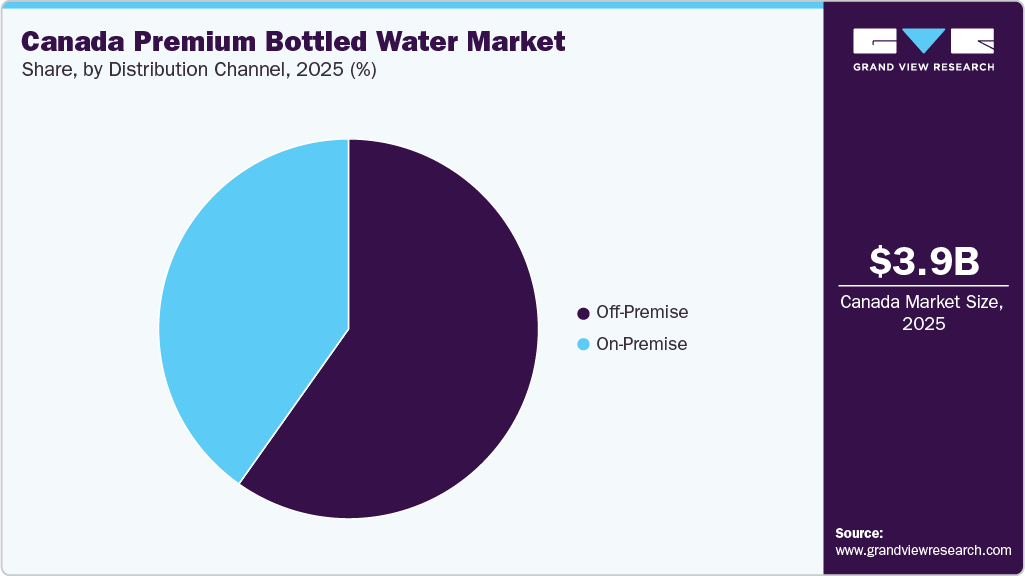
The on-premise channel is projected to register the fastest CAGR of 6.1% from 2026 to 2033, supported by the increasing presence of premium bottled water across restaurants, hotels, fine-dining establishments, and upscale hospitality venues. Growing demand for elevated dining and hospitality experiences is encouraging businesses to offer water products that complement food quality, service standards, and overall brand positioning. Consumer interest in wellness, sustainability, provenance, and sophisticated presentation is further strengthening demand for premium water in these settings. For instance, in June 2025, Canadian premium water brand NORTH introduced a limited-edition Kananaskis bottle for the G7 Summit and highlighted its presence across select upscale hospitality venues and wellness destinations. Positioned around Canadian Rocky Mountain sourcing, purity, balanced mineral content, and sustainable aluminum packaging, the initiative illustrates how premium water brands can leverage high-profile occasions and premium hospitality channels to enhance brand visibility and attract consumers seeking locally sourced, high-quality hydration.
Pack Size Insights
By pack size, up to 500 mL of premium bottled water, representing 40.9% of revenue in 2025. supported by strong consumer demand for portable, single-serve hydration. Smaller formats align well with on-the-go consumption across commuting, travel, fitness, workplaces, dining, and other away-from-home occasions, while also offering consumers an accessible entry point into premium water brands. Premium producers are reinforcing this trend by expanding compact formats that combine convenience, product quality, and differentiated packaging. For instance, in March 2026, Flow reintroduced its 330 mL Original naturally alkaline spring water format across Canadian retail, strengthening its single-serve offering for on-the-go consumption.
The 501-750 mL of premium bottled water are projected to register the fastest CAGR of 5.6% from 2026 to 2033. The 501-750 mL pack-size segment benefits from consumer demand for formats that combine portability with greater hydration volume. These bottles offer a practical option for travel, fitness, outdoor activities, and longer-duration consumption while remaining convenient to carry. Premium water brands are increasingly responding to these occasions through larger single-serve offerings.
Pack Type Insights
The premium bottled water in multi packs held the largest position in the Canada premium bottled water industry, representing 62.0% of revenue in 2025. The multipack segment is supported by increasing consumer preference for convenient bulk purchasing, household stocking, and cost-efficient replenishment. Multi-pack formats are particularly suited to regular consumption occasions, enabling consumers to maintain an adequate supply of premium bottled water while reducing the frequency of individual purchases. Strong distribution through supermarkets, grocery retailers, club stores, and e-commerce platforms further supports segment penetration by providing consumers with convenient access to larger pack configurations. The format also benefits from its suitability for households, workplaces, social gatherings, and routine hydration, while premium brands can use multipacks to improve product visibility and encourage repeat purchasing. Overall, the combination of convenience, purchase efficiency, accessibility, and recurring consumption continues to underpin the leading position of multi-pack formats in the Canadian premium bottled water market.
The premium bottled water in single pack is projected to register the fastest CAGR of 4.9% from 2026 to 2033. The single-pack segment is being driven by the growing preference for on-the-go hydration, convenience, portability, and immediate consumption. Rising mobility and busy lifestyles are encouraging consumers to purchase individual bottles for commuting, travel, fitness, outdoor activities, and workplace consumption. The segment is also benefiting from impulse purchasing through convenience stores, vending machines, restaurants, and cafés, where consumers typically seek ready-to-drink products rather than bulk quantities. In the premium category, premium packaging, distinctive bottle designs, functional water attributes, and sustainability-focused materials are further supporting demand for individual formats.
Key Canada Premium Bottled Water Company Insights
The Canada premium bottled water industry is competitive, with established multinational brands and emerging premium players competing across retail, foodservice, hospitality, and e-commerce channels. Companies are focusing on product innovation, portfolio expansion, sustainable packaging, strategic partnerships, digital marketing, and channel expansion to strengthen market positioning.
Key Canada Premium Bottled Water Companies
-
ESKA
-
Naya
-
Jackson Springs
-
Yoho Fine Water
-
NORTH Water
-
Flow Water
-
Nurture Water
-
10 Thousand BC
-
Canadian ColdFlo
-
Monashee Spring Water
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (ESKA; Naya; Jackson Springs; Flow Water)
Expand premium bottled water portfolios through distinctive sources, premium packaging, sustainability initiatives, and broad retail and hospitality distribution.
Strong brand recognition, established distribution, trusted sources, and premium positioning.
Higher operating costs, regulatory pressures, and intense competition from private-label and specialist brands.
Emerging Players (Yoho Fine Water; NORTH Water; Nurture Water; 10 Thousand BC; Canadian ColdFlo; Monashee Spring Waterhateldon, La Salvetat)
Target niche opportunities through flexible production, specialist offerings, differentiated sourcing, and selected retail or hospitality channels.
Greater flexibility, customer-focused solutions, and differentiated product propositions.
Limited brand awareness, distribution reach, production scale, and marketing resources.
Recent Developments
-
In April 2026, Flow expanded its Canadian offering with Flow Sparkling, a range of Canadian mineral spring waters featuring naturally occurring minerals and electrolytes, with zero sugar, zero calories, and no sweeteners across Original, Lemon + Ginger, Wild Berry, and Cucumber + Mint variants. The launch reflects how manufacturers are leveraging clean-label formulations, functional attributes, flavor innovation, and premium positioning to align with evolving consumer expectations.
-
In March 2026, Flow reintroduced its 330 mL Original naturally alkaline spring water format across Canadian retail, strengthening its single-serve offering for on-the-go consumption.
-
In June 2025, Canadian premium water brand NORTH introduced a limited-edition Kananaskis bottle for the G7 Summit and highlighted its presence across select upscale hospitality venues and wellness destinations.
Canada Premium Bottled Water Market Report Scope
Report Attribute
Details
Market size in 2025
USD 3.9 billion
Estimated market size in 2026
USD 4.2 billion
Projected market size by 2033
USD 6.2 billion
Growth rate (Revenue)
CAGR of 5.6% from 2026 to 2033
Actuals
2021 - 2025
Forecast period
2026 - 2033
Quantitative (Revenue) units
Revenue in USD million/billion, volume in million liters, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, price point, packaging type distribution channel, pack size, pack type
Country scope
Canada
Key companies profiled
ESKA; Naya; Jackson Springs; Yoho Fine Water; NORTH Water; Flow Water; Nurture Water; 10 Thousand BC; Canadian ColdFlo; Monashee Spring Water
Customization scope
Free report customization (equivalent up to 8 analysts’ working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Canada Premium Bottled Water Market Report Segmentation
This report forecasts revenue growth at the country level and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the Canada premium bottled water market report on the basis of product, price point, packaging type, distribution channel, pack size, and pack type.
-
Product Outlook (Volume, Million Liters; Revenue, USD Million, 2021 - 2033)
-
Still Water
-
Sparkling Water
-
Functional Water
-
Others
-
-
Price Point Outlook (Volume, Million Liters; Revenue, USD Million, 2021 - 2033)
-
Premium
-
Super-Premium
-
Ultra-Premium
-
-
Packaging Type Outlook (Volume, Million Liters; Revenue, USD Million, 2021 - 2033)
-
PET Bottles
-
Glass
-
Cans
-
Others
-
-
Distribution Channel Outlook (Volume, Million Liters; Revenue, USD Million, 2021 - 2033)
-
On-Premise
-
Restaurants
-
Hotels & Resorts
-
Cafés & Coffee Shops
-
Bars & Pubs
-
Nightlife Venues
-
Others
-
-
Off-Premise
-
Food / Grocery
-
Mass (incl. supercenters)
-
Clubs
-
Convenience Stores
-
E-commerce / Online
-
Other
-
-
-
Pack Size Outlook (Volume, Million Liters; Revenue, USD Million, 2021 - 2033)
-
Upto 500 ml
-
501-750 ml
-
751-1000 ml
-
Above 1 Liter
-
-
Pack Type Outlook (Volume, Million Liters; Revenue, USD Million, 2021 - 2033)
-
Single Pack
-
Multi Pack
-
Research Methodology
The canada premium bottled water market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each canada premium bottled water segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Product
Revenue capture definition
Still Water
This segment includes the sales of premium still water, including natural spring water, mineral water, artesian water, and purified water without carbonation.
Sparkling Water
This segment includes the sales of premium sparkling water, including naturally sparkling and carbonated water products.
Functional Water
This segment includes the sales of premium water enhanced with functional ingredients, such as electrolytes, vitamins, minerals, antioxidants, and other nutrients intended to support hydration and wellness.
Others
This segment includes the sales of other premium bottled water products, including specialty water products differentiated by unique sourcing, processing, or formulation.
Estimation Model
Title
Key Question
Details
Consumption Profile Layer
Who consumes premium bottled water?
Demand is driven by consumers seeking high-quality hydration, perceived purity, superior taste, natural mineral content, functional benefits, and premium experiences. Wellness awareness, convenience, and interest in sustainable consumption further influence purchasing preferences.
Market Reach Layer
Where are they sold?
Products reach consumers through retail, e-commerce, restaurants, hotels, foodservice, and specialty channels. Distribution breadth supports market penetration.
Innovation & Differentiation Layer
How do brands differentiate?
Brands differentiate through source provenance, mineral composition, functional benefits, sparkling formats, premium bottle designs, and sustainable packaging.
Value Generation Layer
How does consumption convert into market value?
Revenue is generated through premium-priced product sales, supported by brand equity, differentiated offerings, packaging value, and consumer willingness to pay.
Customization Table
Client Request
Customization Delivered
Value Adds
Understand premium bottled water consumer preferences and purchasing behavior
Developed a Canada-specific consumer assessment covering preferences for natural spring water, mineral content, source origin, purity, taste, packaging format, sustainability, and functional benefits. Evaluated purchasing behavior across supermarkets, convenience stores, specialty retailers, foodservice, and e-commerce.
Helps identify high-value consumer segments, key purchase drivers, and attributes that support premium pricing and brand differentiation in the Canada market.
Benchmark competitive positioning of leading premium bottled water brands
Assessed major Canada and international brands based on water source, product positioning, packaging, price tier, brand image, sustainability initiatives, distribution footprint, and product portfolio. Evaluated how brands differentiate through provenance, purity, functionality, and premium packaging.
Provides a structured competitive benchmark to identify positioning gaps, whitespace opportunities, and potential strategies for strengthening market presence
Identify emerging product categories and innovation opportunities
Evaluated emerging trends including still water, sparkling water , functional water and other premium water category. Assessed innovation around ingredients, packaging, sourcing, and consumer experience.
Supports identification of high-potential product opportunities and innovation pathways aligned with evolving Canada preferences for health, wellness, convenience, sustainability, and premium experiences.
About the Author(s)
Consumer F&B Research Team
Consumer Goods · Consumer F&BThis report was authored by the consumer f&b research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the consumer f&b segment of the consumer goods industry. All findings are based on proprietary consumer goods databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst


Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


