
- Home
- »
- Next Generation Technologies
- »
-
Car Insurance Market Size And Share Report, 2026-2033GVR Report cover

Car Insurance Market (2026 - 2033)
Size, Share & Trends Analysis Report By Coverage, By Distribution Channel (Insurance Agents/Brokers), By Vehicle Age (New Vehicle, Used Vehicle), By Application (Personal), By Region, And Segment Forecasts
Market Size, 2025
$914.3MMarket Estimate, 2026
$1,031.0MMarket Forecast, 2033
$2,811.7MCAGR, 2026–2033
15.4%Car Insurance Market Summary
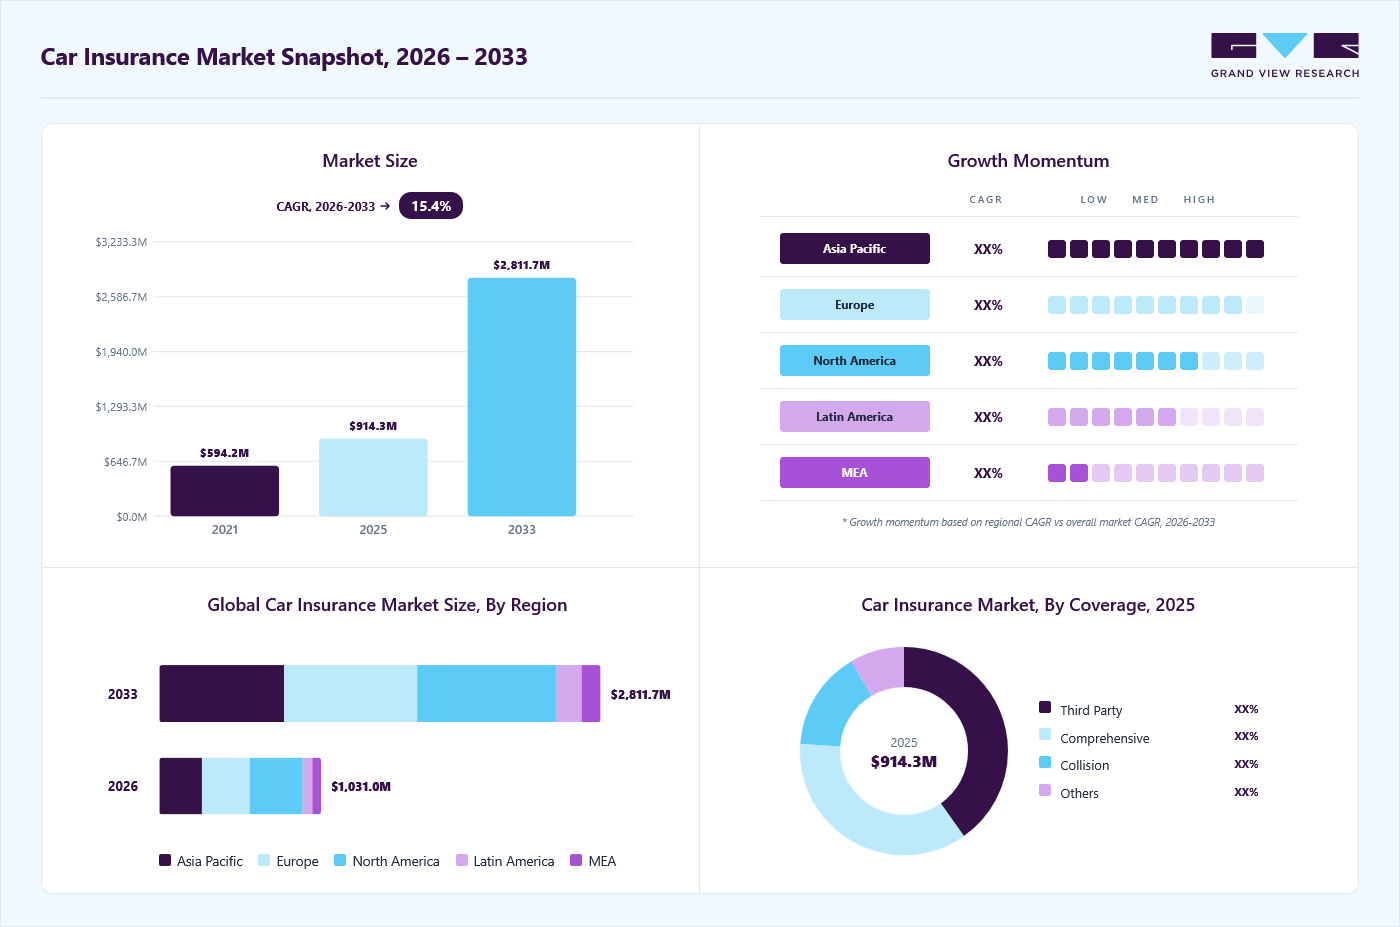
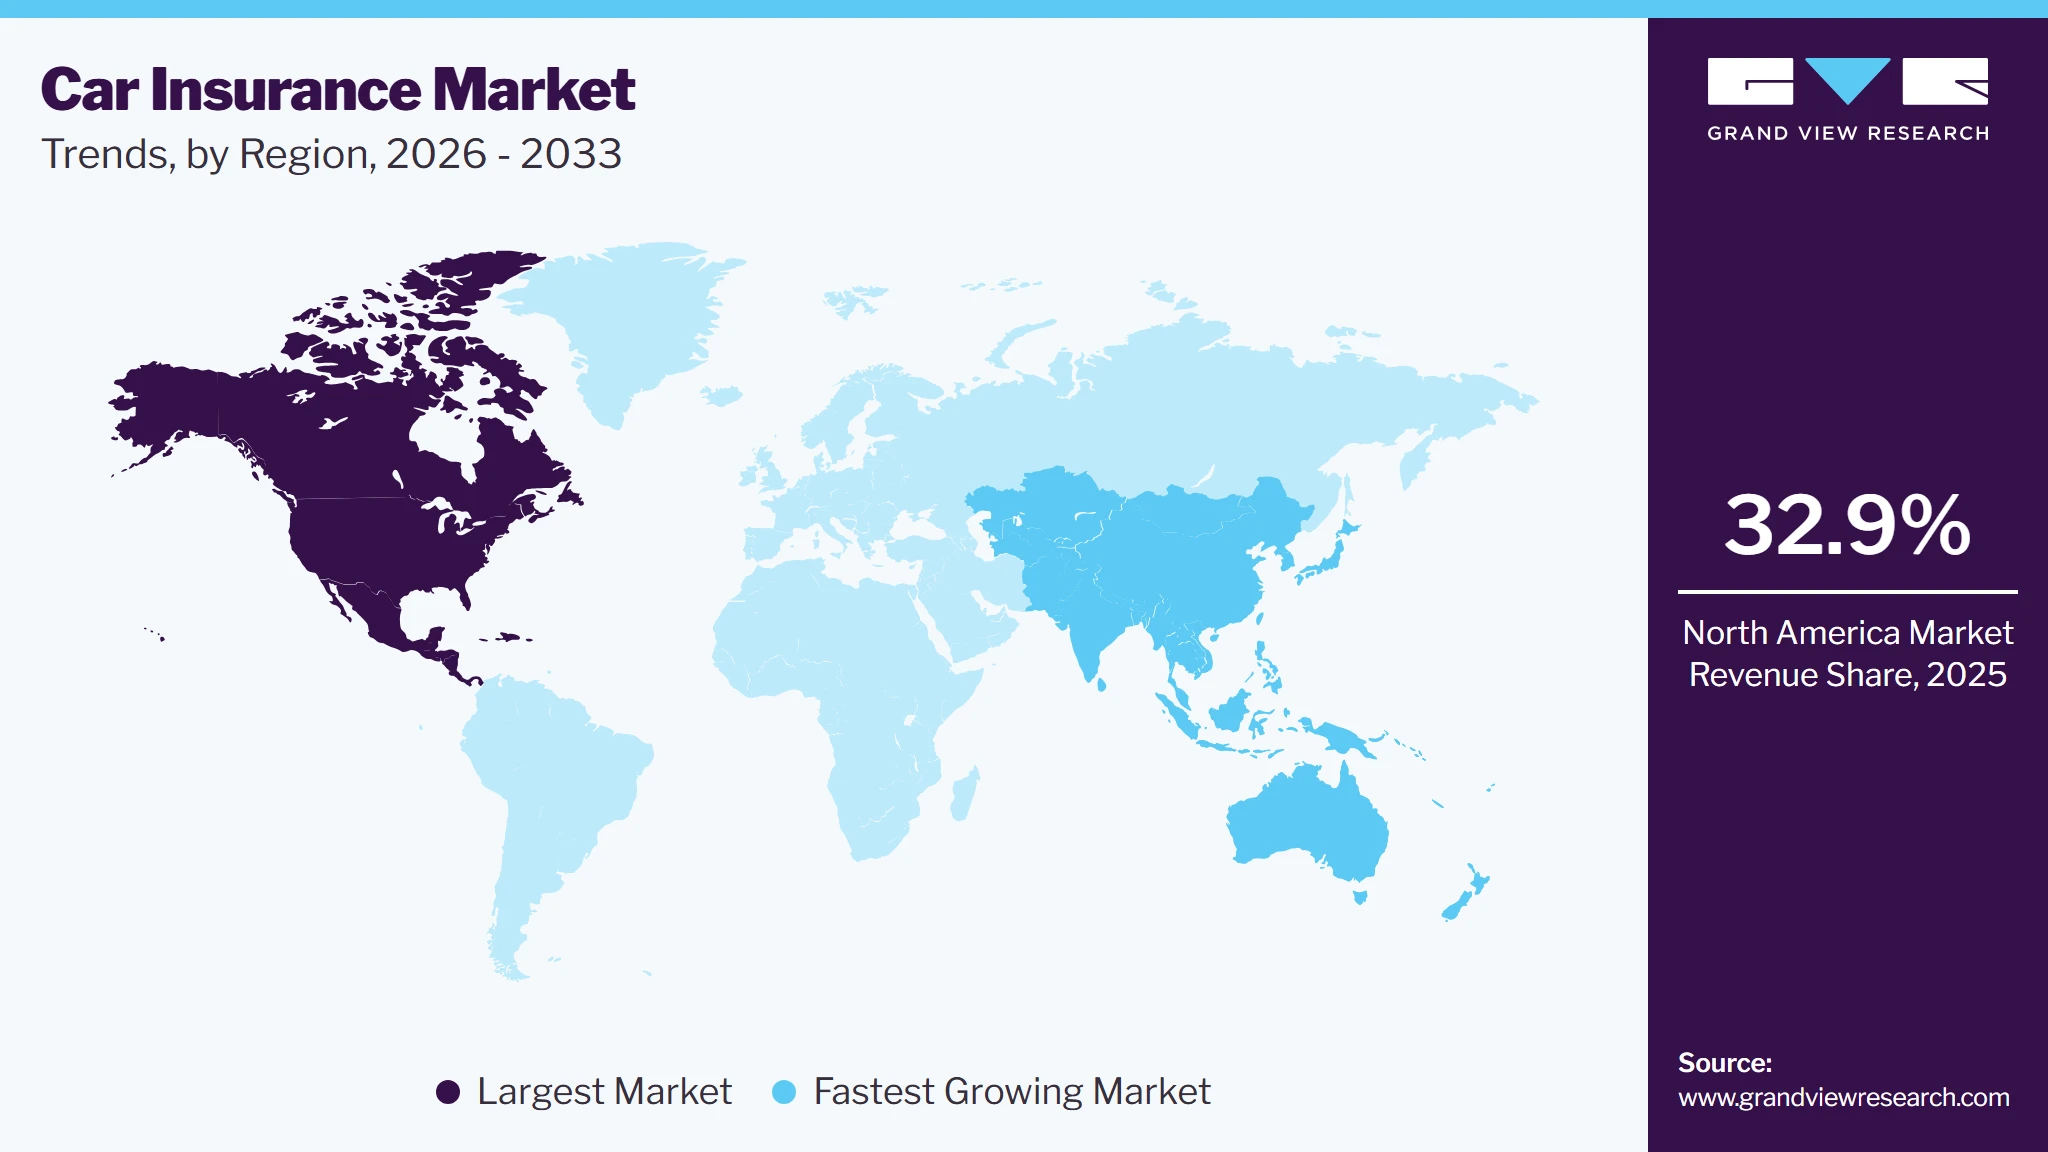
The global car insurance market size was valued at USD 914.3 million in 2025 and projected to grow from USD 1,031.0 million in 2026 to USD 2,811.7 million by 2033, at a CAGR of 15.4% from 2026 to 2033. North America dominated the global market with the largest revenue share of 32.9% in 2025. The rising number of road accidents is significantly contributing to the growth of the industry.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By vehicle age: New vehicle held the largest revenue share of 62.7% in 2025.
- By coverage: Third-party held the largest revenue share of 40.2% in 2025.
- By distribution channel: Insurance agents/brokers held the largest revenue share in 2025.
Regional Highlights
- Largest regional market: North America (32.9% revenue share, 2025)
- Fastest growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S held a dominant market position in 2025.
Market Size & Forecast
- Market size in 2025: USD 914.3 Million
- Estimated market size in 2026: USD 1,031.0 Million
- Projected market size by 2033: USD 2,811.7 Million
- CAGR (2026-2033): 15.4%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
As urban areas become more congested and the number of vehicles on the road rises, the likelihood of accidents naturally increases. This surge in accidents has heightened driver awareness of the need for comprehensive insurance coverage. Consequently, more consumers are purchasing car insurance policies to safeguard against the financial risks associated with accidents, such as vehicle repairs, medical expenses, and legal liabilities. Insurance companies are responding to this trend by expanding their product offerings and enhancing their claims processes to meet the growing demand for reliable and swift coverage.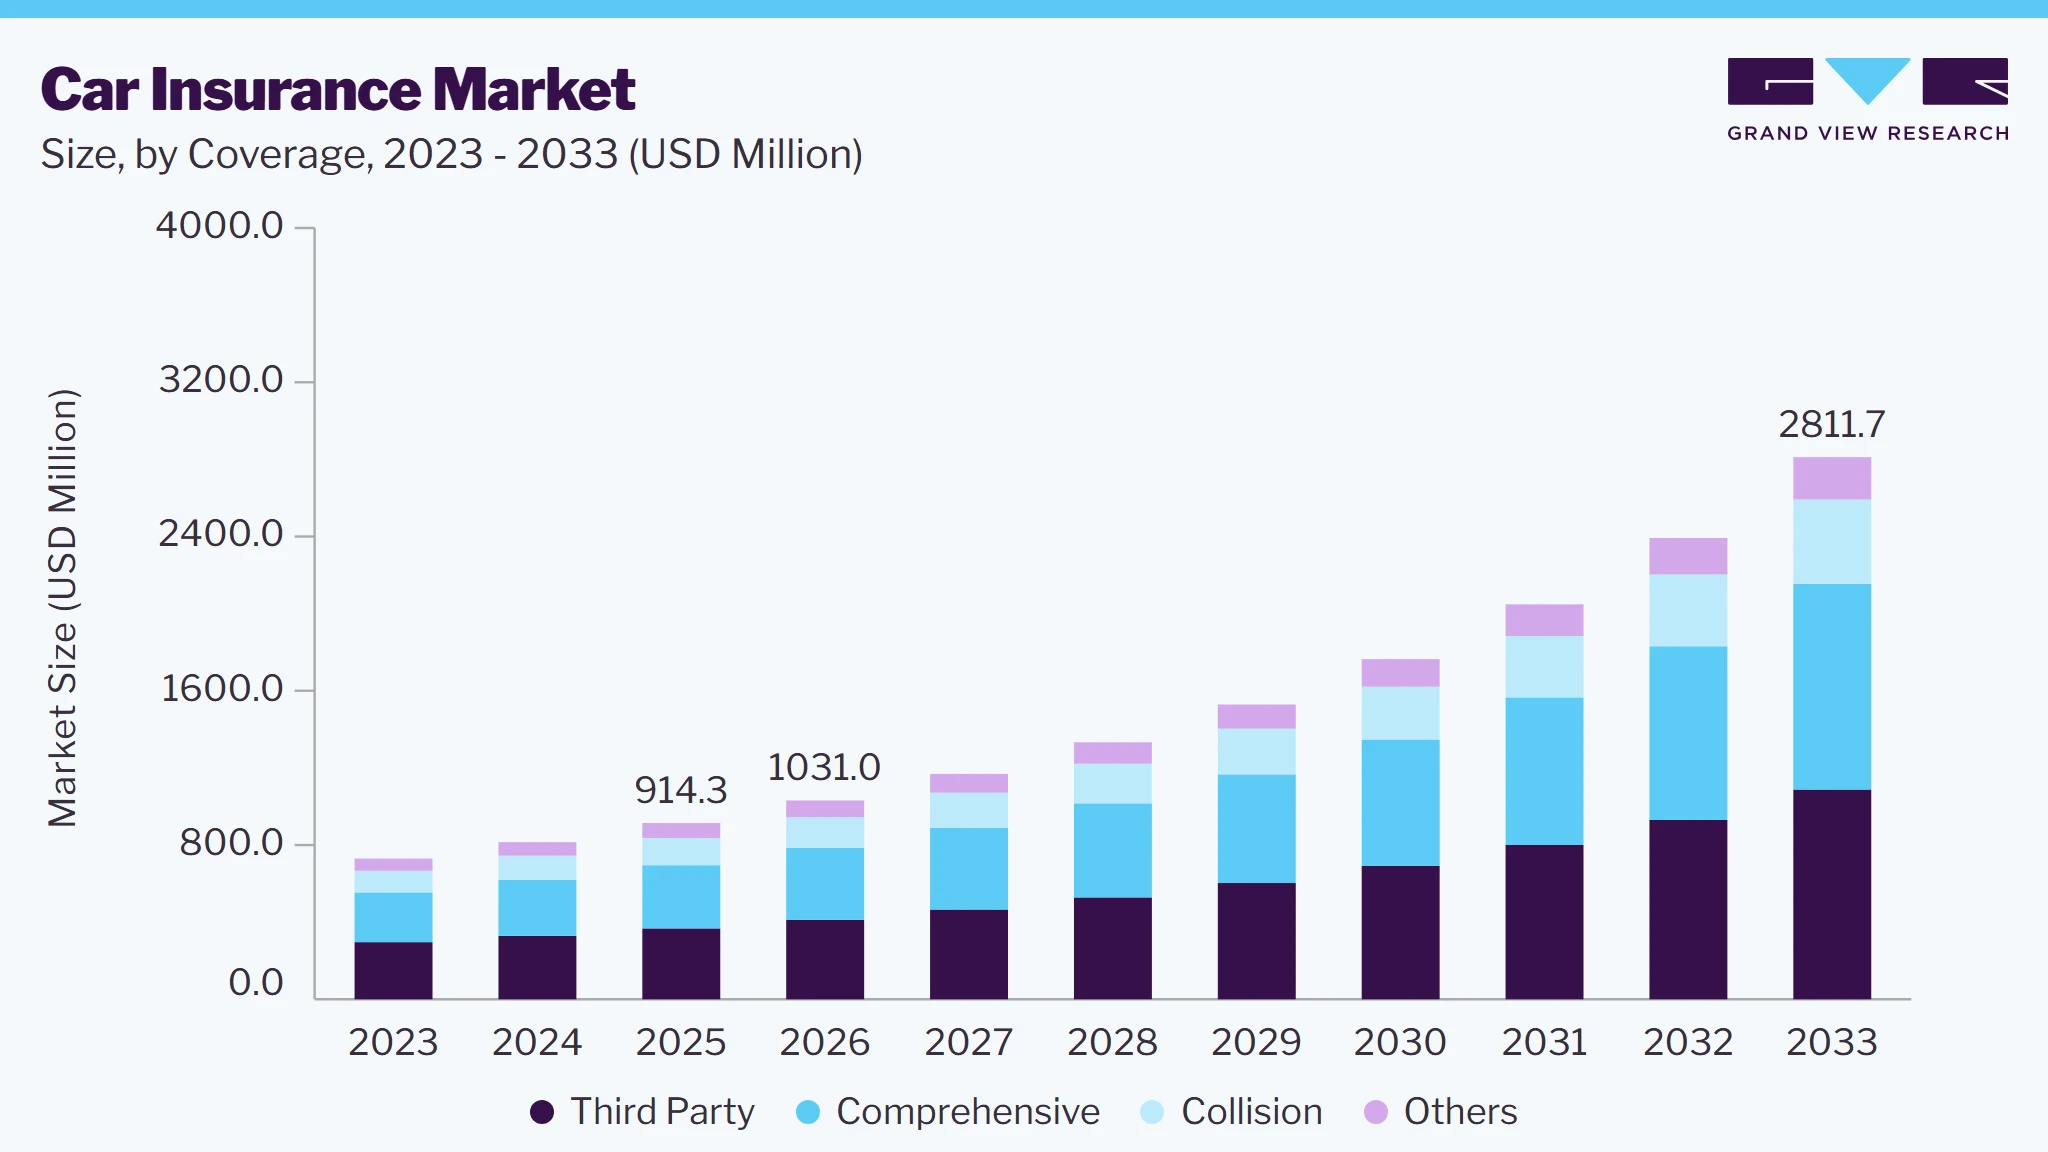 To learn more about this report, Download Free Sample Report
The rising adoption of telematics, which involves using in-car devices to monitor driving behavior and collect data, is also contributing to the growth of the market. This technology enables insurers to offer usage-based insurance (UBI) plans, in which premiums are determined by real-time data on driving habits. These personalized plans are appealing to safer drivers who can benefit from lower premiums while also providing insurers with more accurate risk assessments. As telematics becomes more sophisticated, it is expected to play a pivotal role in reshaping the car insurance landscape.
The growing popularity of electric vehicles (EVs) is also contributing to the market growth. With governments worldwide pushing for greener transportation and offering incentives for EV adoption, insurers are developing specialized policies tailored to these vehicles. EV insurance policies often consider factors unique to electric cars, such as battery life, charging infrastructure, and specialized repair costs. Insurers are also considering the environmental benefits of EVs, potentially offering lower premiums for these vehicles. This shift towards EVs is prompting insurers to rethink traditional underwriting models and create new products that cater to a changing automotive landscape.
The car insurance industry is also being shaped by the increasing prevalence of autonomous vehicles (AVs). As AV technology advances and becomes more widespread, traditional risk models based on human driving behavior are becoming less relevant. Insurers are now focusing on the technological reliability of AV systems and the liability of manufacturers in the event of a malfunction. This shift from driver-centric to vehicle-centric insurance is expected to lead to new policy and coverage options. The rise of AVs presents both challenges and opportunities for insurers as they navigate uncharted territory in risk management.
Digital disruption is another major trend impacting the car insurance market, as more customers are preferring online platforms for purchasing policies and managing claims. Insurtech companies are leading the charge, offering seamless digital experiences and innovative products that challenge traditional insurers. The convenience and transparency of digital platforms are driving higher customer satisfaction and retention rates. Additionally, artificial intelligence and machine learning are being used to automate underwriting processes and improve fraud detection. This digital shift is not only enhancing operational efficiency but also enabling insurers to better cater to evolving consumer preferences, thereby contributing to the growth of the market.
Market Dynamics
The car insurance market is driven by rising vehicle ownership, mandatory motor insurance regulations across many countries, increasing road accident frequency, and growing awareness regarding financial protection against vehicle damage and third-party liabilities. The market is also being transformed by digitalization, with insurers increasingly adopting AI-driven underwriting, telematics, usage-based insurance (UBI), and mobile-first distribution channels to improve customer acquisition and risk assessment. The growing penetration of electric vehicles (EVs), connected cars, and autonomous driving technologies is creating new pricing models and specialized insurance products, further expanding market opportunities.
The increasing implementation of mandatory vehicle insurance regulations across developed and emerging economies is a major driver supporting the growth of the car insurance market. Governments and transportation authorities are strengthening compliance frameworks to ensure financial protection for drivers, passengers, and third parties in the event of vehicle-related damages or liabilities. For instance, in the European Union, motor vehicles must be covered by compulsory third-party insurance, which helps protect accident victims across member states. Rising vehicle ownership, particularly in urban and semi-urban regions, is further encouraging authorities to enforce compulsory third-party liability coverage and stricter policy renewal requirements.
In addition, the integration of digital verification systems, e-governance platforms, and online policy monitoring is improving insurance compliance rates and reducing the number of uninsured vehicles on the road. For instance, Illinois verifies each vehicle’s liability policy at least twice a year through an electronic link between insurers and a third-party vendor, supporting faster compliance checks. These regulatory initiatives are encouraging broader policy adoption and supporting long-term market expansion.
The increasing cost of vehicle repairs and claims settlement is a significant restraint affecting the profitability of the car insurance market. Modern vehicles are increasingly equipped with advanced electronics, sensors, driver-assistance technologies, and premium components, which substantially increase repair costs after accidents or damage. Inflationary pressures on spare parts, labor costs, and supply chain disruptions are increasing overall claim costs for insurers. These rising operational expenses are forcing insurance providers to increase premium rates, reducing affordability for consumers and negatively affecting policy renewals in price-sensitive markets. The growing frequency of fraudulent claims and litigation-related expenses is also adding financial pressure on insurers.
The growing integration of embedded insurance solutions within automotive sales and mobility ecosystems is creating significant growth opportunities for the car insurance market. Automakers, dealerships, financing providers, and digital mobility platforms are increasingly partnering with insurers to offer integrated insurance coverage during vehicle purchase, leasing, or subscription processes. This embedded insurance model simplifies policy acquisition and enhances customer convenience through seamless digital onboarding. The rise of connected mobility services, ride-sharing platforms, and vehicle subscription models is encouraging insurers to develop flexible and short-term insurance offerings tailored to evolving transportation preferences. The expansion of these ecosystem-driven insurance models is expected to create new distribution channels and expand customer reach for insurers globally.
Market Concentration & Characteristics
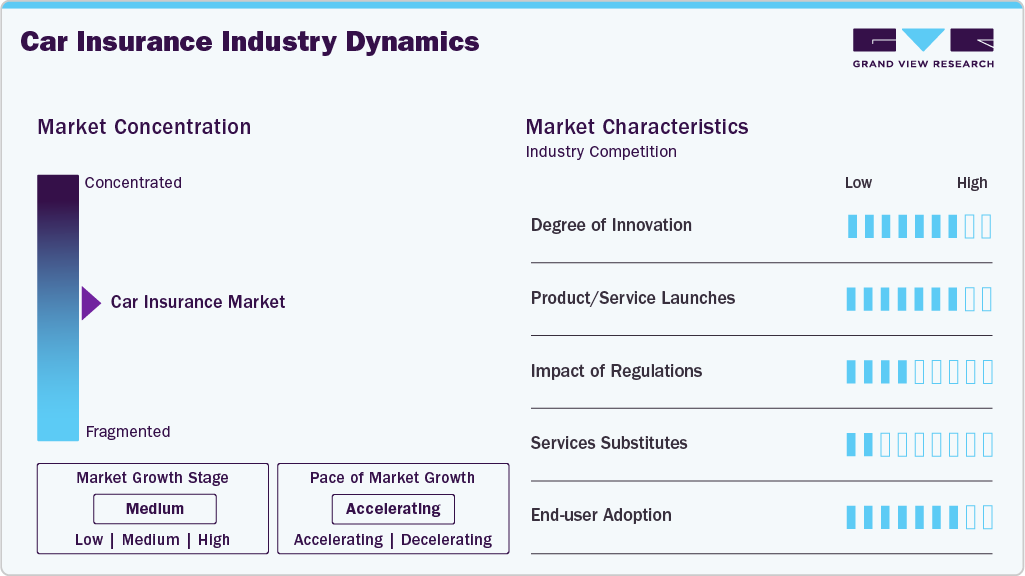
The car insurance market is fragmented, with the presence of several global insurance providers, regional insurers, digital-first insurance companies, and specialized automotive coverage providers competing across personal and commercial vehicle insurance segments. Major insurance companies maintain strong market positions through extensive distribution networks, diversified policy offerings, strong brand recognition, and advanced claims management capabilities. At the same time, the market includes emerging insurtech firms and technology-driven insurers offering app-based policy management, usage-based insurance models, and digital customer engagement solutions.
 To learn more about this report, Download Free Sample Report
The car insurance industry is characterized by increasing vehicle ownership, evolving mobility patterns, and growing demand for personalized insurance coverage solutions. Companies are focusing on integrating artificial intelligence, predictive analytics, connected vehicle technologies, and automated claims processing systems to improve underwriting accuracy, customer experience, and operational efficiency. In addition, rising adoption of electric vehicles, connected cars, and mobility-as-a-service platforms is encouraging insurers to develop specialized coverage models and flexible policy structures. The increasing emphasis on digital distribution channels, fraud prevention technologies, and customer retention strategies is further driving innovation, strategic collaborations, and product differentiation across the global car insurance industry.
Analyst Perspective
The car insurance market is undergoing a significant transformation driven by increasing vehicle ownership, evolving mobility patterns, and rapid digitalization across insurance ecosystems. Mandatory motor insurance regulations, the rising adoption of connected vehicles, and expanding demand for personalized coverage models, such as usage-based and telematics-enabled insurance, support market growth. Insurers are increasingly leveraging artificial intelligence, predictive analytics, and digital claims management platforms to improve underwriting efficiency, customer engagement, and fraud detection capabilities. The emergence of electric vehicles (EVs), shared mobility platforms, and autonomous driving technologies is reshaping risk assessment models and creating opportunities for specialized insurance products.
Coverage Insights
The third-party segment led the car insurance, accounting for 40.2% of the global revenue in 2025. The growth of the segment is driven by regulatory requirements and cost considerations. In many regions, including various countries in Europe and Asia Pacific, third-party insurance is mandatory, driving demand for this type of coverage. In addition, its relatively lower premium cost compared to comprehensive coverage makes it an attractive option for budget-conscious users. The rising number of vehicle registrations and increased awareness of legal obligations are driving the segment's growth. Moreover, the simplicity of third-party coverage, which focuses on liability protection for damage or injury to others, appeals to drivers seeking basic insurance solutions.
The comprehensive segment is projected to witness significant growth from 2026 to 2033. The segment is growing due to its broad range of protections and increasing consumer awareness of the benefits of extensive coverage. Comprehensive insurance offers protection against a wide range of risks, including theft, vandalism, natural disasters, and accidental damage, making it a preferred option for those seeking comprehensive coverage. As vehicle ownership increases and the value of cars rises, drivers are more inclined to invest in comprehensive coverage to safeguard their assets against diverse risks, thereby driving the segment’s growth.
Distribution Channel Insights
The insurance agents/brokers segment dominated the car insurance industry in 2025. The growing demand for personalized service and expert advice can be attributed to the segment’s growth. Agents and brokers offer valuable assistance in navigating the complexities of insurance policies, helping customers select the coverage that best suits their needs. Their in-depth knowledge of various insurance products and ability to compare options from multiple insurers enhance the purchasing experience. In addition, agents and brokers often build long-term relationships with clients, fostering trust and loyalty, thereby driving the segment’s growth.
The direct response segment is expected to grow at the fastest CAGR of 16.8% from 2026 to 2033. Advancements in digital technology and the growing preference for online transaction processes are major factors behind the segment’s growth. Direct response insurance allows customers to purchase policies directly from insurers via online platforms, call centers, or mobile applications, offering convenience and immediate access to insurance products. The increasing adoption of digital tools and the rise of comparison websites are also contributing to the growth of direct response channels, as they enable consumers to easily compare options and purchase policies without the need for intermediaries. This shift towards direct response is expected to continue as more consumers seek efficient, cost-effective ways to manage their insurance needs.
Vehicle Age Insights
The new vehicle segment held the largest market share of 62.7% in 2025 and is expected to be the fastest-growing segment throughout the projection period. This expansion is driven by the increasing sales of new cars globally, fueled by economic recovery, rising disposable incomes, and advancements in automotive technology. New vehicles, often equipped with advanced safety features and telematics, are attracting favorable insurance premiums, making them an attractive segment for insurers. The rapid adoption of electric vehicles (EVs) and connected cars is further bolstering this market, as these vehicles typically require specialized insurance products, offering new revenue streams for insurers. Additionally, the proliferation of digital platforms and insurtech innovations is making it easier for consumers to compare and purchase insurance policies, driving competition and enhancing market growth.
The used vehicle segment is steadily growing, driven by the increasing demand for pre-owned vehicles, which offer cost-effective alternatives to new cars amid economic uncertainties and rising new car prices. This segment is particularly attractive to cost-conscious consumers and first-time buyers, creating a robust market for insurers. Unlike new vehicles, used cars often require tailored insurance products that account for factors such as age, mileage, and condition, leading to diverse policy offerings. The rise of online marketplaces and digital tools for vehicle history reports and valuations has also made it easier for buyers to purchase used cars with greater confidence, subsequently increasing the demand for insurance coverage.
Application Insights
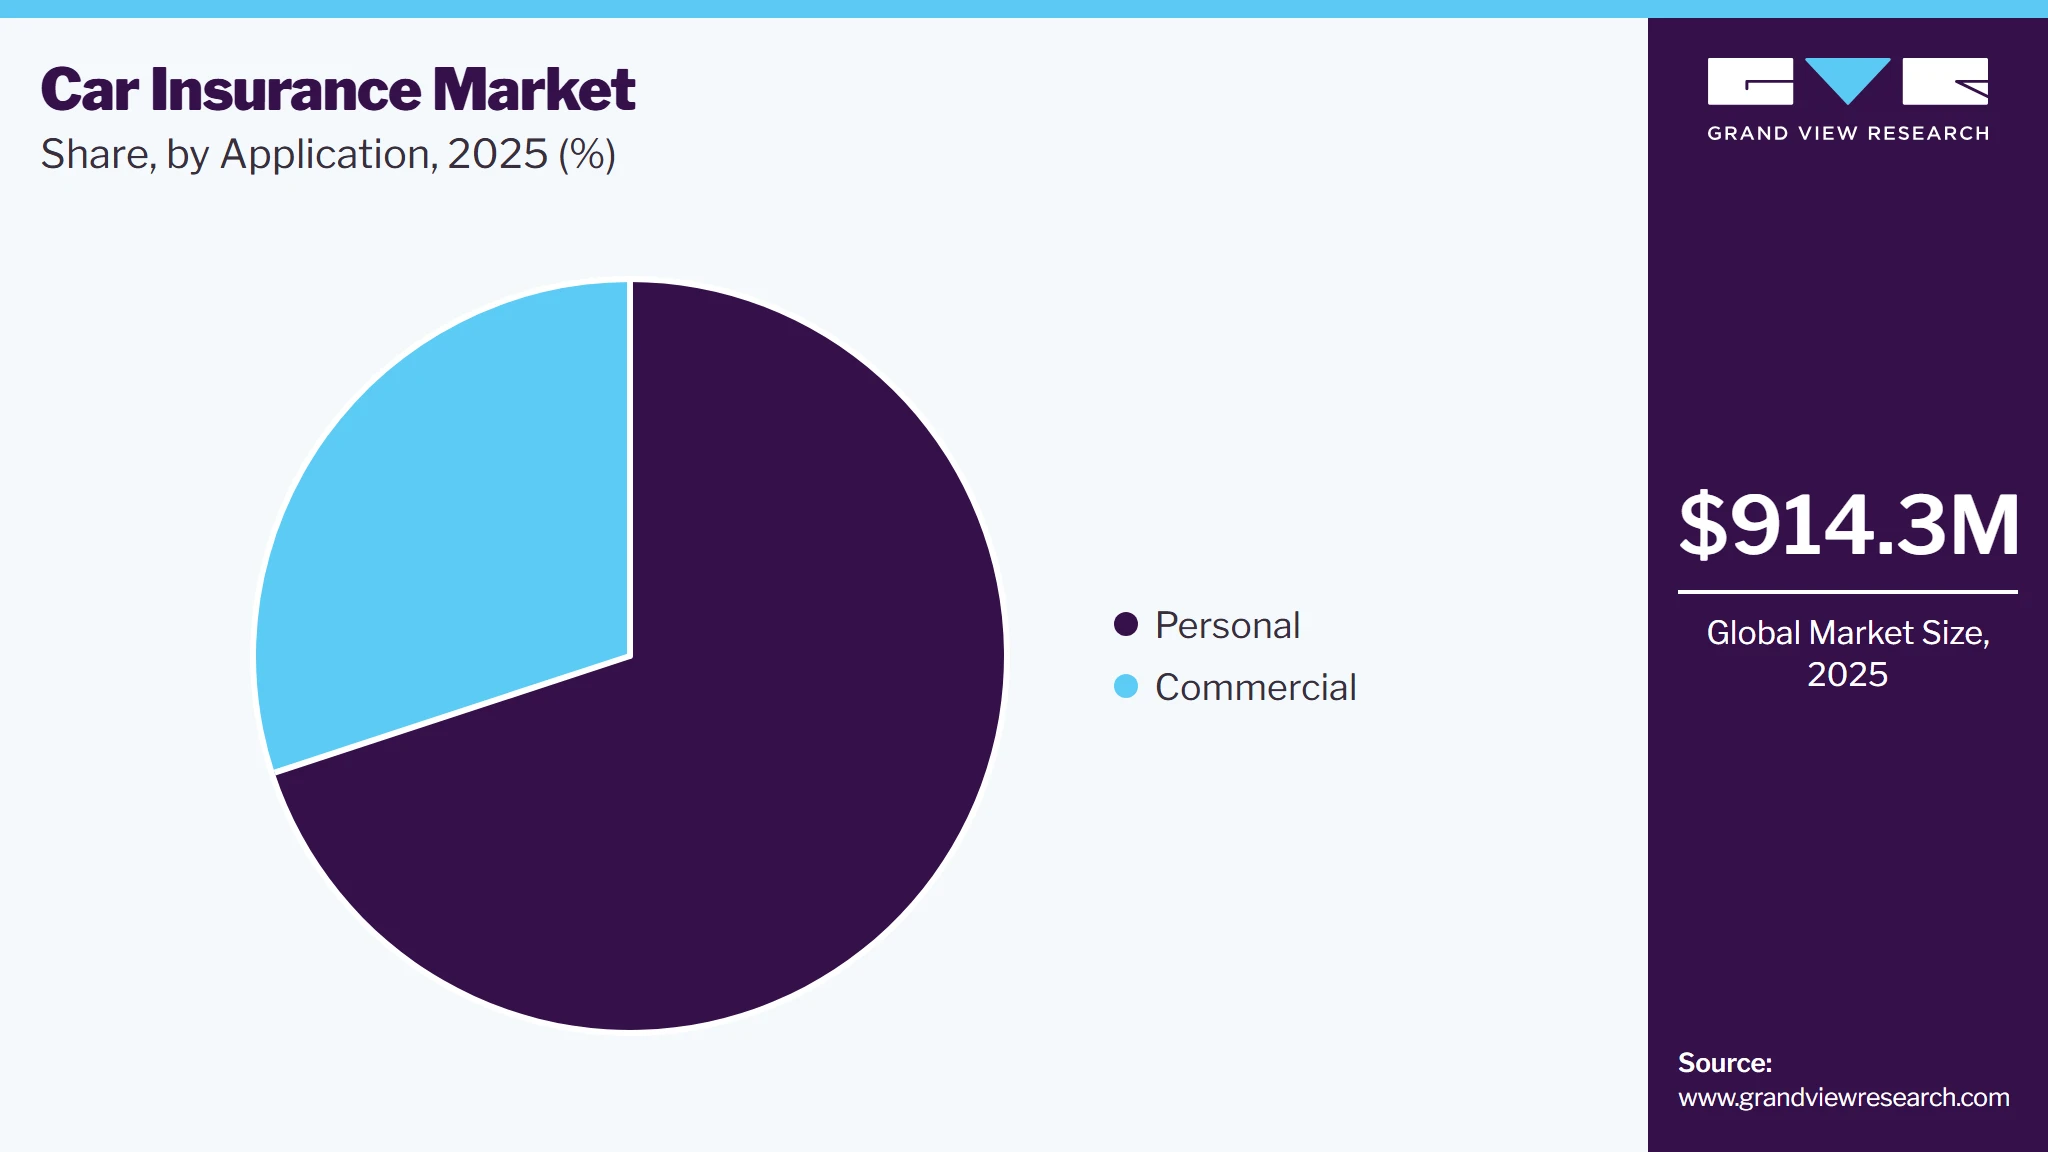
The personal segment held the largest share of the car insurance market in 2025 and is expected to be the fastest-growing segment during the forecast period. The personal car insurance segment is a cornerstone of the broader insurance industry, catering to individual vehicle owners and providing essential financial protection against risks such as accidents, theft, and liability. This market is characterized by intense competition, with insurers striving to offer competitive premiums and tailored coverage options that meet the diverse needs of consumers. The adoption of telematics and usage-based insurance (UBI) is transforming the personal car insurance landscape, enabling insurers to offer more personalized premiums based on driving behavior, appealing to safer drivers seeking lower costs.
 To learn more about this report, Download Free Sample Report
The commercial segment is anticipated to grow at a significant CAGR of 14.4% over the forecast period. The commercial car insurance market is a vital segment of the broader insurance industry, serving businesses that operate fleets of vehicles or rely on transportation as a key component of their operations. The growth of the segment is driven by the growing demand for commercial vehicles across sectors such as logistics, construction, ride-sharing, and delivery services, all of which require comprehensive coverage to protect against risks like accidents, theft, liability, and cargo damage. As businesses expand their fleets and increasingly adopt connected vehicle technologies, the need for specialized, flexible insurance solutions is growing. Insurers are responding by offering tailored policies that account for factors such as vehicle type, usage patterns, driver behavior, and business size.
Regional Insights
The North America car insurance market led the global market and accounted for 32.9% of the global revenue in 2025. Increasing demand for used and new vehicles in the region is expected to create growth opportunities for the regional market. Furthermore, the rising costs of vehicle repairs are contributing to the growth of the North American regional market.
 To learn more about this report, Download Free Sample Report
U.S. Car Insurance Market Trends
The U.S. car insurance industry is anticipated to register significant growth from 2026 to 2033. The rise in urbanization and the growing number of vehicles on the road in the U.S. are contributing to an increased demand for car insurance, as more drivers require coverage to comply with legal requirements.
Europe Car Insurance Market Trends
The Europe car insurance industry is poised for significant growth from 2026 to 2033. The integration of advanced analytics and artificial intelligence into claims processing is reducing operational costs and improving customer satisfaction, driving growth in the market in Europe.
The car insurance market in the UK is witnessing strong adoption of telematics and usage-based insurance (UBI) models, particularly among young and electric vehicle (EV) drivers. Insurers are increasingly leveraging connected-car data, AI-driven underwriting, and app-based driving analytics to offer personalized premiums. Additionally, the rapid expansion of EV ownership is reshaping underwriting practices due to higher battery repair and replacement costs, prompting insurers to introduce specialized EV insurance products.
The Germany car insurance market is trending toward digital-first insurance ecosystems supported by connected mobility and advanced driver-assistance systems (ADAS). German insurers are increasingly integrating telematics, automated claims processing, and embedded insurance services into vehicle financing and leasing platforms. Growing EV adoption and the country’s strong automotive manufacturing base are also encouraging insurers to develop tailored policies for electric and autonomous vehicles.
Asia Pacific Car Insurance Market Trends
The Asia Pacific car insurance industry is anticipated to register significant growth from 2026 to 2033. The expanding adoption of digital platforms and mobile applications by insurers in the Asia Pacific region is enhancing customer engagement and convenience, leading to higher policy renewal rates and attracting new customers.
The car insurance market in China is being driven by the rapid rise of new-energy vehicles (NEVs), including electric and plug-in hybrid vehicles. Insurers are increasingly focusing on NEV-specific products, connected-car insurance, and AI-enabled risk assessment solutions. At the same time, falling NEV insurance premiums and the expansion of smart mobility ecosystems are accelerating digital insurance innovation across the market.
The Japan car insurance market is experiencing growing demand for telematics-based insurance and advanced mobility protection solutions amid increasing adoption of hybrid and electric vehicles. Insurers are investing in AI-powered claims management, connected vehicle technologies, and coverage models designed for autonomous driving and aging-driver safety. The market is also seeing stronger collaboration between insurers, automakers, and mobility service providers to support next-generation transportation ecosystems.
Key Car Insurance Company Insights
Key players operating in the car insurance market include Allianz Group, AXA, Zurich Insurance Group, Bajaj Finserv, Liberty Mutual Insurance, Progressive Casualty Insurance Company, The Travelers Indemnity Company, Chubb, State Farm Mutual Automobile Insurance Company, and American International Group (AIG). The competitive landscape in the car insurance industry is characterized by intense competition among both established players and new entrants. Established players are leveraging their extensive distribution networks, strong brand recognition, and comprehensive product offerings. However, the rise of insurtech companies and digital platforms is significantly contributing to the market by offering innovative, user-friendly products and services, often at competitive prices.
-
Allianz Group is a global insurance and financial services company headquartered in Germany. The company offers a broad portfolio of insurance products, including motor, health, life, and property insurance, serving both individual and corporate customers across multiple international markets.
-
AXA is a France-based multinational insurance company providing life, health, property, casualty, and automobile insurance solutions. The company focuses on digital transformation, customer-centric insurance services, and global risk management solutions.
Key Car Insurance Companies
The following key companies have been profiled for this study on the car insurance market.
-
Allianz Group
-
AXA
-
Zurich Insurance Group
-
Bajaj Finserv
-
Liberty Mutual Insurance
-
Progressive Casualty Insurance Company
-
The Travelers Indemnity Company
-
Chubb
-
State Farm Mutual Automobile Insurance Company
-
American International Group (AIG)
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Mature Players: Allianz Group; AXA; Zurich Insurance Group; Liberty Mutual Insurance; Chubb; American International Group (AIG)
- Focus on AI-driven underwriting, telematics, and automated claims management.
- Invest in partnerships with automakers, mobility platforms, and insurtech companies.
- Strong global presence, diversified insurance portfolios, and advanced risk management capabilities.
- Extensive distribution networks and strong financial resources.
- High operational and claims costs.
- Regulatory complexities and rising competition from digital insurers.
Emerging Players: Bajaj Finserv; Progressive Casualty Insurance Company; The Travelers Indemnity Company; State Farm Mutual Automobile Insurance Company
- Focus on usage-based insurance (UBI), digital policy management, and data-driven pricing strategies.
- Expand through regional growth and digital insurance services.
- Strong domestic customer base and competitive pricing strategies.
- Growing telematics adoption and agile digital platforms.
- Limited international presence compared to global insurers.
- Dependence on regional market conditions and evolving mobility trends.
Recent Developments
-
In April 2026, State Farm announced auto insurance rate reductions for Texas drivers following regulatory approval of a 6.2% personal auto rate cut in California in March 2026, reflecting the company’s efforts to improve pricing competitiveness and customer affordability in key U.S. markets.
-
In August 2025, AXA acquired Prima, a leading direct insurance provider in Italy, to strengthen its presence in the country’s motor insurance market and expand its digital distribution capabilities across the European insurance sector.
Car Insurance Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 914.3 million
Market size value in 2026
USD 1,031.0 million
Revenue forecast in 2033
USD 2,811.7 million
Growth rate
CAGR of 15.4% from 2026 to 2033
Base year for estimation
2025
Actual data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company market share, competitive landscape, growth factors, and trends
Segments covered
Coverage, distribution channel, vehicle age, application, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; China; India; Japan; South Korea; Australia; Brazil; Kingdom of Saudi Arabia (KSA); UAE; South Africa
Key companies profiled
Allianz Group; AXA; Zurich Insurance Group; Bajaj Finserv; Liberty Mutual Insurance; Progressive Casualty Insurance Company; The Travelers Indemnity Company; Chubb; State Farm Mutual Automobile Insurance Company; American International Group (AIG)
Customization scope
Free report customization (equivalent to up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Car Insurance Market Report Segmentation
The report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the car insurance market report based on coverage, distribution channel, vehicle age, application, and region:
-
Coverage Outlook (Revenue, USD Million, 2021 - 2033)
-
Third Party
-
Comprehensive
-
Collision
-
Others
-
-
Distribution Channel Outlook (Revenue, USD Million, 2021 - 2033)
-
Insurance Agents/Brokers
-
Direct Response
-
Banks
-
Others
-
-
Vehicle Age Outlook (Revenue, USD Million, 2021 - 2033)
-
New Vehicle
-
Used Vehicle
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Personal
-
Commercial
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
-
Middle East & Africa (MEA)
-
UAE
-
Kingdom of Saudi Arabia (KSA)
-
South Africa
-
-
Research Methodology
The car insurance market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each car insurance segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Coverage
Revenue capture definition
Third Party
Revenue is captured through premiums collected for policies that cover legal liabilities arising from bodily injury, death, or property damage caused to third parties by the insured vehicle.
Comprehensive
Revenue is captured from premiums charged for broad protection policies covering third-party liabilities along with damages to the insured vehicle caused by accidents, theft, fire, vandalism, natural disasters, and other non-collision events.
Collision
Revenue is generated through premiums collected for policies specifically covering repair or replacement costs of the insured vehicle resulting from collisions with other vehicles or objects, regardless of fault.
Others
Revenue is captured from specialized or add-on insurance offerings such as personal accident cover, roadside assistance, zero depreciation cover, and gap insurance.
Segment - Distribution Channel
Revenue capture definition
Insurance Agents/Brokers
Refers to intermediaries that sell and distribute car insurance policies on behalf of insurers while providing advisory services, policy comparisons, claims support, and customized coverage recommendations.
Direct Response
Refers to insurance policies sold directly by insurers to customers through company-owned channels such as websites, mobile applications, call centers, digital platforms, and direct sales teams without intermediary involvement.
Banks
Refers to the distribution of car insurance products through banking institutions under bancassurance partnerships, where banks cross-sell motor insurance products alongside vehicle financing, loans, or other financial services to their customer base.
Others
Includes alternative distribution channels such as automobile dealerships, affinity partnerships, aggregators/comparison websites, fintech and insurtech platforms.
Segment - Vehicle Age
Revenue capture definition
New Vehicle
Refers to insurance policies designed for newly purchased or recently manufactured vehicles, typically characterized by higher insured values, broader coverage preferences, and increased adoption of comprehensive insurance plans.
Used Vehicle
Refers to insurance policies covering pre-owned or previously registered vehicles that have been owned by one or more users before resale.
Segment - Application
Revenue capture definition
Personal
Refers to car insurance policies designed for privately owned vehicles used for individual, family, or non-commercial purposes.
Commercial
Refers to car insurance policies covering vehicles used for business-related activities, including company-owned fleets, logistics vehicles, ride-hailing vehicles, rental cars, delivery vehicles, and other commercial transportation purposes.
Estimation Model
Layer Name
Key Question
Description
Vehicle Ownership & Insurable Base Layer
What forms the demand base?
Identifies the primary demand drivers for car insurance through analysis of vehicle parc growth, passenger vehicle ownership, commercial vehicle expansion, urbanization trends, income growth, and regulatory requirements for mandatory insurance coverage. This layer evaluates the addressable insured vehicle population across personal and commercial applications.
Insurance Penetration & Distribution Layer
Where is insurance adoption occurring?
Assesses insurance penetration across regions, vehicle categories, and customer segments by evaluating policy adoption rates, mandatory coverage regulations, digital insurance uptake, bancassurance channels, broker networks, and direct-to-consumer insurance ecosystems. This layer determines market accessibility and policy acquisition trends.
Risk, Claims & Premium Optimization Layer
How are policies utilized and priced?
Evaluates claim frequency, accident rates, driver behavior, vehicle age, repair costs, fraud exposure, telematics adoption, and risk profiling models. This layer analyzes how underwriting practices, loss ratios, and risk segmentation influence premium pricing and policy utilization.
Revenue Generation Layer
How is market revenue generated?
Quantifies market revenue through gross written premiums, policy renewals, add-on coverage sales, comprehensive and third-party insurance products, fleet insurance contracts, usage-based insurance models, and digital insurance services. Revenue generation is influenced by premium pricing, policy volumes, retention rates, and expanding insurance product portfolios.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Global Auto Insurance Provider
Evaluation of telematics-based insurance platforms and usage-based insurance (UBI) models
Analysis of digital claims management and AI-powered fraud detection solutions
Benchmarking of connected-car insurance technologies and customer engagement capabilities.
Identified opportunities for personalized premium pricing
Supported faster and more efficient claims processing
Enabled improved fraud prevention and customer retention strategies.
Electric Vehicle (EV) Insurance Company
Assessment of EV-specific insurance coverage models and battery protection solutions
Analysis of EV repair cost trends, charging infrastructure risks, and underwriting frameworks
Benchmarking of insurers offering specialized EV policies and digital servicing capabilities.
Strengthened EV-focused product development strategies
Improved underwriting accuracy for emerging vehicle technologies
Supported expansion into high-growth electric mobility markets.
Regional Insurer Expanding Digital Motor Insurance Services
Market readiness assessment for online policy distribution and mobile-based insurance platforms
Analysis of consumer demand trends for app-based policy management and instant claim settlement
ROI and deployment strategy evaluation for AI-enabled underwriting and automation technologies.
Identified scalable digital insurance growth opportunities
Supported strategic investment planning in insurtech capabilities
Enabled enhanced operational efficiency and customer experience.
Frequently Asked Questions About This Report
Some key players operating in the car insurance market include Allianz Group, AXA, Zurich Insurance Group, Bajaj Finserv, Liberty Mutual Insurance, Progressive Casualty Insurance Company, The Travelers Indemnity Company, Chubb, State Farm Mutual Automobile Insurance Company, and American International Group (AIG).
Key factors that are driving the market growth include the rising number of road accidents and the growing popularity of Electric Vehicles (EVs).
The global car insurance market size was estimated at USD 914.3 million in 2025 and is expected to reach USD 1,031.0 million in 2026.
The global car insurance market is expected to grow at a compound annual growth rate of 15.4% from 2026 to 2033 to reach USD 2,811.7 million by 2033.
North America dominated the car insurance market with a share of 32.9% in 2025. Increasing demand for used and new vehicles in the region is expected to create growth opportunities for the regional market.
Asia Pacific is the fastest-growing region in the market and is expected to grow at a CAGR of 16.6% over the forecast period.
Based on coverage, the third-party segment led the market with a share of 40.2% in 2025, while comprehensive is the significant growing coverage.
Based on distribution channel, the insurance agents/brokers segment dominated the market with a share of 44.2% in 2025, while direct response is the fastest-growing distribution channel.
Based on vehicle age, the new vehicle segment led the market with a share of 62.7% in 2025 and is the fastest-growing segment.
About the Author(s)
Next Generation Technologies Research Team
Technology · Next Generation TechnologiesThis report was authored by the next generation technologies research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the next generation technologies segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


