
- Home
- »
- Renewable Energy
- »
-
Carbon Credit Market Size, Share, Trends Report, 2026-2033GVR Report cover

Carbon Credit Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type, Project Type (Avoidance/Reduction Projects, Removal/Sequestration Projects), By End Use, By Region (North America, Europe, APAC, Latin America, MEA) And Segment Forecasts
Market Size, 2025
$886.8BMarket Estimate, 2026
$1,223.7BMarket Forecast, 2033
$6,129.9BCAGR, 2026–2033
25.9%Carbon Credit Market Summary
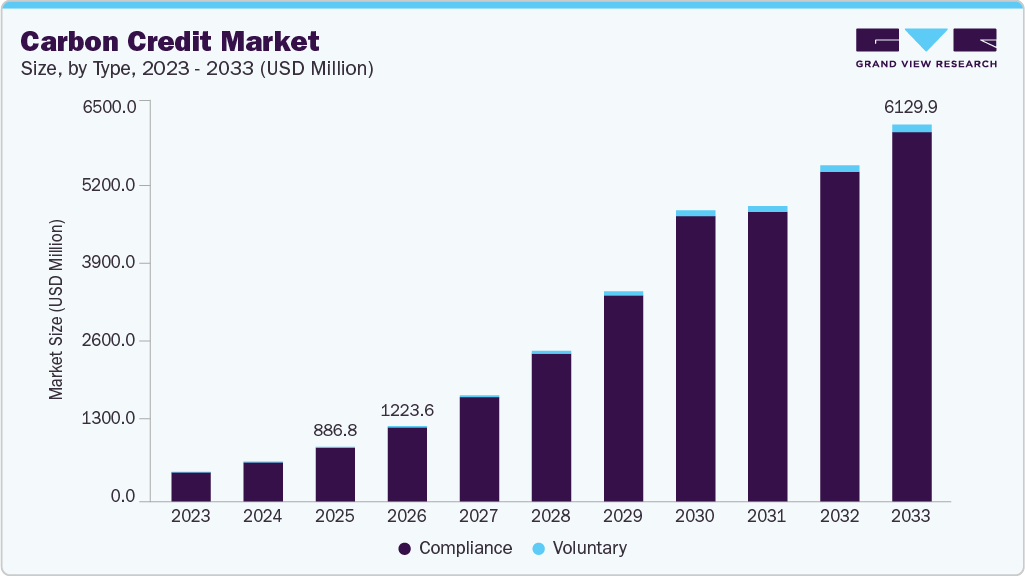
The global carbon credit market size was valued at USD 886.8 billion in 2025 and is projected to grow from USD 1223.7 billion in 2026 to USD 6129.9 billion by 2033, at a CAGR of 25.9% from 2026 to 2033. The market in Europe dominated with a revenue share of 88.7% in 2025. The demand for carbon credits has been increasing in recent years due to factors such as various government-introduced policies & regulations aimed at reducing greenhouse gas (GHG) emissions.
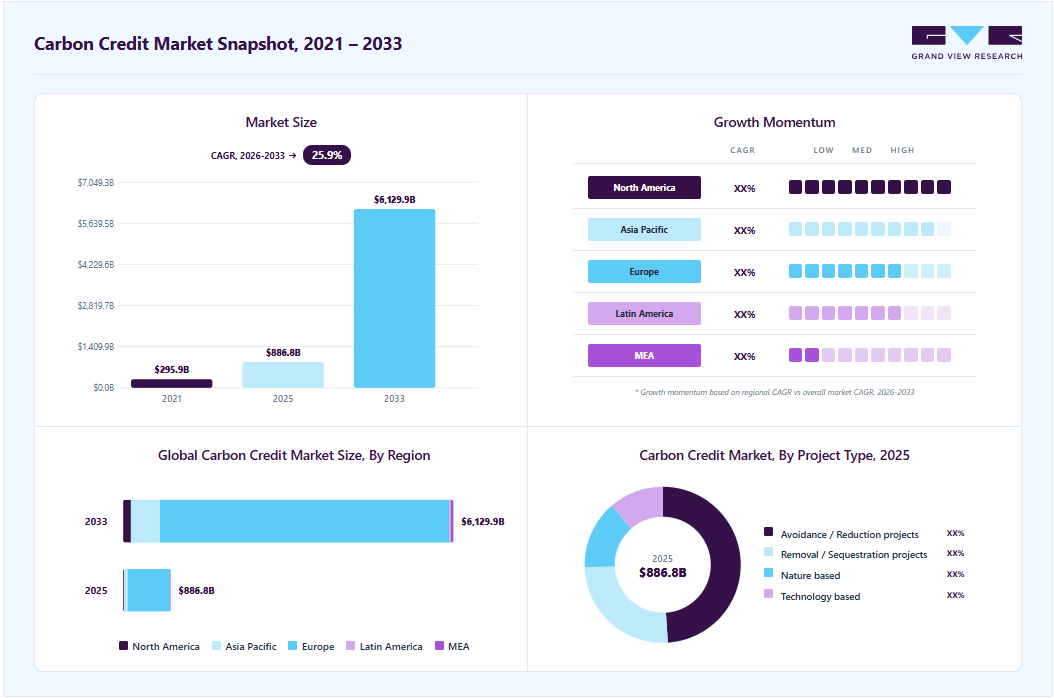 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Compliance segment held the largest revenue share of over 98% in 2025.
- By project type: Avoidance / Reduction projects turbines held the largest revenue share of over 65% in 2025.
- By end use: Power segment accounted for the largest market revenue share of over 31% in 2025.
Regional Highlights
- Largest regional market: Europe (88.7% revenue share, 2025)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 886.8 billion
- Estimated market size in 2026: USD 1223.7 billion
- Projected market size by 2033: USD 6129.9 billion
- CAGR (2026-2033): 25.9%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Companies that are subject to these regulations may need to purchase carbon credits to offset their emissions and comply with the rules. The Indian Government has passed the Energy Conservation Bill, 2022, which clears the way for establishing carbon credit markets. A combination of state-level programs and voluntary markets primarily drives the global market growth.
 To learn more about this report, Download Free Sample Report
There are also voluntary markets in the U.S. where companies can purchase carbon credits to offset their emissions. These voluntary markets are often used by companies that want to reduce their carbon footprint but are not required to do so by regulation. Overall, the U.S. market is relatively small compared to the markets in other regions, such as Europe, but it is growing and could play a larger role in reducing GHG emissions in the future. Companies are increasingly recognizing the importance of sustainability and reducing their carbon footprint as part of their corporate social responsibility initiatives.
Market Dynamics
Governments across major economies are increasingly implementing stricter emission-control policies through carbon taxes and emissions trading programs, thereby accelerating demand for carbon credits across sectors such as energy, manufacturing, transportation, and heavy industries. According to estimates published by the World Bank, over 75 carbon pricing mechanisms are active worldwide, collectively covering approximately one-fourth of global greenhouse gas emissions and generating annual revenues exceeding USD 100 billion. At the same time, growing corporate focus on ESG compliance and climate accountability is further supporting market growth, with thousands of companies globally adopting net-zero strategies and science-based decarbonization targets to reduce their carbon footprint.
Limited institutional preparedness and an underdeveloped carbon trading infrastructure across many developing economies continue to challenge the expansion of the global carbon credit market. Several emerging countries still face difficulties in establishing effective regulatory systems, carbon registries, and reliable monitoring, reporting, and verification (MRV) frameworks necessary for participation in international carbon trading under Article 6 of the Paris Agreement. According to the World Bank, many developing nations require additional financial resources, technical expertise, and governance support to build transparent and credible carbon market ecosystems. Furthermore, high project implementation costs, restricted access to climate financing, and lengthy verification procedures continue to limit participation from small-scale developers and local project operators.
Type Insights
Compliance segment held the largest revenue share of over 98% in 2025. Based on type, the market is further categorized into compliance and voluntary. In terms of revenue, the compliance segment accounted for the largest share of 98.6% in 2025. The compliance carbon credit market is a market where companies and organizations that are regulated by a government or a specific authority are required to offset their carbon emissions by purchasing carbon credits. These credits represent a reduction in GHG emissions from an approved project, such as renewable energy or energy efficiency initiatives.
The voluntary segment is projected to register the fastest CAGR of 30.9% over the forecast period, driven by increasing corporate net-zero commitments, rising demand for high-quality offset projects, and greater participation from businesses seeking flexible, non-regulated pathways to reduce their carbon footprint.
Project Type Insights
Avoidance / Reduction projects turbines held the largest revenue share of over 65% in 2025. Based on project type, the market is divided into removal/sequestration projects and avoidance/reduction projects. The removal/sequestration projects segment is further sub-segmented into technology-based and nature-based projects. In terms of revenue, the avoidance/reduction projects segment dominated the market in 2025, accounting for 65.73% share of the overall revenue. Avoidance/reduction projects involve the implementation of various strategies to avoid or reduce carbon emissions by undertaking measures for improving the energy efficiency of the system and initiating renewable energy projects.
The removal/sequestration projects segment is projected to register the highest CAGR of 26.4% over the assessment period, driven by rising demand for high-integrity carbon removal solutions, increased investment in nature-based and engineered sequestration technologies, and growing corporate preference for credits that deliver measurable and long-term climate impact.
End Use Insights
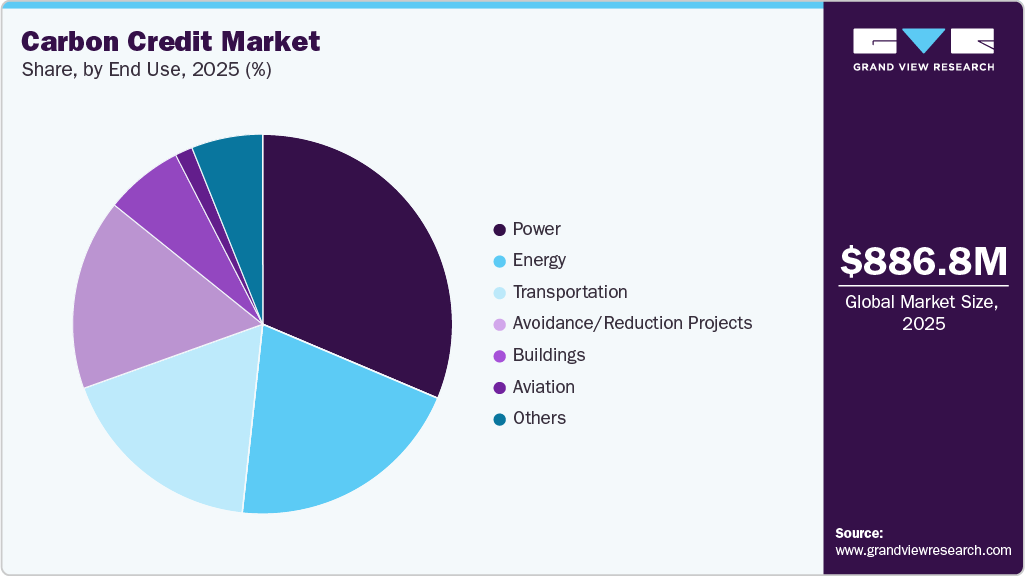
Power segment held the revenue share of over 31% in 2025. The power segment emerged as the largest segment in 2025 with a revenue share of 31.36%. The other segment includes agriculture, forestry, and waste. The power end use segment is a large emitting sector that utilizes low-GHG technologies to adopt carbon-offsetting projects and schemes. Companies worldwide are making efforts to adopt renewable energy sources, such as solar energy, wind energy, and geothermal energy, to reduce their carbon emissions and generate carbon credits. These credits can be further sold to other companies or the open market for additional revenue generation. Carbon offsets are a market-based mechanism used to mitigate GHG emissions, including those in the energy sector.
 To learn more about this report, Download Free Sample Report
The energy segment is projected to register the fastest CAGR of 27.5% over the forecast period, supported by accelerated clean energy transitions, expanding renewable project pipelines, and rising demand for credits generated from sustainable power generation initiatives.
Regional Insights
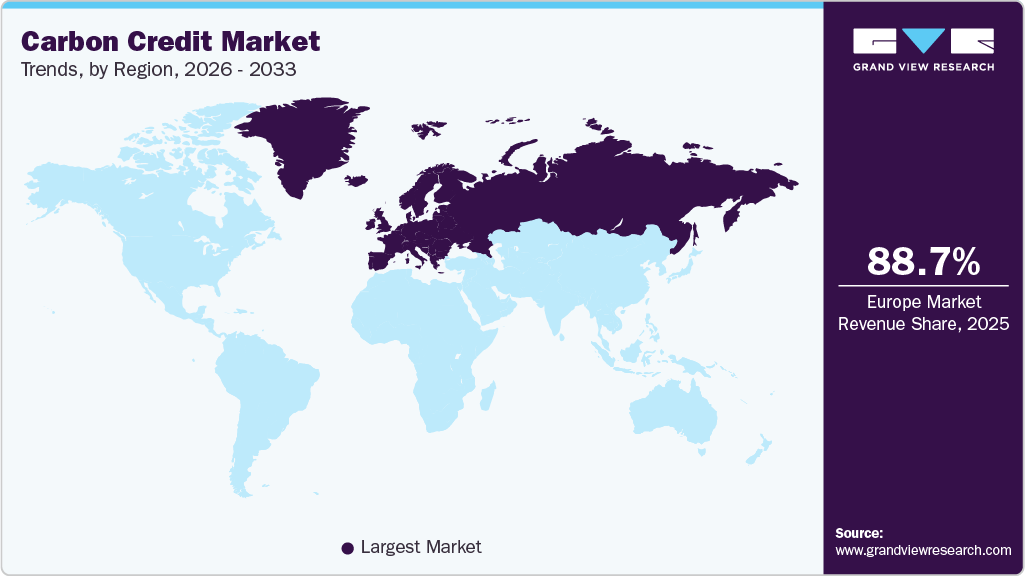
Europe held over 88.68% revenue share of the global carbon credit market. The market is based on the EU’s Emissions Trading System (ETS), which is the largest carbon market in the world. The ETS was established in 2005 and covers more than 11,000 installations in the power and industrial sectors in 31 European countries. These installations are responsible for around 45% of the EU's GHG emissions. The price of carbon offsets in the EU ETS is largely determined by supply and demand. The total supply of allowances is capped by the EU, and the price of carbon credits can fluctuate based on factors, such as economic conditions, energy prices, and climate policies. The demand for carbon credits can also be influenced by factors, such as the price of fossil fuels, the availability of renewable energy, and adoption of low-carbon technologies.
 To learn more about this report, Download Free Sample Report
North America Carbon Credit Market Trends
The North American carbon credit market growth is driven by a combination of government programs and voluntary markets. At the state level, several cap-and-trade programs have been introduced to cap the total amount of greenhouse gas emissions allowed within the state; this requires companies to purchase carbon credits to offset their emissions.
Asia Pacific Carbon Credit Market Trends
The Asia Pacific has most of the countries, such as China and India, with rapidly growing economies. Moreover, the demand for fossil fuels for energy generation is increasing owing to their increased consumption in these countries. It is anticipated to result in increased carbon emissions in the region, which is expected to boost market growth.
Latin America Carbon Credit Market Trends
The Latin America carbon credit market is growing rapidly, supported by abundant natural resources, strong potential for nature-based projects, and rising participation in compliance and voluntary markets. Countries such as Brazil, Colombia, and Peru are becoming key suppliers of high-quality credits through large-scale forestry and REDD+ initiatives. Strengthening climate policies, increasing foreign investment, and growing corporate sustainability commitments are further driving market expansion across the region.
Middle East & Africa Carbon Credit Market Trends
Countries in the region, such as UAE and Saudi Arabia, have signed international GHGs and global thermal maintenance treaties such as the Paris Agreement. These agreements made it mandatory for the countries to reduce their GHG emissions. Furthermore, companies in the region have adopted sustainability measures to reduce their carbon footprint. Hence, due to the international collaboration & agreements and these countries’ active involvement & investment in the implementation of carbon removal projects boosts the market demand.
Key Carbon Credit Company Insights
Key companies are adopting several organic and inorganic growth strategies, such as new product development, mergers & acquisitions, and joint ventures, to expand & maintain their market share. Key companies in the carbon credit market include WGL Holdings Inc, EKI Energy Services Ltd., NativeEnergy, ClearSky Climate Solutions, and 3Degrees Group, Inc., among others.
Key Carbon Credit Companies:
The following are the leading companies in the carbon credit market. These companies collectively hold the largest market share and dictate industry trends.
- 3Degrees Group, Inc.
- Carbon Care Asia Ltd.
- CarbonBetter
- ClearSky Climate Solutions
- EKI Energy Services Ltd.
- Finite Carbon
- NativeEnergy
- South Pole Group
- Torrent Power Ltd.
- WGL Holdings Inc.
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Mature Players: South Pole Group; 3Degrees Group, Inc.; NativeEnergy; Finite Carbon; Carbon Care Asia Ltd.
- Strengthen partnerships with corporations, governments, and financial institutions to support ESG and net-zero commitments.
- Invest in advanced monitoring, reporting, and verification (MRV) technologies, digital carbon platforms, and sustainability advisory services.
- Strong market presence with established carbon project development and climate advisory capabilities.
- Strong relationships with corporate buyers and increasing expertise in sustainability consulting and carbon strategy implementation.
- High operational and project verification costs associated with maintaining credit quality and transparency.
- Dependence on corporate sustainability spending and fluctuating carbon credit prices.
Emerging Players: CarbonBetter; ClearSky Climate Solutions; EKI Energy Services Ltd.
- Expand services across carbon accounting, ESG reporting, and climate risk management for enterprises.
- Increase investments in high-integrity carbon credits, renewable energy projects, and data-driven sustainability platforms.
- Increasing demand for enterprise carbon management and ESG compliance solutions supports growth potential.
- Competitive positioning in emerging voluntary carbon market opportunities and regional project development.
- Comparatively smaller global presence and limited project portfolios versus established climate solution providers.
- Financial and scalability challenges associated with expanding high-quality carbon project pipelines.
Recent Developments
- In March 2024, Toucan launched the world’s first String PV inverter market for biochar carbon credits as a response to increasing carbon credit demand.
Carbon Credit Report Scope
Report Attribute
Details
Market Definition
The carbon credit market size represents the total market value of verified carbon credits transacted across compliance and voluntary markets worldwide.
Market size in 2025
USD 886.8 billion
Estimated market size in 2026
USD 1223.7 billion
Projected market size by 2033
USD 6129.9 billion
Growth rate
CAGR of 25.9% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026-2033
Quantitative Units
Revenue in USD million, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, competitive landscape, growth factors, and trends
Segments covered
Type, project type, end use, and region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; UK; France; China; India; Japan; South Korea; Brazil; Saudi Arabia; UAE
Key companies profiled
3Degrees Group, Inc.; Carbon Care Asia Ltd.; CarbonBetter; ClearSky Climate Solutions; EKI Energy Services Ltd.; Finite Carbon; NativeEnergy; South Pole Group; Torrent Power Ltd.; WGL Holdings Inc.
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
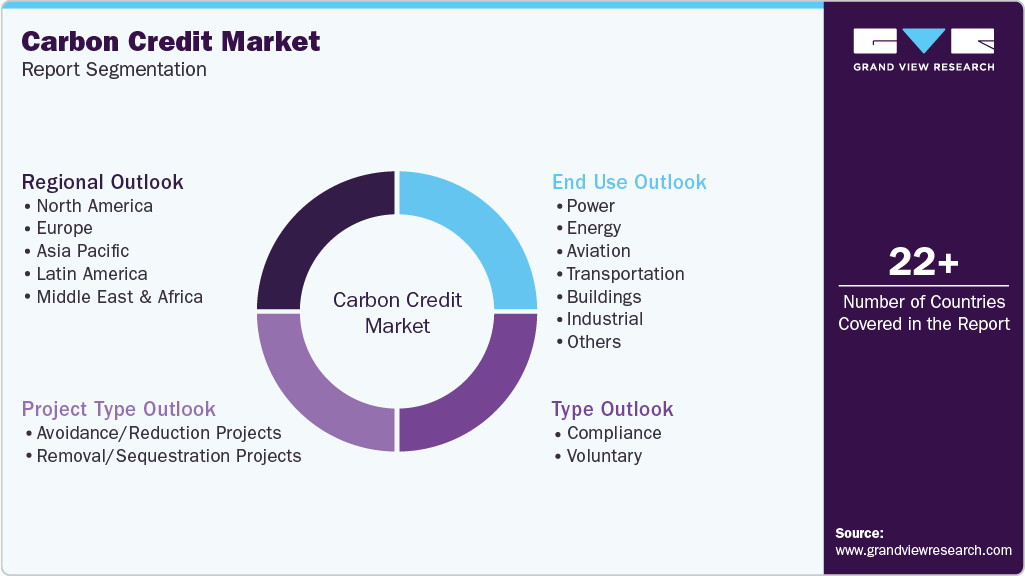
Global Carbon Credit Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the global carbon credit market report on the basis of type, project type, end use and region.
 To learn more about this report, Download Free Sample Report
-
Type (Revenue, USD Million, 2021 - 2033)
-
Compliance
-
Voluntary
-
-
Project Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Avoidance/Reduction Projects
-
Removal/Sequestration Projects
-
Nature based
-
Technology based
-
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Power
-
Energy
-
Aviation
-
Transportation
-
Buildings
-
Industrial
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
-
Latin America
-
Brazil
-
-
Middle East & Africa
-
Saudi Arabia
-
UAE
-
-
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
India Voluntary Carbon Credit Market Assessment
Assessment of the India voluntary carbon credit market covering global and India-specific market outlook, voluntary carbon standards, market sizing, and analysis of biochar, agroforestry, ERW, and methane reduction projects. The study also included project validation processes, case studies, and ecosystem mapping of project developers, NGOs, government initiatives, and corporate buyers in India.
Understanding of India’s evolving voluntary carbon market ecosystem, emerging project opportunities, technology trends, and stakeholder partnerships supporting carbon credit generation and trading activities.
Africa Carbon Credit Market & Energy Transition Assessment
Africa-focused carbon credit market study with energy transition projects and their linkage to carbon markets. The study covered clean cooking initiatives, renewable and decentralized energy projects, waste-to-energy and methane reduction projects, along with case studies and climate finance outlook analysis across the African region.
Strategic insights into Africa’s evolving energy transition landscape, emerging carbon credit generation opportunities, and the impact of climate finance and sustainability projects on regional carbon market development.
E-Bicycle-Led Carbon Credit Generation Market Assessment
A report focused on carbon credit generation through e-bicycle adoption across Europe and Japan. The study included comparative market analysis for the mobility segment, assessment of transport and last-mile delivery emissions reduction potential, regulatory framework analysis, and evaluation of e-bicycle adoption trends in carbon reduction strategies.
Provided strategic insights into mobility-driven carbon monetization opportunities, regional regulatory dynamics, and emerging business models associated with e-bicycle-based carbon credit generation and trading ecosystems.
Frequently Asked Questions About This Report
The market in Europe dominated with a revenue share of 88.7% in 2025.
The global carbon credit market is expected to grow at a compound annual growth rate of 25.9% from 2026 to 2033 to reach USD 6129.9 billion by 2033.
The market in Europe dominated with a revenue share of 88.7% in 2025.
Compliance segment held the largest revenue share of over 98% in 2025.
Avoidance / Reduction projects turbines held the largest revenue share of over 65% in 2025. Based on project type, the market is divided into removal/sequestration projects and avoidance/reduction projects.
The key factors driving the carbon credit market include the rapid expansion of renewable energy projects such as solar and wind, coupled with rising corporate and governmental commitments to reduce greenhouse gas emissions.
The global carbon credit market size was estimated at USD 886.8 billion in 2025 and is expected to reach USD 1223.7 billion in 2026.
Based on the end-use segment, Power held the largest revenue share of more than 31.36% in 2025.
Some of the key vendors operating in the global carbon credit market include 3Degrees Group, Inc. Carbon Care Asia Ltd. CarbonBetter. ClearSky Climate Solutions. EKI Energy Services Ltd. Finite Carbon. NativeEnergy. South Pole Group. Torrent Power Ltd. WGL Holdings Inc., among others.
About the Author(s)
Renewable Energy Research Team
Energy & Power · Renewable EnergyThis report was authored by the renewable energy research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the renewable energy segment of the energy & power industry. All findings are based on proprietary energy & power databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


