
- Home
- »
- Food Additives & Nutricosmetics
- »
-
Carrageenan Market Size, Share And Trends Report, 2033GVR Report cover

Carrageenan Market (2026 - 2033)
Size, Share & Trends Analysis Report By Processing Technology (Semi-refined, Gel Press, Alcohol Precipitation), By Function, By Product Type, By Application, By Region, And Segment Forecasts
Market Size, 2025
$1.0BMarket Estimate, 2026
$1.1BMarket Forecast, 2033
$1.5BCAGR, 2026–2033
4.6%Carrageenan Market Summary
The global carrageenan market size was valued at USD 1.0 billion in 2025 and is projected to grow from USD 1.1 billion in 2026 to USD 1.5 billion by 2033, at a CAGR of 4.6% from 2026 to 2033. Europe dominated the market, accounting for a revenue share of 34.0% in 2025. Increasing product penetration in dairy and processed meat products on account of carrageenan’s mouthfeel characteristics to imitate a fatty feeling is expected to boost market growth over the forecast period.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By processing technology: Semi-refined held a dominant position, contributing 50.2% of total revenue in 2025.
- By function: Thickening agent segment accounted for the largest revenue share of 37.9% in 2025.
- By product type: In 2025, the kappa segment captured the largest revenue share of 68.7% in the market.
- By application: The food & beverage segment dominated the market in 2025, representing 72.9% of total revenue.
Regional Highlights
- Largest regional market: Europe (34.0% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: Germany held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 1.0 billion
- Estimated market size in 2026: USD 1.1 billion
- Projected market size by 2033: USD 1.5 billion
- CAGR (2026-2033): 4.6%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The primary factor contributing to the wide usage of carrageenan in the food industry is its capability to bind with water and enhance the properties of food ingredients. A rising preference for food and pharmaceutical products with ingredients derived from plant sources instead of animal-derived ingredients, such as gelatin, is likely to increase the product demand.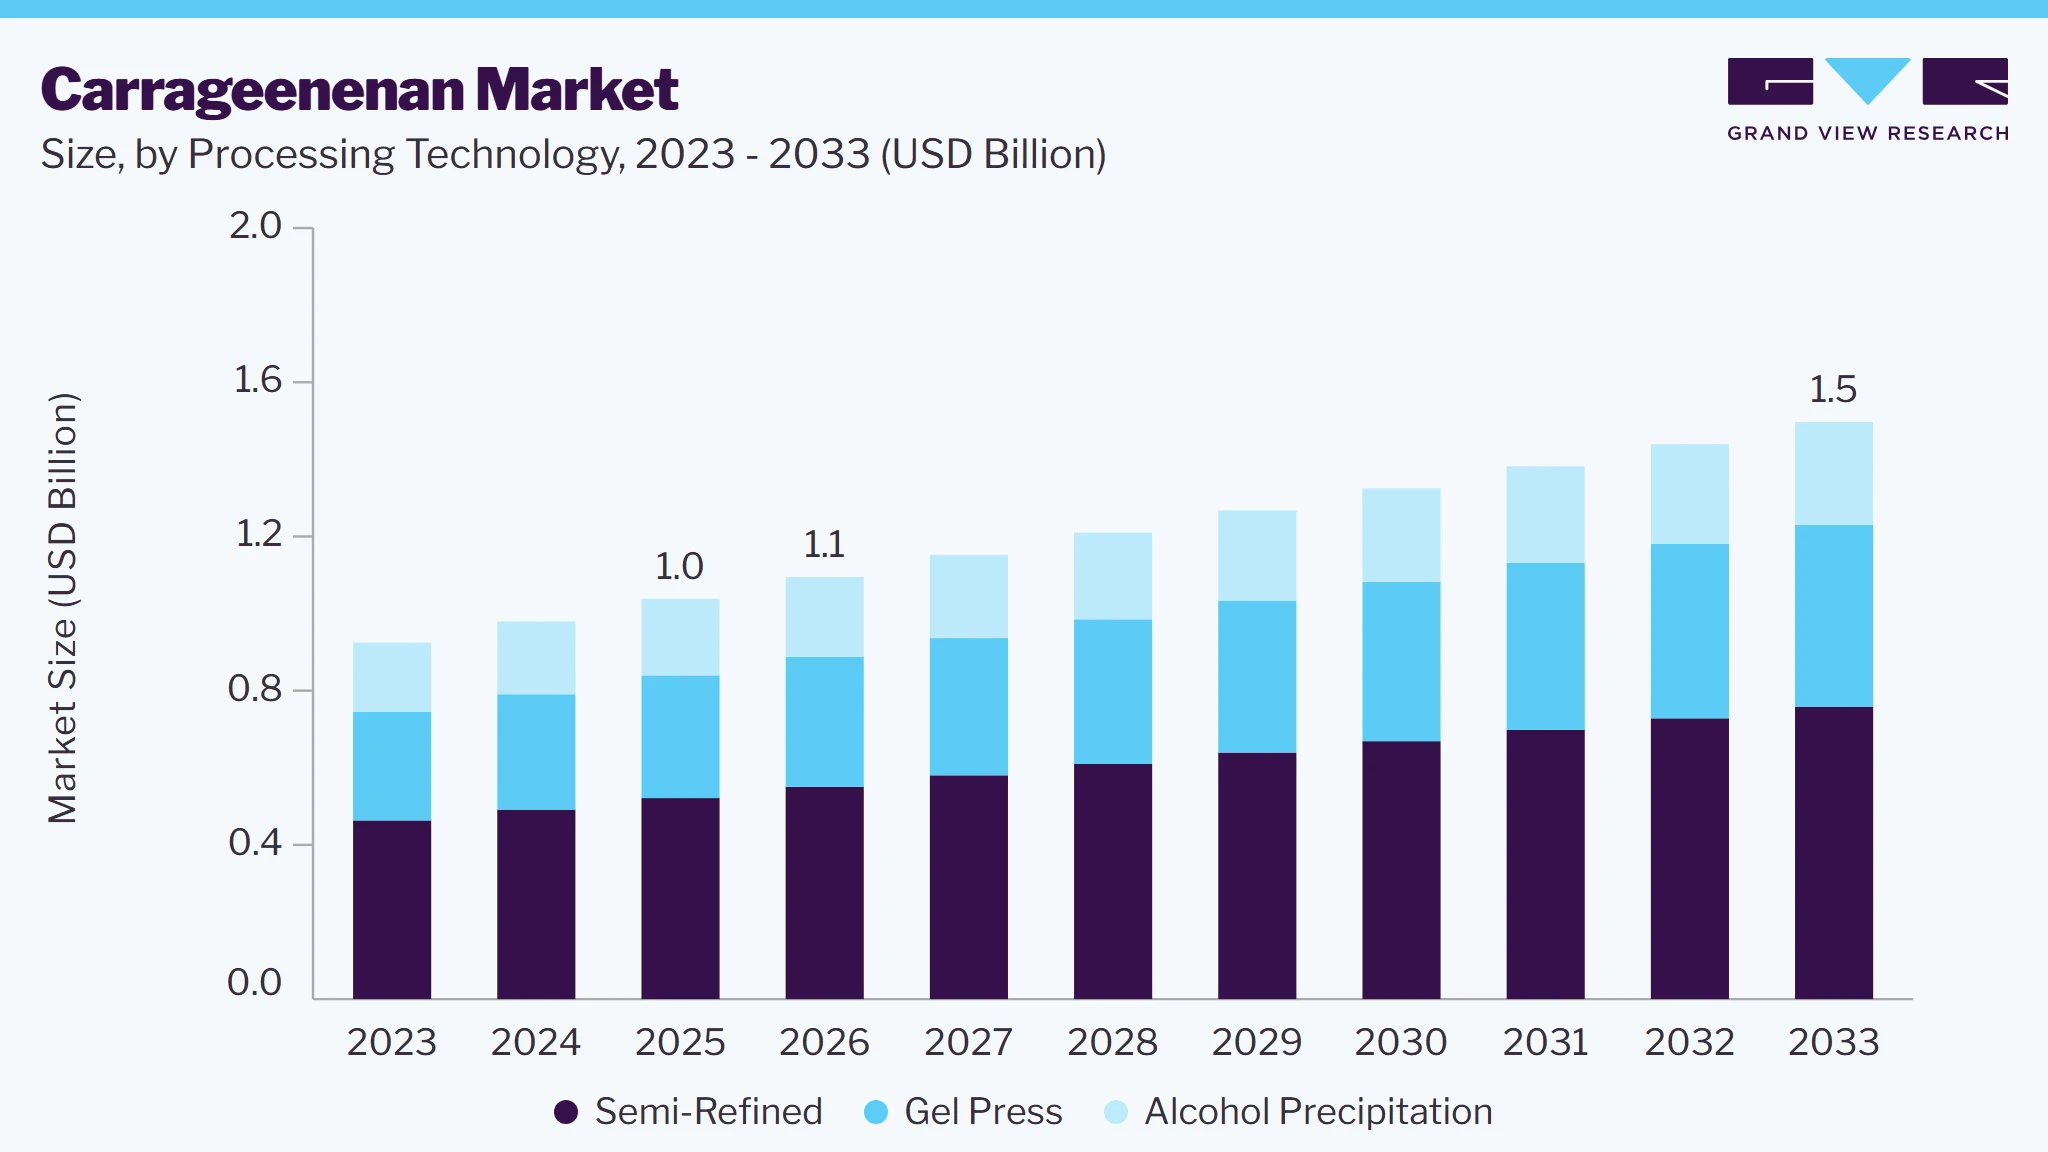 To learn more about this report, Download Free Sample Report
The U.S. accounted for the largest revenue share in 2022 in the North American market. The U.S. is a mature market for processed food products having a large food manufacturing base in the country, making the product a highly in-demand additive for food processing applications, as a thickening and gelling agent.
The product is majorly utilized as a viscosity control agent in personal care products and water-based cosmetics due to its water-binding capacity. It functions as a thickening, stabilizing, and suspending agent in sunscreens, lotions, and body washes. For instance, products such as L'Oréal’s Pure-clay Glow-mask and Natural Moisturizing Lubricant of DreamBrands Inc. contain carrageenan.
The cultivation of the product has led to positive socio-economic development in coastal countries. In Asia Pacific, carrageenan cultivation and processing are increasing particularly in Southeast Asian countries due to the favorable climatic conditions. Technologies such as semi-refined type processing are widely used by small and medium-scale players in these countries owing to comparatively easier processes and lower processing costs.
In this industry, product differentiation depends on raw material and extraction processes followed. Kappa and iota types are suitable for use as gelling agents, whereas lambda is majorly used as a thickening agent as it does not have the ability to form a gel. For instance, Cargill, Incorporated has developed Satiagel ADG 0220 Seabird carrageenan that can be used for gelled dairy desserts. The company has further diversified the product range by developing Seabrid carrageenan, which can be utilized for creamy dairy desserts as a texturizing agent.
It is further considered as a treatment against COVID-19 due to its antiviral properties. In December 2020, a clinical trial was initiated collaboratively by the Cardiff University, Marinomed Biotech AG, Walgreens Boots Alliance, and Abertawe Bro Morgannwg University Health Board for analyzing the efficacy of carrageenan nasal and throat spray against COVID-19.
Market Dynamics
The carrageenan market is witnessing steady growth, driven by increasing demand for natural hydrocolloids across the food & beverage, pharmaceutical, and personal care industries. Rising consumption of processed and convenience foods, coupled with the growing preference for clean-label and plant-based ingredients, continues to support market expansion. At the same time, fluctuations in seaweed raw material availability, evolving regulatory requirements, and price volatility present ongoing challenges.
The growing consumer preference for clean-label, naturally derived, and plant-based food products is a key factor driving the carrageenan market. Food manufacturers are increasingly incorporating carrageenan as a multifunctional ingredient that provides thickening, gelling, stabilizing, and texturizing properties while meeting the industry's shift toward naturally sourced formulations. Its compatibility with dairy, plant-based beverages, processed meat, and dessert applications has strengthened its adoption across a wide range of food products.
The rapid expansion of the global plant-based food and beverage industry is creating sustained demand for carrageenan as an effective stabilizer and texture enhancer. Manufacturers are investing in product innovation and reformulation to improve product quality, shelf life, and consumer appeal, further supporting market growth. As demand for functional, convenient, and premium food products continues to increase, carrageenan is expected to remain an essential ingredient in modern food processing.
The carrageenan market faces a significant challenge from fluctuations in the availability and pricing of red seaweed, the primary raw material used for carrageenan production. Seaweed cultivation is highly dependent on climatic conditions, ocean temperature changes, and disease outbreaks, which can disrupt harvest volumes and create supply imbalances. These uncertainties directly impact production costs and reduce pricing stability for manufacturers.
Increasing competition for high-quality seaweed and supply chain disruptions can affect the consistent availability of raw materials, particularly for producers reliant on imports. Rising procurement costs place pressure on manufacturers' profit margins and may result in higher product prices for end-use industries. Consequently, raw material volatility remains a key restraint limiting the steady expansion of the carrageenan market.
The increasing use of carrageenan beyond food applications presents a significant growth opportunity for the Carrageenan Market. In the pharmaceutical industry, carrageenan is widely utilized as a stabilizer, gelling agent, and controlled-release excipient in tablets, syrups, topical formulations, and oral care products. Similarly, the personal care sector is incorporating carrageenan into skincare, haircare, and cosmetic formulations due to its natural origin, moisture-retention properties, and formulation stability.
Growing consumer demand for naturally derived ingredients and the shift toward sustainable product formulations are encouraging manufacturers to expand the use of carrageenan across high-value applications. Continuous product innovation, coupled with increasing investments in bio-based ingredients, is expected to strengthen its adoption in pharmaceutical and personal care products, creating new revenue opportunities for market participants.
Analyst Perspective
The Carrageenan Market is expected to witness steady growth, supported by rising demand for natural hydrocolloids across the food & beverage, pharmaceutical, and personal care industries. Increasing adoption of clean-label and plant-based formulations, coupled with continuous product innovation and advancements in sustainable seaweed sourcing, is strengthening market prospects. Although raw material price volatility and supply chain constraints remain key challenges, expanding applications in high-value end-use industries are anticipated to create long-term growth opportunities for market participants.
Processing Technology Insights
By processing technology, semi-refined held a dominant position, contributing 50.2% of total revenue in 2025. A semi-refined process is a cost-effective method, thereby gaining traction in the market. Semi-refined carrageenan (SRC) contains insoluble matter, such as cellulose. The advent in technology has led to the emergence of food-grade semi-refined carrageenan, increasing its application in food products, thereby boosting its demand.
In the majority of countries across the globe, semi-refined carrageenan has been tested safe for human consumption and thus can be used in food applications. For instance, semi-refined carrageenan is approved as an ‘E407a’ food additive according to the European Union (EU) regulation 2012/231/EU.
Alcohol precipitation is traditionally used for carrageenan extraction from seaweed, which gives a refined and purified form of the product. However, multiple steps involved in the alcohol precipitation method increase the cost of overall processing which is expected to hamper the segment growth.
Gel press is mainly used to make kappa-type carrageenan as seaweed such as Eucheumacottonii can only be processed through this method. Kappa-type carrageenan has the ability to form a gel when treated with potassium salts such as KCl used in the gel press method.
Function Insights
Thickening agent segment accounted for the largest revenue of 37.9% in 2025. This can be attributed to the rising demand for clean-label thickeners in the food and pharmaceutical industry. The gelling agent segment held a significant revenue share in 2022 owing to the increasing demand for plant-derived gelling additives that can be readily used in vegan products.
The stabilizer segment is expected to grow rapidly with a surge in demand from the bakery, confectionery, and beverage applications. Stabilizers are used to prevent the formation of undesirable ice crystals and improve the texture properties of the product. For instance, a carrageenan stabilizer can improve the mouthfeel of beverages, such as kombucha and coconut water.
The others segment includes carrageenan functionalities such as binding agents and emulsifiers. The others segment is expected to expand at the highest CAGR due to increase in the product demand from manufacturers of ready-to-eat and packaged food products. Constant efforts to phase out genetically modified organisms (GMOs) and partially hydrogenated oils (PHO) based emulsifiers are likely to support the growth of the industry.
Product Type Insights
In 2025, the kappa segment captured the largest revenue share of 68.7% in the market. It is the most used product type in ice creams, cheese, puddings, and chocolates. For instance, MCLS EUROPE, a wholly-owned subsidiary of Mitsubishi Corporation, offers pure refined Kappa carrageenan that can be used in dairy and dessert products as gelling and swelling agents and fat replacers.
Iota carrageenan is being studied for its anti-viral properties. As per a study published on August 09, 2021, by the Journal of Pharmacology Research & Perspectives, nasally administered iota-carrageenan resulted in an increase in the recovery rate of common cold patients. The increase in recovery rate was 139% for those with coronavirus infections; 119% for influenza A infections; and 70% for rhinovirus infection.
Lambda held a relatively lower revenue share in 2022 and is majorly prepared by the alcohol precipitation method. Lambda is a non-gelling sulfated carrageenan extracted from red seaweed. It has a high viscosity and is thereby widely used as a thickening agent in dairy products.
Application Insights
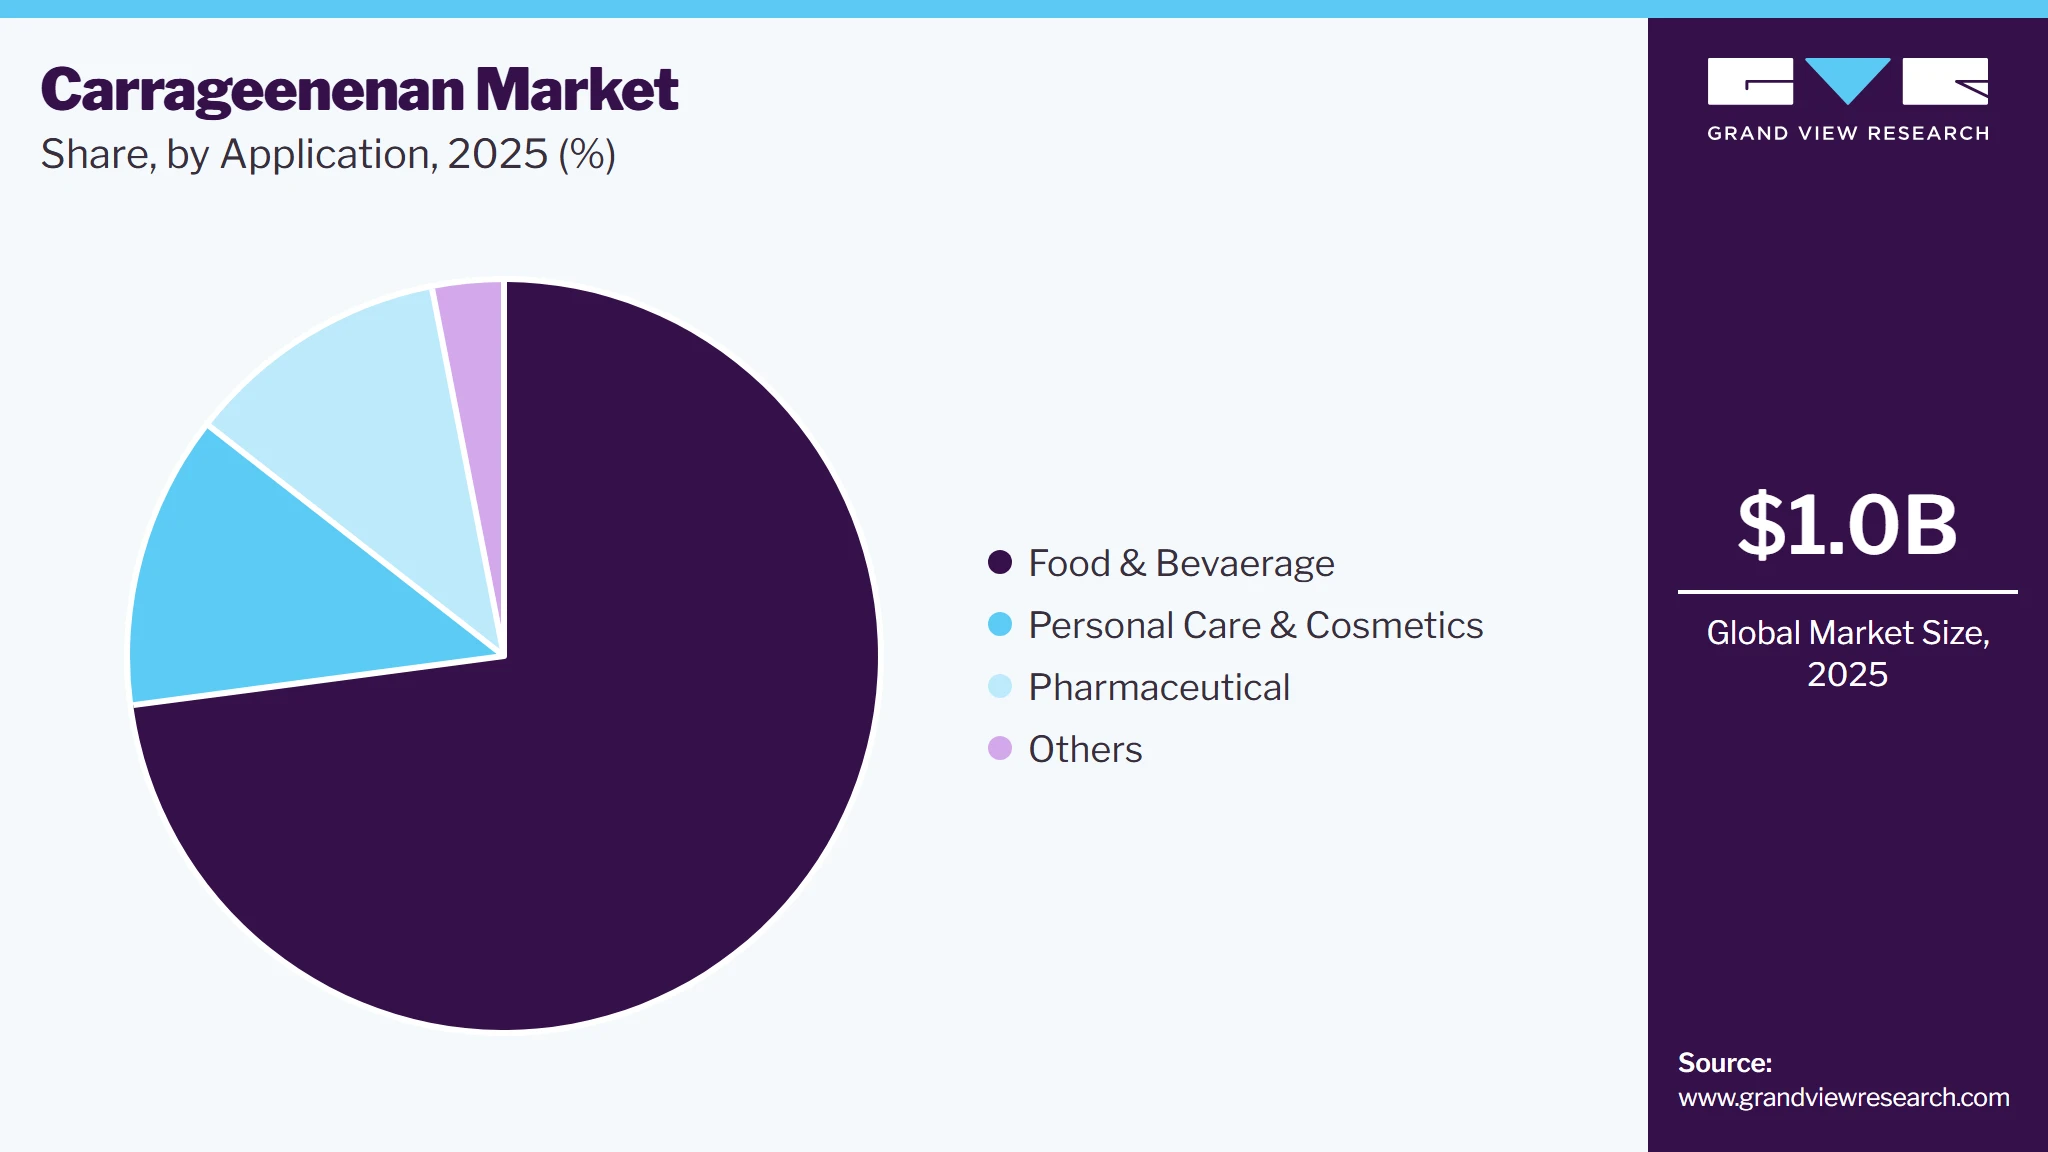
The food & beverage segment dominated the market in 2025, representing 72.9% of total revenue. Carrageenan finds application in bakery, dairy, and meat products and beverages. Carrageenan is added to these products to alter viscosity or texture, which, in turn, improves their sensory properties.
It is utilized as excipients in drug delivery systems. It is also used as a foaming, wetting, solubilizing, and stabilizing agent in pharmaceutical products. Rising R&D investment in drug formulations for the production of stable and effective products is expected to fuel the segment growth.
 To learn more about this report, Download Free Sample Report
The personal care and cosmetics segment is expected to expand at the highest revenue-based CAGR over the projected period on account of the rising applications of the product in the end-use market. This product is added in water-based personal care and cosmetic products as a viscosity control agent owing to its water-binding property.
Other applications include the agriculture industry. The use of the product in agricultural applications represents a promising approach for developing plant growth and plant defense techniques. Carrageenan is also used as thickeners and rheology modifier agents in textile printing.
Regional Insights
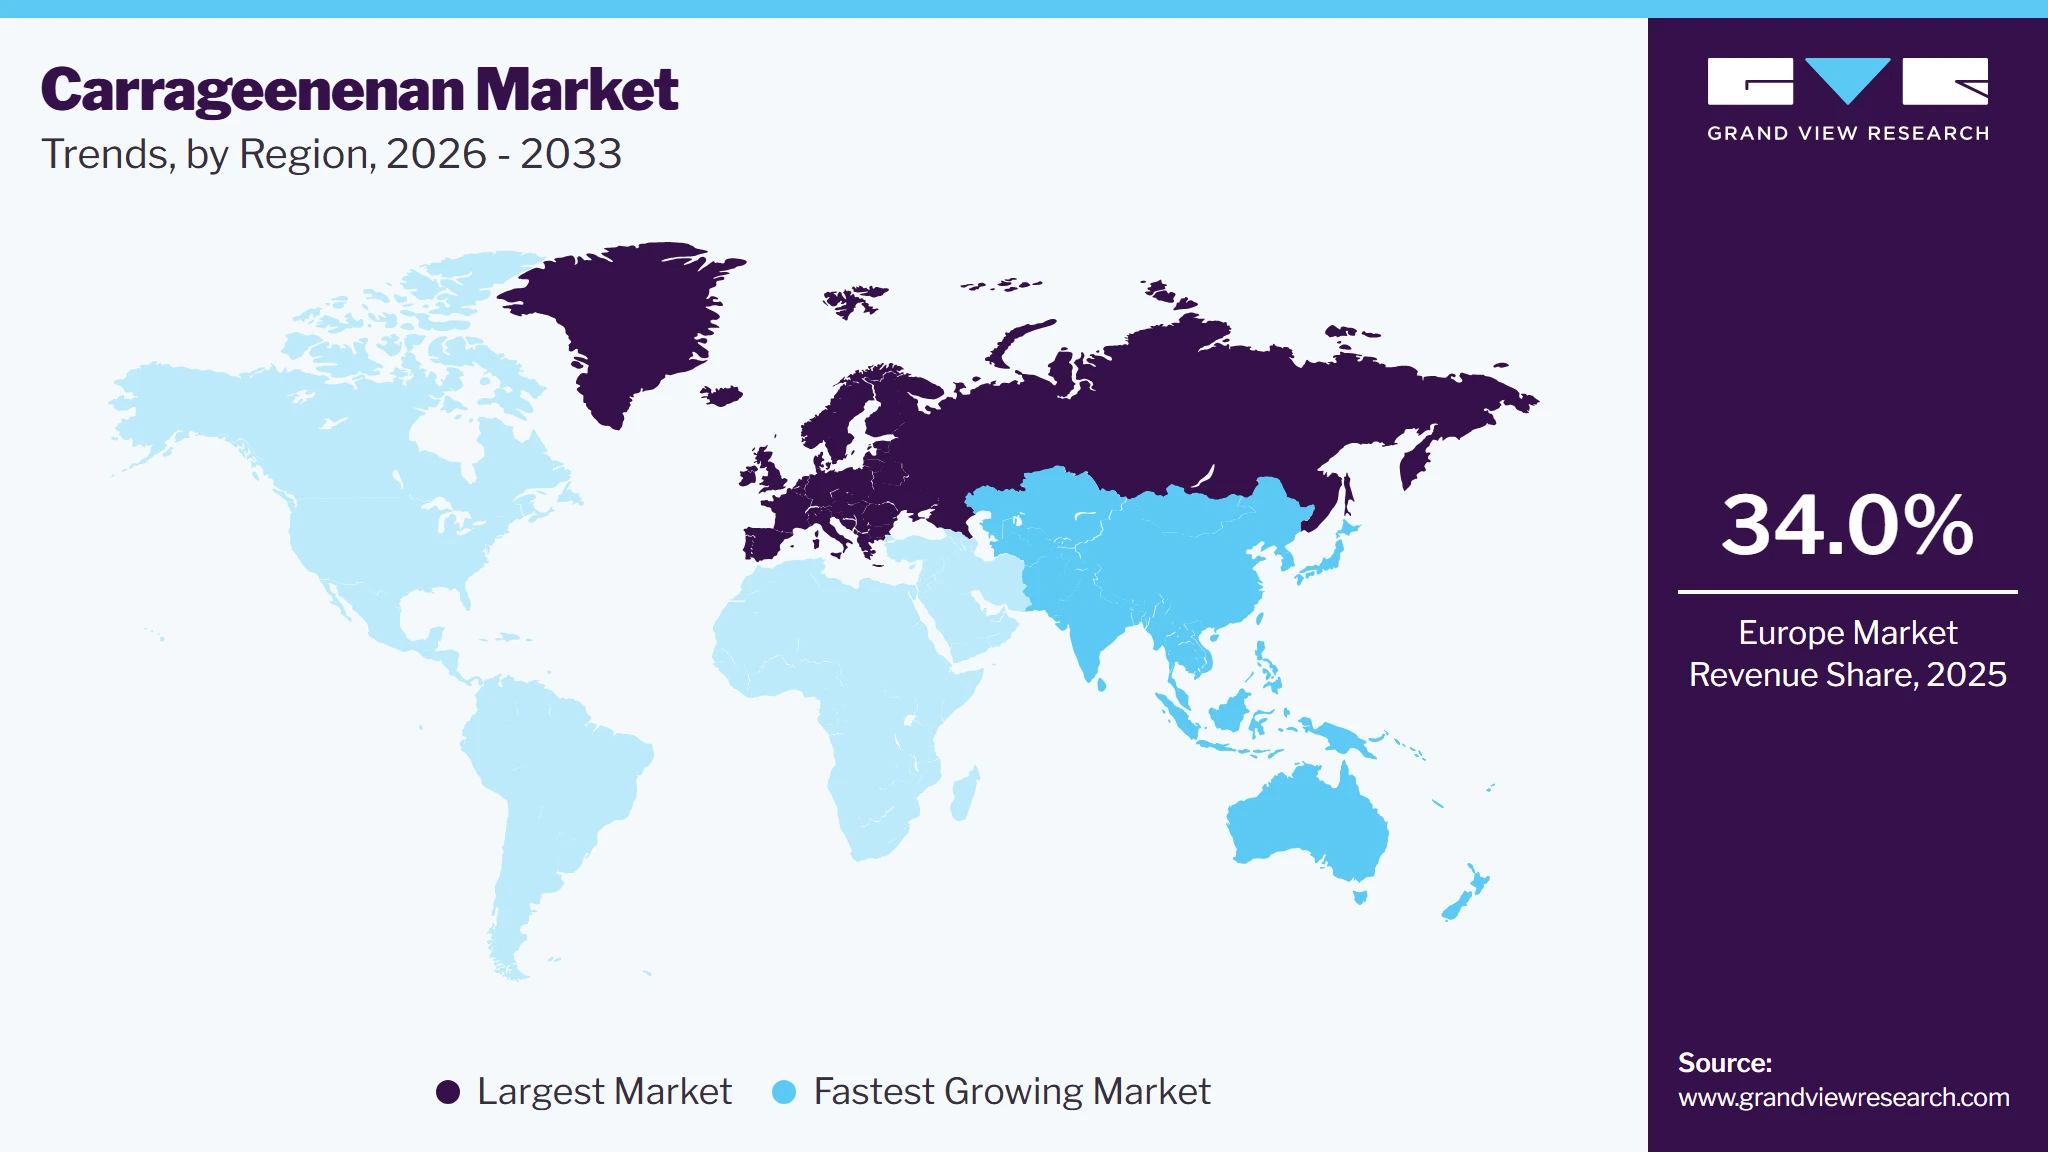
Europe dominated the carrageenan market with the highest revenue share of 34.0% in 2025. Germany dominated the North America carrageenan market in 2025. The growth in the European region can be attributed to favorable government policies. The gel-press technique is gaining popularity in the region since the demand for alcohol precipitated carrageenan incurs higher manufacturing costs. In Europe, both types of carrageenan: refined and semi-refined are approved by the European Union to be used in food products under food additive codes E407 and E 407a, respectively, thus boosting the product demand.
 To learn more about this report, Download Free Sample Report
In 2022, North America accounted for a considerable revenue share. Seaweed processing is increasing in the U.S. and Canada, which is expected to support the market growth in the region. As per the Food and Agricultural Organization, the U.S. was one of the top 10 exporters of seaweed-based hydrocolloids in 2019, accounting for a 4.82% share in the exports of seaweed-based hydrocolloids globally.
The market in the Asia Pacific is likely to expand at the fastest growth rate in terms of revenue over the forecast period. The presence of major food industry players such as China Mengniu Dairy Co. Ltd., and Inner Mongolia Yili Industrial Group Co., Ltd. has resulted in the significant growth of the overall food and beverage industry in China, thus fueling the product demand.
The product demand in Central and South America is primarily driven by Brazil with the growth of the end-use industries. For instance, as per the USDA, the food retail sector in Brazil is expected to grow by 4.5% in 2021, thereby propelling the industry growth.
Key Companies & Market Share Insights
The companies active in the market are focusing on partnerships with small-sized companies having a strong foothold in the local markets. For instance, in August 2020, CP Kelco and Biesterfeld announced an expansion of their partnership in the food and nutrition segment in Europe. As a part of this partnership, Biesterfeld is expected to distribute the former’s carrageenan products in European countries.
Major players engaged in the manufacturing of carrageenan have a global reach owing to their wide geographical presence with several manufacturing facilities and sales offices spread across the major continents.
Key Carrageenan Companies
The following key companies have been profiled for this study on the carrageenan market:
-
DuPont
-
Ingredion Incorporated
-
Ashland
-
CP Kelco U.S., Inc.
-
Cargill, Inc.
-
Ceamsa
-
W Hydrocolloids, Inc.
-
Gelymar
-
Caldic B.V.
-
Ina Food Industry Co. Ltd.
-
PT. Gumindo Perkasa Industri
-
ACCEL Carrageenan Corporation
-
BLG
-
MCPI Corporation
-
AEP Colloid
-
Marcel Carrageenan
-
TBK Manufacturing Corporation
-
Shemberg Ingredients and Gums Corporation
-
Prinova Group LLC
-
LAUTA Ltd.
-
Aquarev Industries
-
Bang &Bonsomer
-
AgargelIndustria e ComercioLtda
-
Zhenpai Hydrocolloids Co., Ltd.
-
Tate & Lyle
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (DuPont
Ingredion Incorporated
Ashland
CP Kelco U.S., Inc.
Cargill, Inc.
Ceamsa
Caldic B.V.
Tate & Lyle
Prinova Group LLC
Ina Food Industry Co. Ltd.)
- Focus on product innovation, diversified hydrocolloid portfolios, strategic acquisitions, global distribution networks, long-term supply agreements, and investments in sustainable sourcing and R&D.
- Strong global brand recognition, extensive manufacturing capabilities, integrated supply chains, advanced processing technologies, broad customer base, and robust regulatory compliance.
- Higher operating costs, complex organizational structures, and slower implementation of product or market-specific changes due to their large global operations.
Emerging Players (W Hydrocolloids, Inc.
Gelymar
PT. Gumindo Perkasa Industri
ACCEL Carrageenan Corporation
BLG
MCPI Corporation
AEP Colloid
Marcel Carrageenan
TBK Manufacturing Corporation
Shemberg Ingredients and Gums Corporation
LAUTA Ltd.
Aquarev Industries
Bang & Bonsomer
Agargel Industria e Comercio Ltda
Zhenpai Hydrocolloids Co., Ltd.)
- Concentrate on expanding production capacity, strengthening regional distribution, improving cost competitiveness, developing customized carrageenan grades, and entering export markets through partnerships.
- Greater operational flexibility, competitive pricing, proximity to seaweed sourcing regions, faster response to customer requirements, and specialization in niche or regional applications.
- Limited global presence, comparatively lower R&D investment, dependence on regional raw material availability, and lower brand recognition in international markets.
Carrageenan Market Report Scope
Report Attribute
Details
Market size in 2025
USD 1.0 billion
Estimated market size in 2026
USD 1.1 billion
Projected market size by 2033
USD 1.5 billion
Growth rate
CAGR of 4.6% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, Volume in kilotons and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Processing technology, function, product type, application, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; U.K.; Germany; France; Italy; China; Japan; India; South Korea; Brazil; Argentina; Saudi Arabia; South Africa
Key companies profiled
DuPont; Ingredion Incorporated; Ashland; CP Kelco U.S., Inc.; Cargill, Inc.; Ceamsa; W Hydrocolloids, Inc.; Gelymar; Caldic B.V.; Ina Food Industry Co. Ltd.; PT. Gumindo Perkasa Industri; ACCEL Carrageenan Corporation; BLG; MCPI Corporation; AEP Colloid; Marcel Carrageenan; TBK Manufacturing Corporation; Shemberg Ingredients and Gums Corporation; Prinova Group LLC; LAUTA Ltd.; Aquarev Industries; Bang &Bonsomer; Agargel Industria e ComercioLtda; Zhenpai Hydrocolloids Co., Ltd.; Tate & Lyle
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Carrageenan Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis on the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global carrageenan market report based on processing technology, function, product type, application, and region:
-
Processing Technology Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Alcohol Precipitation
-
Gel Press
-
Semi-refined
-
-
Function Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Thickening Agent
-
Gelling Agent
-
Stabilizer
-
Others
-
-
Product Type Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Kappa
-
Iota
-
Lambda
-
-
Application Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Food & Beverage
-
Bakery
-
Confectionery
-
Meat Products
-
Dairy Products
-
Sauces & Dressings
-
Beverages
-
Others
-
-
Pharmaceutical
-
Personal Care & Cosmetics
-
Others
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
France
-
U.K.
-
Italy
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Arabia
-
South Africa
-
-
Research Methodology
The carrageenan market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each carrageenan segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Processing Technology
Revenue capture definition
Alcohol Precipitation
Revenue captured under this segment includes sales generated from carrageenan produced using alcohol precipitation technology for high-purity food, pharmaceutical, and specialty industrial applications.
Gel Press
Sales derived from carrageenan processed using gel press technology for food processing and commercial industrial applications are considered within this segment.
Semi-refined
The segment represents revenue associated with semi-refined carrageenan supplied to processed meat, pet food, and other cost-sensitive end-use industries.
Segment - Function
Revenue capture definition
Thickening Agent
This segment comprises revenue generated from carrageenan utilized to enhance viscosity and texture across food & beverages, pharmaceuticals, personal care products, and industrial formulations.
Gelling Agent
Revenue within this segment is attributed to carrageenan used for gel formation in dairy products, confectionery, processed foods, pharmaceutical products, and related applications.
Stabilizer
The segment covers sales of carrageenan employed to maintain product stability, improve consistency, and prevent ingredient separation across multiple industries.
Others
Revenue generated from carrageenan used for water binding, suspension, emulsification, moisture retention, and other specialized functional applications is captured in this segment.
Segment - Product Type
Revenue capture definition
Kappa
This segment represents sales generated from kappa carrageenan supplied to dairy, processed meat, confectionery, plant-based food, and other commercial applications.
Iota
Revenue attributed to iota carrageenan used in dairy desserts, gels, pharmaceutical formulations, and personal care products is included within this segment.
Lambda
The segment encompasses sales of lambda carrageenan utilized for thickening beverages, sauces, dairy products, dressings, and pharmaceutical liquid formulations.
Segment - Application
Revenue capture definition
Food & Beverage
Sales generated from the use of carrageenan in dairy products, processed meat, beverages, bakery, confectionery, desserts, and plant-based foods are reflected in this segment.
Pharmaceutical
This segment includes the commercial value of carrageenan supplied for tablet manufacturing, syrups, topical formulations, oral care products, and other pharmaceutical applications.
Personal Care & Cosmetics
Revenue is derived from carrageenan incorporated into skincare, haircare, cosmetic, and personal hygiene formulations to enhance product performance and stability.
Others
The segment captures revenue from carrageenan utilized across biotechnology, animal nutrition, textile processing, industrial manufacturing, and other emerging end-use applications.
Estimation Model
Layer Name
Key Question
Description
Raw Material & Supply Analysis
How does the availability of red seaweed influence the market?
Assesses seaweed cultivation, raw material sourcing, regional supply dynamics, processing infrastructure, and pricing trends to understand their impact on carrageenan production and profitability.
Processing Technology Analysis
Which processing technologies generate the highest commercial value?
Estimates market revenue across alcohol precipitation, gel press, and semi-refined processing technologies based on production volumes, product quality, manufacturing costs, and industry adoption.
End-use Industry Analysisr
Which application industries are driving market demand?
Quantifies revenue generated from food & beverage, pharmaceutical, personal care & cosmetics, and other industries based on consumption patterns, product innovation, and regulatory developments.
Revenue Estimationr
What is the estimated revenue generated by the global carrageenan market?
Estimates market revenue by analyzing carrageenan production volumes, average selling prices (ASPs), regional consumption patterns, trade statistics, company financials, and demand across key end-use industries.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Segmentation
A comprehensive regional assessment of the carrageenan market was conducted across North America, Europe, Asia Pacific, Latin America, and Middle East & Africa. The study evaluated country-level demand for kappa, iota, and lambda carrageenan while assessing processing technology adoption, functional applications, and consumption across food & beverage, pharmaceutical, personal care & cosmetics, and other industries. Seaweed cultivation, processing capacity, and regional manufacturing trends were also examined.
Provides deeper visibility into regional consumption patterns, production clusters, and country-level growth opportunities. Supports market expansion planning, supply chain optimization, and strategic investment decisions.
Competitive Benchmarking
Leading carrageenan manufacturers were benchmarked based on processing capabilities, product portfolio, raw material sourcing, production capacity, global distribution network, application expertise, sustainability initiatives, and strategic developments. Competitive positioning across food ingredients, pharmaceutical excipients, and personal care applications was also evaluated.
Helps identify competitive strengths, operational capabilities, and market positioning gaps. Facilitates strategic differentiation, partnership evaluation, and long-term competitive planning.
Opportunity Assessment
Emerging opportunities were assessed across clean-label food formulations, plant-based dairy alternatives, processed meat products, pharmaceutical formulations, and natural personal care ingredients. The analysis also examined demand generated by functional food innovation, sustainable hydrocolloid adoption, and expanding processed food consumption.
Enables identification of high-growth application areas and future investment opportunities. Supports innovation planning, product portfolio expansion, and long-term business growth strategies.
Frequently Asked Questions About This Report
The global carrageenan market size was estimated at USD 1.0 billion in 2025 and is projected to grow from USD 1.1 billion in 2026.
Some of the key players operating in the global carrageenan market include DuPont, Ingredion Incorporated, Ashland, CP Kelco U.S., Inc, Cargill, Inc., Ceamsa, W Hydrocolloids, Inc, Gelymar, Caldic B.V., Ina Food Industry Co Ltd., PT. Gumindo Perkasa Industry, ACCEL Carrageenan Corporation, BLG, MCPI Corporation, AEP Colloid, Marcel Carrageenan, and TBK Manufacturing Corporation among others.
Wide applicability for the product market in the food & beverage, oil, and gas, pharmaceutical industry owing to its multi-functionality, especially its ability to modify the viscosity of substances are key factors driving the carrageenan market in the forecast period.
By processing technology, semi-refined held a dominant position, contributing 50.2% of total revenue in 2025. The segment's dominance is attributed to its cost-effective production process and widespread adoption in processed meat, pet food, and other food applications where functional performance is prioritized over high purity.
The Thickening Agent segment accounted for the largest revenue share of 37.9% in 2025. Its leading position is driven by the extensive use of carrageenan to improve viscosity, texture, and mouthfeel across dairy products, beverages, sauces, desserts, and processed foods. Growing demand for clean-label, plant-based, and convenience food products has further accelerated the adoption of carrageenan as a natural thickening ingredient in food and beverage formulations.
The Food & Beverage segment dominated the market in 2025, representing 72.9% of total revenue. This dominance is driven by the extensive use of carrageenan as a thickening, gelling, and stabilizing ingredient in dairy products, processed meat, confectionery, beverages, bakery products, and plant-based foods. Rising demand for convenience foods, clean-label formulations, and improved product texture and shelf life continues to strengthen carrageenan consumption across the global food and beverage industry.
Europe dominated the Carrageenan Market with the highest revenue share of 34.0% in 2025. The region's leadership is driven by the strong presence of established food and beverage manufacturers, increasing demand for clean-label and plant-based products, and widespread adoption of carrageenan in dairy, bakery, confectionery, and processed food applications. Supportive regulatory standards for food additives and continuous innovation in functional food formulations further contribute to sustained market growth across Europe.
The global carrageenan market is expected to grow at a compound annual growth rate of 4.6% from 2026 to 2033 to reach USD 1.5 billion by 2033.
Kappa segment dominated the carrageenan market with a share of nearly 68.7% in 2025 owing to properties including the gelling and stabilizing ability.
About the Author(s)
Food Additives & Nutricosmetics Research Team
Specialty & Chemicals · Food Additives & NutricosmeticsThis report was authored by the food additives & nutricosmetics research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the food additives & nutricosmetics segment of the specialty & chemicals industry. All findings are based on proprietary specialty & chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


