
- Home
- »
- Advanced Interior Materials
- »
-
Chillers Market Size, Share And Trends Report, 2026-2033GVR Report cover

Chillers Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Water-Cooled, Air-Cooled), By Application (Industrial, Commercial), By Compressor Type (Screw Chillers, Centrifugal Chillers, Absorption Chillers), By Region, And Segment Forecasts
Market Size, 2025
$11.2BMarket Estimate, 2026
$11.6BMarket Forecast, 2033
$16.4BCAGR, 2026–2033
5.0%Chillers Market Summary
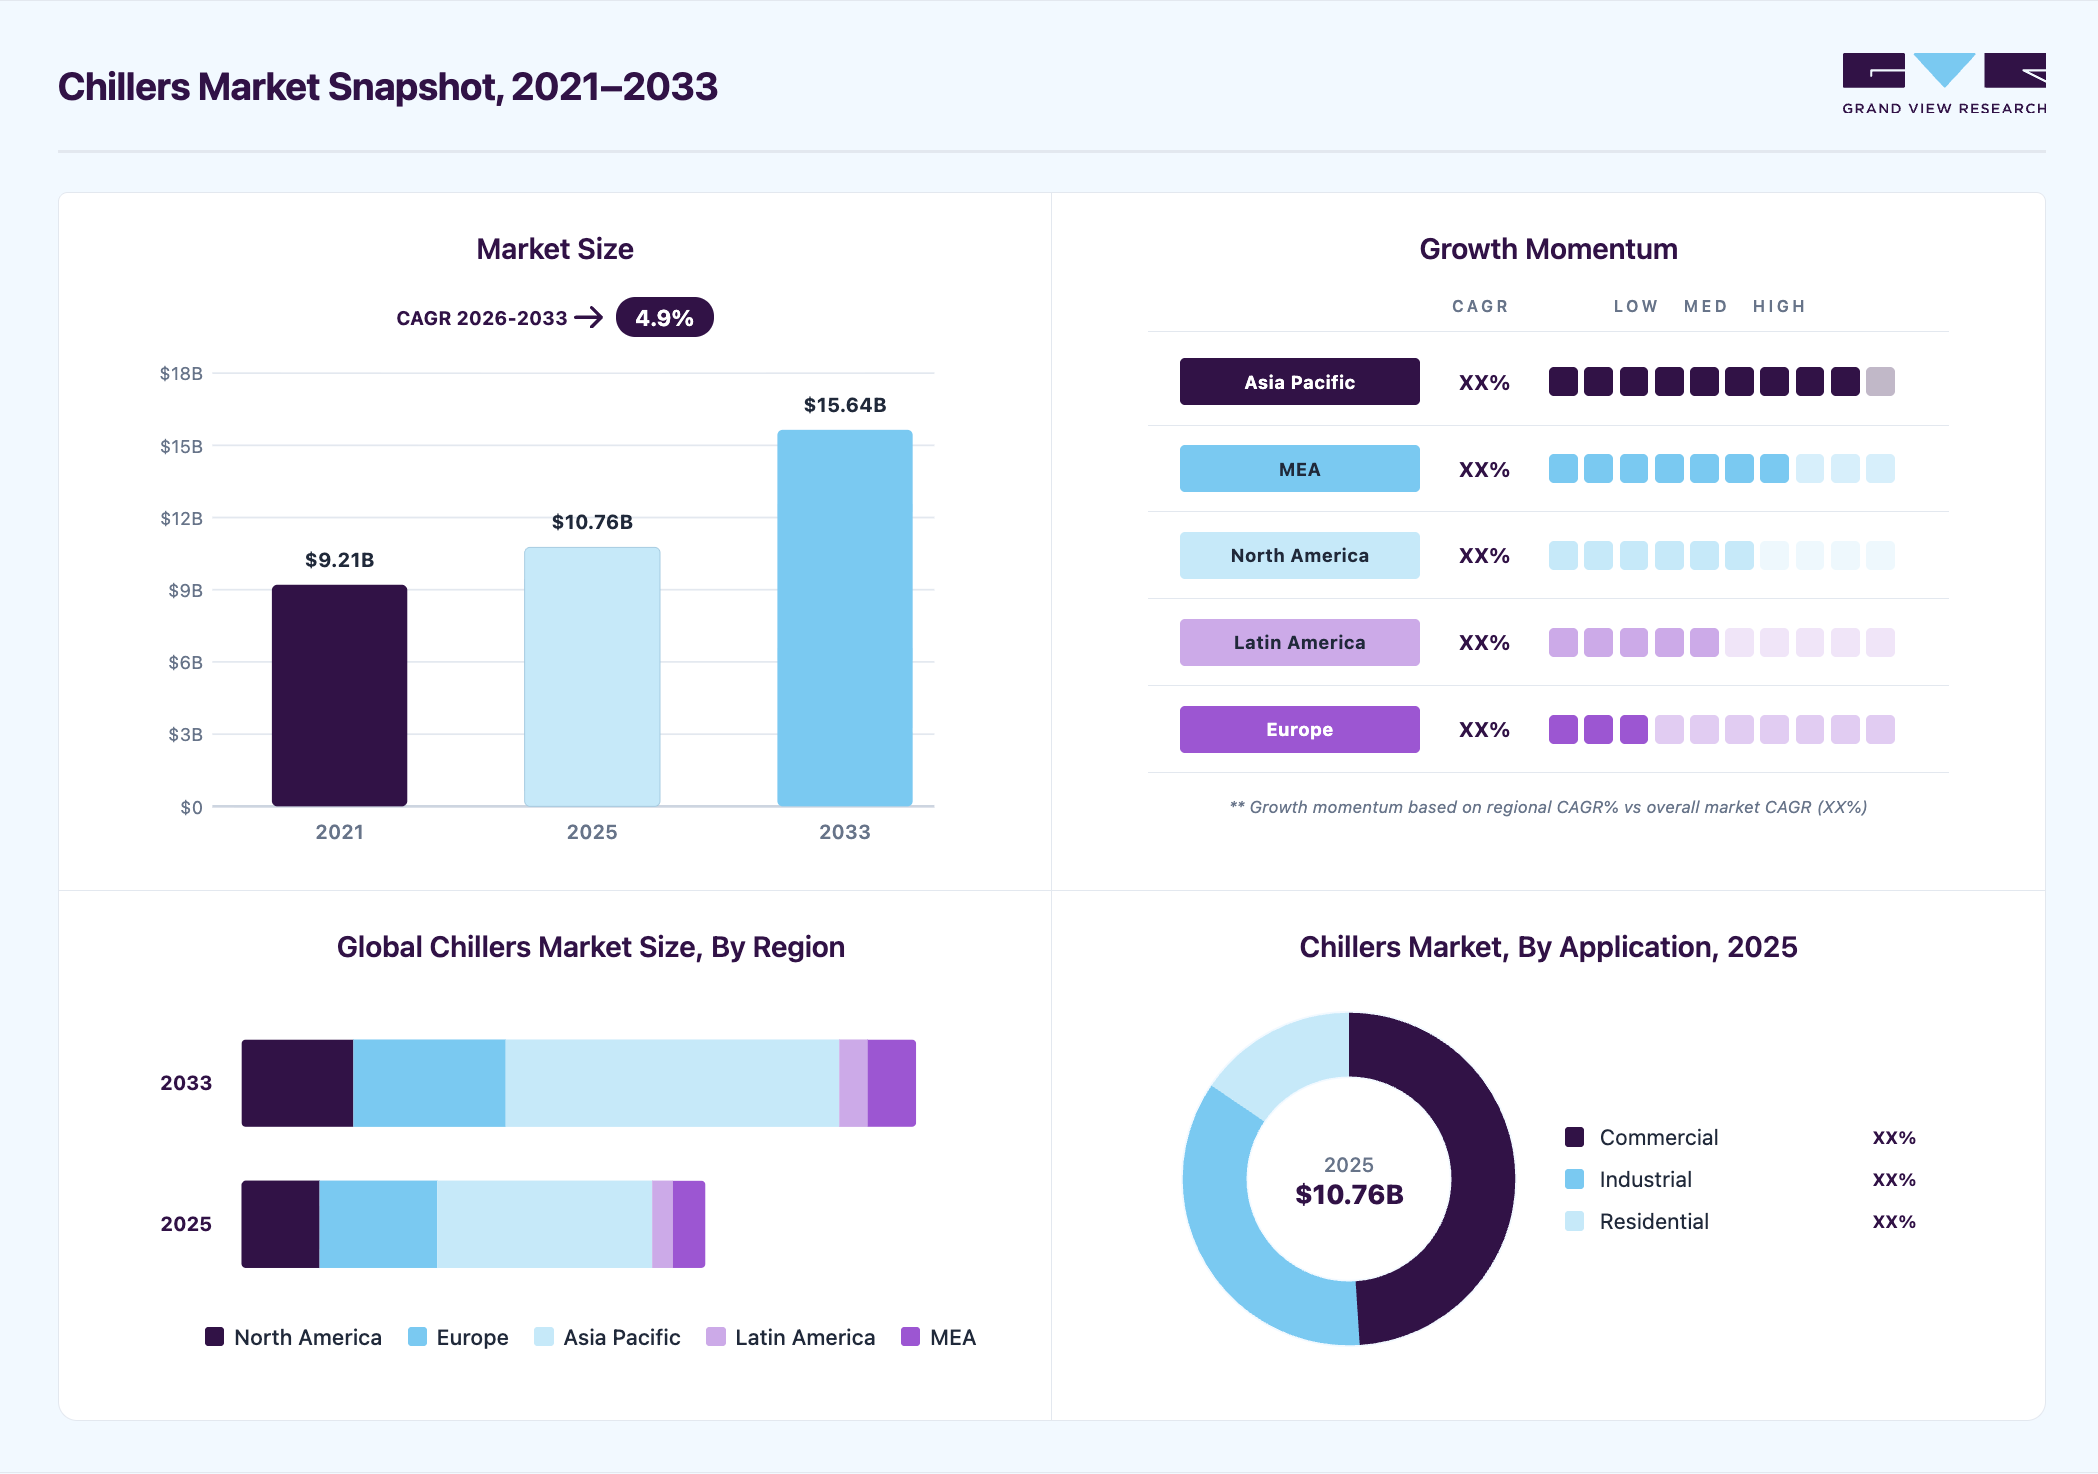
The global chillers market size was valued at USD 11.2 billion in 2025 and is projected to grow from USD 11.6 billion in 2026 to USD 16.4 billion by 2033, at a CAGR of 5.0% from 2026 to 2033. Asia Pacific dominated the market, accounting for the largest revenue share of 46.3% in 2025. The market is driven by the rising need for cost-effective and energy-efficient space cooling applications in commercial and industrial sectors.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product:The water cooled segment segment accounted for the largest revenue share of 59.7% in 2025.
- By application: The commercial segment held the highest revenue share of 56.4% in 2025.
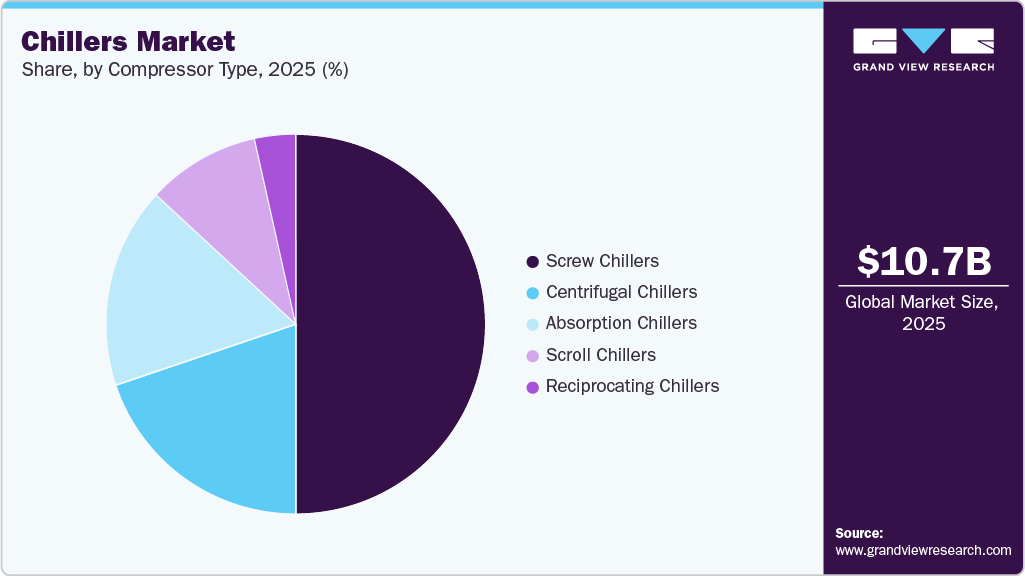
- By compressor type: Screw chillers segment held the largest revenue share of 49.3% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (44.7% revenue share, 2025)
- By country: The market in China held the largest revenue share in 2025.
Market Size & Forecast
- Market size in 2025: USD 11.2 Billion
- Estimated market size in 2026: USD 11.6 Billion
- Projected market size by 2033: USD 16.4 Billion
- CAGR (2026-2033): 5.0%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
This, in turn, will likely augment the demand for chillers over the forecast period. According to the U.S. Census Bureau, non-residential commercial construction spending has risen nearly 7% in 2024 compared to the previous year, with manufacturing projects experiencing a notable 23% growth. Additionally, data centers, which are essential for housing computer systems and servers for data storage and processing, continue to see substantial investments.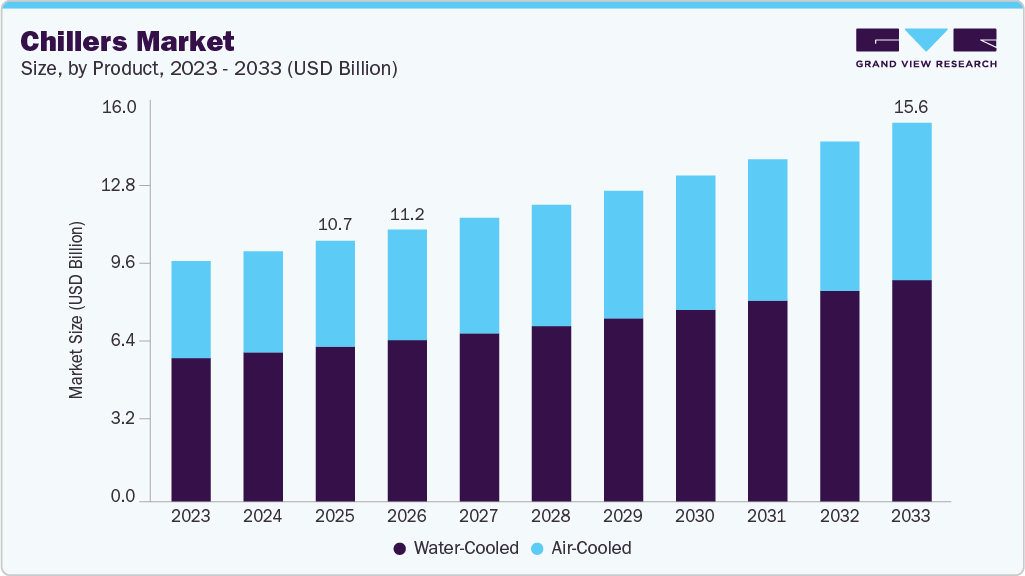 To learn more about this report, Download Free Sample Report
For instance, Meta recently announced a USD 5 billion investment in a data center project in rural Louisiana. This surge in construction spending, particularly in manufacturing and data centers, is significantly driving the demand for advanced chiller systems. Both sectors require efficient, high-capacity cooling solutions to maintain optimal operational conditions, further fueling the growth of the chillers market as companies invest in infrastructure that supports temperature-sensitive environments.
Market Dynamics
The growing demand for energy-efficient and environmentally friendly cooling solutions is a key driver for the chiller market. As industries and commercial sectors face increasing energy costs, businesses are opting for advanced chillers that reduce power consumption. Additionally, stringent government regulations aimed at lowering carbon footprints are encouraging the adoption of eco-friendly refrigerants and more efficient systems. This shift towards sustainability is propelling market growth.
High initial investment costs and ongoing maintenance expenses are significant restraints for the chiller market. While energy-efficient models can offer long-term savings, the upfront cost of advanced chillers remains prohibitive for many businesses. Furthermore, the need for specialized installation and skilled technicians increases the operational costs. These factors limit the adoption of chillers, especially in cost-sensitive markets.
The increasing demand for smart, connected chiller systems presents a notable opportunity in the market. IoT-enabled chillers, offering real-time monitoring and predictive maintenance, are gaining traction in sectors like healthcare and data centers. Furthermore, the shift toward sustainable refrigerants and energy-efficient systems opens opportunities for innovation. Manufacturers can capitalize on these trends to offer advanced, eco-friendly products in response to global sustainability goals.
Market Concentration & Characteristics
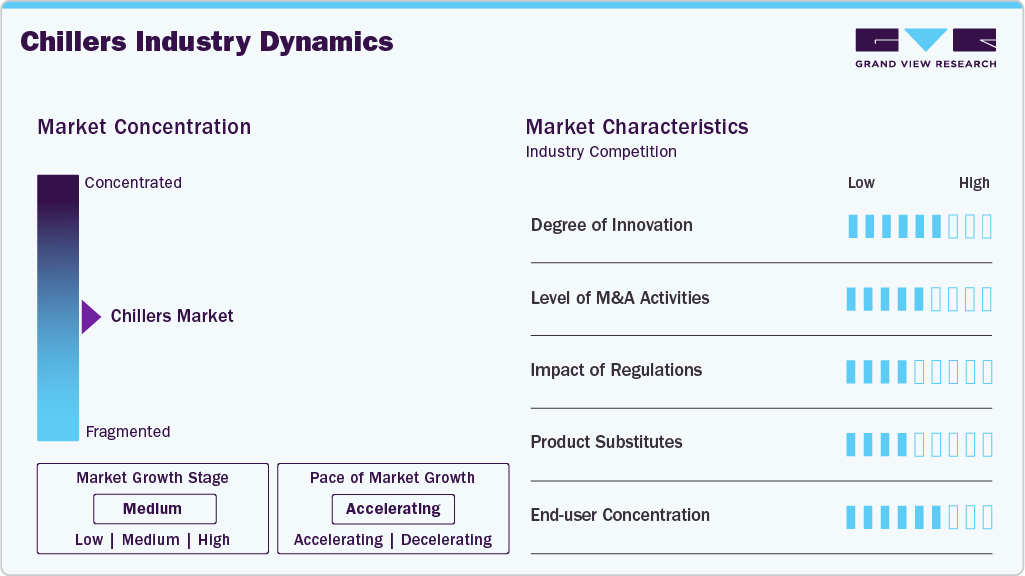
The chillers market is characterized by a relatively high level of industry concentration, with a few key players holding a significant share of the market. Prominent global manufacturers, such as Carrier, Trane, and Johnson Controls, have established a strong presence in the region, owing to their advanced technological capabilities and expansive distribution networks. These companies cater to the growing demand across a wide range of industries, including commercial real estate, manufacturing, healthcare, and data centers, which require efficient cooling solutions. The demand for chillers in the region is rising due to increasing industrial activities, urbanization, and the need for energy-efficient systems, driving the growth of these key players.
A key characteristic of the chillers market is its rapid growth, driven by factors such as industrialization, urban expansion, and a heightened focus on energy efficiency. As countries in the region continue to develop their infrastructure and industrial sectors, the demand for cooling systems, including air-cooled and water-cooled chillers, is expected to rise significantly. The increasing emphasis on environmental sustainability, energy-saving technologies, and the growing demand for air conditioning in both residential and commercial sectors have further accelerated this trend.
 To learn more about this report, Download Free Sample Report
Another defining feature of the chillers market is the diversity in consumer requirements and product types, driven by the varying industrial and commercial sectors across the region. For example, the healthcare sector in countries like Japan and South Korea requires high-performance chillers to ensure precise temperature control in sensitive environments such as hospitals and laboratories. In contrast, industrial sectors in countries like China and India demand heavy-duty, energy-efficient systems to meet the cooling needs of factories, manufacturing plants, and data centers. This variation in demand has created a fragmented market with products tailored to specific applications, prompting manufacturers to continually innovate in order to address these diverse requirements.
Analyst Perspective
The chillers market is influenced by trends in commercial construction, industrial expansion, data center development, and investments in healthcare and institutional infrastructure, all of which drive demand for cooling systems. End users are increasingly prioritizing energy efficiency, lifecycle cost savings, and sustainability goals, encouraging the adoption of advanced chiller technologies. Manufacturers are focusing on product innovation, smart monitoring capabilities, and compliance with evolving refrigerant regulations to strengthen their market position. Across the value chain, demand is supported by both new installations and retrofit projects aimed at improving energy performance. Regulatory measures targeting energy efficiency and the phasedown of high-global-warming-potential refrigerants are accelerating technology upgrades. At the same time, macroeconomic factors such as fluctuations in construction activity, industrial investment cycles, interest rates, energy prices, and supply chain conditions can influence capital spending decisions and impact market growth.
Product Insights
Water-cooled chillers held a significant share of the market and accounted for a share of of 59.7% in 2025, owing to its compact size, high energy-efficiency and long life. Water-cooled chillers offer a broad cooling capacity of 10-4,000 tons and are an ideal choice for indoor applications. They are best suited for various industrial applications with high thermal output. Water-cooled chillers can handle wide cooling loads, generally observed in chemical plants, manufacturing facilities, and medical facilities.
The demand for air-cooled chillers is expected to surge worldwide during the forecast period owing to their smooth operations at extremely low temperatures as these chillers eliminate the problems associated with the activity of cooling towers during the winter season. Moreover, increasing water scarcity across the world is anticipated to contribute to the demand for air-cooled chillers as they eliminate the requirement for water.
Application Insights
Commercial application segment holds substantial share in the chillers market around 56.4% in 2025. Chillers play a crucial role in commercial buildings by providing essential cooling effects. Their primary function is to counterbalance the heat accumulated from various internal and external sources. External factors, such as sunlight, wind, and outdoor temperature, contribute to heat gain, while internal influences include moisture from individuals, lighting, and heat generated by electrical or mechanical equipment. The advantages provided by chillers in managing these diverse factors within commercial spaces are expected to drive their demand in the coming years.
In industrial applications, chillers play a vital role in managing and controlling temperatures for various processes and equipment. They are extensively employed in manufacturing facilities, chemical plants, and other industrial settings to cool machinery, control ambient temperatures, and ensure optimal conditions for production. Chillers contribute to process efficiency and product quality by preventing overheating, maintaining consistency in manufacturing processes, and facilitating precise temperature control.
Compressor Type Insights
The screw chillers compressor type segment dominated the market and accounted for for 49.3% in 2025. Screw chillers can be an air-cooled or water-cooled chillers depending on their functions and designs. They comprise two helical slot rotors, which compress refrigerant gases for cooling purposes. These chillers are used in applications that have high-power circulation requirements. Screw chillers are used in the chemicals, automotive, and printing industries. Moreover, they offer highly energy-efficient cooling capabilities required by industrial and commercial end users.
 To learn more about this report, Download Free Sample Report
Scroll chillers use scroll compressors to remove heat from spaces or specified rooms by compressing refrigerating fluids. They have a higher coefficient of performance (COP) compared to the other types of chillers as their compressors produce high cooling output per unit of energy input. These types of chillers are usually installed in large industrial or commercial settings. Moreover, scroll chillers are designed to be compatible with a wide range of refrigerants such as R-407C, R-134a, and R-410A making them suitable for various industrial applications.
Regional Insights
The North American chiller market is experiencing significant growth driven by increasing demand for energy-efficient solutions across commercial and industrial sectors. Rising environmental concerns and stringent regulations on energy consumption are pushing businesses to adopt more sustainable cooling systems.
U.S. Chillers Market Trends
The chillers market in the U.S. is expected to grow at a CAGR of 4.9% from 2026 to 2033. In the U.S., the chiller market is expanding due to rising demand for energy-efficient cooling solutions in the commercial, industrial, and residential sectors. Government regulations, such as those from the EPA, are promoting the use of eco-friendly refrigerants and reducing the carbon footprint of cooling systems. The demand for advanced, smart chillers with features like predictive maintenance is increasing.
The chillers market in the Canada is expected to grow at a CAGR of 4.0% from 2026 to 2033. Canada’s chiller market is driven by the adoption of energy-efficient and sustainable cooling systems, particularly in the commercial and industrial sectors. The country’s stringent environmental regulations are promoting the use of eco-friendly refrigerants and advanced chiller technologies. The demand for chillers in data centers and the growing construction industry are key contributors to market expansion.
Europe Chillers Market Trends
The European chiller market is growing steadily, with a focus on energy efficiency and sustainable cooling solutions. Stringent environmental regulations, such as the EU F-Gas Regulation, are driving the adoption of chillers with low-GWP (Global Warming Potential) refrigerants. The demand for energy-efficient HVAC systems in commercial buildings, data centers, and industrial facilities is increasing.
The Germany chillers market held 22.2% share in the European market. Germany is a key player in the European chiller market, driven by its strong industrial base and emphasis on energy efficiency. The demand for high-performance, energy-efficient chillers is growing in sectors like manufacturing, automotive, and healthcare. Germany's strict environmental regulations, along with the increasing focus on renewable energy sources, are pushing businesses to adopt sustainable chiller systems.
The UK chillers market is driven by rising commitment to reducing carbon emissions, and its transition toward green technologies is encouraging the adoption of advanced, eco-friendly chillers. Furthermore, smart chiller systems with IoT integration are gaining traction in the market.
Asia Pacific Chillers Market Trends
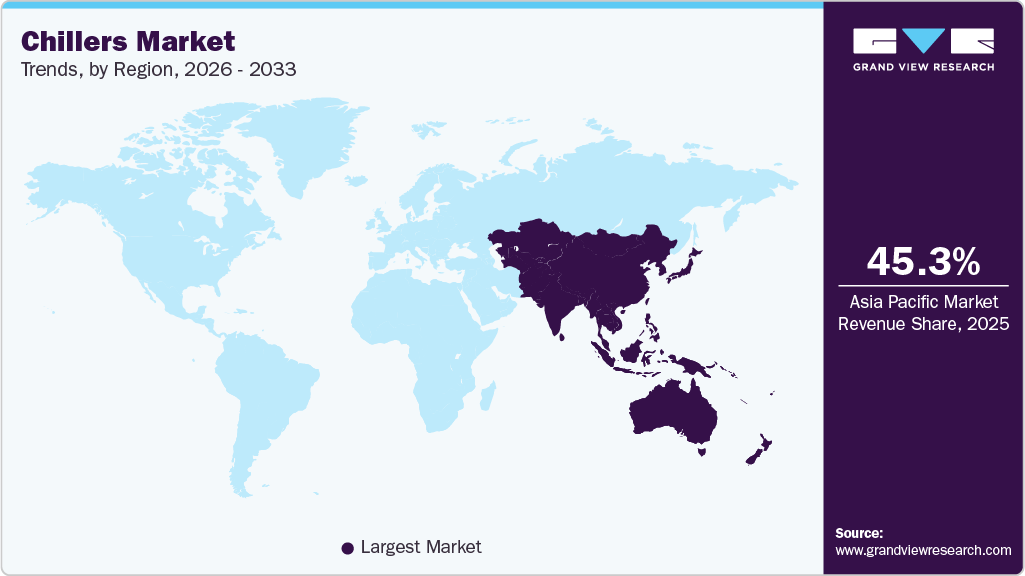
Asia Pacific region led the market and accounted for 44.7% of the global chillers market in 2025. The market is witnessing rapid growth due to rapid industrialization, urbanization, and increased demand for cooling solutions. Countries like China, India, and Japan are driving market growth with rising infrastructure development, industrial activities, and the need for air conditioning systems.
 To learn more about this report, Download Free Sample Report
The China chillers market held a significant share in the Asia Pacific market. The demand for energy-efficient cooling systems is growing across industrial, commercial, and residential sectors. Stringent government regulations on energy consumption and sustainability are driving the adoption of advanced chillers. Additionally, local manufacturers are enhancing their production capabilities, creating both domestic and export opportunities.
The chillers market in the India is expected to grow at a CAGR of 6.9% from 2026 to 2033. India's chiller market is experiencing strong growth due to rapid industrialization, expanding infrastructure, and increased demand for air conditioning. The government's initiatives to improve energy efficiency and reduce carbon emissions are encouraging the adoption of eco-friendly and energy-efficient chillers. The healthcare, commercial, and industrial sectors are major contributors to market demand.
Middle East & Africa Chillers Market Trends
The chiller market in the Middle East and Africa is witnessing growth, particularly in regions with expanding commercial, residential, and industrial sectors. Countries in the Gulf Cooperation Council (GCC), such as Saudi Arabia and the UAE, are key drivers of market expansion due to their booming construction sectors and extreme weather conditions, creating high demand for cooling solutions.
The Saudi Arabia chiller market is growing rapidly due to the country’s significant construction boom and rising industrial activities. The demand for chillers is driven by the need for air conditioning in commercial, industrial, and residential sectors, particularly due to the extreme temperatures. Additionally, the government’s focus on energy efficiency and reducing environmental impact is driving the adoption of energy-efficient and eco-friendly chiller technologies. The healthcare and hospitality sectors also contribute significantly to market demand.
Latin America Chillers Market Trends
The Latin American chiller market is expanding, fueled by growing infrastructure development, industrialization, and the rising demand for cooling solutions. Countries like Brazil and Mexico are experiencing increased demand for commercial and industrial chillers. The focus on energy efficiency and environmental sustainability is driving the adoption of chillers with low environmental impact. Moreover, the growth in sectors like healthcare, retail, and manufacturing is spurring the need for reliable and efficient cooling systems.
Brazil is the largest market for chillers in Latin America, driven by rapid urbanization, infrastructure development, and increased industrial activities. The demand for energy-efficient and sustainable chillers is growing, especially in sectors like healthcare, commercial real estate, and manufacturing. Brazil’s commitment to reducing energy consumption and improving environmental standards is pushing businesses to adopt advanced, eco-friendly chiller technologies.
Key Chillers Manufacturers Insights
Some of the key players operating in the market include Trane, Carrier, and Daikin Industries, Ltd.
-
Carrier provides boilers, air conditioners, furnaces, air purifiers, humidifiers, heat pumps, air scrubbers, ventilators, thermostats, UV lamps, dehumidifiers, building controls, and energy services to the retail, commercial, transport, and foodservice sectors. The company was acquired by United Technologies Corporation in 1979; however, it was separated into a separate business in April 2020.
-
Trane is a member of the Ingersoll Rand family of brands. The company operates its business in two segments, namely climate and industrial. The industrial segment offers products and services that enhance energy efficiency, operations, and productivity. It includes power tools, compressed air & gas systems, fluid management systems, material handling systems, and utility & low-speed consumer vehicles. The climate segment provides energy-efficient products and services, including HVAC systems. The company is engaged in the manufacturing of residential, industrial, and commercial HVAC systems. It offers products, such as HVAC accessories, thermostat controls, ductless systems, geothermal systems, packaged systems, heat pumps, coils, gas & oil furnaces, air handlers, and air conditioners.
Key Chillers Companies:
The following are the leading companies in the chillers market. These companies collectively hold the largest market share and dictate industry trends.
- Trane
- Cold Shot Chillers
- Tandem Chillers
- Drake Refrigeration, Inc
- Refra
- Carrier
- FRIGEL FIRENZE S.p.A.
- Midea
- Daikin Industries, Ltd.
- Johnson Controls
- Rite-Temp
- General Air Products
- ClimaCool Corp.
- Fluid Chillers, Inc.
- Multistack International Limited
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (e.g., Trane, Carrier, DAIKIN INDUSTRIES, LTD., Johnson Controls, Midea)
- Strengthen market presence through global distribution networks, service capabilities, strategic acquisitions, and investments in data center, healthcare, and industrial cooling solutions.
- Strengthen market presence through global distribution networks, service capabilities, strategic acquisitions, and investments in data center, healthcare, and industrial cooling solutions.
- Strong brand recognition, extensive installed base, and comprehensive product offerings across commercial and industrial applications.
- Advanced R&D capabilities enabling development of energy-efficient, IoT-enabled, and sustainability-focused chiller systems.
- Advanced R&D capabilities enabling development of energy-efficient, IoT-enabled, and sustainability-focused chiller systems.
- Higher equipment and lifecycle costs compared to regional and niche competitors.
Emerging & Regional Players (e.g., FRIGEL FIRENZE S.p.A., Refra, Multistack, LLC, regional players)
- Focus on specialized process cooling applications, custom-engineered chiller systems, and niche industrial requirements.
- Expand regional presence through application-specific solutions for plastics, food processing, printing, electronics, pharmaceutical, and laboratory cooling applications.
- High customization capabilities, shorter lead times, and flexibility in meeting unique customer specifications.
- Strong technical expertise in targeted industrial cooling applications and specialized process environments.
- Limited geographic reach, brand visibility, and distribution networks compared to global HVAC leaders.
- Lower investment capacity for large-scale R&D, advanced digital technologies, and global expansion initiatives.
Recent Developments
-
In January 2025, Midea announced it is expanding its manufacturing in Thailand, a key production base, by building two new plants in Rayong. A 66.4 million baht plant, expected to open in Q2 of this year, will produce VRF systems and chillers (600,000 units annually, 90% for export). Another plant, projected for completion in 2026, will produce microwaves, refrigerators, and freezers.
-
In December 2024, Vertiv Group Corp acquired certain assets and technologies of BiXin Energy Technology (BSE), a China-based chiller manufacturer. This acquisition expands Vertiv's chiller portfolio, particularly for high-performance computing and AI applications. BSE specializes in water-cooled and air-cooled systems with up to 5.5 MW capacity, plus heat recovery solutions.
Chillers Market Report Scope
Report Attribute
Details
Market size in 2025
USD 11.2 billion
Estimated market size in 2026
USD 11.6 billion
Projected market size by 2033
USD 16.4 billion
Growth rate
CAGR of 5.0% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2025 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, Application, Compressor Type, and Region
Regional scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Russia; China; Japan; India; Australia; South Korea; Thailand; Indonesia; Malaysia; Brazil; Argentina; Saudi Arabia; South Africa; UAE
Key companies profiled
Trane (Trane Technologies plc); Cold Shot Chillers; Tandem Chillers; Drake Refrigeration, Inc.; Refra; Carrier; FRIGEL FIRENZE S.p.A.; Midea; Daikin Industries, Ltd.; Johnson Controls; Rite-Temp; General Air Products; ClimaCool Corp.; Fluid Chillers, Inc.; Multistack International Limited
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Chillers Market Report Segmentation
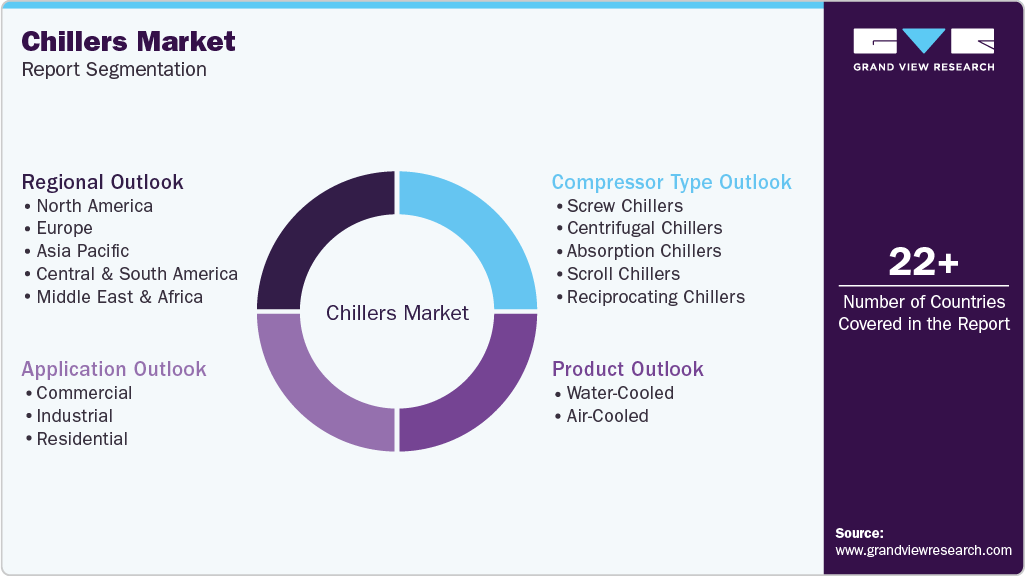
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global chillers market report based on product, application, compressor type, and region.
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Water-Cooled
-
<50kW
-
51-100kW
-
101-500kW
-
501-1000kW
-
1001-1500kW
-
>1501kW
-
-
Air-Cooled
-
<50kW
-
51-100kW
-
101-500kW
-
501-1000kW
-
1001-1500kW
-
>1501kW
-
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Commercial
-
Corporate Offices
-
Data Centers
-
Public Buildings
-
Mercantile & Service
-
Healthcare
-
Others
-
-
Industrial
-
Chemicals & Petrochemicals
-
Food & Beverage
-
Metal Manufacturing & Machining
-
Medical & Pharmaceutical
-
Plastics
-
Others
-
-
Residential
-
-
Compressor Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Screw Chillers
-
Centrifugal Chillers
-
Absorption Chillers
-
Scroll Chillers
-
Reciprocating Chillers
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
France
-
UK
-
Italy
-
Spain
-
Russia
-
-
Asia Pacific
-
China
-
Japan
-
India
-
Australia
-
Thailand
-
South Korea
-
Indonesia
-
Malaysia
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East and Africa
-
Saudi Arabia
-
South Africa
-
UAE
-
-
Research Methodology
The chillers market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each chillers segment quantified using the revenue-capture definitions in the table below.
Segment Definitions
Segment - Product
Revenue Capture Definition
Water-Cooled Chillers
The segment considers revenue generated from the sale of water-cooled chiller systems utilized across commercial, industrial, and residential facilities. This segment includes units ranging from below 50 kW to above 1501 kW.
Air-Cooled Chillers
The segment refers to revenue generated from the sale of air-cooled chiller systems utilized across commercial, industrial, and residential facilities. This segment includes units spanning various capacity ranges from below 50 kW to above 1501 kW.
Segment - Application
Revenue Capture Definition
Commercial
Revenue generated from the sale of chillers utilized in commercial facilities. The segment is further divided into corporate offices, data centers, public buildings, mercantile & service, healthcare, and others.
Industrial
Revenue generated from the sale of chillers utilized in industrial facilities. The segment is further segmented into chemicals & petrochemicals, food & beverage, metal manufacturing, pharmaceuticals, plastics, and other industrial operations.
Residential
Revenue generated from the sale of chillers utilized in residential buildings and housing complexes.
Segment - Compressor Type
Revenue Capture Definition
Screw Chillers
Revenue generated from the sale of chiller systems equipped with screw compressors. These systems are utilized to provide reliable and energy-efficient cooling across commercial and industrial facilities requiring medium- to high-capacity cooling performance.
Centrifugal Chillers
Revenue generated from the sale of chiller systems equipped with centrifugal compressors. These systems are designed to deliver high-capacity cooling and energy-efficient operation across large commercial buildings, industrial plants, and district cooling applications.
Absorption Chillers
Revenue generated from the sale of absorption of chiller systems. These systems utilize thermal energy sources such as steam, hot water, or waste heat to provide cooling across commercial and industrial facilities.
Scroll Chillers
Revenue generated from the sale of chillers equipped with scroll compressors. These systems are utilized to provide efficient cooling across residential, commercial, and light industrial applications requiring compact and reliable cooling solutions.
Reciprocating Chillers
Revenue generated from sale of chillers equipped with reciprocating compressors. These systems are deployed to provide cooling and temperature control across commercial and industrial facilities requiring flexible and dependable cooling performance.
Estimation Model
Layer Name
Key Question
Description
End-Use Industry Demand Generation`
Which end-use industries drive demand for chillers?
This layer identifies and quantifies demand for chillers across key end-use industries. Demand is primarily driven by cooling requirements in commercial buildings, industrial facilities, healthcare institutions, data centers, and other infrastructure requiring temperature control and process cooling.
Product and Application Consumption Mapping
How is chiller demand distributed across applications and product types?
This layer translates end-use demand into chiller requirements based on application, cooling capacity, and product type. Different facilities require varying cooling loads and chiller technologies depending on operating conditions and efficiency requirements.
Supply-Side Validation and Market Capture
Do manufacturer sales and shipment volumes validate the estimated demand
This layer validates demand estimates using manufacturer revenues, shipment volumes, production capacities, and distribution channel data. It ensures that bottom-up demand calculations align with actual market activity.
Revenue Modeling, Market Sizing, and Forecasting
What market revenue is generated from the estimated volumes, and how will it evolve over the forecast period?
This layer converts validated demand and shipment estimates into market revenue and develops forecasts. Calculations are based on volume estimates and average selling prices (ASPs), incorporating key assumptions such as construction activity, industrial investment, data center expansion, replacement demand, and broader market conditions.
Delivered Customizations
This report has been delivered with the following In-depth customizations
CLIENT REQUEST
CUSTOMIZATION DELIVERED
VALUE ADDS
Competitive Benchmarking
The study provided a detailed company market share analysis, assessing the relative revenue contribution and competitive positioning of leading participants in the chillers market. The analysis included an evaluation of market concentration, competitive dynamics, and the presence of key players across regions and end-use industries.
Company market share analysis aided benchmark competitive performance, identify market leaders and emerging challengers, and understand the structure of the competitive landscape. It also provided valuable insights into market consolidation, strategic positioning, and growth opportunities, enabling the assessment of competitive risks and refining of market strategies.
Regional Segmentation
The study incorporated a detailed regional segmentation of the chillers market, providing market size estimates and forecasts across major regions and key countries. The analysis evaluated regional demand patterns, end-use industry dynamics, infrastructure development trends, and regulatory influences shaping chiller adoption across different geographies.
Regional segmentation enabled the identification of high-growth markets, emerging investment hotspots, and region-specific demand drivers. It also supported strategic decision-making by highlighting geographic variations in construction activity, industrial development, data center investments, energy efficiency initiatives, and competitive intensity.
Opportunity assessment
The study included a comprehensive opportunity assessment that identifies emerging growth areas across end-use industries, technologies, applications, and regions. The analysis evaluated market trends, evolving customer requirements, and investment patterns to highlight the most attractive opportunities for future growth.
Opportunity assessment aided stakeholders prioritize high-potential market segments, anticipate future demand shifts, and align growth strategies with evolving industry trends. It also provided insights into areas such as smart chiller technologies, sustainable refrigerants, data center cooling, and infrastructure expansion, supporting informed investment and product development decisions.
Frequently Asked Questions About This Report
Some of the key players operating in the chillers market include Trane, Cold Shot Chillers, Tandem Chillers, Drake Refrigeration, Inc., Refra, Carrier, FRIGEL FIRENZE S.p.A., Midea, Rite-Temp, Multistack, LLC., DAIKIN INDUSTRIES, Ltd., General Air Product, ClimaCool Corp., Johnson Controls, Fluid Chillers, Inc
Key factors that are driving the chillers market growth include the rising temperatures due to global warming are likely to drive the demand for cooling equipment. Increasing adoption of chillers owing to their ability to remove heat from the building and maintain internal temperature is anticipated to drive the market.
The chillers market size was estimated at USD 11.2 billion in 2025 and is expected to be USD 11.6 billion in 2026.
The commercial segment dominated the chillers market in 2025, accounting for 56.4% of global revenue, driven by widespread deployment of HVAC systems across office buildings, retail centers, hotels, hospitals, and other commercial facilities.
The screw chillers segment led the market in 2025, accounting for 49.3% of global revenue, owing to its high energy efficiency, reliability, and suitability for medium- to large-scale commercial and industrial cooling applications.
The Asia Pacific chillers market held the largest share of the global market in 2025, accounting for 46.3% of revenue, driven by rapid industrialization, expanding commercial infrastructure, and growing demand for process cooling and HVAC systems across key economies.
The global chillers market, in terms of revenue, is expected to grow at a compound annual growth rate of 5.0% from 2026 to 2033 to reach USD 16.3 billion by 2033.
Water-cooled chillers held a significant share of the market and accounted for a share of 59.7% in 2025, due to their compact size, high energy-efficiency and long life. Water-cooled chillers offer a broad cooling capacity of 10–4,000 tons and are an ideal choice for indoor applications. They are best suited for various industrial applications with high thermal output.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


