
- Home
- »
- Medical Devices
- »
-
Clinical Trial Management Services Market Report 2026-2033GVR Report cover

Clinical Trial Management Services Market (2026 - 2033)
Size, Share & Trends Analysis Report By Service (Clinical Trial Monitoring, Regulatory Submissions, Clinical Trial Data Management, Medical Writing), By Indication (Oncology, Diabetes, Obesity), By End-use, By Region, And Segment Forecasts
Market Size, 2025
$36.2BMarket Estimate, 2026
$39.2BMarket Forecast, 2033
$68.4BCAGR, 2026–2033
8.3%Clinical Trial Management Services Market Summary
The global clinical trial management services market size was valued at USD 36.2 billion in 2025 and is projected to grow from USD 39.2 billion in 2026 to USD 68.4 billion by 2033, at a CAGR of 8.3% from 2026 to 2033. North America dominated the market, accounting for the largest share of 34.7% in 2025. The clinical trial management services industry’s growth is driven by technological advancements in clinical trial monitoring services, rising R&D expenditure by pharmaceutical and biopharmaceutical companies, and the growing number of outsourced clinical trial management projects.
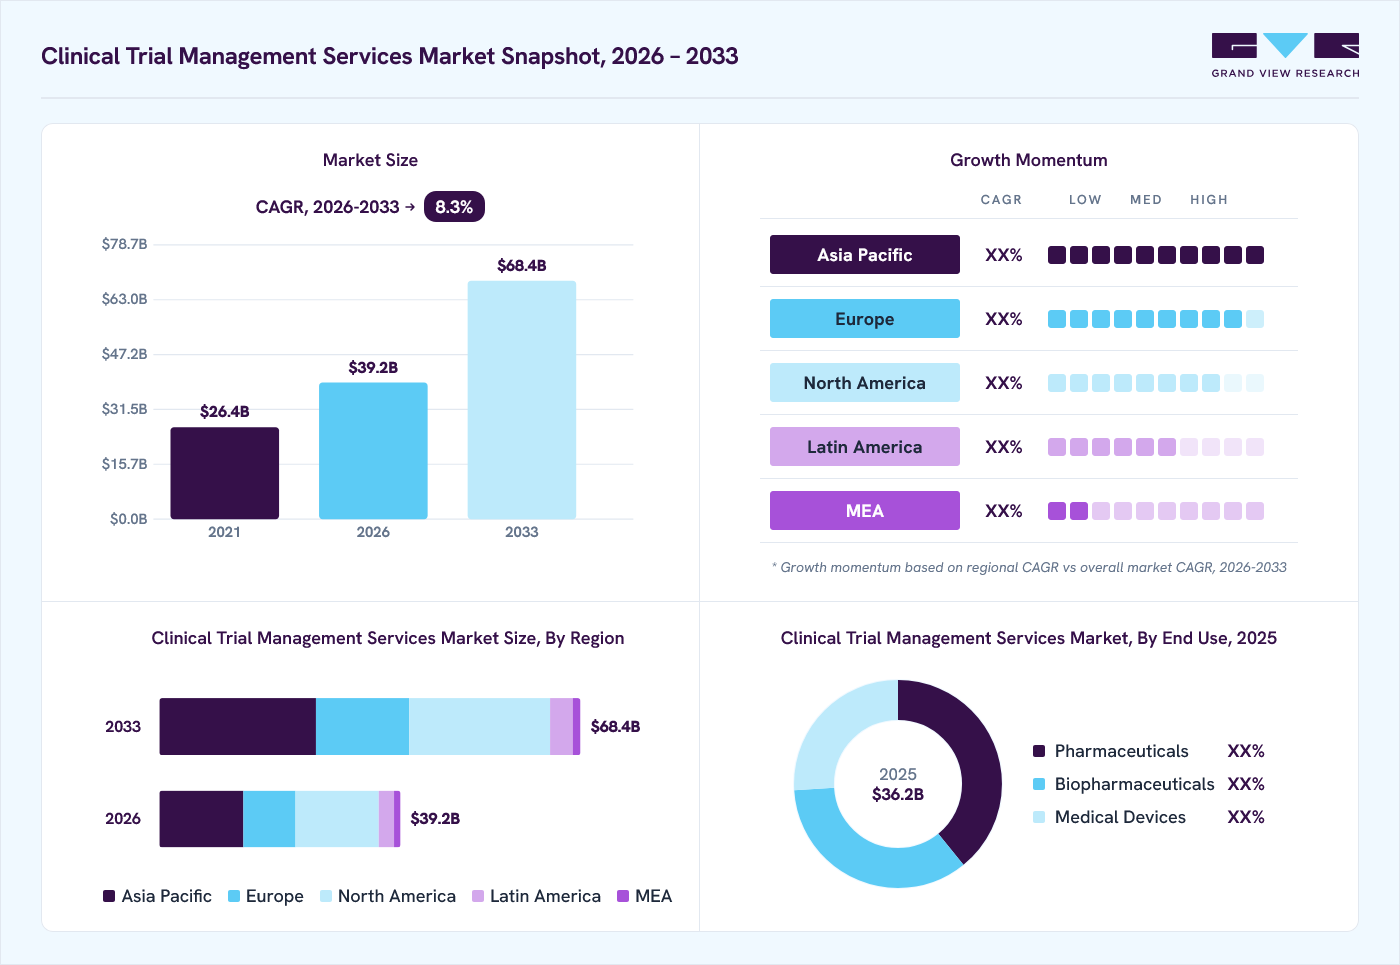 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By service: Clinical trial monitoring held the largest revenue share of 27.5% in 2025.
- By indication: Oncology held the largest revenue share of 37.4% in 2025.
- By end-use: Pharmaceuticals held the largest revenue share of 39.1% in 2025.
Regional Highlights
- Largest regional market: North America (34.7% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (fastest CAGR, 2026-2033)
- By country: The U.S. held the largest revenue share of North America in 2025.
Market Size & Forecast
- Market size in 2025: USD 36.2 Billion
- Estimated market size in 2026: USD 39.2 Billion
- Projected market size by 2033: USD 68.4 Billion
- CAGR (2026-2033): 8.3%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
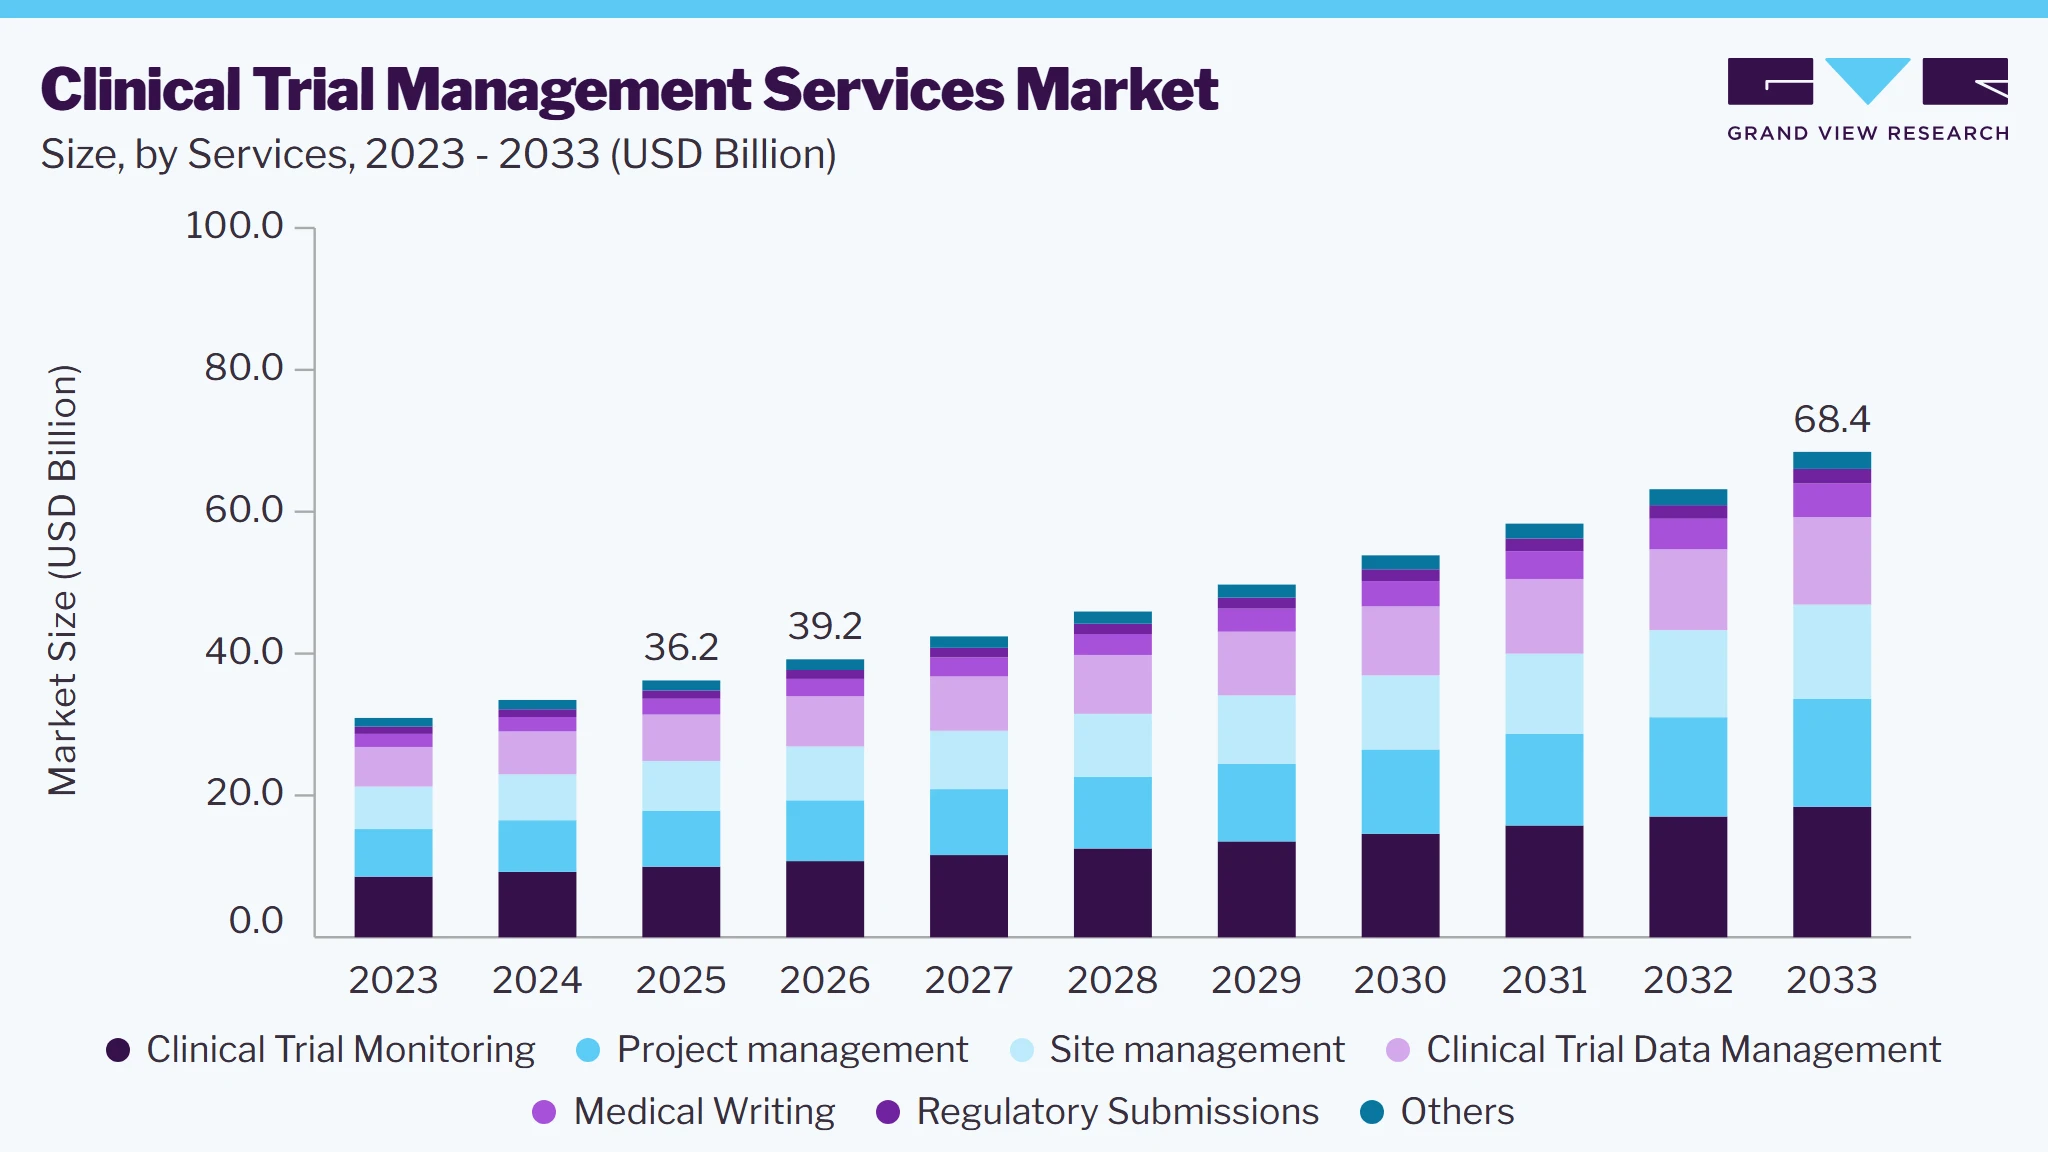 To learn more about this report, Download Free Sample Report
Market Dynamics
The clinical development landscape is becoming increasingly complex as pharmaceutical and biotechnology companies advance larger volumes of oncology, rare disease, immunology, and precision medicine candidates into clinical evaluation. These therapies often require adaptive trial designs, biomarker-based patient selection, multi-country site coordination, and extensive regulatory documentation, creating greater demand for specialized clinical trial management services. Furthermore, the increasing use of decentralized trial components, electronic clinical outcome assessments, remote monitoring technologies, and real-world data collection is changing operational requirements across clinical studies. Regulatory agencies are also encouraging patient-centric trial models and greater diversity in clinical research participation, leading sponsors to seek external expertise for study planning, site management, patient recruitment, data oversight, and regulatory compliance. As a result, clinical trial management service providers are becoming integral partners in supporting the efficient execution of increasingly sophisticated global clinical programs.
The increasing outsourcing of clinical operations is a major driver of growth in the clinical trial management services market, as sponsors seek to manage rising trial complexity while controlling development timelines and operational costs. Clinical studies involving oncology, cell therapy, gene therapy, and rare disease indications frequently require specialized site networks, patient recruitment capabilities, regulatory expertise, and advanced trial oversight that many sponsors do not maintain internally. Large pharmaceutical companies are directing greater attention to portfolio expansion, asset licensing, and commercialization, leading to wider adoption of external clinical management partners for study execution. Smaller biotechnology firms, which account for a substantial share of innovative drug development, often operate with limited internal clinical infrastructure and therefore engage contract service providers throughout Phase I, Phase II, and Phase III development.
For instance, in May 2025, IQVIA announced a strategic collaboration with SCRI Development Innovations to accelerate global oncology clinical trials by combining IQVIA's clinical development, data, technology, and recruitment capabilities with SCRI's community oncology research network. The collaboration is designed to simplify outsourcing for biopharmaceutical sponsors and improve trial activation and patient enrollment. Furthermore, sponsors are increasingly seeking end-to-end service models that cover study start-up, site management, patient recruitment, clinical monitoring, data management, and regulatory support, contributing to longer-duration strategic partnerships across the clinical development ecosystem.
Regulatory compliance remains a significant challenge for organizations that provide clinical trial management services, as clinical studies generate large volumes of patient, safety, operational, and site-level data across multiple jurisdictions. Sponsors and service providers must comply with evolving requirements from the U.S. FDA, European Medicines Agency, and other regulatory authorities governing data integrity, patient privacy, informed consent procedures, safety reporting, and trial documentation. Any deficiencies in monitoring activities, protocol adherence, source data verification, or electronic data management systems can result in regulatory observations, study delays, or additional inspection requirements.
Furthermore, increasing adoption of decentralized trial technologies and digital health tools has expanded the volume and diversity of clinical data requiring oversight. Managing information collected from electronic patient-reported outcomes, wearable devices, telemedicine platforms, and electronic health records introduces additional operational complexity. Failure to maintain consistent data quality standards across global study sites can affect trial timelines and increase development costs, creating ongoing compliance burdens for clinical trial management providers.
The growing adoption of decentralized and hybrid clinical trials presents substantial opportunities for clinical trial management service providers as sponsors seek to improve patient recruitment, retention, and study accessibility. Traditional site-based trials often face enrollment challenges, particularly in rare disease, neurology, and chronic disease studies, where eligible patients may be geographically dispersed. Decentralized approaches incorporating telemedicine consultations, electronic consent platforms, remote patient monitoring devices, and home healthcare services can expand access to broader patient populations while reducing the burden on participants.
For instance, in March 2025, ICON plc partnered with Mural Health to deploy the Mural Link participant management platform across clinical studies. The solution includes participant payments, travel support, site participant communication, and reporting tools designed to reduce barriers to trial participation and strengthen hybrid and decentralized trial execution capabilities. Furthermore, increasing regulatory acceptance of remote data collection methodologies is encouraging broader implementation of hybrid study models. Service providers capable of integrating digital technologies, virtual site management, patient engagement platforms, and remote monitoring solutions are positioned to benefit from rising demand as decentralized clinical research becomes a larger component of global drug development strategies.
Market Concentration & Characteristics
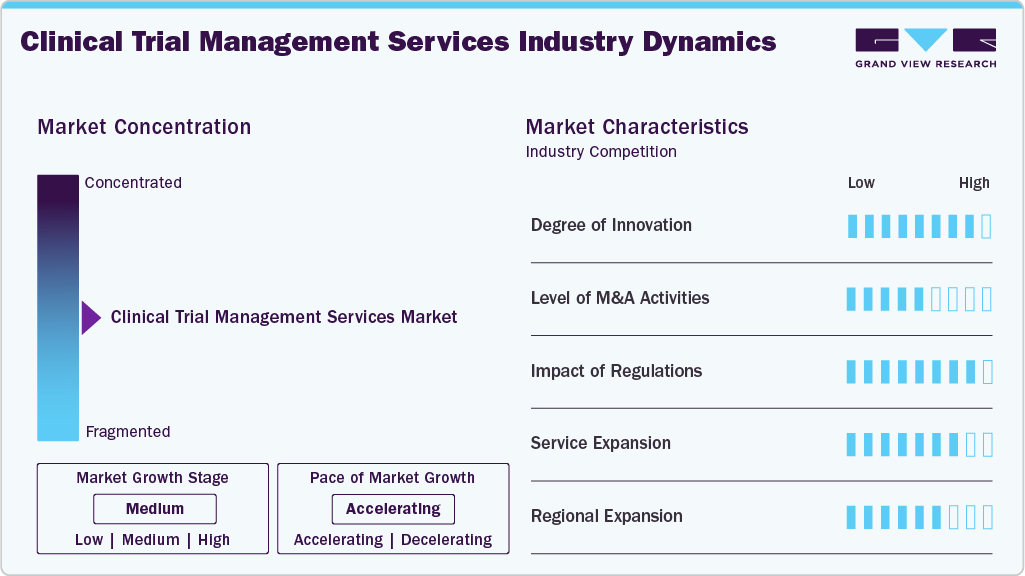
The clinical trial management services market’s growth stage is moderate, and the pace of growth is accelerating. The market is characterized by the degree of innovation, level of M&A activities, regulatory impact, service expansion, and regional expansion.
Innovation in the clinical trial management services industry focuses on improving trial execution, patient recruitment, data collection, and study oversight. Sponsors are increasingly adopting decentralized and hybrid trial models that incorporate telemedicine, electronic consent platforms, wearable devices, remote patient monitoring, and electronic clinical outcome assessments. These technologies help address enrollment challenges and improve patient retention, particularly in oncology, rare disease, and neurology studies. Furthermore, clinical trial designs are becoming more sophisticated with wider use of adaptive protocols, biomarker-driven enrollment strategies, and platform trials.
 To learn more about this report, Download Free Sample Report
Mergers and acquisitions remain an important strategy among clinical research organizations and trial management providers seeking to expand therapeutic expertise, technology capabilities, and geographic reach. Acquisitions are increasingly focused on decentralized trial platforms, patient recruitment technologies, real-world evidence capabilities, and specialized therapeutic areas such as oncology and rare diseases. Consolidation enables providers to offer integrated services covering study startup, clinical monitoring, data management, medical writing, regulatory support, and pharmacovigilance through a single delivery model.
Regulatory requirements continue to shape the clinical trial management services landscape as authorities place greater focus on data integrity, patient safety, transparency, and diversity in clinical research. Sponsors and service providers must comply with evolving guidance related to decentralized trials, electronic records, remote monitoring, data privacy, and advanced statistical methodologies. Furthermore, increasing the adoption of complex trial designs requires more extensive regulatory interactions and documentation. Regulatory expectations surrounding clinical data quality, protocol compliance, and safety reporting have increased operational demands across all phases of development.
Clinical trial management service providers are expanding beyond traditional monitoring and project management activities to support broader sponsor requirements throughout the clinical development lifecycle. Service portfolios increasingly include decentralized trial management, patient recruitment and retention services, medical writing, regulatory consulting, clinical data management, biostatistics, and risk-based monitoring.
Regional expansion remains a key strategic priority as sponsors seek broader patient access, faster enrollment, and diversified trial execution capabilities. Asia Pacific continues to attract clinical development activity due to its large treatment-naive patient population, expanding investigator networks, and improving regulatory infrastructure. China has become a significant contributor to early-stage clinical development, while North America continues to lead Phase II and Phase III activity.
Analyst Perspective
The clinical trial management services market is experiencing strong growth, driven by increasing clinical trial activity, rising pharmaceutical and biopharmaceutical R&D investments, and greater outsourcing to improve development efficiency. The expanding pipeline of biologics, cell and gene therapies, precision medicines, and medical devices is increasing demand for clinical trial monitoring, site management, project management, data management, regulatory submissions, and medical writing services. Furthermore, the growing complexity of global multicenter studies, evolving regulatory requirements, and increasing adoption of decentralized trials and digital technologies are accelerating demand for technology-enabled service providers with strong therapeutic expertise and global capabilities. The continued growth in oncology, autoimmune, metabolic, and rare disease clinical trials, along with expanding research infrastructure and CRO collaborations, is expected to further support market growth.
Impact of U.S. Tariffs on the Global Clinical Trial Management Services Market
The U.S. tariff policies have had an indirect effect on the market by impacting the pharmaceutical development costs and global research supply chains. Increased tariffs on laboratory equipment, electronic components, medical devices, and imported research materials have increased operational expenditure across clinical development programs. These cost increases affect sponsors conducting multinational studies, particularly when specialized diagnostic equipment, trial supplies, and laboratory materials are sourced internationally.
Besides, pharmaceutical companies are reassessing supply chain strategies and expanding regional sourcing networks to reduce exposure to trade-related uncertainties. This shift has increased demand for clinical trial management providers with strong operational capabilities across North America, Europe, and the Asia Pacific, enabling sponsors to maintain continuity in study execution. Furthermore, growing interest in regionalized clinical development strategies is creating opportunities for service providers with established site networks, local regulatory expertise, and geographically diversified operational infrastructure. As a result, tariff-related market changes are encouraging greater focus on supply chain resilience, regional flexibility, and operational efficiency across global clinical research programs.
Technological Advancements
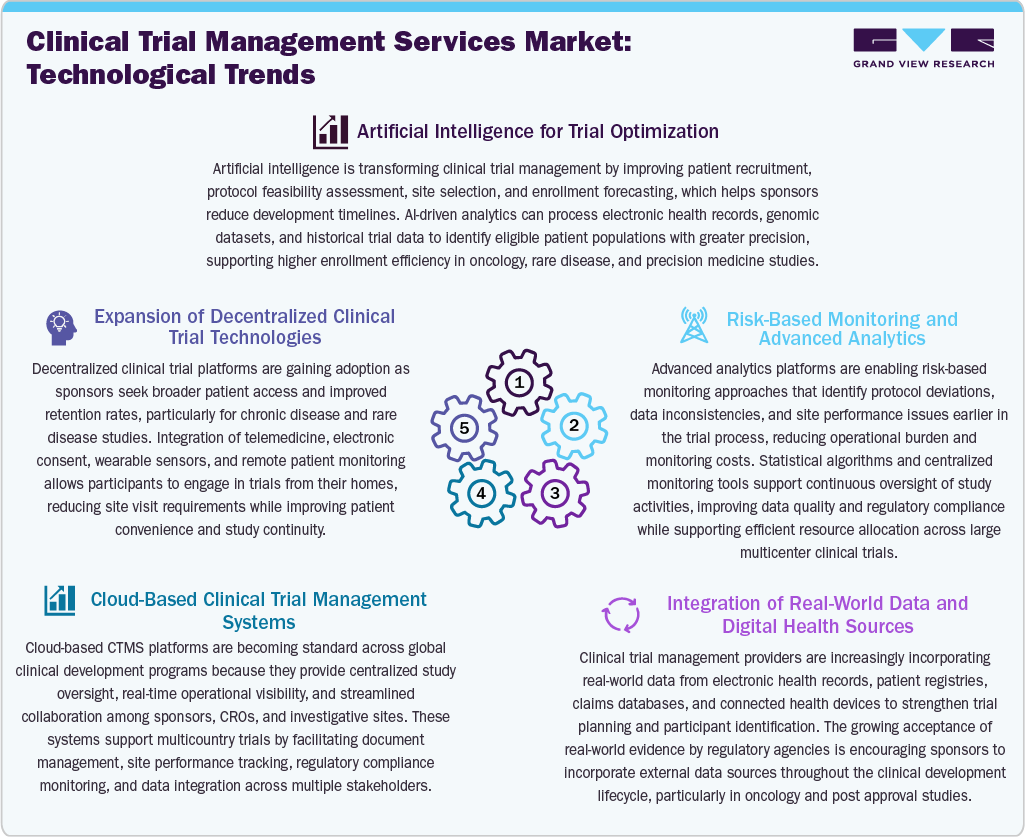
Clinical trial management services are undergoing significant technological transformation as sponsors seek greater efficiency, data quality, and patient engagement throughout the clinical development process. Artificial intelligence and predictive analytics are increasingly being incorporated into patient identification, site selection, enrollment forecasting, and protocol optimization, helping sponsors address recruitment bottlenecks in complex studies. The growing adoption of decentralized and hybrid trial models has accelerated the use of telemedicine platforms, electronic consent solutions, wearable devices, and remote patient monitoring technologies, allowing participants to engage in studies with fewer site visits.
 To learn more about this report, Download Free Sample Report
Cloud-based clinical trial management systems are gaining wider acceptance as they provide centralized oversight of study operations and facilitate collaboration among sponsors, CROs, investigators, and regulatory stakeholders. Furthermore, the integration of real-world data sources, such as electronic health records, patient registries, and claims databases, is improving trial feasibility assessments and participant identification strategies. Risk-based monitoring approaches supported by advanced analytics enable earlier detection of protocol deviations and site performance issues, reducing the need for extensive on-site monitoring. These technological advancements are improving study execution, supporting regulatory compliance, and helping sponsors manage increasingly complex global clinical trials.
Pricing Model Analysis
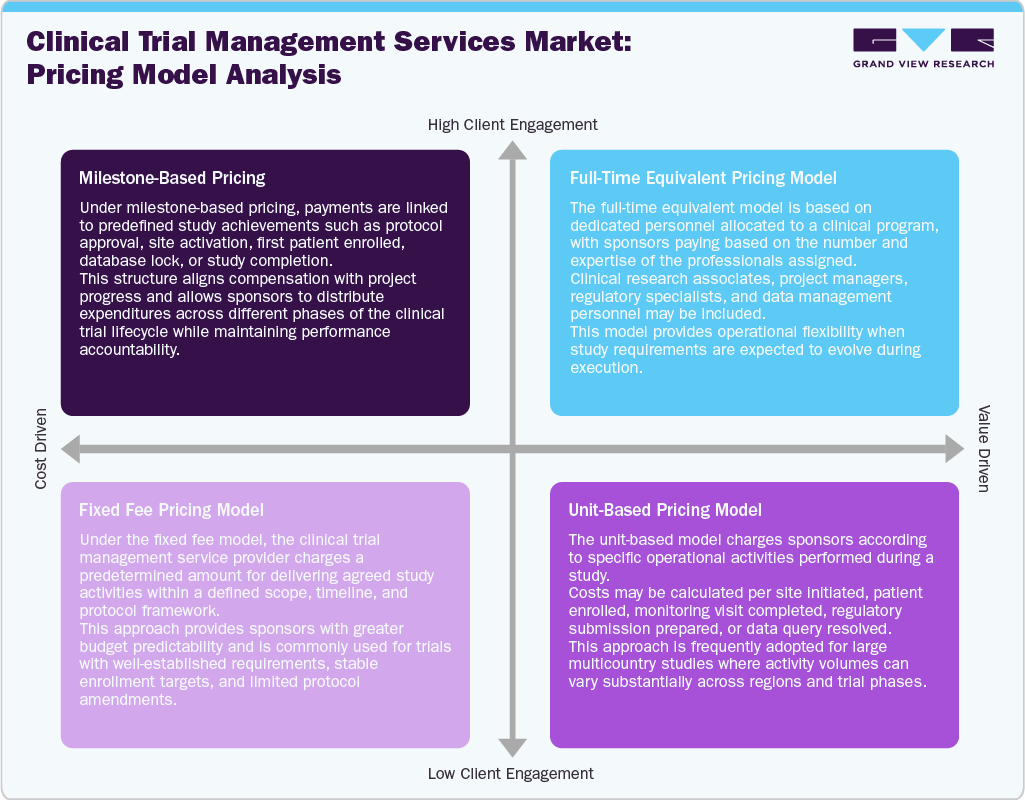
Clinical trial management services utilize several pricing structures depending on study complexity, duration, and operational requirements. Fixed-fee pricing is widely used for trials with clearly defined scopes as it provides budget certainty throughout the project. Full-time equivalent arrangements are preferred when sponsors require dedicated resources and flexibility to accommodate protocol modifications or changing enrollment strategies.
 To learn more about this report, Download Free Sample Report
Milestone-based pricing ties payments to key clinical development milestones, creating a direct link between project progress and financial commitments. Unit-based pricing is commonly adopted for large, geographically diverse studies, where specific operational activities, such as patient enrollment, site management, monitoring visits, or regulatory submissions, determine costs. The increasing complexity of oncology, rare disease, and decentralized clinical trials has encouraged sponsors to adopt hybrid pricing arrangements that combine multiple models within a single engagement. This allows clinical trial management providers to align service delivery with sponsor objectives while maintaining transparency in project costs and resource utilization.
Services Insights
The clinical trial monitoring segment led the market with the largest revenue share of 27.5% in 2025. The segment growth is driven by its critical role in maintaining protocol compliance, patient safety, and data quality across clinical studies. Growing volumes of multicenter and multinational trials have increased the demand for monitoring activities, including site initiation, source data verification, risk assessment, and safety oversight. Sponsors are increasingly adopting centralized, risk-based, and remote monitoring approaches to improve operational efficiency while reducing the costs of traditional site visits. Furthermore, the expansion of decentralized and hybrid clinical trials has increased the need for continuous oversight of patient-generated data collected through digital platforms and connected devices. These factors have positioned clinical trial monitoring as a core service category across all phases of drug development.
The medical writing segment is anticipated to register the fastest growth during the forecast period as clinical programs become more complex and regulatory documentation requirements continue to increase. Medical writing supports the preparation of study protocols, clinical study reports, investigator brochures, informed consent forms, regulatory submissions, and safety narratives. The rising number of oncology, rare disease, cell therapy, and gene therapy trials is creating greater demand for specialized scientific documentation that complies with regulatory expectations across multiple jurisdictions. Furthermore, growing clinical activity among emerging biotechnology companies, many of which operate with limited internal regulatory resources, is increasing demand for outsourcing of professional medical writing services throughout the clinical development process.
Indication Insights
The oncology segment led the clinical trial management services industry with the largest revenue share of 37.4% in 2025. The segment growth is attributed to the substantial investment in cancer research and the growing number of oncology studies worldwide. Cancer remains one of the most active therapeutic areas in drug development, as pharmaceutical and biotechnology companies continue to advance targeted therapies, antibody-drug conjugates, immunotherapies, radiopharmaceuticals, and cell-based treatments. Oncology trials frequently involve biomarker screening, genomic profiling, adaptive study designs, and complex patient stratification requirements, increasing the need for specialized trial management expertise. For instance, according to the World Health Organization, global cancer cases are projected to reach approximately 35 million by 2050 compared with 20 million in 2022. The increasing disease burden, coupled with continued innovation in precision oncology, is sustaining strong demand for clinical trial management services across the oncology segment.
The diabetes segment is expected to emerge as the second-fastest-growing segment during the forecast period due to the rising global burden of diabetes and the ongoing development of innovative therapies to improve disease management. Increasing research activity focused on novel insulin formulations, glucose-lowering agents, combination therapies, and disease-modifying treatments is driving the number of clinical trials in this therapeutic area. Furthermore, growing adoption of digital health technologies, continuous glucose monitoring systems, and personalized treatment strategies has increased the complexity of diabetes clinical studies, creating greater demand for comprehensive clinical trial management services. The expanding focus on improving long-term patient outcomes and addressing diabetes-related complications is further supporting sustained investment in diabetes clinical research.
End-use Insights
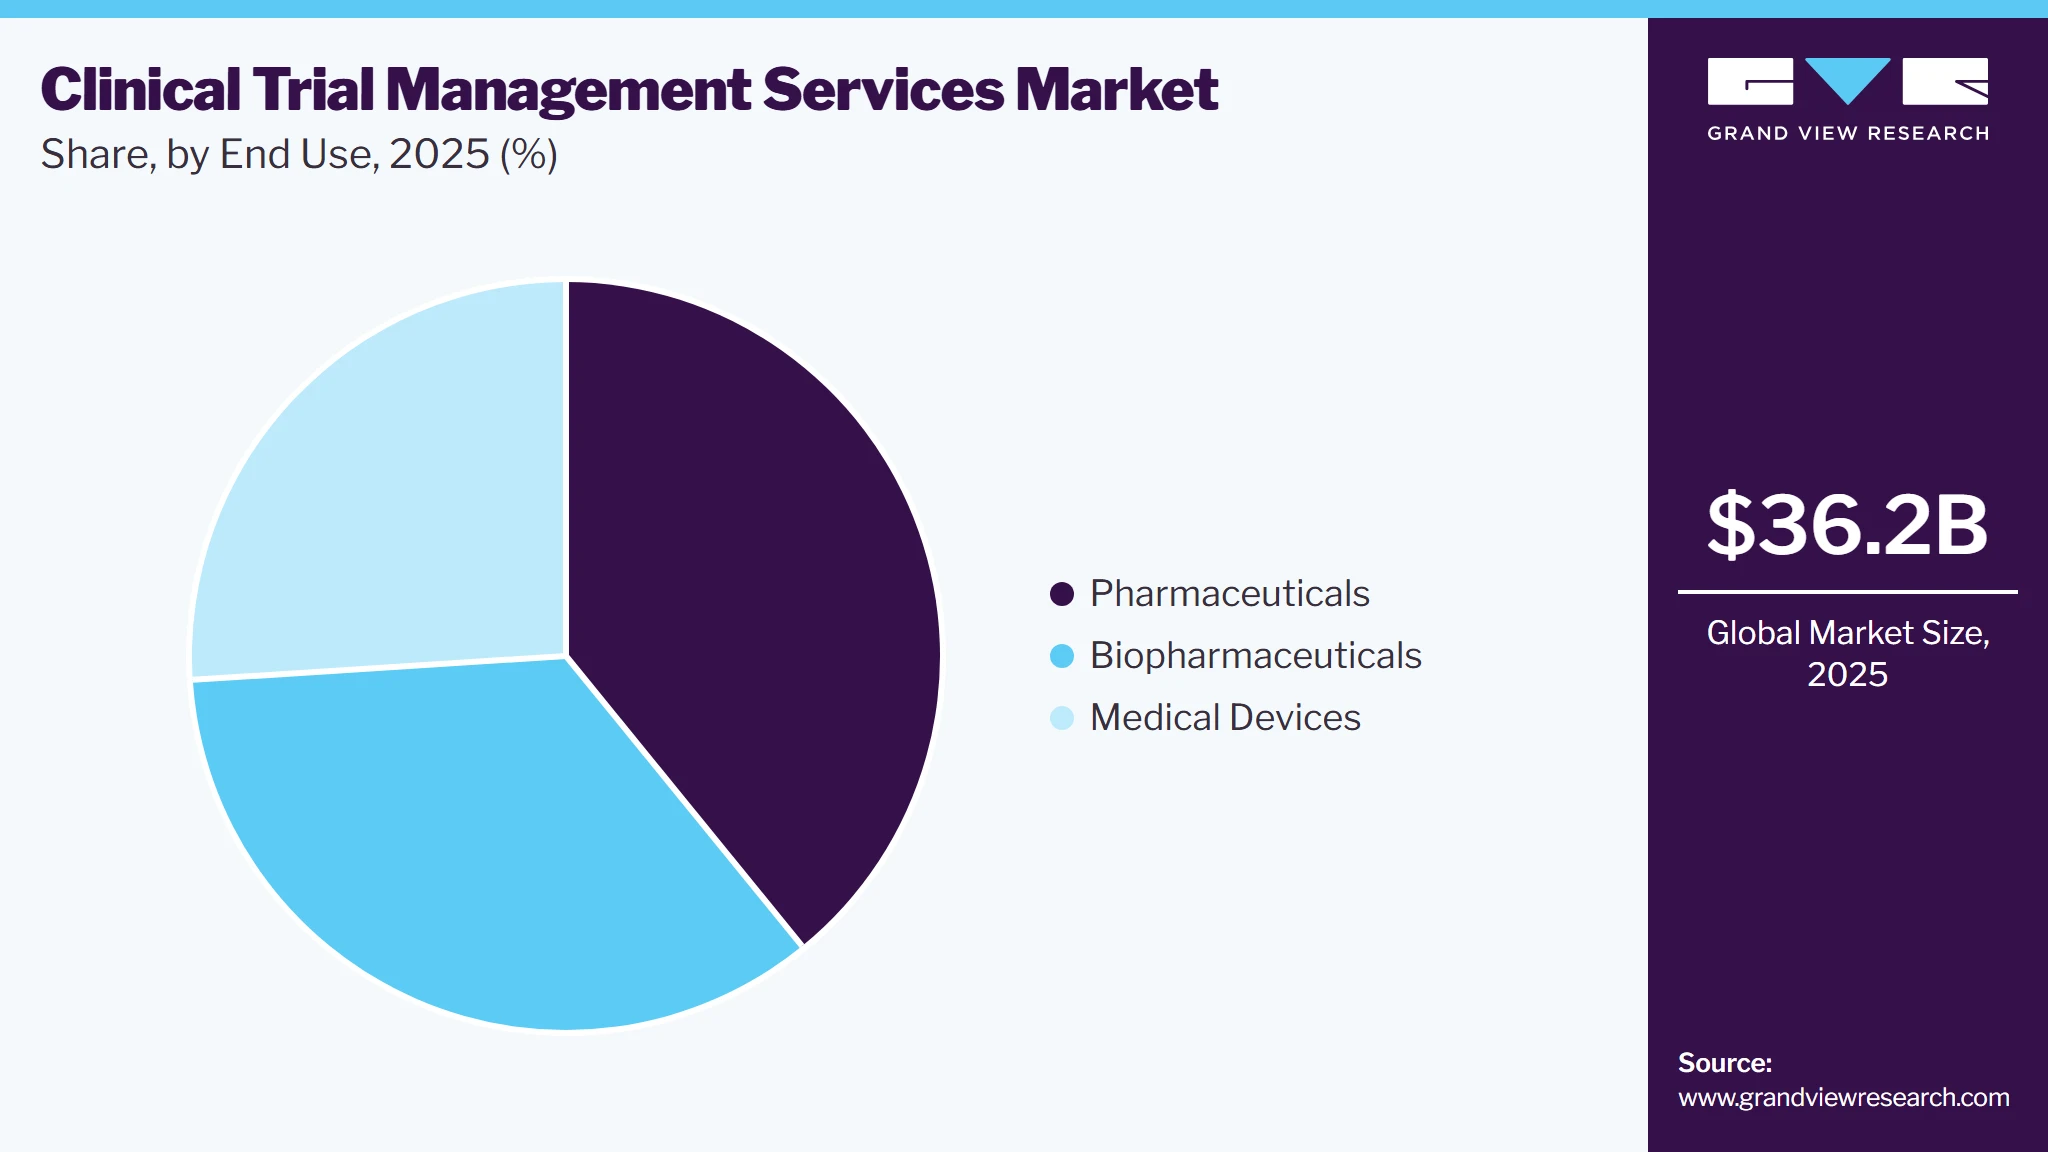
The pharmaceutical companies segment led the clinical trial management services market with the largest revenue share of 39.1% in 2025. The growth is driven by sustained investment in drug discovery and clinical development across major therapeutic areas. Large pharmaceutical organizations continue to maintain extensive pipelines spanning oncology, cardiovascular diseases, metabolic disorders, infectious diseases, and central nervous system conditions. Increasing numbers of Phase II and Phase III studies, coupled with growing regulatory requirements and global site networks, are driving demand for external clinical trial management expertise. Furthermore, pharmaceutical sponsors are increasingly outsourcing operational functions to improve development efficiency, accelerate patient enrollment, and manage rising clinical research costs.
 To learn more about this report, Download Free Sample Report
The biopharmaceutical segment is anticipated to register the fastest growth during the forecast period due to expanding development of biologics, biosimilars, cell therapies, gene therapies, and other advanced treatment modalities. Clinical studies involving biologic products typically require specialized patient selection strategies, advanced safety monitoring, cold-chain logistics, and extensive regulatory oversight, thereby increasing demand for experienced trial management partners. Furthermore, the growing prevalence of rare diseases and increasing investment by biotechnology companies in innovative therapies are supporting the segment’s growth.
Regional Insights
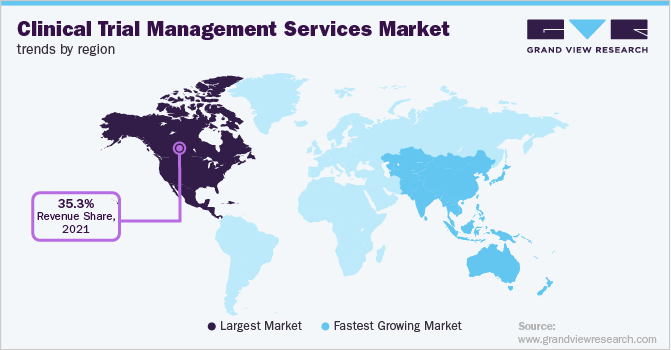
North America dominated the clinical trial management servicesmarket with the largest revenue share of 34.7% in 2025, driven by the region's concentration of pharmaceutical sponsors, biotechnology innovators, academic research institutions, and contract research organizations. The region continues to generate substantial clinical development activity across oncology, immunology, neuroscience, and rare disease indications, creating sustained demand for trial monitoring, site management, regulatory support, and patient recruitment services. Furthermore, increasing adoption of decentralized trial methodologies and digital health technologies has accelerated the need for advanced trial management capabilities. The growing complexity of clinical protocols and rising volume of multicenter studies continue to support the outsourcing of trial operations across the region.
 To learn more about this report, Download Free Sample Report
U.S. Clinical Trial Management Services Market Trends
The U.S. clinical trial management services industry held the largest share of North America in 2025.The country hosts a significant share of global investigational studies involving oncology, cell therapies, gene therapies, and precision medicine products. Growing investment in novel therapeutic modalities has increased demand for specialized trial management services capable of handling complex protocols, biomarker-driven enrollment strategies, and extensive regulatory documentation. Furthermore, the increasing adoption of decentralized clinical trial models, electronic data capture systems, and remote monitoring solutions is driving market expansion. The presence of major pharmaceutical companies, biotechnology firms, and leading contract research organizations continues to support long-term growth.
The clinical trial management services market in Canada is expected to grow steadily over the forecast period, driven by the country's strong clinical research infrastructure, a highly skilled healthcare workforce, and afavorable regulatory environment. Canada remains an attractive destination for multinational clinical studies because of its diverse patient population, high-quality healthcare system, and internationally recognized research institutions. Furthermore, increasing investments in oncology, rare diseases, neuroscience, and immunology research are generating demand for trial monitoring, patient recruitment, regulatory support, and clinical data management services. The growing adoption of decentralized clinical trial models and digital health technologies is further driving demand for specialized clinical trial management providers nationwide.
Europe Clinical Trial Management Services Market Trends
Europe accounted for a significant share of the global clinical trial management services industry in 2025, driven by its strong pharmaceutical sector, advanced healthcare systems, and increasing focus on innovative therapies. Rising clinical research activity across oncology, autoimmune diseases, cardiovascular disorders, and neurological conditions is generating demand for specialized trial management services. Furthermore, collaborative initiatives involving pharmaceutical companies, academic institutions, healthcare providers, and research networks are supporting multinational study execution across the region. The growing adoption of digital trial technologies and data-driven clinical development strategies is further strengthening the market.
In addition, Europe continues to attract global clinical development activity due to the increasing number of multicountry clinical studies conducted under harmonized regulatory frameworks. The implementation of the Clinical Trials Information System and the European Union Clinical Trials Regulation has simplified trial applications across member states, reducing administrative burdens for sponsors and research organizations. Furthermore, Europe remains a leading region for research into rare diseases and advanced therapy medicinal products, creating demand for specialized clinical trial management expertise. Growing investment in precision medicine initiatives, biomarker-driven studies, and real-world evidence generation is further increasing the complexity of clinical programs and supporting demand for outsourced trial management services.
The clinical trial management services market in Germany held the largest share of the European market in 2025, driven by its extensive pharmaceutical manufacturing base, advanced healthcare infrastructure, and strong investment in biomedical research. The country remains a preferred location for multinational clinical studies due to its experienced investigator network and established research institutions. Furthermore, the growing development of innovative biologics, oncology therapies, and rare disease treatments is driving demand for comprehensive trial management solutions. Sponsors continue to utilize external service providers to support study execution, regulatory submissions, and data management activities.
The UK clinical trial management services market is expected to grow significantly over the forecast period. The market is driven by the country's established life sciences sector and strong clinical research infrastructure. Access to centralized healthcare data through the National Health Service supports efficient patient identification and recruitment, particularly in large-scale clinical studies. Furthermore, increasing government support for life sciences innovation and growing investment in precision medicine programs are contributing to higher clinical trial volumes. Demand for clinical trial management services is also increasing as sponsors seek support for decentralized studies, regulatory compliance, and patient engagement initiatives.
Asia Pacific Clinical Trial Management Services Market Trends
Asia Pacific is projected to register the fastest CAGR during the forecast period, driven by increasing pharmaceutical research investments, improved clinical research infrastructure, and expanding patient access across major economies. Countries throughout the region are attracting more clinical development activity due to large treatment-eligible populations, cost advantages, and evolving regulatory environments. Furthermore, the rising prevalence of chronic diseases such as cancer, diabetes, and cardiovascular disorders is increasing demand for clinical studies and supporting the adoption of professional trial management services. Expanding participation of regional biotechnology companies is further contributing to market growth.
The China clinical trial management services market is rapidly growing due to the rapid expansion of its biopharmaceutical sector and increasing investment in innovative drug development. Regulatory reforms implemented over recent years have improved clinical trial approval timelines and encouraged both domestic and multinational sponsors to expand research activities within the country. Furthermore, the rising incidence of cancer, metabolic diseases, and age-related disorders is generating demand for large patient recruitment programs and complex clinical studies. These trends continue to support the adoption of clinical trial management services across all development phases.
The clinical trial management services market in Japan is driven by its sophisticated healthcare system, established regulatory framework, and ongoing investment in advanced therapeutics. The country remains an important market for oncology, regenerative medicine, and rare disease research, creating opportunities for service providers with expertise in complex clinical programs. Furthermore, increased collaboration between pharmaceutical companies and research institutions is driving sustained clinical trial activity and growing demand for trial management support.
The India Clinical Trial Management Services market is experiencing rapid expansion, attributed to the increasing outsourcing of clinical development activities by global pharmaceutical and biotechnology companies. The country's large and diverse patient population supports faster recruitment across multiple therapeutic areas, while improvements in regulatory processes have strengthened confidence among international sponsors. Furthermore, rising investment in biotechnology research, expansion of hospital-based research networks, and increasing adoption of digital clinical trial technologies are creating favorable conditions for market growth. Growing numbers of global multicenter studies are expected to further support demand for clinical trial management services.
Latin America Clinical Trial Management Services Market Trends
The clinical trial management services industry in Latin America is expected to grow significantly, driven by increased participation in international clinical studies and expanding healthcare research capabilities. The region offers access to diverse patient populations and comparatively lower operational costs, making it attractive for sponsors seeking efficient trial execution. Furthermore, improvements in regulatory procedures across several countries are facilitating study approvals and supporting growth in outsourced clinical research activities. The rising prevalence of chronic diseases is also contributing to increasing clinical trial volumes throughout the region.
The Brazil Clinical Trial Management Services market is driven by its sizable patient population, expanding research infrastructure, and growing clinical trial activity. Pharmaceutical and biotechnology companies are increasingly selecting countries for studies on oncology, infectious diseases, metabolic disorders, and cardiovascular conditions. Furthermore, ongoing regulatory improvements and growing availability of specialized research services are enhancing Brazil's attractiveness as a destination for multinational clinical development programs.
Middle East & Africa Clinical Trial Management Services Market Trends
The Middle East and Africa clinical trial management services industry is projected to grow steadily, driven by rising healthcare investments and growing interest in expanding regional clinical research capabilities. Governments and healthcare organizations are investing in research infrastructure and strengthening regulatory frameworks to attract international studies. Furthermore, the rising incidence of chronic diseases and increasing collaboration between research institutions and pharmaceutical companies are creating new opportunities for clinical trial management service providers across the region.
The UAE Clinical Trial Management Services market is anticipated to expand at a notable pace, driven by increasing government investment in healthcare innovation, biomedical research, and life sciences infrastructure. The country is positioning itself as a regional hub for clinical research through initiatives focused on precision medicine, genomics, and advanced healthcare technologies. Furthermore, the rising prevalence of chronic diseases such as diabetes, cardiovascular disorders, and cancer is increasing interest in conducting local and regional clinical studies. The presence of specialized healthcare centers, improvements in regulatory frameworks, and growing collaboration among healthcare providers, pharmaceutical companies, and research institutions are contributing to the rising demand for clinical trial management services. The increasing adoption of electronic health systems and digital healthcare platforms is also supporting efficient patient recruitment and study management activities nationwide.
Key Clinical Trial Management Services Company Insights
The key players operating across the market are adopting strategic initiatives such as service launches, mergers & acquisitions, partnerships & agreements, and expansions to gain a competitive edge in the market. For instance, in May 2025, IQVIA announced a strategic collaboration with SCRI Development Innovations to accelerate global oncology clinical trials by combining IQVIA's global clinical development capabilities with SCRI's community oncology research network and patient recruitment expertise. The collaboration aims to improve trial activation timelines, patient enrollment, and clinical data delivery across oncology studies.
Key Clinical Trial Management Services Companies:
The following key companies have been profiled for this study of the clinical trial management services market.
-
CTI Clinical Trial & Consulting
-
Charles River Laboratories
-
Medpace Holdings, Inc.
-
Wuxi Apptec
-
SGS Société Générale de Surveillance SA
-
Labcorp
-
IQVIA Holdings, Inc.
-
Syneous Health
-
Atlantic Research Group
- ICON Plc
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Mature Players: IQVIA Inc.
- The mature players in the market emphasize developing capabilities in drug development, biologics manufacturing, sterile fill finish, and manufacturing services.
- These include having regulatory-compliant infrastructures, advanced manufacturing technologies, strategic acquisitions, and global expansion.
- The mature players have the capability to manufacture products in large volumes with regulatory approvals globally and a portfolio of diversified services.
- These organizations enjoy competitive advantages by having end-to-end outsourcing capabilities and strong quality management systems, experience with biologics, and long-term pharmaceutical outsourcing partnerships.
- Regulatory compliance costs, sophisticated manufacturing operations, and costs incurred from maintaining facilities around the globe might pose a threat to the profit margins of mature CDMO players.
- Slow operations and decision-making, as well as heavy reliance on large-scale commercial deals, pose risks for emerging players when the markets experience volatility.
Emerging Players: Charles River Laboratories
- The emerging players employ flexible, focused strategies, with an emphasis on highly potent APIs, biologics, cell and gene therapy, and small-volume clinical manufacturing.
- These players seek to develop additional capabilities like flexibility, efficiency, having fast turnaround times, and expanding regionally.
- The emerging players benefit from operational flexibility, technical expertise in focused niches, and the adoption of advanced manufacturing technologies at a faster rate.
- Being operationally lean helps emerging players compete effectively with the larger multinational competitors.
- Limited capabilities due to small manufacturing capacity, lack of experience in dealing with regulations, shortage of funds, and the absence of a broad footprint in the global market are major weaknesses for emerging players.
Recent Developments
-
In December 2025, ICON plc announced the acquisition of Clinical Research Management, Inc. to strengthen its presence in government-sponsored research and expand capabilities in vaccine and infectious disease clinical studies. The transaction broadens ICON's service portfolio and enhances its ability to manage complex public health research programs.
-
In August 2025, IQVIA and Veeva Systems entered into long-term clinical and commercial partnerships that allow integration of clinical technologies, software platforms, and data solutions. The agreement is expected to improve operational efficiency and data accessibility across clinical development programs.
Clinical Trial Management Services Market Report Scope
Report Attribute
Details
Market size in 2025
USD 36.2 billion
Estimated market size in 2026
USD 39.2 billion
Projected market size by 2033
USD 68.4 billion
Growth rate
CAGR of 8.3% from 2026 to 2033
Actual data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Service, indication, end-use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Sweden; Norway; China; India; Japan; Australia; South Korea; Thailand; Brazil; Argentina; South Africa; UAE; Saudi Arabia; Kuwait; Qatar; Oman
Key companies profiled
CTI Clinical Trial & Consulting; Charles River Laboratories; Medpace Holdings, Inc.; Wuxi AppTec; SGS Société Générale de Surveillance SA; Labcorp; IQVIA, Inc.; Syneos Health; Atlantic Research Group; ICON Plc
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Clinical Trial Management Services Market Report Segmentation
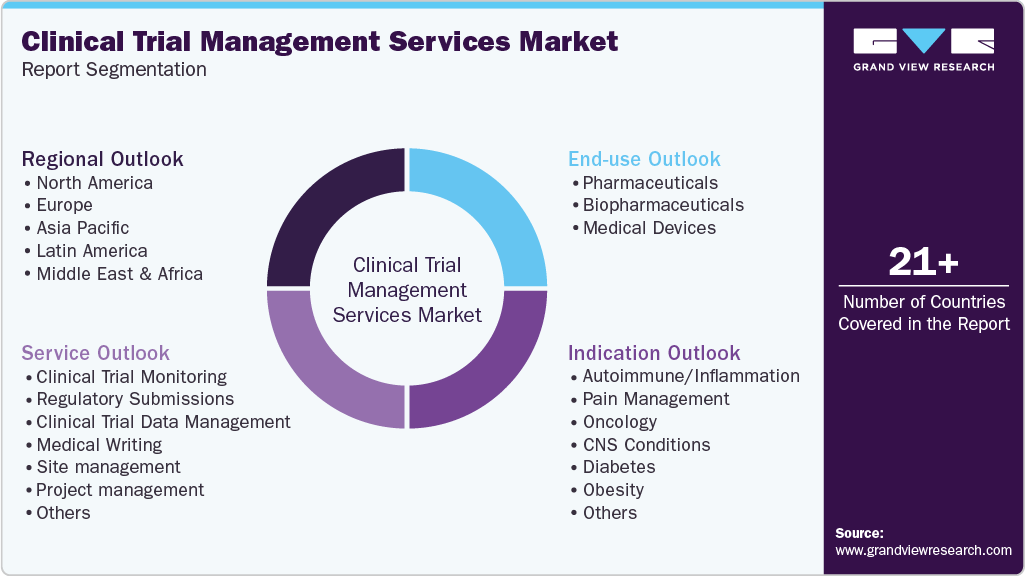
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global clinical trial management services market report based on service, indication, end-use and region:
 To learn more about this report, Download Free Sample Report
-
Service Outlook (Revenue, USD Million, 2021 - 2033)
-
Clinical Trial Monitoring
-
Regulatory Submissions
-
Clinical Trial Data Management
-
Medical Writing
-
Site management
-
Project management
-
Others
-
-
Indication Outlook (Revenue, USD Million, 2021 - 2033)
-
Autoimmune/Inflammation
-
Pain management
-
Oncology
-
CNS conditions
-
Diabetes
-
Obesity
-
Cardiovascular
-
Others
-
-
End-use Outlook (Revenue, USD Million, 2021 - 2033)
-
Pharmaceuticals
-
Biopharmaceuticals
-
Medical Devices
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
UAE
-
Saudi Arabia
-
Kuwait
-
Qatar
-
Oman
-
-
Research Methodology
The clinical trial management services market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each clinical trial management services segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Service
Revenue capture definition
Clinical Trial Monitoring
The segment captures revenue generated by clinical trial monitoring services provided to oversee study conduct across Phase I to Phase IV clinical trials. Services include site initiation, routine monitoring visits, source data verification, protocol compliance assessment, patient safety monitoring, risk-based monitoring, remote monitoring, site close-out activities, and regulatory documentation to ensure Good Clinical Practice (GCP) compliance and data integrity.
Regulatory Submissions
The segment captures revenue generated by regulatory submission services supporting clinical trial approvals and ongoing regulatory compliance. Services include preparation and submission of clinical trial applications, investigational new drug (IND) dossiers, clinical study reports, ethics committee documentation, regulatory correspondence, lifecycle submissions, and support for interactions with regulatory authorities throughout clinical development.
Clinical Trial Data Management
The segment captures revenue generated by clinical trial data management services for collecting, validating, processing, and maintaining clinical study data. Services include electronic data capture (EDC) setup, database design, data validation, query management, database lock, coding of medical terms, quality control, and preparation of clinical datasets for statistical analysis and regulatory submissions.
Medical Writing
The segment captures revenue generated by medical writing services supporting clinical development and regulatory documentation. Services include preparation of clinical study protocols, investigator brochures, informed consent forms, clinical study reports, regulatory submission documents, safety narratives, scientific publications, manuscripts, and other medical communication materials required during clinical research.
Site Management
The segment captures revenue generated by site management services supporting the operational execution of clinical trials at investigative sites. Services include site selection, feasibility assessments, site activation, patient recruitment support, investigator coordination, contract administration, site training, document management, and site close-out activities to ensure efficient trial execution.
Project Management
The segment captures revenue generated by project management services provided for planning, coordinating, and overseeing clinical trial operations. Services include study planning, timeline management, budget oversight, vendor coordination, resource allocation, risk management, quality management, sponsor communication, and overall operational governance throughout the clinical trial lifecycle.
Others
The segment captures revenue generated by other clinical trial management services, including clinical trial logistics, pharmacovigilance support, quality assurance, clinical trial technology support, decentralized clinical trial coordination, patient engagement services, training, auditing, and consulting services that facilitate efficient clinical trial execution.
Segment - Indication
Revenue capture definition
Autoimmune/Inflammation
The segment captures revenue generated by clinical trial management services provided for studies evaluating therapies for autoimmune and inflammatory disorders. Services support clinical research involving rheumatoid arthritis, psoriasis, inflammatory bowel disease, lupus, multiple sclerosis, and other immune-mediated diseases requiring complex patient monitoring and long-term efficacy assessments.
Pain Management
The segment captures revenue generated by clinical trial management services provided for studies evaluating acute and chronic pain therapies. Services support clinical research involving non-opioid analgesics, opioid therapies, neuromodulation technologies, biologics, regenerative therapies, and other pain management interventions requiring efficacy, safety, and patient-reported outcome assessments.
Oncology
The segment captures revenue generated by clinical trial management services provided for oncology clinical trials. Services support studies involving chemotherapy, targeted therapies, immunotherapies, antibody-drug conjugates (ADCs), cell and gene therapies, radiopharmaceuticals, and combination therapies requiring complex trial designs, biomarker evaluation, and extensive patient monitoring.
CNS Conditions
The segment captures revenue generated by clinical trial management services provided for studies evaluating therapies for central nervous system disorders. Services support clinical research involving Alzheimer's disease, Parkinson's disease, epilepsy, depression, schizophrenia, multiple sclerosis, and other neurological and psychiatric disorders requiring specialized endpoints and long-term patient follow-up.
Diabetes
The segment captures revenue generated by clinical trial management services provided for studies evaluating diabetes therapies and associated technologies. Services support clinical research involving insulin products, GLP-1 receptor agonists, SGLT2 inhibitors, combination therapies, diabetes devices, continuous glucose monitoring systems, and digital health solutions.
Obesity
The segment captures revenue generated by clinical trial management services provided for studies evaluating obesity therapies and weight management interventions. Services support clinical research involving anti-obesity drugs, metabolic therapies, combination treatments, medical devices, digital therapeutics, and lifestyle intervention programs designed to improve long-term weight management outcomes.
Cardiovascular
The segment captures revenue generated by clinical trial management services provided for cardiovascular clinical studies. Services support research involving heart failure, hypertension, coronary artery disease, dyslipidemia, arrhythmias, anticoagulants, cardiovascular devices, structural heart interventions, and other cardiovascular therapies requiring large multicenter clinical trials.
Others
The segment captures revenue generated by clinical trial management services provided for studies across additional therapeutic areas, including infectious diseases, respiratory disorders, rare diseases, gastrointestinal disorders, ophthalmology, dermatology, nephrology, hematology, and other indications not included in the above segments.
Segment - End Use
Revenue capture definition
Pharmaceuticals
The segment captures revenue generated by clinical trial management services provided to pharmaceutical companies developing small-molecule drugs and branded pharmaceutical products. Services include clinical trial monitoring, project management, data management, site management, regulatory submissions, medical writing, and operational support across all phases of clinical development.
Biopharmaceuticals
The segment captures revenue generated by clinical trial management services provided to biopharmaceutical companies developing biologics, biosimilars, monoclonal antibodies, vaccines, cell and gene therapies, recombinant proteins, and other advanced therapeutics. Services include comprehensive clinical trial management, regulatory support, data management, and global study coordination throughout clinical development.
Medical Devices
The segment captures revenue generated by clinical trial management services provided to medical device manufacturers conducting clinical investigations to evaluate the safety, performance, and effectiveness of diagnostic, therapeutic, implantable, digital, and combination medical devices. Services include study monitoring, site management, regulatory submissions, data management, project management, and post-market clinical follow-up support.
Estimation Model
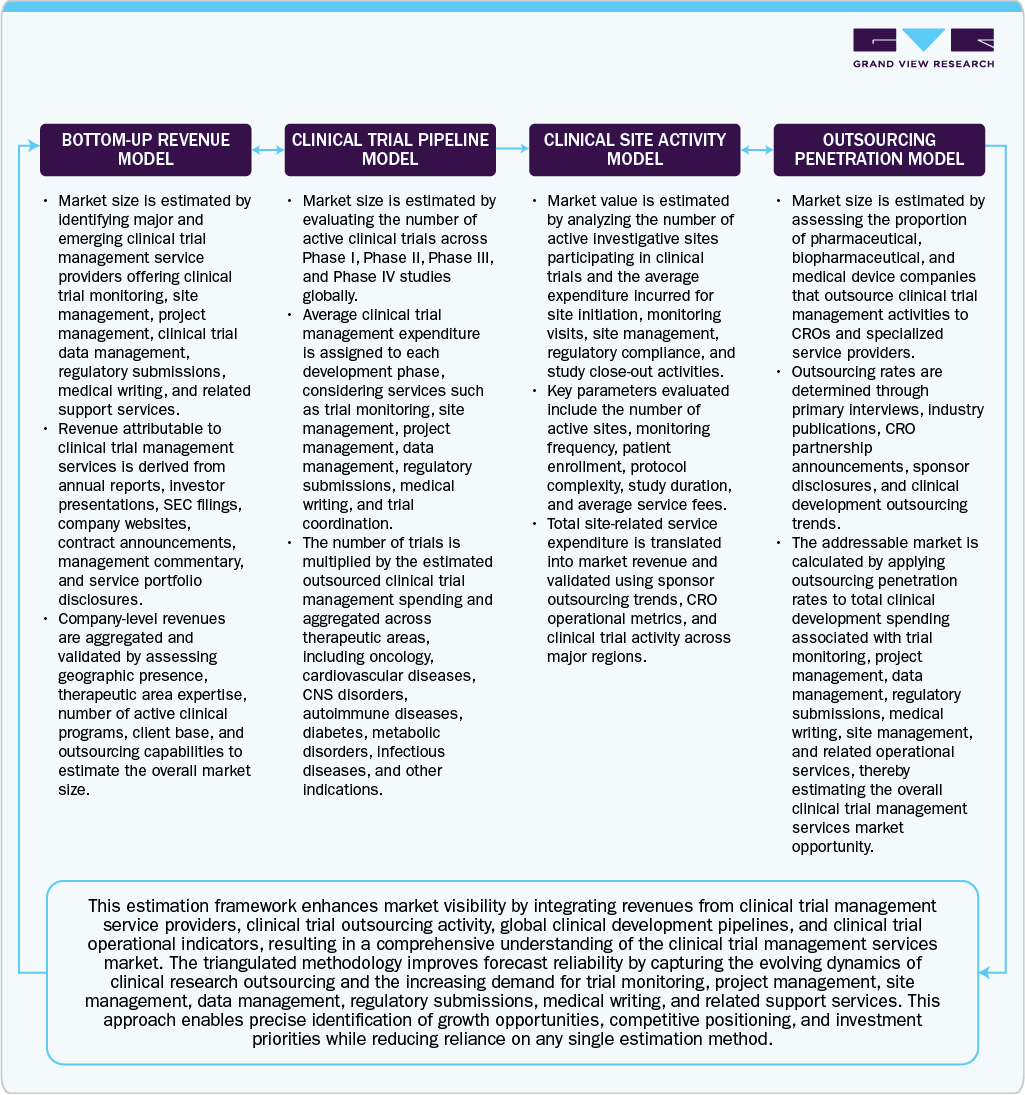 To learn more about this report, Download Free Sample Report
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Assessment of Clinical Trial Outsourcing Trends by Therapeutic Area
Evaluated outsourcing activity across oncology, autoimmune diseases, rare diseases, cardiovascular disorders, neuroscience, and infectious diseases. Assessed sponsor preferences for clinical monitoring, patient recruitment, medical writing, regulatory affairs, and data management services. Included analysis of outsourcing intensity by trial phase and sponsor type.
Helps identify therapeutic areas generating the highest demand for clinical trial management services and supports prioritization of business development efforts.
Analysis of Patient Recruitment and Site Selection Landscape
Developed a country-level assessment of patient recruitment performance, investigator availability, site density, enrollment timelines, and participant retention trends across major clinical research markets. Included evaluation of recruitment challenges and opportunities by therapeutic area and study complexity.
Enables sponsors and service providers to identify favorable trial locations, improve enrollment strategies, and reduce delays associated with patient recruitment.
Evaluation of Decentralized and Hybrid Clinical Trial Adoption
Assessed adoption of decentralized and hybrid trial models across key regions, including utilization of telehealth visits, electronic consent, wearable devices, remote monitoring, and direct-to-patient services. Examined regulatory acceptance, sponsor adoption trends, and technology deployment across different study types.
Provides insights into emerging service opportunities and helps organizations align investments with evolving clinical trial operating models.
Frequently Asked Questions About This Report
The global clinical trial management services market size was valued at USD 36.2 billion in 2025 and is estimated at USD 39.2 billion for 2026.
The global clinical trial management services market is expected to grow at a CAGR of 8.3% from 2026 to 2033, reaching USD 68.4 billion.
The clinical trial monitoring segment led with a 27.5% revenue share in 2025, while medical writing is the fastest-growing segment.
The oncology segment led with a 37.4% revenue share in 2025, while diabetes is the second fastest-growing segment.
The pharmaceuticals segment led with a 39.1% revenue share in 2025, while biopharmaceuticals is the fastest-growing segment.
Key players include CTI Clinical Trial & Consulting, Charles River Laboratories, Medpace Holdings, Inc., Wuxi Apptec, SGS Société Générale de Surveillance SA, Labcorp, IQVIA Holdings, Inc., Syneous Health, Atlantic Research Group, and ICON Plc among others.
The market's growth is driven by technological advancements in clinical trial monitoring services, rising R&D expenditure by pharmaceutical and biopharmaceutical companies, and the growing number of outsourced clinical trial management projects.
North America dominated with a 34.7% revenue share in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


