
- Home
- »
- Plastics, Polymers & Resins
- »
-
Construction Films Market Size & Share Report, 2026-2033GVR Report cover
![Construction Films Market (2026 - 2033)Report]()
Construction Films Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Vapor Barrier Films, Gas Barrier Films, Window Films, Solar Films), By Resin Type, By Application, By Function, By End Use, By Distribution Channel, Region, And Segment Forecasts
Market Size, 2025
$19.6BMarket Estimate, 2026
$20.6BMarket Forecast, 2033
$29.6BCAGR, 2026–2033
5.3%Construction Films Market Summary
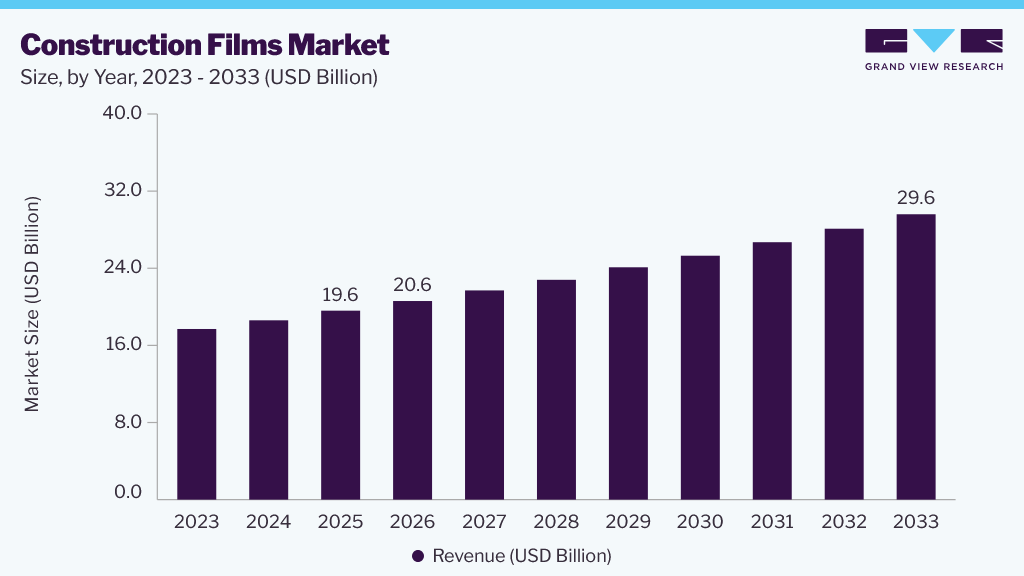
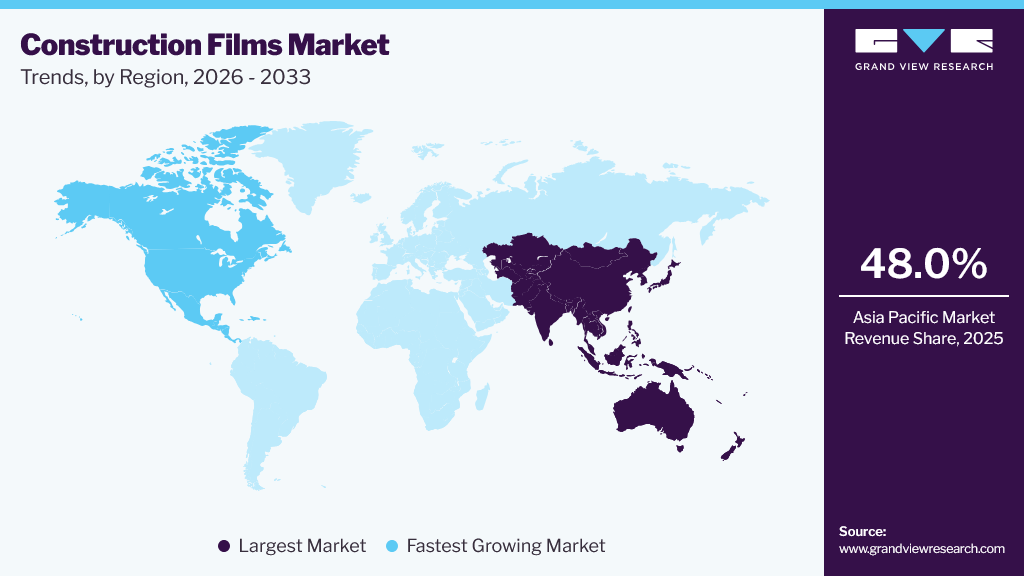
The global construction films market size was valued at USD 19.6 billion in 2025 and is projected to grow from USD 20.6 billion in 2026 to USD 29.6 billion in 2033, at a CAGR of 5.3% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 48.0% in 2025. Construction films are widely used in residential, commercial, and infrastructure projects for moisture protection, temporary surface protection, concrete curing, vapor barriers, and weatherproofing during construction activities.
Key Market Trends & Insights
- By product: The vapor barrier films segment held the largest market share of around 31.5% in 2025.
- By resin type: The polyolefin films segment held the largest market share of around 26.0% in 2025.
- By end use: The commercial use segment held the largest market share of 45.5% in 2025.
- By application: The roofing segment held the largest market share of over 22.0% in 2025.
- By function: The protection segment held the largest market share of more than 35.0% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (48.0% revenue share, 2025)
- Fastest-growing regional market: North America (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 19.6 Billion
- Estimated market size in 2026: USD 20.6 Billion
- Projected market size by 2033: USD 29.6 Billion
- CAGR (2026-2033): 5.3%
Rapid urbanization, infrastructure development, and increasing investments in residential and commercial construction continue to drive demand for construction films worldwide. The growing adoption of prefabricated construction methods and stringent building quality standards are further increasing the use of protective films to improve construction efficiency and safeguard building materials during installation. For instance, in May 2025, in May 2025, JPFL Films announced the installation of new BOPP, PET, and CPP film production lines at its Nashik facility. The expansion is intended to strengthen the company's manufacturing capabilities and support growing demand across its film product portfolio.Increasing emphasis on durable building materials and sustainable construction practices is further supporting market growth. Construction films are increasingly used as moisture barriers, vapor control layers, and concrete curing films to improve construction quality and material performance. Meanwhile, manufacturers are expanding the availability of recyclable and resource-efficient film solutions to align with evolving environmental regulations and green building requirements, creating new growth opportunities for the market.
Analyst Perspective
The construction films market is entering a phase of value-driven growth, where product performance and regulatory compliance are becoming as important as volume demand. As construction projects become more complex and quality standards continue to tighten, demand is shifting toward high-performance films that provide moisture protection, weather resistance, vapor control, and surface protection throughout the construction lifecycle. Sustainability is also reshaping product development, encouraging manufacturers to introduce recyclable materials and improve resource efficiency without compromising performance. While rapid infrastructure development and urban expansion will continue to support market demand, renovation and rehabilitation activities in developed economies are expected to provide stable long-term opportunities. Companies that strengthen manufacturing capabilities, expand specialty film portfolios, and align their products with evolving building standards are expected to gain a stronger competitive position over the forecast period.
Product Insights
The vapor barrier films segment held the largest market share of around 31.5% in 2025. The segment's dominance is driven by increasing demand for effective moisture protection across residential, commercial, and infrastructure projects. Vapor barrier films are widely used to improve building durability, protect insulation systems, and comply with building standards related to moisture control and energy efficiency. Growing investments in modern construction, combined with increasing adoption of high-performance building materials, continue to support demand for vapor barrier films across developed and emerging markets.
The solar films segment is expected to register the fastest CAGR during the forecast period. Growth is driven by increasing adoption of energy-efficient buildings, green construction practices, and demand for solutions that improve indoor thermal performance and reduce cooling requirements. The rising adoption of sustainable building standards and growing investments in commercial and residential infrastructure are further supporting market growth. For instance, in July 2025, LINTEC Corporation launched BR-50UH RECYCLE 100, a solar-control window film designed to reduce solar heat while maintaining high transparency for offices, residential buildings, and commercial facilities. The launch reflects continued product innovation in energy-efficient building materials.
Resins type Insights
The polyolefin films segment held the largest market share of around 26.0% in 2025, due to the widespread use of polyolefin-based films across moisture barriers, protective coverings, vapor barriers, and temporary surface protection in residential, commercial, and infrastructure projects. Polyolefin offers an effective balance of durability, processability, and cost efficiency, making it a preferred material for large-scale construction applications. Growing demand for lightweight, recyclable, and high-performance construction films, together with increasing construction activity across emerging economies, continues to support segment growth.
The ethylene vinyl alcohol (EVOH) segment is expected to register the fastest CAGR during the forecast period. Growth is driven by increasing demand for high-performance multilayer construction films that provide enhanced barrier performance and long-term durability. EVOH is increasingly incorporated into advanced film structures for building envelopes, roofing membranes, flooring systems, and protective construction applications that require improved barrier properties. Rising adoption of premium construction materials and growing emphasis on building durability and material performance are expected to support continued demand for EVOH-based construction films.
Application Insights
The roofing segment held the largest market share of over 22.0% in 2025, driven by the increasing adoption of high-performance roofing membranes across residential, commercial, and industrial construction projects. Construction films are widely used in roofing systems to provide moisture protection, improve weather resistance, and enhance the durability of building structures. Rising investments in new construction, roof replacement, and renovation projects, together with growing demand for long-lasting and energy-efficient roofing solutions, continue to support demand for construction films in roofing applications.
The building envelope segment is expected to register the fastest CAGR during the forecast period. Growth is driven by increasing adoption of high-performance building envelope systems that improve moisture management, air sealing, and overall building performance. Construction films are increasingly incorporated into exterior wall assemblies and insulation systems to support compliance with modern building standards and energy-efficiency requirements. Rising investment in sustainable construction, high-performance commercial buildings, and green infrastructure projects is expected to accelerate demand for construction films used in building-envelope applications throughout the forecast period.
Function Insights
By function, the protection segment held the largest market share of more than 35.0% in 2025. The widespread use of construction films to protect building materials, structural components, and finished surfaces during construction, transportation, storage, and renovation activities. Protection films help minimize damage caused by moisture, dust, debris, weather exposure, and mechanical wear, reducing maintenance requirements and material losses on construction sites. Growing investments in residential, commercial, and infrastructure projects continue to support demand for protective construction films across a wide range of applications.
The glazing is expected to grow at the fastest CAGR during the forecast period. Growth is driven by increasing demand for energy-efficient buildings and advanced glazing solutions that improve indoor comfort and building performance. Construction films used in glazing applications reduce solar heat gain, improve thermal efficiency, minimize glare, and enhance the performance of glass systems in residential and commercial buildings. Rising adoption of green building practices, energy-efficiency regulations, and retrofit projects is expected to accelerate demand for glazing films throughout the forecast period.
End Use Insights
The commercial segment held the largest market share, over 45.5%, in 2025. The increasing construction of office buildings, shopping centers, hospitals, educational institutions, warehouses, and other commercial facilities requires durable moisture protection and weather-resistant building materials. Construction films are widely used in roofing systems, building envelopes, temporary surface protection, and vapor barrier applications to improve building performance and construction efficiency. Rising investments in commercial infrastructure and renovation projects continue to support demand for construction films across developed and emerging markets.
The residential use is expected to grow at the fastest CAGR during the forecast period. Growth is supported by increased housing construction, the expansion of affordable housing projects, and rising renovation activity across both developed and emerging economies. Construction films are increasingly adopted in residential buildings for moisture management, insulation support, roofing, and temporary surface protection during construction and remodeling. Growing demand for durable, cost-effective building materials and continued advancements in construction film technologies are expected to support long-term growth in the residential segment.
Distribution Channel Insights
The direct segment held the largest market share of around 80.0% in 2025. The segment's dominance is driven by increased procurement through direct relationships with manufacturers for large-scale residential, commercial, and infrastructure projects. Direct sales enable manufacturers to supply project-specific products in bulk while improving delivery coordination and technical support for contractors and construction companies. For instance, in April 2024, Shish Industries Limited entered into a five-year commercial trade agreement with Best Construction Products Inc. (U.S.) to supply construction and thermal insulation products. The agreement reflects continued focus on strengthening long-term supply arrangements across international markets.
Third-party distribution channels are expected to grow significantly during the forecast period. The increasing demand for wider product availability across regional markets and the expanding role of distributors in serving small and medium-sized contractors. Third-party distributors provide local inventory, logistics support, and faster product availability, helping manufacturers expand their market reach without establishing dedicated sales networks. Growing construction activity across geographically diverse markets is expected to further support demand for third-party distribution channels.
Regional Insights
Asia Pacific dominated the construction films market, accounting for approximately 48.0% of the global revenue in 2025. The region benefits from a well-established manufacturing base for polymer films, enabling cost-efficient production and widespread product availability. Strong domestic supply chains, expanding exports, and the presence of major film manufacturers have positioned the Asia Pacific as a key production hub for construction films. In addition, the increasing adoption of prefabricated construction methods is supporting demand for films used in temporary protection, moisture management, and building-envelope applications.
The China construction films market is expected to witness significant growth during the forecast period. Growth is supported by continuous product innovation and increasing availability of advanced construction protection materials designed to improve building durability and installation efficiency. For instance, in February 2024, DuPont launched Tyvek Protec PSU Peel & Stick Underlayment, a roofing underlayment designed for construction applications that delivers high-temperature and UV resistance. The introduction reflects continued innovation in construction protection products available for modern building projects.
The India construction films market is expected to register strong growth over the forecast period. Demand is supported by increasing adoption of organized construction practices and greater use of protective materials to improve construction quality and reduce material losses at project sites. Growing preference for waterproofing systems, roofing protection, and moisture management solutions across residential and commercial developments is expected to expand the use of construction films. The market is also benefiting from rising awareness of long-term building durability and lifecycle performance among contractors and developers.
North America Construction Films Market Trends
The North America film construction market is expected to grow fastest during forecast period. Market growth is supported by the increasing adoption of premium construction materials across renovation and building rehabilitation projects, where protective films are widely used to improve installation quality and extend the service life of building components. The region is also witnessing growing demand for high-performance construction films that simplify installation and reduce long-term maintenance requirements across residential and commercial buildings. For instance, In August 2024, Avery Dennison launched SkyLite 20 XTRM Pro, an exterior skylight window film for residential and commercial buildings in North America. According to the company, the product is designed to provide enhanced durability, improve energy performance, and enable faster installation. The launch reflects continued innovation in high-performance construction film solutions for the regional market.
Europe Construction Films Market Trends
Europe construction films market is expected to witness substantial growth. The region is characterized by a mature construction industry with a strong focus on renovation, refurbishment, and long-term building performance. Construction films are increasingly used in roofing systems, building envelope applications, and temporary surface protection to improve installation quality and extend the service life of building materials. Growing adoption of premium construction products and increasing replacement of aging building components continue to support demand for high-performance construction films across the region.
The UK construction films market is expected to grow steadily over the forecast period. Demand is supported by increasing renovation of residential and commercial buildings and the growing use of advanced protective materials in roofing, insulation, and moisture management applications. Contractors are increasingly adopting high-performance construction films to improve installation efficiency, reduce material damage during construction, and enhance long-term building durability. The continued modernization of existing buildings is expected to create sustained demand for construction films across the UK market.
Key Construction Films Market Companies Insights
The construction films market is characterized by continuous product innovation, capacity expansion, and strategic collaborations among leading manufacturers. Companies are strengthening their specialty film portfolios, improving manufacturing capabilities, and expanding regional distribution networks to address evolving construction requirements and reinforce their competitive position in global markets.
Key Construction Films Companies
The following key companies have been profiled for this study on the construction films market:
-
Raven Industries
-
Berry Global, Inc.
-
Saint-Gobain
-
DuPont
-
Eastman Chemical Company
-
Polyplex
-
RKW Group
-
Plastika Kritis S.A.
-
Qenos Pty Ltd.
-
KURARAY CO., LTD.
-
Reinforced Plastics Industries
-
CLIMAX SYNTHETIC PVT. LTD.
-
Poly-America, L.P.
Recent Developments
- In February 2025, Saint-Gobain completed the acquisition of FOSROC, strengthening its global construction chemicals business and expanding its presence in high-growth markets, including India, the Middle East, and Asia-Pacific. The acquisition enhances Saint-Gobain's portfolio of solutions for the construction industry.
Construction Films Market Report Scope
Report Attribute
Details
Market size in 2025
USD 19.6 billion
Estimated market size in 2026
USD 20.6 billion
Projected market size by 2033
USD 29.6 billion
Growth rate
CAGR of 5.3% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
North America; Europe; Asia Pacific; Latin America; MEA
Segments covered
Product; resin type; application; function; end use; distribution channel; region
Regional Scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country Scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Russia; Denmark; Sweden; Norway; China; India; Japan; South Korea; Australia; Indonesia; Vietnam; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
Raven Industries; Berry Global, Inc.; Saint-Gobain; DuPont; Eastman Chemical Company; Polyplex; RKW Group; Plastika Kritis S.A.; Qenos Pty Ltd.; KURARAY CO., LTD.; Reinforced Plastics Industries; CLIMAX SYNTHETIC PVT. LTD.; Poly-America, L.P.
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Construction Films Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and analyzes the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global construction films market report based on product, resin type, application, function, end use, distribution channel, and region.
- Product Outlook (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
- Vapor Barrier Films
- Gas Barrier Films
- Window Films
- Solar Films
- Others
- Resin Type Outlook (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
- Polyolefin Films
- Polyester Films
- Nylon Films
- Ethylene Vinyl Alcohol Films
- Polyvinyl Butyral Films
- Fluoropolymer Films
- Polyvinylidene Chloride Films
- Polyimide Films
- Bio-based Polymer Films
- Polyvinyl Chloride Films
- Others
- Application Outlook (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
- Flooring
- Walls & Ceilings
- Windows
- Doors
- Roofing
- Building & Enveloping
- Electrical
- HVAC
- Plumbing
- Others
- Function Outlook (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
- Bonding
- Protection
- Insulation
- Glazing
- Soundproofing
- Cable Management
- End Use Outlook (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
- Residential
- Commercial
- Industrial
- Distribution Channel Outlook (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
- Direct
- Third-party
- Regional Outlook (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- Germany
- France
- Italy
- Spain
- Russia
- Denmark
- Sweden
- Norway
- Asia Pacific
- China
- Japan
- India
- Australia
- South Korea
- Indonesia
- Vietnam
- Latin America
- Brazil
- Argentina
- Middle East and Africa (MEA)
- South Africa
- Saudi Arabia
- UAE
- Kuwait
- North America
Frequently Asked Questions About This Report
The global construction films market size was valued at USD 19.6 billion in 2025 and is estimated at USD 20.6 billion for 2026.
The global construction films market is expected to grow at a CAGR of 5.3% from 2026 to 2033, reaching USD 11.3 billion.
Asia Pacific dominated with a revenue share of approximately 48.0% in 2025.
Key players in the market include Raven Industries; Berry Global, Inc.; Saint-Gobain; DuPont; Eastman Chemical Company; Polyplex; RKW Group; Plastika Kritis S.A.; Qenos Pty Ltd.; KURARAY CO., LTD.; Reinforced Plastics Industries; CLIMAX SYNTHETIC PVT. LTD.; Poly-America, L.P., and others.
The vapor barrier films construction films segment accounted for the largest revenue share of around 31.5% in 2025.
About the Author(s)
Plastics, Polymers & Resins Research Team
Bulk Chemicals · Plastics, Polymers & ResinsThis report was authored by the plastics, polymers & resins research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the plastics, polymers & resins segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst


Customize this report to your needs — add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


