
- Home
- »
- Biotechnology
- »
-
Continuous Bioprocessing Market Size & Share Report, 2033GVR Report cover

Continuous Bioprocessing Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Instruments, Consumables & Reagents), By Application (Monoclonal Antibodies, Vaccines, Cell & Gene Therapy, Research & Development), By End-use, By Region, And Segment Forecasts
Market Size, 2025
$387.9MMarket Estimate, 2026
$460.3MMarket Forecast, 2033
$1,443.7MCAGR, 2026–2033
17.7%Continuous Bioprocessing Market Summary
The global continuous bioprocessing market size was valued at USD 387.9 million in 2025 and is projected to grow from USD 460.3 million in 2026 to USD 1,443.7 million by 2033, at a CAGR of 17.7% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 31.0% in 2025. The industry is driven by the growing demand for cost-efficient and scalable biopharmaceutical production, particularly for monoclonal antibodies, vaccines, and cell & gene therapies.
Key Market Trends & Insights
- By product: Consumables & reagents led the market with a share of around 65.0% in 2025.
- By application: Monoclonal antibodies dominated the market with a share of around 29.0% in 2025.
- By end-use: Pharmaceutical and biotechnology companies held the largest share of around 48.0% in 2025.
Regional Highlights
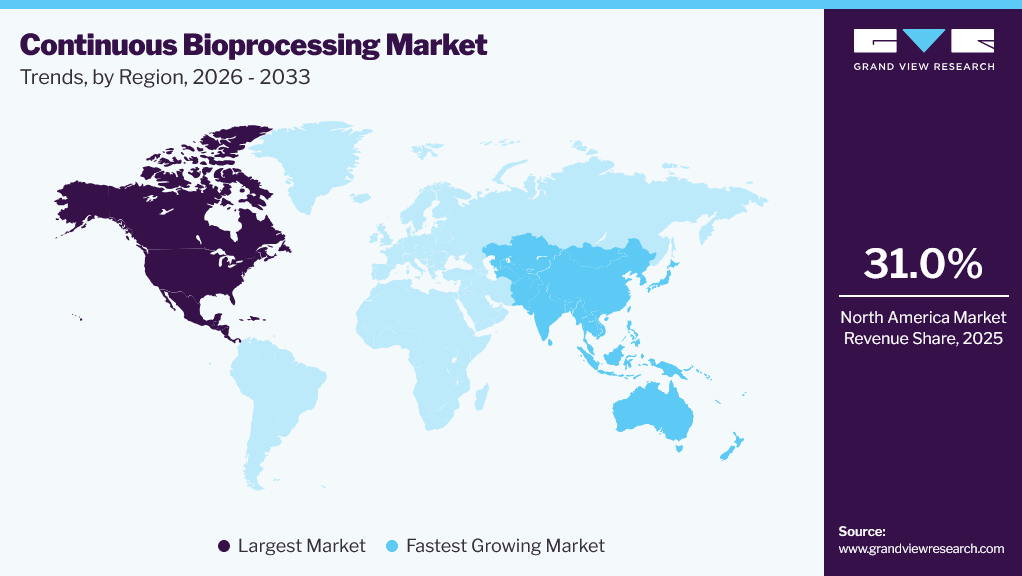
- Largest regional market: North America (31.0% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 387.9 Million
- Estimated market size in 2026: USD 460.3 Million
- Projected market size by 2033: USD 1,443.7 Million
- CAGR (2026-2033): 17.7%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Process intensification, enabled by automation, real-time monitoring, and single-use technologies, is enhancing productivity and reducing operational costs. Regulatory frameworks are increasingly accommodating continuous manufacturing approaches. The FDA and EMA have adopted ICH Q13, which provides scientific and regulatory considerations for the development, implementation, operation, and lifecycle management of continuous manufacturing processes, thereby supporting broader industry adoption.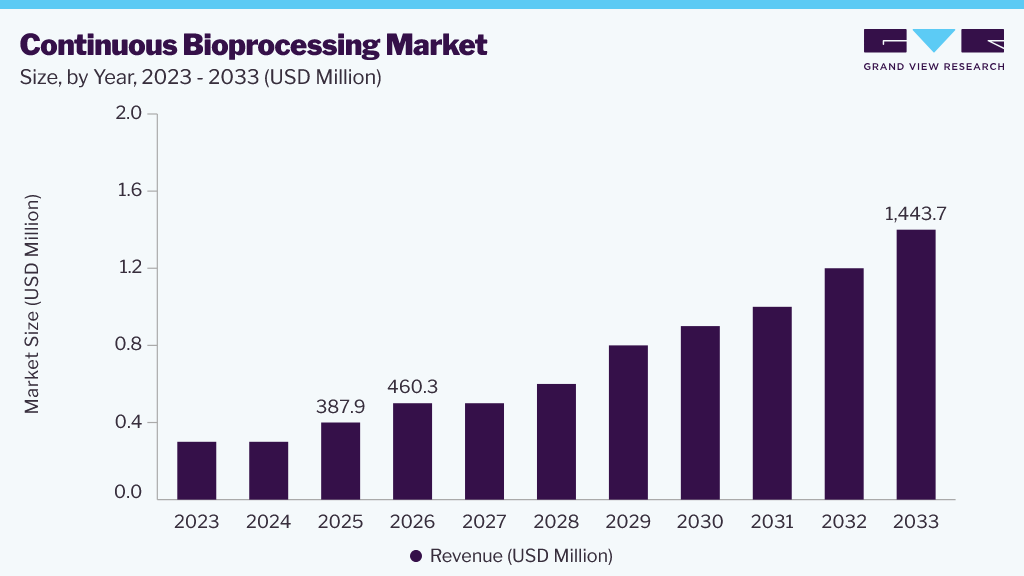 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
The industry forecast indicates significant growth, driven by increasing adoption of advanced biomanufacturing technologies, rising demand for biologics, and ongoing investments in automation and process optimization. Furthermore, continuous bioprocessing enables higher productivity, reduced costs, and better product consistency, making it a preferred choice for pharmaceutical and biotech companies. Additionally, the growing prevalence of chronic diseases such as cancer, autoimmune disorders, and infectious diseases has intensified the need for faster and more cost-effective biologic drug production, further accelerating market growth.
Another major driver is the technological advancements in bioprocessing equipment and automation. The integration of real-time process monitoring, single-use bioreactors, perfusion systems, and advanced analytics has significantly improved the feasibility of continuous bioprocessing. Companies are investing in digital bio manufacturing solutions, artificial intelligence, and machine learning to optimize process control, ensuring higher yields and product quality. Moreover, regulatory agencies, including the FDA and EMA, are encouraging the adoption of continuous bioprocessing by providing guidelines and implementation support, thereby reducing barriers for companies looking to transition from batch to continuous operations.
The shift toward cost-efficient and sustainable manufacturing practices is also propelling the continuous bioprocessing market. Traditional batch processing generates significant waste and requires large production facilities, leading to high capital and operational expenses. Continuous bioprocessing minimizes resource consumption, reduces waste, and enhances overall process efficiency, making it an attractive option for companies seeking sustainable manufacturing solutions. Additionally, the biopharmaceutical industry's growing focus on decentralized manufacturing and flexible production capabilities, especially in response to global healthcare demands and pandemic preparedness, has further driven the adoption of continuous bioprocessing technologies.
Growing Demand for Biologics & Biosimilars
The growing demand for biologics and biosimilars is increasing interest in intensified and continuous manufacturing approaches that can improve productivity, reduce process hold times, and support more flexible production strategies. This is particularly relevant for monoclonal antibodies, recombinant proteins, and other high-volume biologics where manufacturers are seeking greater throughput and process consistency. With rising global demand for monoclonal antibodies (mAbs), gene therapies, and recombinant proteins, companies are increasingly shifting from traditional batch processing to continuous bioprocessing to improve yields, reduce production time, and ensure consistent product quality. For instance, Boehringer Ingelheim has integrated continuous bioprocessing in its large-scale biologics manufacturing to enhance efficiency, while Samsung Biologics has expanded its single-use and perfusion-based bioprocessing capabilities to support biosimilar production. Similarly, Amgen has leveraged continuous manufacturing for next-gen biologics, aiming to reduce costs and enhance process control. As more companies invest in intensified bioprocessing strategies, the adoption of continuous bioprocessing is expected to accelerate, particularly in the biosimilar and novel biologics segments.
Technological Advancements in Bioprocessing Systems
Technological advancements and single-use systems are key drivers of the continuous bioprocessing market, enabling greater flexibility, reduced contamination risks, and cost savings. Innovations in perfusion bioreactors, real-time Process Analytical Technology (PAT), and automated control systems are making continuous processing more efficient and scalable. Merck KGaA has developed Mobius single-use bioreactors to support continuous perfusion processes, reducing downtime and improving operational efficiency. Cytiva (formerly GE Healthcare) has expanded its FlexFactory platform, integrating single-use filtration, chromatography, and bioreactors for seamless continuous biomanufacturing. Additionally, Thermo Fisher Scientific has invested in single-use systems for intensified upstream and downstream processing, allowing faster batch turnover and lower capital investment. As companies increasingly adopt disposable, modular, and automated solutions, the continuous bioprocessing industry is set to expand, particularly in the manufacturing of biologics and biosimilars.
For instance, in January 2024, Merck announced that its Life Science business had signed a non-binding Memorandum of Understanding (MoU) with Mycenax Biotech to explore a potential collaboration to deliver innovative, high-capacity bioprocessing solutions to Taiwan and international markets. The agreement focuses on integrating Merck’s BioContinuum Platform across the entire bioprocessing spectrum for Mycenax’s customers, with plans to incorporate automation and digitalization into production workflows. This partnership aims to drive process intensification, support the transition to BioProcessing 4.0, and advance continuous bioprocessing technologies.
Analyst Perspective
The continuous bioprocessing market is growing as biopharmaceutical manufacturers pursue greater productivity, consistency, and facility efficiency. Integrated workflows reduce interruptions and enable smaller, more flexible facilities than batch operations. Rising production of monoclonal antibodies, vaccines, recombinant proteins, and other biologics drives demand for perfusion bioreactors, continuous chromatography, filtration, and process analytics. Modular and single-use systems add flexibility while reducing changeovers and contamination risks. Investment in advanced biomanufacturing infrastructure across North America, Europe, and Asia Pacific is expected to support market growth over the forecast period.
Product Insights
The consumables & reagents segment held the largest market share, at around 65.0%, in 2025. The increasing adoption of single-use technologies (SUTs), advancements in cell culture media, and the need for high-purity reagents to support uninterrupted bioproduction. The shift from traditional batch processing to continuous bioprocessing has led to a growing demand for single-use bioreactors, perfusion media, chromatography resins, filters, and biosensors, which enhance process efficiency and reduce contamination risks. For instance, in 2025, Sartorius expanded its sterile filtration portfolio with Sartopore EVO, a PFAS-free sterilizing-grade filter designed to reduce protein and excipient adsorption while supporting biopharmaceutical manufacturing workflows. The development highlights ongoing innovation in critical filtration consumables used across upstream and downstream bioprocessing operations.
The instruments segment is expected to grow at a significant CAGR from 2026 to 2033. The increasing demand for automated, scalable, and high-efficiency bioprocessing solutions to enhance biologics production. The shift toward perfusion-based bioreactors, continuous chromatography systems, and real-time monitoring tools is fueling innovation, allowing manufacturers to achieve higher yields, reduced process variability, and improved cost efficiency. For instance, in May 2025, Thermo Fisher Scientific expanded its DynaDrive single-use bioreactor portfolio with a 5 L benchtop system designed to support scalable upstream process development. The platform uses consistent reactor design and film architecture across development and larger production scales, supporting smoother process transfer within biomanufacturing workflows.
Application Insights
The monoclonal antibodies segment held a significant market share of around 29.0% in 2025. The increasing global demand for biological therapies, particularly for treating cancer, autoimmune diseases, and infectious diseases. Continuous bioprocessing enhances process efficiency, scalability, and cost-effectiveness, making it ideal for high-volume mAb production. Companies such as Sartorius, Cytiva, and Thermo Fisher Scientific are investing in perfusion bioreactors, continuous chromatography, and real-time monitoring systems to optimize yield and maintain consistent product quality. Additionally, the shift towards biosimilars and regulatory support for process intensification further fuels adoption, as manufacturers seek to reduce production costs while maintaining high product purity and potency. For instance, in September 2025, Sartorius highlighted the role of end-to-end continuous bioprocessing in monoclonal antibody manufacturing, emphasizing its potential to reduce the cost of goods and environmental impact while supporting the growing demand for mAb therapies.
The vaccine segment is expected to grow at the fastest CAGR from 2026 to 2033, due to the need for rapid, scalable, and cost-effective production, particularly with the increasing emphasis on strengthening vaccine manufacturing capacity and improving production efficiency. Continuous manufacturing enables higher yields, shorter production cycles, and greater flexibility, which are crucial for mRNA-, viral vector-, and recombinant protein-based vaccines. For instance, in February 2025, Thermo Fisher Scientific reported a collaboration with the National Institute of Allergy and Infectious Diseases to improve scalable production of a malaria transmission-blocking vaccine candidate using the Thermo Scientific HyPerforma Single-Use Fermentor. The work demonstrates the use of scalable bioprocessing equipment to improve vaccine production efficiency and support manufacturing scale-up.
End-use Insights
The pharmaceutical and biotechnology companies segment held the largest market share of around 48.0% in 2025. The increasing demand for efficient, high-yield, and cost-effective biologics production. With the rise of monoclonal antibodies, biosimilars, cell & gene therapies, and next-generation vaccines, biopharma firms are shifting from traditional batch processing to continuous manufacturing to enhance productivity and scalability. Companies such as Thermo Fisher Scientific, Cytiva (Danaher), and Sartorius are providing automated perfusion bioreactors, continuous chromatography, and process analytical technology (PAT) to optimize real-time monitoring and control. For instance, in 2025, Sartorius reported that its PIONIC platform, developed with Sanofi, was being used to support the industry's shift from batch to continuous bioprocessing, enabling faster, more efficient, and more sustainable biopharmaceutical manufacturing.
The CMOs & CROs segment is expected to witness the fastest CAGR during the forecast period, driven by the growing demand for outsourced biopharmaceutical development and production. As biopharma companies focus on cost reduction and faster time-to-market, CMOs are investing in single-use, modular, and automated continuous processing systems to improve efficiency and flexibility. Leading CMOs such as Lonza, WuXi Biologics, and Samsung Biologics are expanding their continuous manufacturing capabilities to handle high-throughput production of biologics, biosimilars, and gene therapies. Additionally, CROs are leveraging advanced bioprocessing technologies for early-stage research, process development, and clinical-scale manufacturing, driving overall market growth in the continuous bioprocessing space. For instance, in April 2025, Lonza joined the Center for Continuous Manufacturing and Advanced Crystallization (CMAC) to strengthen its service offering and support the development and implementation of continuous processing technologies within its CDMO operations.
Regional Insights
North America continuous bioprocessing market dominated the global industry with the largest revenue share of approximately 31.0% in 2025. The market is driven by strong investments in biopharmaceutical R&D, advanced manufacturing infrastructure, and supportive regulatory policies. Leading players such as Thermo Fisher Scientific, Cytiva (Danaher), and Sartorius are investing heavily in next-generation bioprocessing technologies to support the production of biologics, biosimilars, and cell & gene therapies. Additionally, government initiatives, such as funding from the Biomedical Advanced Research and Development Authority (BARDA) and the growing adoption of single-use technologies, are fueling market expansion.
 To learn more about this report, Download Free Sample Report
U.S. Continuous Bioprocessing Market Trends
The continuous bioprocessing industry in the U.S. is growing due to the presence of leading biopharma companies, extensive R&D investments, and FDA regulatory support for continuous manufacturing. The demand for personalized medicine, mAbs, and gene therapies is driving biopharmaceutical firms to adopt high-efficiency bioprocessing solutions, including automated perfusion bioreactors and real-time monitoring systems. Companies like Amgen, Lonza, and WuXi Biologics are expanding their continuous manufacturing capabilities, further boosting market growth.
Asia Pacific Continuous Bioprocessing Market Trends
The continuous bioprocessing industry in the Asia-Pacific region is driven by rising biopharmaceutical investments, increasing biosimilar production, and expanding biomanufacturing hubs in countries such as China, Japan, India, and South Korea. Governments are supporting local biologics production through favorable policies and funding initiatives, while global biopharma companies are partnering with regional CMOs and CROs to expand their presence. The adoption of continuous bioprocessing is further accelerated by advancements in single-use bioreactors, continuous purification, and PAT technologies.
China continuous bioprocessing market is supported by expanding biologics manufacturing capacity, growing domestic investment in biotechnology, and rising demand for biosimilars, monoclonal antibodies, and advanced therapies. Continued investment in large-scale biomanufacturing infrastructure and process intensification is increasing the adoption of advanced upstream and downstream processing technologies.
The continuous bioprocessing industry in Japan is driven by its aging population, rising demand for biologics, and a strong regulatory framework that supports process intensification. Leading pharmaceutical companies like Takeda and Astellas are investing in continuous biomanufacturing technologies to improve efficiency and reduce costs. The Japanese government is promoting bioprocessing innovation through funding initiatives, while CMOs such as CMIC Group are expanding their continuous manufacturing capabilities to serve both domestic and global markets.
Europe Continuous Bioprocessing Market Trends
The continuous bioprocessing market in Europe is driven by stringent regulatory requirements, significant investment in biotech R&D, and leading biopharma companies such as Roche, Novartis, and Sanofi. The European Medicines Agency (EMA) supports continuous manufacturing initiatives, leading to increased adoption of single-use technologies, continuous chromatography, and real-time process monitoring. Additionally, the region's focus on biosimilars and personalized medicine is accelerating the adoption of continuous bioprocessing across biopharma companies and CMOs.
The UK continuous bioprocessing market is growing due to government funding for advanced biomanufacturing and strong partnerships between academia and industry. Organizations like the Cell and Gene Therapy Catapult are supporting the development of next-generation bioprocessing solutions, while major biopharma firms and CMOs are investing in continuous bioreactor systems and AI-driven process analytics. The demand for biosimilars, gene therapies, and advanced vaccines is further driving market expansion.
The bioprocessing industry in Germany leads the European market with strong biotech R&D investments, a highly skilled workforce, and key players such as Merck KGaA and Sartorius pioneering continuous bioprocessing technologies. The country’s focus on biomanufacturing innovation, regulatory compliance, and process automation is driving demand for continuous chromatography, perfusion bioreactors, and PAT-enabled systems. Additionally, Germany's high biosimilar adoption rates and the presence of leading CMOs make it a crucial market for continued growth in bioprocessing.
Latin America Continuous Bioprocessing Market Trends
The continuous bioprocessing industry in Latin America is expanding due to growing biopharmaceutical production, increasing investments in biosimilars, and government support for local biomanufacturing. Countries like Brazil, Argentina, and Mexico are investing in advanced biologics production, while global companies are forming regional partnerships with local CMOs to establish continuous manufacturing capabilities. The demand for cost-effective biologics and vaccines is further propelling market growth in the region.
Continuous bioprocessing in Brazil is a major player in Latin America’s biopharmaceutical market, with increasing government investments in biologic drug production and vaccine manufacturing. The Brazilian Health Regulatory Agency (ANVISA) is promoting advanced biomanufacturing technologies, encouraging local firms like Instituto Butantan and Fiocruz to adopt continuous bioprocessing solutions. The demand for biosimilars, vaccines, and monoclonal antibodies is driving market expansion, with global biopharma companies partnering with Brazilian CMOs to establish continuous biomanufacturing capabilities.
Key Continuous Bioprocessing Company Insights
The continuous bioprocessing industry is dominated by key players such as Cytiva (Danaher), Sartorius AG, Thermo Fisher Scientific Inc., and others. These companies drive market growth through innovations in continuous bioreactors, perfusion systems, chromatography solutions, and single-use technologies, catering to the rising demand for efficient biologics production. Merck KGaA and Agilent provide consumables and analytical tools for process monitoring, enhancing scalability and efficiency. Strategic acquisitions, collaborations, and technological advancements continue to shape the competitive landscape, making continuous bioprocessing a key driver in biopharmaceutical manufacturing.
WuXi Biologics is more concentrated on biopharmaceutical development and manufacturing services, with its competitive position driven primarily by manufacturing scale and strategic capacity expansion rather than equipment supply.
Market participants are advancing continuous bioprocessing through perfusion bioreactors, continuous chromatography systems, single-use flow paths, process analytical technologies, and integrated automation platforms. Strategic collaborations, platform partnerships, and investments in end-to-end process intensification are becoming increasingly important as manufacturers seek scalable and flexible continuous bioprocessing solutions.
Key Continuous Bioprocessing Companies
The following key companies have been profiled for this study on the continuous bioprocessing market.
-
Asahi Kasei Bioprocess America, Inc.
-
Cytiva (Danaher)
-
Ginkgo Bioworks
-
Merck KGaA
-
Repligen Corporation
-
Sartorius AG
-
Thermo Fisher Scientific Inc.
-
WuXi Biologics
Recent Developments
-
In June 2024, PAK BioSolutions secured USD 12 million in funding from Arboretum Ventures, BroadOak Capital Partners, and other investors to support the expansion of its commercial operations and product development for its automated continuous manufacturing systems designed for biologics. The company's PAK Pilot System can process 50 to 500 liters of cell culture daily, serving a significant portion of the biopharmaceutical production market with an efficient, scalable solution.
-
In May 2024, Sartorius and Sanofi announced a collaboration to commercialize an integrated, end-to-end continuous downstream bioprocessing platform, combining hardware, single-use consumables, and automation technologies to streamline purification processes and improve biopharmaceutical manufacturing efficiency. The platform was subsequently introduced under the PIONIC name in September 2024.
Continuous Bioprocessing Market Report Scope
Report Attribute
Details
Market size in 2025
USD 387.9 million
Estimated market size in 2026
USD 460.3 million
Projected market size by 2033
USD 1,443.7 million
Growth rate
CAGR of 17.7% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 – 2024
Forecast period
2026 – 2033
Quantitative units
Revenue in USD million, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, application, end-use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Sweden; Norway; China; Japan; India; Australia; South Korea; Thailand; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait
Key companies profiled
Sartorius AG; Thermo Fisher Scientific Inc.; WuXi Biologics; Ginkgo Bioworks; Merck KGaA; Cytiva (Danaher); Repligen Corporation; Asahi Kasei Bioprocess America, Inc.
Customization scope
Free report customization (equivalent to 8 analyst working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Continuous Bioprocessing Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends and opportunities across each sub-segment from 2021 to 2033. For this study, Grand View Research has segmented the global continuous bioprocessing market report based on product, application, end-use, and region:
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Instruments
-
Bioreactors
-
Filtration Systems
-
Chromatography Systems
-
Process Analytical Technologies
-
Others
-
-
Consumables & Reagents
-
Media & Buffers
-
Filters & Membranes
-
Resin
-
Tubing & Bags
-
Others
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Monoclonal antibodies
-
Vaccines
-
Cell and Gene Therapy
-
Research & Development
-
Other Applications
-
-
End-use Outlook (Revenue, USD Million, 2021 - 2033)
-
Pharmaceutical and Biotechnology Companies
-
CMOs and CROs
-
Research and Academic Institutes
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
Italy
-
France
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
China
-
Japan
-
India
-
Australia
-
Thailand
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
-
Frequently Asked Questions About This Report
The global continuous bioprocessing market size was valued at USD 387.9 million in 2025 and is estimated at USD 460.3 million for 2026.
The global continuous bioprocessing market is expected to grow at a CAGR of 17.7% from 2026 to 2033, reaching USD 1,443.7 million.
The increasing demand for biopharmaceuticals, including monoclonal antibodies, cell and gene therapies, and vaccines, is a key driver of the continuous bioprocessing industry. Traditional batch processing methods are often inefficient, leading to high costs, long production cycles, and limited scalability.
Asia Pacific is the fastest-growing region over the forecast period.
The pharmaceutical and biotechnology companies segment held the largest revenue share of over 48.0% in 2025.
North America dominated with an approximately 31.0% revenue share in 2025. The market is driven by strong investments in biopharmaceutical R&D, advanced manufacturing infrastructure, and supportive regulatory policies.
Key players in the market include Sartorius AG; Thermo Fisher Scientific Inc.; WuXi Biologics; Ginkgo Bioworks; Merck KGaA; Cytiva (Danaher); Repligen Corporation; Asahi Kasei Bioprocess America, Inc., and others.
The consumables & reagents segment held the largest revenue share of over 65.0% in 2025, and it is expected to grow with the fastest CAGR over the forecast period.
The monoclonal antibodies segment held the largest revenue share of over 29.0% in 2025.
About the Author(s)
Biotechnology Research Team
Healthcare · BiotechnologyThis report was authored by the biotechnology research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the biotechnology segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


