
- Home
- »
- Agrochemicals & Fertilizers
- »
-
Crop Protection Chemicals Market Size Report, 2026-2033GVR Report cover

Crop Protection Chemicals Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Herbicides, Fungicides, Insecticides, Biopesticides), By Application (Cereals & Grains, Oilseeds & Pulses, Fruits & Vegetables), By Region (North America, MEA), And Segment Forecasts
Market Size, 2025
$50.3BMarket Estimate, 2026
$53.0BMarket Forecast, 2033
$80.2BCAGR, 2026–2033
6.1%Crop Protection Chemicals Market Summary
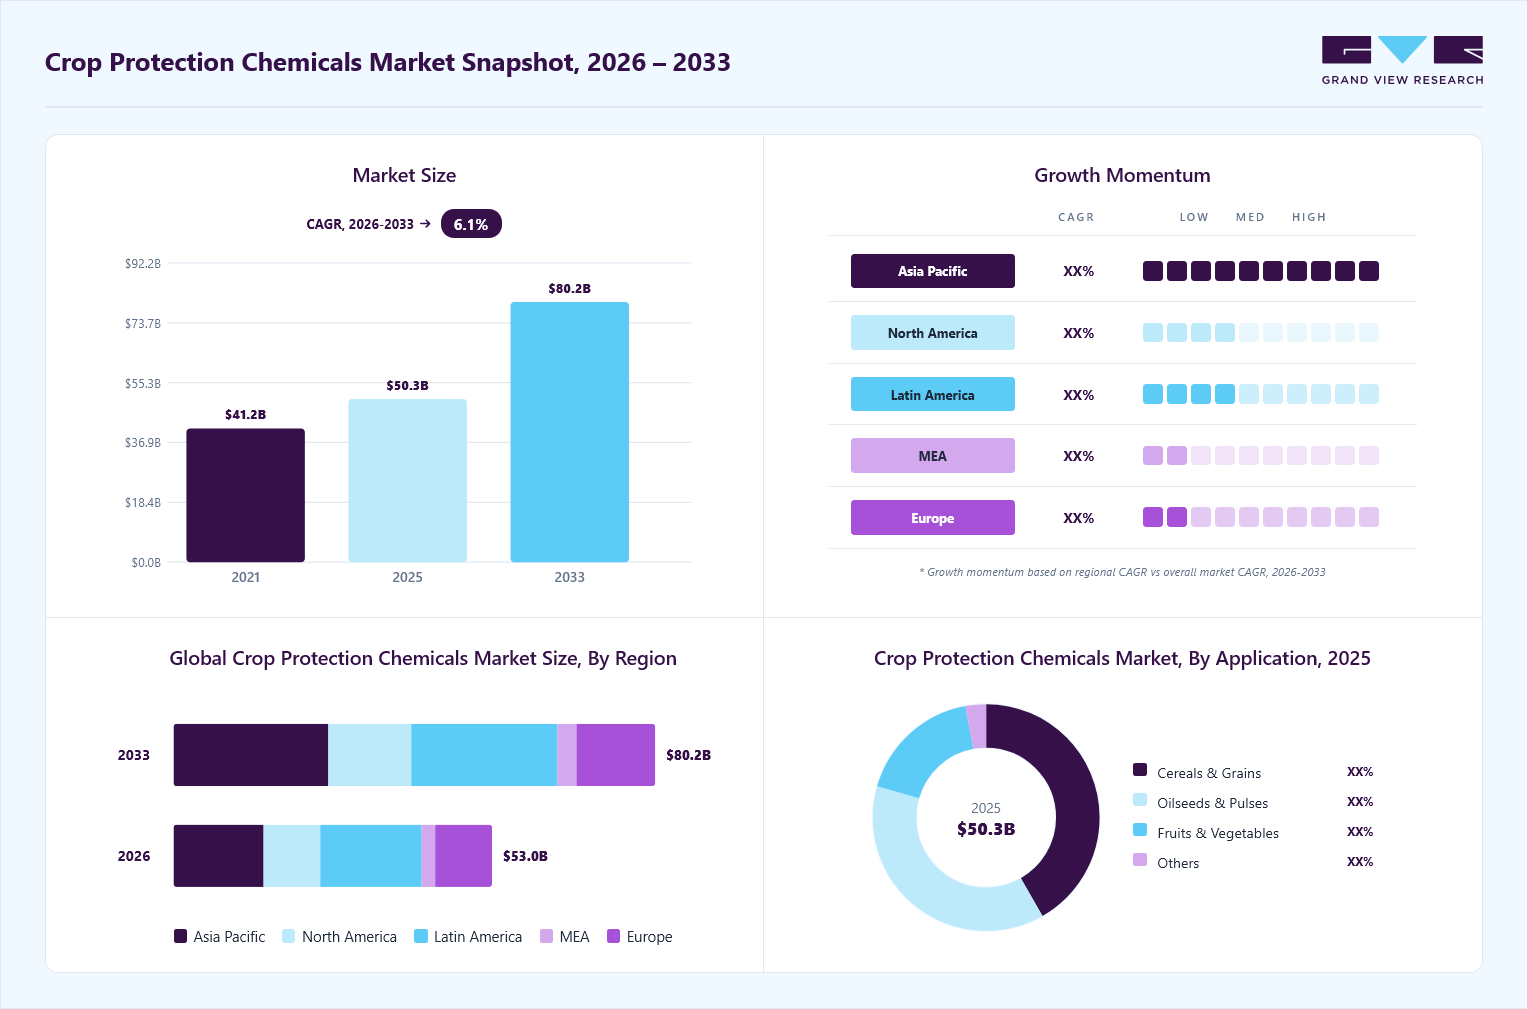
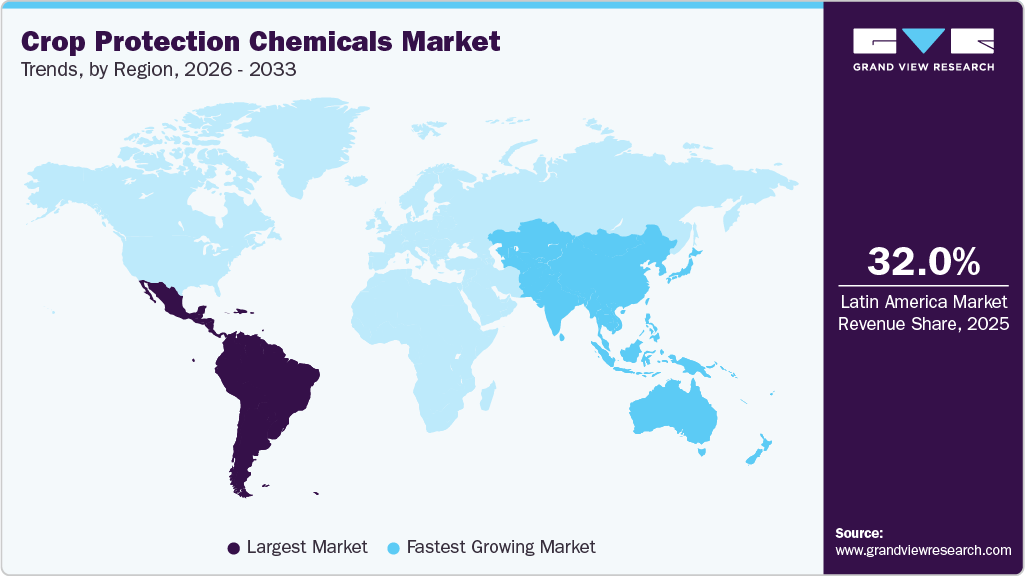
The global crop protection chemicals market size was valued at USD 50.3 billion in 2025 and is projected to grow from USD 53.0 billion in 2026 to USD 80.2 billion by 2033, at a CAGR of 6.1% from 2026 to 2033. Latin America accounted for 32.0% of the global market revenue in 2025. The market growth is primarily driven by the rising need to enhance agricultural productivity and protect crops from pests, diseases, and weeds amid increasing global food demand.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Herbicides segment accounted for the largest share of the crop protection chemicals market, representing 44.1% of total revenue in 2025.
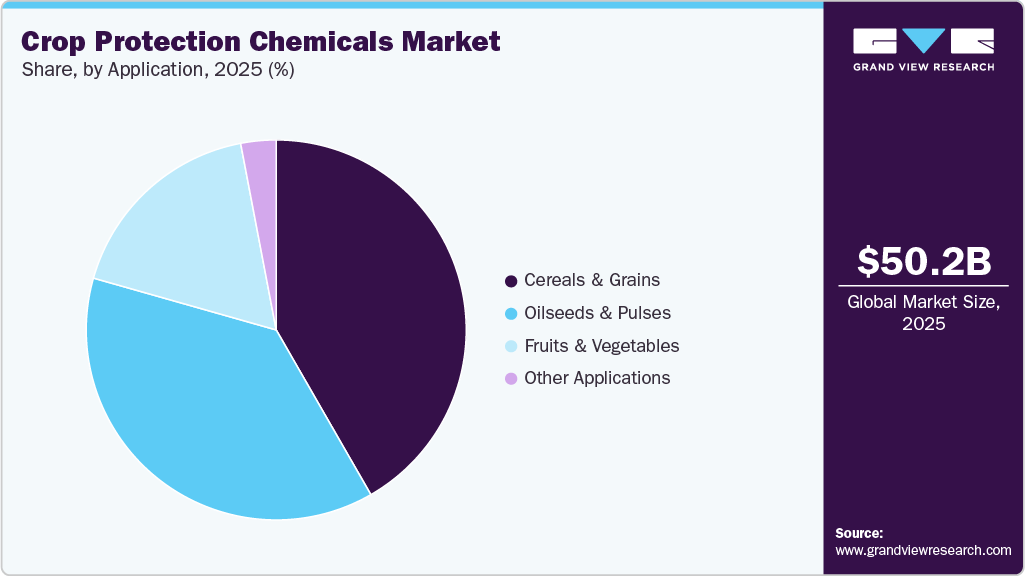
- By application: Cereals & grains segment accounted for the largest share of 41.7% in 2025.
Regional Highlights
- Largest regional market: Latin America (32.0% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: Brazil maintained a leading position in the Latin America crop protection market.
Market Size & Forecast
- Market Size in 2025: USD 50.3 Billion
- Estimated Market Size in 2026: USD 53.0 Billion
- Projected Market Size by 2033: USD 80.2 Billion
- CAGR (2026-2033): 6.1%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Farmers, agribusinesses, and governments are placing greater emphasis on improving crop yields, reducing post-harvest losses, and ensuring food security. This growth is further supported by the expansion of commercial farming, the adoption of advanced crop protection solutions, and increasing awareness regarding effective pest and disease management practices across key agricultural regions.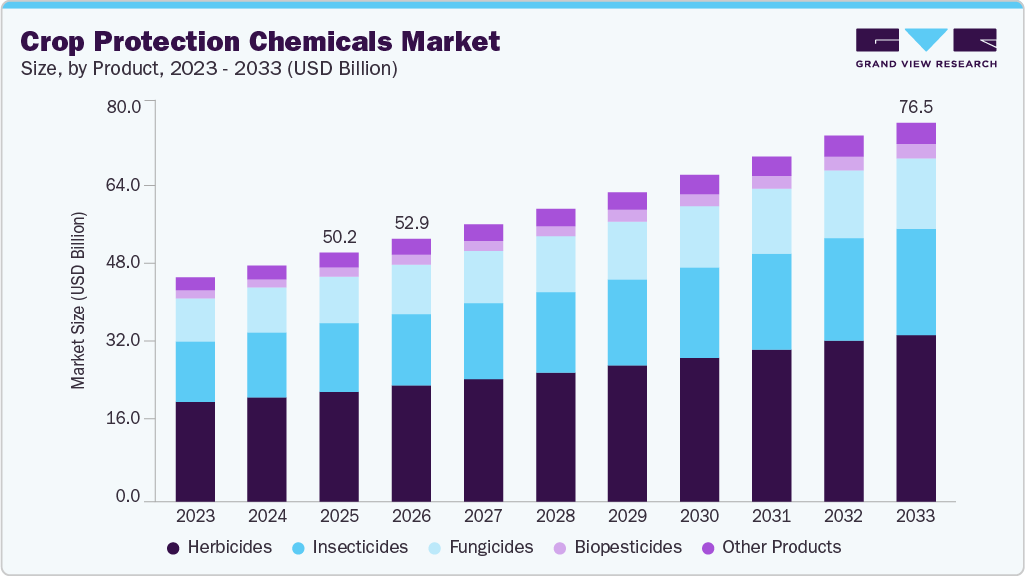 To learn more about this report, Download Free Sample Report
A key application driving the growth of the crop protection chemicals market is commercial agriculture, particularly in the cultivation of cereals, grains, oilseeds, and high-value crops. With increasing pressure to improve crop yields and reduce losses caused by pests, weeds, and diseases, farmers are adopting advanced crop protection solutions to enhance farm productivity and profitability. The use of selective herbicides, broad-spectrum insecticides, and effective fungicides improves crop health while optimizing input efficiency. In addition, agricultural producers are increasingly aligning with regulatory guidelines and integrated pest management (IPM) practices to ensure safe and responsible chemical usage. Consequently, large-scale and mechanized farming operations remain among the most commercially impactful application areas within the global crop protection chemicals market.
 To learn more about this report, Download Free Sample Report
In horticulture and specialty crop production, including fruits, vegetables, and plantation crops, demand for crop protection chemicals is steadily increasing due to the high susceptibility of these crops to pests and diseases. Growers are increasingly adopting targeted and high-efficacy formulations that provide effective protection while minimizing residue levels and environmental impact. The growing focus on quality produce, export standards, and compliance with food safety regulations has further encouraged the use of advanced fungicides and insecticides. In addition, the gradual shift toward low-toxicity and biodegradable formulations supports sustainable farming practices and helps meet stringent regulatory and consumer requirements.
Market Dynamics
The crop protection chemicals market is experiencing significant growth due to the increasing need to safeguard agricultural productivity, minimize crop losses, and ensure food security amid rising global population pressures. Farmers are increasingly relying on crop protection chemicals, including herbicides, insecticides, fungicides, and other specialty formulations, to protect crops from weeds, pests, and diseases that can significantly reduce yields and quality. The expansion of commercial farming, growing adoption of modern agricultural practices, and increasing demand for high-value crops are further driving market growth. Government initiatives supporting agricultural modernization and the development of advanced crop protection technologies continue to strengthen market expansion across major agricultural regions.
The growing need to improve agricultural productivity and reduce crop losses is a major driver of the crop protection chemicals market. Pests, weeds, fungal infections, and other crop diseases continue to pose significant challenges to farmers by reducing yield potential and affecting crop quality. Crop protection chemicals play a critical role in protecting crops throughout the cultivation cycle, enabling farmers to maximize productivity and achieve more consistent harvest outcomes.
The impact of this trend is evident across a wide range of crop categories, including cereals & grains, fruits & vegetables, oilseeds & pulses, and plantation crops. Farmers are increasingly adopting advanced herbicides, fungicides, insecticides, and integrated crop protection programs to improve field performance and optimize resource utilization. As agricultural producers face mounting pressure to increase food production while managing limited arable land resources, demand for effective crop protection chemicals is expected to grow steadily across global farming systems.
The increasing adoption of organic farming practices and biological crop protection solutions presents a key restraint for the crop protection chemicals market. Many farmers, agricultural cooperatives, and food producers are shifting toward production systems that emphasize reduced chemical usage, biological pest control methods, and environmentally sustainable farming practices. This transition is being driven by rising consumer demand for organic food products and increasing awareness regarding the environmental impact of synthetic agricultural chemicals.
Demand for certain conventional crop protection chemicals may face limitations in regions with strong organic farming adoption. Regulatory restrictions on chemical residues and stricter environmental compliance requirements are further encouraging the use of biological alternatives and integrated pest management strategies. While crop protection remains essential for agricultural productivity, the growing preference for non-synthetic solutions may moderate growth opportunities for traditional crop protection chemical manufacturers in some markets.
The increasing focus on sustainable agriculture and precision farming is creating substantial growth opportunities for participants in the crop protection chemicals market. Farmers are seeking innovative crop protection solutions that deliver high efficacy while minimizing environmental impact, reducing chemical usage, and improving application efficiency. This trend is driving demand for next-generation formulations, bio-based crop protection products, targeted application technologies, and precision agriculture-compatible chemical solutions.
The opportunity is particularly strong as governments, agricultural institutions, and food supply chain stakeholders promote sustainable farming practices and responsible chemical use. Manufacturers can capitalize on this trend by developing advanced crop protection products with improved safety profiles, lower environmental footprints, and enhanced performance characteristics. Investments in precision application technologies, integrated pest management solutions, and sustainable crop protection innovations can help companies strengthen their market position and generate long-term growth opportunities across diverse agricultural sectors worldwide.
Market Concentration & Characteristics
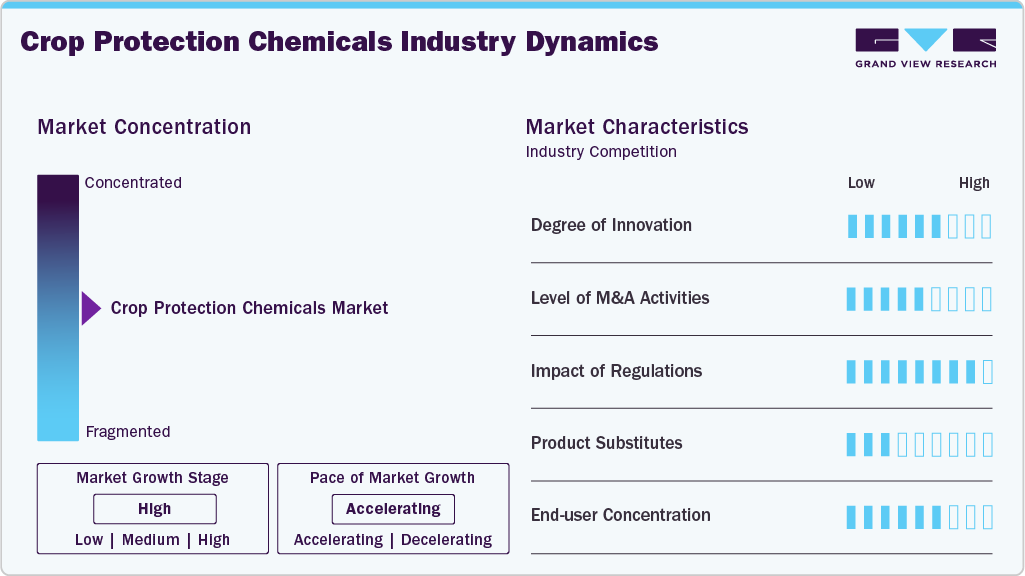
The crop protection chemicals market is moderately fragmented, with market leadership concentrated among several large, vertically integrated agrochemical manufacturers. These key players leverage economies of scale, strong in-house research and development capabilities, access to critical active ingredients, and extensive global distribution networks to maintain a competitive advantage. Their integration across the crop protection value chain from active ingredient development and formulation to packaging and distribution enables improved cost efficiency, consistent product quality, and reliable supply. This strategic positioning allows companies to effectively serve a broad range of agricultural applications, including cereals and grains, oilseeds, fruits and vegetables, and plantation crops, reinforcing their market presence and supporting the widespread adoption of advanced crop protection solutions worldwide.
 To learn more about this report, Download Free Sample Report
At the same time, emerging players in Asia Pacific, Latin America, and the Middle East & Africa are steadily expanding their presence in the crop protection chemicals market by leveraging cost-efficient manufacturing capabilities, favorable climatic conditions for agricultural inputs, and rising domestic demand for effective crop protection solutions. These regional manufacturers are supported by targeted investments in formulation facilities, active ingredient production, and localized distribution networks strategically positioned near key agricultural regions. Their focus is on delivering cost-effective and scalable crop protection products across high-demand segments such as cereals and grains, oilseeds, fruits and vegetables, and plantation crops. This evolving landscape characterized by global consolidation among established multinational agrochemical companies alongside regionally driven expansion continues to reshape the competitive dynamics of the global crop protection chemicals market.
Analyst Perspective
The Crop Protection Chemicals Market is expected to experience strong growth, driven by rising global food demand, increasing pressure to enhance agricultural productivity, and the growing need to protect crops from weeds, insects, and diseases. Farmers are increasingly adopting advanced herbicides, fungicides, insecticides, and biological crop protection solutions to minimize yield losses and improve crop quality. The expansion of commercial agriculture, precision farming technologies, and integrated pest management practices is further supporting market growth.
Product Insights
The herbicides segment accounted for the largest share of the crop protection chemicals market, representing 44.1% of total revenue in 2025. This dominance is primarily attributed to the widespread need for effective weed management across major crops, including cereals, grains, and oilseeds, where weed infestation significantly impacts yield and crop quality. Herbicides offer cost-effective and efficient weed control solutions, supporting large-scale agricultural operations and reducing labor dependency. Their broad applicability, ease of use, and proven effectiveness have led to their extensive adoption across both developed and emerging agricultural markets.
Insecticides and fungicides continue to witness steady demand due to the growing prevalence of pest infestations and crop diseases driven by changing climatic conditions. Insecticides play a critical role in protecting crops from insects that cause direct yield losses, while fungicides are increasingly used to manage fungal diseases in high-value crops such as fruits, vegetables, and plantation crops. Furthermore, growing regulatory focus and sustainability initiatives are encouraging the gradual adoption of low-toxicity and bio-based crop protection products, which offer improved environmental profiles while maintaining effective pest and disease control. Collectively, these diverse product categories enable farmers to enhance crop productivity, manage resistance, and comply with evolving agricultural and environmental standards worldwide.
Application Insights
The cereals & grains segment accounted for the largest share of the Crop Protection market, representing 41.7% of total revenue in 2025. The strong demand from this segment is driven by the large-scale cultivation of staple crops such as wheat, rice, corn, and barley, which are highly susceptible to weed competition, insect infestations, and fungal diseases. Given their critical role in global food security, farmers prioritize the use of crop protection chemicals to safeguard yields, improve crop quality, and ensure stable production levels. The extensive acreage under cereals and grains, combined with the need for cost-effective and efficient crop protection solutions, continues to support high product consumption in this segment.
In addition to cereals and grains, oilseeds and pulses, fruits and vegetables, and plantation crops contribute significantly to overall market demand. Fruits and vegetables, in particular, require intensive crop protection due to their sensitivity to pests and diseases and the need to meet strict quality and residue standards for domestic consumption and exports. Meanwhile, oilseeds and plantation crops benefit from targeted application of herbicides, insecticides, and fungicides to manage crop-specific challenges and improve productivity. Collectively, these application segments reinforce the sustained growth of the global crop protection chemicals market across diverse agricultural systems.
 To learn more about this report, Download Free Sample Report
Oilseeds and pulses represent the second-largest application segment in the global crop protection chemicals market, driven by the increasing cultivation of crops such as soybean, rapeseed, sunflower, chickpea, and lentils across key agricultural regions. These crops are particularly vulnerable to weed competition, insect pressure, and fungal infections during critical growth stages, which necessitates the use of effective crop protection solutions. The application of herbicides, insecticides, and fungicides helps improve crop establishment, enhance yield stability, and protect oil and protein content, making crop protection chemicals an essential input for oilseeds and pulses cultivation.
In addition to yield protection, the use of crop protection chemicals in oilseeds and pulses aligns with broader sustainability and productivity objectives in modern agriculture. Targeted formulations and optimized application practices help reduce input losses, improve resistance management, and minimize environmental impact. Increasing adoption of integrated pest management practices and growing awareness of residue compliance further support the use of advanced crop protection solutions in this segment. As global demand for edible oils and plant-based proteins continues to rise, oilseeds and pulses remain a critical application area, supporting sustained demand within the global crop protection chemicals market.
Regional Insights
Latin America accounted for 32.0% of the crop protection market revenue in 2025, driven primarily by the region’s extensive agricultural land base and large-scale cultivation of key commercial crops such as soybean, corn, sugarcane, and coffee. The region’s strong dependence on agriculture, combined with rising adoption of modern farming practices, has led to sustained demand for crop protection chemicals to manage weeds, pests, and crop diseases effectively. Countries such as Brazil and Argentina play a central role in regional market growth due to their high input-intensive farming systems and significant export-oriented agricultural production.
 To learn more about this report, Download Free Sample Report
Growth in Latin America is further supported by increasing awareness among farmers regarding yield optimization, resistance management, and crop quality improvement. The widespread use of herbicides, insecticides, and fungicides across row crops and plantation agriculture has become an integral part of crop management practices in the region. In addition, supportive government policies, expanding distribution networks, and the presence of both multinational and regional agrochemical companies are improving product accessibility and adoption. Ongoing investments in agricultural technology and the gradual integration of precision farming practices continue to strengthen Latin America’s leading position in the global crop protection chemicals market.
Brazil Crop Protection Chemicals Market Trends
Brazil maintained a leading position in the Latin America crop protection market, driven by the country’s large-scale cultivation of row crops such as soybean, corn, and sugarcane. Brazil’s highly mechanized and input-intensive agricultural system relies heavily on crop protection chemicals to manage weed pressure, insect infestations, and crop diseases across extensive farming areas. The widespread adoption of herbicides, insecticides, and fungicides is critical to maintaining high yield levels and supporting the country’s strong position in global agricultural exports.
The use of crop protection chemicals in Brazil is further supported by increasing awareness of integrated pest management practices, resistance management, and yield optimization among commercial farmers. Leading agrochemical companies are introducing advanced formulations with improved efficacy, selectivity, and environmental profiles to meet evolving regulatory requirements and sustainability goals. In addition, expanding distribution networks, favorable agro-climatic conditions, and ongoing investments in agricultural technology continue to reinforce Brazil’s dominant role in the Latin America crop protection chemicals market.
Asia Pacific Crop Protection Chemicals Market Trends
The Asia Pacific crop protection chemicals market emerged as the second-largest regional market, accounting for a 27.8% share in 2025 and the fastest growing market during forecast period, supported by extensive agricultural activity and rising adoption of modern crop management practices across the region. Countries such as China, India, Japan, and several Southeast Asian nations rely heavily on crop protection chemicals to safeguard yields of staple crops, including rice, wheat, and corn, as well as fruits and vegetables. The growing need to improve food security for a rapidly expanding population continues to drive demand for herbicides, insecticides, and fungicides across both smallholder and commercial farming systems.
Market growth in Asia Pacific is further strengthened by increasing government support for agricultural productivity, expanding awareness of integrated pest management practices, and improving access to crop protection products through well-established distribution networks. In addition, the presence of a large number of regional manufacturers and increasing investments by multinational agrochemical companies are enhancing product availability and affordability. Ongoing advancements in formulation technologies and the gradual adoption of precision agriculture tools are expected to further support the Asia Pacific crop protection chemicals market, reinforcing its position as the second-largest region globally.
China crop protection chemicals market has witnessed steady growth, driven by the need to enhance agricultural productivity while adhering to stringent environmental and food safety regulations. Farmers across the country rely on crop protection chemicals to manage weeds, insects, and crop diseases across major crops such as corn, soybean, wheat, and fruits and vegetables. The widespread adoption of modern farming practices and precision agriculture techniques has further increased demand for effective and targeted crop protection solutions.
Europe Crop Protection Chemicals Market Trends
Europe represents the third-largest regional market for crop protection chemicals, accounting for a value share of 18.1% in 2025. Market demand in the region is shaped by the need to maintain crop productivity while complying with some of the world’s most stringent environmental and food safety regulations. European farmers widely use crop protection chemicals to manage weeds, pests, and diseases across cereals, oilseeds, fruits, and vegetables, particularly in countries with large agricultural sectors such as France, Germany, Spain, and Italy.
Growth in the European market is increasingly influenced by regulatory frameworks that promote responsible chemical usage, including restrictions on high-risk active ingredients and tighter residue limits. This has accelerated the adoption of advanced formulations with improved selectivity, reduced toxicity, and lower environmental persistence. In addition, strong emphasis on integrated pest management practices, sustainable agriculture, and traceable food supply chains continues to shape product development and usage patterns. These factors collectively support Europe’s steady demand for crop protection chemicals while reinforcing the region’s role as a key, regulation-driven market within the global landscape.
Crop protection chemicals market in Germany growth is shaped by sustainable agriculture, integrated pest management practices, and the adoption of eco-friendly formulations with reduced toxicity and environmental persistence. Leading agrochemical companies are investing in advanced herbicides, insecticides, and fungicides that provide targeted protection while supporting regulatory compliance and minimizing ecological impact. Additionally, strong research and development infrastructure, government support for sustainable farming practices, and increasing awareness among farmers regarding efficient crop protection techniques continue to strengthen Germany’s position as a key market within Europe and the global crop protection chemicals landscape.
North America Crop Protection Chemicals Market Trends
Market growth in North America is further supported by regulatory oversight from agencies such as the U.S. Environmental Protection Agency (EPA) and Health Canada, which encourage the use of safer, low-toxicity, and environmentally friendly crop protection solutions. Farmers and agribusinesses are increasingly adopting advanced herbicides, insecticides, and fungicides to optimize yields, improve crop quality, and comply with food safety and sustainability standards. In addition, growing awareness of integrated pest management, precision agriculture, and environmentally responsible farming practices continues to drive demand for effective and targeted crop protection chemicals across North America.
Middle East and Africa Crop Protection Chemicals Market Trends
Demand for crop protection chemicals in MEA region is particularly strong in countries investing in large-scale commercial agriculture and export-oriented farming, where herbicides, insecticides, and fungicides are critical for managing weeds, pests, and crop diseases. In the Middle East, favorable climatic conditions and increasing investment in modern farming infrastructure support higher adoption of advanced crop protection solutions, while in Africa, rising awareness of food security, yield optimization, and sustainable farming practices is boosting market uptake. Additionally, growing foreign investment, technology partnerships, and knowledge transfer are expected to further accelerate the adoption of effective and environmentally responsible crop protection chemicals across the MEA region.
Key Crop Protection Chemicals Company Insights
BASF SE, headquartered in Ludwigshafen, Germany, is a leading and well-established player in the global crop protection chemicals market, leveraging decades of expertise in agrochemicals, specialty formulations, and sustainable farming solutions. The company offers a comprehensive portfolio of high-performance herbicides, insecticides, fungicides, and bio-based crop protection products designed for diverse agricultural applications, including cereals and grains, oilseeds and pulses, fruits and vegetables, and plantation crops. These solutions provide essential functionalities such as effective pest and weed control, disease management, crop yield enhancement, and resistance mitigation, helping farmers optimize productivity and maintain crop quality. BASF’s vertically integrated production network and extensive global supply chain enable the delivery of reliable, scalable, and high-quality crop protection solutions with strong regional adaptability.
Key Crop Protection Chemicals Companies
The following key companies have been profiled for this study on the crop protection chemicals market.
-
American Vanguard Corporation
-
Arysta LifeSciences Corporation
-
Bayer AG
-
BASF SE
-
FMC Corporation
-
Corteva
-
Dhr. Hansen Holding A/S
-
UPL Limited
-
Syngenta Group
-
Sumitomo Chemical Co. Ltd.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Bayer AG, BASF SE, FMC Corporation, Corteva, UPL Limited, Syngenta Group, Sumitomo Chemical Co. Ltd.)
- Focus on comprehensive crop protection portfolios comprising herbicides, fungicides, insecticides, seed treatments, and biological crop protection products.
- Invest heavily in R&D to develop novel active ingredients, resistance-management solutions, and precision agriculture technologies.
- Expand market presence through acquisitions, licensing agreements, strategic collaborations, and global distribution networks.
- Strengthen sustainability initiatives through low-residue formulations, biological products, and integrated pest management solutions.
- Strong global brand recognition and extensive distribution channels across key agricultural regions.
- Diverse product portfolios covering major crop protection segments and crop types.
- Significant financial resources and research capabilities enable continuous innovation and regulatory compliance.
- Strong relationships with growers, distributors, and agricultural institutions worldwide.
- High regulatory approval costs and lengthy product development cycles.
- Exposure to increasing environmental regulations, product registration challenges, and active ingredient restrictions.
- Large organizational structures may reduce agility in responding to niche market opportunities.
- Patent expirations and generic competition can pressure profit margins.
Emerging / Regional Players (American Vanguard Corporation, Arysta LifeScience Corporation, Chr. Hansen Holding A/S)
- Focus on niche crop protection segments, biological pesticides, specialty formulations, and region-specific agricultural solutions.
- Expand through regional partnerships, distributor networks, and targeted acquisitions.
- Emphasize sustainable crop protection technologies, biopesticides, and differentiated product offerings.
- Develop customized solutions for specific crops, pest challenges, and local farming conditions.
- Greater operational flexibility and faster responsiveness to changing customer requirements.
- Strong expertise in biological crop protection, specialty products, and localized agricultural applications.
- Ability to address niche market opportunities underserved by multinational competitors.
- More agile commercialization of innovative and sustainable crop protection technologies.
- Limited geographic footprint and smaller manufacturing capacities compared with global market leaders.
- Lower R&D budgets may restrict development of proprietary active ingredients and broad product pipelines.
- Greater dependence on selected product categories and regional markets increases business risk.
- More limited regulatory resources can constrain expansion into highly regulated international markets.
Recent Developments
-
In August 2025, Karnataka, UPL Sustainable Agri Solutions launched Brucia, a new post-emergent herbicide specifically for maize crops in India. The product offers farmers an effective, safe, and efficient solution against persistent and resistant weeds and is being made available through dealers and distributors across major maize-growing districts. Such product launches enhance adoption of advanced crop protection solutions, improve crop yields, and address resistance challenges, thereby driving growth in India and broader crop protection chemicals market.
Crop Protection Chemicals Market Report Scope
Report Attribute
Details
Market size in 2025
USD 50.3 billion
Estimated market size in 2026
USD 53.0 billion
Projected market size by 2033
USD 80.2 billion
Growth rate
CAGR of 6.1% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Volume, Kilotons; Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, application, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; France; Spain; Italy; UK; Eastern Europe; China; India; Japan; South Korea; Thailand; Australia; Indonesia; Brazil; Argentina; South Africa; Saudi Arabia
Key companies profiled
American Vanguard Corporation; Arysta LifeSciences Corporation; Bayer AG; BASF SE; FMC Corporation; Corteva; Dhr. Hansen Holding A/S; UPL Limited; Syngenta Group; Sumitomo Chemical Co. Ltd.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Crop Protection Chemicals Market Report Segmentation
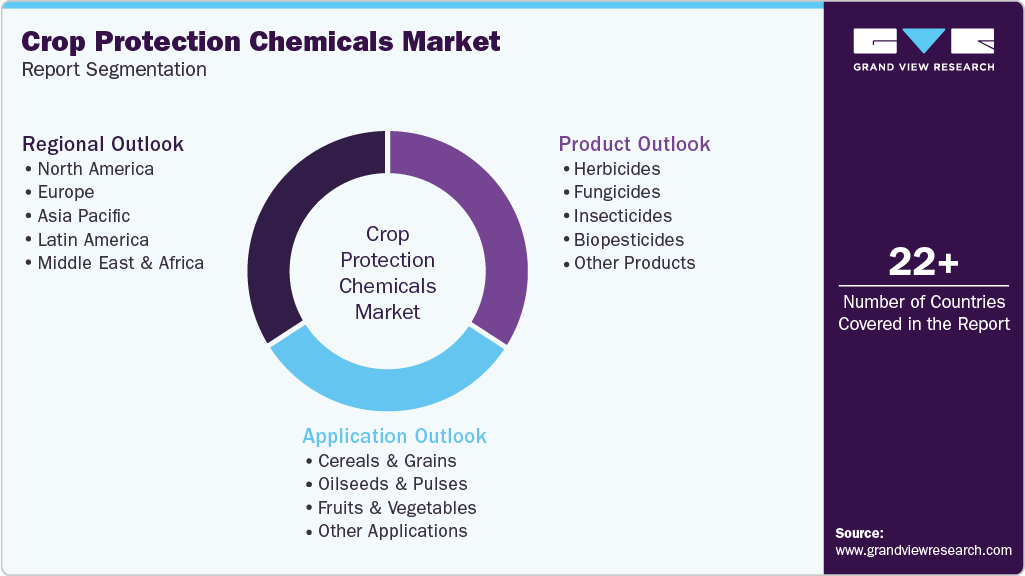
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global crop protection chemicals market report based on product, application, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Million; Volume, Kilotons, 2021 - 2033)
-
Herbicides
-
By Product
-
Selective
-
Non-selective
-
-
By Active Ingredients
-
Glyphosate
-
Atrazine
-
2,4-D
-
Other Active Herbicide Ingredients
-
-
-
Fungicides
-
By Active Ingredients
-
Chlorathalonil
-
Sulfur
-
PCNB
-
Maneb
-
Other Active Fungicide Ingredients
-
-
-
Insecticides
-
By Active Ingredients
-
Malathion
-
Carbaryl
-
Chlorpyrifos
-
Other Active Insecticide Ingredients
-
-
-
Biopesticides
-
Other Products
-
-
Application Outlook (Revenue, USD Million; Volume, Kilotons, 2021 - 2033)
-
Cereals & Grains
-
Oilseeds & Pulses
-
Fruits & Vegetables
-
Other Applications
-
-
Regional Outlook (Revenue, USD Million; Volume, Kilotons, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
France
-
Spain
-
Italy
-
UK
-
Eastern Europe
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Indonesia
-
Thailand
-
Australia
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Arabia
-
South Africa
-
-
Research Methodology
Segment Definition
Segment - Product
Revenue capture definition
Herbicides
Revenue generated from herbicide products used to control weeds in agricultural crops, helping reduce competition for nutrients, water, and sunlight while improving crop productivity and yield performance.
Fungicides
Revenue generated from fungicide products applied to prevent, manage, and control fungal diseases in crops, protecting crop quality, reducing yield losses, and supporting agricultural productivity.
Insecticides
Revenue generated from insecticide products used to control insect pests that damage crops during cultivation, helping farmers minimize crop losses and maintain yield and quality standards.
Biopesticides
Revenue generated from biological crop protection products, including microbial, botanical, and biochemical formulations, used to manage pests and diseases through environmentally sustainable crop protection practices.
Others
Revenue generated from other crop protection products, including nematicides, acaricides, molluscicides, rodenticides, plant growth regulators, seed treatment chemicals, and specialty crop protection solutions that support overall crop health and productivity.
Segment - Application
Revenue capture definition
Cereals & Grains
Revenue generated from crop protection chemicals used in the cultivation of cereals and grains such as wheat, rice, corn, barley, oats, and sorghum to control weeds, pests, and diseases while improving crop yield and quality.
Oilseeds & Pulses
Revenue generated from crop protection chemicals applied in oilseed and pulse crops, including soybean, canola, sunflower, groundnut, peas, lentils, chickpeas, and beans, to protect crops from insects, diseases, and weed infestations.
Fruits & Vegetables
Revenue generated from crop protection products used in fruit and vegetable cultivation to manage pests, fungal infections, and weeds, helping improve crop quality, marketability, and agricultural productivity.
Others
Revenue generated from crop protection chemical applications across other agricultural crops, including plantation crops, fiber crops, sugar crops, forage crops, ornamental plants, turf, and specialty horticultural crops not classified under the above categories.
Estimation Model
Layer Name
Key Question
Description
Agricultural Cultivation Base Layer
What forms the demand base?
Identify global cultivation areas and production volumes of major crop categories, including cereals & grains, oilseeds & pulses, fruits & vegetables, and other crops. This layer establishes the agricultural production base that drives demand for crop protection chemicals by determining the total cultivated area exposed to weed infestations, insect pests, fungal diseases, and other crop health threats requiring protection measures.
Crop Protection Adoption Layer
Where are crop protection chemicals used?
Estimate the proportion of agricultural land utilizing crop protection chemicals across crop categories, farming systems, and geographic regions. Assess adoption levels of herbicides, fungicides, insecticides, biopesticides, and other crop protection products in conventional farming, integrated pest management (IPM) systems, precision agriculture operations, and sustainable farming practices.
Application Intensity Layer
How much crop protection chemicals is used?
Analyze average application rates and treatment frequency of crop protection chemicals across different crops and pest management programs. Consumption intensity is determined by crop type, pest and disease pressure, weed prevalence, climatic conditions, resistance management requirements, cultivation practices, product formulation, and regional regulatory frameworks.
Revenue Layer
How is market revenue generated?
Market revenue is quantified through the sale of herbicides, fungicides, insecticides, biopesticides, seed treatment products, and other crop protection solutions used to safeguard crop yields and quality. Revenue is generated from recurring demand across commercial farms, agricultural cooperatives, plantation operators, specialty crop producers, and agribusiness enterprises seeking effective pest, disease, and weed management solutions to maximize agricultural productivity and profitability.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Cross-Segmentation Analysis
Detailed cross-segmentation assessment evaluating the relationship between product types (herbicides, fungicides, insecticides, biopesticides, and other crop protection products) and crop applications (cereals & grains, oilseeds & pulses, fruits & vegetables, and others). Analysis identifies product utilization patterns, pest and disease control requirements, adoption trends, demand concentration, and revenue contribution across intersecting segments.
Supports product portfolio optimization and market prioritization by identifying the most attractive product-crop combinations, enabling improved resource allocation, sales targeting, product development planning, and strategic decision-making.
Competitive Benchmarking
Comparative evaluation of leading crop protection chemical manufacturers based on product portfolio breadth, active ingredient portfolio, biological and conventional crop protection capabilities, geographic presence, distribution strength, regulatory approvals, sustainability initiatives, R&D investments, and strategic developments across global agricultural markets.
Assists competitive intelligence, partnership evaluation, and supplier assessment by providing deeper visibility into market positioning, competitive advantages, innovation capabilities, differentiation strategies, and long-term growth potential.
Opportunity Assessment
Comprehensive assessment of emerging opportunities associated with biological crop protection products, integrated pest management (IPM), precision agriculture technologies, resistance management solutions, sustainable farming practices, digital agriculture integration, and expanding demand for environmentally responsible crop protection products.
Helps identify high-growth investment areas, emerging application opportunities, innovation priorities, and market expansion prospects, supporting long-term growth strategies and business development initiatives across the crop protection chemicals value chain.
Frequently Asked Questions About This Report
Key factors that are driving the development of new and more effective active ingredients, including biopesticides and environmentally friendly alternatives, enhance the efficacy of crop protection solutions while minimizing environmental impact.
Asia Pacific is the fastest-growing region over the forecast period.
The global crop protection chemicals market size was estimated at USD 50.3 billion in 2025 and is expected to reach USD 53.0 billion in 2026.
The global crop protection chemicals market is expected to grow at a compound annual growth rate of 6.1% from 2026 to 2033, reaching USD 80.2 billion by 2033.
Latin America crop protection chemicals market dominated the global market, accounting for a 32.0% value share in 2025, Investment in modern farming practices is another critical driver of the crop protection chemicals market in these regions.
Some of the key players operating in the market include American Vanguard Corporation; Arysta LifeSciences Corporation; Bayer AG; BASF SE; FMC Corporation; Corteva; Dhr. Hansen Holding A/S; UPL Limited; Syngenta Group; Sumitomo Chemical Co. Ltd.
The herbicides segment accounted for the largest share of the crop protection chemicals market, representing 44.1% of total revenue in 2025.
The cereals & grains segment accounted for the largest share of the Crop Protection market, representing 41.7% of total revenue in 2025.
About the Author(s)
Agrochemicals & Fertilizers Research Team
Bulk Chemicals · Agrochemicals & FertilizersThis report was authored by the agrochemicals & fertilizers research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the agrochemicals & fertilizers segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


